Week 10/26–10/30: Big Tech's Capex Bill and Intel's Collapse Hand SPX a Third Straight Weekly Loss as Small Caps and Defensives Rally
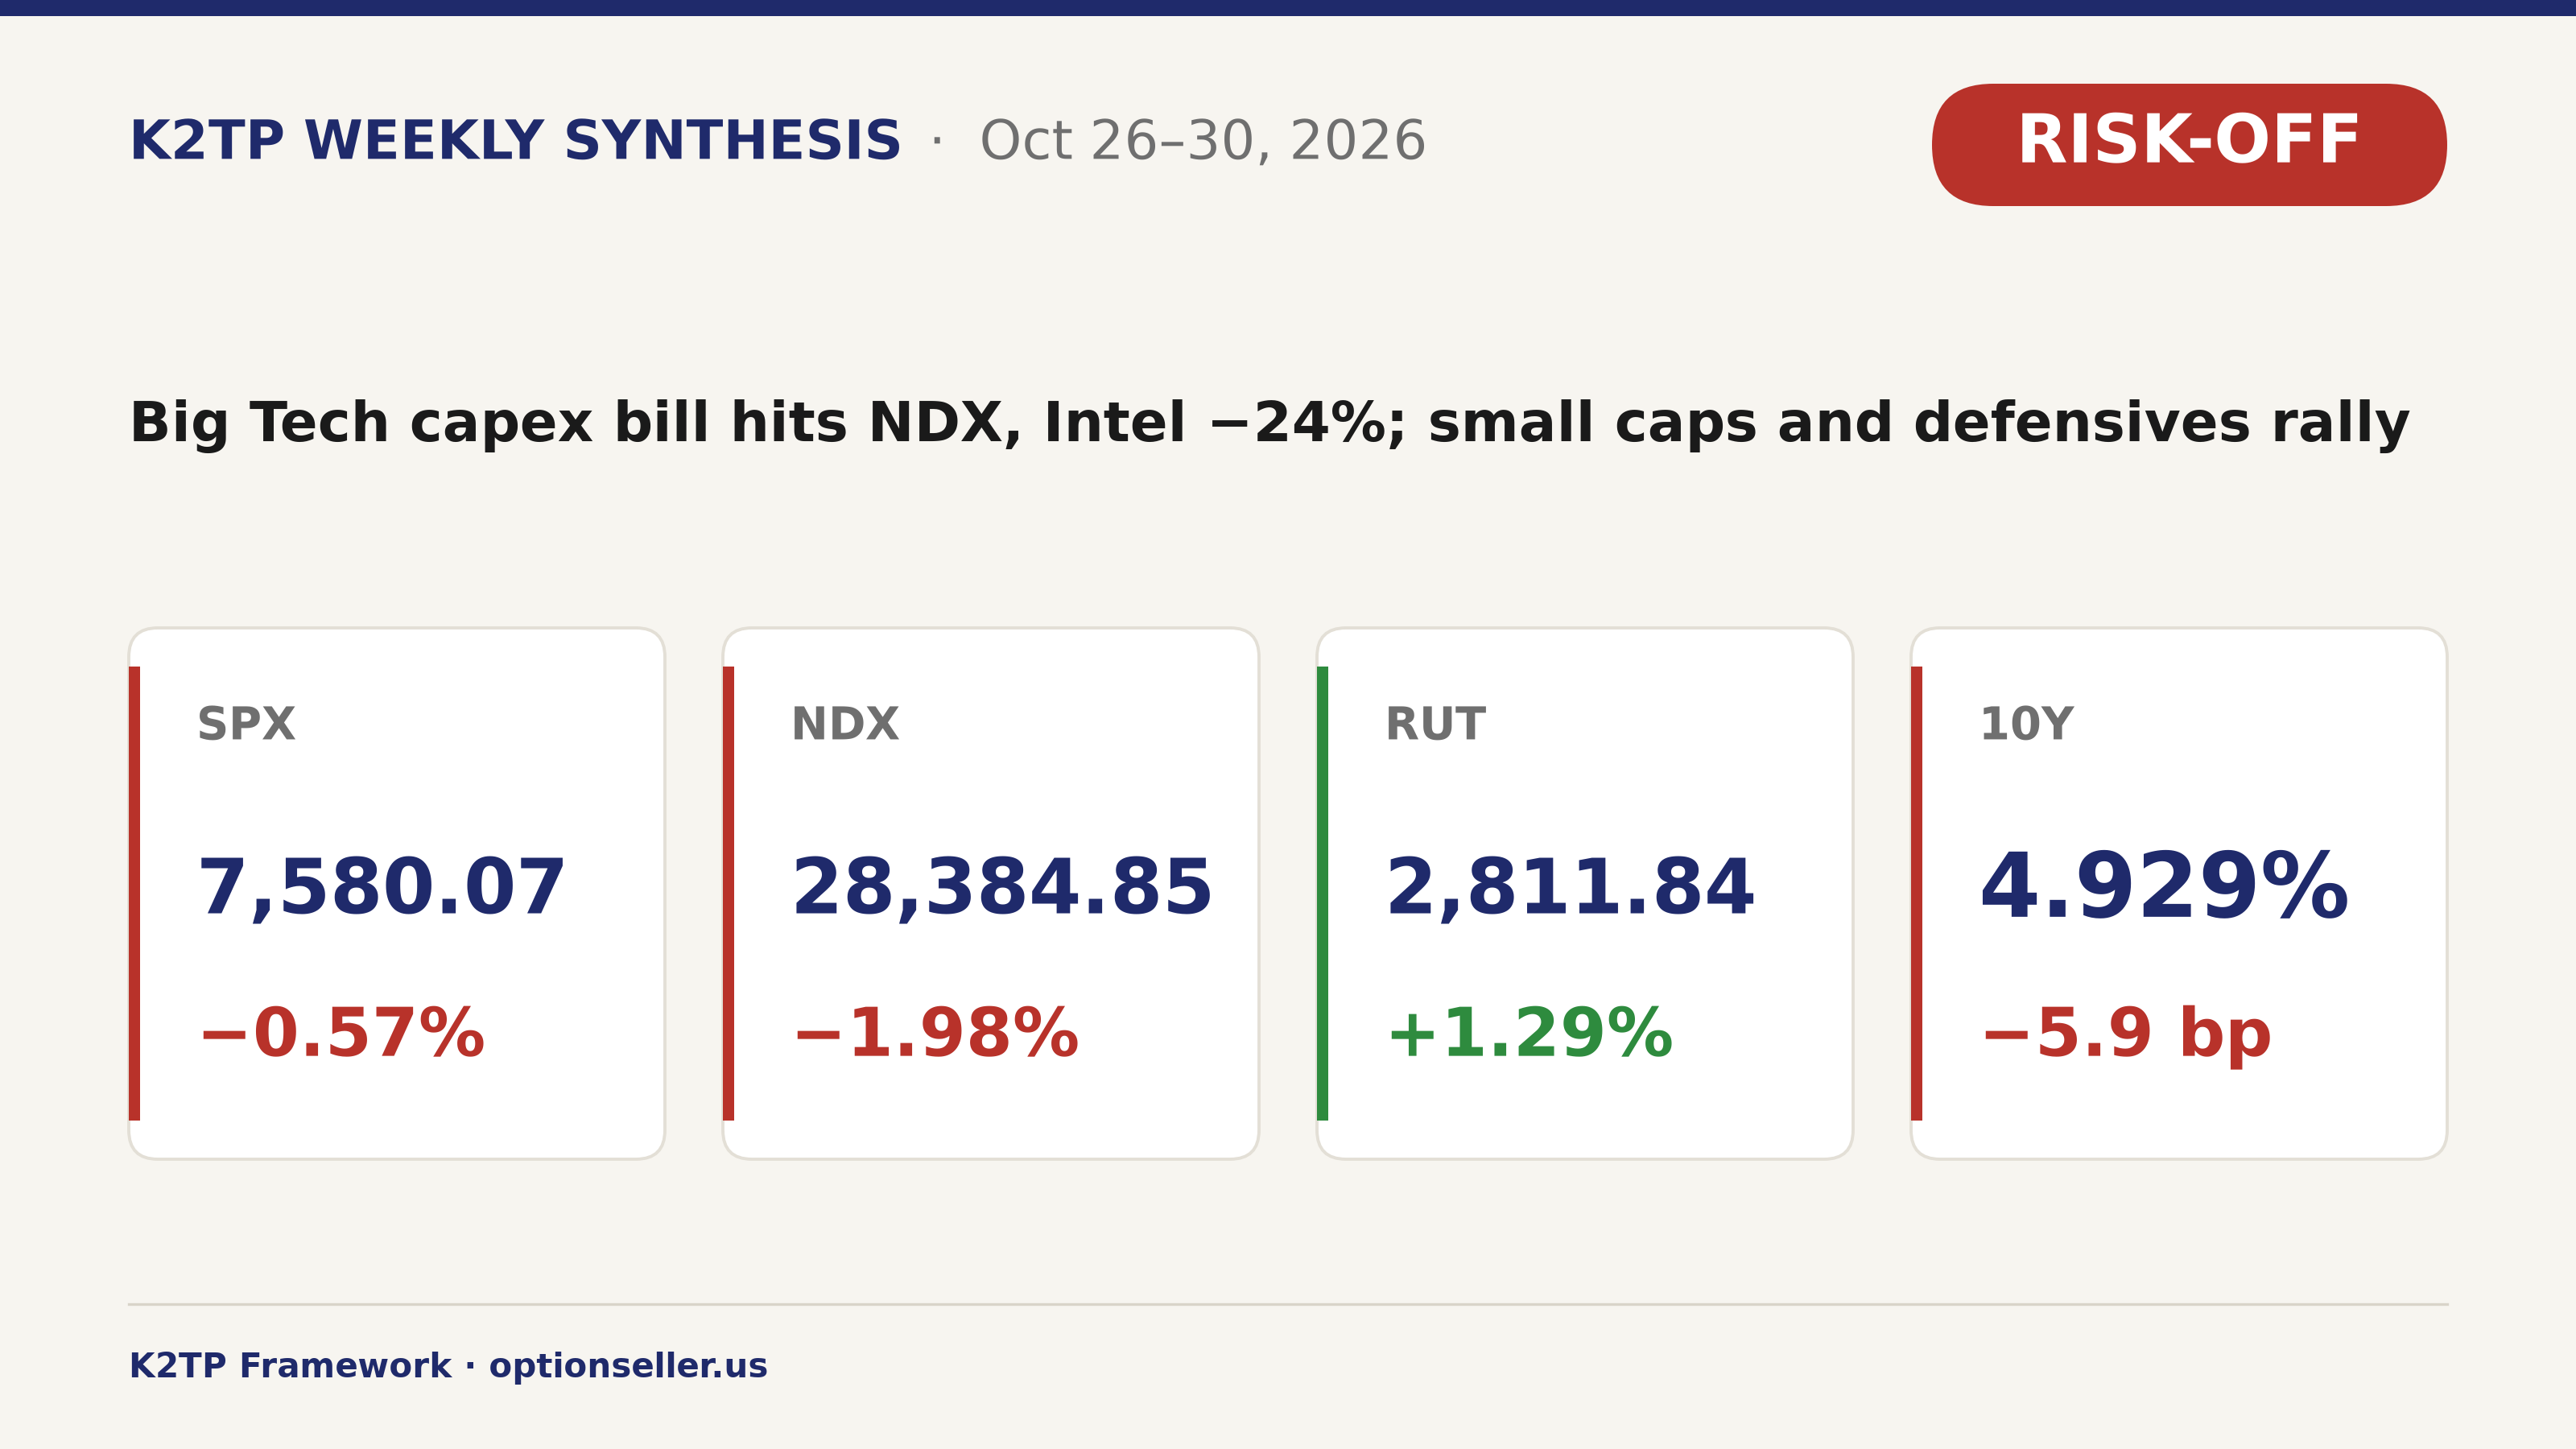
SPX −0.57%, NDX −1.98%, RUT +1.29%, VIX −0.15%, 10Y −5.9 bp. Chips rallied into Wednesday on Anthropic and Broadcom, then Alphabet, Amazon and Intel turned AI capex back into the market's main fear; the regime ends the week RISK-OFF.
WEEK'S KEY HEADLINES
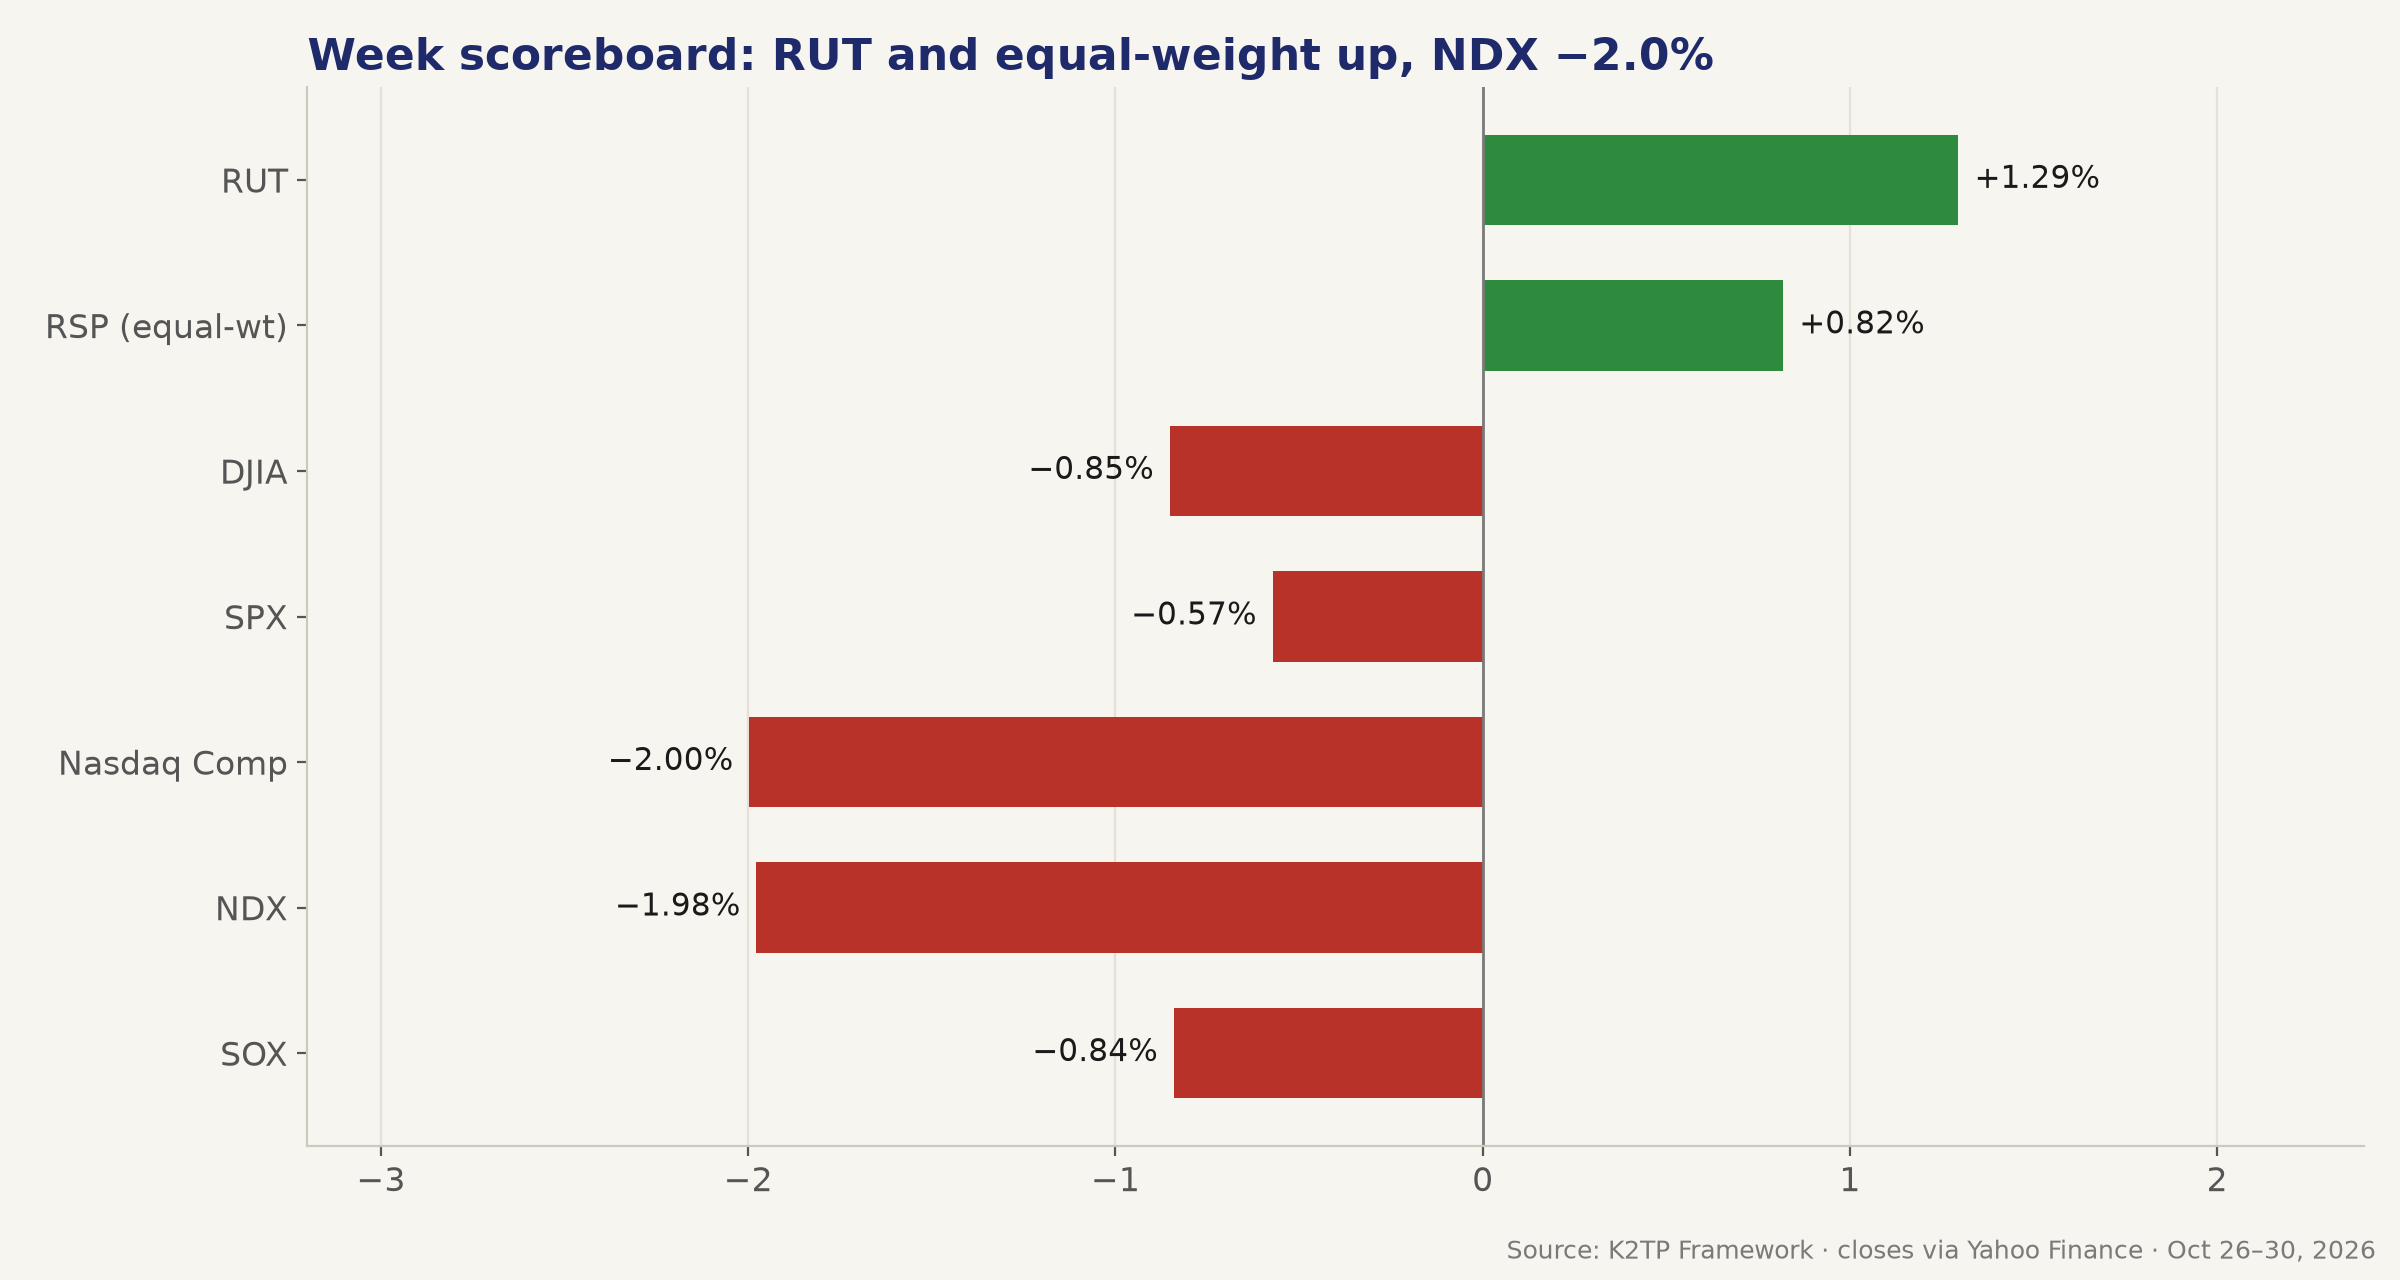
- SPX −0.57% to 7,580.07, its third straight weekly loss and lowest close of October; NDX −1.98%, Nasdaq Composite −2.00%, DJIA −0.85%
- RUT +1.29% and equal-weight RSP +0.82% beat SPX again: a second straight rotation week out of mega-cap tech
- SPX rose three days to 7,743.98 on Wednesday (week high 7,758.43 at 11:40 AM PT, right after the FOMC), then fell Thursday and −1.82% on Friday, its worst day since June
- AI swung both ways: Anthropic's S-1 and a $63B Broadcom chip financing lifted SOX +2.82% and +3.60% Mon–Tue; Friday SOX −7.20% after Intel's guide. SOX −0.84% for the week
- Earnings: Microsoft rallied on Azure +48%; Alphabet (FCF −$9.07B) and Amazon ($77.3B quarterly capex) were sold; Intel −28.58% Friday on a weak Q4 guide. Week: INTC −24.38%, GOOGL −12.61%
- FOMC held at 3.75%–4.00% on a 10-2 vote with two hike dissents; Friday, Dallas Fed's Logan called for at least two more hikes
- Data held up: Q3 GDP 3.4% vs 3.2%, PCE and core PCE in line (3.6% / 3.1% y/y), claims 194K, consumer confidence 91.7 vs 81
- 10Y −5.9 bp to 4.929% after topping 5.04% on FOMC day; WTI $103.27 → $104.12, with one settle under $100 on Tuesday; expiring December Brent $117.64
- Sectors: 9 of 11 up; XLV +3.12%, XLB +2.79%, XLU +2.04% led; XLC −5.32% and XLK −2.03% lagged
- VIX 19.45 → 19.42, but the range was 16.21 (Wed) to 23.93 (Fri)
- Regime: 🟡 TRANSITION (Mon) → 🟢 RISK-ON narrow (Tue–Wed) → 🟡 TRANSITION (Thu) → 🔴 RISK-OFF (Fri close)
- Weekend: Doha talks on a "two-day" Hormuz reopening plan, tanker incidents in the Gulf, OPEC+ holds December output. Monday: oil −4%, ISM Manufacturing 55.5 beat, SPX back above the weekly pivot. See WEEKEND DEVELOPMENTS
THE WEEK DAY BY DAY
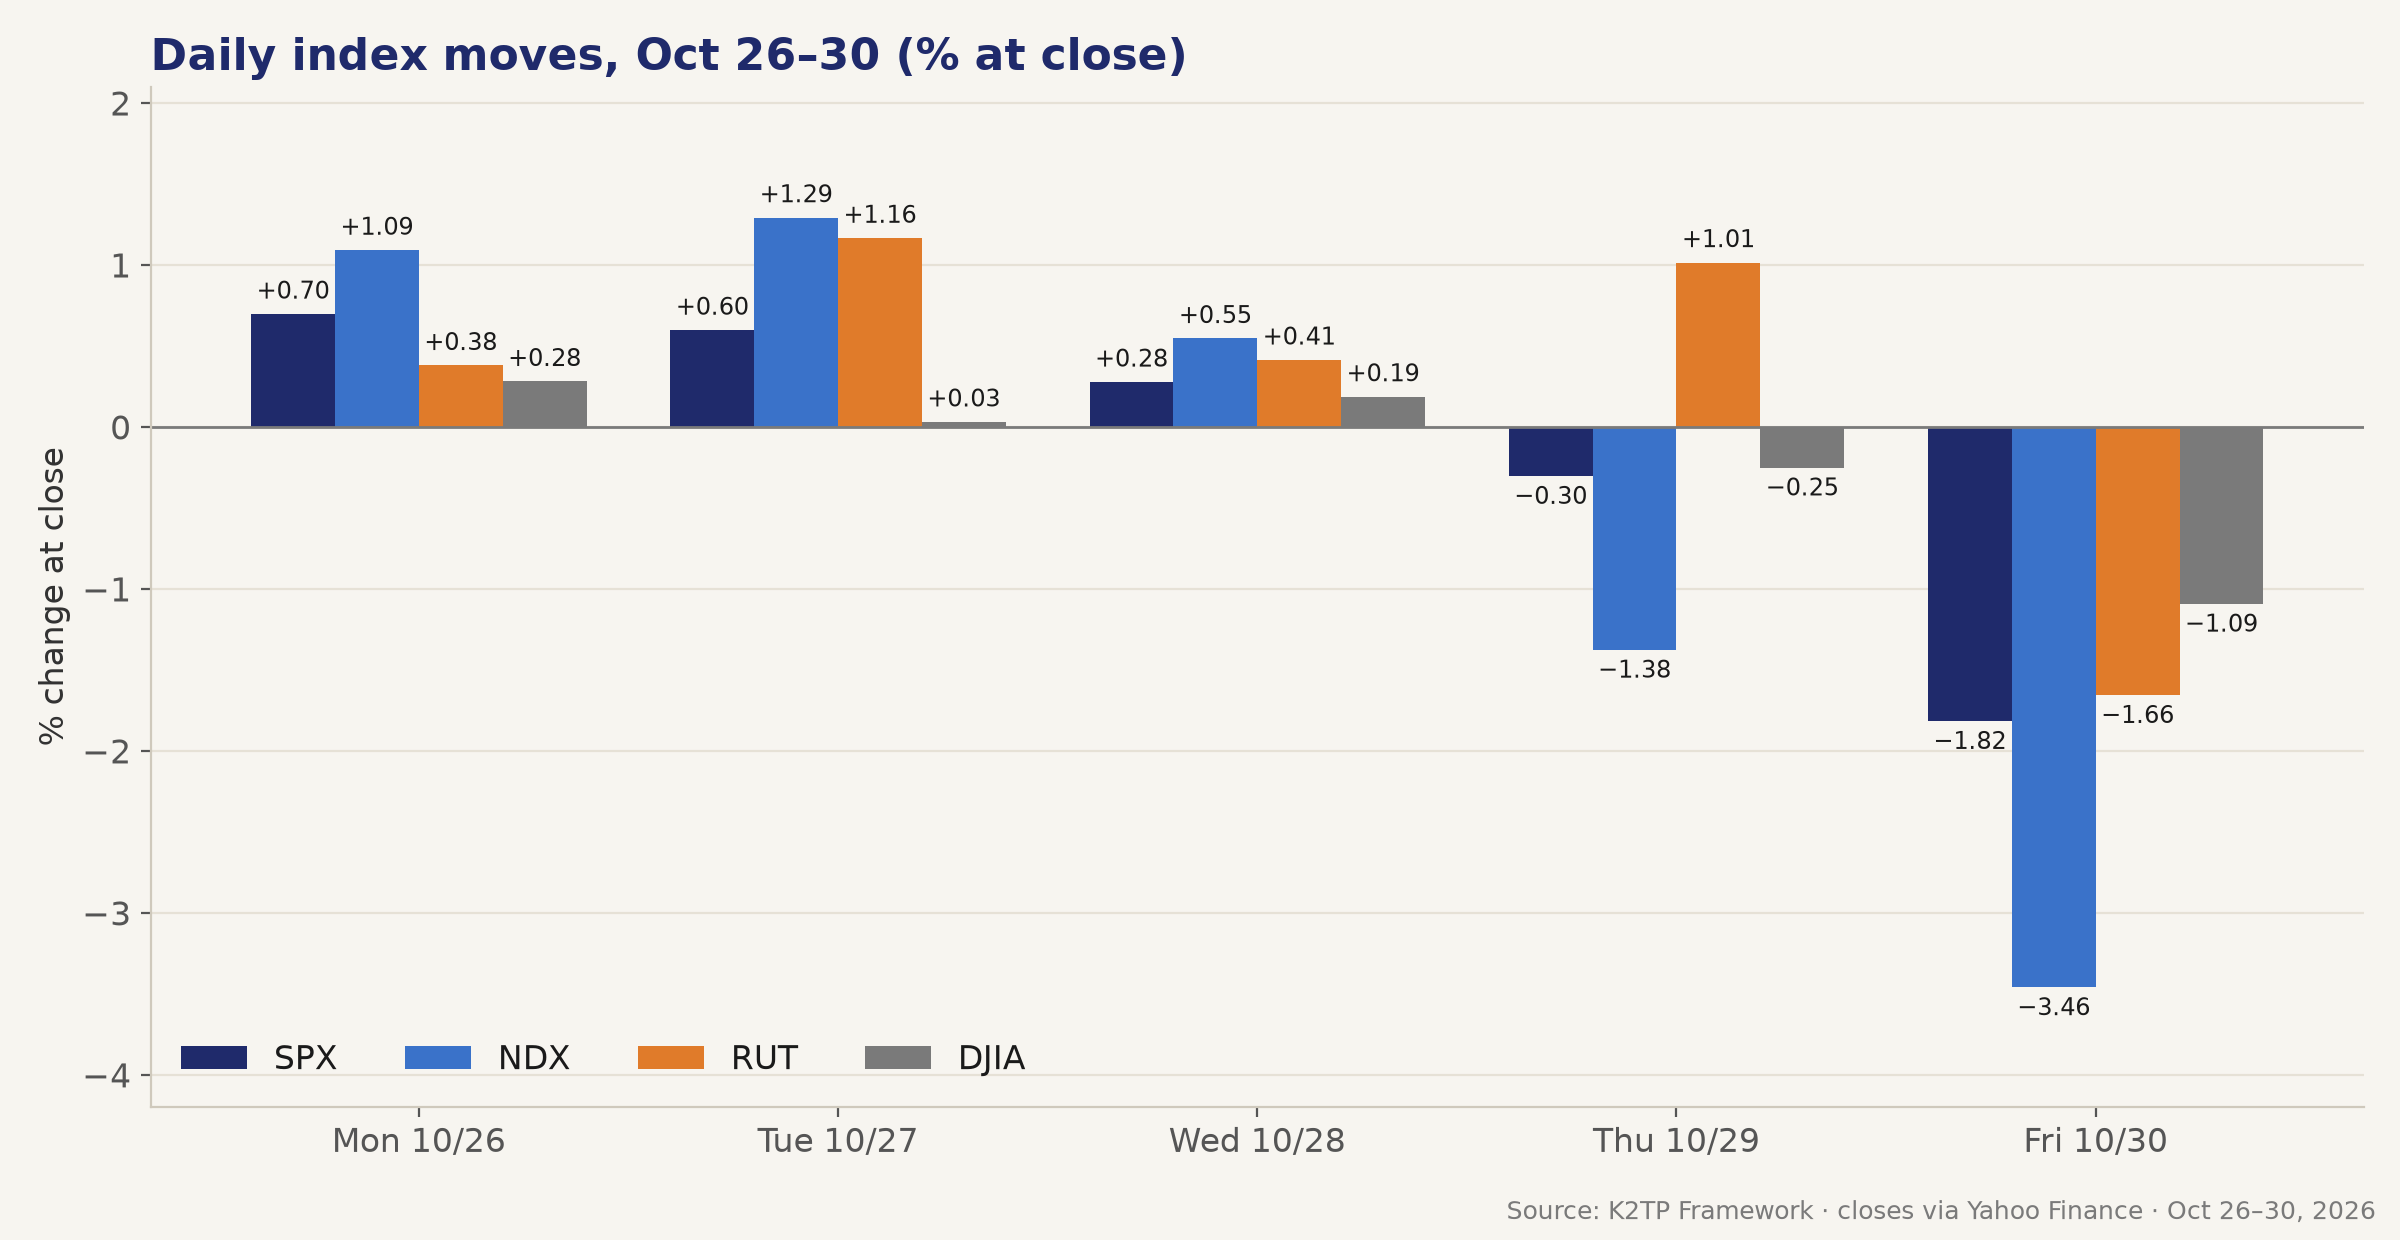
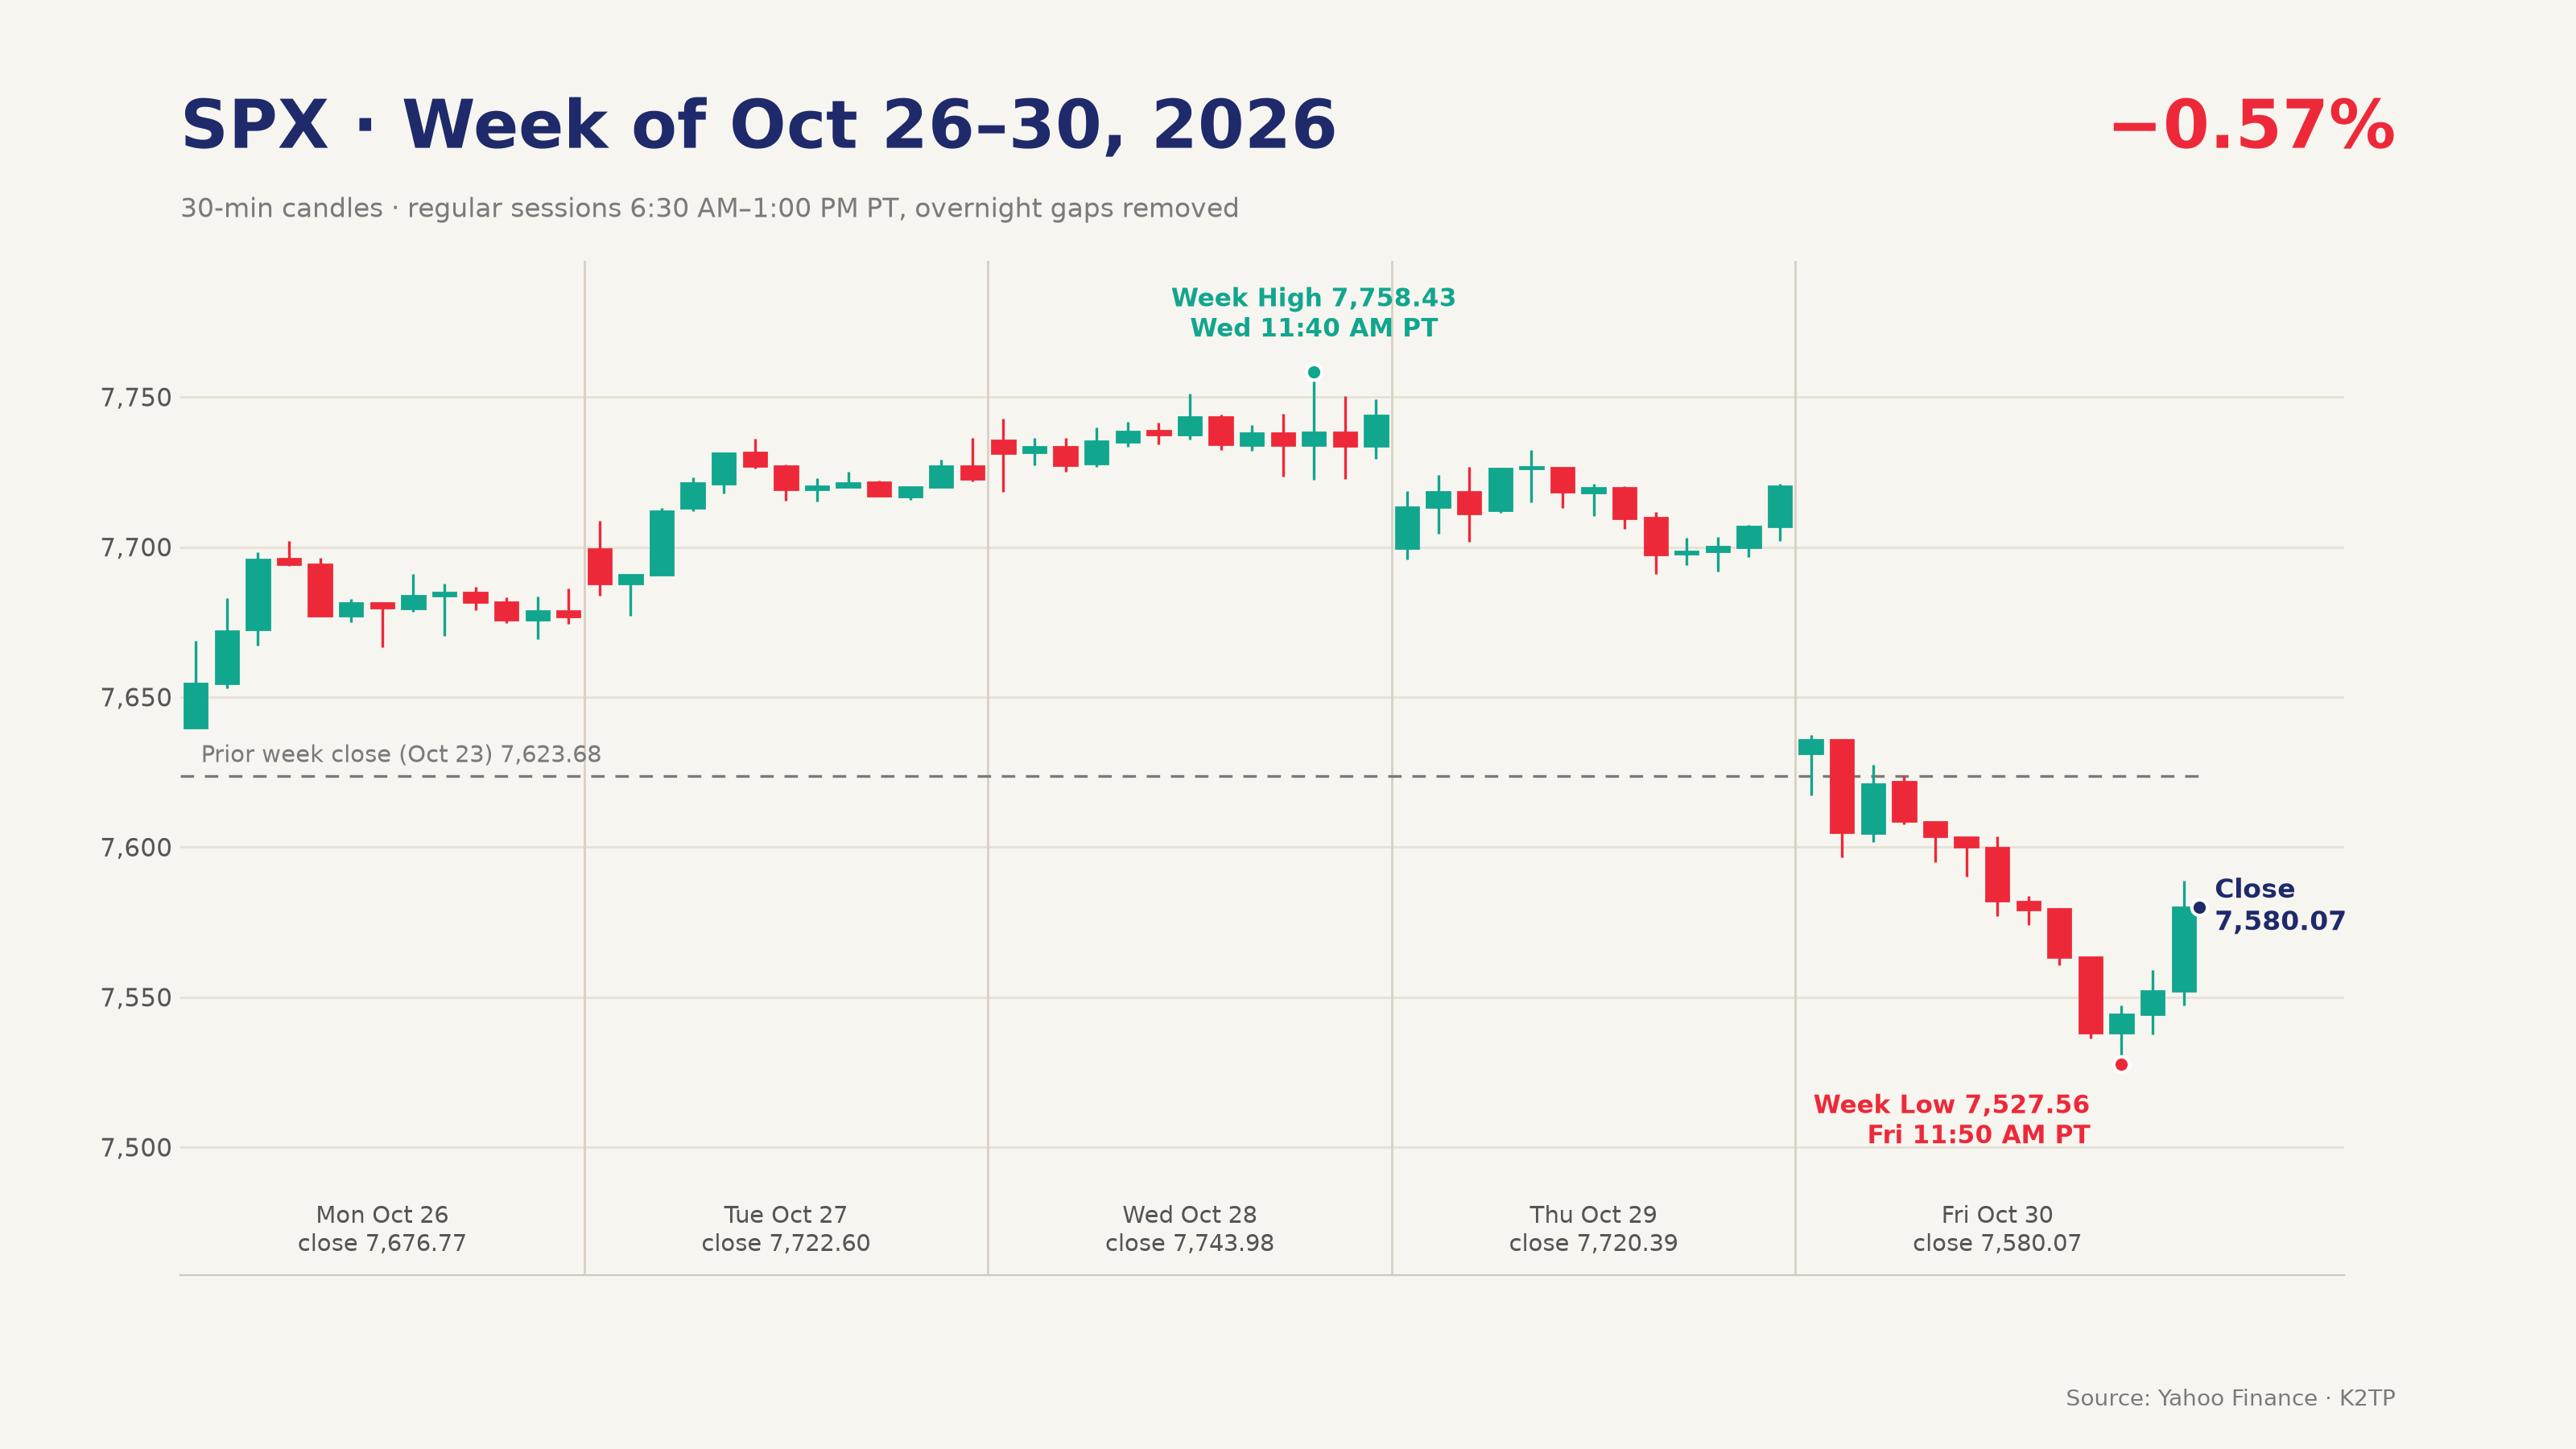
| Day | SPX | NDX | RUT | VIX | 10Y | Regime | Driver |
|---|---|---|---|---|---|---|---|
| Mon 10/26 | 7,676.77 (+0.70%) | +1.09% | +0.38% | 18.39 | 4.986% | 🟡 | Anthropic S-1 lifts chips; Meta's $95B equity plan; Brazil −20% |
| Tue 10/27 | 7,722.60 (+0.60%) | +1.29% | +1.16% | 17.52 | 4.993% | 🟢 | $63B Broadcom–Anthropic financing, SOX +3.60%; BA −10.69% |
| Wed 10/28 | 7,743.98 (+0.28%) | +0.55% | +0.41% | 16.91 | 5.045% | 🟢 | FOMC hold 10-2; ORCL +10.73%; GOOGL −10% after hours |
| Thu 10/29 | 7,720.39 (−0.30%) | −1.38% | +1.01% | 17.20 | 4.989% | 🟡 | GOOGL −12.64%, NOW −26.95%; RSP +1.20%; GDP 3.4% |
| Fri 10/30 | 7,580.07 (−1.82%) | −3.46% | −1.66% | 19.42 | 4.929% | 🔴 | Intel −28.58%, SOX −7.20%; Logan wants two more hikes |
- Mon–Wed: three up days, but narrow. RSP was +0.11% Tuesday and −0.04% Wednesday while SPX rose
- Thursday: the index dipped only 0.30%, yet 9 of 11 sectors rose and RSP beat SPX by 150 bp. That was money leaving tech, not leaving stocks
- Friday: the chip crash and Logan's hawkish comments broke the rotation; even RUT fell 1.66%. SPX closed below the 7,590.19 midday low
→ The same story as the week before, but sharper: AI demand is strong, but the bill for AI capex now lands in free cash flow, and the market sells the megacaps that pay it.
AI AND SEMIS: FROM ANTHROPIC EUPHORIA TO INTEL'S CRASH
- Monday: Anthropic filed its S-1 to list on the Nasdaq as "ANT", with $16.29B of first-half revenue (+1,304%); SOX +2.82%. Meta plans to raise up to $95B in equity for AI; META −1.88% 🟢
- Tuesday: banks are providing $63B to fund Anthropic's purchase of Broadcom chips; SOX +3.60%, AMD +5.45%, AVGO +4.00%. Oracle expanded its OpenAI, Google TPU and Nvidia deals 🟢
- Wednesday: ORCL +10.73% after reaffirming FY2027 revenue of at least $90B; SK Hynix's record quarter lifted memory (MU +5.86%, LRCX +5.39%)
- Thursday: after-hours capex news drove the reversal: Alphabet −12.64% on negative free cash flow, ServiceNow −26.95%, Fortinet −20.09% 🔴
- Friday: Intel −28.58%, its worst day since the 1970s (CNBC), after a Q4 revenue guide of $15B–$16B vs $17.1B. SOX −7.20%, AMD −10.88%, ARM −9.97%, TSM −5.95%, AVGO −5.48%, NVDA −4.22% 🔴
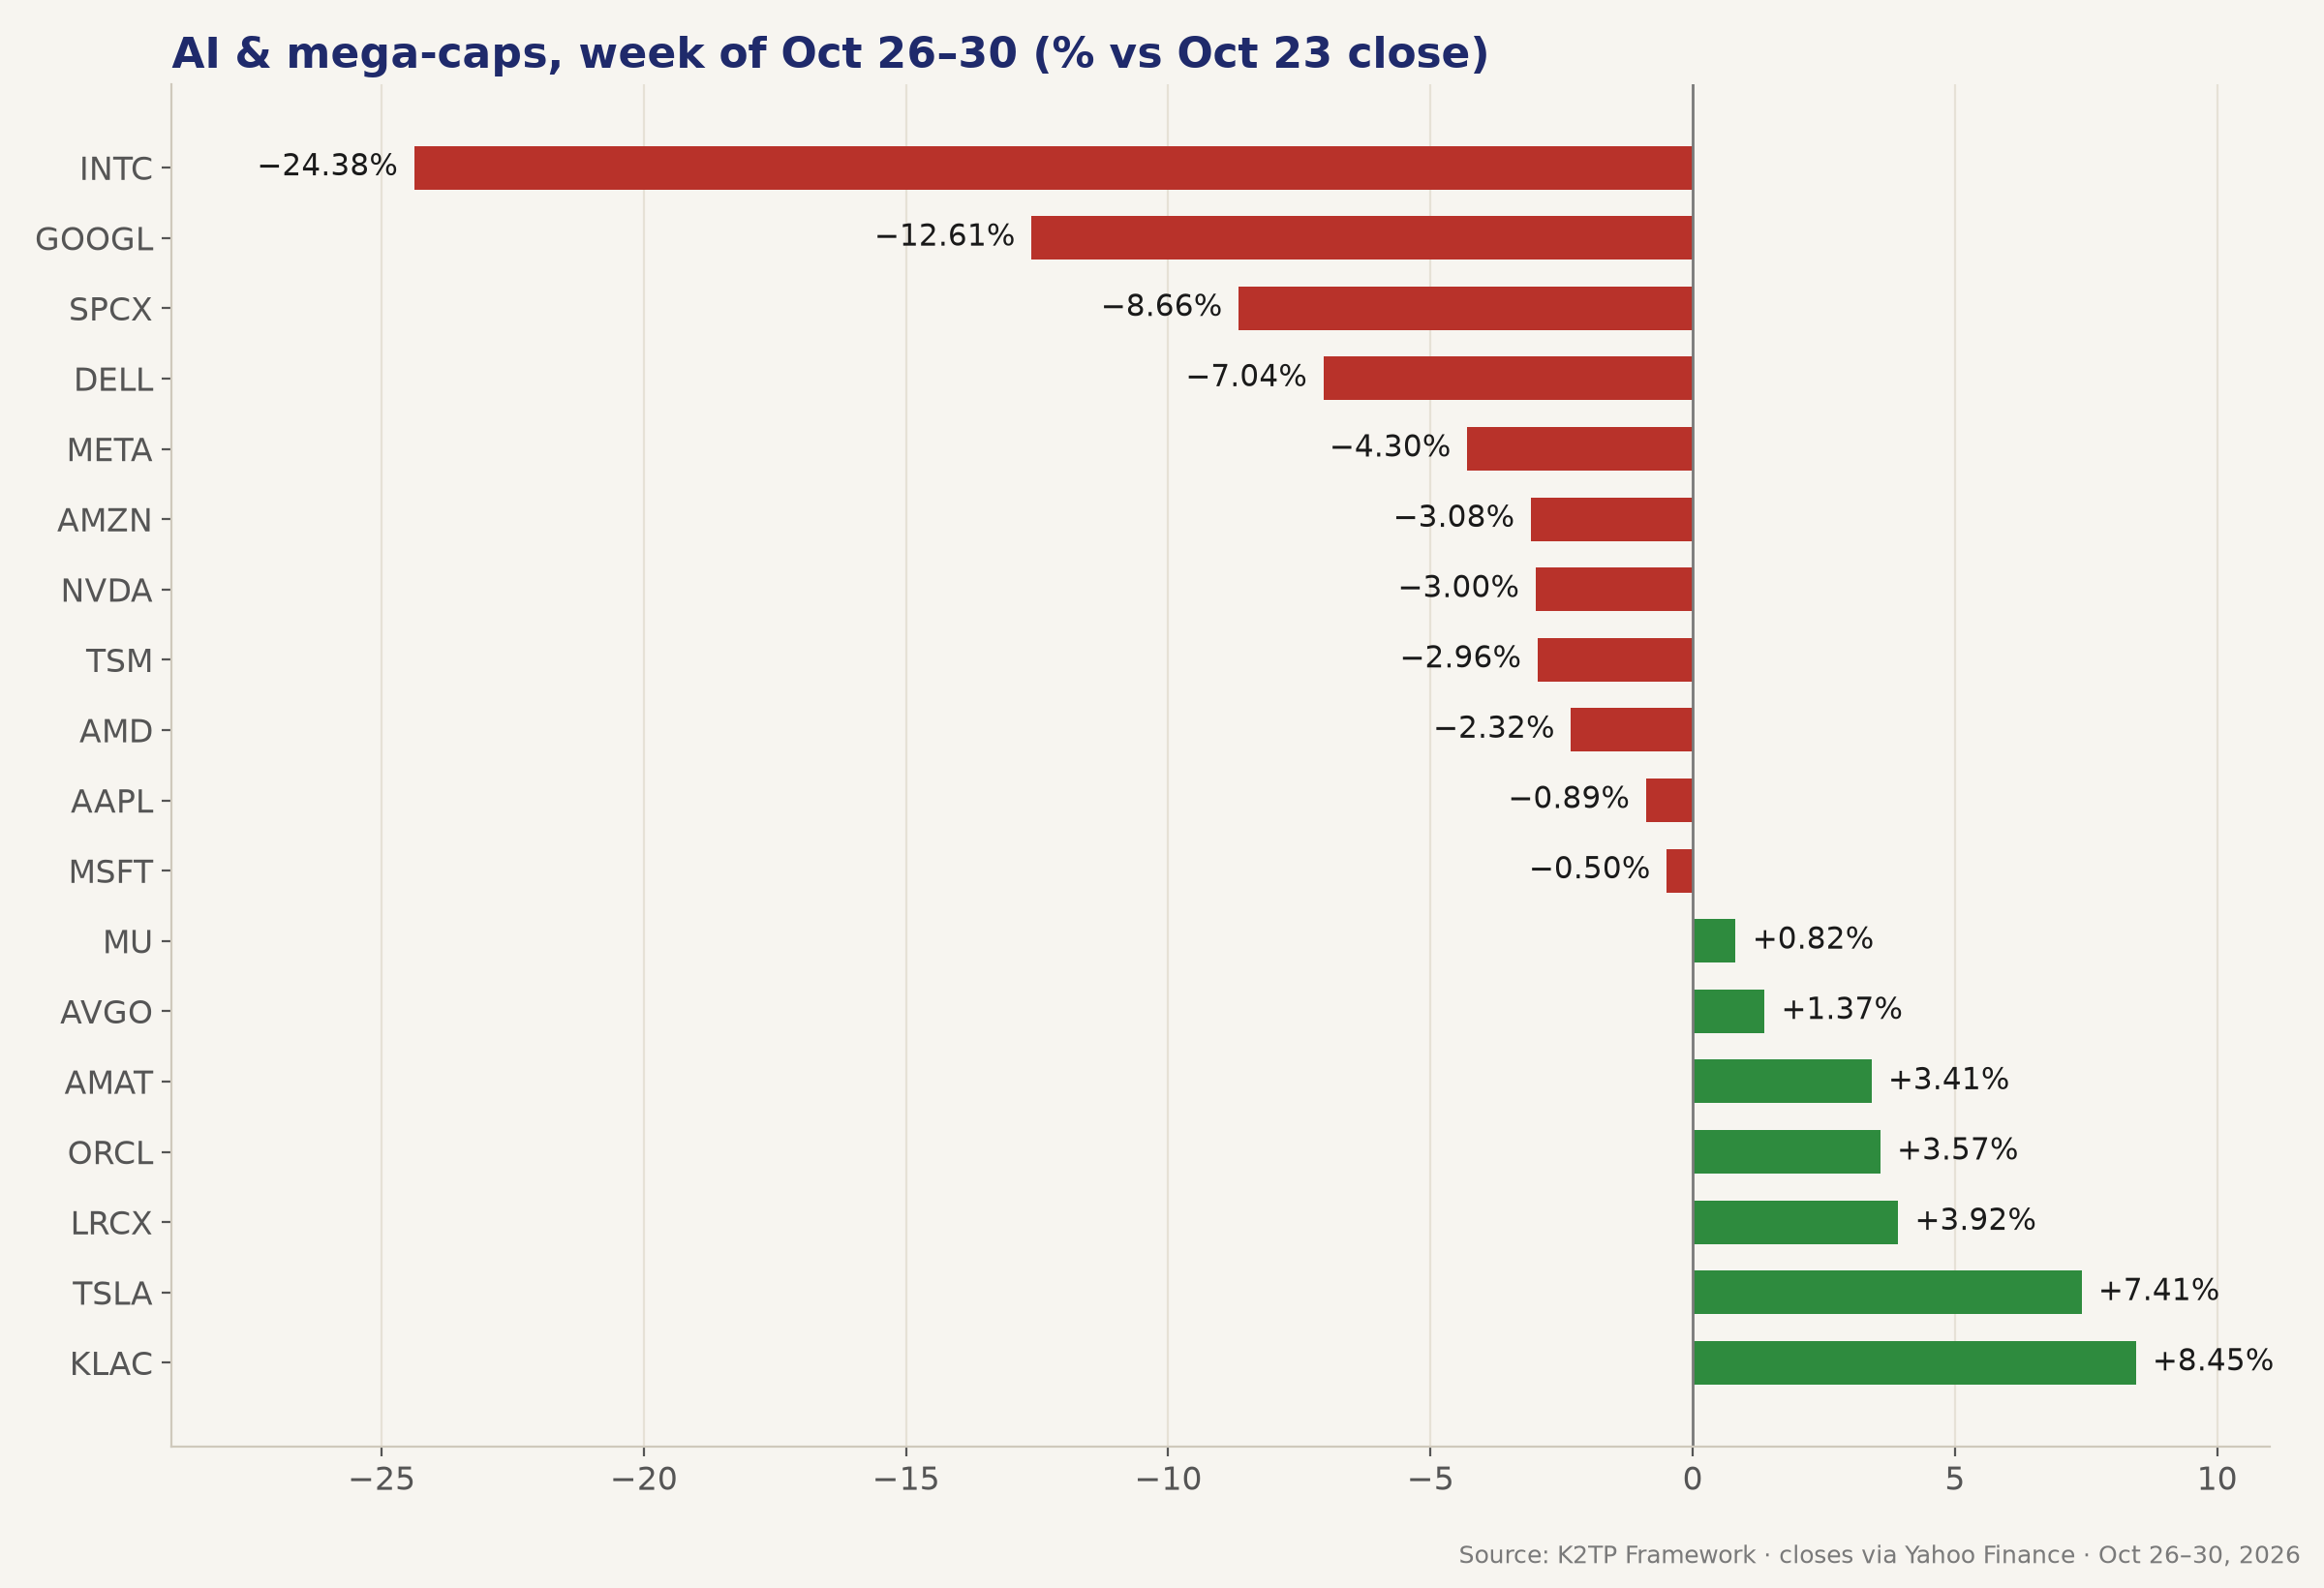
- Week: INTC −24.38%, GOOGL −12.61%, SPCX −8.66%, DELL −7.04%, META −4.30%, AMZN −3.08%, NVDA −3.00%; KLAC +8.45%, TSLA +7.41%, LRCX +3.92%, ORCL +3.57%, AMAT +3.41%. SOX −15.36% for October
→ Demand for compute is not the problem; Anthropic, Broadcom and Oracle proved it again. What hurts is who pays: when a megacap's free cash flow turns negative, the market sells it, and a weak guide like Intel's pulls down the whole chip complex.
EARNINGS: AZURE REWARDED, CAPEX PUNISHED
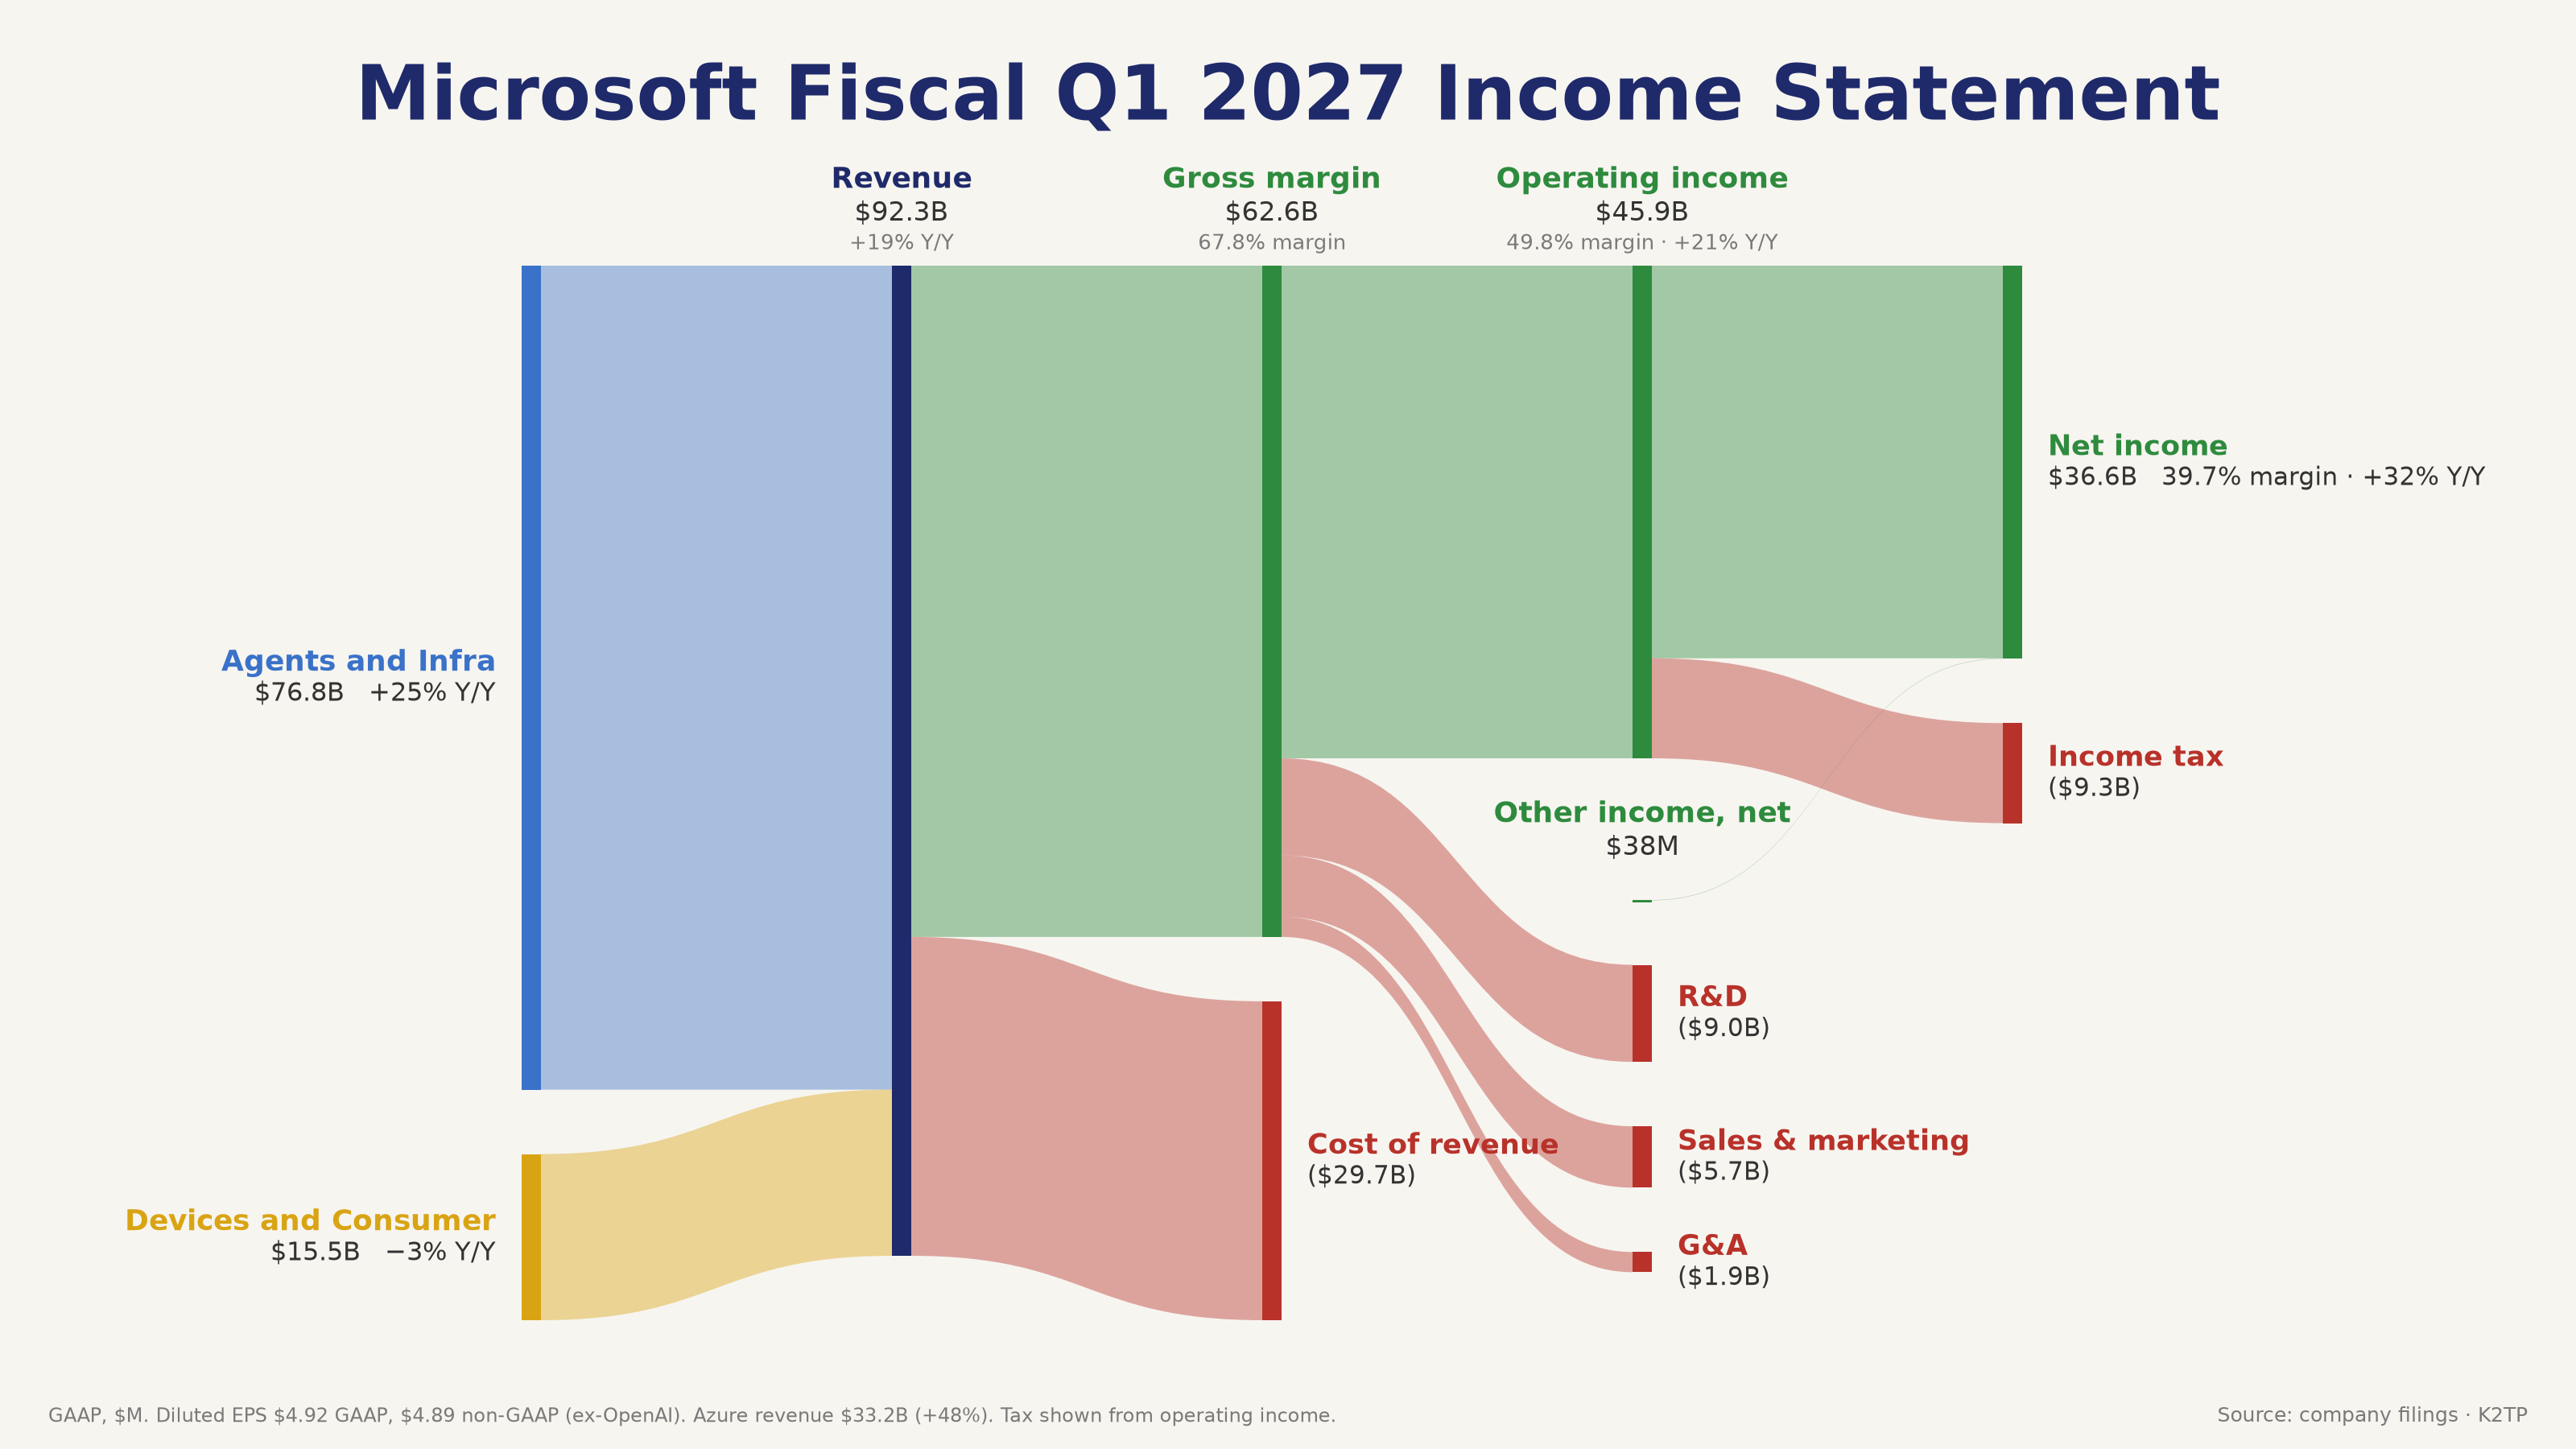
- Microsoft (Wed after the close, fiscal Q1 2027): revenue $92.28B (+19%) vs $90.69B expected; non-GAAP EPS $4.89 vs $4.73; Azure +48%. +2.88% after hours 🟢
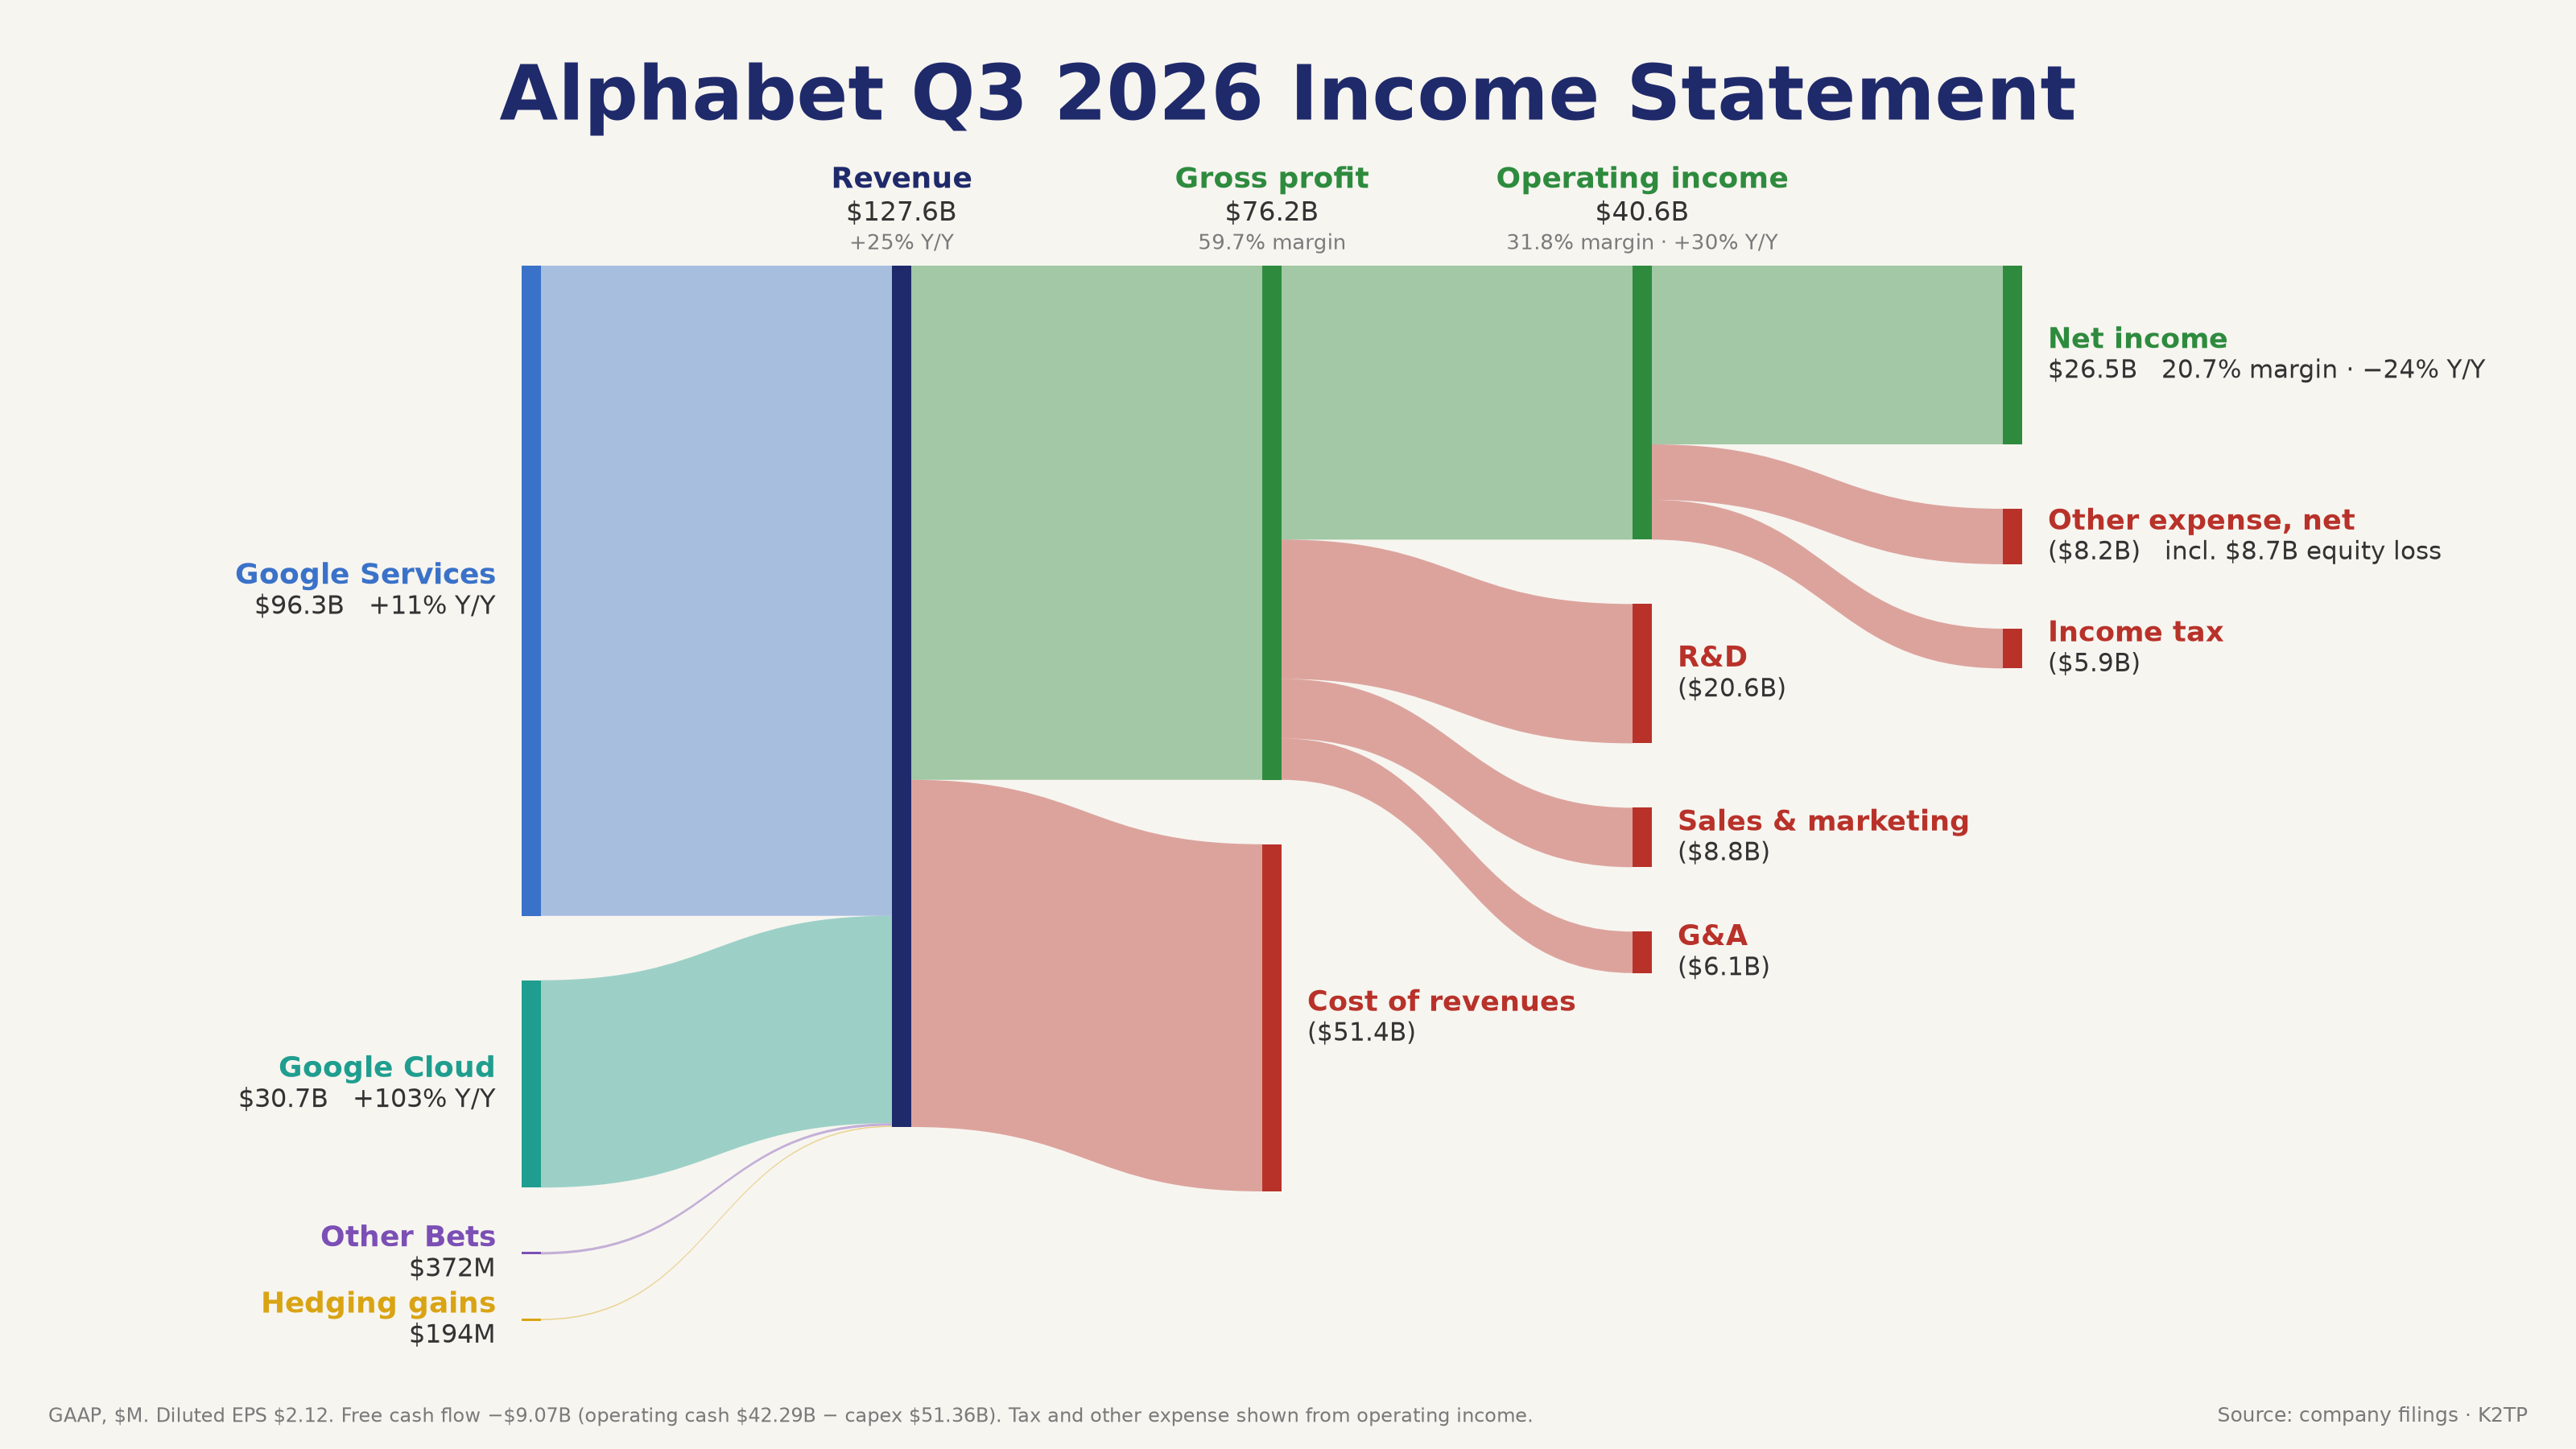
- Alphabet (Wed after the close): revenue $127.58B (+25%) vs $128.22B expected; EPS $2.67 excluding an $8.7B equity loss vs $3.02 expected; capex $51.36B and FCF −$9.07B. GOOGL −12.64% Thursday 🔴
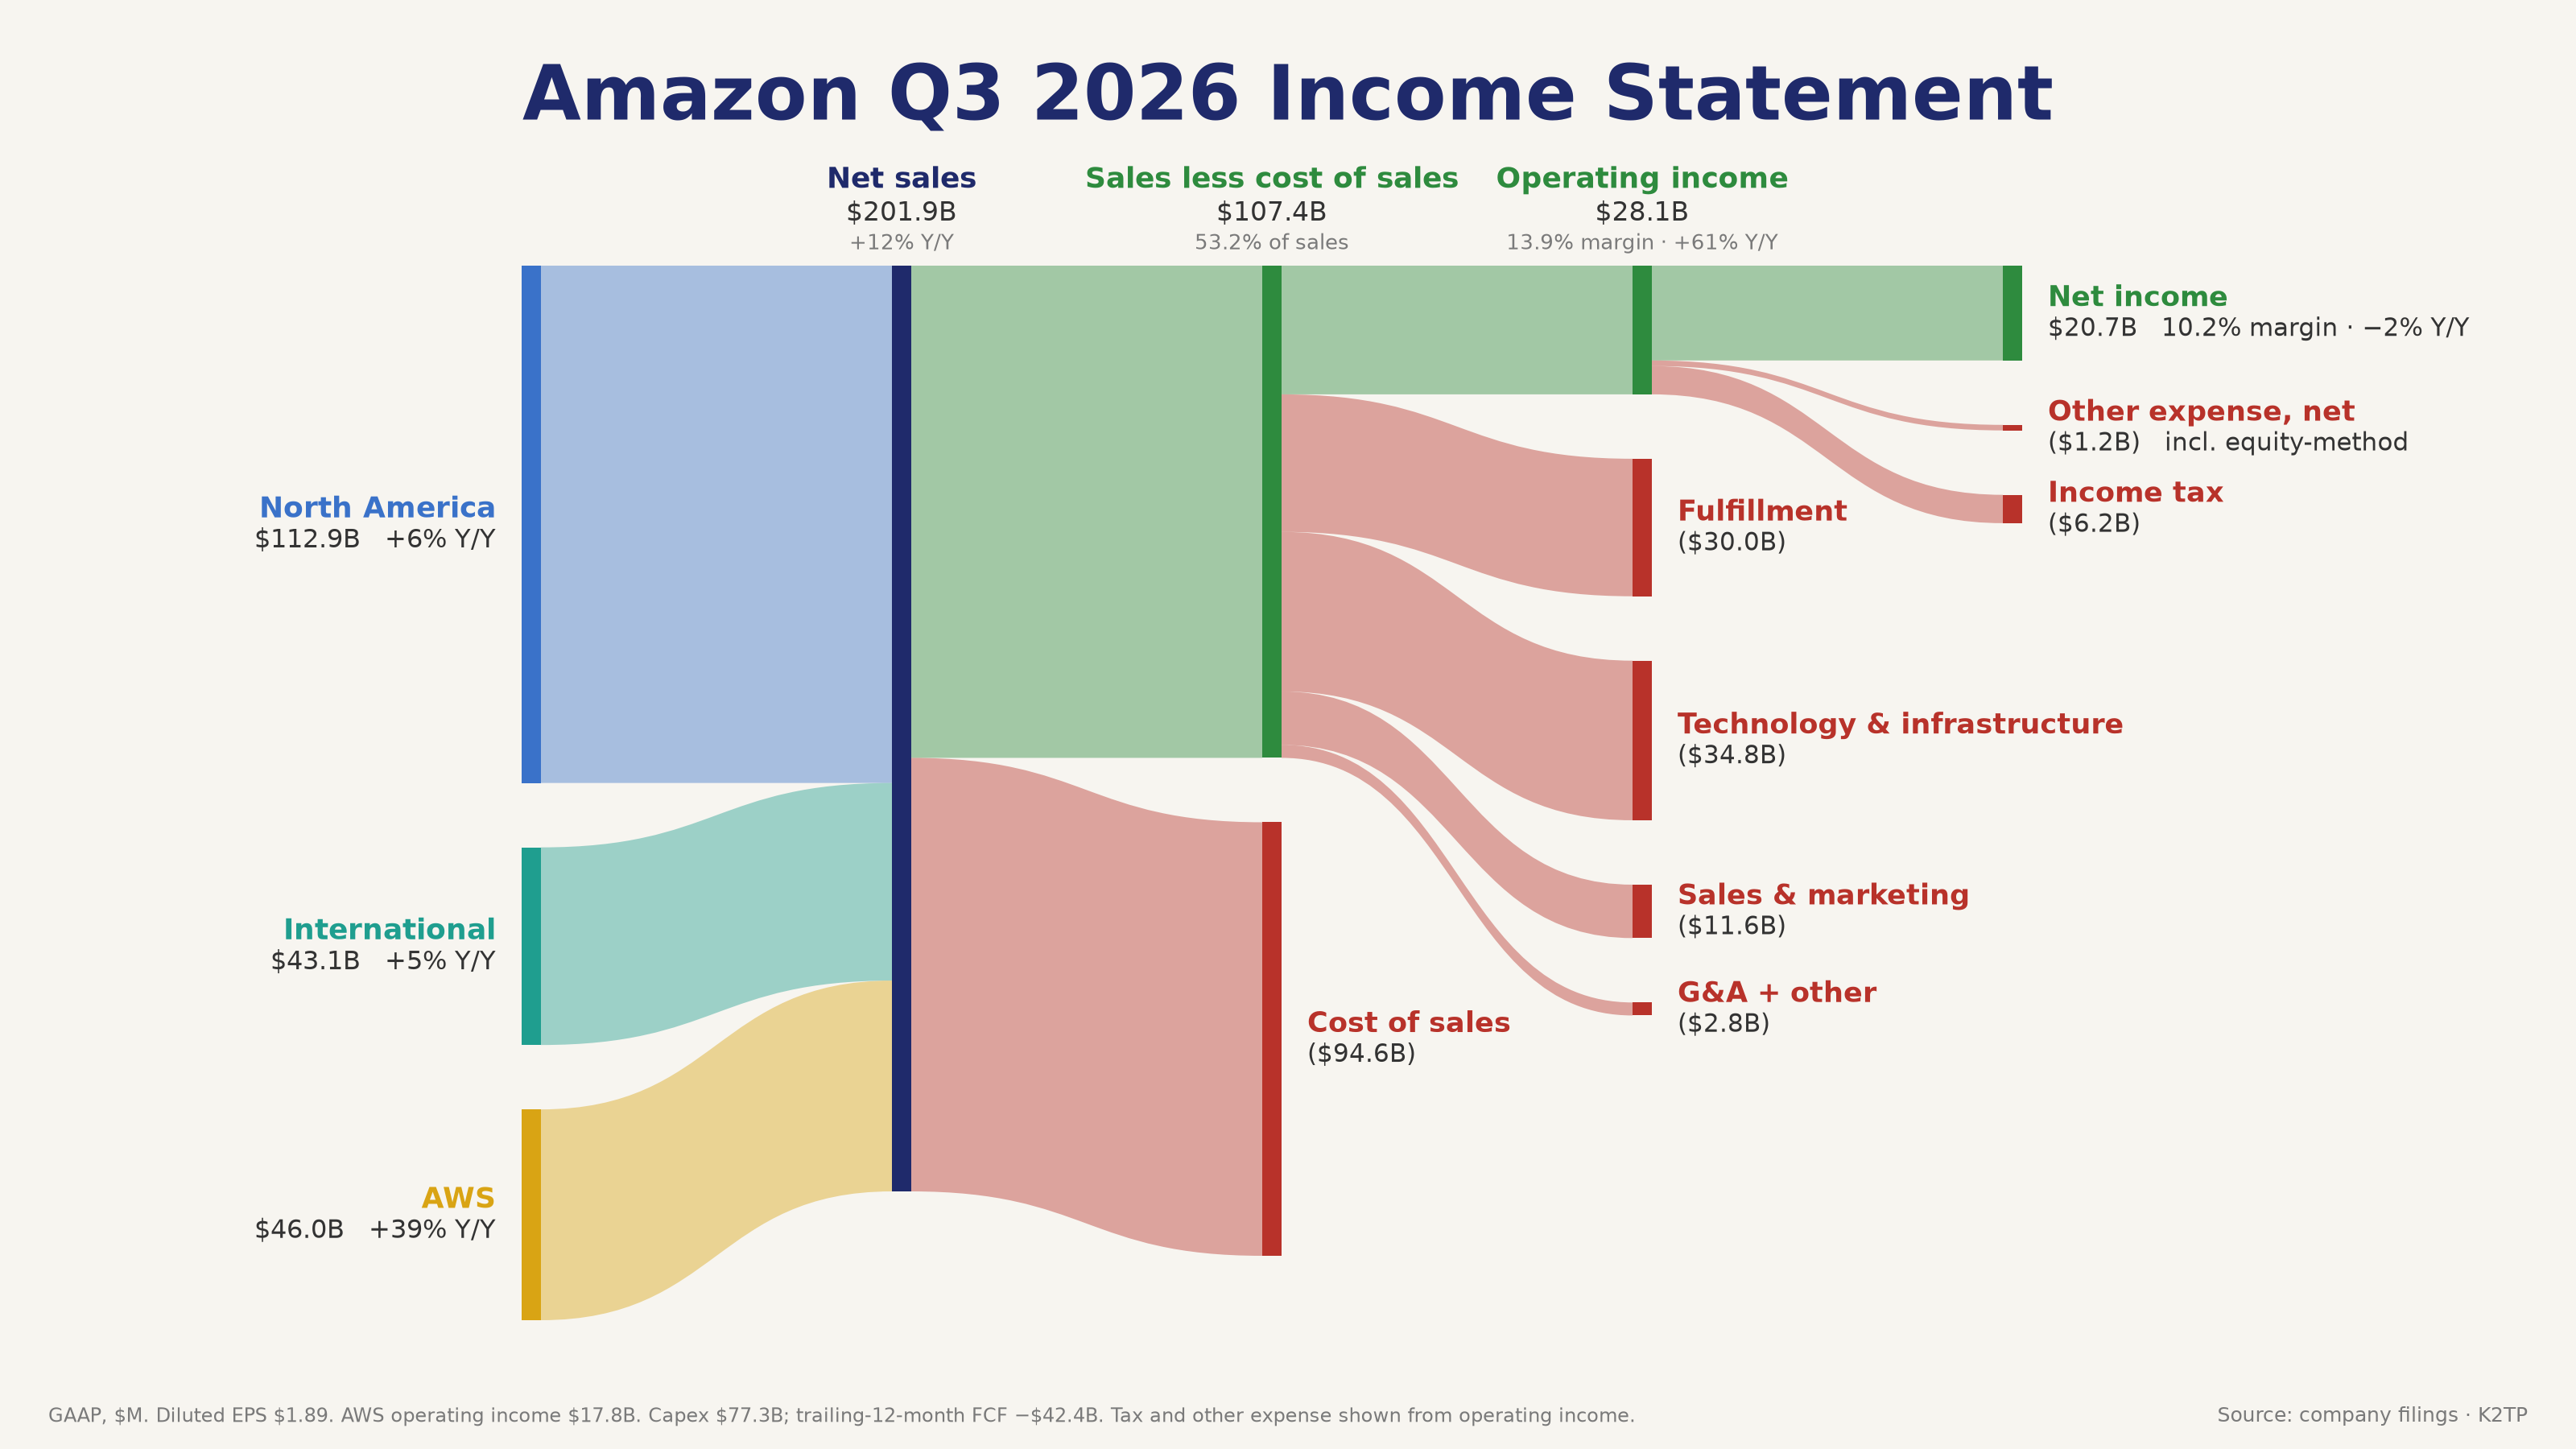
- Amazon (Thu after the close): net sales $201.94B vs $202.31B; EPS $1.89 vs $1.96; AWS +39% but quarterly capex $77.3B and trailing FCF −$42.4B. It recovered from −7.24% pre-market to close −1.41% Friday 🟡
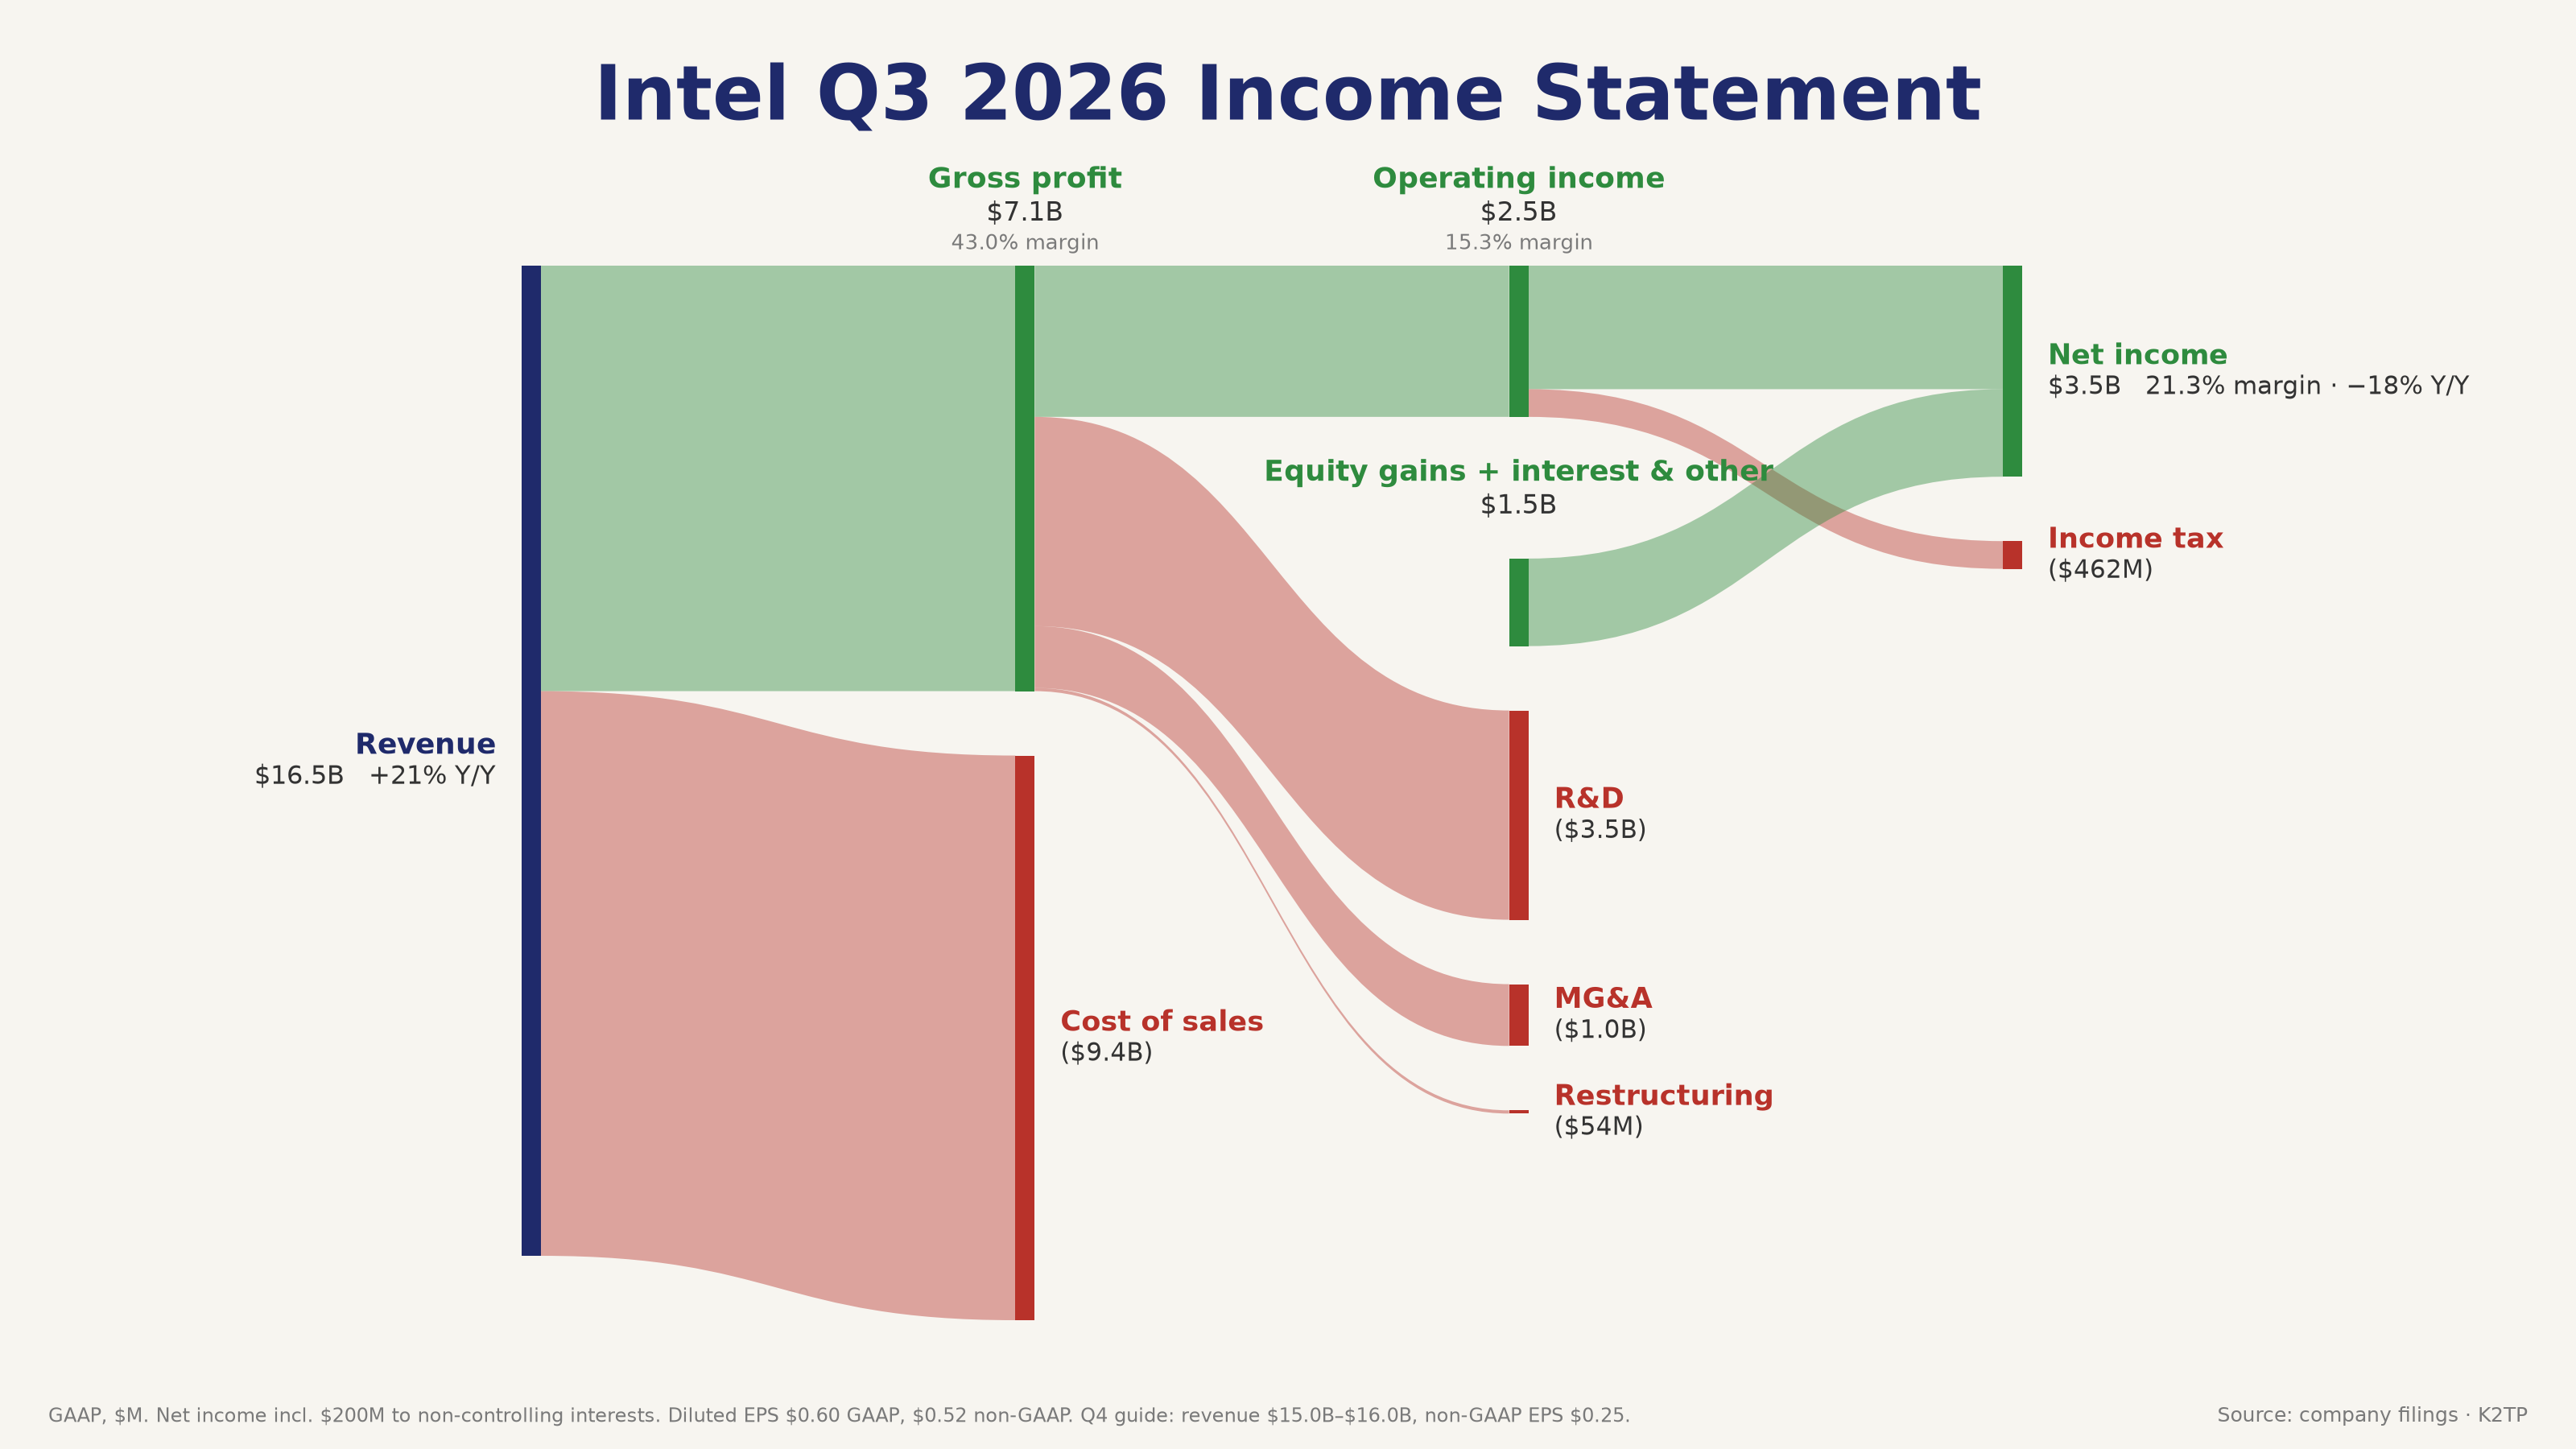
- Intel (Thu after the close): revenue $16.51B (+21%), non-GAAP EPS $0.52 vs $0.40, but a Q4 revenue guide of $15B–$16B vs $17.1B. INTC −28.58% Friday 🔴
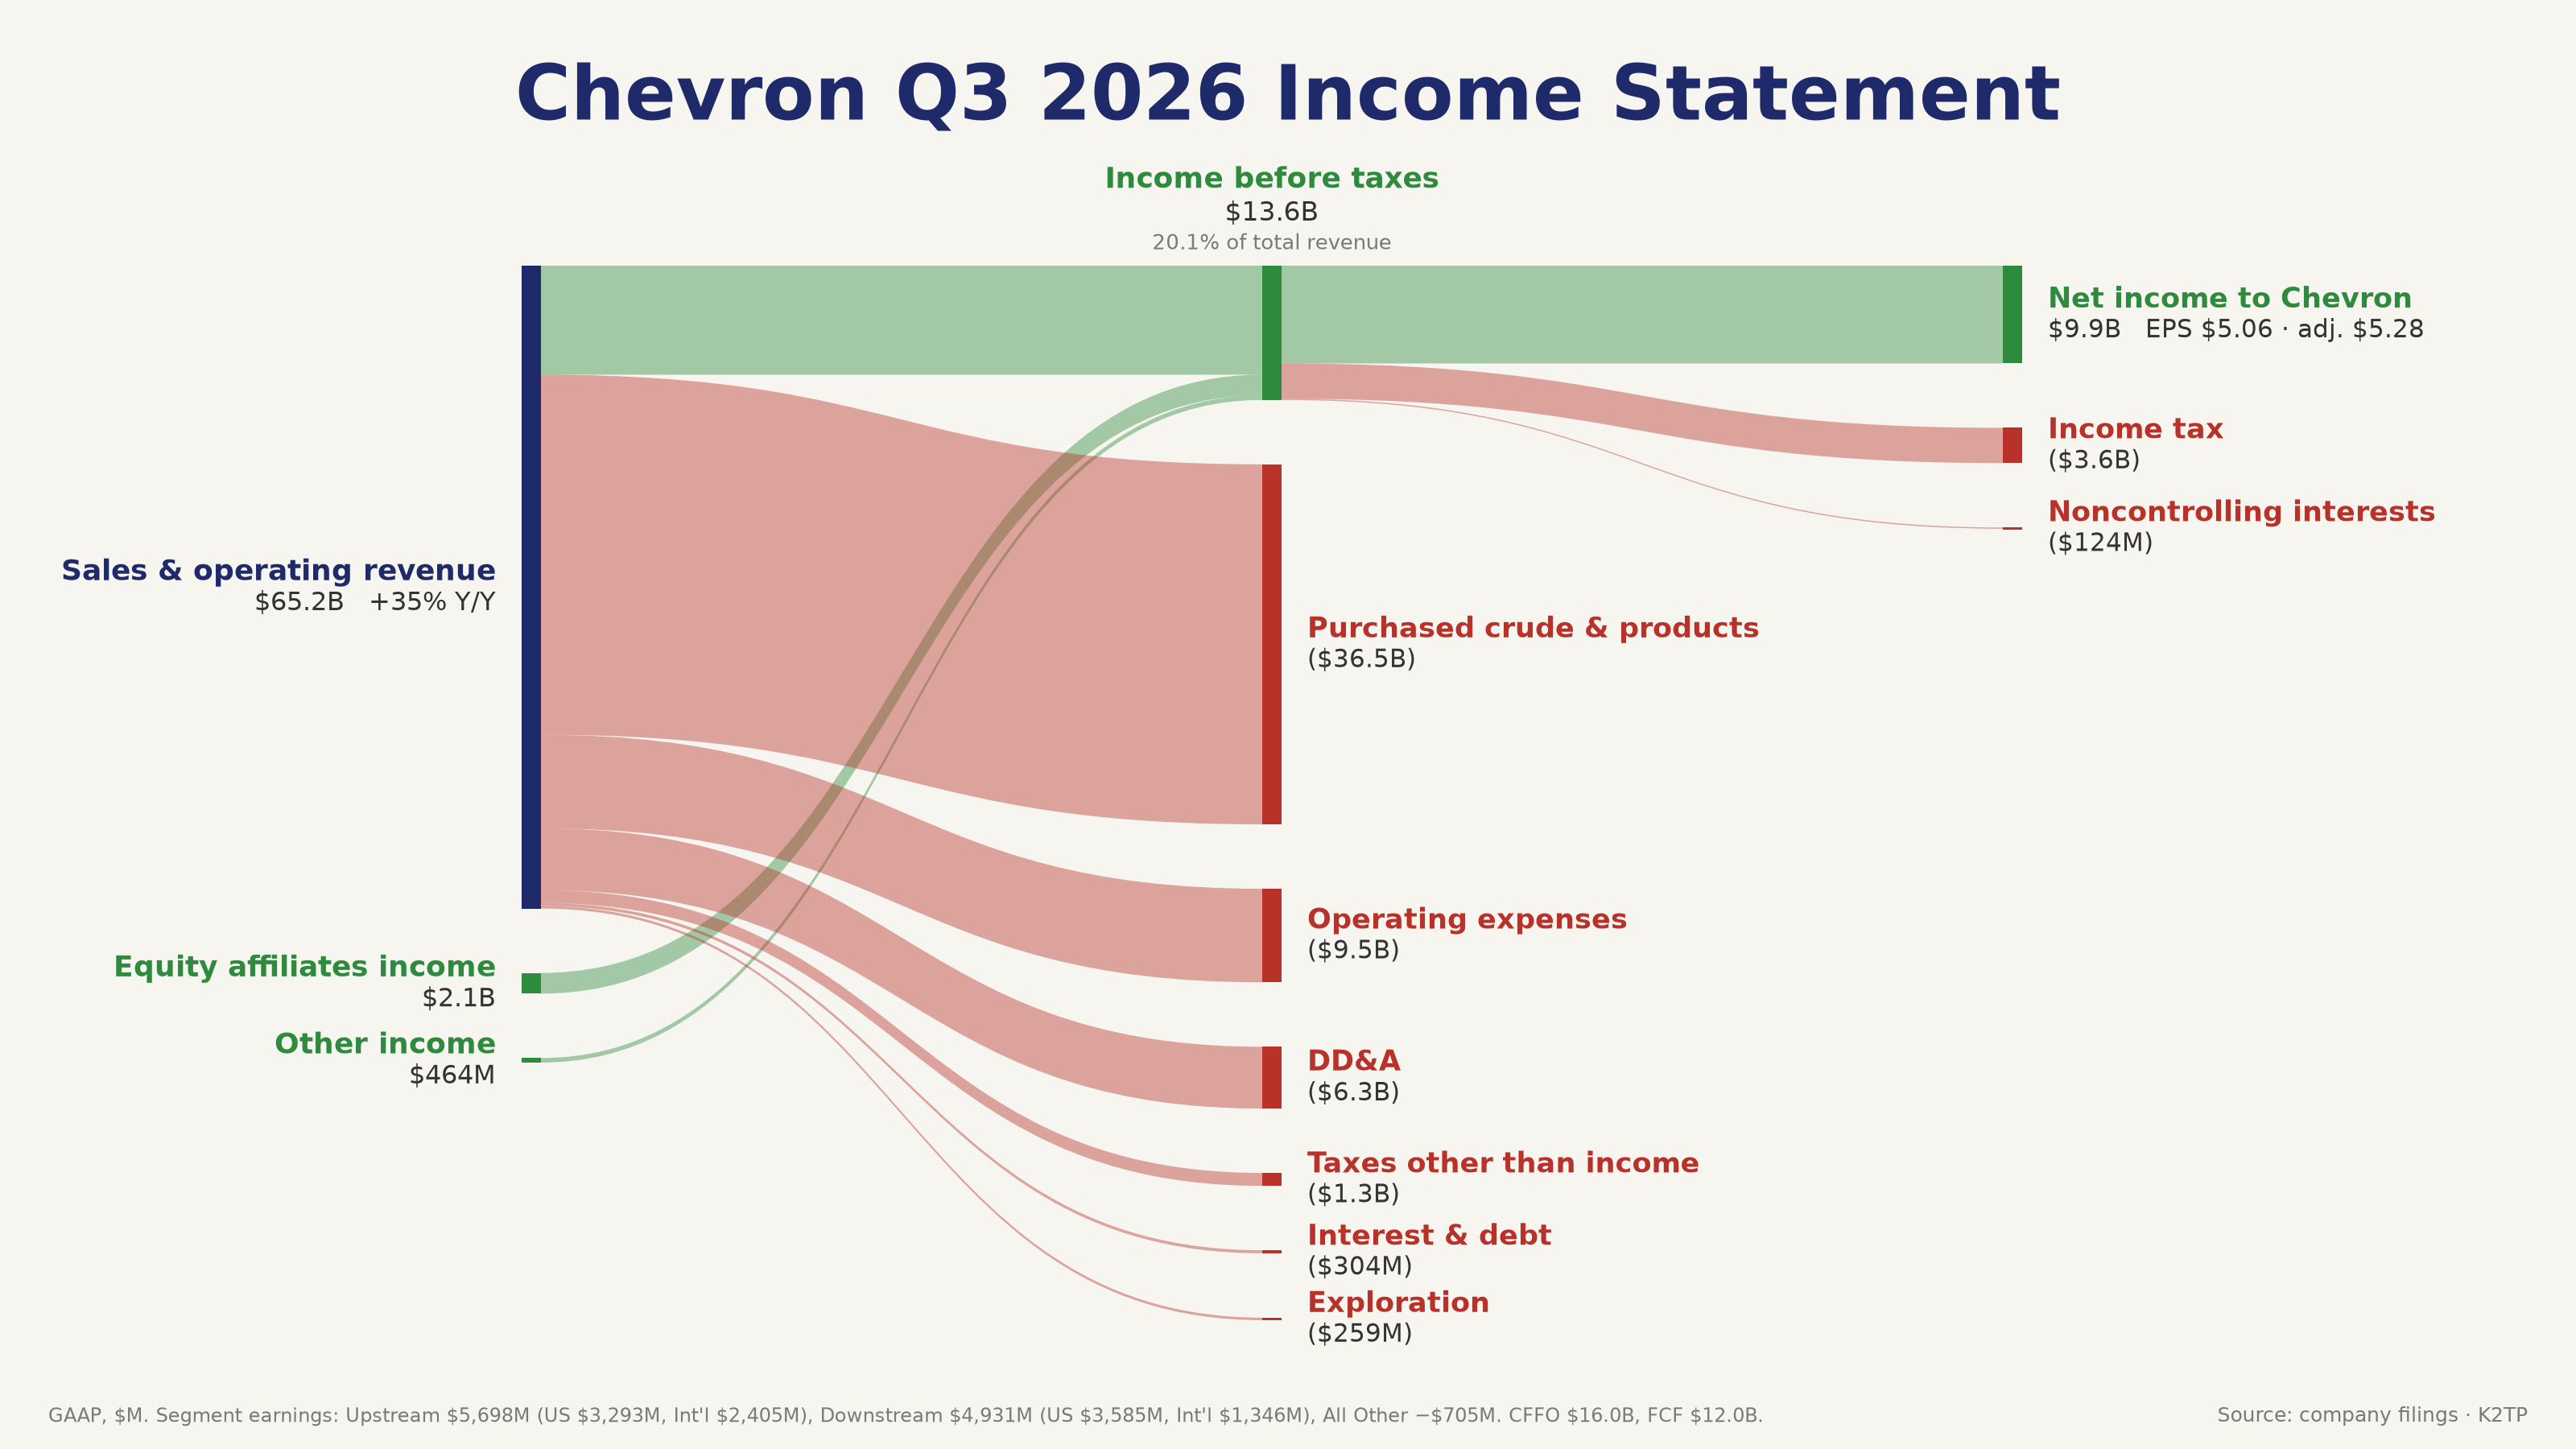
- Chevron (Fri): adjusted EPS $5.28 vs $4.93, FCF $12.0B; CVX +1.75%. ExxonMobil's profit doubled to $15.4B; XOM +2.16% 🟢
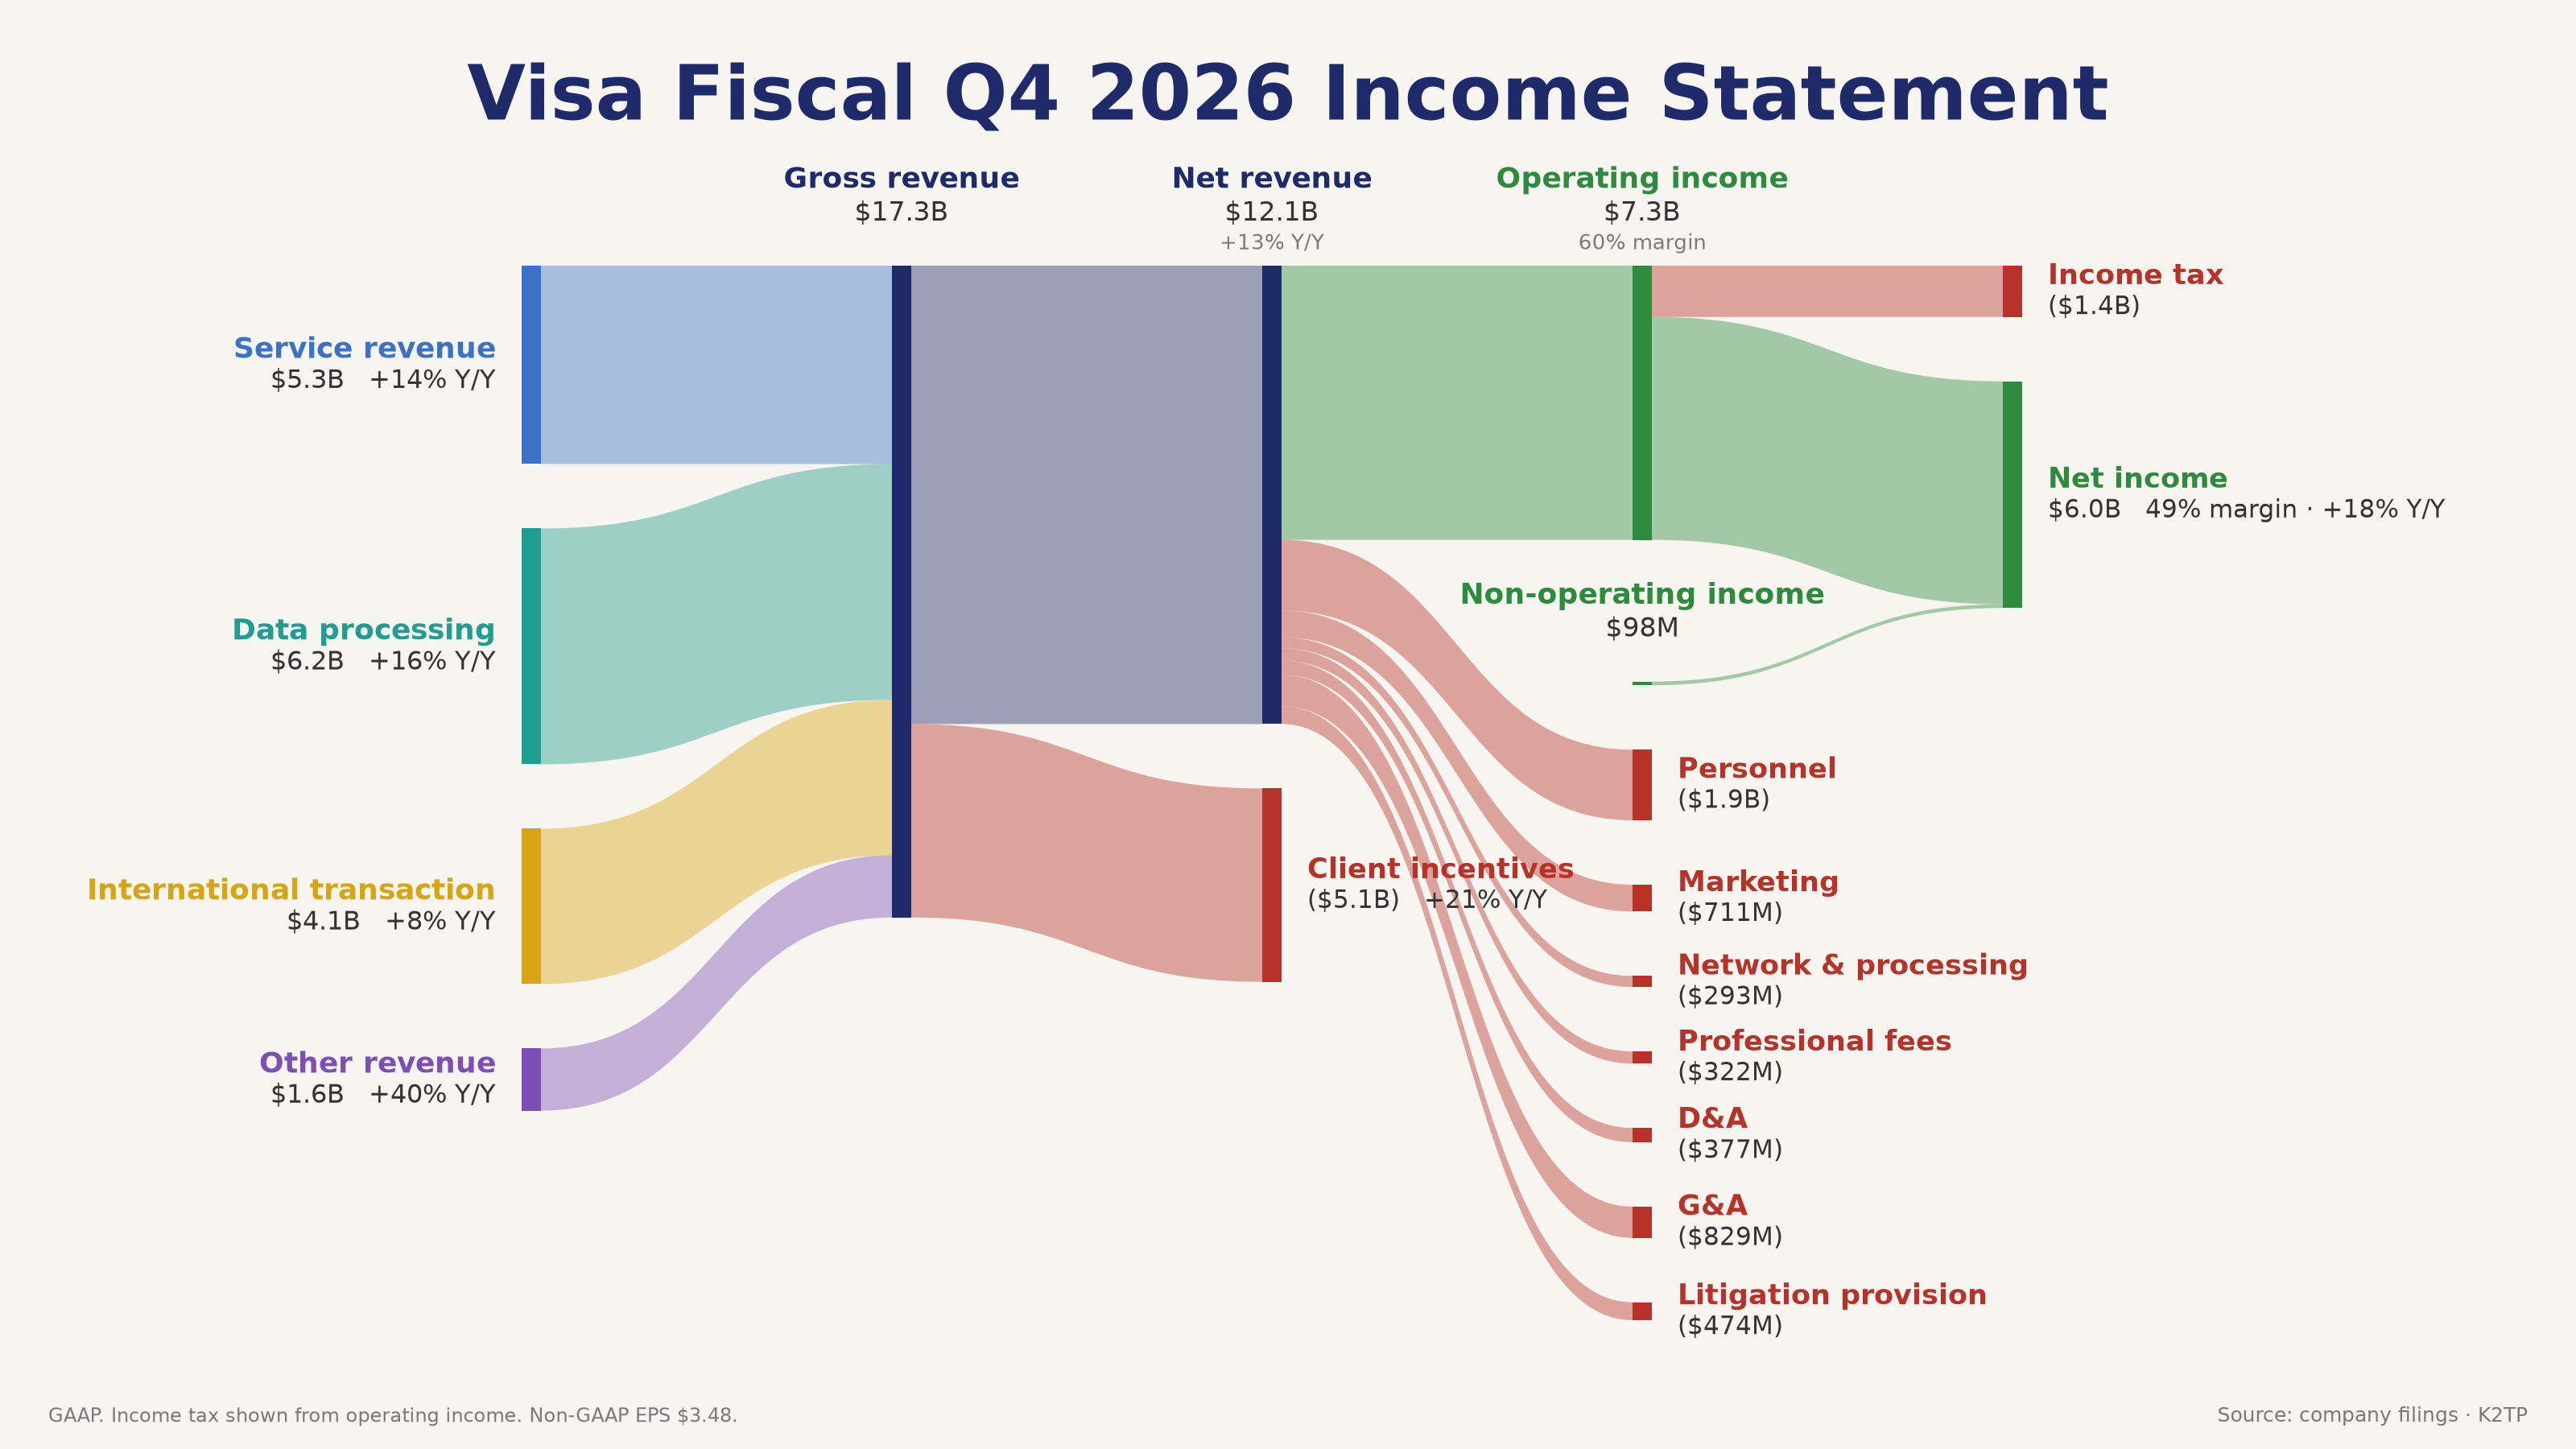
- Visa (Tue after the close): net revenue $12.14B (+13%), non-GAAP EPS $3.48 vs $3.44, dividend +16%; V −1.15% after hours
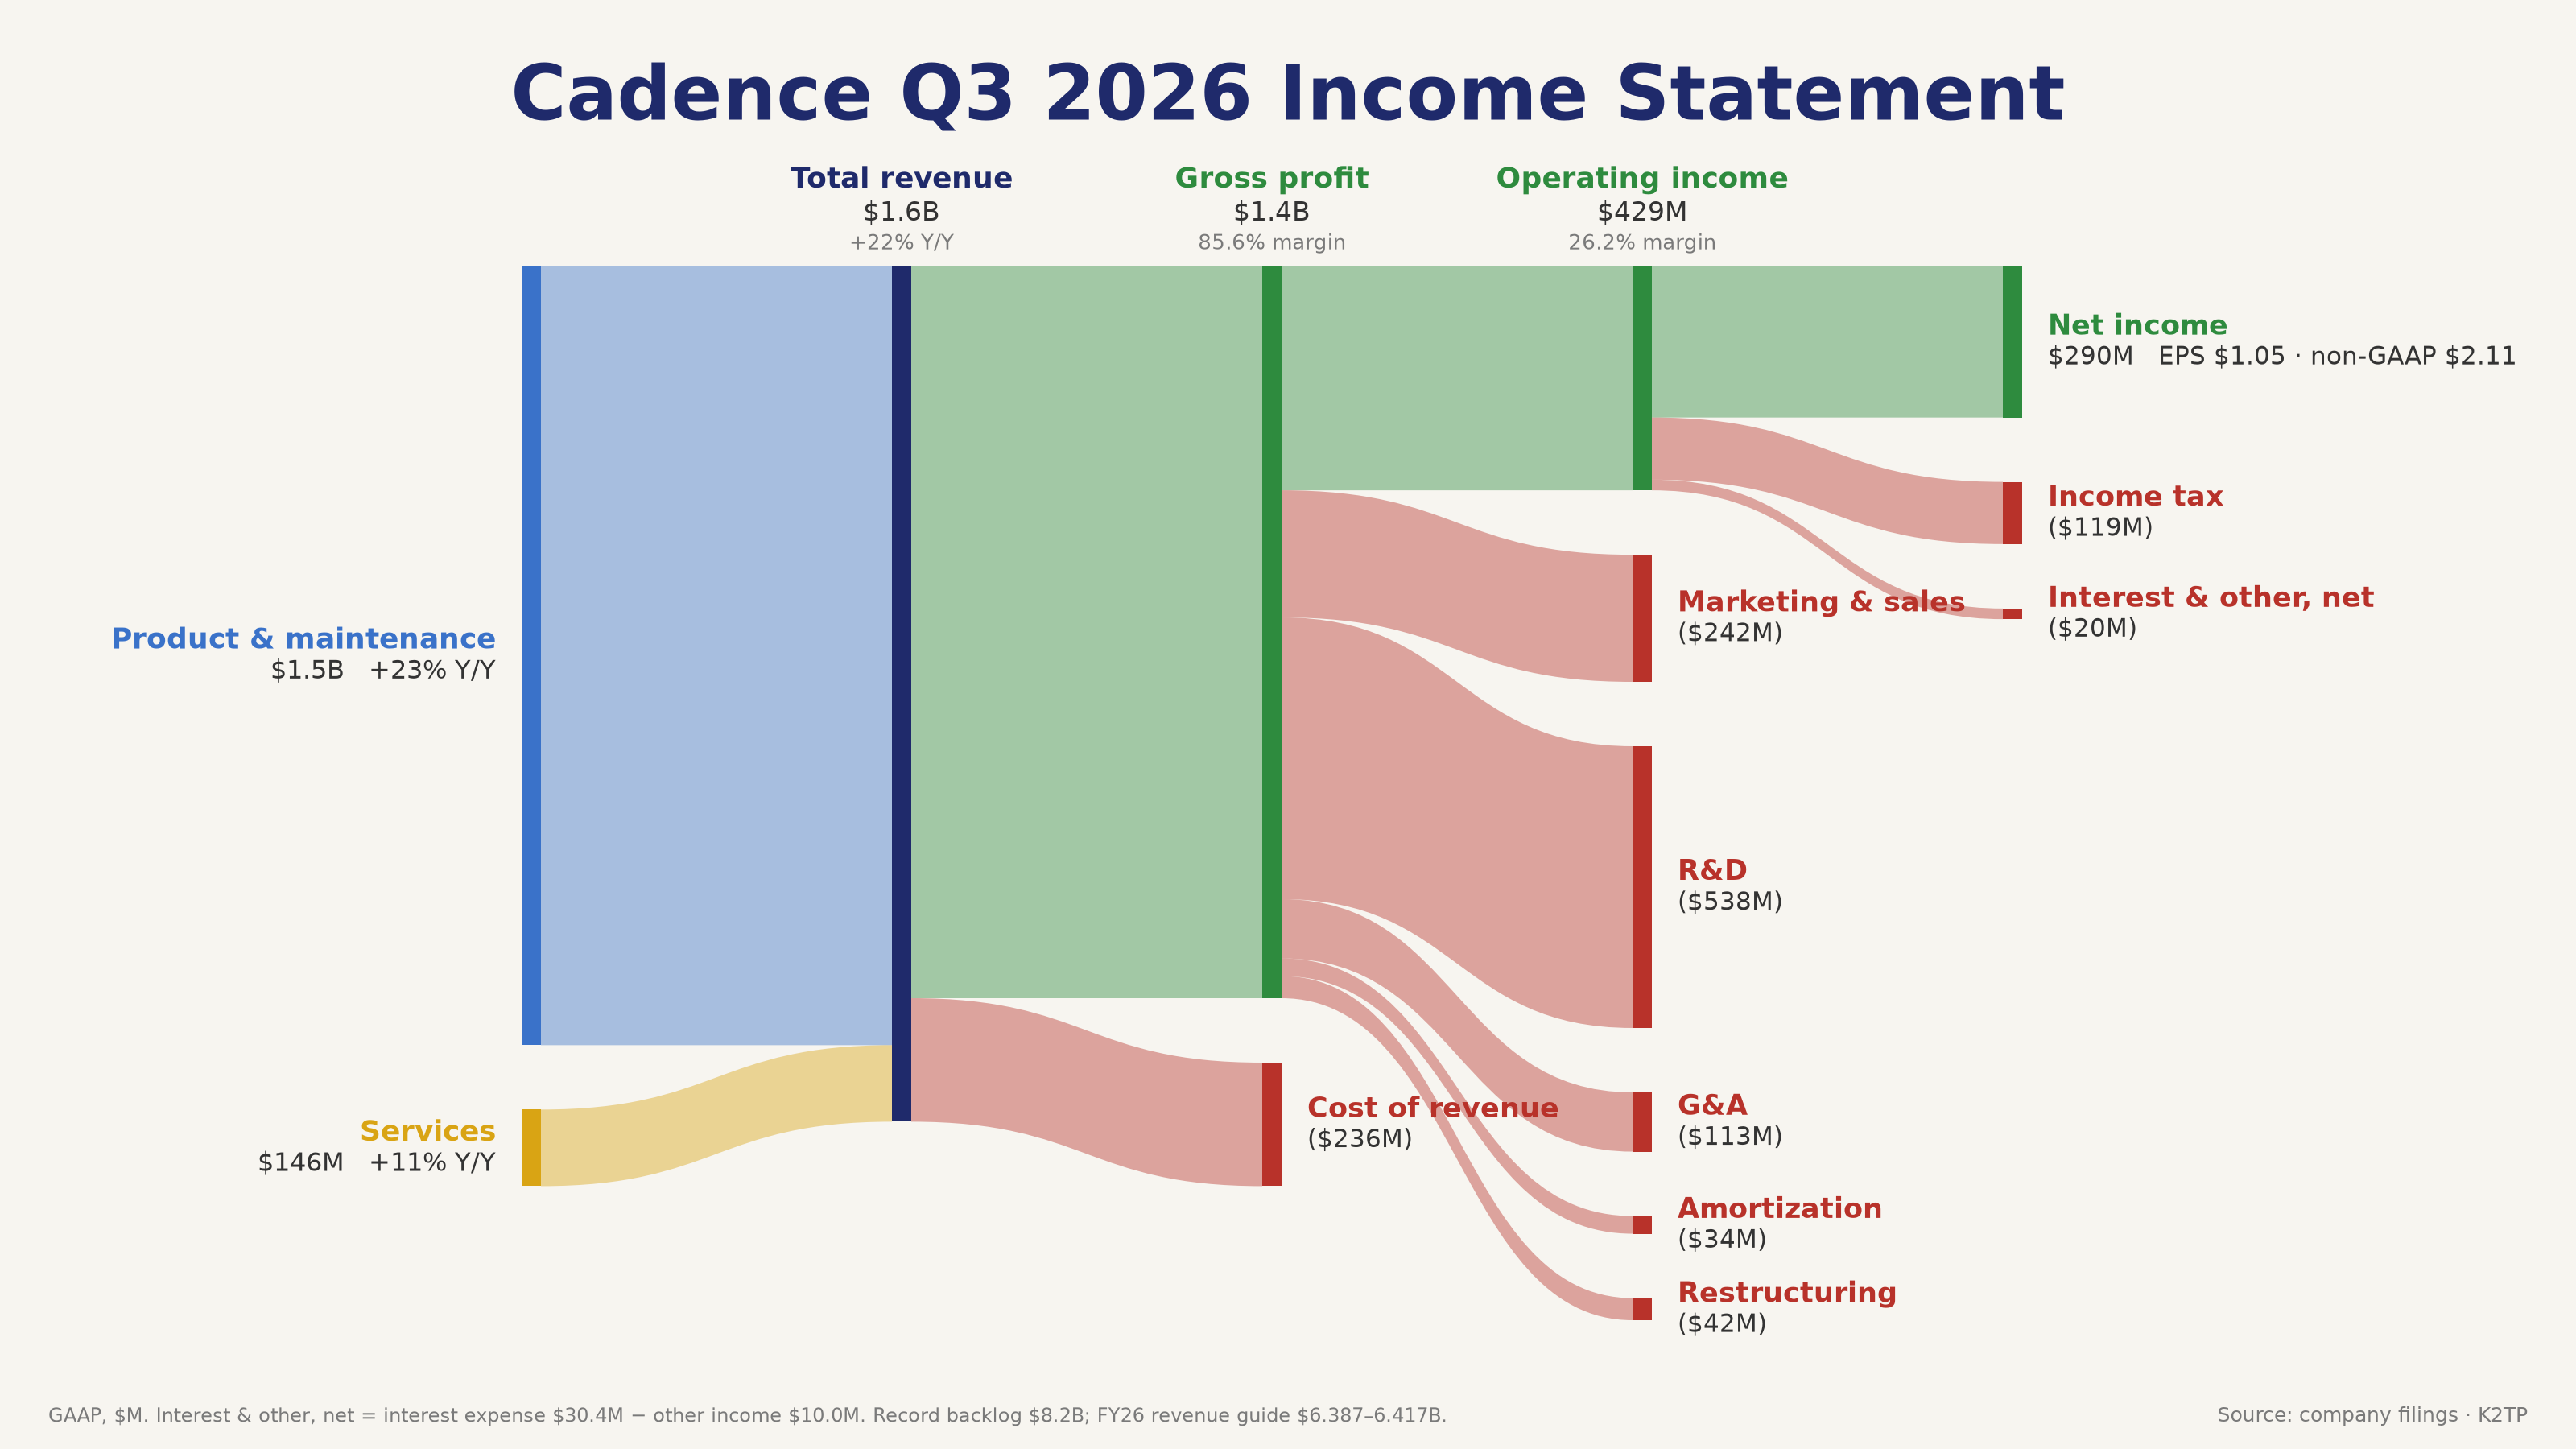
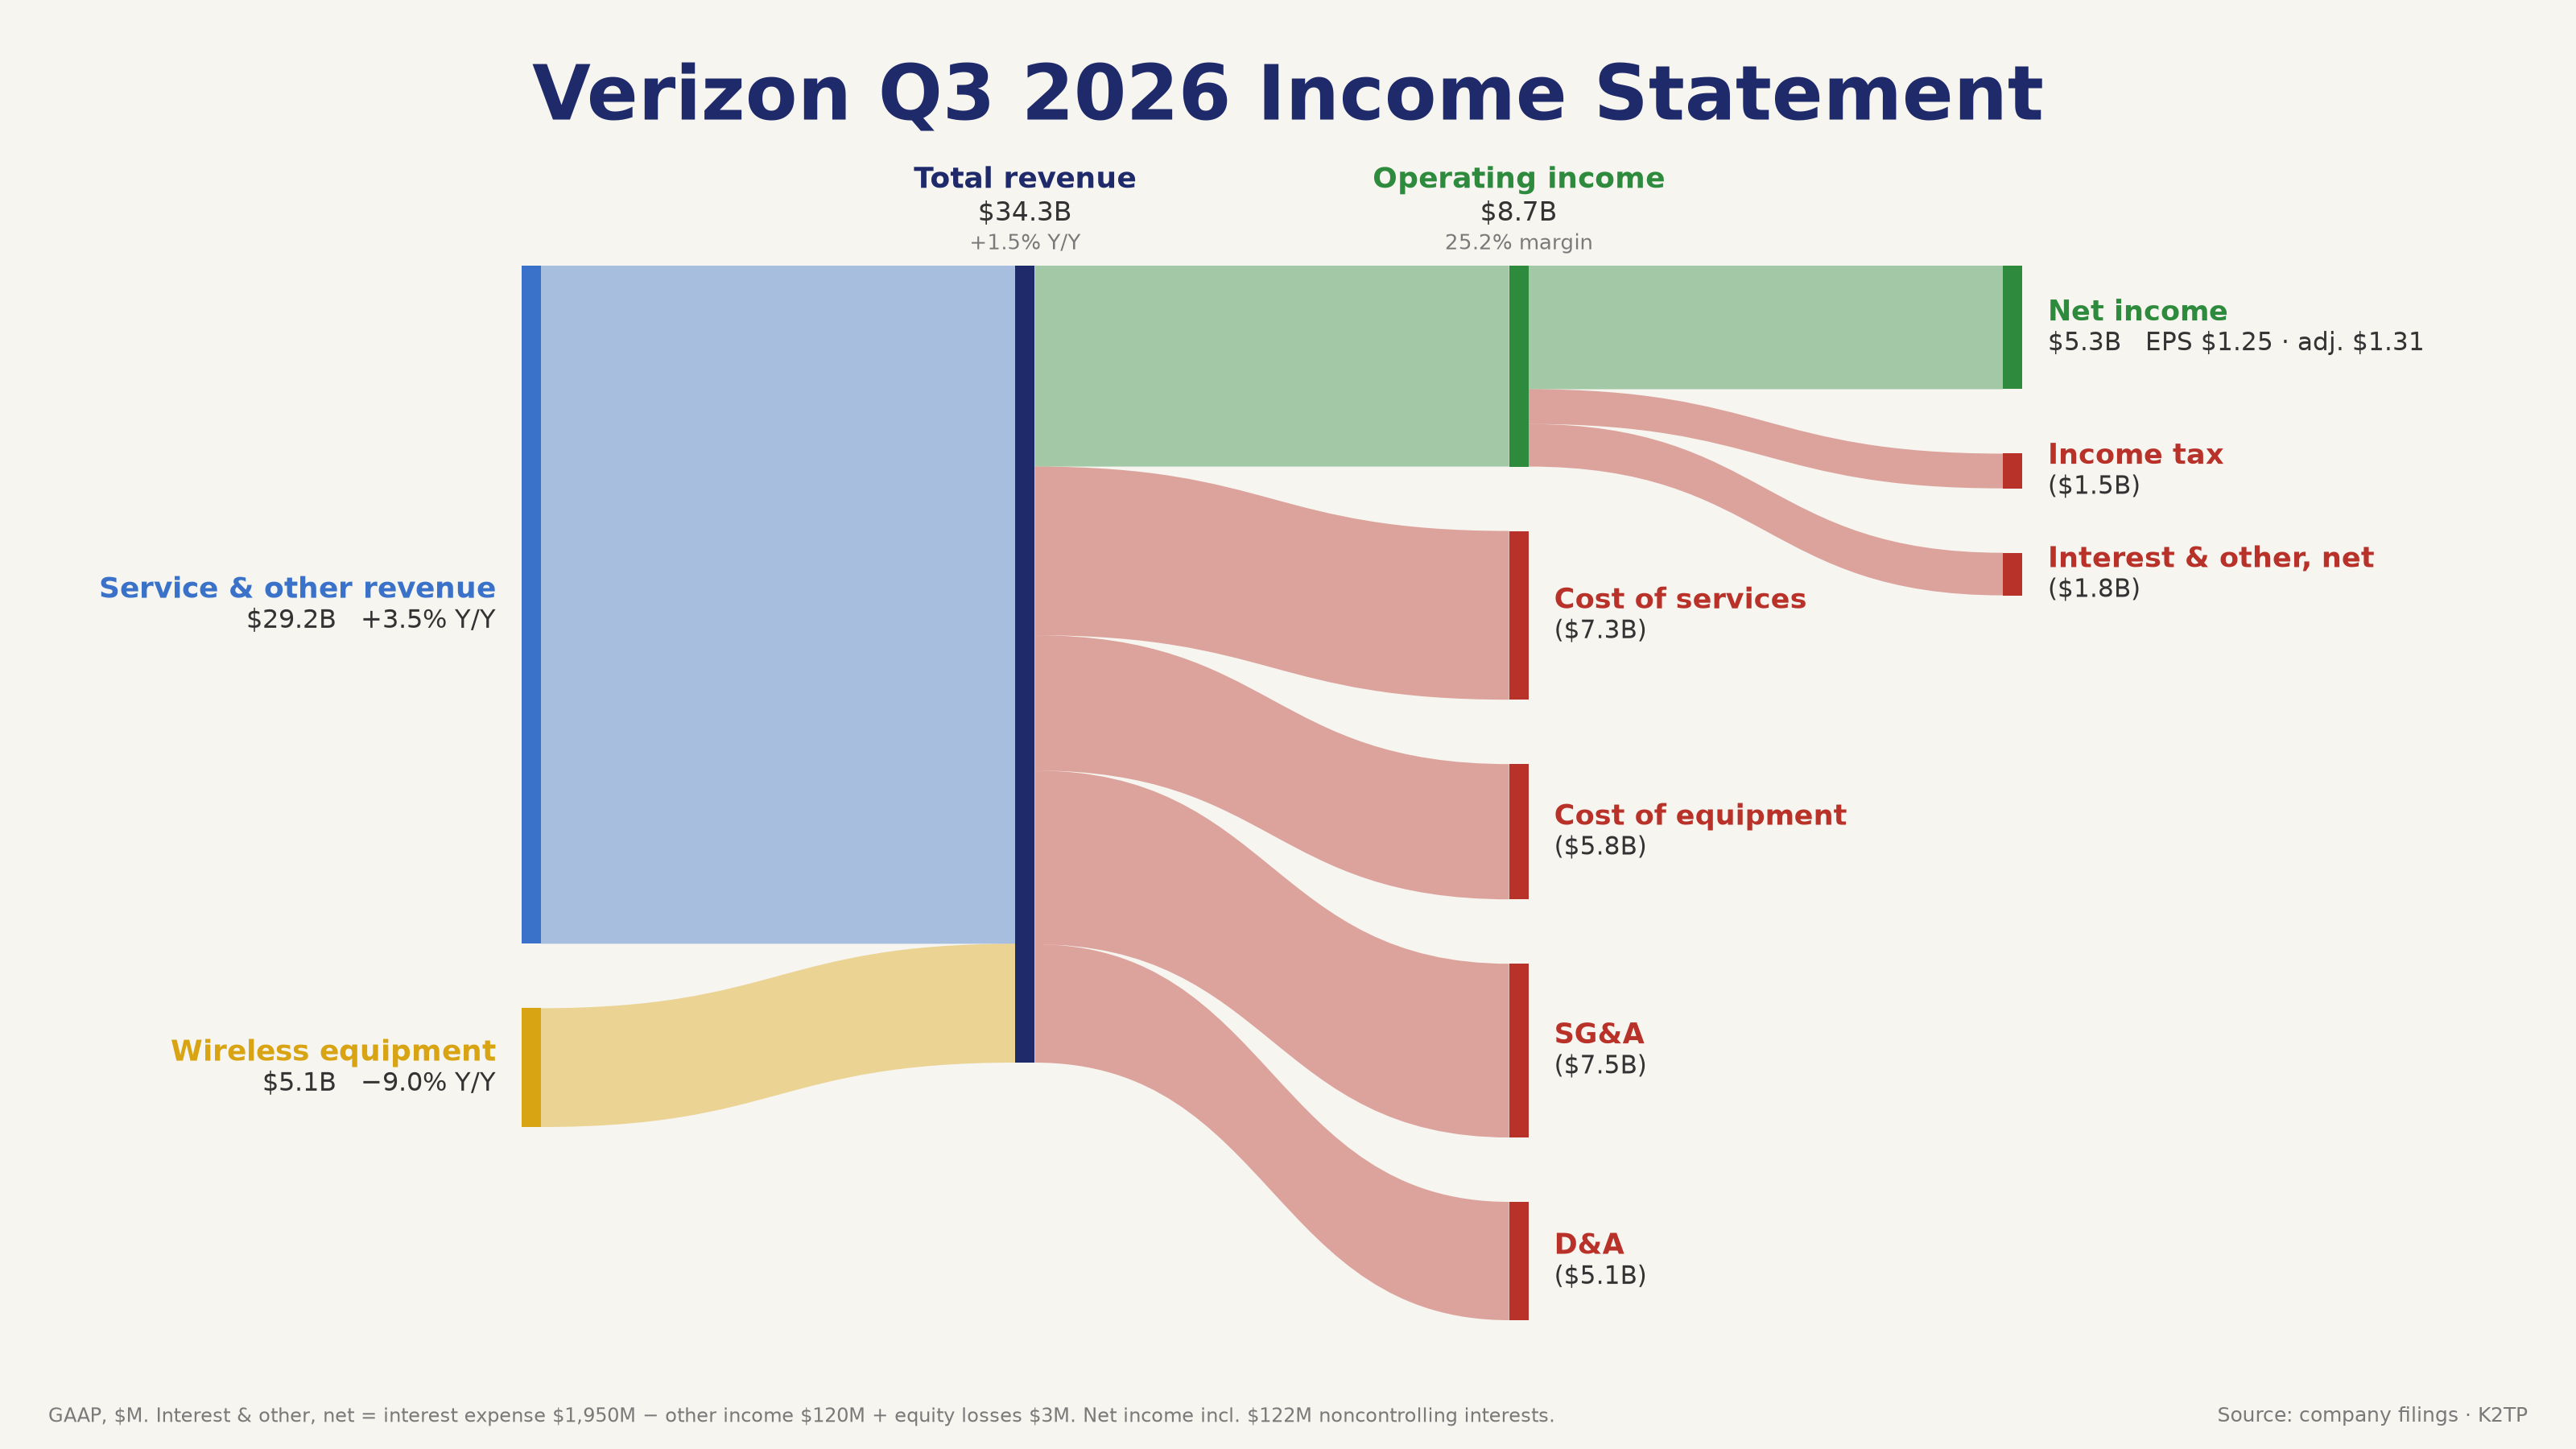
- Cadence (Mon after the close): revenue $1.633B (+22%), non-GAAP EPS $2.11 vs $2.05, record backlog $8.2B 🟢. Verizon: adjusted EPS $1.31 beat, revenue $34.31B missed; VZ −3.49% 🔴
- Outside tech: LLY +6.63% Thursday after raising 2026 revenue guidance to $91B–$92B (LLY +11.31% for the week); UPS +5.75%, Vertiv +16.48%; Boeing −10.69%, Caterpillar −9.25%, Reddit −29.22%
→ The market pays for growth that turns into cash (Azure, Lilly, Chevron) and punishes growth that consumes cash (Alphabet, Amazon) or guides lower (Intel).
MACRO DATA: STRONG GROWTH, IN-LINE INFLATION
- Q3 GDP (advance) 3.4% vs 3.2% expected; September PCE 3.6% y/y and core PCE 3.1% y/y, both in line 🟢
- Jobless claims 194K vs 198K; Q3 Employment Cost Index 0.8% q/q, in line
- Conference Board confidence 91.7 vs 81 expected; new home sales 676K vs 650.5K; Chicago PMI 55.3 vs 56
- Freddie Mac 30-year mortgage rate 7.24%
→ Growth is strong and inflation is not falling. That keeps the Fed leaning toward hikes, not cuts.
FED AND RATES: A HAWKISH HOLD, THEN LOGAN
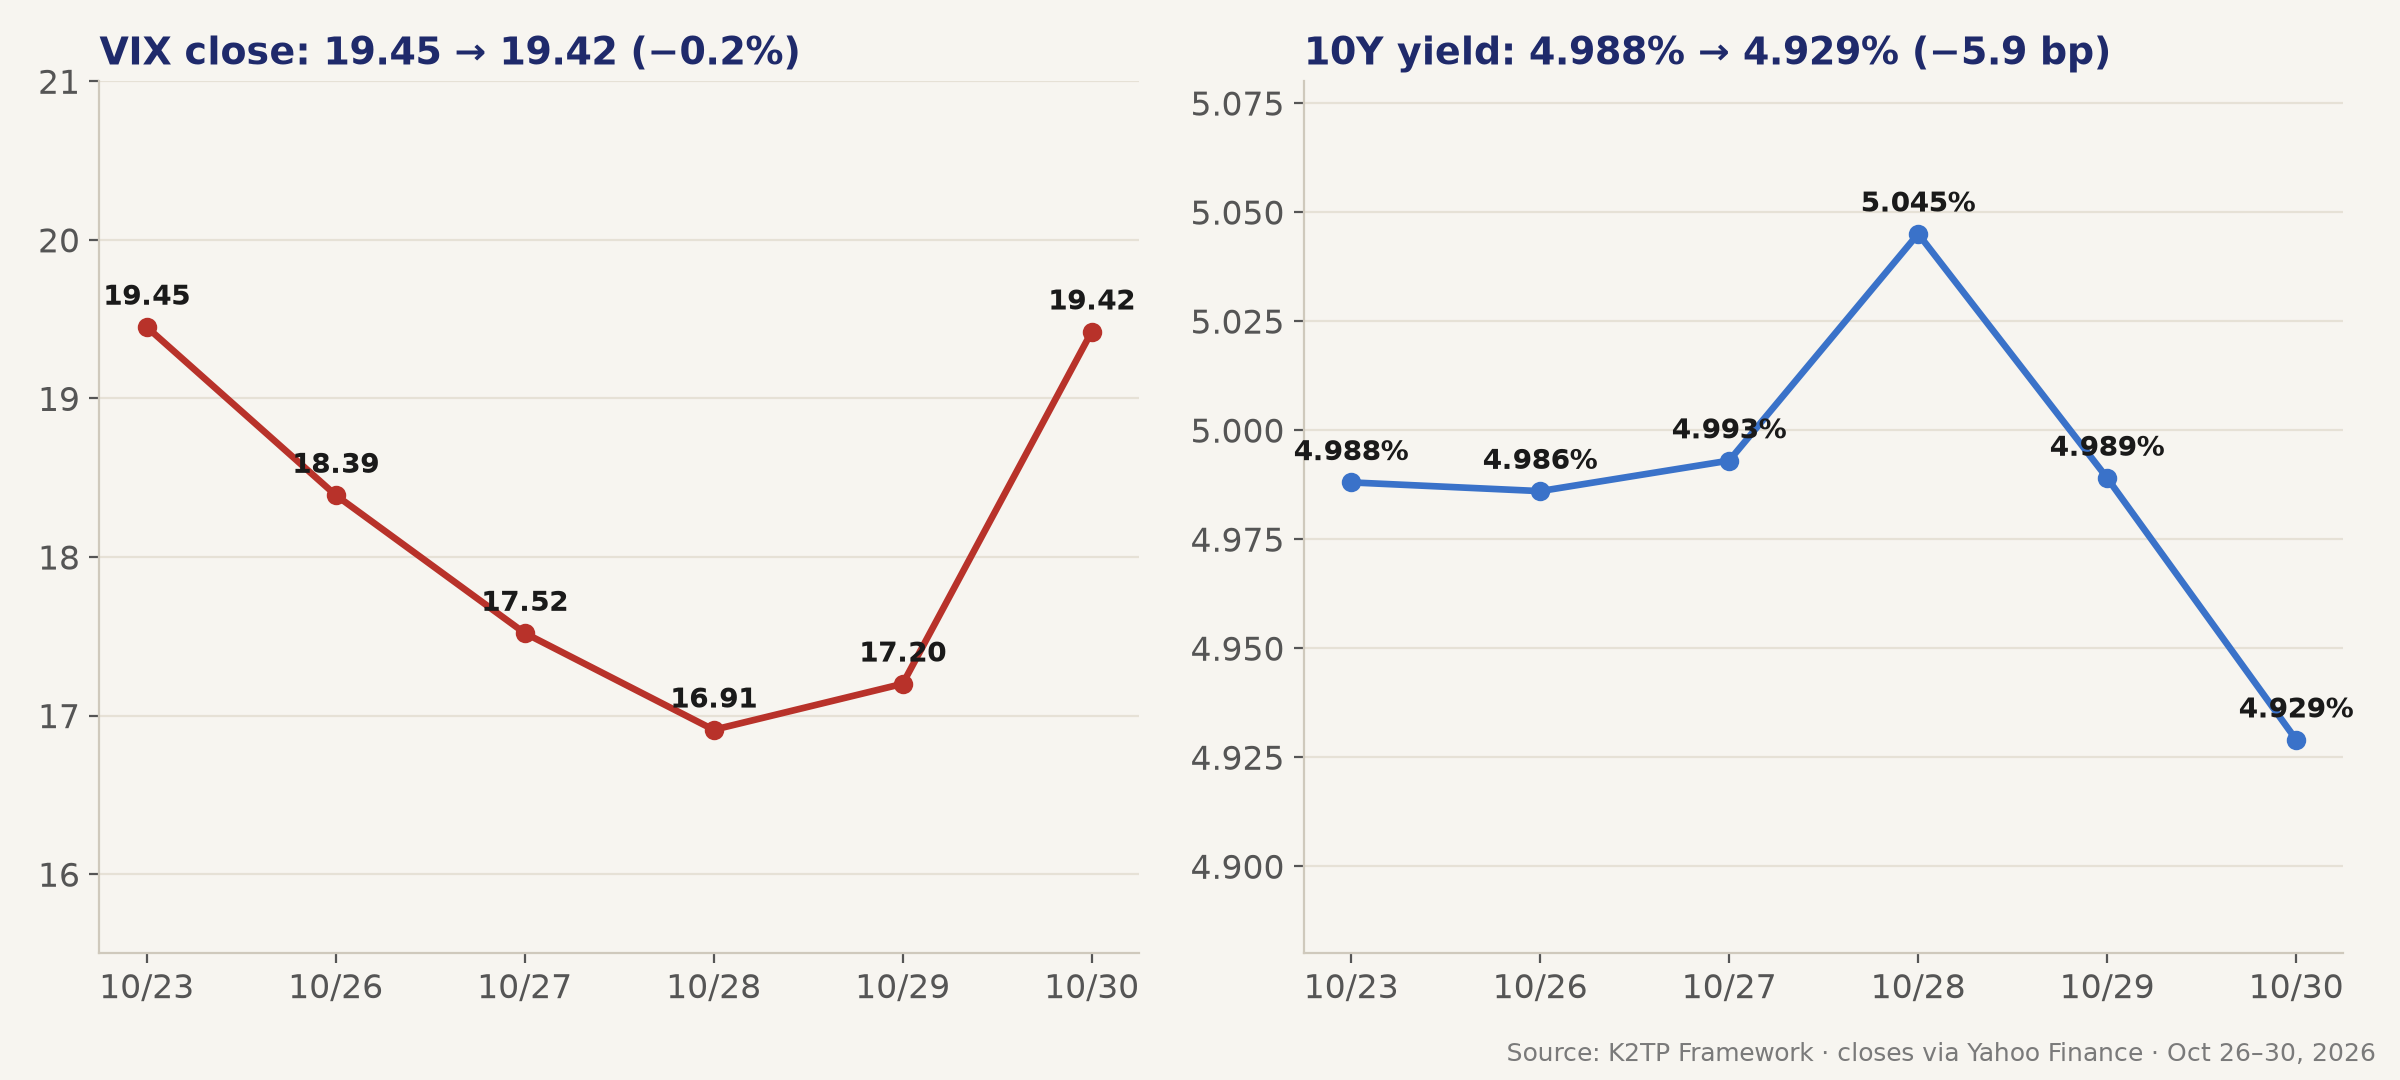
- Wednesday: the FOMC held at 3.75%–4.00% on a 10-2 vote; Cook and Hammack dissented for a 25 bp hike. Warsh gave no forward guidance and said he will not prejudge December
- Bear steepener on FOMC day: 10Y +5.2 bp to 5.045%, 30Y 5.361%; the Bank of Canada hiked to 2.50% the same day; the ECB held at 2.50% Thursday
- Friday 10:31 AM PT: Dallas Fed's Logan said the Fed needs at least two more quarter-point hikes; SPX fell to its 7,527.56 low over the next hour and VIX hit 23.93
- Yields still fell into the weekend on haven demand: 2Y 4.59%, 10Y 4.929%, 5Y 4.805% → 4.721%, 30Y 5.315% → 5.309%
- December hike odds: about 90% per FinancialJuice (unconfirmed); updated CME FedWatch figures were not available
→ The Fed is in no hurry to help: two dissents for a hike and Logan's comments keep December live. Lower yields this week came from fear, not from dovish policy.
OIL AND GEOPOLITICS: WTI BACK ABOVE $104
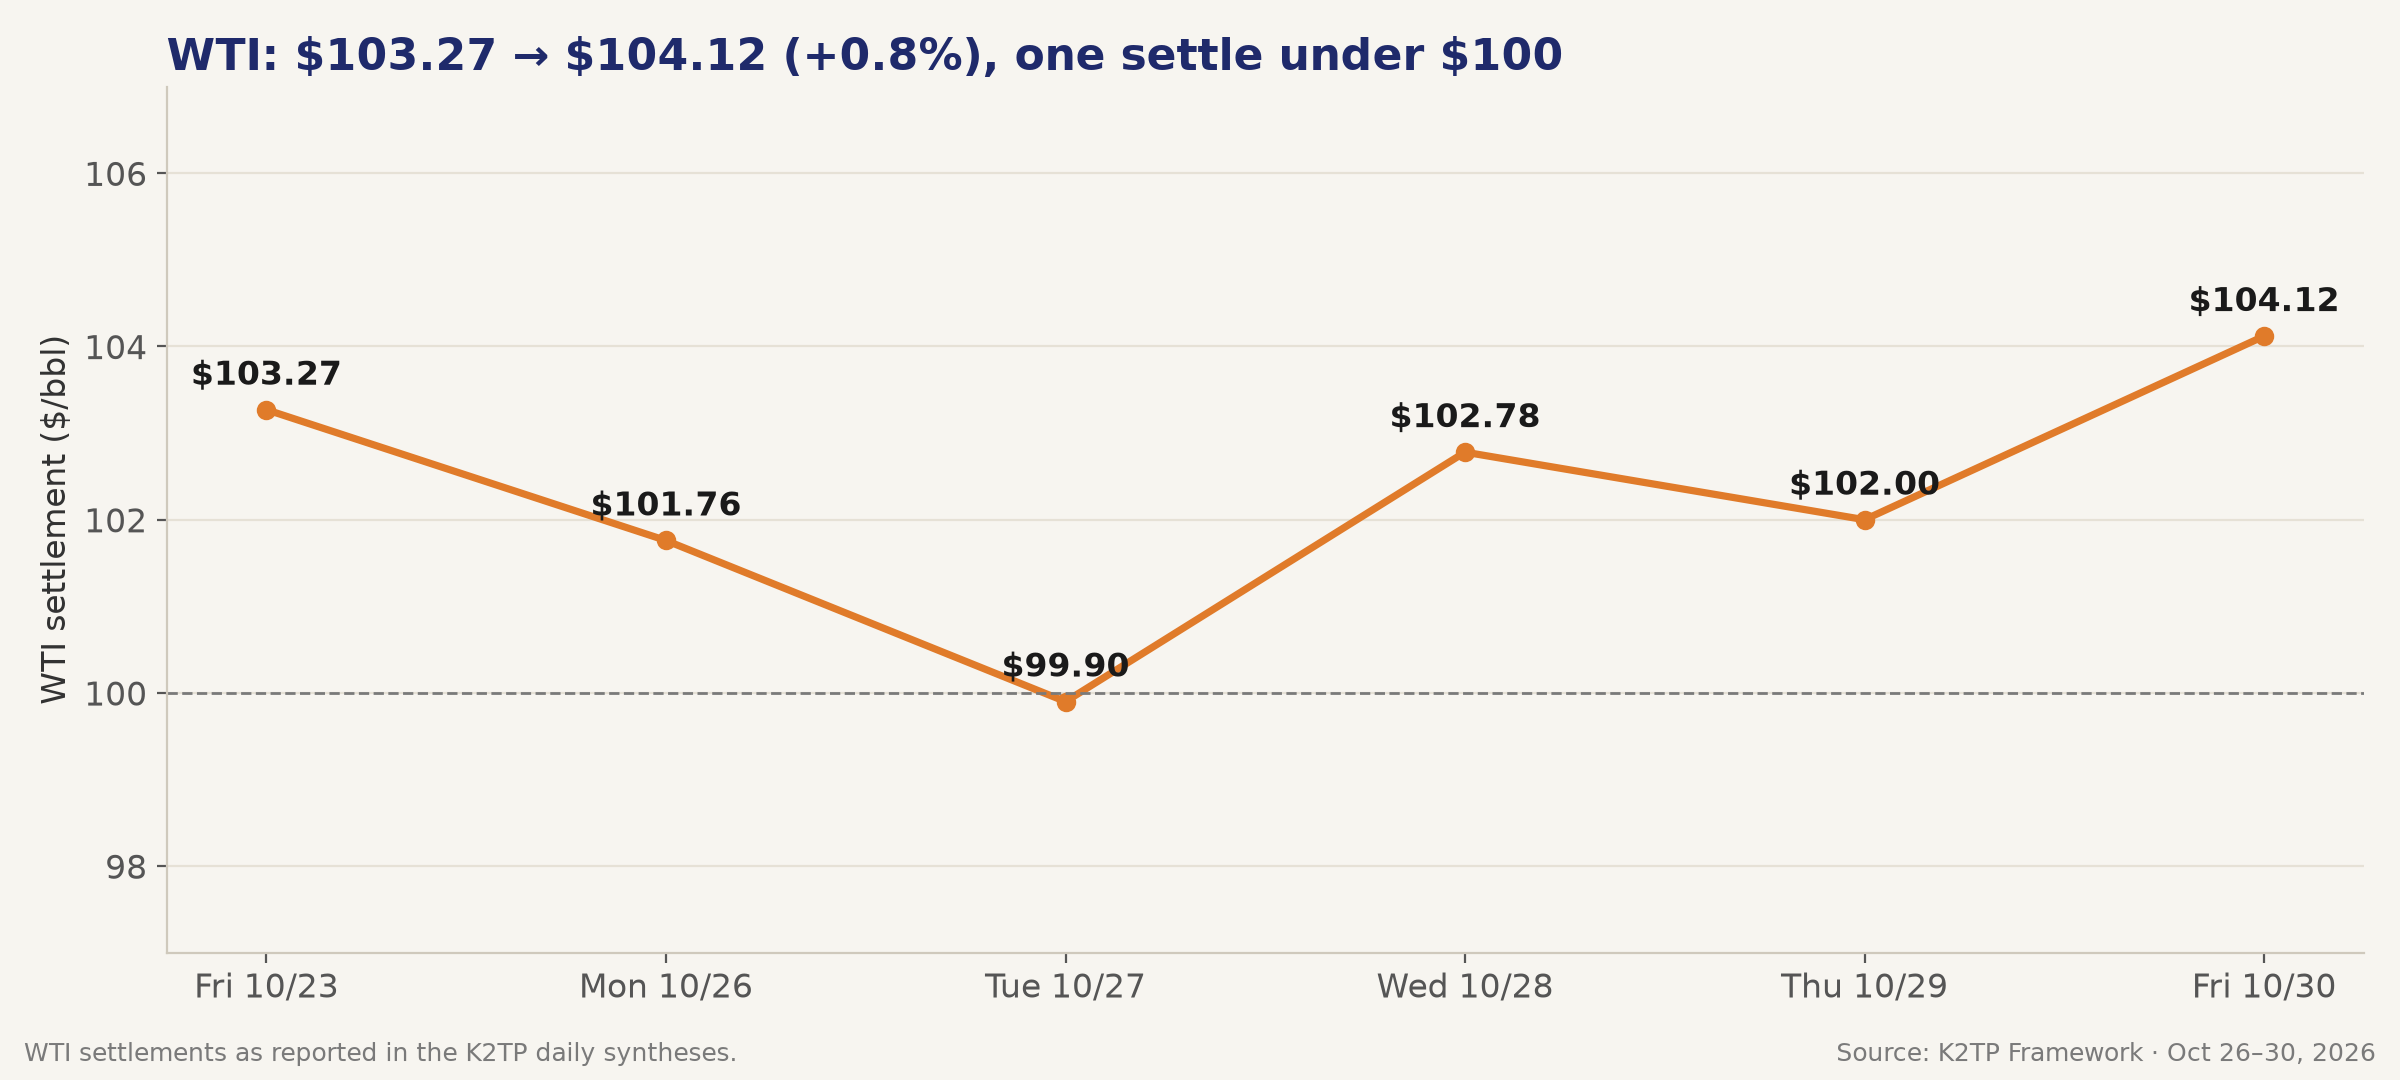
- WTI settlements: $103.27 (Oct 23) → $101.76 → $99.90 → $102.78 → $102.00 → $104.12 (+0.8% for the week); Tuesday was the first settle under $100 in this run
- Expiring December Brent settled at $117.64 Friday (+2.4%), the highest since late April; January Brent $113.43
- Drivers: Houthi attacks on Saudi oil sites (Ras Tanura, Abqaiq, Rabigh, claimed), a vessel on fire in the Strait of Hormuz Thursday (UKMTO), a 1.892M-barrel EIA crude draw; brief dips on Iran ceasefire talk
- XLE +1.00% for the week, +1.91% on Friday as money hid in energy
→ Oil above $100 is still the main macro risk. It keeps inflation sticky and gives the Fed a reason to stay hawkish.
SECTORS AND ROTATION: HEALTHCARE AND MATERIALS WIN, COMMUNICATIONS LOSE
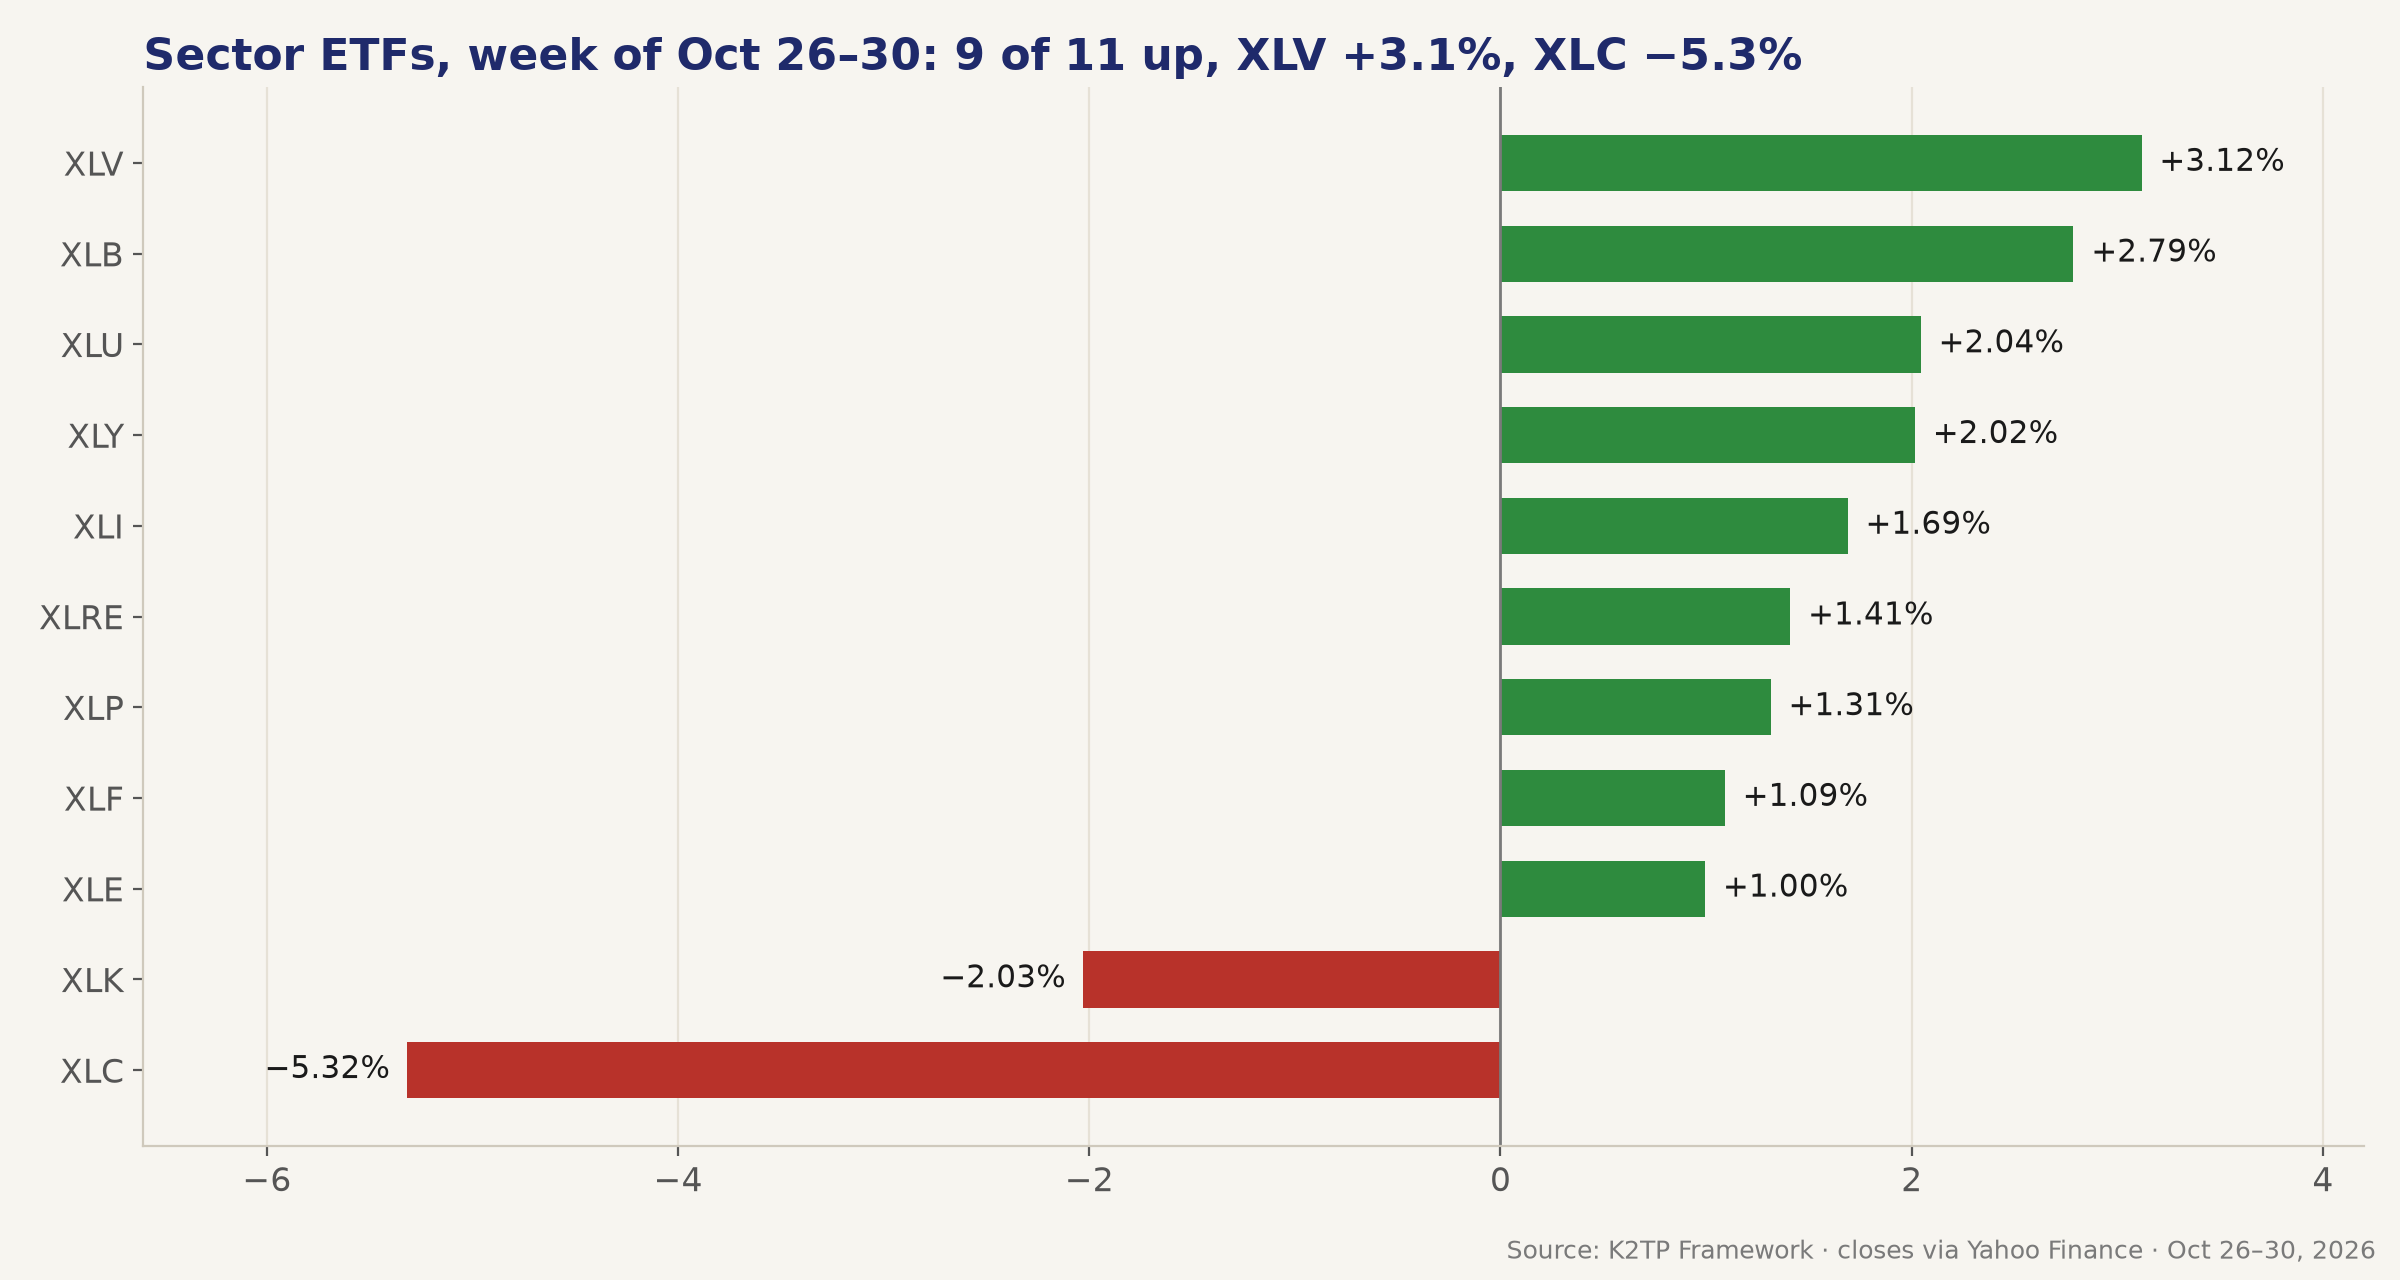
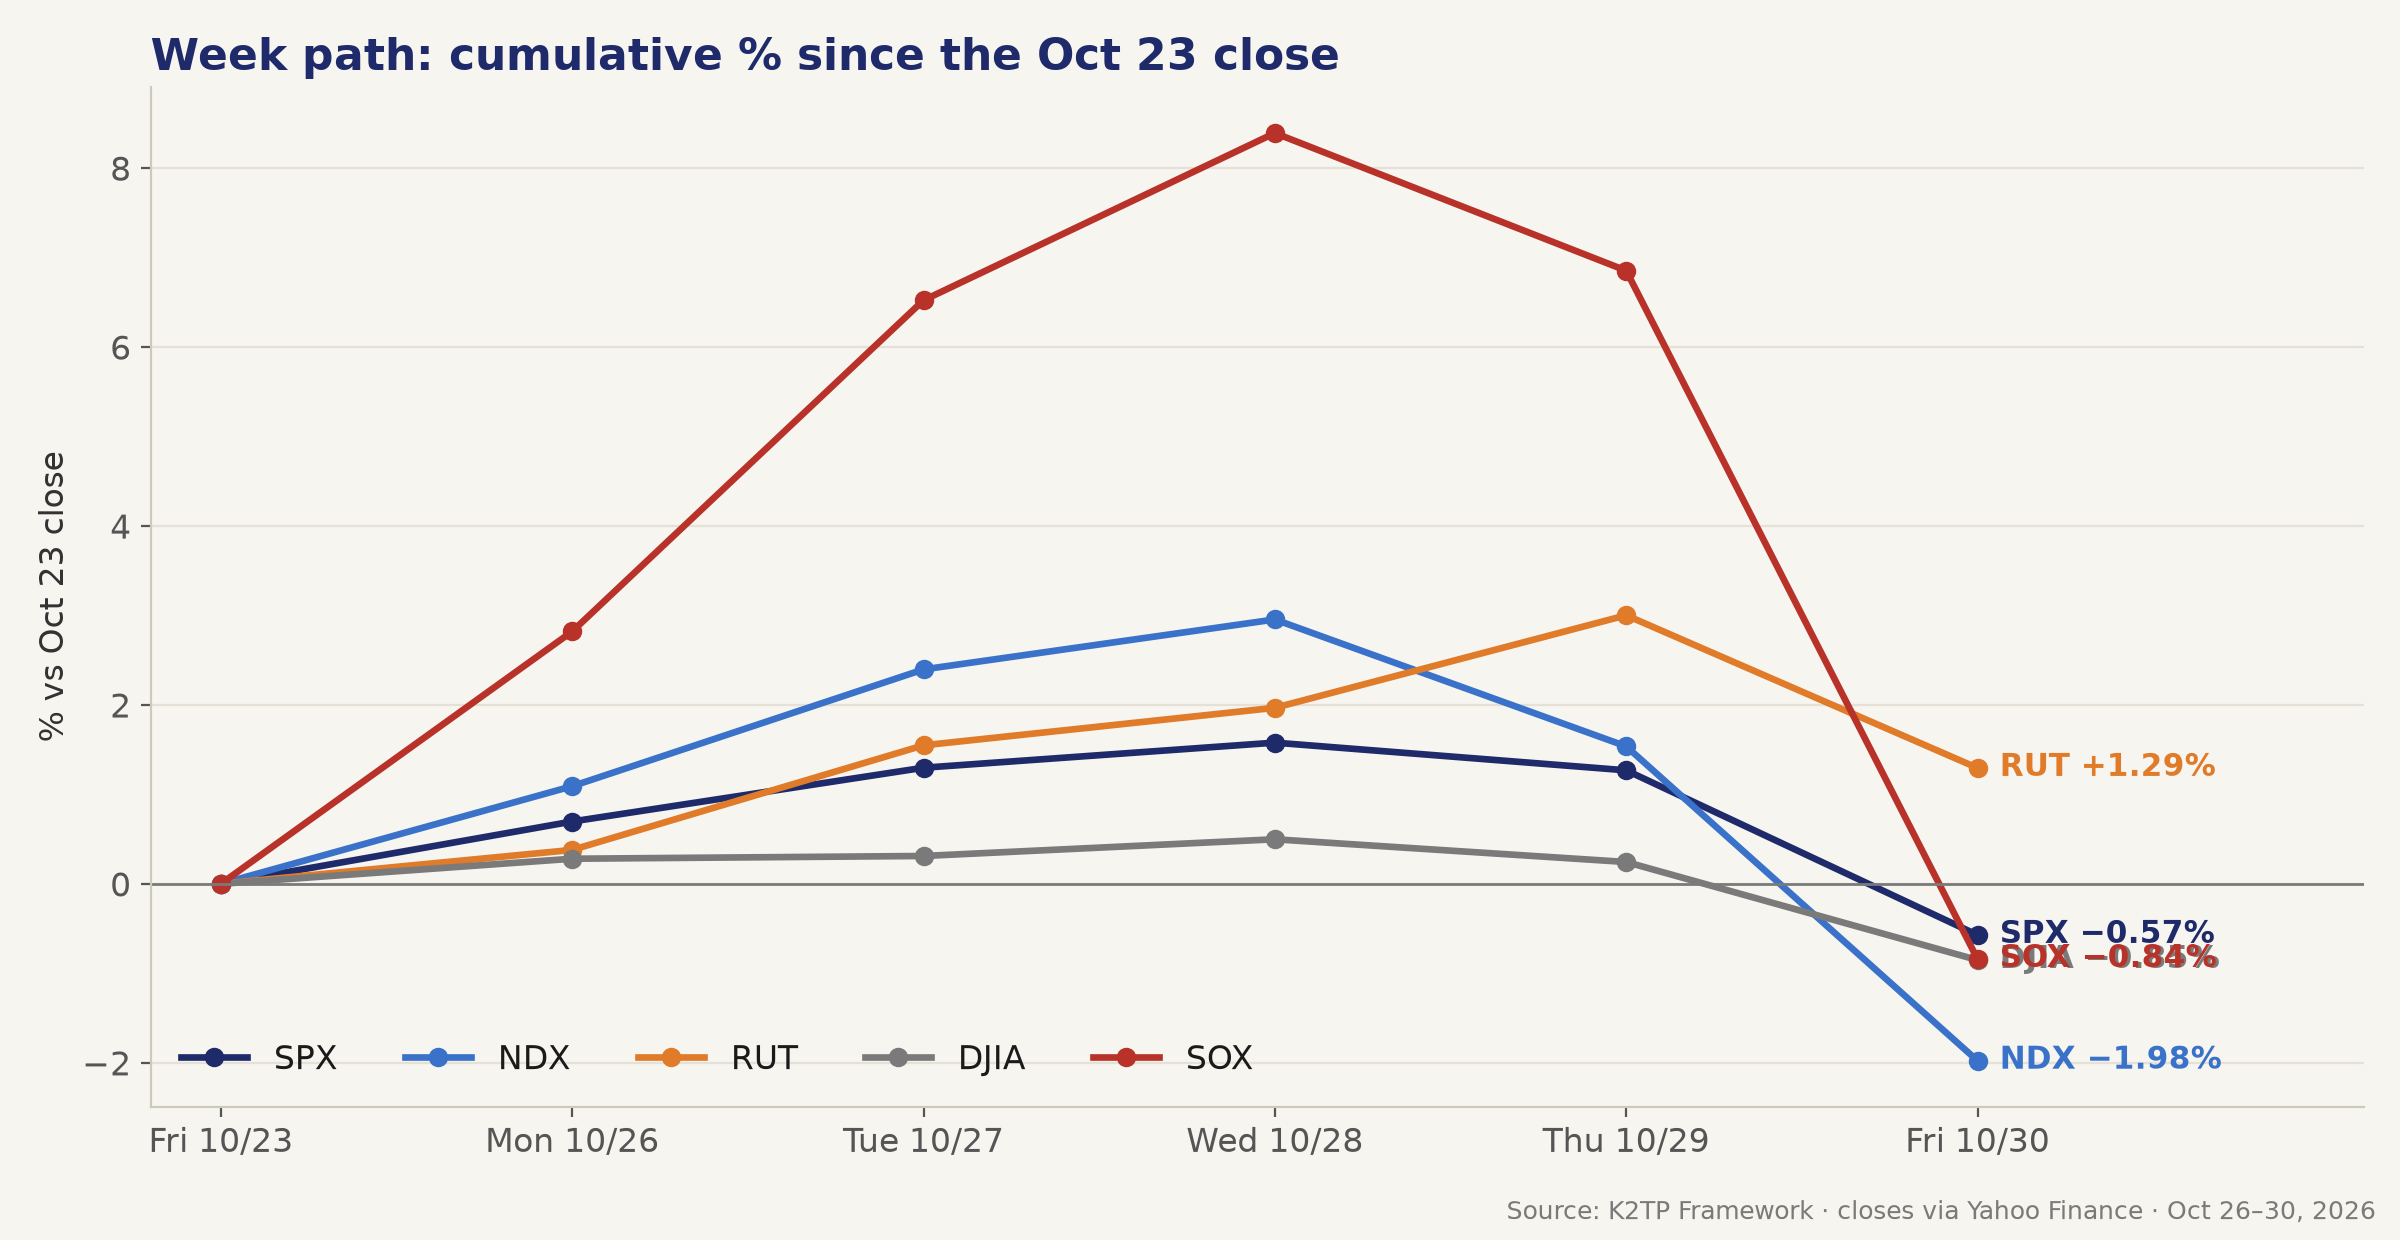
- 9 of 11 sector ETFs rose: XLV +3.12%, XLB +2.79%, XLU +2.04%, XLY +2.02%, XLI +1.69%, XLRE +1.41%, XLP +1.31%, XLF +1.09%, XLE +1.00%; XLK −2.03%, XLC −5.32%
- Thursday was the peak of the rotation: RSP +1.20% vs SPX −0.30%, XLV +2.40%, XLRE +2.21%
- Winners outside tech: GM +15.12%, LLY +11.31%, TMUS +6.76%, GE +5.66%, LMT +5.42%; DoorDash agreed to buy Instacart for $65 per share
- Communication services was the worst sector: GOOGL −12.61%, NFLX −5.73%, META −4.30%
→ Money keeps leaving AI megacaps for healthcare, materials and defensives. The cap-weighted SPX can't go up while its biggest names fall, even when most stocks rise.
THE WEEK'S MARKET
Indices (Oct 30 close, change vs Oct 23 close):
| Index | Oct 23 | Oct 30 | Week |
|---|---|---|---|
| SPX | 7,623.68 | 7,580.07 | −0.57% |
| NDX | 28,957.53 | 28,384.85 | −1.98% |
| Nasdaq Composite | 25,955.34 | 25,437.00 | −2.00% |
| RUT | 2,775.90 | 2,811.84 | +1.29% |
| DJIA | 52,215.16 | 51,770.31 | −0.85% |
| SOX | 10,779.46 | 10,688.80 | −0.84% |
| VIX | 19.45 | 19.42 | −0.15% |
| 10Y | 4.988% | 4.929% | −5.9 bp |
- SPX week range: 7,527.56 (Fri low) to 7,758.43 (Wed high); record close still 7,818.93
- NDX week range: 28,093.24 to 29,848.71
Volatility:
- VIX 19.45 → 19.42; low 16.21 (Wed), Friday intraday high 23.93
- VIX9D 19.25, VIX3M 20.78: VIX9D briefly moved above VIX3M on Friday, then the curve closed back in Contango
Breadth:
- RSP +0.82% vs SPX −0.57%; RUT +1.29%; 9 of 11 sectors up
- Official weekly A/D totals: unavailable
Cross-asset:
- WTI $104.12 (+0.8%), December Brent $117.64 at expiry; BTC about $80.8K → $77.4K (−4.2%)
Option-seller angle:
- Friday's VIX spike to 23.93 restored premium, but the event calendar is heavy: Apple (Mon), midterms (Tue), AMD (Tue), jobs report (Fri)
- Avoid tight Iron Condors on NDX; prefer defined-risk spreads and smaller size on short puts in chips
WEEKEND DEVELOPMENTS
- U.S.–Iran talks: Sunday was the third day of talks in Doha; Reuters and CNBC report a proposal to reopen the Strait of Hormuz within two days of a deal. Iran's Araqchi said there is no final conclusion. Rubio said Saturday that Trump has not decided on strikes and prefers diplomacy; Trump said Sunday Iran will end "one way or the other" but pledged no attack before the Nov 3 vote.
→ A deal would cut oil's risk premium quickly; Monday's oil drop shows the market already leans that way.
- Iran's warnings: Khamenei promised a "geographically unrestricted response" to any threat; an Iranian official said Iran is debating whether to lift its ban on nuclear weapons, with no decision taken (Reuters).
→ Tail risk remains if talks fail.
- Gulf shipping: The IRGC said two tankers hit mines on an "unauthorized route" (Iranian state media only, unconfirmed). UKMTO reported a vessel struck by an unknown projectile; Qatar said its LNG carrier Al-Mayeda was attacked Friday.
→ Shipping risk in Hormuz has not gone away, even with talks moving.
- OPEC+: Seven producers kept December output targets unchanged; next meeting Nov 29.
→ No supply relief from OPEC+; any oil drop has to come from diplomacy.
- China: official manufacturing PMI 49.3 (Saturday), still in contraction.
→ Weak global demand caps oil's upside a little.
- Crypto: BTC slid from about $80.8K to about $77.4K over the week.
→ Weak risk appetite outside equities.
- Sunday futures open (3 PM PT): ES 7,632, NQ 28,630.75, both slightly higher (ES +0.26%, NQ +0.32% at 3:33 PM PT); WTI $102.42, Brent $111.72. By about 5:43 PM PT ES +0.41%, NQ +0.80%.
→ A calm open: no gap down, oil easing on the Doha news.
- Monday overnight and pre-market: WTI fell to about $99.64 (−4.3%) and Brent $108.71 on a draft proposal after the Doha talks; Kospi +2.24%; Oracle −4% pre-market after filing a $10B common stock offering. ES traded 7,628.75–7,693.75 overnight.
→ Lower oil is the best news for equities; Oracle's share sale is another sign of the AI funding pressure.
- Monday open (7:00 AM PT): ISM Manufacturing 55.5 vs 54.5–54.6 expected; prices paid 75.2 (from 77.9), employment 52.4. SPX opened 7,610.83 and traded at 7,640.56 near 7:50 AM PT (high 7,662.23), above the weekly pivot; VIX 18.19.
→ SPX is testing the Bull scenario below early. It still has to hold above 7,624 into the close.
NEXT WEEK PIVOTS: SPX & NQ
Weekly floor pivots: P = (H+L+C)/3; R1 = 2P−L; S1 = 2P−H; R2 = P+(H−L); S2 = P−(H−L). Yahoo Finance data, week of 10/26–10/30. Source: K2TP Framework.
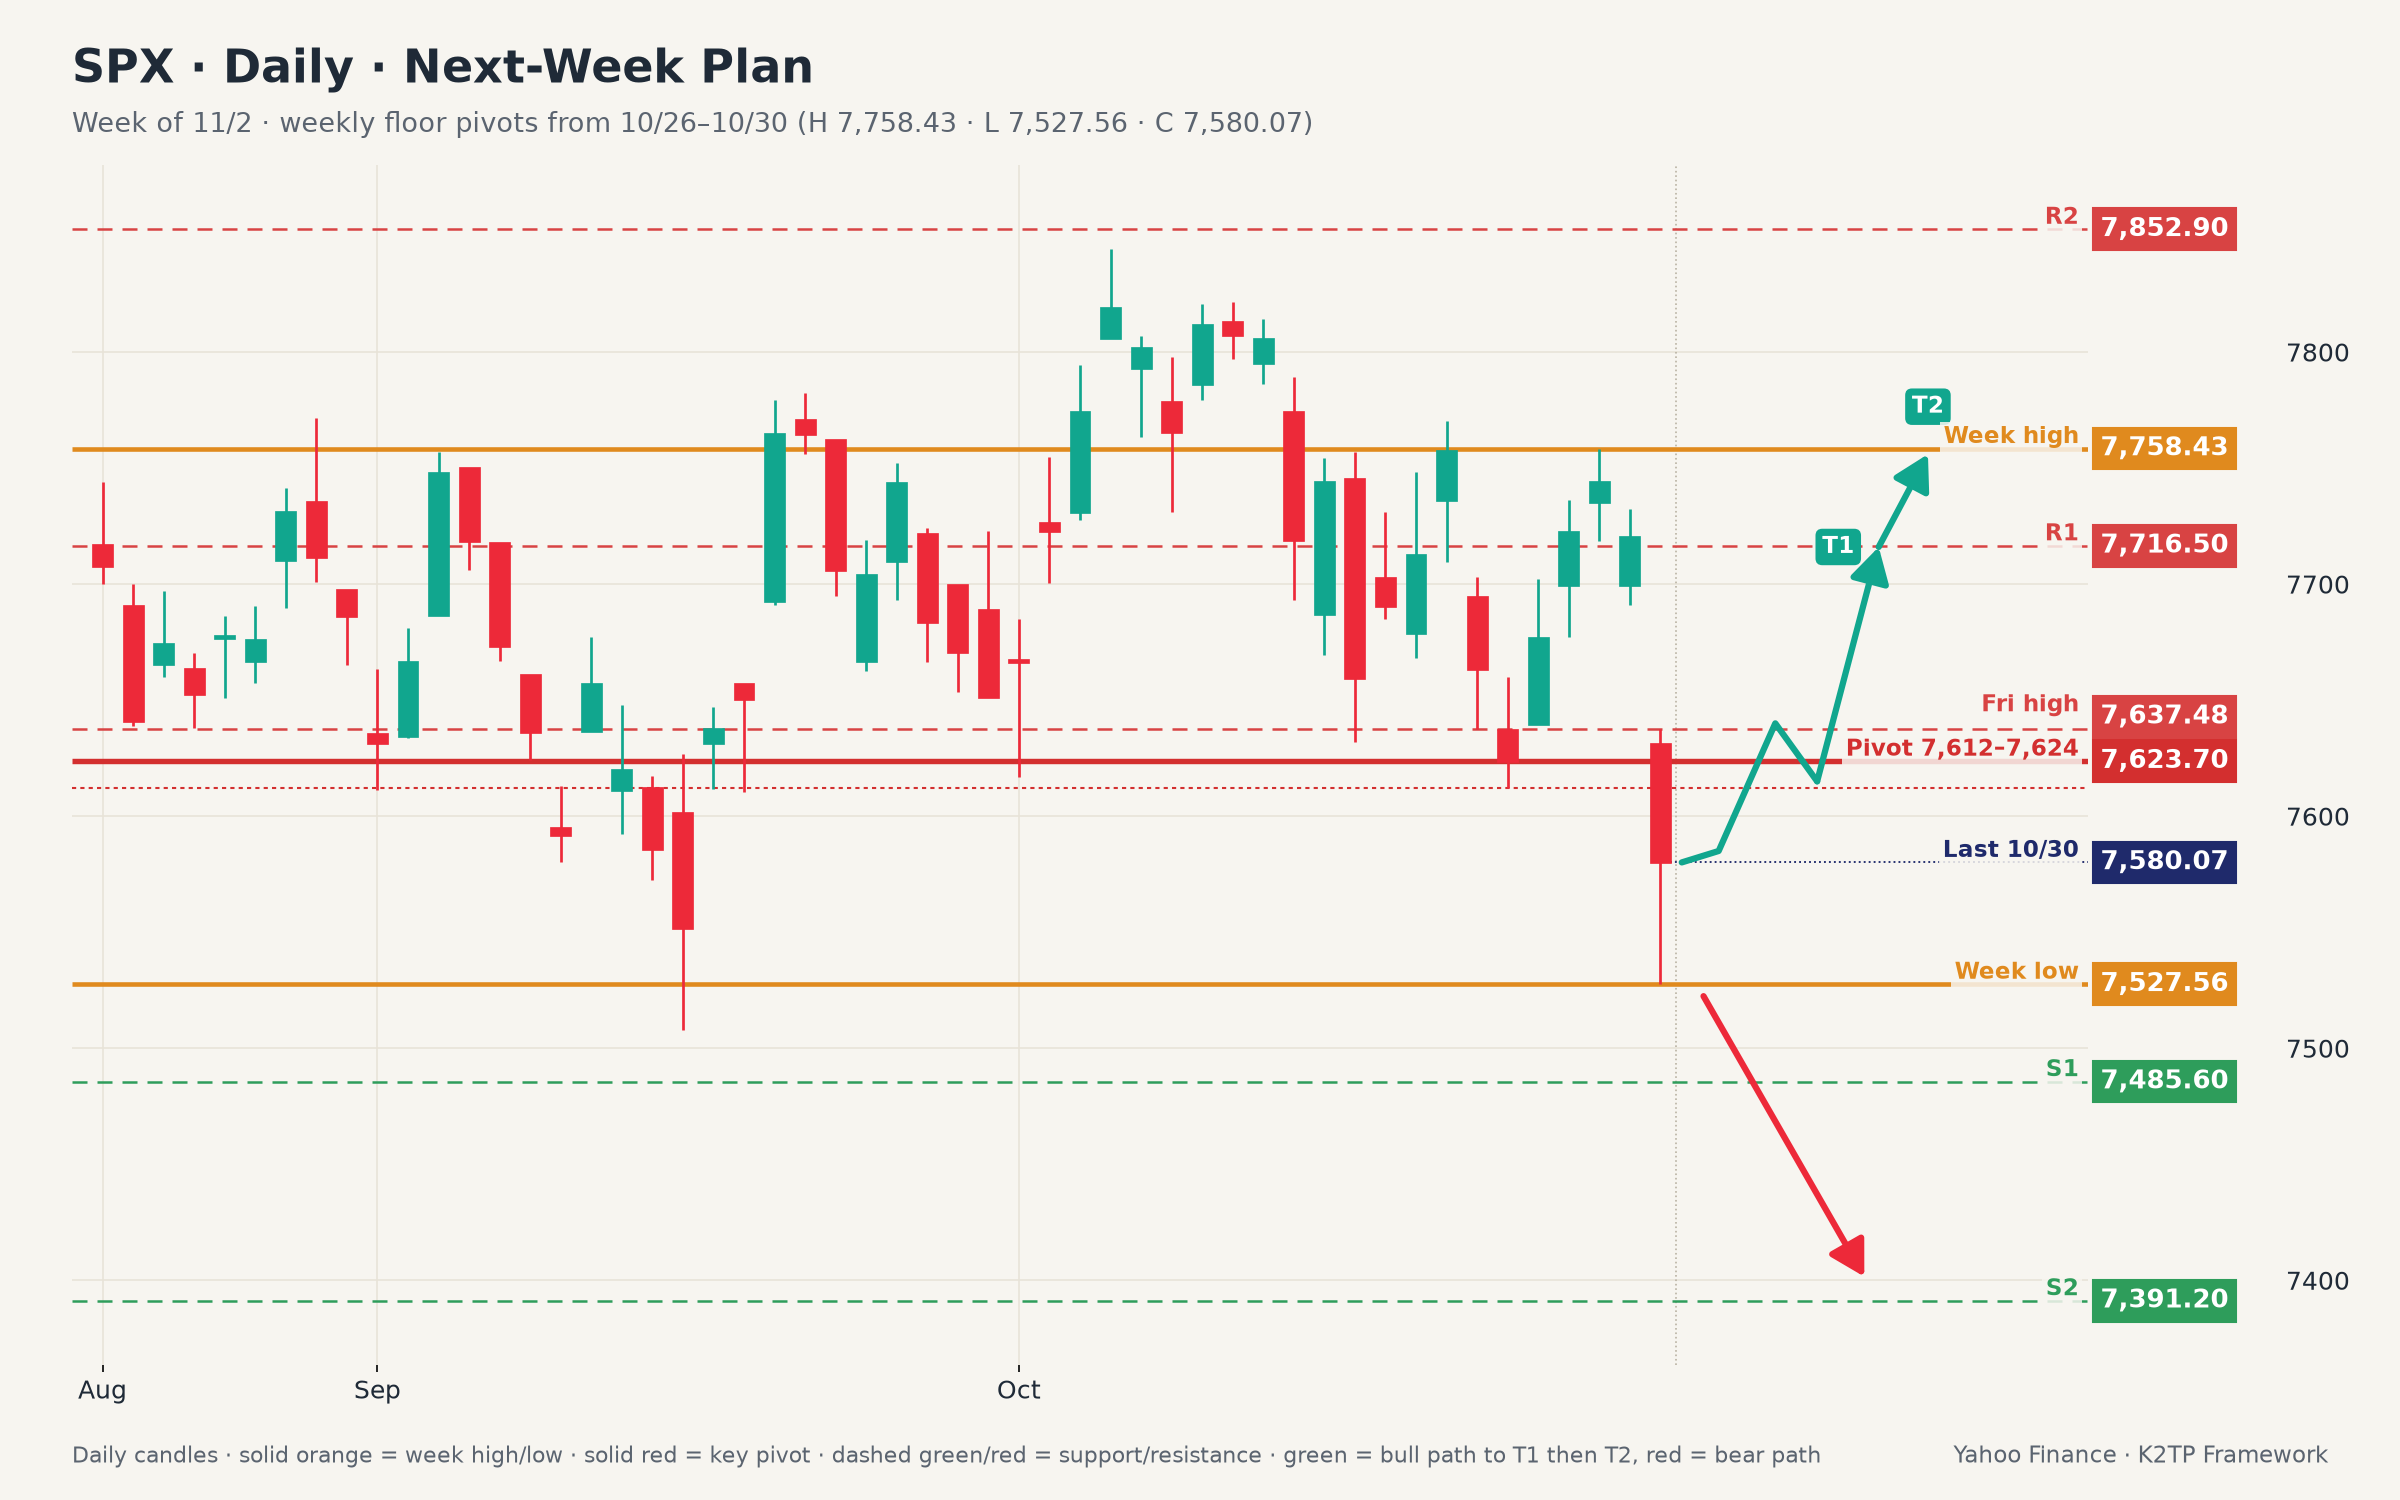
SPX (cash): H 7,758.43 (Wed 11:40 AM PT), L 7,527.56 (Fri 11:50 AM PT), C 7,580.07.
- Floor pivots: P 7,622.0, R1 7,716.5, R2 7,852.9, S1 7,485.6, S2 7,391.2.
- Main pivot zone 7,612–7,624: P + prior-week close (7,623.68) + Oct 23 low (7,612.07).
- Resistance: 7,637.48 (Friday high), 7,716–7,720 (R1 + Thursday close 7,720.39), 7,758 (week high), 7,853 (R2). Support: 7,528 (week low), 7,486 (S1), 7,391 (S2).
- Bull: hold above 7,624 with VIX under 19.42 → 7,716–7,720; confirmed above 7,758.
- Neutral: 7,528–7,624 range into the midterms and the jobs report.
- Bear: close below 7,528 with VIX above ~20.8 (VIX3M) and especially above 23.93 → 7,486, then 7,391.
→ While SPX is below 7,716, favor call spreads above 7,758 and keep puts far below 7,486 until Apple, AMD and Friday's jobs report are out.
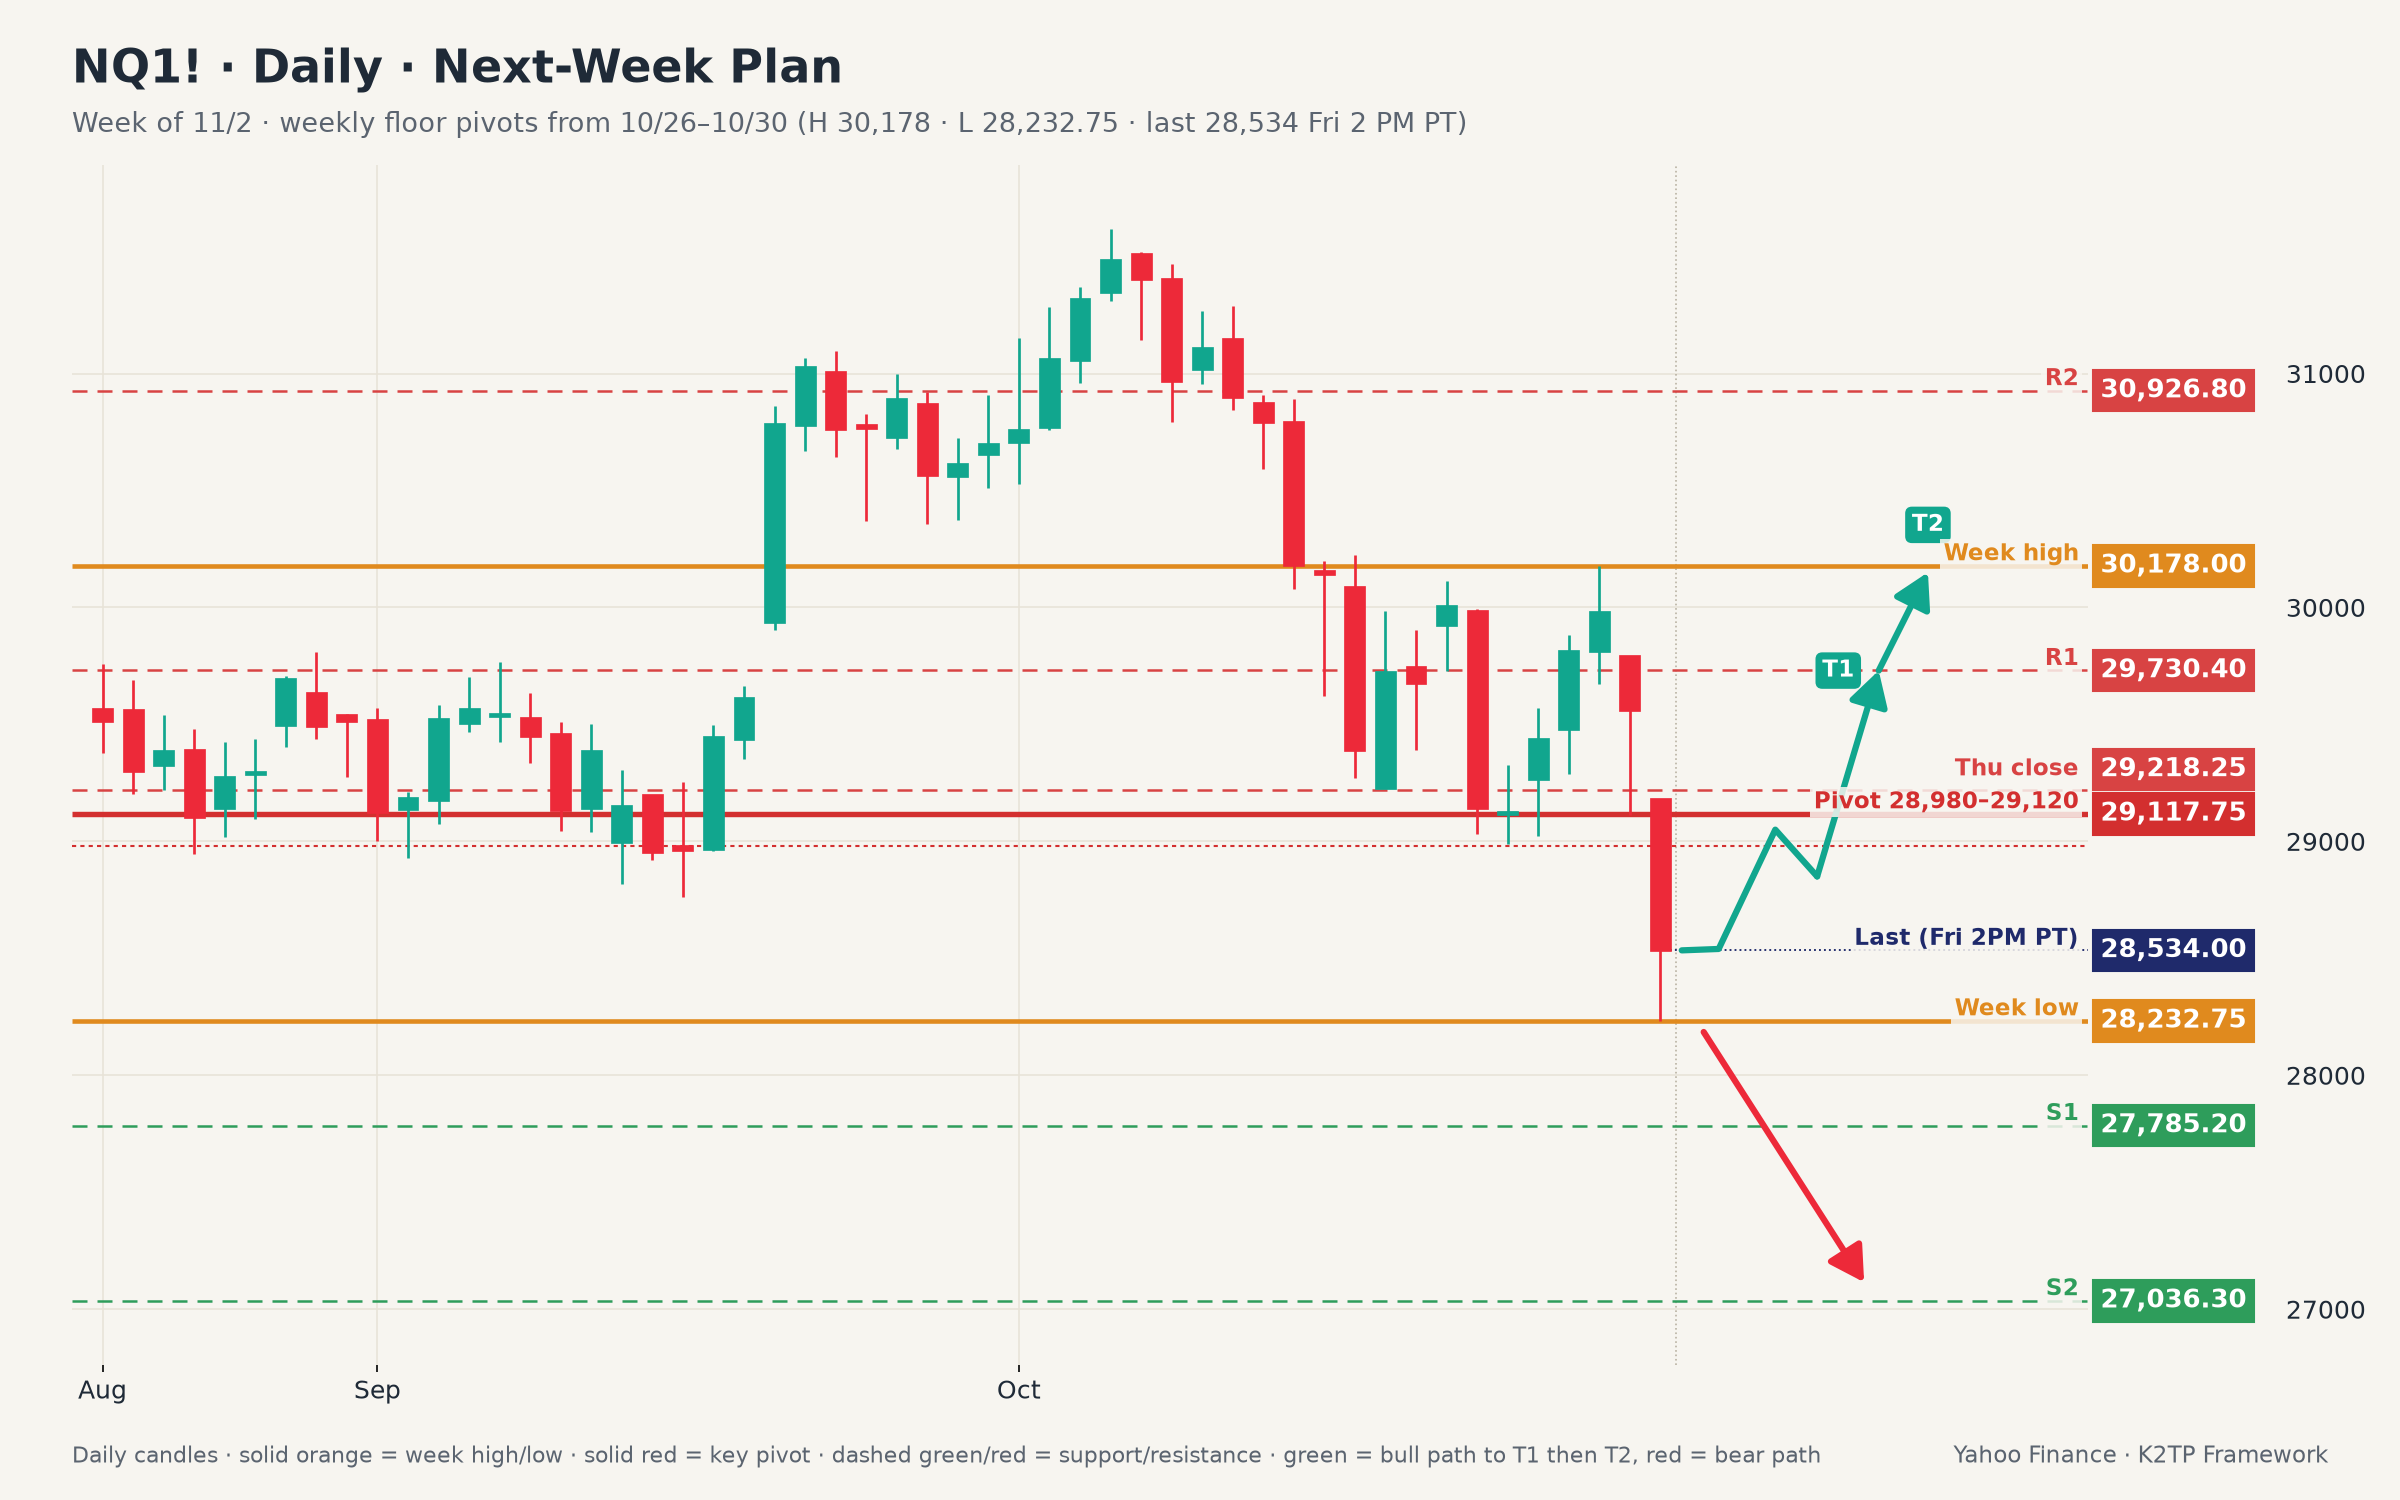
NQ (NQ=F, front month, full futures session Sun 3 PM PT → Fri 2 PM PT): H 30,178.00 (Wed 1:00 PM PT), L 28,232.75 (Fri 11:50 AM PT), C 28,534.00 (Friday 2 PM PT close, not settlement).
- Floor pivots: P 28,981.6, R1 29,730.4, R2 30,926.8, S1 27,785.2, S2 27,036.3.
- Main pivot zone 28,980–29,120: P + prior-week close (29,117.75). Thursday's close of 29,218.25 is the next resistance.
- Resistance: 29,218, 29,562 (Friday high), 29,730 (R1), 30,178 (week high), 30,927 (R2). Support: 28,233 (week low), 27,785 (S1), 27,036 (S2).
- Bull: reclaim and hold above 29,120 → 29,562–29,730; confirmed above 30,178.
- Neutral: 28,233–29,120 range. Monday morning NQ trades about 28,825, inside this range.
- Bear: close below 28,233 → 27,785, then 27,036.
→ While NQ is below 29,120, favor call spreads above 29,730 and keep puts far below 27,785 until Apple and AMD have reported.
- NDX cash reference (H 29,848.71, L 28,093.24, C 28,384.85): P 28,775.6, R1 29,458.0, R2 30,531.1, S1 27,702.5, S2 27,020.1.
- Basis: at Friday's close NQ was about 149 points above NDX and ES (7,614) about 34 points above SPX. Add that spread to cash levels when trading futures.
BOTTOM LINE
- SPX lost only 0.57%, but NDX fell 1.98% while RUT rose 1.29% and RSP 0.82%: a second rotation week out of AI megacaps.
- AI demand is not the problem. Free cash flow is: Alphabet and Amazon were sold for spending, Intel for its guide, and Oracle is now selling stock.
- The Fed held but leaned hawkish (two hike dissents, Logan wants two more hikes), while oil stayed above $100 for most of the week.
- The regime ends the week 🔴 RISK-OFF. It moves back to 🟡 TRANSITION only if SPX holds above the 7,612–7,624 pivot zone with VIX under 19.42; Monday morning's ISM beat and oil drop are testing that. A close below 7,528 opens the Bear case.
WHAT TO WATCH NEXT WEEK (PT)
| Day | Data (PT) | Earnings |
|---|---|---|
| Mon 11/2 | 7:00 AM: ISM Manufacturing (55.5, beat) | After: AAPL, PLTR |
| Tue 11/3 | US midterm elections; 7:00 AM: JOLTS | After: AMD |
| Wed 11/4 | 5:15 AM: ADP employment; 7:00 AM: ISM Services | n/a |
| Thu 11/5 | 5:30 AM: jobless claims | n/a |
| Fri 11/6 | 5:30 AM: October jobs report (forecast 63K, prior 29K) | n/a |
- Also this week: McDonald's, Qualcomm, Uber, Pfizer, Amgen (check company notices for exact days)
- Iran: the Doha talks and Hormuz reopening; Trump pledged no attack before the Nov 3 vote
- Oracle's $10B share sale and Apple's numbers decide whether AI megacaps stabilize
Expected (Bull): SPX holds above 7,624 with VIX under 19.42, WTI below $100 and a calm midterm result. Expected (Bear): SPX closes under 7,527.56 with VIX above 23.93, oil back above $104 and a hot jobs report that lifts hike odds.
Sources: K2TP daily syntheses for Oct 26–30, 2026, the K2TP briefs for Oct 26–30 and the Nov 2 Pre-Market brief. Weekly closes from Yahoo Finance; oil settlements, news and data from Reuters, AP, CNBC, WSJ and Bloomberg; weekend news from Reuters, CNBC and Business Standard; earnings Sankeys from official company releases. Analysis: K2TP Framework.