Week 10/19–10/23: Meta's Capex Shock and $117 Brent Hand SPX a Second Weekly Loss as Small Caps Rally
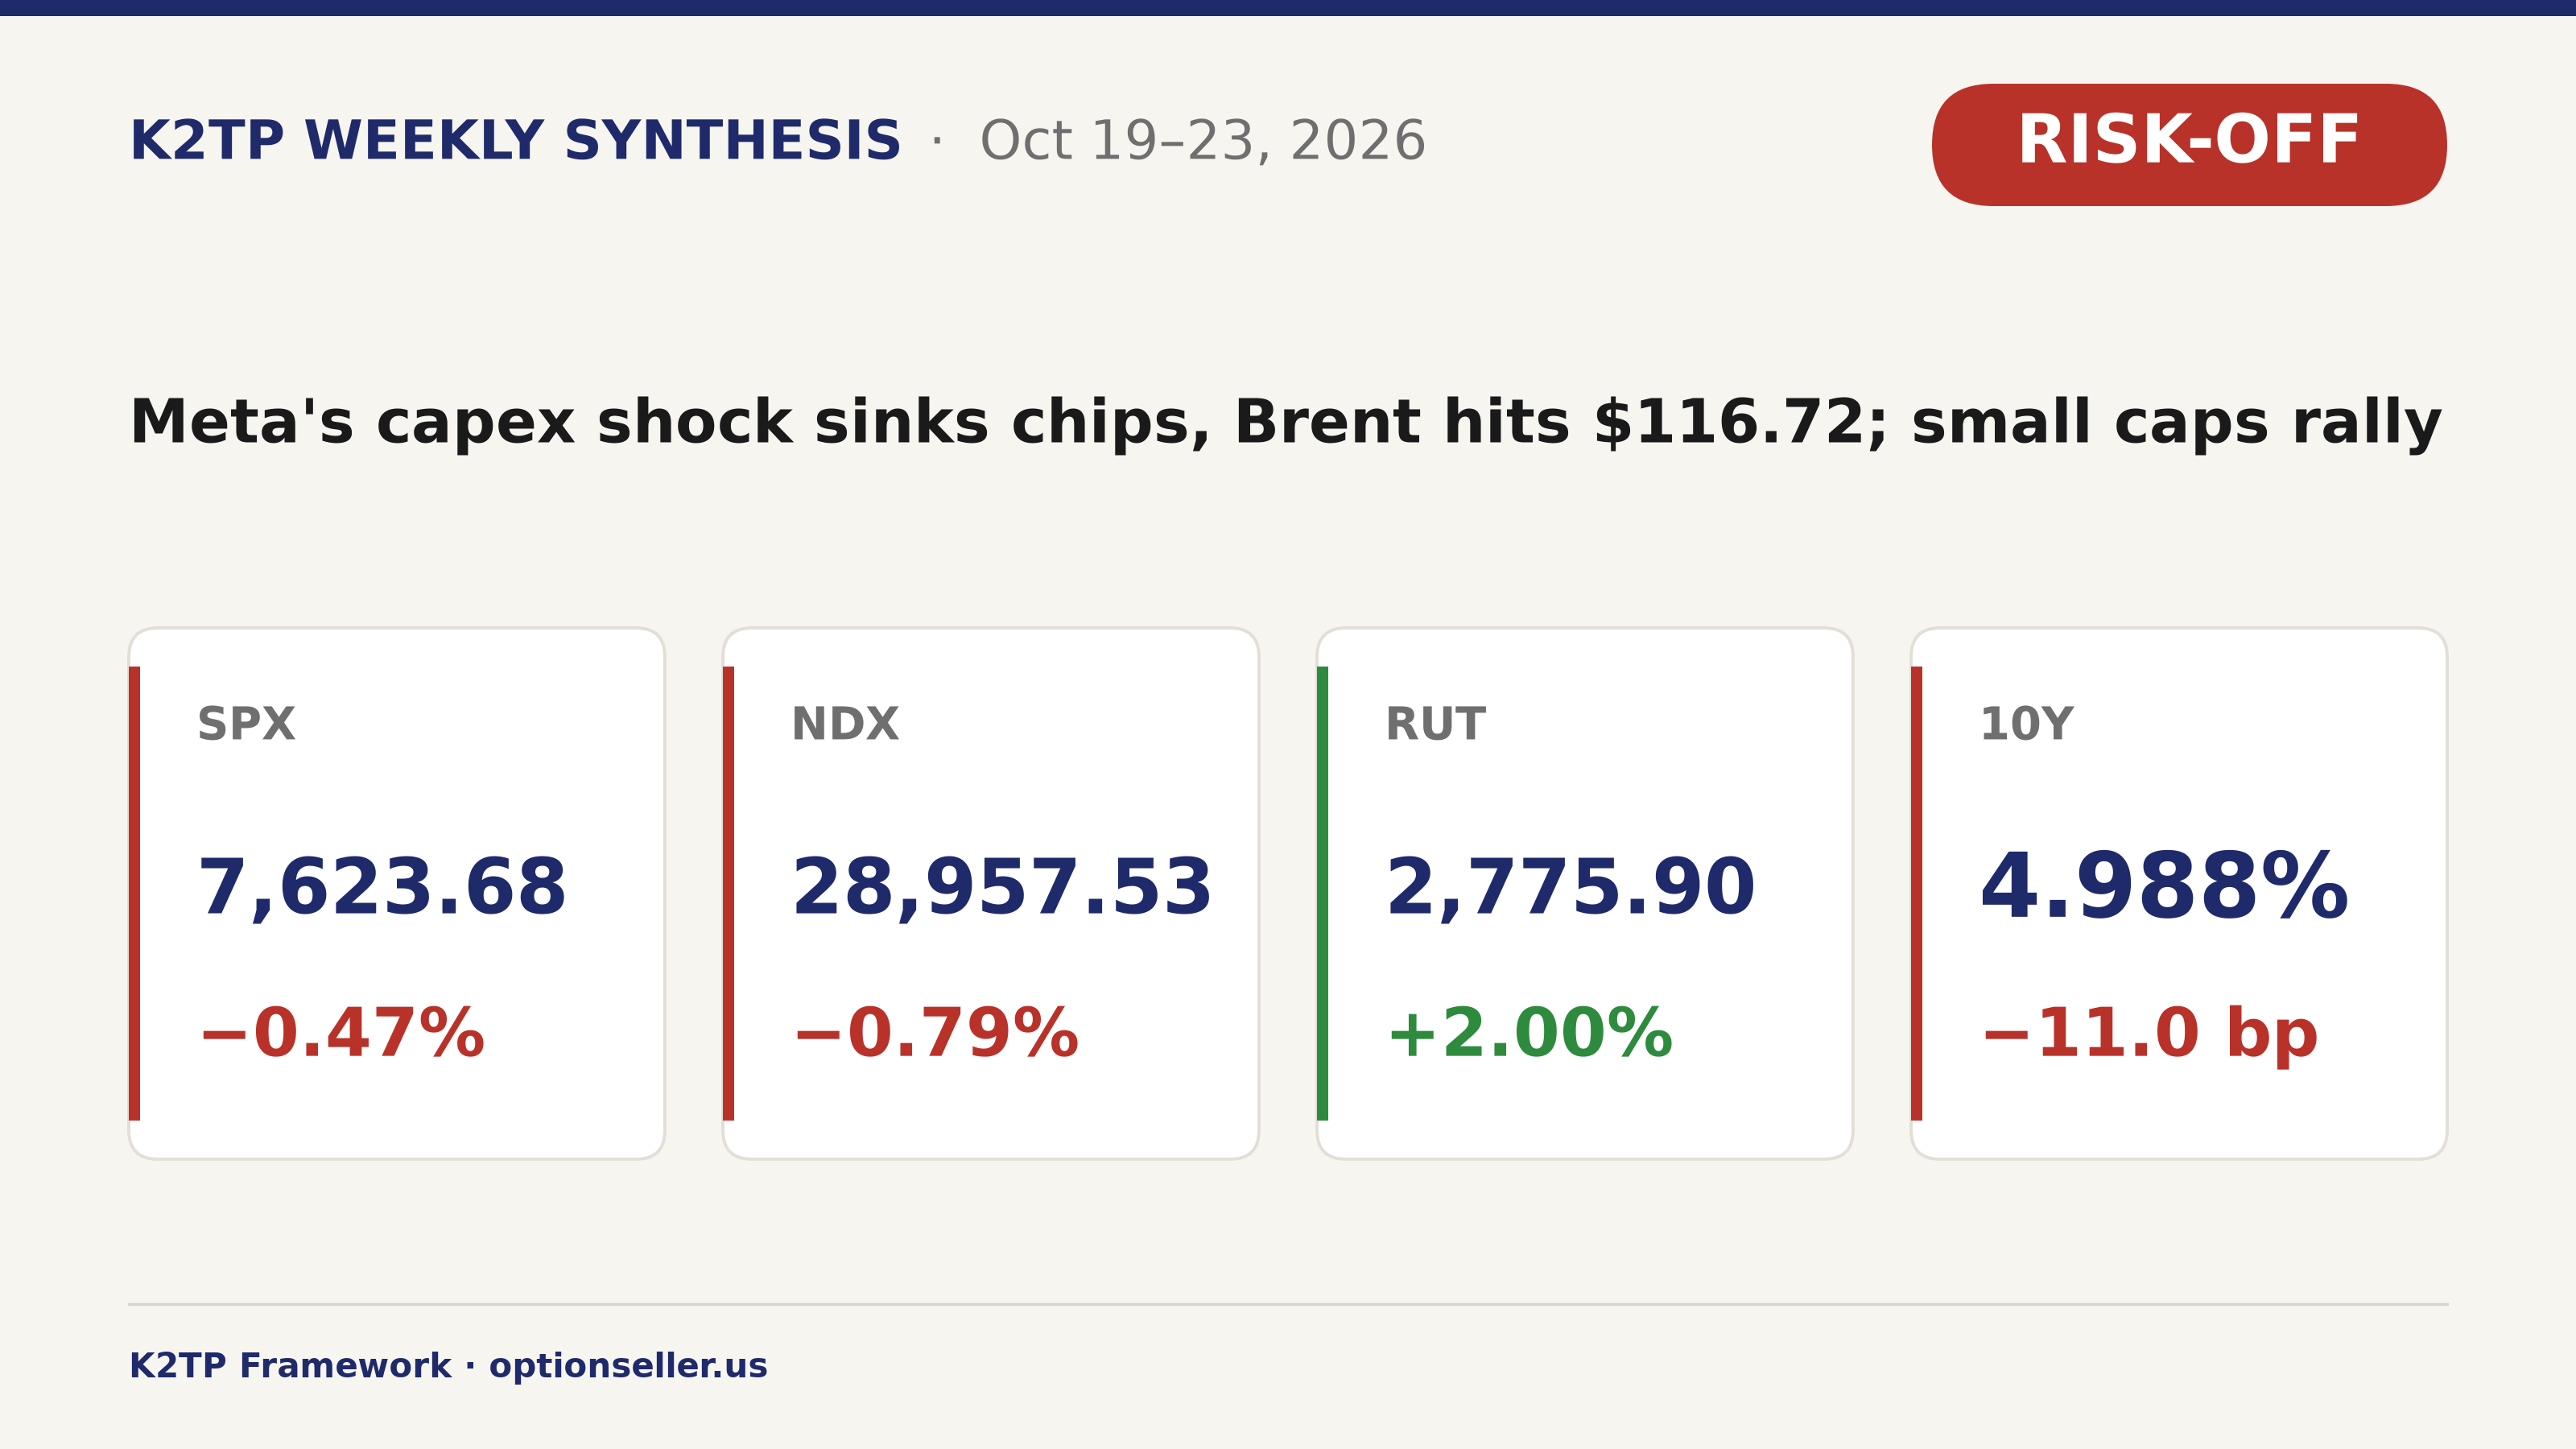
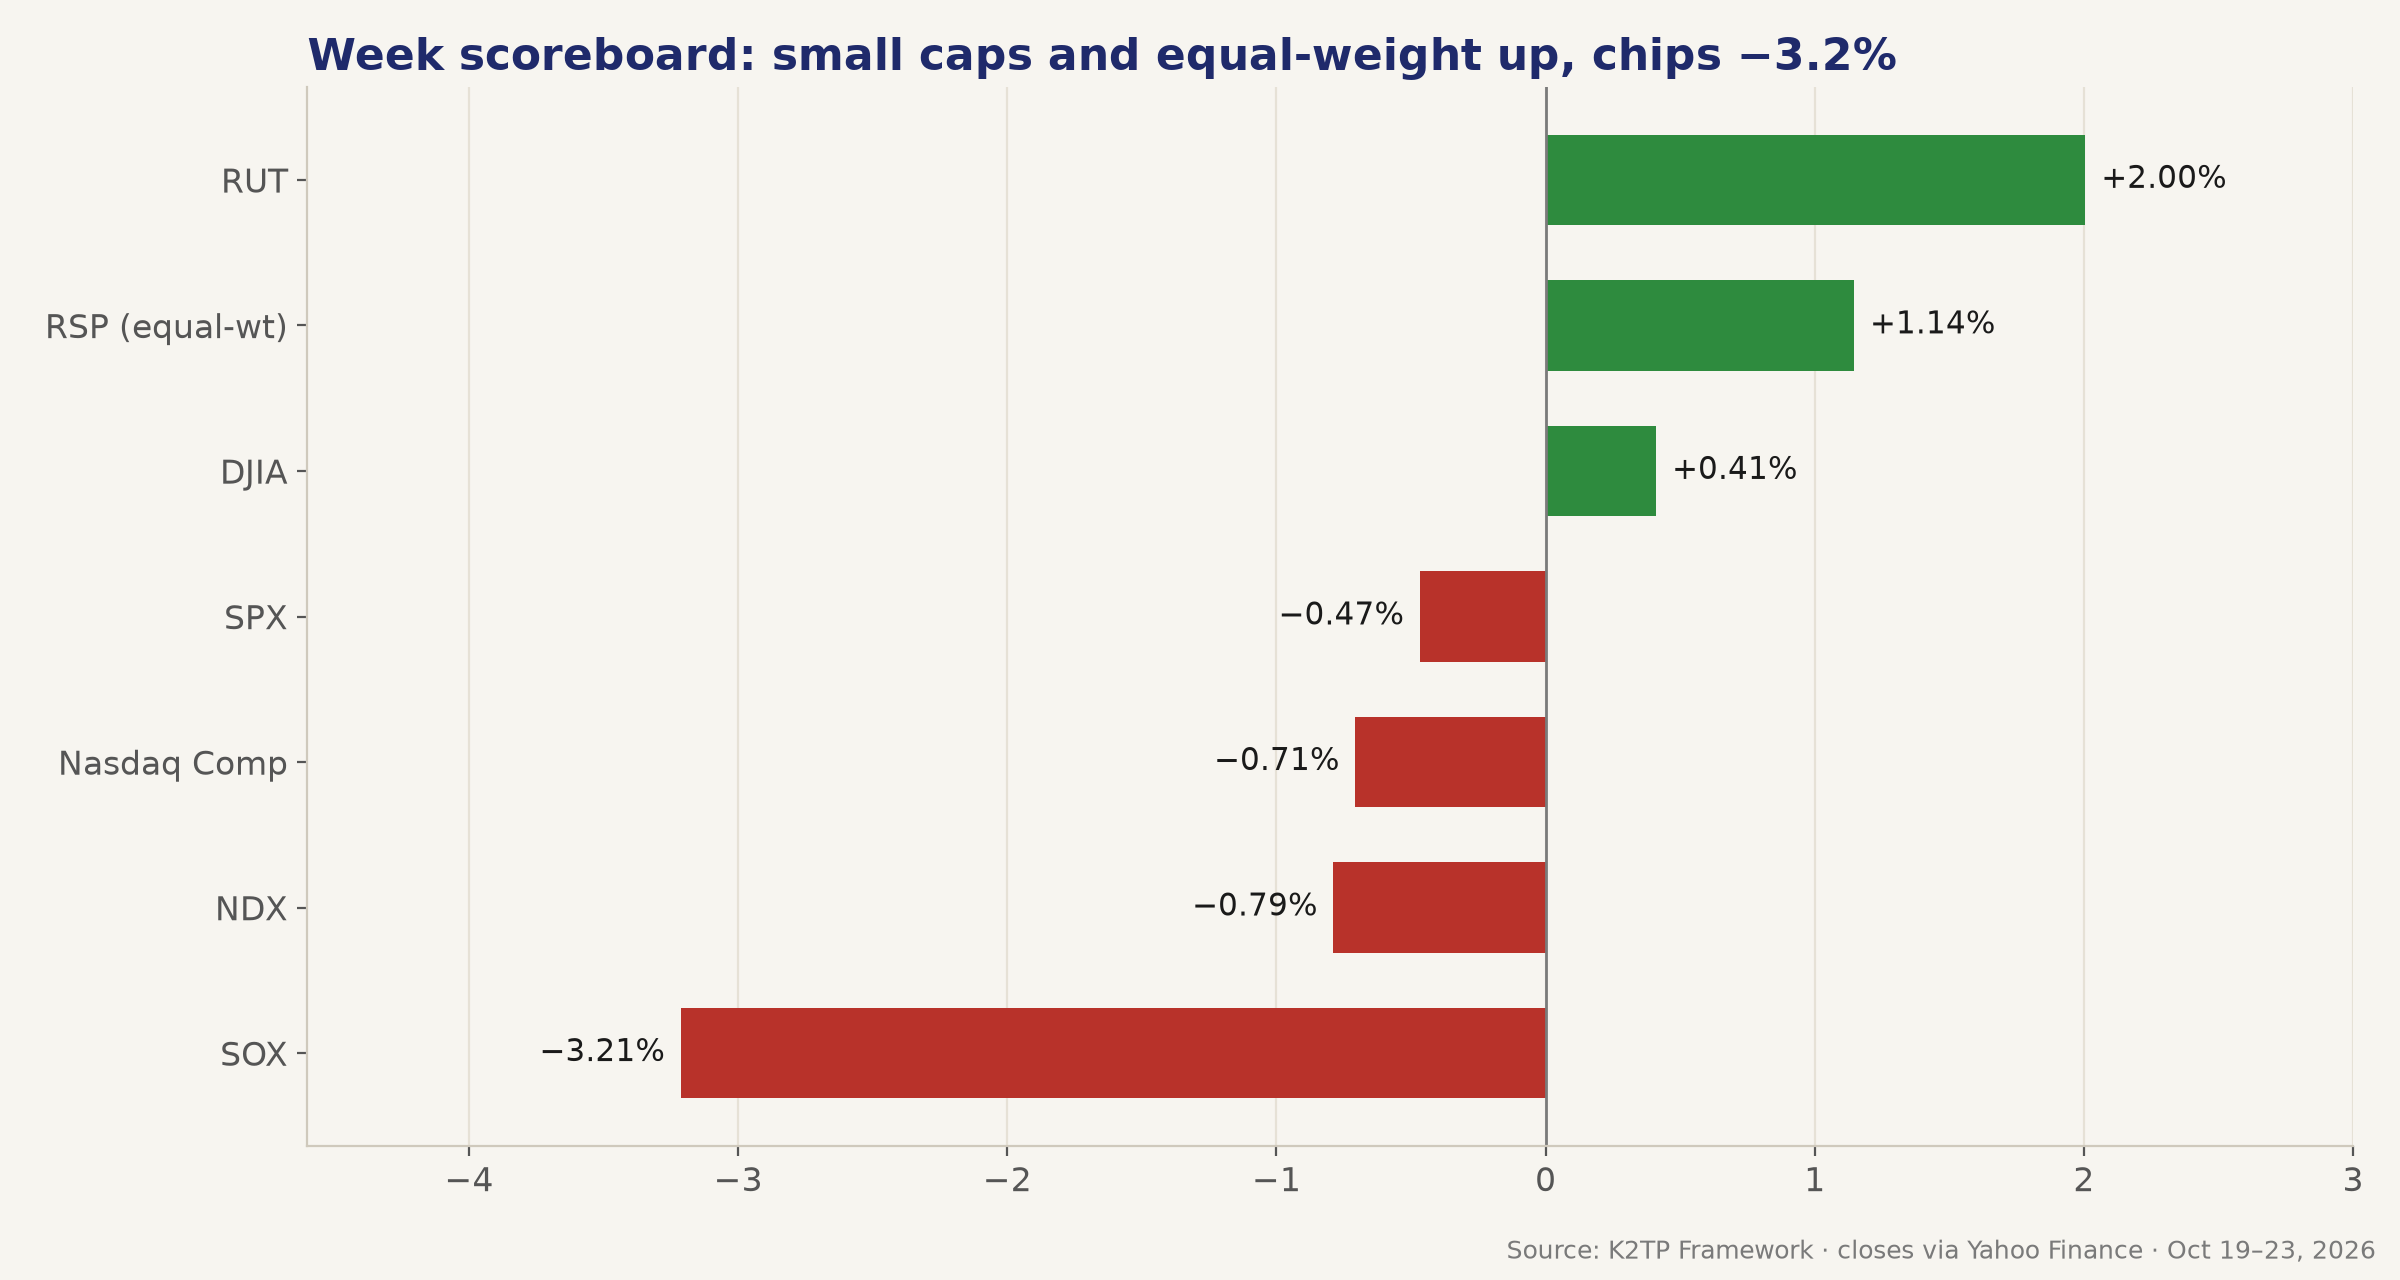
SPX −0.47%, NDX −0.79%, RUT +2.00%, VIX −2.7%, 10Y −11.0 bp. Money left AI and chips for small caps, value and energy; the regime ends the week RISK-OFF.
WEEK'S KEY HEADLINES
- SPX −0.47% to 7,623.68, its second straight weekly loss (AP); NDX −0.79%, Nasdaq Composite −0.71%; the Dow +0.41% for its third straight weekly gain (Reuters)
- RUT +2.00% and equal-weight RSP +1.14% beat SPX by about 1.6 points or more: a rotation week, not a broad liquidation
- SPX rose three days to 7,757.17 on Wednesday (high 7,770.40), then Meta's capex shock on Thursday gave it its worst day since July (−1.21%)
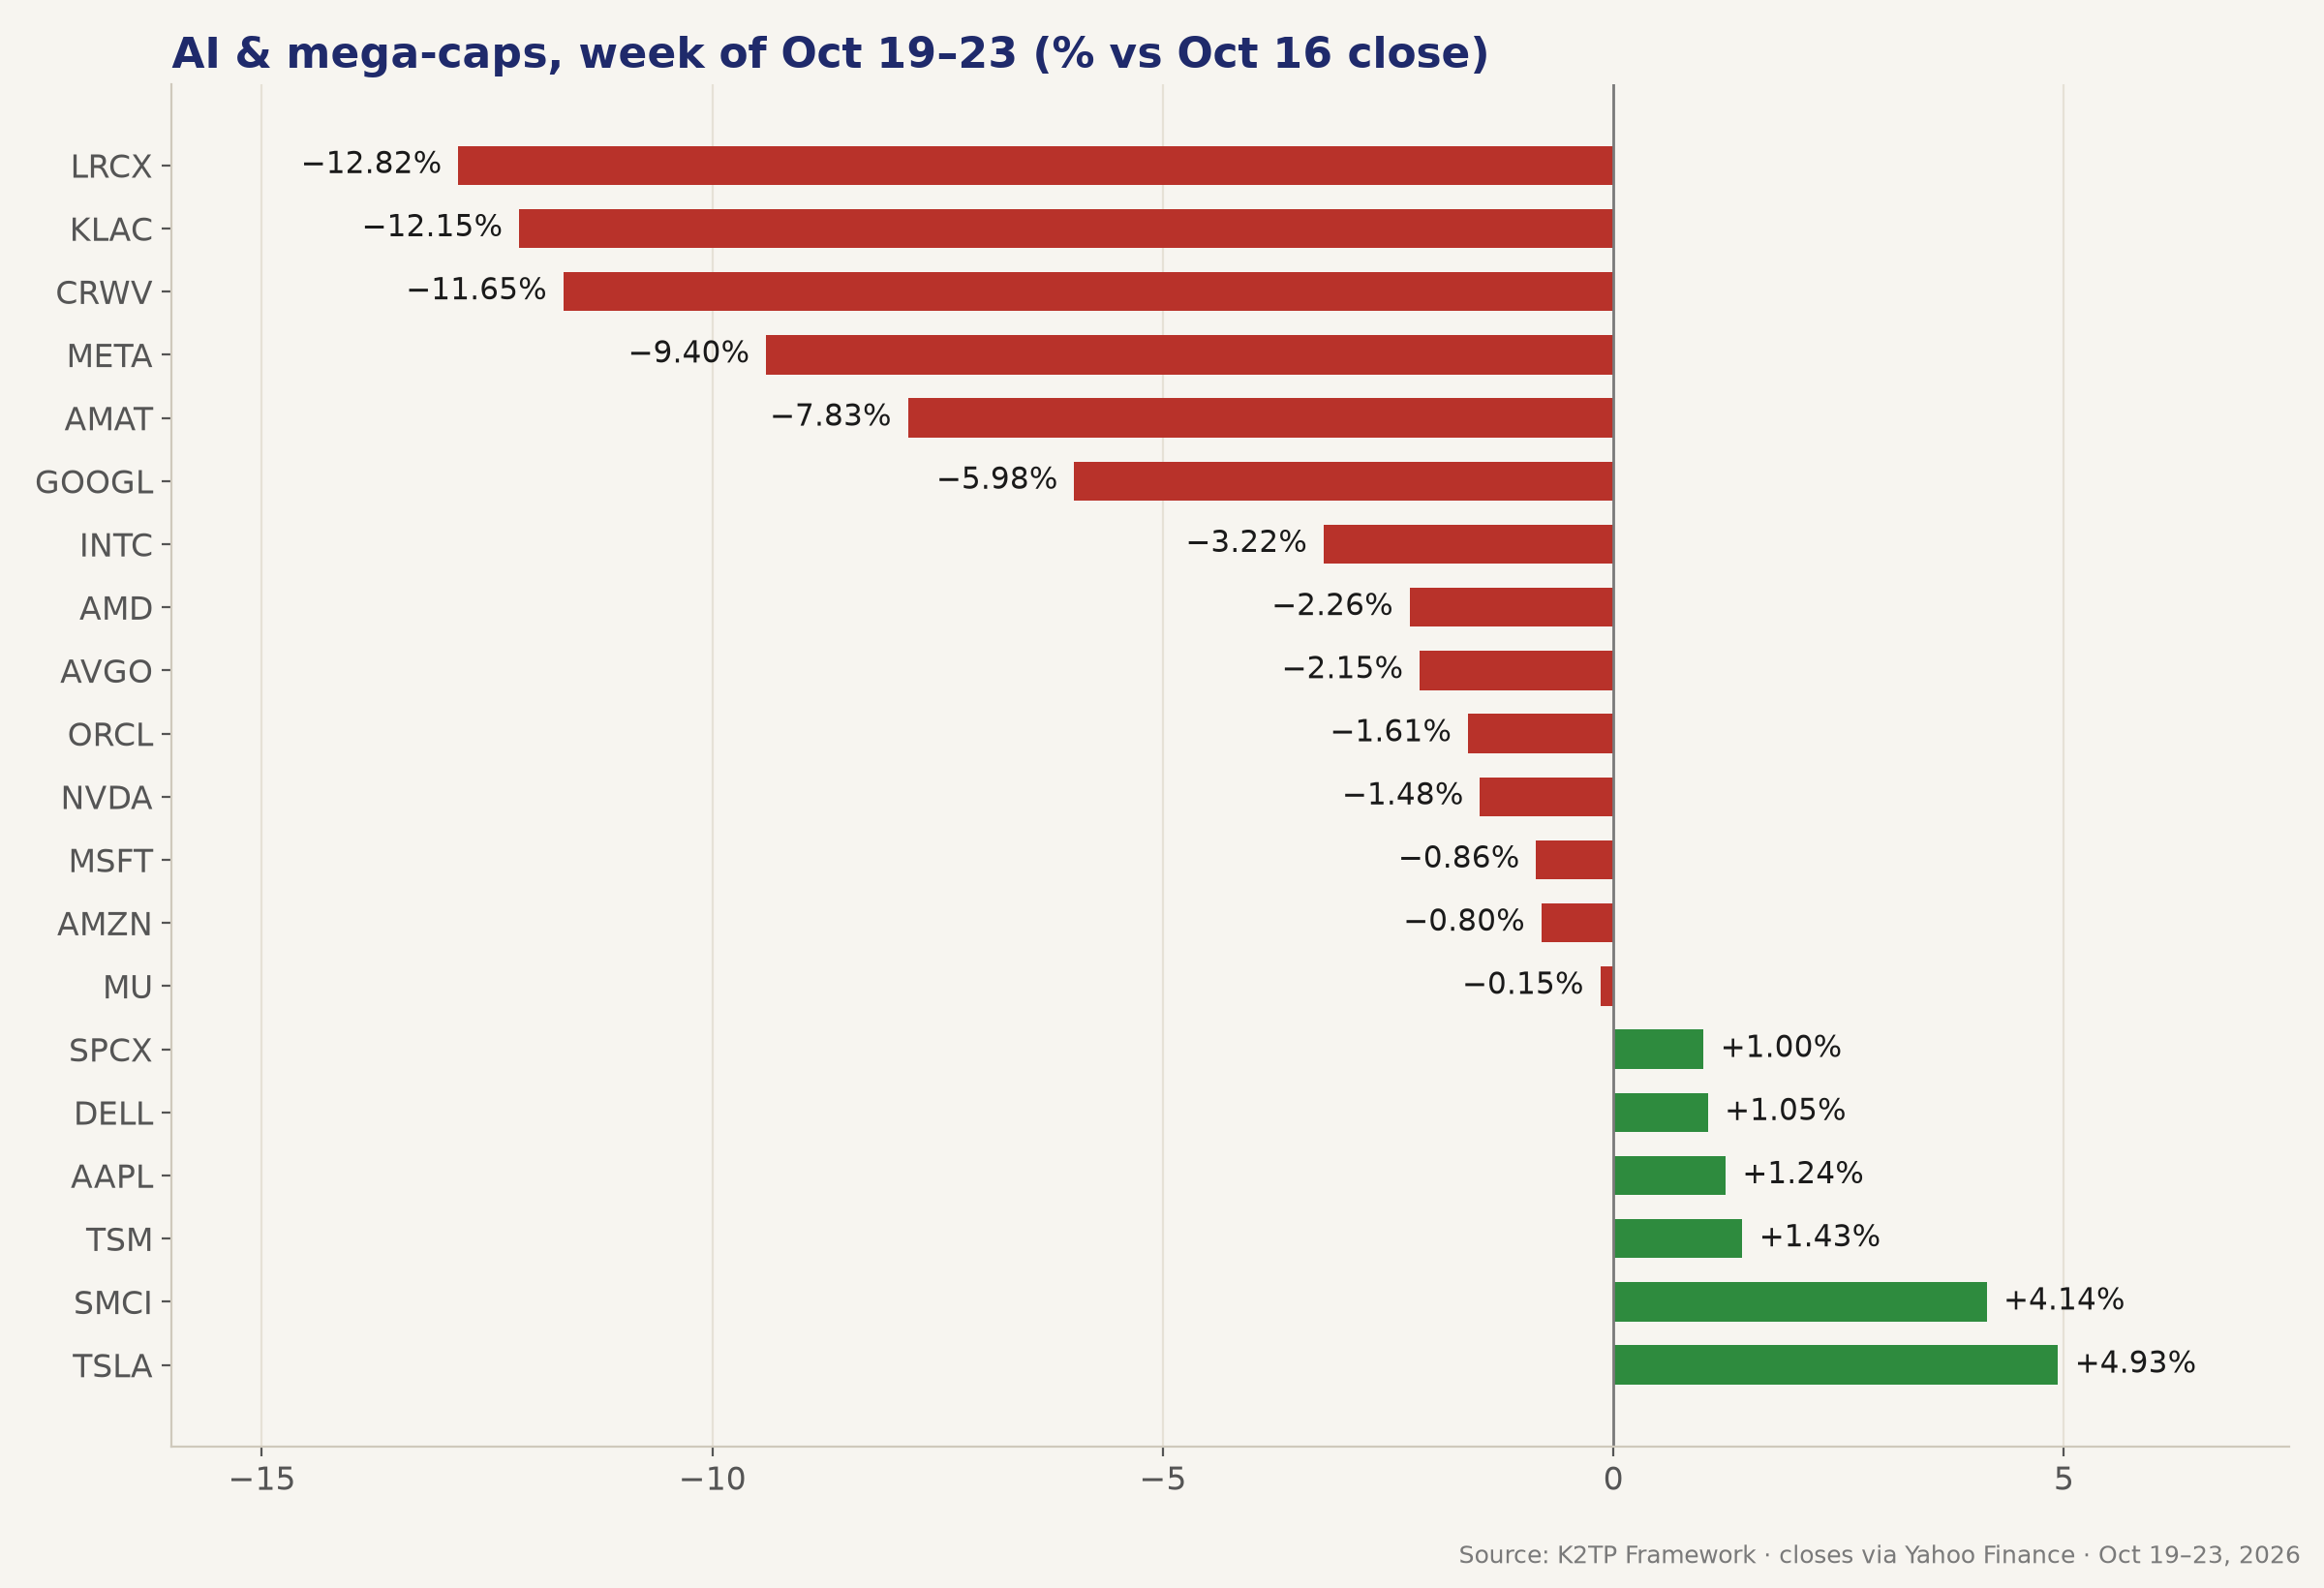
- SOX −3.21% for the week after −6.72% on Thursday; LRCX −12.82%, KLAC −12.15%, CRWV −11.65%, META −9.40%, AMAT −7.83%
- Earnings: SpaceX revenue +161% and Super Micro's raised guide lifted AI hardware; Meta beat but raised capex to $135–145B and created nonvoting Class C shares; Tesla, Netflix and Western Digital fell after their reports
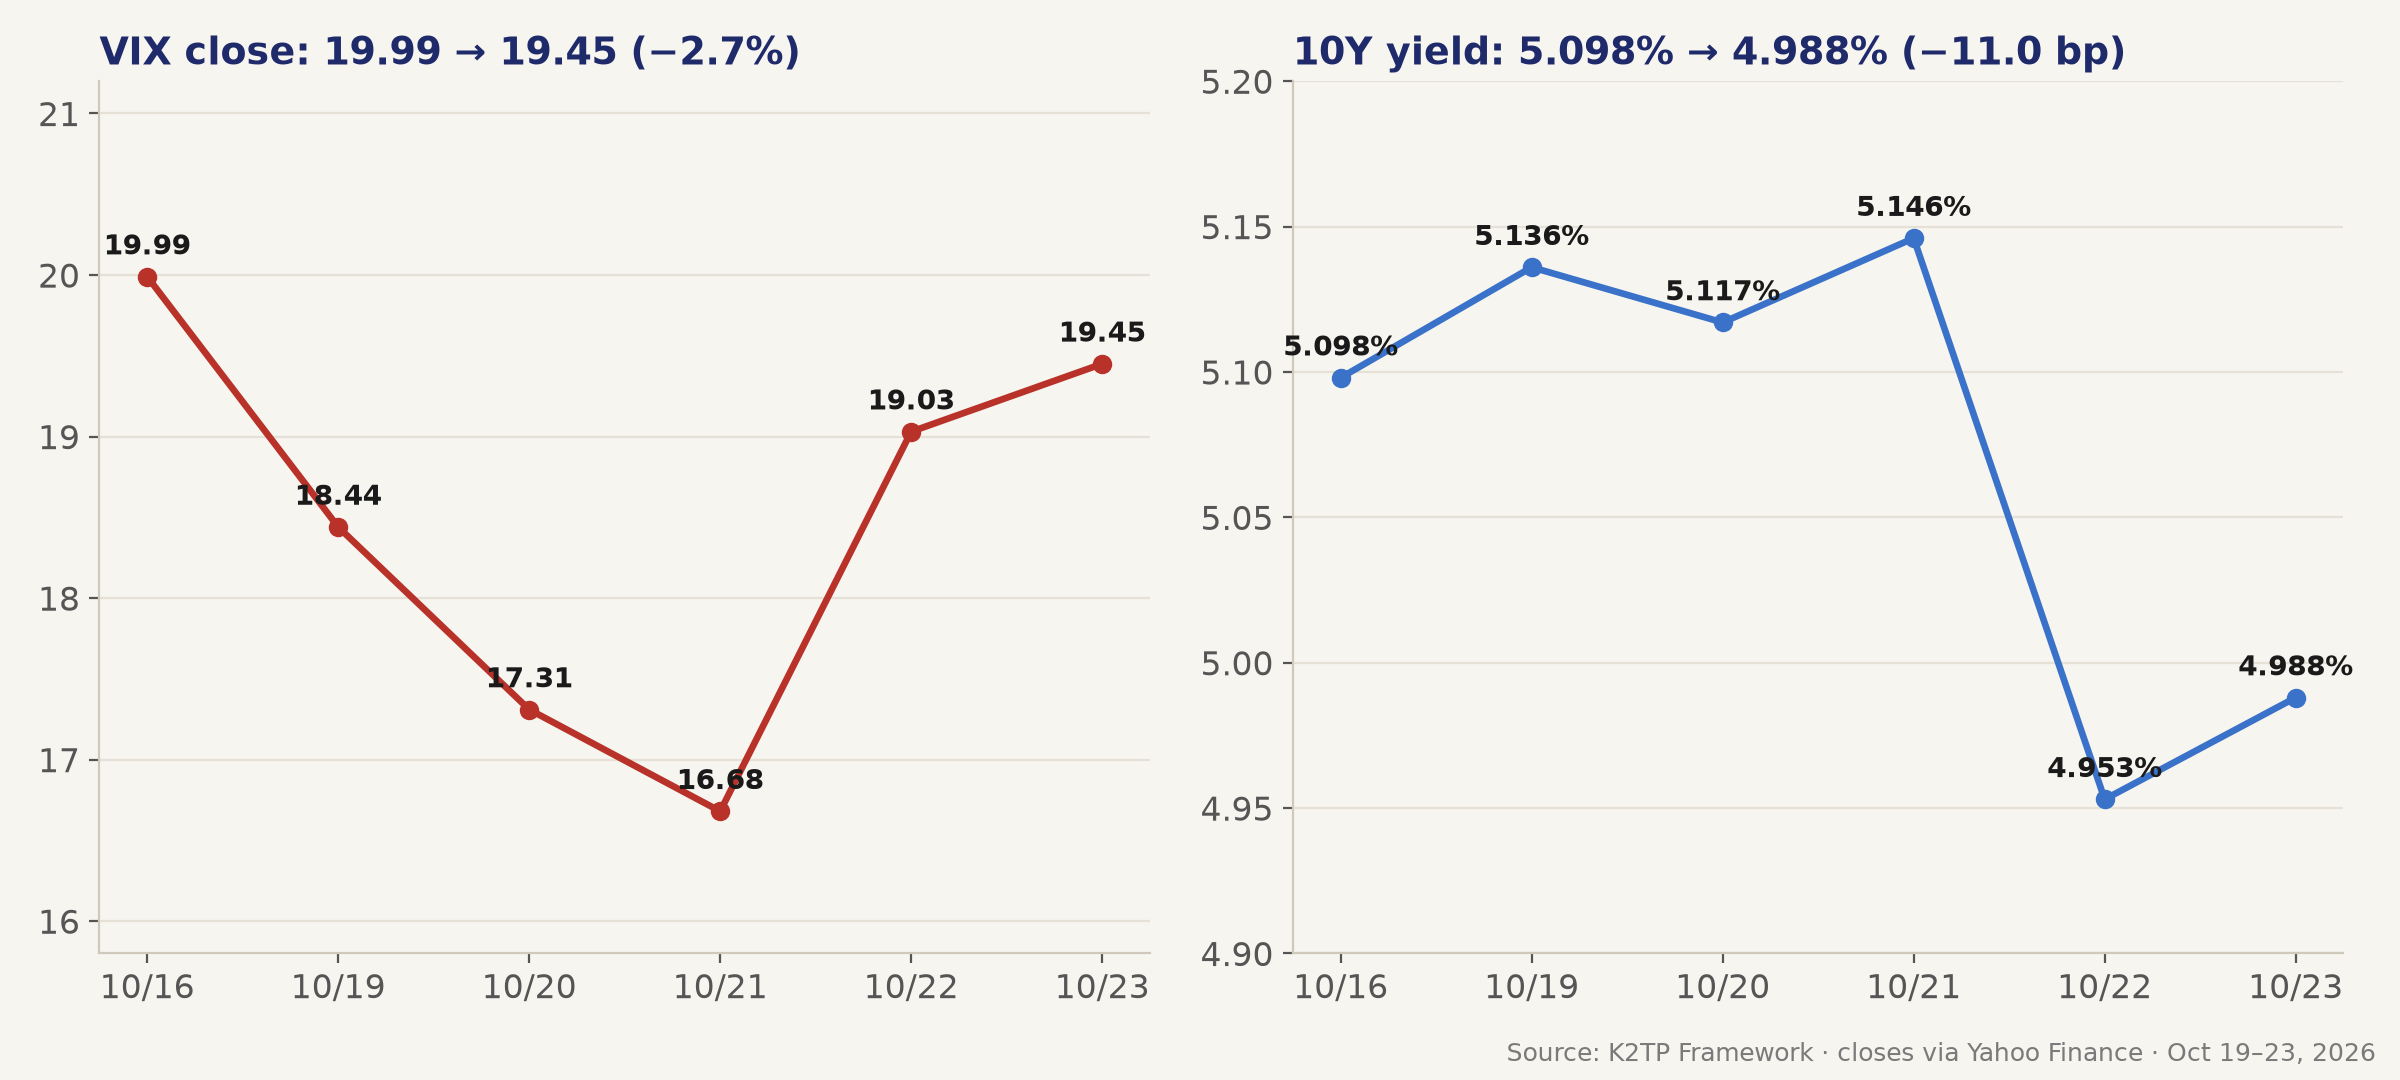
- 10Y −11.0 bp to 4.988% (5.098% on Oct 16), almost all from Thursday's −19.3 bp haven rally, the biggest drop since March 10, 2023 (Reuters)
- Brent +6.2% to $116.72, its highest since April 29, on U.S.–Iran escalation risk and Houthi attacks in Saudi Arabia; XLE +1.60% and energy at a record
- SpaceX's talks to lease ~80,000 cell sites hit telecoms on Friday: T −10.71% and TMUS −7.89% for the week, while CCI +4.51%
- VIX 19.99 → 19.45 (−2.7%), but the path was a V: 16.68 on Wednesday, 20.66 intraday on Friday
- Sectors: 8 of 11 up; XLE +1.60% and XLV +1.45% led, XLC −4.36% and XLI −1.87% lagged
- Regime: 🔴 RISK-OFF (Mon pre-market) → 🟡 TRANSITION (Mon midday–Wed) → 🔴 RISK-OFF (Thu–Fri close)
- Weekend: Trump kept both a strike and a deal with Iran open ("no strike today" on Sunday), the Houthis claimed attacks on Saudi oil infrastructure (damage unconfirmed), BTC broke $80K. See WEEKEND DEVELOPMENTS
THE WEEK DAY BY DAY
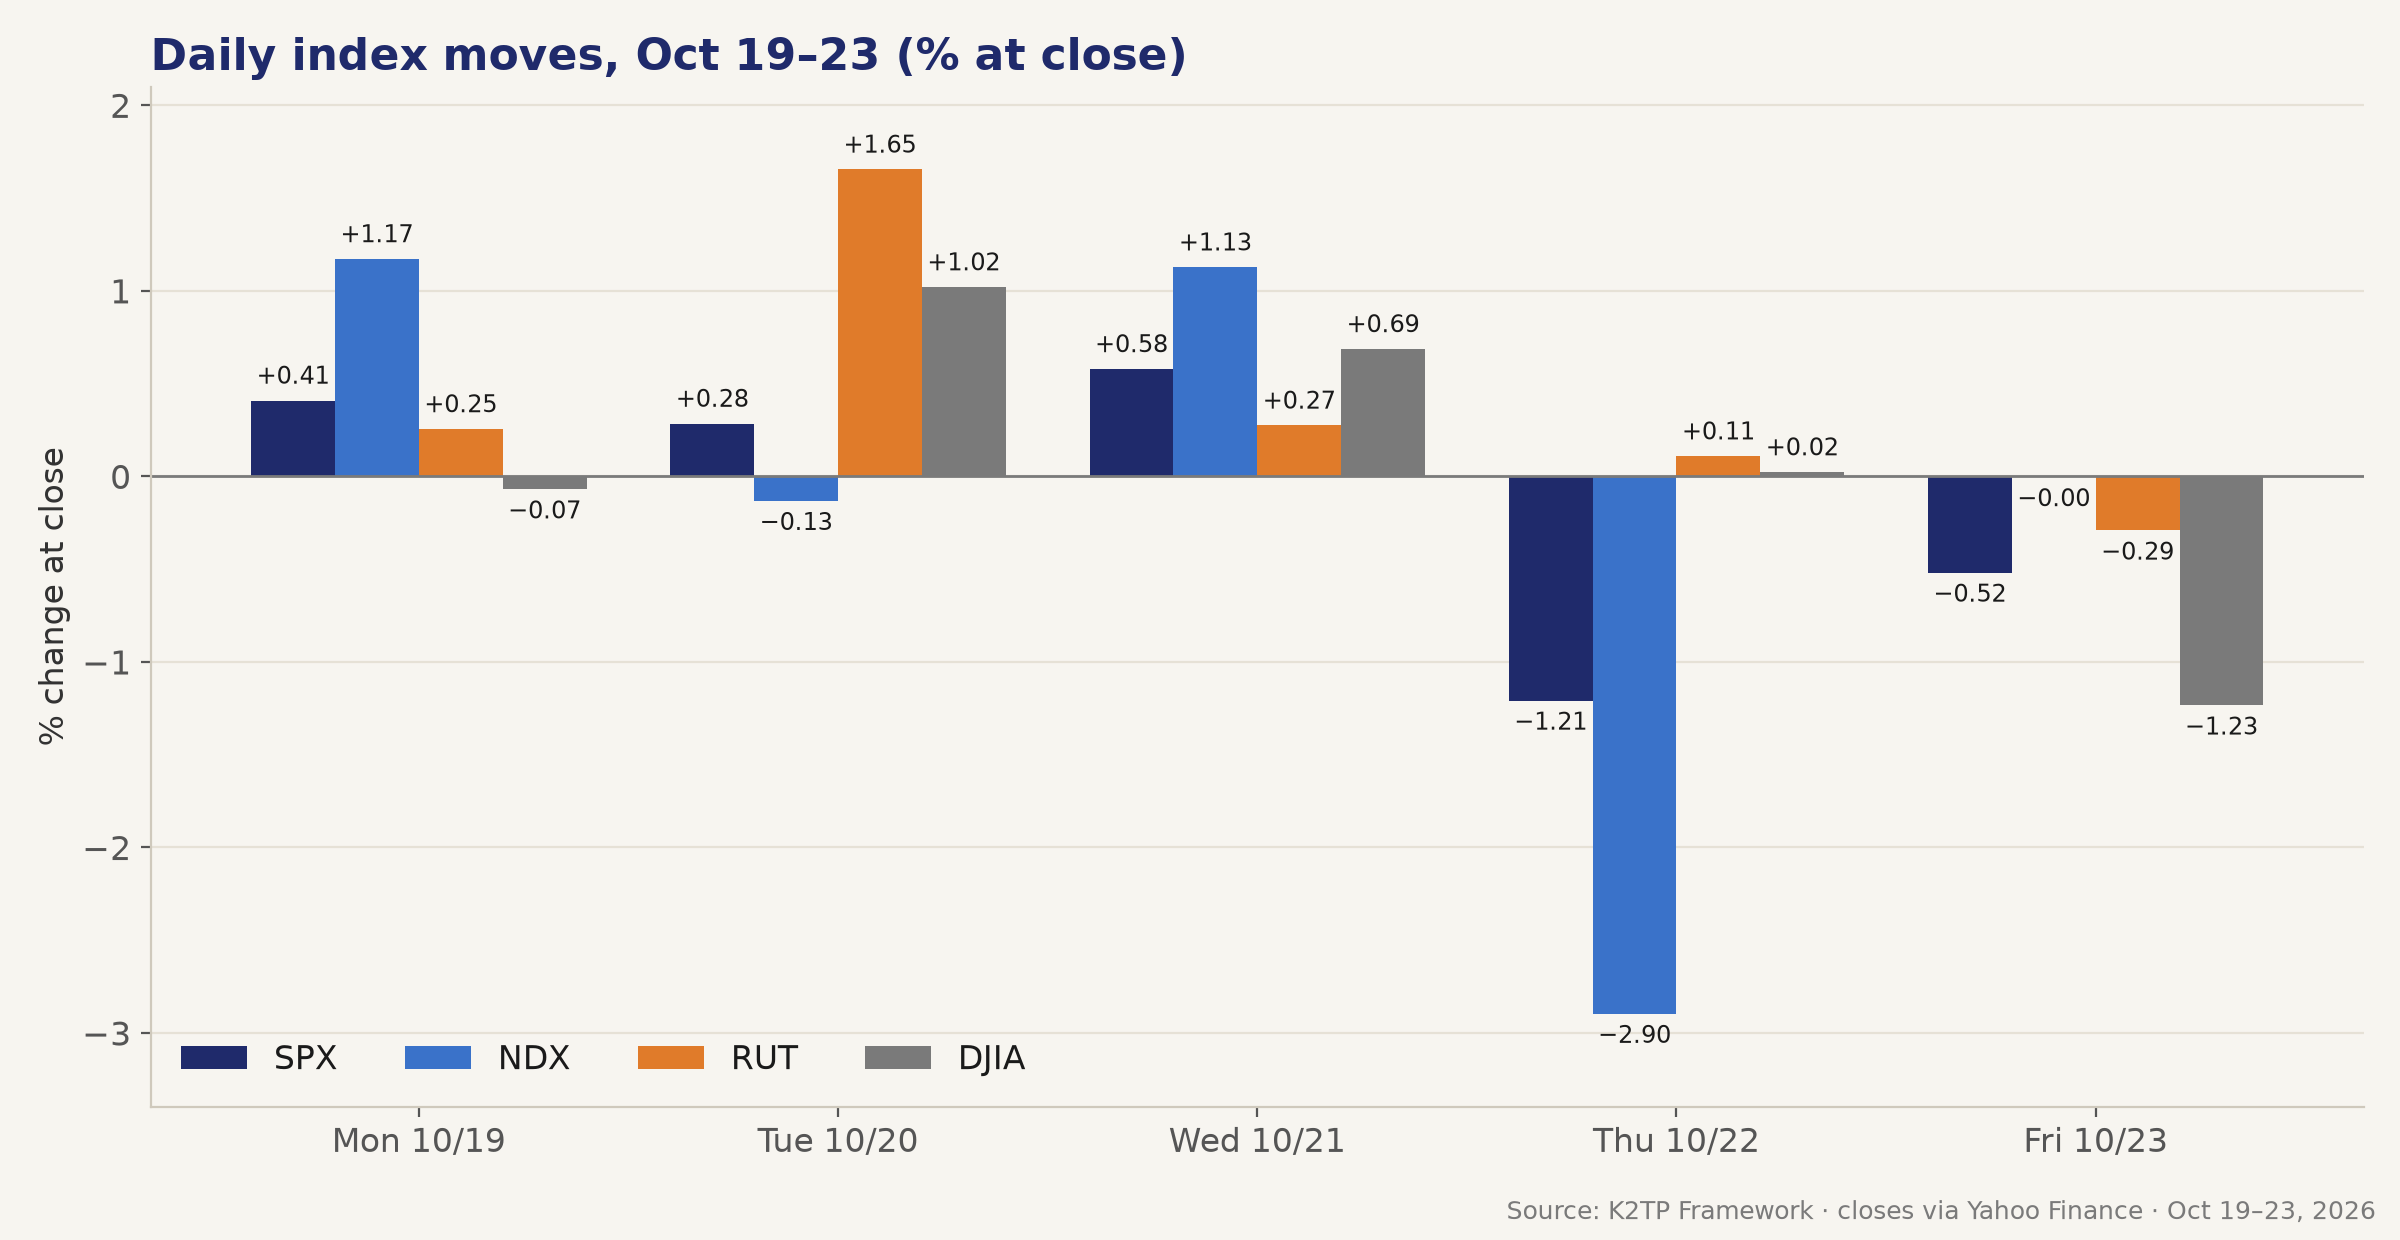
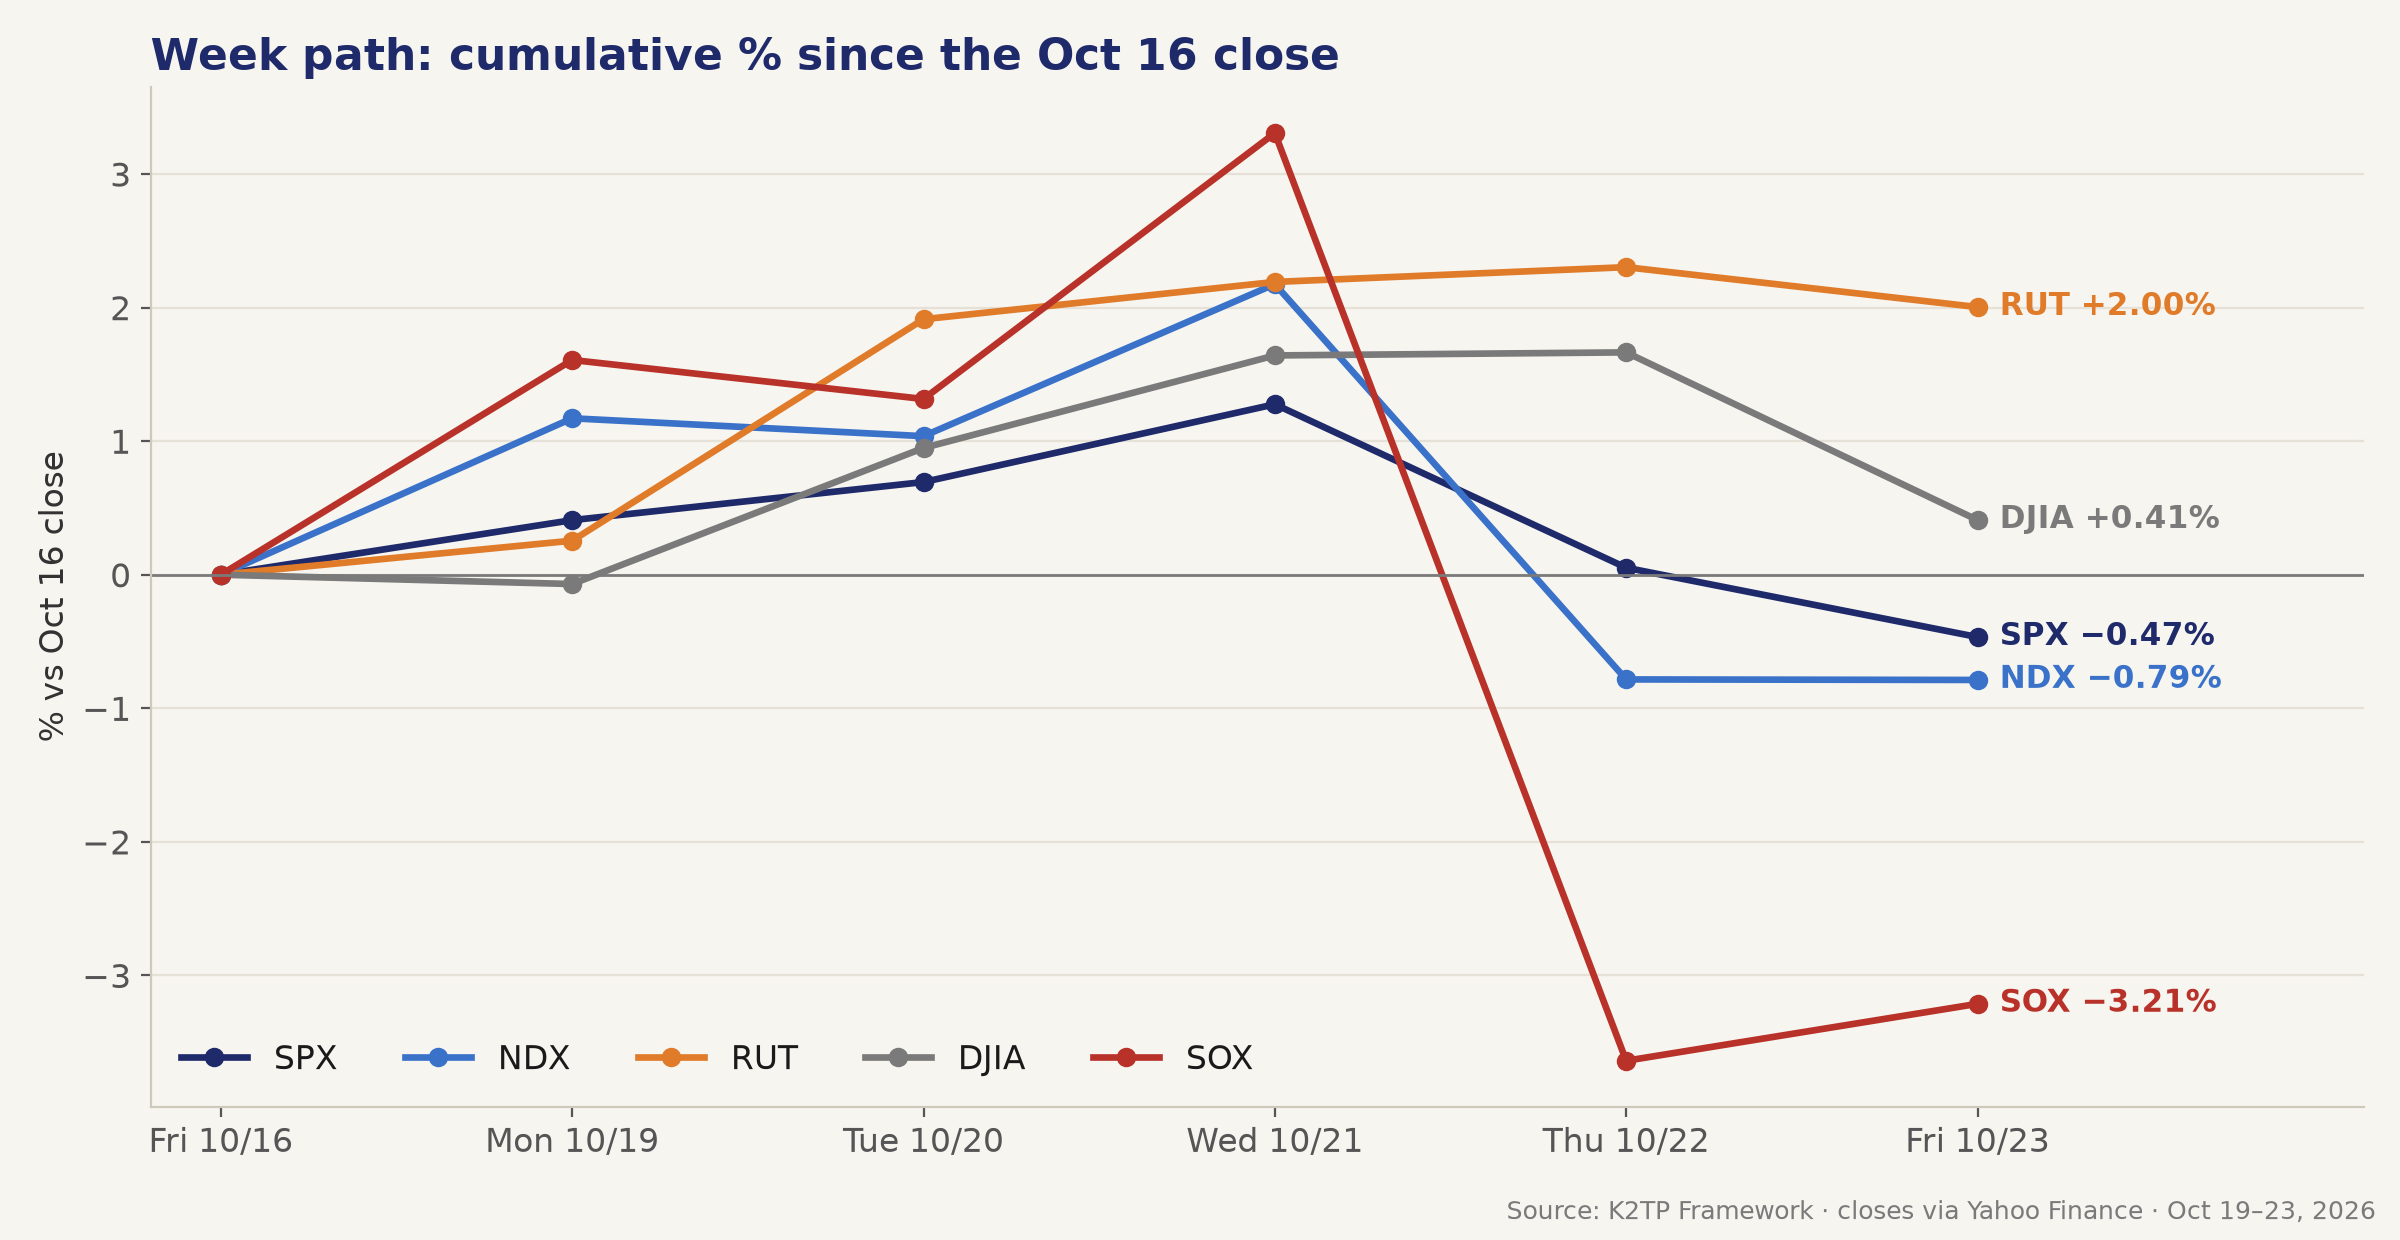
| Day | SPX | NDX | RUT | VIX | 10Y | Regime | Driver |
|---|---|---|---|---|---|---|---|
| Mon 10/19 | 7,690.73 (+0.41%) | +1.17% | +0.25% | 18.44 | 5.136% | 🟡 | SOX snaps an 8-day losing streak; AMZN +4.98% |
| Tue 10/20 | 7,712.57 (+0.28%) | −0.13% | +1.65% | 17.31 | 5.117% | 🟡 | Broad rotation, healthcare record; weak housing |
| Wed 10/21 | 7,757.17 (+0.58%) | +1.13% | +0.27% | 16.68 | 5.146% | 🟡 | SpaceX and SMCI lift AI hardware; 20Y auction tails |
| Thu 10/22 | 7,663.43 (−1.21%) | −2.90% | +0.11% | 19.03 | 4.953% | 🔴 | Meta capex shock, SOX −6.72%; 10Y −19.3 bp |
| Fri 10/23 | 7,623.68 (−0.52%) | −0.00% | −0.29% | 19.45 | 4.988% | 🔴 | Brent $116.72; SpaceX hits telecoms; AXP job cuts |
- Monday–Wednesday was a relief rally: SOX broke its longest losing streak since 2008, and SPX closed Wednesday above Tuesday's high
- Breadth peaked on Tuesday (RUT +1.65%, NYSE advancers 2.04-to-1) and thinned on Wednesday even as SPX rose (more NYSE new lows than new highs)
- Thursday erased the week's gain in one session; Friday's bounces were sold below Thursday's 7,663.43 close
→ The week split in two. AI was rewarded through Wednesday, then Meta's funding plan turned the market back to the same question as the prior week: who pays for the AI buildout?
AI AND SEMIS: META REIGNITES THE CAPEX SCARE
- Monday: SOX +1.61% snapped an eight-day, ~15.7% losing streak, its longest since October 2008 (Reuters); AMZN +4.98% after Morgan Stanley named it a top pick
- Tuesday after hours: SpaceX (SPCX) revenue $14.58B (+161% y/y) and a Q1 2027 revenue guide of $33B–$37B; Super Micro raised its fiscal Q1 revenue guide to $18.5B–$19.5B. Wednesday SPCX +7.79%, SMCI +9.55%, XLK +1.67% 🟢
- Thursday: Meta −6.98% despite a beat; 2026 capex low end raised to $135–145B, the first cash burn in more than a decade, and nonvoting Class C shares to fund AI; Meta 5-year CDS hit a record 114.79 bp (Reuters) 🔴
- SOX −6.72% on Thursday, its biggest drop since June 23: LRCX −11.76%, CRWV −10.06%, KLAC −9.55%, AMD −8.10%, INTC −8.04%
- Friday: only a weak bounce (SOX +0.44%); Nvidia's Jensen Huang told CNBC there is "a scarcity of capital" for AI infrastructure
- Week: LRCX −12.82%, KLAC −12.15%, CRWV −11.65%, META −9.40%, AMAT −7.83%, GOOGL −5.98%; TSLA +4.93%, SMCI +4.14%, TSM +1.43%, AAPL +1.24%
→ Demand for AI hardware is not the issue; SpaceX and Super Micro showed it is still very strong. The issue is financing. When a beat comes with higher capex, new share classes and wider credit spreads, the market sells the whole supply chain, with chip equipment hit hardest.
EARNINGS: STRONG BEATS, PUNISHED GUIDANCE
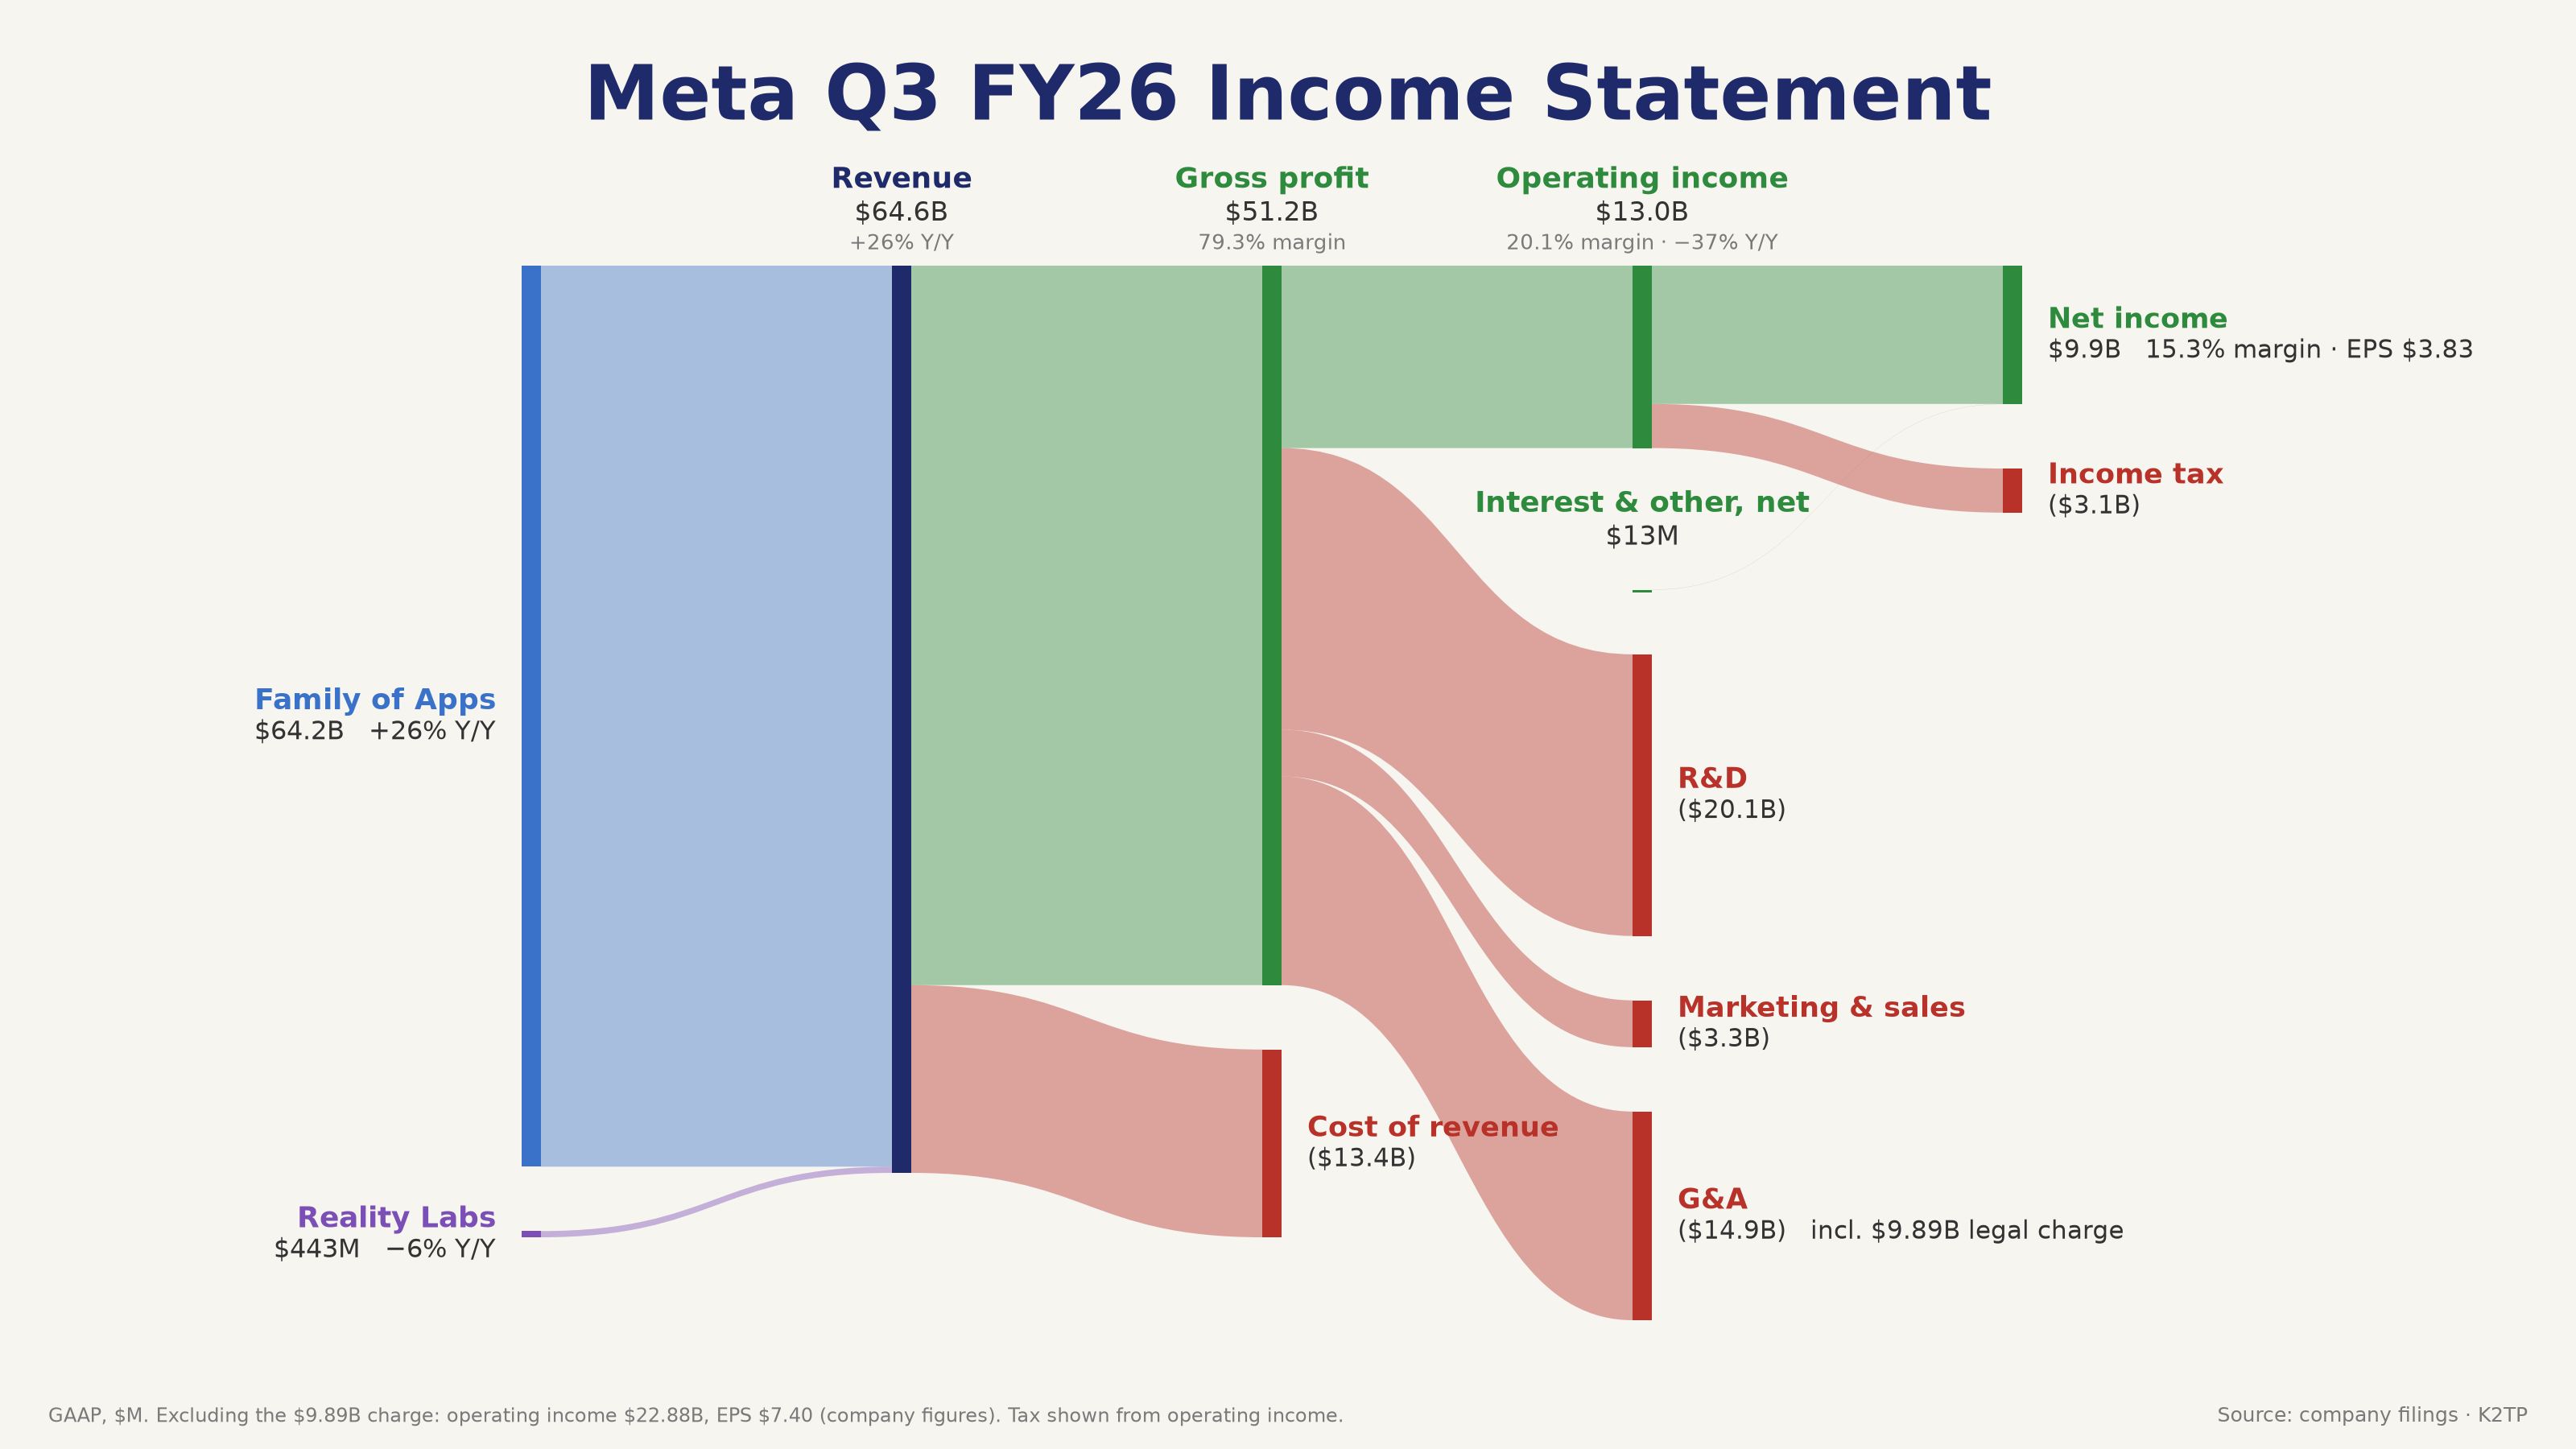
- Meta (Wed after the close): revenue $64.60B (+26% y/y) vs $63.33B expected; GAAP EPS $3.83 including a $9.89B legal charge (EPS $7.40 excluding it); Q4 revenue guide $73–76B; Q3 free cash flow −$2.12B. +2.12% after hours, then −6.98% on Thursday 🔴
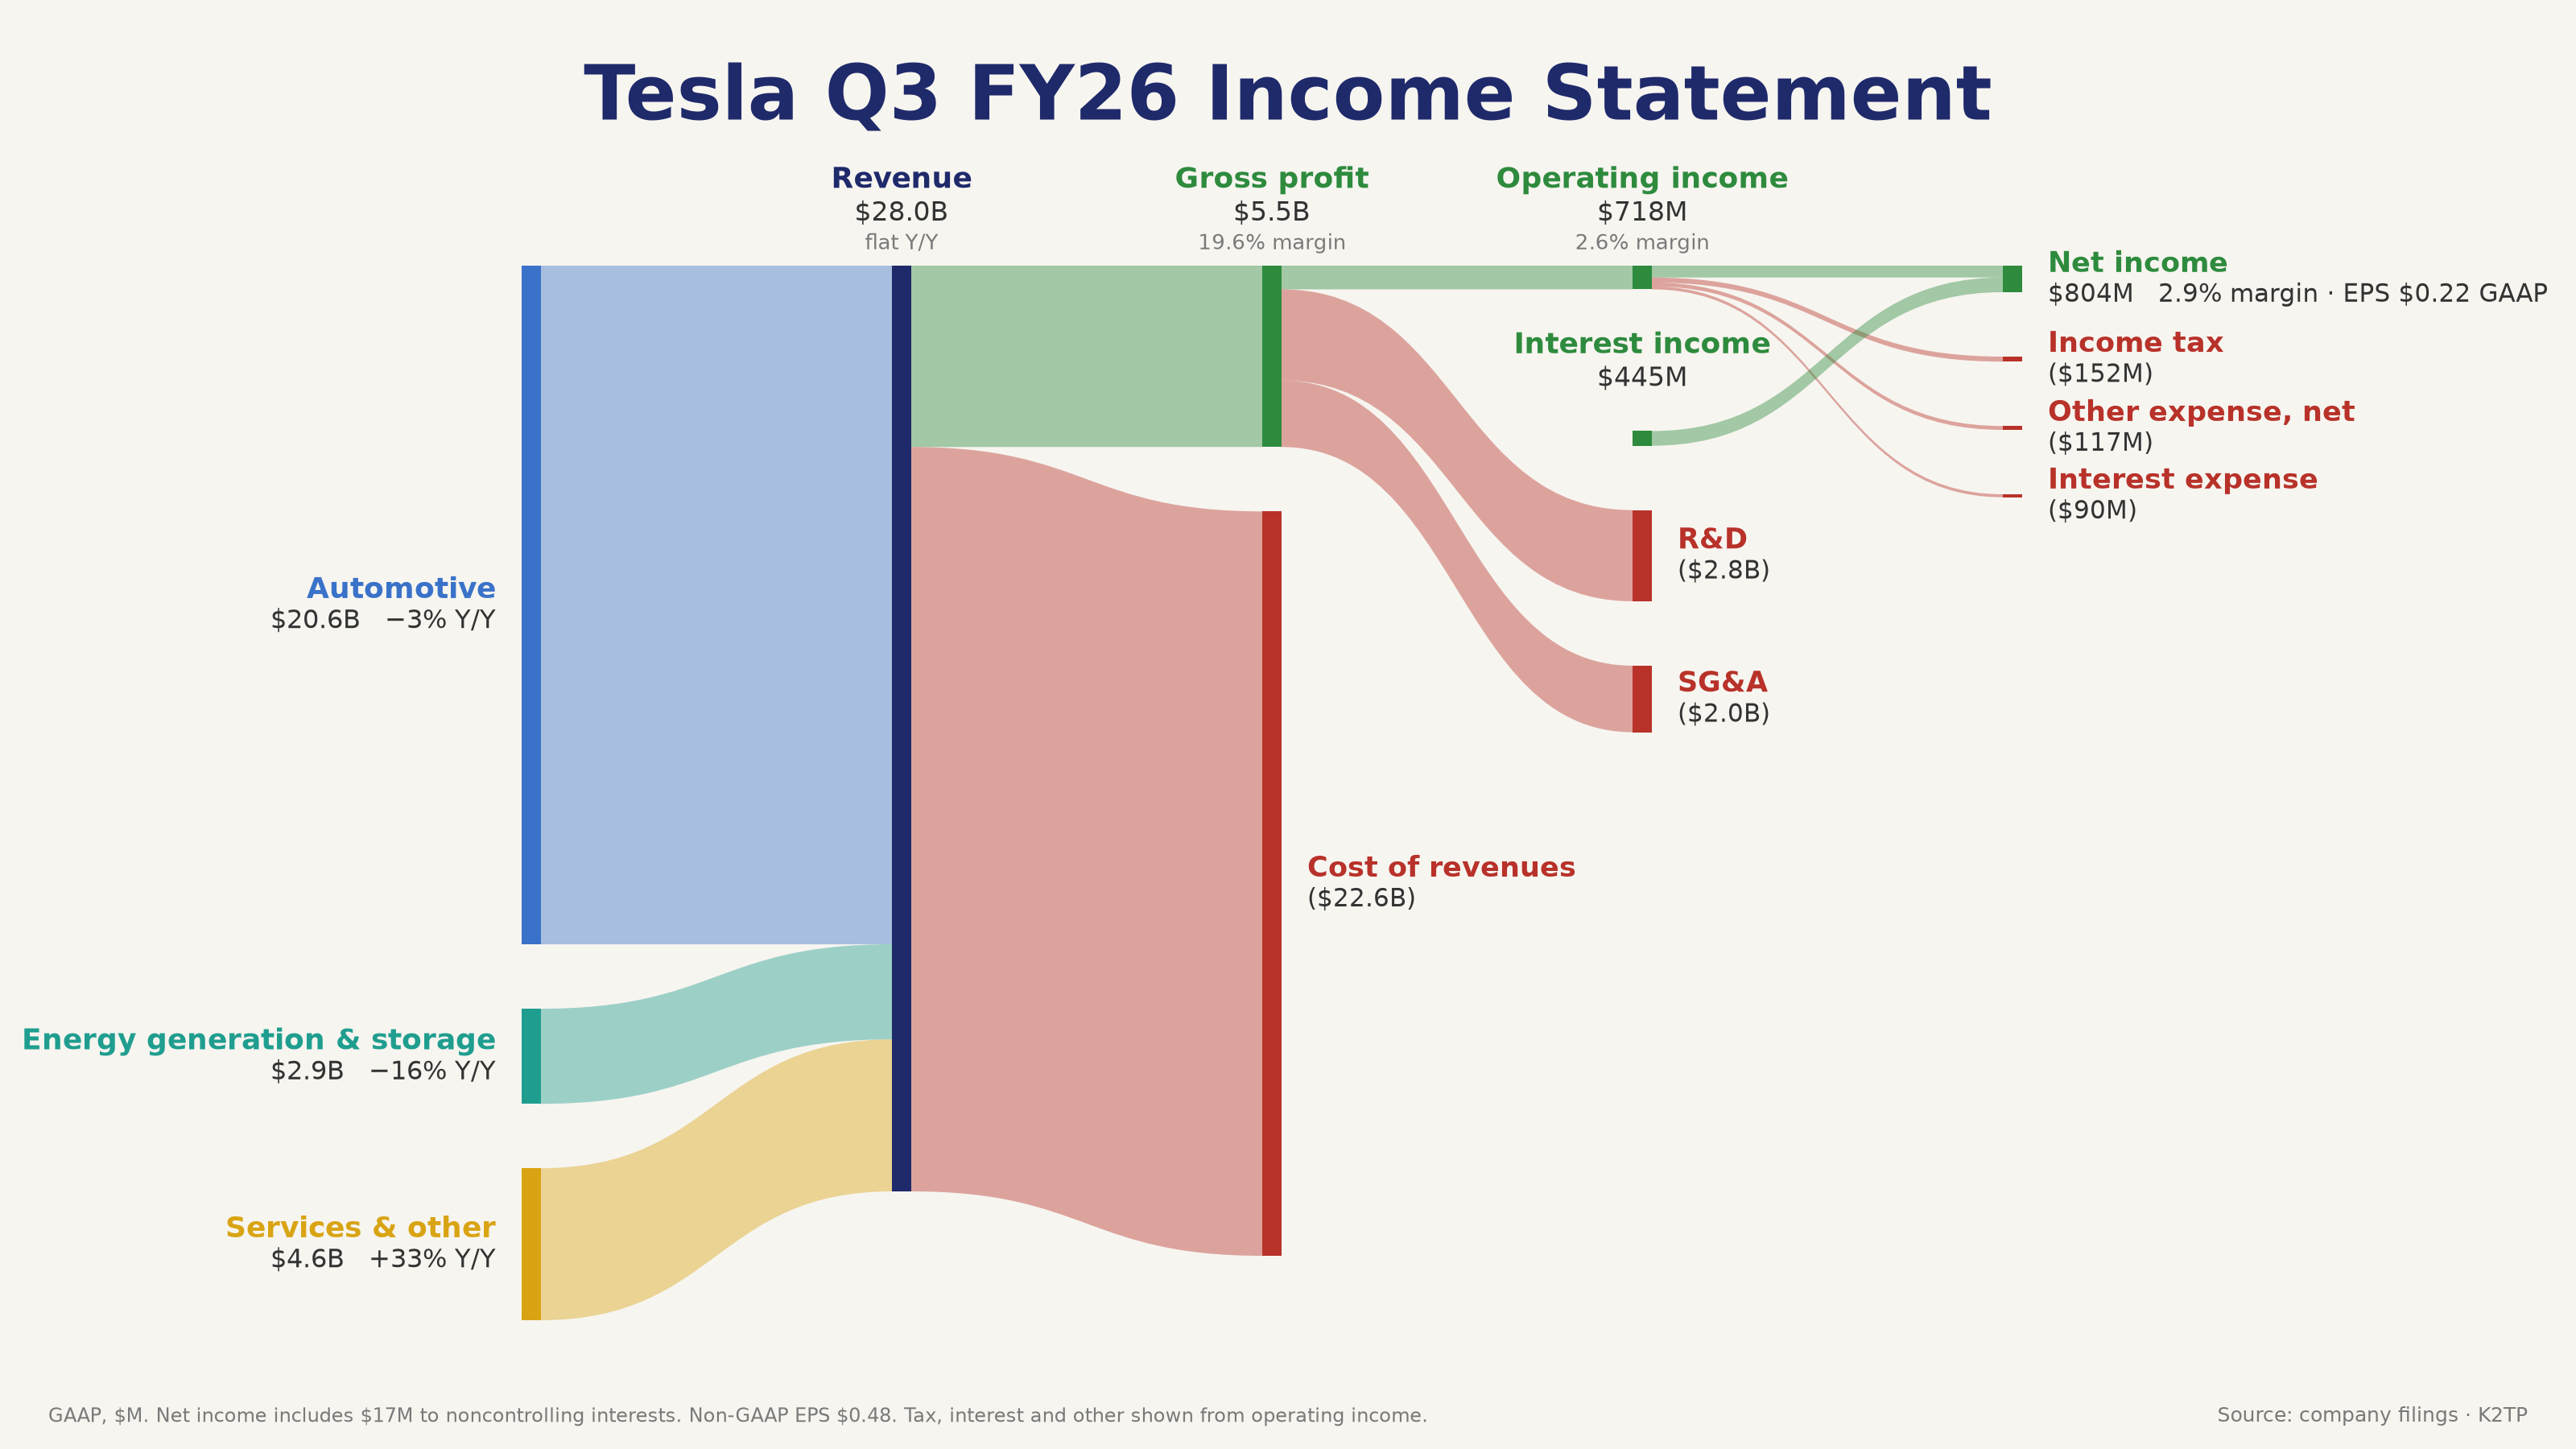
- Tesla (Wed after the close): revenue $28.05B (flat y/y), non-GAAP EPS $0.48 vs $0.44; gross margin 19.6%; 2026 capex cut to about $20B. −3.32% after hours, yet TSLA +4.93% for the week on SpaceX–Tesla merger talk
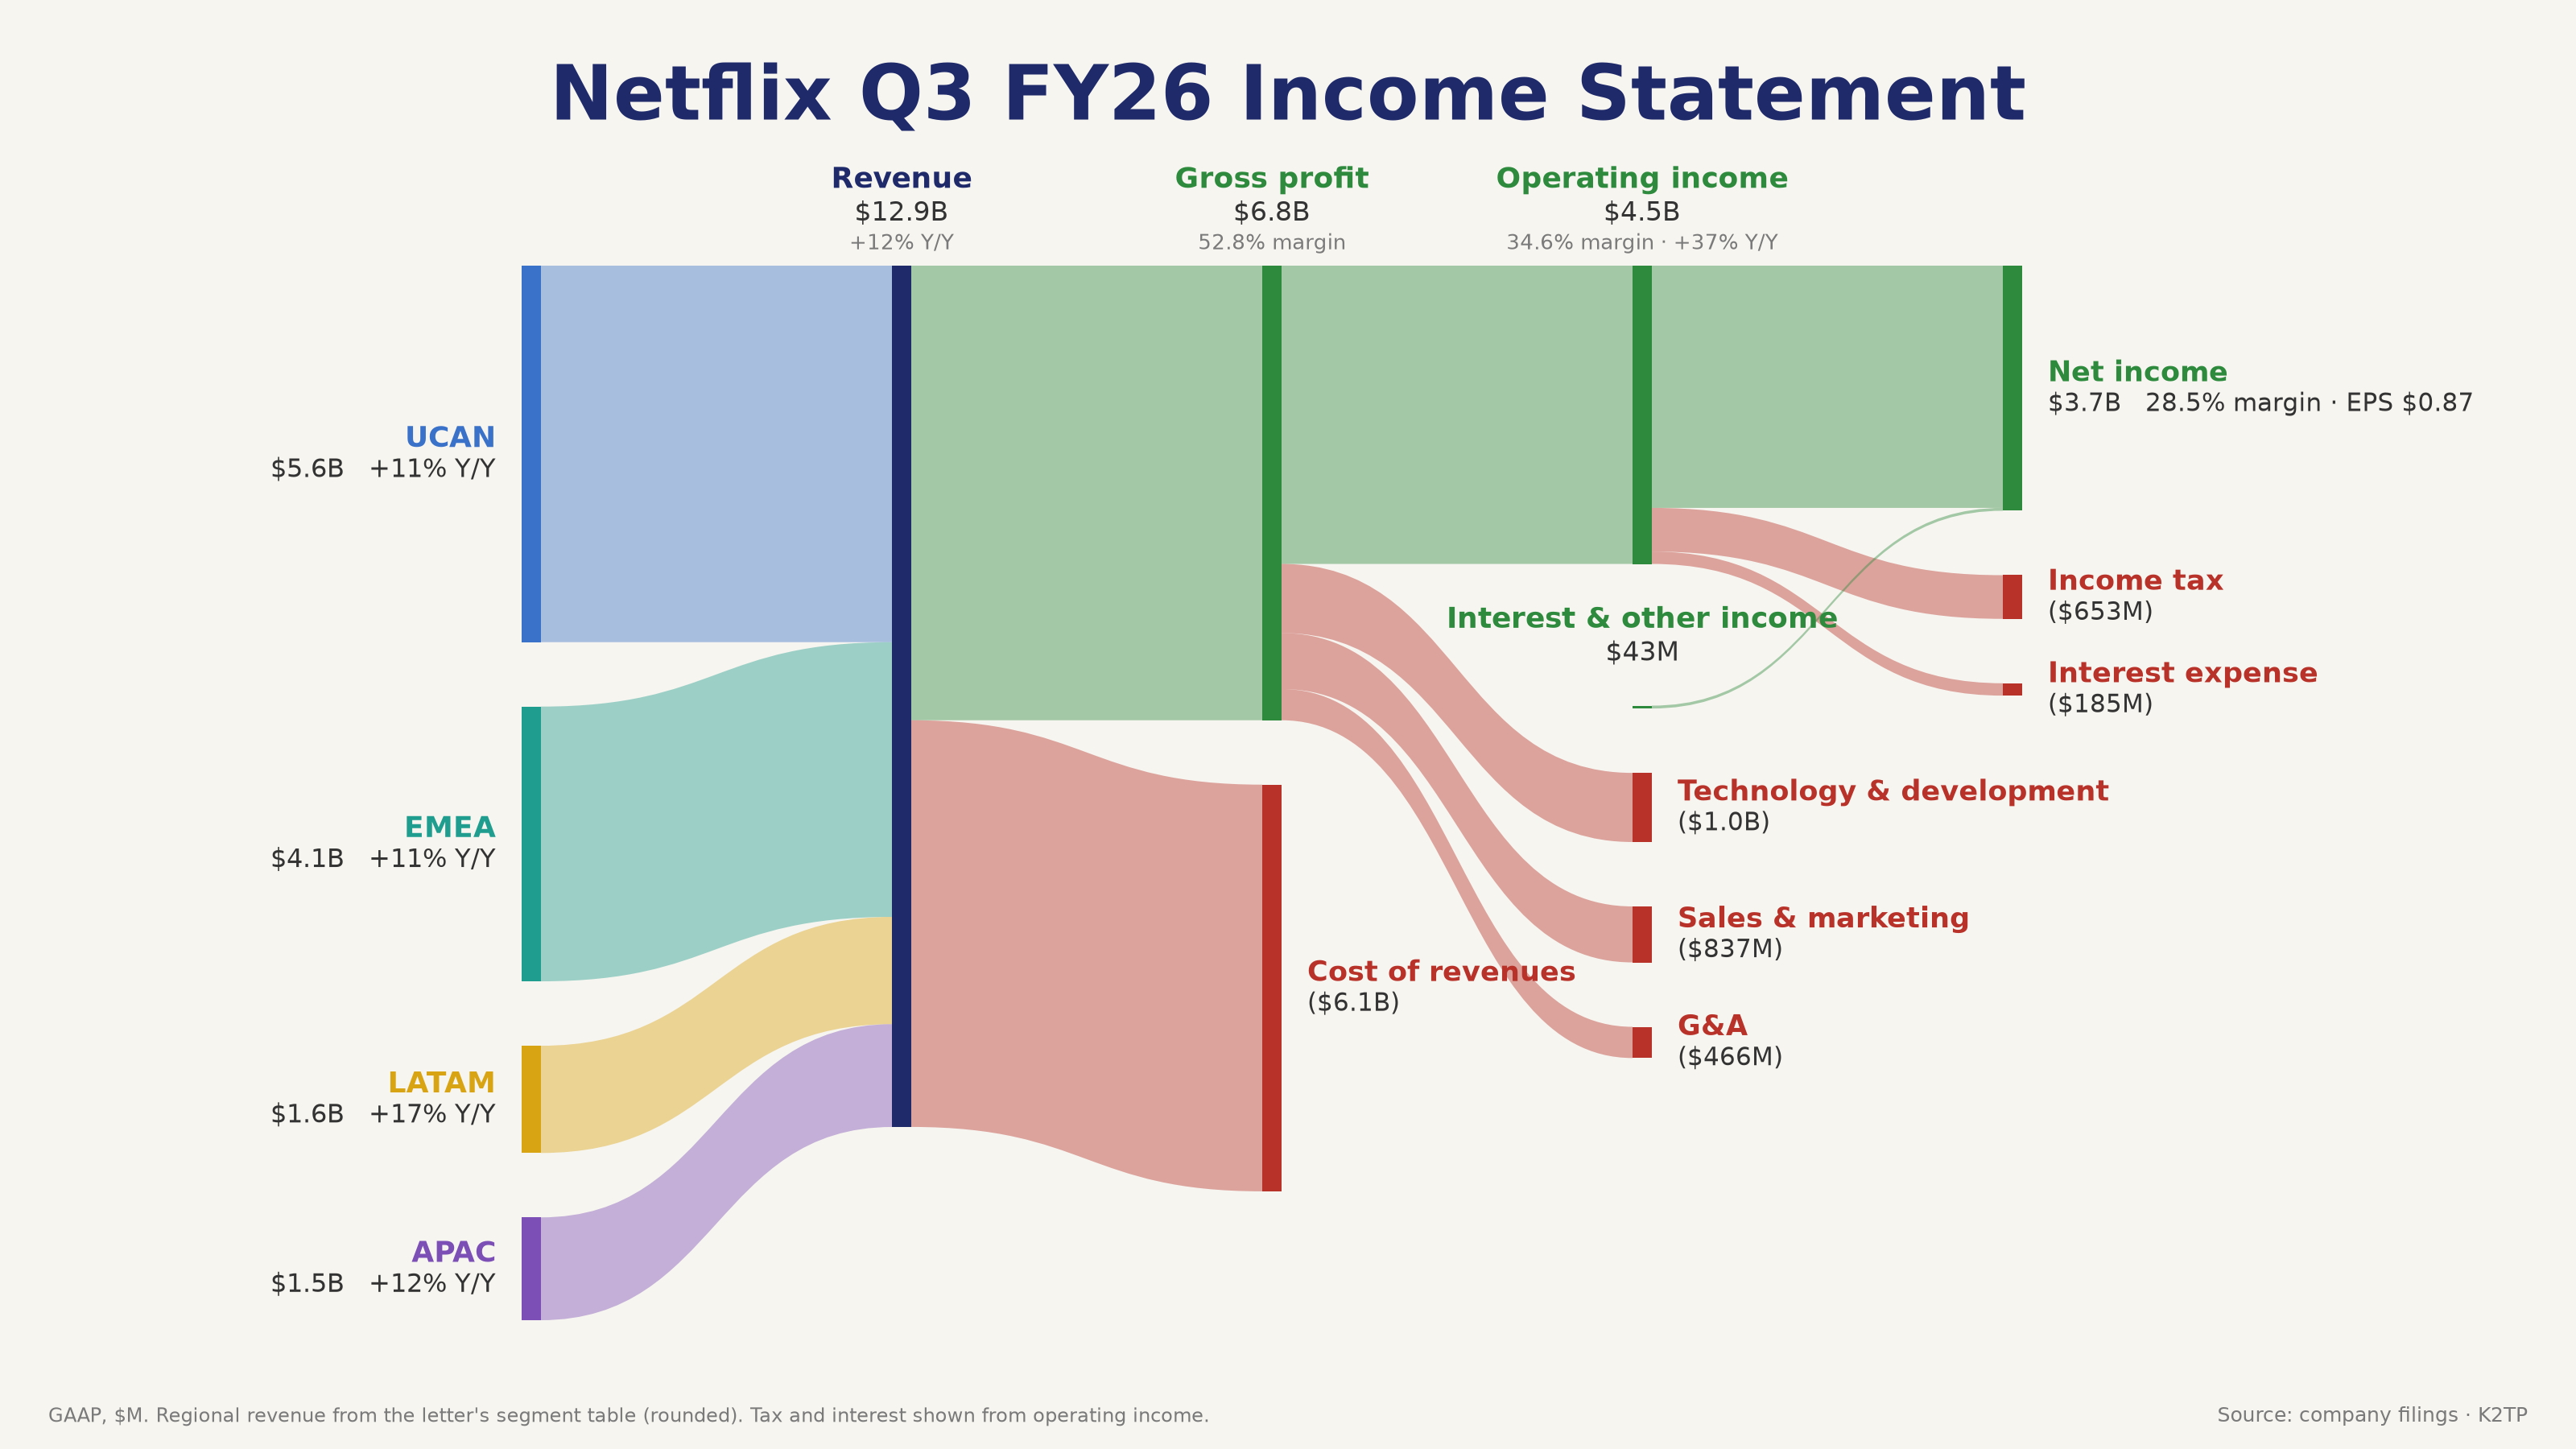
- Netflix (Tue after the close): revenue $12.87B (+12% y/y), EPS $0.87 vs $0.82; but the Q4 EPS guide of $0.67 vs $0.73 and a cut to 2026 ad revenue (~$2.7B). NFLX −6.64% for the week 🔴
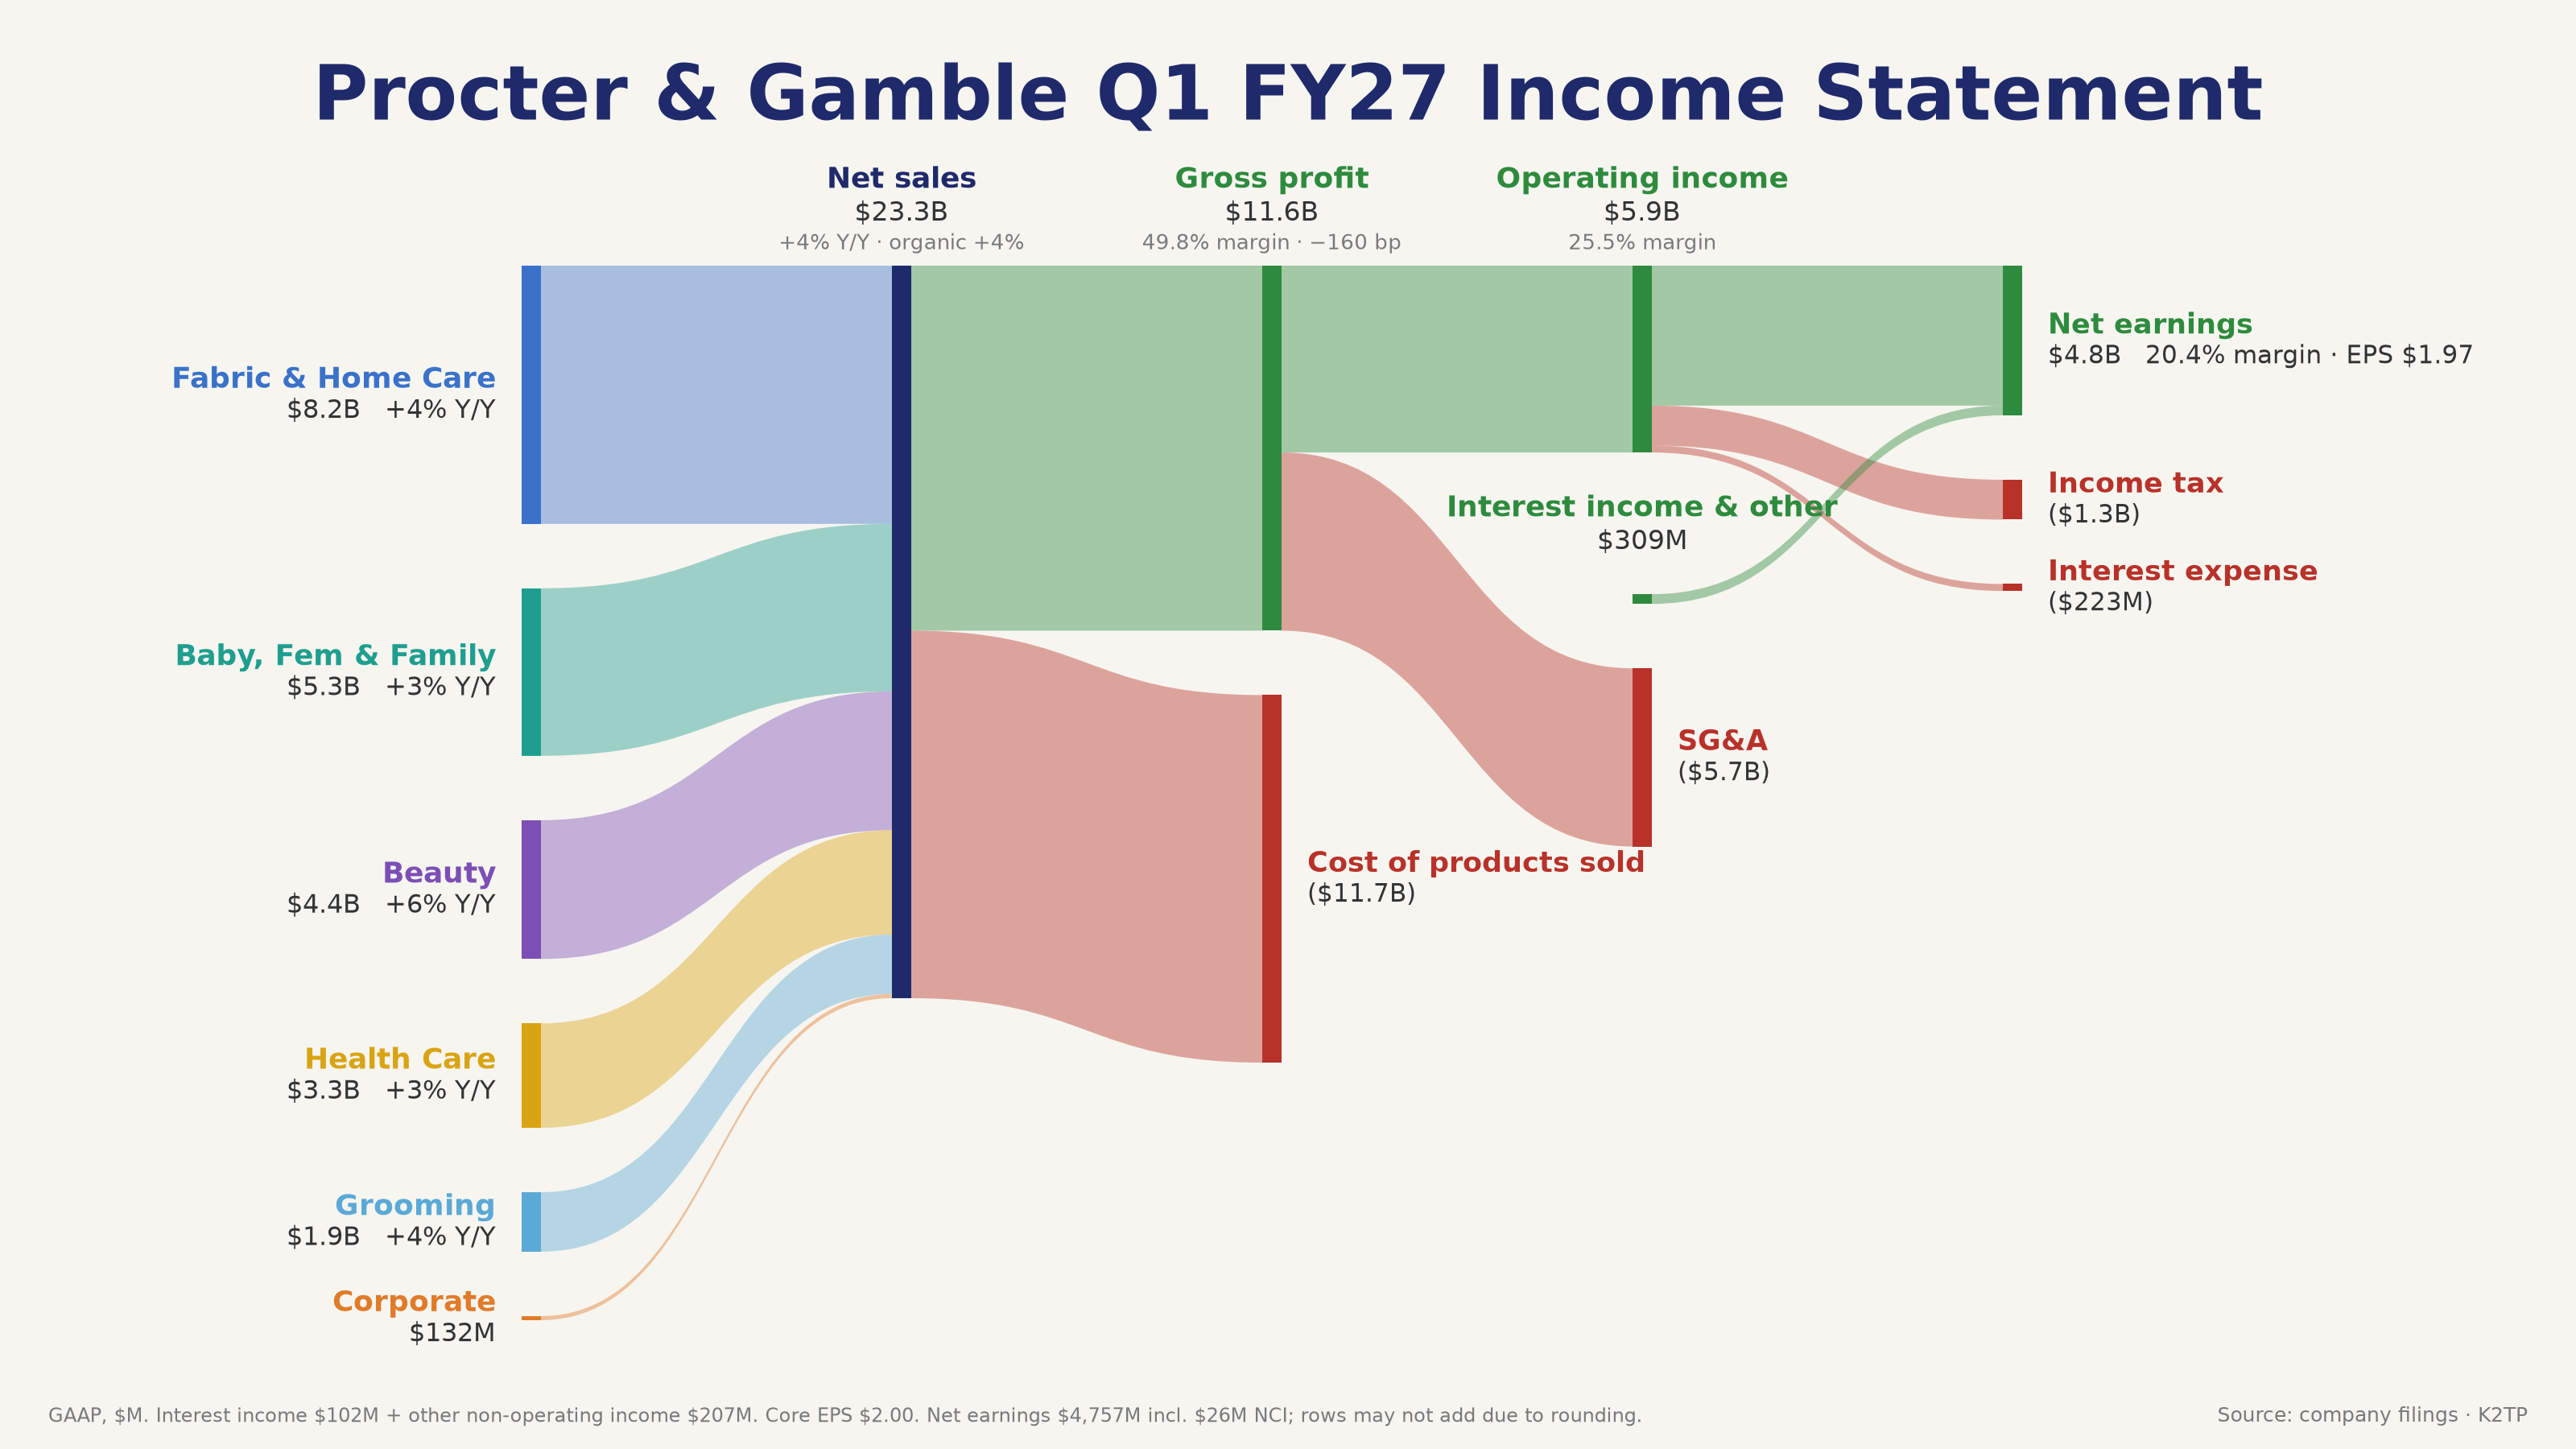
- P&G (Thu): sales $23.28B vs $22.82B, core EPS $2.00 vs $1.89; PG +5.58% on the day. Lockheed Martin adjusted EPS $9.77 vs $7.25 and a raised outlook; LMT +9.44% for the week 🟢
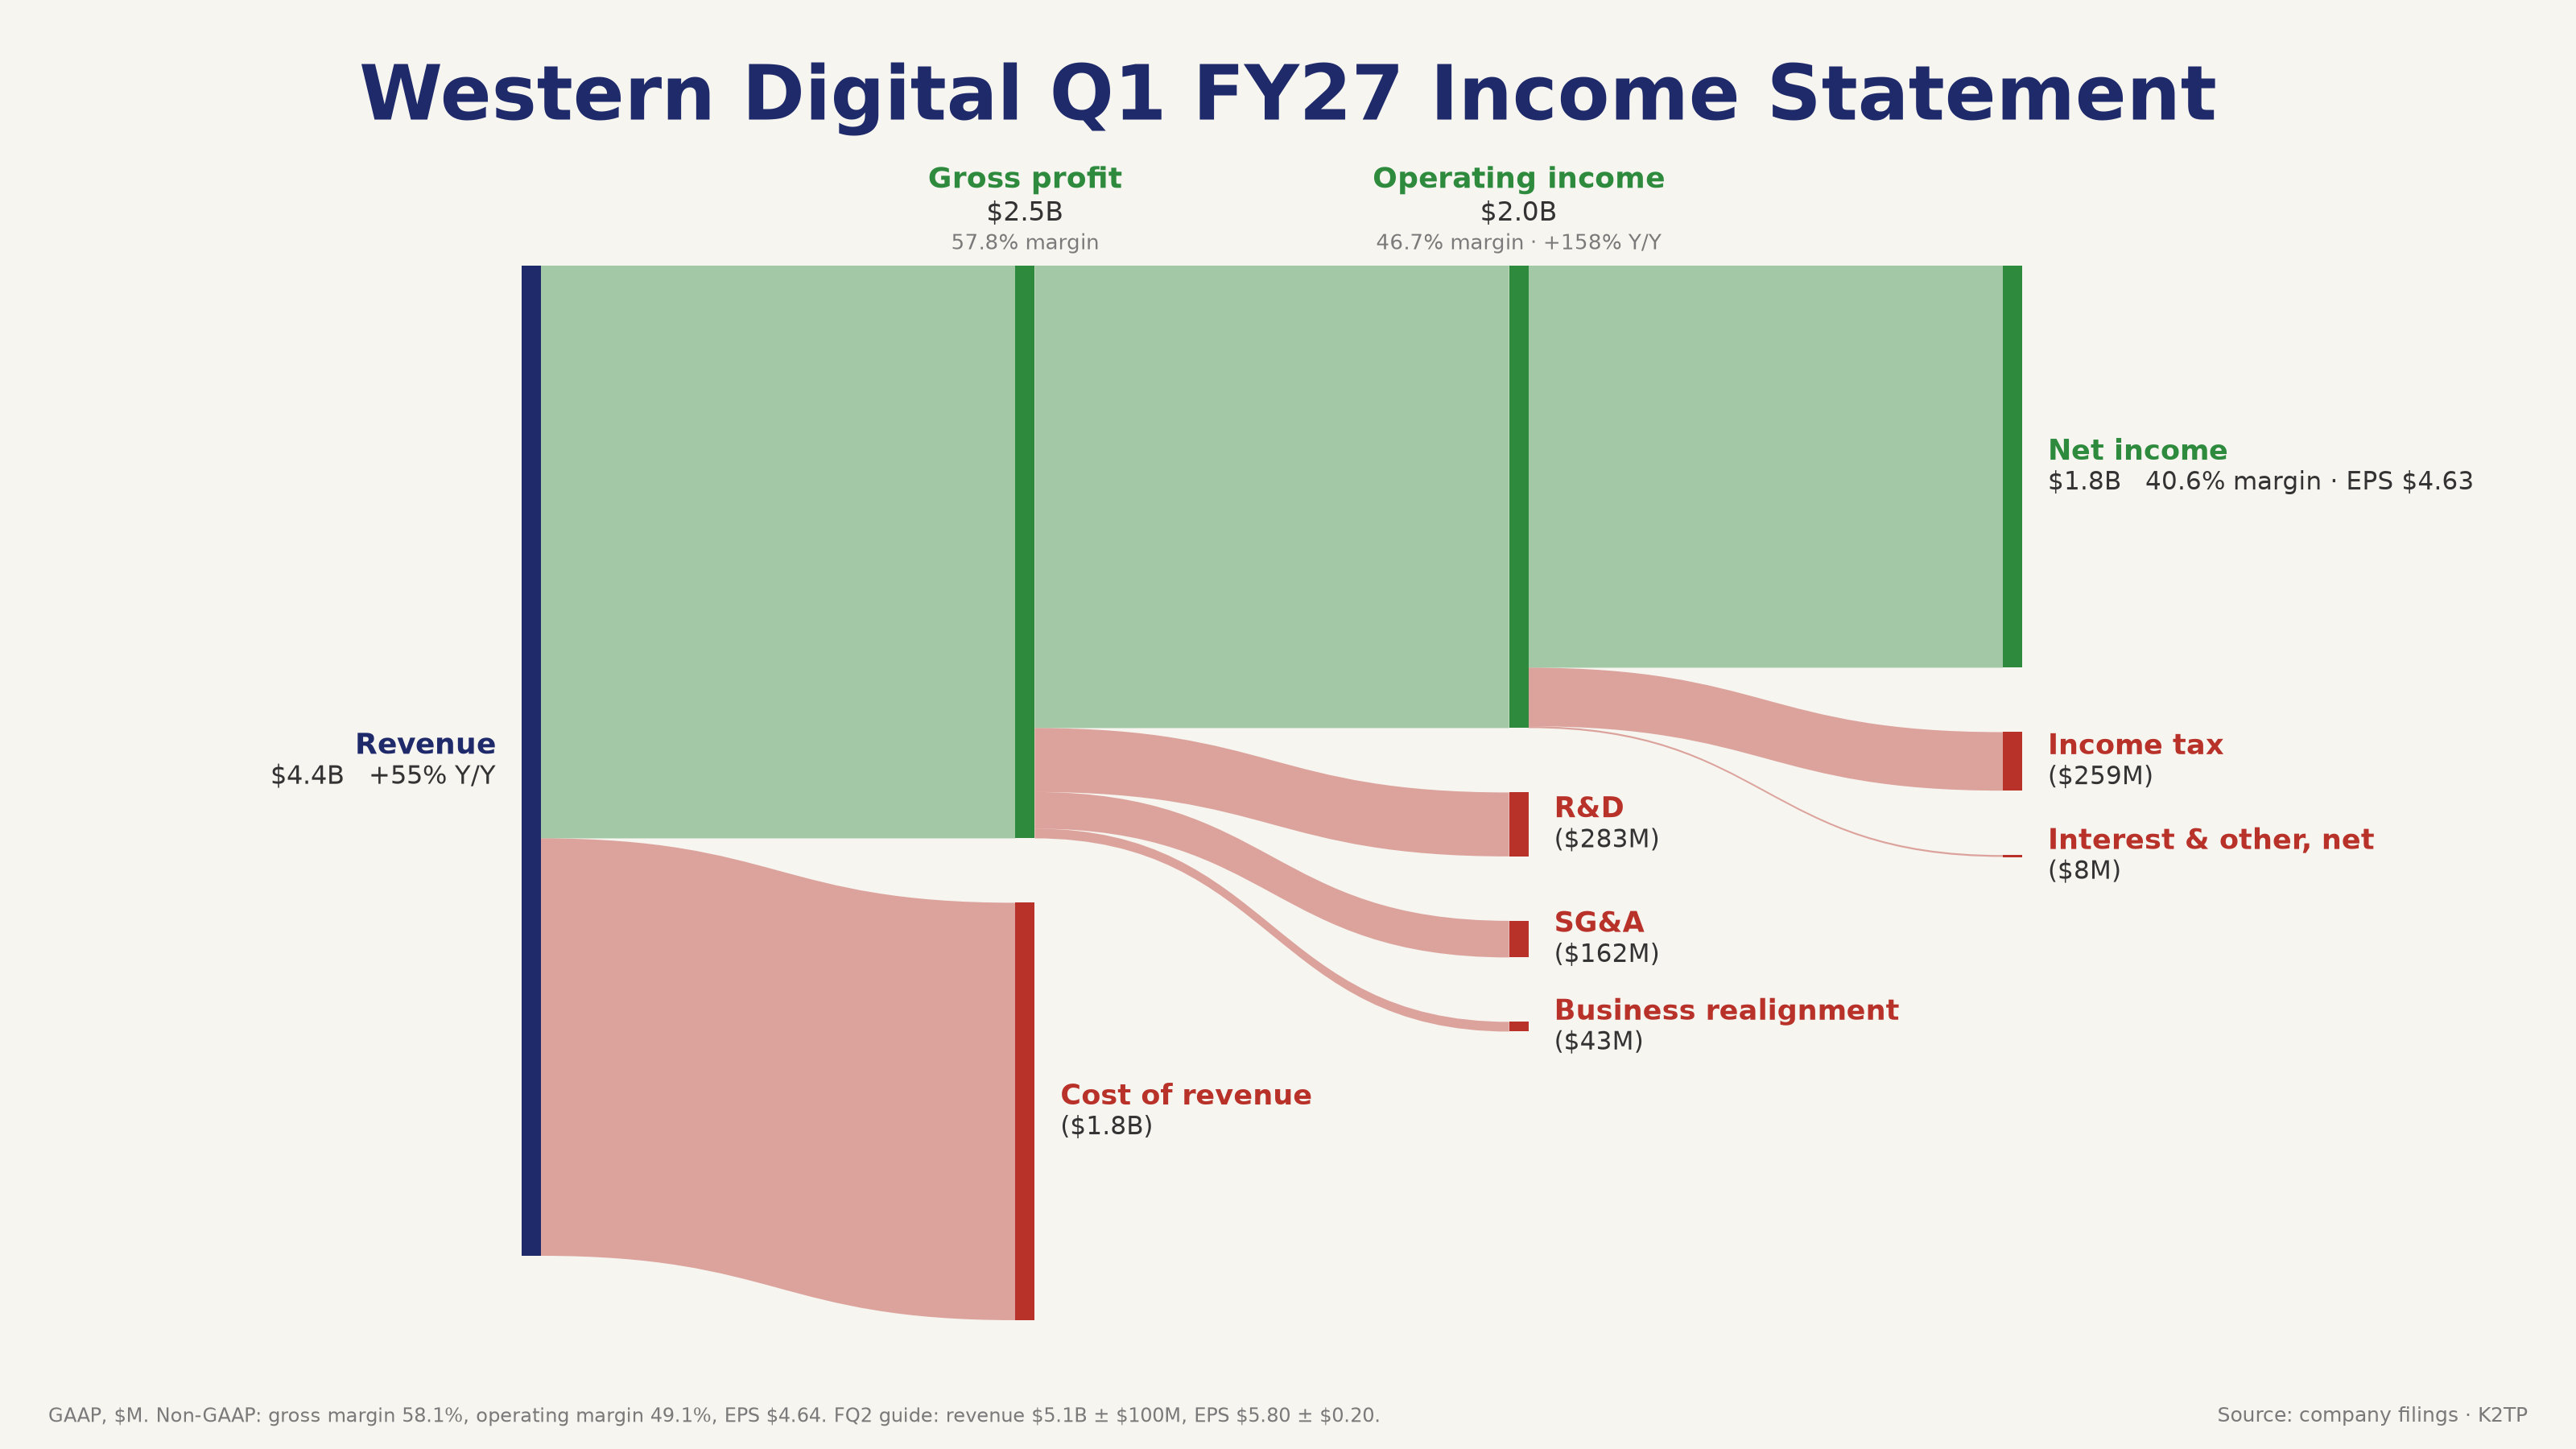
- Western Digital (Thu after the close): revenue $4.38B (+55% y/y), non-GAAP EPS $4.64 vs $4.09 and a strong guide, yet −6.54% after hours on rising input costs and capex
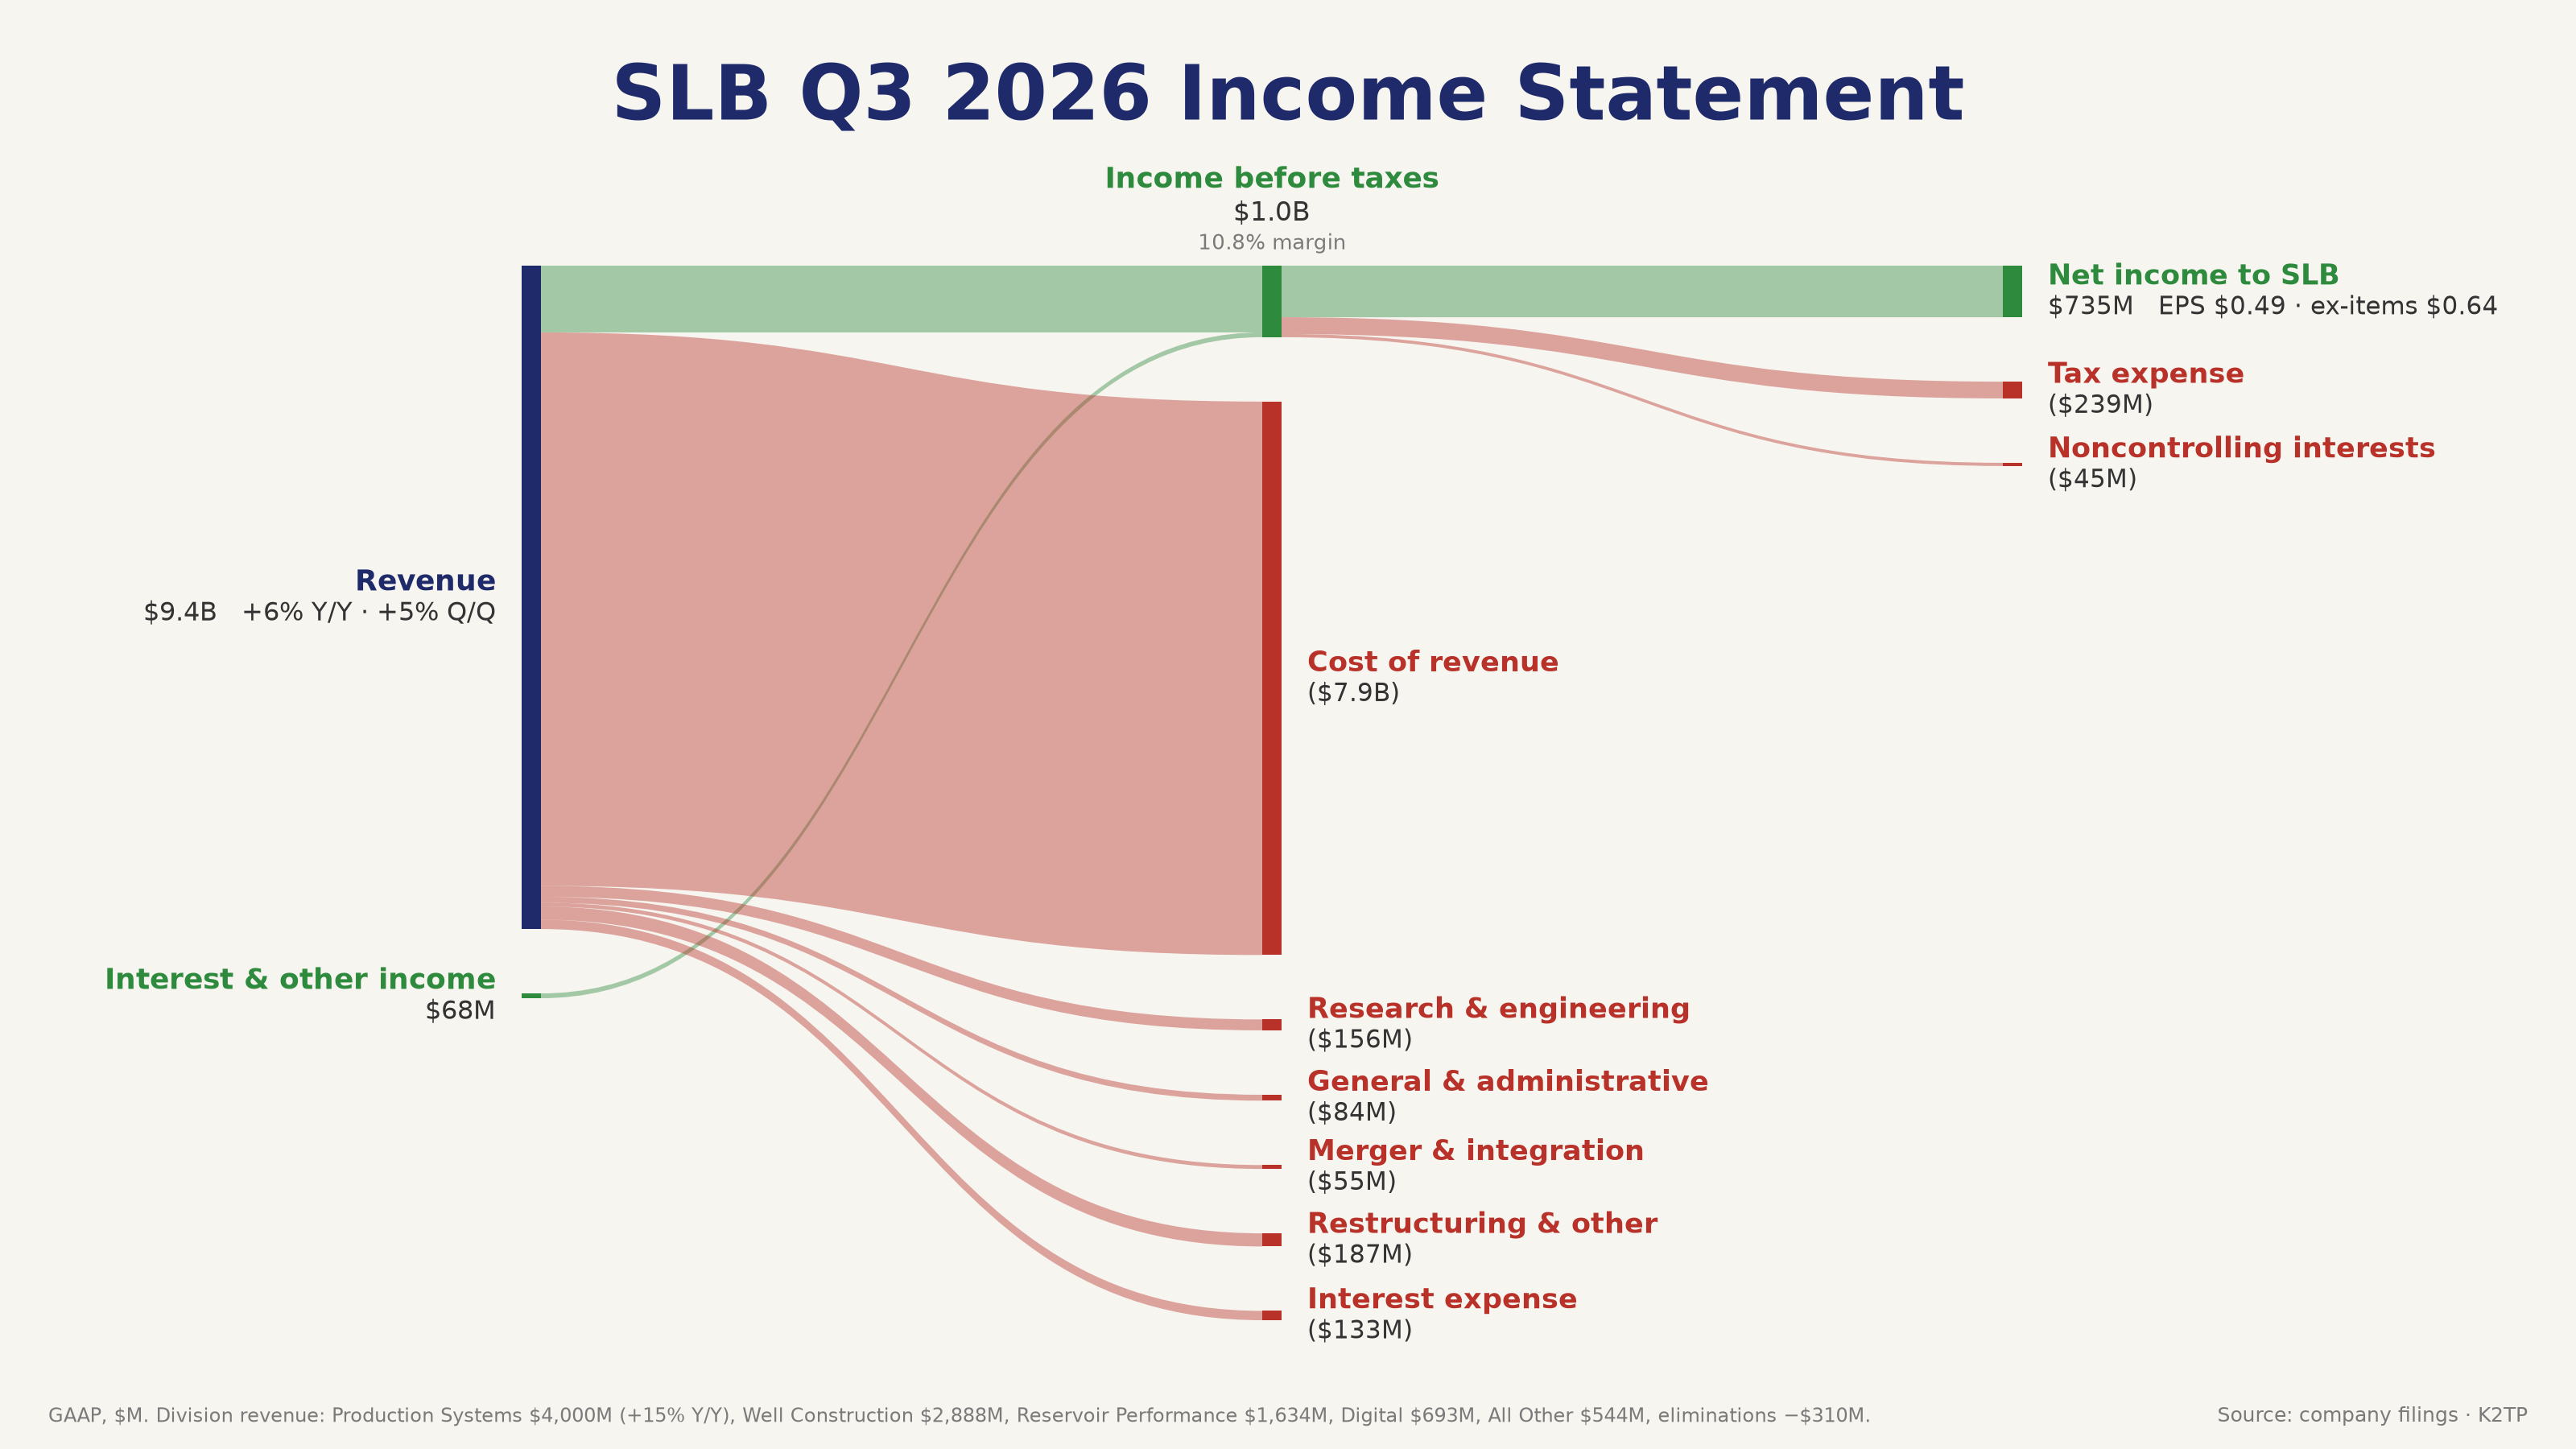
- SLB (Fri): revenue $9.45B (+6% y/y), EPS ex-items $0.64; SLB +7.08% on the day and +7.19% for the week 🟢
- Industrials split: MMM +5.29% and NOC +6.07% for the week on beats and raises; GM −9.58% (soft EPS guide) and GE −8.98% (free cash flow miss)
- American Express (Fri): record revenue $20.06B and a raised EPS guide ($18.30–18.60), but −3.68% on a ~5% workforce cut
- 83% of the 111 S&P 500 companies that had reported Q3 beat estimates (LSEG via Reuters, Thursday)
→ Beats are the norm, so the market trades guidance, costs and capex. Defense, staples and energy were rewarded; anything that raised spending or cut its outlook was sold.
MACRO DATA: HOUSING SLUMPS, JOBS AND PMIs HOLD UP
- Housing was the weak spot: NAHB 29, the lowest since June 2012; September housing starts 1.221M vs 1.30M expected; pending home sales −7.3% m/m to the lowest since the series began in 2001 🔴
- Mortgage rates averaged 7.40%, the highest in nearly three years (Reuters)
- Labor held up: initial jobless claims 194K vs 200K expected; continuing claims 1.728M 🟢
- Activity steady: S&P Global flash composite PMI 57.6 (forecast 57.6, prior 58.4), manufacturing 56.0, services 57.9; Kansas City Fed manufacturing 16 (from 20); LEI flat at 99.6 vs −0.2% expected
- Sentiment weak: UMich expectations 48.8 vs 47.1 expected; 5-year inflation expectations 3.5%; overall sentiment near a record low (Reuters)
→ Housing is cracking under 7%+ mortgage rates, but jobs and business surveys are not. The data do not argue for a Fed cut, so oil and rates remain the swing factors.
FED AND RATES: AN AUCTION TAIL, THEN A HAVEN RALLY
- October hike odds: 16.1% → 17.2% (Mon) → 14.9% (Tue) (CME FedWatch via Reuters); Cboe cited 73.7% odds of a December hike
- Wednesday's $13B 20-year auction stopped at 5.469% with a 0.9 bp tail; the 10Y peaked at 5.146%
- Thursday: 10Y −19.3 bp to 4.953% as Treasurys rallied as a haven, the biggest drop since March 10, 2023; it broke below 5% for the first time in nearly a month (WSJ)
- Week: 10Y 5.098% → 4.988% (−11.0 bp), 5Y 4.899% → 4.805% (−9.4 bp), 30Y 5.436% → 5.315% (−12.1 bp)
- The Fed was in its blackout; the FOMC decides on Wed Oct 28. CME FedWatch prices about an 88% chance of a hold (Kiplinger, Oct 23)
→ Bonds rallied on fear, not on dovish data. With Brent near $117, a 10Y under 5% does not by itself lift tech, and the Fed has little reason to sound dovish next week.
OIL AND GEOPOLITICS: BRENT HITS $116.72
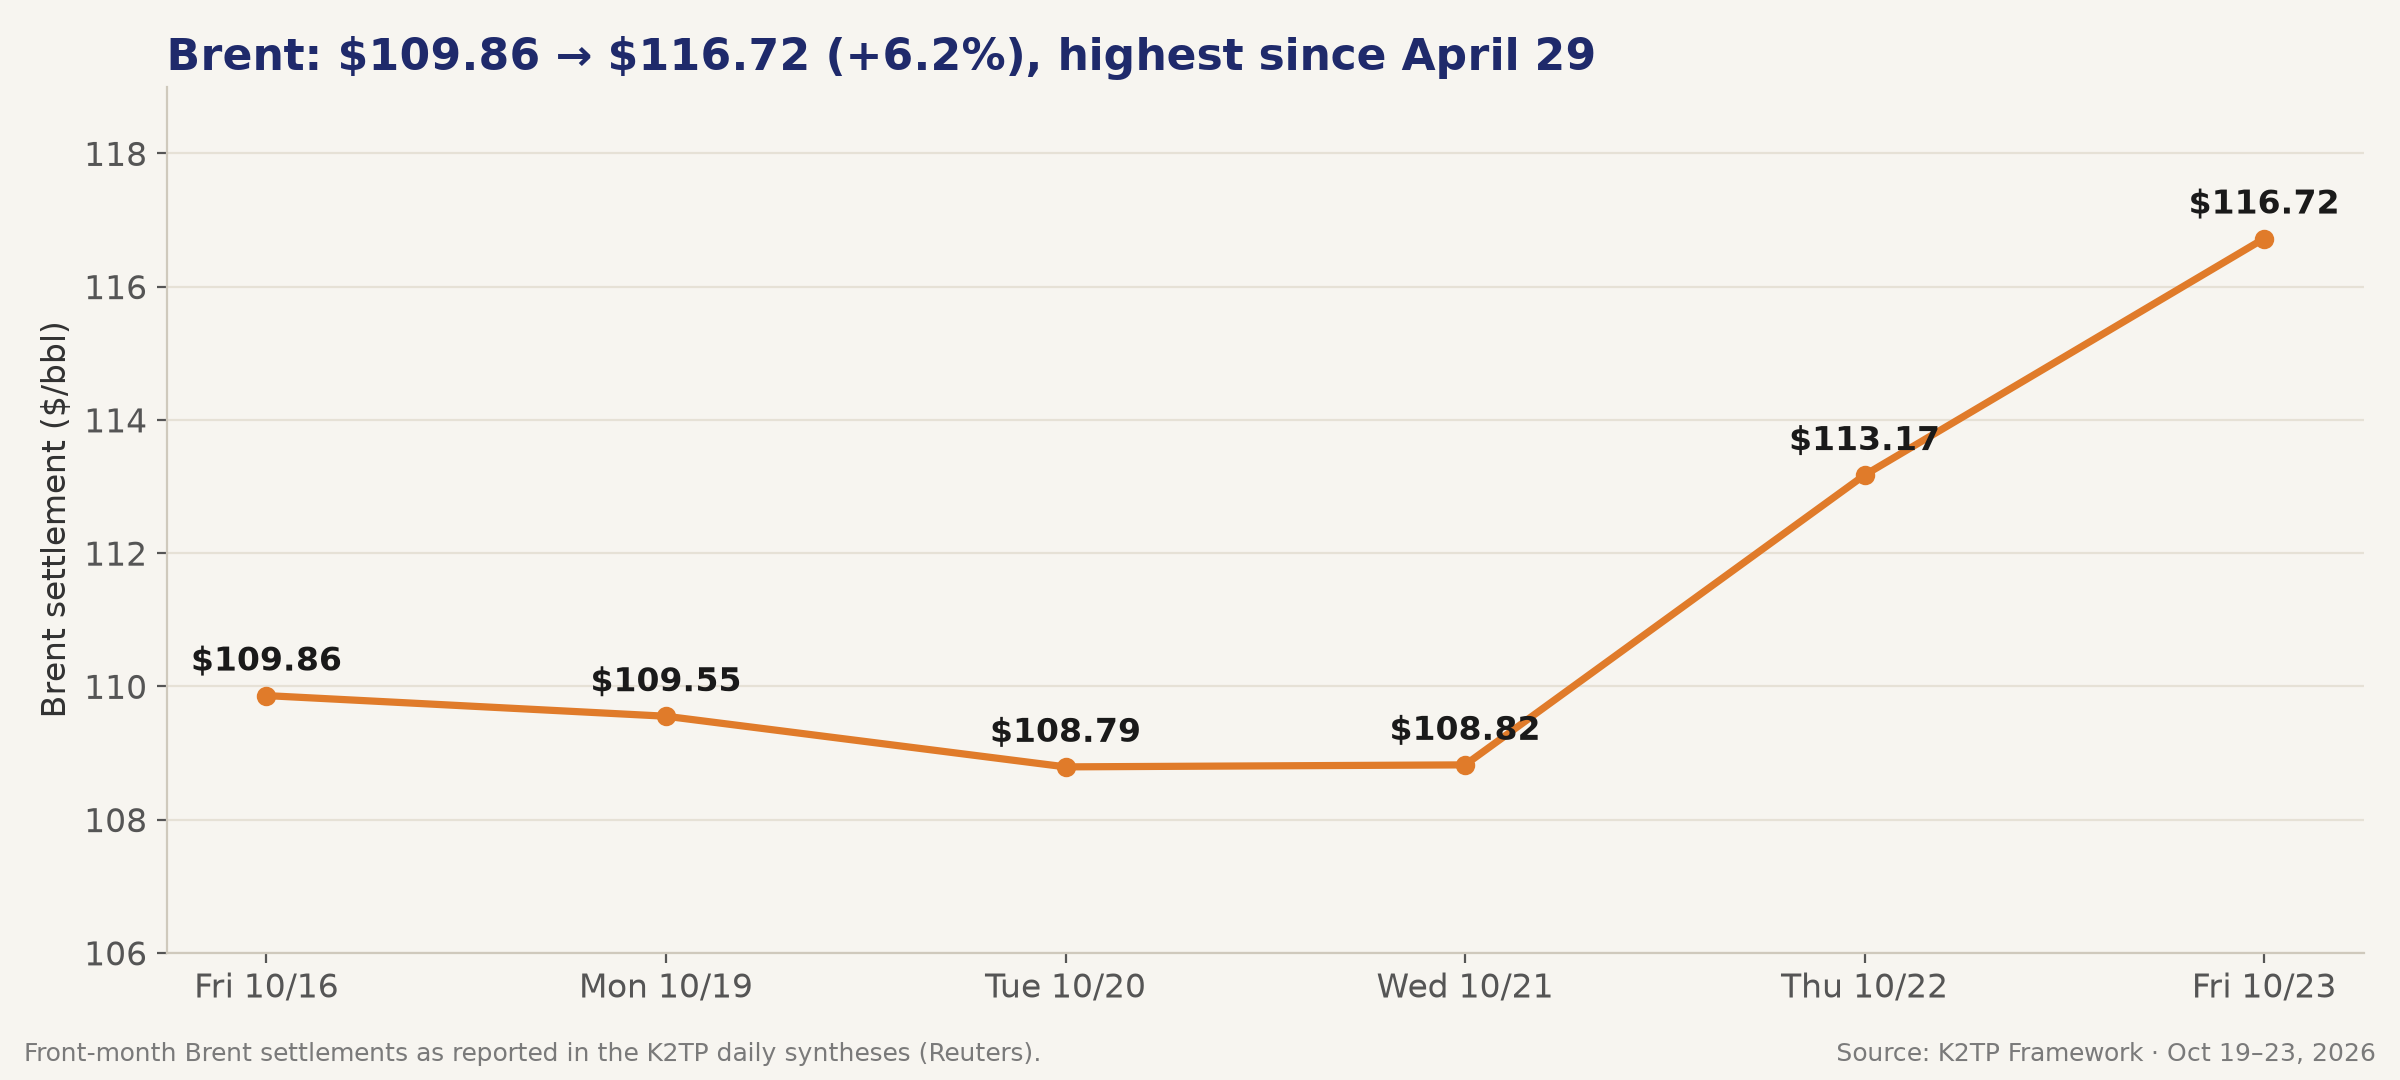
- Brent settlements: $109.86 (Oct 16) → $109.55 → $108.79 → $108.82 → $113.17 → $116.72, +6.2% for the week and the highest since April 29; WTI $103.27 (+2.3% for the week, Reuters) 🔴
- Drivers: Houthi attacks on Saudi sites, reports of possible new U.S.–Israel strikes on Iran, and Iran's threat to hit civilian targets in neighboring countries (CNBC, WSJ)
- Thursday after the close, Trump invoked the Defense Production Act for petroleum capacity; it did not cap prices
- The Iranian and Russian presidents meet in Moscow next week (Friday Pre-Close brief)
- XLE +1.60% for the week, energy at a record (Reuters); SLB +7.19%, CVX +3.65%, XOM +2.36%; gold $4,186.70 → $4,010.00 (−4.2%) despite the risk
→ Oil is the main macro input now. Brent near $117 feeds inflation risk right before the FOMC and pressures every sector except energy.
SECTORS AND ROTATION: SMALL CAPS AND EQUAL-WEIGHT WIN
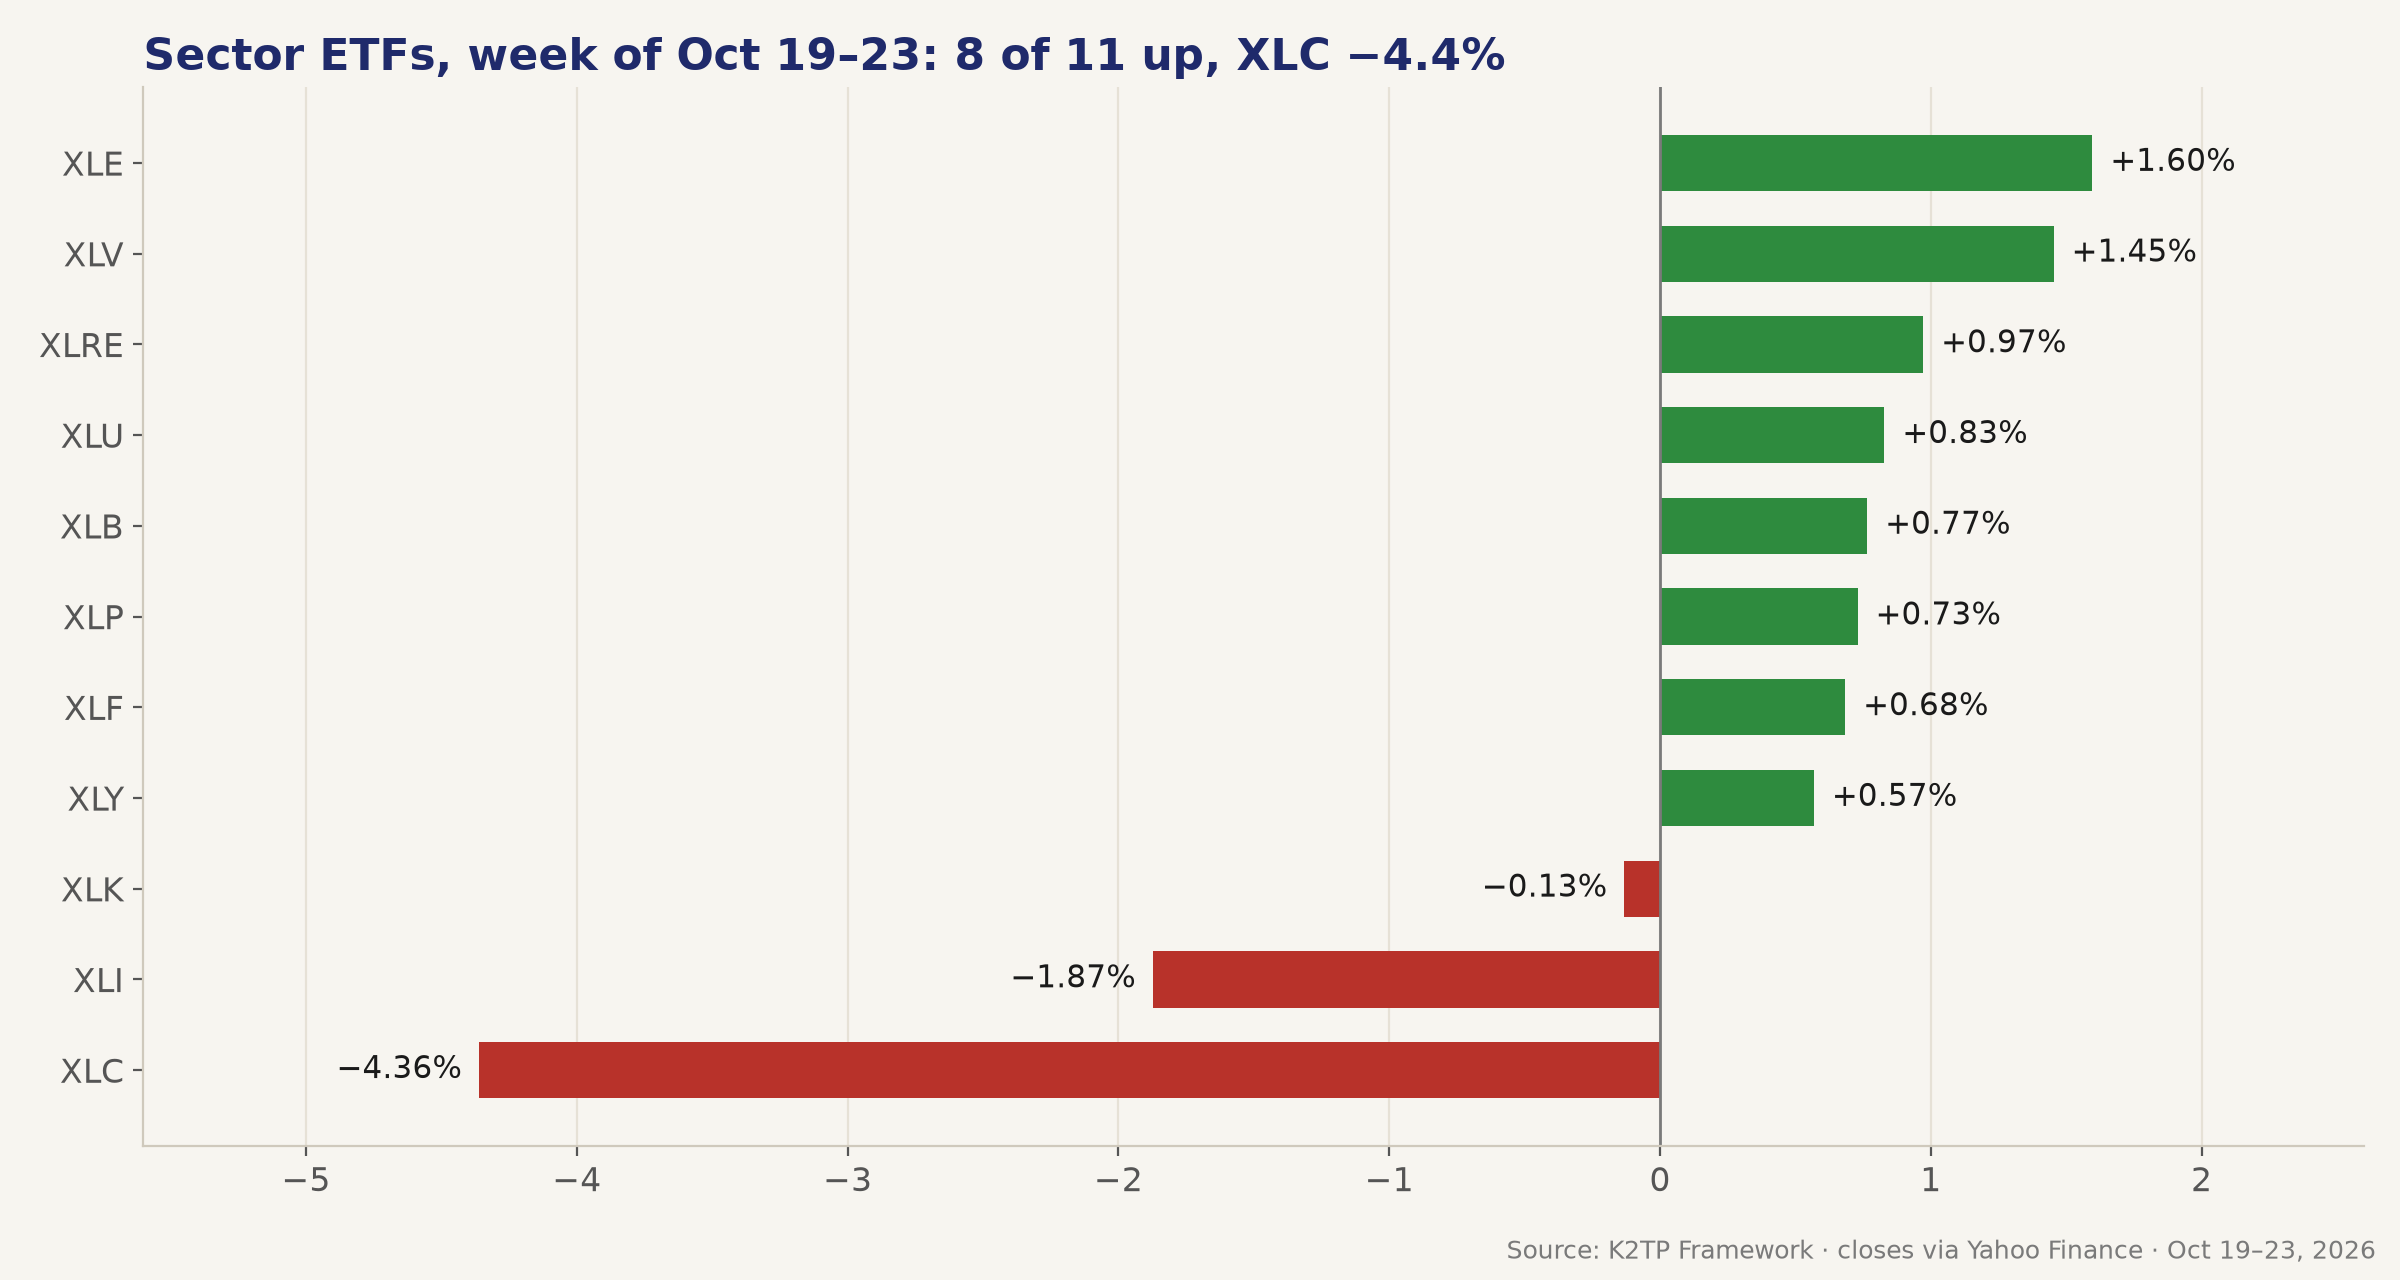
- 8 of 11 sector ETFs rose: XLE +1.60%, XLV +1.45%, XLRE +0.97%, XLU +0.83%, XLB +0.77%, XLP +0.73%, XLF +0.68%, XLY +0.57%; XLK −0.13%, XLI −1.87%, XLC −4.36%
- Tuesday was the broadest day: healthcare hit a record and LLY (+3.49%) was the S&P 500's biggest point contributor; RUT +1.65%, its biggest gain since Aug 4 (Reuters)
- Thursday's defensive bid (XLP +3.31%, XLU +2.07%) partly unwound on Friday (XLP −1.92%), as traders cut exposure before the weekend
- Communication services was the worst sector: META −9.40%, GOOGL −5.98%, NFLX −6.64%, T −10.71%, TMUS −7.89%
- Winners outside tech: BX +10.66%, LMT +9.44%, IBM +9.23%, SLB +7.19%, NOC +6.07%, MMM +5.29%
→ Money did not leave the market; it left AI. The cap-weighted SPX cannot rise while its largest names fall together, even when the average stock goes up.
THE WEEK'S MARKET
Indices (Oct 23 close, change vs Oct 16 close):
| Index | Oct 16 | Oct 23 | Week |
|---|---|---|---|
| SPX | 7,659.44 | 7,623.68 | −0.47% |
| NDX | 29,187.55 | 28,957.53 | −0.79% |
| Nasdaq Composite | 26,140.03 | 25,955.34 | −0.71% |
| RUT | 2,721.37 | 2,775.90 | +2.00% |
| DJIA | 52,002.41 | 52,215.16 | +0.41% |
| SOX | 11,137.29 | 10,779.46 | −3.21% |
| VIX | 19.99 | 19.45 | −2.70% |
| 10Y | 5.098% | 4.988% | −11.0 bp |
- SPX week range: 7,612.07 (Fri low) to 7,770.40 (Wed high); the record close is still 7,818.93
- NDX week range: 28,825.72 to 29,928.31; RUT 2,725.19 to 2,791.72
Volatility:
- VIX 19.99 → 19.45; low 16.51, Friday intraday high 20.66
- VIX9D 20.12 → 18.70, VIX3M 20.50 → 20.48: the curve is back in Contango (VIX9D < VIX < VIX3M) after last Friday's flat curve
- CNN Fear & Greed 20, "Extreme Fear" (Friday Midday brief)
Breadth:
- RSP +1.14% vs SPX −0.47%; RUT +2.00%
- Official weekly A/D totals: unavailable. Daily: NYSE advancers led 2.04-to-1 on Tuesday; decliners led 1.69-to-1 on Monday and 1.72-to-1 on Friday (Reuters)
Cross-asset:
- Brent $116.72 (+6.2%), WTI $103.27 (+2.3%), gold $4,010.00 (−4.2%), DXY 101.75 (flat from 101.78), BTC ~$80,843 (~−0.6%)
- Europe: STOXX 600 about −1.4%, its steepest weekly loss since early September (Reuters)
SPX key levels into next week:
- 7,818.93: record close
- 7,770.40: week high (Wed)
- 7,702.94: Thursday's high
- 7,663.43: Thursday's close; 7,660.15: Friday's high, the first lines to reclaim
- 7,623.68: close
- 7,612.07: week low (Fri)
- VIX: 18.87 and 20.66
Option-seller angle:
- Bull case: SPX back above 7,660.15–7,663.43 with VIX under 18.87. Even then, sell put premium only far out of the money and in small size until MSFT, GOOGL and AMZN have reported.
- Bear case: SPX under 7,612.07 with VIX above 20.66 opens a deeper leg. Cut short-put size or use defined-risk spreads.
- Event risk stacks up on Wed–Thu: the FOMC (Wed 11:00 AM PT), MSFT and GOOGL (Wed after the close), GDP and PCE (Thu 5:30 AM PT), AMZN (Thu after the close). Avoid tight Iron Condors on NDX through those days.
- Weekend gap risk from Iran headlines. Avoid short premium through earnings on single names, especially chips and platforms.
WEEKEND DEVELOPMENTS
- U.S.–Iran: On Saturday Trump said a U.S. strike on Iran could come "tomorrow". On Fox on Sunday morning he said he was weighing a "deal" against "finish them off", then confirmed "no strike today". Iran says messages via Qatari mediators continue, but it bars U.S. ships from the Gulf (AP, CBS).
→ Two-way headline risk: a strike or a deal can land at any time.
- CENTCOM plans: According to The Hill (via Al Jazeera), CENTCOM has follow-up strike plans ready, likely for after the Nov 3 midterms. Not officially confirmed.
→ Escalation risk may stretch into early November, not just this week.
- Houthis and Saudi oil: The Houthis claim Saturday attacks on Aramco Yanbu, the Rabigh refinery, the East-West pipeline, pumping stations and Riyadh/Dammam/Najran airports. The Saudi-led coalition says it intercepted 2 missiles aimed at Yanbu and Taif (CNBC, Reuters). Damage unconfirmed.
→ The East-West pipeline is the Hormuz bypass; confirmed damage would add to Brent's risk premium.
- U.S. personnel: A DNI memo warns Iranian plots against U.S. officials have reached "advanced stages". More staff drawdowns in Lebanon, the UAE, Qatar and Jordan, and ordered departure at the embassy in Saudi Arabia (NBC).
→ Another sign Washington is bracing for a bad scenario.
- Crypto: BTC broke $80K on Saturday, low about $79.1K, around $80.3K on Sunday. Liquidation figures are single-source and left out.
→ Weak weekend risk appetite.
- Corporate: No notable weekend news on Meta, Tesla, SpaceX or China trade. Oracle AI World opens Sunday.
- Open outlook (Sunday 3 PM PT): Brent likely gaps higher and ES/NQ open slightly lower; "no strike today" may soften it.
→ Keep far-strike hedges and avoid short-dated premium into Wednesday–Thursday.
BOTTOM LINE
- The index barely moved (SPX −0.47%), but leadership changed hard: RUT +2.00%, RSP +1.14%, SOX −3.21%, META −9.40%.
- AI demand stayed strong (SpaceX, Super Micro, Western Digital), but Meta's funding plan made AI capex a credit question, and chip equipment paid the most.
- Bonds rallied on fear (10Y −11.0 bp) while Brent rose 6% to $116.72. That mix squeezes the Fed ahead of Wednesday's decision.
- The regime ends the week 🔴 RISK-OFF. It returns to 🟡 TRANSITION only if SPX reclaims 7,663.43 with VIX under 18.87 and chips stabilize after the MSFT, GOOGL and AMZN reports.
WHAT TO WATCH NEXT WEEK (PT)
| Day | Data (PT) | Earnings |
|---|---|---|
| Sun 10/25 | 3:00 PM: futures reopen | — |
| Mon 10/26 | $69B 2-year note auction | Before: VZ · After: CDNS, NUE, WELL, PSA |
| Tue 10/27 | 5:30 AM: durable goods; 6:00 AM: Case-Shiller; 7:00 AM: new home sales, Conference Board consumer confidence; FOMC day 1 | Before: KO, BA, UPS, HCA, SPGI, AMT · After: V, STX, NXPI, HOOD |
| Wed 10/28 | 5:30 AM: trade balance; 11:00 AM: FOMC decision; 11:30 AM: Warsh press conference; Bank of Canada decision | Before: GEV, ADP, BSX, VRT · After: MSFT, GOOGL, KLAC, TMUS, NOW |
| Thu 10/29 | 5:30 AM: Q3 GDP (advance), September PCE and core PCE, personal income and spending, jobless claims | Before: LLY, MA, MRK, CAT, LIN · After: AMZN, INTC, SNDK, SBUX, GILD |
| Fri 10/30 | 5:30 AM: employment cost index (Q3); 6:45 AM: Chicago PMI; 9:00 AM: Fed's Daly; 9:30 AM: Fed's Musalem | Before: XOM, CVX, ABBV, GD |
- Weekend: Iran headlines and the Brent $116.72 line when futures reopen Sunday afternoon
- Wed–Thu hold most of the risk: the FOMC plus MSFT and GOOGL on Wednesday, GDP, PCE and AMZN on Thursday; 177 S&P 500 companies report this week (StockTitan)
- Consensus EPS (Nasdaq): MSFT $4.71, GOOGL $2.94, AMZN $2.01, LLY $5.38, XOM $3.96; capex guidance from MSFT, GOOGL and AMZN decides whether chips stabilize
- Next: Apple reports Mon Nov 2 after the close; Nov 3: US midterms
Expected (Bull): SPX back above 7,663.43 with VIX under 18.87, Brent easing below $113.17 and a calm FOMC. Expected (Bear): SPX under 7,612.07 with VIX above 20.66, Brent above $116.72 and hawkish FOMC language.
Sources: K2TP daily syntheses for Oct 19–23, 2026, and the K2TP briefs for Oct 19–23 (Pre-Market, Midday, Pre-Close, Evening Recap; Friday has no Evening Recap, so Friday uses official closes). Weekly closes from Yahoo Finance; oil settlements, news and breadth from Reuters, AP, CNBC, WSJ and Bloomberg; next-week calendar from StockTitan, Kiplinger and company notices, converted to PT; earnings Sankeys from official company releases. Analysis: K2TP Framework.