Week 10/12–10/16: Hot Inflation and AI-Debt Stress Hand SPX Its Worst Week Since June
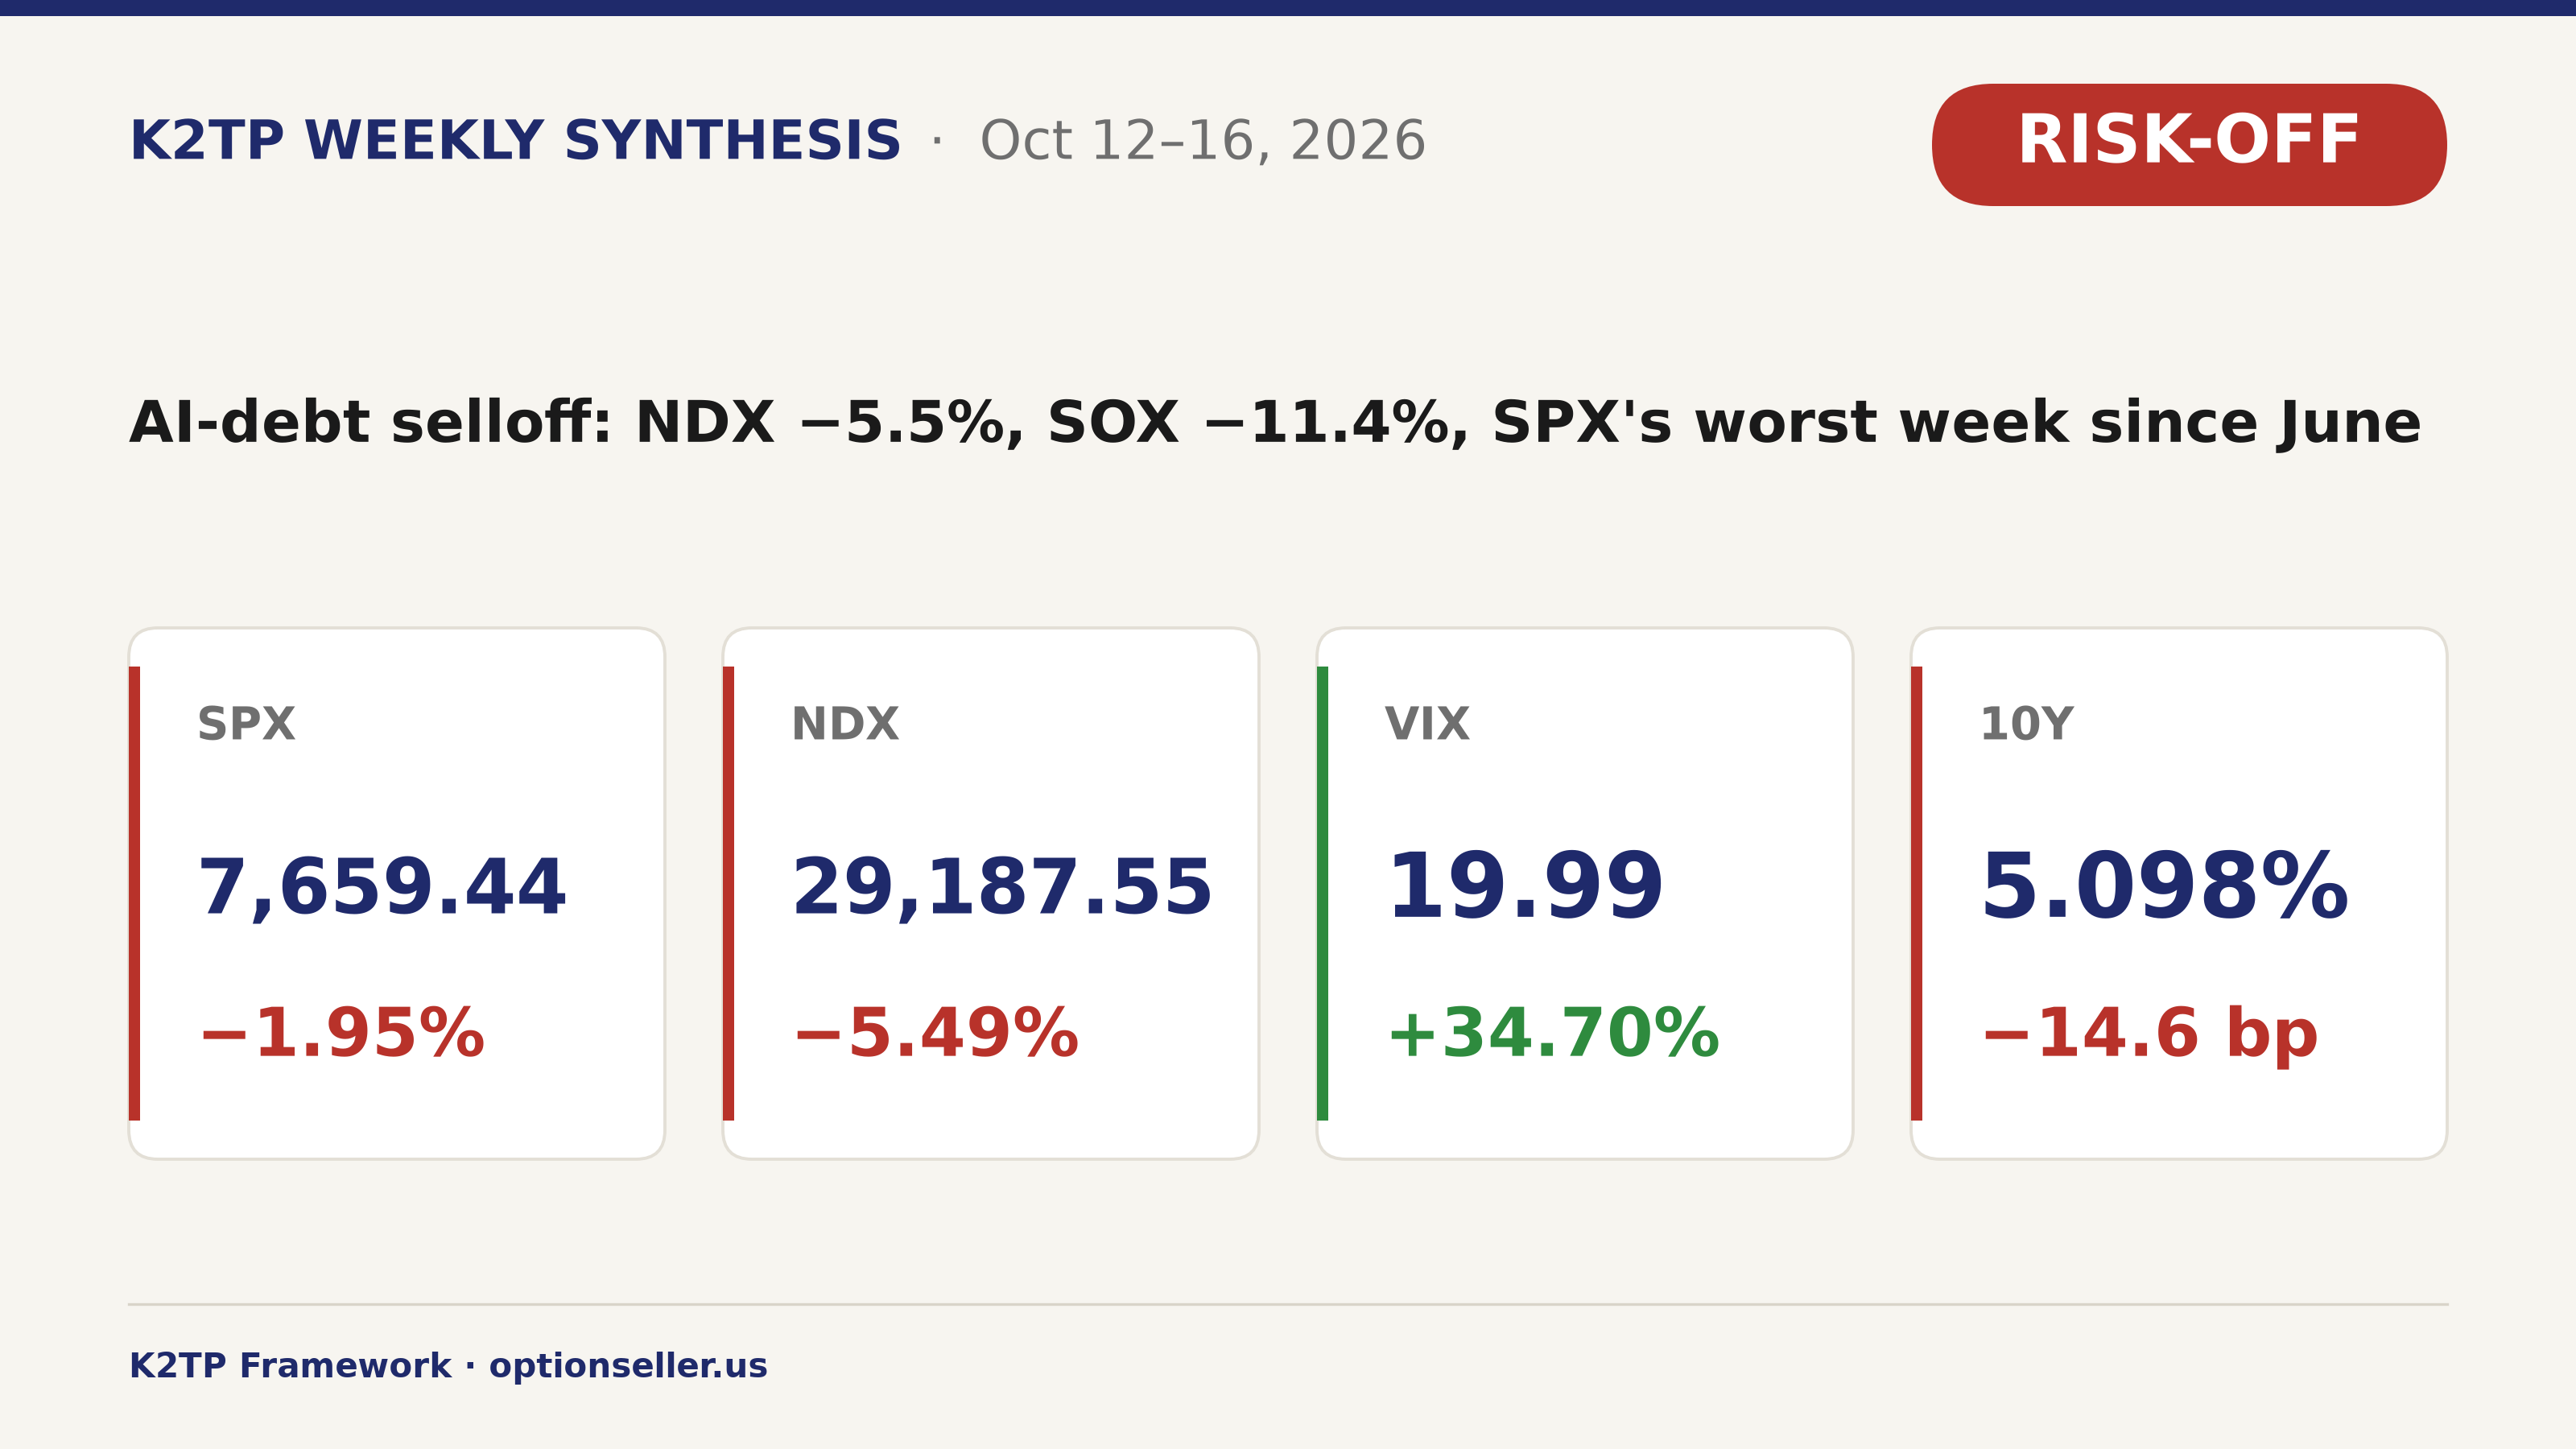
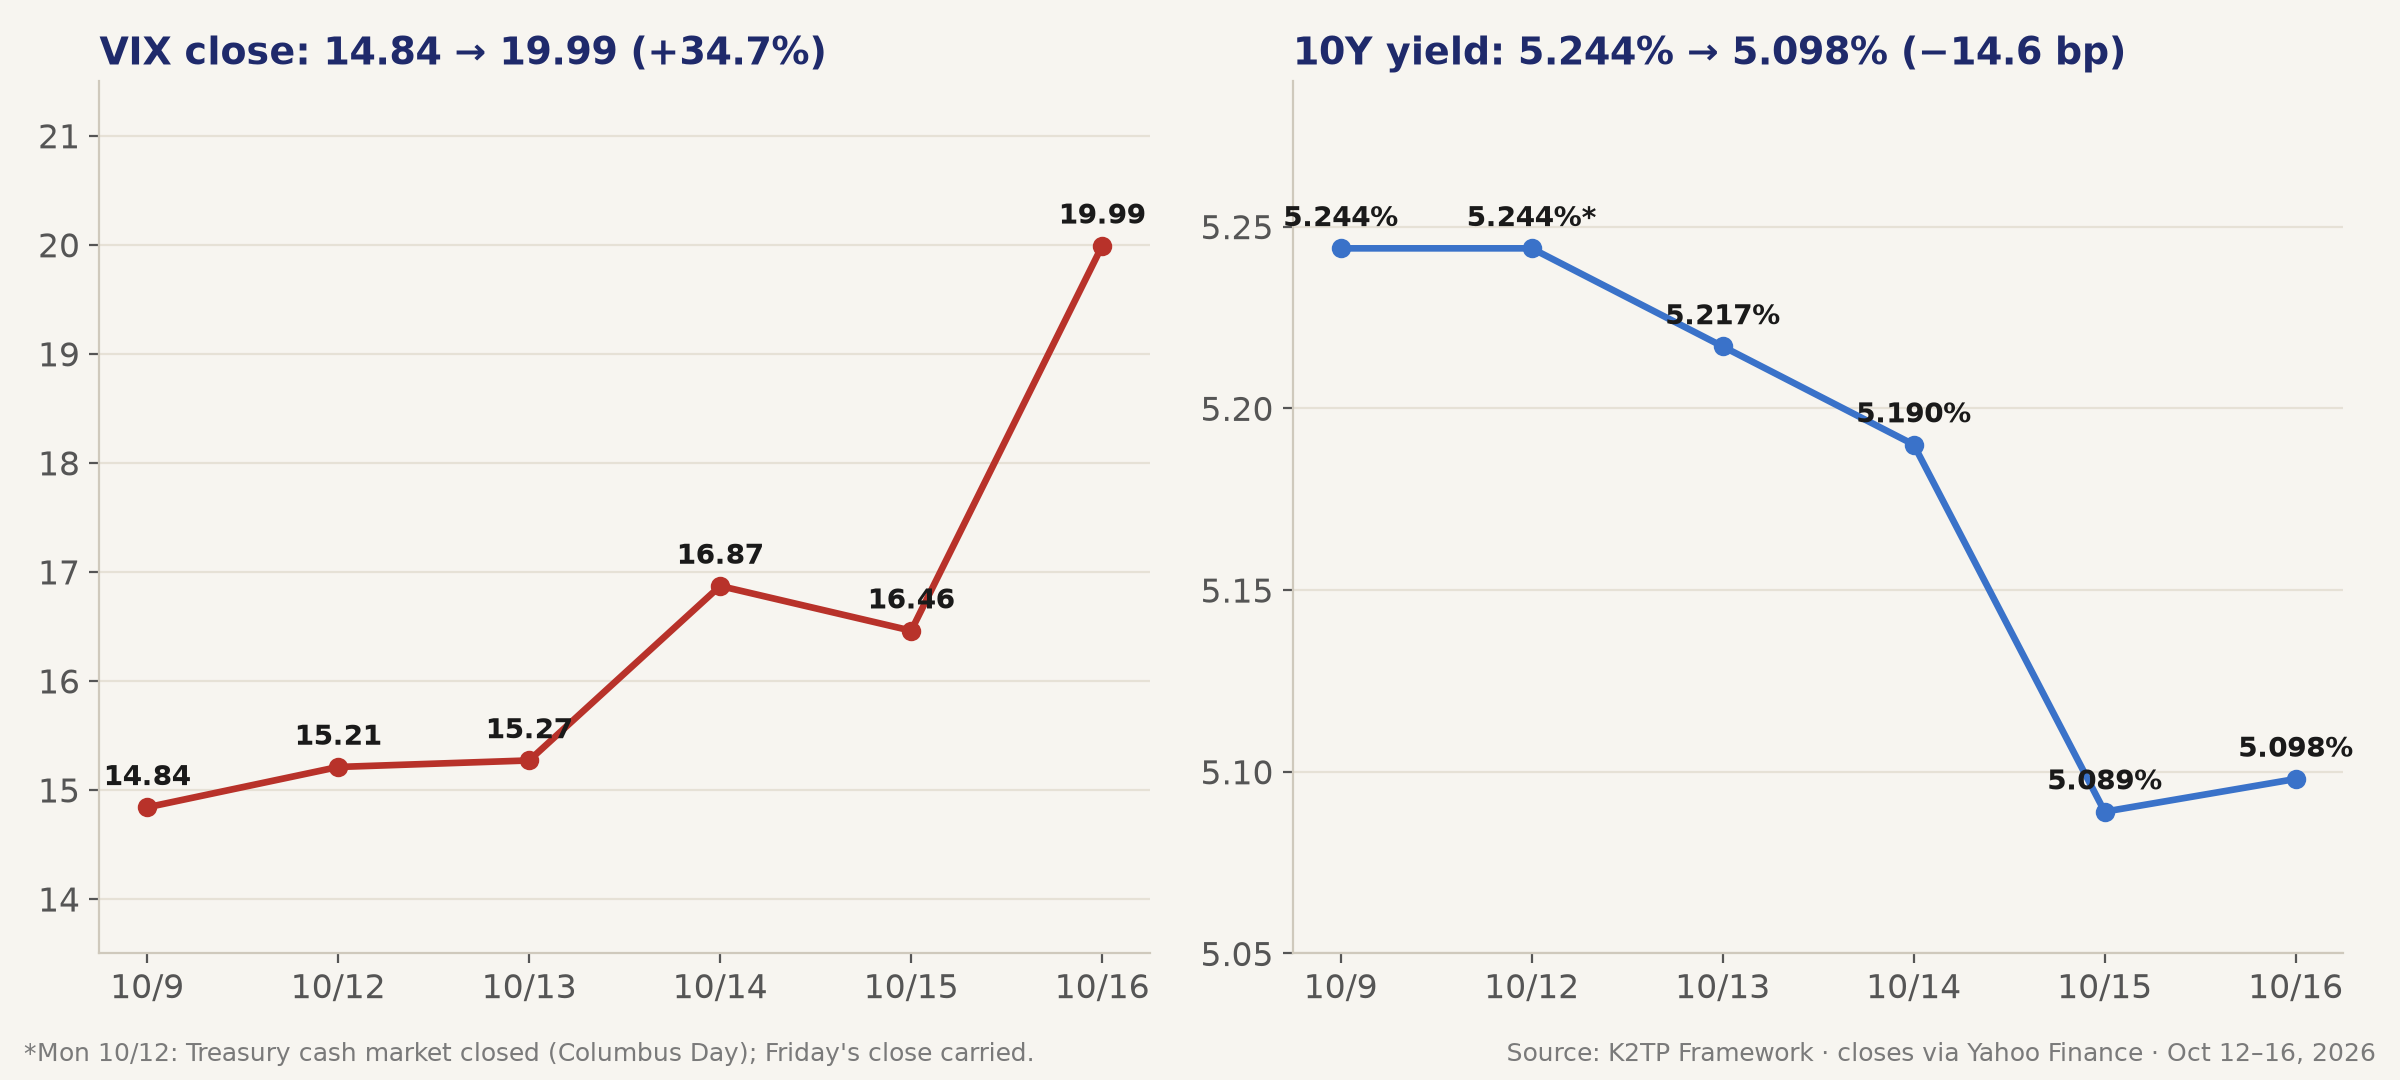
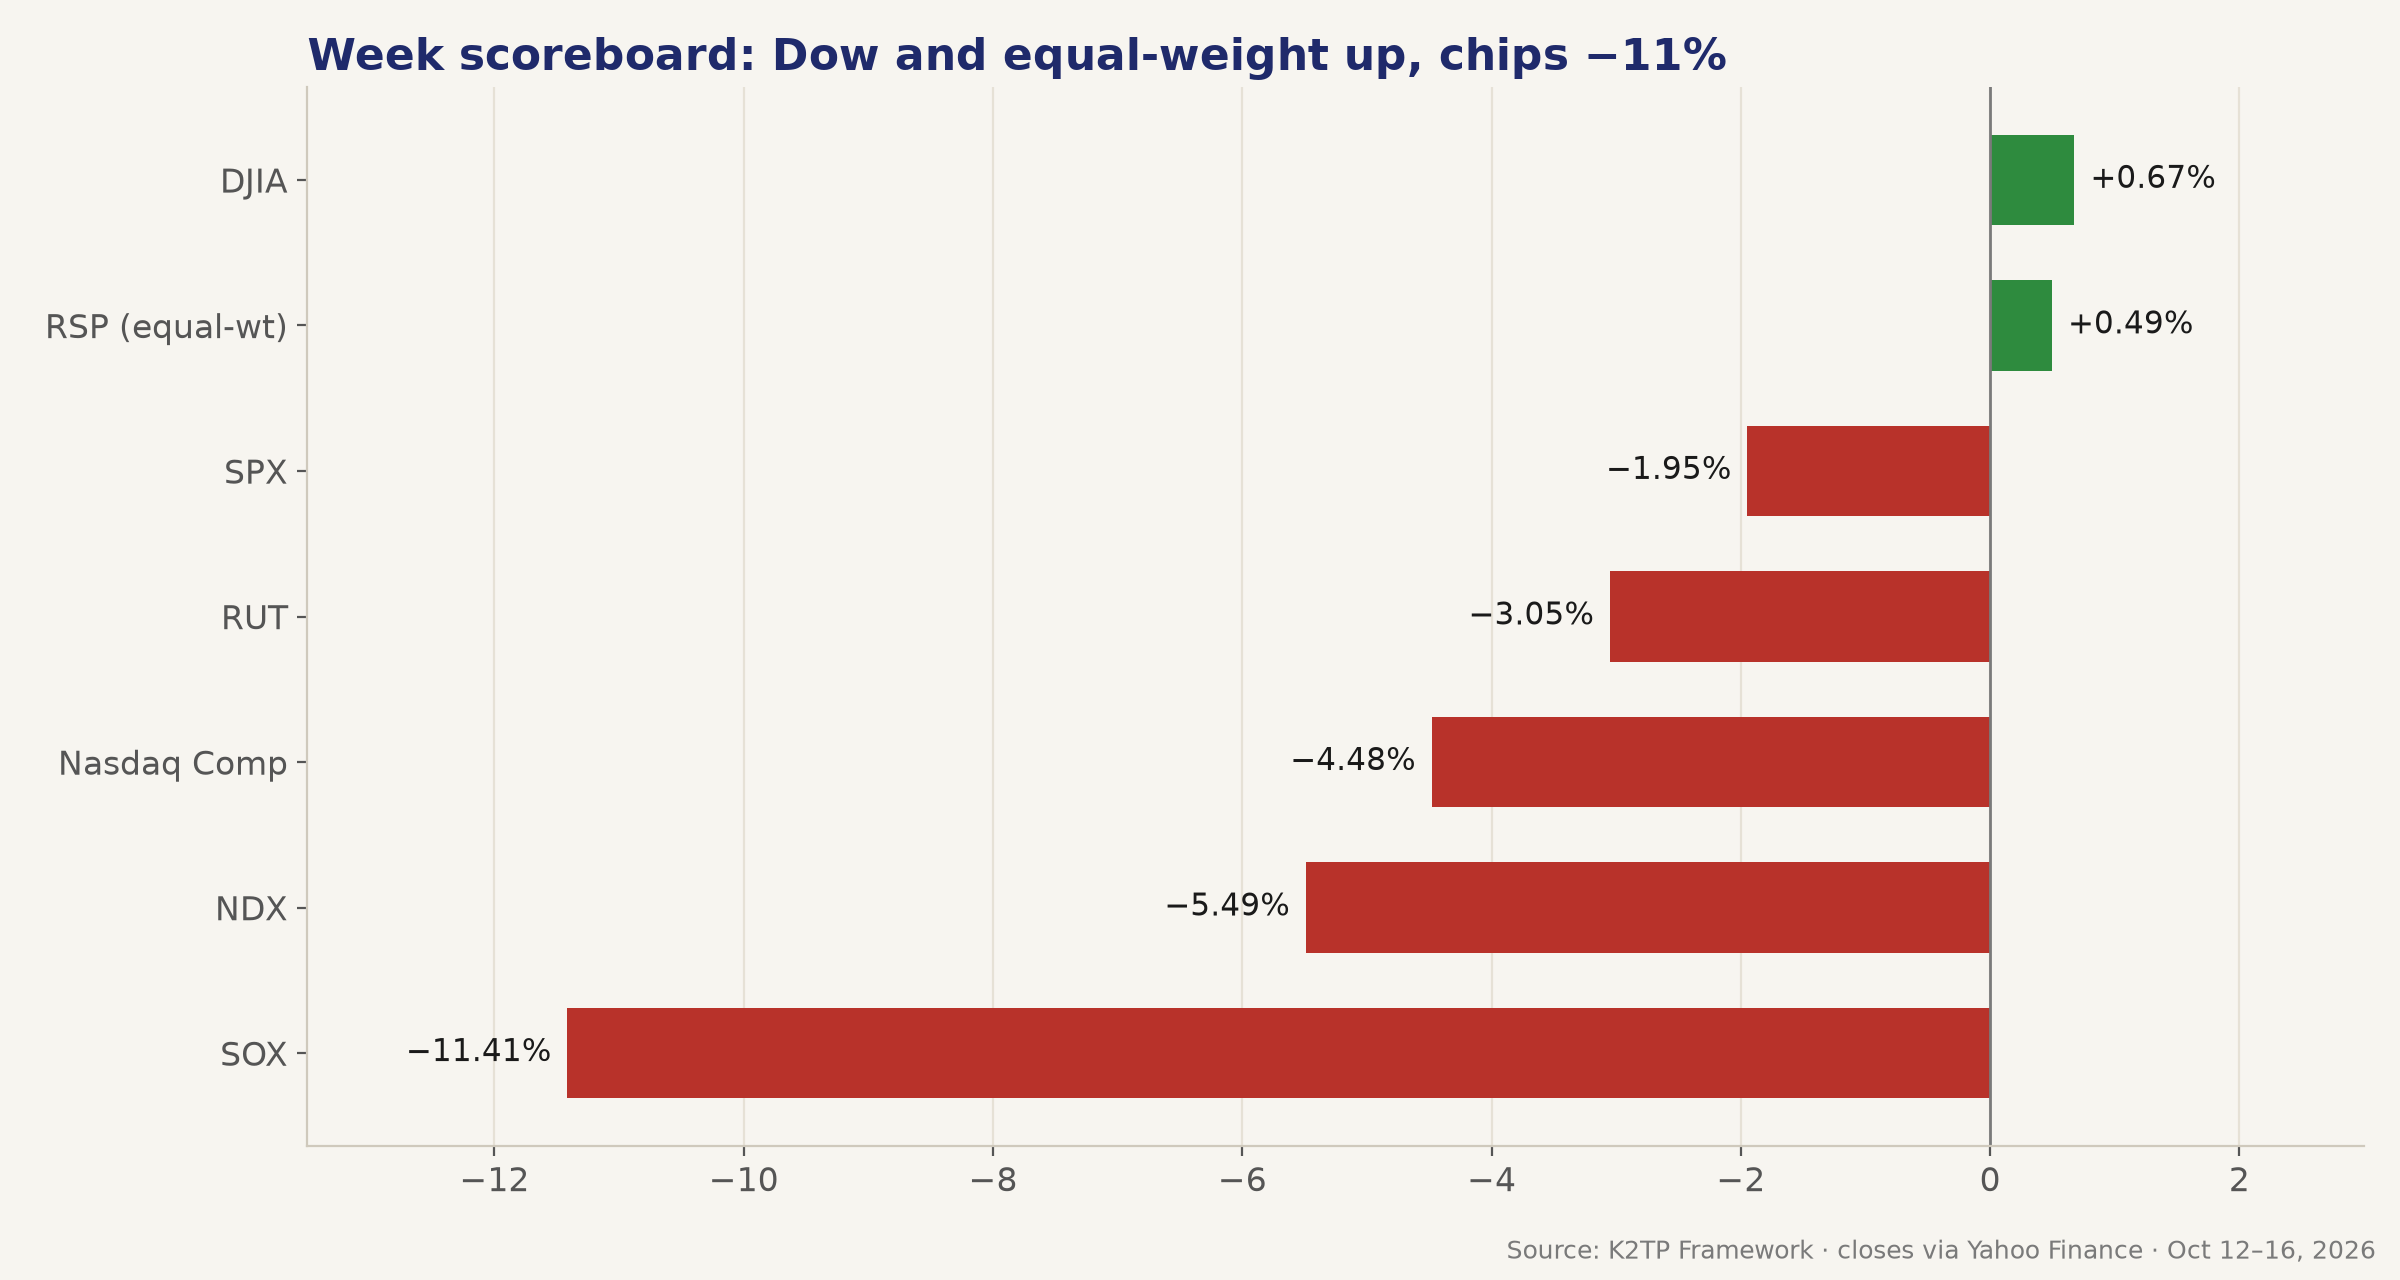
SPX −1.95%, NDX −5.49%, RUT −3.05%, VIX +34.7%, 10Y −14.6 bp. Bonds rallied, but money left AI for energy, staples and health care.
KEY HEADLINES OF THE WEEK
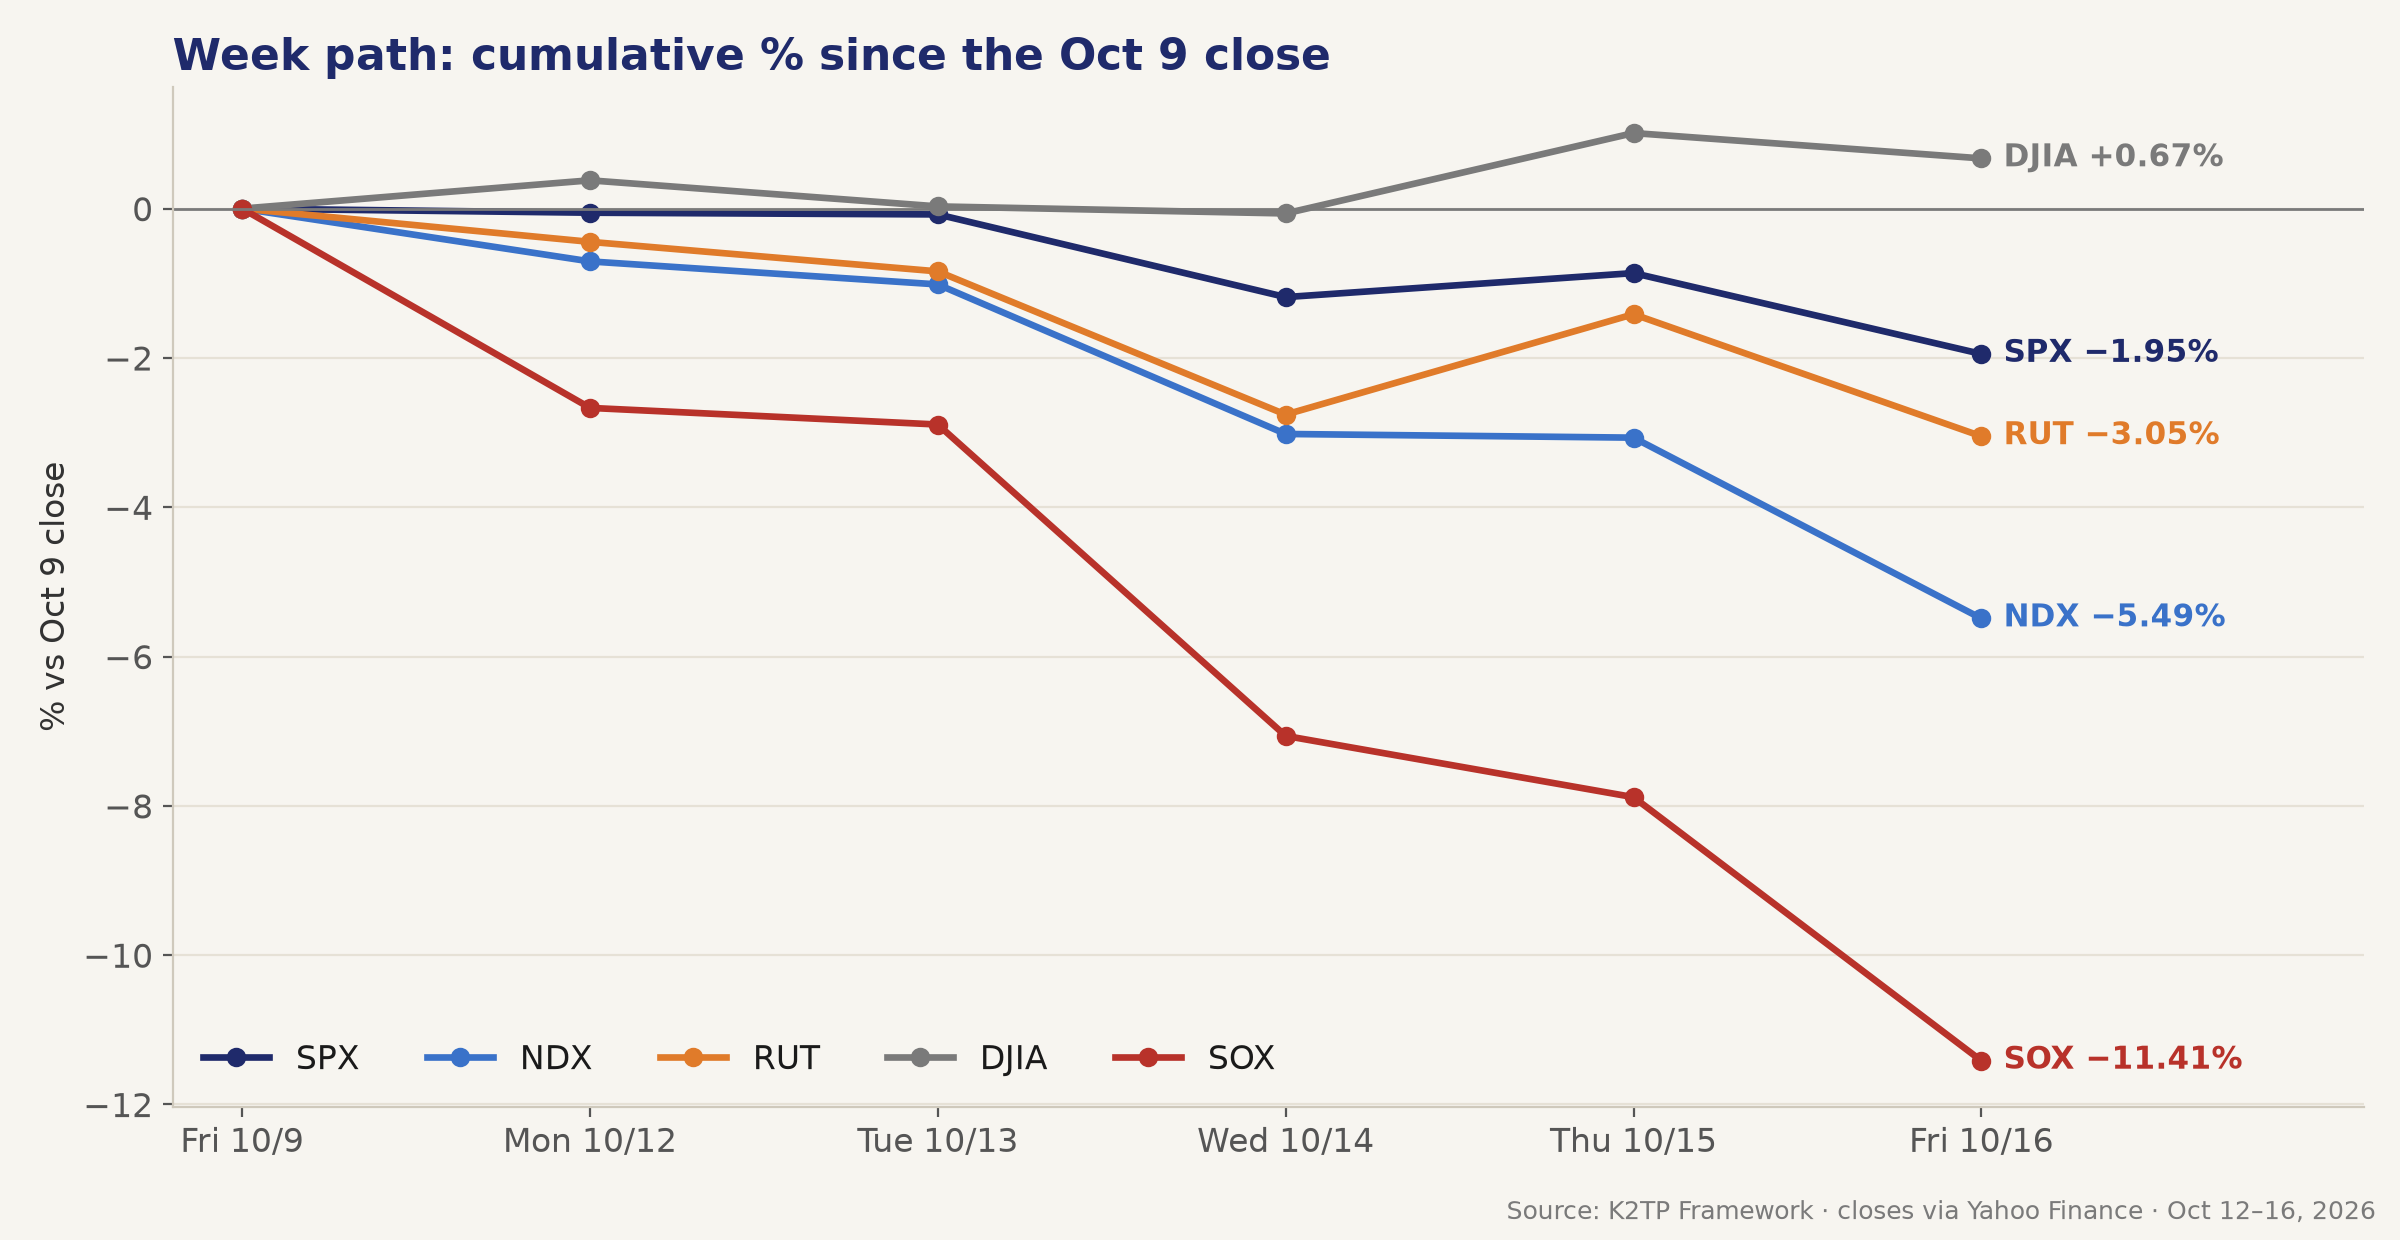
- SPX −1.95% to 7,659.44, its worst week since June; NDX −5.49%, Nasdaq Composite −4.48%, RUT −3.05%
- The Dow (+0.67%) and equal-weight RSP (+0.49%) still finished the week higher: this was an AI selloff, not a broad liquidation
- SOX −11.41% for the week and eight straight daily declines; CRWV −25.2%, DELL −22.9%, AMAT −19.3%, MU −14.6%
- Three hot price prints: CPI (core +0.3% m/m vs +0.2%), PPI (+1.3% m/m vs +0.6%), import prices (+1.1% vs +0.8%)
- October hike odds spiked to 53.7% after CPI, then faded to ~16% by Friday morning
- 10Y fell 14.6 bp to 5.098% even with hot data; the 30Y logged its biggest weekly drop in more than a year (MarketWatch)
- Brent +4.9% to $109.86, touching $110 for the first time since May on Strait of Hormuz attacks
- VIX 14.84 → 19.99 (+34.7%); VIX9D ended above VIX after Friday's flush
- Bank earnings were mixed and sold: JPM and BAC missed on EPS; GS and MS beat but fell
- Sectors: 7 of 11 up; XLP +5.02% and XLE +4.86% led, XLK −7.70% was the big loser
- Regime: 🟡 TRANSITION (Mon–Tue) → 🔴 RISK-OFF (Wed) → 🟡 TRANSITION (Thu) → 🔴 RISK-OFF (Fri close)
THE WEEK DAY BY DAY
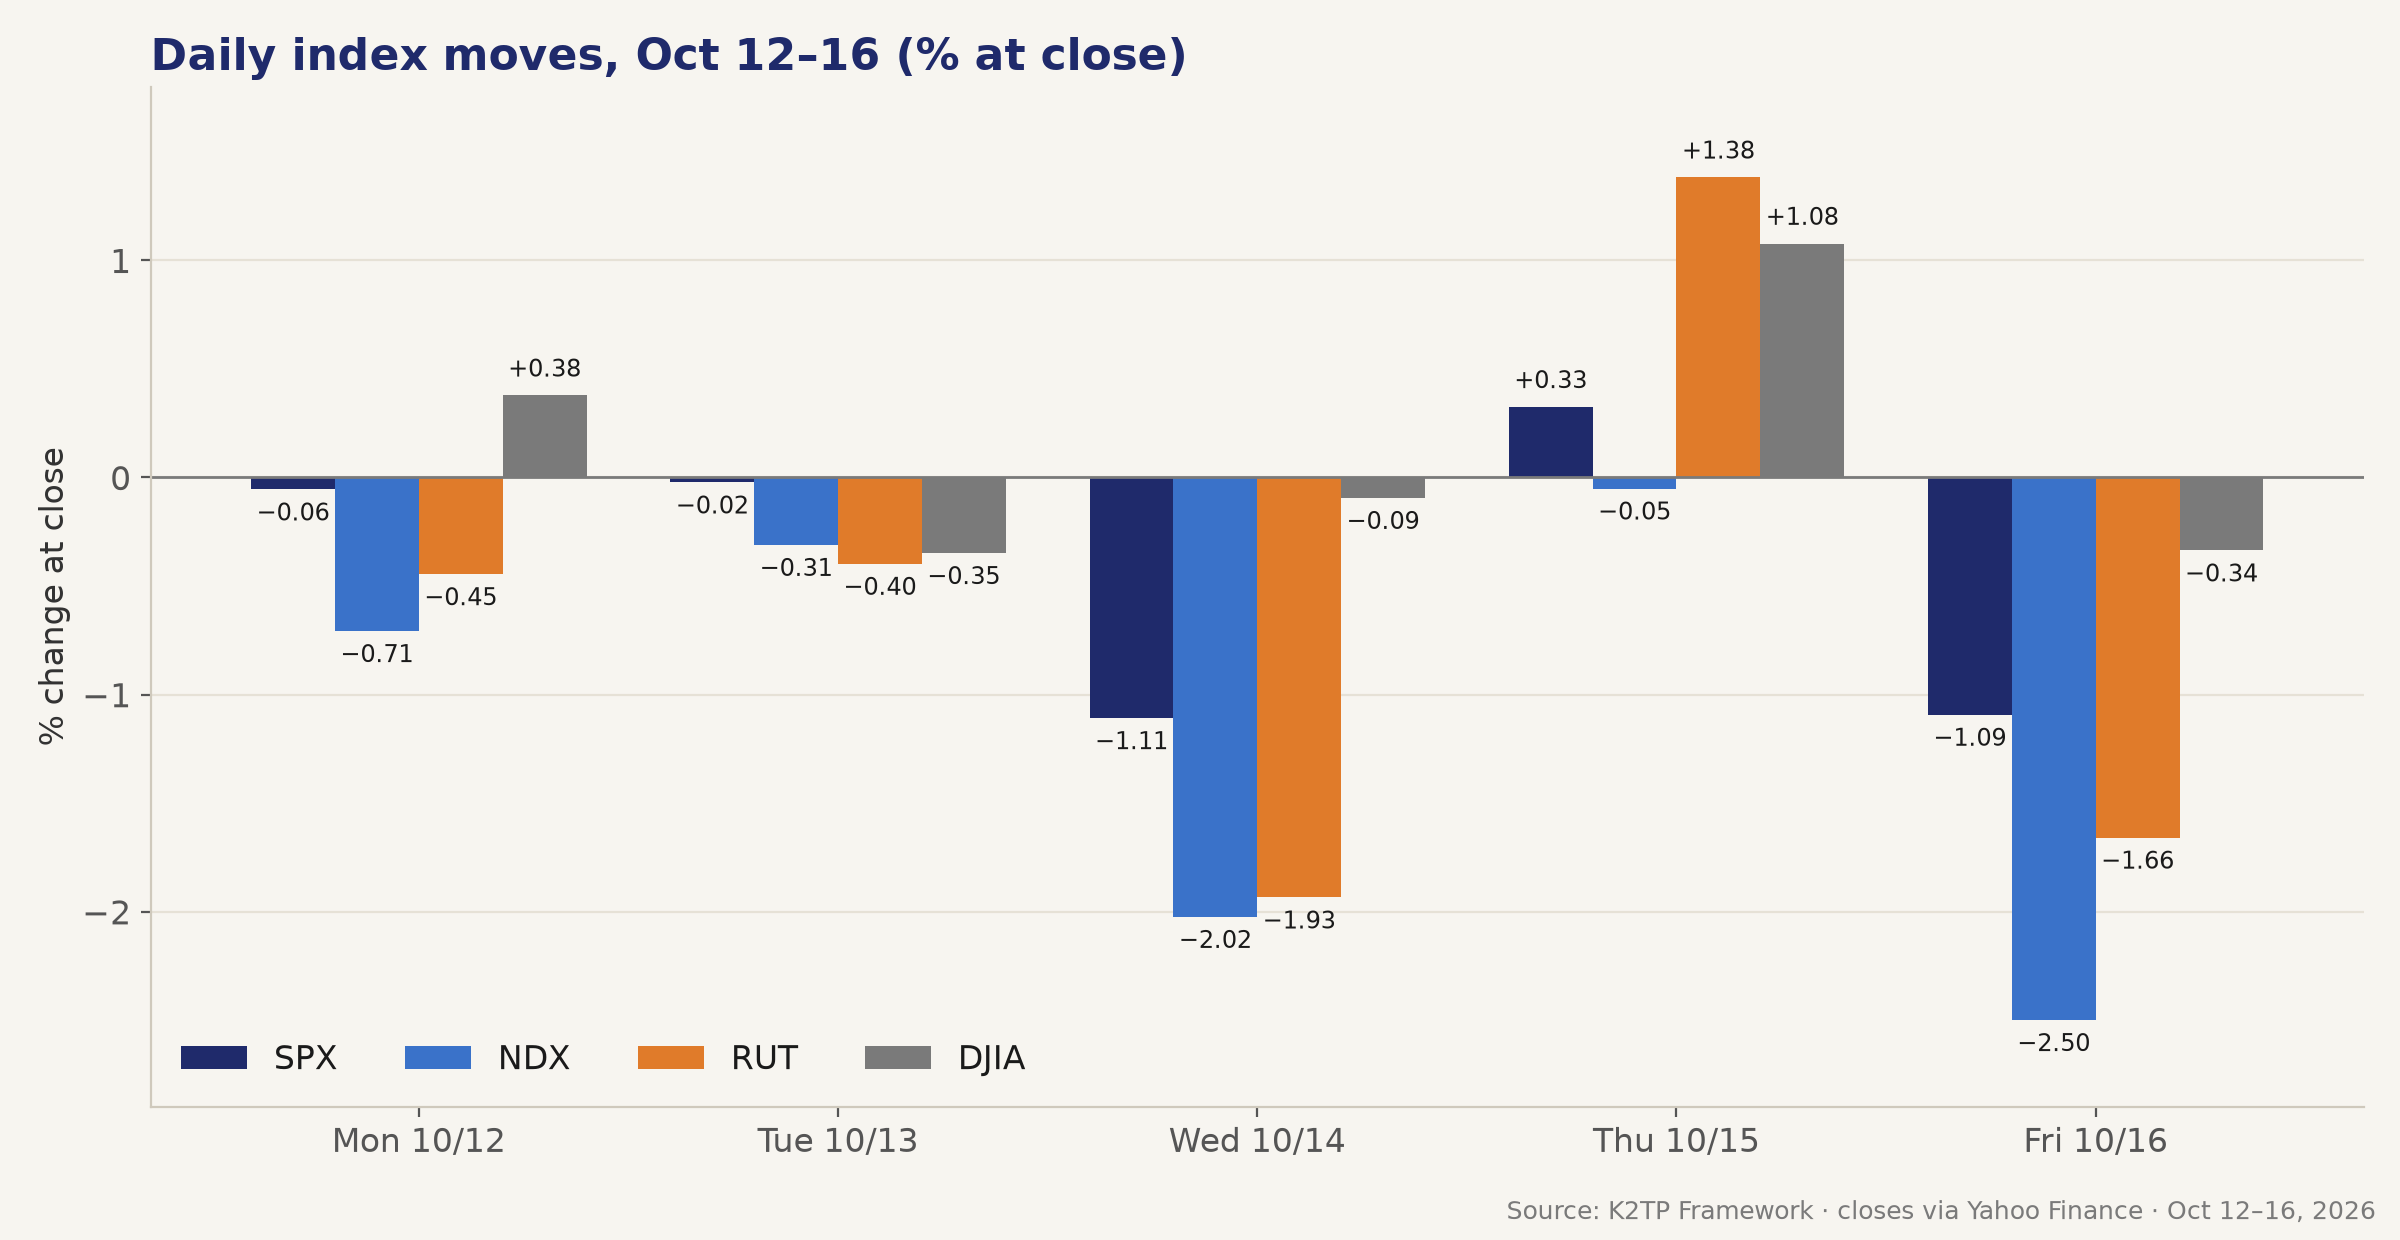
| Day | SPX | NDX | RUT | VIX | 10Y | Regime | Driver |
|---|---|---|---|---|---|---|---|
| Mon 10/12 | 7,807.24 (−0.06%) | −0.71% | −0.45% | 15.21 | closed | 🟡 | Memory-led chip selloff; bonds shut for Columbus Day |
| Tue 10/13 | 7,805.45 (−0.02%) | −0.31% | −0.40% | 15.27 | 5.217% | 🟡 | Banks open earnings; JPM misses; late chip rebound |
| Wed 10/14 | 7,718.94 (−1.11%) | −2.02% | −1.93% | 16.87 | 5.190% | 🔴 | Hot CPI; AI infrastructure unwind |
| Thu 10/15 | 7,744.06 (+0.33%) | −0.05% | +1.38% | 16.46 | 5.089% | 🟡 | Hot PPI, bonds rally; rotation into small caps |
| Fri 10/16 | 7,659.44 (−1.09%) | −2.50% | −1.66% | 19.99 | 5.098% | 🔴 | CoreWeave debt stress, Brent $110, OpEx |
- Monday and Tuesday were nearly flat for SPX, held up by platforms (META +3.38% Mon, +2.63% Tue) while chips slid
- Wednesday's CPI broke the range: SPX lost Friday's 7,779.34 low, and the week never recovered it
- Thursday's bounce came from rotation (RUT +1.38%, Dow +1.08%), not from tech
- Friday failed at a 7,756.84 opening high and closed at the week's low area (low 7,631.77)
→ The week was not one crash. It was a steady drain from AI, with two hard down days (Wed and Fri) that each took NDX down about 2–2.5%.
INFLATION: THREE HOT PRINTS IN THREE DAYS
| Release (September) | Actual | Forecast | Prior |
|---|---|---|---|
| CPI m/m | +0.6% | +0.5% to +0.6% | +0.4% |
| CPI y/y | 3.7% | 3.6% | 3.4% |
| Core CPI m/m | +0.3% | +0.2% | +0.3% |
| Core CPI y/y | 2.6% | 2.4% to 2.5% | 2.4% |
| PPI m/m | +1.3% | +0.6% | +0.5% |
| PPI y/y | 6.3% | 5.5% | 5.6% |
| Core PPI m/m | +0.7% | +0.3% | +0.2% |
| Import prices m/m | +1.1% | +0.8% | +0.5% (rev.) |
| Export prices m/m | +2.2% | +1.0% | +1.2% (rev.) |
- CPI: the biggest monthly gain in five months, with energy driving much of the headline 🔴
- PPI: the largest monthly jump since 2022; CNBC pointed to energy/diesel pass-through 🔴
- Import prices 8.1% y/y (prior 7.0%) 🔴
- Beige Book (Wed): slight growth overall, prices robust in 3 districts and moderate in 8
→ Every price gauge this week came in above forecast. Energy explains much of it, but core CPI at +0.3% for a second month means the Fed cannot call it only oil.
ACTIVITY: THE CONSUMER AND FACTORIES STILL HOLD UP
| Release | Actual | Forecast | Prior |
|---|---|---|---|
| Retail sales m/m | +0.8% | +0.4% | +1.3% |
| Retail sales ex autos m/m | +0.9% | +0.5% | +1.4% |
| Initial jobless claims | 199K | 200K | 198K |
| Empire State | 25.5 | 10.3 | 7.6 |
| Philly Fed | 20.9 | 28.4 | 37.8 |
| Industrial production m/m | +0.7% | +0.4% | +0.1% (rev.) |
| Capacity utilization | 76.9% | n/a | 76.4% (rev.) |
- Retail sales and industrial production beat 🟢; Philly Fed missed but stayed in expansion
- Claims stayed near 200K: no sign of labor stress in the weekly data
→ Hot prices plus firm activity is the hawkish mix. It explains why hike risk shifted to December and January rather than disappearing.
FED AND RATES: HIKE ODDS ROUND-TRIP, BONDS RALLY ANYWAY
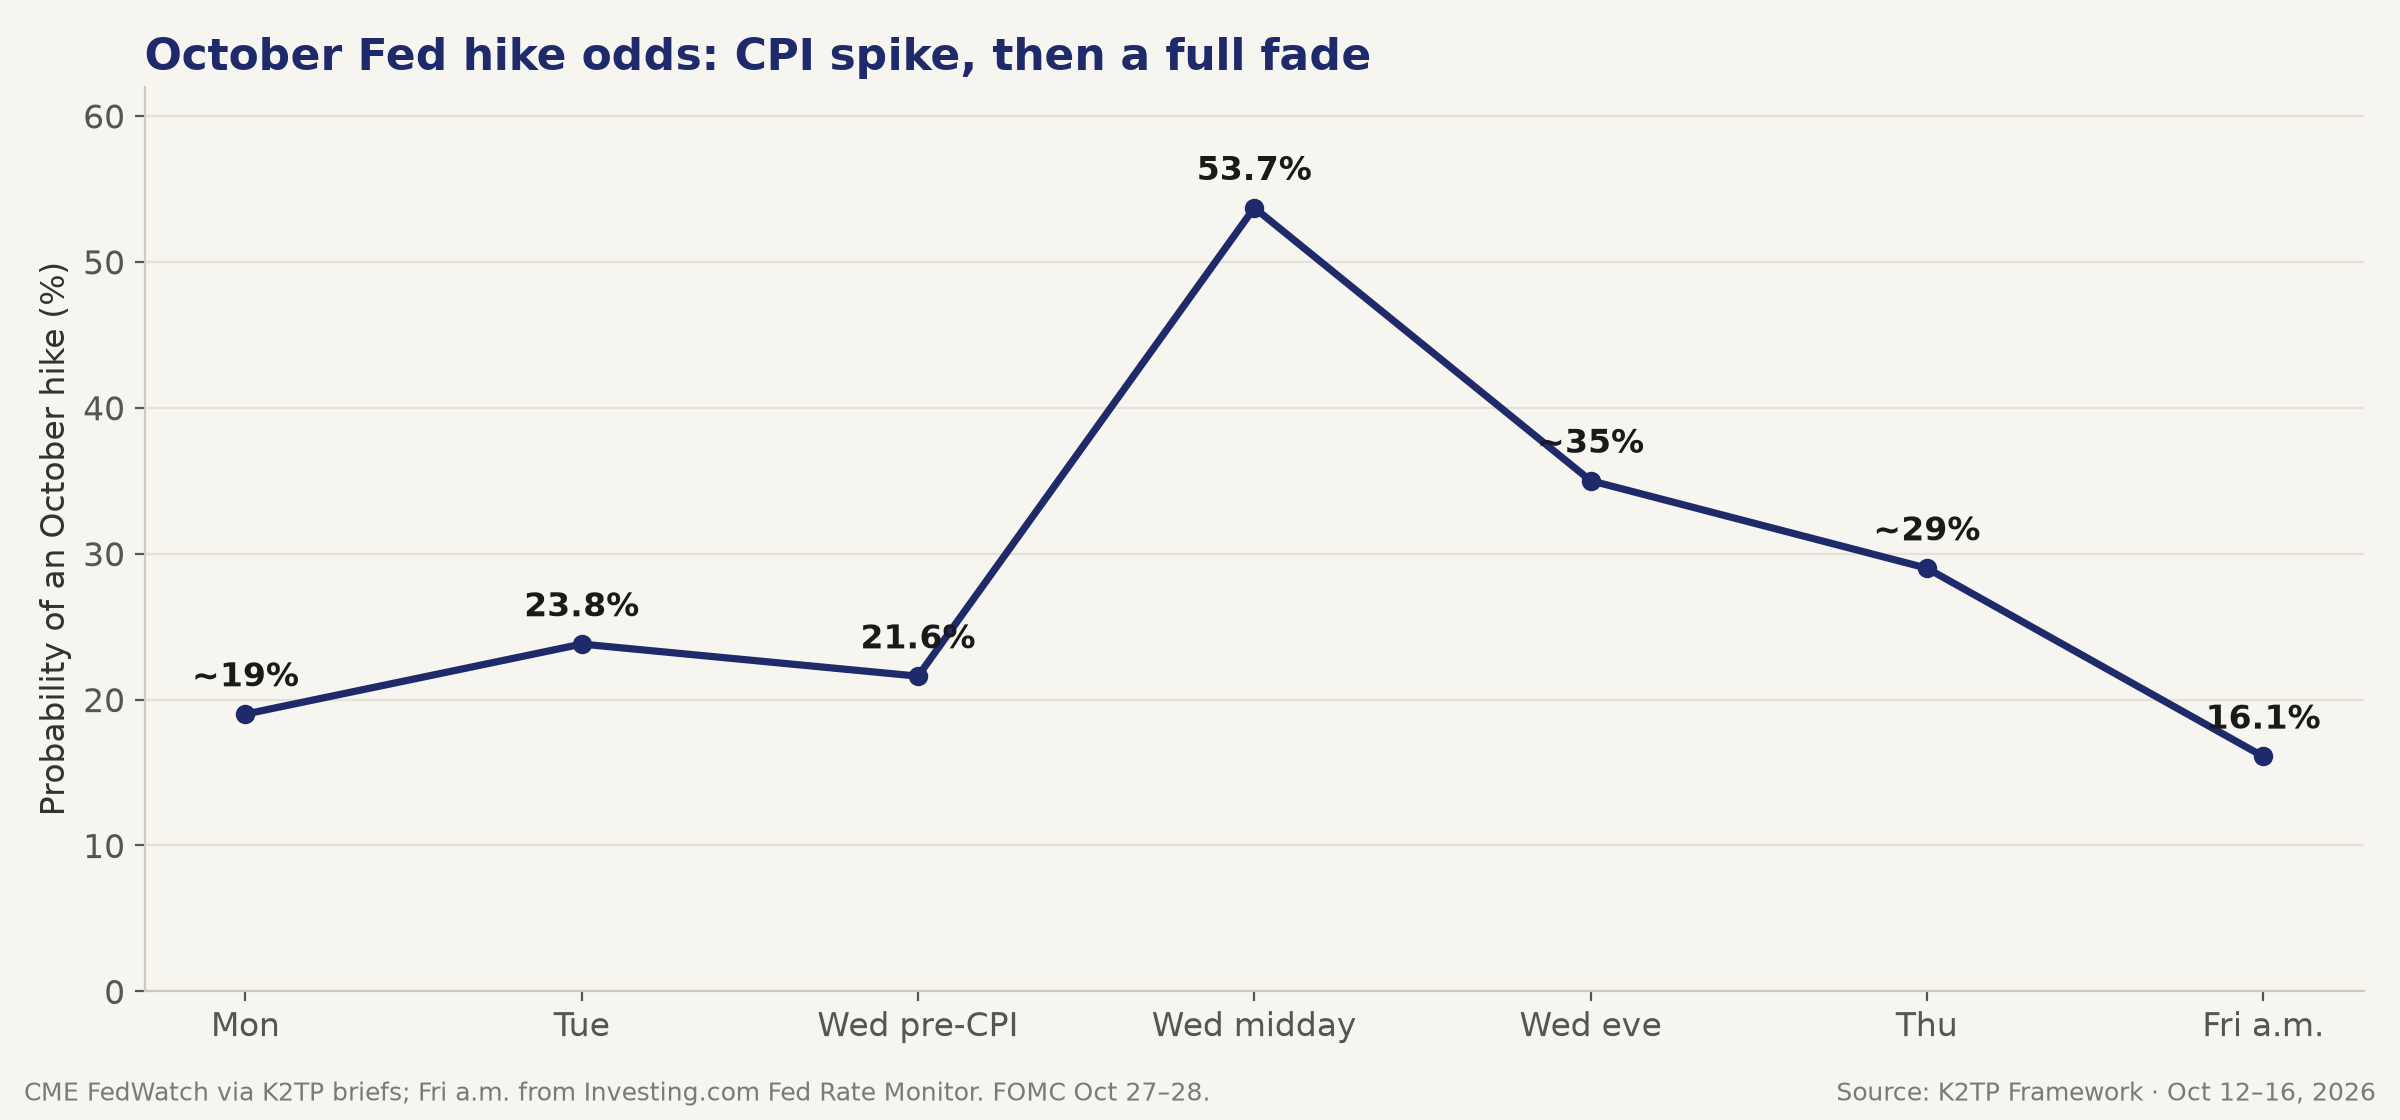
- October hike odds (CME FedWatch via the briefs): ~19% Mon → ~23.8% Tue → 21.6% pre-CPI → 53.7% Wed midday → ~35% Wed evening → ~29% Thu → ~16.1% Fri morning (Investing.com Fed Rate Monitor)
- Fed speakers: Hammack (Mon) backed a restrictive stance; Collins (Tue) sees hikes "a bit further" by year-end; Bowman (Wed) said the Fed has time to wait; Warsh (Thu night) gave no meeting guidance
- Barclays now expects 25 bp hikes in December and January (Reuters)
- 10Y: 5.244% → 5.098% (−14.6 bp); 5Y 5.021% → 4.899% (−12.2 bp); 30Y 5.600% → 5.436% (−16.4 bp)
- CPI day: the 10Y spiked to 5.325% pre-market, then closed at 5.190%. PPI day: −10.1 bp to 5.089%
- DXY 102.23 → 101.78; gold $4,216.30 → $4,186.70
→ The long end rallied through three hot prints. Bonds treated the week as growth and geopolitical risk, not as a new inflation regime. But with Brent near $110, bonds did not cushion Friday's equity selloff.
EARNINGS: BANKS OPEN THE SEASON, TSMC BEATS AND RAISES
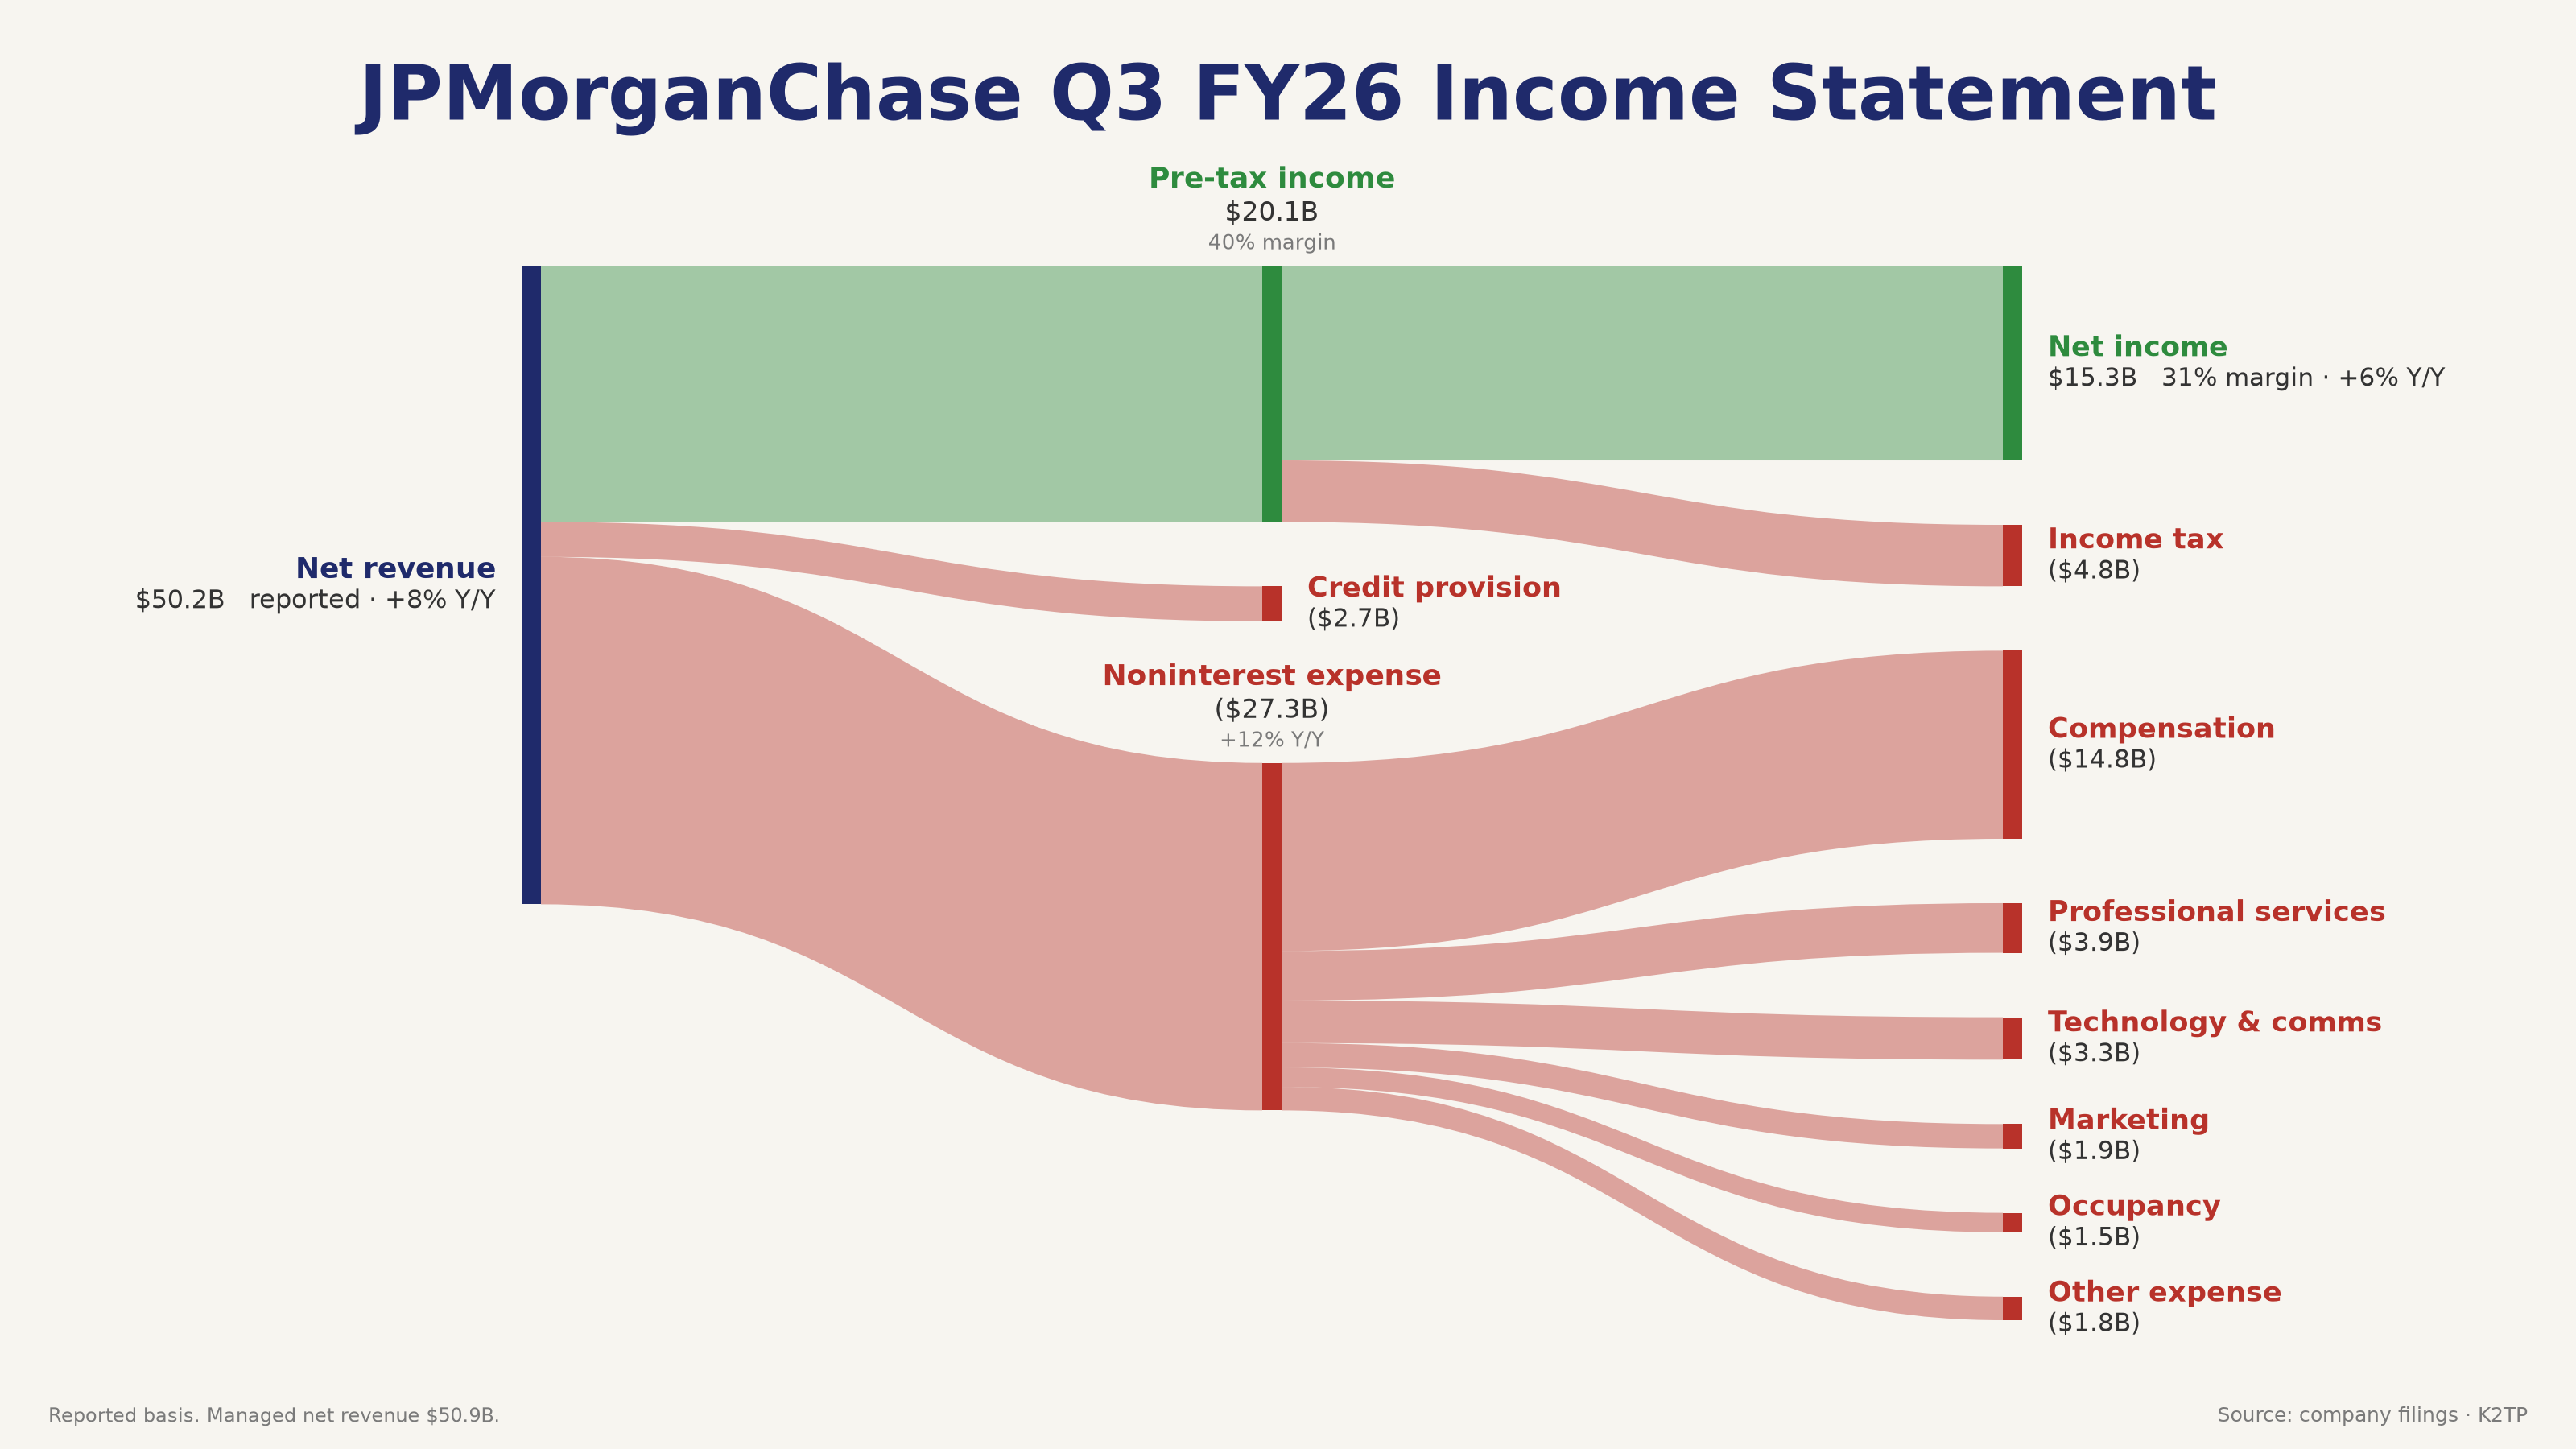
- JPM (Tue): EPS $5.57 vs ~$5.93 expected, its first profit miss in nearly three years 🔴. Stock −0.86% on the day, +2.02% on the week
- GS (Tue): EPS $17.01, a beat 🟢, yet −0.23% on the day; C −5.60% and WFC −3.10% the same session
- JNJ (Tue): raised full-year guidance, yet −5.73%
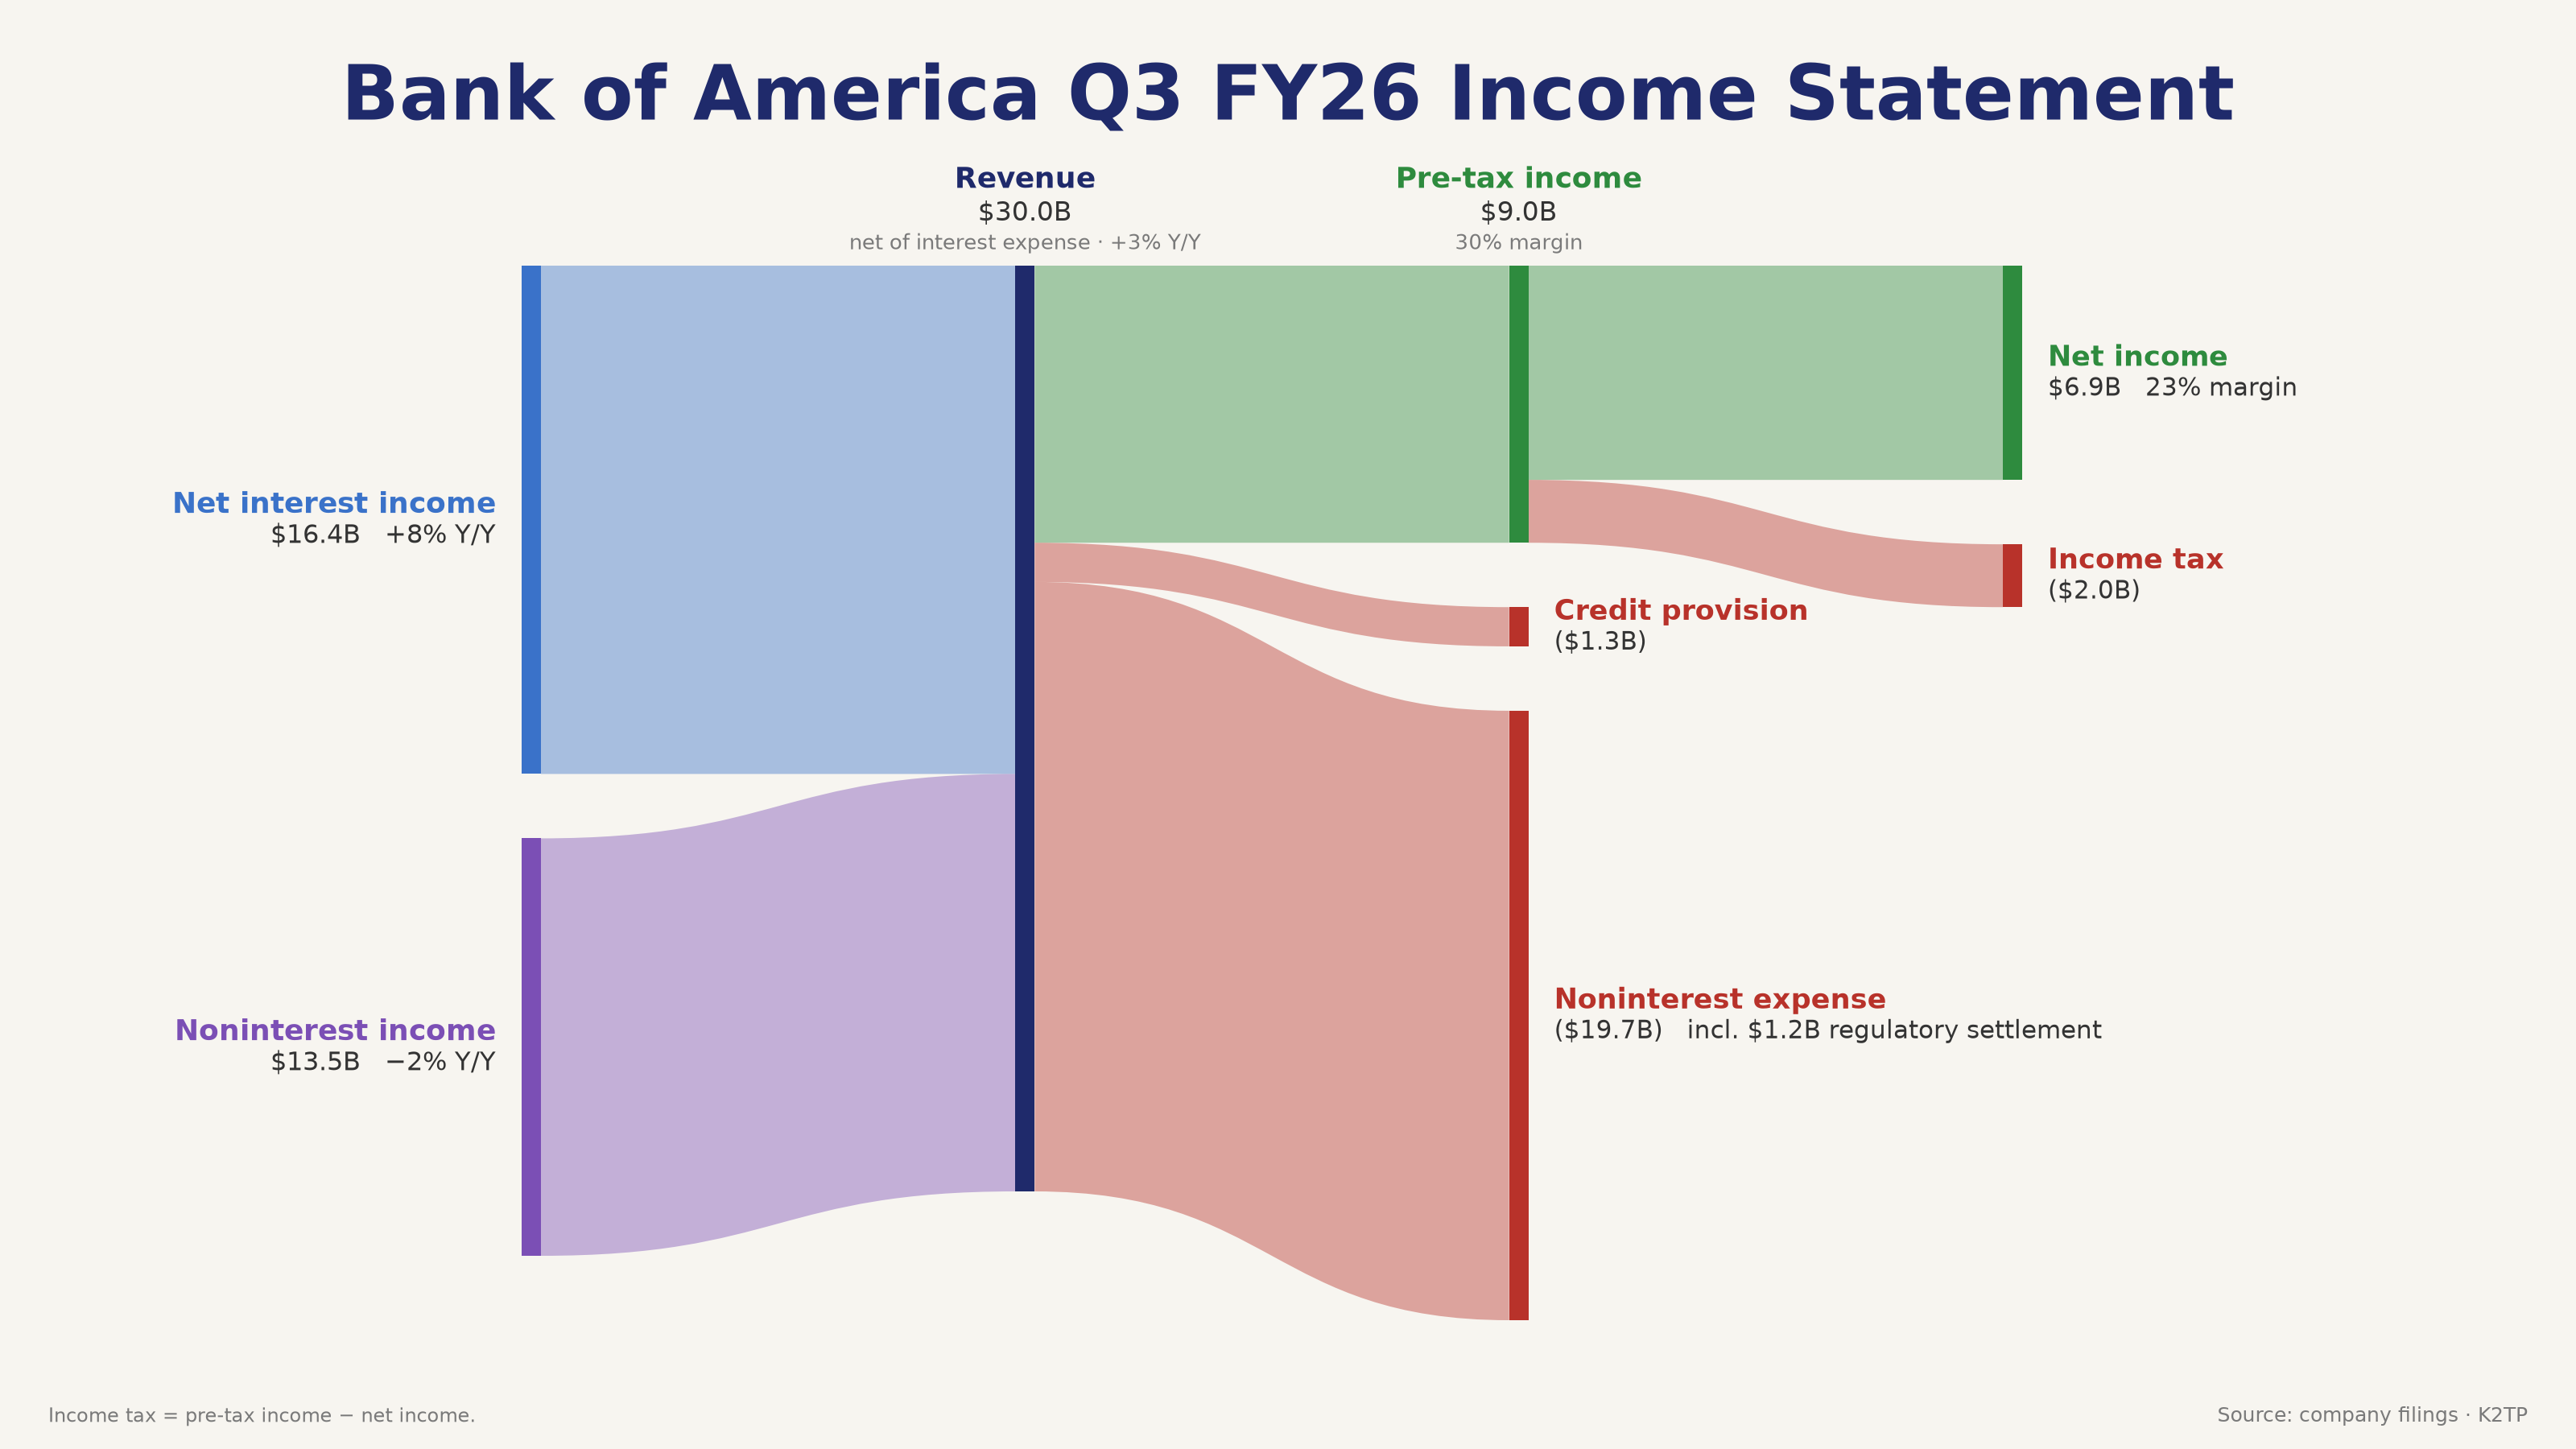
- BAC (Wed): EPS $1.08 vs $1.11 🔴, hit by a $1.2B AML settlement (about −$0.17/share); NII +8%. Stock −5.69% on the week
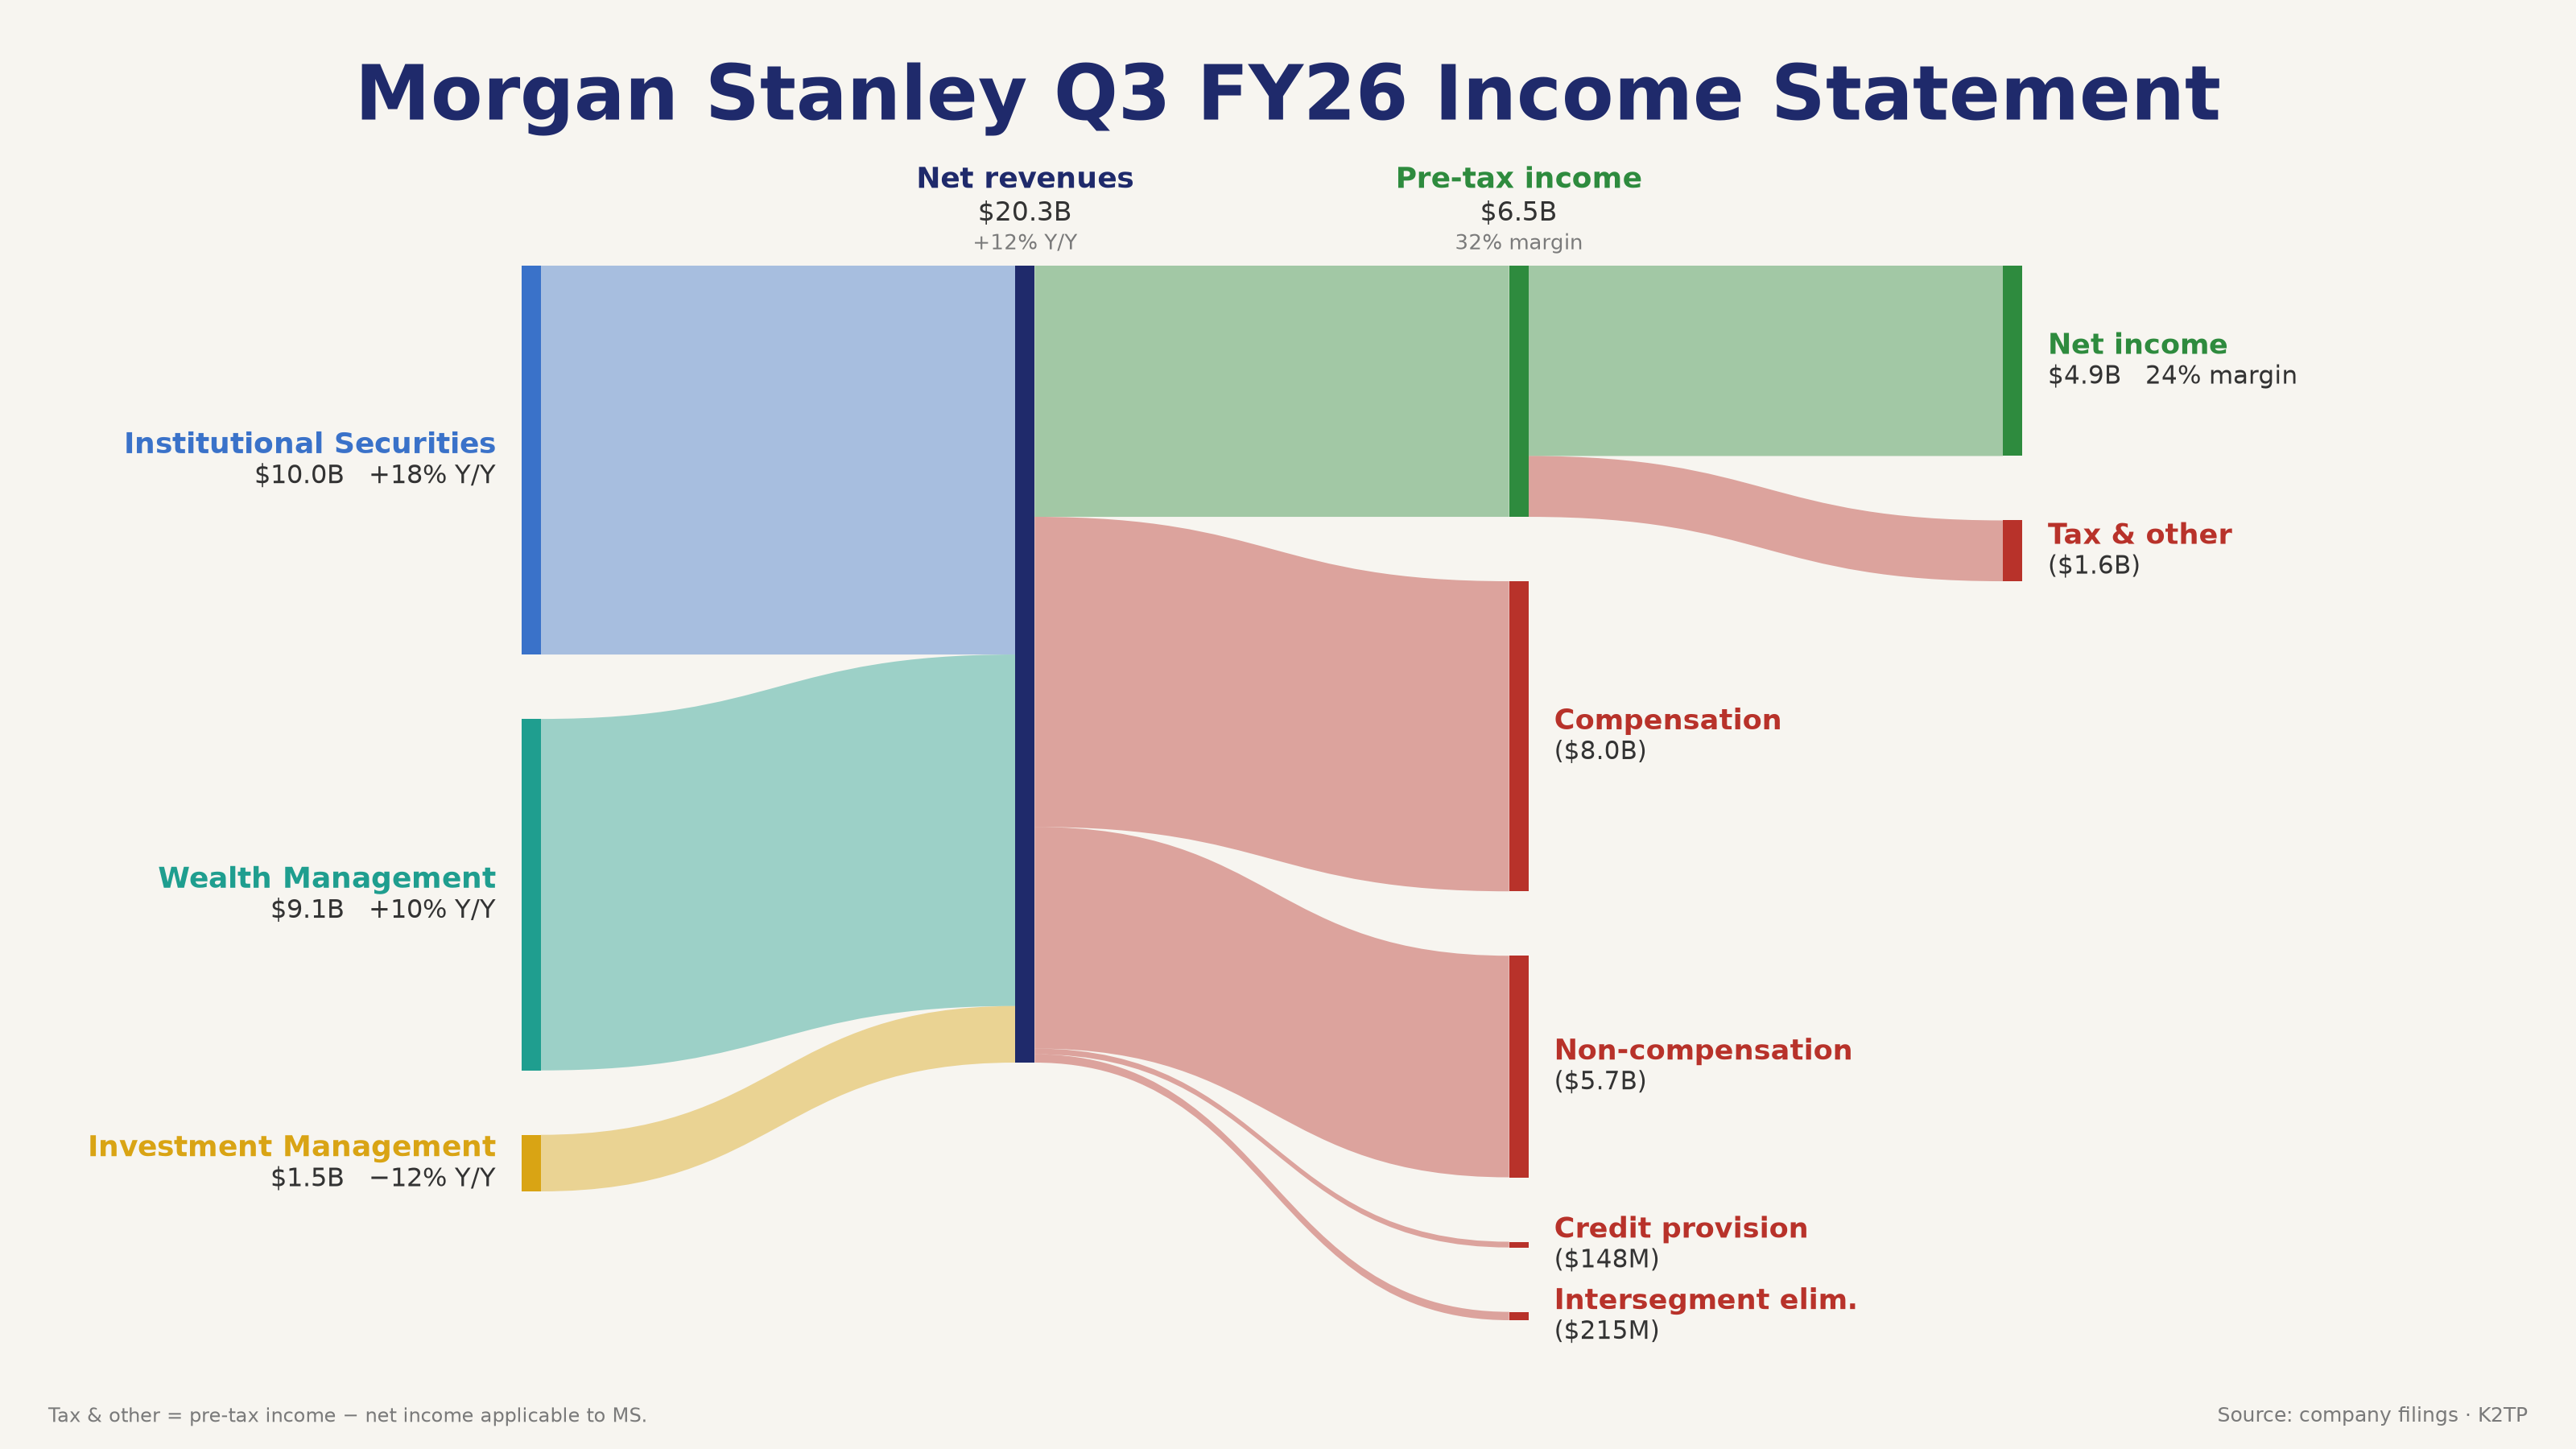
- MS (Wed): EPS $3.03 vs ~$2.93 🟢; revenue $20.3B (+12% y/y); equities trading $5.80B (+41%). Stock −4.97% on the week
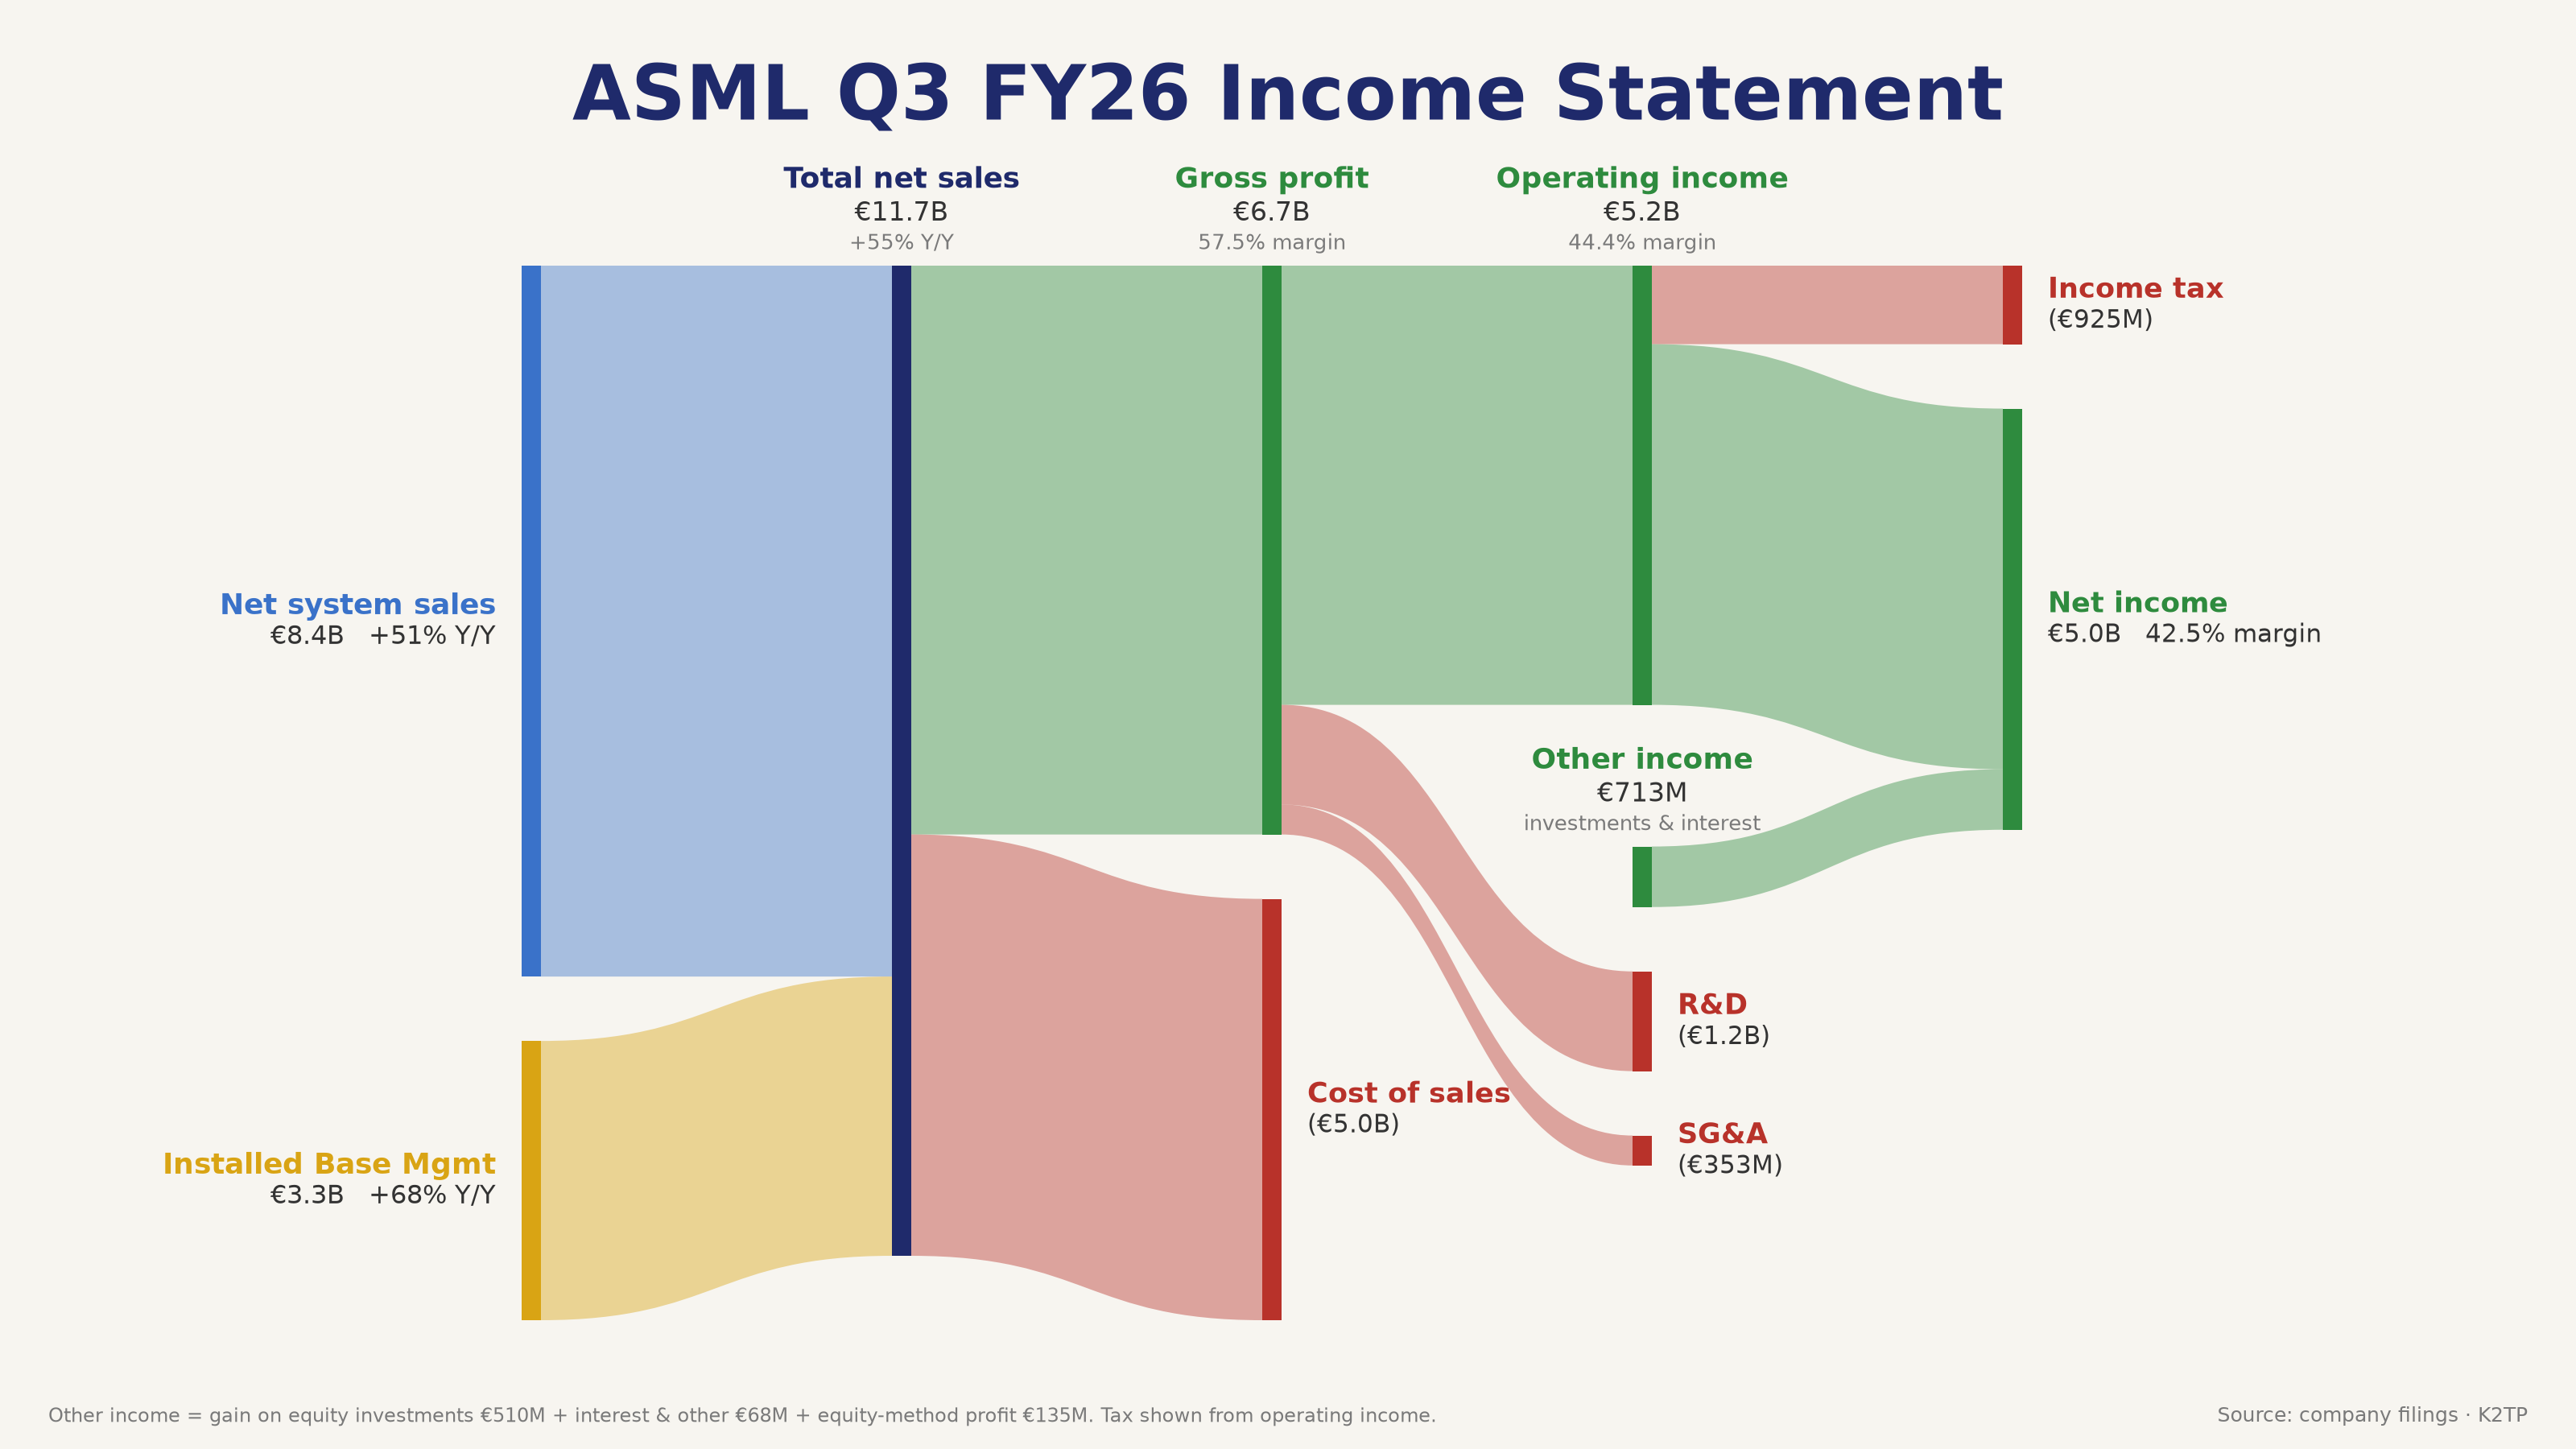
- ASML (Wed): Q3 sales €11.7B, gross margin 57.5%; Q4 guide €14.2–15.2B 🟢. The ADR still fell with semis
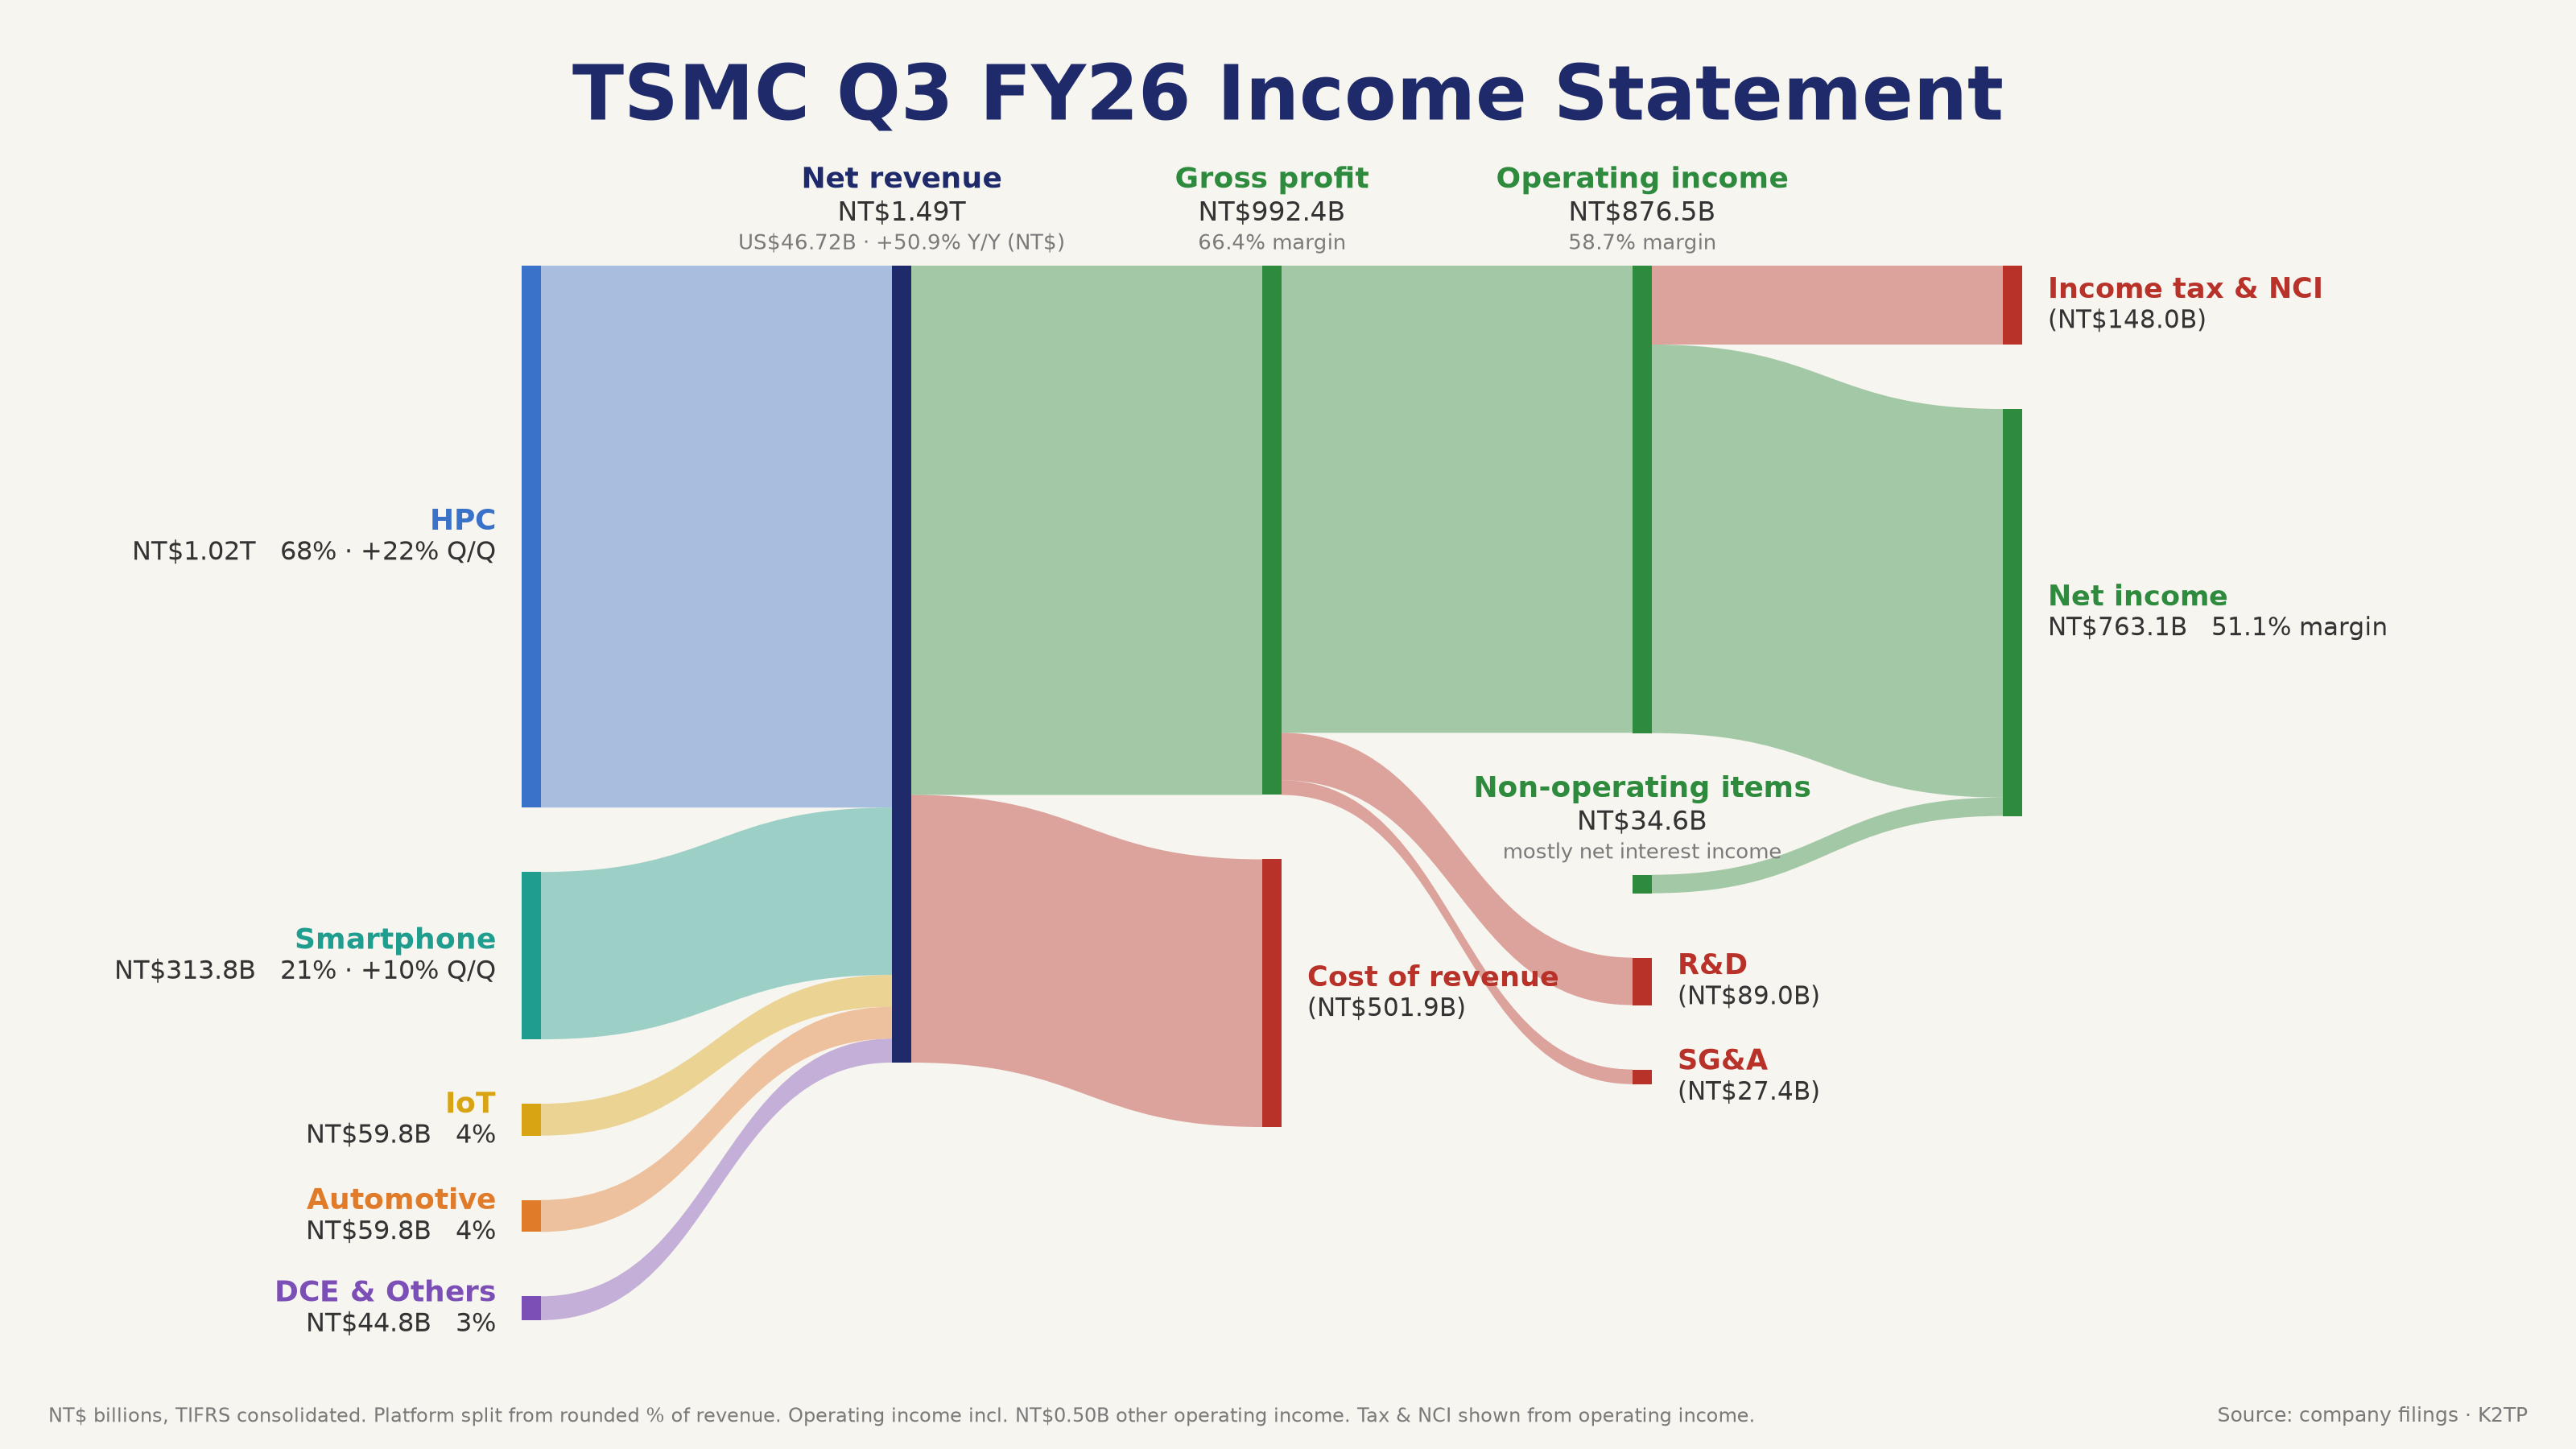
- TSMC (Thu): revenue US$46.72B vs a $44.6–45.8B guide, net profit +68.7% y/y 🟢; Q4 guide $52.3–54.3B. CFO flagged ~2% gross-margin dilution; TSM −8.98% on the week 🔴
- Thu after hours: Alcoa beat on EPS; IBKR and J.B. Hunt slightly missed on EPS
- Fri: TRV core EPS $9.18 (vs $8.14 a year ago), TFC adjusted EPS $1.16, MTB EPS $5.04, CFG EPS $1.41 (+34% y/y)
- Season so far: of about 45 S&P 500 companies reported, 85% beat earnings estimates (FactSet via CNBC)
→ Good numbers were not enough. Beats were sold (GS, MS, ASML, TSMC) and misses were punished (BAC). The market's problem this week was valuation and AI financing, not earnings.
AI AND SEMIS: THE FINANCING STORY TAKES OVER
- SOX 12,572.42 → 11,137.29 (−11.41%), down every day of the week
- Mon: memory sold off on China's CXMT progress (MU −3.88%); Tue: Kospi fell more than 7%, AMAT −6.69%
- Wed: AI infrastructure unwind after CPI: ORCL −8.83%, DELL −11.27%, CoreWeave about −15%; Barclays cut DELL and HPE
- Thu: Jensen Huang lifted CRWV +5.94%, but SOX still fell a seventh day despite TSMC's beat
- Fri: CoreWeave −11.91%; Reuters reported its bonds yielding above 15%. Chips and platforms broke together
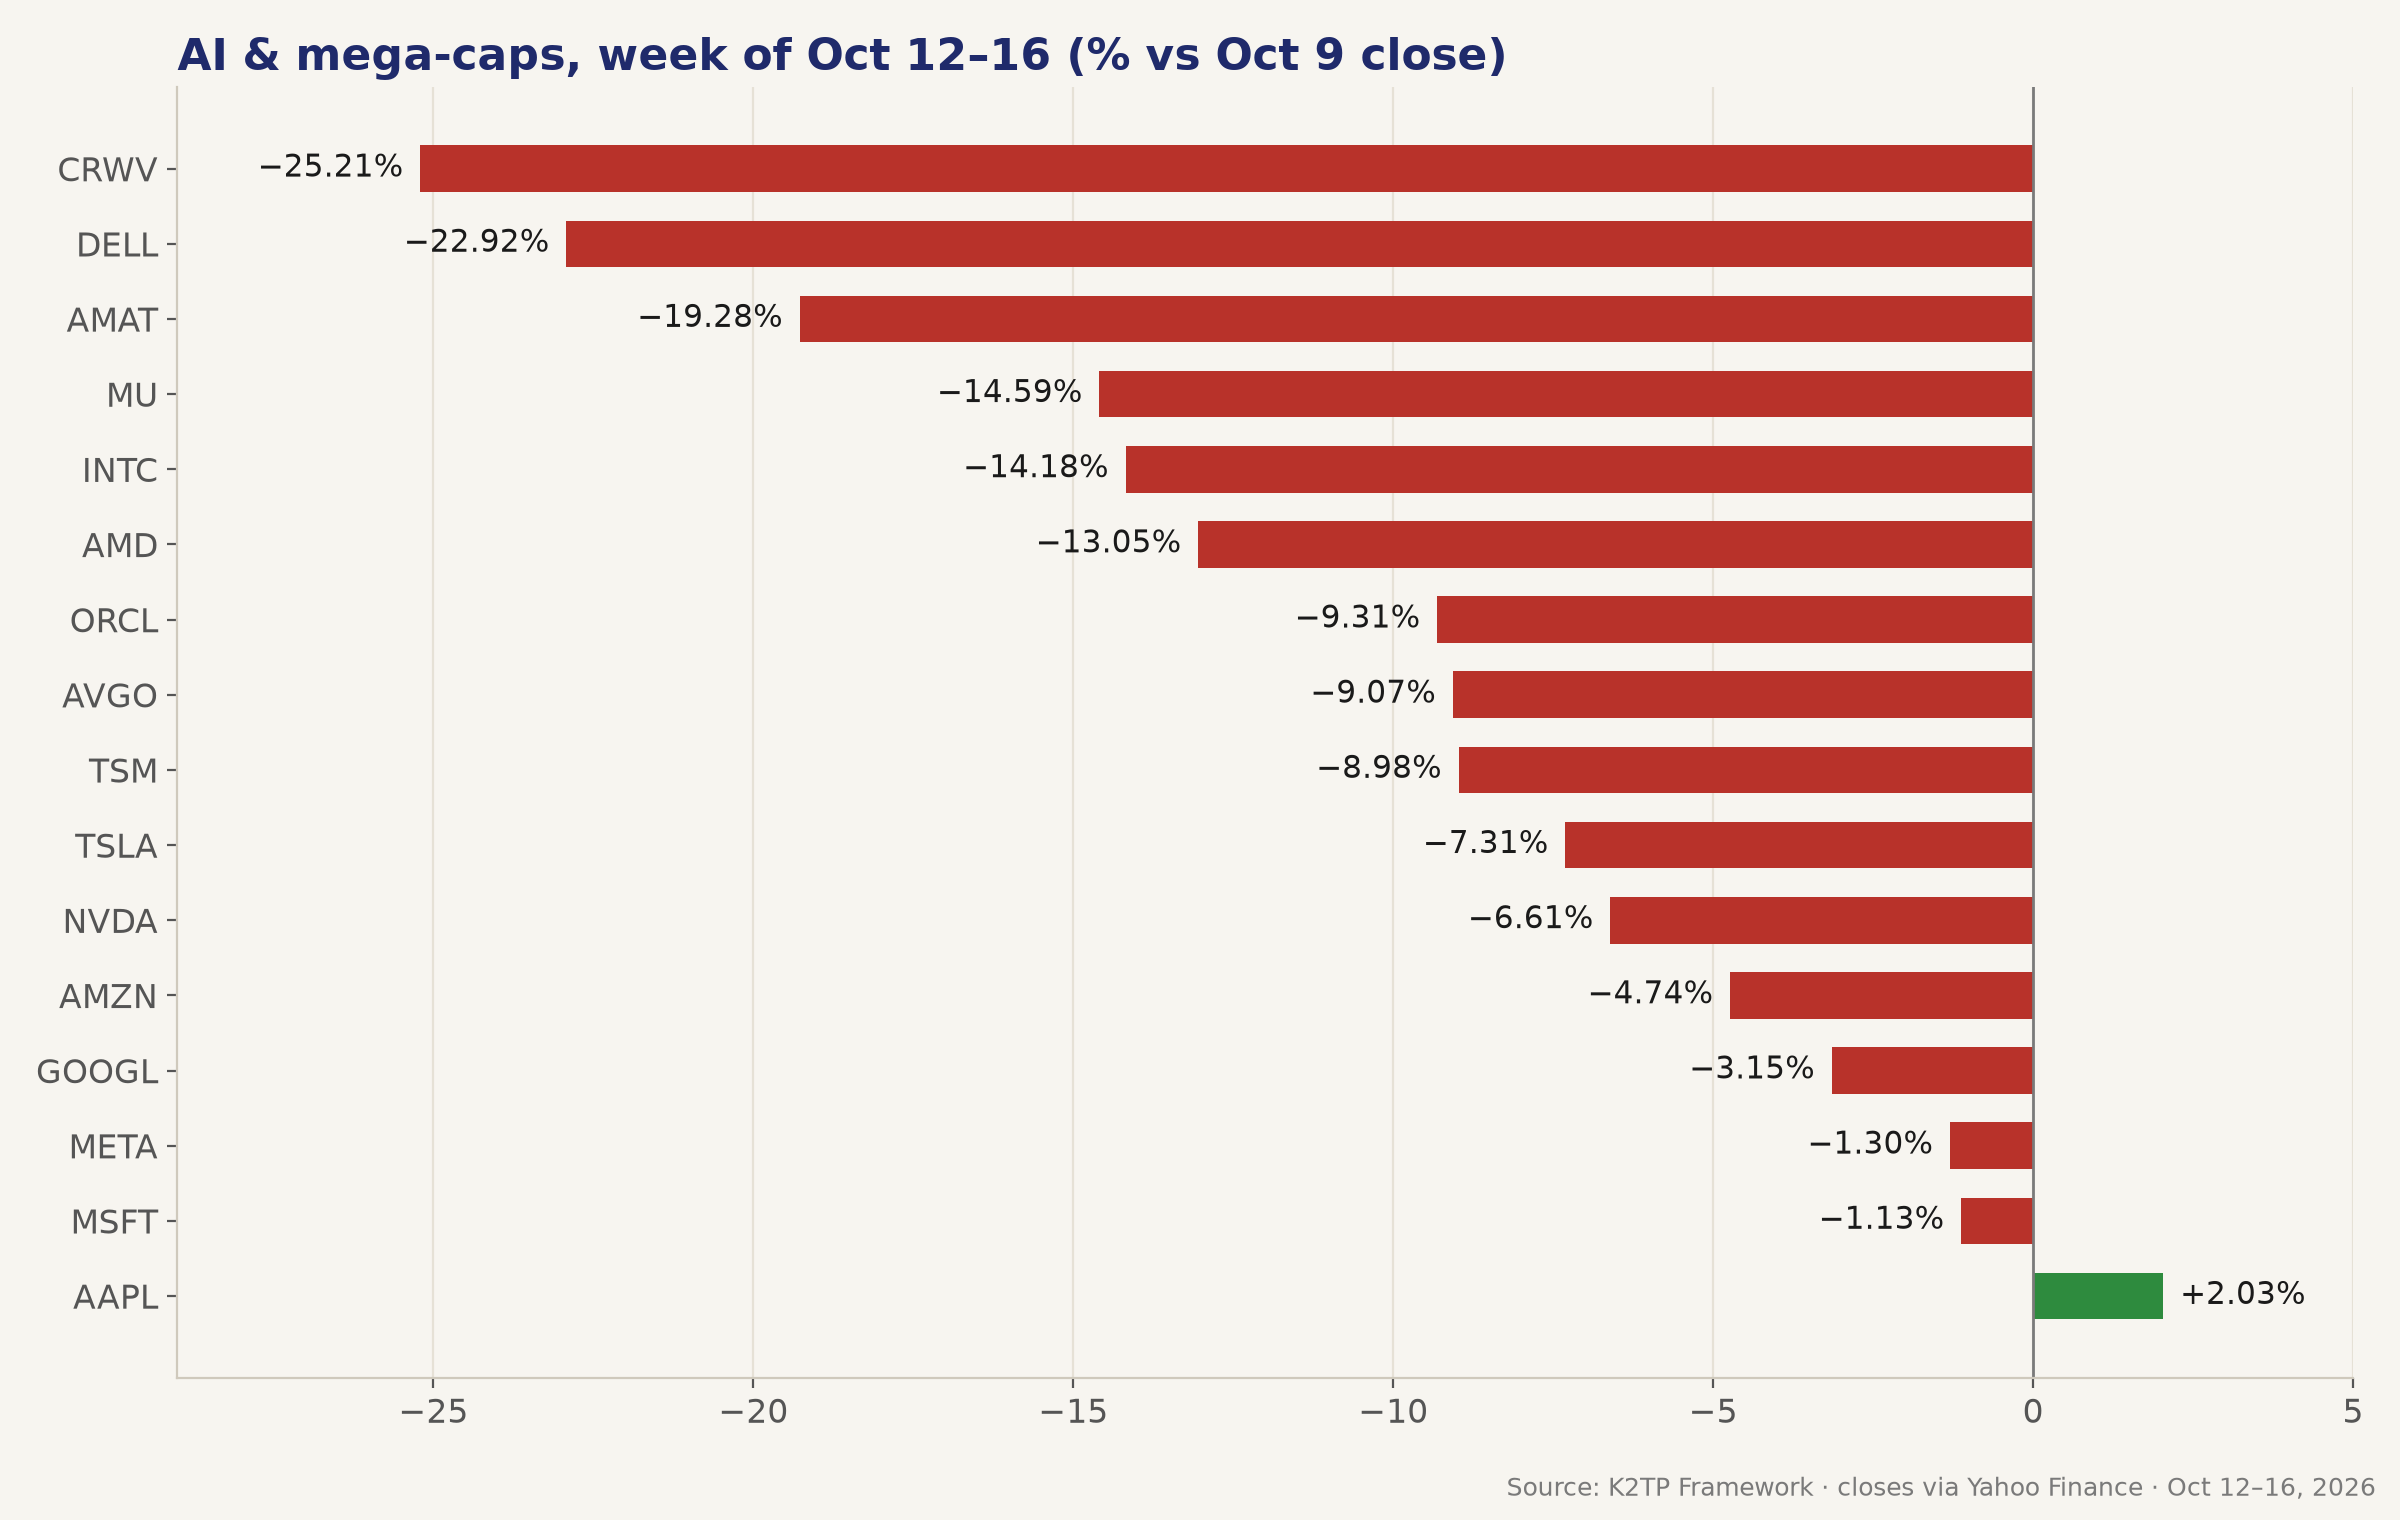
- Week: CRWV −25.21%, DELL −22.92%, AMAT −19.28%, MU −14.59%, INTC −14.18%, AMD −13.05%, ORCL −9.31%, AVGO −9.07%, TSM −8.98%, NVDA −6.61%
- Mega-caps: TSLA −7.31%, AMZN −4.74%, GOOGL −3.15%, META −1.30%, MSFT −1.13%; AAPL +2.03% was the only gainer
→ AI demand news was good (TSMC raised again). The selling was about who pays for the build-out: levered neoclouds, servers and memory took the heaviest losses.
SECTORS AND ROTATION: DEFENSIVES WIN THE WEEK
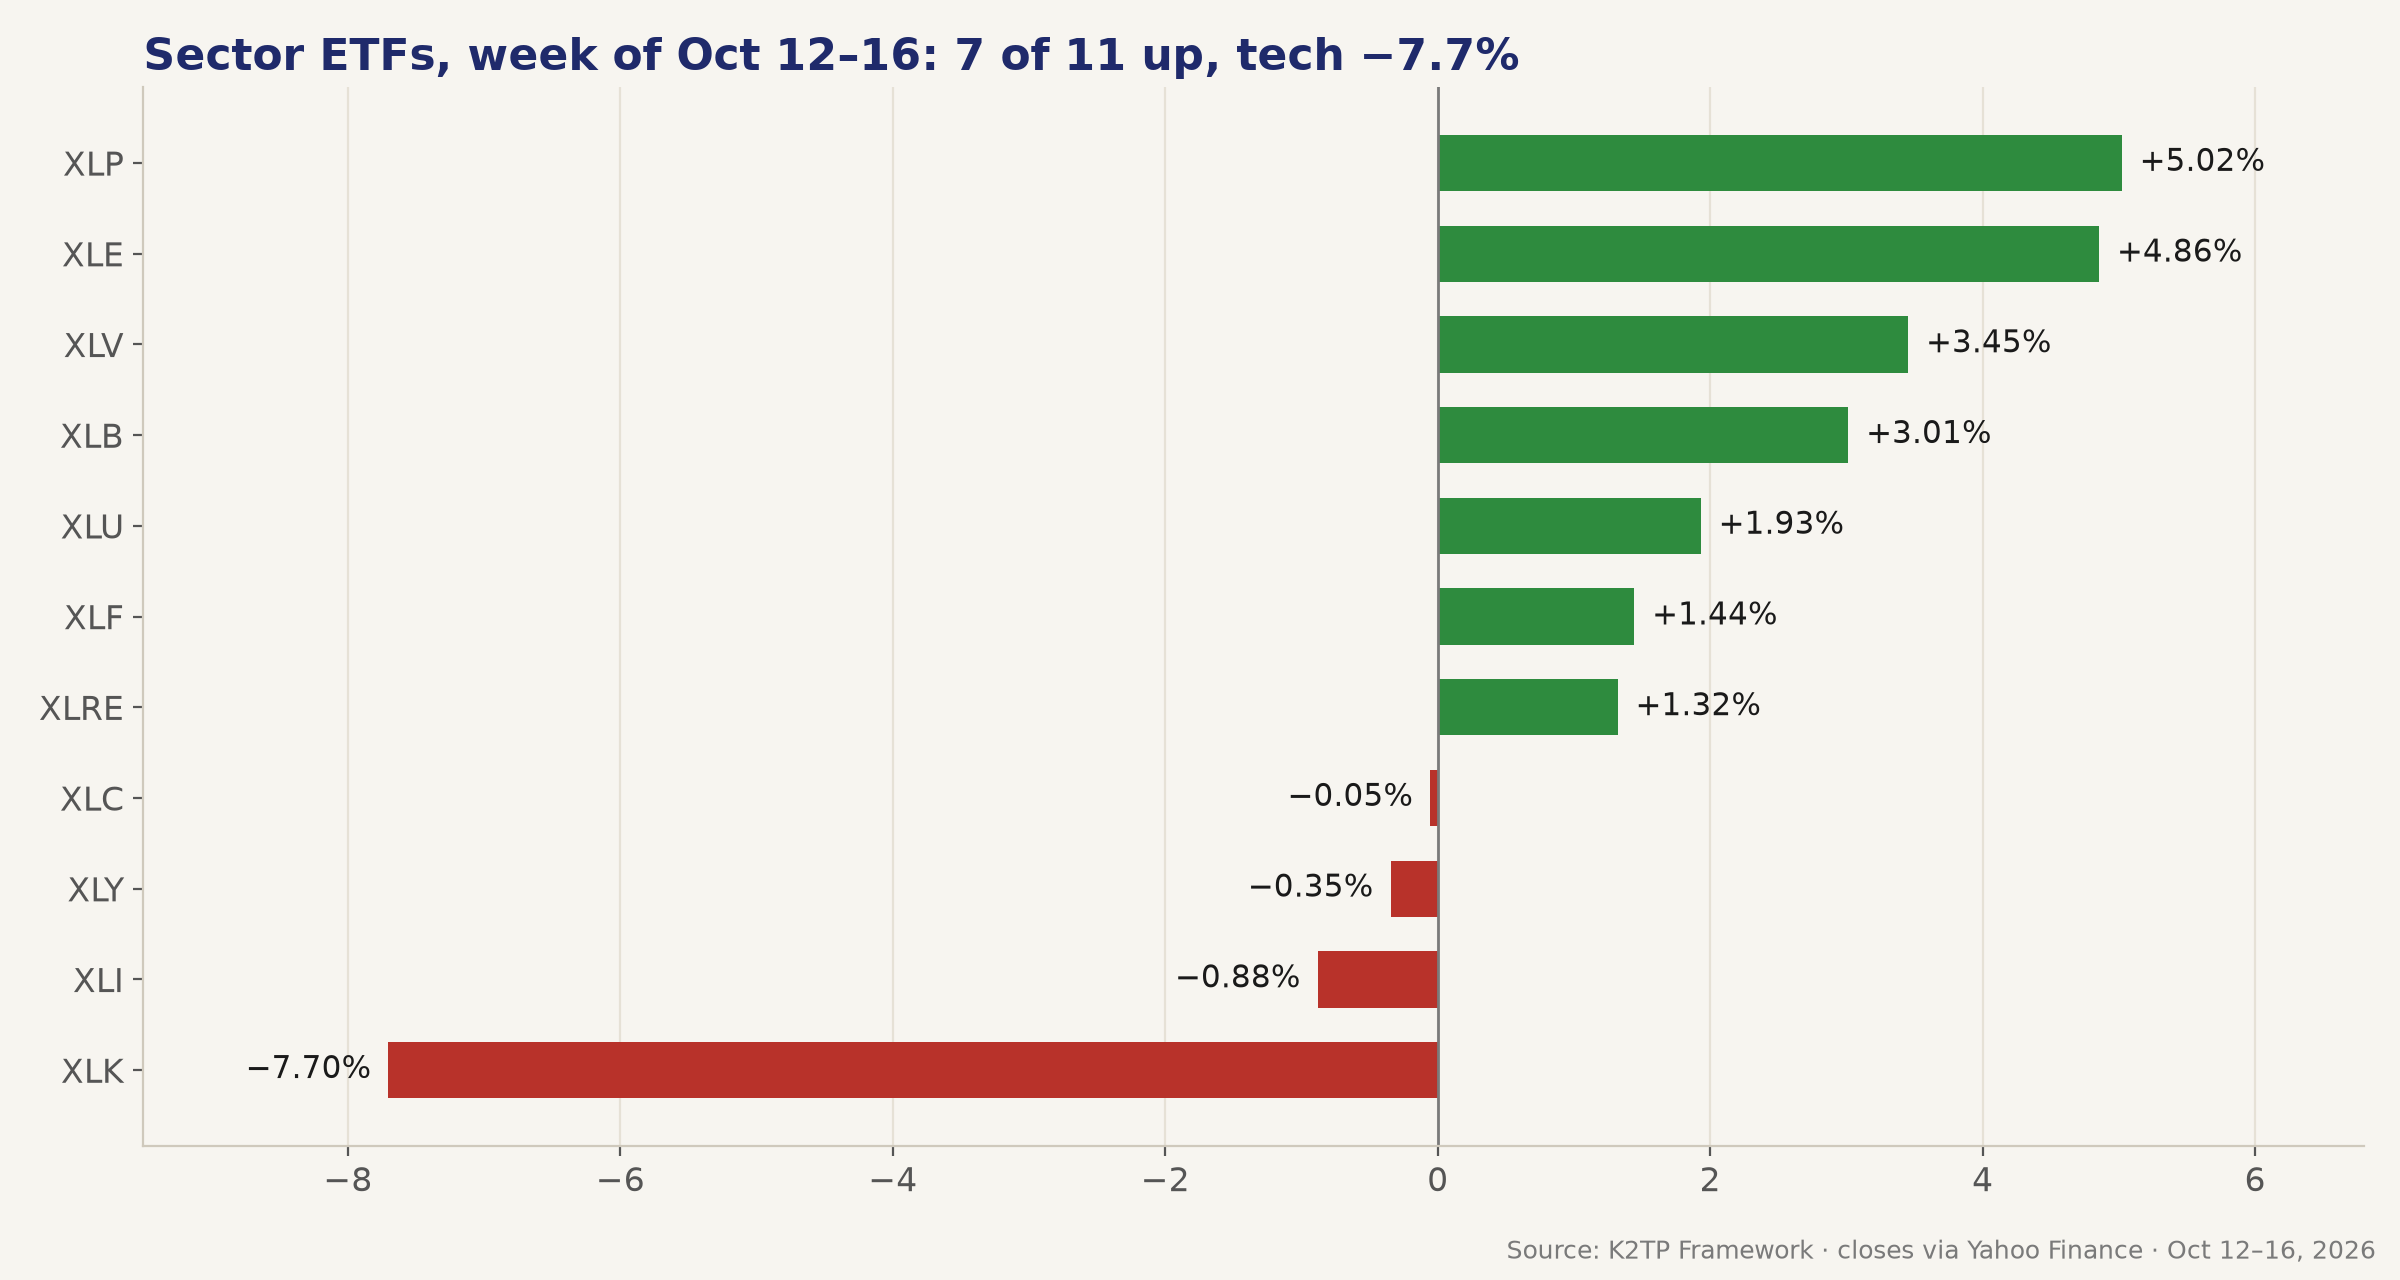
- Week: XLP +5.02%, XLE +4.86%, XLV +3.45%, XLB +3.01%, XLU +1.93%, XLF +1.44%, XLRE +1.32%
- Losers: XLK −7.70%, XLI −0.88%, XLY −0.35%, XLC −0.05%
- RSP +0.49% vs SPX −1.95%: equal-weight beat cap-weight by about 2.4 points
- Small caps did not hold: RUT −3.05% despite Thursday's +1.38%
→ Money stayed in equities but moved to staples, energy and health care. By Friday even small caps and cyclicals were sold, which is why the regime closed RISK-OFF.
OIL AND GEOPOLITICS: BRENT TESTS $110
- Brent: $104.72 (Oct 9 settle) → $109.86 (Oct 16 settle), +4.9%; it touched $110 Friday, the highest since May 🔴
- WTI: $91.85 (Oct 9 settle) → $99.04 on Friday (Yahoo CL=F)
- Drivers: weekend tanker attacks around the Strait of Hormuz, a US blockade of Iranian ports, and doubts over Russian diesel supply
- Offsets: the IEA agreed to release more than 20M barrels of fuel; the DOE requested proposals for an SPR exchange of up to 17M barrels
- EIA crude (Thu): −8.557M barrels vs +0.2M expected
→ Oil is the link between geopolitics and the inflation prints. Above $105, it keeps both CPI risk and P/E pressure alive.
THE WEEK'S MARKET
Indices (Oct 16 close, change vs Oct 9 close):
| Index | Oct 9 | Oct 16 | Week |
|---|---|---|---|
| SPX | 7,811.54 | 7,659.44 | −1.95% |
| NDX | 30,883.15 | 29,187.55 | −5.49% |
| Nasdaq Composite | 27,366.17 | 26,140.03 | −4.48% |
| RUT | 2,806.98 | 2,721.37 | −3.05% |
| DJIA | 51,654.95 | 52,002.41 | +0.67% |
| SOX | 12,572.42 | 11,137.29 | −11.41% |
| VIX | 14.84 | 19.99 | +34.70% |
| 10Y | 5.244% | 5.098% | −14.6 bp |
- SPX week range: 7,631.77 (Fri low) to 7,821.67 (Mon high); the record close is still 7,818.93
- NDX week range: 29,073.29 to 30,813.96
- The Nasdaq snapped a four-week winning streak; SPX fell for the fourth time in six weeks (Investopedia)
Volatility:
- VIX 14.84 → 19.99; Friday intraday high 22.31
- VIX9D 11.26 → 20.12 and VIX3M 17.77 → 20.50: the curve went from steep Contango to nearly flat, with VIX9D above VIX
- Short-dated hedging demand jumped into the weekend; this is not yet panic (VIX under 22.31 at the close)
Breadth:
- Official closing A/D totals for the week: unavailable
- Nasdaq new lows outnumbered new highs every day the briefs measured it (e.g., 22 vs 466 on Wed, 49 vs 263 on Fri)
Cross-asset:
- Brent $109.86 (+4.9%), gold $4,186.70 (−0.7%), DXY 101.78 (−0.4%), BTC ~$81,300
SPX key levels into next week:
- 7,818.93: record close
- 7,756.84: Friday's high
- 7,744.06: Thursday's close
- 7,691.56: Friday's midday low, the first line to reclaim
- 7,659.44: close
- 7,631.77: week low
- VIX: 20.00 and 22.31
Option-seller angle:
- Bull case: SPX back above 7,691.56 with VIX under 20 and SOX breaking its losing streak. Even then, sell put premium only far out of the money and in small size.
- Bear case: SPX under 7,631.77 with VIX above 22.31 opens a deeper de-risking leg. Cut short-put size or use defined-risk spreads.
- Avoid tight Iron Condors on NDX and semis: SOX has fallen eight straight days and the VIX curve is flat.
- Earnings risk is concentrated: NFLX (Tue), TSLA and META (Wed) report after the close. Avoid short premium through those prints on single names.
BOTTOM LINE
- Inflation ran hot all week (CPI, PPI, import prices), but bonds still rallied. Rates were not what broke equities.
- The break came from AI financing: CoreWeave's debt stress spread to servers, memory, equipment and then the platforms. SOX fell 11.4% and NDX 5.5%.
- Money hid in staples, energy and health care. The Dow and equal-weight finished green, but by Friday the defensive bid could no longer offset tech.
- The regime ends the week RISK-OFF. It returns to TRANSITION only once CRWV/SOX stabilize and SPX reclaims 7,691.56.
WHAT TO WATCH NEXT WEEK (PT)
| Day | Data (PT) | Earnings |
|---|---|---|
| Sun 10/18 | 7:00 PM: China Q3 GDP, industrial production, retail sales | — |
| Mon 10/19 | 7:00 AM: NAHB housing market index | Before: FITB, CLF · After: ZION, STLD |
| Tue 10/20 | 5:30 AM: housing starts & permits; 7:00 AM: pending home sales | Before: GE, GM, RTX, MMM, NOC, HAL · After: NFLX, COF, ISRG, UAL |
| Wed 10/21 | 4:00 AM: MBA mortgage applications | Before: ABT, TMO, PM, CME · After: TSLA, META, IBM, TXN, LRCX, CSX |
| Thu 10/22 | 5:30 AM: jobless claims; 7:00 AM: leading indicators | Before: PG, BX, HON, LMT, UNP, CMCSA, SPOT, VLO · After: WDC, NEM |
| Fri 10/23 | 6:45 AM: S&P Global flash PMIs; 7:00 AM: UMich sentiment (final) | Before: AXP, SLB |
- Weekend: Strait of Hormuz headlines and the Brent $110 line
- CoreWeave stock and bonds as the AI-credit gauge; META and TSLA on Wednesday are the AI-capex test
- About 70 S&P 500 companies report next week (CNBC)
- Oct 27–28: FOMC; Nov 3: US midterms
Expected (Bull): SPX above 7,691.56 with VIX under 20 and SOX snapping its losing streak. Expected (Bear): SPX under 7,631.77 with VIX above 22.31 and Brent above $110.
Sources: K2TP daily syntheses for Oct 14, 15 and 16, 2026, and the K2TP briefs for Oct 12–16 (Pre-Market, Midday, Pre-Close, Evening Recap; Friday has no Evening Recap, so Friday uses official closes). Weekly closes from Yahoo Finance; oil settlements, news and breadth from Reuters, AP, MarketWatch, CNBC and Investopedia; next-week calendar from Schwab Network, CNBC and Liquid, converted to PT; earnings Sankeys from official Q3 2026 company releases. Analysis: K2TP Framework.