Market 11/3: Democrats win the House and the Senate in the midterms; futures drop on the results, then pare most of the loss, while AMD and Arista beat after a narrow, chip-led session
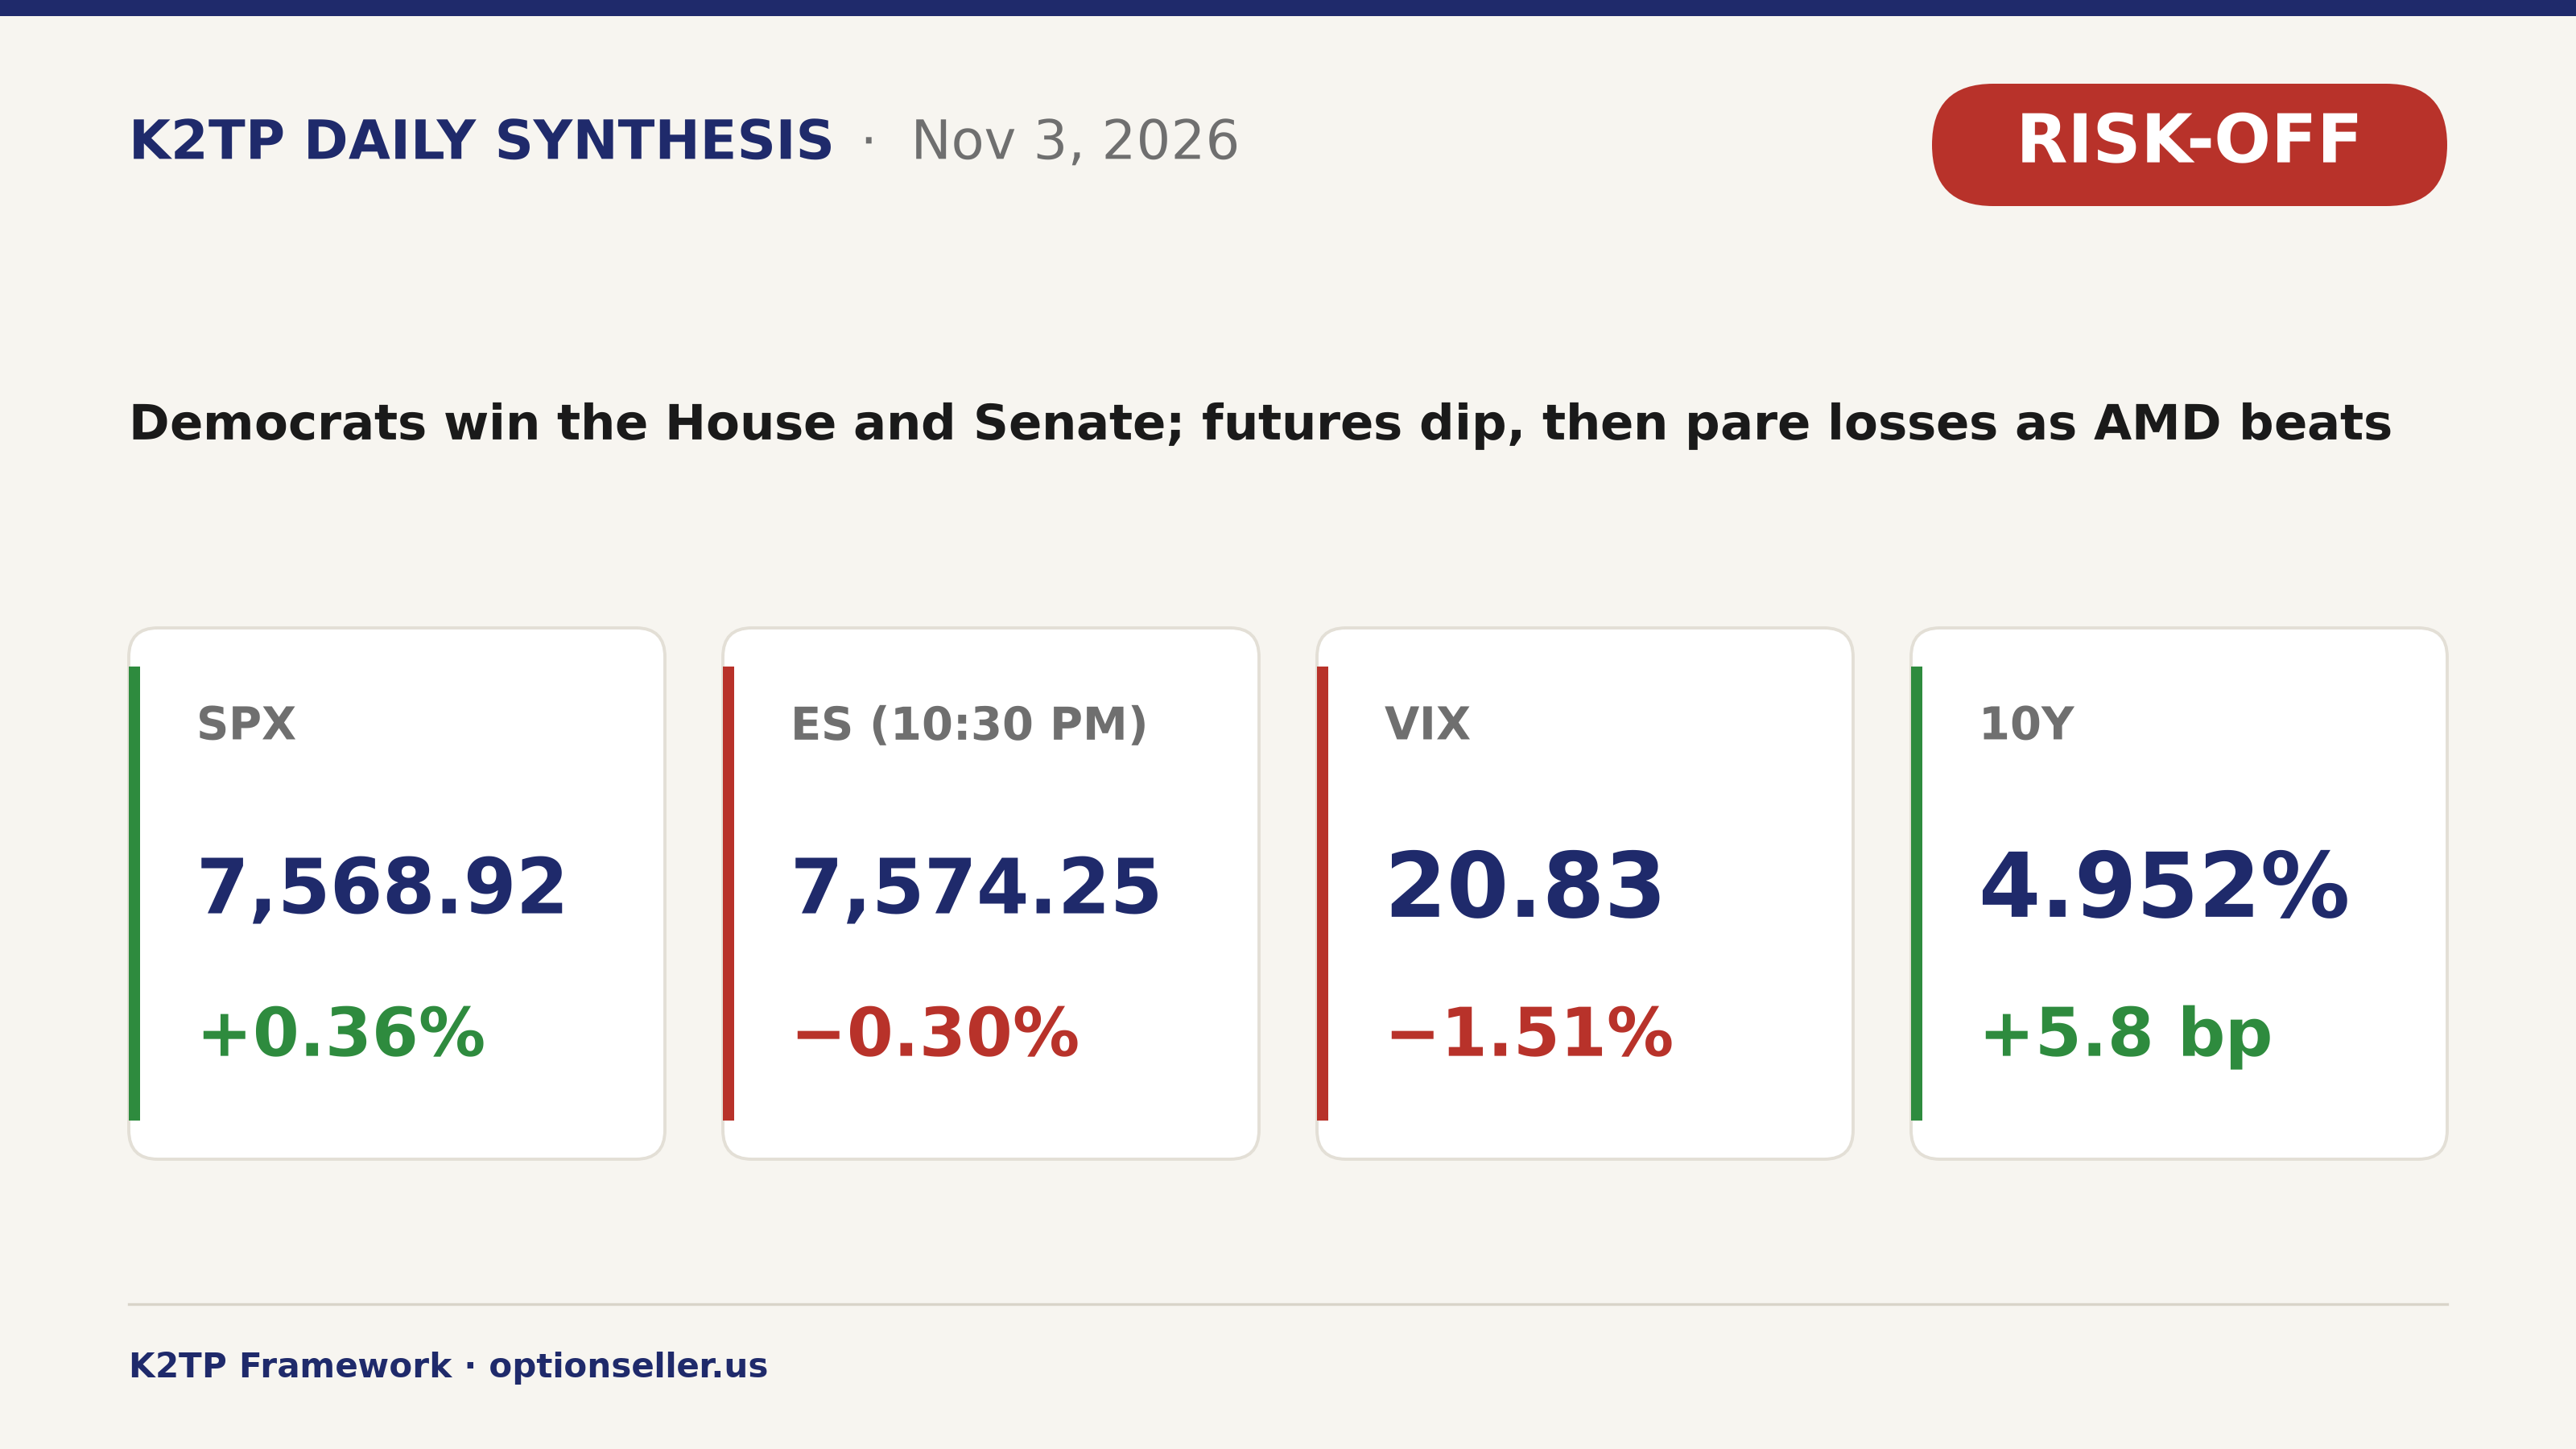
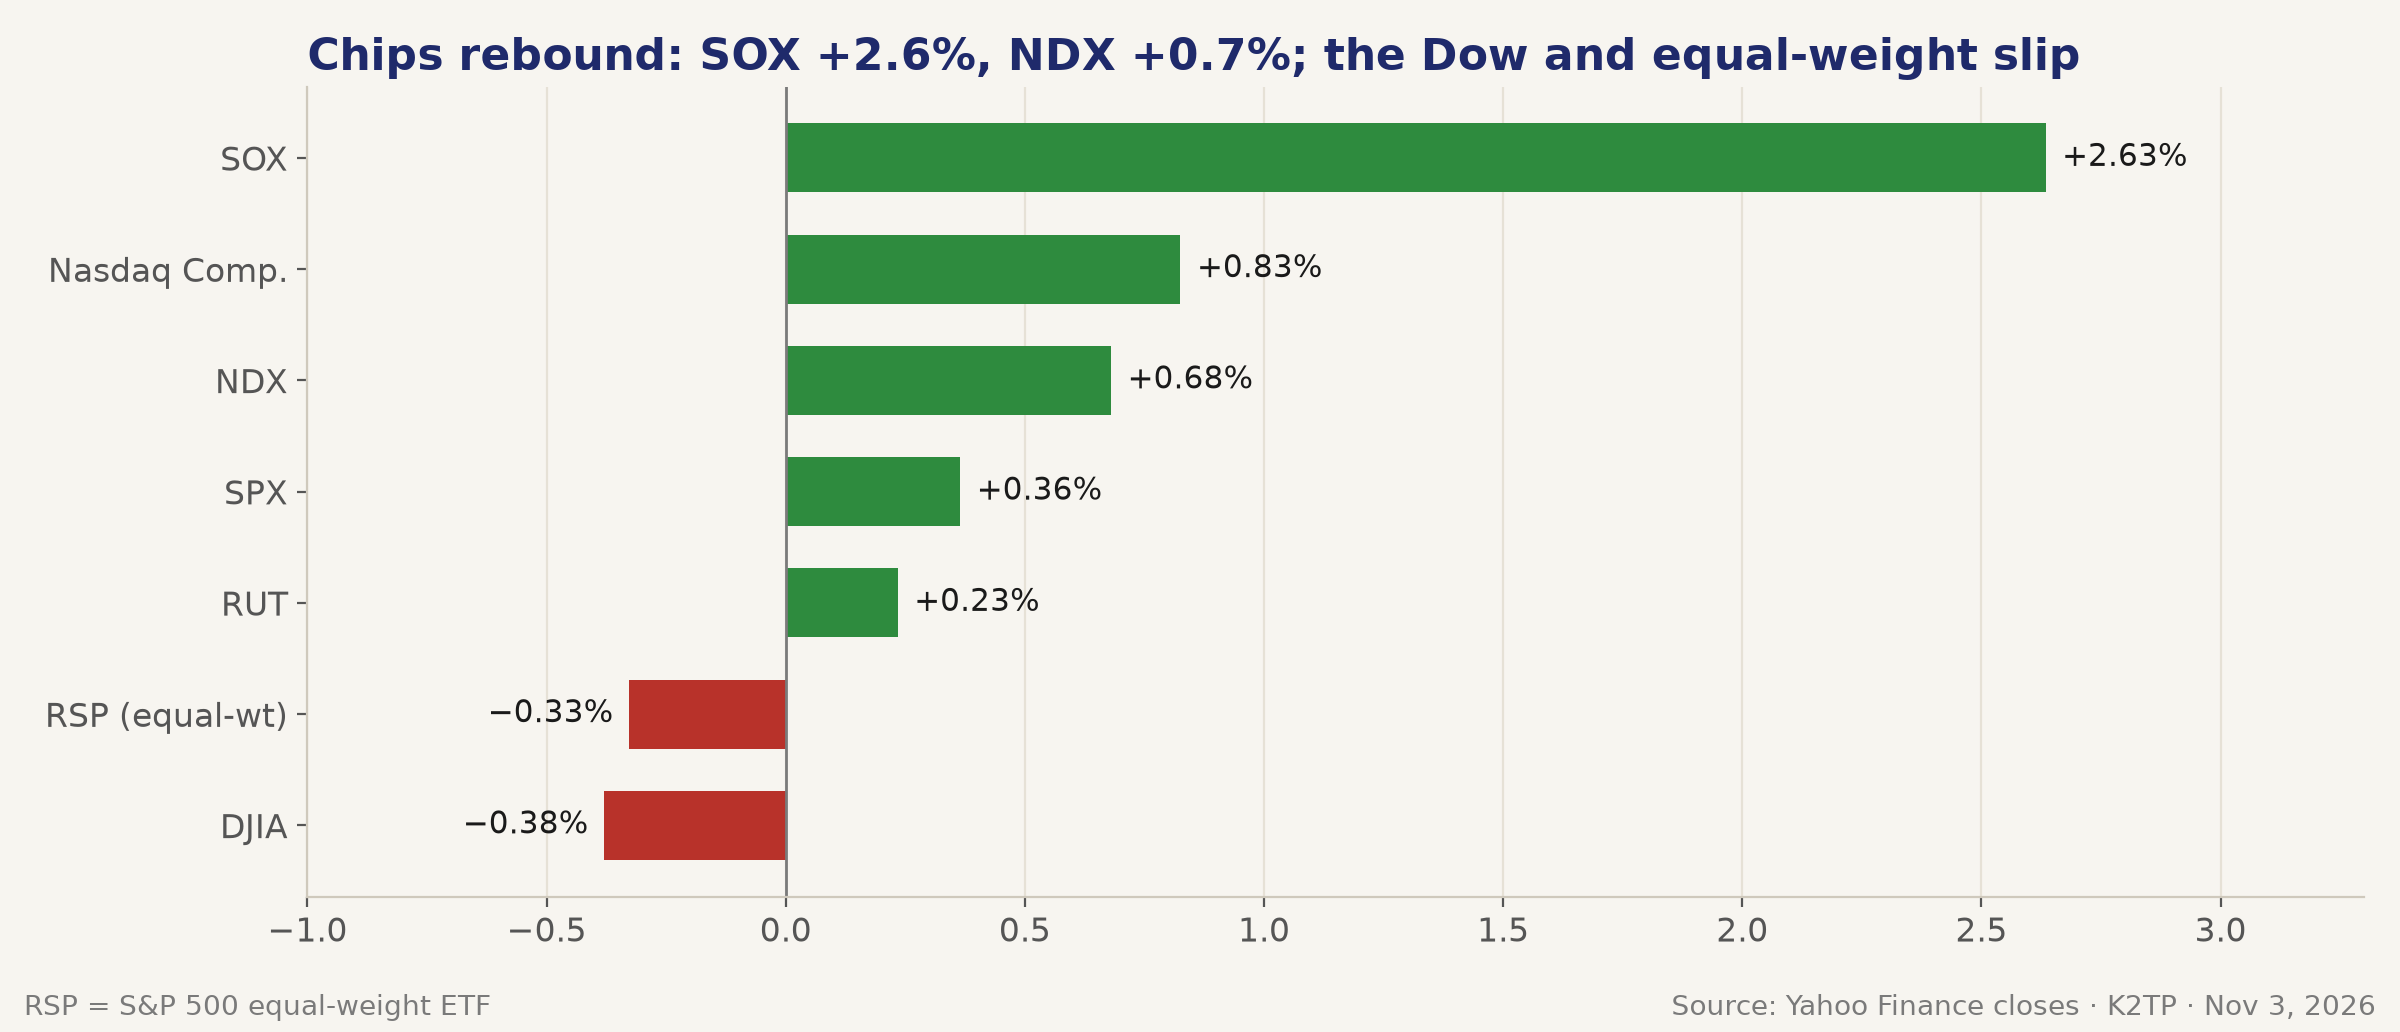
SPX +0.36%, NDX +0.68%, SOX +2.63%, Nasdaq Composite +0.83%, DJIA −0.38%, RUT +0.23%, RSP −0.33%, VIX −1.51% to 20.83. ORCL +5.85%, AMD +3.65%, AVGO +3.07% and MSFT +2.74% while WMT −2.22% and AAPL −1.90%; only 4 of 11 sector ETFs rise. JOLTS beat lifts the 10Y to 4.952% (+5.8 bp). After hours AMD +5.02% and ANET +9.47%. At 10:30 PM PT ES is −0.30% after a 7,490.00 low, gold +2.2%, DXY −0.3%.
KEY HEADLINES
- MIDTERMS: the AP projects that Democrats win the House and take control of the Senate, giving them full control of Congress; NBC, CBS and Fox News also project a Democratic House (Decision Desk HQ called it at 6:11 PM PT), and CBS projects the Senate flip. Many House races and the Maine Senate race are still uncalled by the AP, so the final margins are not known 🔴
- Futures reaction: ES rose to about 7,622 after AMD's report, then slid as results came in; Yahoo shows an overnight low of 7,490.00, and at 10:30 PM PT ES is 7,574.25 (−0.30%), NQ 28,204.00 (−0.36%), YM −0.10%, RTY +0.09%
- Havens and the dollar: gold about $4,028 (+2.2%), 10Y 4.931% tonight (−1.9 bp from the close), DXY 101.51 (−0.35%); Nikkei −1.7% after being down as much as about 4.8%
- After-hours policy trade: FSLR +2.74%, TAN +3.25%; UNH −1.47%, DJT −5.88%, GEO −2.39%, LMT −0.47% (CNBC extended-hours quotes)
- SPX +0.36% to 7,568.92 (range 7,545.39–7,594.61); NDX +0.68% to 28,180.26; Nasdaq Composite +0.83% to 25,372.01; DJIA −0.38% to 51,786.72; RUT +0.23% to 2,812.45
- Chips bounce after two down days: SOX +2.63% to 10,600.40; ORCL +5.85%, AMD +3.65%, AVGO +3.07%, MSFT +2.74%, MU +2.58%, NVDA +2.29%
- A narrow tape: RSP −0.33% vs SPX +0.36%; only XLK, XLC, XLI and XLRE rise; XLP −2.07% and XLB −2.01% lead the losers
- JOLTS 7.523M vs 7.164M expected; a bear steepener takes the 10Y to 4.952% and the 2Y to 4.614%; 2s10s 31.1 → 33.6 bp
- AMD beats (8-K Ex. 99.1): revenue $13.38B (+45% Y/Y), non-GAAP EPS $2.09, Data Center $8.55B (+97%), Q4 revenue guide about $17B ±3% with a non-GAAP gross margin of about 55%; AMD 508.20 (+5.02%) after hours
- Regime: 🔴 RISK-OFF (Evening Recap, unchanged); the session ran 🔴 → 🟡 TRANSITION at midday and pre-close, then back to 🔴 as futures fell on the results
- Wednesday: ADP 5:15 AM PT, ISM Services 7:00 AM PT, EIA crude 7:30 AM PT; payrolls Friday 5:30 AM PT
MIDTERMS: DEMOCRATS TAKE THE HOUSE AND THE SENATE
House:
- Decision Desk HQ projected Democratic control at 6:11 PM PT (via FinancialJuice)
- NBC News projected Democratic control (article timestamped 7:08 PM PT); its tally at last check was 225 D, 134 R and 76 uncalled, a net Democratic gain of 28 so far, and NBC's estimate is about 255 Democratic seats
- Fox News projected Democratic control (published 8:38 PM PT); CBS News also projects it
- The AP: "Democrats win the US House, taking full control of Congress" (story updated 10:29 PM PT)
- Still open: dozens of individual House races are uncalled, so the final majority is not known. The 255-seat figure is NBC's estimate, not a result
Senate:
- The AP projects that Democrats win control of the Senate (on the AP live page by its 10:17 PM PT update; the exact call time is not shown); CBS News also projects the flip (article updated 8:46 PM PT)
- Democratic pickups called so far include Texas, North Carolina (Roy Cooper), South Carolina, Ohio, Kansas and Iowa; the AP counts 7 Senate seats flipped in total. Democrats held Georgia (Jon Ossoff) and New Hampshire (Chris Pappas); Republican Ashley Moody held Florida
- CBS's tally at last check: 53 D, 42 R, with the rest undecided, so the final size of the majority is not settled
- Maine: Susan Collins conceded to Democrat Troy Jackson, but the AP has not yet called the race
- Governors (AP): Democrats won Georgia (Keisha Lance Bottoms), Ohio (Amy Acton), Iowa (Rob Sand) and Texas (Gina Hinojosa)
- Trump says he will accept the results: "I don't view it as a hit on me"
→ The market's base case before the vote was a Democratic House; the Senate was the swing factor, and the Evening Recap flagged a Democratic Senate as the bear case. That has now happened, yet ES is only −0.30% at 10:30 PM PT and well off its 7,490.00 low. A divided government (Democratic Congress, Republican White House) usually means gridlock rather than new laws, which may be why the first drop is fading. Policy-exposed groups (managed care, defense, private prisons, solar) are where the repricing shows up.
MARKETS REACT: FUTURES, YIELDS, DOLLAR AND AFTER-HOURS SECTORS
- ES path: about 7,622 at 3:15 PM PT on AMD, down from about 4:00 PM PT as results came in, 7,537.50 (−0.78%) at the 6:25 PM PT Evening Recap, an overnight low of 7,490.00 on Yahoo, and 7,574.25 (−0.30%) at 10:30 PM PT 🟡
- NQ fell as much as 1.50% at the Recap and to a 27,621.25 low; it is 28,204.00 (−0.36%) now. The ES–SPX basis of about 27.8 points puts implied SPX near 7,546 now, and near 7,462 at the ES low
- 10Y: 4.952% at the session close, about 4.90% at 6:25 PM PT, 4.931% at 10:38 PM PT (CNBC); TLT +0.22% after hours
- DXY 101.51 (−0.35%, CNBC); at 6:25 PM PT EUR/USD was 1.1259 and USD/JPY 157.77 (FinancialJuice): the dollar weakens against the euro, yen, sterling and franc
- Gold about $4,028 (+2.2%), the largest cross-asset move tonight; WTI $96.48 (+0.4%); BTC about $77,860
- After hours (CNBC, extended session to 5:00 PM PT): SPY −0.29%, QQQ −0.53%, IWM −0.41%; XLY −0.64%, XLC −0.43%, XLI −0.38%; AAPL −0.63%, NVDA −0.26%
- Policy-sensitive names: FSLR +2.74%, TAN +3.25%; UNH −1.47%, DJT −5.88%, GEO −2.39%, LMT −0.47%
- Asia: Nikkei −1.66% at 62,036.88 after an intraday low of 60,030.10; Kospi +0.28% after a 5,421.72–5,828.13 range; Hang Seng +1.11%, Shanghai +1.89%
→ The first reaction was risk-off (stocks and the dollar down, gold up), but bonds rallied rather than sold off, and futures have recovered more than half of the drop. For Wednesday's open the question is whether the selling resumes in the cash session or the gap closes.
AMD AND ARISTA BEAT ON AI DEMAND
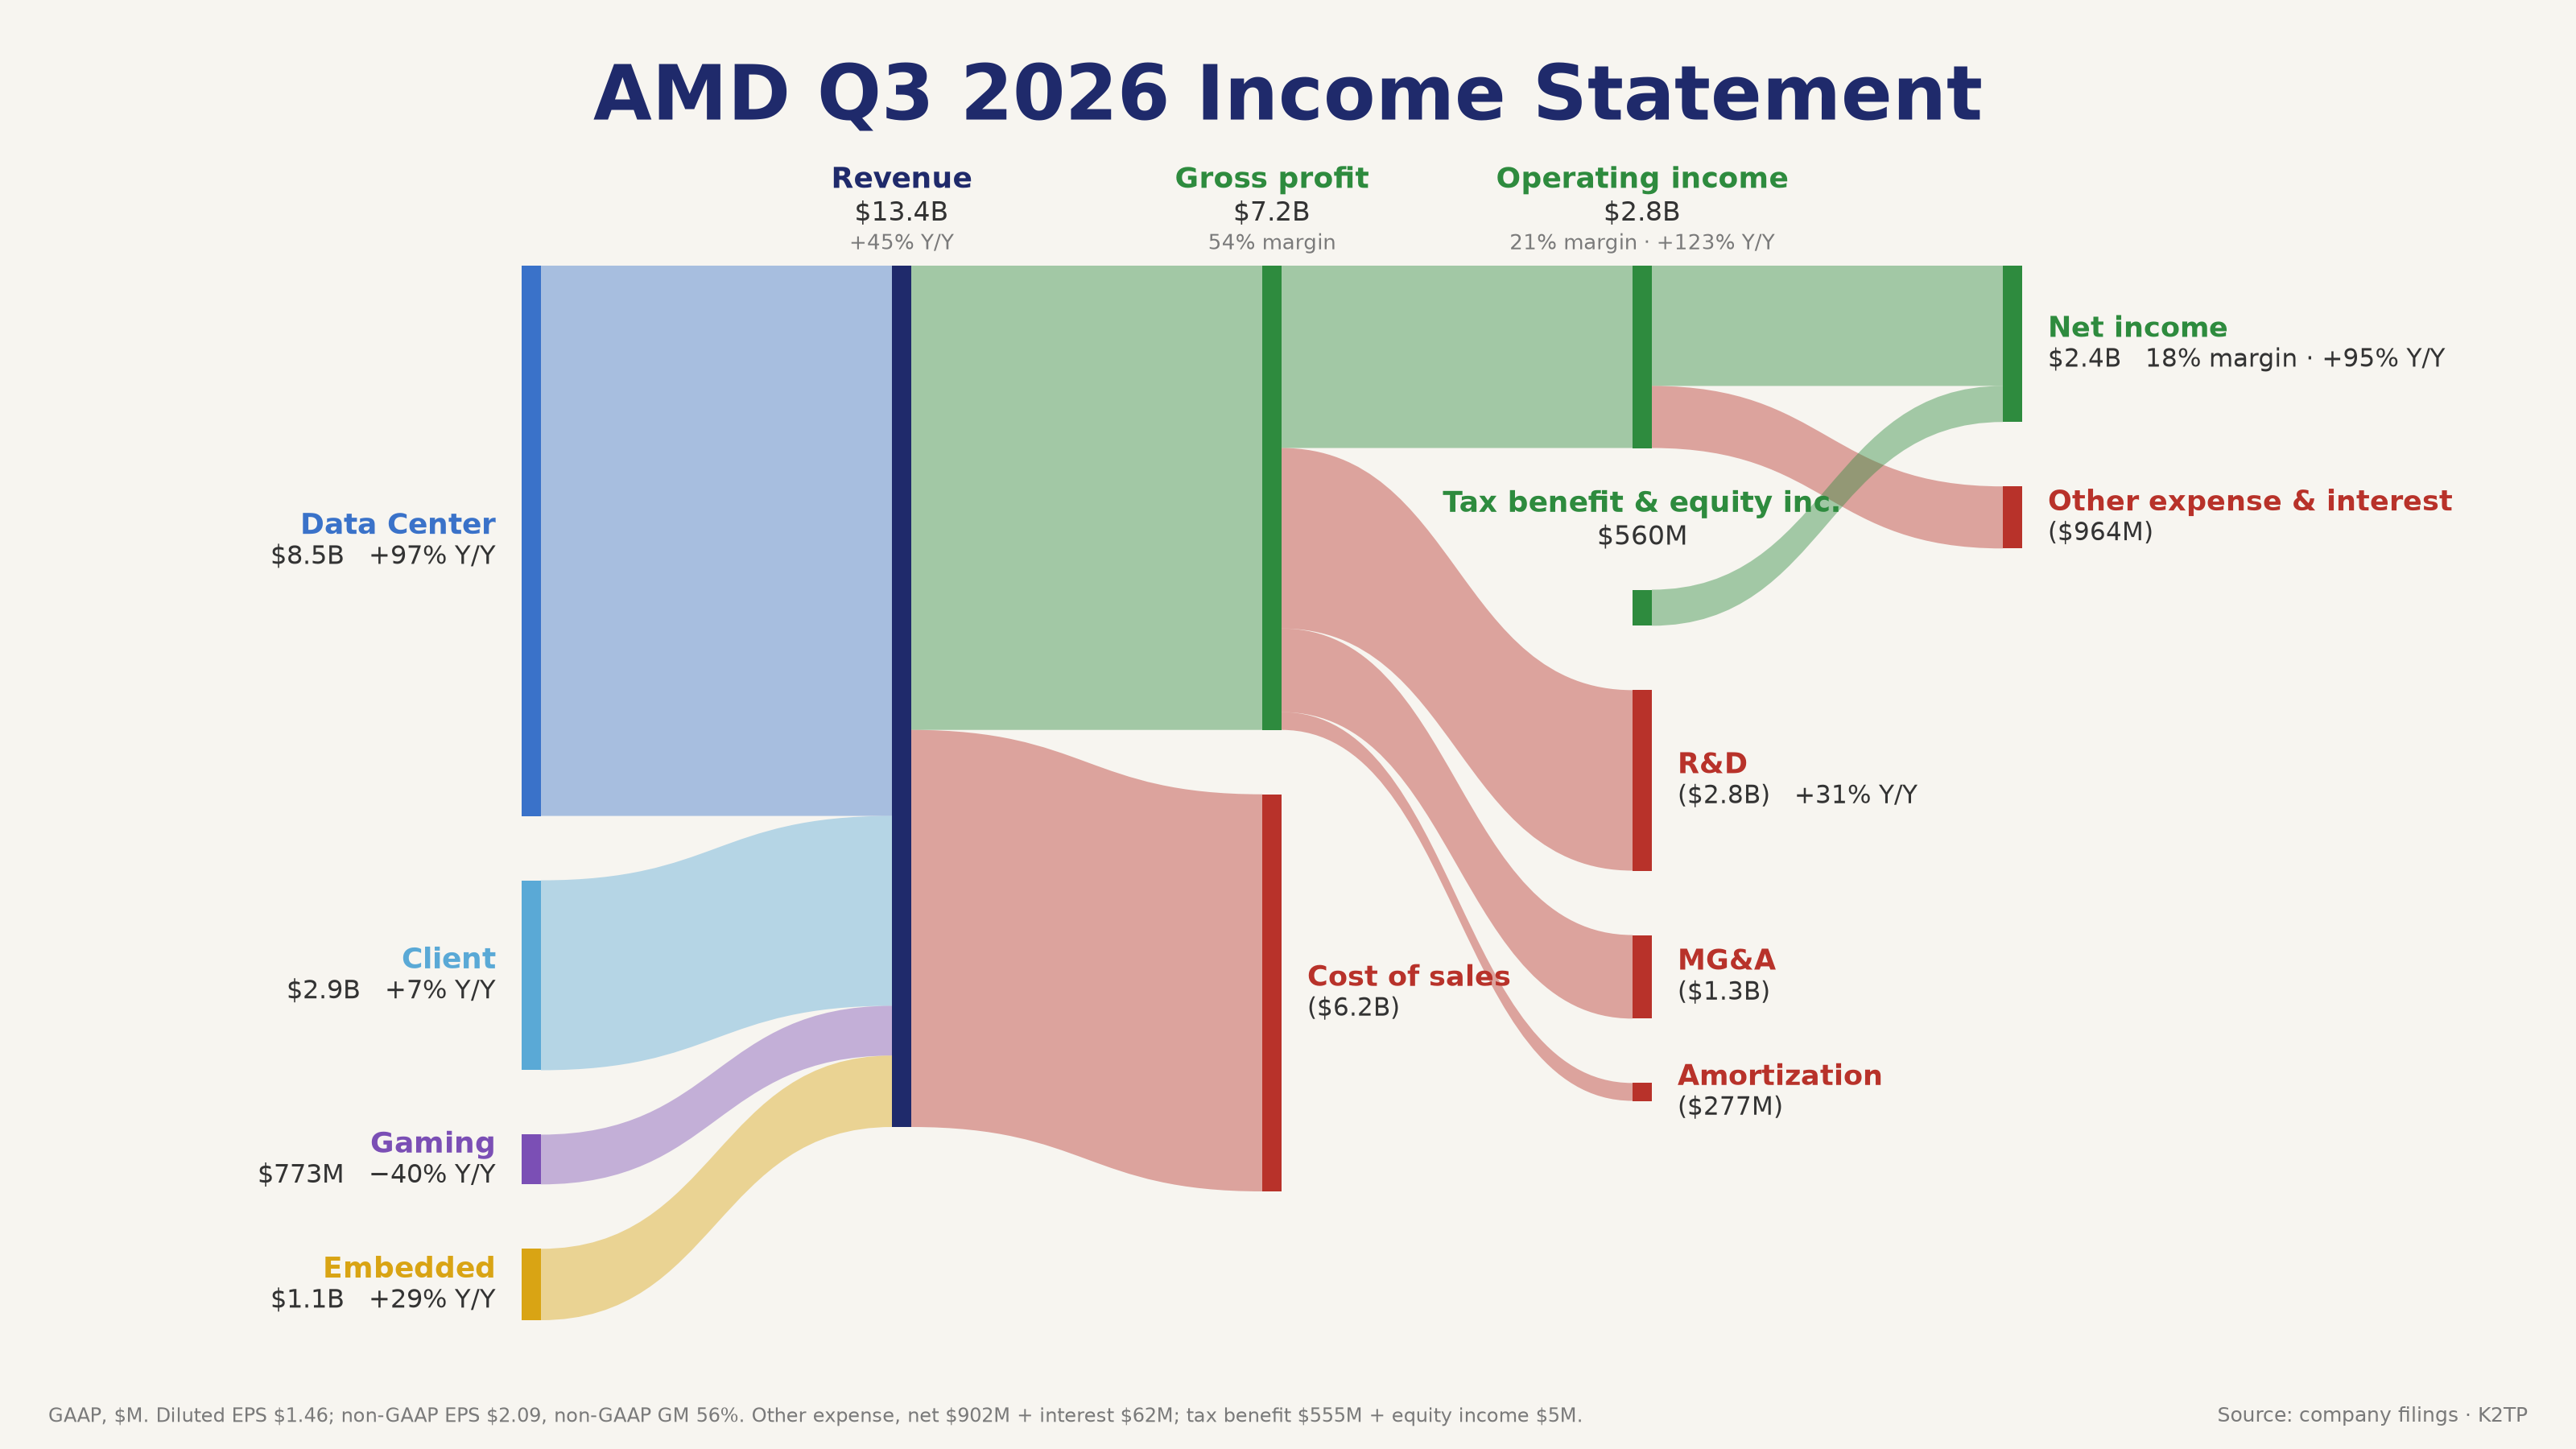
- AMD (8-K Ex. 99.1, Q3 2026): revenue $13,377M (+45% Y/Y, +16% Q/Q) vs about $13.08B expected; GAAP diluted EPS $1.46, non-GAAP EPS $2.09 (+74% Y/Y) vs $1.97; non-GAAP gross margin 56% 🟢
- Segments: Data Center $8,546M (+97% Y/Y) on EPYC and the MI450 launch; Client $2,949M (+7%); Gaming $773M (−40%); Embedded $1,109M (+29%)
- GAAP operating income $2,832M (21% margin, +123% Y/Y); R&D $2,803M (+31%); other expense, net $902M and a $555M tax benefit; net income $2,428M
- Q4 guide: revenue about $17B ±3% (midpoint +66% Y/Y, +27% Q/Q), non-GAAP gross margin about 55% vs 55.5% expected; AMD says growth accelerates in Q4 as it scales Helios and Venice
- AMD closed +3.65% at 483.90 and traded 508.20 (+5.02%) after hours; ES and NQ were up 0.2% and 0.4% at 3:00 PM PT on the report, before the election move
- Arista (ANET): revenue about $3.66B vs $3.33B expected, Q4 guide $3.9B–$4.0B (X News, unconfirmed); ANET 186.00 (+9.47%) after hours
- Amgen −1.36% and Booking −1.39% after hours; result details unavailable
→ AMD's beat and a guide implying 27% sequential growth confirm the AI capex cycle is intact. The slightly softer margin guide is the only blemish, and it did not stop the stock. AI hardware has a fresh support going into Wednesday, even with the macro selling.
CHIPS AND AI CARRY THE SESSION
- Pre-market: chips bounced (MU +4.31%, AMD +4.16%, INTC +3.97%) while AAPL −4.01% and PLTR −6.22% fell after earnings; SHOP −15.67% on a miss
- At midday SOX was +3.37%; at pre-close leadership rotated to MSFT and AMZN; SOX closed +2.63% to 10,600.40 (high 10,761.85)
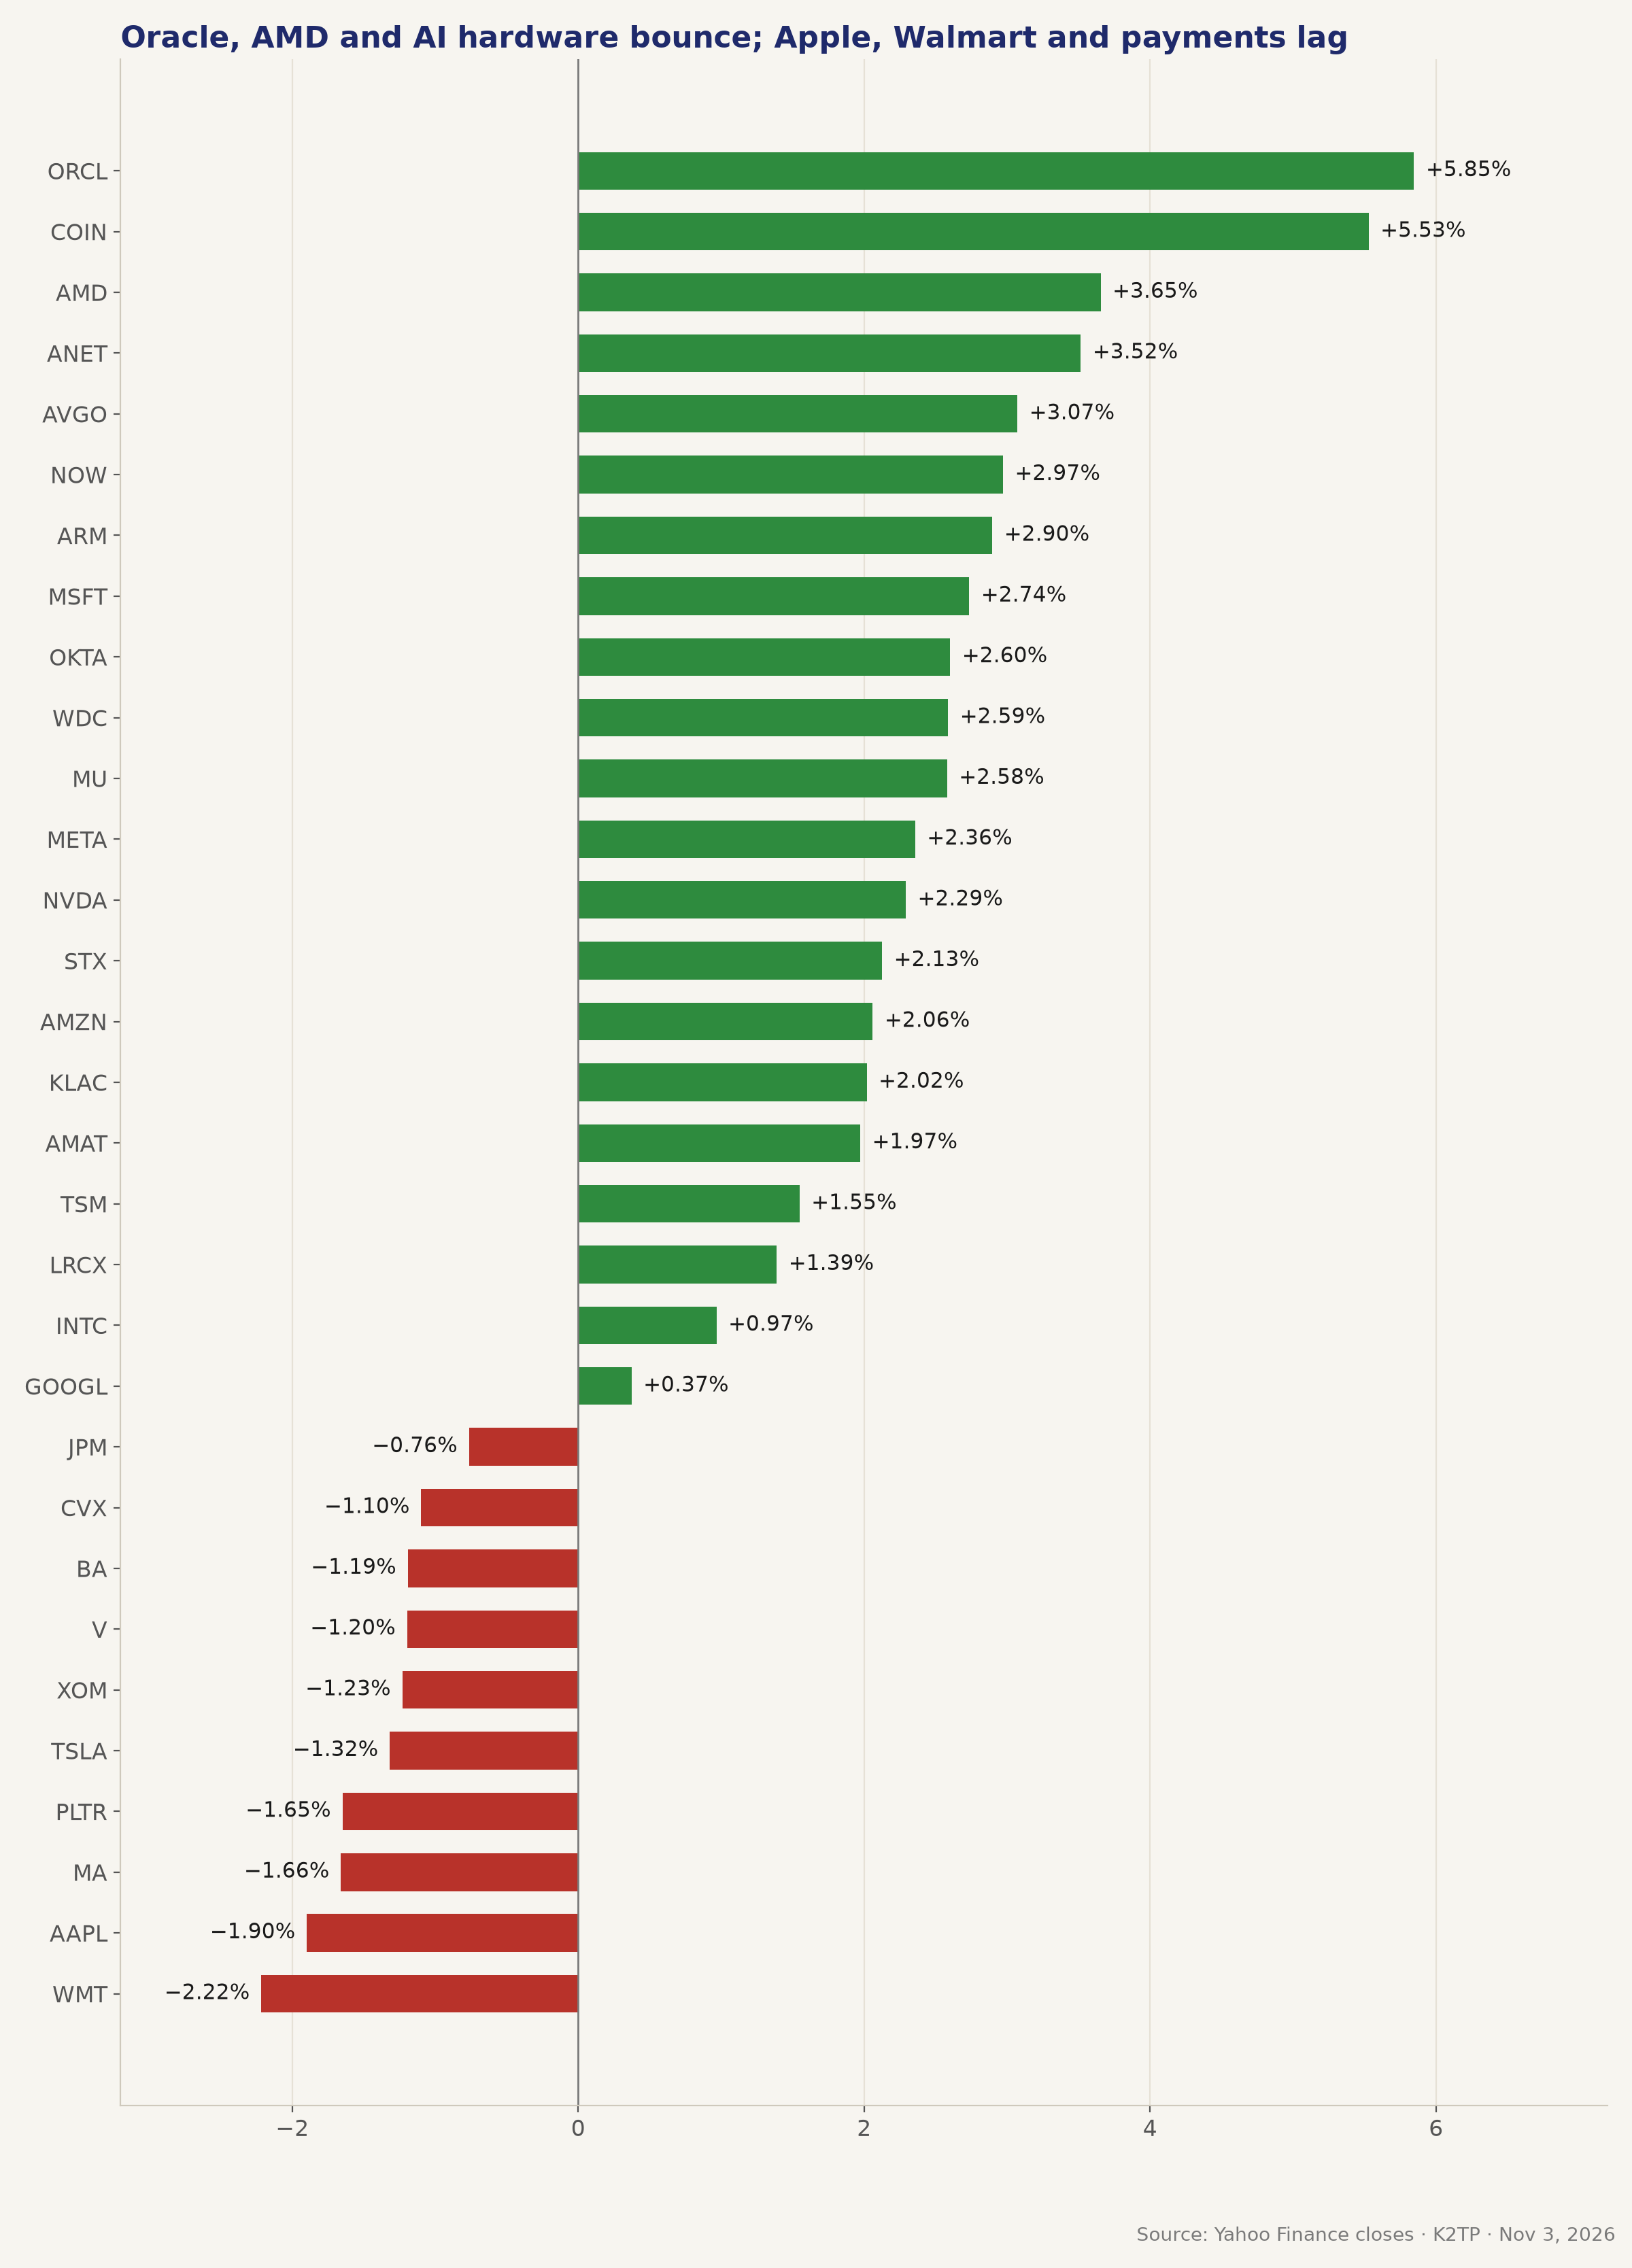
- ORCL +5.85% after Monday's slide; AVGO +3.07%, ARM +2.90%, MU +2.58%, NVDA +2.29%, KLAC +2.02%, AMAT +1.97%, TSM +1.55%, LRCX +1.39%
- Equipment faded after a 10:50 AM PT report that US officials held up chip-tool approvals for SK Hynix in China
- Software and mega-caps: NOW +2.97%, MSFT +2.74%, META +2.36%, AMZN +2.06%, COIN +5.53%; Meta priced $15B of senior notes
- Laggards: WMT −2.22%, AAPL −1.90% (well off its −4.01% pre-market), MA −1.66%, PLTR −1.65%, TSLA −1.32%, XOM −1.23%, V −1.20%
→ After two days of selling on AI funding supply, money came back into chips and AI software. But it was a cap-weighted rally, not a broad one.
JOLTS BEAT; A BEAR STEEPENER
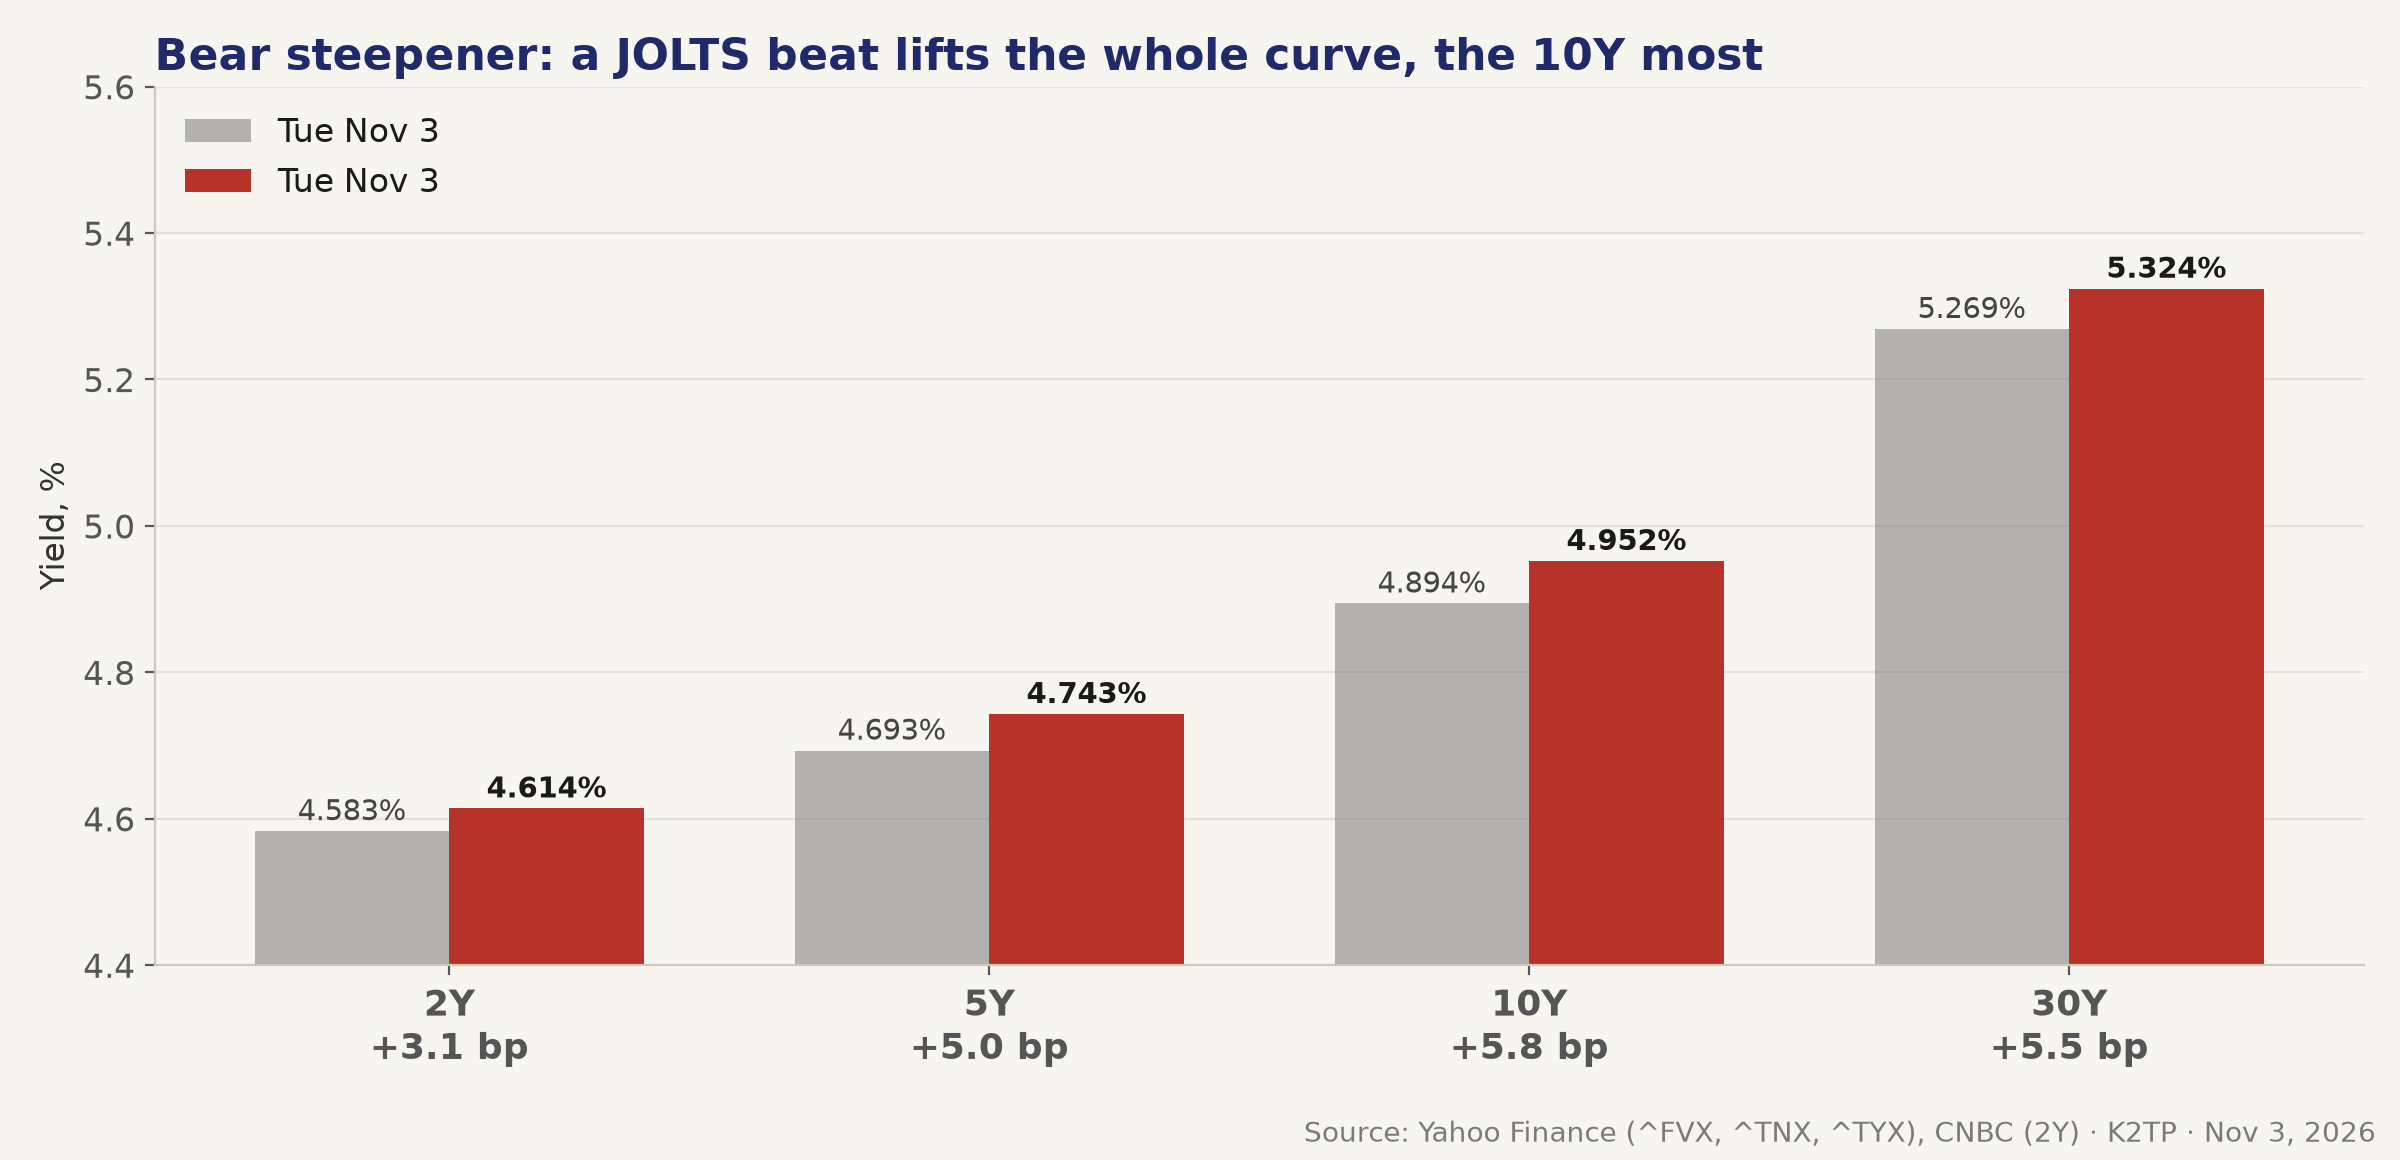
- 7:00 AM PT: JOLTS job openings 7.523M vs 7.164M expected (7.079M prior); factory orders +1.8% vs +1.2%; durable goods revised to 1.9%
- Closing yields: 2Y 4.614% (+3.1 bp, CNBC), 5Y 4.743%, 10Y 4.952%, 30Y 5.324%; 2s10s 31.1 → 33.6 bp
- ECB's Nagel said a December hike is very likely; ECB's Kocher said it is likely if nothing changes
- Tonight the curve rallies on the election news: 10Y 4.931% at 10:38 PM PT
- Updated FedWatch probabilities: unavailable
→ Hot labor demand pushed yields up in the session, then the election flipped bonds into a haven bid. ADP and ISM Services on Wednesday decide whether that rally holds.
A NARROW TAPE: ONLY 4 OF 11 SECTORS UP
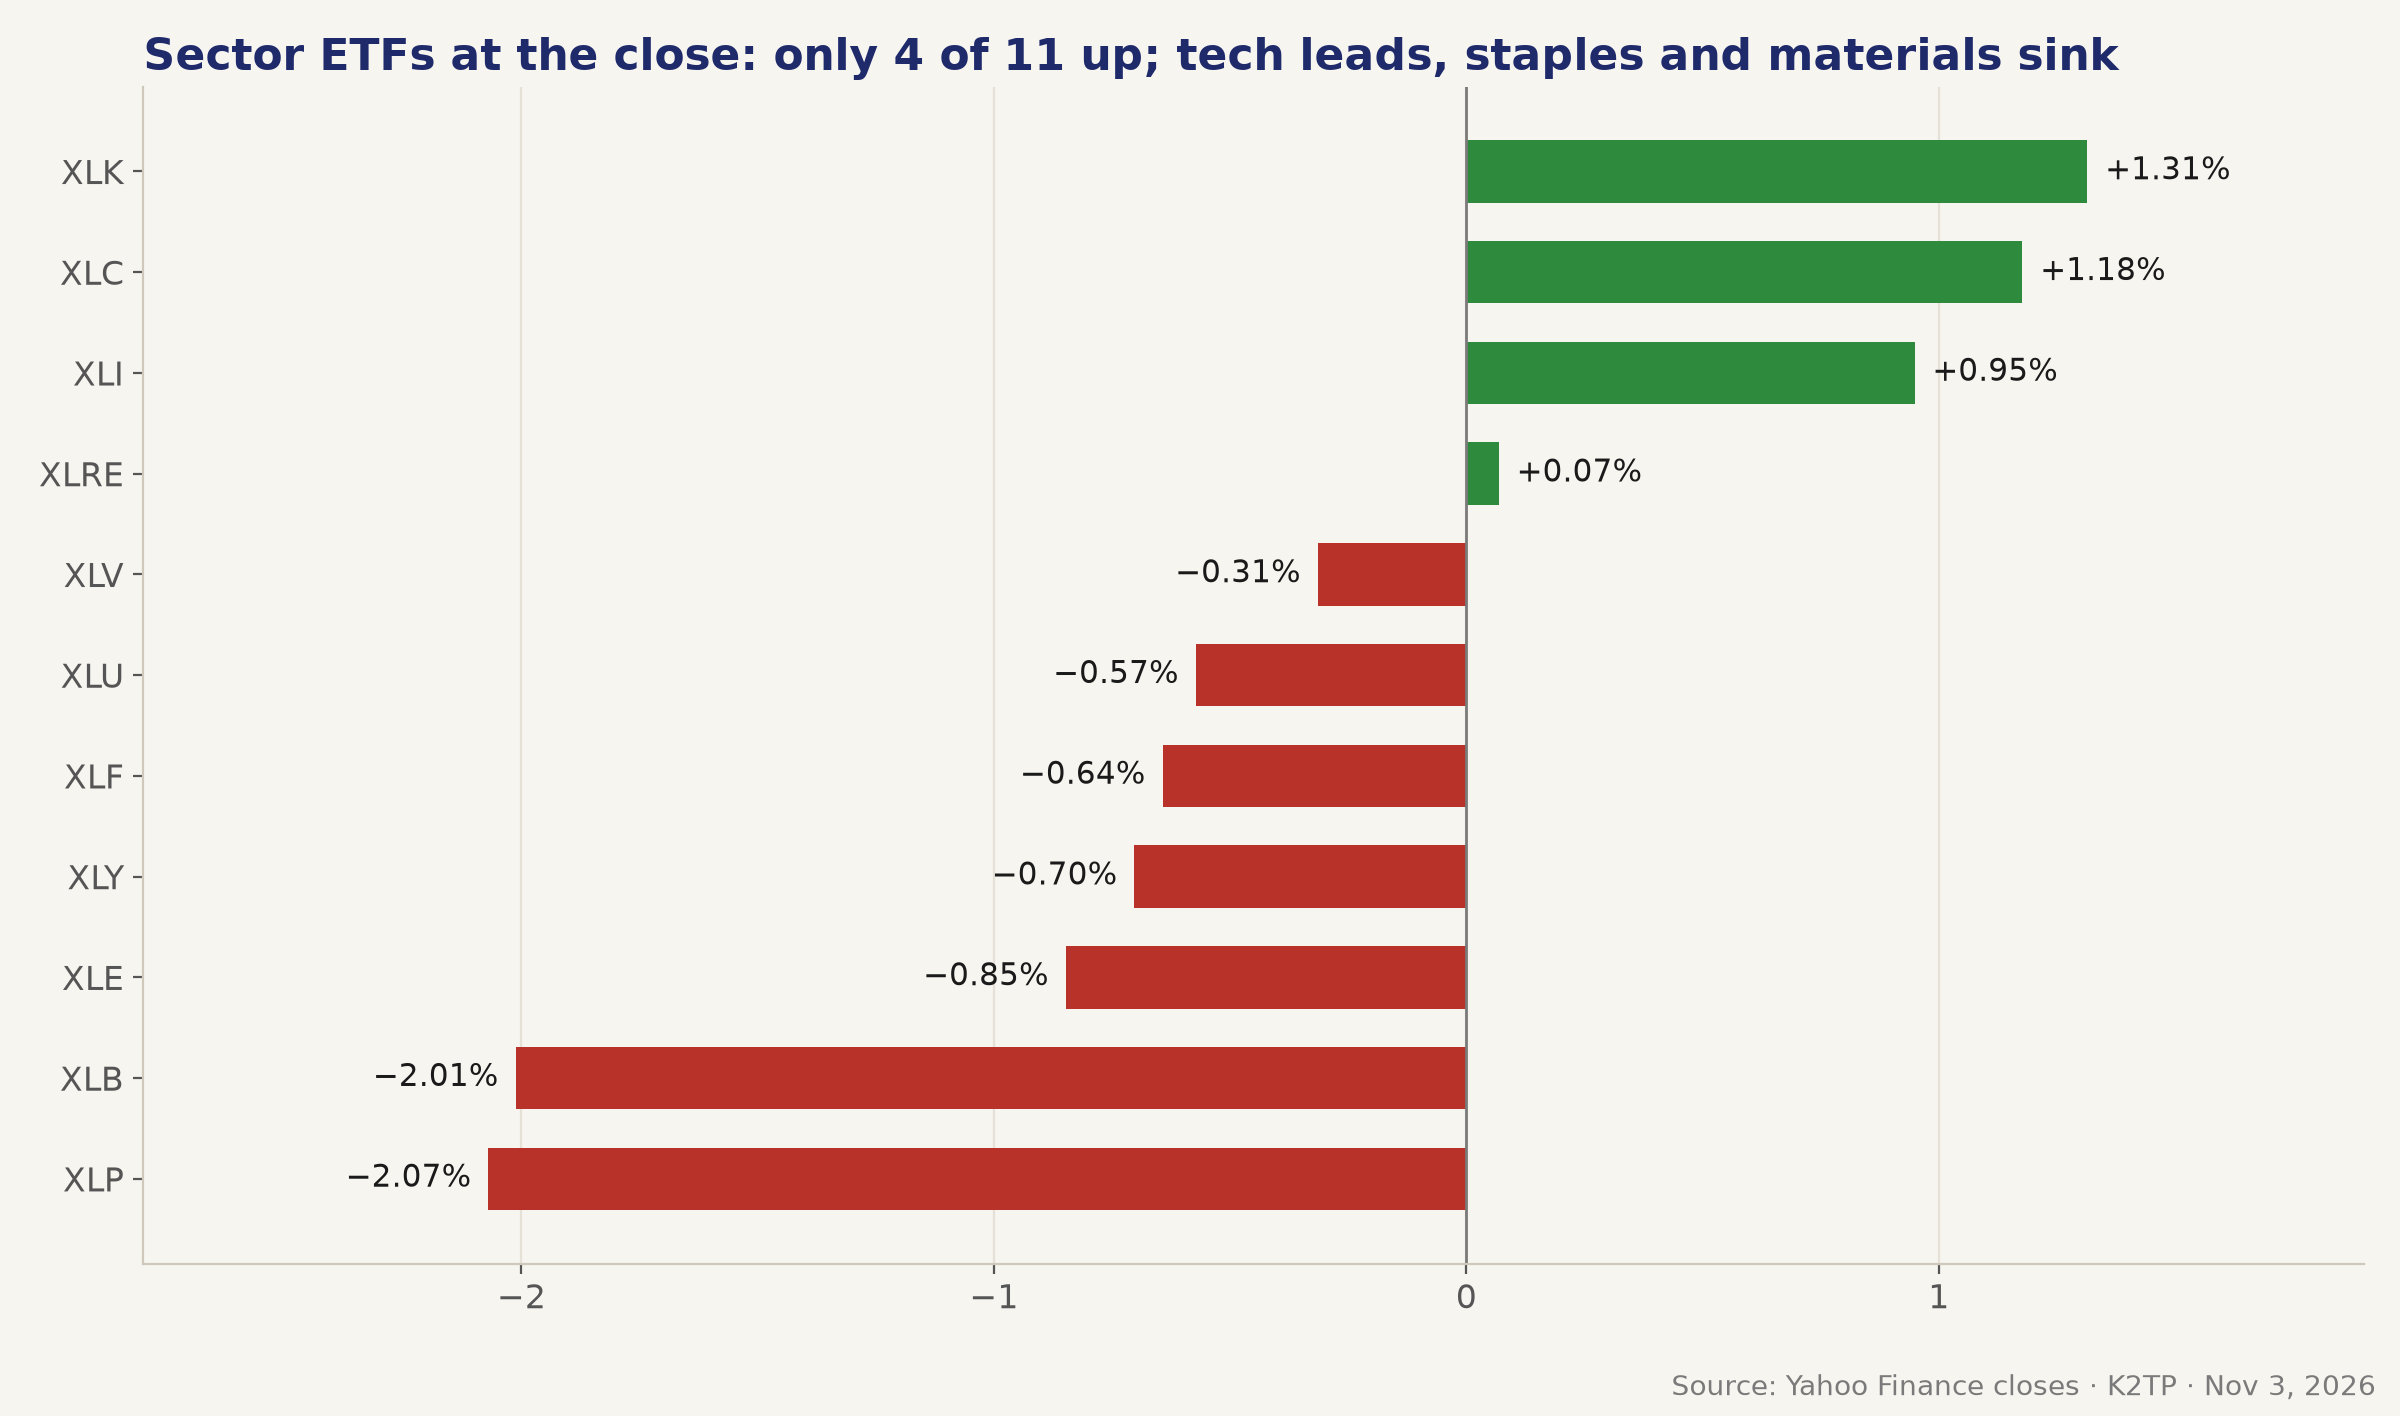
- Up: XLK +1.31%, XLC +1.18%, XLI +0.95%, XLRE +0.07%; down: XLP −2.07%, XLB −2.01%, XLE −0.85%, XLY −0.70%, XLF −0.64%, XLU −0.57%, XLV −0.31% 🔴
- RSP −0.33% vs SPX +0.36%, a 69 bp gap; SPY +0.30%, QQQ +0.62%, IWM +0.23%
- The MOC imbalance showed about $880M to sell for the S&P 500 and $1.40B for the Nasdaq 100
→ The opposite of Monday: a cap-weighted gain while most stocks fell. That leaves SPX leaning on a few mega-caps going into the election shock.
SPX: HIGH AT 10:30 AM, A FADE INTO THE VOTE
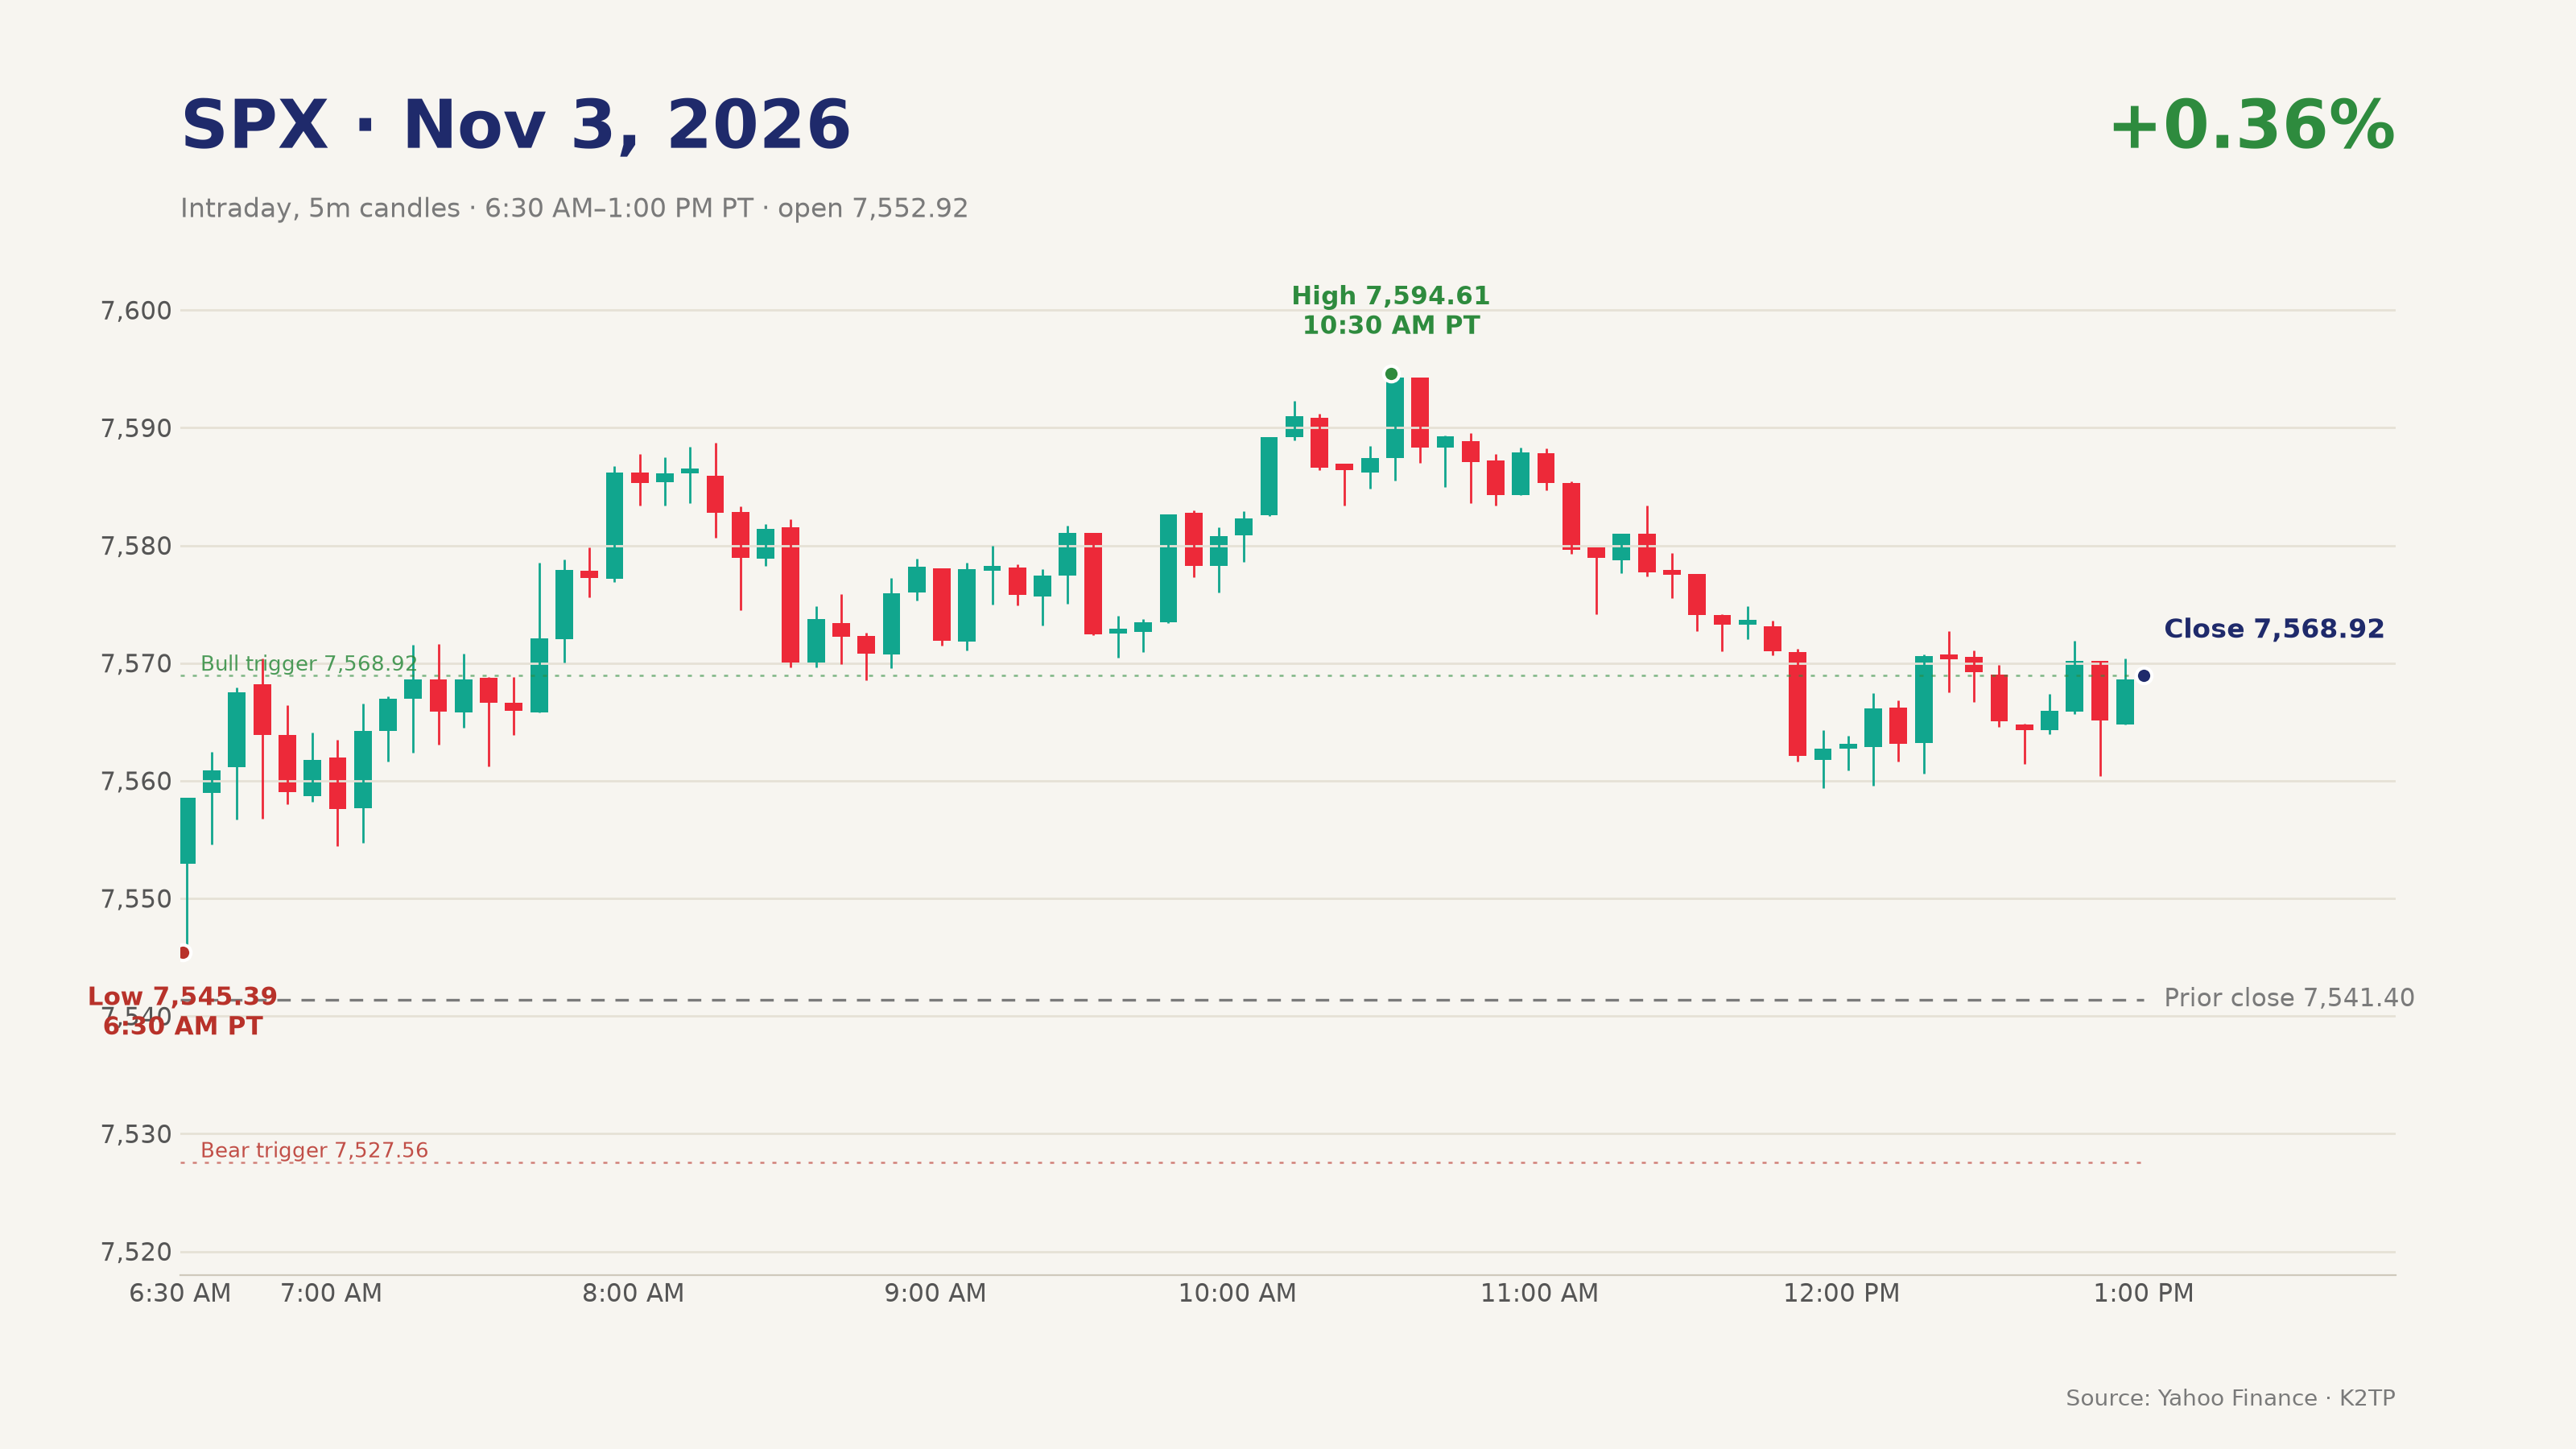
- Pre-market: ES −0.14%, implied SPX near 7,531, just above the 7,527.56 Bear line
- SPX opened at 7,552.92, printed its 7,545.39 low in the first minutes, and reached 7,575.50 by midday
- The 7,594.61 high came at 10:30 AM PT, above the midday Bull level of 7,588.70, but VIX only matched its 20.29 low instead of breaking it, so the Bull confirm stayed 1 of 2
- SPX slid to 7,559.36 around 11:50 AM PT, was 7,562.70 at pre-close and closed at 7,568.92; the Bear line (SPX under 7,545.39 with VIX above 21.91) was never close
→ A positive close, but 26 points off the high, with no follow-through. The session's range (7,545.39–7,594.61) is now the frame for Wednesday.
MARKET: A NARROW CHIP RALLY, THEN AN ELECTION SHOCK OVERNIGHT
Indices (close):
- SPX 7,568.92 (+0.36%), range 7,545.39–7,594.61
- NDX 28,180.26 (+0.68%); Nasdaq Composite 25,372.01 (+0.83%)
- DJIA 51,786.72 (−0.38%)
- RUT 2,812.45 (+0.23%)
- RSP 219.26 (−0.33%)
- SOX 10,600.40 (+2.63%)
Intraday path: ES −0.14% pre-market with AAPL and PLTR lower. SPX opened at 7,552.92, made its 7,545.39 low early, was 7,575.50 at midday, hit 7,594.61 at 10:30 AM PT, dipped to 7,559.36 around 11:50 AM PT, was 7,562.70 at pre-close and closed at 7,568.92.
Sector rotation:
- Up: XLK +1.31%, XLC +1.18%, XLI +0.95%, XLRE +0.07%
- Down: XLV −0.31%, XLU −0.57%, XLF −0.64%, XLY −0.70%, XLE −0.85%, XLB −2.01%, XLP −2.07%
- Mega-caps: MSFT +2.74%, META +2.36%, NVDA +2.29%, AMZN +2.06%, GOOGL +0.37%, TSLA −1.32%, AAPL −1.90%
Market internals:
- RSP −0.33% vs SPX +0.36%; QQQ +0.62%, IWM +0.23%
- 4 of 11 sectors up, from 3 of 11 at pre-close
- NYSE advance/decline at the close: unavailable
Volatility: 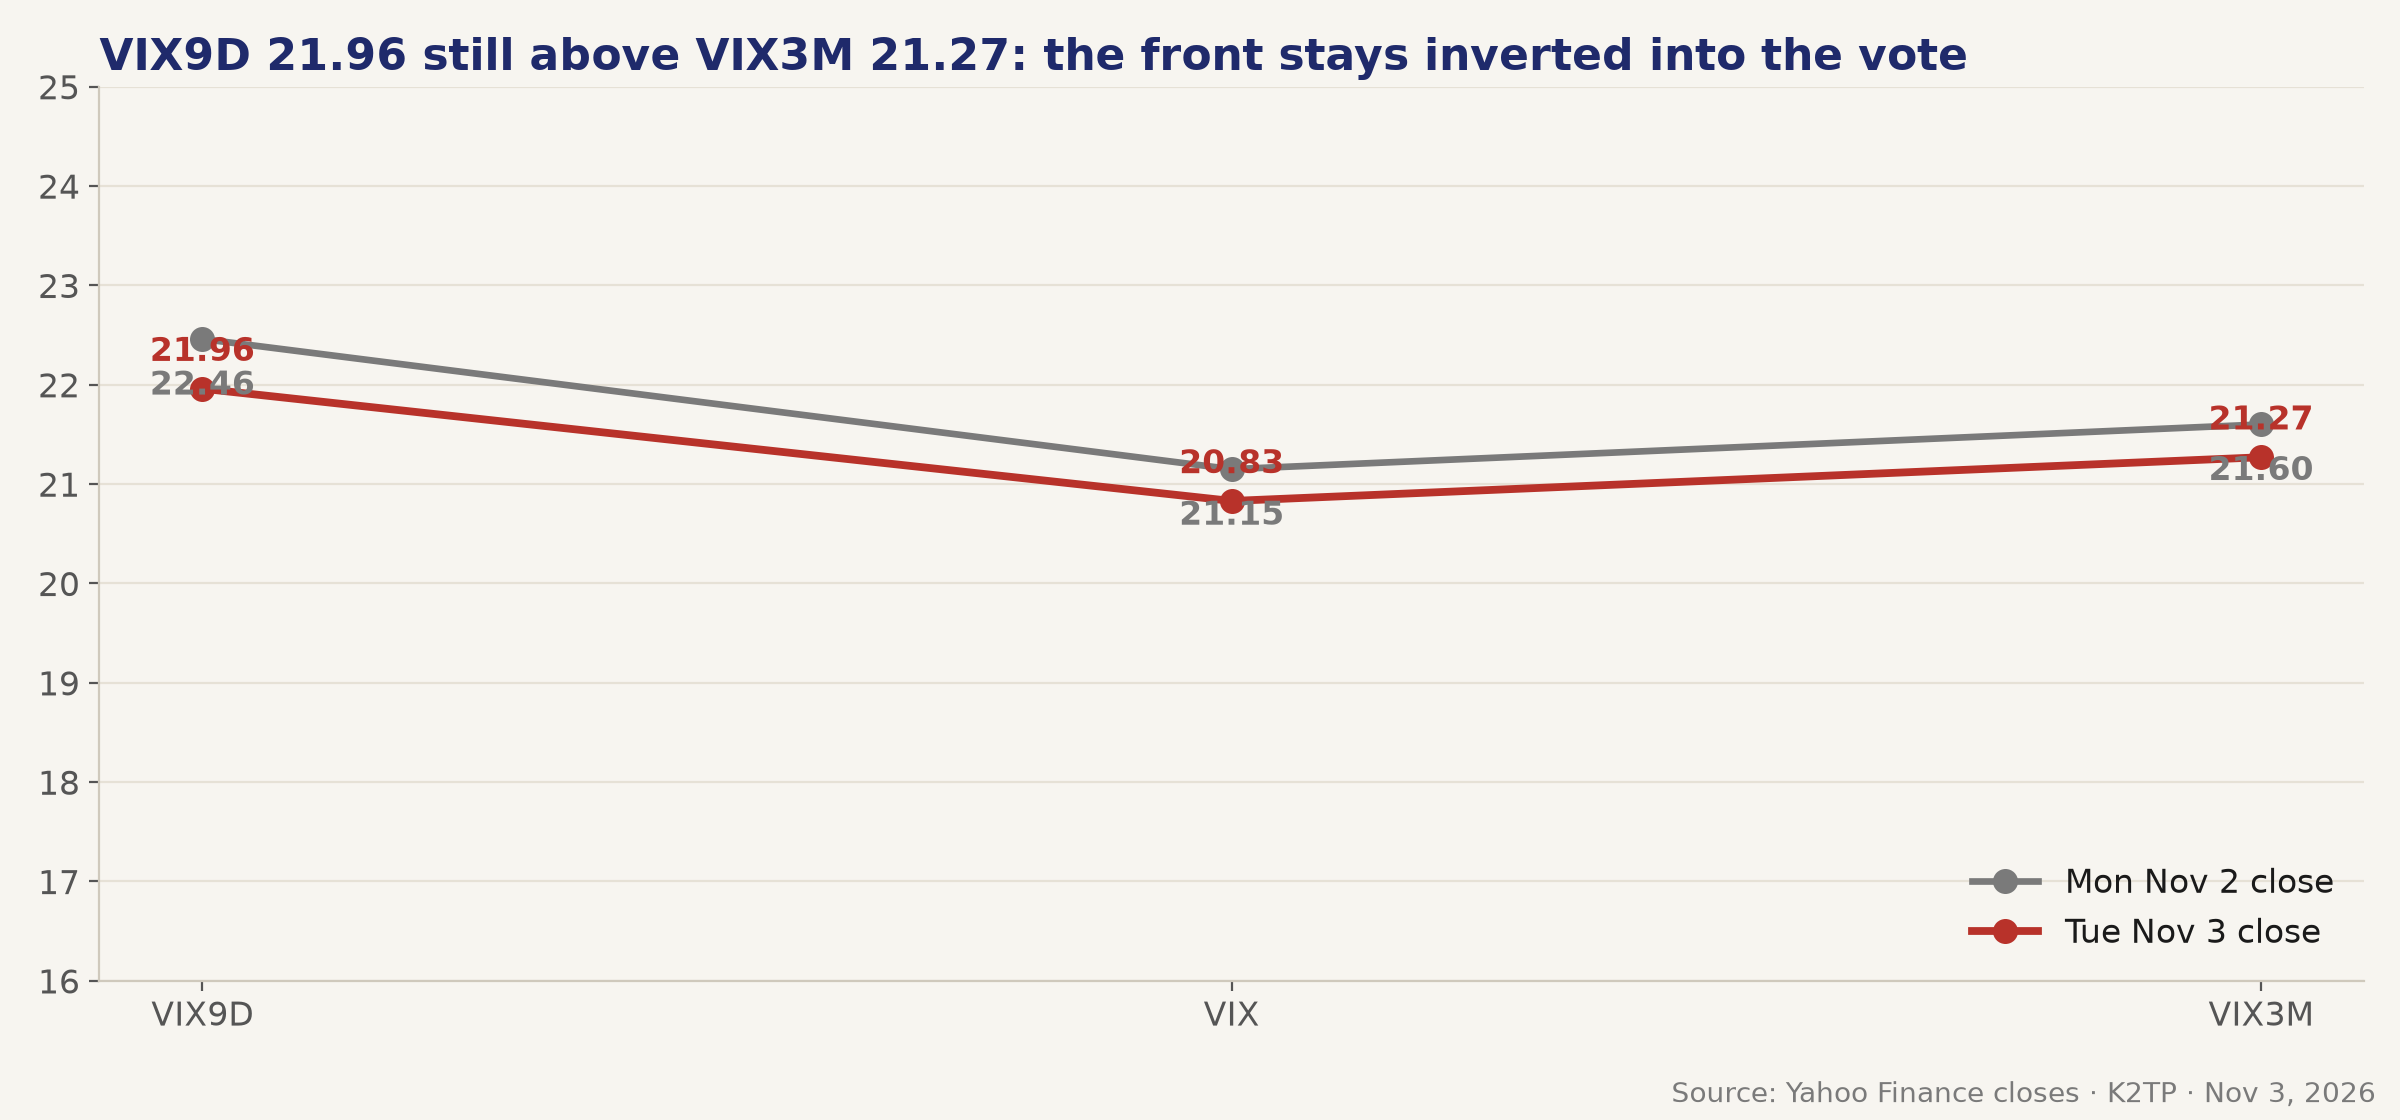
- VIX 20.83 (−1.51%), range 20.29–21.91
- VIX9D 21.96, VIX3M 21.27: the front of the curve is still inverted going into the results
- VVIX 107.40 (−2.78%)
- Gamma levels: unavailable
Cross-asset:
- Session close: 2Y 4.614%, 5Y 4.743%, 10Y 4.952%, 30Y 5.324%; tonight 10Y 4.931%
- WTI settled $96.09, Brent $103.60; API crude stocks −5.27M barrels; WTI $96.48 tonight
- Gold about $4,028 (+2.2%); DXY 101.51 (−0.35%); BTC about $77,860
Global:
- Europe: Euro Stoxx 50 −0.51%, DAX −0.45%, CAC 40 −0.34%, FTSE 100 −1.14%
- Tonight: Nikkei −1.66%, Kospi +0.28%, Hang Seng +1.11%, Shanghai +1.89%; China's October services PMI 50.8 vs 51.7 expected
- Iran: Trump told the FT the US has no immediate plan to attack Iran
Key SPX levels:
- 7,594.61: Tuesday's high
- 7,568.92: Tuesday's close; the Bull line is SPX above it with VIX under 20.29
- 7,545.39: Tuesday's low; ES 7,574.25 at 10:30 PM PT implies SPX near 7,546, right on it
- 7,527.56: Friday's low; the Bear line is SPX under it with VIX above 21.91
- About 7,462: implied SPX at the 7,490.00 ES overnight low
- VIX: 20.29 and 21.91
Option seller corner (Wednesday):
- The binary event is behind us: both chambers are projected, so event premium should start to bleed out. VIX9D above VIX3M means short-dated premium is rich; sell it only after the open settles and ADP (5:15 AM PT) and ISM Services (7:00 AM PT) are out.
- Bull scenario: the gap fills and SPX trades back above 7,568.92 with VIX under 20.29; far-OTM SPX put spreads below 7,527.56 become reasonable, with the overnight low as the reference.
- Bear scenario: cash selling resumes and SPX breaks 7,527.56 with VIX above 21.91; then the 7,462 area (the ES low) is the next test. Keep size small and defined-risk only; no naked puts into a breaking tape.
- Single names: avoid short premium in policy-exposed groups until the dust settles (managed care such as UNH, defense, private prisons); AMD and ANET implied vol should drop after earnings, but they gapped up, so put sellers should strike below the pre-earnings close (AMD 483.90, ANET 169.91).
- Favor broad underlyings (SPX) over NDX: NQ took the bigger hit overnight, and Wednesday's breadth still has to prove itself.
BOTTOM LINE
- Democrats are projected to win both the House and the Senate. Futures fell as much as about 1.4% on ES, then recovered to −0.30%, with gold +2.2% and the 10Y lower.
- The session itself was a narrow chip and AI rally (SOX +2.63%, SPX +0.36%) with weak breadth (RSP −0.33%, 4 of 11 sectors) and a bear steepener after JOLTS.
- AMD and Arista beat after the close and support AI hardware. Regime 🔴 RISK-OFF. 7,527.56 is the line to hold; 7,568.92 with VIX under 20.29 is the way back to TRANSITION.
Watch Wednesday (PT):
- Overnight: remaining House races and the Maine Senate call; the final Senate majority
- 5:15 AM: ADP employment (67K expected vs 90K prior)
- 6:30 AM: the cash open and the gap versus Tuesday's 7,568.92 close
- 7:00 AM: ISM Services PMI (54.8 expected vs 54.9 prior)
- 7:30 AM: EIA crude stocks
- Later this week: October payrolls Friday 5:30 AM (65K expected vs 29K prior)
Bull expectation: the election selloff fades, AMD keeps chips bid, and SPX trades above 7,568.92 with VIX under 20.29. Bear expectation: selling resumes at the cash open, policy-exposed sectors drag, and SPX breaks 7,527.56 with VIX above 21.91.
Sources: 3 K2TP briefs for 11/3/2026 (Pre-Market, Midday, Pre-Close) and the 11/3 Evening Recap. Election projections from the AP (live results page and race calls), CBS News, NBC News, Fox News and Decision Desk HQ (via FinancialJuice). Official closes, intraday data and overnight futures from Yahoo Finance; yields, DXY and extended-hours quotes from CNBC; news and data from Reuters, CNBC and FinancialJuice; Arista from X News (unconfirmed); AMD Sankey from AMD's Q3 2026 press release (8-K Ex. 99.1), SEC EDGAR. Analysis: K2TP Framework.