Market 11/2: Chips sink again and the Nasdaq 100 enters a correction while oil plunges 7% on Iran diplomacy; SPX closes at its low, then Apple's margin guide weighs after hours
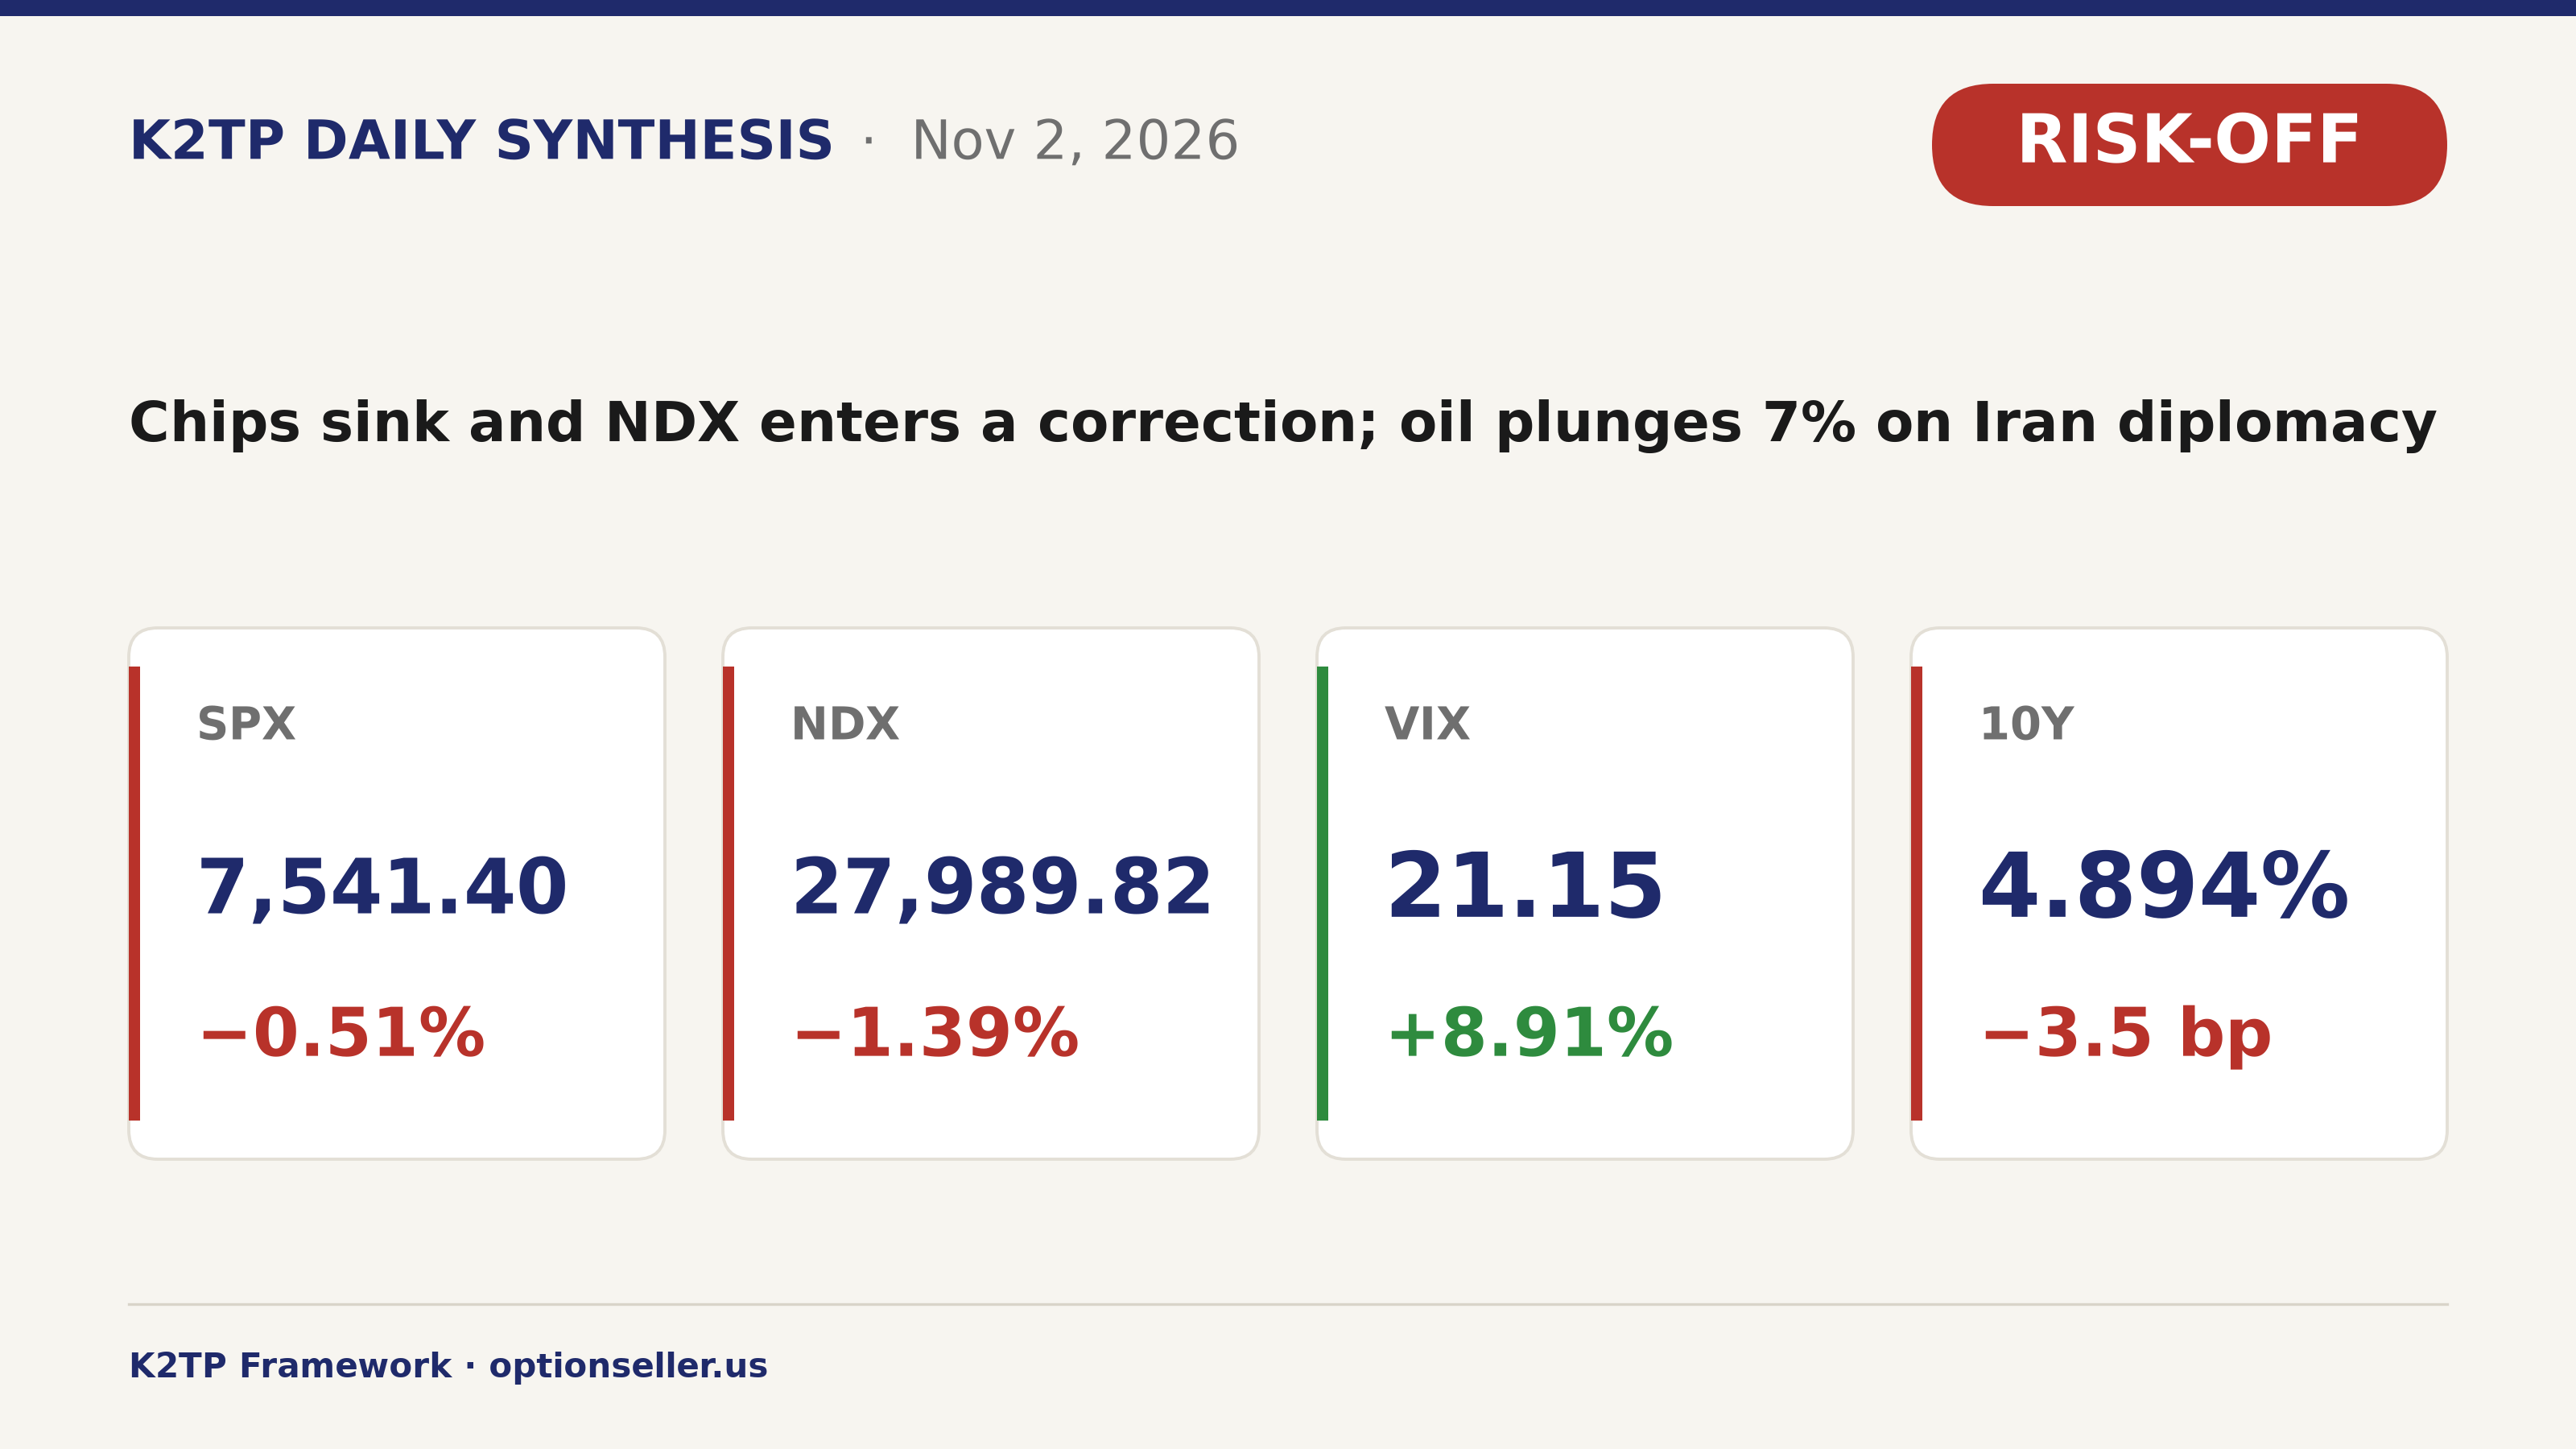
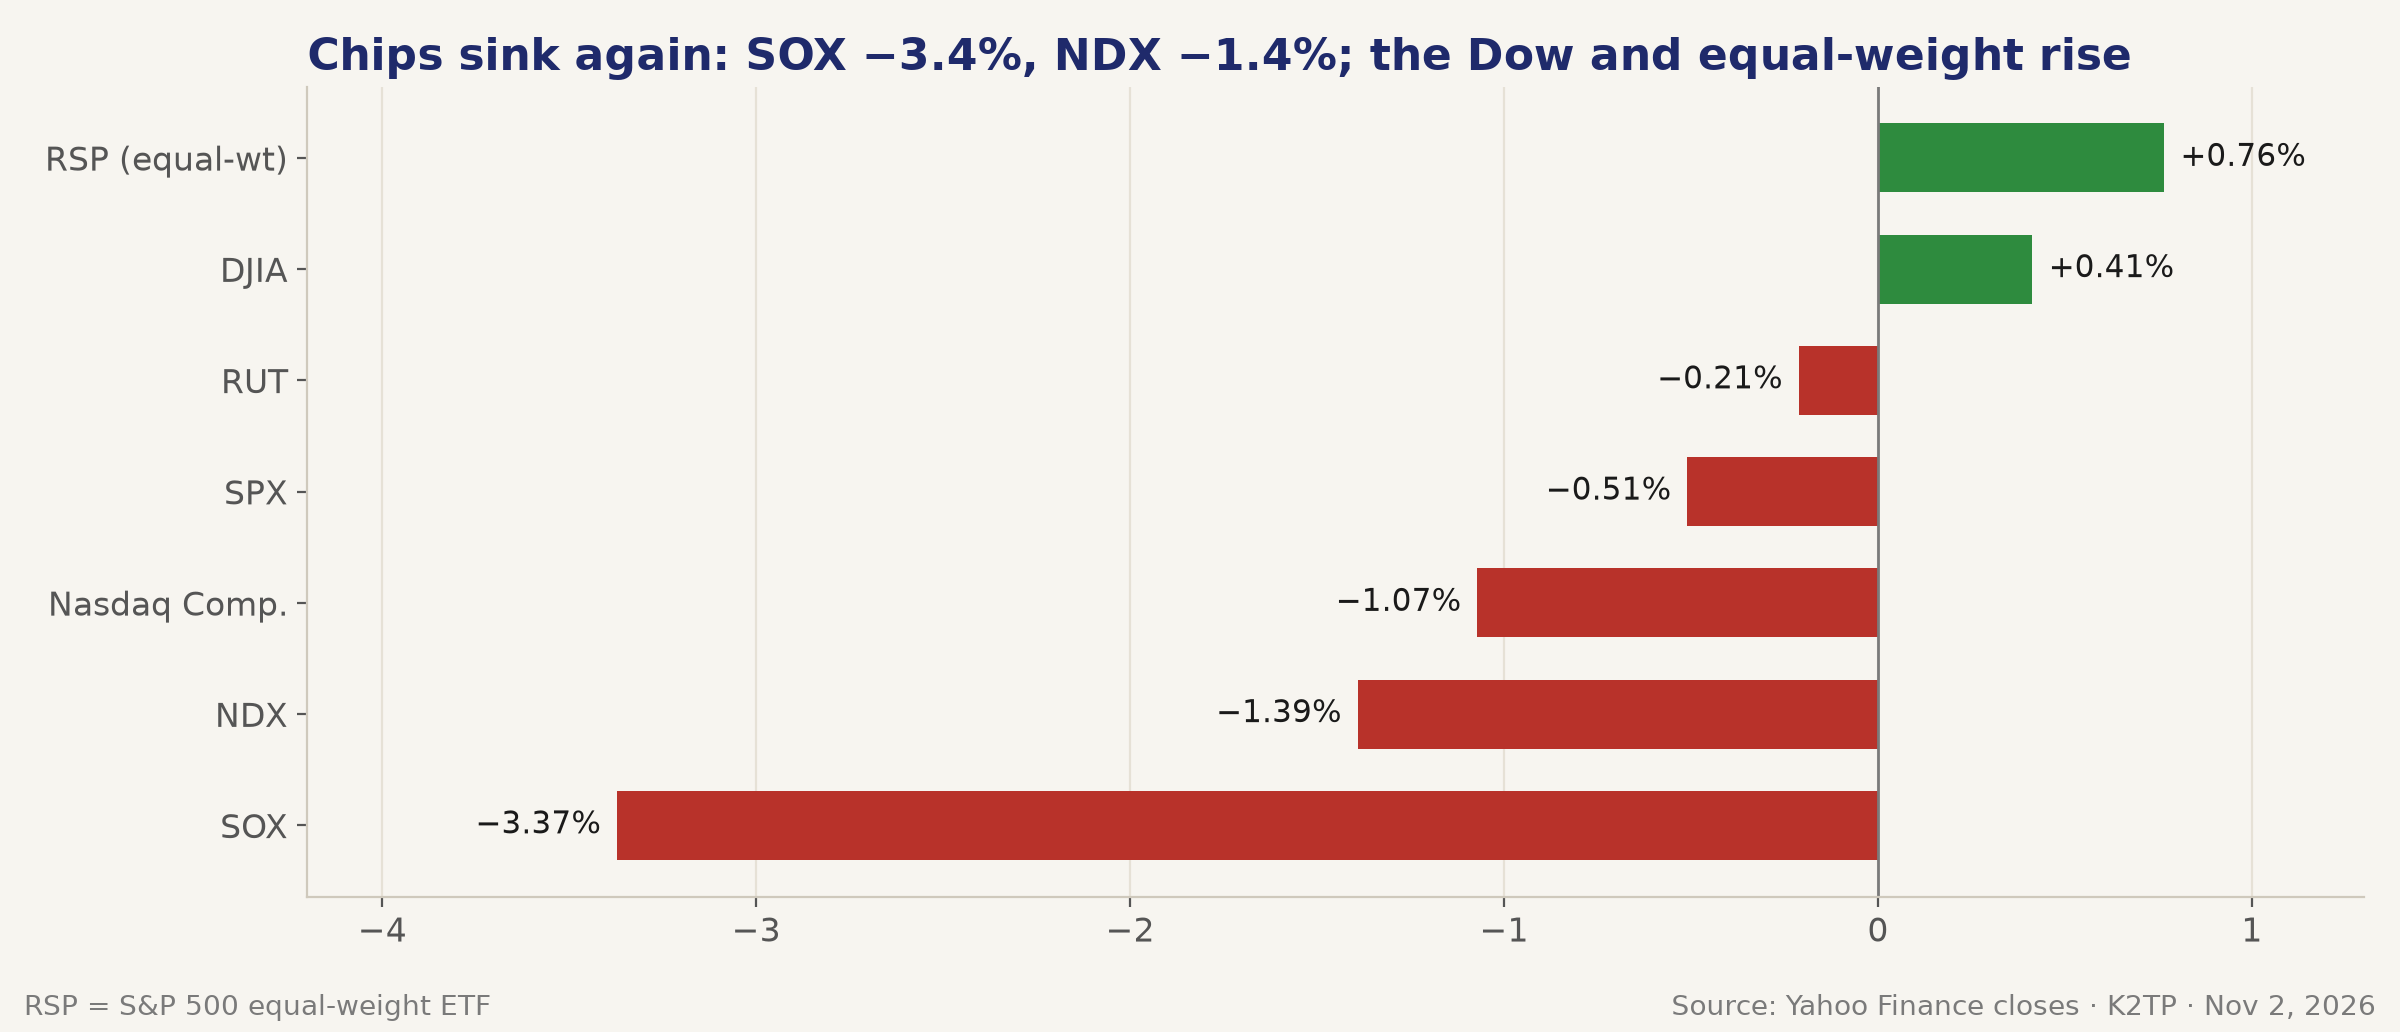
SPX −0.51%, NDX −1.39%, SOX −3.37%, Nasdaq Composite −1.07%, DJIA +0.41%, RUT −0.21%, RSP +0.76%, VIX +8.91% to 21.15. INTC −8.80%, ORCL −8.76%, AMD −7.52% and OKTA −11.22% while MA +3.15%, WMT +3.38% and AMZN +2.20%; 8 of 11 sector ETFs rise. WTI settles $96.46 (−7.36%); 10Y 4.894% (−3.5 bp). After hours AAPL −2.81% on a 45%–46% gross margin guide.
KEY HEADLINES
- SPX −0.51% to 7,541.40 (−38.67 points), closing near its 7,539.38 low after a 7,662.23 high; NDX −1.39% to 27,989.82; Nasdaq Composite −1.07% to 25,164.36; DJIA +0.41% to 51,983.98; RUT −0.21% to 2,805.88
- Chips sell off for a second session: SOX −3.37% to 10,328.33 after −7.20% on Friday; INTC −8.80%, AMD −7.52%, STX −7.88%, WDC −7.52%, MU −5.78%; the Nasdaq 100 entered a correction (Bloomberg via FinancialJuice)
- AI funding supply weighs on the group: ORCL −8.76% after a $10B common stock offering, Meta eyes at least a $20B bond sale, Anthropic plans a UK retail IPO
- Oil collapses on US-Iran diplomacy: WTI settles $96.46 (−7.36%), Brent $104.77 (−7.63%); XLE −3.96%. After the close, reports of explosions on Qeshm Island and a WSJ report of a US strike (unconfirmed)
- ISM Manufacturing 55.5 vs 54.5 expected with prices paid easing to 75.2; a bull flattener takes the 10Y to 4.894% (−3.5 bp) while the 2Y holds at 4.583%
- Rotation, not an exit: RSP +0.76% vs SPX −0.51%; XLY +2.41%, XLF +1.86%, XLB +1.76%; MA +3.15%, V +2.88%, WMT +3.38%
- Apple beats (EPS $2.10 vs $1.99, revenue $114.48B vs $113.39B), but a December-quarter gross margin guide of 45%–46% vs 46.3% sends AAPL to $328.81 (−2.81%) after hours; PLTR beats and raises but slips 3.00%
- Regime: 🔴 RISK-OFF (from 🟡 TRANSITION at midday); SPX closed under the pre-close Bear line of 7,554.78 and VIX touched 21.77
- Tuesday: US midterm elections, JOLTS at 7:00 AM PT, AMD after the close
CHIPS SINK AGAIN AND THE NASDAQ 100 ENTERS A CORRECTION
- Chips opened higher (TSM +1.45% pre-market after Sam Altman's visit to South Korea; Hassett said "I don't think there's risk of AI wholesale selloff"), then reversed lower 🔴
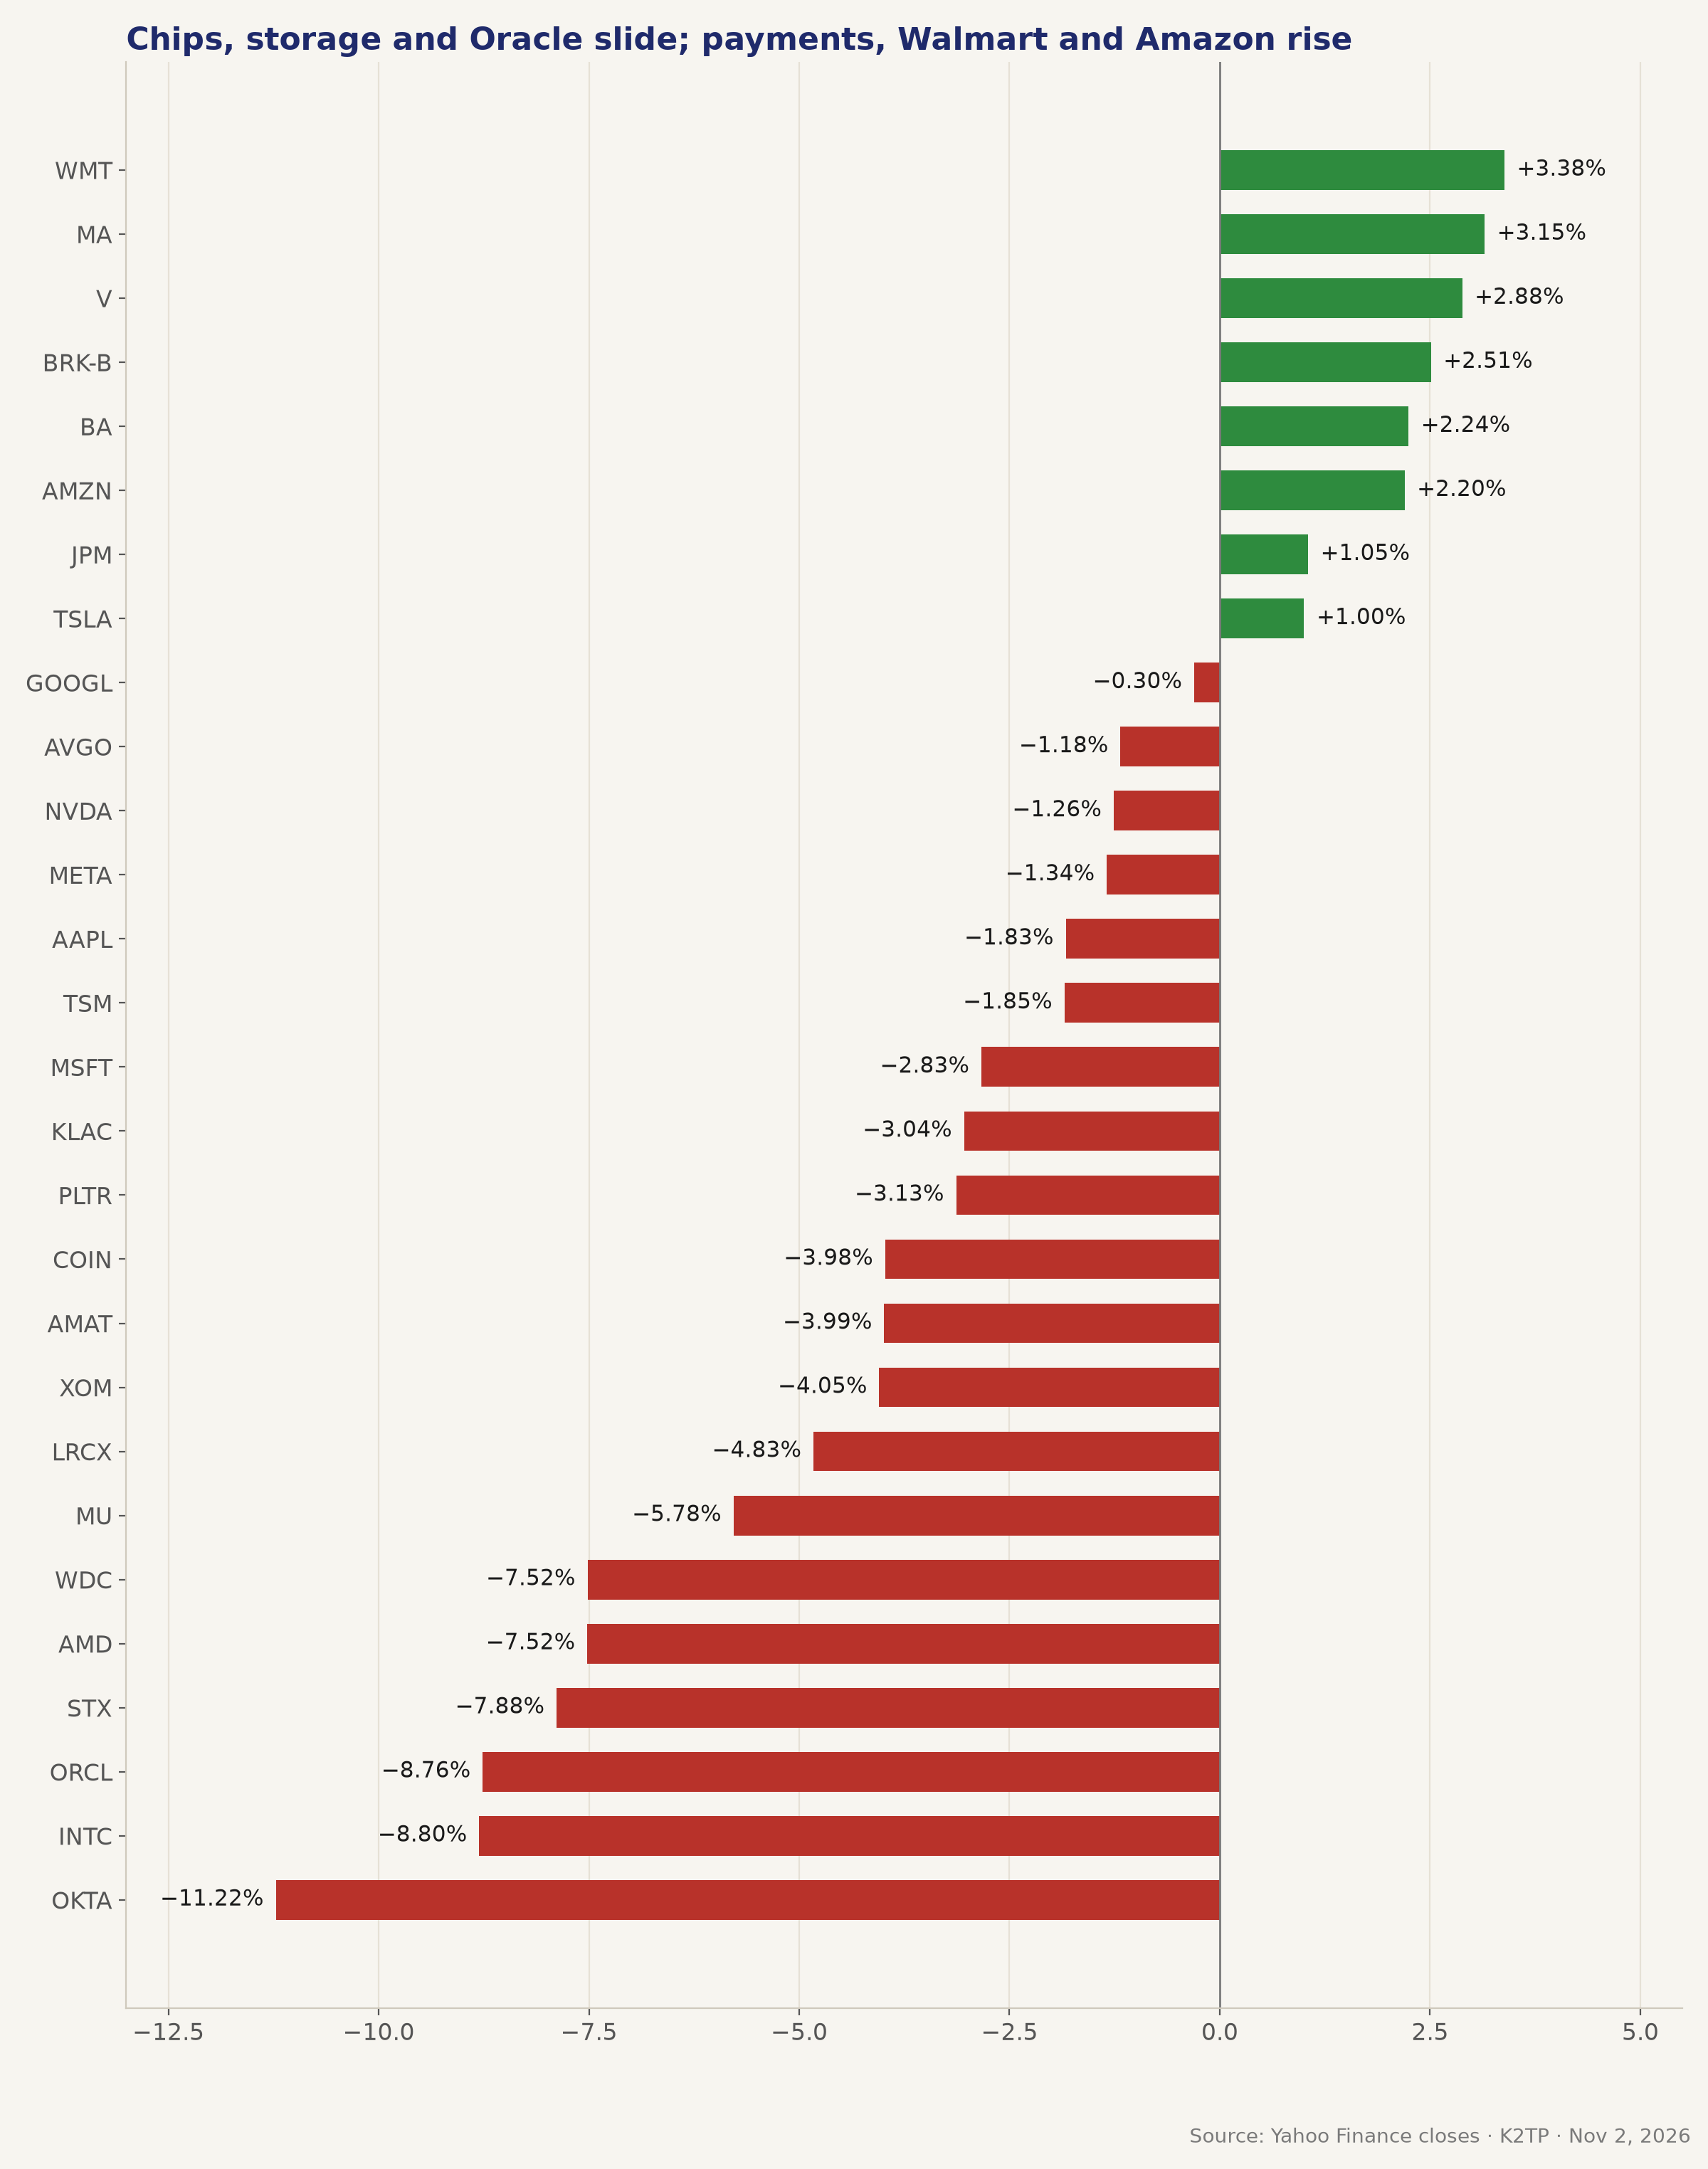
- SOX −3.37% to 10,328.33 (range 10,300.98–10,890.94), SOXX −3.79%; INTC −8.80% to 59.97, AMD −7.52% to 466.84, MU −5.78%, LRCX −4.83%, AMAT −3.99%, KLAC −3.04%, ARM −4.46%, TSM −1.85%
- Storage and software also fell: STX −7.88%, WDC −7.52%, OKTA −11.22% (set to join the S&P 500 in place of Kenvue), MSFT −2.83%, PLTR −3.13%, COIN −3.98%
- ORCL −8.76% to 119.22 even though its $10B share sale reportedly drew excess demand; Meta plans a dollar and euro bond sale of at least $20B; Anthropic plans a UK retail IPO alongside its US offering, and per the WSJ its investors are pushing for a valuation near $1.5T
- The pre-close brief found no single headline behind the chip move; the likely driver is the supply of AI-related paper
- FinancialJuice relayed Bloomberg's wrap that the Nasdaq 100 entered a correction as the chip selloff offset the oil slump
→ Chips are not reacting to earnings anymore but to funding: each new equity or bond deal tied to AI pulls money out of the hardware leaders. NDX −1.39% vs RSP +0.76% shows the damage is concentrated.
APPLE BEATS, BUT THE MARGIN GUIDE WEIGHS AFTER HOURS
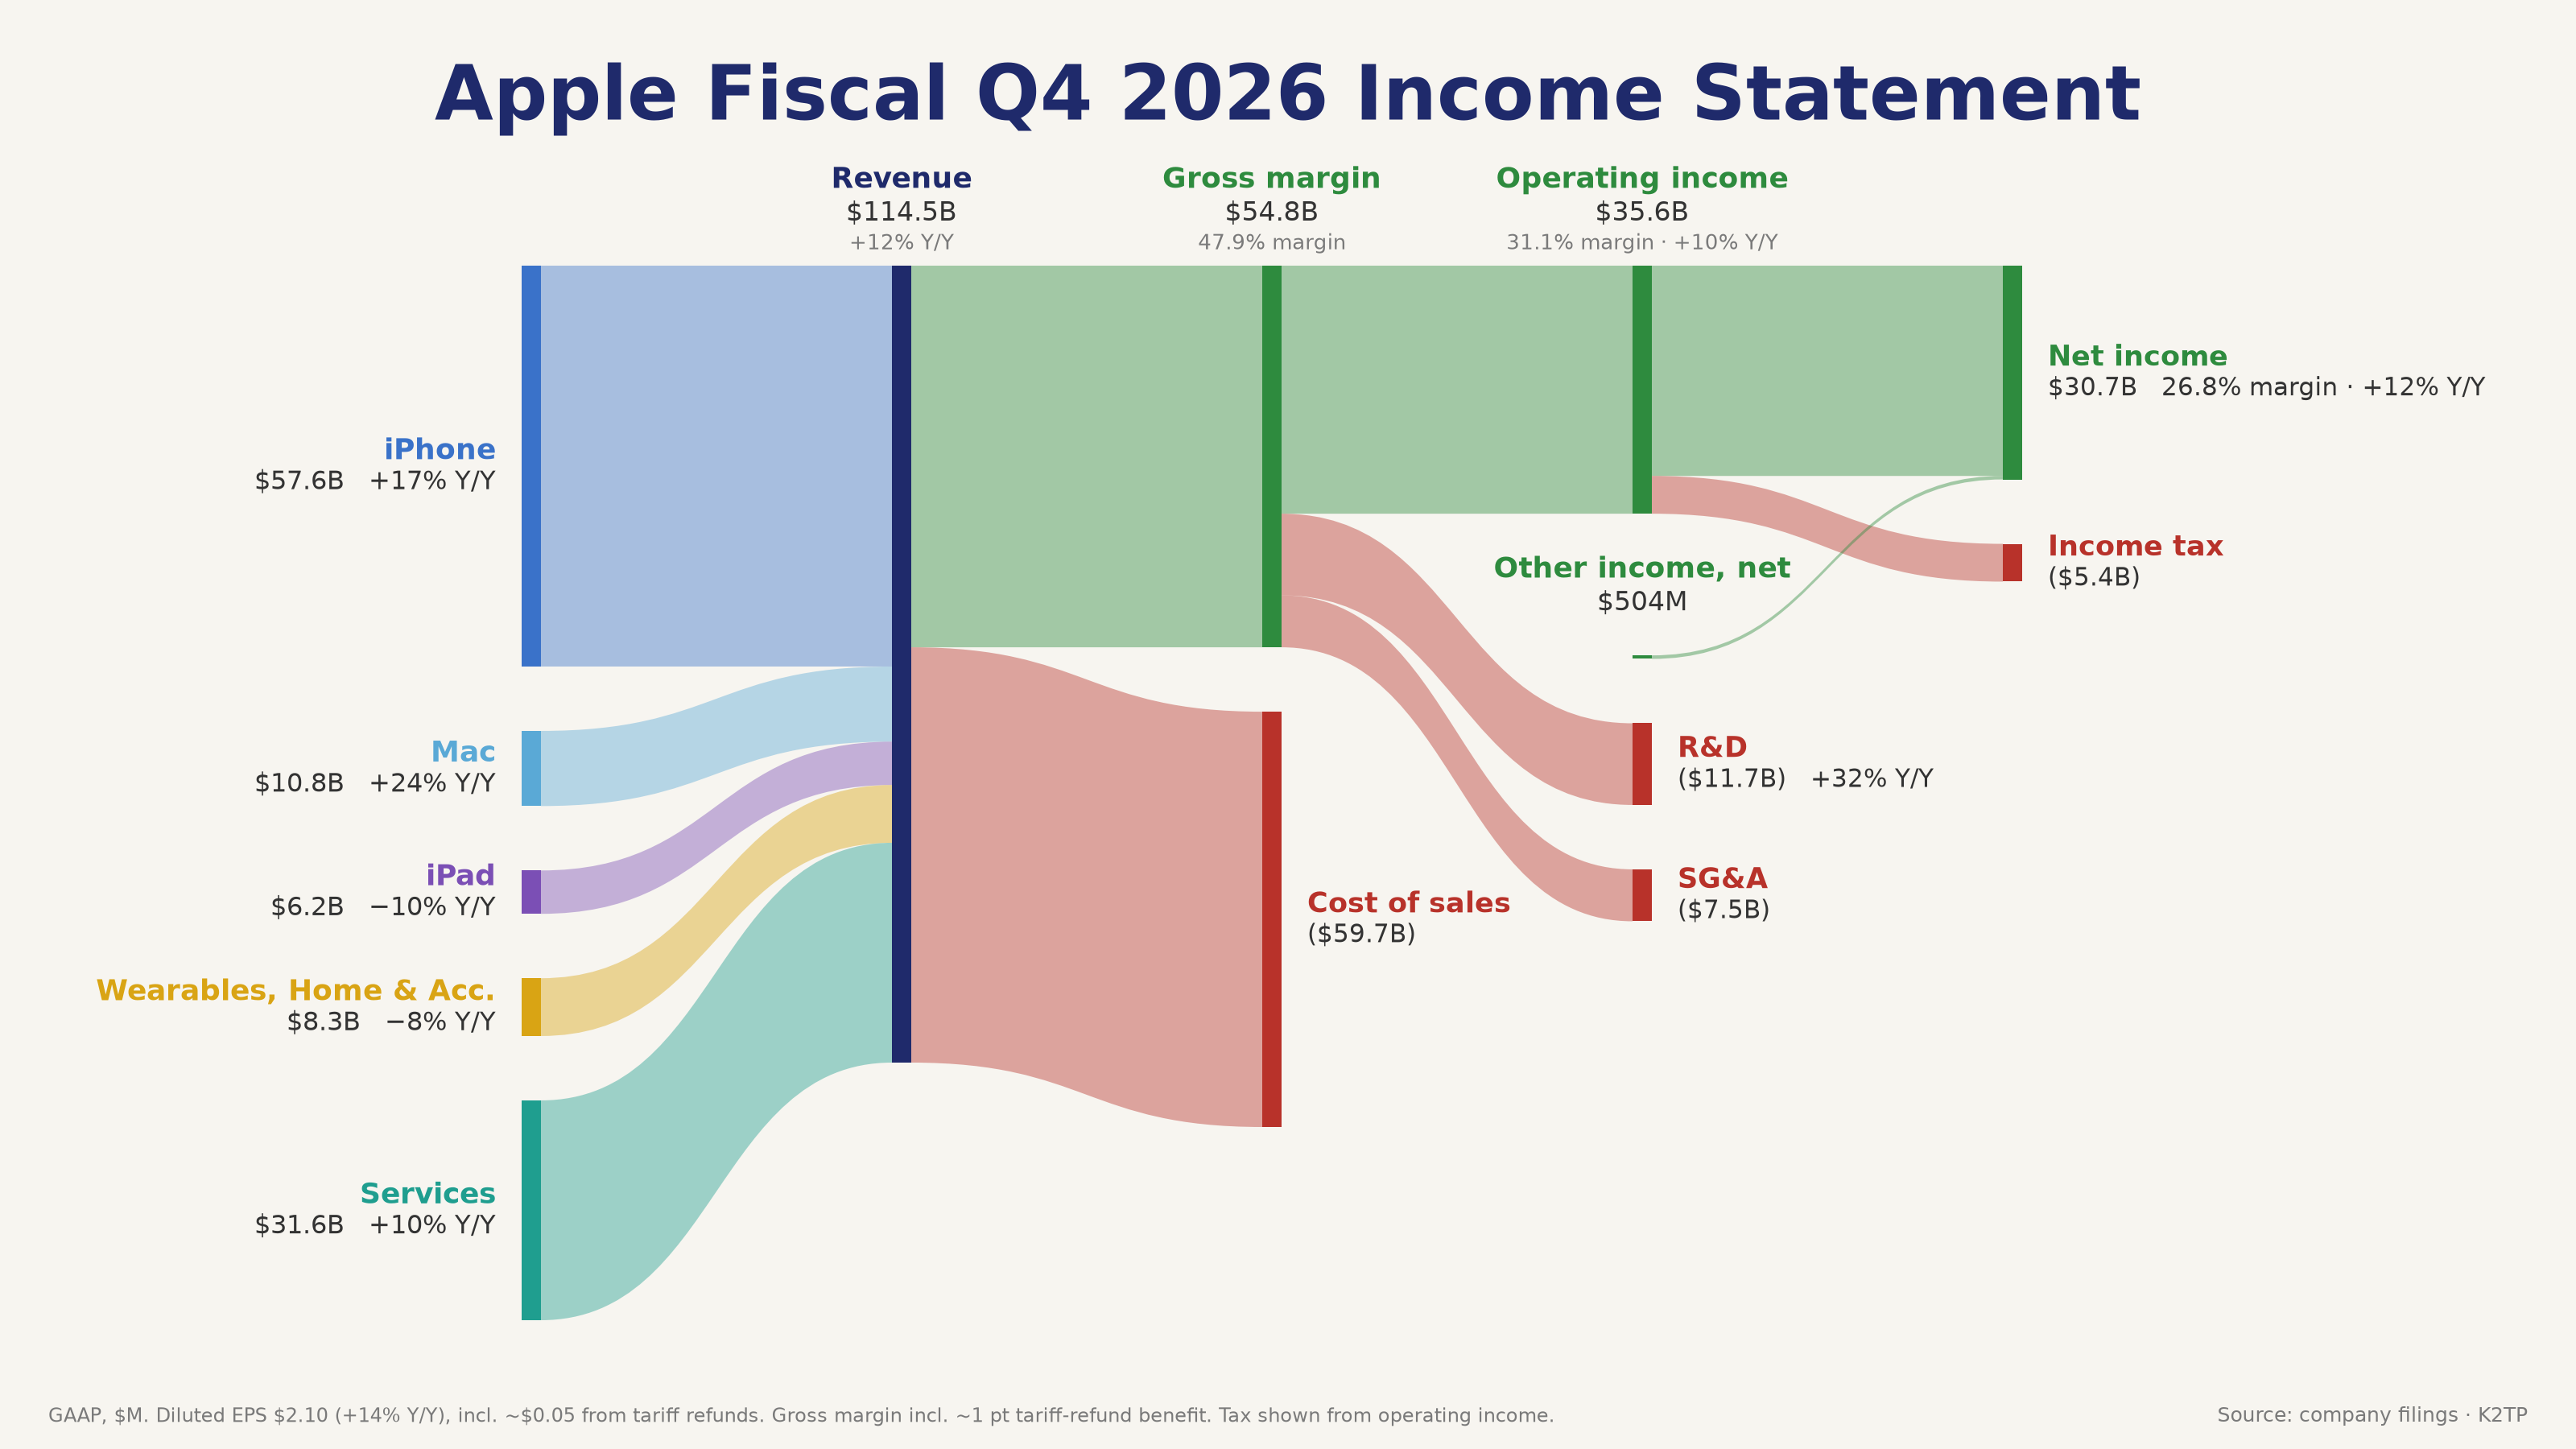
- Apple (8-K Ex. 99.1, fiscal Q4 2026): revenue $114.48B (+12% Y/Y) vs $113.39B expected; diluted EPS $2.10 (+14%) vs $1.99, including about $0.05 from tariff refunds; gross margin 47.9%, including about 1 point from tariff refunds 🟡
- iPhone $57.58B (+17% Y/Y) vs $56.54B, Mac $10.79B vs $9.61B, Services $31.57B (+10%); iPad $6.23B vs $6.7B and Wearables, Home and Accessories $8.3B vs $9.06B missed
- Operating income $35.63B (31.1% margin), R&D $11.73B (+32% Y/Y), net income $30.71B; dividend $0.27 per share
- December-quarter guide: revenue growth 7%–10%, gross margin 45%–46% vs 46.3% expected, Services growth 8%–9%; the CFO said memory costs will keep rising, and purchase obligations rose $33B in the quarter
- AAPL closed −1.83% at 338.32, rose to about $340 after the release, fell as low as $323.33 during the call and ended extended hours at $328.81 (−2.81%)
- Read-through: MU, KLAC and AMAT rose after hours on Apple's memory comments (MU +0.69%, KLAC +1.43%, AMAT +1.08%)
- Palantir: adj. EPS $0.44 vs $0.41, revenue $2.31B vs $2.17B, Q4 revenue guide $2.65B vs $2.46B, yet PLTR −3.00% after hours; FN +10.42%, LSCC +8.69%, UPWK +11.63%, CLX +2.30%, BMRN −5.12%
→ Apple's beat is real, but the margin guide confirms that memory costs are now hitting the biggest buyers. That same pricing power is what supports MU and the equipment names after hours.
OIL DROPS 7% ON IRAN DIPLOMACY, THEN QESHM HEADLINES
- Pre-market: WTI −4.30% to $99.64 after Sunday's Doha talks and a draft proposal; Pezeshkian said the Supreme Leader granted negotiating authority; Iran said Hormuz cannot reopen before sanctions are lifted; Goldman raised its December Brent forecast to $105 🟢
- WTI settled at $96.46 (−7.36%) and Brent at $104.77 (−7.63%); Trump said Iran wants to make a deal, oil will go lower, there is no rush to restart the war, and answered "No" to striking Iran after the elections; Qatari mediators headed to Tehran
- VP Vance said at 12:24 PM PT that he feels good about deal prospects; from 1:04 PM PT, Iranian media reported explosions on Qeshm Island, and at 4:42 PM PT the WSJ reported a US strike on Qeshm; the IRGC said it captured 2 US drones (unconfirmed)
- WTI is little changed tonight at $96.31 (−0.16%); gold about $3,954, DXY about 101.9, BTC about $76,890
- XLE −3.96%, XOM −4.05%, CVX −3.29%; consumer and transport names benefited
→ Oil below $100 takes pressure off inflation and supports the consumer, but the Qeshm headlines show the risk is still two-sided. So far the market is not treating the strike as a break in the talks.
ISM BEATS WITH SOFTER PRICES; A BULL FLATTENER
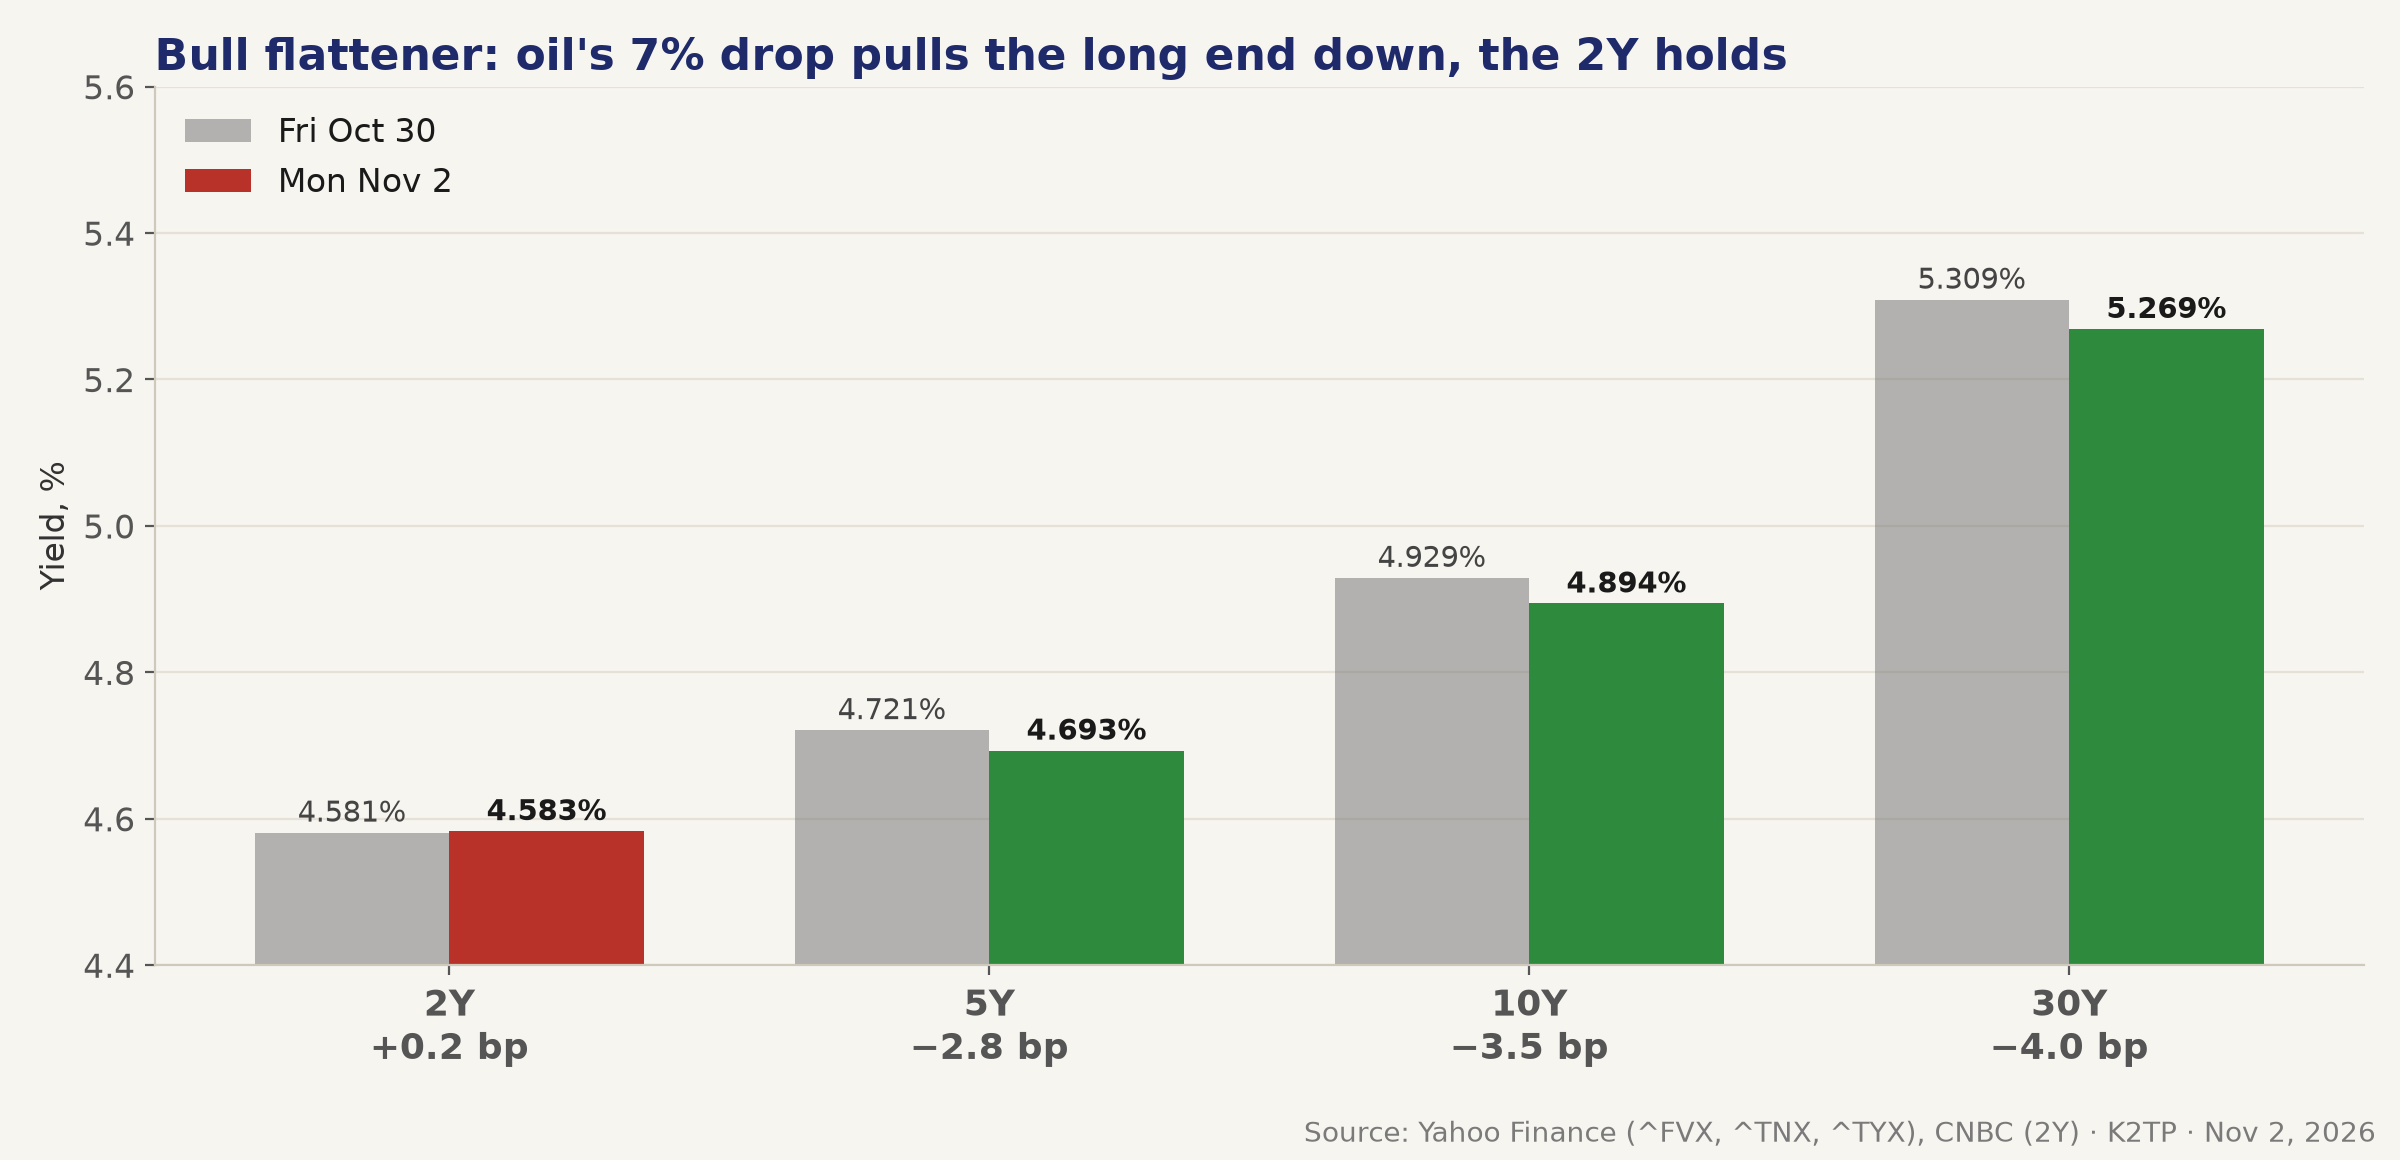
- 7:00 AM PT: ISM Manufacturing 55.5 vs 54.5 expected and prior; new orders 55.5, employment 52.4; prices paid 75.2 vs 77.2 expected and 77.9 prior 🟢
- S&P Global final manufacturing PMI 54.9 vs 56; construction spending −1.9% vs +0.3% expected
- Treasury raised its quarterly privately held net borrowing estimate to $739B, $87B above the May projection on a like-for-like basis (FinancialJuice, unconfirmed)
- Bill auctions: 3-month 4.040%, 6-month 4.150%
- Closing yields: 2Y 4.583% (+0.2 bp, CNBC), 5Y 4.693% (−2.8 bp), 10Y 4.894% (−3.5 bp), 30Y 5.269% (−4.0 bp); 2s10s flattened from 34.8 bp to 31.1 bp; tonight the 10Y is back near 4.915%
- Updated FedWatch probabilities: unavailable
→ The long end follows oil lower, but the 2Y holding near 4.58% says the market is not pricing a quicker Fed turn. JOLTS on Tuesday and Friday's payrolls matter more for the front end.
ROTATION: CONSUMER, FINANCIALS AND THE DOW RISE
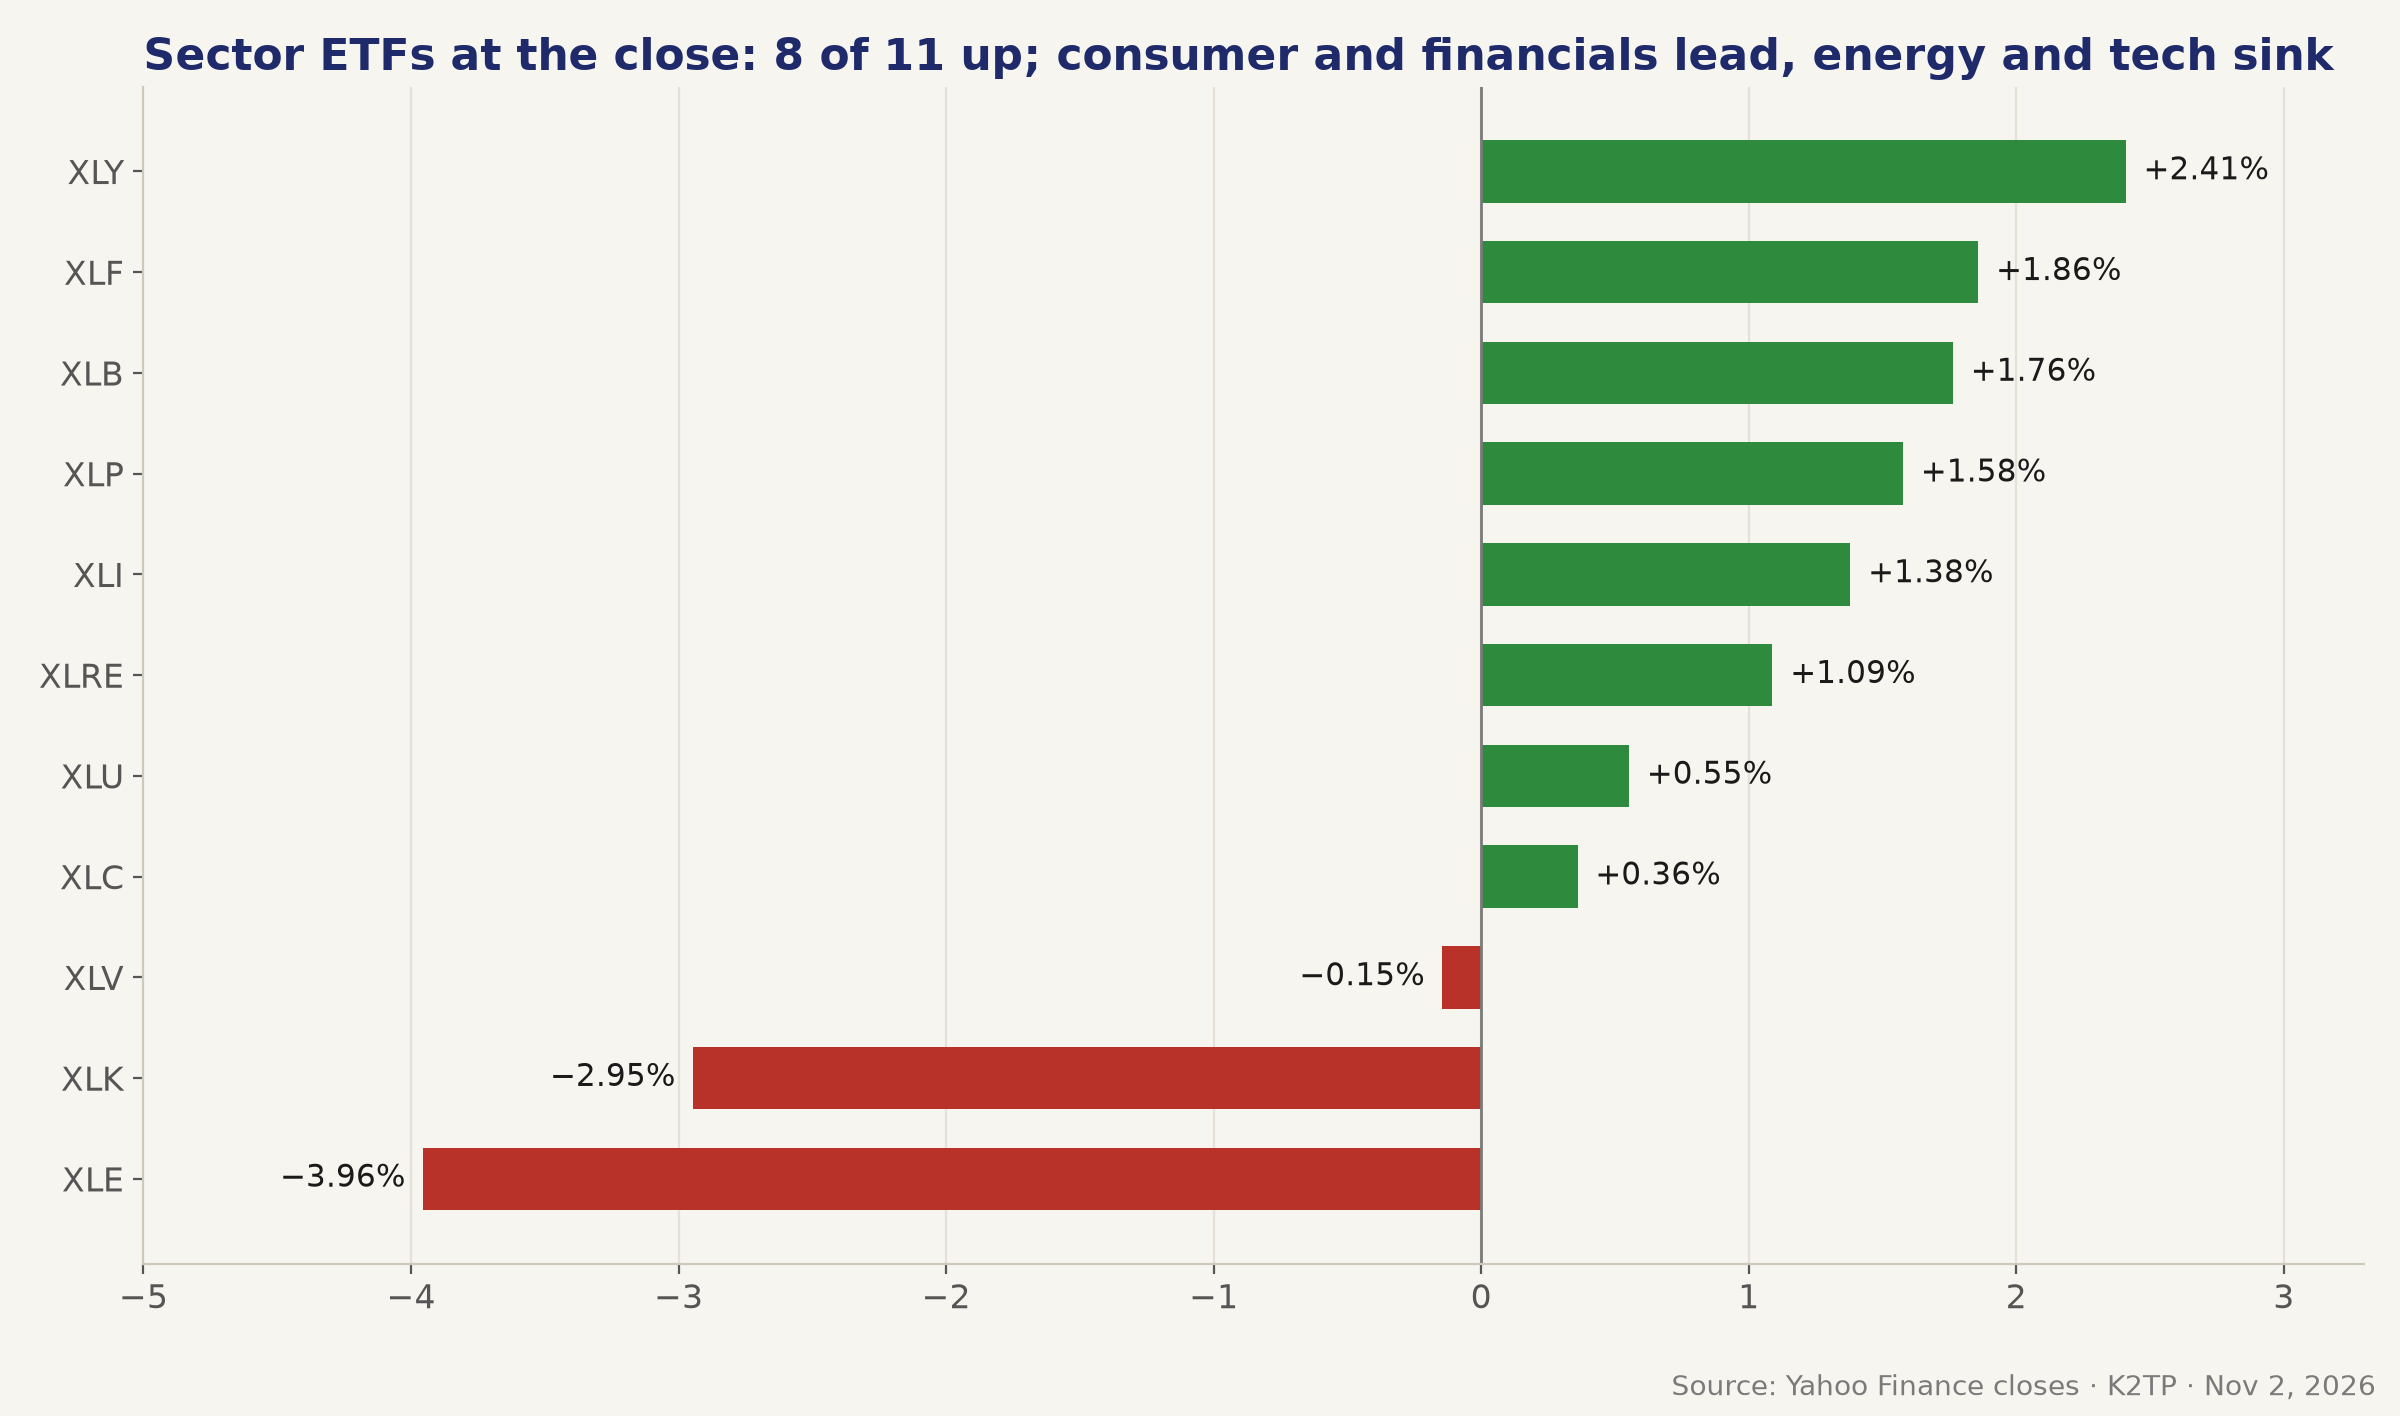
- 8 of 11 sector ETFs rose: XLY +2.41%, XLF +1.86%, XLB +1.76%, XLP +1.58%, XLI +1.38%, XLRE +1.09%, XLU +0.55%, XLC +0.36%; XLV −0.15%, XLK −2.95%, XLE −3.96% 🟡
- Payments and value names led: MA +3.15%, V +2.88%, WMT +3.38%, BRK-B +2.51%, BA +2.24%, JPM +1.05%
- AMZN +2.20% to 245.63 (up as much as 4.53% at midday), TSLA +1.00%
- NYSE advancers led decliners 2.97:1 at midday and Nasdaq 1.78:1; Fear & Greed at 30
- The MOC imbalance showed about $1.19B to buy for the S&P 500
→ Money is rotating out of AI hardware rather than leaving equities. Breadth is fine, but cap-weighted SPX keeps losing to chips and mega-caps.
SPX: HIGH AFTER ISM, LOW AT THE CLOSE
- Pre-market: ES +0.32% (7,638.25), NQ +0.57%; implied SPX near 7,604, above the 7,590.19 Bull line with VIX 19.45
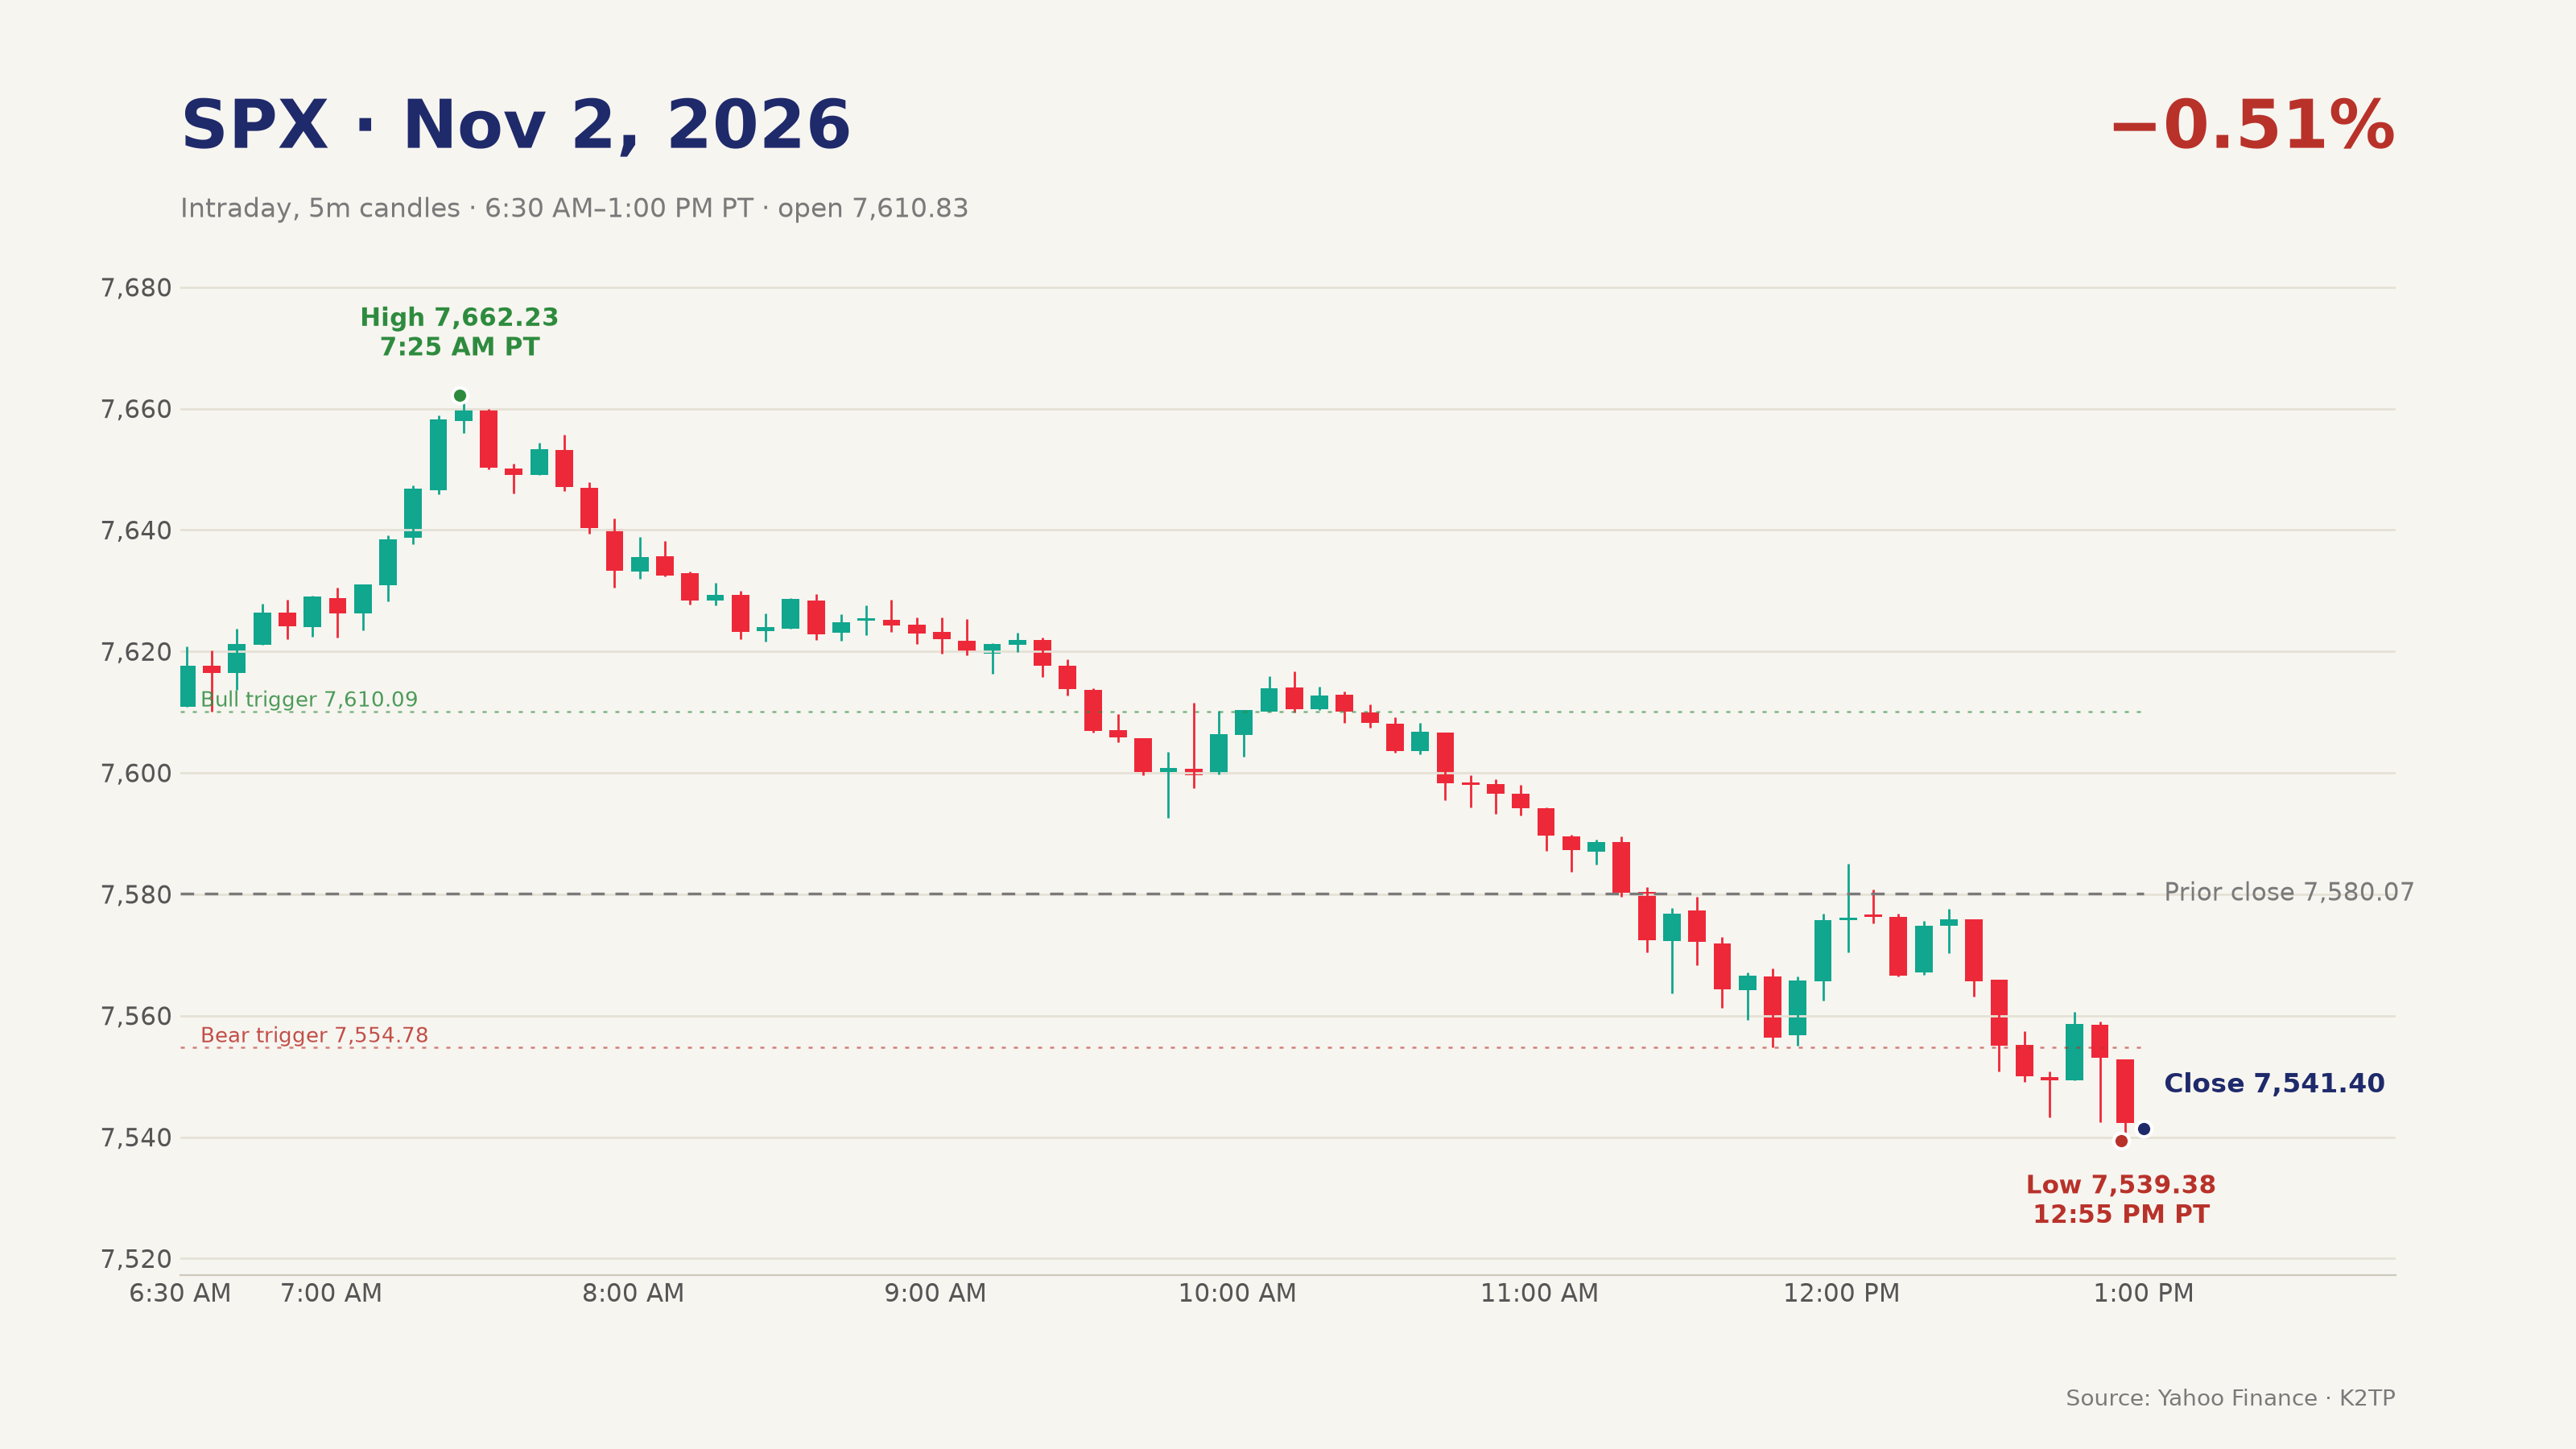
- SPX opened at 7,610.83 and hit its 7,662.23 high at 7:25 AM PT after ISM, above Friday's 7,637.48 high, with VIX at an 18.03 low; the pre-market Bull confirm was reached but did not hold
- At midday SPX was 7,619.91 (+0.53%); at pre-close 7,568.48 (−0.15%), back under Friday's 7,580.07 close
- SPX fell into the close to a 7,539.38 low at 12:55 PM PT and closed at 7,541.40; VIX printed a 21.77 high
- The pre-close Bear line (SPX under 7,554.78 with VIX above 21.58) was largely met; the Bull line (SPX above 7,610.09 with VIX under 19.56) was not
→ A 121-point reversal from the post-ISM high to the close, with no late bounce, is a weak signal into Tuesday. Friday's 7,527.56 low is the next support.
MARKET: CHIPS DRAG SPX TO ITS LOW WHILE BREADTH HOLDS UP
Indices (close):
- SPX 7,541.40 (−0.51%), range 7,539.38–7,662.23
- NDX 27,989.82 (−1.39%); Nasdaq Composite 25,164.36 (−1.07%)
- DJIA 51,983.98 (+0.41%)
- RUT 2,805.88 (−0.21%)
- RSP 219.98 (+0.76%)
- SOX 10,328.33 (−3.37%)
Intraday path: ES +0.32% pre-market on Iran diplomacy. SPX opened at 7,610.83, peaked at 7,662.23 at 7:25 AM PT after ISM, was at 7,619.91 at midday and 7,568.48 at pre-close, then fell to 7,539.38 at 12:55 PM PT and closed at 7,541.40.
Sector rotation:
- Up: XLY +2.41%, XLF +1.86%, XLB +1.76%, XLP +1.58%, XLI +1.38%, XLRE +1.09%, XLU +0.55%, XLC +0.36%
- Down: XLV −0.15%, XLK −2.95%, XLE −3.96%
- Mega-caps: AMZN +2.20%, TSLA +1.00%, GOOGL −0.30%, AVGO −1.18%, NVDA −1.26%, META −1.34%, AAPL −1.83%, MSFT −2.83%, AMD −7.52%, ORCL −8.76%, INTC −8.80%
Market internals:
- RSP +0.76% vs SPX −0.51%, a 127 bp gap; SPY −0.48%, QQQ −1.36%, IWM −0.07%
- 8 of 11 sectors up, from 9 of 11 at pre-close
- NYSE advance/decline at the close: unavailable (2.97:1 at midday)
Volatility: 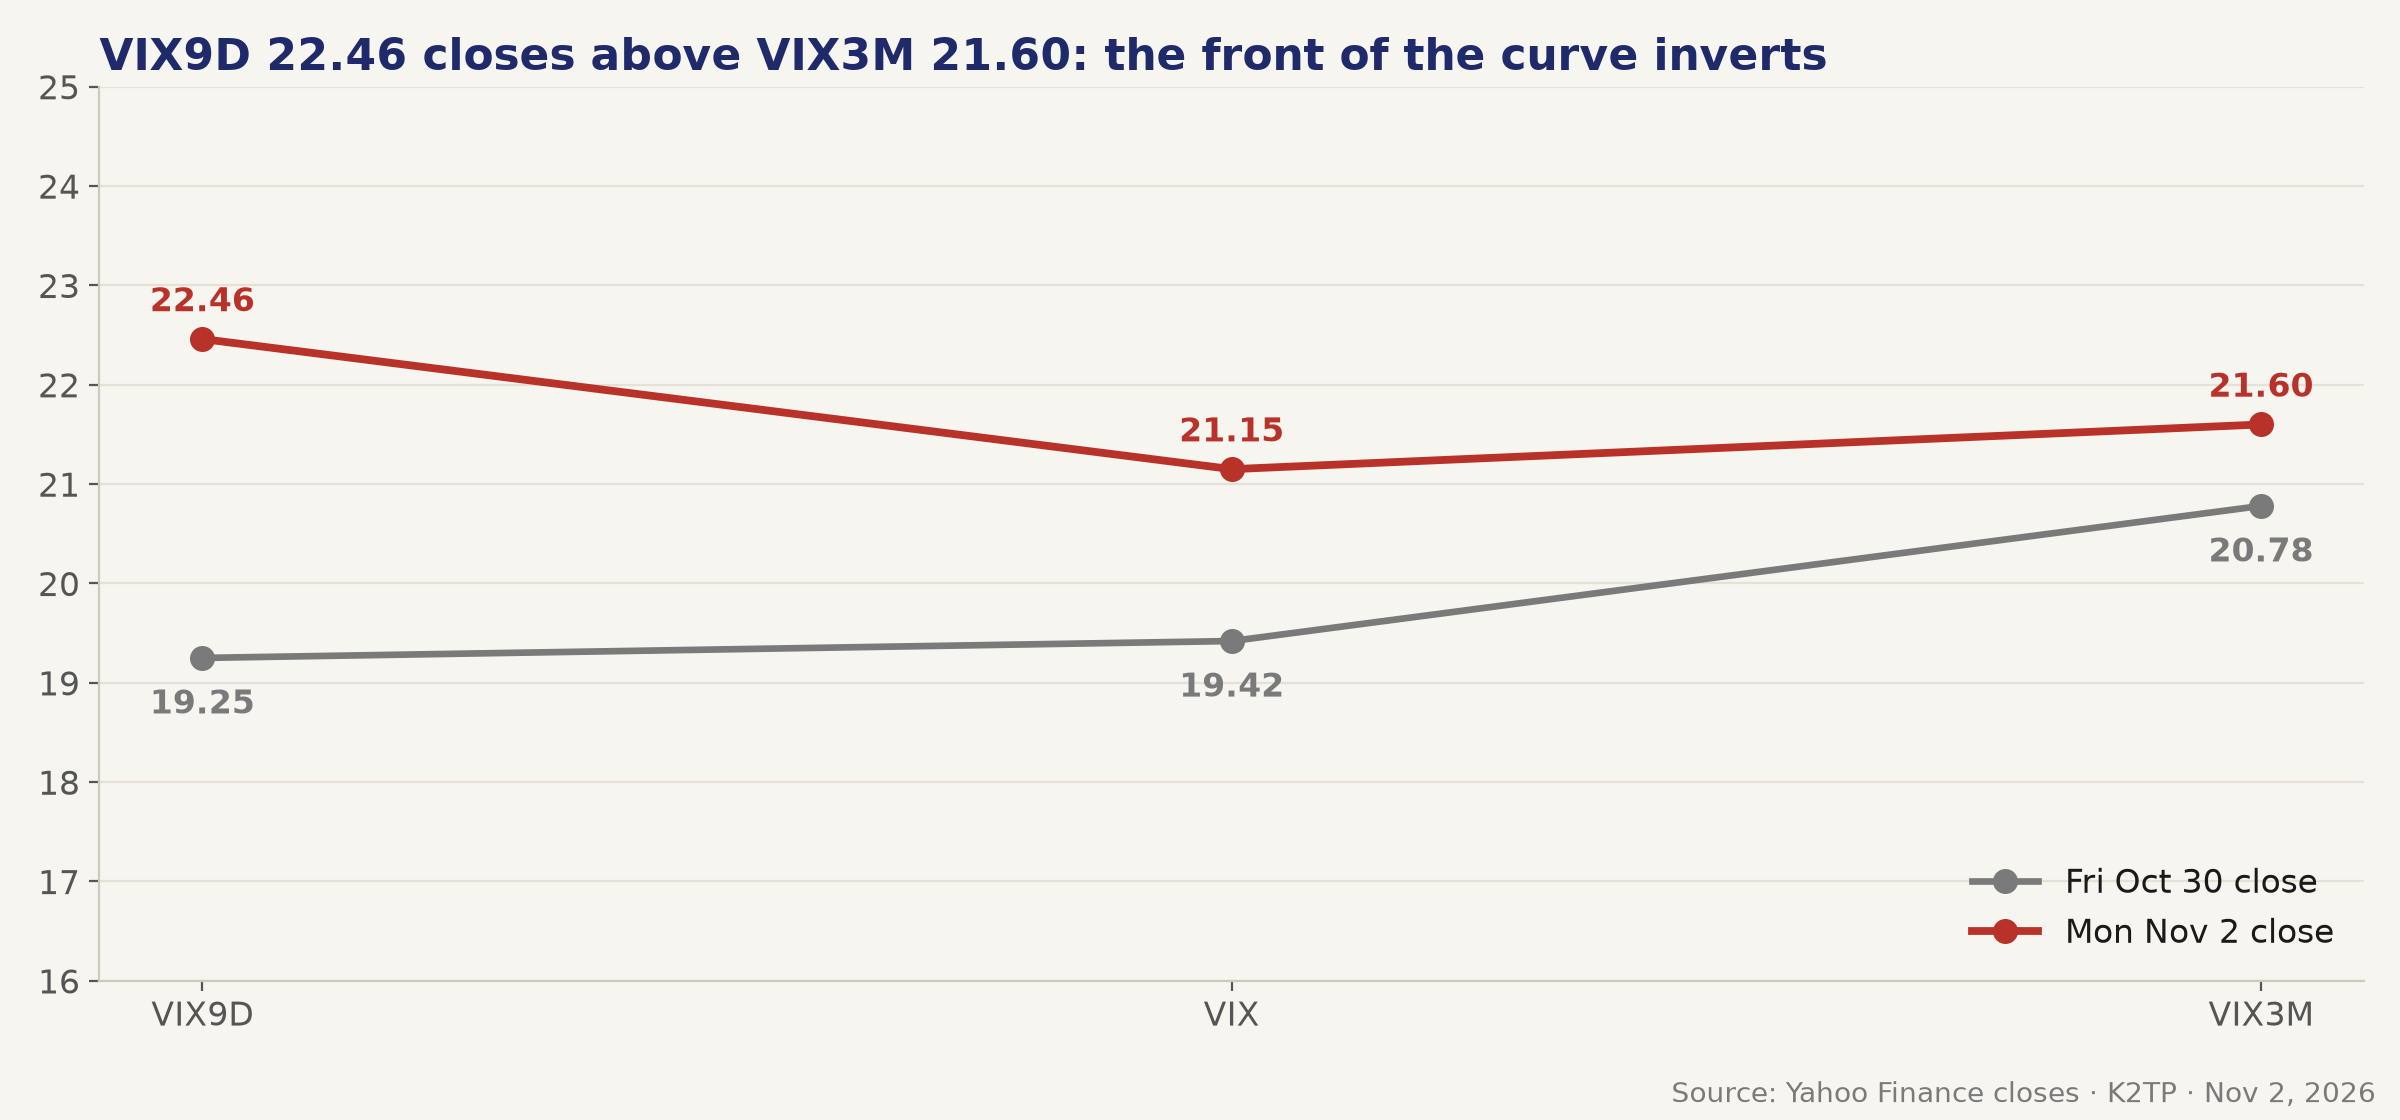
- VIX 21.15 (+8.91%), range 18.03–21.77
- VIX9D 22.46, VIX3M 21.60: the front of the curve closed inverted
- VVIX 110.47 (high 111.85)
- Gamma levels: unavailable
Cross-asset:
- 2Y 4.583%, 5Y 4.693%, 10Y 4.894%, 30Y 5.269%
- WTI settled $96.46 (−7.36%), Brent $104.77 (−7.63%)
- Gold about $3,954; DXY about 101.9; BTC about $76,890
Global:
- Asia (Monday): Kospi +2.24%, Shanghai +1.08%, Hang Seng +0.42%, Nikkei −0.33%; China manufacturing PMI 52.0
- Europe: Euro Stoxx 50 +0.73%, DAX +0.63%, CAC 40 +0.98%, FTSE 100 +0.29%
- Tonight: Kospi −2.32%, Japan closed for a holiday; the PBOC raises the FX deposit reserve ratio from 4% to 6% from November 15, and the offshore yuan fell 0.26% to 6.6642
Key SPX levels:
- 7,662.23: Monday's high
- 7,610.09–7,610.83: midday low and the open, now resistance
- 7,580.07: Friday's close; reclaiming it with VIX under 19.42 moves the read to TRANSITION
- 7,541.40 / 7,539.38: Monday's close and low
- 7,527.56: Friday's low; a break with VIX above 21.77 deepens RISK-OFF
- ES 7,580.25 tonight implies SPX near 7,547
- VIX: 19.42 and 21.77
Option seller corner:
- Bull scenario: AAPL's drop gets bought, JOLTS keeps the 10Y under 4.95%, and SPX reclaims 7,580.07 with VIX under 19.42; the regime eases to TRANSITION. Add far-OTM SPX put spreads only after the first election results.
- Bear scenario: SPX breaks 7,527.56 with VIX above 21.77 as chips keep falling into AMD. Keep short-put size small, use defined-risk spreads only and avoid single-name chips before AMD reports.
- VIX9D above VIX3M means short-dated protection is priced richer than three-month protection. Premium is fatter, but Tuesday combines JOLTS, the election and AMD, so size for gap risk and favor expirations after the event.
- Favor broad underlyings such as SPX or RSP over NDX; financials, consumer and industrials are holding, chips are not.
BOTTOM LINE
- Chips sold off for a second day on AI funding supply: SOX −3.37%, NDX −1.39% and into a correction, SPX −0.51% to 7,541.40 at its low.
- Oil's 7% drop on Iran diplomacy fed a rotation into consumer, financials and the Dow and a bull flattener, but did not save the index.
- Regime 🔴 RISK-OFF. Apple's margin guide adds pressure after hours; 7,527.56 is the support, and 7,580.07 with VIX under 19.42 is the way back to TRANSITION.
Watch Tuesday (PT):
- All day: US midterm elections; first results after polls close in the evening
- 4:00–5:00 AM: Shopify, Pfizer, Eaton, Marathon Petroleum and Apollo report
- 7:00 AM: September JOLTS (7.11M expected vs 7.08M prior)
- After the close: AMD (call 2:00 PM PT), Amgen, Arista Networks and Booking
- Later this week: ISM Services Wednesday 7:00 AM; October payrolls Friday 5:30 AM (63K expected vs 29K prior)
- Overnight: Qeshm and Iran headlines; AAPL at the open
Bull expectation: AAPL's drop is bought, chips extend tonight's small bounce, and SPX reclaims 7,580.07 with VIX under 19.42. Bear expectation: AAPL weighs on the open, chips keep sliding into AMD, and SPX breaks 7,527.56 with VIX above 21.77.
Sources: 3 K2TP briefs for 11/2/2026 (Pre-Market, Midday, Pre-Close) and the 11/2 Evening Recap. Official closes and intraday data from Yahoo Finance; 2Y and Treasury yields from CNBC; oil settlements, news and data from Reuters, CNBC, Bloomberg, WSJ and FinancialJuice; Apple and Palantir results from CNBC and Investing.com; Apple Sankey from Apple's fiscal Q4 2026 press release (8-K Ex. 99.1), SEC EDGAR. Analysis: K2TP Framework.