Market 10/30: Intel's guide sparks the worst chip selloff since June, Fed's Logan calls for two more hikes, and SPX closes a third straight losing week at its lowest close of October
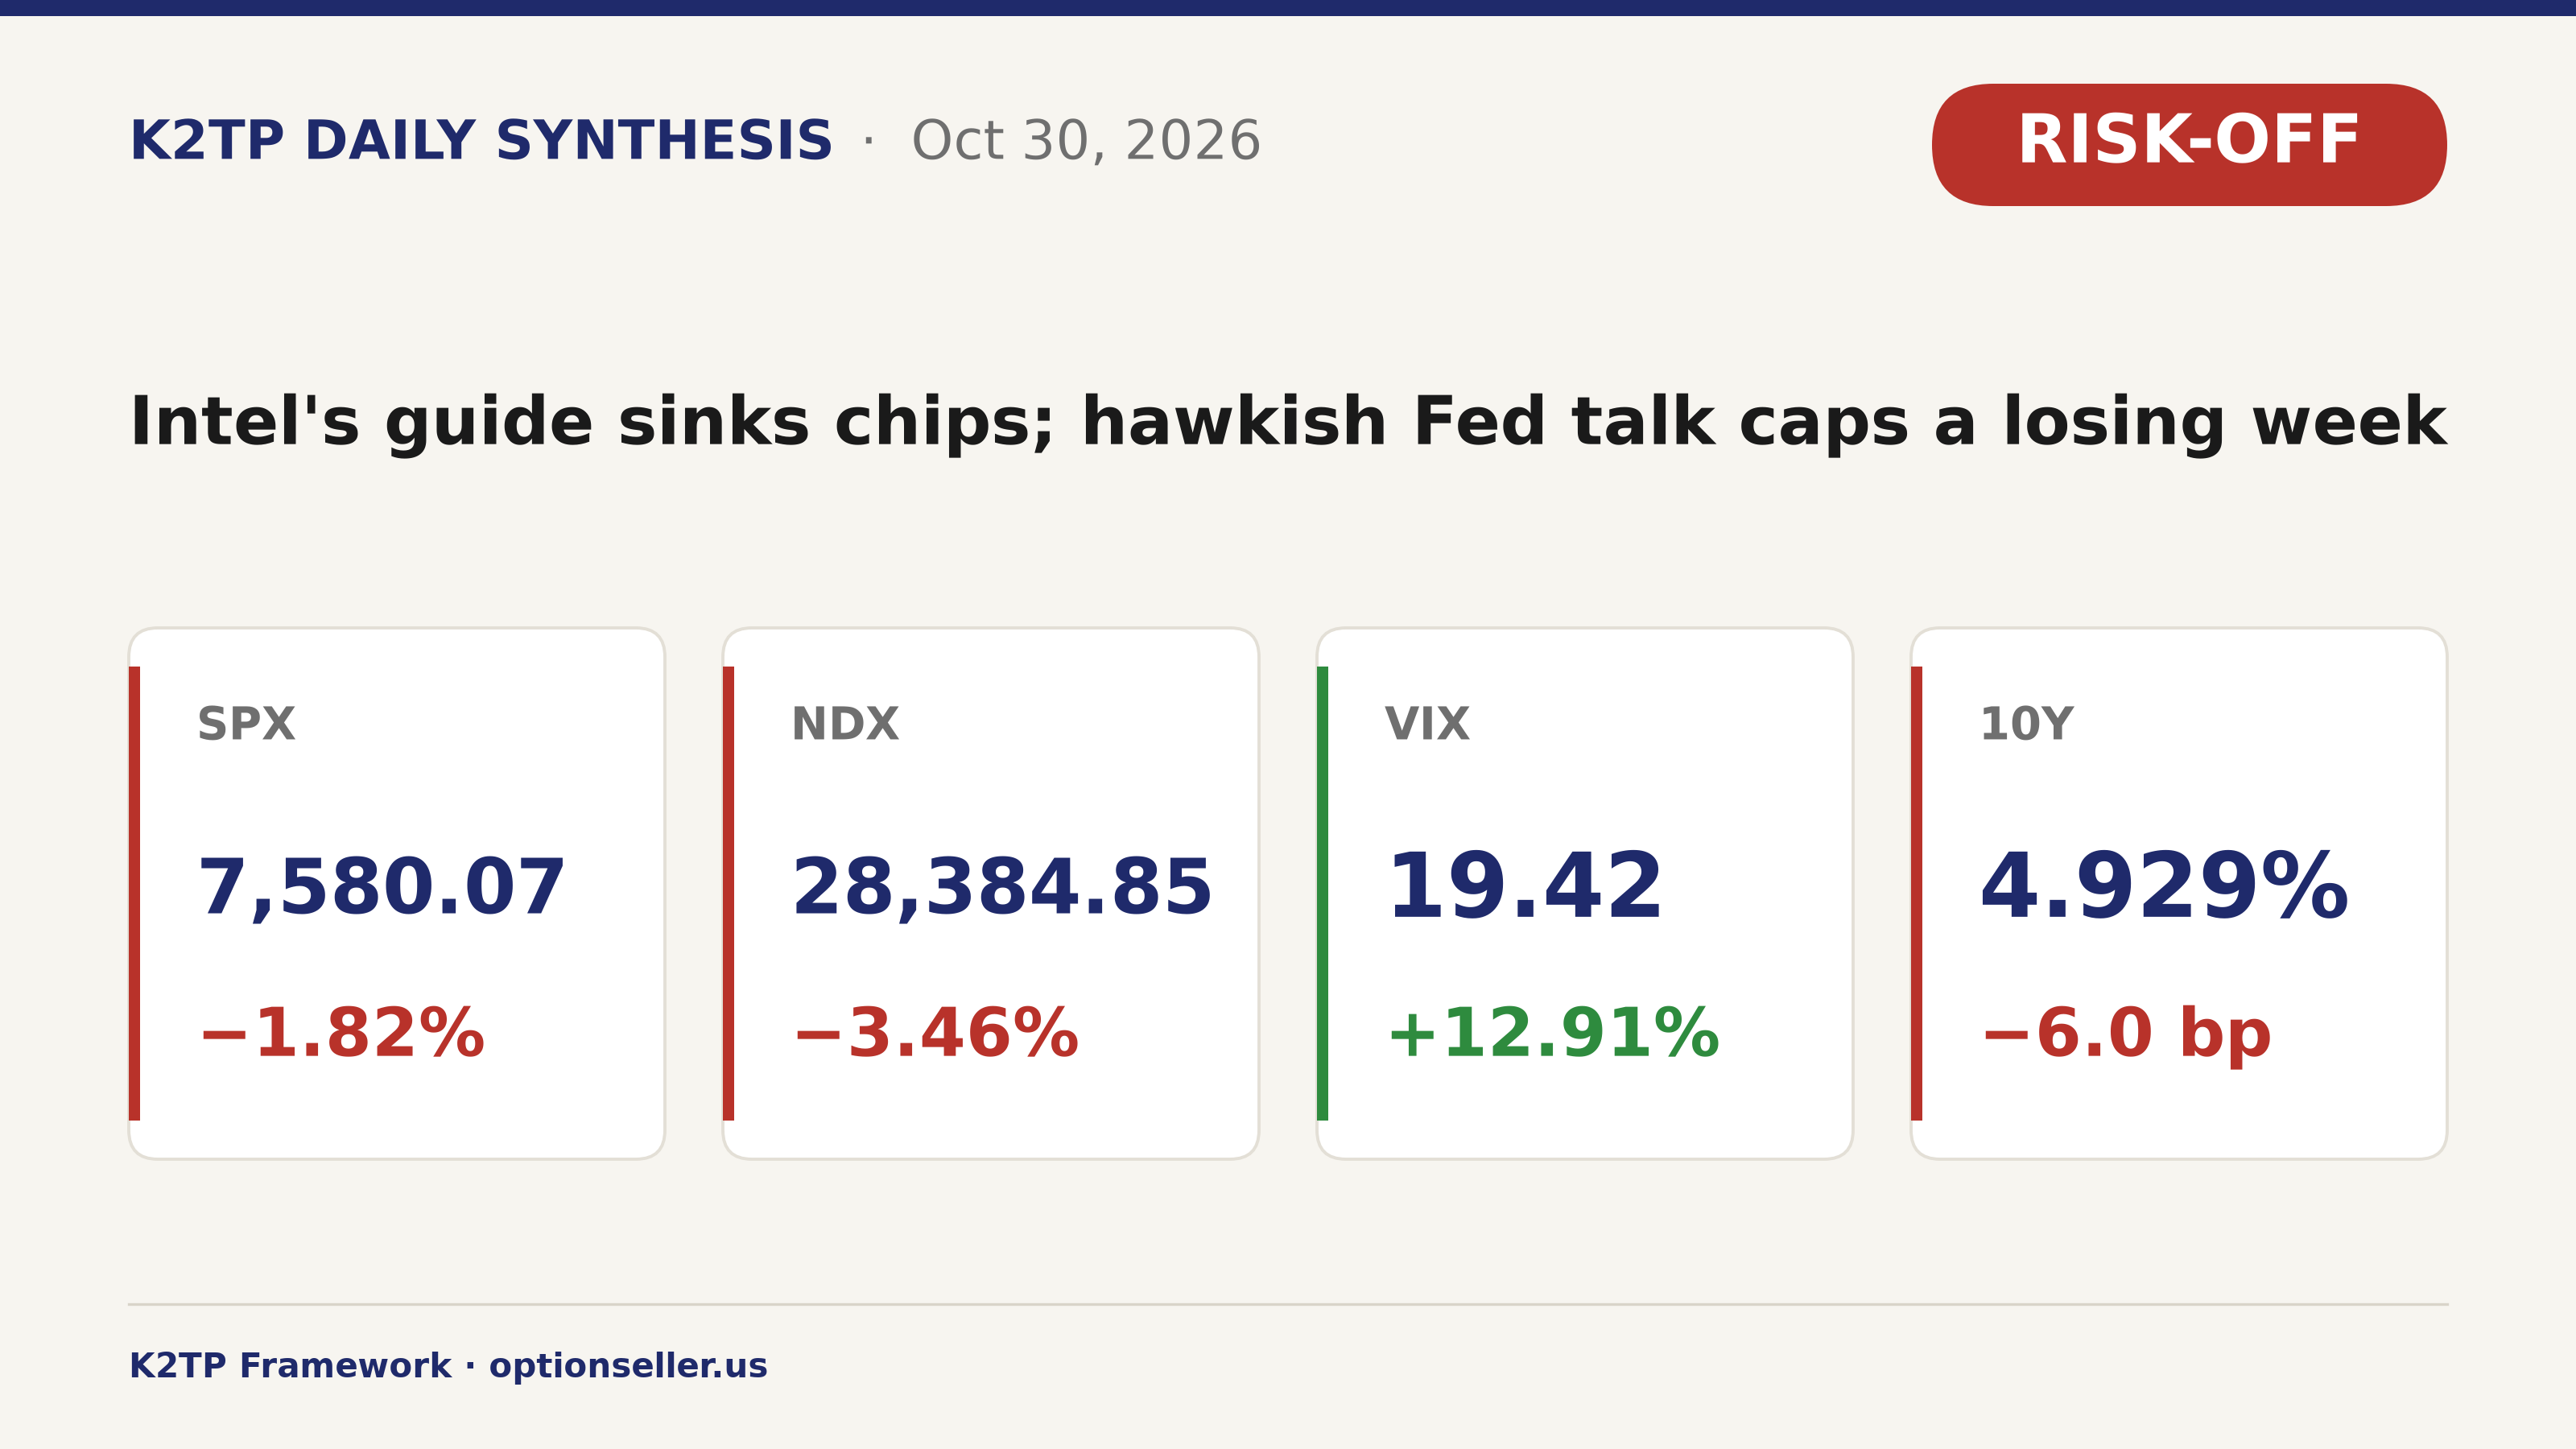
SPX −1.82%, NDX −3.46%, SOX −7.20%, DJIA −1.09%, RUT −1.66%, RSP −0.79%, VIX +12.91% to 19.42 after a 23.93 high. INTC −28.58%, RDDT −29.22%, AMD −10.88% while XLE +1.91%, XLP +1.41% and LLY +3.19%; 6 of 11 sector ETFs up. 2Y 4.59% (−6.6 bp), 10Y 4.929% (−6.0 bp). WTI settled $104.12 (+2.08%). Week: SPX −0.57%, NDX −1.98%; October: SOX −15.36%.
KEY HEADLINES
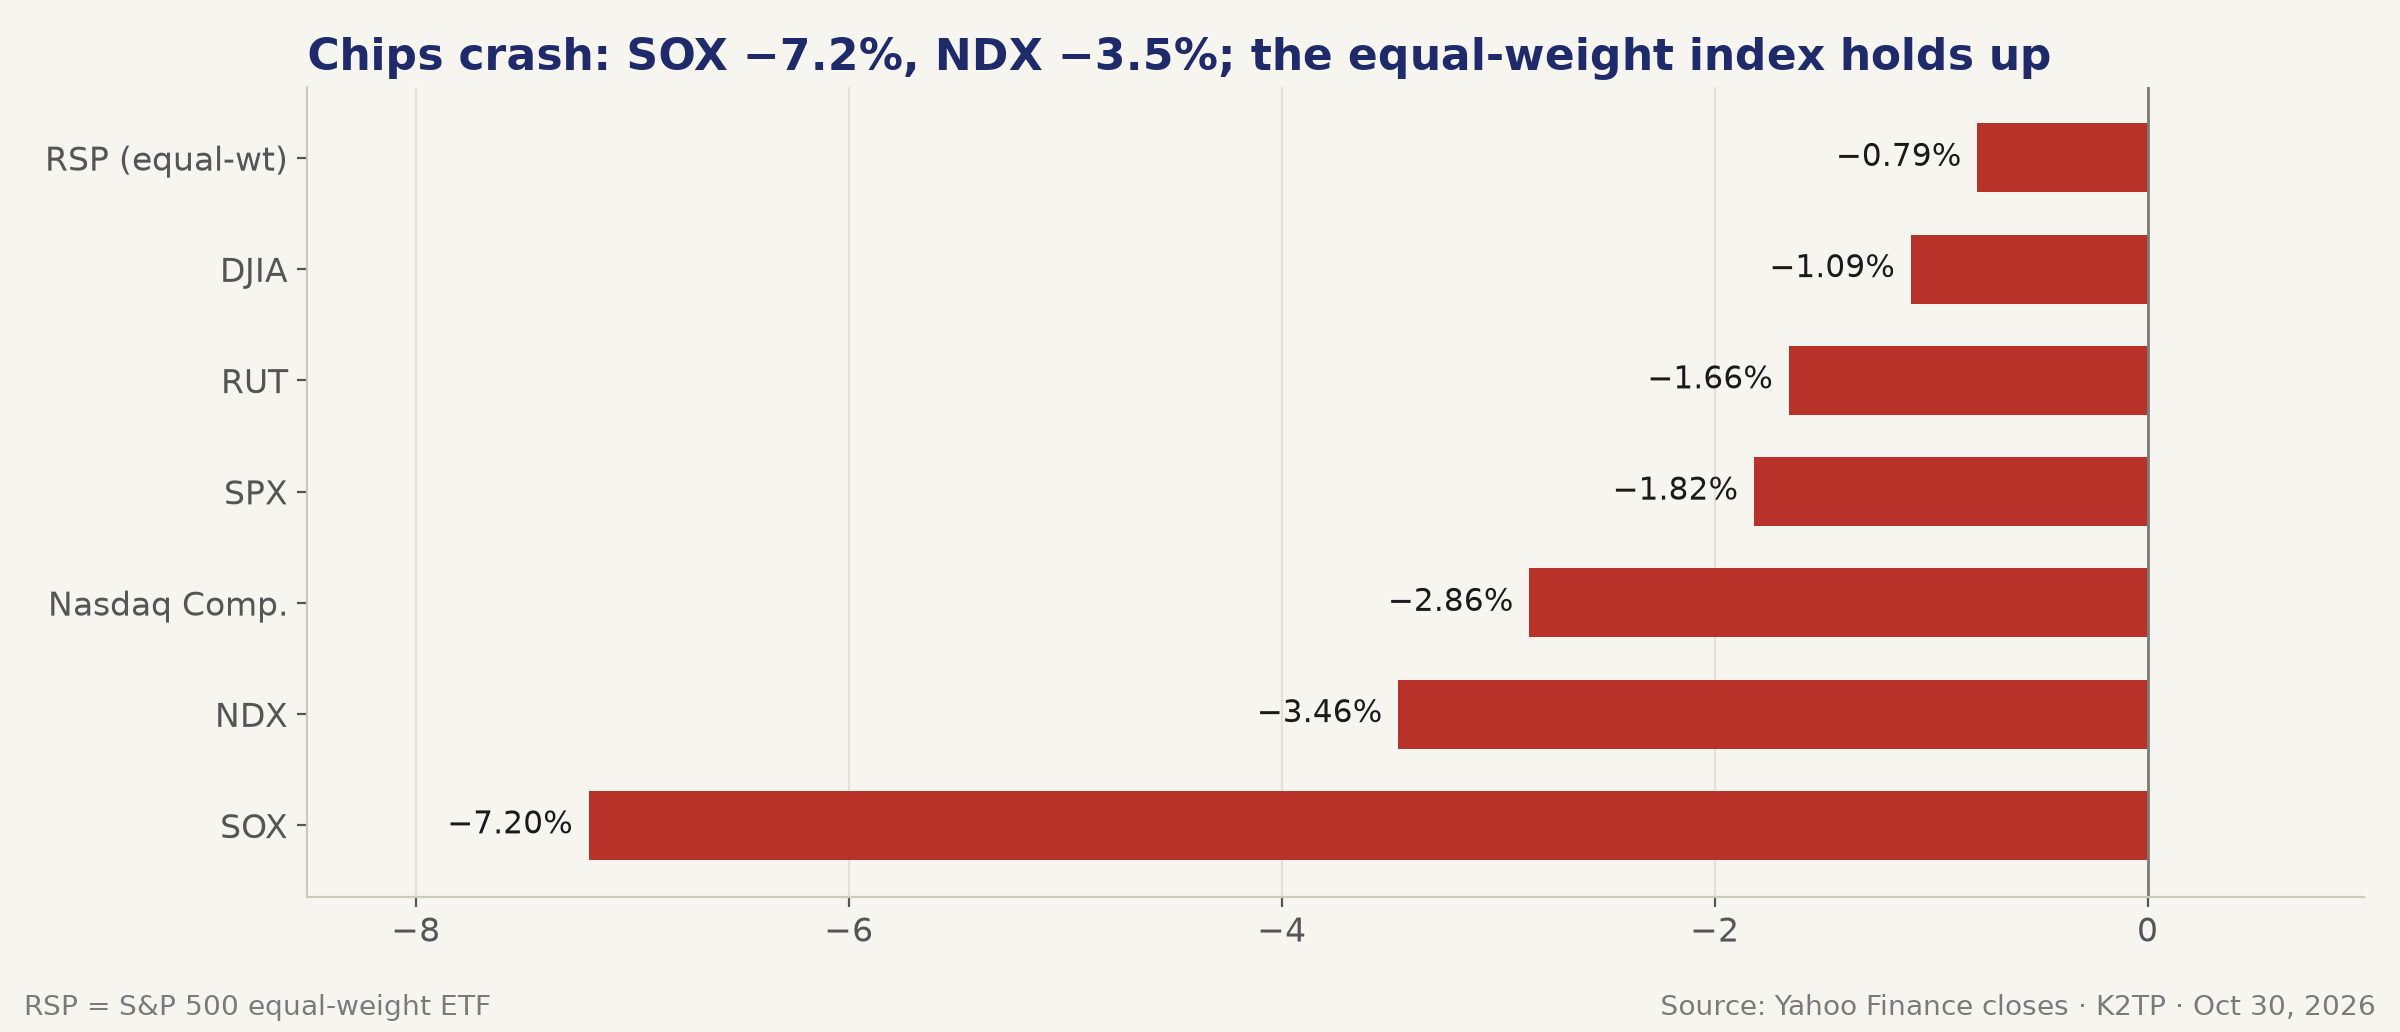
- SPX −1.82% to 7,580.07 (−140.32 pts), the worst day since June and the lowest close of October; NDX −3.46% to 28,384.85; Nasdaq Composite −2.86% to 25,437.00; DJIA −1.09% to 51,770.31; RUT −1.66% to 2,811.84
- Chips crashed: SOX −7.20% to 10,688.80 (low 10,439.01) and SOXX −8.24%; Intel −28.58% to 65.76, its worst day since the 1970s per CNBC, after a weak Q4 guide and downgrades from BofA and D.A. Davidson
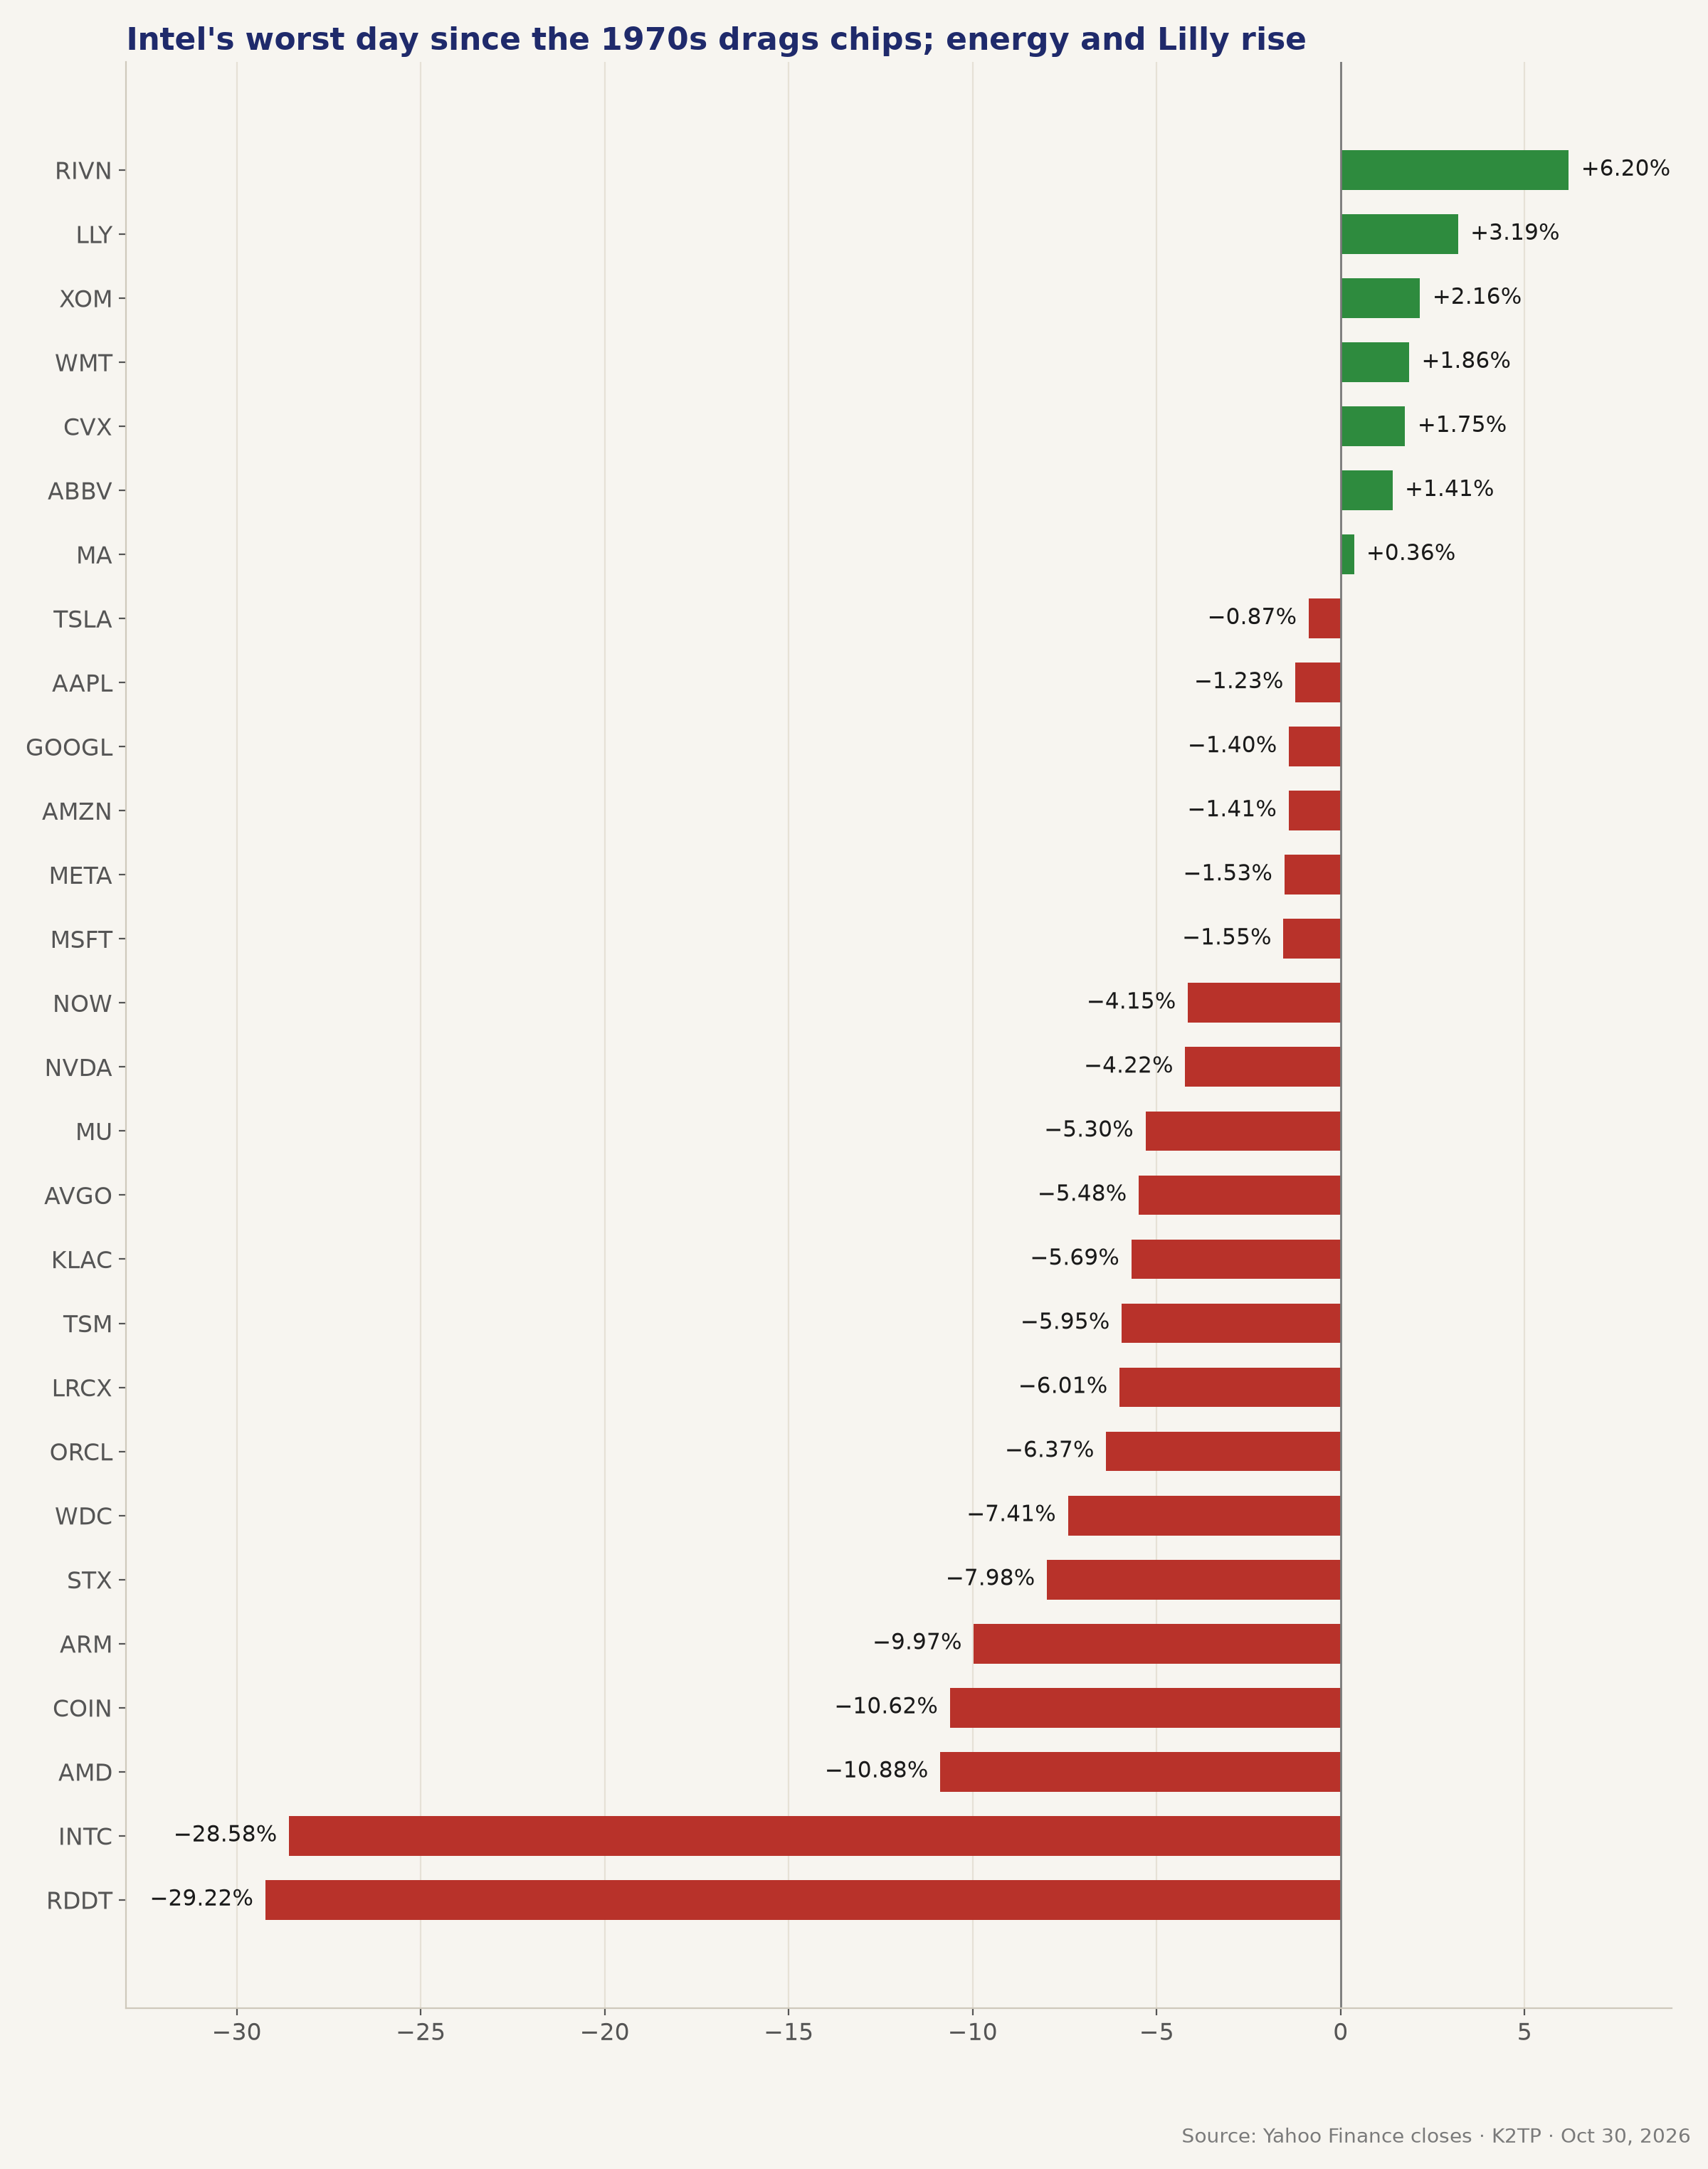
- Contagion through AI hardware and software: AMD −10.88%, ARM −9.97%, STX −7.98%, WDC −7.41%, ORCL −6.37%, TSM −5.95%, AVGO −5.48%, NVDA −4.22%; RDDT −29.22% and COIN −10.62% after their reports
- Amazon recovered from −7.24% pre-market to close −1.41% at 240.35 after trading as low as 229.36
- Fed: Dallas Fed's Logan said at 10:31 AM PT that the Fed needs at least two more quarter-point hikes; SPX slid from about 7,578 to its 7,527.56 low over the next hour while VIX spiked to 23.93
- Yields still fell: 2Y 4.59% (−6.6 bp), 10Y 4.929% (−6.0 bp); Q3 ECI 0.8% q/q was in line; Chicago PMI 55.3 vs 56 expected
- Energy and defensives absorbed flows: XLE +1.91%, XLP +1.41%; Chevron and ExxonMobil beat; WTI settled $104.12 (+2.08%) and expiring December Brent $117.64 (+2.4%), the highest settles since late April
- Regime: 🔴 RISK-OFF (from 🟡 TRANSITION in the morning); the close at 7,580.07 sits below the 7,590.19 midday low, but VIX 19.42 is back under 20.27
- Next week: ISM Manufacturing Monday, the US midterms Tuesday, Apple and Palantir after Monday's close, AMD after Tuesday's close, and the October jobs report Friday
INTEL'S GUIDE TURNS INTO A FULL CHIP SELLOFF
- Intel guided Q4 non-GAAP EPS to $0.25 and revenue to $15B–$16B vs estimates of $0.43 and $17.1B, citing a PC slowdown through at least the first half of next year; the Israel fab incident costs about $600M of revenue over two quarters 🔴
- INTC −28.58% to 65.76 (low 63.20); BofA cut it to neutral with a $100 price objective (Midday brief); the US government's stake lost about $12B in value
- SOX −7.20%, its lowest close since May and biggest drop since late June per Reuters; SOXX −8.24%
- AMD −10.88% to 504.80 and ARM −9.97%; storage names STX −7.98% and WDC −7.41%; equipment LRCX −6.01%, KLAC −5.69%; TSM −5.95%, AVGO −5.48%, MU −5.30%, NVDA −4.22% to 204.64
- The selling reached AI software and credit: ORCL −6.37%, NOW −4.15%; the FT reported Blackstone told investors Anthropic may not secure an investment-grade rating (9:47 AM PT), and the SEC enforcement director said the agency is examining AI disclosures (10:49 AM PT)
- Reddit −29.22% and Coinbase −10.62% after Thursday's reports, with Coinbase also hit by the Binance hack
→ Intel's guide was the spark, but the market used it to cut AI hardware exposure across the board. NDX −3.46% vs RSP −0.79% shows the damage was concentrated in the largest AI names.
AMAZON CLAWS BACK MOST OF ITS LOSS
- Amazon (reported Thursday): revenue $201.9B vs $202.2B expected, EPS $1.89 vs $1.97, trailing FCF −$42.4B on quarterly capex of $77.3B; Q4 operating income guidance $28.5B–$33.5B vs $33.2B 🟡
- AMZN was −7.24% pre-market, traded as low as 229.36, and closed −1.41% at 240.35
- Mega-caps fell less than chips: AAPL −1.23%, GOOGL −1.40%, META −1.53%, MSFT −1.55%, TSLA −0.87%
→ Buyers stepped in on Amazon even as chips broke. The market is separating AI spenders with strong core businesses from chip suppliers whose guidance is slipping.
HAWKISH FED TALK, BUT BONDS RALLY
- 5:30 AM PT: Q3 Employment Cost Index 0.8% q/q, in line, removing a wage-inflation scare (Pre-Market brief) 🟡
- Chicago PMI 55.3 vs 56 expected and 58.8 prior
- Richmond Fed's Barkin said AI investment creates demand-side inflation "the Fed can lean against"; SF Fed's Daly said AI matters for near- and medium-term policy (Midday brief)
- St. Louis Fed's Musalem said risks remain tilted toward elevated inflation; Dallas Fed's Logan said the Fed needs at least two more quarter-point hikes and called inflation not returning to 2% unacceptable (Pre-Close brief)
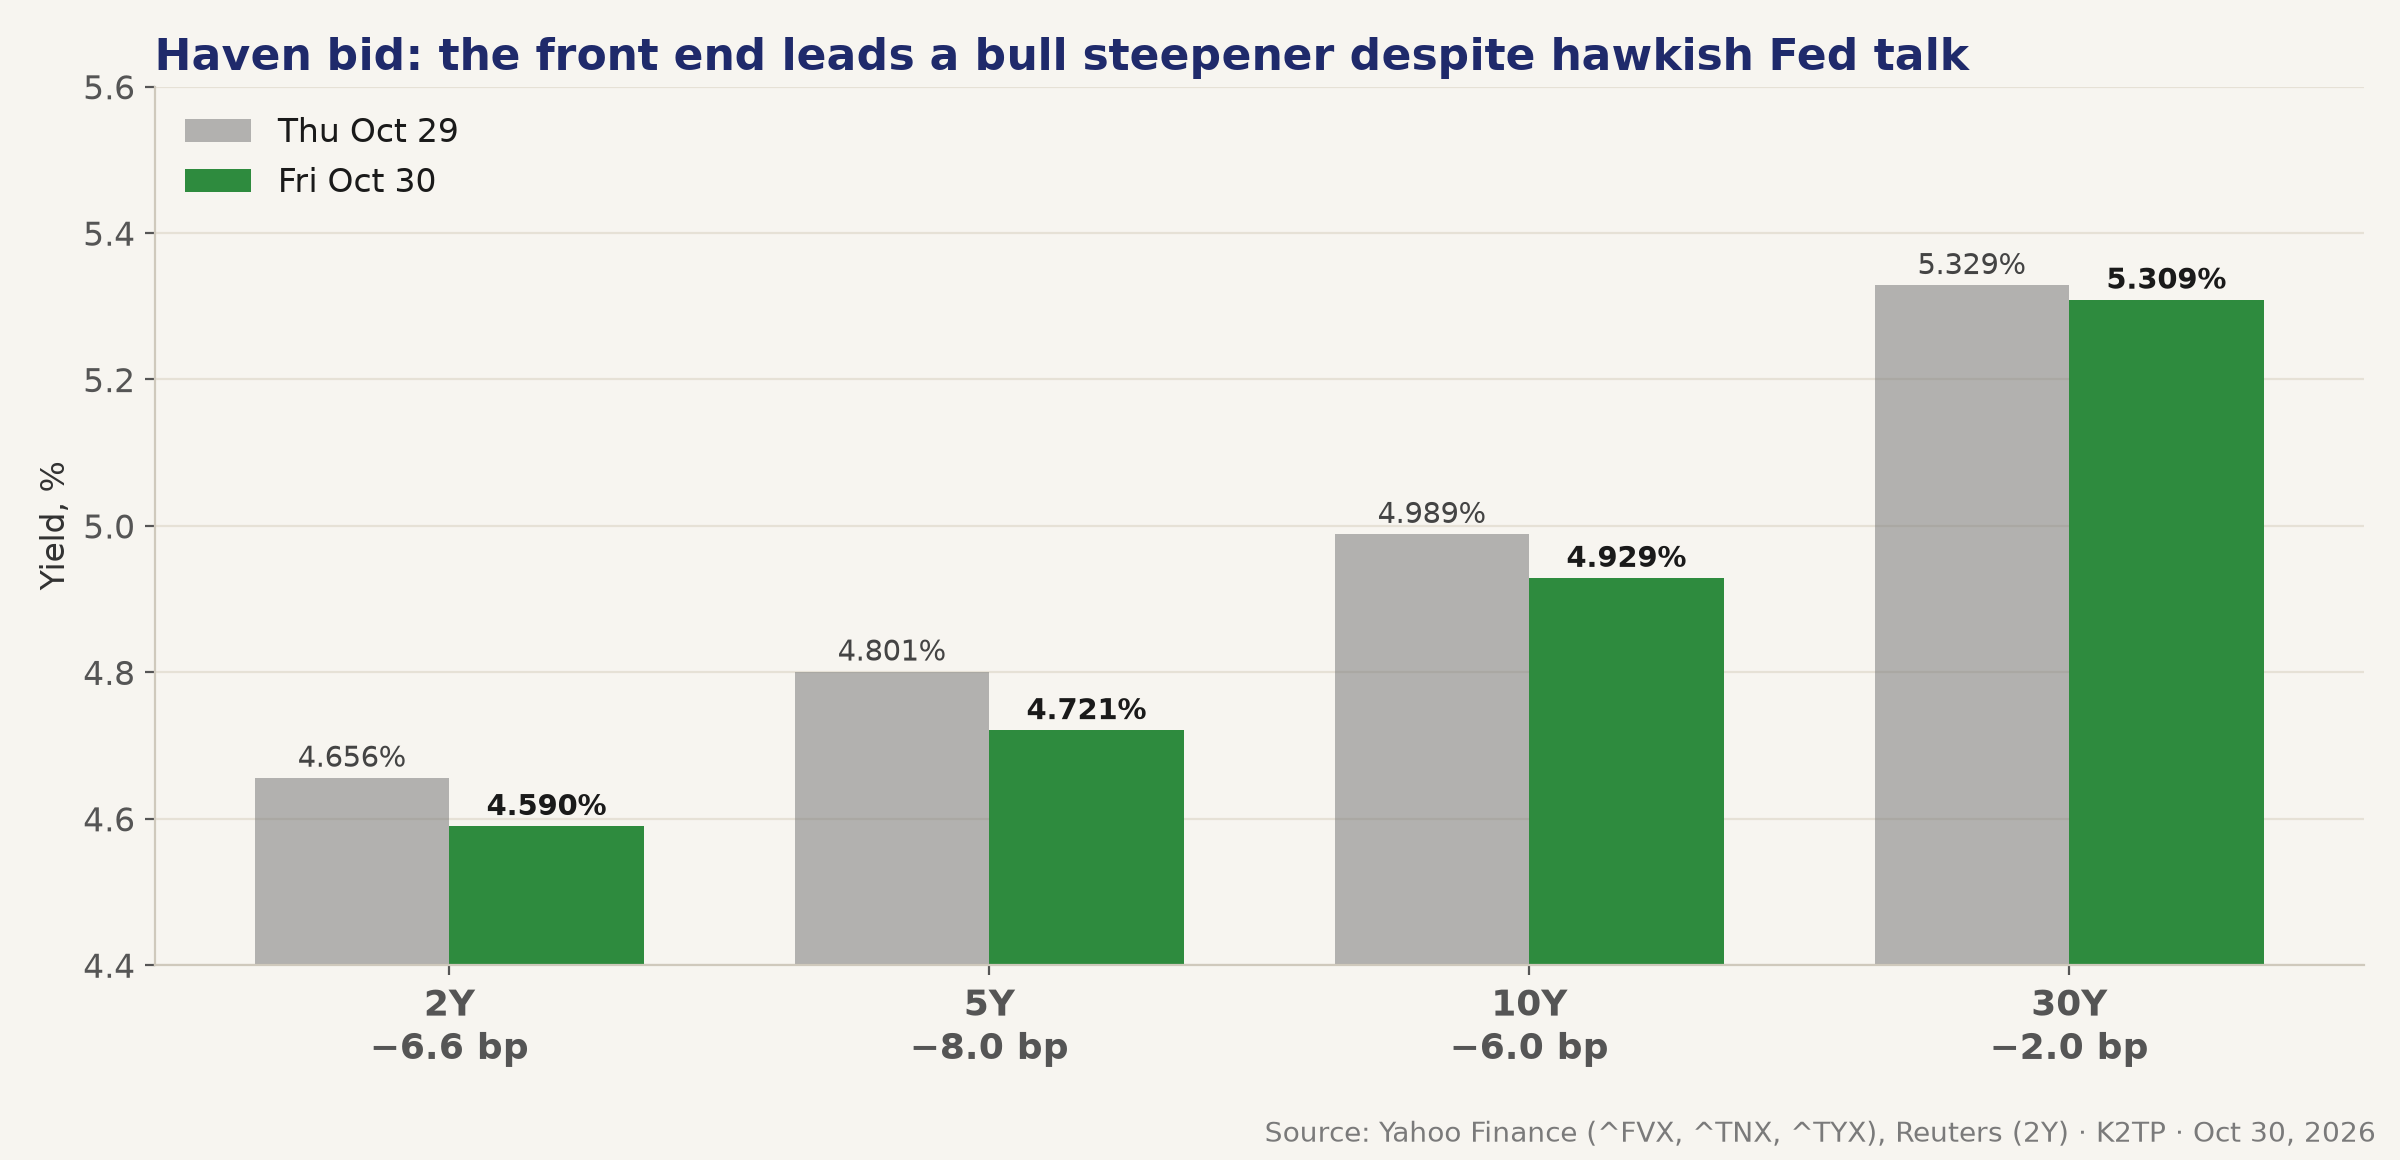
- Closing yields: 2Y 4.59% (−6.6 bp, Reuters), 5Y 4.721% (−8.0 bp), 10Y 4.929% (−6.0 bp), 30Y 5.309% (−2.0 bp); Reuters says the 10Y is on track for its biggest monthly drop in nearly three years
- Updated FedWatch odds: unavailable
→ Fed speakers were hawkish, but the bond market bought duration as a haven from the equity selloff. A falling 2Y alongside calls for more hikes says growth fear is outweighing the Fed's message for now.
ENERGY EARNINGS AND OIL CARRY THE DEFENSIVES
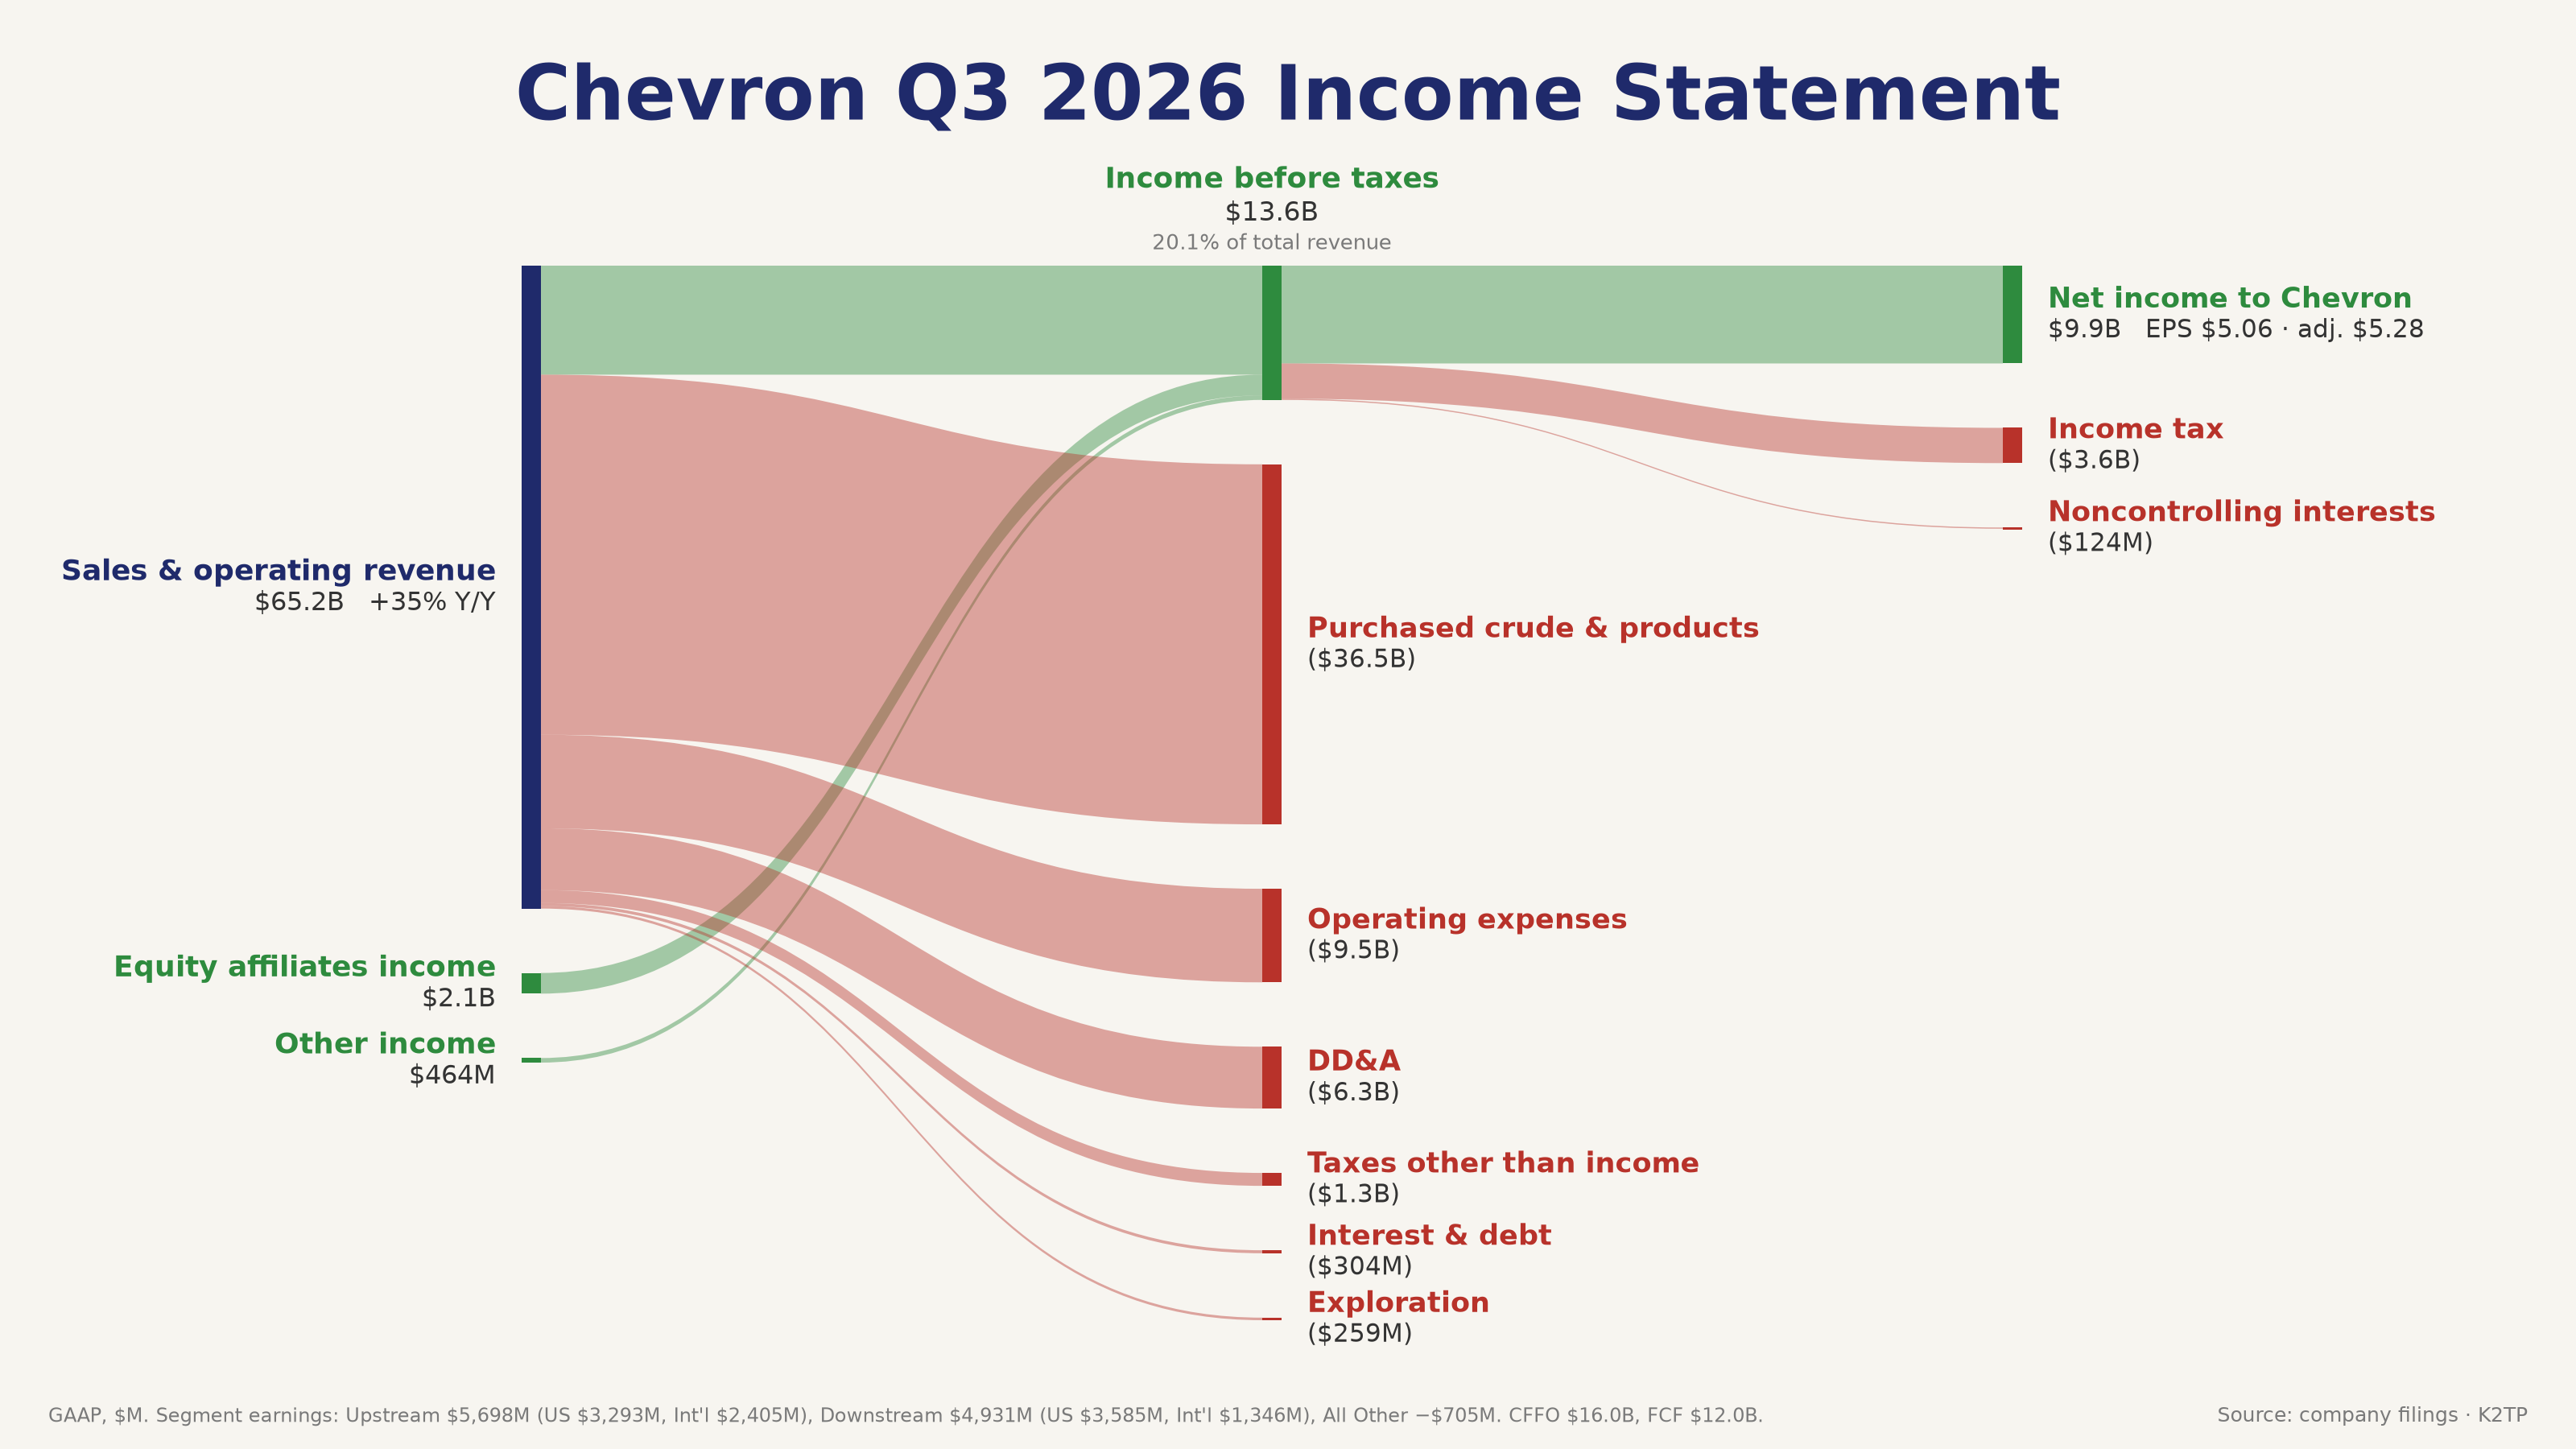
- Chevron (8-K Ex. 99.1, Q3 2026): earnings $9.92B, EPS $5.06; adjusted $10.36B, $5.28 vs $4.93 expected; sales and operating revenue $65.24B (+35% Y/Y); CFFO $16.0B, FCF $12.0B; CVX +1.75% to 235.52 🟢
- ExxonMobil's Q3 profit doubled to $15.4B from $7.5B; XOM +2.16% to 187.25
- AbbVie adj. EPS $3.82 vs $3.74, full-year guidance $13.95–$13.99; ABBV +1.41%
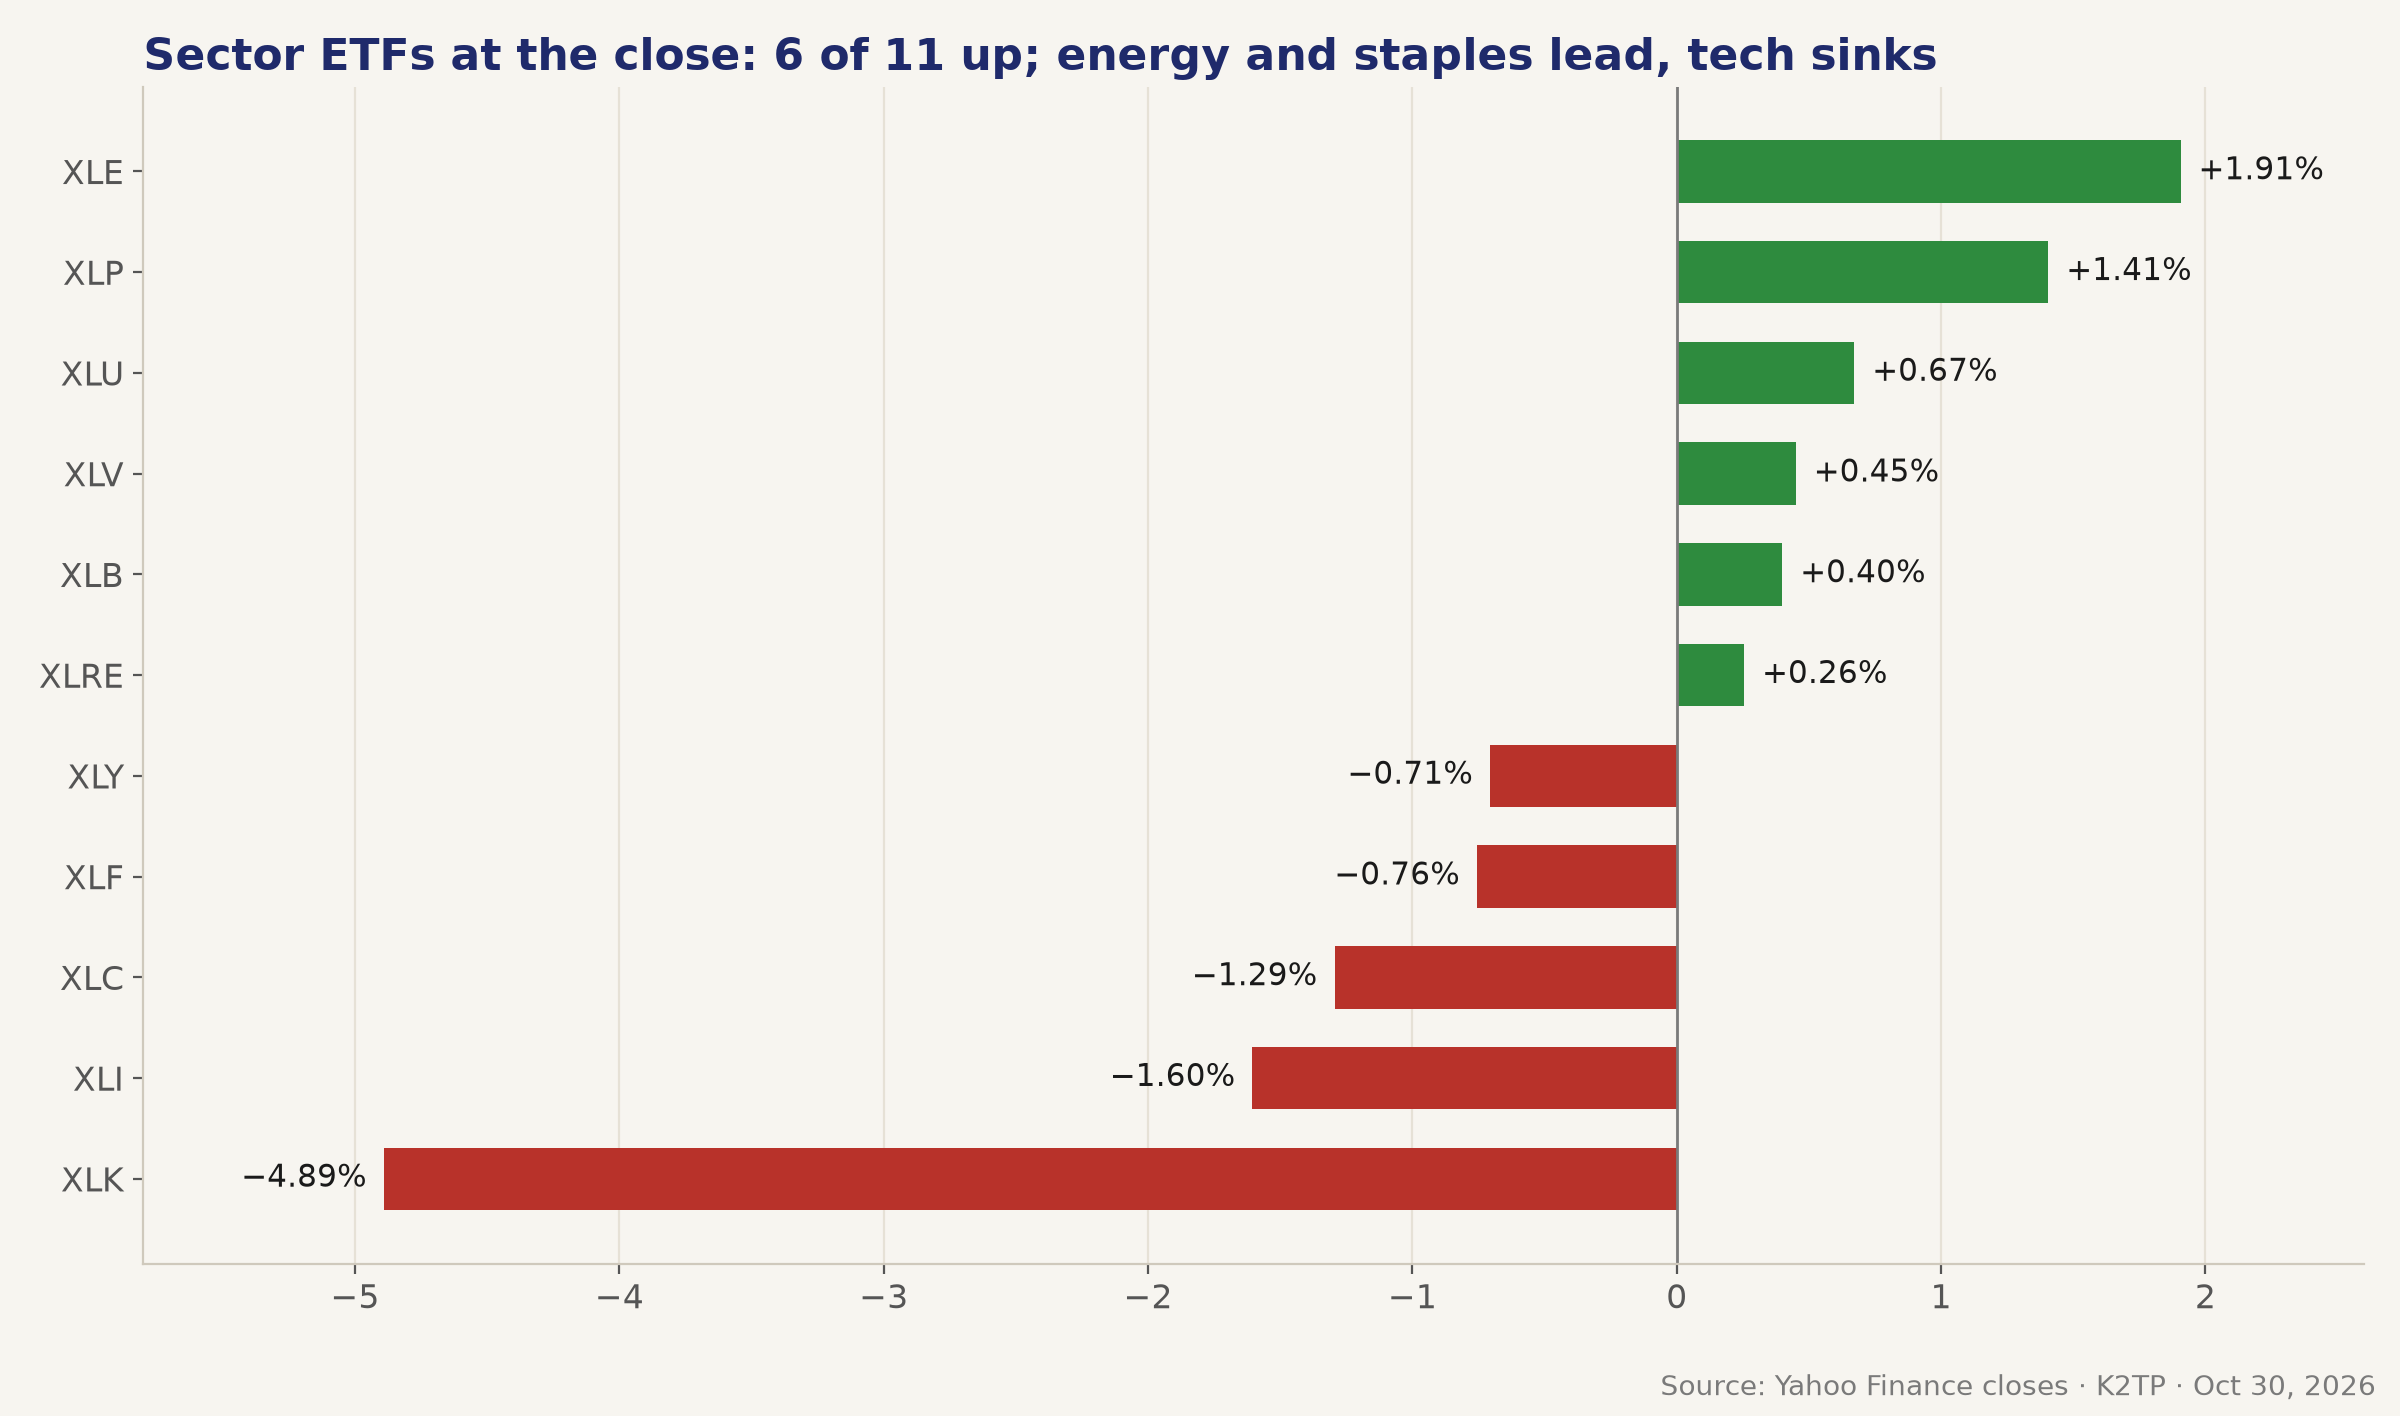
- 6 of 11 sector ETFs rose: XLE +1.91%, XLP +1.41%, XLU +0.67%, XLV +0.45%, XLB +0.40%, XLRE +0.26%; XLY −0.71%, XLF −0.76%, XLC −1.29%, XLI −1.60%, XLK −4.89%
- Other gainers: RIVN +6.20%, LLY +3.19% to 1,417.54, WMT +1.86%, MA +0.36%
→ Money hid in energy, staples and health care rather than leaving equities entirely. That kept RSP's loss under half of SPX's.
HORMUZ PUSHES OIL TO SIX-MONTH HIGHS
- Iranian state media said a super tanker carrying more than 2 million barrels hit a sea mine at the mouth of the Strait of Hormuz; UKMTO reported an incident south of Iran's Lavan Island (Pre-Market and Pre-Close briefs) 🔴
- Qatari mediators were in Tehran and CBS reported signs of progress; Trump said the war will "end very soon"; reports raised the possibility of US strikes after the November 3 midterms; the Houthis attacked Aden airport
- December WTI settled at $104.12 (+2.08%) and expiring December Brent at $117.64 (+2.4%), the highest settles since late April; January Brent $113.43; in October Brent rose 13.6% and WTI 15.2%
- Gold about $3,885 (about −3.6%), DXY 101.96, BTC about $77,212 (−0.72%)
→ Oil above $100 keeps the inflation story alive for the Fed hawks. A weekend headline from the Gulf could gap futures either way on Sunday.
SPX: HIGH IN THE FIRST HALF HOUR, LOW AFTER LOGAN, A LATE BOUNCE
- Pre-market: ES −1.13%, NQ −2.65%; SPX implied near 7,634, below the 7,677.16 bear line; VIX 18.60
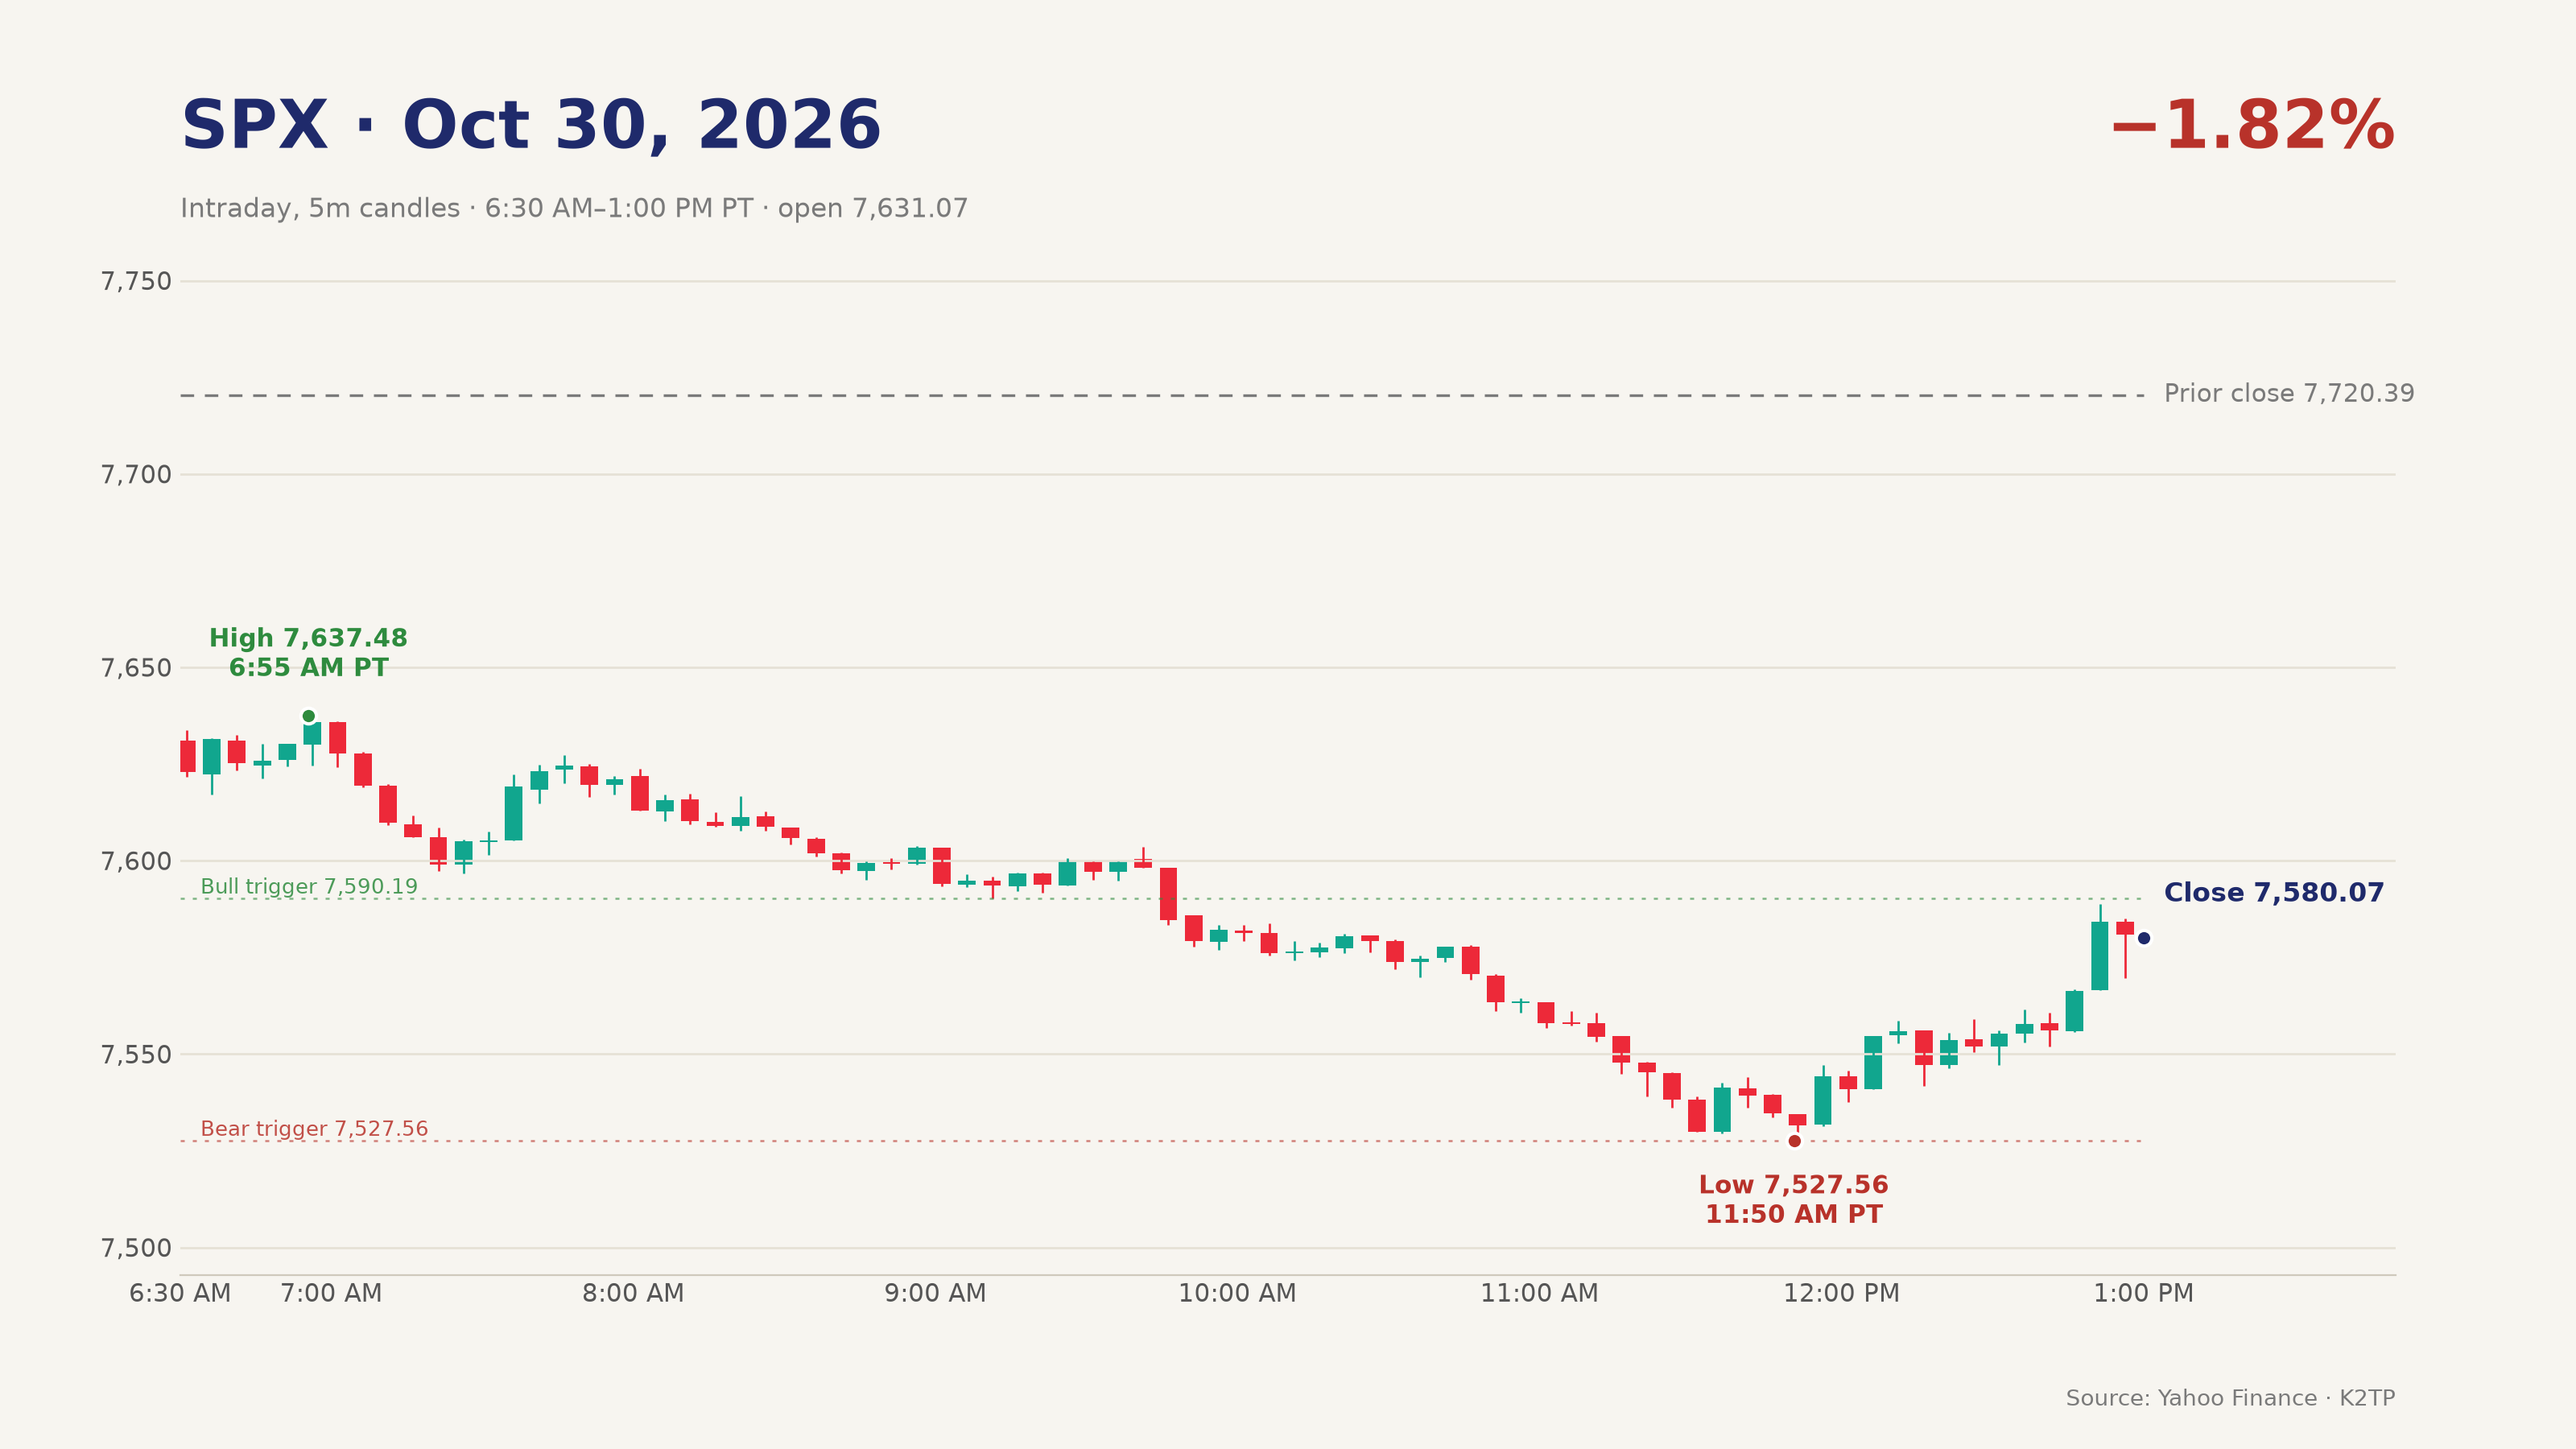
- SPX opened at 7,631.07 and set the day high of 7,637.48 at 6:55 AM PT, then slid below the October 23 low of 7,612.07; at midday SPX was 7,594.53 (−1.63%) after a 7,590.19 low, with VIX at 20.03
- After Logan's remarks at 10:31 AM PT, SPX hit the day low of 7,527.56 at 11:50 AM PT while VIX touched 23.93 and VIX9D briefly moved above VIX3M
- At the pre-close SPX was 7,553.47 (−2.16%); month-end buying lifted it to close at 7,580.07
- The pre-close Bear line (SPX under 7,527.56 with VIX above 23.93) did not fire; the Bull line (SPX above 7,590.19 with VIX under 20.27) was half met, with VIX 19.42 under 20.27 but SPX 10 points short
→ The 7,527.56 low held into the close and VIX retreated, but SPX finished below both 7,612.07 and 7,590.19. Those two lines are the first test for Monday.
THE WEEK AND THE MONTH
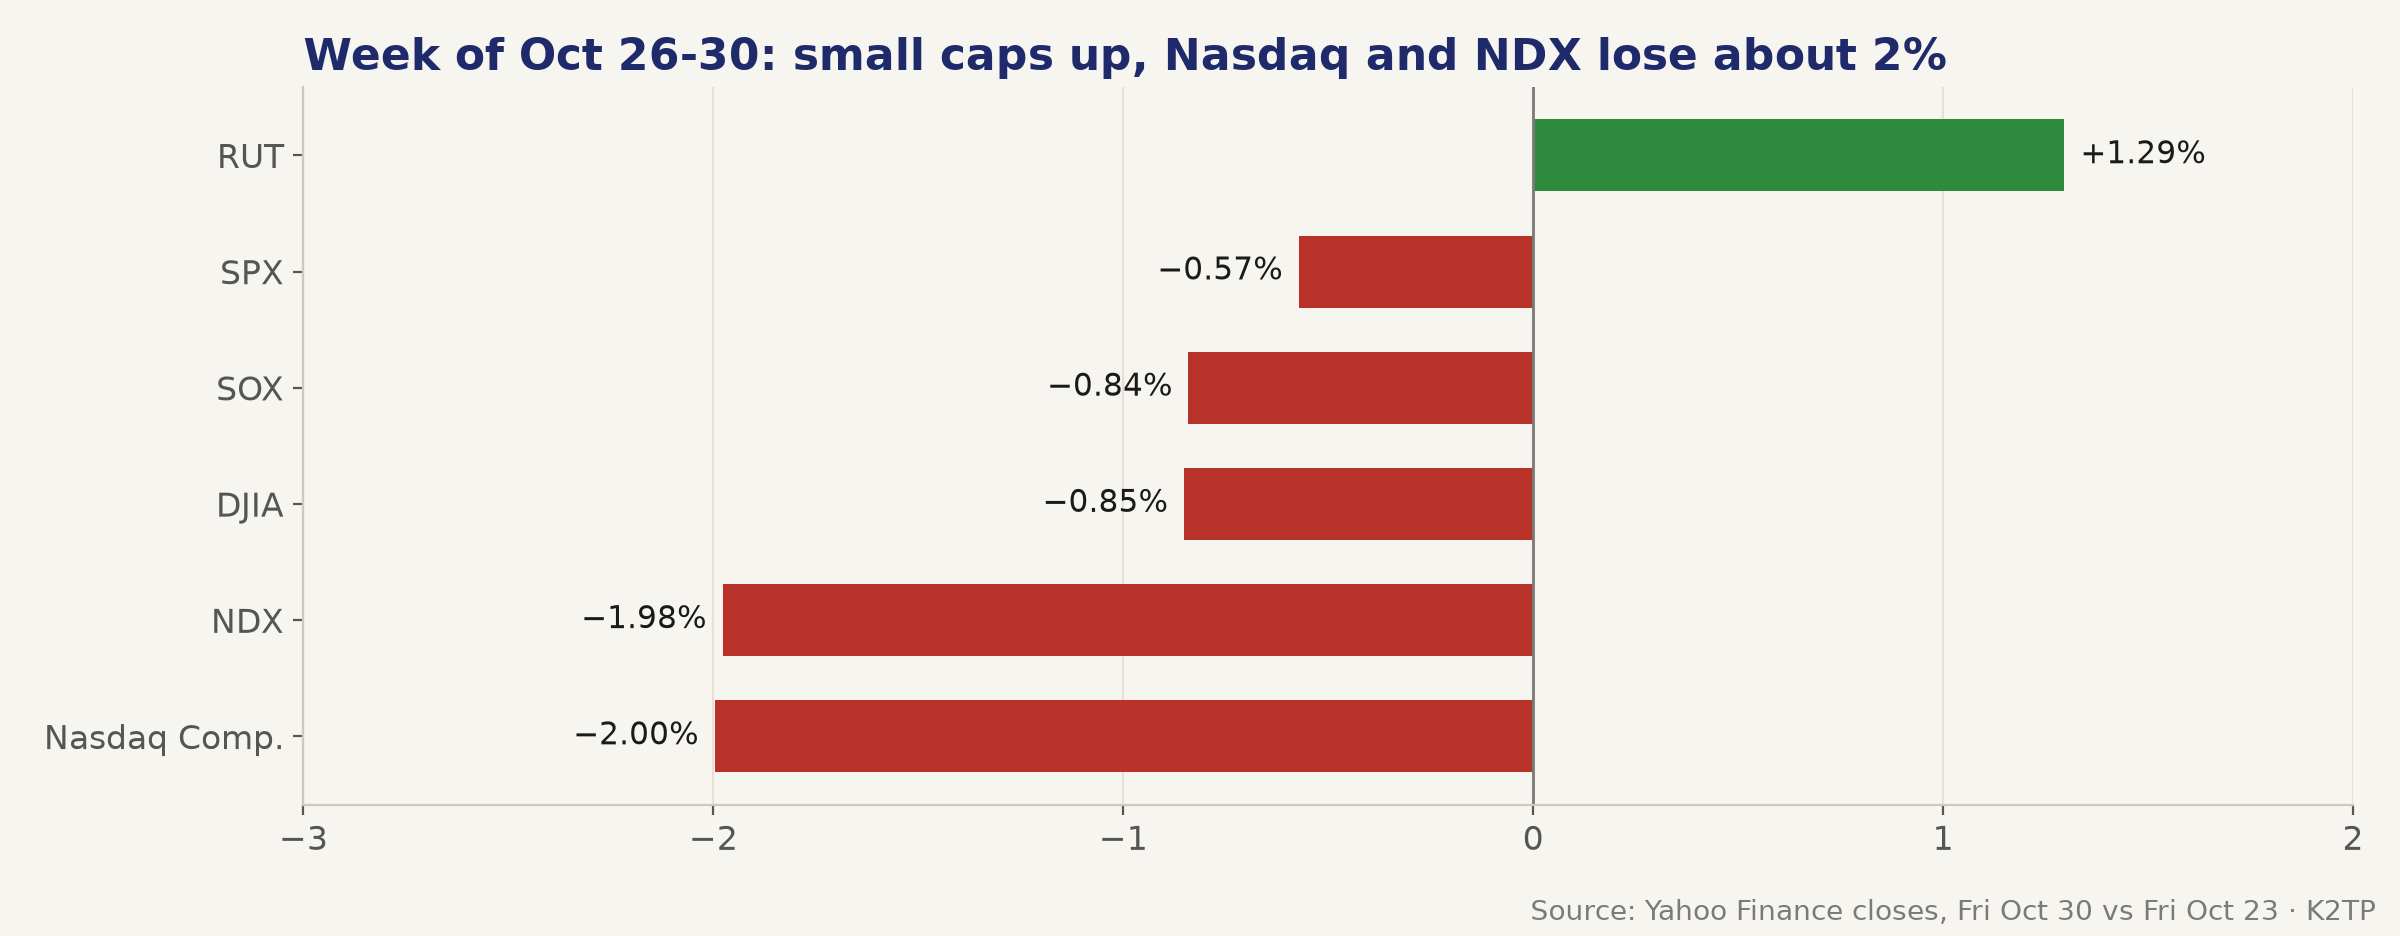
- Week (Fri vs Fri): RUT +1.29%, SPX −0.57%, SOX −0.84%, DJIA −0.85%, NDX −1.98%, Nasdaq Composite −2.00%; SPX's third straight weekly loss
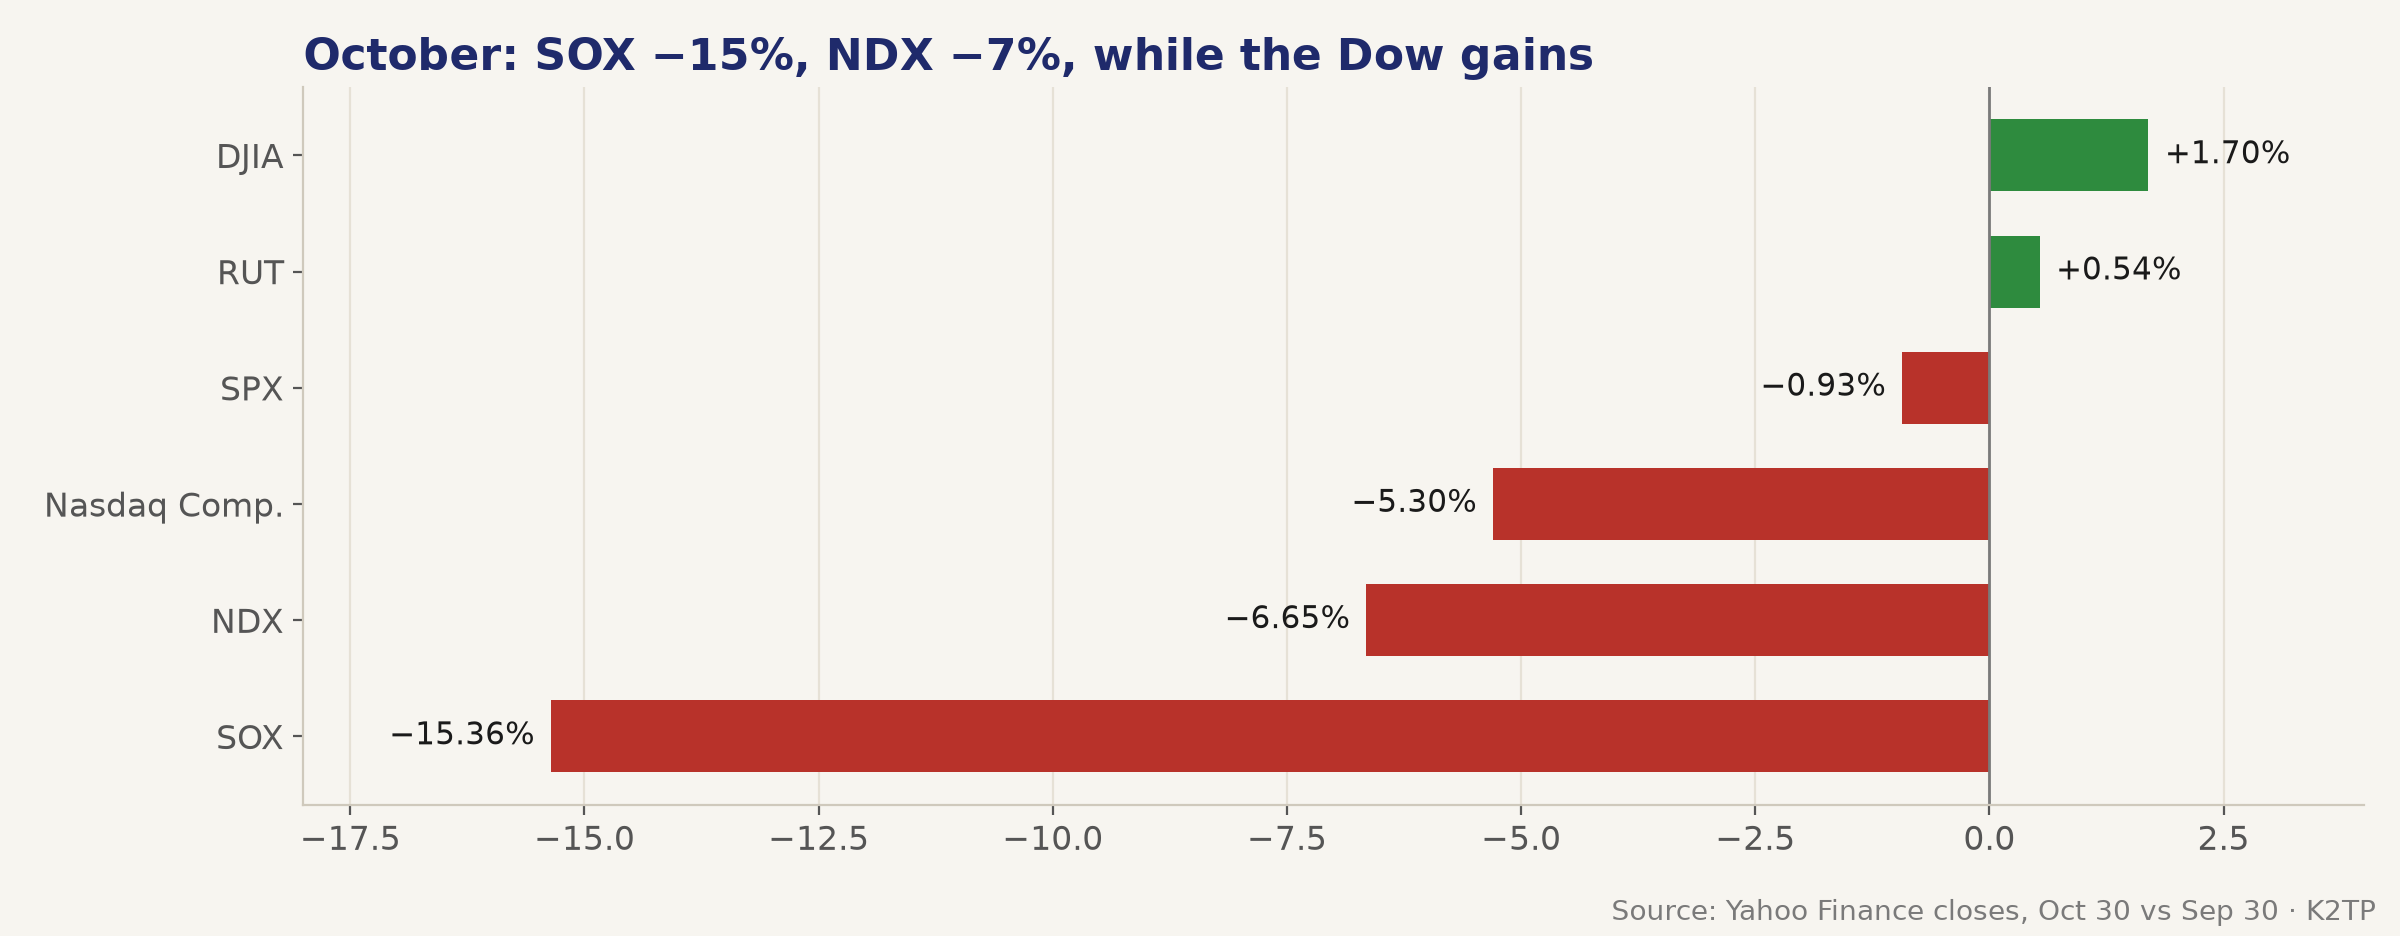
- October: DJIA +1.70%, RUT +0.54%, SPX −0.93%, Nasdaq Composite −5.30%, NDX −6.65%, SOX −15.36%
- The week's main theme was the AI capex reckoning: Alphabet −12.64% Thursday on negative FCF, then Amazon's capex and Intel's guide; health care and staples led the rotation
→ Under the index, the average stock had a far better October than the AI leaders. Small caps and the Dow ended the month higher while chips lost 15%.
MARKET: CHIPS CRASH, DEFENSIVES HOLD, VOLATILITY SPIKES
Indices (close):
- SPX 7,580.07 (−1.82%), range 7,527.56–7,637.48
- NDX 28,384.85 (−3.46%); Nasdaq Composite 25,437.00 (−2.86%)
- DJIA 51,770.31 (−1.09%)
- RUT 2,811.84 (−1.66%)
- RSP 218.31 (−0.79%)
- SOX 10,688.80 (−7.20%)
Intraday path: ES −1.13% and NQ −2.65% pre-market on Intel and Amazon. SPX opened at 7,631.07, peaked at 7,637.48 at 6:55 AM PT, stood at 7,594.53 at midday, fell to 7,527.56 at 11:50 AM PT after Logan's hike call, was 7,553.47 at the pre-close and closed at 7,580.07.
Sector rotation:
- Up: XLE +1.91%, XLP +1.41%, XLU +0.67%, XLV +0.45%, XLB +0.40%, XLRE +0.26%
- Down: XLY −0.71%, XLF −0.76%, XLC −1.29%, XLI −1.60%, XLK −4.89%
- Mega-caps: TSLA −0.87%, AAPL −1.23%, GOOGL −1.40%, AMZN −1.41%, META −1.53%, MSFT −1.55%, NVDA −4.22%, AVGO −5.48%, TSM −5.95%, AMD −10.88%, INTC −28.58%
Market internals:
- RSP −0.79% vs SPX −1.82%, a 103 bp gap; IWM −1.65%, QQQ −3.47%
- 6 of 11 sectors up, up from 5 of 11 at midday and the pre-close
- NYSE advance/decline data: unavailable
Volatility:
- VIX 19.42 (+12.91%), range 18.03–23.93
- VIX9D 19.25 (high 25.06), VIX3M 20.78; the front of the curve inverted intraday and closed back in contango
- VVIX 106.43 (high 124.06)
- Gamma levels: unavailable
Cross-asset:
- 2Y 4.59%, 5Y 4.721%, 10Y 4.929%, 30Y 5.309%
- WTI $104.12 settle (+2.08%), Brent December $117.64 settle (expired), January $113.43
- Gold about $3,885; DXY 101.96; BTC about $77,212
Global:
- Asia (Friday): Nikkei −2.1% to 63,290.11, Kospi −3.5%, Shanghai −1.4%, Hang Seng +1.5%
- Europe: Euro Stoxx 50 −1.22%, DAX −0.85%, CAC 40 flat, FTSE 100 +0.07%; Italian CPI 5.4% y/y vs 4.6% expected, eurozone Q3 GDP 0.4% vs 0.2%; the BoJ held and left the door open to a December hike (Pre-Market brief)
Key SPX levels:
- 7,637.48: Friday high; reclaiming it with VIX under 18.03 would ease RISK-OFF
- 7,612.07: October 23 low, now resistance
- 7,590.19: Friday's midday low, the first line to reclaim
- 7,580.07: close
- 7,527.56: Friday low; under it with VIX above 23.93 extends RISK-OFF
- 7,306: the 200-day moving average cited by BTIG (CNBC)
- VIX: 20.27 and 23.93
Option seller's corner:
- Bull case: SPX reclaims 7,590.19 and then 7,612.07 with VIX under 20.27 after Monday's ISM; the regime eases toward TRANSITION. Add far-OTM SPX put spreads only after the midterm result is known.
- Bear case: SPX under 7,527.56 with VIX above 23.93 opens a path toward the 7,306 200-day average. Keep short-put size small, use only defined-risk spreads and avoid single chip names into AMD's report on Tuesday.
- VIX 19.42 sits under VIX3M 20.78, but the intraday inversion and VVIX at 124 show demand for near-term protection. Premium is richer, but the week holds the midterms, AMD, Apple and payrolls, so size for gaps.
- Favor broad underlyings such as SPX or RSP over NDX; energy and staples held up, chips did not.
BOTTOM LINE
- Intel's guide turned into the worst chip selloff since June: SOX −7.20%, NDX −3.46%, SPX −1.82% to 7,580.07, its lowest close of October.
- Logan's call for two more hikes added pressure, but bonds rallied as a haven: 2Y 4.59%, 10Y 4.929%.
- Regime 🔴 RISK-OFF. The 7,527.56 low held and VIX eased to 19.42 into the close; reclaiming 7,590.19 with VIX under 20.27 is the first step back toward TRANSITION.
Watch next week (PT):
- Mon 7:00 AM: October ISM Manufacturing; after the close: Apple and Palantir
- Tue: US midterm elections; after the close: AMD (Q3 guide about $13B ± $300M)
- During the week: ISM Services, JOLTS, earnings from McDonald's, Qualcomm, Uber, Pfizer and Amgen, plus more Fed speakers
- Fri 5:30 AM: October jobs report (consensus about 55K–56K payrolls, unemployment 4.2%, wages +0.3% m/m)
- Over the weekend: Hormuz and Iran headlines before Sunday's futures open
Bull expectation: no Gulf escalation over the weekend, chips stabilize, SPX reclaims 7,590.19 and 7,612.07 with VIX under 20.27. Bear expectation: a Gulf headline lifts oil again, chips extend losses, SPX breaks 7,527.56 with VIX above 23.93.
Sources: 3 K2TP briefs for 10/30/2026 (Pre-Market, Midday, Pre-Close); there is no Evening Recap on Fridays. Official closing and intraday prices from Yahoo Finance; 2Y from Reuters; oil settlements, news and data from Reuters, CNBC, AFP, Newsquawk and FinancialJuice; next-week calendar from CNBC and Trading Economics; Chevron Sankey from Chevron's Q3 2026 release (8-K Ex. 99.1), SEC EDGAR. Analysis: K2TP Framework.