Market 10/29: Tech sells off while the rest of the market rallies, and a strong GDP print and in-line PCE pull yields lower; after the bell Intel sinks 23% on a weak guide and Amazon 7% on $77.3B of capex
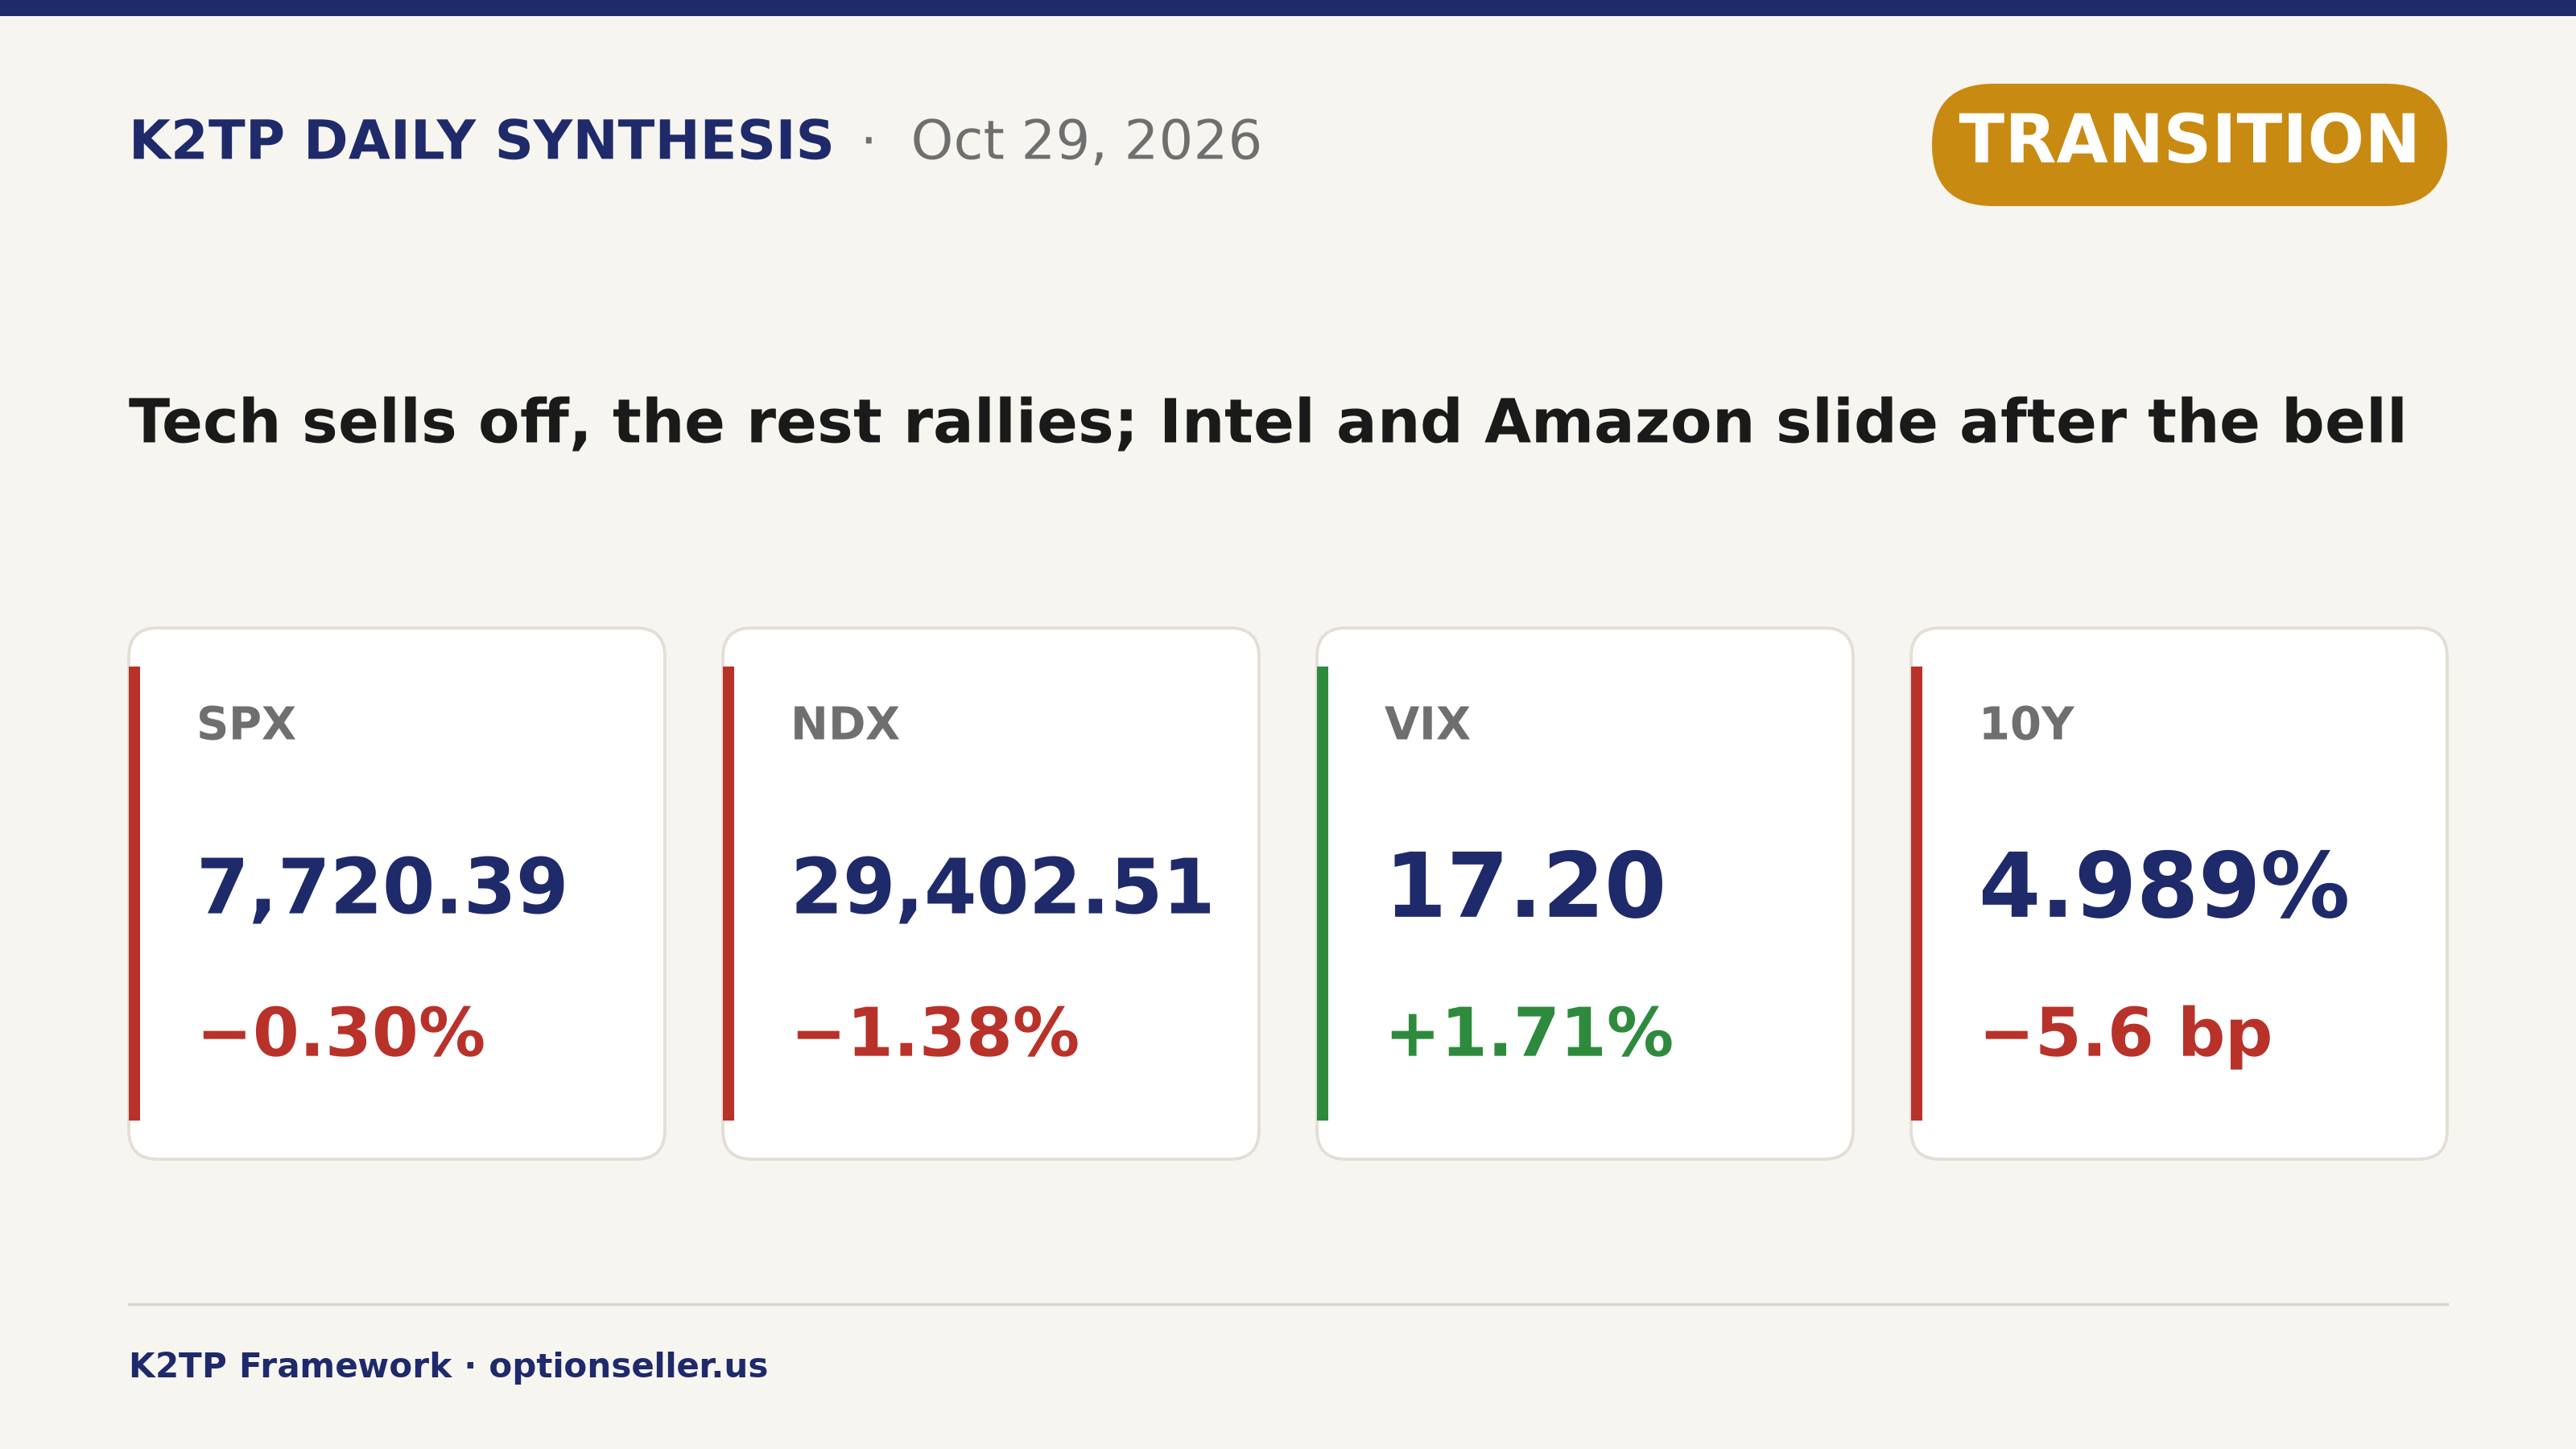
SPX −0.30%, NDX −1.38%, DJIA −0.25%, RUT +1.01%, RSP +1.20%, VIX +1.71% to 17.20. GOOGL −12.64%, NOW −26.95%, CAT −9.25% while LLY +6.63% and MA +4.16%; 9 of 11 sector ETFs up. 2Y 4.656% (−7.9 bp), 10Y 4.989% (−5.6 bp). After hours INTC −23.01%, AMZN −7.30%; NQ futures about −2.4% tonight.
KEY HEADLINES
- SPX −0.30% to 7,720.39 (−23.59 pts); NDX −1.38% to 29,402.51; Nasdaq Composite −1.38%; DJIA −0.25% to 52,342.56; RUT +1.01% to 2,859.22
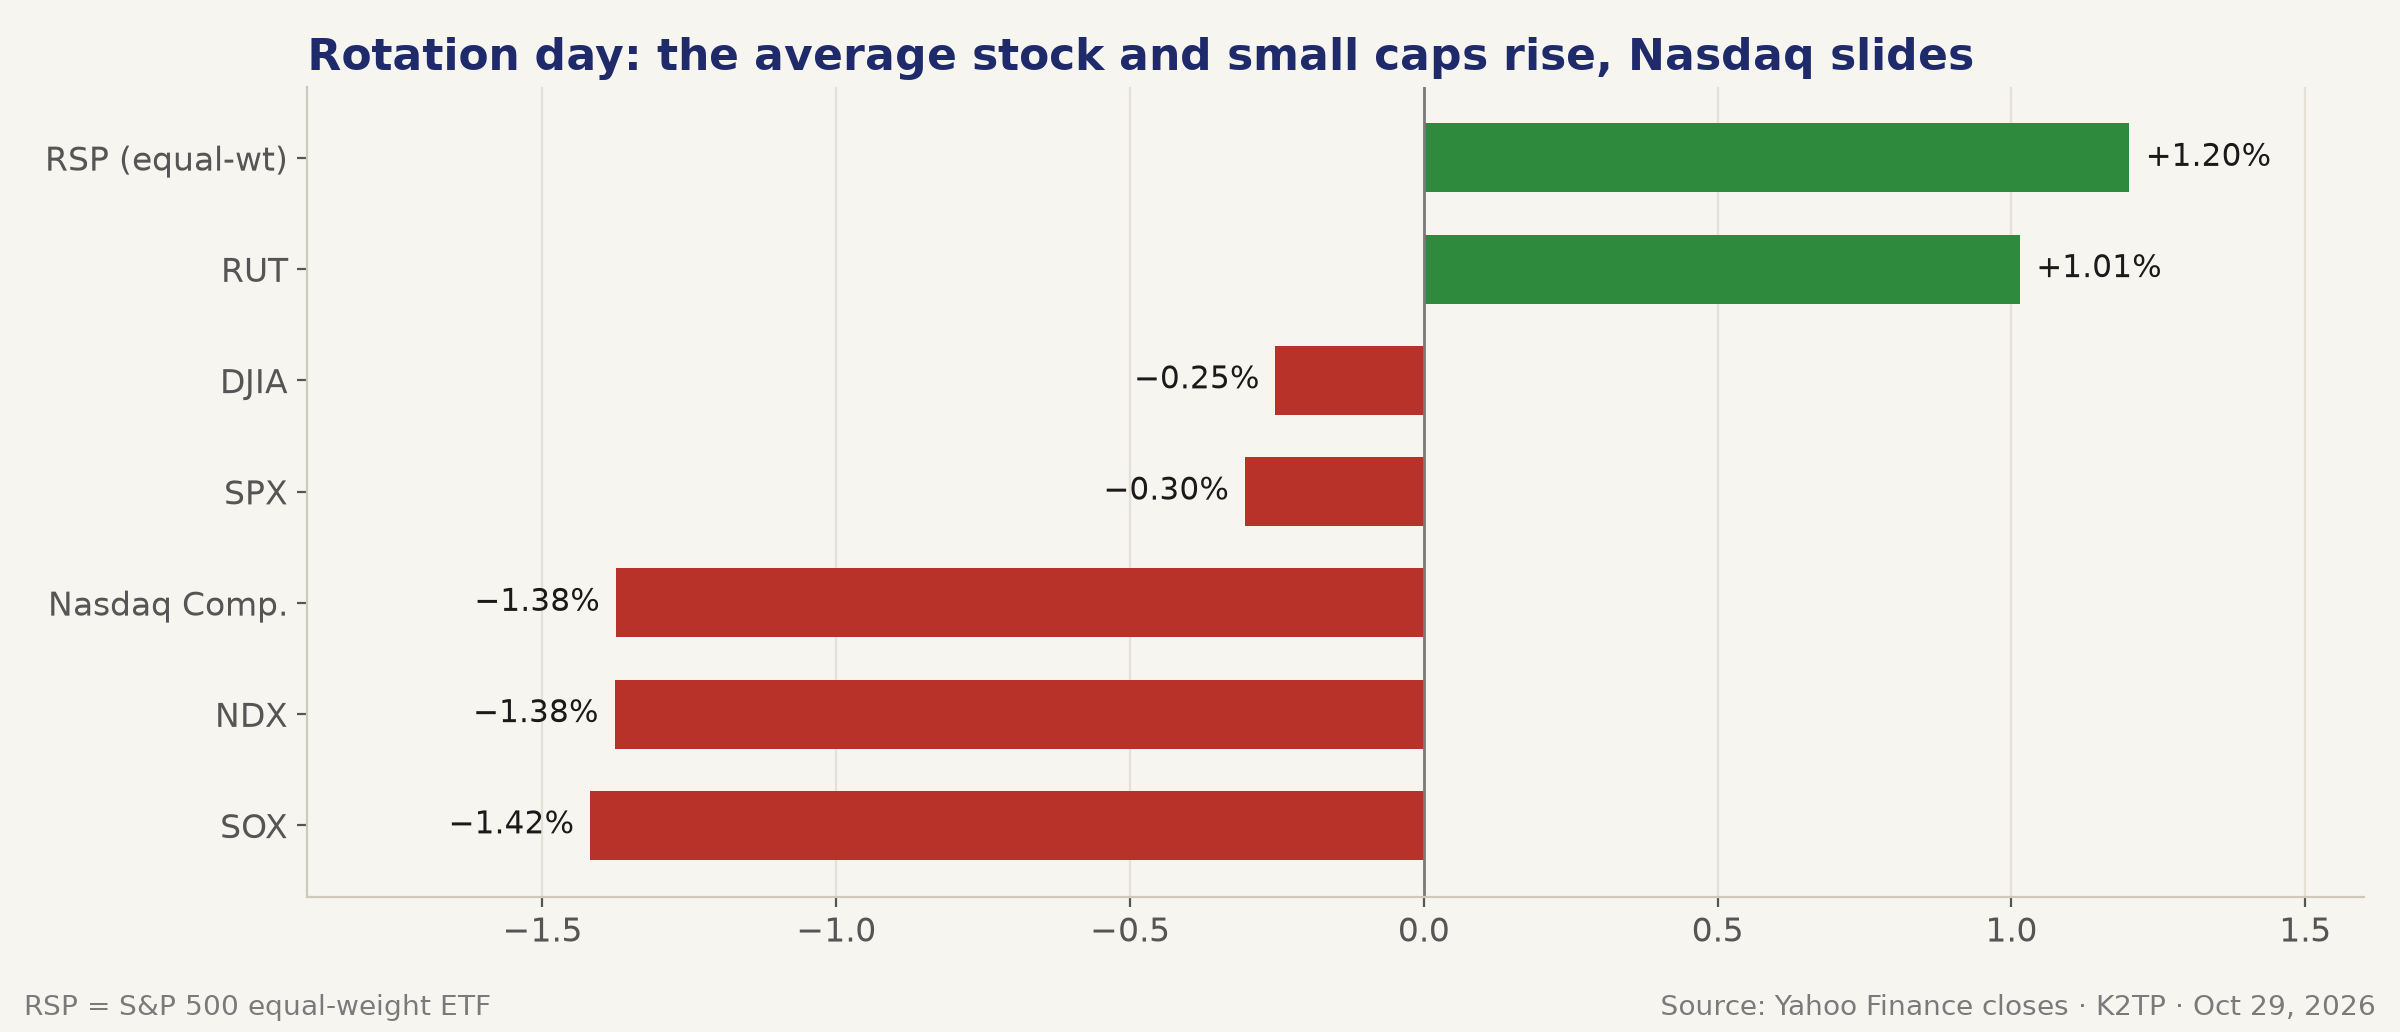
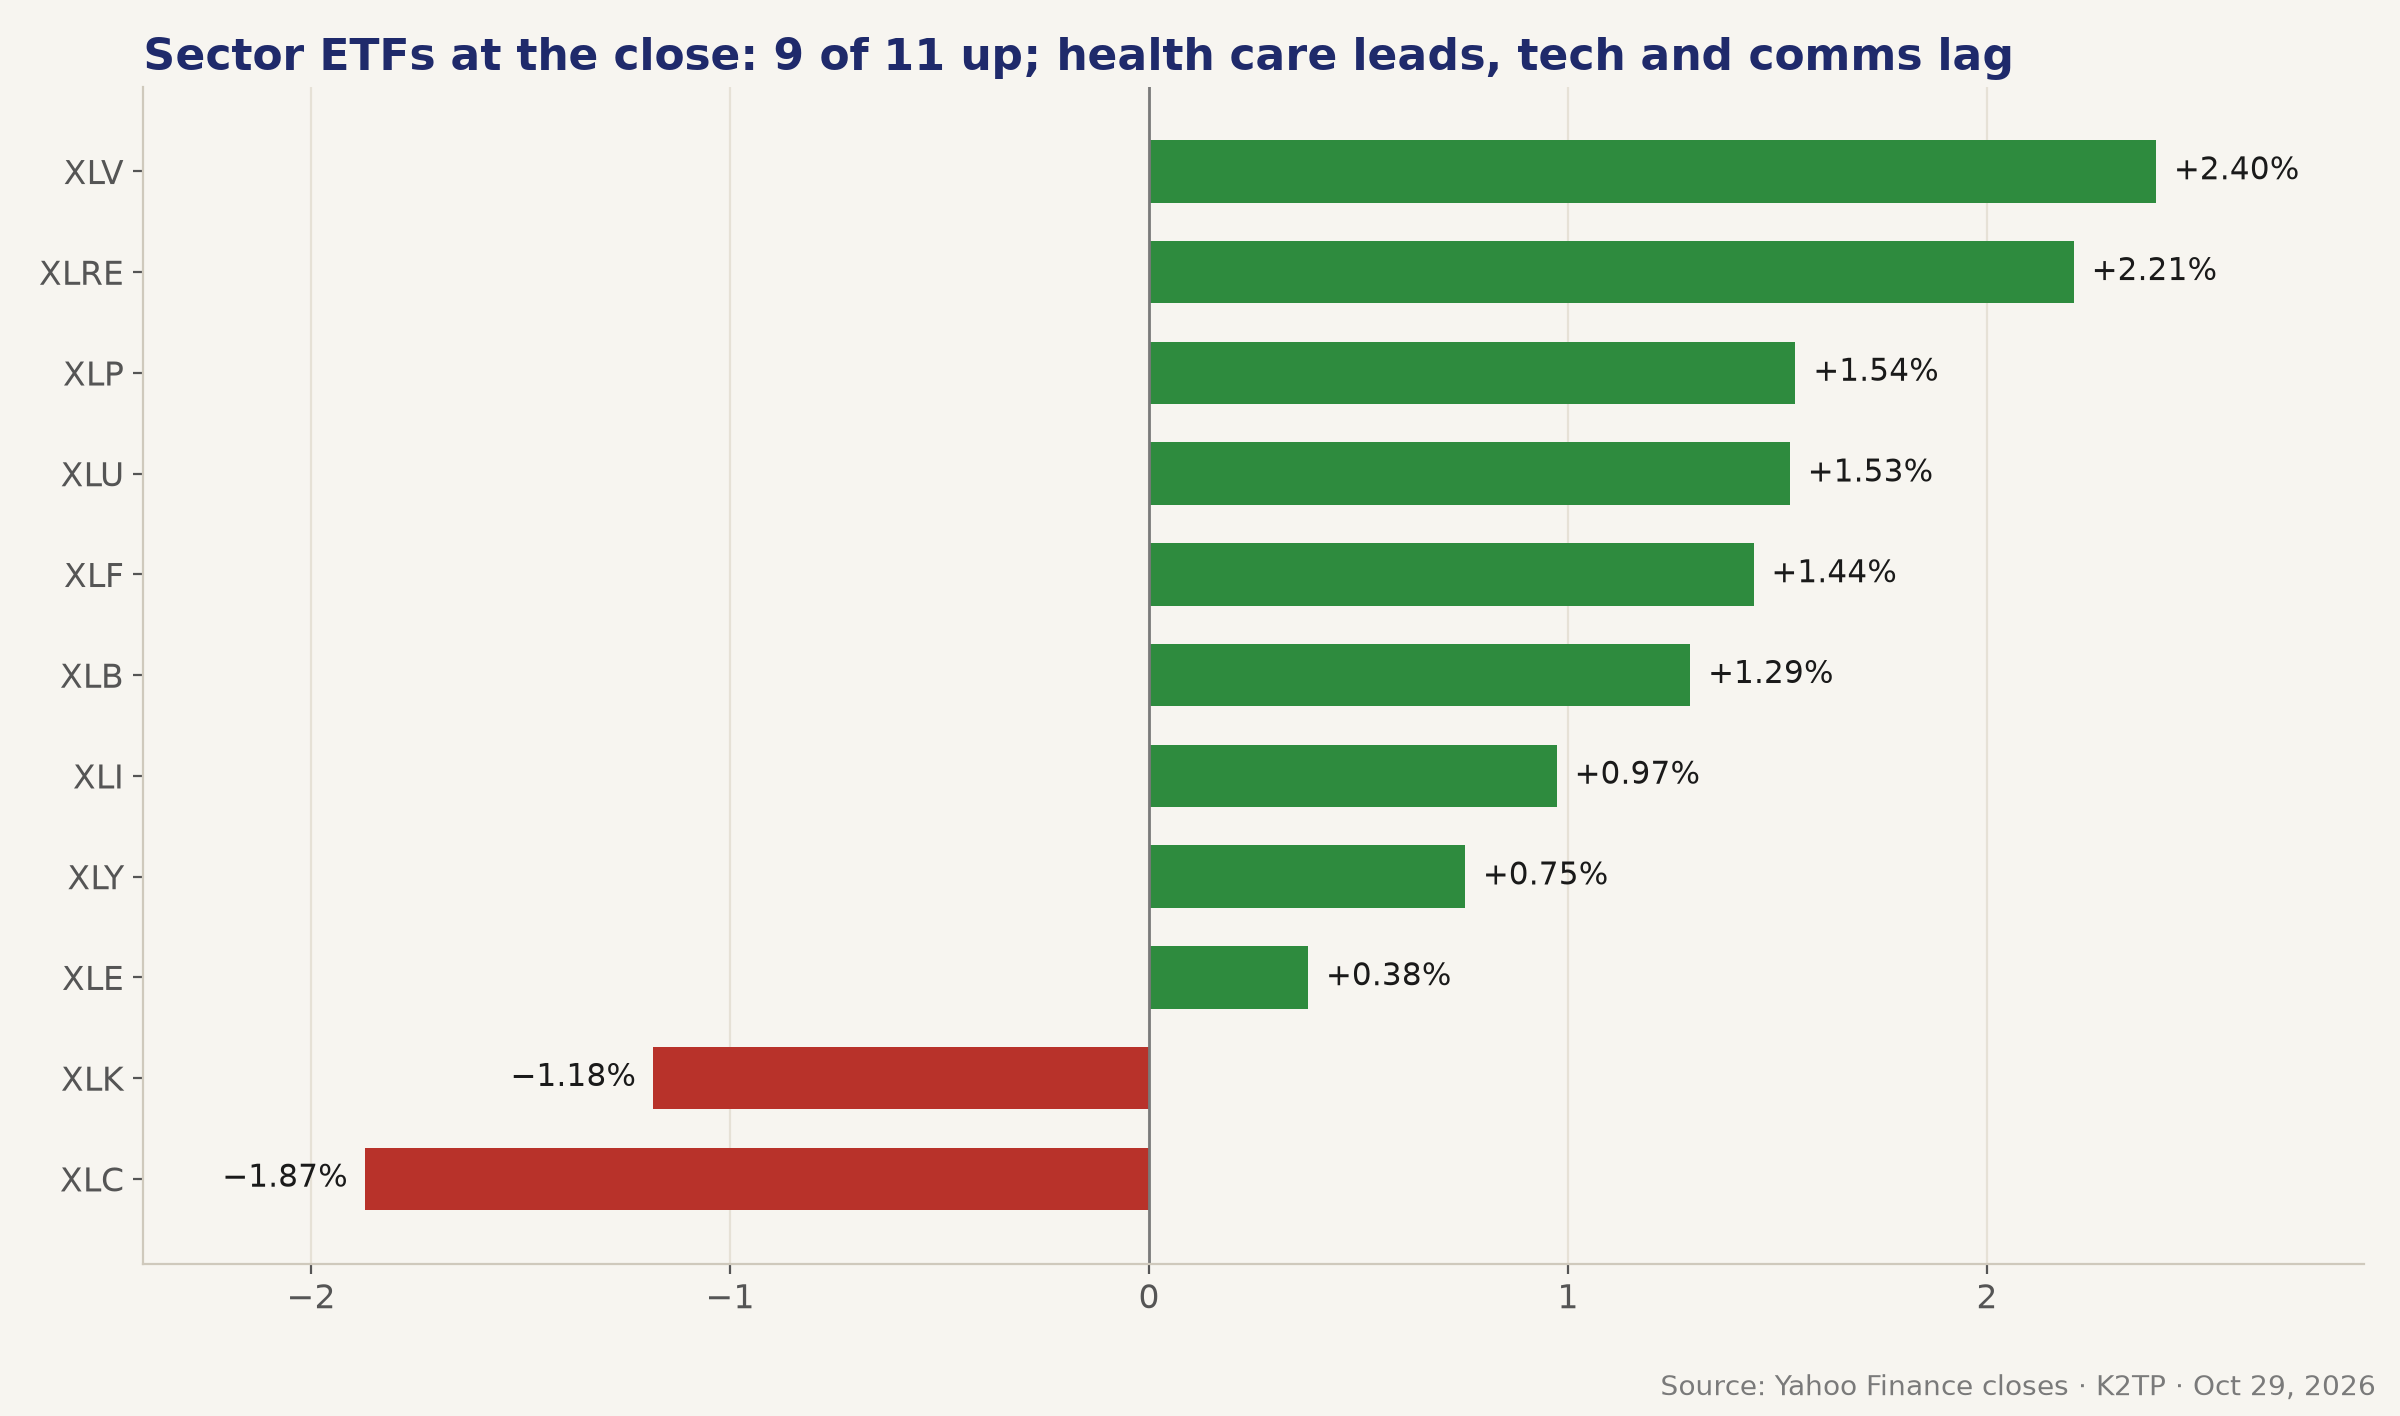
- The strongest rotation of the week: RSP (equal-weight) +1.20%, beating SPX by 150 bp; 9 of 11 sector ETFs rose, led by XLV +2.40% and XLRE +2.21%; XLC −1.87%, XLK −1.18%
- 5:30 AM PT data: Q3 GDP 3.4% vs 3.2% expected; PCE 3.6% y/y and core PCE 3.1% y/y, both in line; initial jobless claims 194K vs 198K
- Reaction to Wednesday night's earnings: GOOGL −12.64%, NOW −26.95%, FTNT −20.09%; CAT −9.25% despite a beat; LLY +6.63% after raising 2026 revenue guidance to $91B–$92B
- Deals: DoorDash agreed to buy Maplebear (Instacart) for $65 per share, DASH +5.61%; Bloomberg reported Marvell is in talks to buy Lumentum, MRVL −13.24%
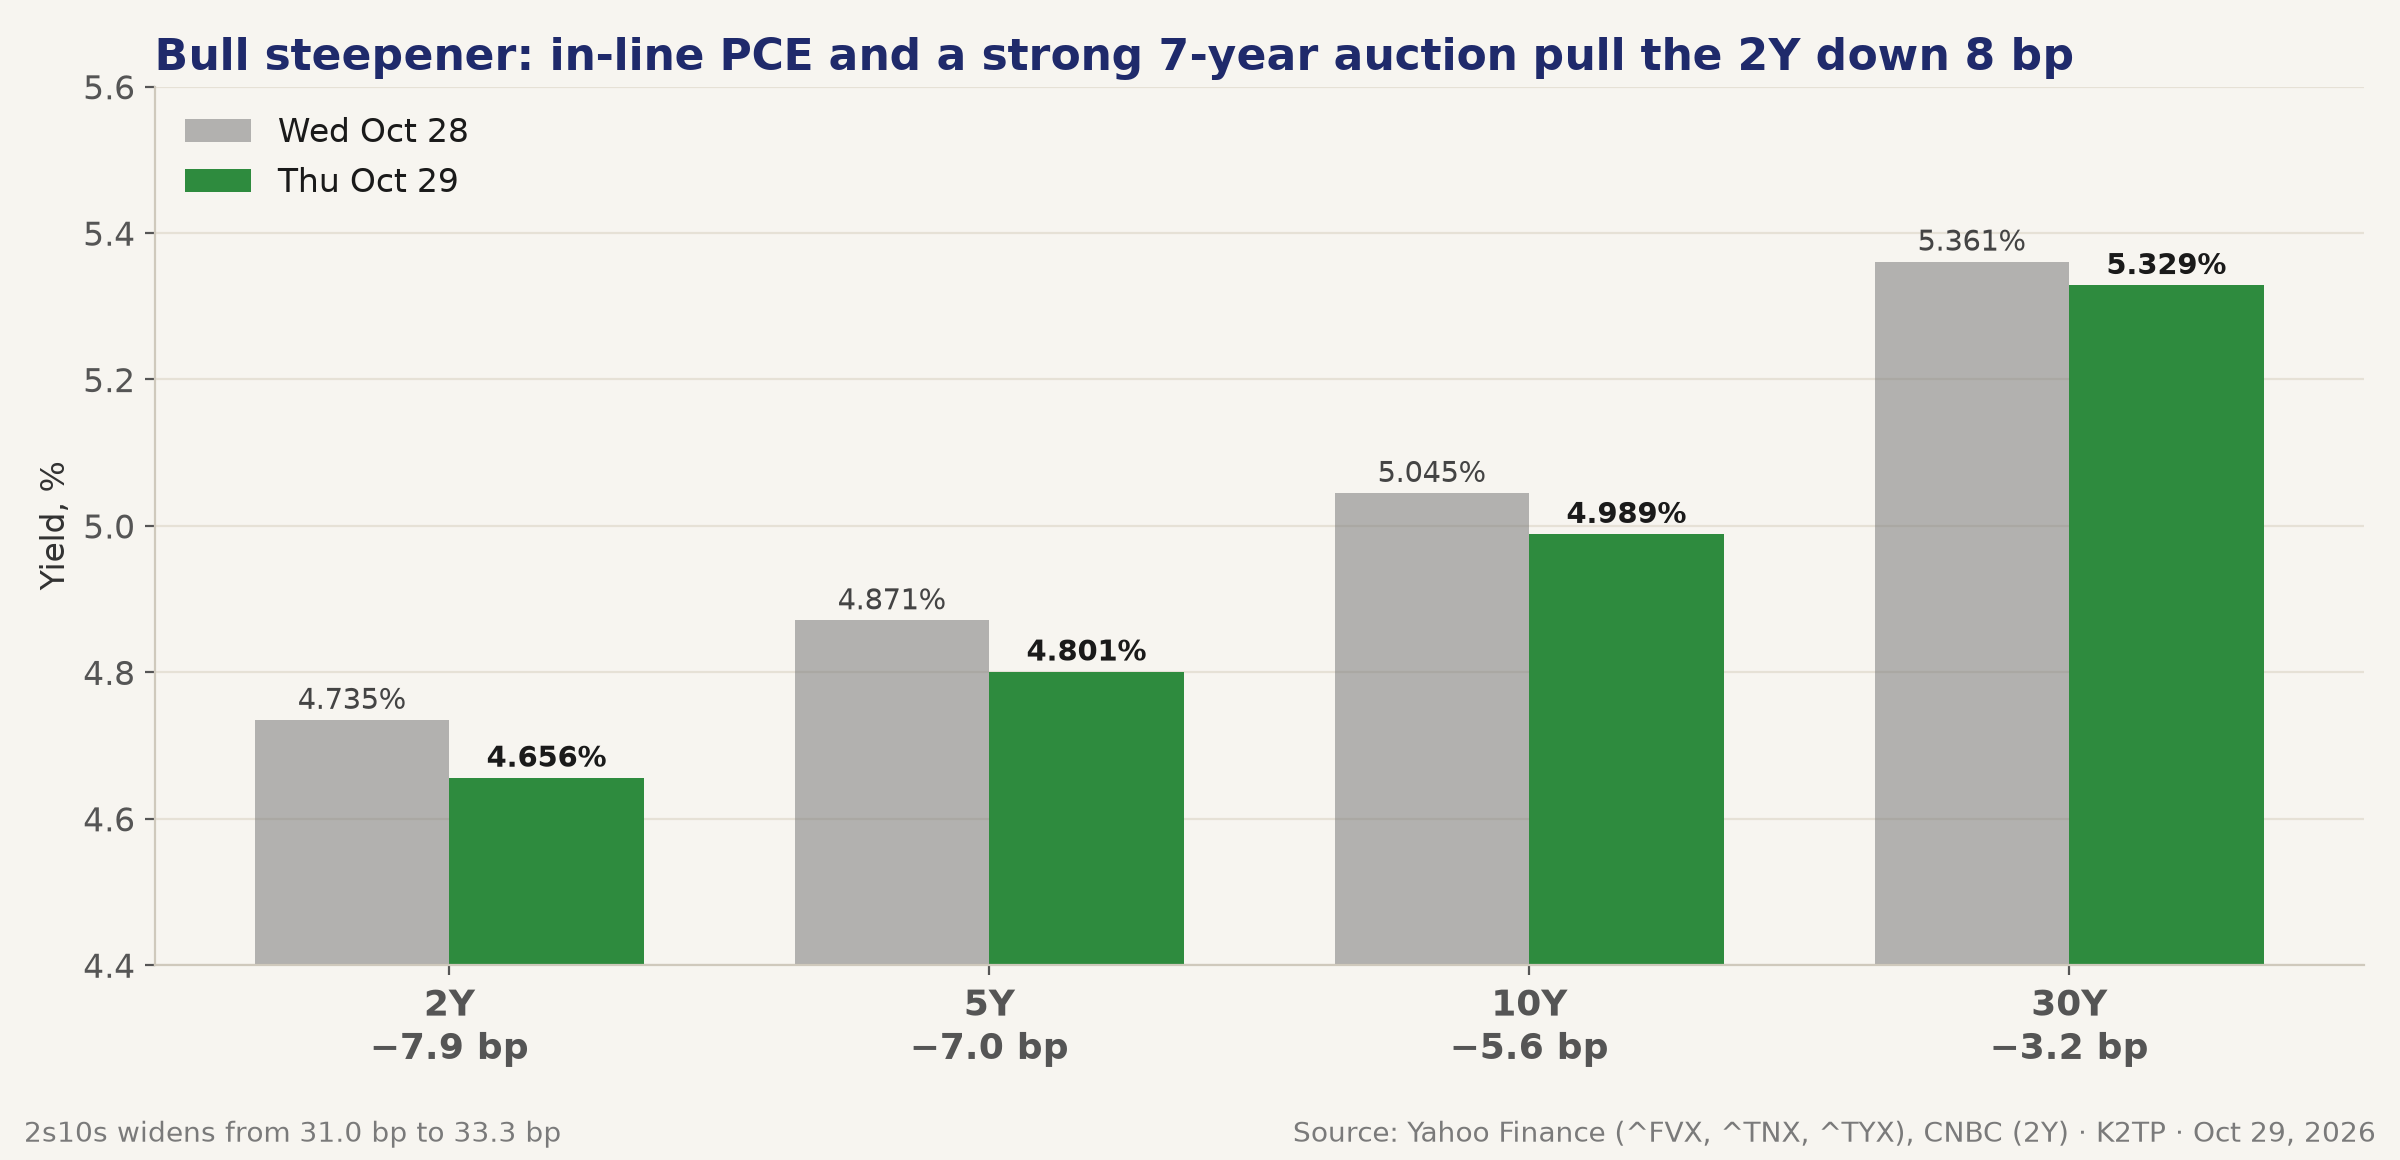
- Bull steepener: 2Y −7.9 bp to 4.656%, 10Y −5.6 bp to 4.989%; the 7-year auction stopped at 4.894%, on the screws, with a 2.46 bid-to-cover
- The ECB held at 2.50%; according to sources, ECB officials are ready to hike in December
- After hours: Intel −23.01% on Q4 revenue guidance of $15B–$16B vs $17.1B expected; Amazon −7.30% on quarterly capex of $77.3B and trailing FCF of −$42.4B despite AWS +39%
- The Houthis claimed attacks on Saudi oil sites (Ras Tanura, Abqaiq, Rabigh); UKMTO reported a vessel on fire in the Strait of Hormuz at about 4:57 PM PT; WTI about $104.80 at 6:52 PM PT
- Regime: 🟡 TRANSITION (from 🟢 RISK-ON); ES implies an SPX open below the 7,677.16 line; the Employment Cost Index (ECI) is due Friday at 5:30 AM PT
STRONG GDP, IN-LINE PCE, LOWER YIELDS
- Q3 advance GDP 3.4% vs 3.2% expected (prior 2.2%); GDP price index 2.3% vs 3.2% expected (Pre-Market brief) 🟢
- September PCE: 3.6% y/y (+0.5% m/m), core 3.1% y/y (+0.3% m/m), in line; personal spending +0.5% vs 0.6%; initial jobless claims 194K vs 198K
- 7-year auction: 4.894%, on the screws, bid-to-cover 2.46, indirect 57.77% (Pre-Close brief)
- Closing yields: 2Y 4.656% (−7.9 bp), 5Y 4.801% (−7.0 bp), 10Y 4.989% (−5.6 bp, back below 5%), 30Y 5.329% (−3.2 bp); 2s10s widened from 31.0 bp to 33.3 bp
- Tonight, per the Evening Recap: 2Y near 4.565% and 10Y near 4.90% as the bond rally continues
- Freddie Mac 30-year mortgage rate 7.24% (Midday brief); an updated FedWatch reading after the rally is unavailable
→ PCE was not hotter than feared and the 7-year auction went smoothly, so the front end rallied most. A 2Y down about 17 bp from Wednesday's close to tonight says the market is pricing out part of the post-FOMC hike risk, and Friday morning's ECI is the next test.
TECH SELLS OFF, THE REST OF THE MARKET RALLIES
- FinancialJuice summed up the session as a tech selloff that sparked a broad rotation while bonds rallied (Evening Recap) 🟢
- 9 of 11 sector ETFs rose: XLV +2.40%, XLRE +2.21%, XLP +1.54%, XLU +1.53%, XLF +1.44%, XLB +1.29%, XLI +0.97%, XLY +0.75%, XLE +0.38%; XLK −1.18%, XLC −1.87%
- RSP +1.20% and IWM +0.97% beat SPY −0.38% and QQQ −1.42%; RUT +1.01%
- NDX −1.38% and SOX −1.42% pulled SPX lower even though most stocks rose
- The MOC imbalance showed about $4.48B to buy for the S&P 500; NYSE advance/decline data are unavailable
→ This was the best breadth of the week, but the cap-weighted index still fell on mega-cap tech. Money moved into rate-sensitive and defensive groups as yields fell rather than leaving the market.
EARNINGS: ALPHABET AND SERVICENOW PUNISHED, LILLY AND MASTERCARD REWARDED
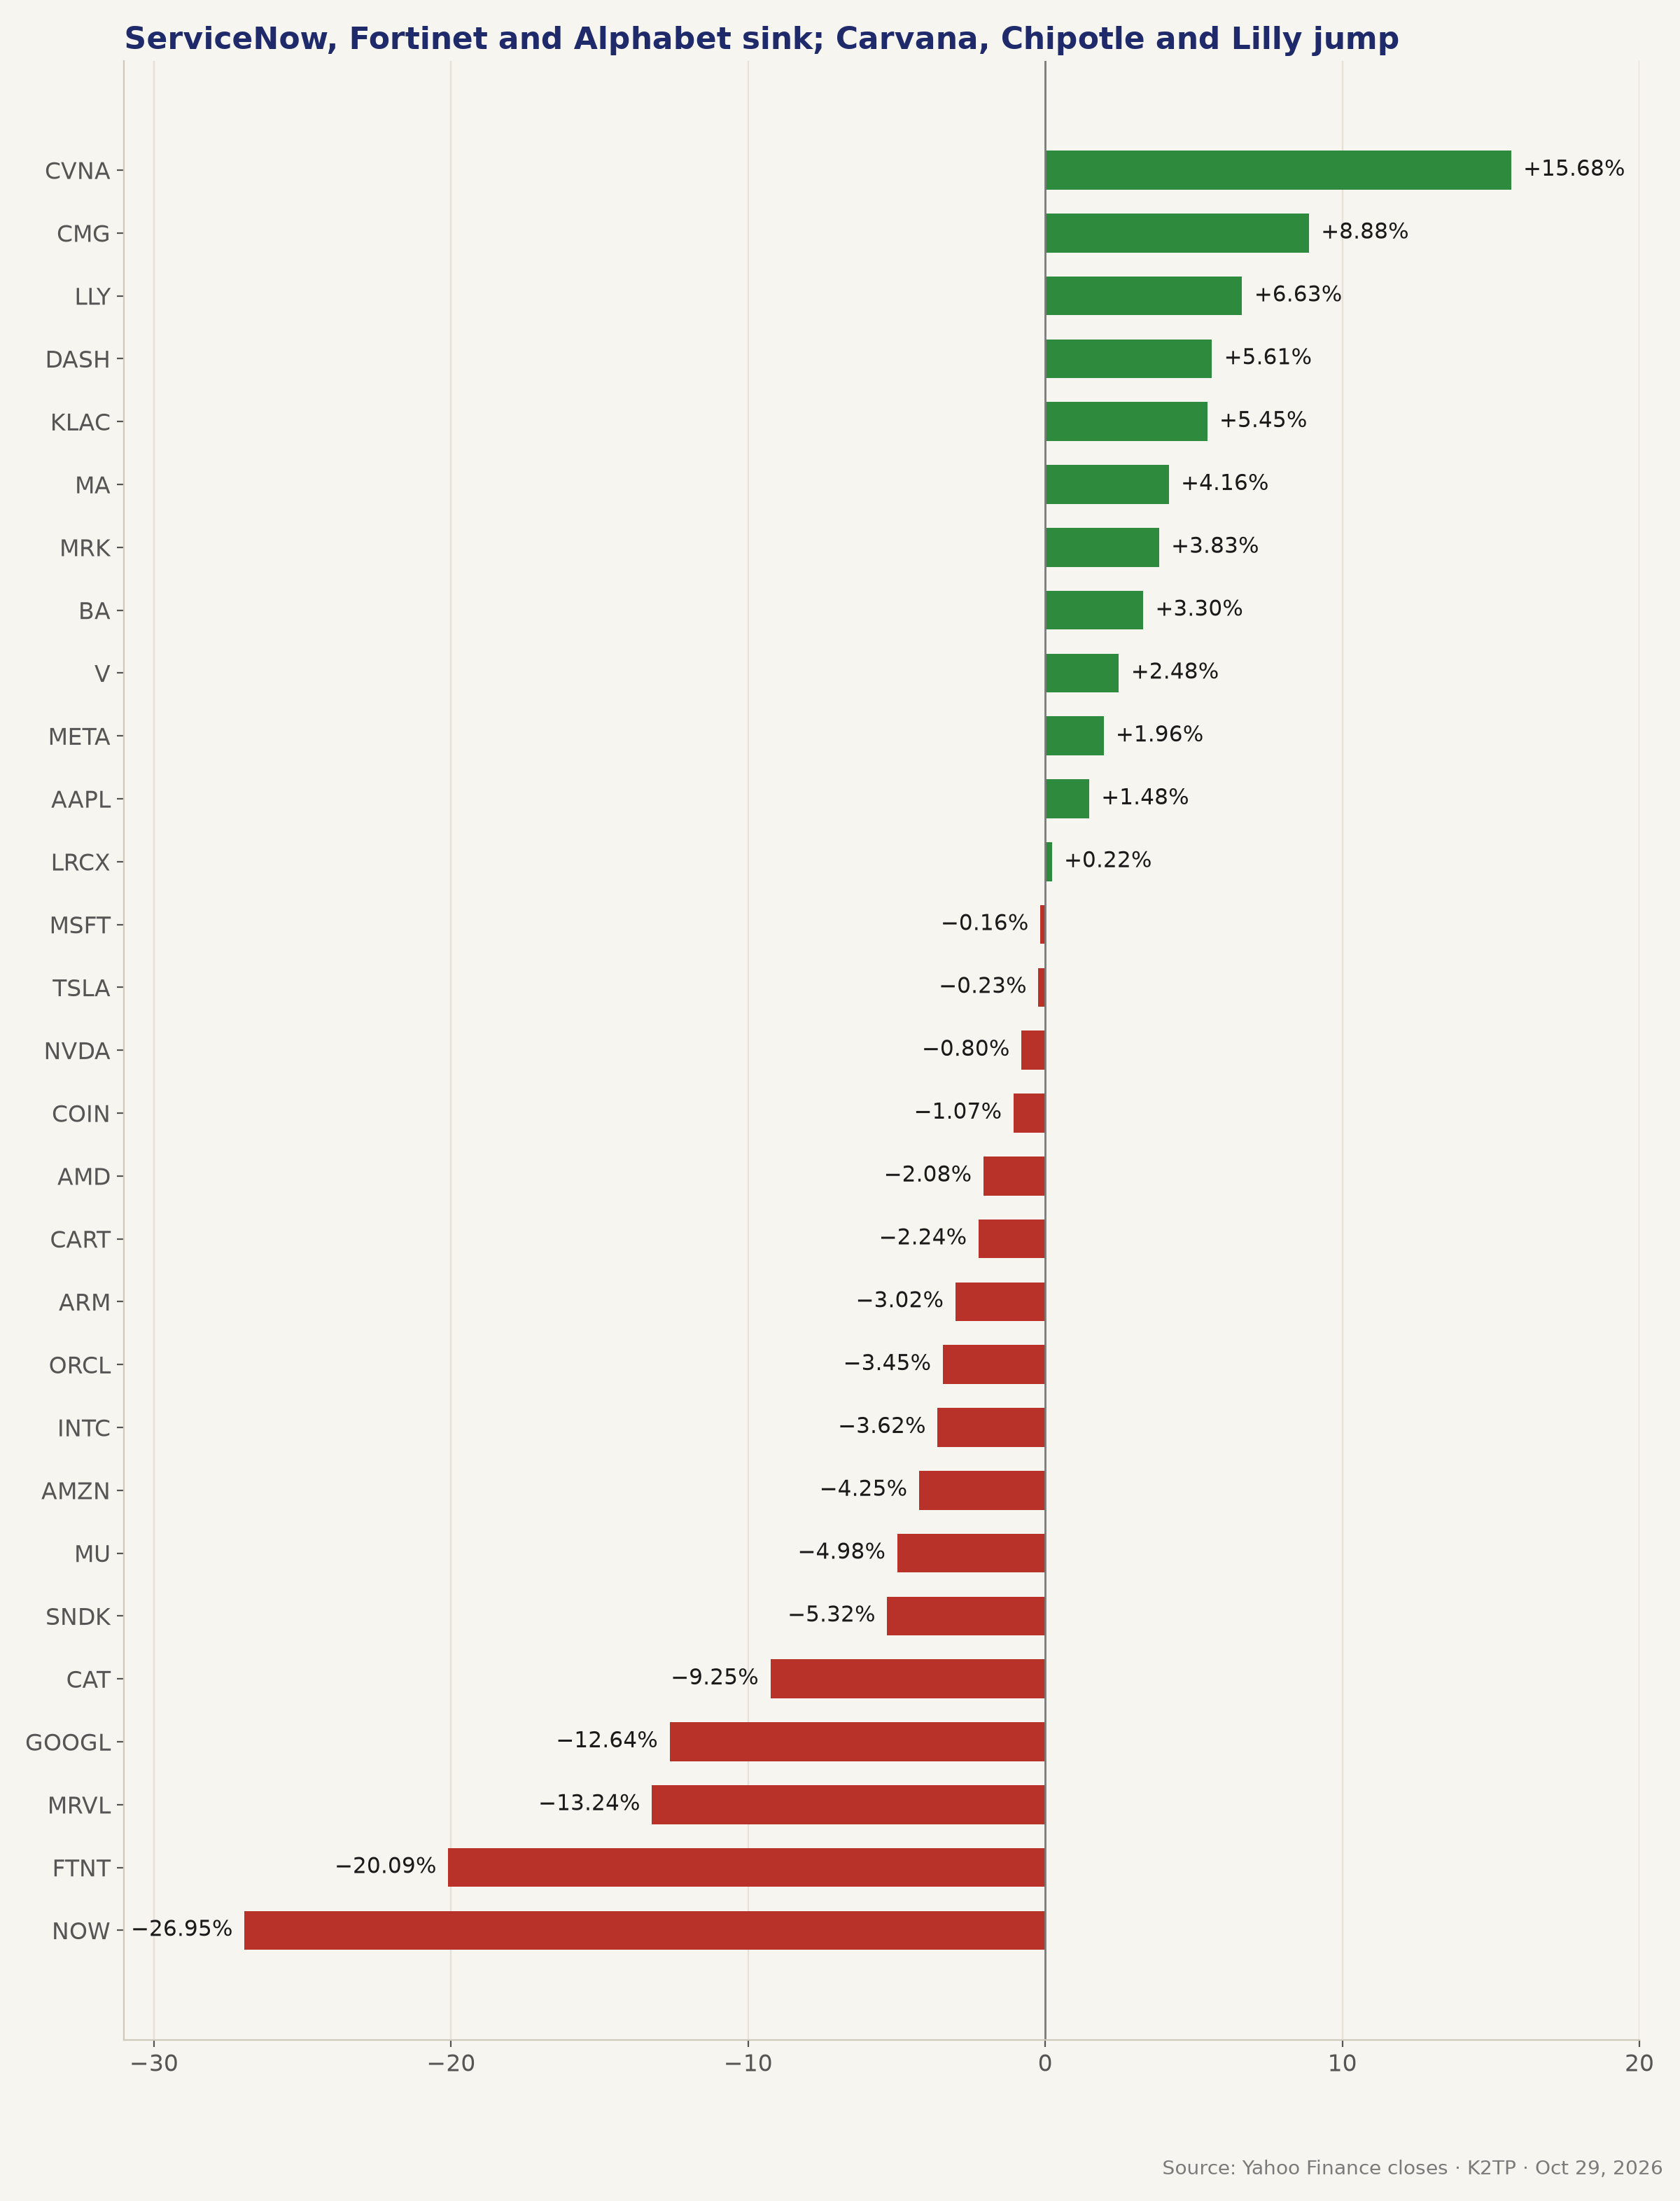
- Alphabet: GOOGL −12.64% to 283.82 after Search revenue of $63.35B missed the $64.96B estimate and free cash flow turned negative (reported Wednesday night) 🔴
- ServiceNow −26.95% to 109.67; Fortinet −20.09% to 139.10; Marvell −13.24% on the reported Lumentum talks
- Caterpillar: adj. EPS $7.20 vs $7.08, revenue $20.68B vs $20.55B, 2026 outlook kept, yet CAT −9.25% to 647.39
- Eli Lilly: adj. EPS $7.48, revenue $24.40B, 2026 revenue guidance raised to $91B–$92B; LLY +6.63% to 1,373.70; MRK +3.83%
- Mastercard: adj. EPS $5.31 vs $5.17, revenue $9.8B; MA +4.16%, V +2.48%
- Other big gainers: CVNA +15.68%, CMG +8.88%, DASH +5.61%, KLAC +5.45%, BA +3.30%; META +1.96%, AAPL +1.48%
- Microsoft launched a bond sale of at least $25B; MSFT −0.16% (Pre-Market brief)
→ The market hit software and Alphabet hard but rewarded names with clear cash generation such as Lilly and Mastercard. The rotation out of AI mega-caps was the session's main theme.
AFTER HOURS: AMAZON FACES THE CAPEX-VERSUS-FCF TEST
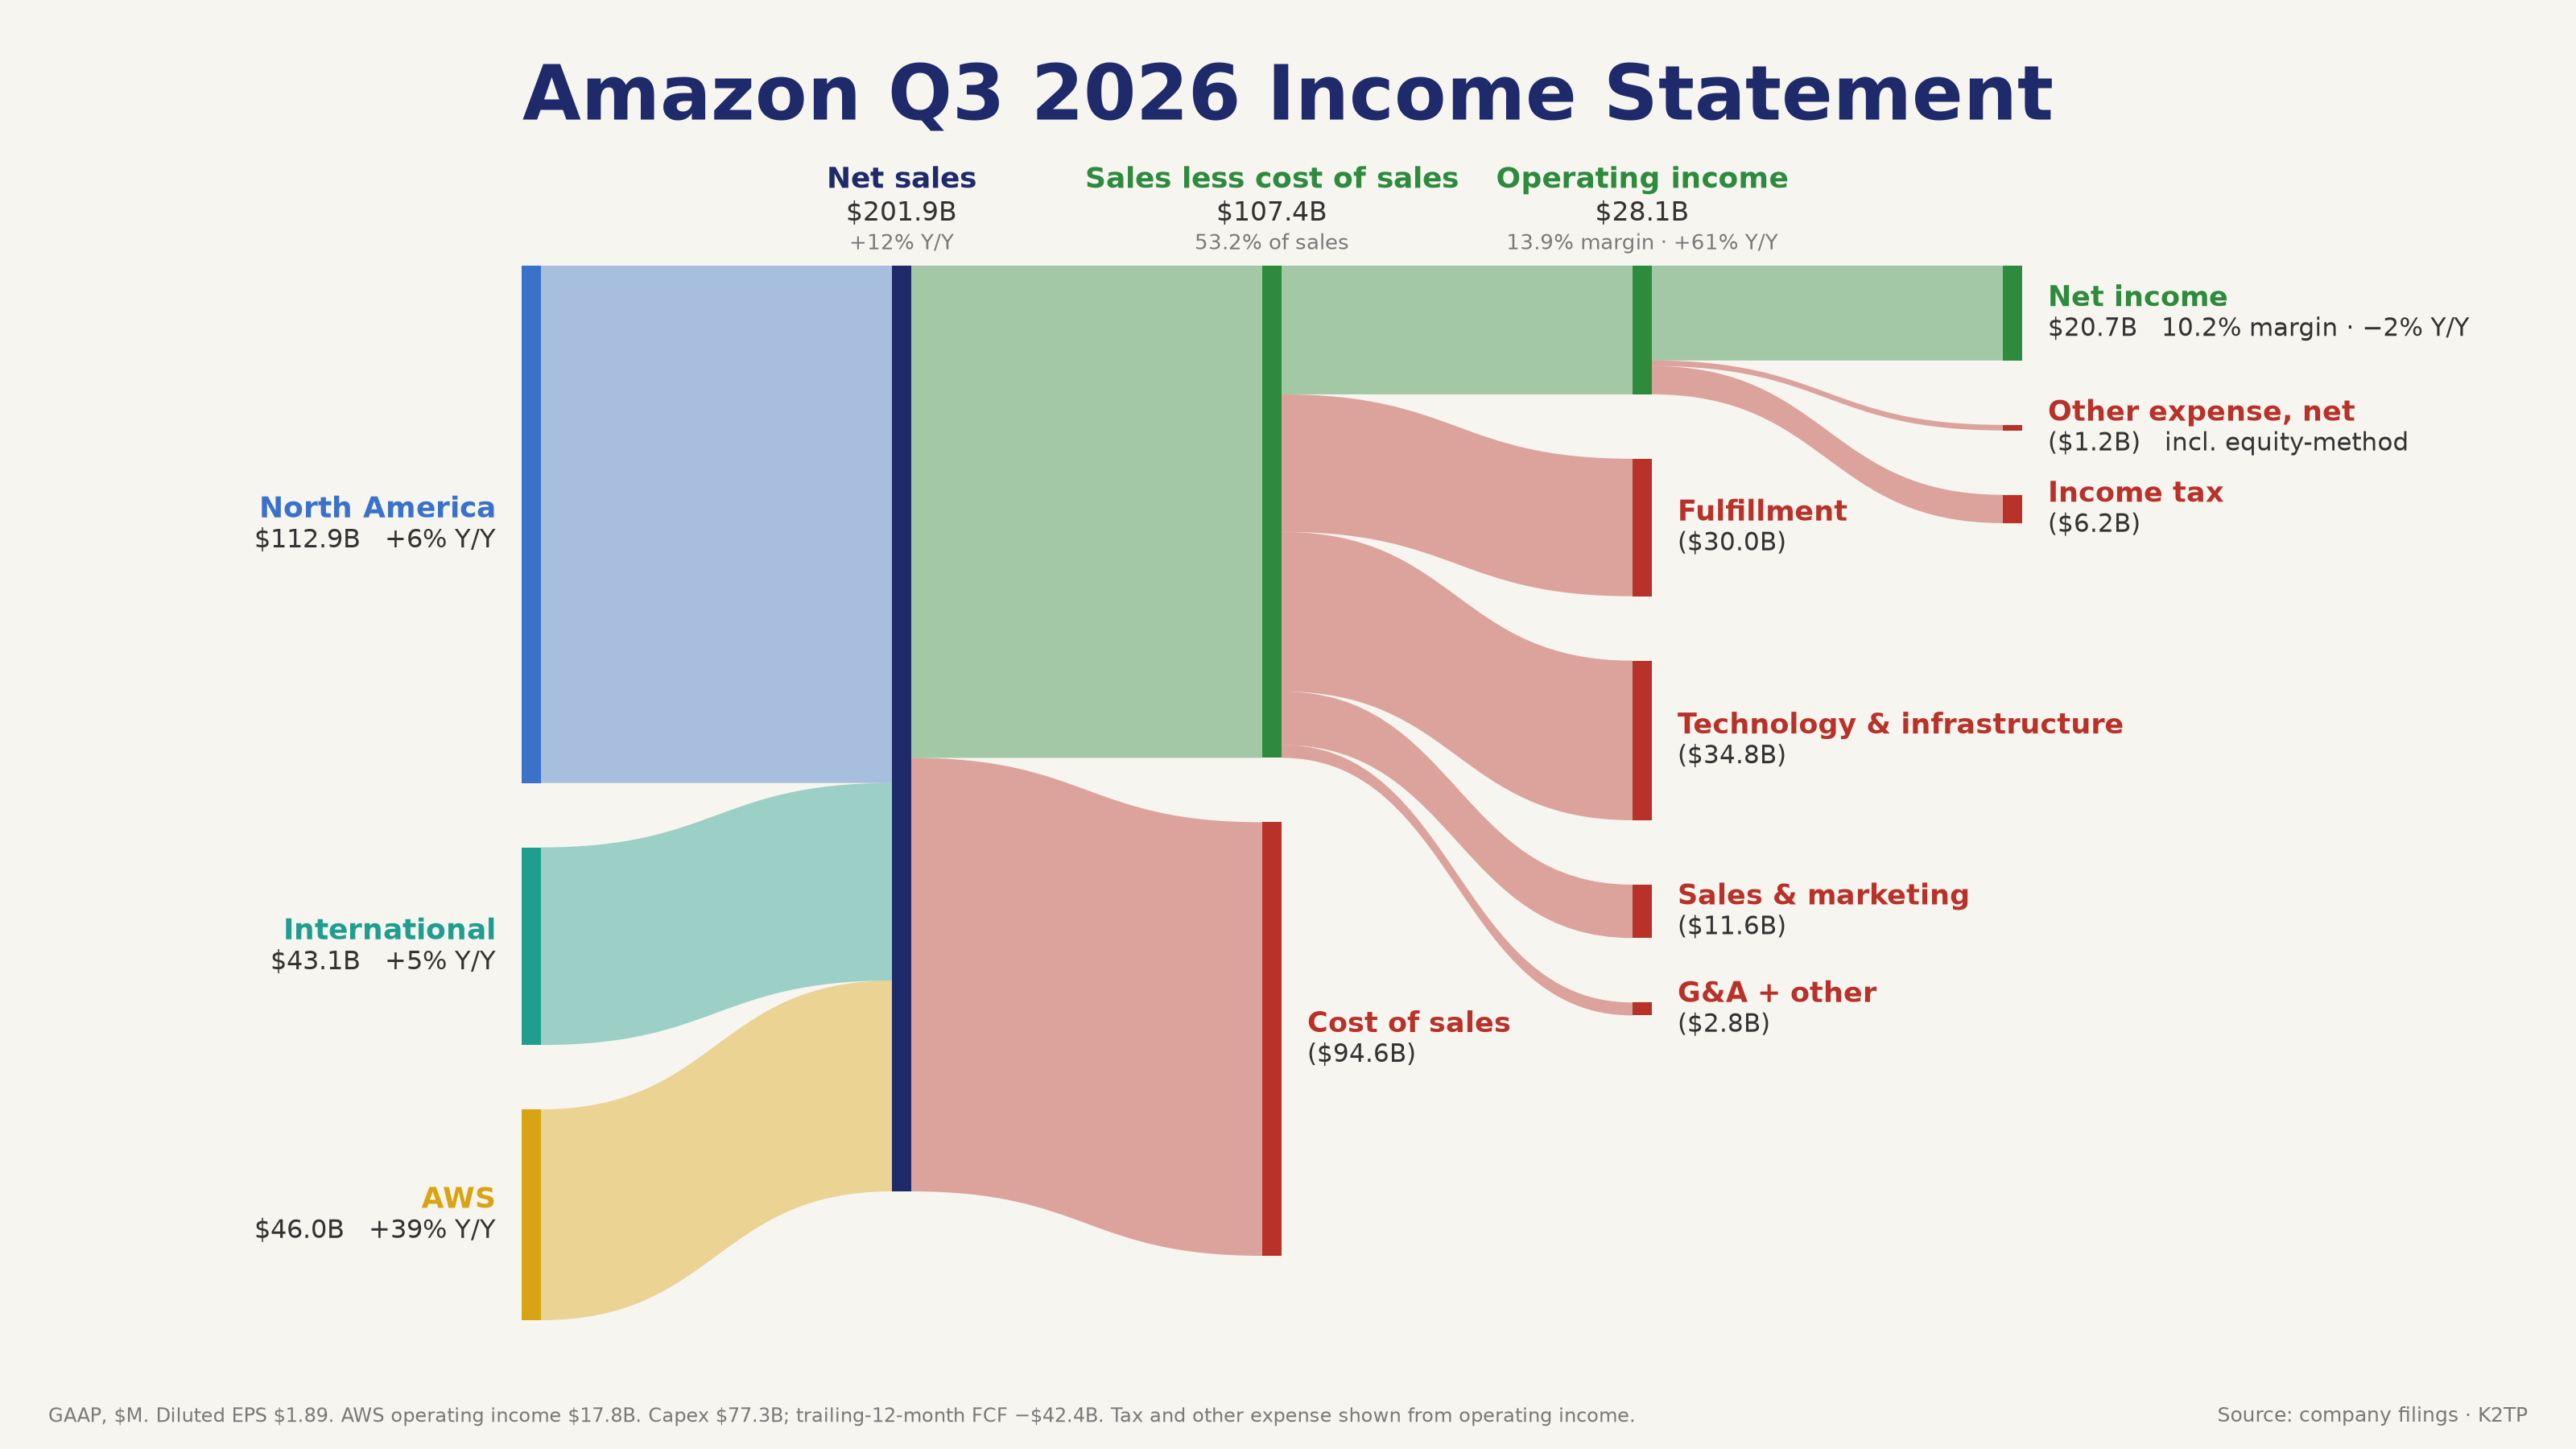
- Amazon (8-K Ex. 99.1, Q3 2026): net sales $201.94B (+12%) vs $202.31B expected; EPS $1.89 vs $1.96; operating income $28.08B, a 13.9% margin and Amazon's highest ever 🔴
- By segment: North America $112.85B (+6%), International $43.11B (+5%), AWS $45.98B (+39%); AWS operating income $17.77B
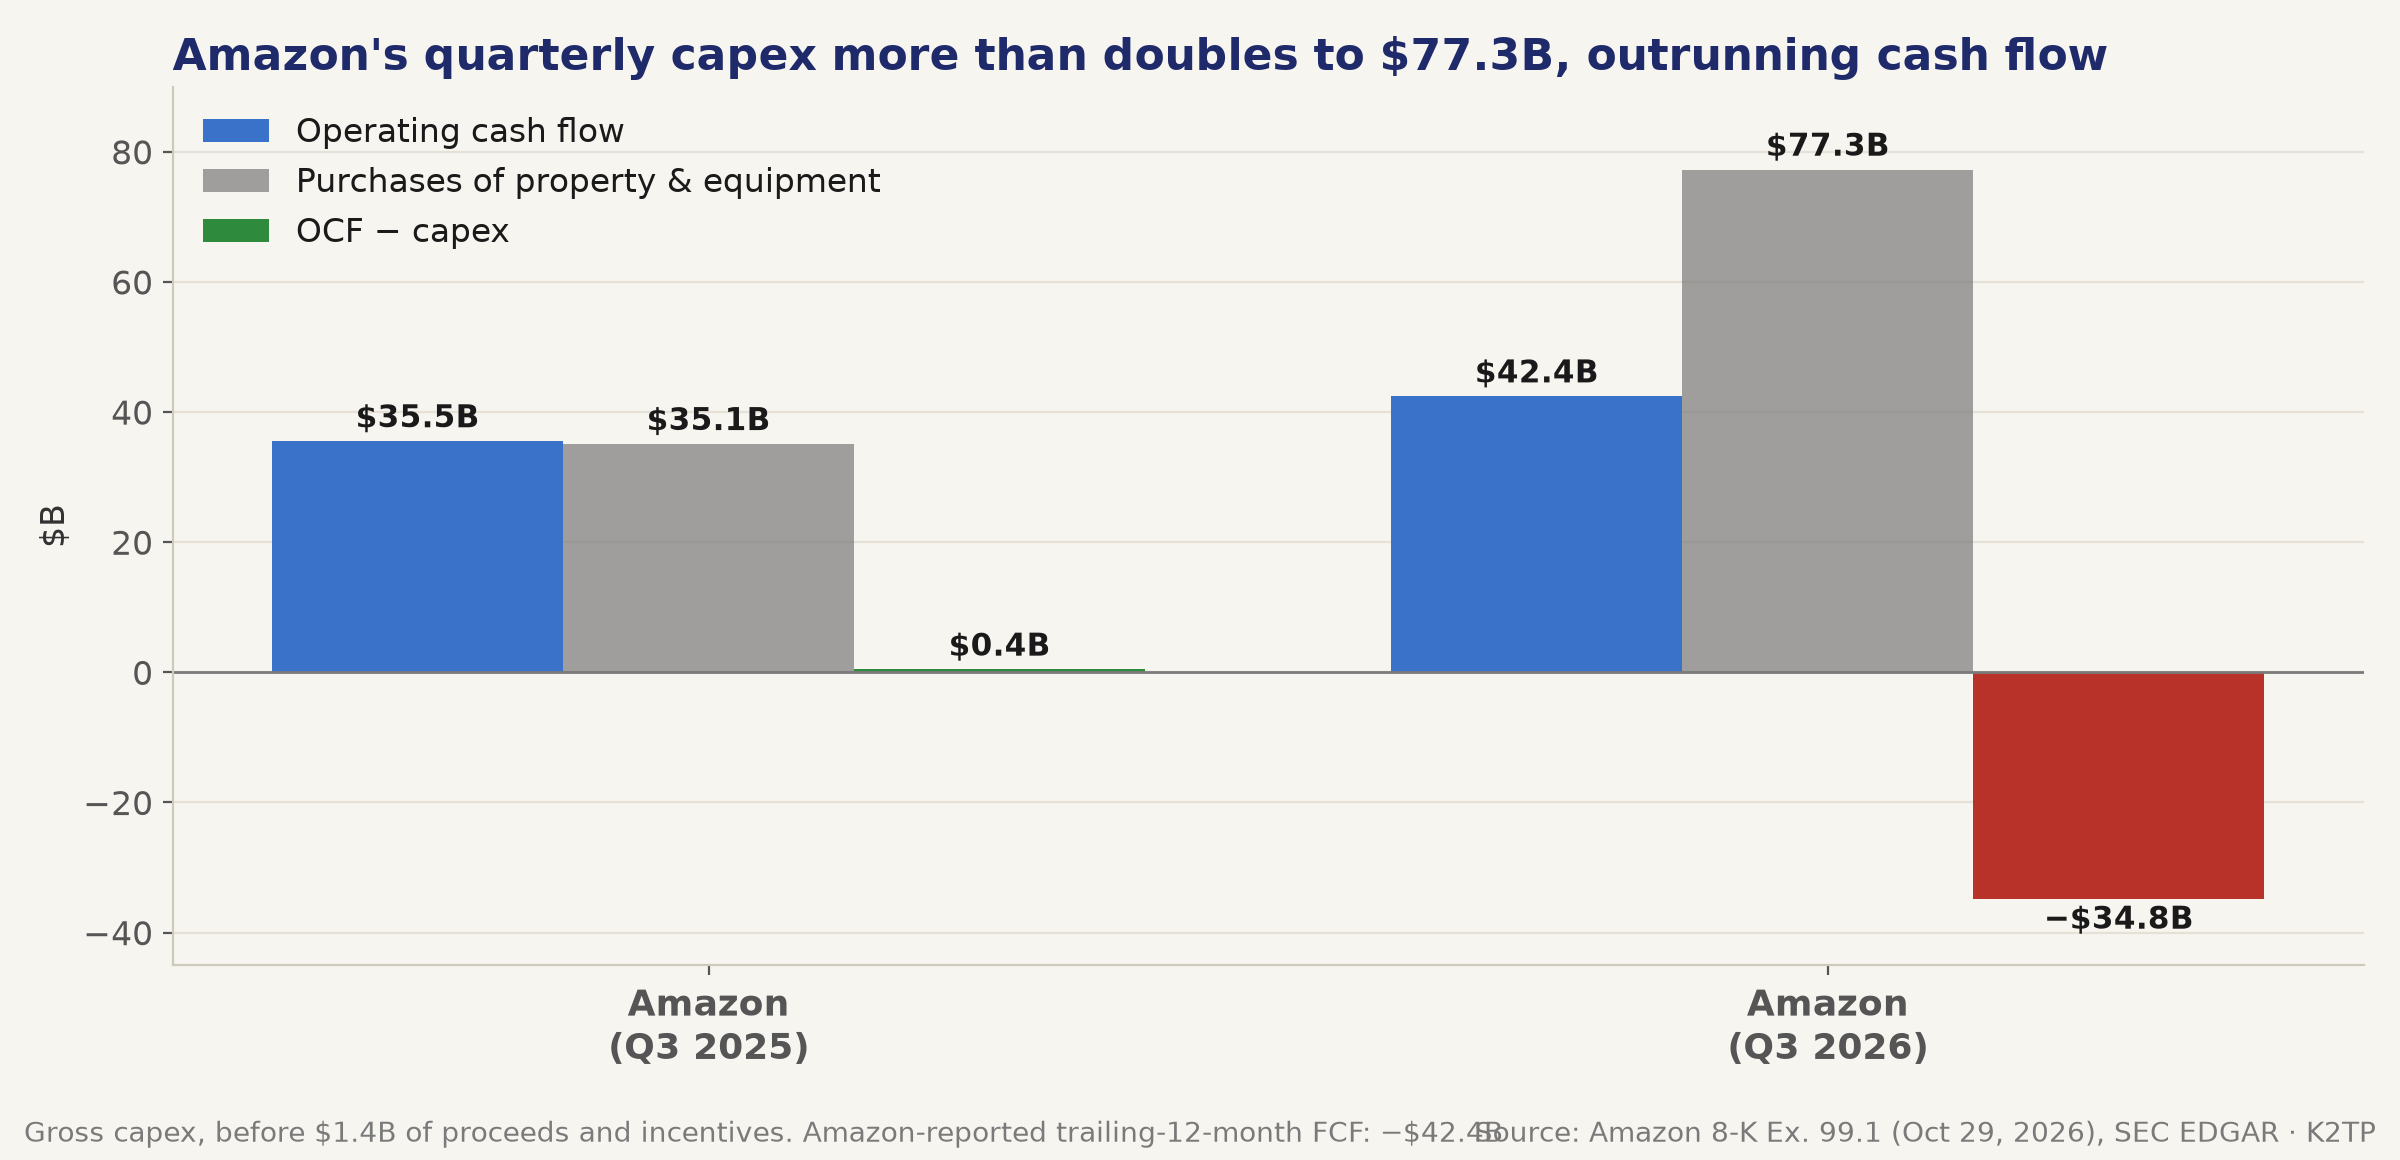
- Capex (purchases of property and equipment) of $77.26B in the quarter vs $35.10B a year ago, against operating cash flow of $42.42B; Amazon-reported trailing-12-month FCF −$42.4B
- Q4 guidance: net sales $240B–$247B, around the $244.5B estimate; operating income $28.5B–$33.5B
- AMZN −4.25% to 243.79 in the regular session, then −7.30% to 225.99 after hours
→ As with Alphabet on Wednesday, the market punished AI capex that drives free cash flow negative. AWS's fastest growth in nearly five years was not enough to offset that spending.
AFTER HOURS: INTEL'S GUIDE DRAGS THE CHIPS
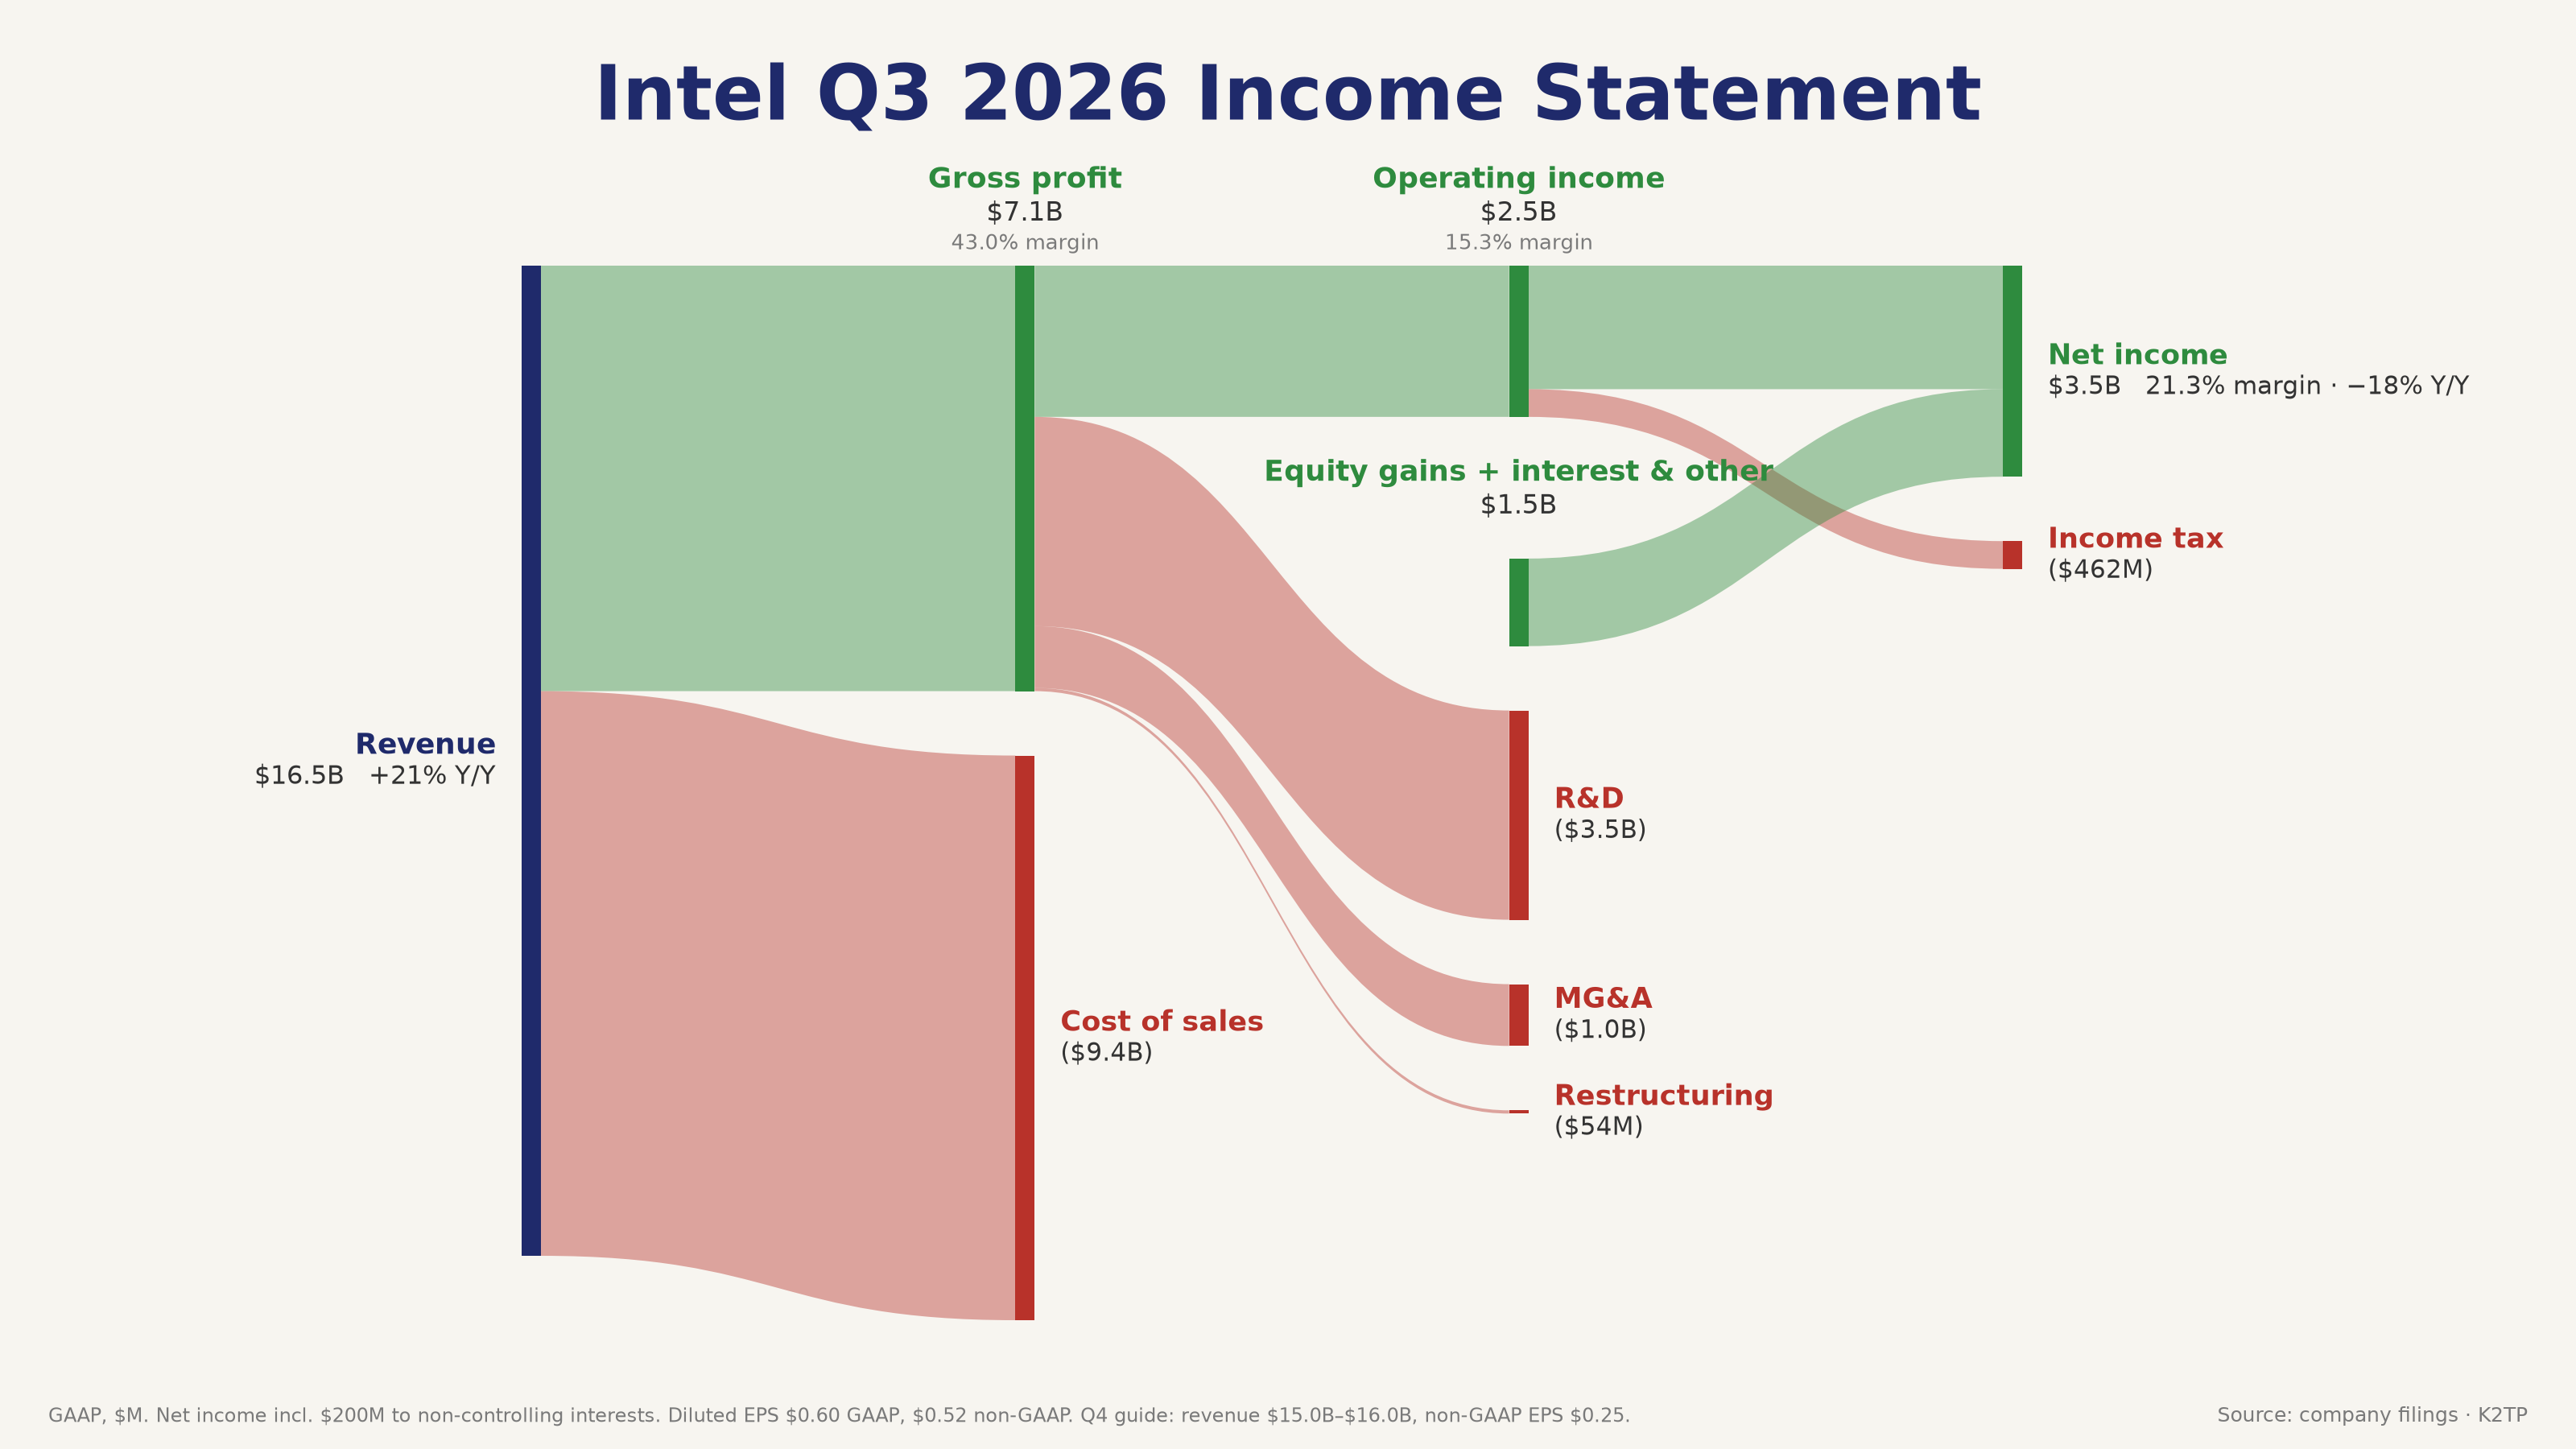
- Intel (8-K Ex. 99.1, Q3 2026): revenue $16.51B (+21%); gross margin 43.0%; EPS $0.60 GAAP, $0.52 non-GAAP vs $0.40 expected 🔴
- Data Center and AI $7.3B (+78%), Client Computing and Physical AI $8.1B (−5%), Intel Foundry $6.7B (+58%)
- Q4 guidance: revenue $15.0B–$16.0B vs $17.1B expected; non-GAAP EPS $0.25 vs $0.43; non-GAAP gross margin 38.0%
- Per the Evening Recap, the reasons were a PC slowdown through at least the first half of 2027 and an Israel factory shutdown; CEO Lip-Bu Tan said CPU demand remains robust and the priority is more Xeon supply
- After-hours reaction: INTC −23.01% to 70.89, AMD −6.75%, MU −3.43%, AVGO −2.86%, NVDA −1.64%
- Other after-hours movers: Reddit −18.21%, Twilio −16.91%, Coinbase −4.74% (revenue $1.22B, in line), Starbucks −1.84% (comps +7.2%), Rivian +5.59%
→ Intel beat the quarter but guided weak, and the pressure spread across chips tonight. That is the biggest risk for NDX at Friday's open.
HORMUZ AND SAUDI ATTACKS PUSH OIL BACK UP
- Thursday morning three tankers hit mines in the Strait of Hormuz; Semafor reported peace-deal talks (unconfirmed) (Pre-Market brief) 🟡
- UKMTO reported a tanker struck at about 10:55 AM PT; December WTI settled at $102.00 (−0.76%) (Pre-Close brief)
- Just before the close the Houthis claimed attacks on Saudi Ras Tanura, Abqaiq and Rabigh; UKMTO reported a vessel on fire 25 nm northeast of Khasab at about 4:57 PM PT
- The US Department of Energy lent 16.75M barrels from the Strategic Petroleum Reserve (Evening Recap)
- Tonight (6:52 PM PT, Yahoo): WTI about $104.80, Brent about $113.84; gold $4,010.50
→ Oil is climbing tonight after the attacks on Saudi Arabia. If WTI holds above $100, the long-end rally will be hard to extend.
SPX: A LOW OPEN, A MORNING LOW, A RECOVERY TO 7,720 AT THE CLOSE
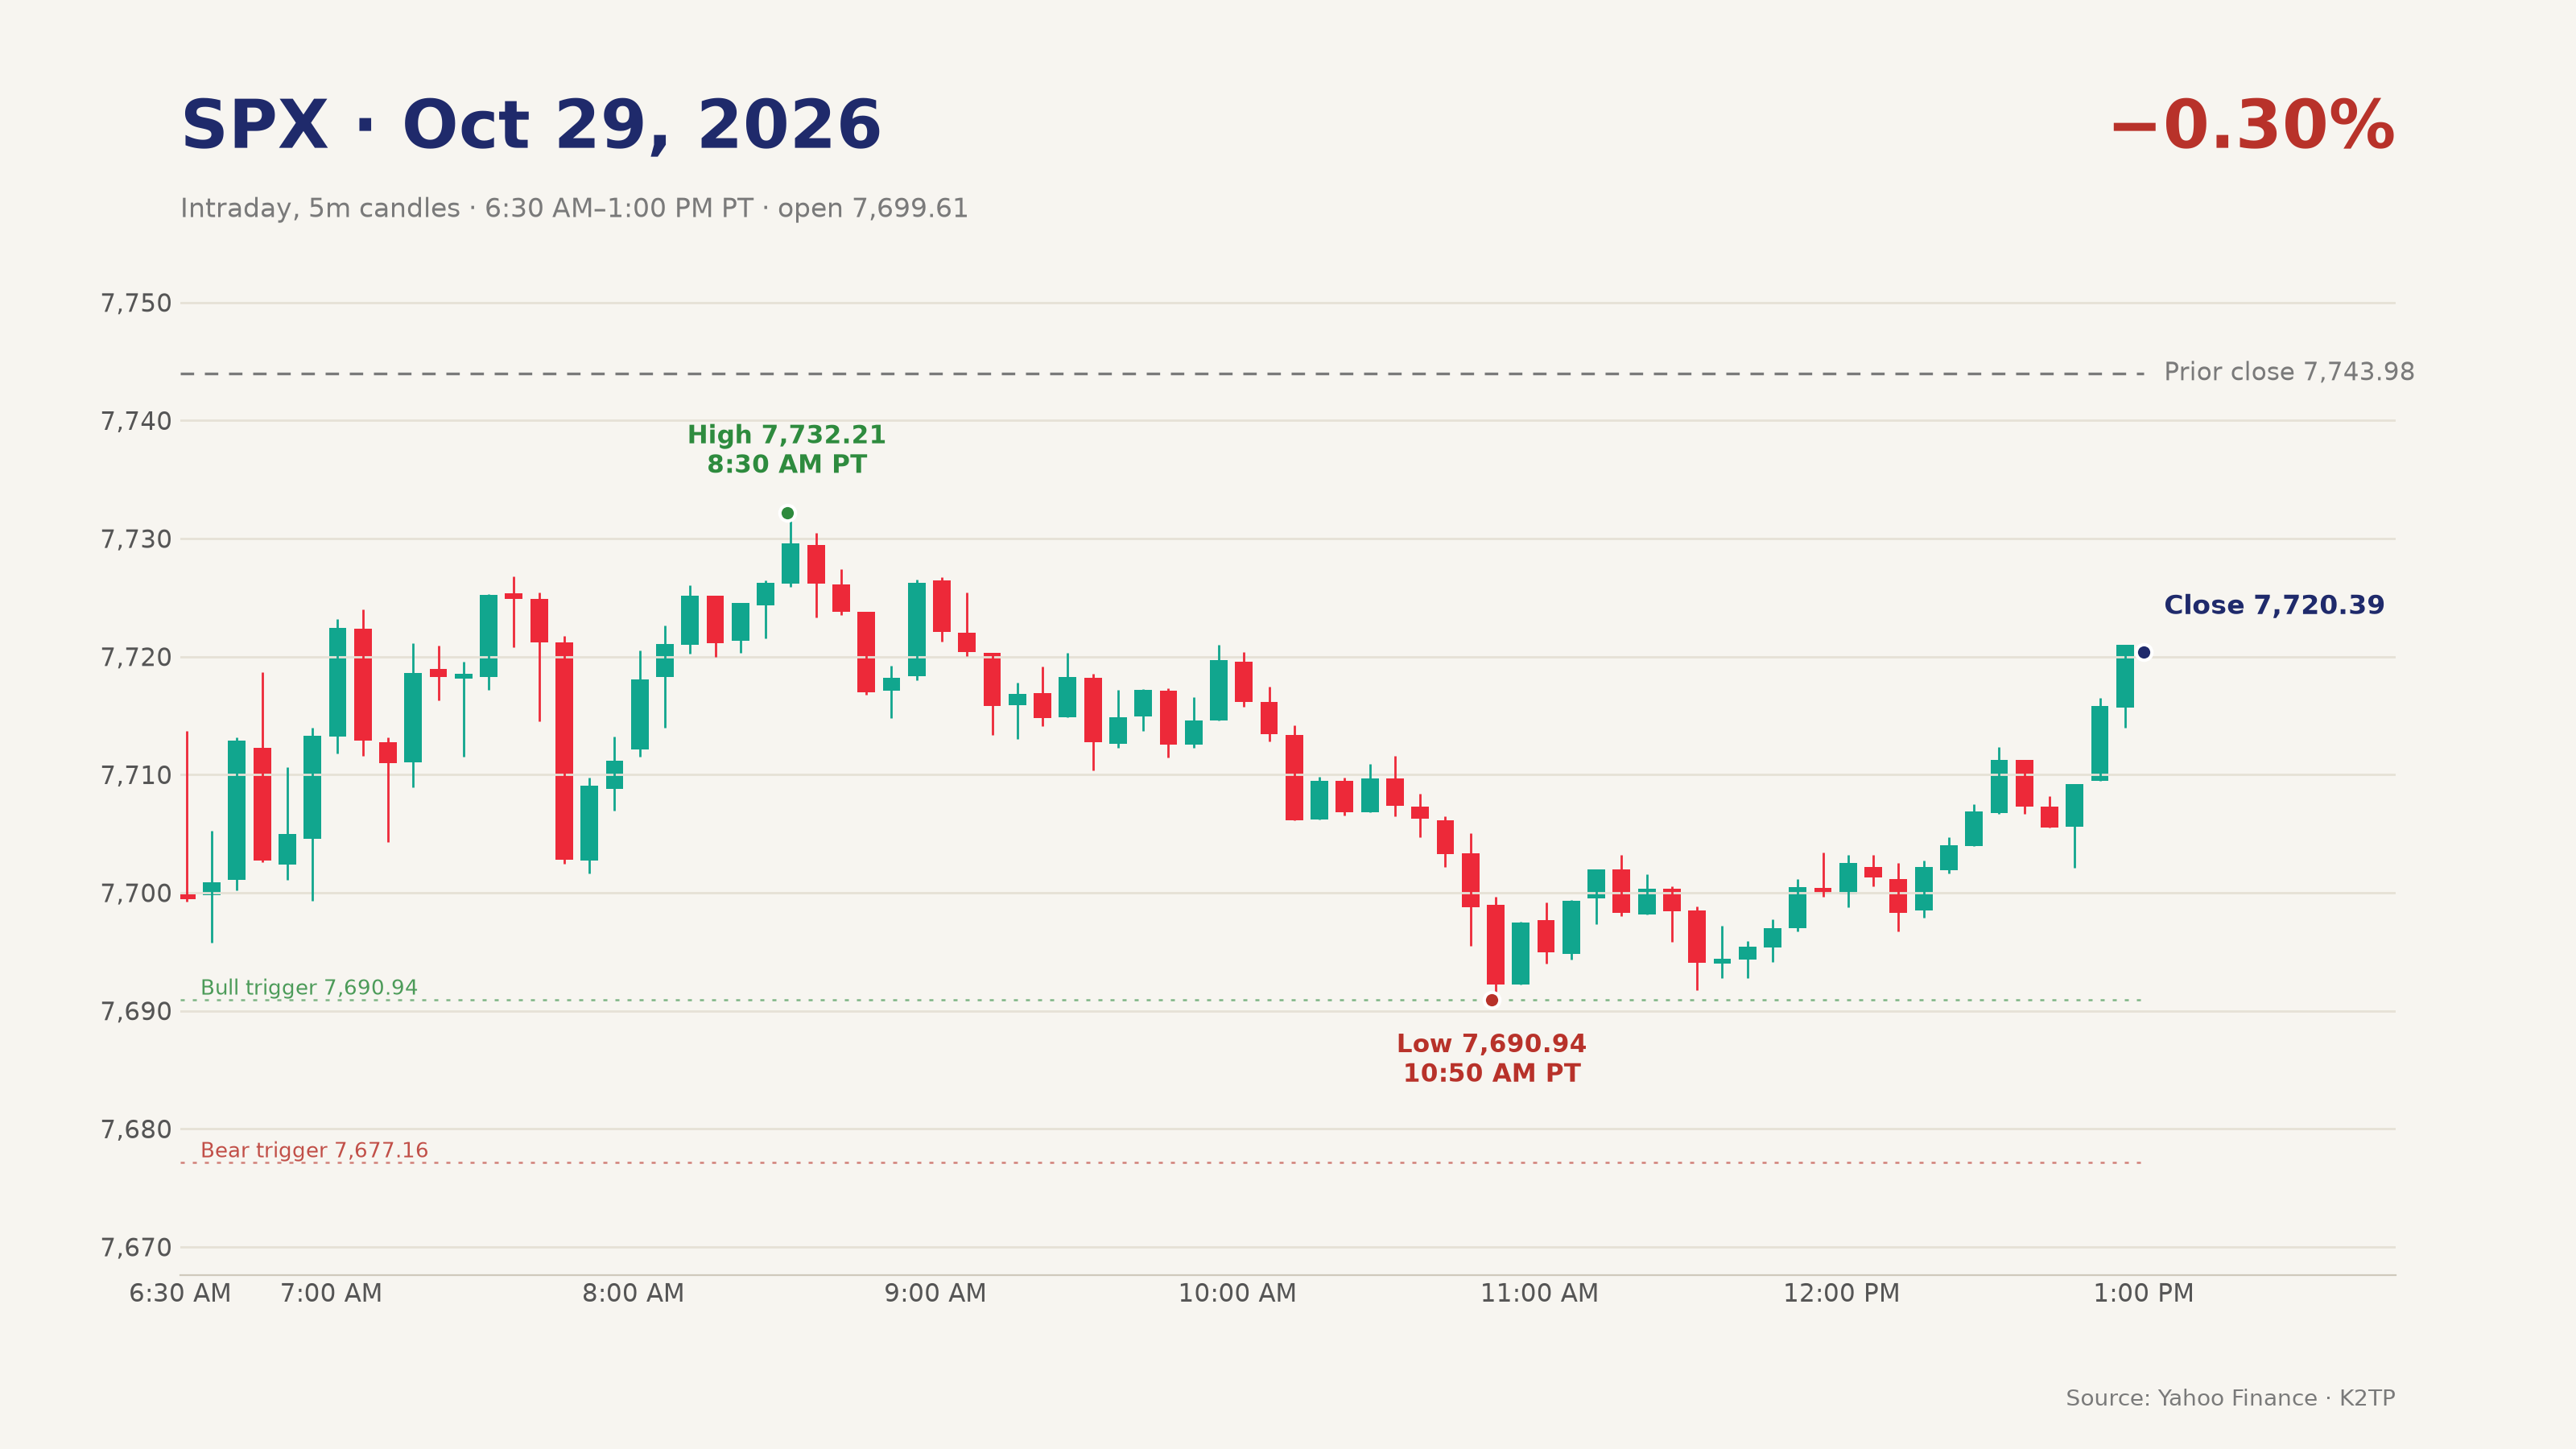
- Pre-market: ES −0.38%, NQ −1.20%; implied SPX near 7,715; VIX 17.08
- SPX opened at 7,699.61, set the day high of 7,732.21 at 8:30 AM PT, then slipped to 7,714.77 at midday (−0.38%)
- SPX hit the day low of 7,690.94 at 10:50 AM PT, stood at 7,700.67 at the pre-close, then rallied in the final hour to close at 7,720.39
- The pre-close Bull trigger (SPX above 7,719.74 with VIX below 16.21) was half met: SPX closed above it but VIX ended at 17.20; the Bear trigger (below 7,690.94 with VIX above 17.36) did not fire in the session
- Tonight ES was 7,666.25 (about −1.1% vs the 7,754.25 settlement) at 6:52 PM PT, implying an SPX open near 7,635–7,645, below the 7,690.94 low
→ Buyers defended 7,690.94 during the session, but Intel and Amazon after hours could open SPX below that area. 7,677.16 is Friday's deciding line.
MARKET: TECH SELLS OFF, BREADTH IS THE WEEK'S BEST, YIELDS FALL
Indices (close):
- SPX 7,720.39 (−0.30%), range 7,690.94–7,732.21
- NDX 29,402.51 (−1.38%); Nasdaq Composite 26,184.72 (−1.38%)
- DJIA 52,342.56 (−0.25%)
- RUT 2,859.22 (+1.01%)
- RSP 220.04 (+1.20%)
- SOX 11,518.20 (−1.42%)
Intraday path: Pre-market ES −0.38% and NQ −1.20% on Alphabet and ServiceNow, while GDP beat and PCE came in line. SPX opened at 7,699.61, peaked at 7,732.21 at 8:30 AM PT, stood at 7,714.77 at midday, bottomed at 7,690.94 at 10:50 AM PT and recovered to close at 7,720.39, above the 7,700.67 pre-close level.
Sector rotation:
- Up: XLV +2.40%, XLRE +2.21%, XLP +1.54%, XLU +1.53%, XLF +1.44%, XLB +1.29%, XLI +0.97%, XLY +0.75%, XLE +0.38%
- Down: XLK −1.18%, XLC −1.87%
- Mega-caps: META +1.96%, AAPL +1.48%, MSFT −0.16%, TSLA −0.23%, NVDA −0.80%, TSM −1.75%, AVGO −1.94%, AMD −2.08%, INTC −3.62%, AMZN −4.25%, MU −4.98%, GOOGL −12.64%
Market internals:
- RSP +1.20% vs SPX −0.30%, a 150 bp gap; RUT +1.01% and IWM +0.97%
- 9 of 11 sectors up, improved from 8 of 11 at the pre-close (RSP +0.87%)
- NYSE and Nasdaq advance/decline data are unavailable today
Volatility:
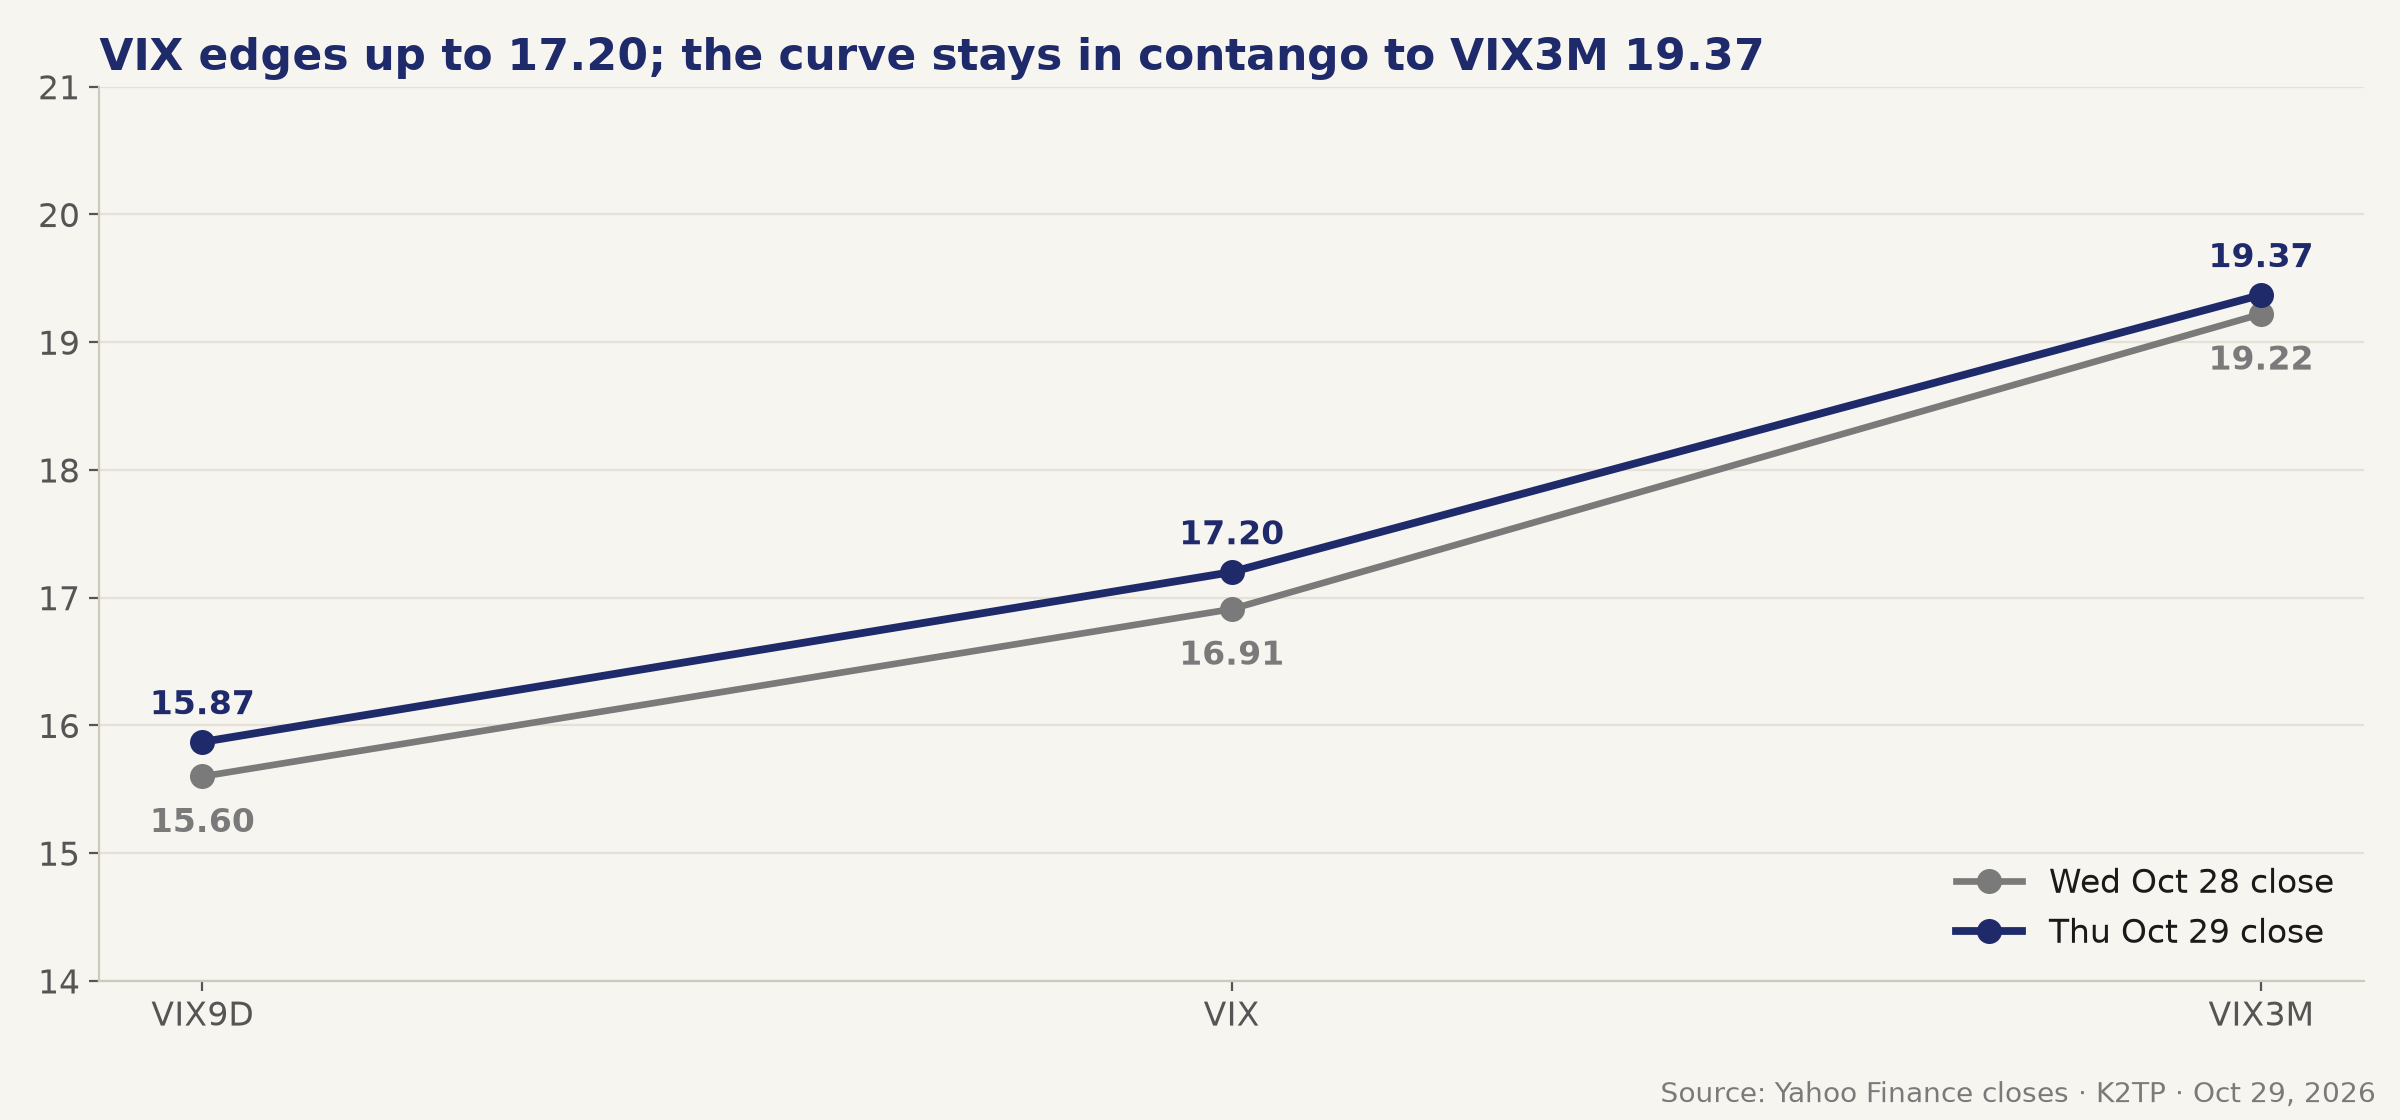
- VIX 17.20 (+1.71%), range 16.21–17.36
- VIX9D 15.87, VIX3M 19.37: the curve stays in contango
- VVIX 98.01 (+1.45%)
Cross-asset:
- December WTI settled at $102.00 (−0.76%), about $104.80 tonight; Brent about $113.84 tonight
- Gold $4,010.50; DXY about 101.72; BTC about $76,500 tonight after Circle and Tether froze about 800M USDC and $1.567B USDT tied to a possible Binance hack (Evening Recap)
- Tonight (6:52 PM PT, Yahoo): ES 7,666.25, NQ 28,836.25 (about −2.4% vs the 29,562.00 settlement), YM 52,361, RTY 2,850.30
Global:
- Asia (Thursday, Pre-Market brief): Nikkei +1.36%, Kospi −1.24%; North Korea launched about 10 missiles; China's onshore yuan hit its strongest since June 2022
- Europe close: DAX +1.31%, CAC 40 +1.05%, Euro Stoxx 50 +0.64%, FTSE 100 +0.26%; the ECB held at 2.50%, Lagarde said hyperscaler debt is pushing yields up, and she plans to step down on February 7
- Tonight (Yahoo, about 6:45 PM PT): Nikkei −2.90%, Kospi −4.84%, Shanghai −1.24%, Hang Seng +0.61%; Japan's September industrial output +2.2% vs 1.2% expected, Tokyo core CPI 2.6% in line (Evening Recap)
Key SPX levels:
- 7,732.21: Thursday high
- 7,720.39: close; holding above it with VIX below 17.20 invalidates the Bear case
- 7,700.67: pre-close level
- 7,690.94: Thursday low, the Bull confirmation line if reclaimed with VIX below 17.20
- 7,677.16: RISK-OFF line if VIX is above 18.55
- 7,612.07: October 23 low
- VIX: 17.20 and 18.55
Option seller's corner:
- Bull case: SPX reclaims 7,690.94 with VIX below 17.20, the gap gets bought and the regime returns to RISK-ON. Add far-OTM SPX put spreads only after the 5:30 AM PT ECI has settled and the first hour has passed.
- Bear case: SPX below 7,677.16 with VIX above 18.55 confirms RISK-OFF and opens a path to 7,612.07. Then cut short-put size, use only defined-risk spreads and avoid NDX with NQ −2.4% tonight.
- VIX9D 15.87 sits below VIX 17.20 and VIX3M 19.37, so near-dated premium is cheap despite the ECI, gap risk and month-end flows. Selling the front end pays little for the risk.
- Favor broad underlyings such as RSP or RUT over NDX; avoid short premium on single chip names until the Intel impact settles.
BOTTOM LINE
- A rotation day: tech and Alphabet pulled SPX −0.30% to 7,720.39, but RSP +1.20%, RUT +1.01% and 9 of 11 sectors rose.
- Strong GDP, in-line PCE and a good 7-year auction drove a bull steepener: 2Y 4.656% (−7.9 bp), 10Y 4.989%, back below 5%.
- Regime 🟡 TRANSITION. After hours Intel −23% on its Q4 guide and Amazon −7% on $77.3B of capex; NQ futures about −2.4% tonight. SPX below 7,677.16 with VIX above 18.55 shifts the read to RISK-OFF.
Watch Friday (PT):
- 3:15–4:45 AM: Q3 earnings from Chevron (EPS est. $4.82), ExxonMobil ($4.01), AbbVie ($3.77)
- 5:30 AM: Q3 Employment Cost Index (est. 0.8% q/q, prior 0.9%)
- 6:45 AM: October Chicago PMI (est. 54.8, prior 58.8)
- 1:00 PM: close of October's last session, month-end flows
- At the open: whether the INTC and AMZN gaps spread across chips and AI hardware; oil after the attacks on Saudi Arabia
Bull expectation: ECI at or below 0.8%, the 10Y holds below 5%, chips stabilize and NQ recovers half of tonight's loss, SPX reclaims 7,690.94 with VIX below 17.20. Bear expectation: SPX opens near 7,640 and fails to reclaim 7,690.94, Intel's guide spreads across chips, a hot ECI stops the bond rally, SPX below 7,677.16 with VIX above 18.55.
Sources: 4 K2TP briefs for 10/29/2026 (Pre-Market, Midday, Pre-Close, Evening Recap). Official closing, intraday and tonight's futures prices from Yahoo Finance; 2Y from CNBC; oil settlements, news and data from CNBC, Bloomberg, Reuters and FinancialJuice; Amazon and Intel Sankeys and the capex chart from Amazon's and Intel's Q3 2026 releases (8-K Ex. 99.1), SEC EDGAR. Analysis: K2TP Framework.