Market 10/28: The Fed holds with two hike dissents and Oracle and memory chips lift SPX as the 10Y tops 5%; after the bell Alphabet sinks on negative free cash flow while Microsoft rallies on Azure
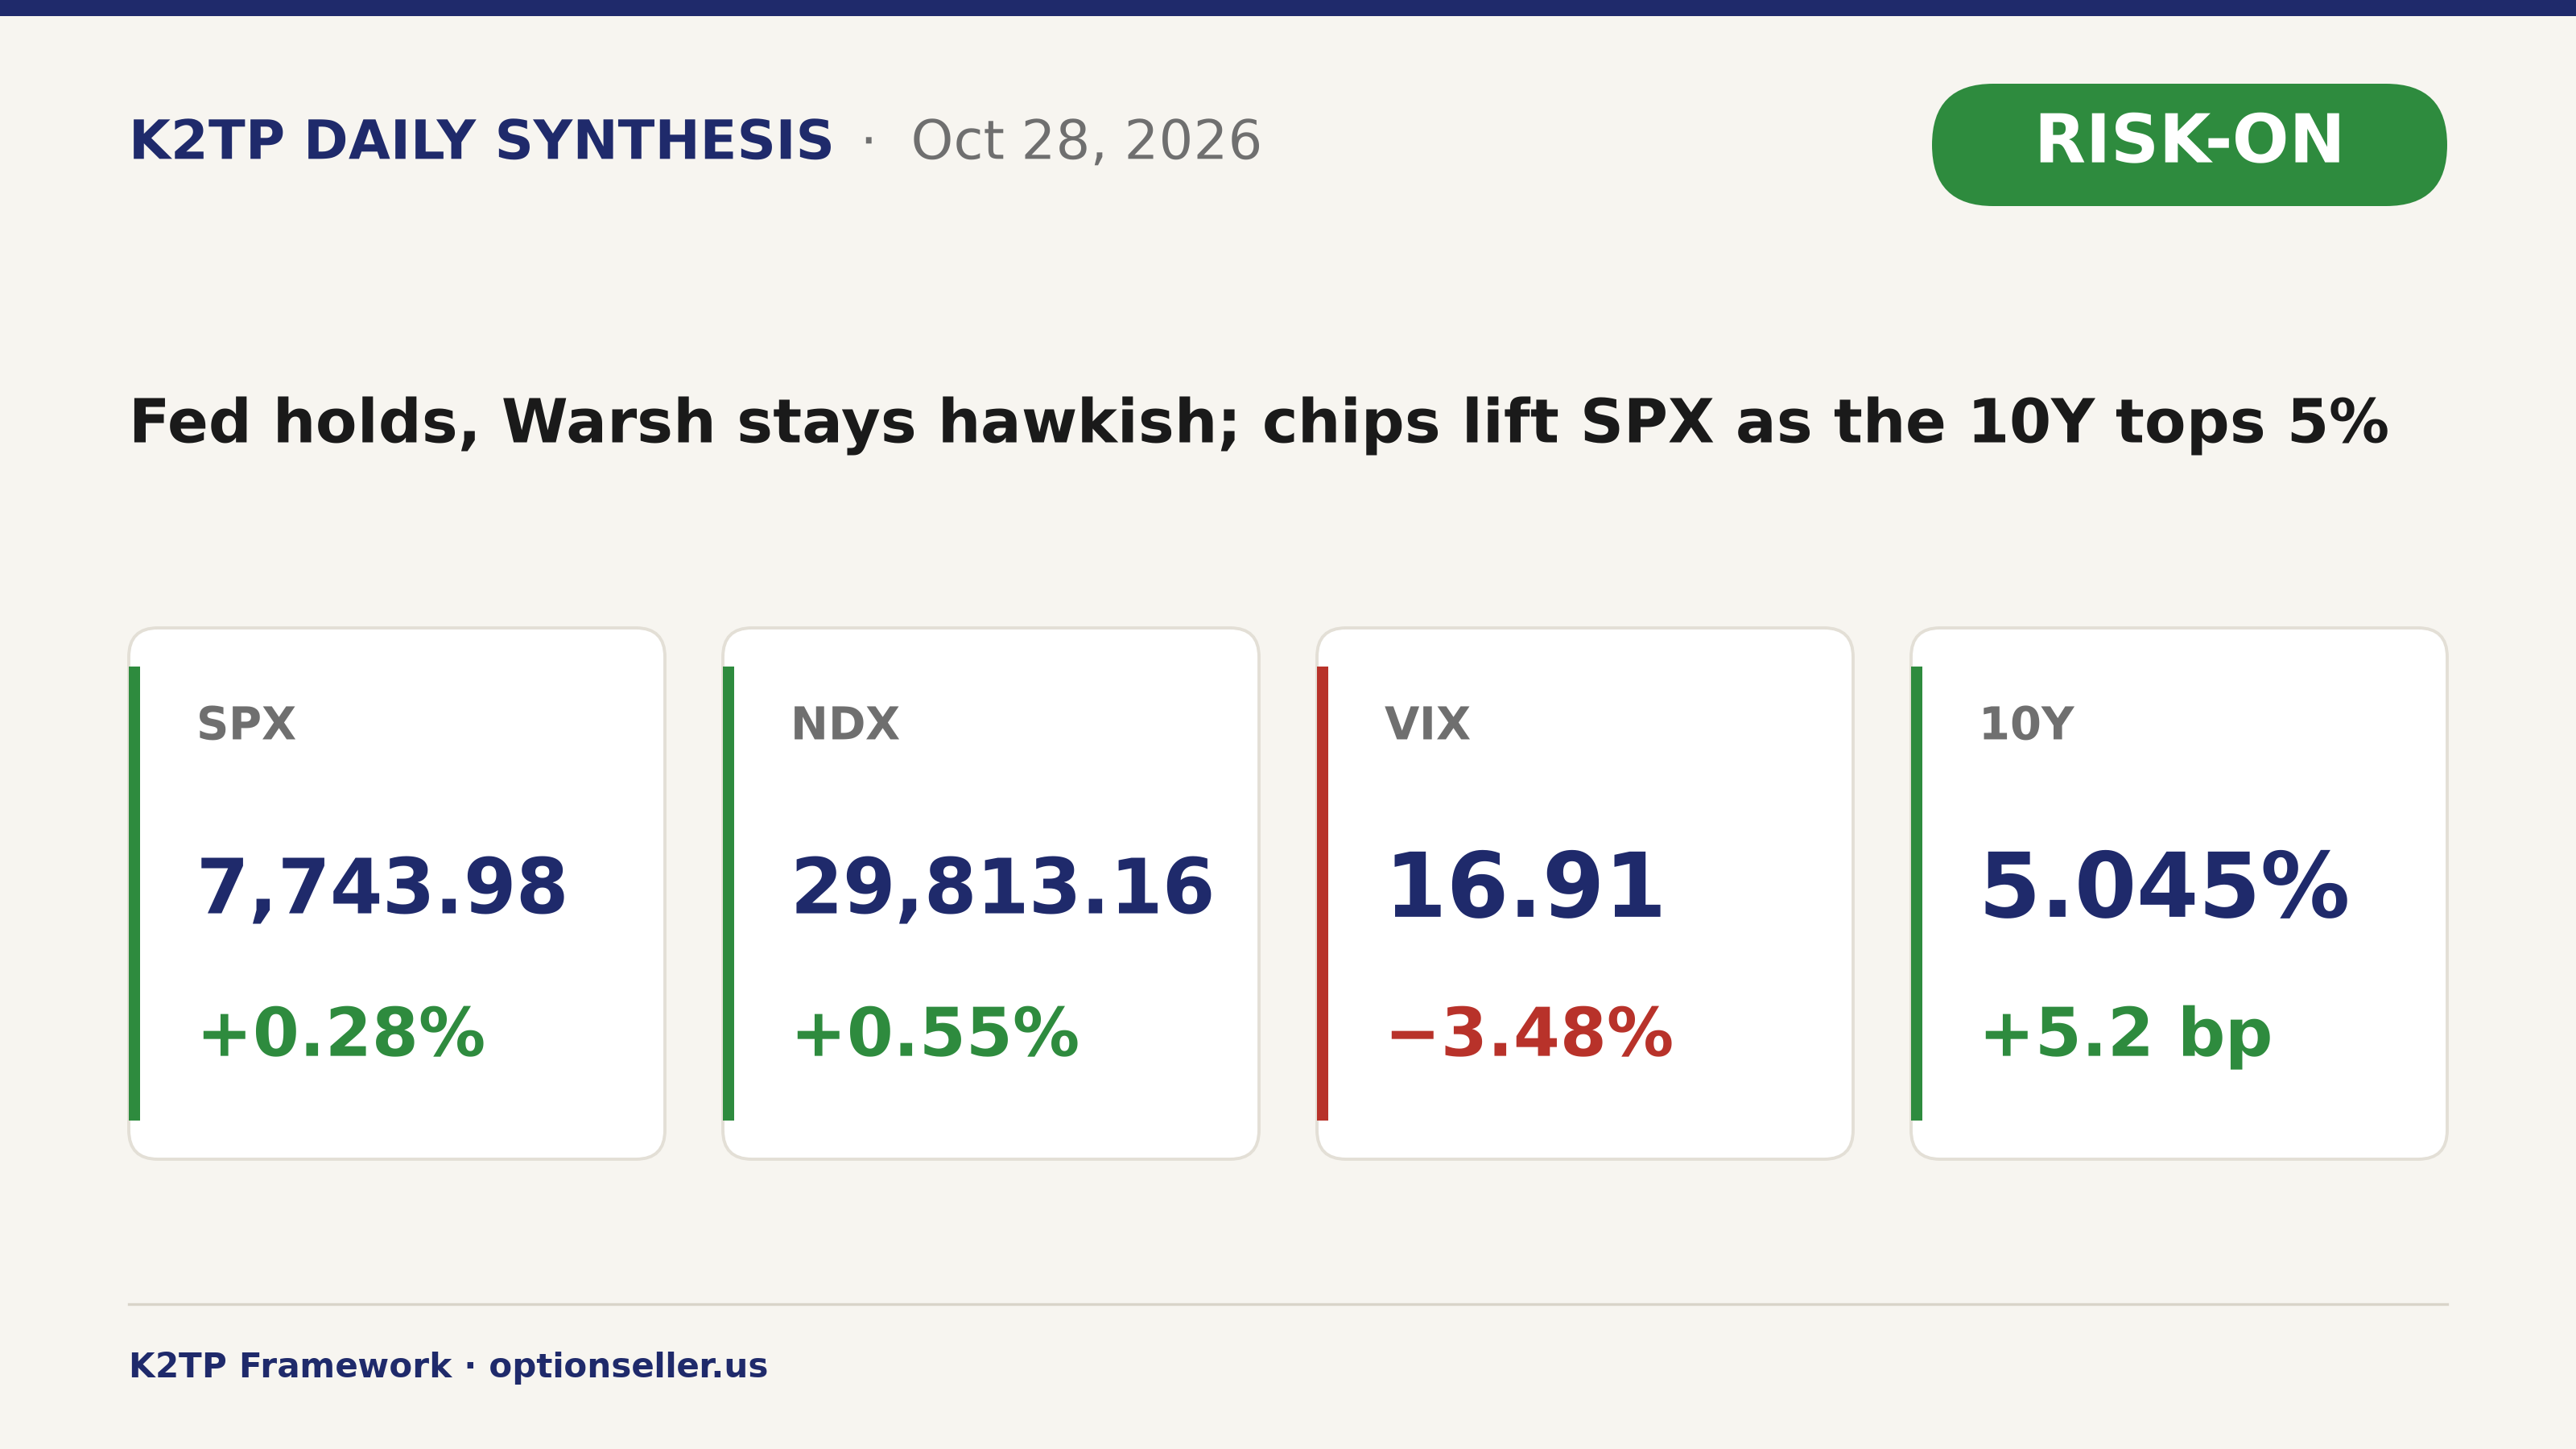
SPX +0.28%, NDX +0.55%, DJIA +0.19%, VIX −3.48% to 16.91. FOMC held at 3.75%–4.00% on a 10-2 vote; SOX +1.75% with ORCL +10.73%, VRT +16.48% and MU +5.86%; 10Y 5.045% (+5.2 bp). After hours GOOGL −9.97% on FCF of −$9.07B, MSFT +2.88% on Azure +48%, NOW −18.10%.
KEY HEADLINES
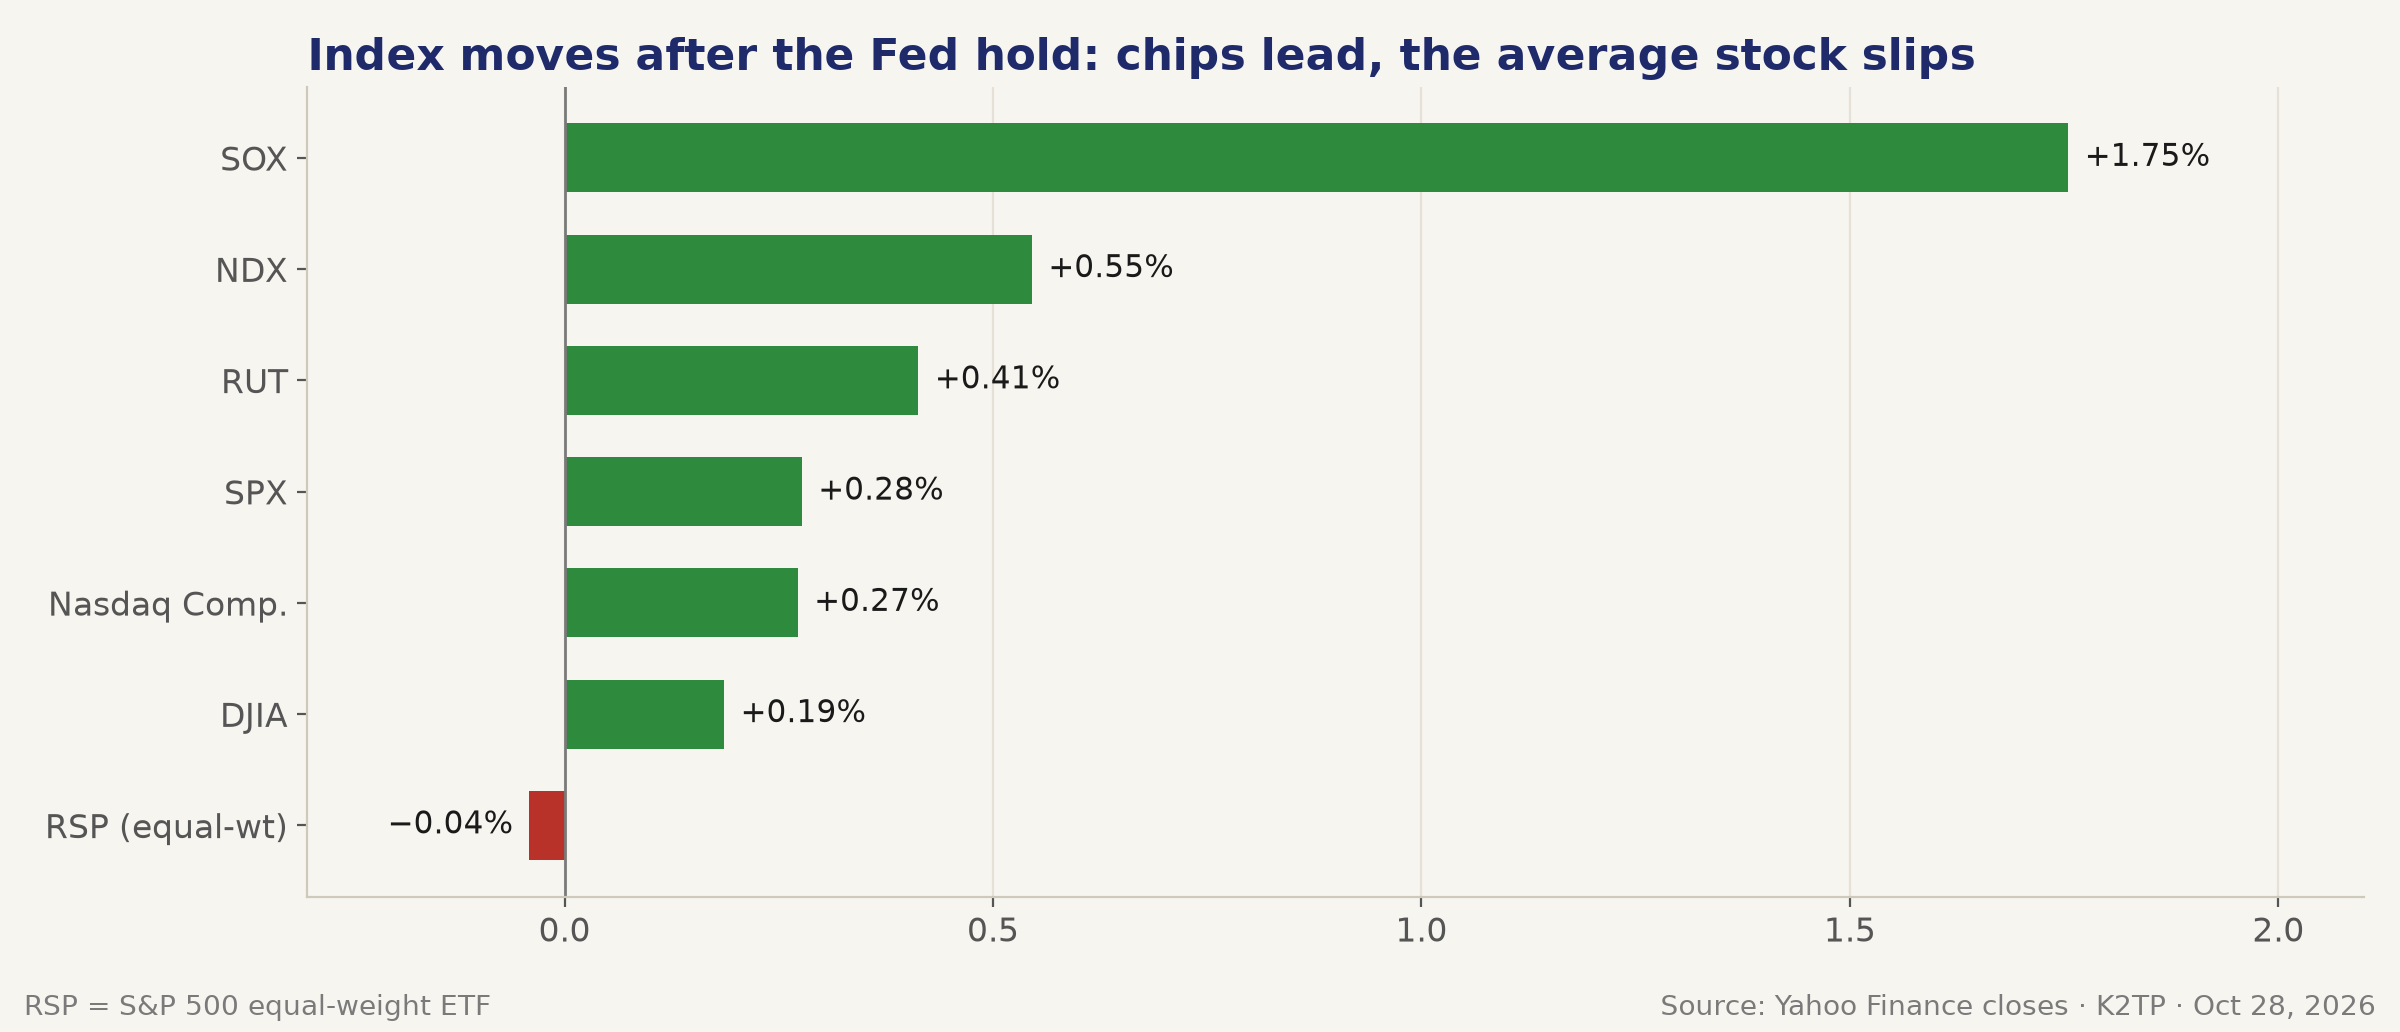
- SPX +0.28% to 7,743.98 (+21.38 pts); NDX +0.55% to 29,813.16; Nasdaq Composite +0.27%; DJIA +0.19% to 52,475.10; RUT +0.41%
- FOMC held at 3.75%–4.00% on a 10-2 vote, with Cook and Hammack dissenting for a 25 bp hike; Warsh gave no forward guidance and said he will not prejudge December
- SPX dipped to 7,722.37 into the press conference, spiked to the day high of 7,758.43 at 11:40 AM PT, faded to 7,722.78 at 12:10 PM PT and closed at 7,743.98
- Oracle +10.73% after reaffirming FY2027 revenue of at least $90B; SK Hynix's record quarter lifted memory and equipment: MU +5.86%, LRCX +5.39%, KLAC +3.33%; SOX +1.75%
- Narrow again: RSP −0.04%, 6 of 11 sector ETFs up; XLU −0.84% and XLRE −0.73% fell as the 10Y closed at 5.045%
- Bear steepener: 2Y −2.1 bp to 4.716%, 10Y +5.2 bp, 30Y +5.6 bp to 5.361%; 2s10s widened from 25.6 bp to 32.9 bp
- The Bank of Canada hiked to 2.50% and said it may hike again; December WTI settled at $102.78 (+2.88%) after a 1.892M-barrel EIA crude draw
- Pre-market earnings: Vertiv +16.48% on a beat and raise, GE HealthCare +6.62%; Boston Scientific −5.84% after a guide cut, Enphase −16.03%
- After hours: Alphabet −9.97% on capex of $51.36B and FCF of −$9.07B; Microsoft +2.88% on revenue of $92.28B and Azure +48%; ServiceNow −18.10%, Fortinet about −25%; NQ futures −1.32% at 6:56 PM PT
- Regime: 🟢 RISK-ON (narrow, tested); Q3 GDP and September PCE Thursday at 5:30 AM PT
THE FED HOLDS, WARSH KEEPS DECEMBER OPEN
- FOMC kept the target range at 3.75%–4.00% on a 10-2 vote; Governor Cook and Hammack wanted a 25 bp hike (Pre-Close brief) 🟡
- Statement: inflation remains elevated and domestic spending has been resilient; more information will help set the appropriate stance
- Warsh: the committee "has not grown easier", "the monetary medicine is starting to work", he does not believe in forward guidance absent a crisis and will not prejudge December; credit spreads have widened and rates are affecting the technology complex
- Market reaction: SPX fell to 7,722.37 into the press conference, then jumped to 7,758.43 between 11:30 and 11:40 AM PT as VIX touched 16.93
- FinancialJuice reports traders still price about 90% odds of a December hike (unconfirmed); earlier, the Bank of Canada raised its rate to 2.50% from 2.25% and lifted its 2026 inflation forecast to 2.9%
- Warsh's next scheduled appearance is a task force field hearing on November 16
→ Two hike dissents and no guidance keep December live. The market read the hold as less hawkish than feared, so the front end eased, but Thursday's PCE is the next test of that read.
ORACLE AND MEMORY CHIPS CARRY THE INDEX
- SK Hynix posted a record quarter, said its DRAM and HBM output is sold out through 2029 and announced more than $23B in shareholder returns; Kospi +6.63% on Wednesday (Pre-Market brief) 🟢
- Oracle reaffirmed its FY2027 outlook of at least $90B revenue and targets at least $225B by FY2030; ORCL +10.73% to 144.54 (high 148.48)
- Memory and equipment led: MU +5.86%, LRCX +5.39%, STX +4.51%, WDC +4.08%, ARM +4.10%, KLAC +3.33%, AMD +3.24%, AVGO +2.77%, INTC +1.91%; SOX +1.75% to 11,684.00
- NVDA −1.17% on a report that the DOJ is examining its Hugging Face acquisition (FinancialJuice, unconfirmed); META −1.24%; AAPL −0.94% after launching a touch-screen MacBook Pro at $2,899
- GOOGL +1.34% in regular hours after launching Gemini 4 Carbon, before falling after its report
- NDX +0.55% beat SPX +0.28% by 27 bp; equal-weight RSP −0.04%
→ The AI supply chain keeps getting paid, now in memory and equipment. But NVDA and META lagged, and the chip leaders gave back about 2% after hours once Alphabet's cash burn came out.
RATE-SENSITIVE SECTORS FALL AS THE 10Y TOPS 5%
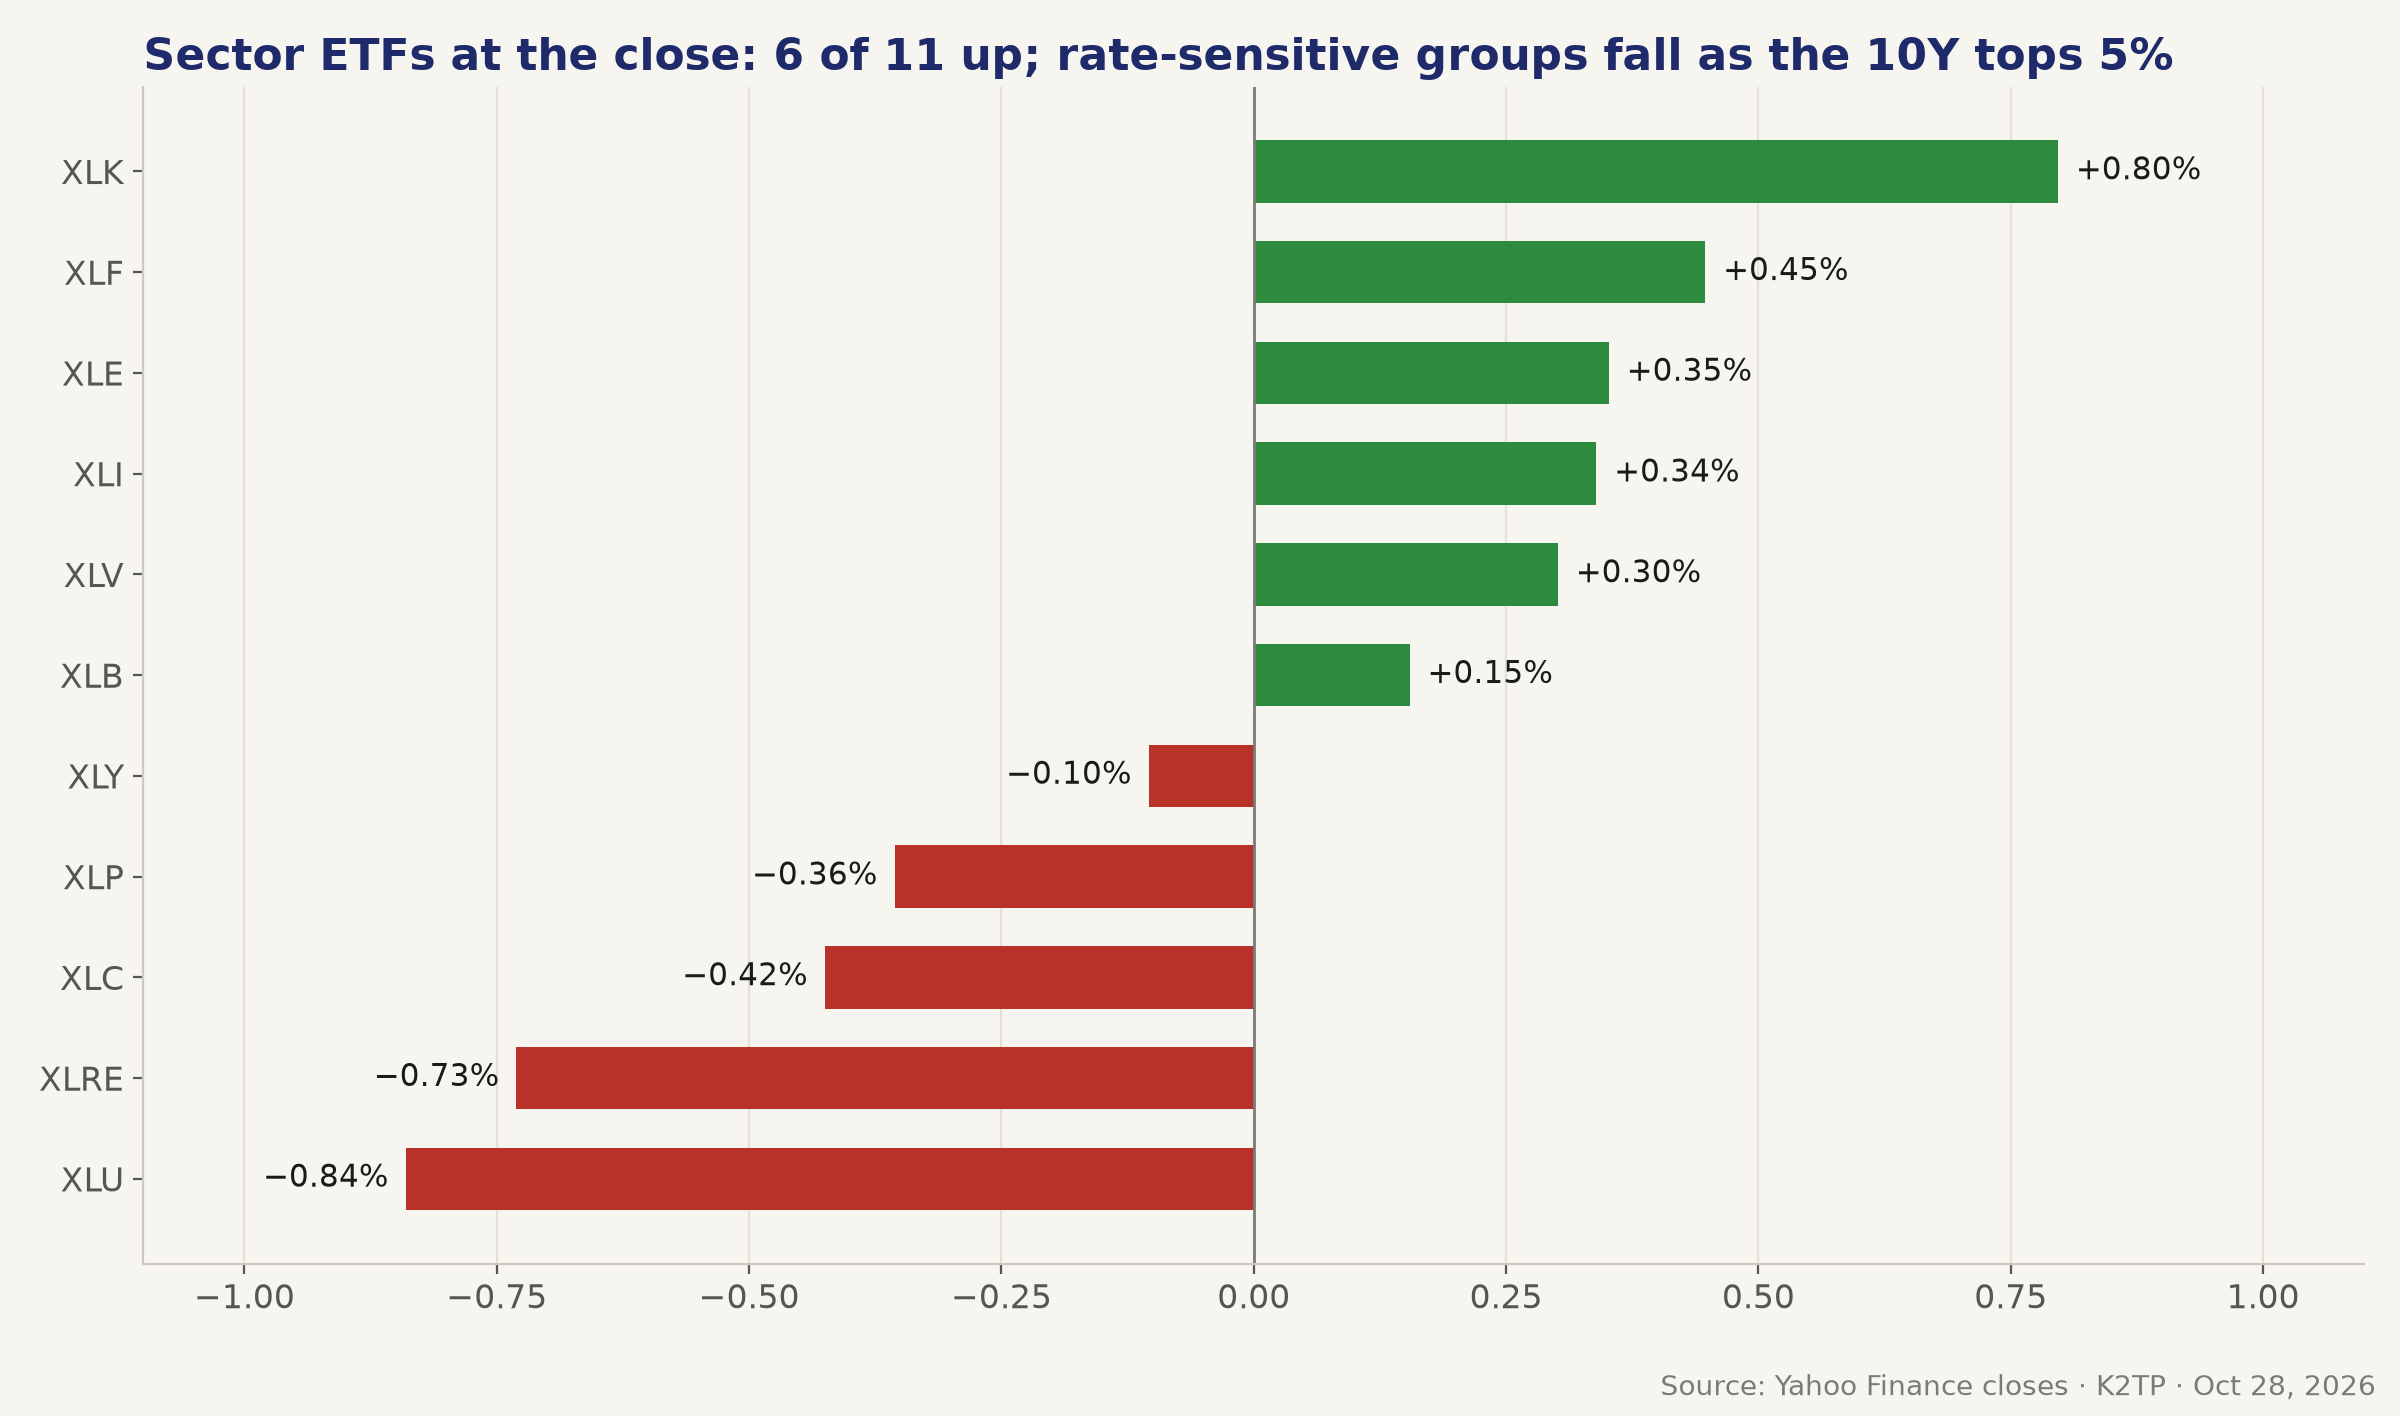
- 6/11 sector ETFs rose: XLK +0.80%, XLF +0.45%, XLE +0.35%, XLI +0.34%, XLV +0.30%, XLB +0.15%; XLY −0.10%, XLP −0.36%, XLC −0.42%, XLRE −0.73%, XLU −0.84%
- RSP −0.04% trailed SPX by 32 bp; it was −0.10% at midday and −0.47% at pre-close, so breadth improved into the close
- Small caps held up: RUT +0.41% and IWM +0.40%, after RUT was −0.09% at pre-close
- Utilities and real estate were the weakest groups as the 10Y crossed 5% at midday and closed at 5.045%
- NYSE advance/decline data were unavailable in all four briefs
→ Breadth recovered in the last hour, but the sectors that need lower long rates lost. With the 10Y above 5%, RISK-ON stays narrow and leans on tech.
EARNINGS: MICROSOFT BEATS, ALPHABET'S FCF TURNS NEGATIVE
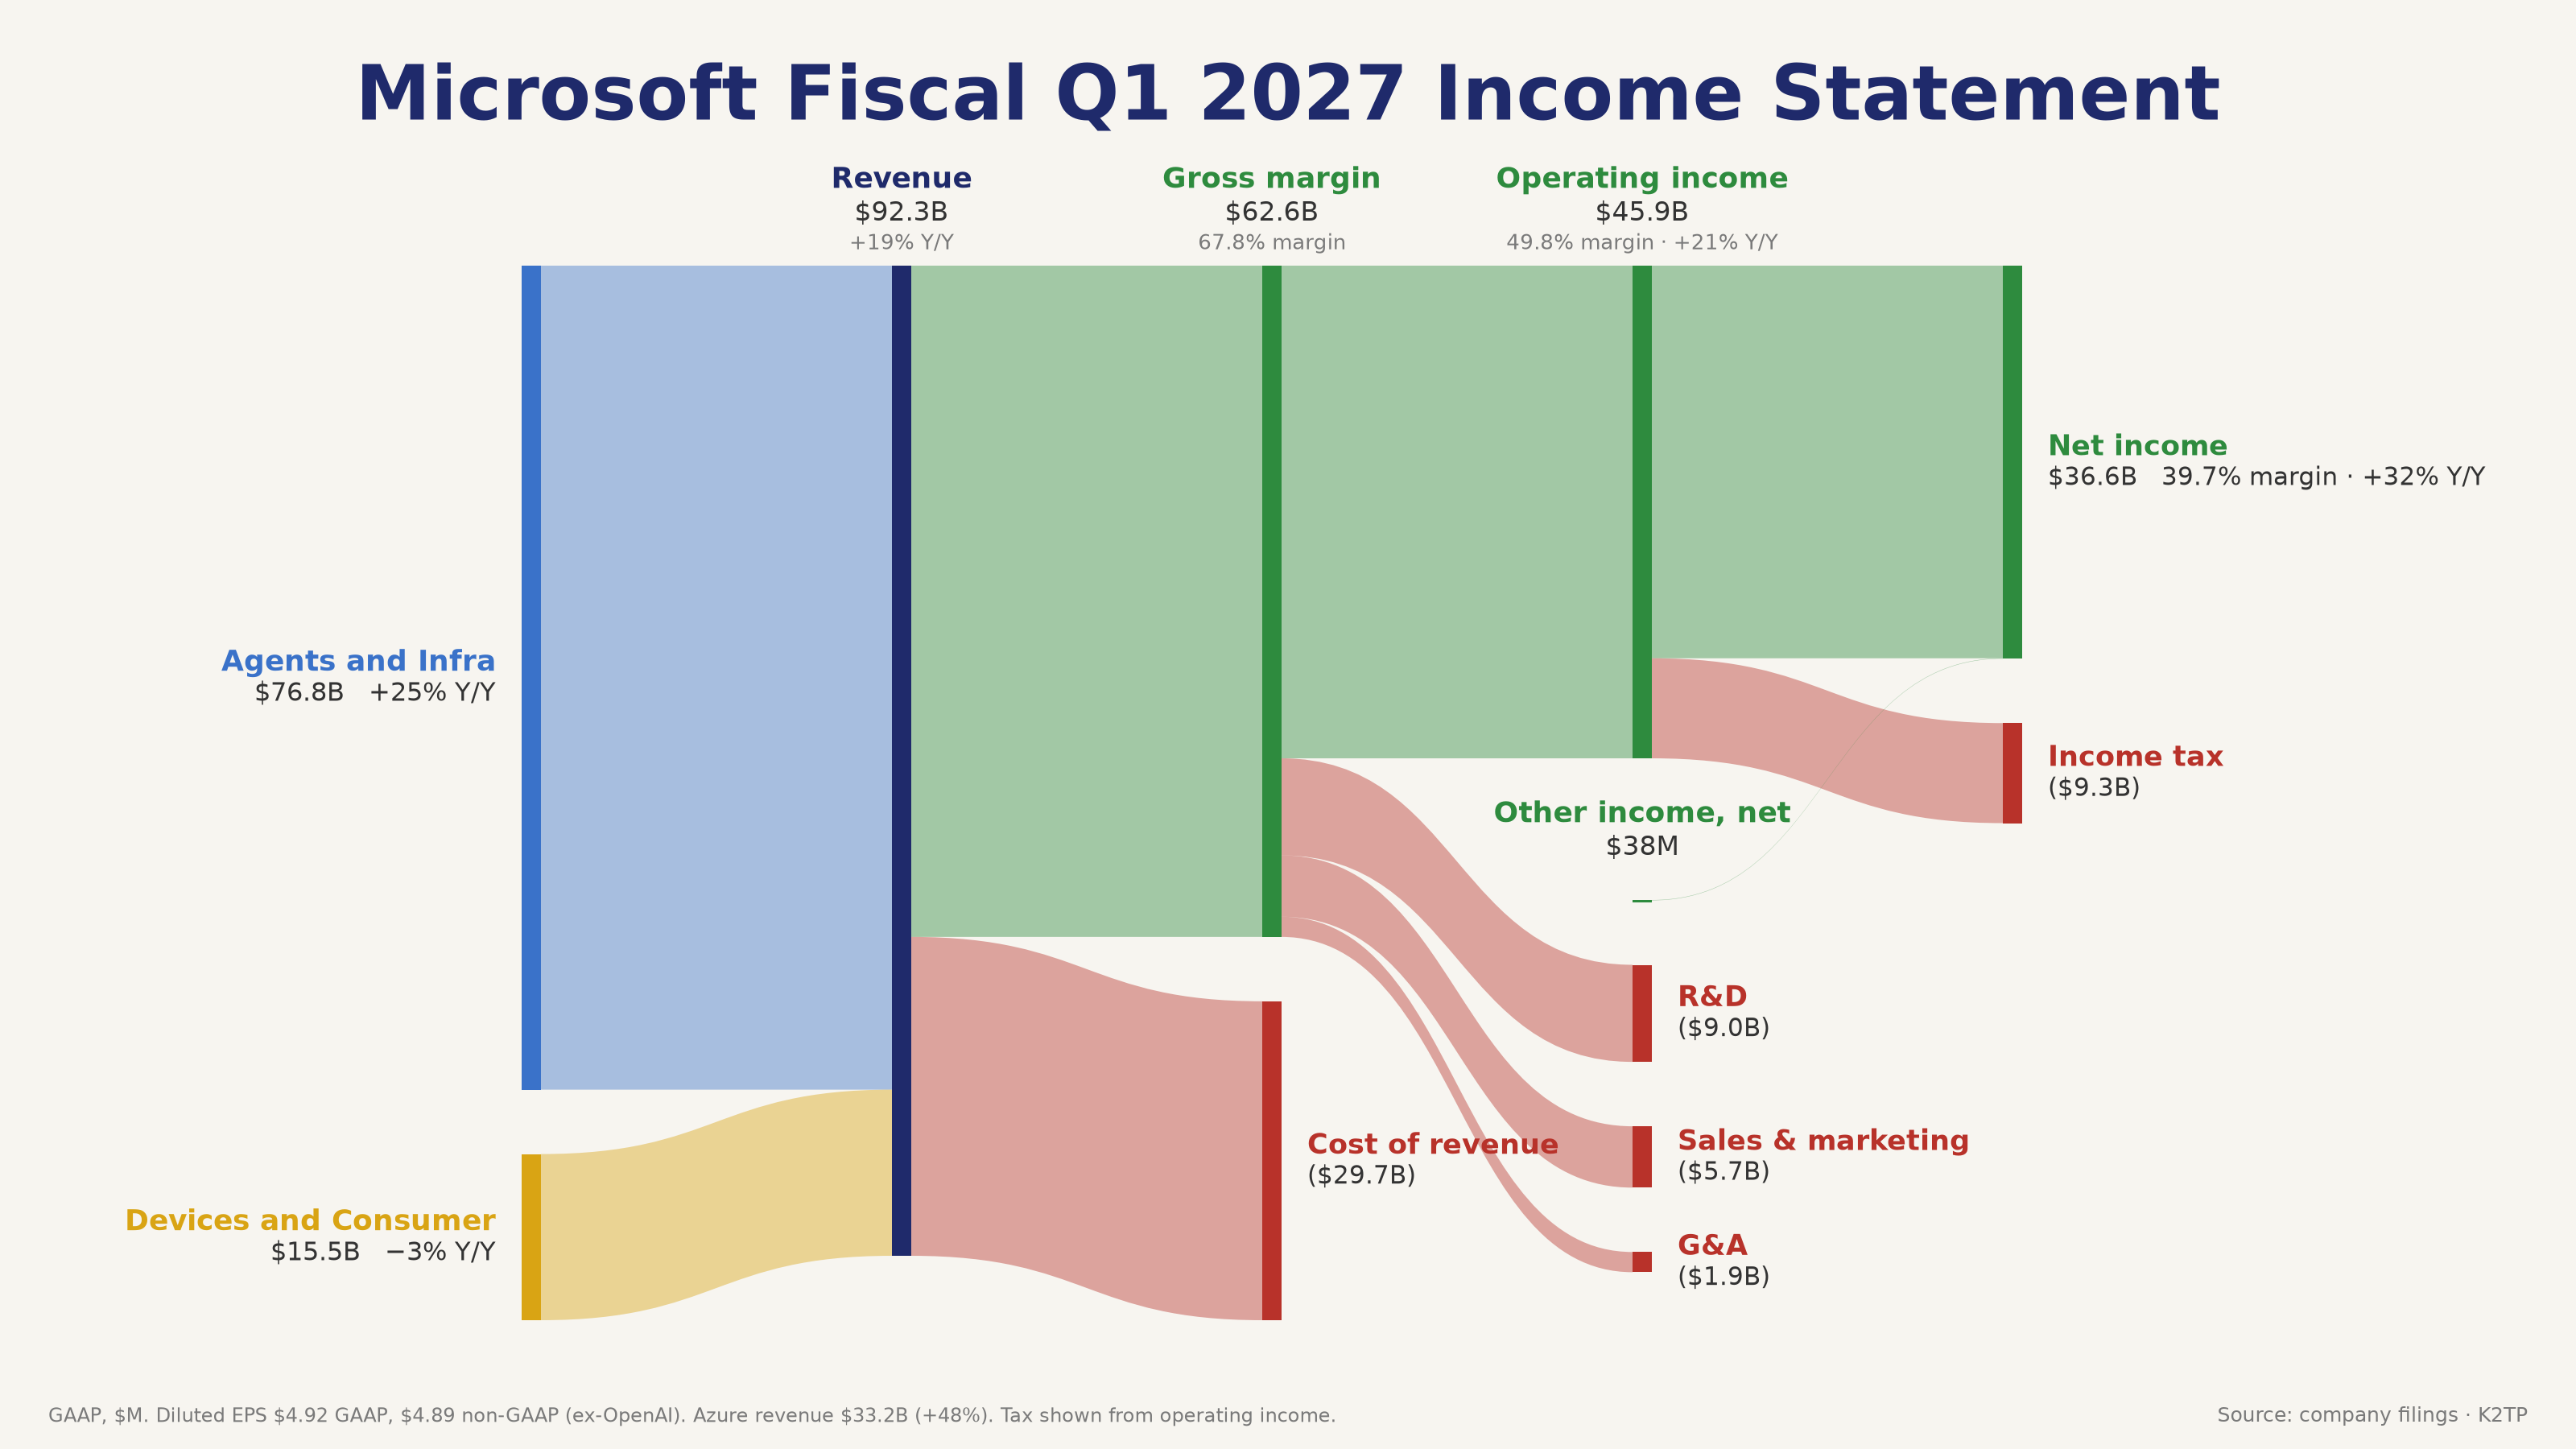
- Microsoft (8-K Ex. 99.1, fiscal Q1 2027): revenue $92.28B (+19%) vs $90.69B expected; operating income $45.92B (+21%); GAAP EPS $4.92, non-GAAP EPS $4.89 (ex-OpenAI) vs $4.73 expected (CNBC) 🟢
- Agents and Infra revenue $76.80B (+25%), Devices and Consumer $15.48B (−3%); Azure revenue $33.17B (+48% vs about 44.8% expected); Microsoft Cloud $63.9B (+30%); commercial RPO +73% to $677B
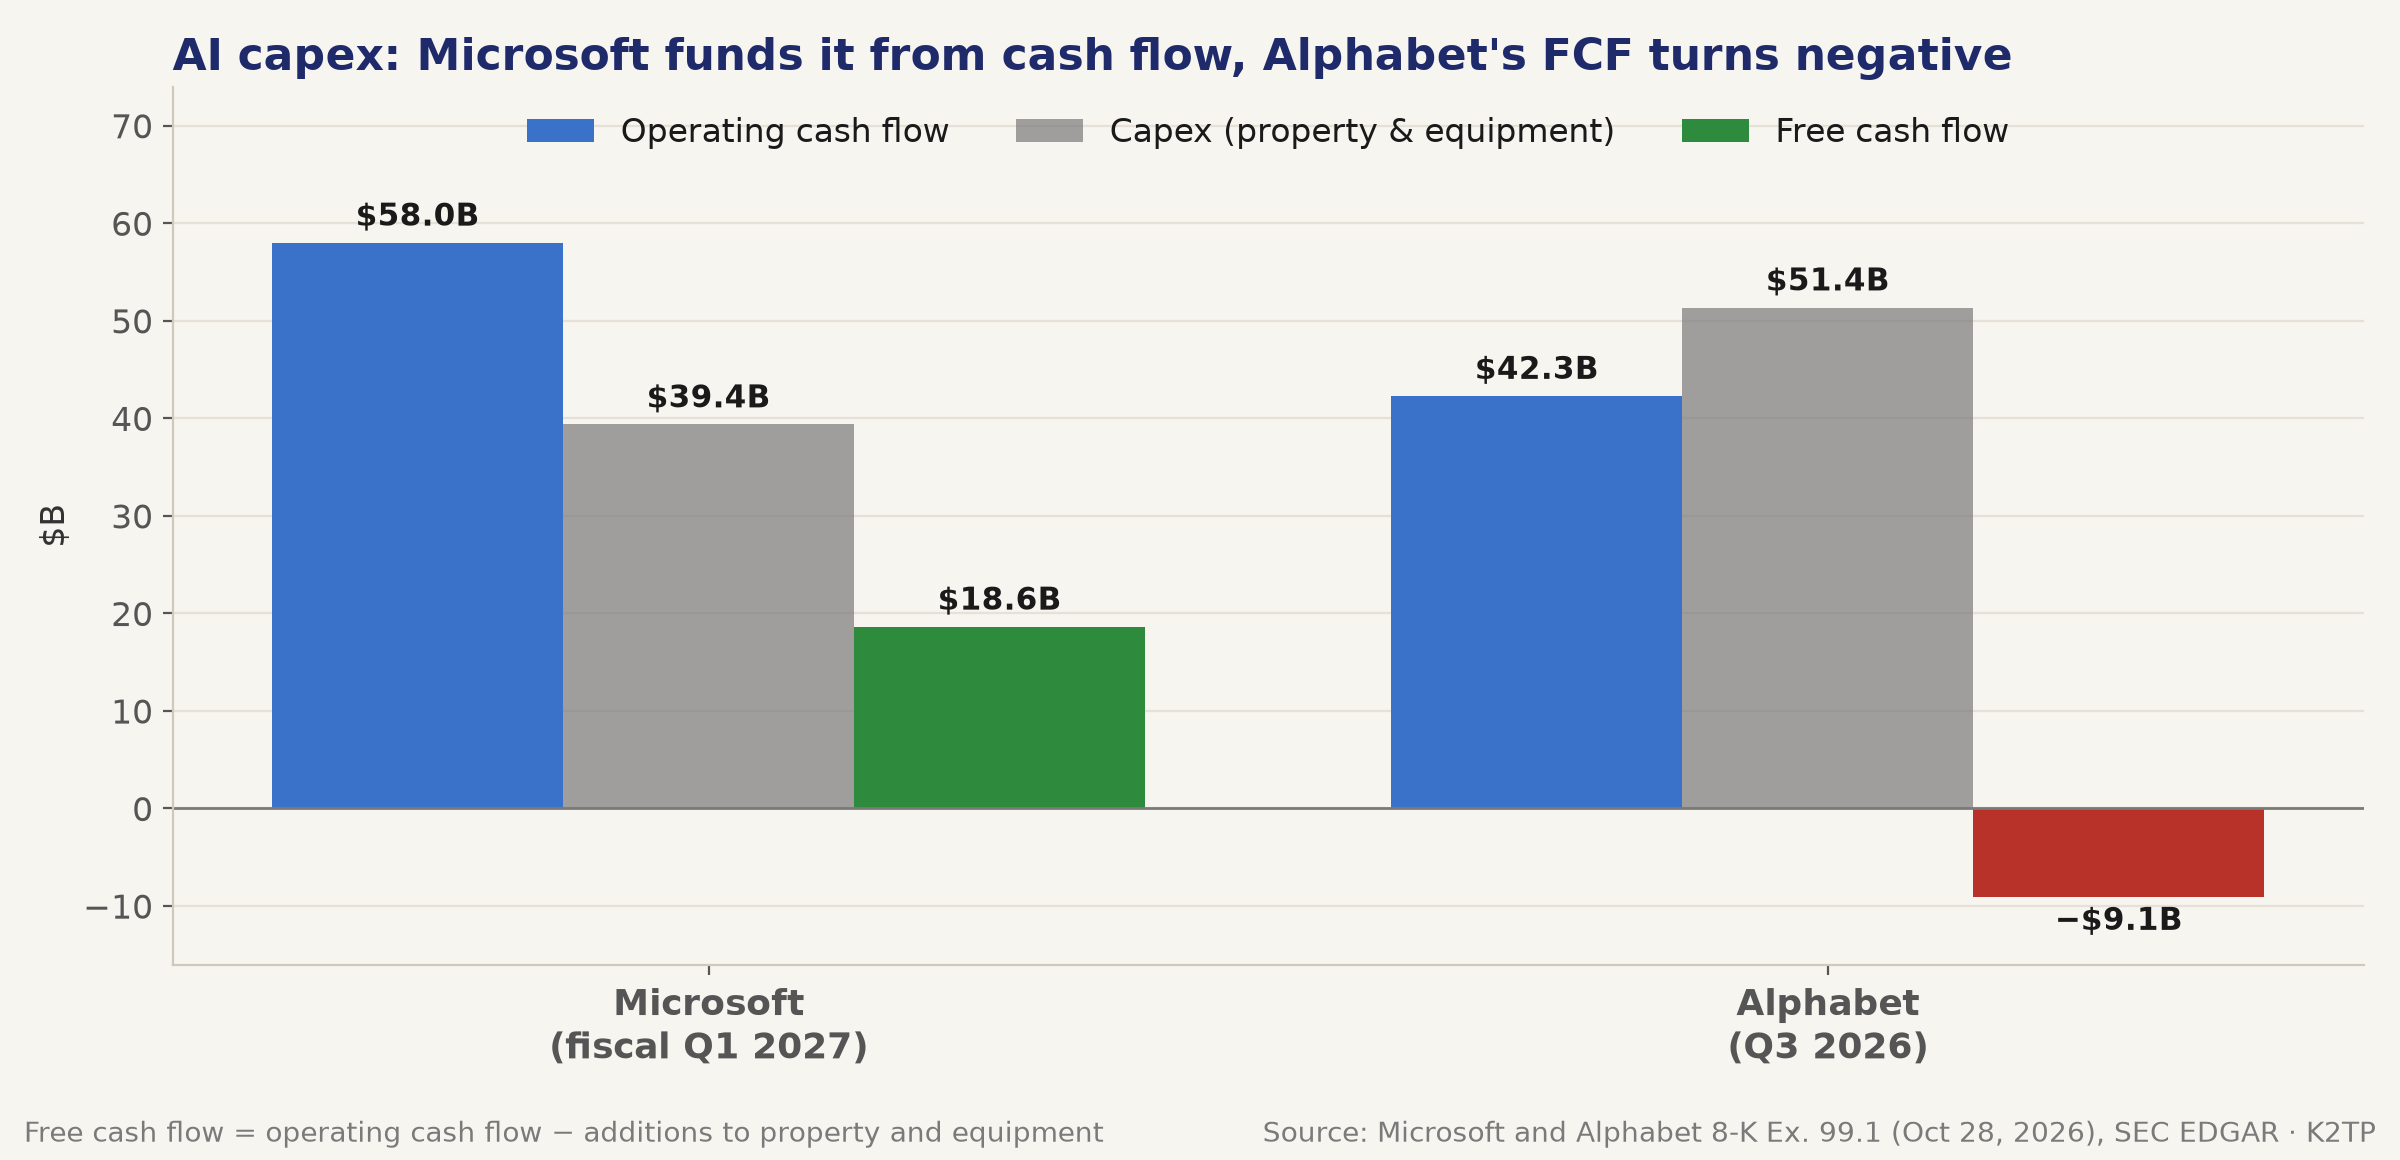
- Microsoft's operating cash flow was $58.00B and capex (additions to property and equipment) $39.37B, so free cash flow stayed positive at about $18.63B; the CFO guided Q2 revenue to $96B–$97.1B, Azure growth to 49%–50% and calendar-year capex to about $170B (CNBC, FinancialJuice); MSFT +2.88% to 546.30 after hours
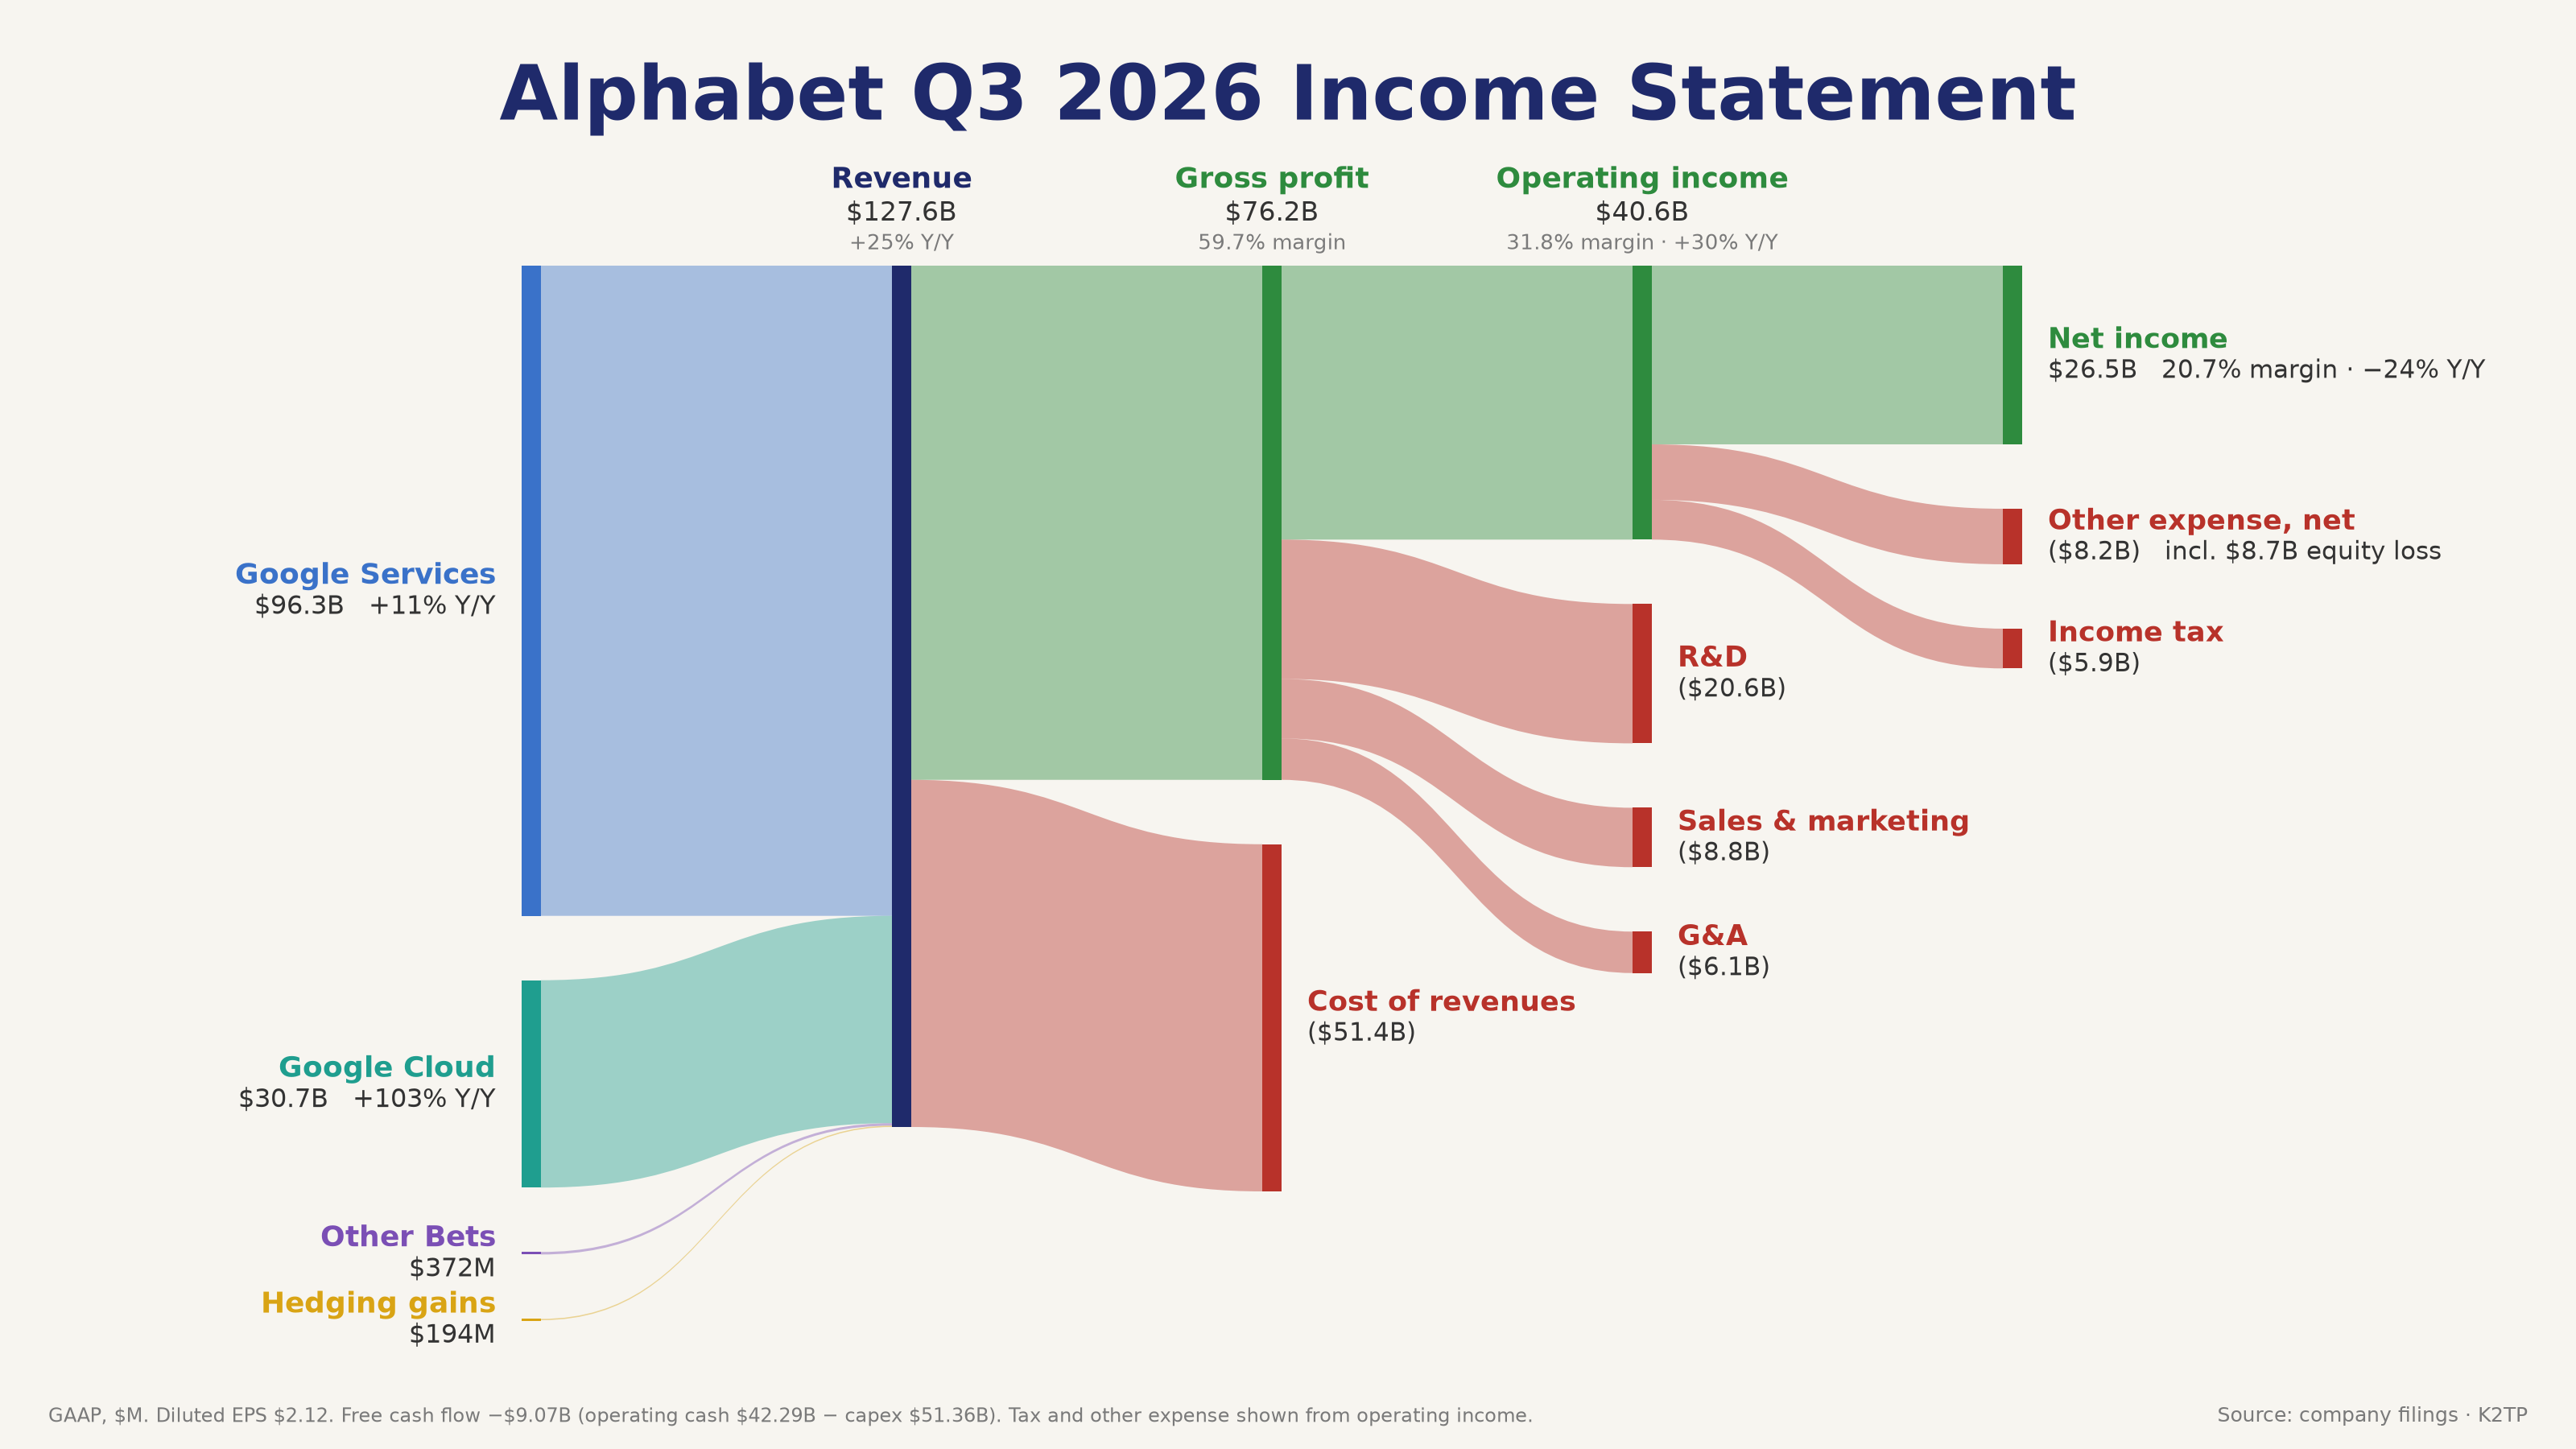
- Alphabet (8-K Ex. 99.1, Q3 2026): revenue $127.58B (+25%) vs $128.22B expected; operating income $40.58B (31.8% margin); GAAP EPS $2.12 after an $8.7B equity securities loss that cut EPS by $0.55, so $2.67 excluding it vs $3.02 expected (CNBC) 🔴
- Google Search & other $63.35B (+12%) vs about $64.9B expected; Google Cloud $30.71B (+103%) vs $29.1B, Cloud operating income $11.12B
- Alphabet capex was $51.36B against operating cash flow of $42.29B, so FCF was −$9.07B vs about −$2.70B expected; 2026 capex stays at $195B–$205B and 2027 spending will increase significantly (CNBC, Reuters); GOOGL −9.97% to 292.50 after hours
- Others after hours: ServiceNow −18.10% to 122.95 (adj. EPS $1.00 vs $1.02, Q4 cRPO guide 18.5% vs about 19%); Fortinet about −25%; KLA +3.95% on a Q2 revenue guide of $4.70B vs $4.487B; Chipotle +7.00% on same-store sales +2.1%; T-Mobile +0.70%; Ford −1.01%; Carvana +8.28% after the SEC closed its investigation
- Before the open: Vertiv adj. EPS $2.21 vs $1.82, revenue $4.31B vs $3.75B, 2026 EPS guide $7.15; GE Vernova orders $29B, revenue $12.6B (+27%) and a $20B buyback, yet GEV −1.90%; Boston Scientific adj. EPS $0.73 vs $0.75 and a 2026 guide cut to $3.16–$3.18 citing a cyberattack
→ The market is rewarding AI spending that cash flow pays for (Microsoft) and punishing spending that drains it (Alphabet). Amazon faces the same test Thursday after the close.
THE BIG SINGLE-STOCK MOVES
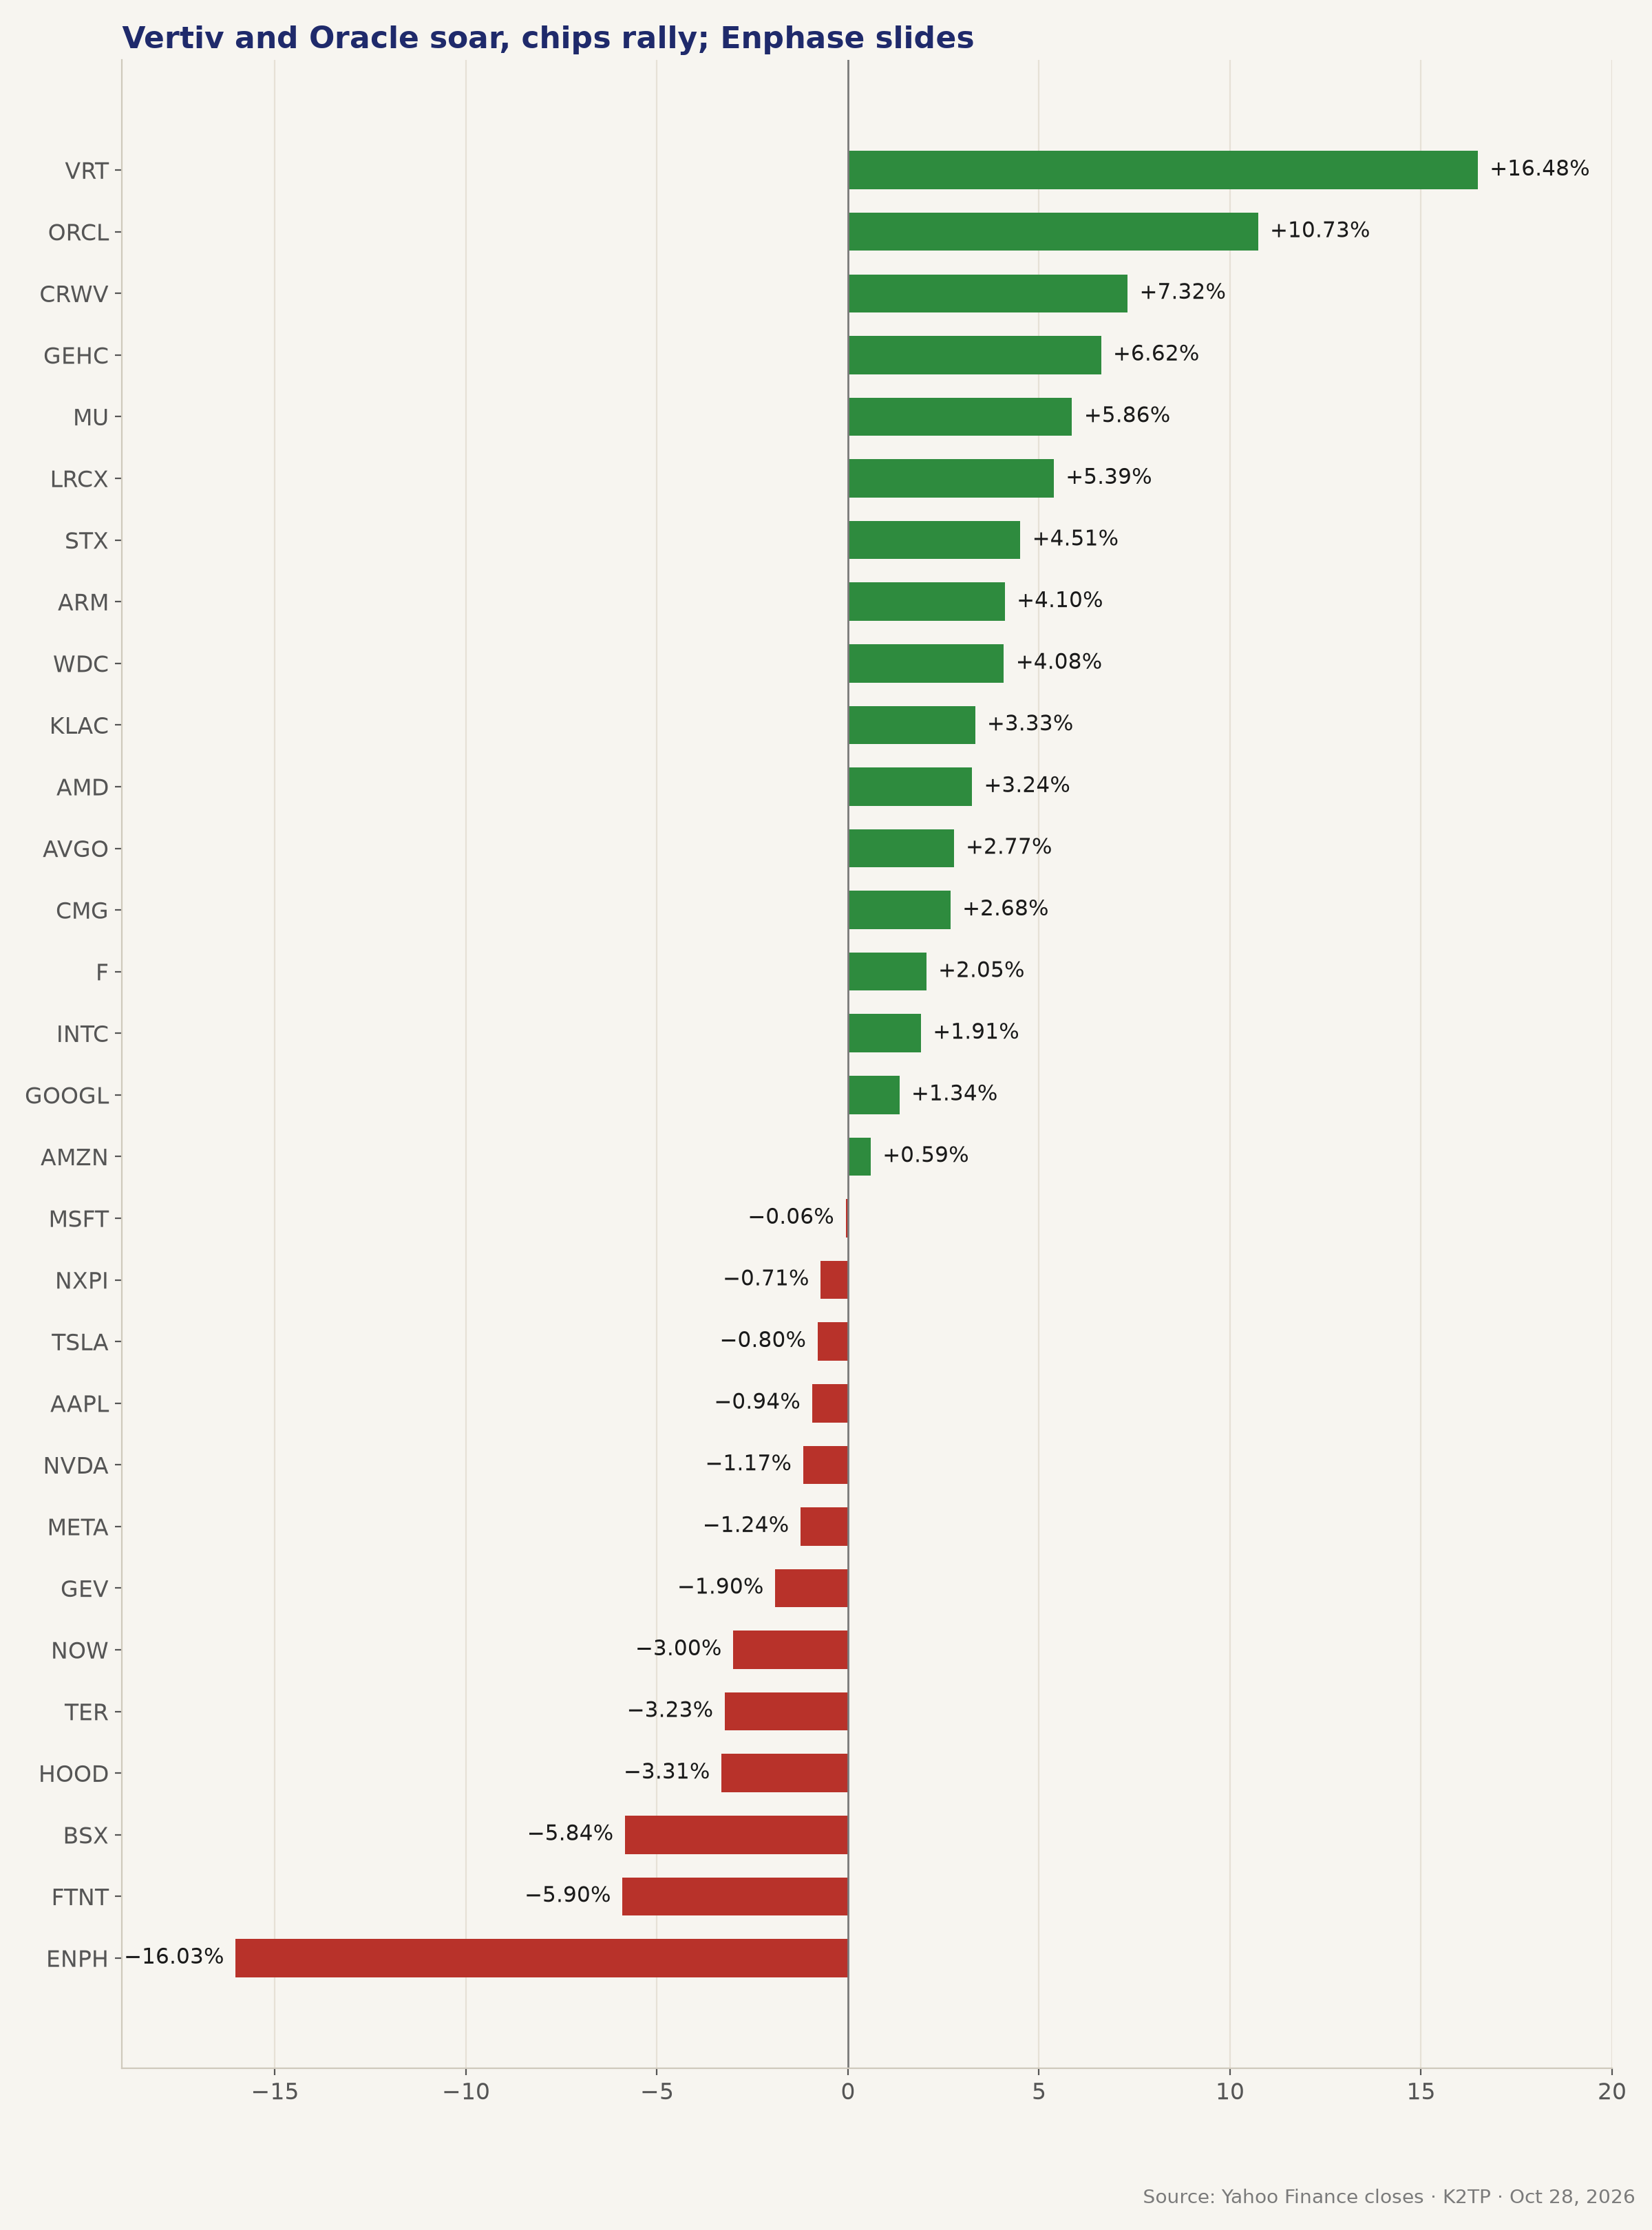
- Gainers: VRT +16.48%, ORCL +10.73%, CRWV +7.32%, GEHC +6.62%, MU +5.86%, LRCX +5.39%, STX +4.51%, ARM +4.10%, WDC +4.08%
- Losers: ENPH −16.03%, FTNT −5.90%, BSX −5.84%, HOOD −3.31%, TER −3.23%, NOW −3.00%, GEV −1.90%
- Boston Scientific recovered from −12.67% before the open to −5.84%; Enphase from −20.60% to −16.03%
- After hours the regular-session leaders gave back about 2%: ORCL −2.41%, MU −2.47%, AVGO −2.19%, AMD −1.99%
→ The biggest moves were earnings-driven. The after-hours give-back in ORCL and memory shows that the AI trade is vulnerable when a hyperscaler's cash flow disappoints.
OIL BACK ABOVE $100 KEEPS THE LONG END HEAVY
- December WTI settled at $102.78 (+2.88%) and reached $103.50 at midday after EIA crude stocks fell 1.892M barrels vs 0M expected; gasoline +3.87M (Midday and Pre-Close briefs) 🟡
- Axios reports that large US strikes on Iran are possible after the midterms (unconfirmed); Iran's foreign minister said Iran still gives diplomacy a chance
- Israel's election has no clear winner, with official results due November 4 (Pre-Market brief)
- Tonight (6:56 PM PT): WTI about $101.87, Brent about $110.55; XLE +0.35% at the close
- Gold settled at $4,051.60 and was about $4,074.50 tonight
→ Oil above $100 is why the long end did not follow the 2Y lower after the hold. It keeps the inflation risk live into PCE.
A BEAR STEEPENER AFTER THE HOLD
- Advance goods trade deficit −$134.9B vs −$130.2B expected; MBA mortgage applications +3.4% with the 30-year rate at 7.37%; wholesale inventories +0.6% (Pre-Market and Midday briefs)
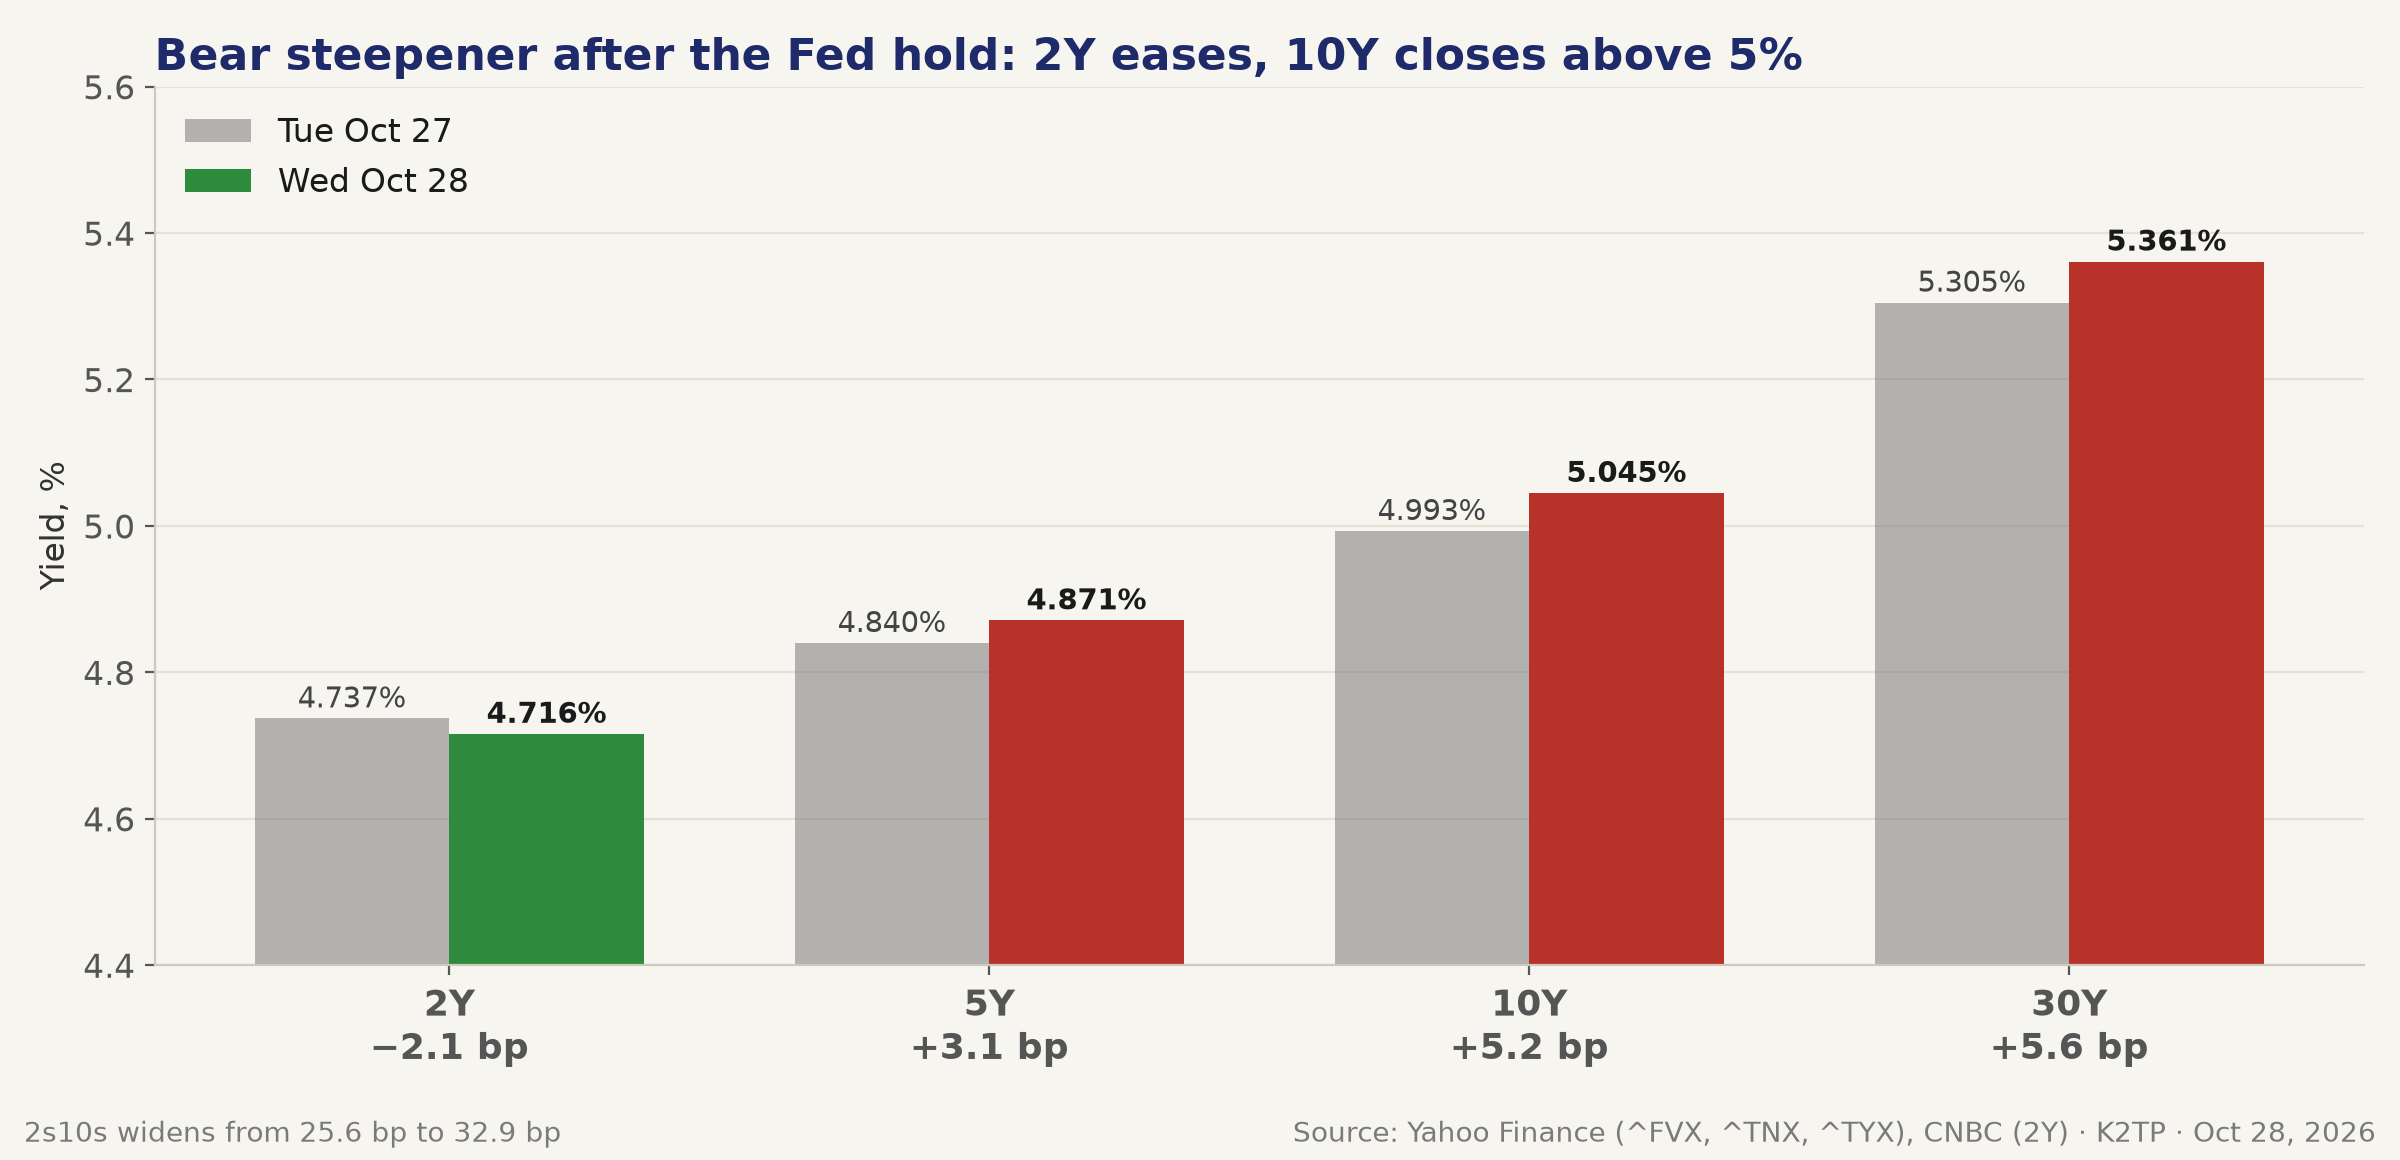
- Bank of Canada hike and oil pushed the 2Y up to 4.776% by midday; after the FOMC it fell to 4.716% (Midday and Pre-Close briefs)
- Closing yields: 2Y 4.716% (−2.1 bp), 5Y 4.871% (+3.1 bp), 10Y 5.045% (+5.2 bp, range 4.991–5.049%), 30Y 5.361% (+5.6 bp); 2s10s widened from 25.6 bp to 32.9 bp
- LSEG data show traders pricing at least three 25 bp hikes by late 2027 (Pre-Market brief, Reuters)
- 7-year note auction Thursday at 9:00 AM PT; the previous sale cleared at 5.085%
→ The front end read the hold as less hawkish, but oil and term premium push the long end up. A 10Y above 5% is now a direct headwind for long-duration tech and rate-sensitive sectors.
SPX DIPS INTO THE FED, SPIKES IN THE PRESS CONFERENCE, CLOSES IN THE UPPER HALF
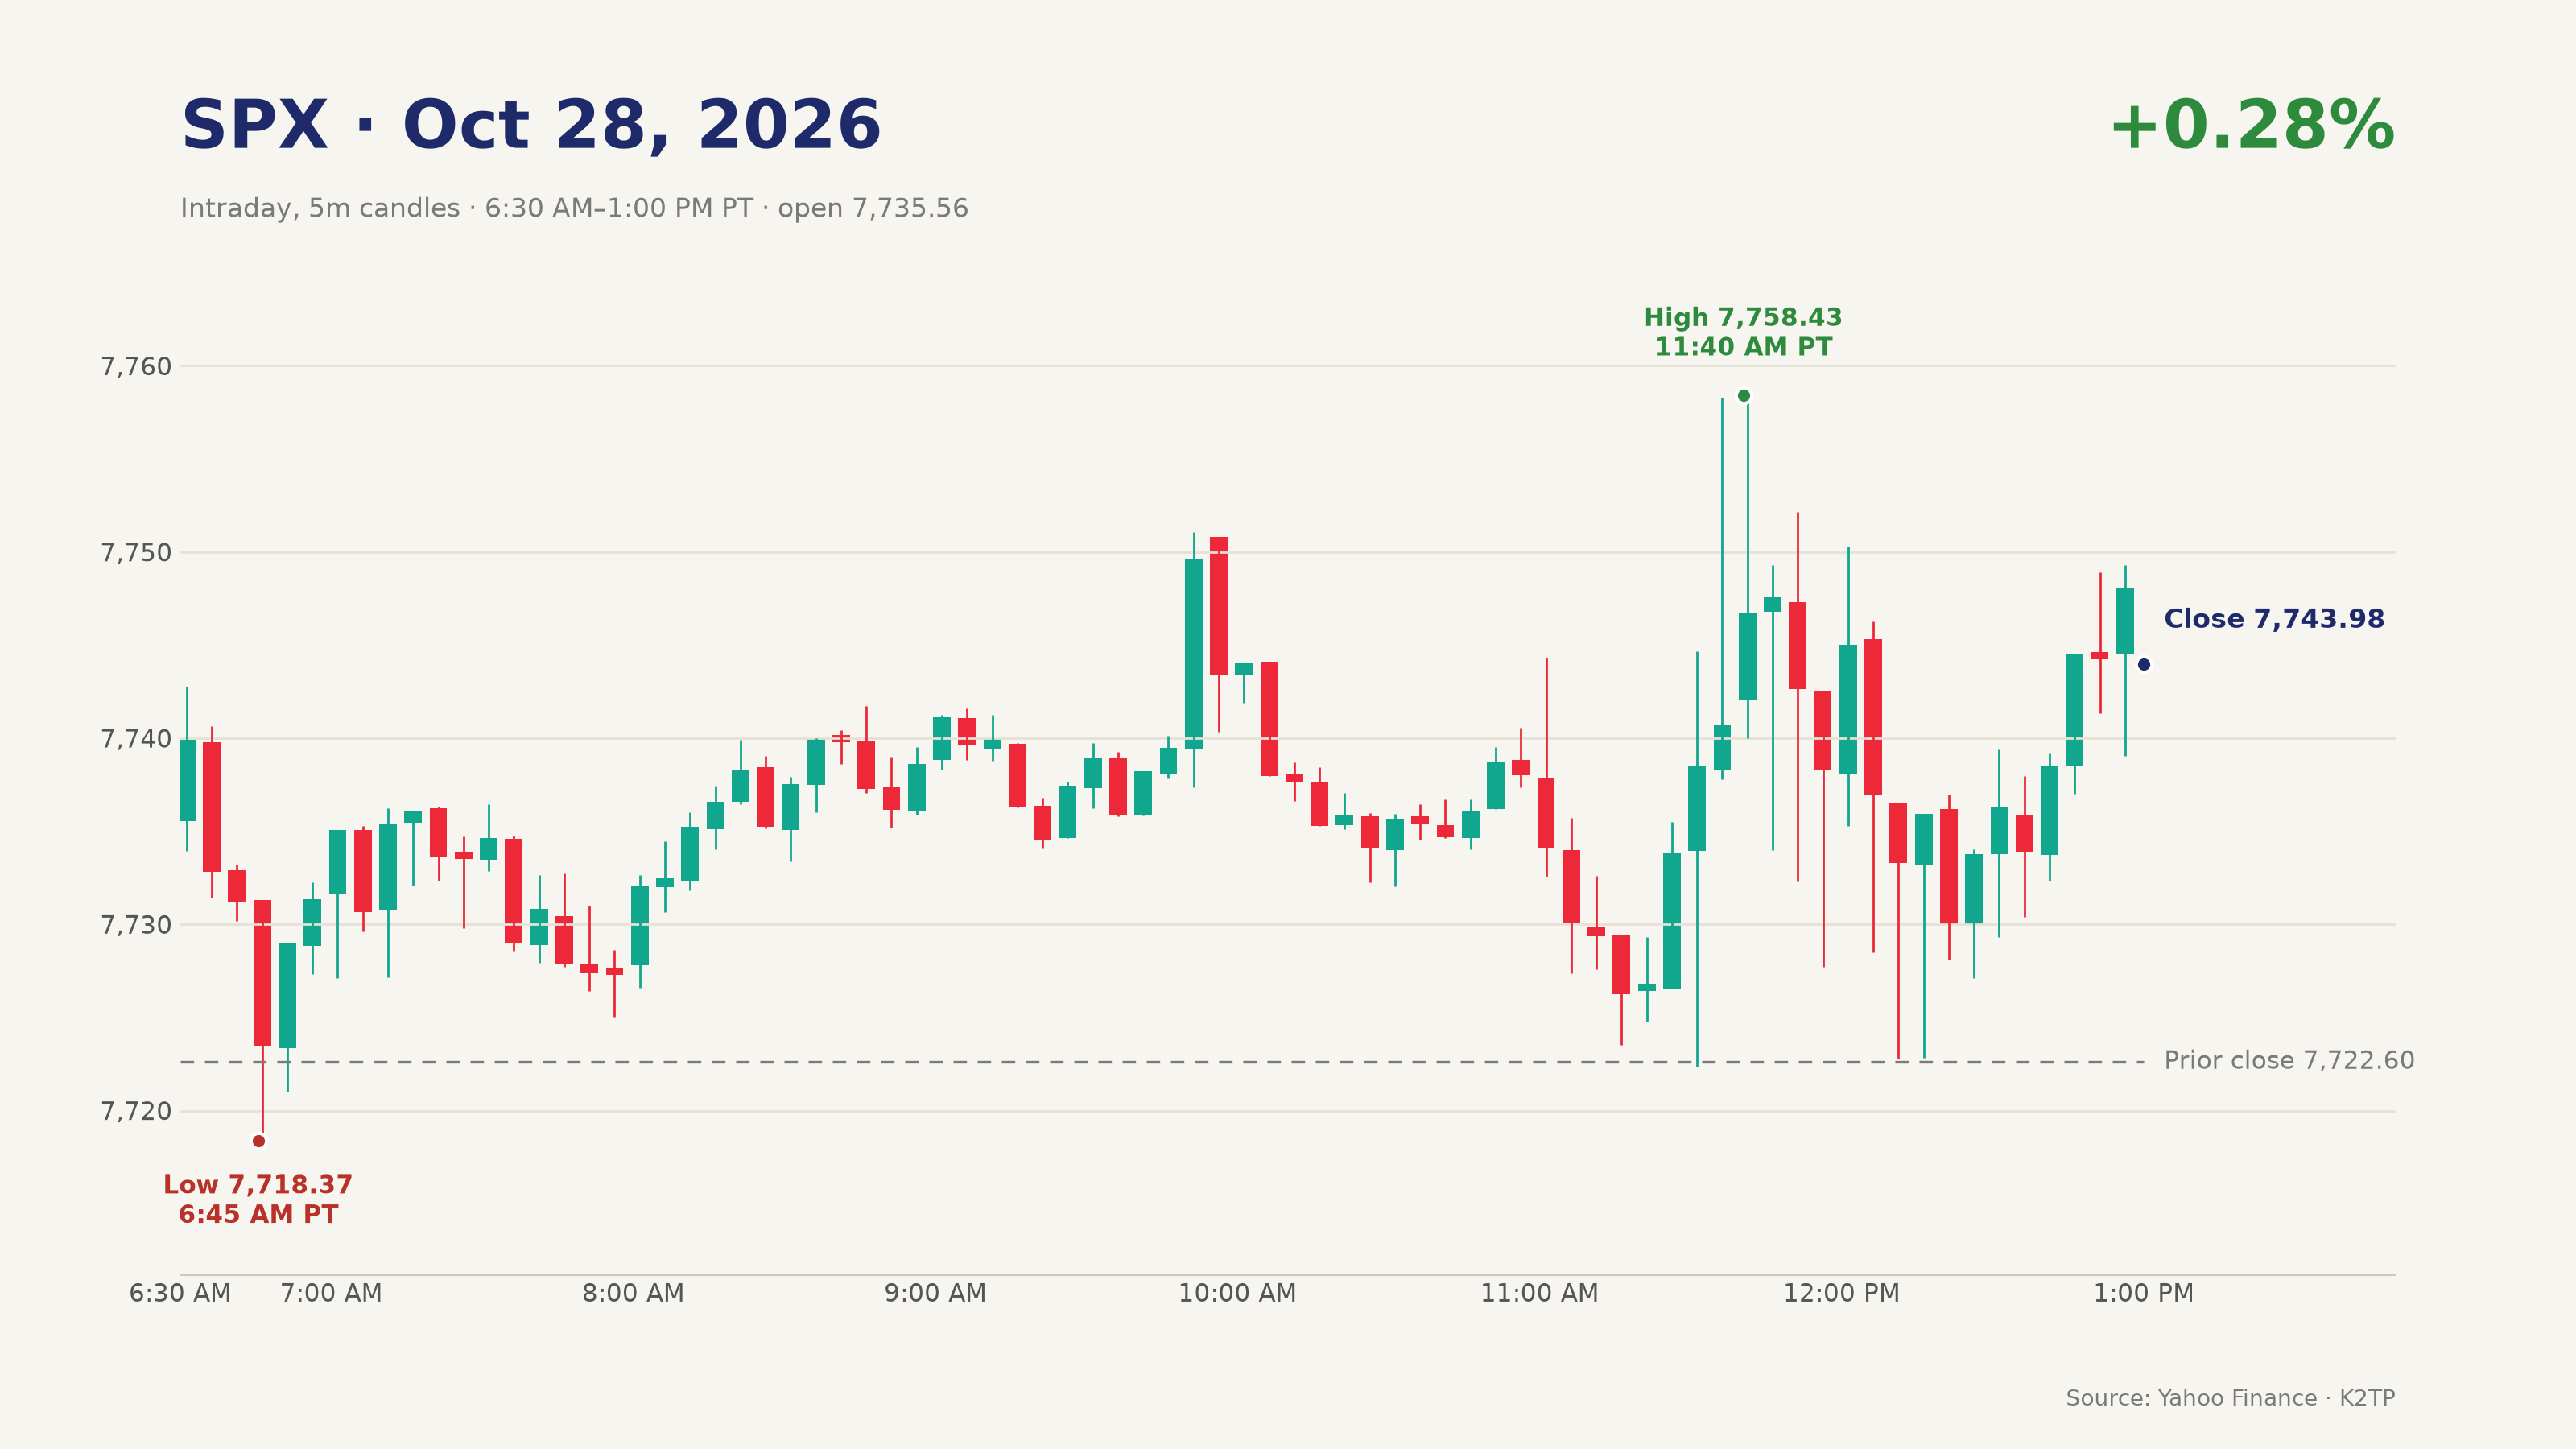
- Pre-market: ES +0.23%, NQ +0.41%; implied SPX near 7,740, just above Tuesday's 7,736.24 high, with VIX at 17.43
- SPX opened at 7,735.56, touched 7,742.75 in the first five minutes, then fell to the day low of 7,718.37 at 6:45 AM PT
- SPX was 7,735.80 at midday (+0.17%); a pop to 7,751.06 at 9:50 AM PT did not hold
- Into the press conference SPX fell to 7,722.37, then spiked to the day high of 7,758.43 at 11:40 AM PT, and VIX touched 16.93
- SPX faded to 7,722.78 at 12:10 PM PT (pre-close 7,727.66), then rallied in the last 15 minutes to close at 7,743.98
- The pre-close Bull trigger was half met: VIX closed at 16.91, under 16.93, but SPX never got back above 7,758.43; the Bear trigger (under 7,718.37 with VIX above 17.77) did not fire
→ Buyers held the morning low twice and closed SPX in the upper part of the range. 7,718–7,758 is the range going into PCE and the Alphabet reaction.
MARKET: THE FED HOLDS, CHIPS AND ORACLE LIFT SPX AS THE 10Y TOPS 5%
Indices (close):
- SPX 7,743.98 (+0.28%), range 7,718.37–7,758.43
- NDX 29,813.16 (+0.55%); Nasdaq Composite 26,549.85 (+0.27%)
- DJIA 52,475.10 (+0.19%)
- RUT 2,830.51 (+0.41%)
- RSP 217.43 (−0.04%)
- SOX 11,684.00 (+1.75%)
Intraday path: Pre-market ES +0.23% and NQ +0.41% on SK Hynix's record quarter. SPX opened at 7,735.56, hit the low of 7,718.37 at 6:45 AM PT, was 7,735.80 at midday, dipped to 7,722.37 into Warsh's press conference, set the day high of 7,758.43 at 11:40 AM PT, faded to 7,722.78 at 12:10 PM PT and closed at 7,743.98.
Sector rotation:
- Up: XLK +0.80%, XLF +0.45%, XLE +0.35%, XLI +0.34%, XLV +0.30%, XLB +0.15%
- Down: XLY −0.10%, XLP −0.36%, XLC −0.42%, XLRE −0.73%, XLU −0.84%
- Mega-cap: ORCL +10.73%, MU +5.86%, AMD +3.24%, AVGO +2.77%, GOOGL +1.34%, TSM +0.60%, AMZN +0.59%; MSFT −0.06%, TSLA −0.80%, AAPL −0.94%, NVDA −1.17%, META −1.24%
Internals:
- RSP −0.04% vs SPX +0.28%; RUT +0.41% and IWM +0.40% held up
- NYSE and Nasdaq advance/decline data were unavailable today
- 6 of 11 sectors up: breadth improved from pre-close (5/11, RSP −0.47%) but rate-sensitive sectors lagged
Volatility:
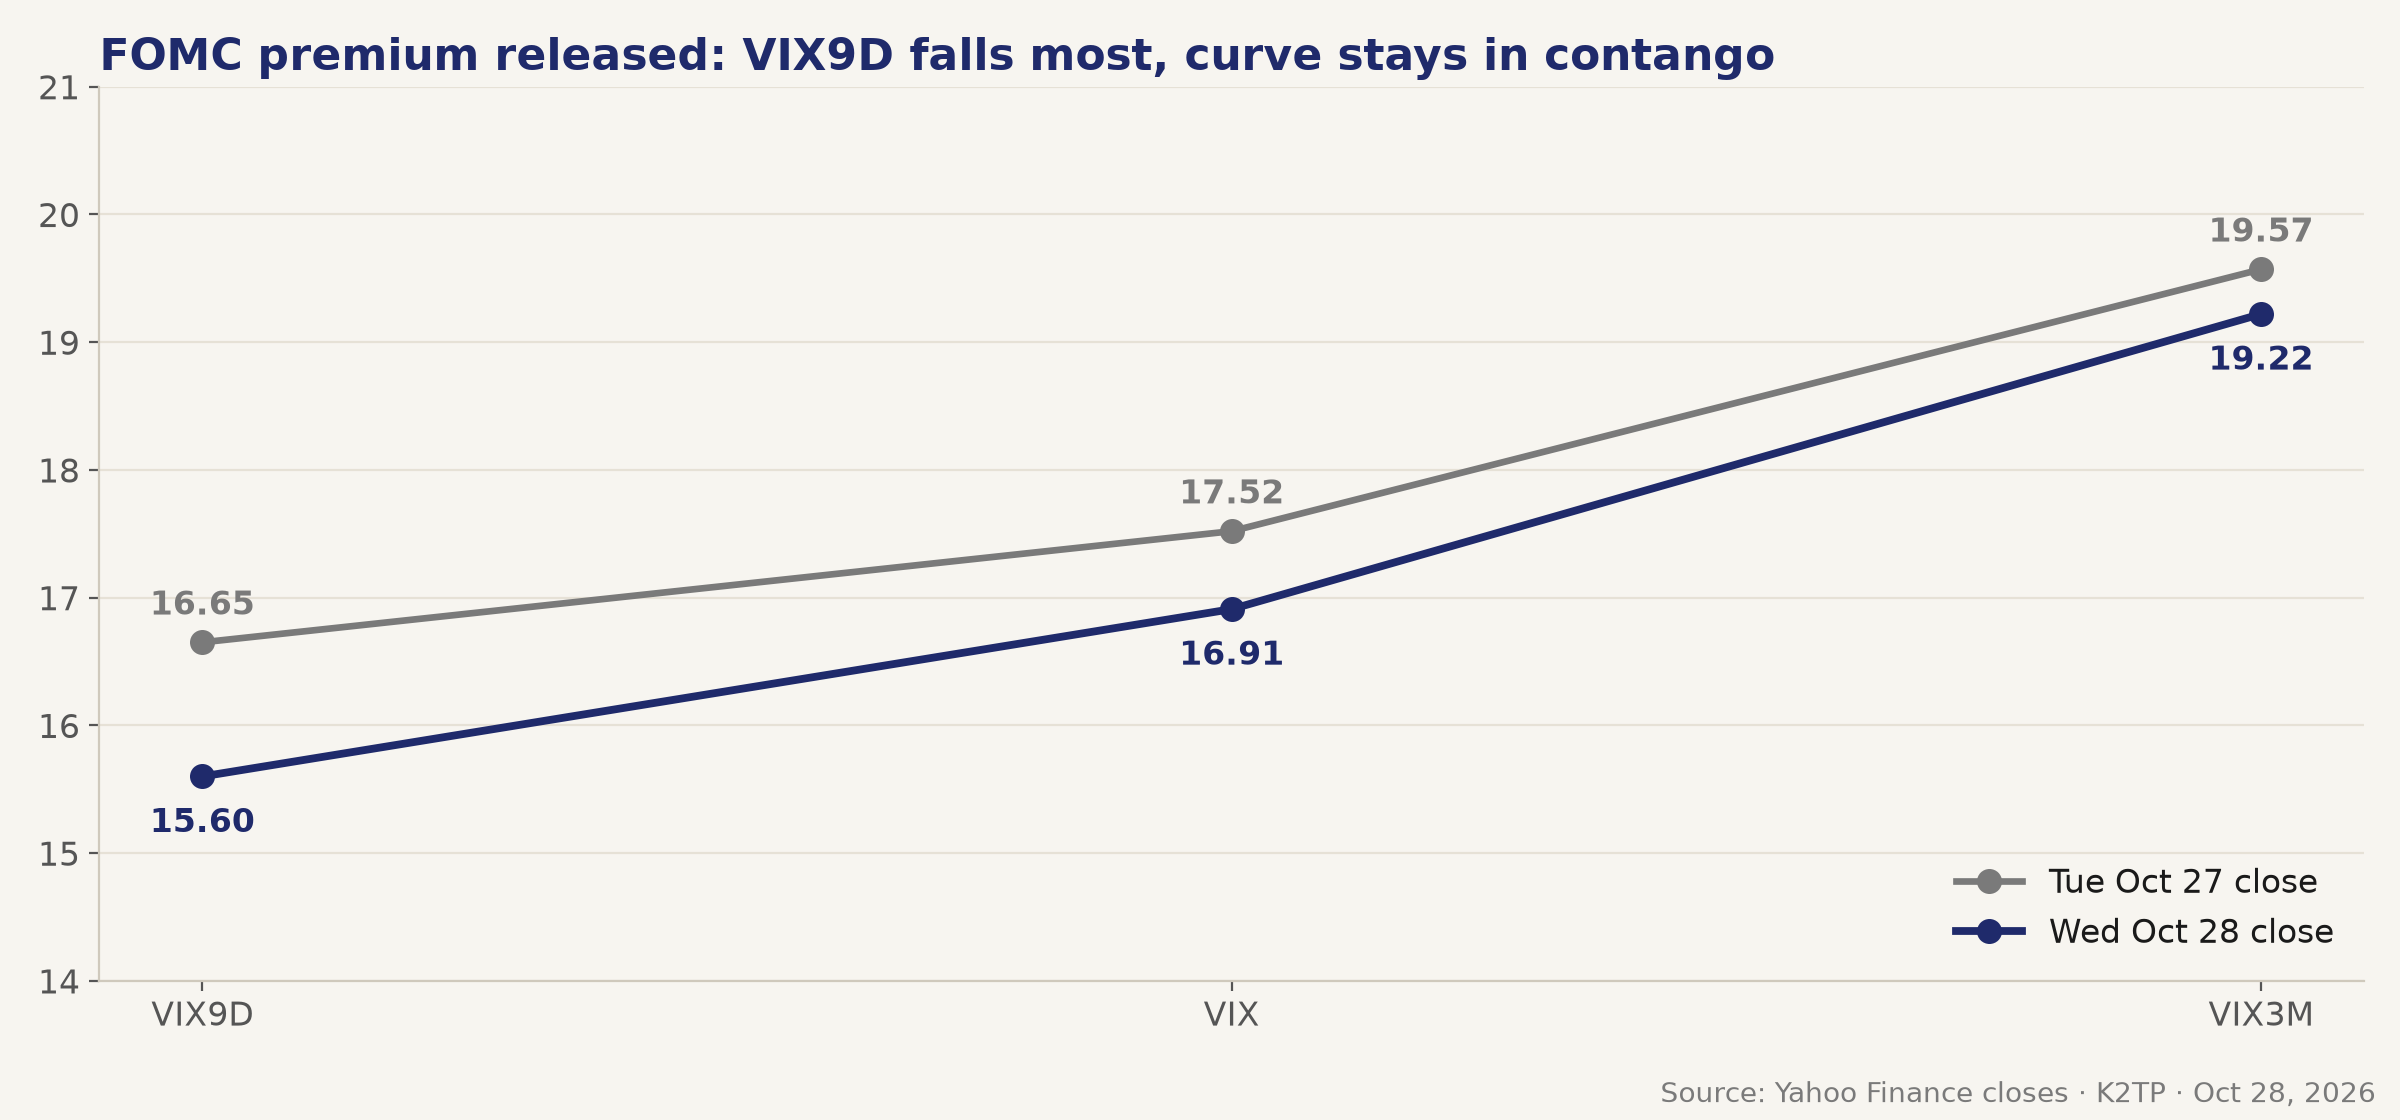
- VIX 16.91 (−3.48%), range 16.21–17.77
- VIX9D 15.60, VIX3M 19.22: the FOMC premium came out of the front end and the curve stays in contango
- VVIX 96.61 (−2.86%)
Cross-asset:
- WTI December settled at $102.78 (+2.88%), about $101.87 tonight; Brent about $110.55 tonight
- Gold settled at $4,051.60, about $4,074.50 tonight; DXY 102.13; BTC about $79,900 tonight
- Tonight (6:56 PM PT): ES 7,754.00 (−0.38%), NQ 29,584.25 (−1.32%); in the Evening Recap YM was +0.28% and RTY +0.66%
Global:
- Asia (Wednesday, Pre-Market brief): Kospi +6.63%, Taiwan +2.16%, Nikkei +1.08%, Shanghai −0.43%, Hang Seng −0.50%
- Europe at the close: DAX +0.44%, Euro Stoxx 50 +0.05%, FTSE 100 +0.07% (Pre-Close brief)
- Tonight: the PBOC injected 1 trillion yuan via overnight reverse repos and set the yuan midpoint at its strongest since February 2023 (Evening Recap); early Thursday Nikkei −0.10%, Kospi −2.86% (Yahoo, about 6:50 PM PT)
Key SPX levels:
- 7,758.43: Wednesday's high, Bull trigger
- 7,743.98: close
- 7,727.66: pre-close level
- 7,718.37: Wednesday's low, Bear trigger
- 7,702.13: base-range floor, TRANSITION line on a close below
- 7,677.16: Tuesday's low, RISK-OFF line with VIX above 18.55
- VIX: 16.21 and 17.77
Option seller corner:
- Bull case: SPX above 7,758.43 with VIX under 16.21 broadens RISK-ON. Add new far-OTM SPX put spreads only after the 5:30 AM PT GDP and PCE prints settle.
- Bear case: SPX under 7,718.37 with VIX above 17.77 tests the narrow rally. Then cut short-put size and use only defined-risk spreads, especially on NDX, where Alphabet's −10% after hours already hits the open.
- VIX9D 15.60 sits below VIX 16.91 and VIX3M 19.22, so near-dated premium is cheap even though it covers PCE and Amazon. Selling those expirations pays little for the event risk.
- Avoid short premium through single-stock earnings (AMZN, COIN Thursday after the close). NDX carries gap risk with NQ futures −1.32% tonight.
BOTTOM LINE
- The Fed held at 3.75%–4.00% with two hike dissents and Warsh kept December open; the 2Y eased but the 10Y closed at 5.045% as oil stayed above $100.
- Oracle and memory chips lifted SPX +0.28% to 7,743.98, but breadth was narrow: RSP −0.04%, 6 of 11 sectors up, utilities and real estate lower.
- Regime 🟢 RISK-ON (narrow, tested). After the bell, Alphabet's −$9.07B FCF hit the AI trade while Microsoft's self-funded capex was rewarded; NQ futures are −1.32% tonight. A close under 7,702.13 returns the read to TRANSITION.
What to watch Thursday (PT):
- 5:30 AM: Q3 GDP (forecast 3.2%, prior 2.2%), September PCE (forecast 3.6% y/y, core 3.1%), initial jobless claims (forecast 198K)
- 6:15 AM: ECB rate decision
- 9:00 AM: 7-year note auction (previous 5.085%)
- After the close: Amazon (EPS est. $1.97, revenue est. $202.21B), Coinbase
- The open: whether Alphabet's after-hours drop spreads to AI hardware and the other hyperscalers
Bull expectation: GDP and PCE land in line, the 10Y slips back under 5%, Microsoft and chips offset Alphabet, and SPX takes out 7,758.43 with VIX under 16.21. Bear expectation: PCE runs hot and the 2Y retraces its post-FOMC drop, Alphabet's FCF drain spreads to AI hardware, SPX loses 7,718.37 and VIX rises above 17.77.
Sources: the four K2TP briefs for 10/28/2026 (Pre-Market, Midday, Pre-Close, Evening Recap). Official closing and intraday prices from Yahoo Finance; 2Y from CNBC; oil settlements, news and data from CNBC, Reuters, Investing.com and FinancialJuice; Microsoft and Alphabet Sankeys and the capex chart from the Microsoft fiscal Q1 2027 (8-K Ex. 99.1) and Alphabet Q3 2026 (8-K Ex. 99.1) releases, SEC EDGAR. Analysis: K2TP Framework.