Market 10/26: Anthropic's IPO filing lifts chips and SPX clears Friday's high; Meta's $95B raise and Brazil's selloff limit the rally
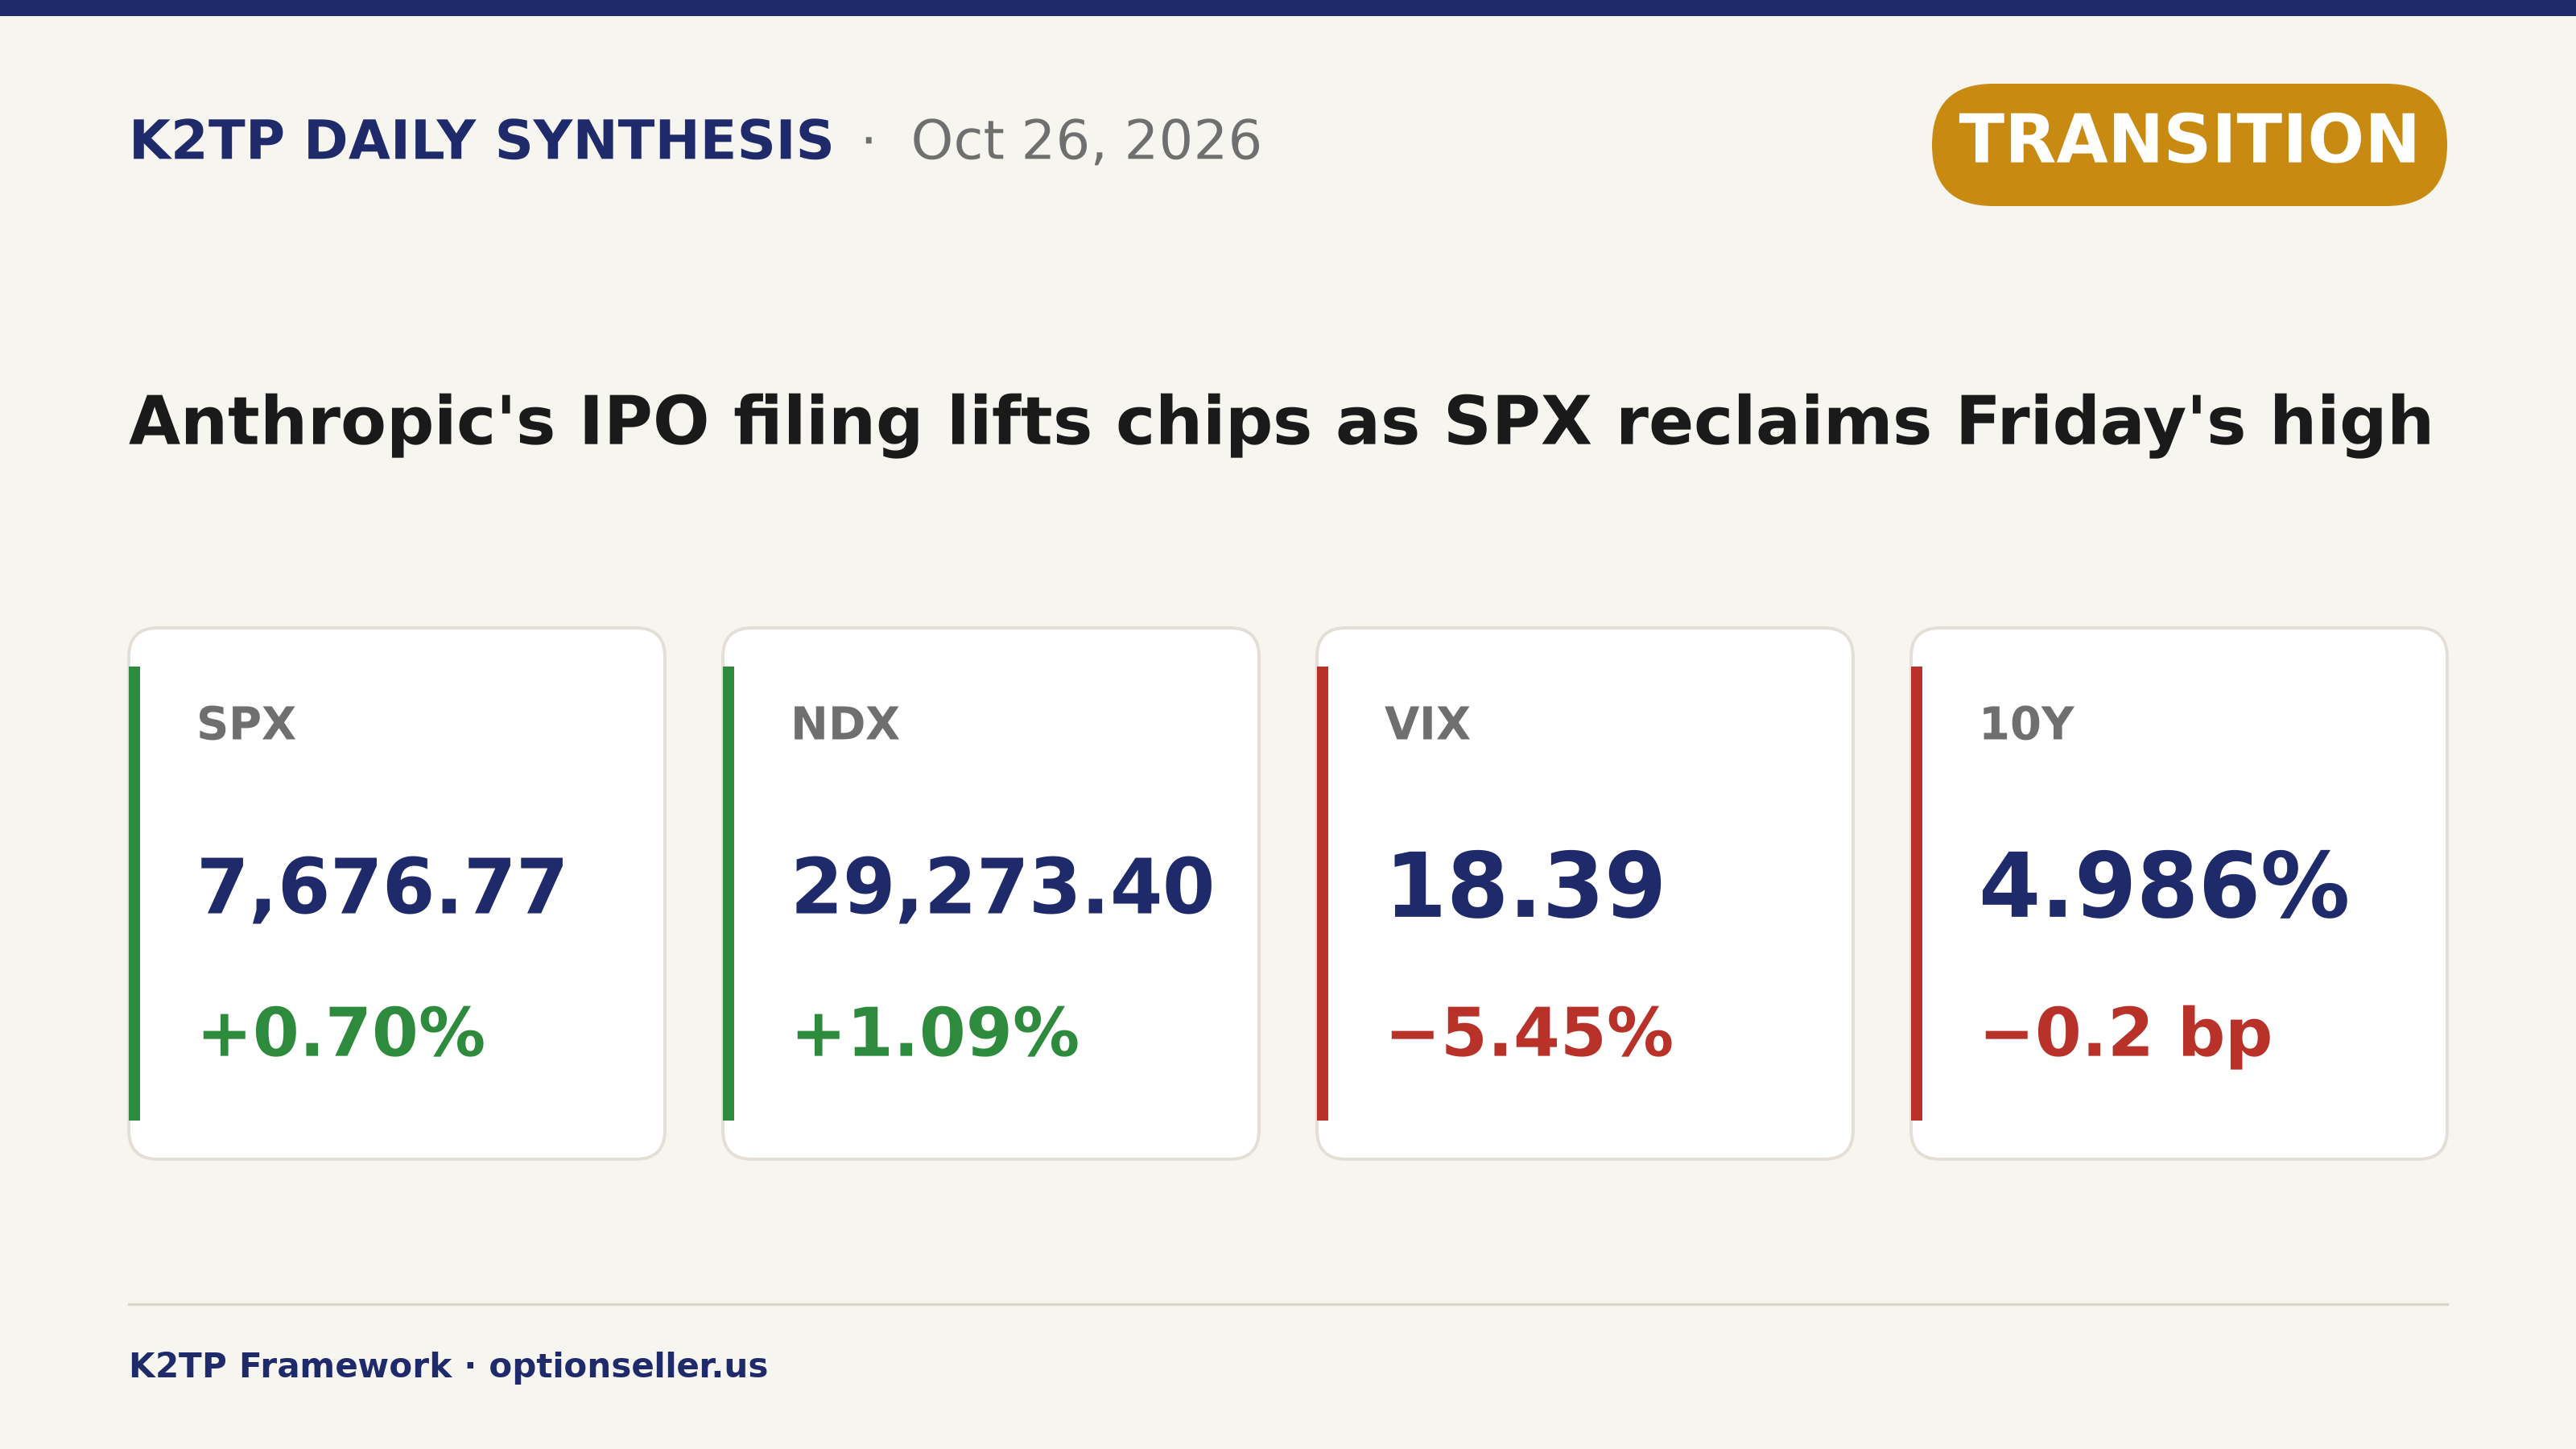
SPX +0.70%, NDX +1.09%, DJIA +0.28%, VIX −5.45% to 18.39. SOX +2.82% and TSLA +5.21% lead; META −1.88% on its equity plan and EWZ −19.82% after Lula's re-election; WTI settles $101.76, still above $100.
KEY HEADLINES
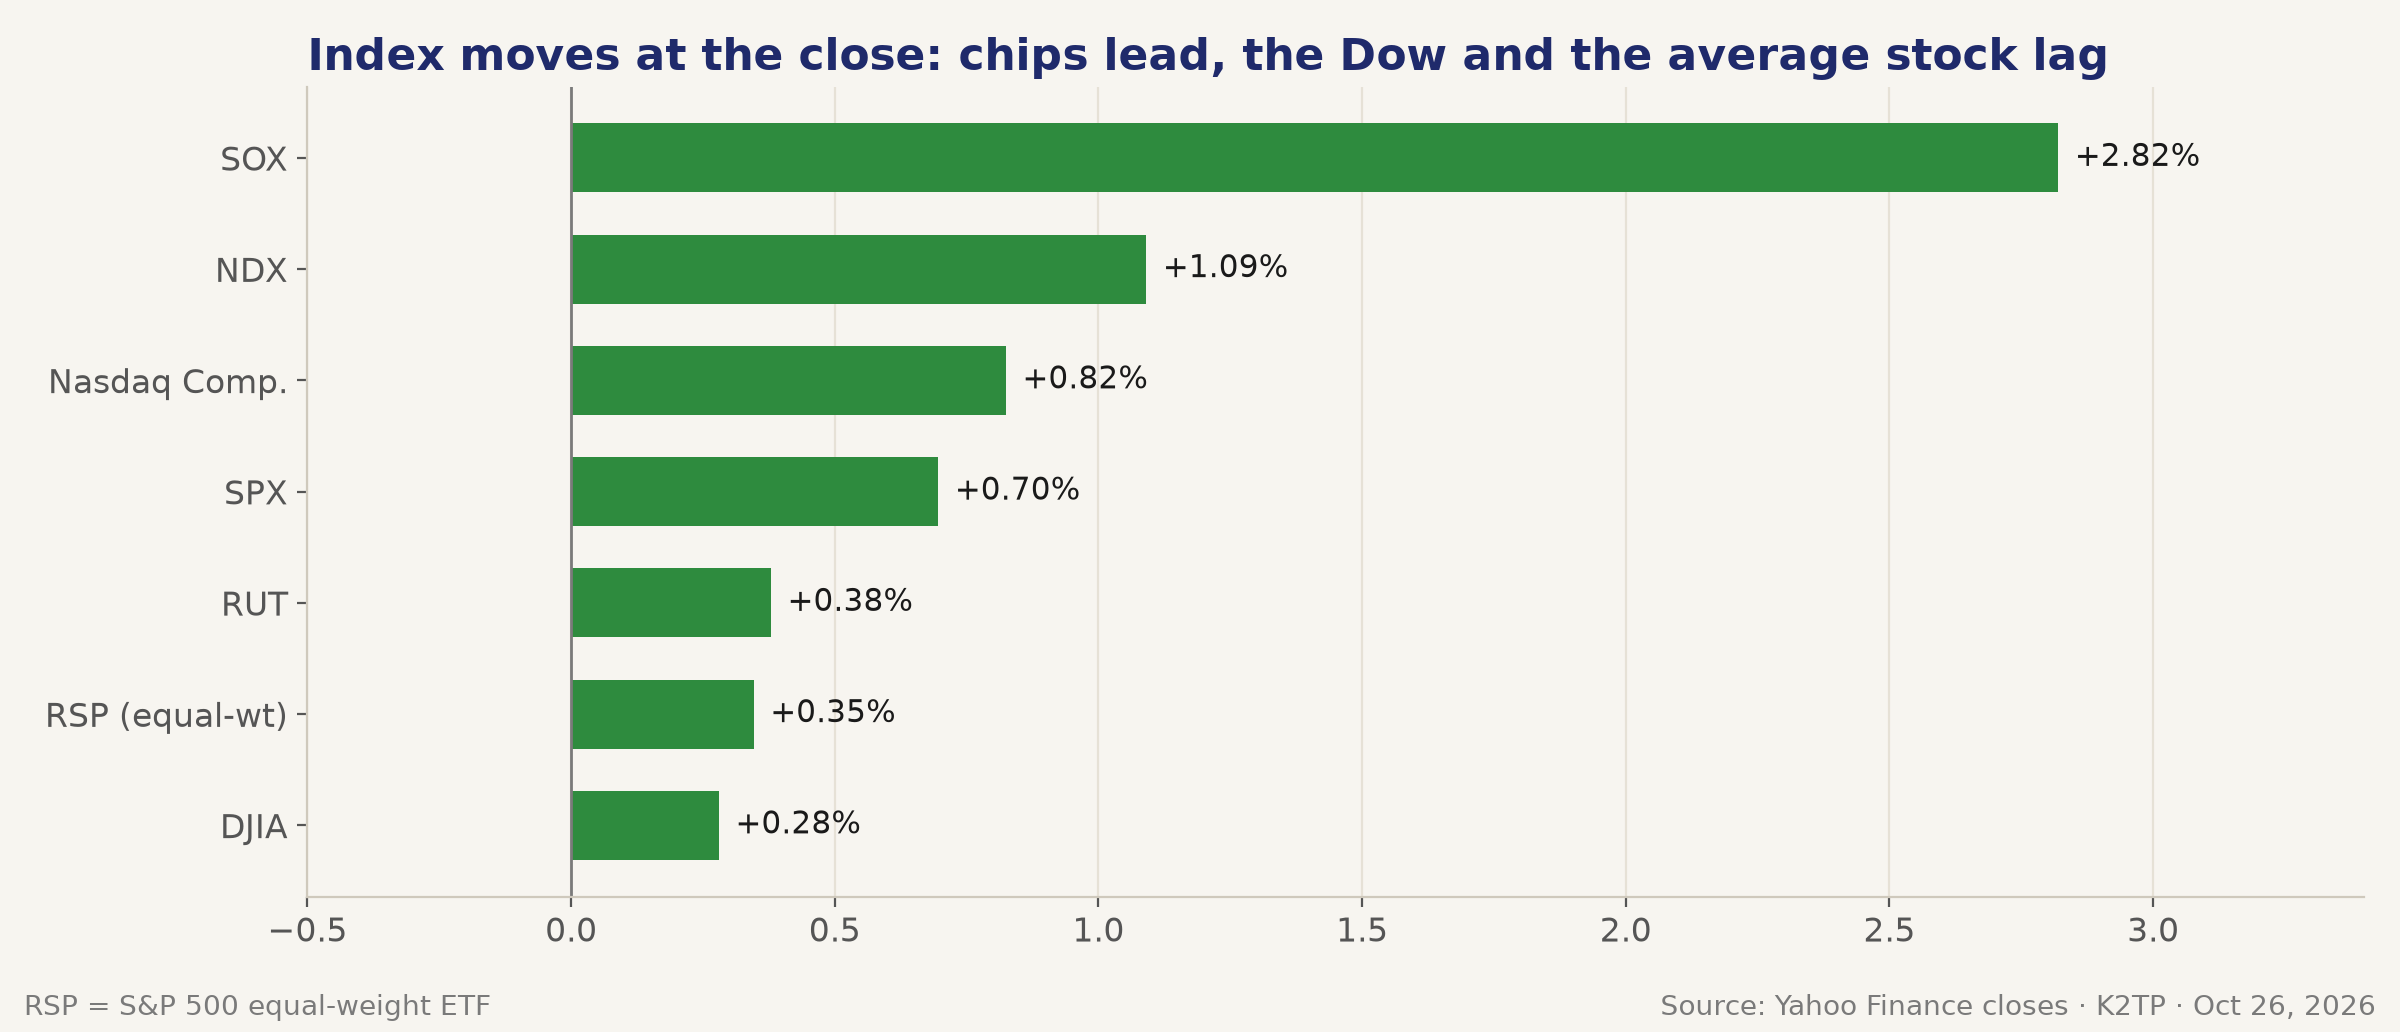
- SPX +0.70% to 7,676.77 (+53.09 points); NDX +1.09% to 29,273.40; Nasdaq Composite +0.82%; DJIA +0.28% to 52,361.58; RUT +0.38%
- Anthropic publicly filed its S-1 to list on the Nasdaq as "ANT", reporting $16.29B of revenue for the six months to June, up 1,304% (Midday brief); SOX +2.82%, INTC +4.04%, MU +2.98%, AMD +2.80%, NVDA +2.39%, AVGO +2.33%
- Meta plans to raise up to $95B in equity for AI ($35B underwritten first, then a $60B at-the-market program); META −1.88% and XLC −1.57%, the worst sector
- SPX cleared Friday's 7,660.15 high with VIX under 18.87, meeting the pre-market Bull line; it peaked at 7,702.13 around 8:00 AM PT, then held a 7,667–7,696 range
- TSLA +5.21% after a Barclays upgrade to overweight (target $450 from $370); AAPL −1.10%, GOOGL −1.06%
- Brazil shock: EWZ −19.82% and the Bovespa −13.88% after Lula's surprise re-election; MercadoLibre −7.81%
- Verizon −3.49%: adjusted EPS $1.31 beat, revenue $34.31B missed; FICO −13.15% on a Wells Fargo downgrade; RRC +17.66% on EQT's all-stock deal
- $69B 2-year auction tailed 0.3 bp at 4.708%; 10Y 4.986% (−0.2 bp), 5Y +1.9 bp, 30Y −1.4 bp
- WTI settled $101.76 (−1.46%) after a $103.13 high; Houthis attacked Saudi pumping stations and Riyadh airport (Reuters)
- After hours: a $63B financing vehicle will lease Broadcom XPUs to Anthropic (AVGO +1.32%); Celestica about +10% to +16%, Cadence about +2.4%, Whirlpool about −9%
- Regime: 🟡 TRANSITION, up from RISK-OFF; breadth is modest, oil is above $100 and the FOMC decides Wednesday
ANTHROPIC'S IPO FILING REVIVES THE AI TRADE
- Anthropic publicly filed for a Nasdaq IPO under the ticker "ANT"; revenue for the six months ended June was $16.29B, versus $1.16B a year earlier (Midday brief) 🟢
- Chips led all day: SOX +2.82% to 11,083.47 (high 11,182.46); LITE +8.19%, COHR +5.83%, INTC +4.04%, WDC +3.63%, LRCX +3.22%, MU +2.98%, AMD +2.80%, NVDA +2.39%, AVGO +2.33%, TSM +1.40%
- More AI funding: Meta's up-to-$95B equity plan, with Nvidia, AMD and Broadcom offering to buy up to $5B of the shares; SpaceX signed a $40B GPU financing deal with Apollo (Pre-Market brief)
- After the close, Bank of America, Blackstone, Citi and Morgan Stanley set up a $63B financing vehicle to buy Broadcom XPU accelerators and lease them to Anthropic from 2027; AVGO +1.32% after hours (Evening Recap)
- OpenAI is rolling out GPT-6.1 Terra (Pre-Close brief); the FTC wants Anthropic executives to testify in a probe (Axios via FinancialJuice, unconfirmed)
- SOX was +3.43% at the pre-close; a sell-side market-on-close imbalance (about $1.72B in the S&P 500, $1.49B in the Nasdaq 100) trimmed the gain into the bell
- CNBC notes the semiconductor ETF is still down about 13% this month and about 25% from its high
→ Funding visibility for AI is back, and it lifts the suppliers first. But chips are rebounding from a deep October drawdown, so this is a relief rally until MSFT and GOOGL confirm capex on Wednesday.
META'S RAISE WEIGHS ON COMMUNICATION SERVICES; TESLA LEADS MEGACAPS
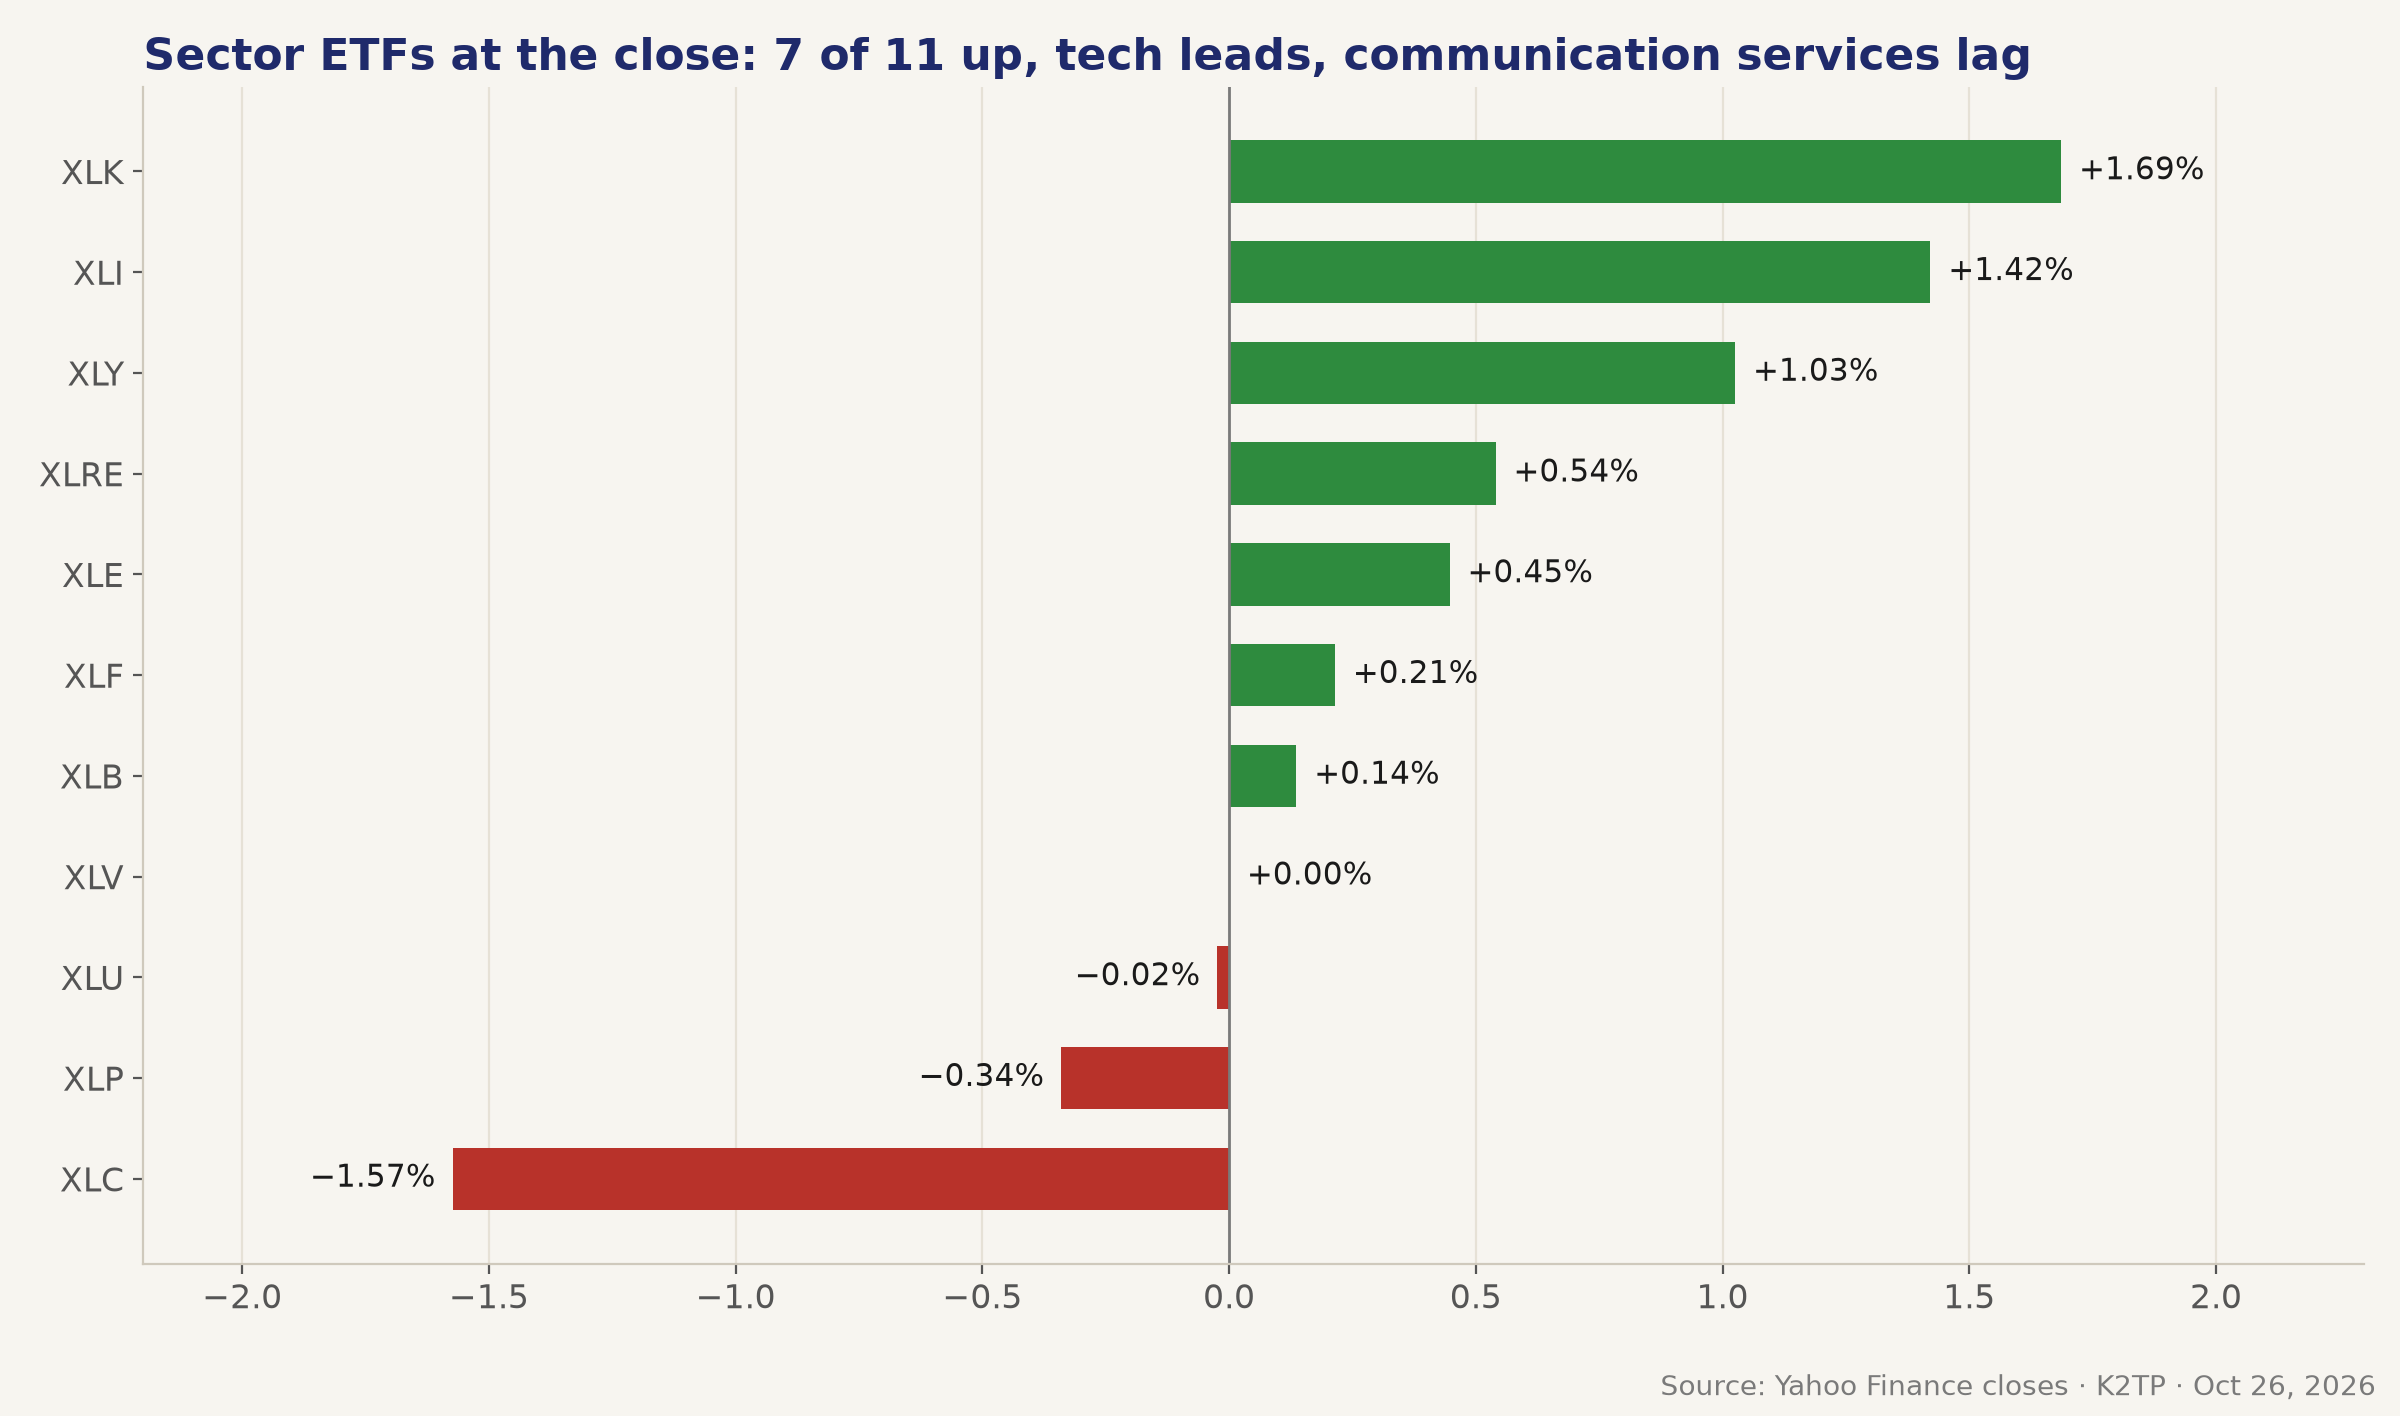
- 7 of 11 sector ETFs rose: XLK +1.69%, XLI +1.42%, XLY +1.03%, XLRE +0.54%, XLE +0.45%, XLF +0.21%, XLB +0.14%; XLV flat (+0.00%); XLU −0.02%, XLP −0.34%, XLC −1.57%
- META −1.88%: it rose about 1.5% pre-market on the funding plan, then faded (−0.07% at midday, −1.23% at the pre-close); GOOGL −1.06%, NFLX −2.96% and VZ −3.49% also pulled XLC lower 🔴
- TSLA +5.21% to 391.62 after Barclays upgraded it to overweight and raised its target to $450 from $370; it drove most of XLY's gain 🟢
- AAPL −1.10%: Apple said Siri AI is unavailable in the EU and acknowledged an inner-display issue on a small number of iPhone Duo units (Pre-Close brief)
- MSFT +1.54%; FinancialJuice reported Microsoft plans buyouts for 60,000 workers (unconfirmed); AMZN +0.44%
- Defense bid: LMT +5.13%
→ The market rewards AI suppliers but charges the spenders for dilution and funding costs. That split matters for Wednesday, when MSFT and GOOGL report after the close.
EARNINGS: VERIZON SLIPS; CADENCE AND CELESTICA RISE AFTER THE BELL
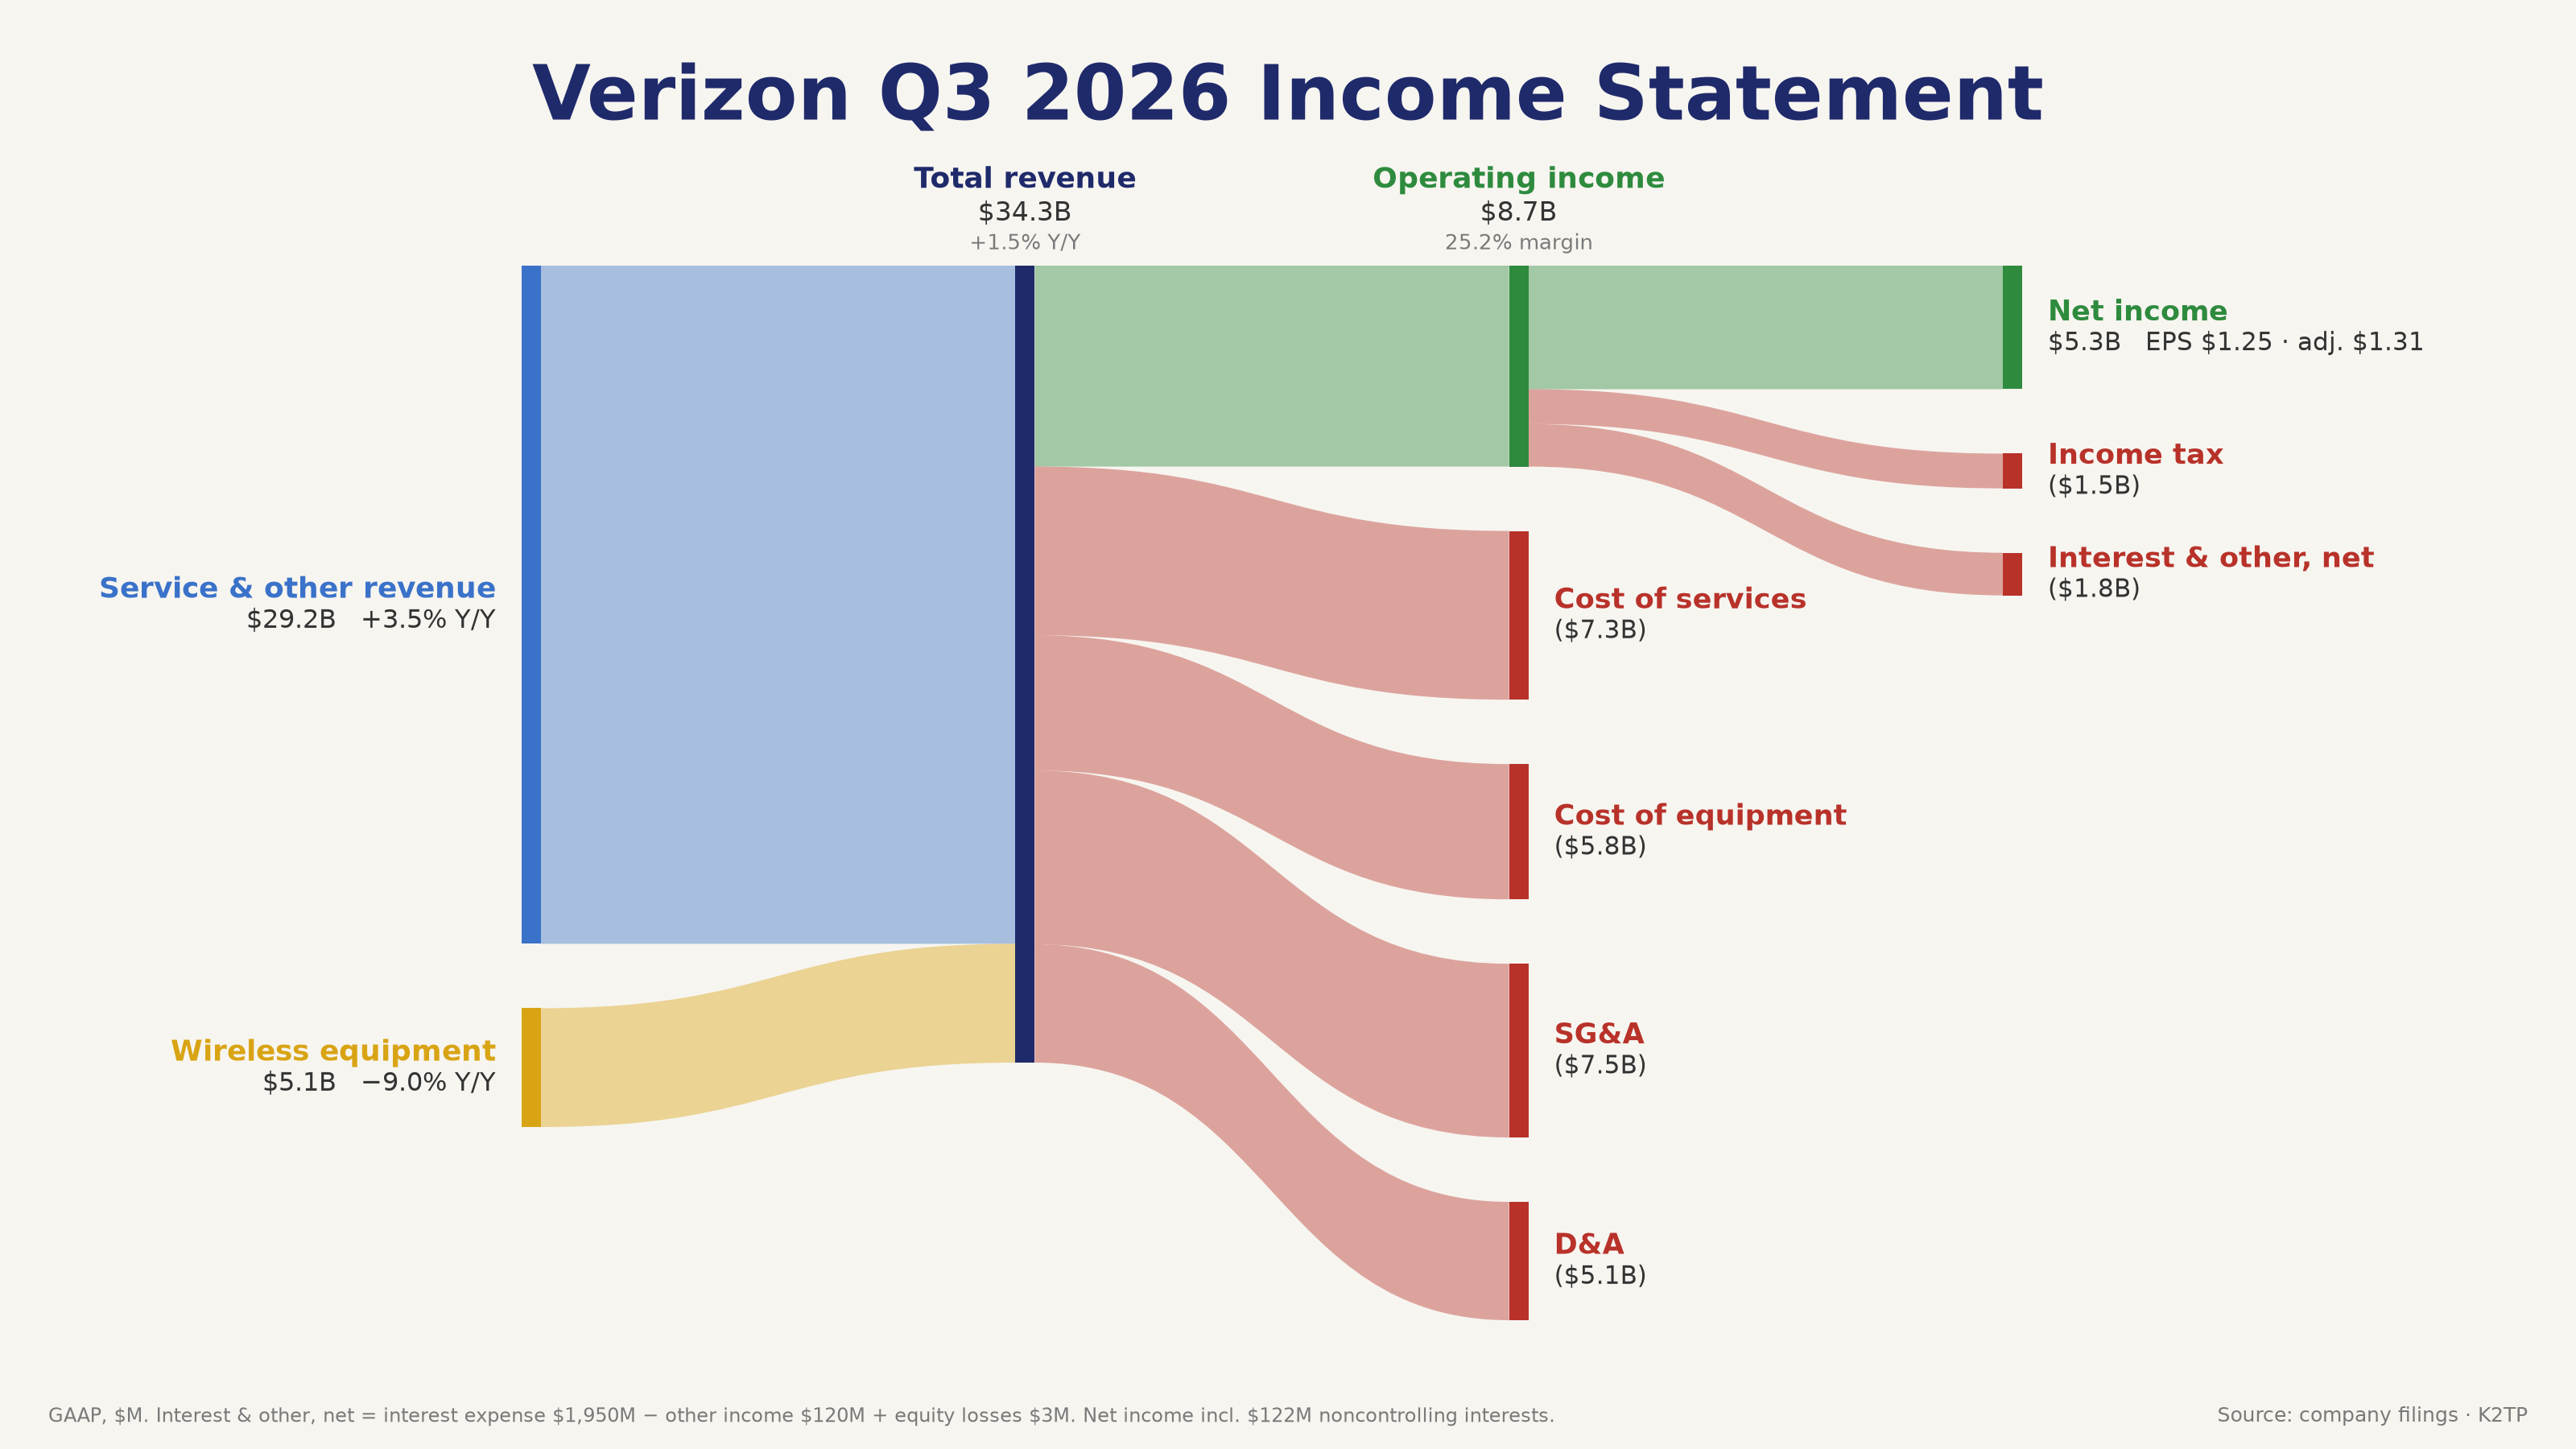
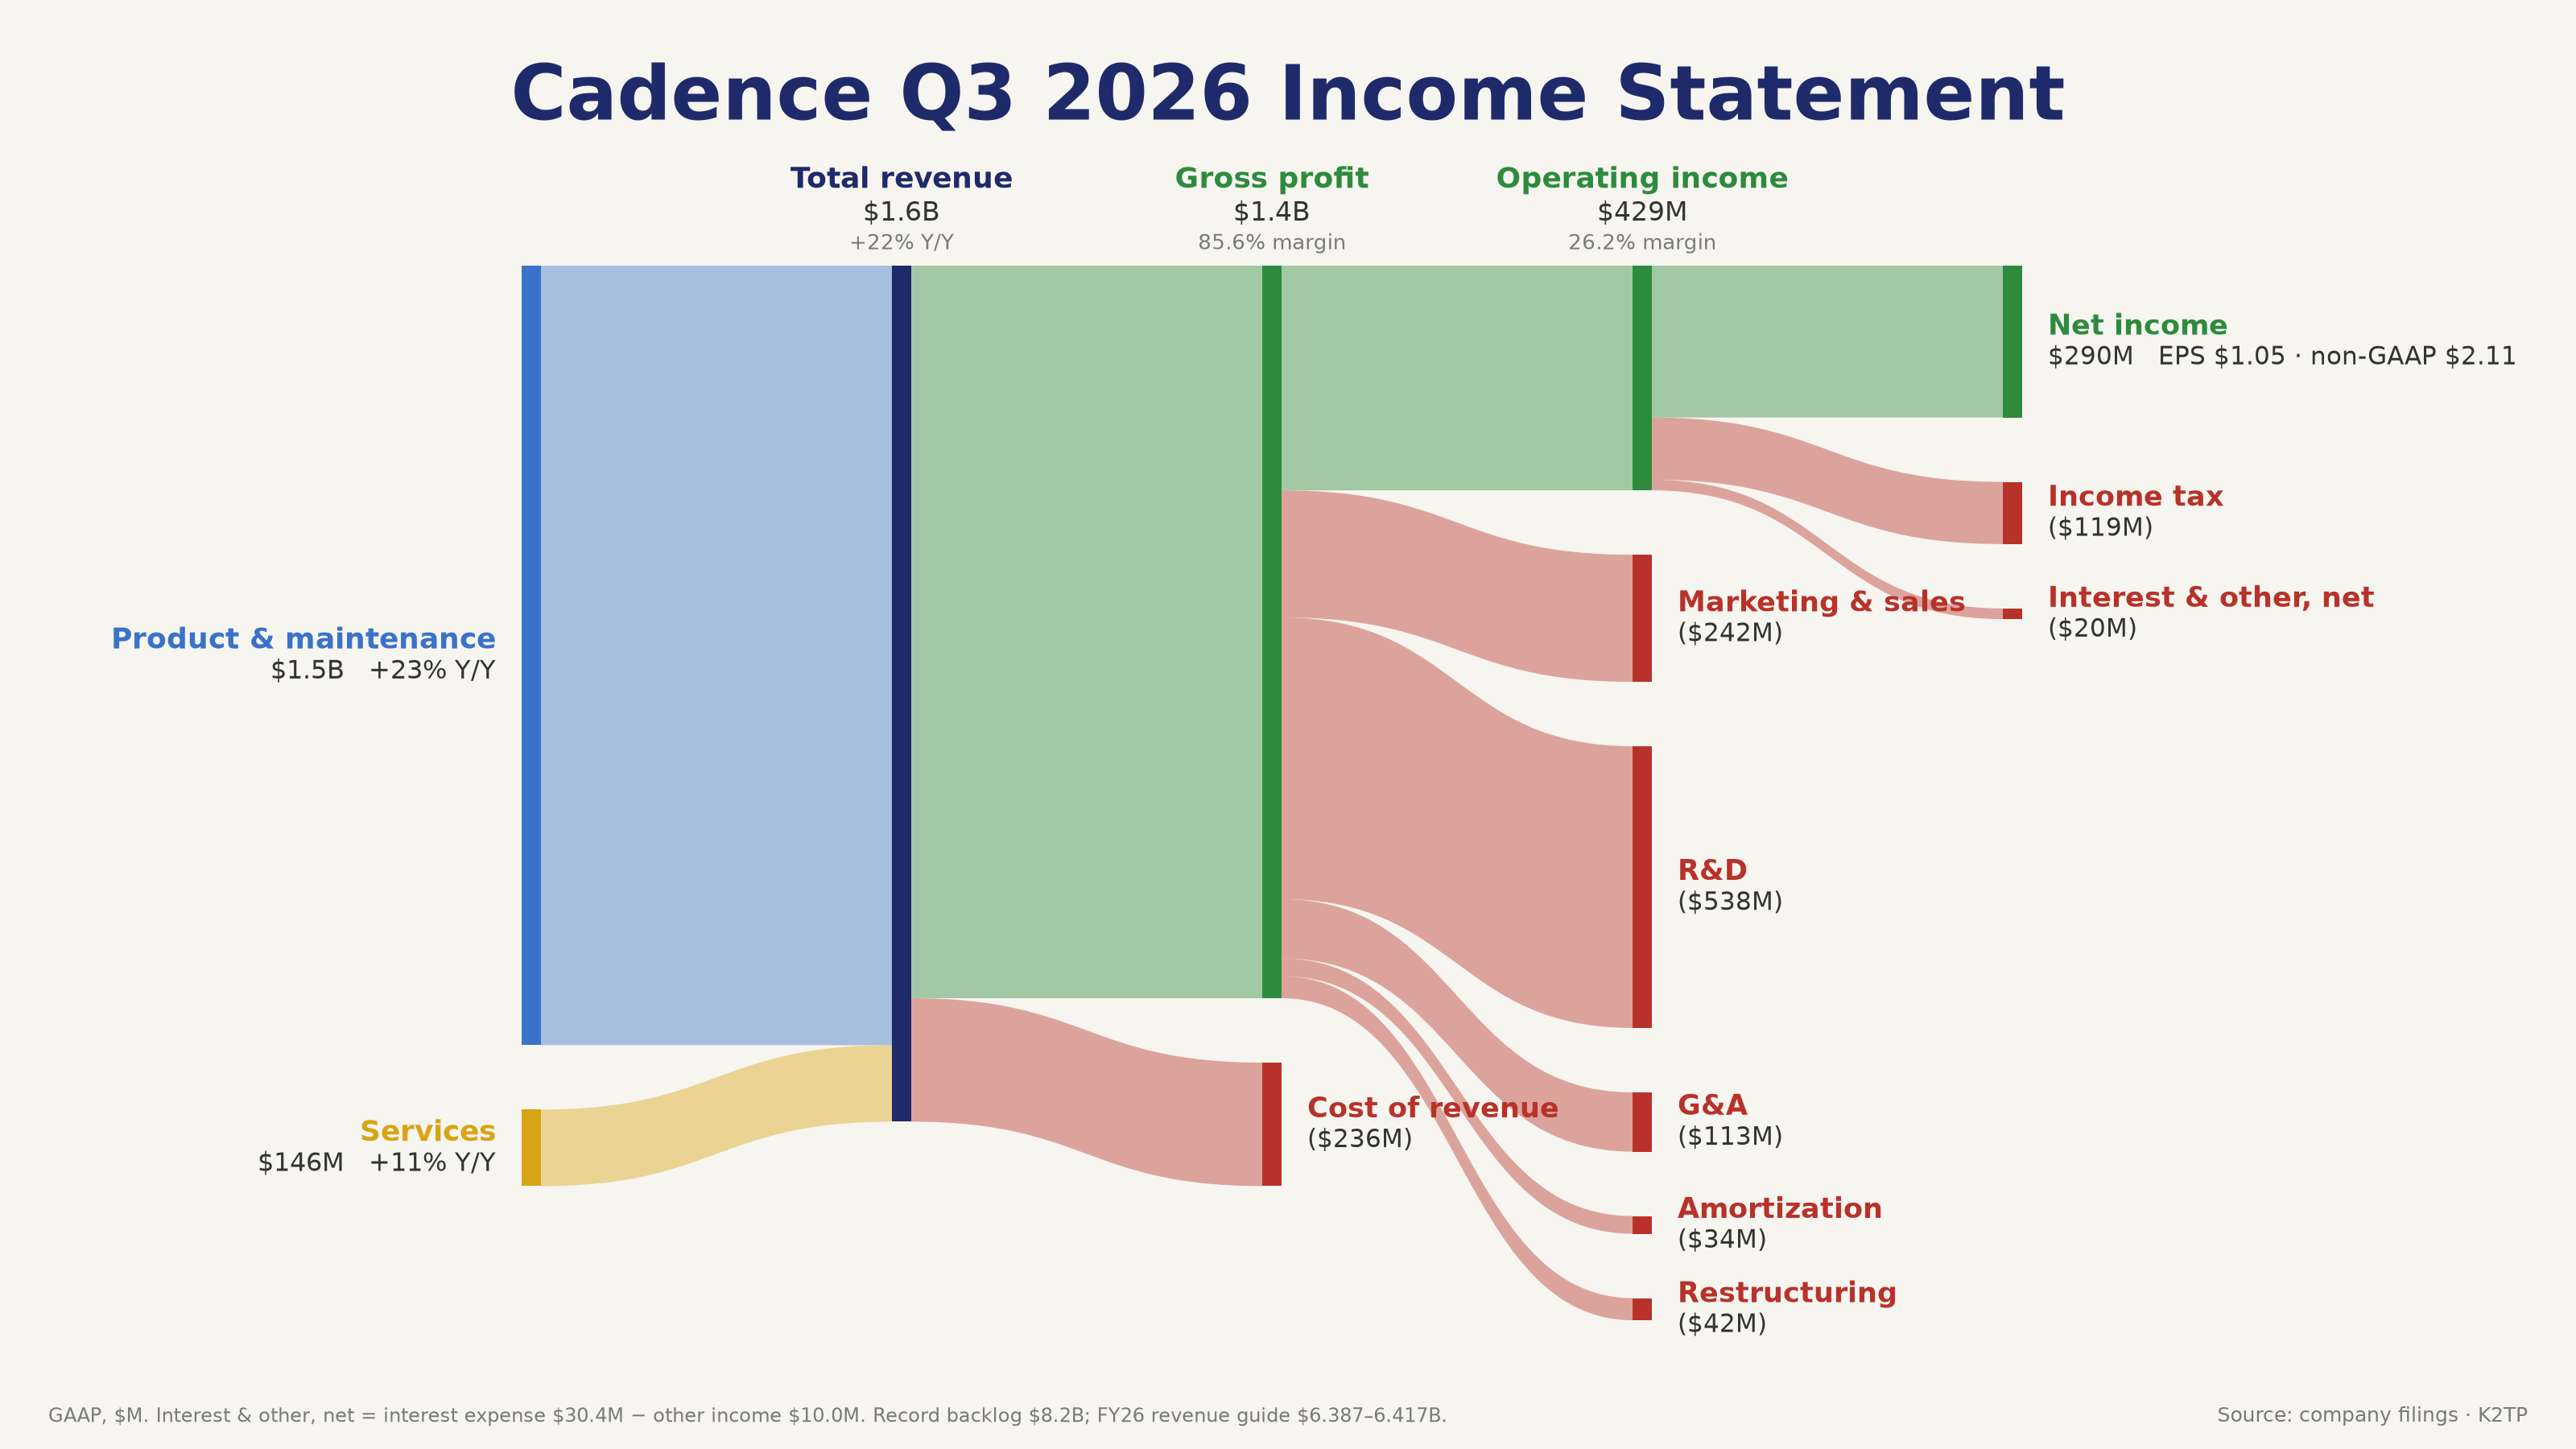
- Verizon (8-K): revenue $34.31B (+1.5% YoY) versus about $34.76B expected (Pre-Market brief); service and other revenue +3.5%, wireless equipment −9.0%; GAAP EPS $1.25, adjusted EPS $1.31 (+8.3%) versus $1.28 expected 🔴
- VZ added 406,000 postpaid phones, raised 2026 guidance for the third straight quarter (adjusted EPS $5.04–5.06) and signed a $2B+ AI infrastructure deal with AWS; the stock still fell 3.49%
- Cadence (8-K): revenue $1.633B (+22% YoY), GAAP EPS $1.05, non-GAAP EPS $2.11 versus $2.05 expected (CNBC); record backlog $8.2B; 2026 revenue guide $6.387–6.417B (about 21% growth); $2.5B more buyback; CDNS about +2.4% after hours 🟢
- Celestica: adjusted EPS $3.30 versus $2.99, revenue $5.83B (+83% YoY) versus $5.44B; first 2027 outlook of $40.0B revenue and $21.50 EPS; CLS about +10% to +16% after hours after a −5.14% regular session (Investing.com) 🟢
- Amkor revenue $1.99B (AMKR about +5% after hours); Whirlpool adjusted loss $0.21 versus a $0.80 profit expected and a 2026 revenue guide cut to $14.5B (WHR about −9%); JetBlue about +7%; Rambus about −2% (CNBC)
→ AI hardware keeps beating (CLS, CDNS, AMKR), while the consumer side (WHR) is weak. Tonight's reports favor chips at Tuesday's open.
SINGLE-STOCK SHOCKS: BRAZIL, FICO AND A GAS MERGER
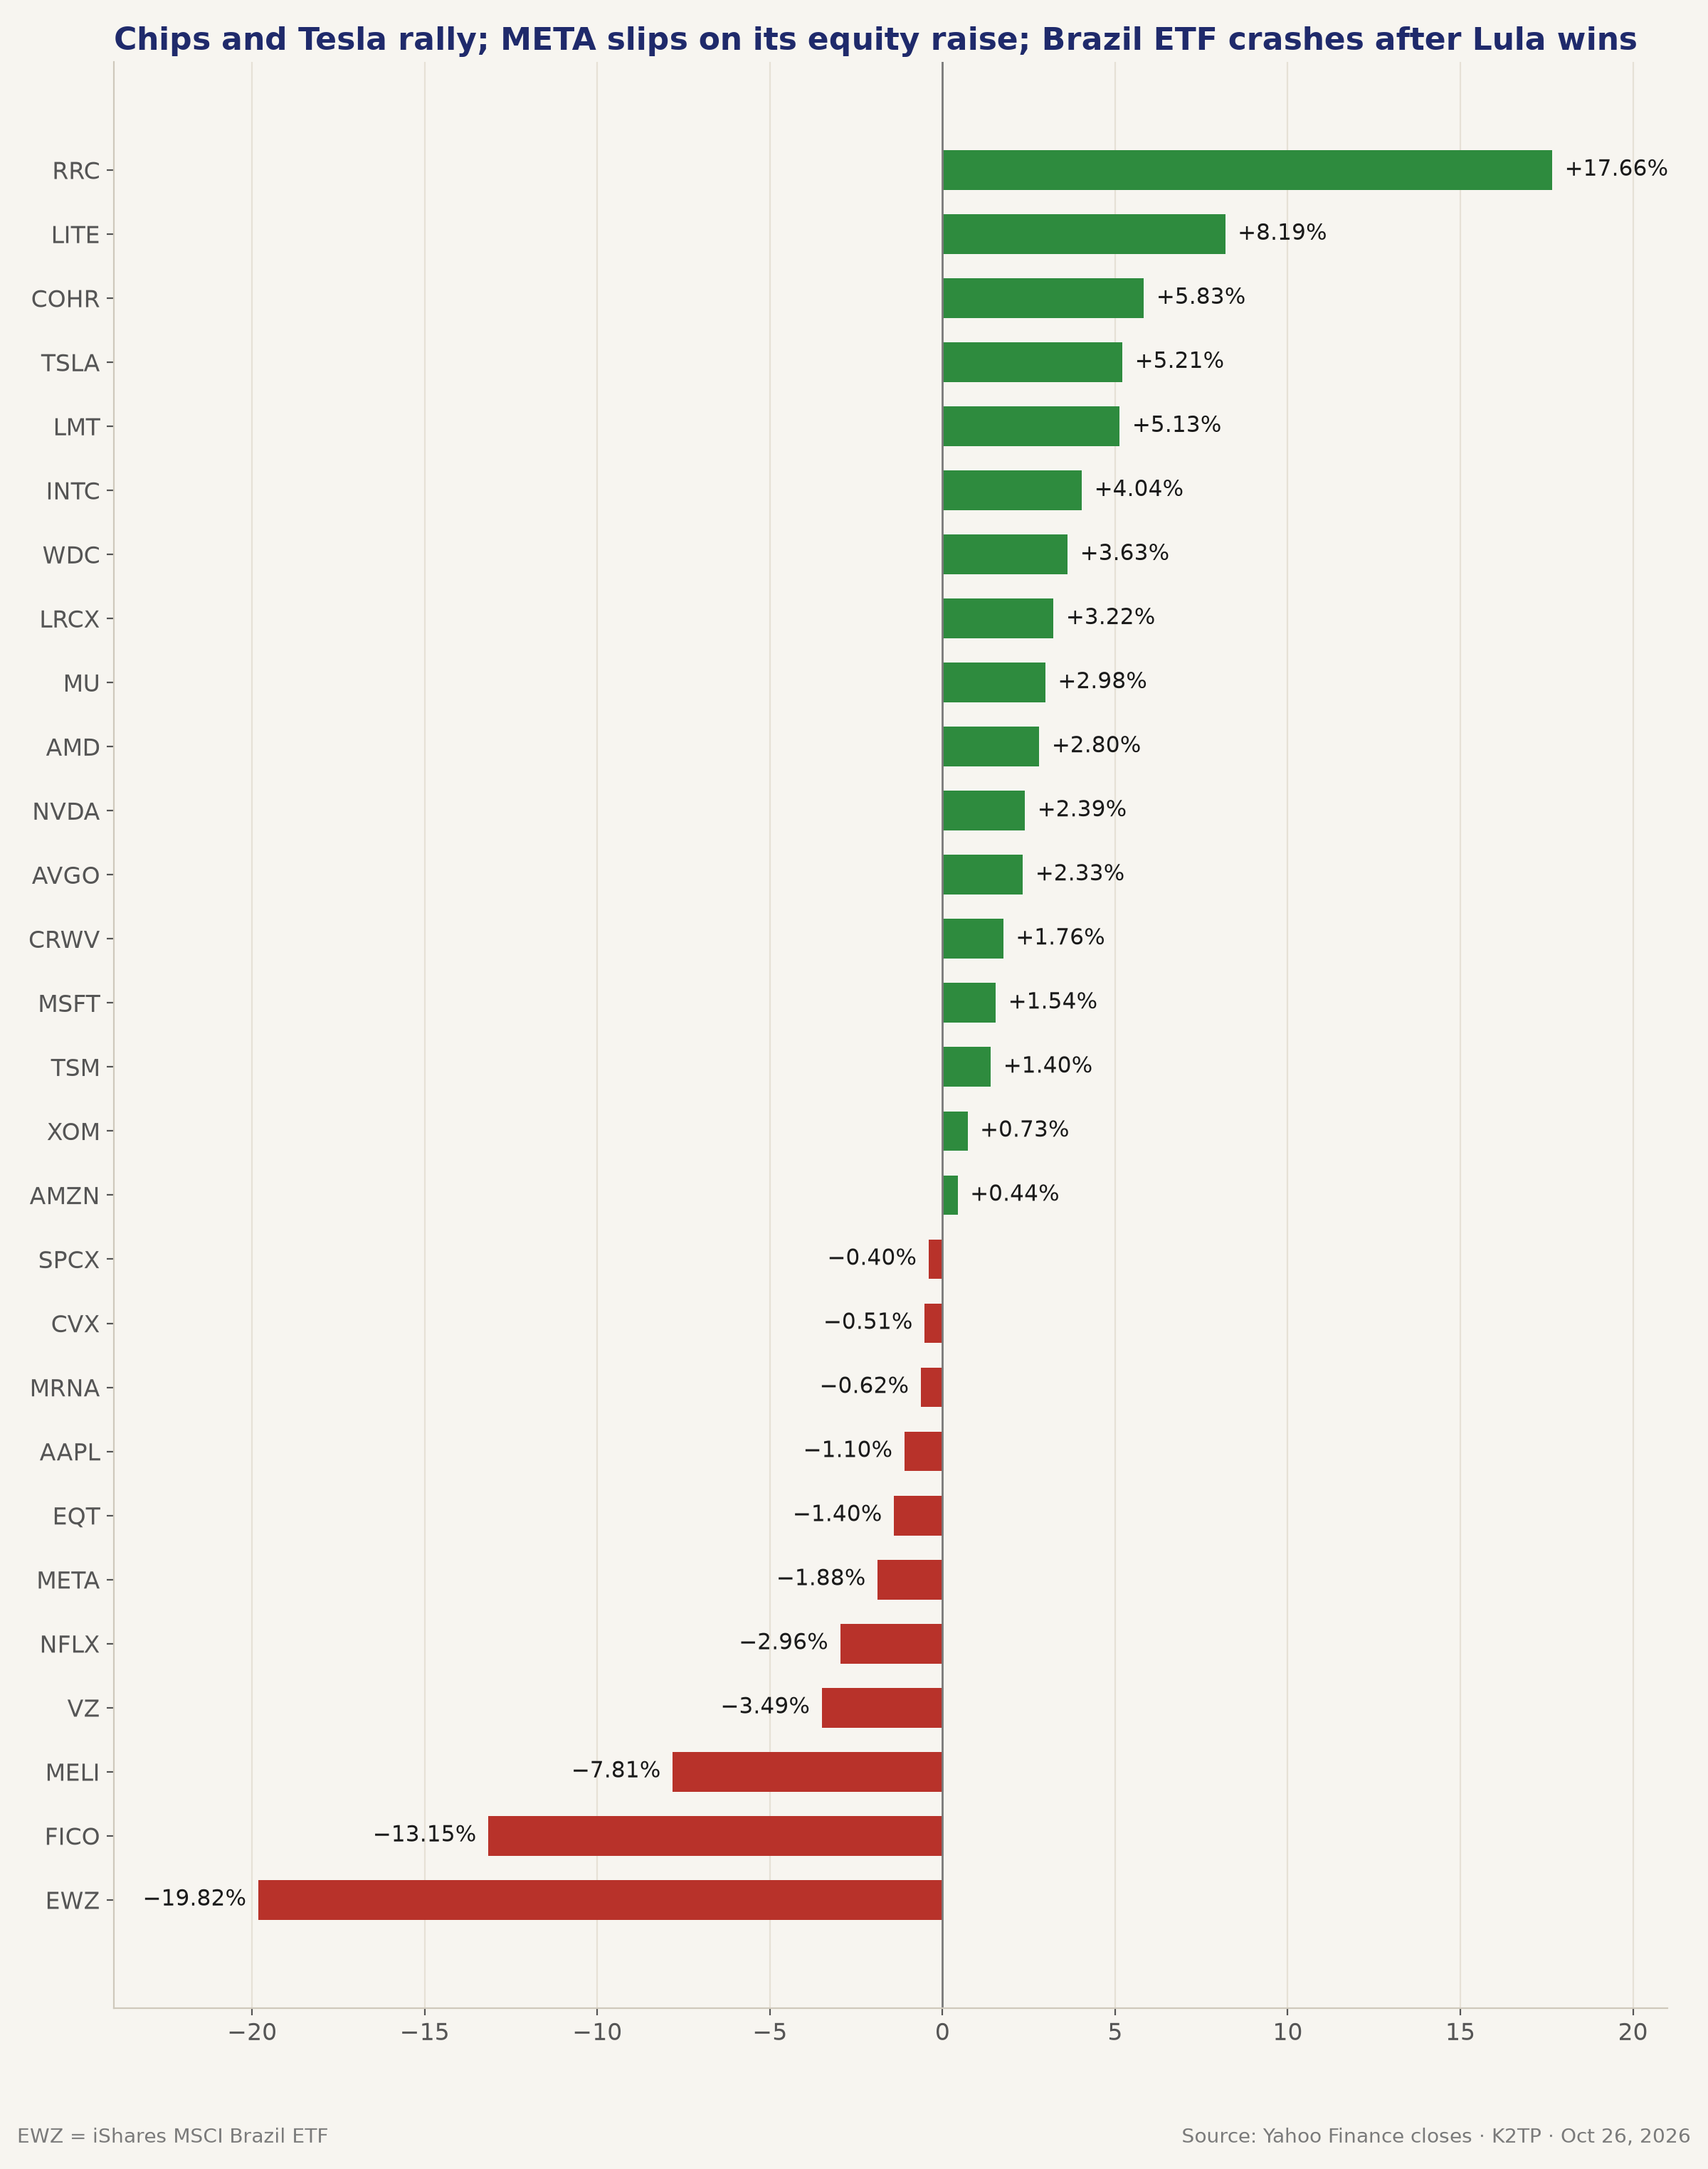
- Lula's surprise re-election hit Brazilian assets: EWZ −19.82% (it was −26.37% pre-market), the Bovespa −13.88%, MercadoLibre −7.81% 🔴
- U.S. futures and the dollar showed little spillover from Brazil (Pre-Market brief)
- FICO −13.15% to 708.07 after a Wells Fargo downgrade; it was down as much as 17.7% intraday (low 671.19)
- EQT agreed to buy Range Resources in an all-stock deal: RRC +17.66%, EQT −1.40%
- Moderna fell 8.55% pre-market on Phase 3 cancer vaccine data but closed only −0.62%
→ These are big single-stock and single-country moves, but they stayed contained. Brazil is the one to watch for spillover into EM and financials with Brazil exposure.
OIL EASES BUT STAYS ABOVE $100
- December WTI settled $101.76 (−$1.51, −1.46%) after a $100.33 low and a $103.13 high; Brent settled $110.74 (Evening Recap). Yahoo's front-month Brent rolled, so its daily percentage is not comparable to Friday's $116.72 🟡
- Diplomacy: a Qatari official visited Tehran as part of mediation; Iran, Turkey, Pakistan and Saudi Arabia agreed to continue talks; Putin meets Iran's Pezeshkian and the Emir of Qatar in Moscow on Tuesday (Midday brief)
- Risk stayed live: Houthis attacked Saudi Arabia's East-West crude pumping stations and Riyadh airport (Reuters); Iran warned Israel it will respond in kind; UKMTO received reports of a vessel on fire near Iraq (Pre-Close brief)
- Tonight the Saudi-led coalition said it destroyed three Houthi ballistic missiles; Iran's state TV said Tehran is open to a shorter U.S. proposal timeline (FinancialJuice, unconfirmed)
- The U.S. SPR fell to 282.6 million barrels, the lowest since 1982 (Midday brief); Fitch warned that broader U.S. price pressures raise the risk that inflation persists
- XLE +0.45%, XOM +0.73%, CVX −0.51%; gold settled near $4,038.40 (Evening Recap)
→ Oil above $100 is the bull condition still missing. Fitch's warning and the record-low SPR keep inflation in focus two days before the FOMC.
2-YEAR AUCTION TAILS; THE CURVE FLATTENS INTO THE FOMC
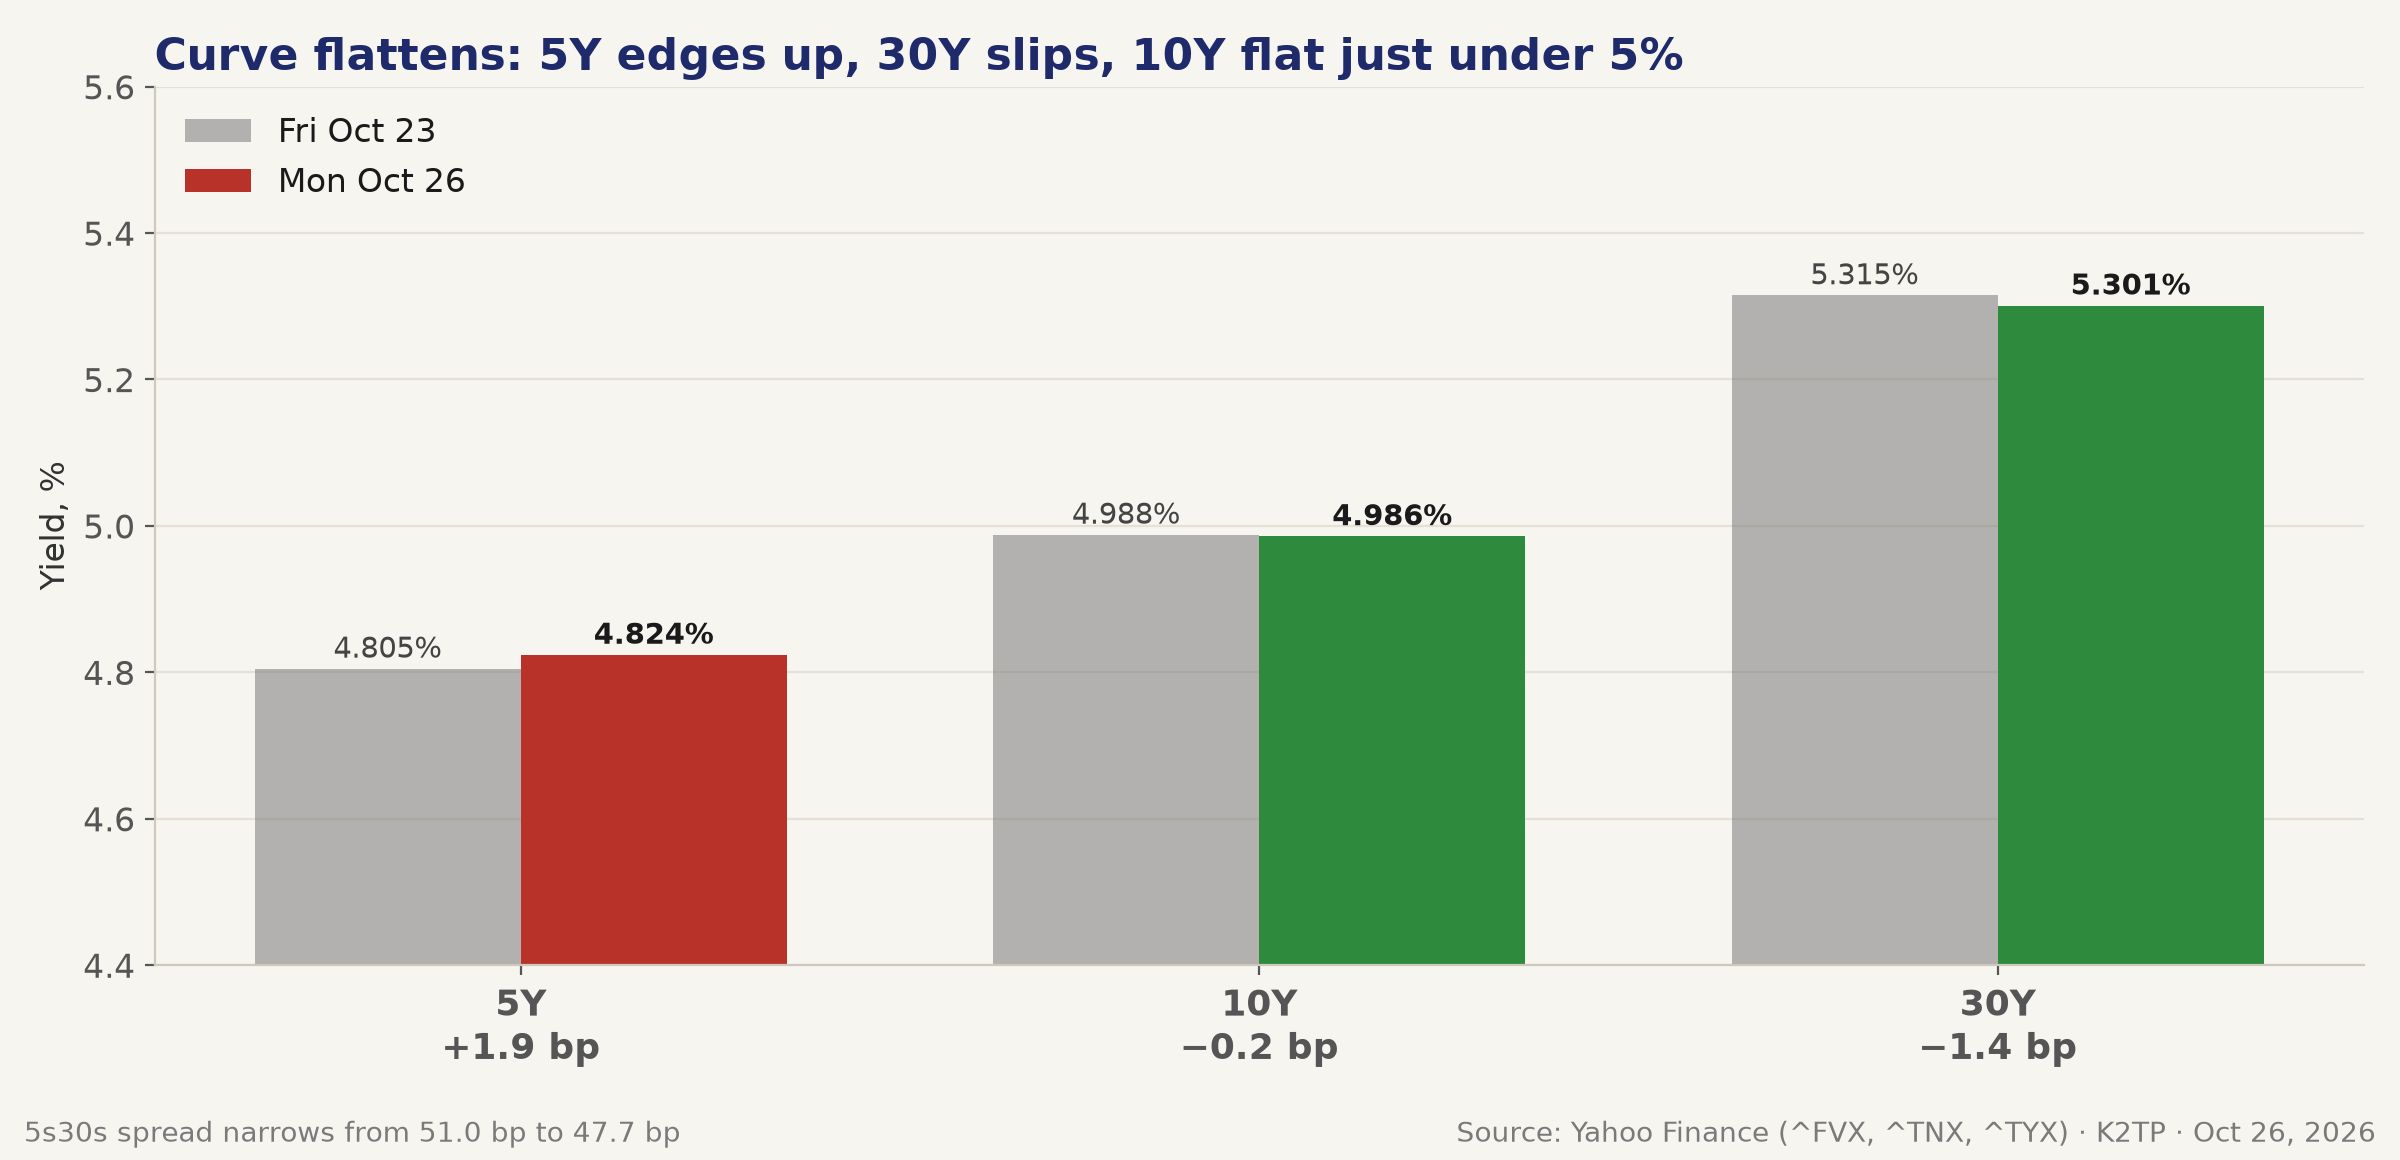
- $69B 2-year notes stopped at 4.708% versus 4.705% when-issued (0.3 bp tail); bid-to-cover 2.59 versus 2.63; indirects 45.68%, directs 41.32%, dealers 13% (Pre-Close brief) 🟡
- Closing yields: 10Y 4.986% (−0.2 bp, range 4.961–5.003%), 5Y 4.824% (+1.9 bp), 30Y 5.301% (−1.4 bp); 5s30s narrowed from 51.0 bp to 47.7 bp
- Bills: 3-month 4.050% (bid-to-cover 3.07), 6-month 4.210% (2.63); Treasury buyback of up to $6B on Tuesday
- Data: Chicago Fed National Activity Index 0.07 versus −0.095 expected; Dallas Fed manufacturing 13.4 versus 8.8 expected and 9.8 prior; Germany's Ifo 90.2 versus 89.9
- U.S. high-grade bond sales are set for a record $1.76 trillion this year (Pre-Close brief)
- FOMC starts Tuesday; decision Wednesday 10/28 at 11:00 AM PT, press conference 11:30 AM PT. The September meeting raised rates to 3.75%–4.00%; today's FedWatch odds are unavailable
→ A flat 10Y under 5% let stocks rally. But the belly cheapened after the 2Y tail, so the front end is not relaxed before Tuesday's 5-year auction and the Fed.
SPX CLEARS FRIDAY'S HIGH, THEN HOLDS A RANGE
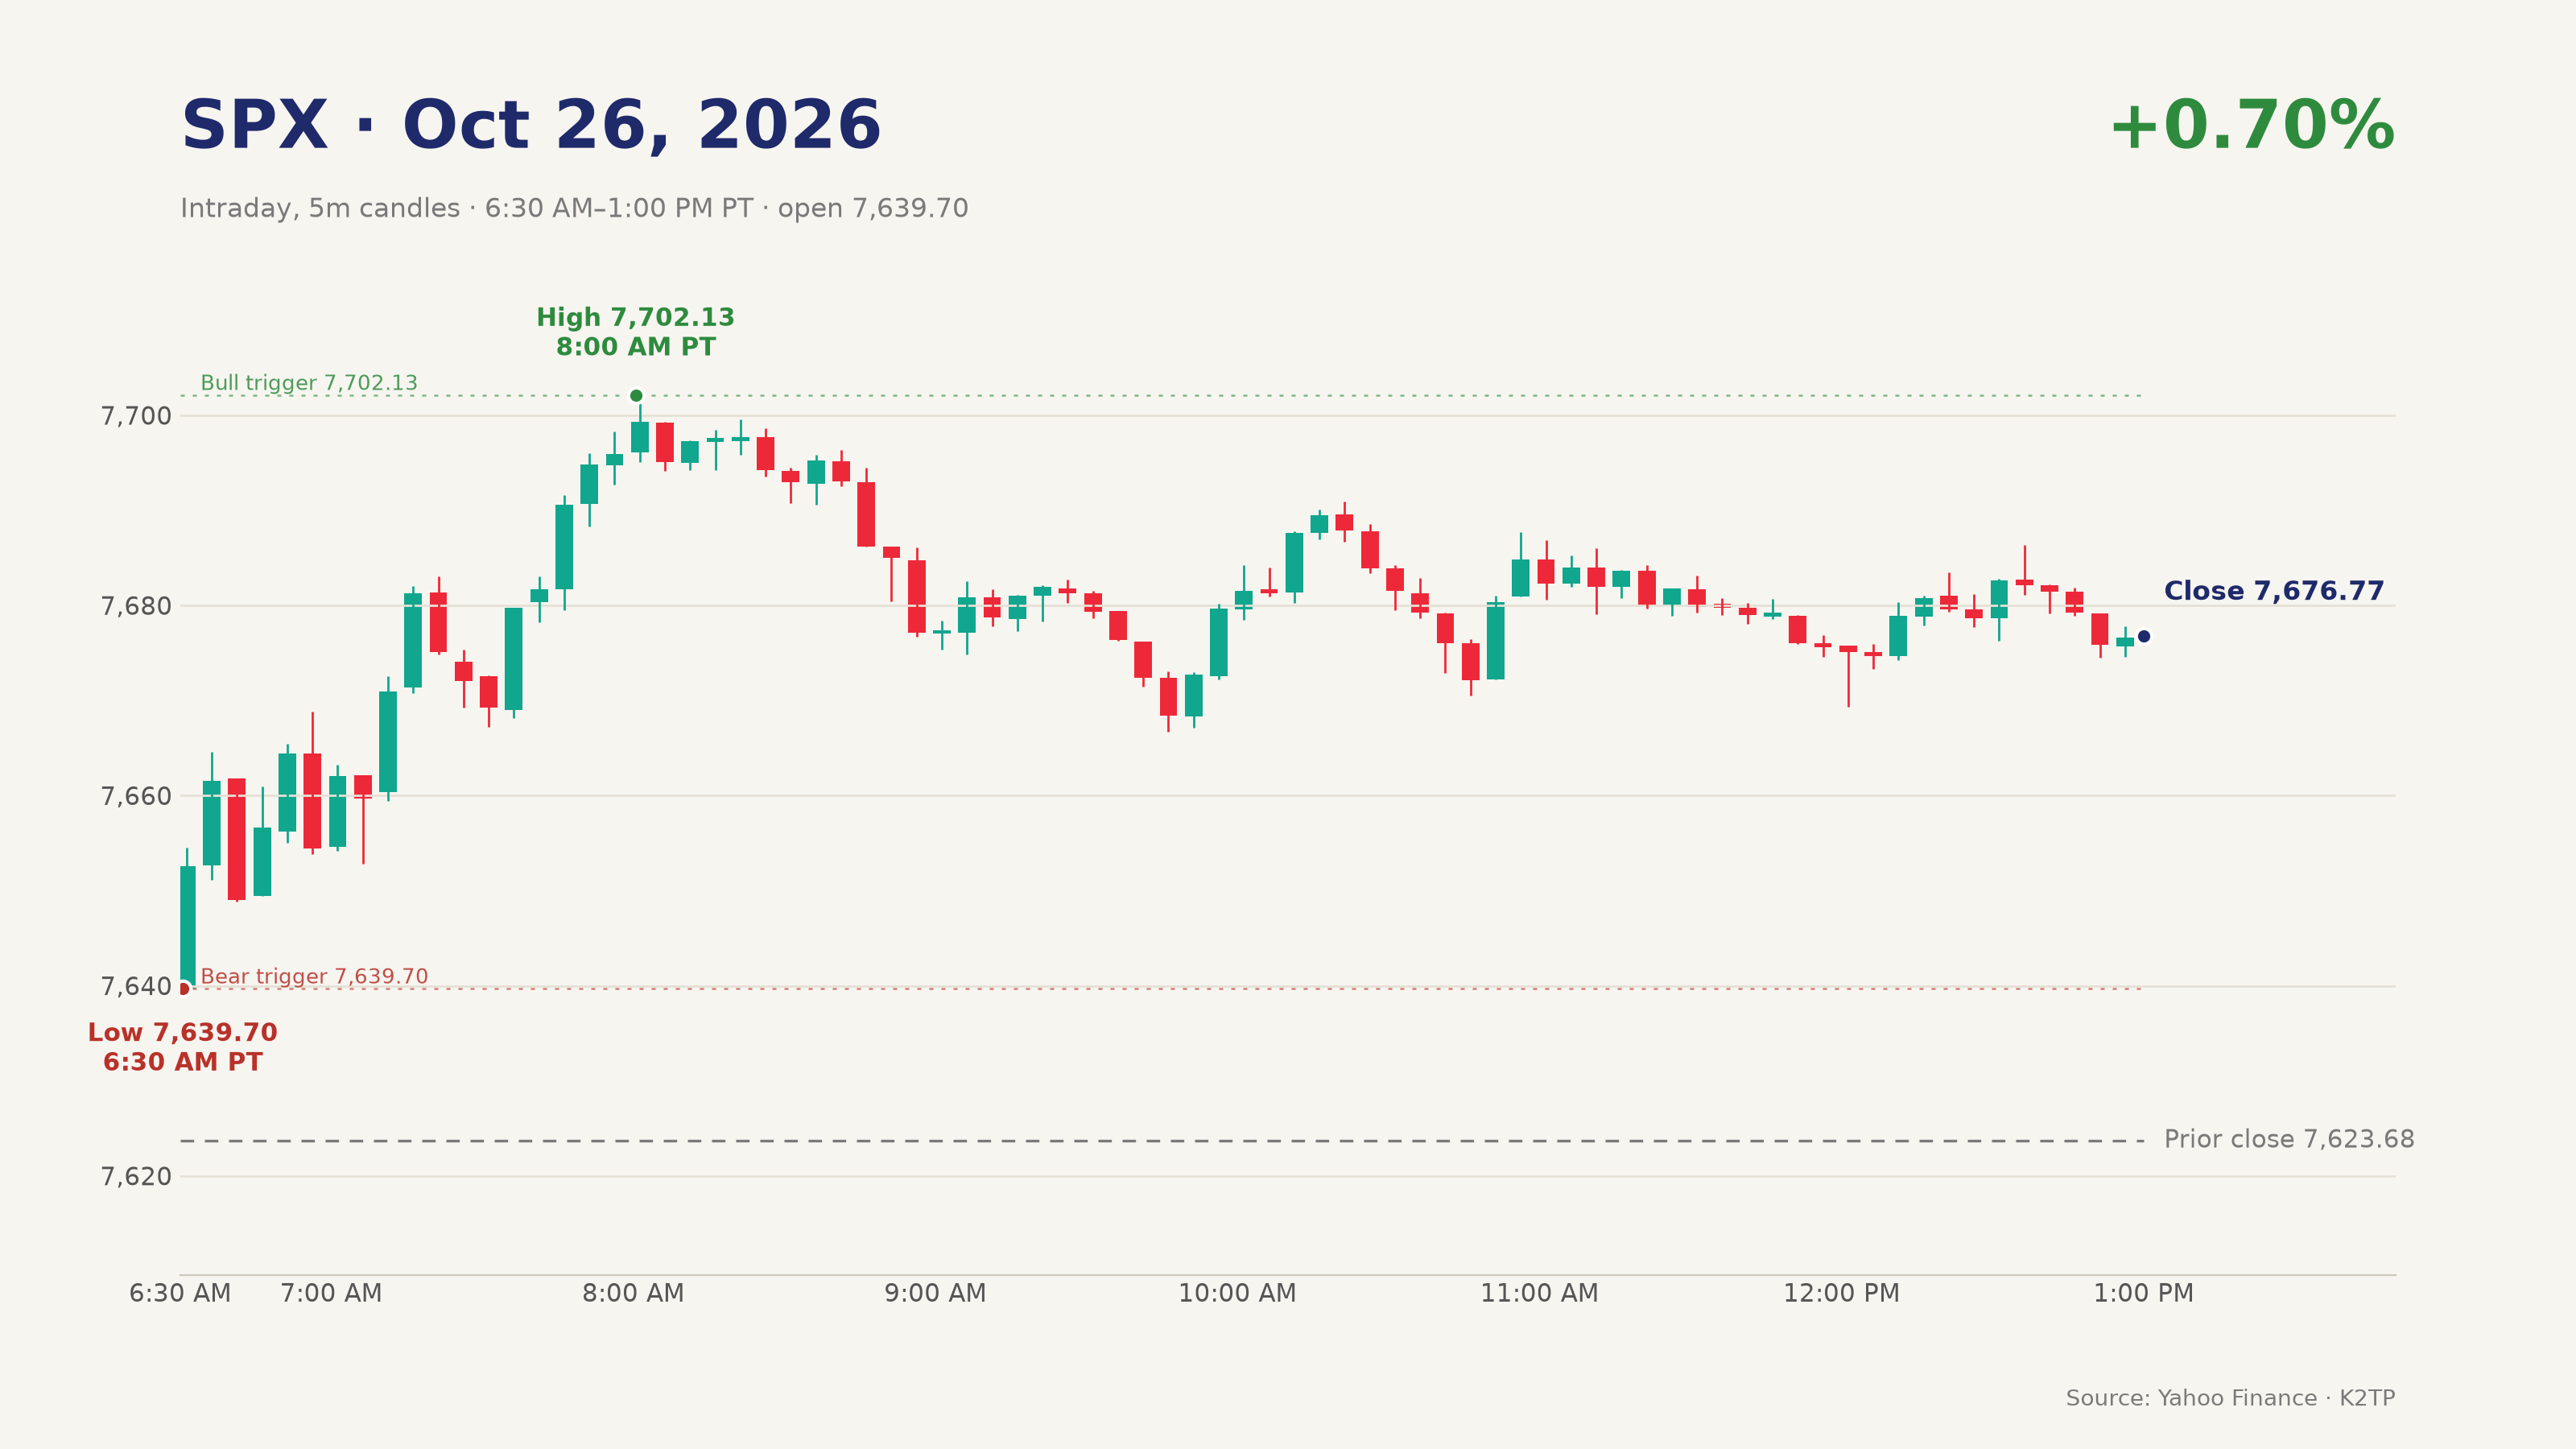
- Pre-market: ES +0.42%, NQ +0.69% as WTI dropped toward $101; implied SPX near 7,656, just below Friday's 7,660.15 high
- SPX opened at 7,639.70, which was also the session low, and closed above Friday's 7,660.15 high by 7:15 AM PT; VIX fell to its 17.79 low at 8:45 AM PT
- The pre-market Bull line (SPX above 7,660.15 with VIX under 18.87) was met, so the regime moved from RISK-OFF to TRANSITION by midday
- Session high 7,702.13 around 8:00 AM PT; SPX was 7,681.14 at midday and 7,679.24 at the pre-close
- Closed at 7,676.77, 16.62 points above Friday's high; the pre-close Bull line (above 7,702.13 with VIX under 17.79) and the 7,660 Bear line both held
→ The breakout held into the close, but after 8:30 AM PT SPX stayed between 7,666.74 and 7,696.35 and never retested 7,702. The 7,660–7,702 range is the battleground into the FOMC.
MARKET: CHIPS CARRY SPX ABOVE FRIDAY'S HIGH, META AND BRAZIL LAG
Indices (close):
- SPX 7,676.77 (+0.70%), range 7,639.70–7,702.13
- NDX 29,273.40 (+1.09%); Nasdaq Composite 26,169.38 (+0.82%)
- DJIA 52,361.58 (+0.28%)
- RUT 2,786.42 (+0.38%)
- RSP 217.29 (+0.35%)
- SOX 11,083.47 (+2.82%)
Intraday path: Pre-market ES +0.42%, NQ +0.69% on Gulf mediation and the AI funding headlines. SPX opened at its 7,639.70 low, broke Friday's 7,660.15 high by 7:15 AM PT, peaked at 7,702.13 around 8:00 AM PT, was 7,681.14 at midday and 7,679.24 before the close, and closed at 7,676.77.
Sector rotation:
- Gainers: XLK +1.69%, XLI +1.42%, XLY +1.03%, XLRE +0.54%, XLE +0.45%, XLF +0.21%, XLB +0.14%
- Flat or lower: XLV +0.00%, XLU −0.02%, XLP −0.34%, XLC −1.57%
- Megacaps: TSLA +5.21%, AMD +2.80%, NVDA +2.39%, AVGO +2.33%, MSFT +1.54%, TSM +1.40%, AMZN +0.44%; GOOGL −1.06%, AAPL −1.10%, META −1.88%
Internals:
- NYSE: advancers led decliners 1.36-to-1; Nasdaq 1.09-to-1 (Reuters)
- S&P 500: 7 new highs and 7 new lows; Nasdaq: 82 new highs and 349 new lows
- Volume 16.7B shares versus a 17.2B 20-day average
- RSP +0.35% and IWM +0.45% trailed SPX +0.70%: chips and megacaps did the lifting
Volatility:
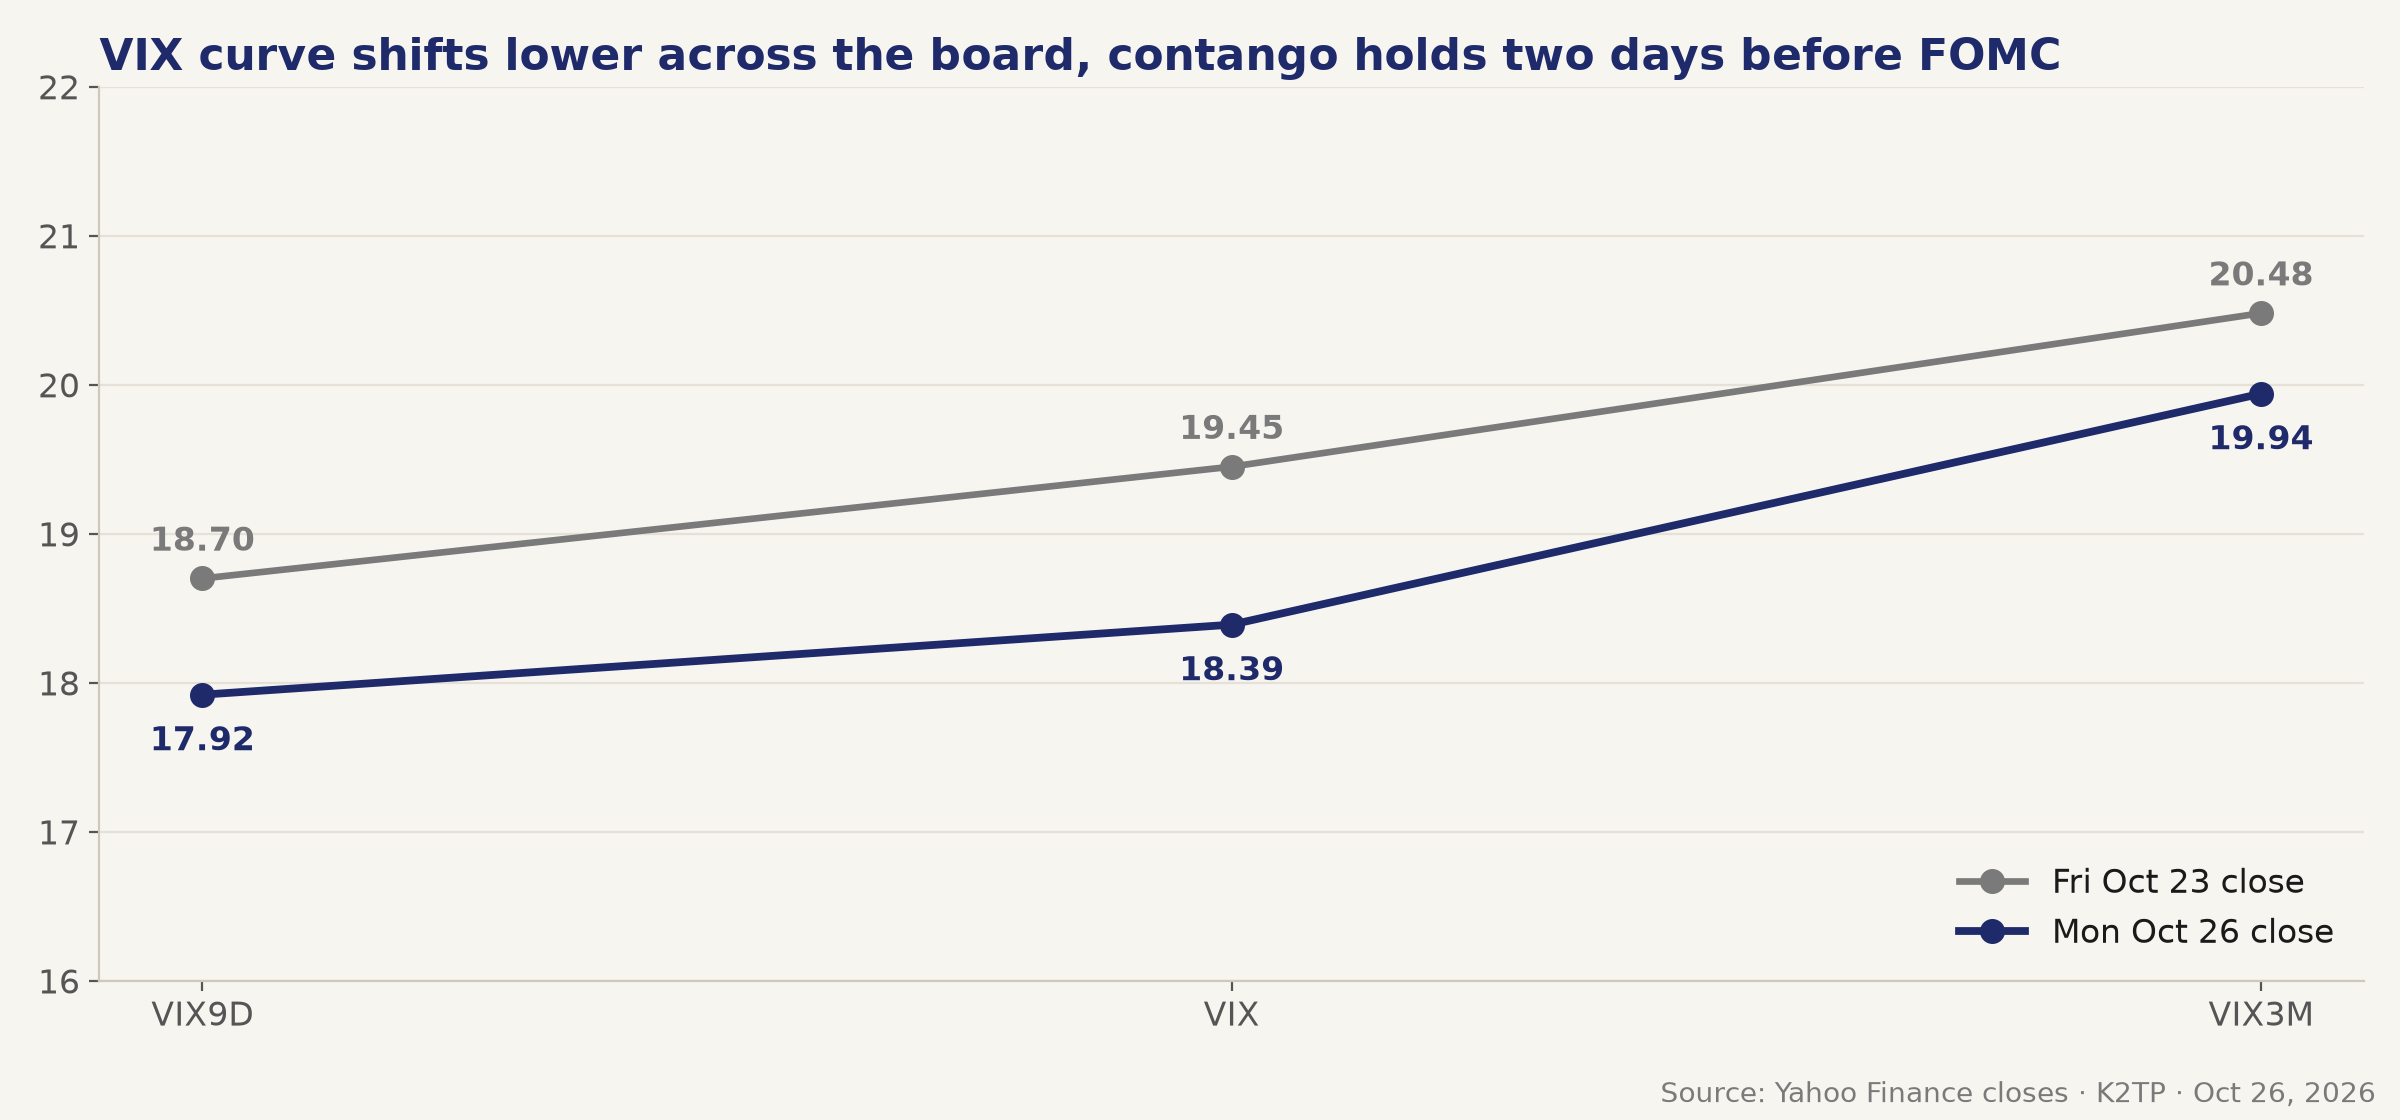
- VIX 18.39 (−5.45%), range 17.79–19.84
- VIX9D 17.92 (from 18.70), VIX3M 19.94 (from 20.48): the whole curve shifted lower and contango held
- VVIX 101.43 (−7.54%)
Cross-asset:
- WTI $101.76 (−1.46%), Brent $110.74 at settlement
- Gold about $4,038.40; DXY about 102.10 tonight; BTC about $80,098 tonight (Evening Recap)
- ES December settled 7,714.50 and is 7,727.25 (+0.17%) tonight; NQ settled 29,437.25
Global:
- Asia (Monday, Pre-Market brief): Hang Seng +0.51%, Shanghai +0.19%, Nikkei −0.80%, Kospi −1.46%
- Europe: Euro Stoxx 50 +0.79%, DAX +0.91%, CAC +0.83%, FTSE +0.72% (Yahoo)
- Asia tonight: Nikkei +2.21%, Kospi +3.69%; South Korea's Q3 GDP +1.0% q/q versus 0.7% expected (Evening Recap)
Key SPX levels:
- 7,702.13: Monday high, Bull line
- 7,681.14: midday level
- 7,676.77: close
- 7,660.15: Friday high, invalidation line
- 7,639.70: Monday open and low, Bear line
- 7,623.68: Friday close
- VIX: 17.79 and 19.84
Option seller corner:
- Bull case: SPX above 7,702.13 with VIX under 17.79 turns the regime RISK-ON. Even then, keep new far-OTM SPX put spreads small until Wednesday's 11:00 AM PT decision is out.
- Bear case: SPX under 7,639.70 with VIX above 19.84 turns the regime back to RISK-OFF. Then cut short put size and use only defined-risk spreads, especially in NDX and chips.
- VIX9D 17.92 is under VIX 18.39 and VIX3M 19.94, so near-dated premium is cheap even though it covers the FOMC and the MSFT/GOOGL reports. Selling those expirations pays less for the same event risk.
- Avoid short premium through earnings in single names (MSFT, GOOGL Wednesday; V, STX, NXPI Tuesday after the close). Brazil-exposed names and oil-sensitive sectors carry gap risk from headlines.
BOTTOM LINE
- Anthropic's IPO filing and new AI funding deals lifted chips (SOX +2.82%), and SPX closed 16.62 points above Friday's 7,660.15 high.
- The rally was narrow: Meta's $95B equity plan sank communication services, Brazil crashed after Lula's re-election, Nasdaq new lows beat new highs and volume was below average.
- Regime 🟡 TRANSITION. The breakout held, but WTI above $100, a tailed 2-year auction and the FOMC keep it short of RISK-ON; SPX needs 7,702.13 with VIX under 17.79 to upgrade.
What to watch Tuesday (PT):
- Before the open: Coca-Cola, Boeing, UPS, S&P Global, Corning, HCA, Freeport-McMoRan, PayPal, Novartis
- 5:30 AM: durable goods orders (Sep); 7:00 AM: Conference Board consumer confidence (forecast 81) and new home sales (forecast 650K)
- 10:00 AM: $70B 5-year note auction; FOMC day one; Treasury buyback of up to $6B
- After the close: Visa, Seagate, NXP, Robinhood, Teradyne, Waste Management, EQT
- Wednesday: FOMC decision 11:00 AM; Microsoft and Alphabet after the close
Bull expectation: ES holds tonight's gain, Celestica and Broadcom extend the chip bid, WTI slips under $100, the 5-year auction goes smoothly, SPX takes out 7,702.13 and VIX breaks under 17.79. Bear expectation: a Gulf or Houthi headline lifts Brent back above $111, earnings disappoint and the chip bid fades, SPX loses 7,639.70 and VIX rises above 19.84.
Sources: 4 K2TP briefs for 10/26/2026 (Pre-Market, Midday, Pre-Close, Evening Recap). Official closing and intraday prices from Yahoo Finance; oil settlements, breadth, news and data from Reuters, CNBC, Investing.com, Newsquawk and FinancialJuice; Sankeys from Verizon's Q3 2026 release (8-K Ex. 99) and Cadence's Q3 2026 release (8-K Ex. 99.01), SEC EDGAR. Analysis: K2TP Framework.