Market 10/23: Oil jumps on Iran risk and SpaceX hits telecoms; the Dow drops 1.2% as SPX logs a second weekly loss
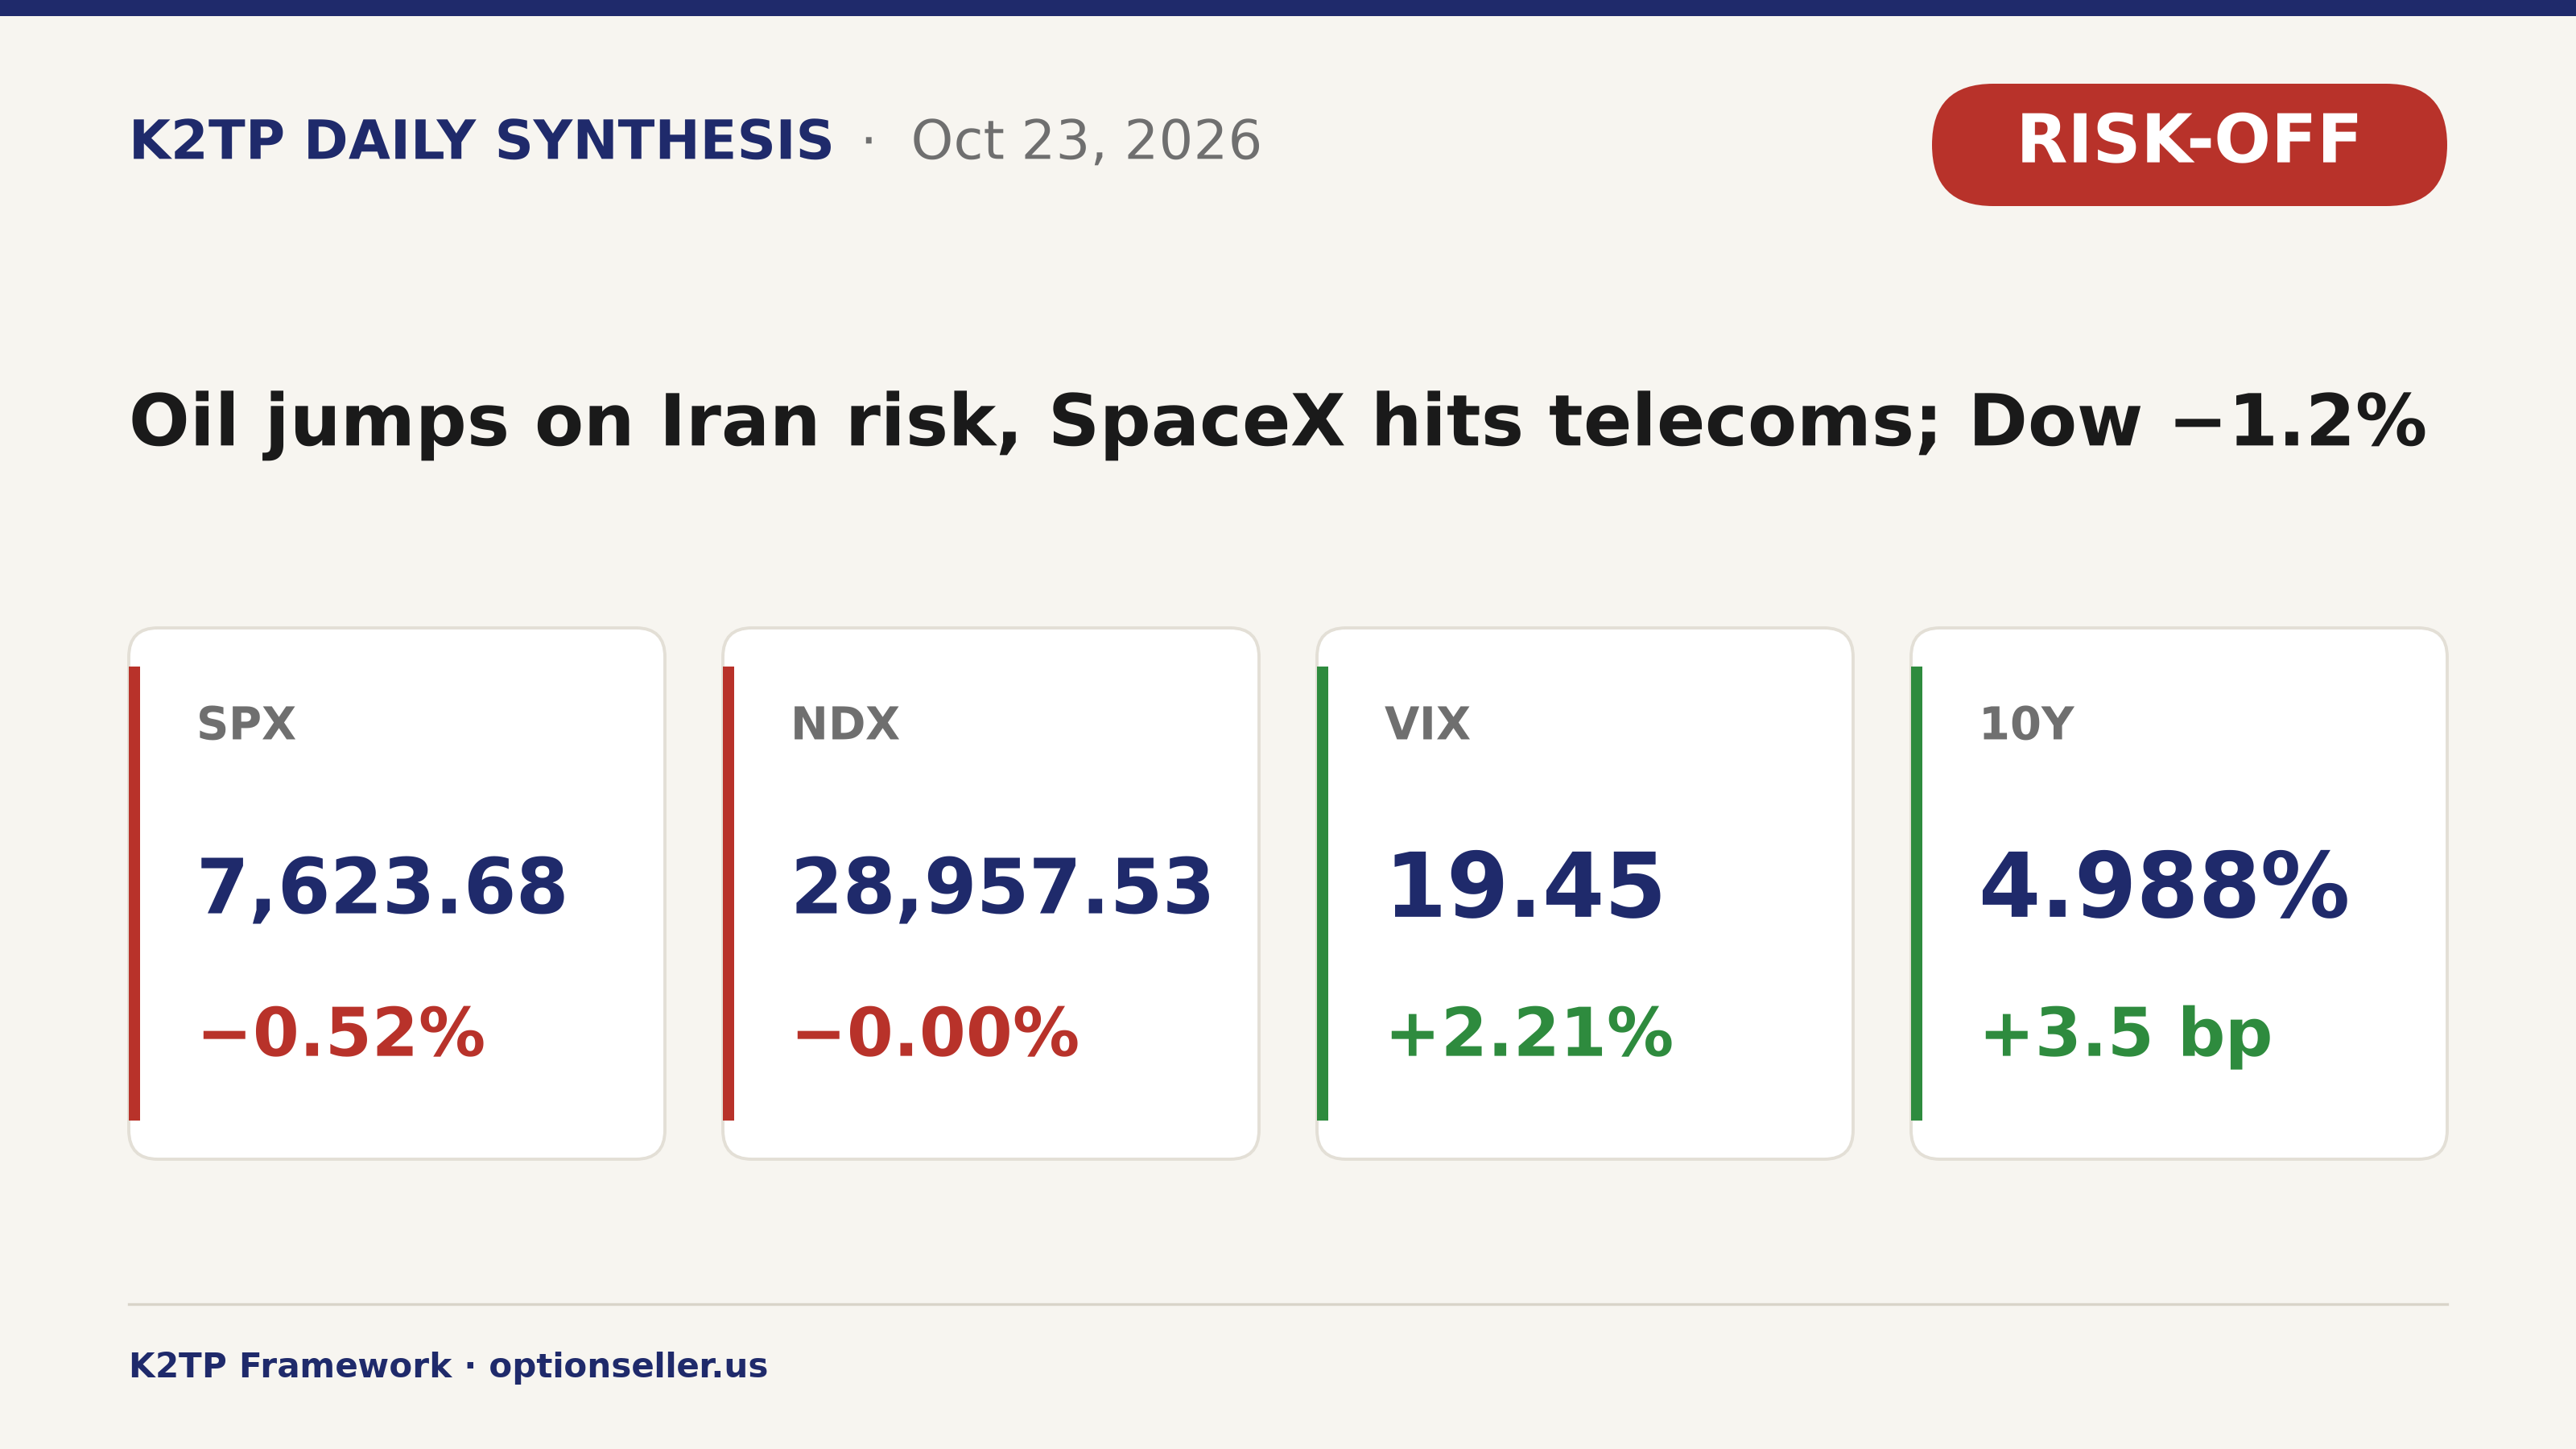
SPX −0.52%, NDX flat (−0.00%), DJIA −1.23%, VIX +2.21%. Brent settles $116.72, its highest since April 29; XLE +2.60% while AT&T and T-Mobile sink nearly 8%; chips steady after Thursday's rout.
KEY HEADLINES
- SPX −0.52% to 7,623.68 (−39.75 points); DJIA −1.23% (−652.82 points) to 52,215.16; Nasdaq Composite −0.21%; NDX −0.00%; RUT −0.29%
- Brent settled $116.72 (+3.14%), its highest since April 29, and WTI $103.27 (+3.8%) on U.S.-Iran escalation risk and Houthi attacks in Saudi Arabia (Reuters)
- Energy led: XLE +2.60% (the S&P 500 energy sector hit a record high, Reuters); SLB +7.08% after a Q3 beat, XOM +2.79%, CVX +2.88%
- SpaceX is in talks for access to about 80,000 U.S. cell sites for a fourth wireless carrier (Bloomberg): AT&T −7.96%, T-Mobile −7.71%, Verizon −1.19%; tower owners Crown Castle +9.06%, American Tower +4.08%
- American Express −3.68% on a ~5% workforce cut, the biggest drag on the Dow; Thursday's defensive rotation unwound (XLP −1.92%, XLV −1.11%, XLU −0.72%)
- Chips steadied: SOX +0.44%, MU +2.46%, AMD +1.74%, INTC +1.72%; NVDA −0.59%, META −0.96%
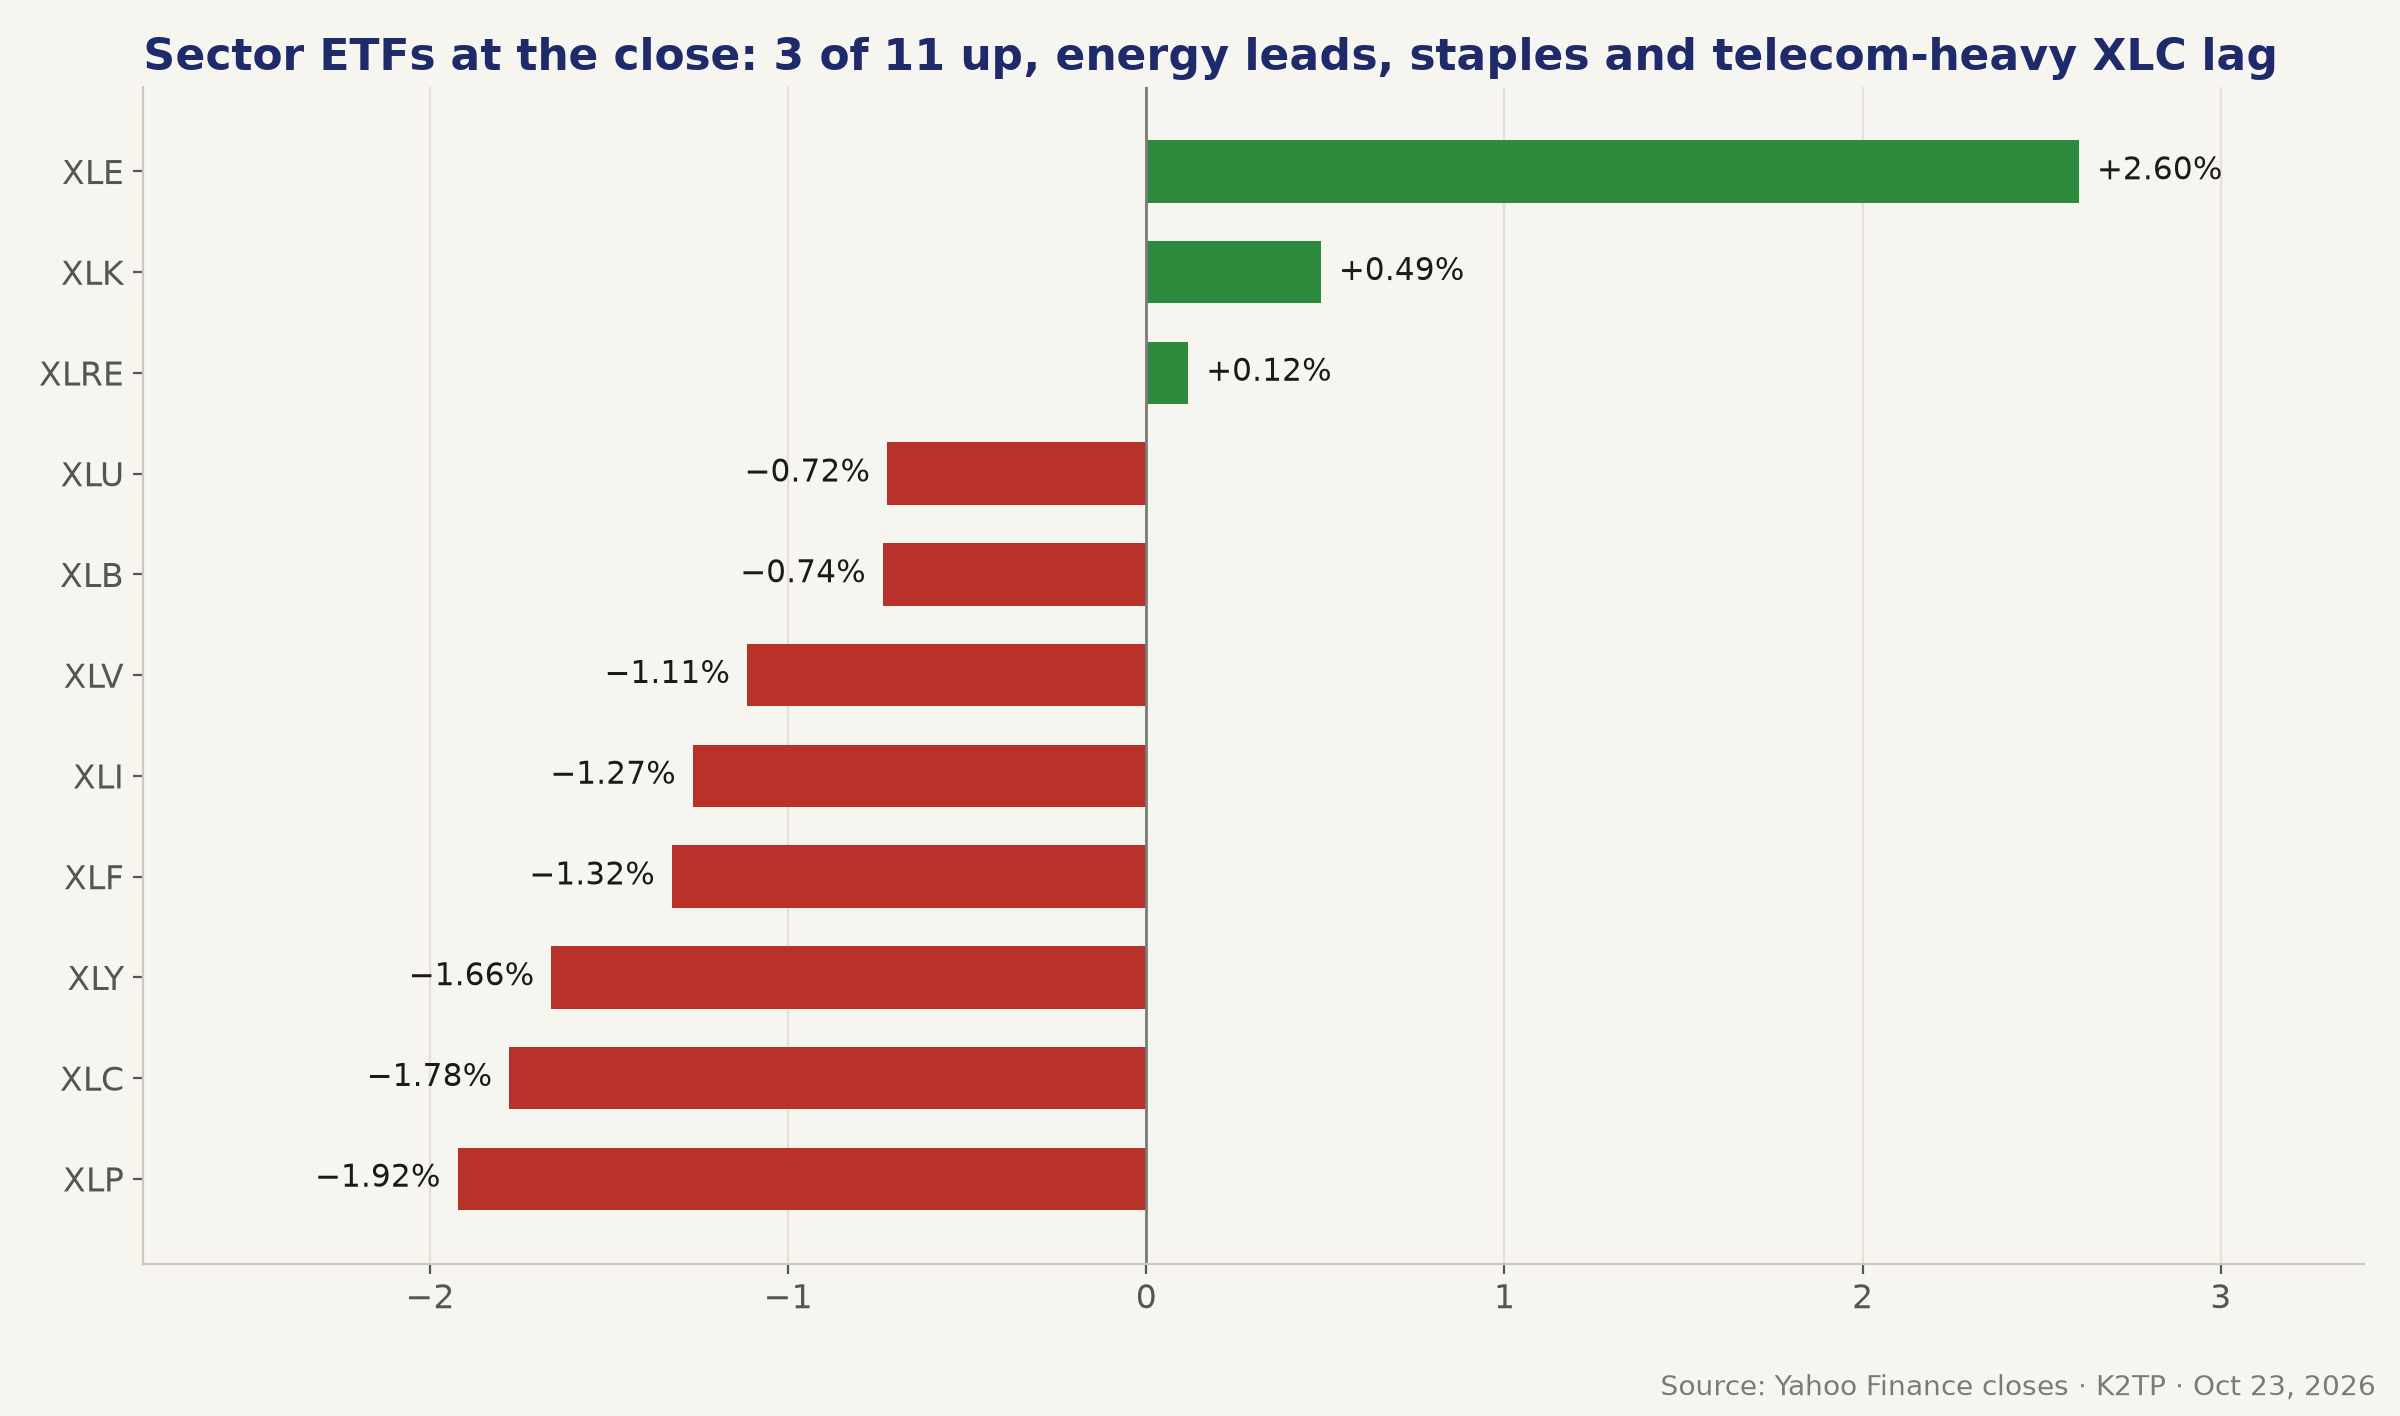
- Breadth weak: NYSE decliners beat advancers 1.72-to-1, Nasdaq 1.57-to-1 (Reuters); RSP −0.77%; only 3 of 11 sector ETFs rose
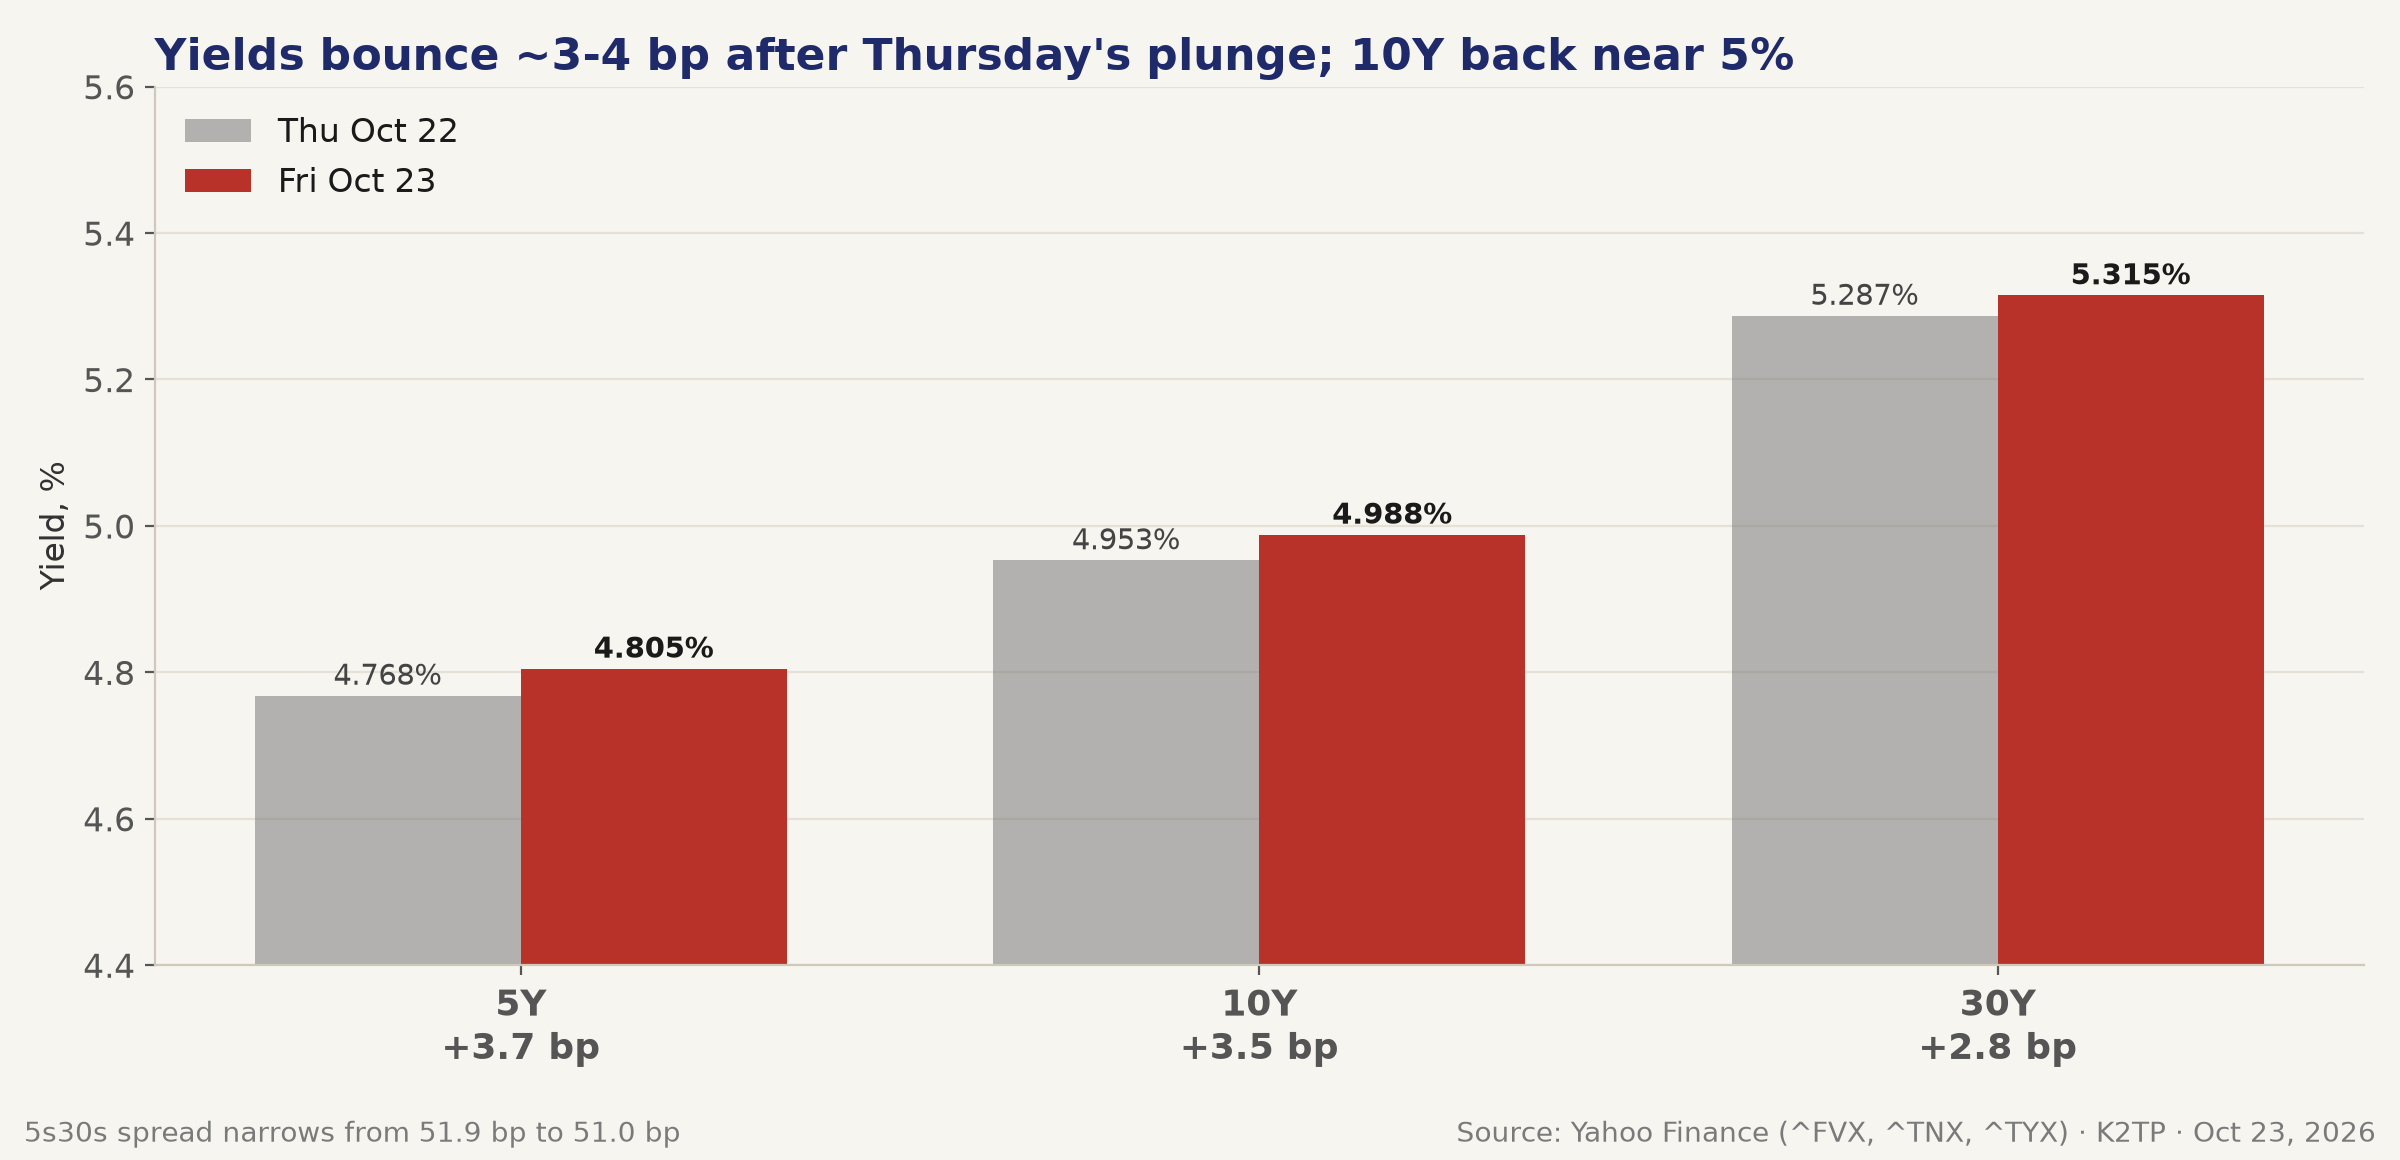
- 10Y +3.5 bp to 4.988% after Thursday's plunge; VIX 19.45 (+2.21%), touched 20.66 intraday
- SPX briefly hit the pre-market Bear trigger at 7,612.07 (7:27 AM PT), rallied to 7,660.15 (8:34 AM PT), then faded into the close
- Week: SPX −0.47%, Nasdaq −0.71%, SOX −3.21%; Dow +0.41% (third straight weekly gain), RUT +2.00%
- Regime: 🔴 RISK-OFF into the weekend, with Iran headline risk and the FOMC on Oct 27–28
OIL AND IRAN RISK LIFT ENERGY TO A RECORD
- Brent settled $116.72 (+$3.55, +3.14%), the highest since April 29; WTI $103.27 (+$3.80, +3.8%). For the week Brent rose 6% and WTI 2.3% (Reuters) 🔴
- Drivers: reports that the U.S. and Israel may be planning renewed strikes on Iran (CNBC); the U.S. is sending more forces to the region, and Iran warned it would hit civilian targets in neighboring countries if the air campaign restarts (WSJ)
- Other Gulf headlines: UKMTO reported a tanker hit by an unknown projectile near Oman (Midday brief); Iranian officials said Tehran has plans to target Gulf undersea cables if attacked again, and the Iranian and Russian presidents will meet in Moscow next week (Pre-Close brief); the UAE reported an oil spill (Reuters)
- Supply responses did not cap prices: Germany's EBV opened a reserve tender (Pre-Close brief); Baker Hughes oil rigs 460 (from 459), total rigs flat at 603
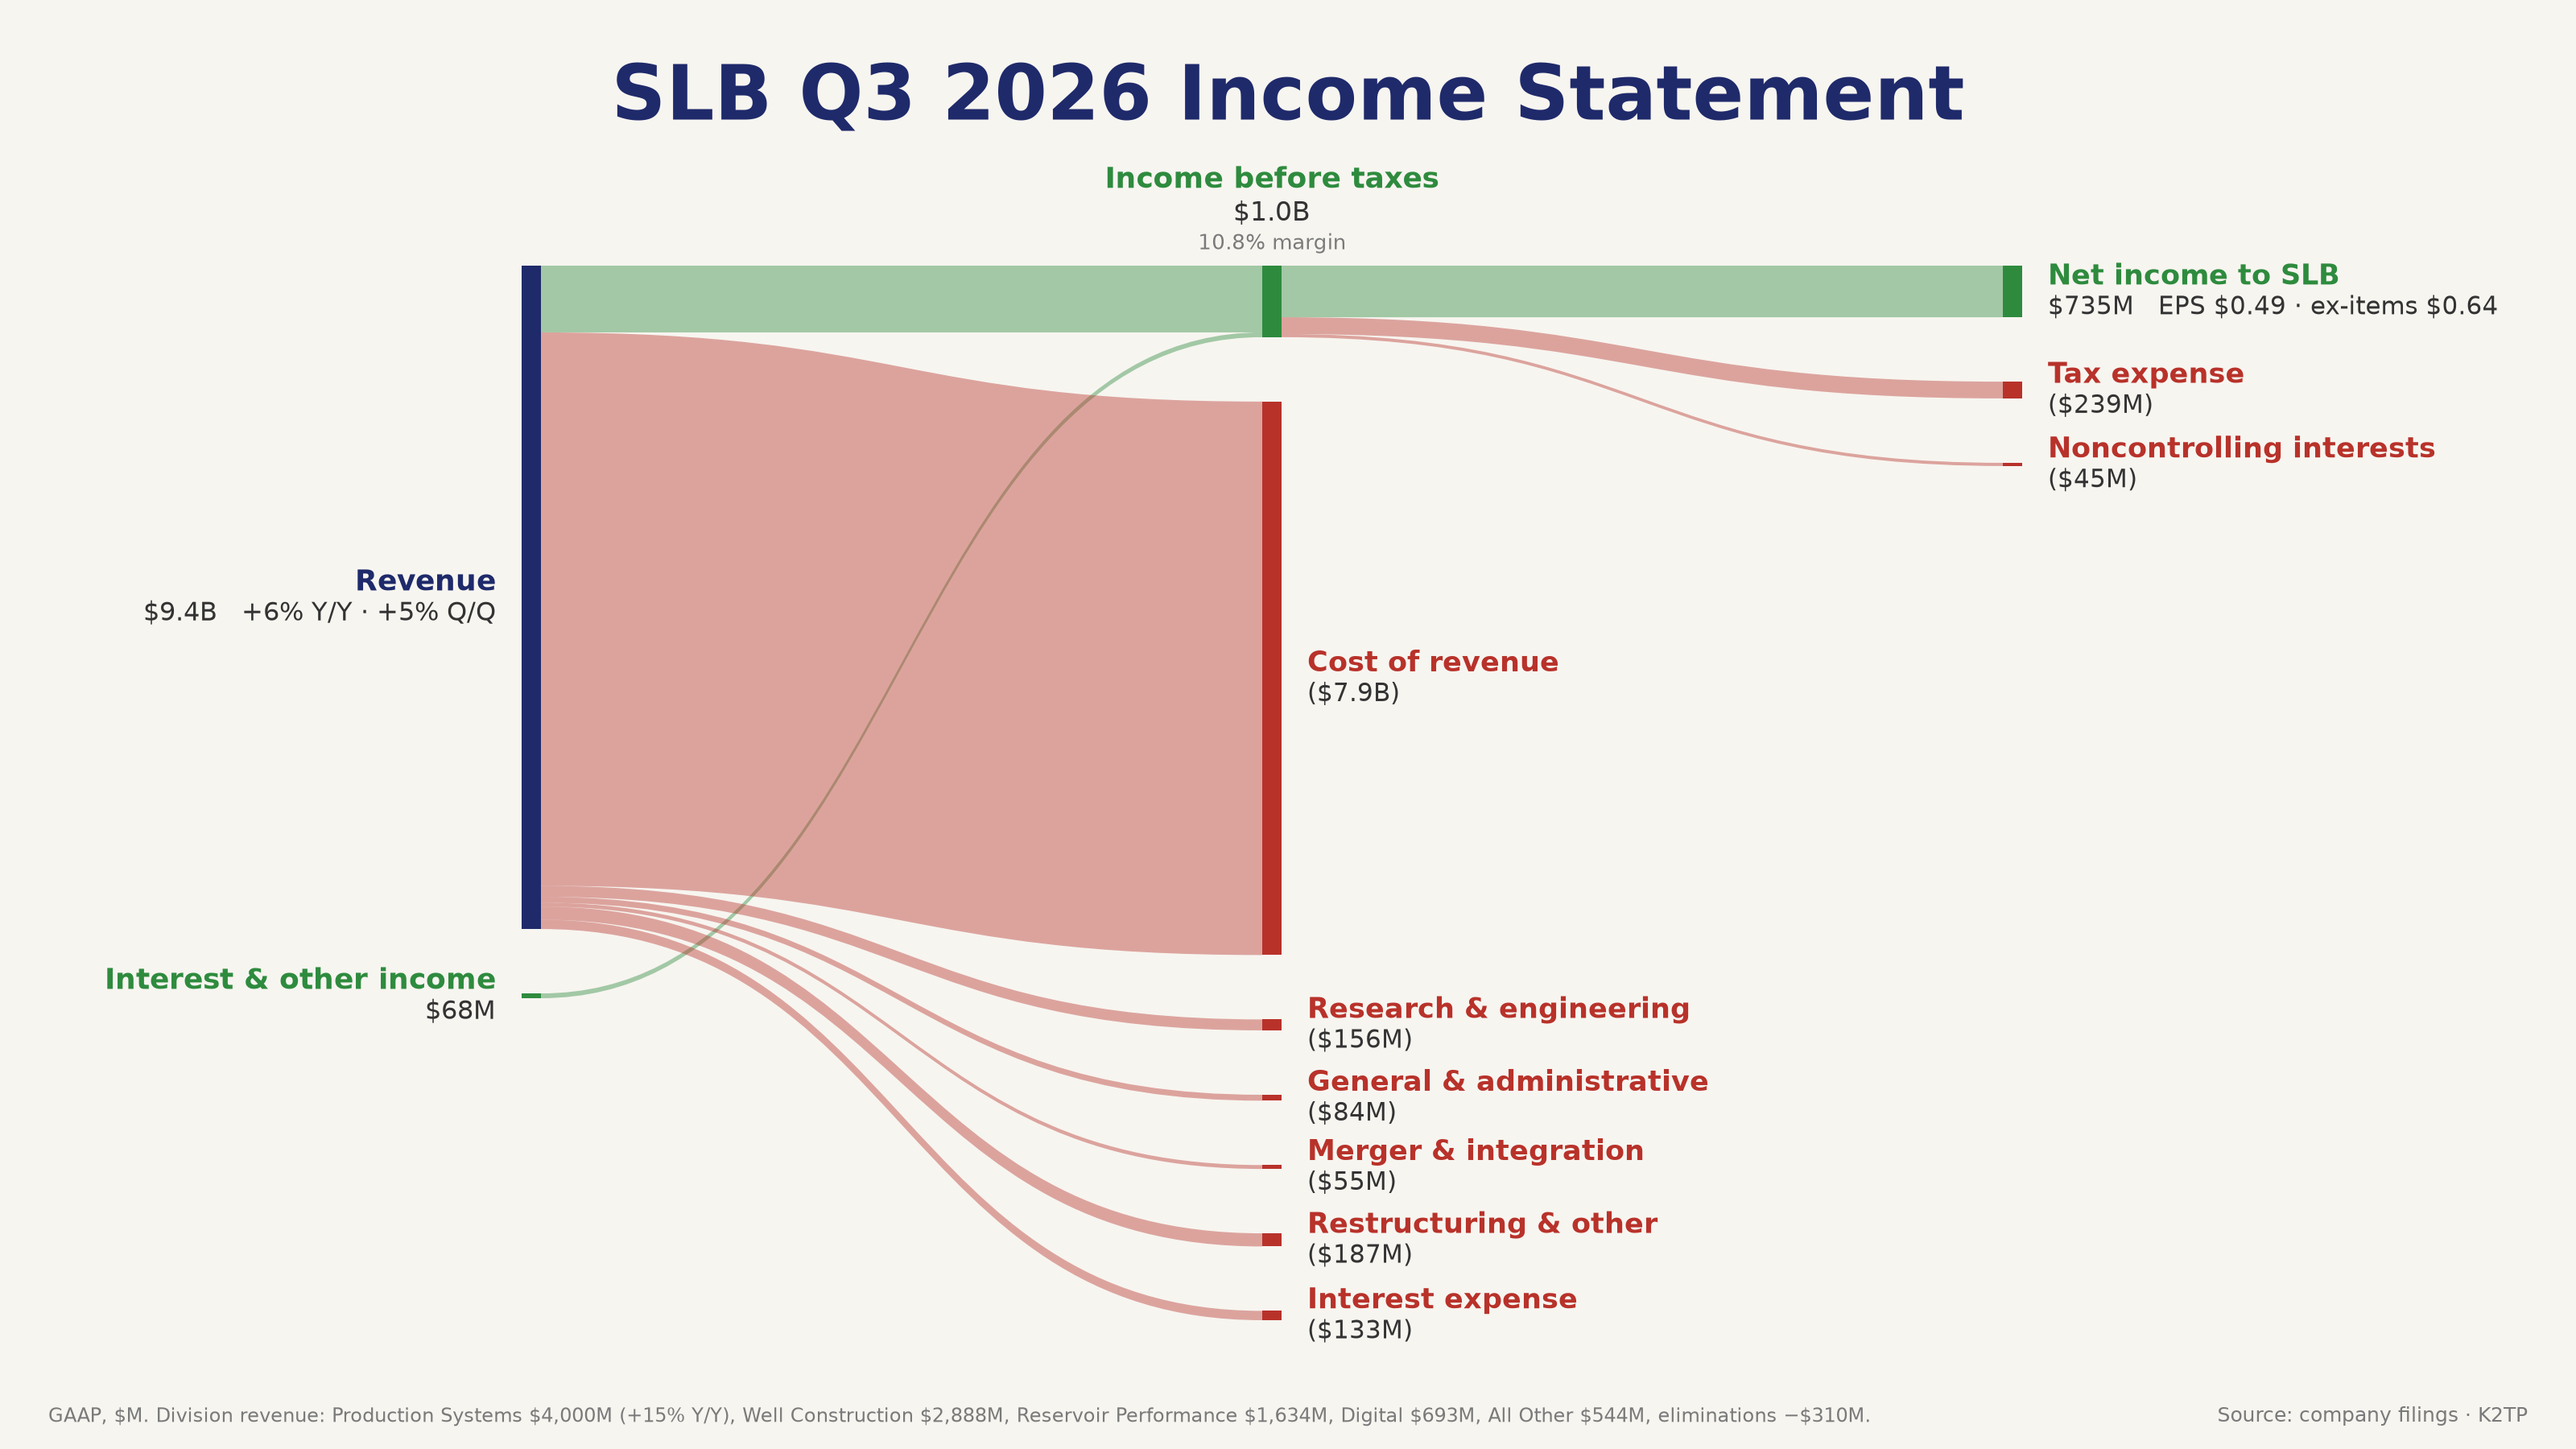
- SLB +7.08% (8-K): revenue $9.45B (+6% YoY, +5% QoQ), EPS ex-items $0.64 (+16% QoQ), GAAP EPS $0.49; Production Systems revenue +15% YoY; adjusted EBITDA $2.07B; free cash flow $828M 🟢
- XLE +2.60%, XOM +2.79%, CVX +2.88%; gold fell to $4,010.00 (−1.24%) despite the geopolitical risk
→ Oil is the market's main input right now. Brent near $117 feeds inflation risk five days before the FOMC, so it keeps rate hike odds alive and pressures everything except energy.
SPACEX HITS TELECOMS, TOWER OWNERS RALLY
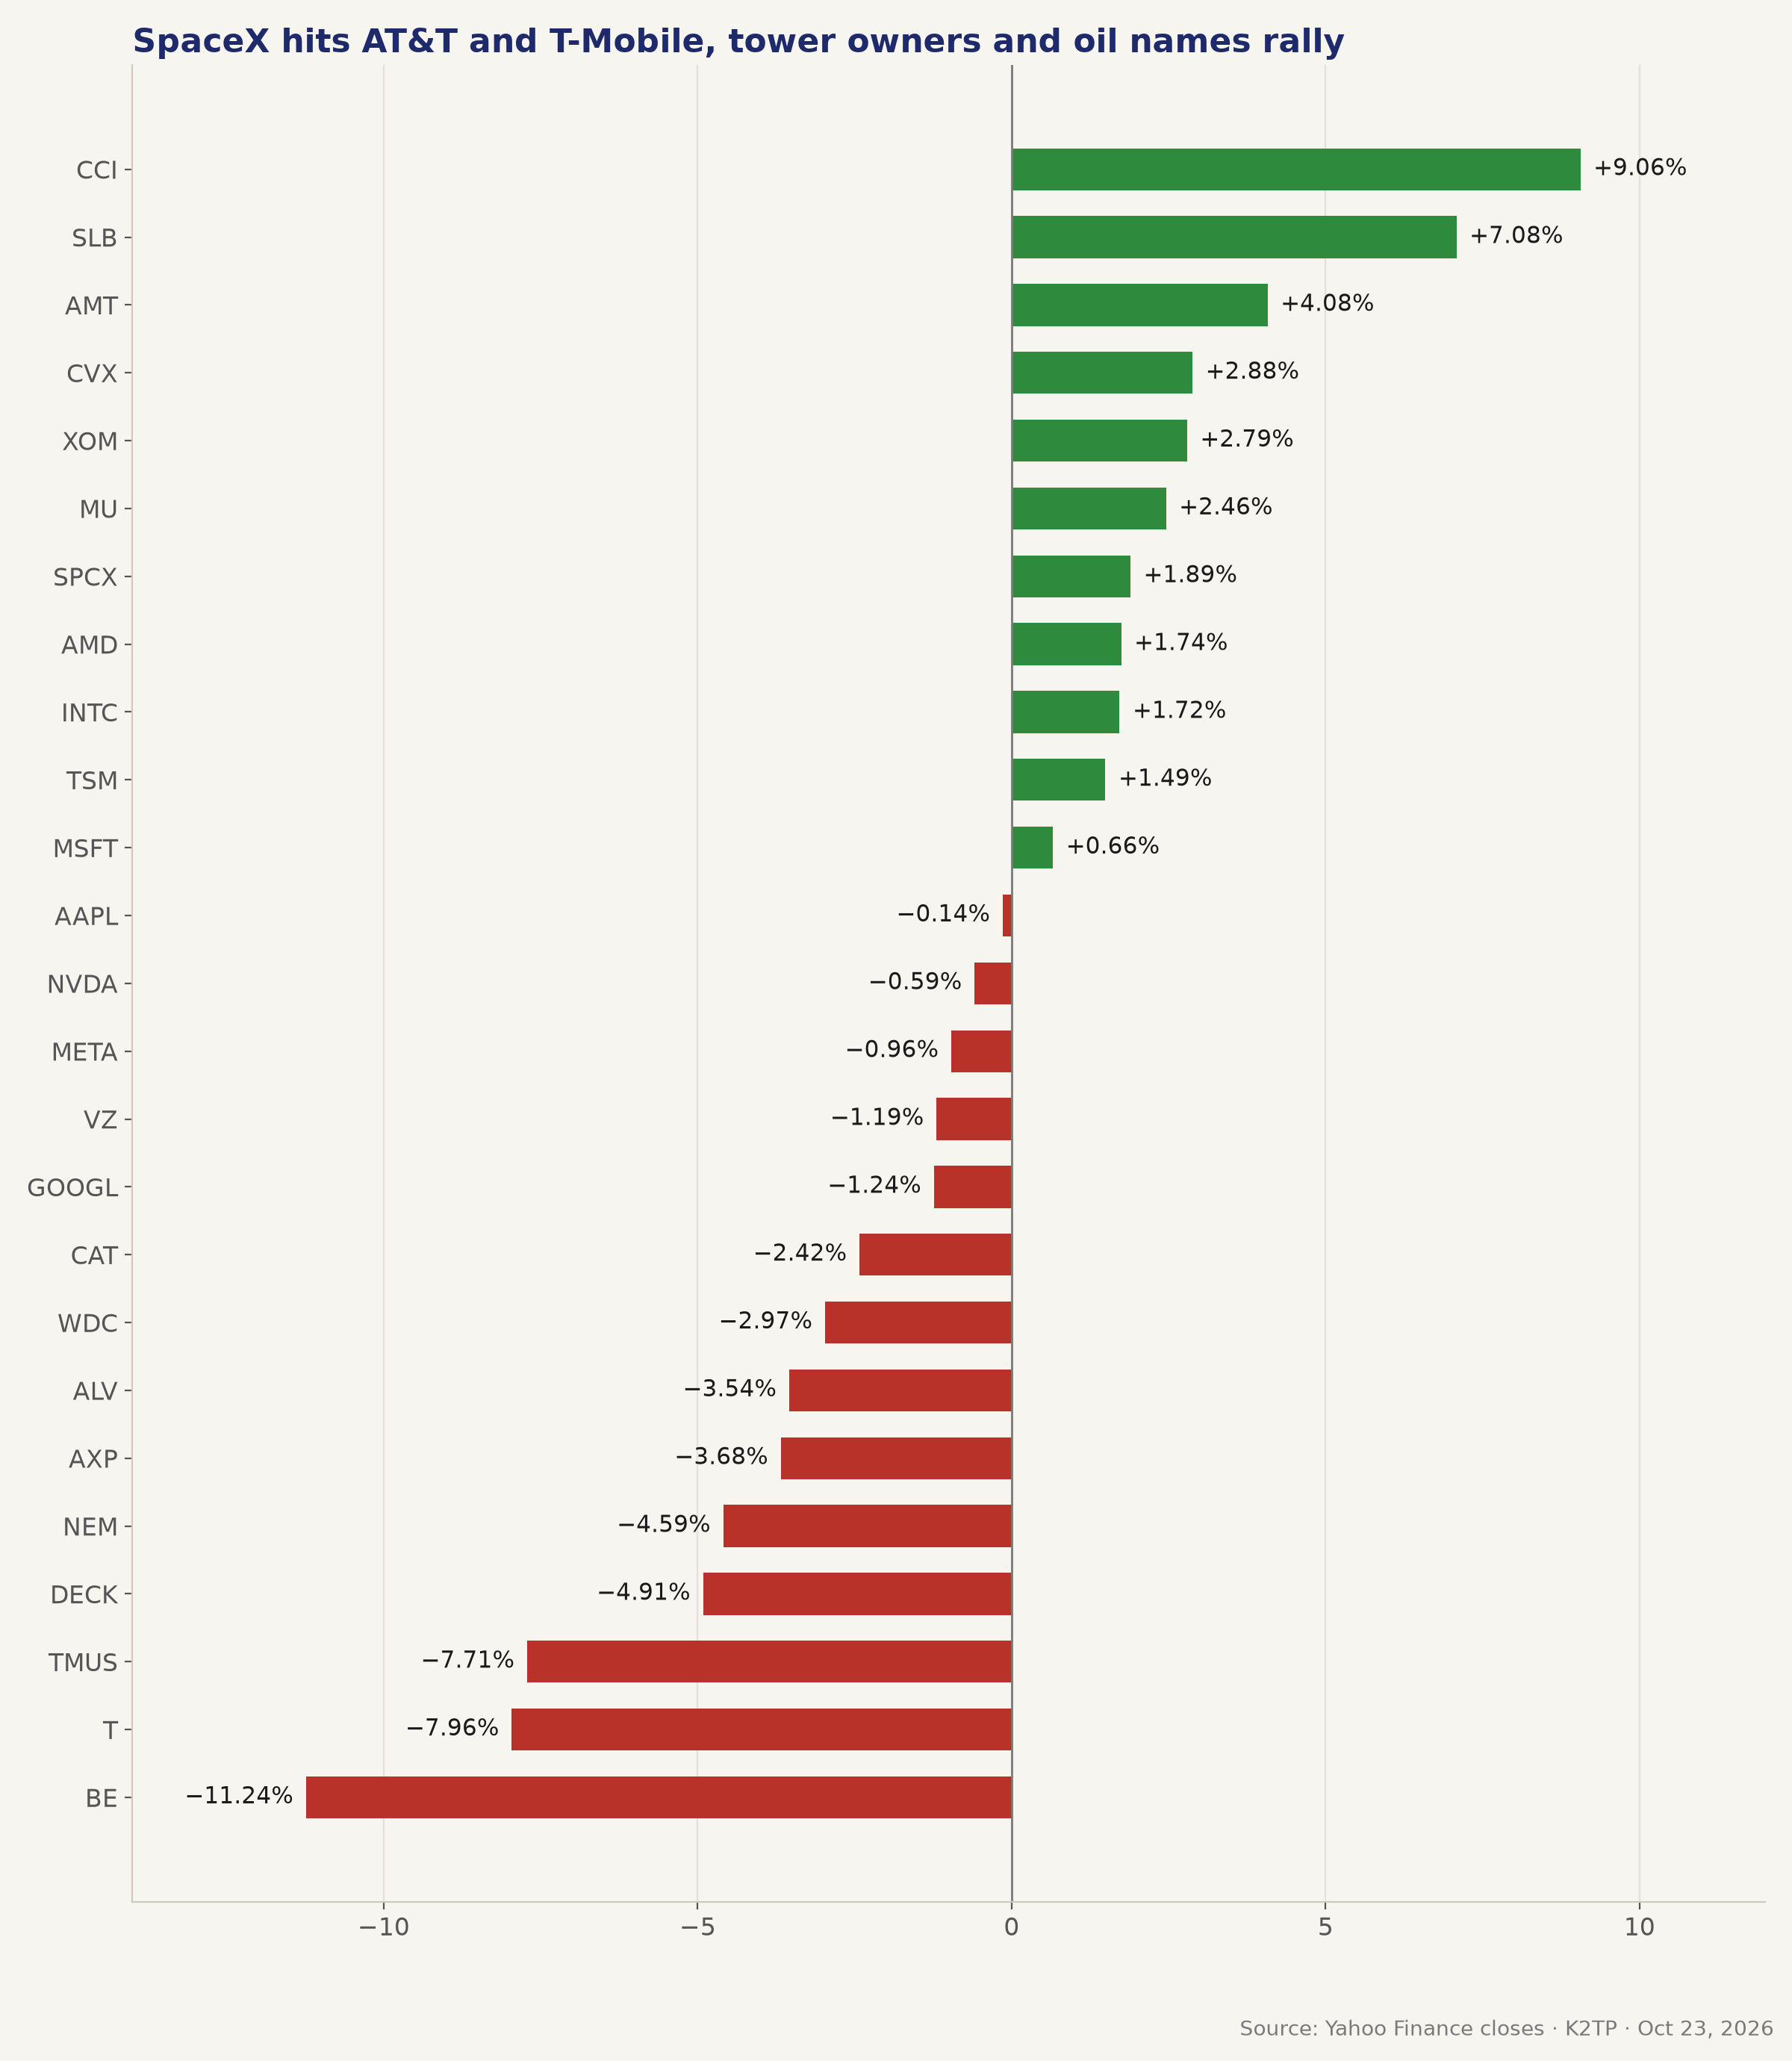
- Bloomberg reported SpaceX is in talks to lease about 80,000 cell towers to build a fourth nationwide carrier (Pre-Market brief)
- Carriers sold off all session and closed near their lows: AT&T (T) −7.96%, T-Mobile (TMUS) −7.71%, Verizon (VZ) −1.19% 🔴
- Tower owners gained: Crown Castle (CCI) +9.06% (it was +12.14% pre-market), American Tower (AMT) +4.08% 🟢
- SpaceX (SPCX) +1.89%; PhillipCapital double-upgraded it to buy and raised its target to $250 from $75 (CNBC)
- Telecoms pulled XLC down 1.78%, the second-worst sector, and added to the Dow's losses
→ This is a new competition risk for carriers, not a one-day headline. Telecoms lose their defensive role, which matters for portfolios that use T or VZ as a haven.
THURSDAY'S DEFENSIVE ROTATION UNWINDS; AMEX WEIGHS ON THE DOW
- 8 of 11 sector ETFs fell: XLP −1.92%, XLC −1.78%, XLY −1.66%, XLF −1.32%, XLI −1.27%, XLV −1.11%, XLB −0.74%, XLU −0.72%; gainers XLE +2.60%, XLK +0.49%, XLRE +0.12%
- American Express (AXP) −3.68% (8-K): record revenue of $20.06B (+9%) versus about $20.32B expected (Pre-Market brief); GAAP EPS $5.42, adjusted EPS $4.68 (+13%); full-year EPS guidance raised to $18.30–18.60 ($17.60–17.90 adjusted) 🔴
- AXP will cut about 5% of its workforce to "prepare for AI" (CNBC); it also raised its profit forecast (Reuters); Q3 included a $336M pretax restructuring charge and a $982M gain on the GBTG stake sale
- Caterpillar −2.42% and Autoliv −3.54% added to the industrial losses; CNN's Fear & Greed Index sat at 20, "Extreme Fear" (Midday brief)
- DJIA −1.23% versus SPX −0.52%; RSP −0.77% lagged SPX, the opposite of Thursday
→ Money is not finding a clear haven: staples, healthcare and utilities fell along with financials. That looks like traders cutting exposure before a weekend with Gulf risk and a Fed decision, not a rotation.
CHIPS STEADY, BUT THE BOUNCE FADES
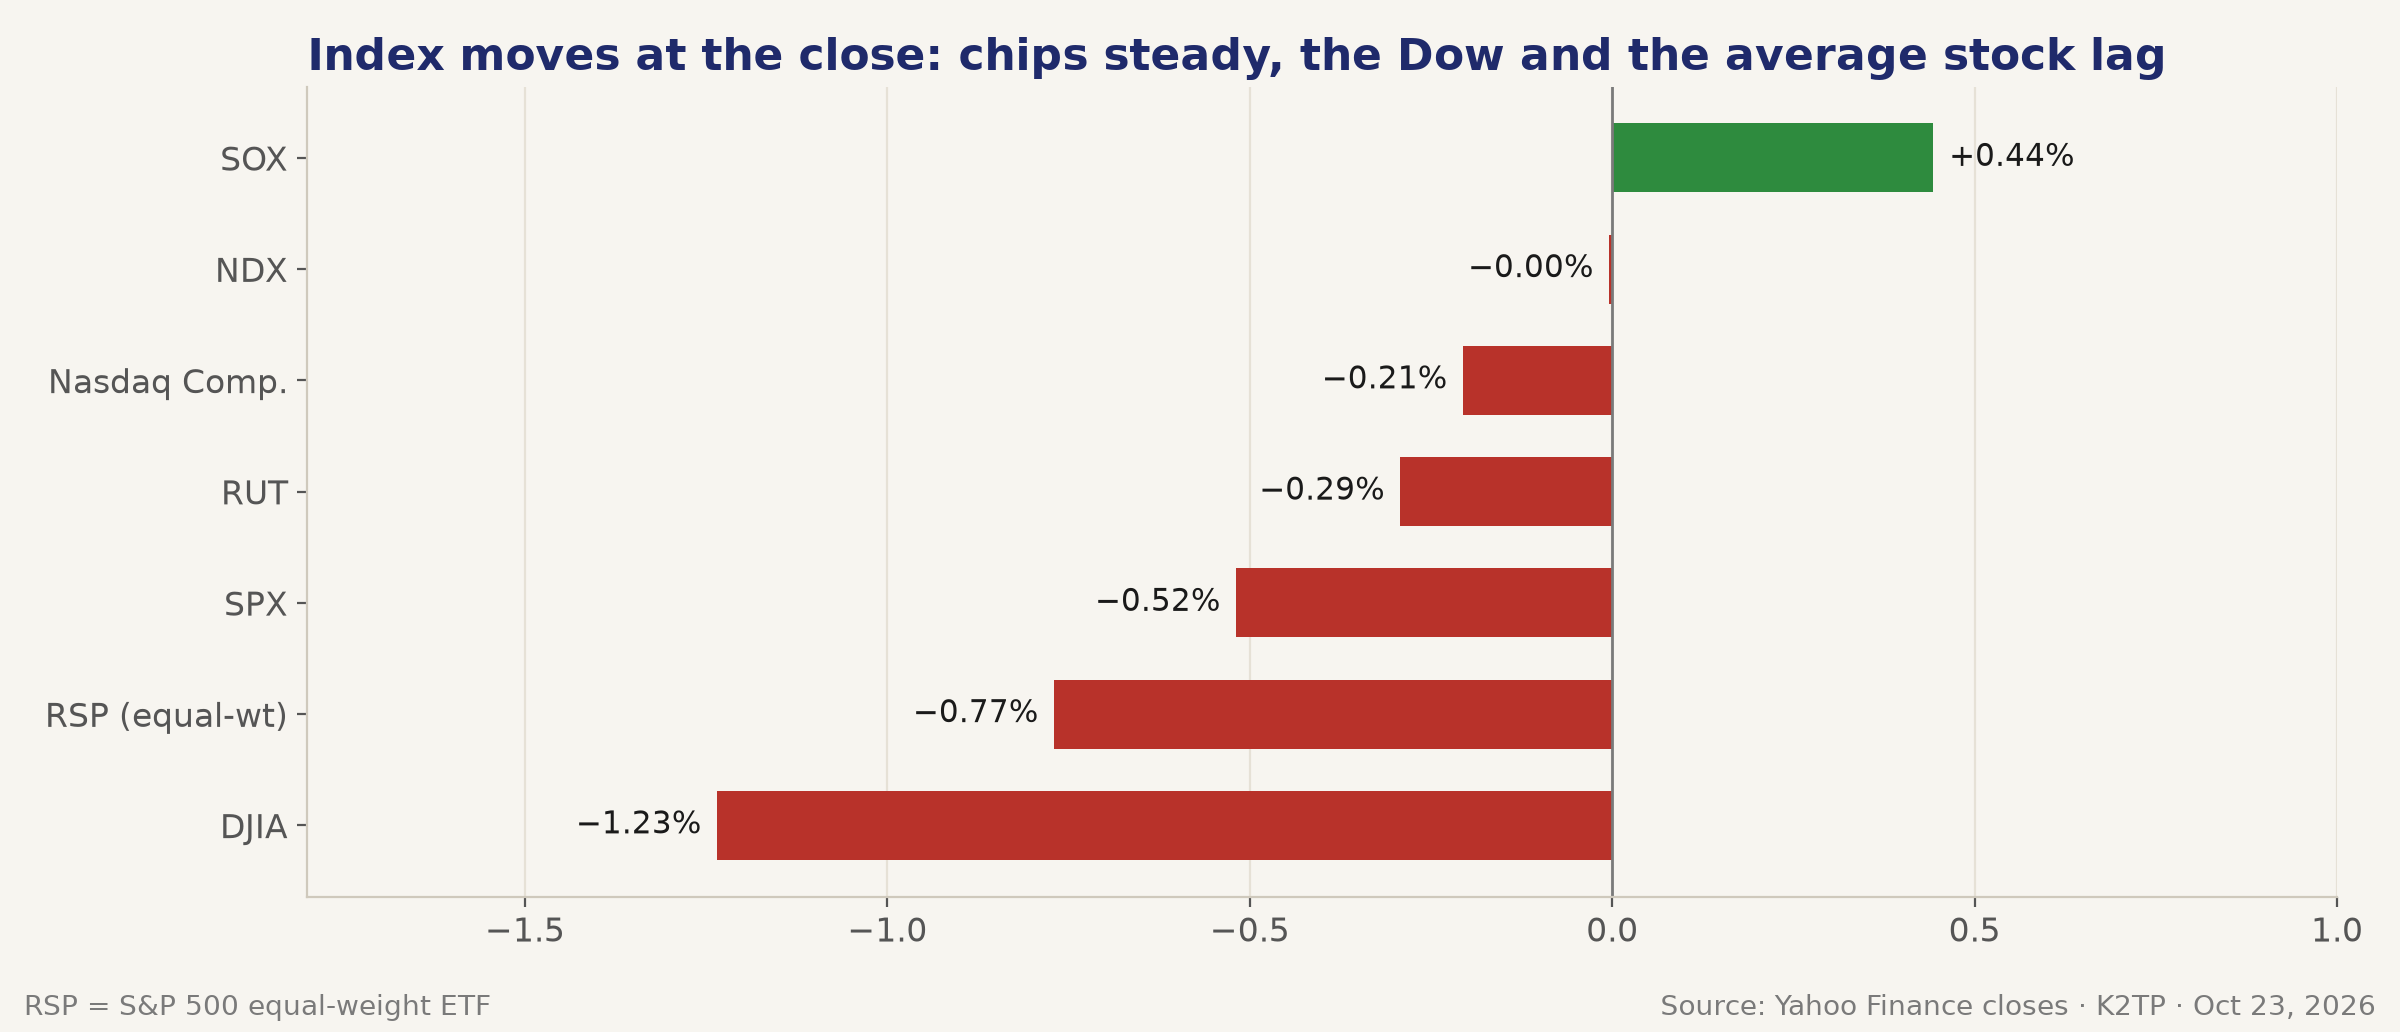
- SOX +0.44% to 10,779.46 after Thursday's −6.72%, the biggest drop since June; it was +1.07% at midday (Midday brief)
- MU +2.46%, AMD +1.74%, INTC +1.72%, TSM +1.49%, MSFT +0.66%; NVDA −0.59%, AVGO −0.48%, META −0.96%, GOOGL −1.24%, AMZN −0.95%; CoreWeave (CRWV) −2.46%
- Nvidia's Jensen Huang told CNBC there is "a scarcity of capital" for AI infrastructure (Pre-Market brief); SK Hynix pulled the planned U.S. IPO of its memory-chip unit (Midday brief)
- Nikkei reported Meta's Chief AI Officer said Muse AI will rely on subscriptions and enterprise services, not ads (Pre-Close brief)
- NDX closed flat (−1.16 points) to 28,957.53; Nasdaq Composite −0.21%
→ This was an oversold bounce, not a return of AI leadership. With MSFT, GOOGL and AMZN reporting next week, capex guidance will decide whether chips stabilize or test new lows.
DATA STEADY, YIELDS BACK NEAR 5%
- S&P Global flash PMI (October): composite 57.6 (forecast 57.6, previous 58.4), manufacturing 56.0, services 57.9 (Midday brief)
- UMich final October: expectations 48.8 versus 47.1 forecast; 5-year inflation expectations steady at 3.5%; overall sentiment stayed near a record low (Reuters)
- Closing yields: 10Y 4.988% (+3.5 bp, range 4.95–5.00%), 5Y 4.805% (+3.7 bp), 30Y 5.315% (+2.8 bp); 5s30s narrowed from 51.9 bp to 51.0 bp 🔴
- For the week, the 10Y fell 11.0 bp (from 5.098% on Oct 16), mostly on Thursday's haven rally
- The Fed is in its blackout; FOMC decision Wed Oct 28 at 11:00 AM PT. A Reuters poll cited by FinancialJuice showed 19 of 34 economists expect the Bank of Canada to hike on Oct 28 (unconfirmed, Midday brief)
- Europe: eurozone flash composite PMI 51.9 versus 52.7 expected, France 48.4; UK 53.1 (Pre-Market brief)
→ The data did not change the Fed outlook, but oil did. A 10Y near 5% plus Brent above $116 makes it hard for the Fed to sound dovish next week.
SPX TOUCHES THE BEAR LINE, RECOVERS, THEN FADES
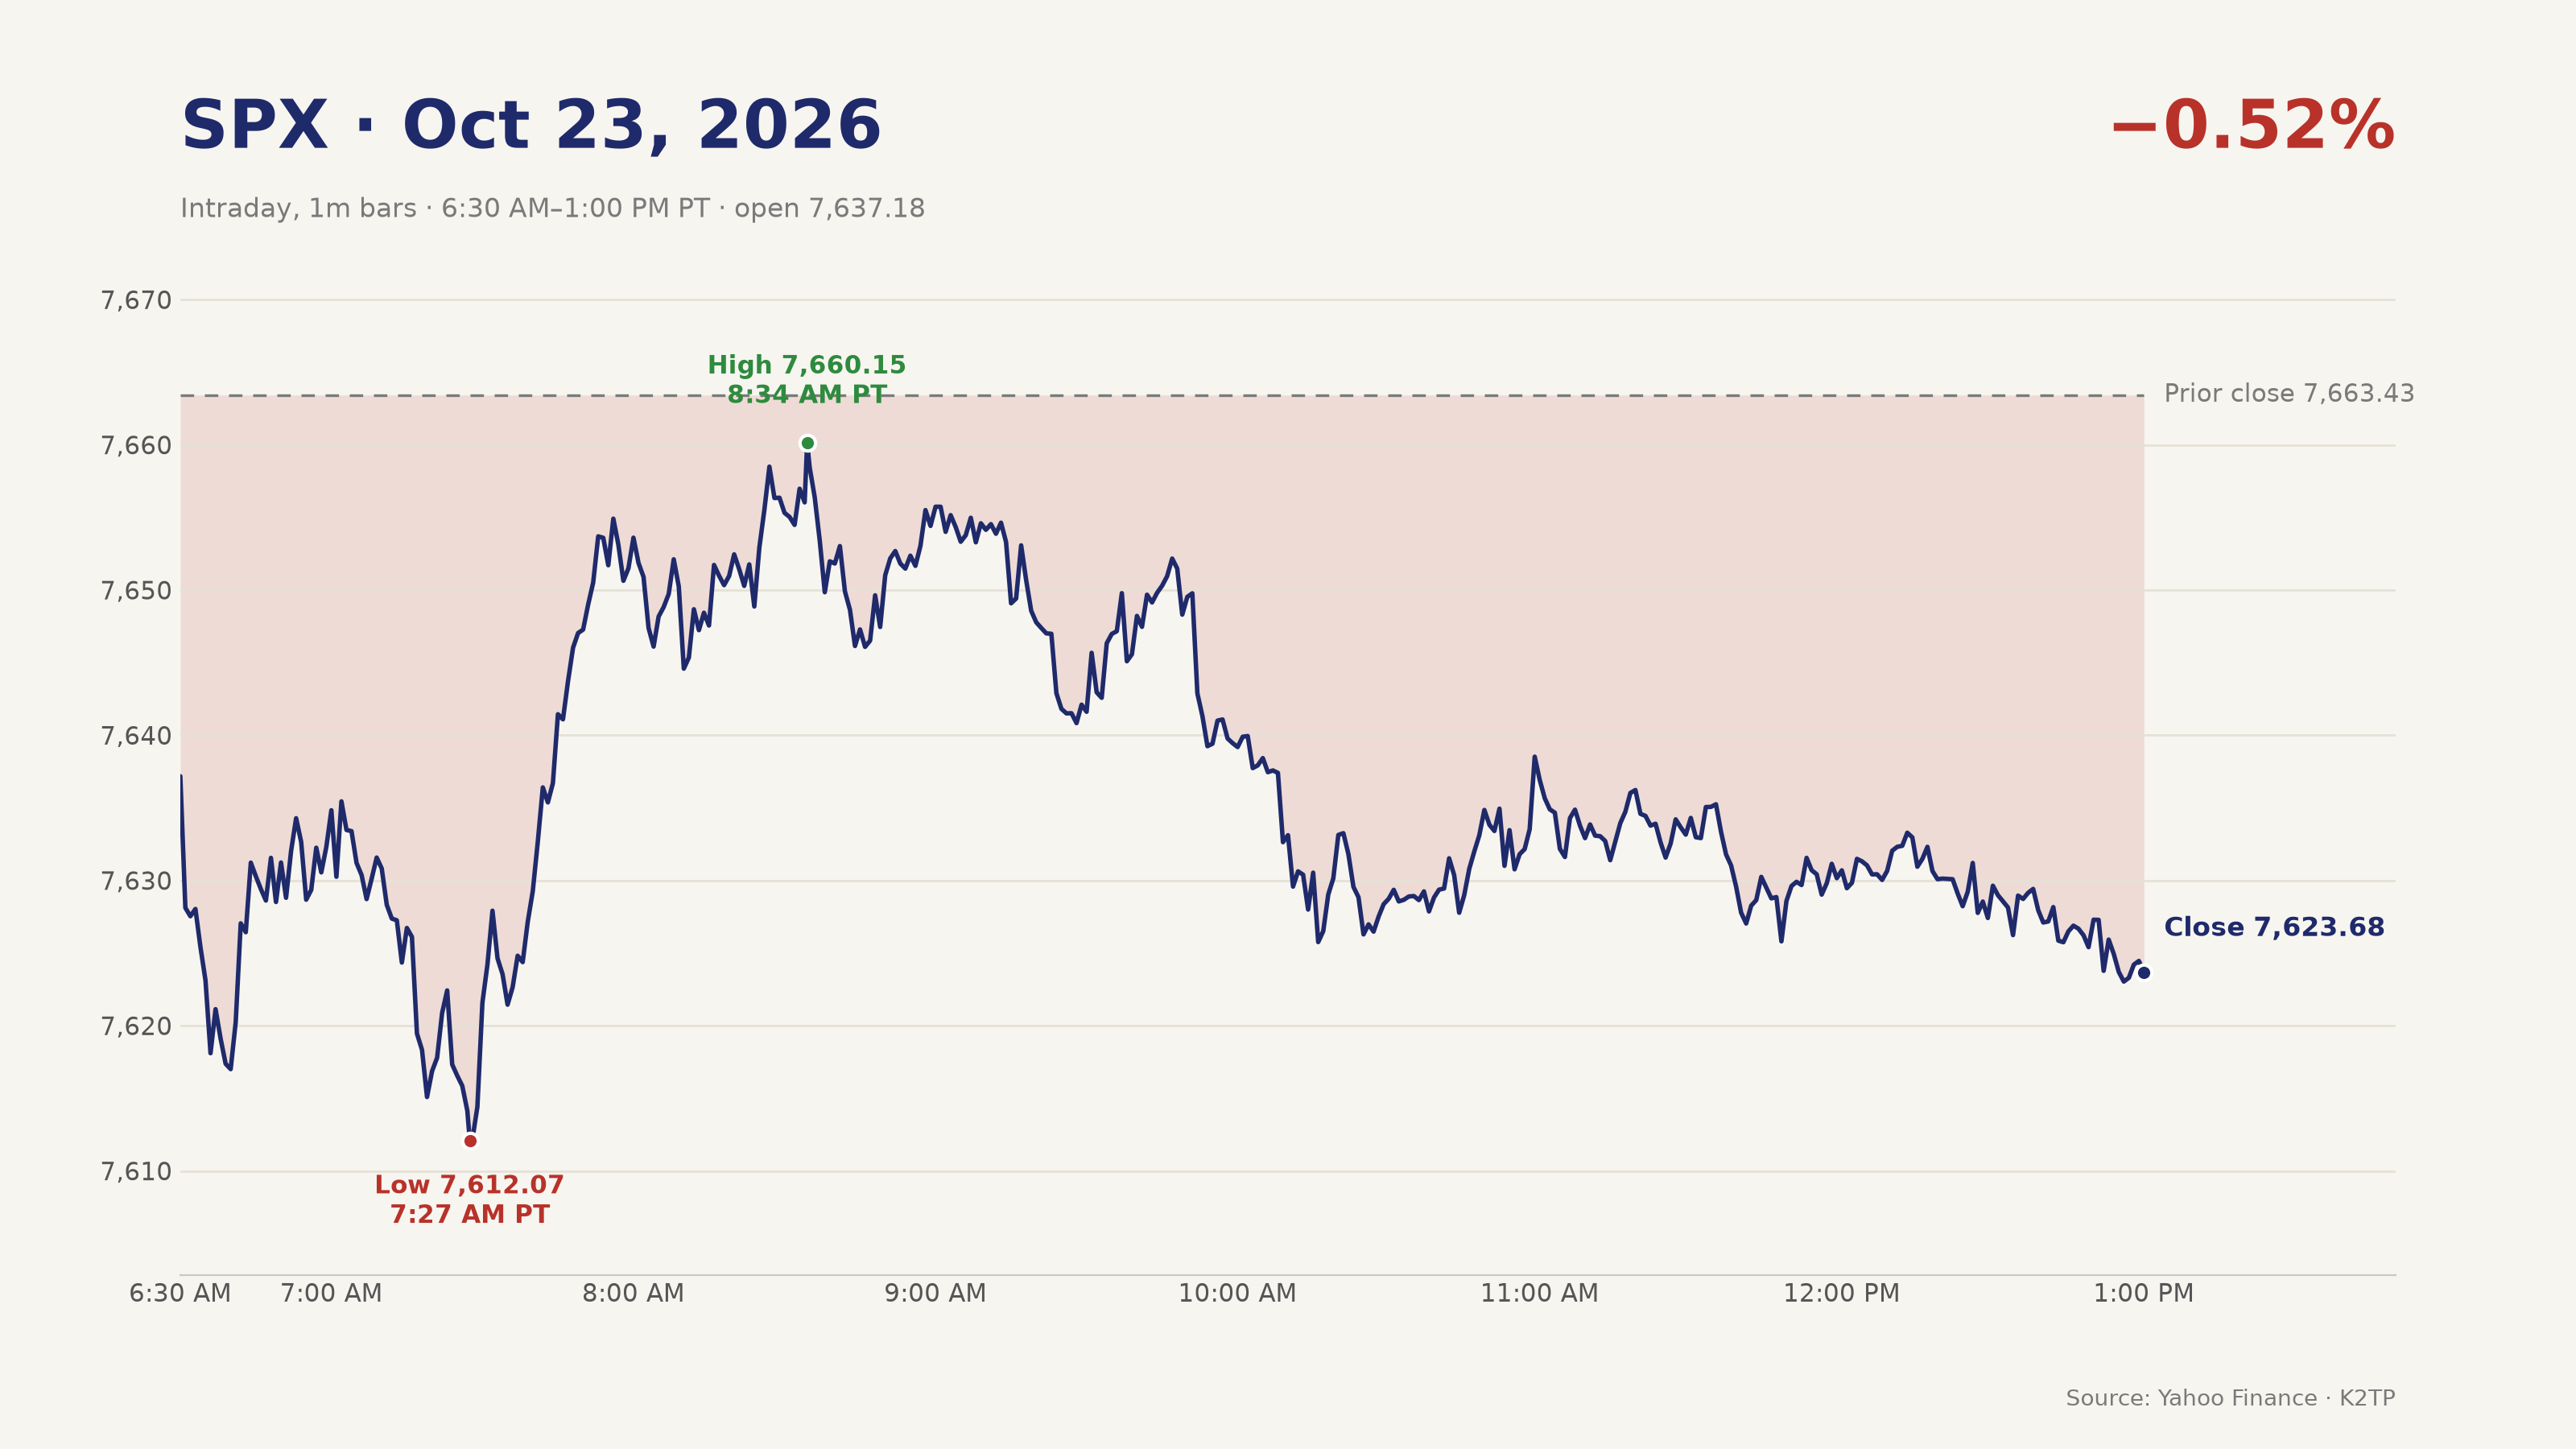
- Opened 7,637.18, right on Thursday's 7,637.36 low, and fell to the session low of 7,612.07 at 7:27 AM PT as VIX hit 20.66
- The pre-market Bear trigger (SPX below 7,637.36 with VIX above 20.31) fired between 7:15 and 7:30 AM PT, then reversed by 7:40 AM PT (Midday brief)
- Rallied to the session high of 7,660.15 at 8:34 AM PT, still below Thursday's 7,663.43 close; at midday SPX was 7,646.89 with VIX 19.22
- Faded after 9:30 AM PT as oil kept rising; at the Pre-Close brief it was 7,631.57 with VIX 19.85, and it closed at 7,623.68, 11.61 points above the low
- Pre-Close triggers: Bull (close above 7,646.89 with VIX below 19.22) and Bear (close below 7,612.07 with VIX above 20.66) both failed
→ The 7,612.07 low held into the close, but every bounce was sold below Thursday's close. Sellers still control the short term until SPX clears 7,660–7,663.
WEEKLY RECAP: SMALL CAPS AND THE DOW UP, CHIPS LEAD LOSSES
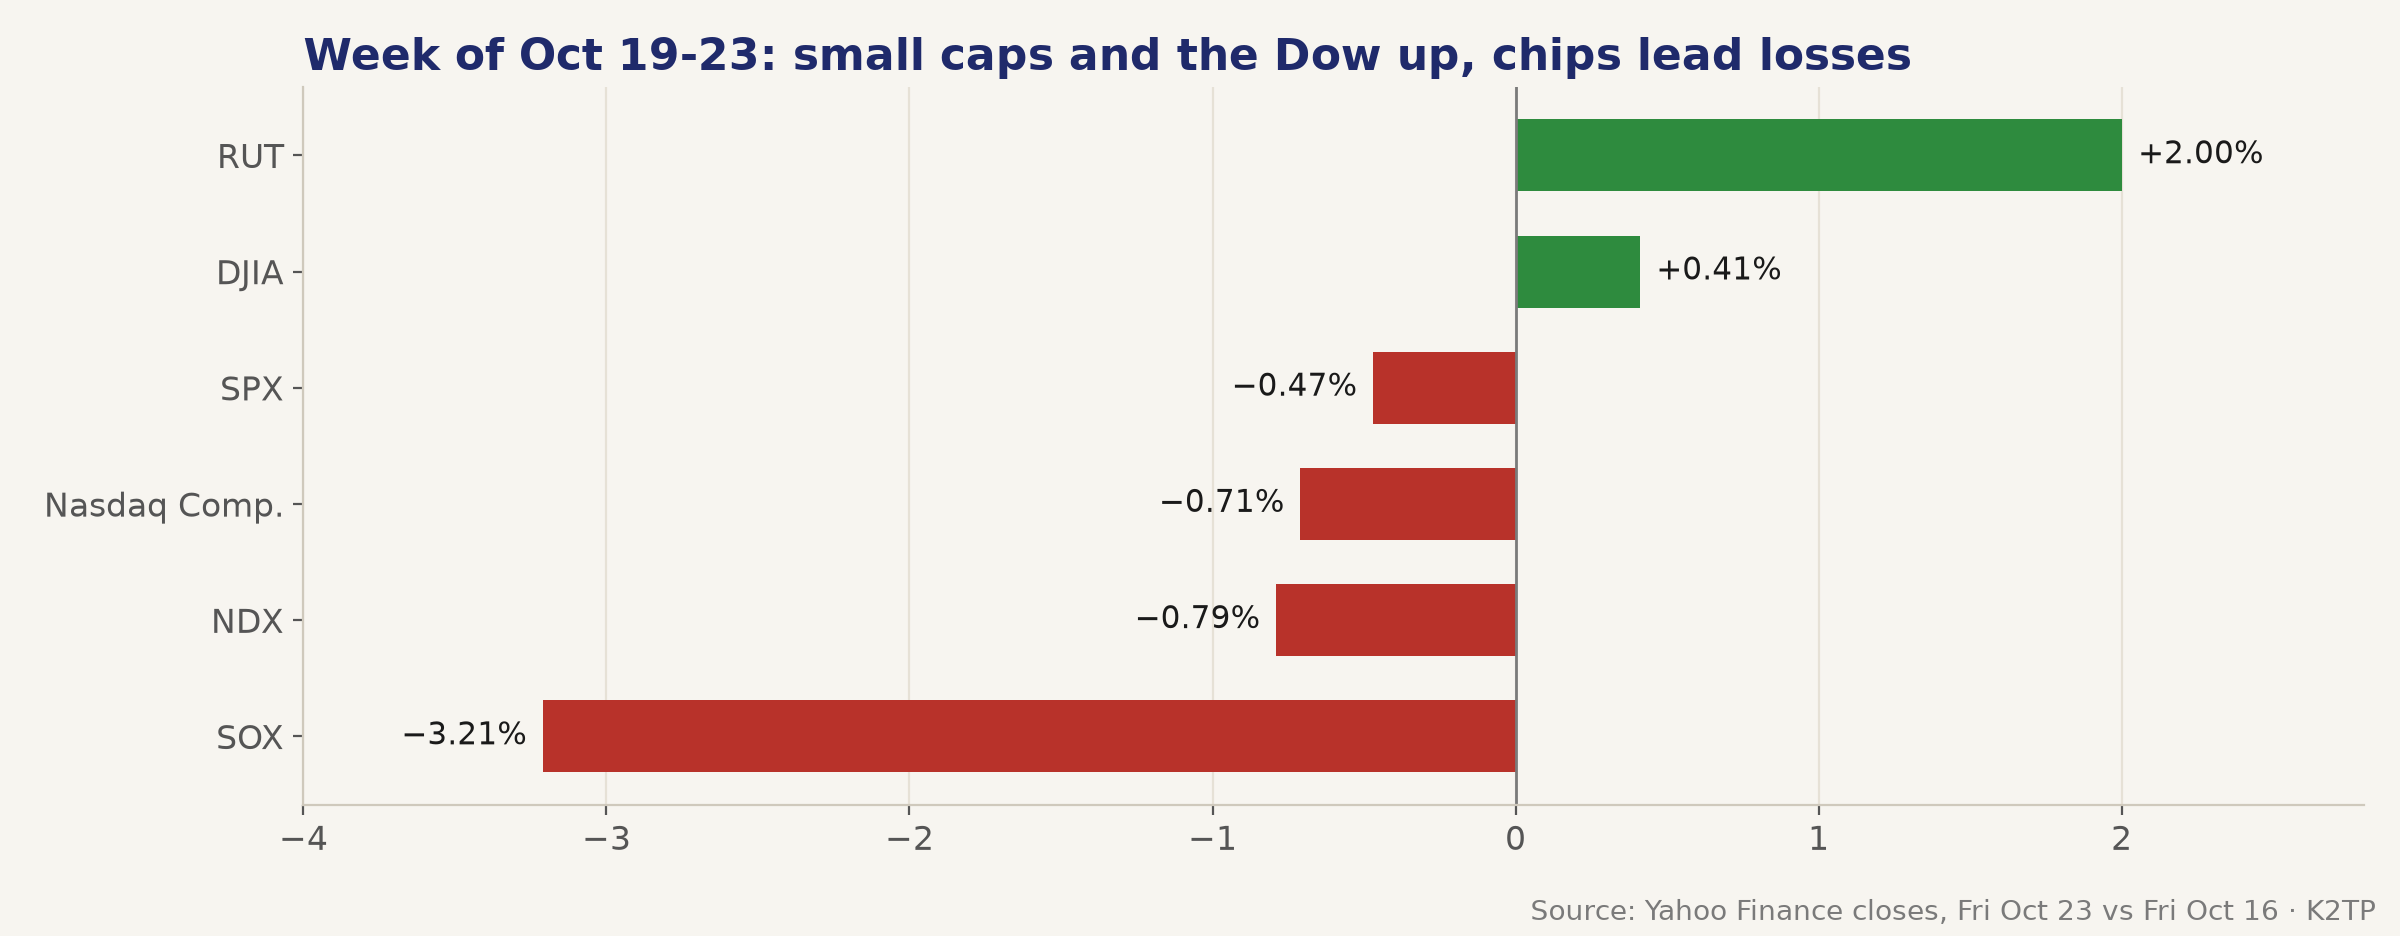
- Week (Fri Oct 23 versus Fri Oct 16 close): RUT +2.00%, DJIA +0.41%, SPX −0.47%, Nasdaq −0.71%, NDX −0.79%, SOX −3.21%
- SPX posted a second straight weekly loss (AP); the Dow had its third straight weekly gain (Reuters)
- VIX 19.99 → 19.45 for the week; 10Y 5.098% → 4.988% (−11.0 bp); Brent +6%, WTI +2.3% (Reuters)
- European stocks had their steepest weekly loss since early September: STOXX 600 about −1.4% (Reuters)
→ The week moved leadership away from AI and chips toward small caps, value and energy. The cap-weighted index needs AI to stabilize to recover.
MARKET: OIL AND TELECOMS SINK THE DOW, CHIPS HOLD NDX FLAT
Indices (close):
- SPX 7,623.68 (−0.52%), range 7,612.07–7,660.15
- NDX 28,957.53 (−0.00%); Nasdaq Composite 25,955.34 (−0.21%)
- DJIA 52,215.16 (−1.23%)
- RUT 2,775.90 (−0.29%)
- RSP 216.54 (−0.77%)
- SOX 10,779.46 (+0.44%)
Intraday path: Pre-market YM −0.76%, ES −0.35%, NQ −0.19% on the SpaceX telecom report and higher oil. SPX opened 7,637.18, hit its 7,612.07 low at 7:27 AM PT, peaked at 7,660.15 at 8:34 AM PT, was at 7,646.89 at midday and 7,631.57 before the close, and closed at 7,623.68.
Sector rotation:
- Gainers: XLE +2.60%, XLK +0.49%, XLRE +0.12%
- Decliners: XLU −0.72%, XLB −0.74%, XLV −1.11%, XLI −1.27%, XLF −1.32%, XLY −1.66%, XLC −1.78%, XLP −1.92%
- Megacaps: MU +2.46%, AMD +1.74%, TSM +1.49%, MSFT +0.66%; AAPL −0.14%, AVGO −0.48%, NVDA −0.59%, TSLA −0.63%, AMZN −0.95%, META −0.96%, GOOGL −1.24%
Internals:
- NYSE: decliners outnumbered advancers 1.72-to-1; Nasdaq 1.57-to-1 (Reuters)
- Nearly three of every four S&P 500 stocks fell (AP)
- RSP −0.77% and IWM −0.33% versus SPX −0.52%: weakness was broad, cushioned only by energy and chips
Volatility:
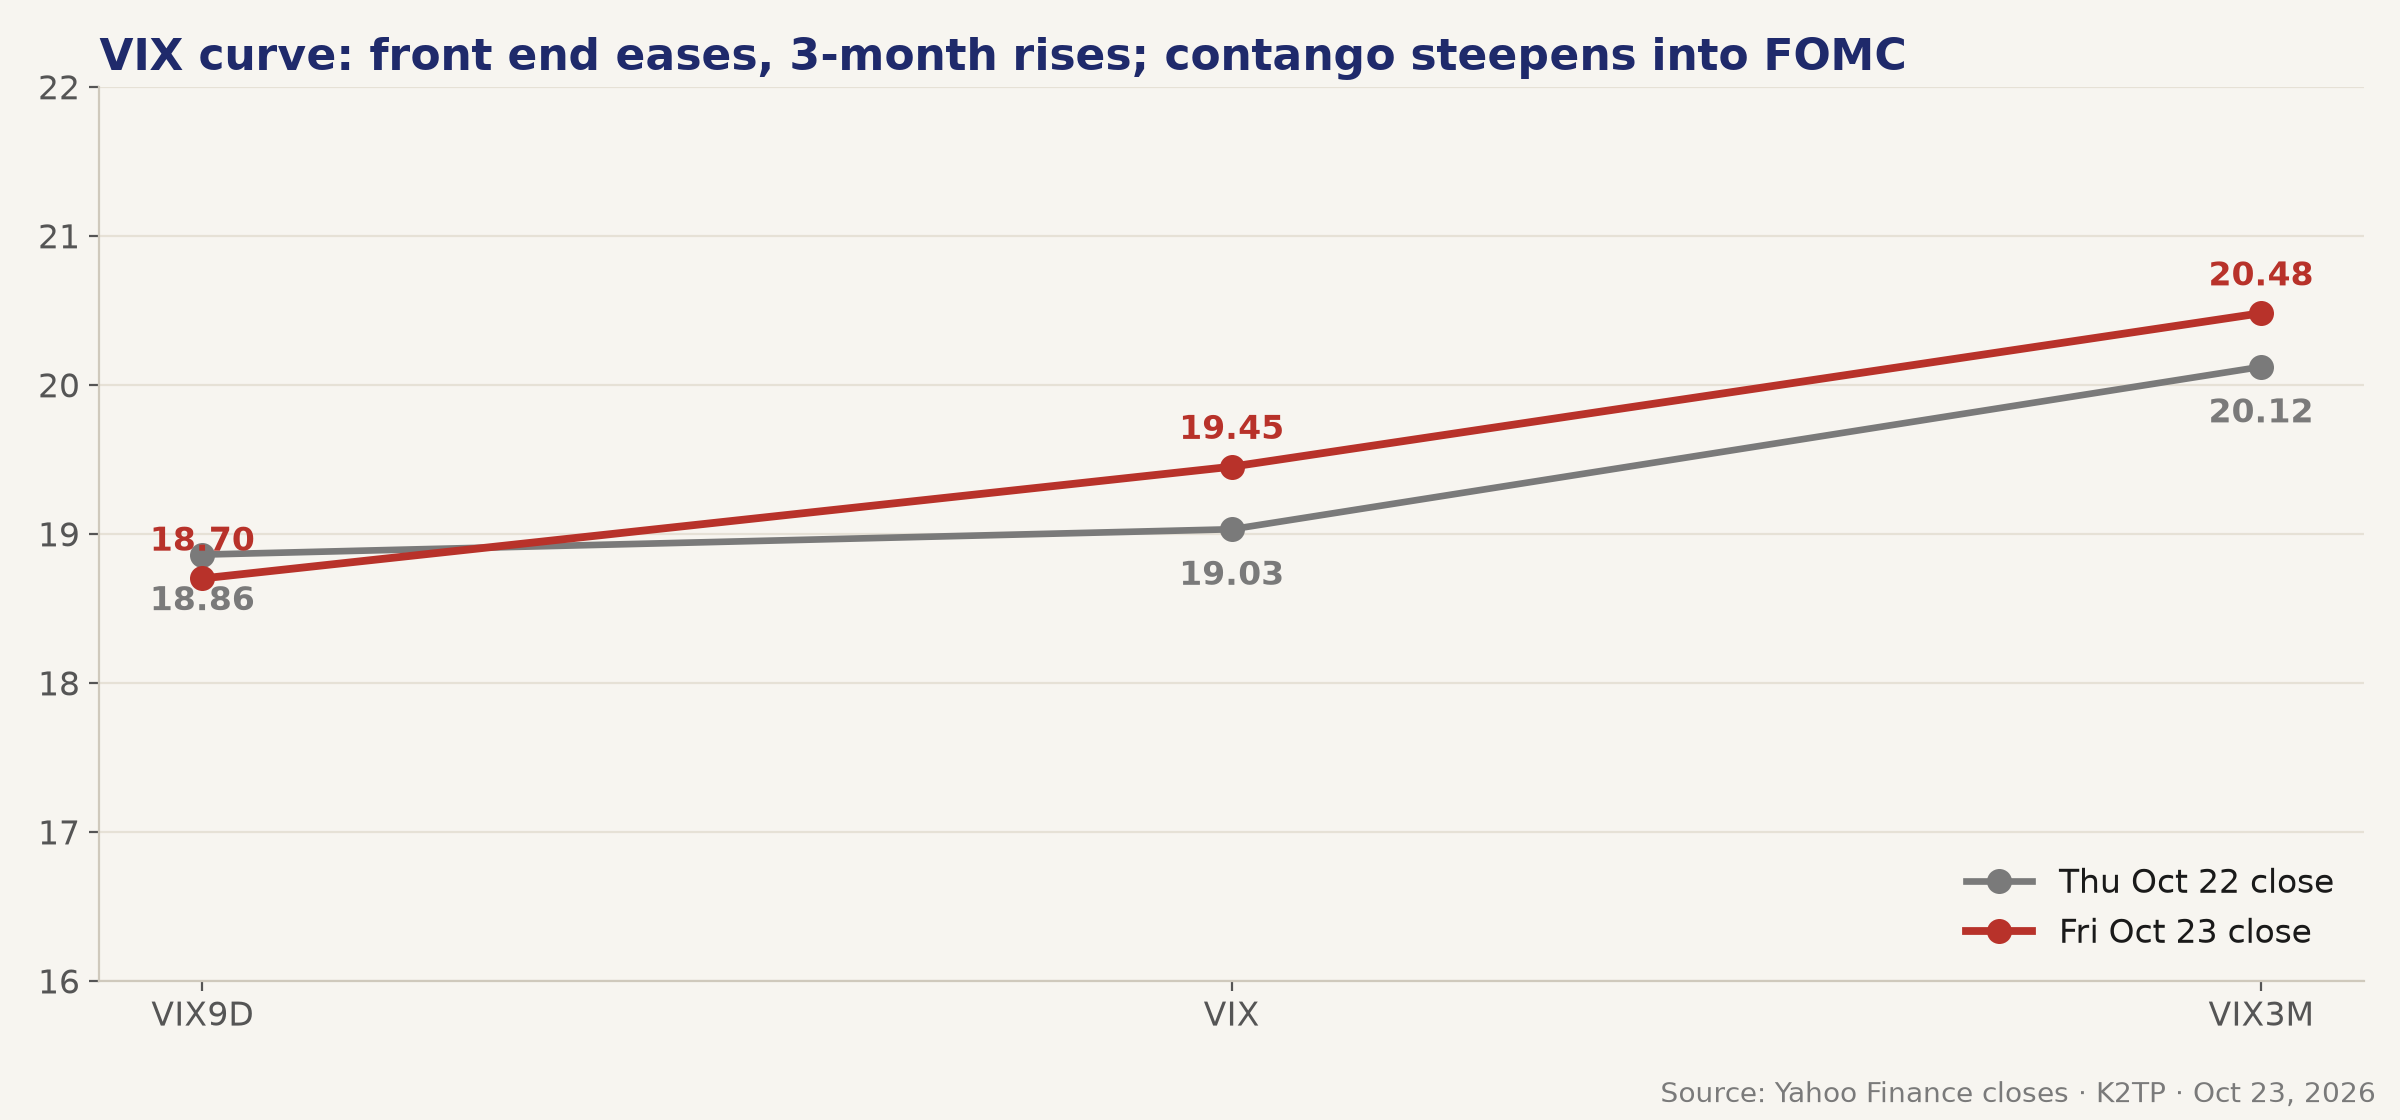
- VIX 19.45 (+2.21%), range 18.87–20.66
- VIX9D 18.70 (from 18.86), VIX3M 20.48 (from 20.12): the front end eased while 3-month rose, so contango steepened into FOMC and the weekend
- VVIX 109.70 (+1.63%)
Cross-asset:
- Brent $116.72 (+3.14%), WTI $103.27 (+3.8%) at settlement (Reuters)
- Gold $4,010.00 (−1.24%); DXY 101.75 (+0.14%); BTC about $80,843 (−0.58%, Yahoo)
- ES December futures last at 7,672.50 (Yahoo); futures reopen Sunday at 3:00 PM PT
Global:
- Asia (Friday, Pre-Market brief): Shanghai +0.89%, Hang Seng +0.69%, Kospi +0.30% (after falling as much as 4%, Reuters), Nikkei −0.34%
- Europe: Euro Stoxx 50 −0.31%, CAC −0.36%, FTSE −0.32%, DAX −0.75%; STOXX 600 −0.31% to 635.77 (Reuters)
Key SPX levels:
- 7,702.94: Thursday high
- 7,663.43: Thursday close
- 7,660.15: Friday high, Bull line
- 7,646.89: midday level
- 7,623.68: close
- 7,612.07: Friday low, Bear line
- VIX: 18.87 and 20.66
Option seller corner:
- Bull case: SPX above 7,660.15 with VIX below 18.87 moves the regime to TRANSITION. Then consider small far-OTM SPX put spreads to capture premium after the FOMC.
- Bear case: SPX below 7,612.07 with VIX above 20.66 deepens RISK-OFF. Then cut short put size, use only defined-risk spreads and avoid naked short puts in NDX and chips.
- VIX near 19.5 with VIX3M at 20.48 means the market is pricing FOMC and Gulf risk further out the curve. If you sell expirations after Oct 28, use wider strikes.
- Weekend gap risk is high (Iran, Brent near $117): avoid holding unhedged short premium into Monday's open; telecoms (T, TMUS) and energy carry the biggest gap risk.
BOTTOM LINE
- Oil set the tone: Brent settled $116.72 (highest since April 29) on U.S.-Iran escalation risk; energy hit a record while most other sectors fell.
- SpaceX's wireless push sank AT&T and T-Mobile nearly 8%, and AXP's job cuts pulled the Dow down 1.23%; chips only steadied (SOX +0.44%, NDX flat).
- Regime 🔴 RISK-OFF. SPX held the 7,612.07 low but closed near it, breadth was weak and the 10Y is back near 5%; SPX needs to clear 7,660.15 with VIX below 18.87 to move to TRANSITION.
What to watch next week (PT):
- Weekend: U.S.-Iran headlines, Houthi activity, any strikes; futures reopen Sunday 3:00 PM
- Monday Oct 26: $69B 2-year note auction
- Oct 27–28: FOMC, decision Wednesday Oct 28 at 11:00 AM; Bank of Canada decision Oct 28
- Earnings: Microsoft, Alphabet and Amazon report next week; about one-third of the S&P 500 reports (Reuters)
- Iranian and Russian presidents meet in Moscow next week
Bull expectation: a quiet weekend in the Gulf, Brent eases back below $113, hyperscaler capex guidance reassures, SPX clears 7,660.15 and VIX falls below 18.87. Bear expectation: strikes resume over the weekend and Brent breaks above $117, the 10Y pushes back above 5%, SPX loses 7,612.07 and VIX rises above 20.66.
Sources: 3 K2TP briefs for 10/23/2026 (Pre-Market, Midday, Pre-Close; there is no Friday Evening Recap). Official closing and intraday prices from Yahoo Finance; oil settlements, breadth, news and data from Reuters, AP, CNBC, WSJ and FinancialJuice; Sankey from SLB's Q3 2026 release (8-K Ex. 99, SEC EDGAR); AXP figures from its Q3 2026 release (8-K Ex. 99.1). Analysis: K2TP Framework.