Market 10/22: Meta's AI capex shock sinks chips; SPX has its worst day since July as money rotates into defensives and bonds
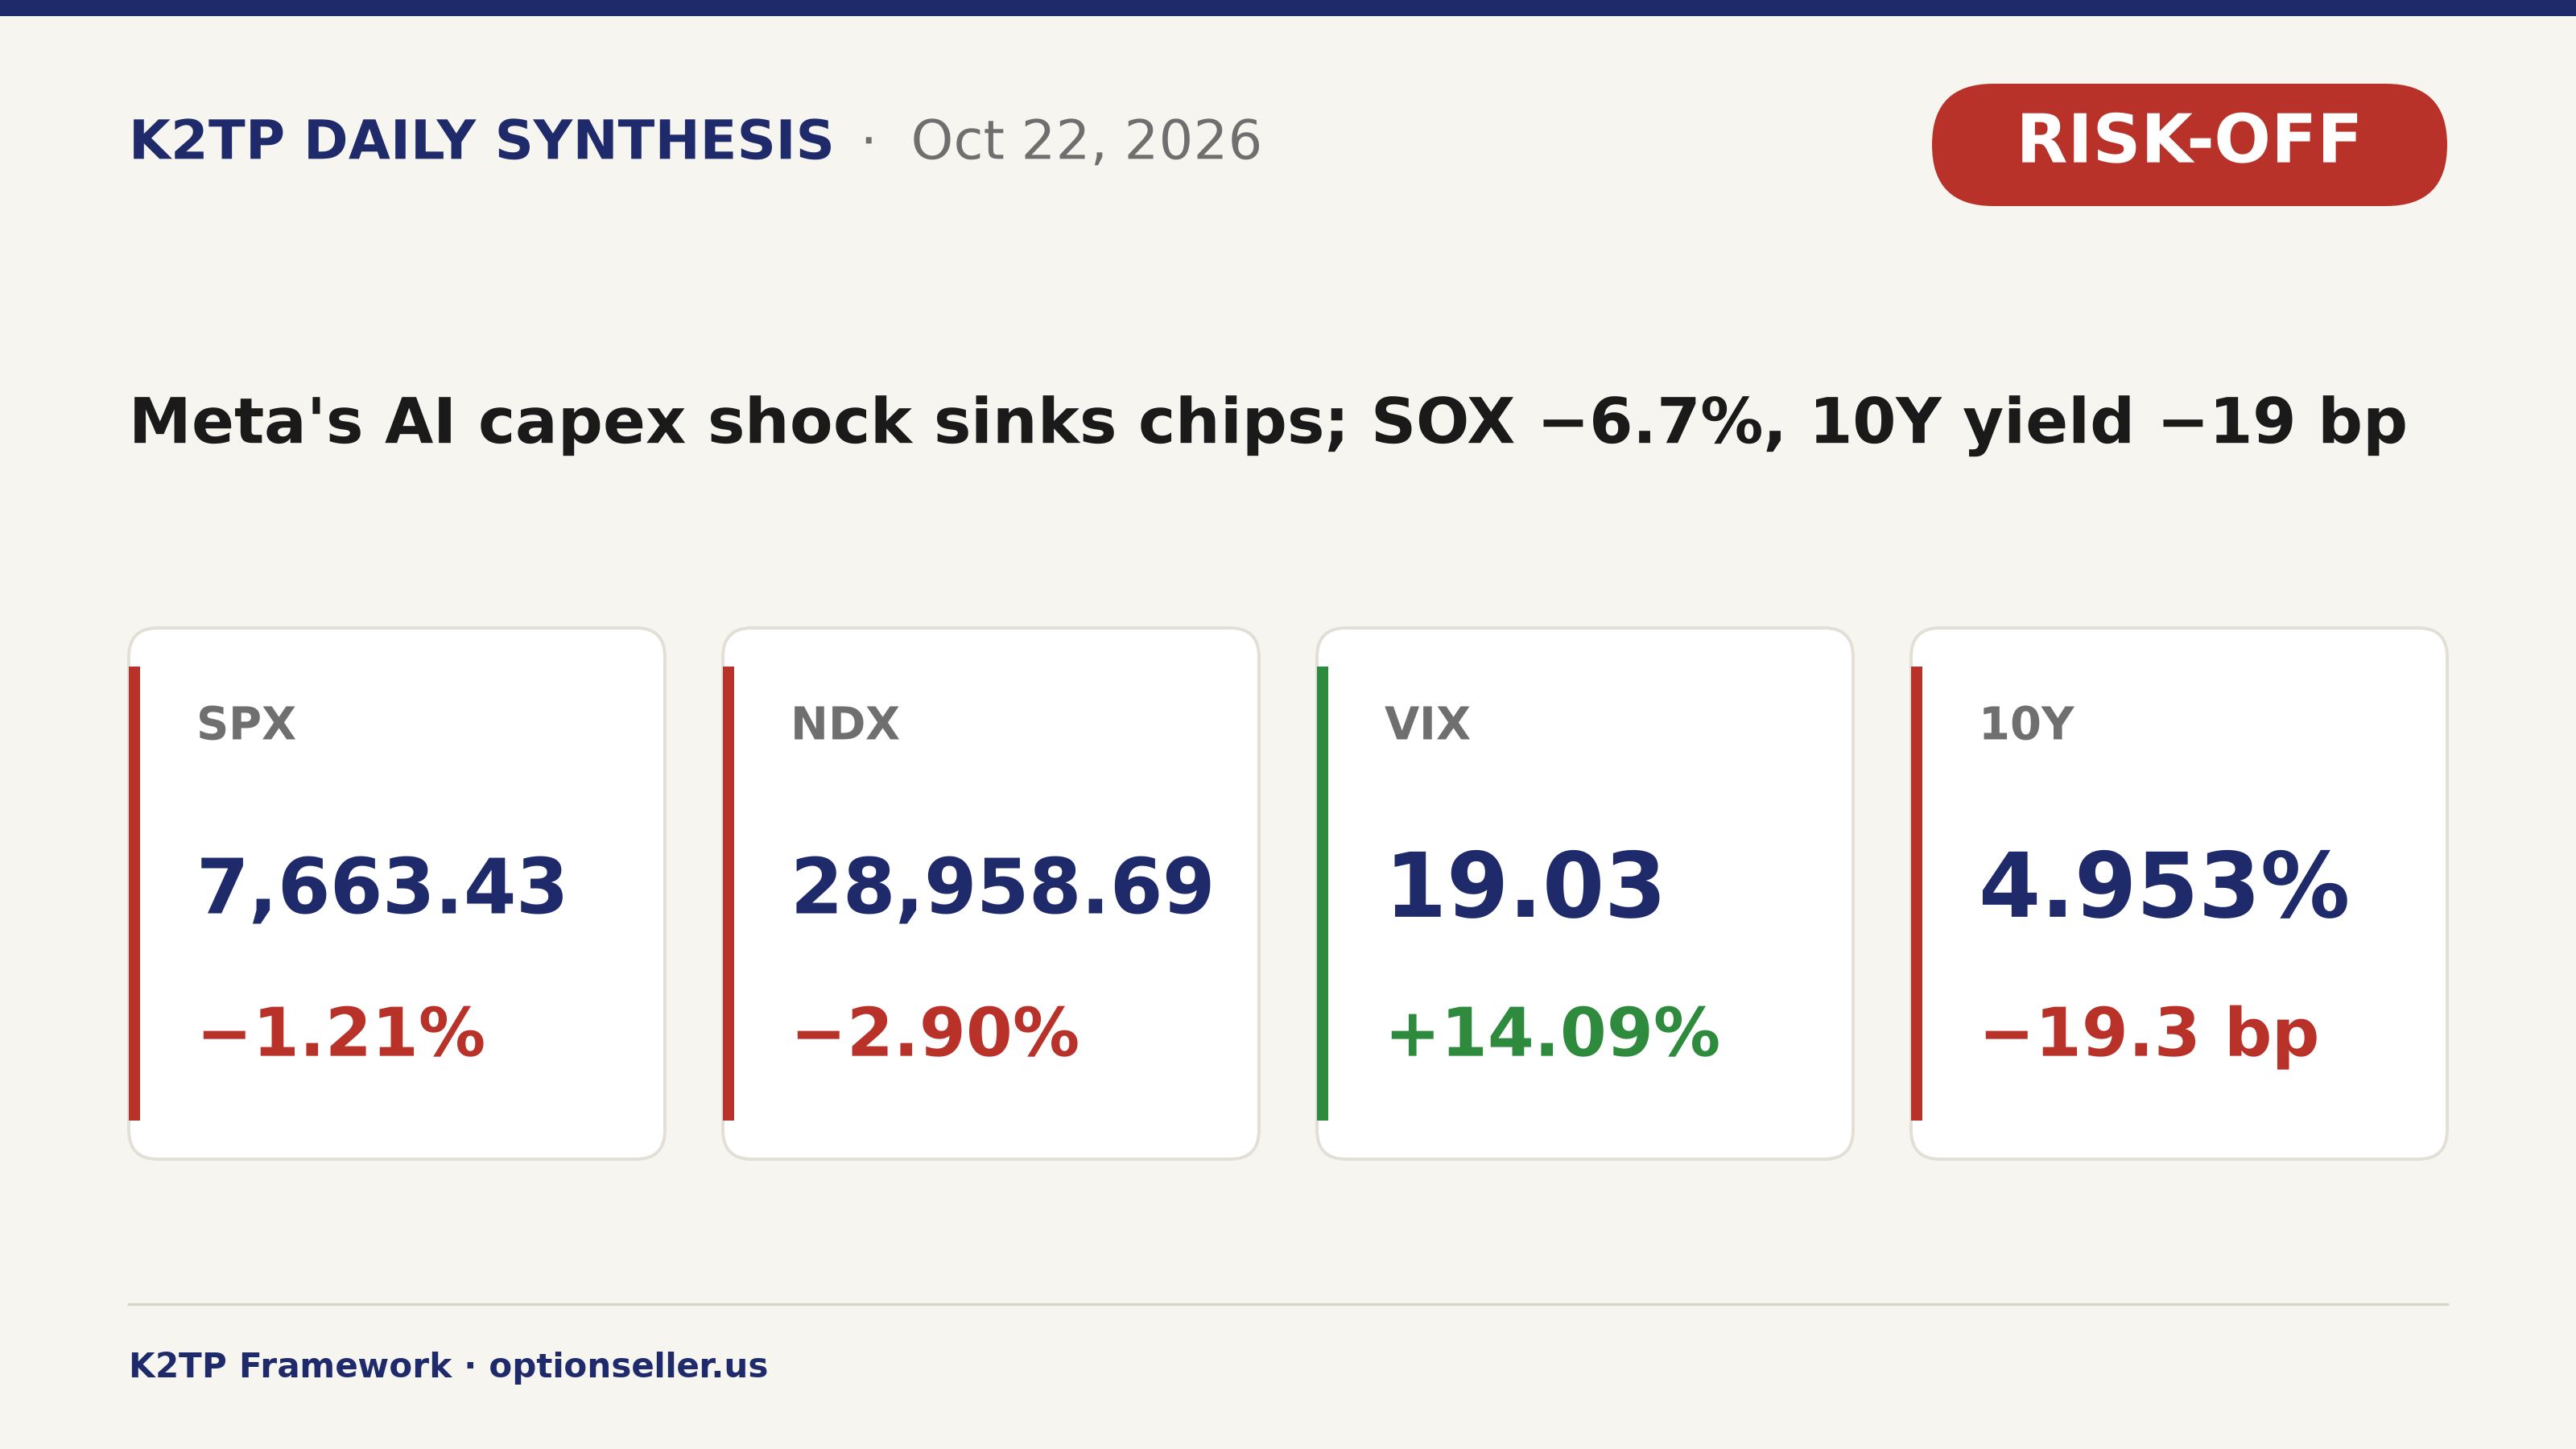
SPX −1.21%, NDX −2.90%, VIX +14.09%. SOX −6.72%, 10Y −19.3 bp, Brent at a five-month high; yet RSP +0.73% and the Dow stays green on staples, defense and financials.
KEY HEADLINES
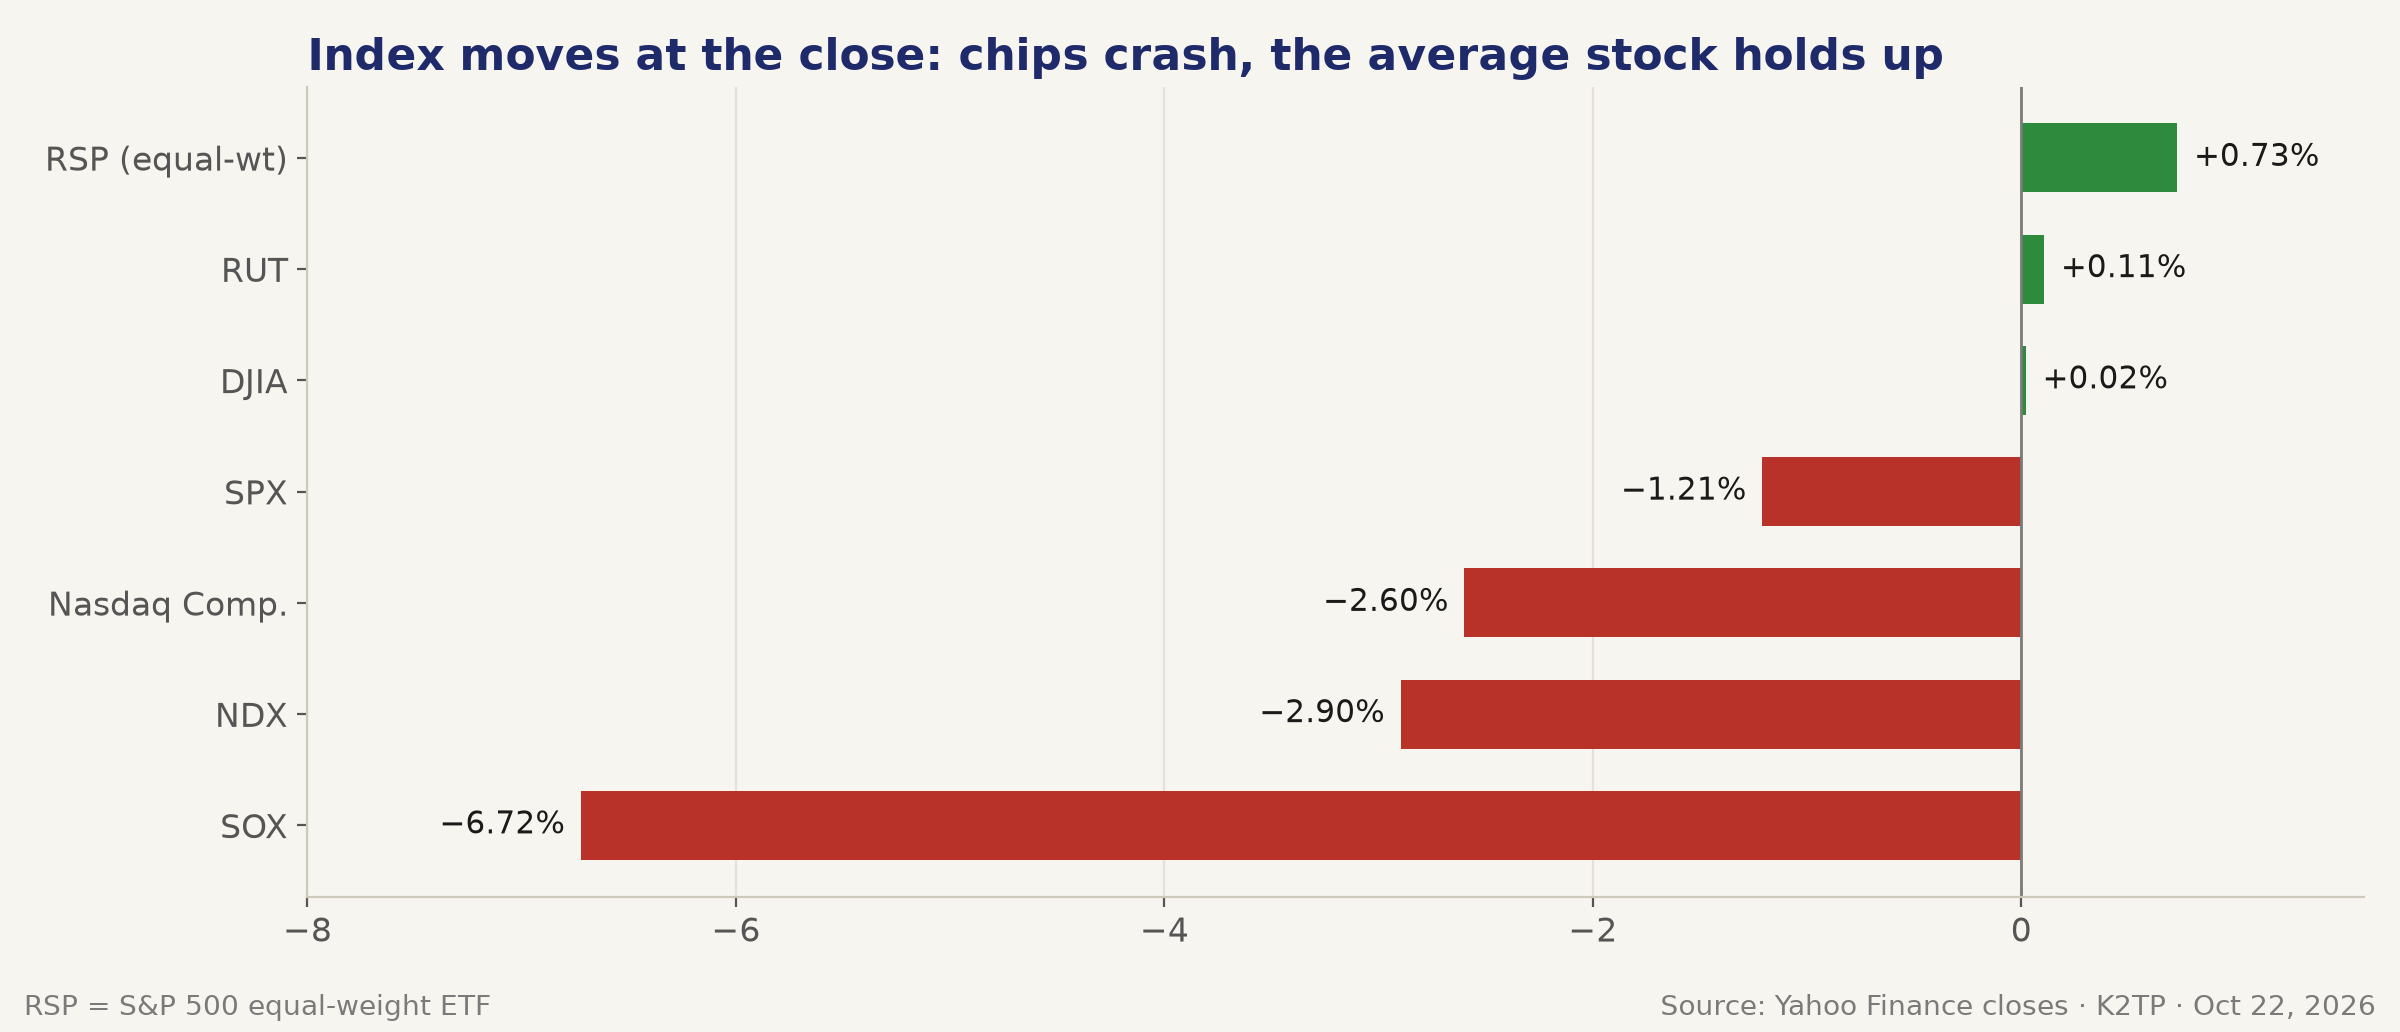
- SPX −1.21% to 7,663.43, its worst day since July; NDX −2.90%, Nasdaq Composite −2.60% (steepest since early June, Reuters); Dow +0.02%
- Meta −6.98% despite a beat: 2026 capex low end raised to $135–145B, first cash burn in more than a decade, and a plan for nonvoting Class C shares; Meta 5-year CDS hit a record 114.79 bp (Reuters)
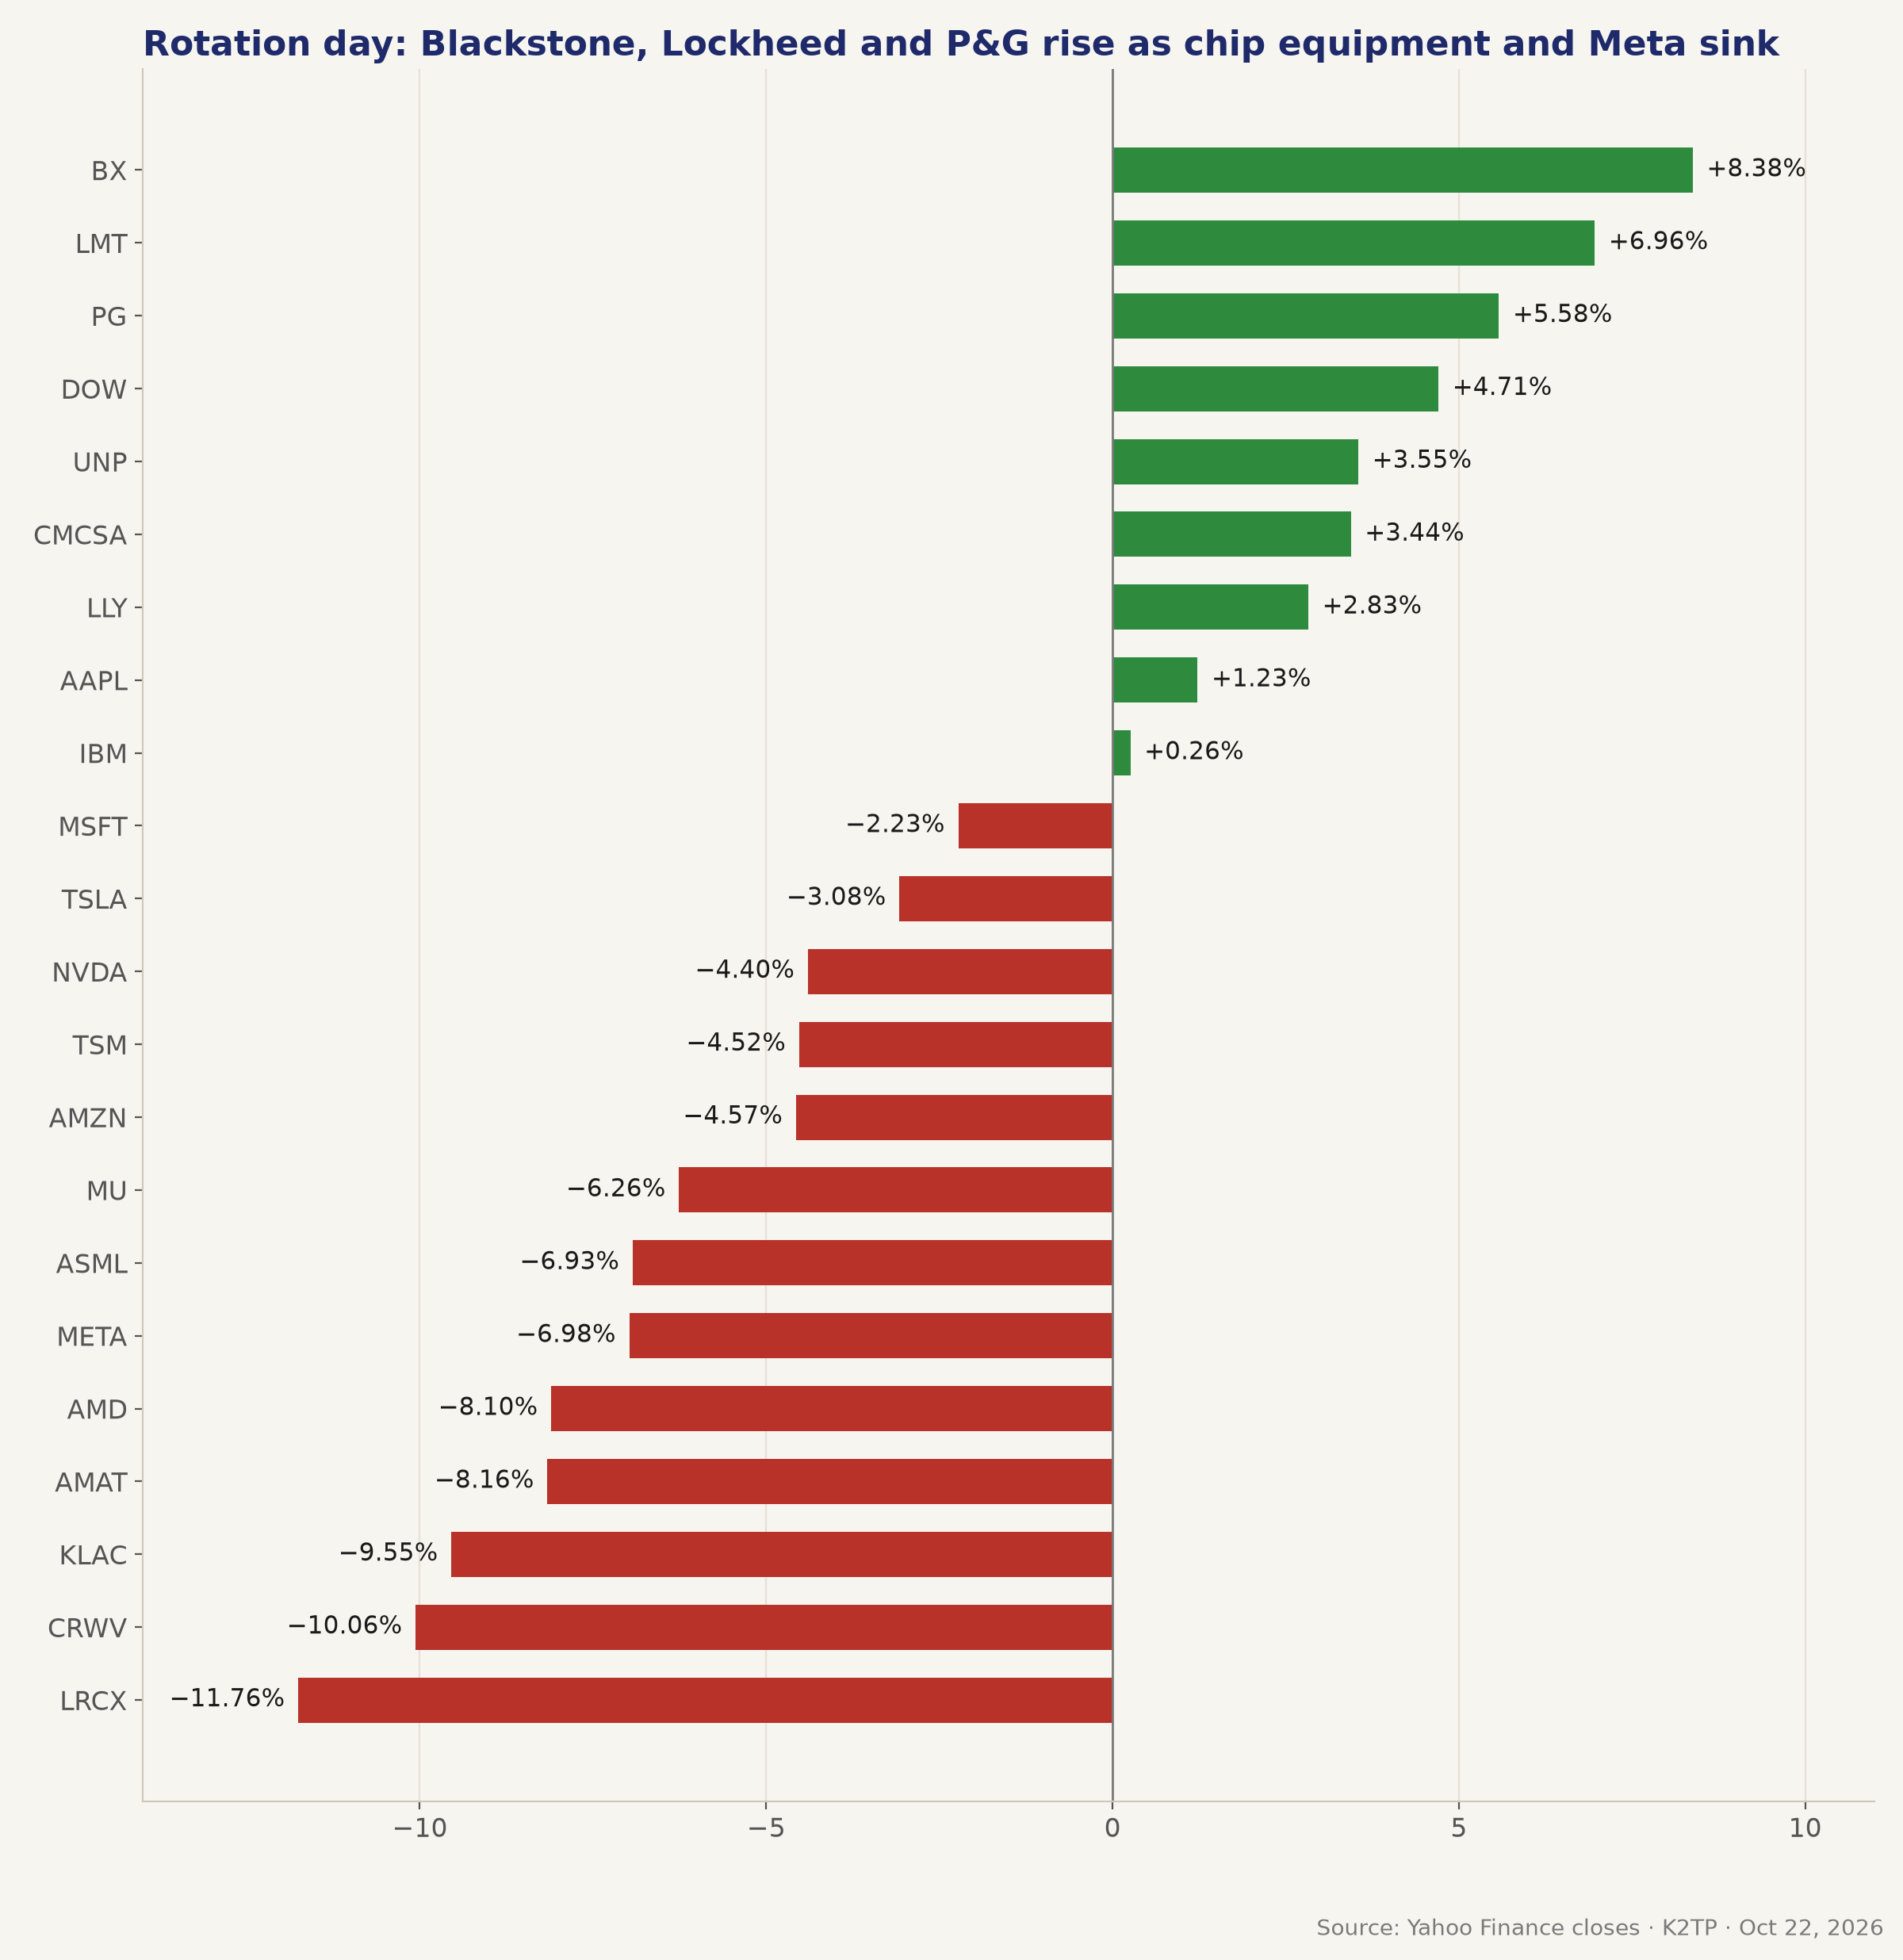
- SOX −6.72%, its biggest fall since June 23 and now more than 26% below its June 22 record: LRCX −11.76%, CRWV −10.06%, KLAC −9.55%, AMD −8.10%, INTC −8.04%
- Sharp rotation: XLP +3.31%, XLU +2.07%; Blackstone +8.38%, Lockheed Martin +6.96%, P&G +5.58% on results; RSP +0.73% beat SPX by about 1.9 points
- Haven bid in Treasurys: 10Y −19.3 bp to 4.953%, the biggest drop since March 10, 2023 (Reuters); 5Y −20.4 bp; 5s30s steepens to 51.9 bp
- Brent settled $113.17 (+4%), a five-month high, after Houthi attacks in Saudi Arabia; after the close Trump invoked the Defense Production Act (DPA) for petroleum capacity
- VIX 19.03 (+14.09%), touched 20.31 intraday; VVIX 107.94 (+14.16%)
- SPX hit 7,637.36 at 12:02 PM PT, then recovered 26.07 points into the close on a $2.93B buy-side MOC imbalance
- After hours: Western Digital −6.54% despite a beat and raise; Deckers −6.99%, Bloom Energy −6.86%, Comfort Systems −5.92%
- Regime: 🔴 RISK-OFF into Friday; tonight (about 7 PM PT) ES −0.17%, NQ −0.08%, Brent $114.14
META REIGNITES THE AI CAPEX SCARE
- Meta's Q3 beat (revenue $64.60B vs $63.33B expected, EPS $3.83 vs $3.57; Q4 guide $73–76B), but shares went from +2.12% after hours Wednesday to a steep loss 🔴
- The low end of 2026 capex rose by $5B to $135–145B; Reuters notes the first cash burn in more than a decade
- To fund AI, Meta created nonvoting Class C shares that could raise "hundreds of billions" over years; a filing showed about $825B of additional AI infrastructure commitments (K2TP Midday brief)
- Meta 5-year CDS hit a record 114.79 bp: AI cost worries have spread to credit (Reuters)
- META closed $648.85 (−6.98%), losing about $114B in market value; AMZN −4.57%, GOOGL −3.15%, MSFT −2.23%; AAPL +1.23% was the only megacap gainer
- Nvidia's Jensen Huang told CNBC neocloud demand is "off the charts" but capital is scarce; CoreWeave (CRWV) −10.06%, SpaceX (SPCX) −9.14%
→ The market no longer rewards beats that come with higher capex and new funding. The question is now who pays for the AI buildout, and that hits the whole supply chain.
CHIPS COLLAPSE: SOX −6.72%
- SOX −6.72% to 10,731.98, the biggest fall since June 23; more than 26% below its June 22 record close but still +51.5% YTD (Reuters) 🔴
- Equipment led the decline: Lam Research (LRCX) −11.76% after citing supply-chain constraints in guidance, KLA (KLAC) −9.55%, Applied Materials (AMAT) −8.16%, ASML −6.93%
- Chips and memory: AMD −8.10%, INTC −8.04%, MU −6.26%, TSM −4.52%, NVDA −4.40%, AVGO −4.31%; Sandisk and Marvell also fell more than 8% (Reuters)
- AI infrastructure: Dell −6.78%, WDC −6.43%, SMCI −5.20%, ORCL −2.78%
- This was a second straight day of selling: LRCX was already deep in the red premarket after reporting Wednesday evening; XLK −3.29% was the worst sector
→ The AI complex is no longer supporting SPX in the short term. When equipment makers and capex beneficiaries sell off together, the pressure comes from positioning and the cost of capital, not from one report.
MONEY ROTATES INTO DEFENSIVES AND VALUE
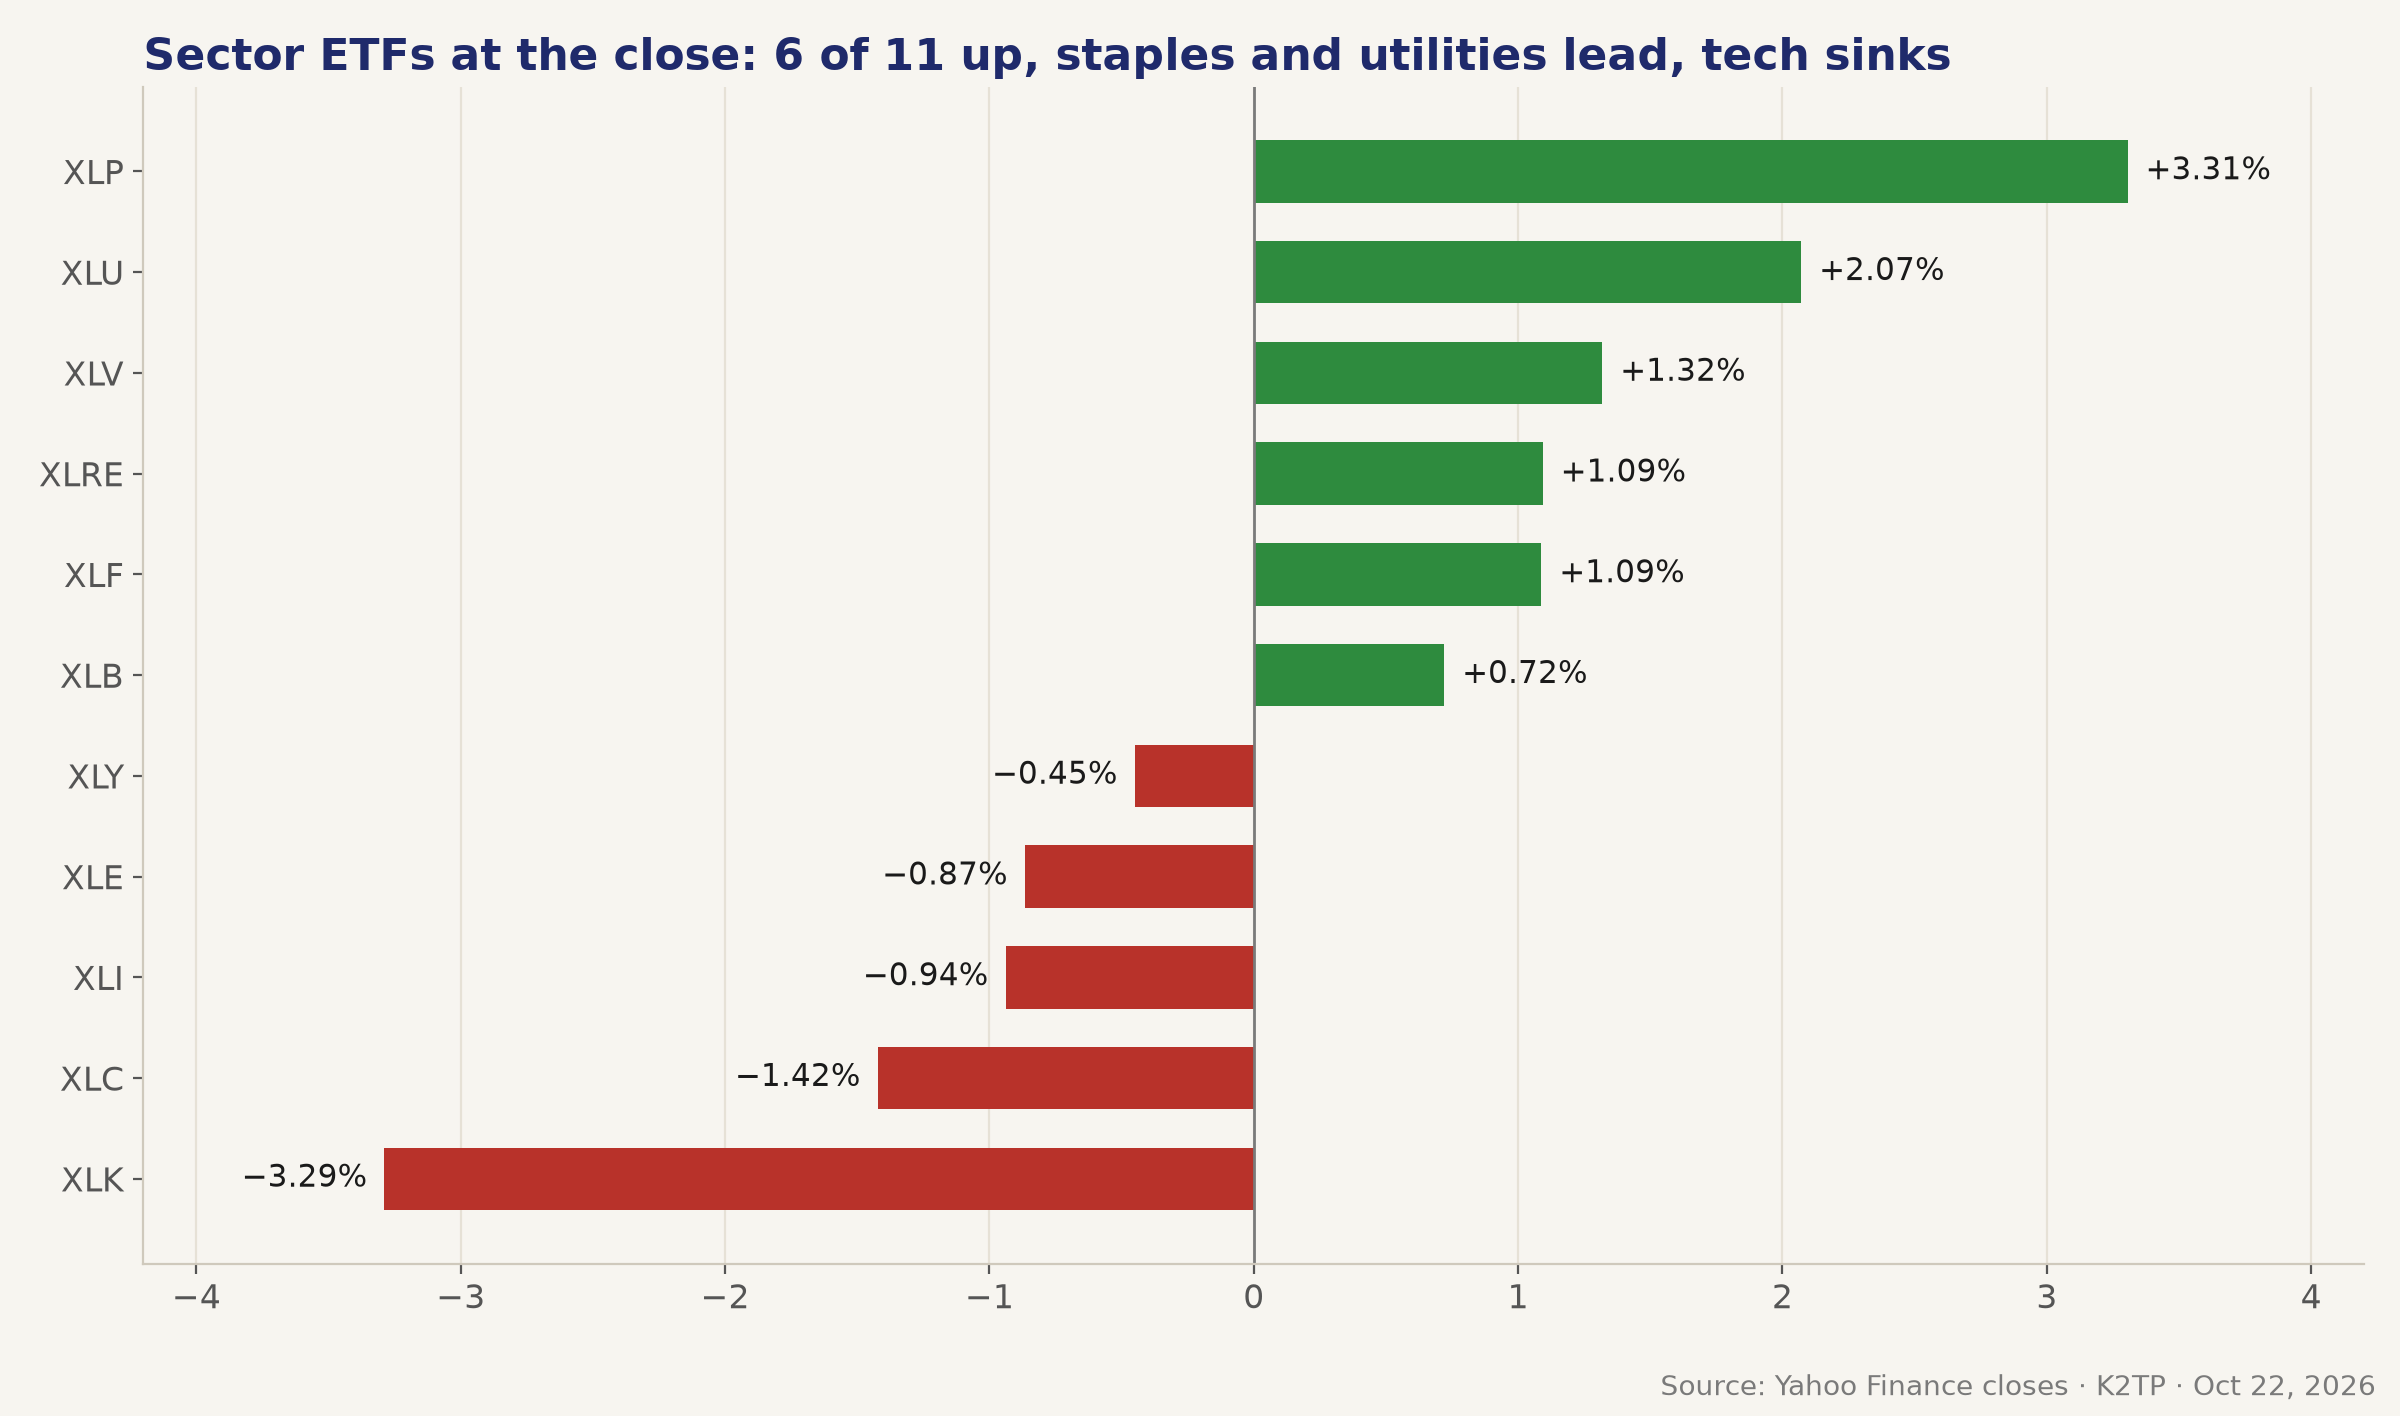
- 6 of 11 sector ETFs rose: XLP +3.31%, XLU +2.07%, XLV +1.32%, XLF +1.09%, XLRE +1.09%, XLB +0.72%; decliners: XLK −3.29%, XLC −1.42%, XLI −0.94%, XLE −0.87%, XLY −0.45%
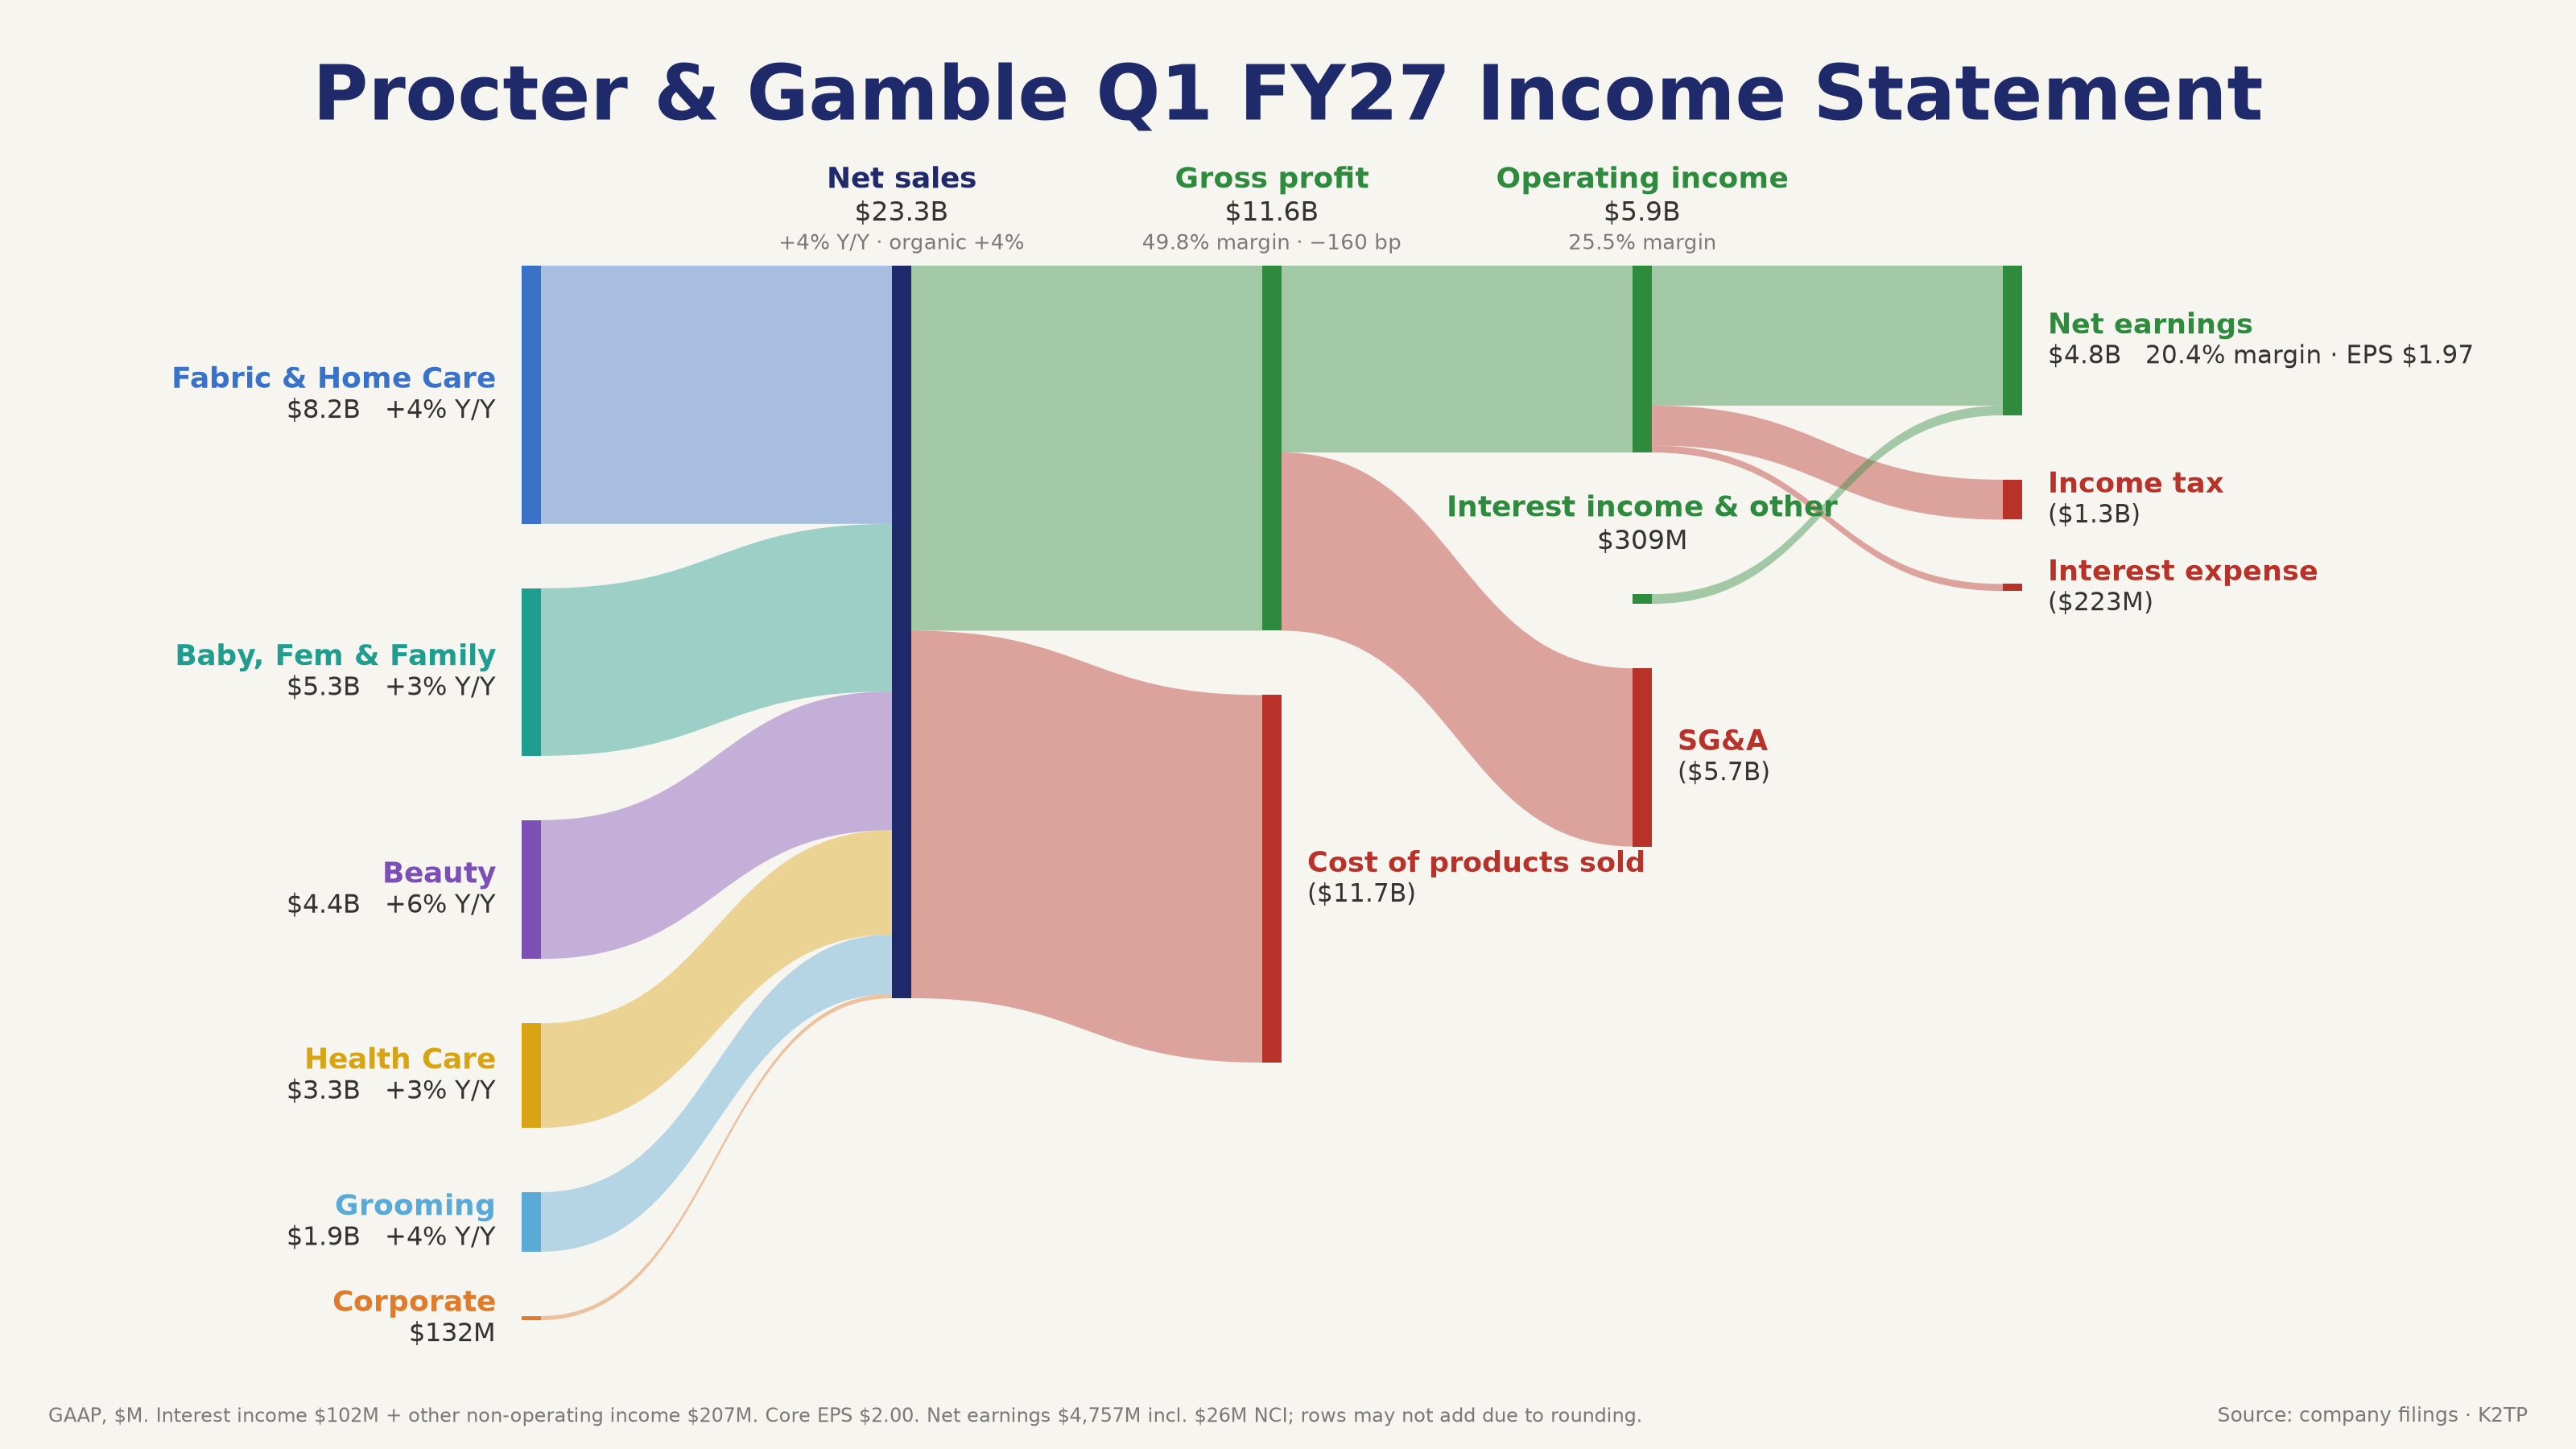
- P&G (PG) +5.58% (8-K): sales $23.28B (+4%, organic +4%) vs $22.82B expected; core EPS $2.00 vs $1.89; all five segments grew, Beauty +6% 🟢
- But gross margin fell 160 bp to 49.8%; P&G now sees about $1.4B after tax of FY27 commodity headwinds and kept its core EPS guide at $6.89–7.11
- Lockheed Martin (LMT) +6.96%: adjusted EPS $9.77 vs $7.25, revenue $20.70B vs $20.35B, raised full-year outlook (EPS $30.35–30.75) 🟢
- Blackstone (BX) +8.38% after calling wider credit spreads on AI-related debt an opportunity (Reuters); Union Pacific (UNP) +3.55% despite flagging fuel costs; Dow Inc. +4.71%, Comcast +3.44%, American Airlines +2.94%
- Spotify +11.1% (Reuters); IBM +0.26% after recovering from a $240.00 low (premarket −6.94%)
- 83% of the 111 S&P 500 companies that have reported Q3 beat estimates (LSEG via Reuters)
→ Money is not leaving the market, it is leaving AI. Defensives, defense and financials hold up the Dow and RSP, but cannot lift the cap-weighted index when its largest names fall together.
TREASURYS RALLY HARD AS A HAVEN
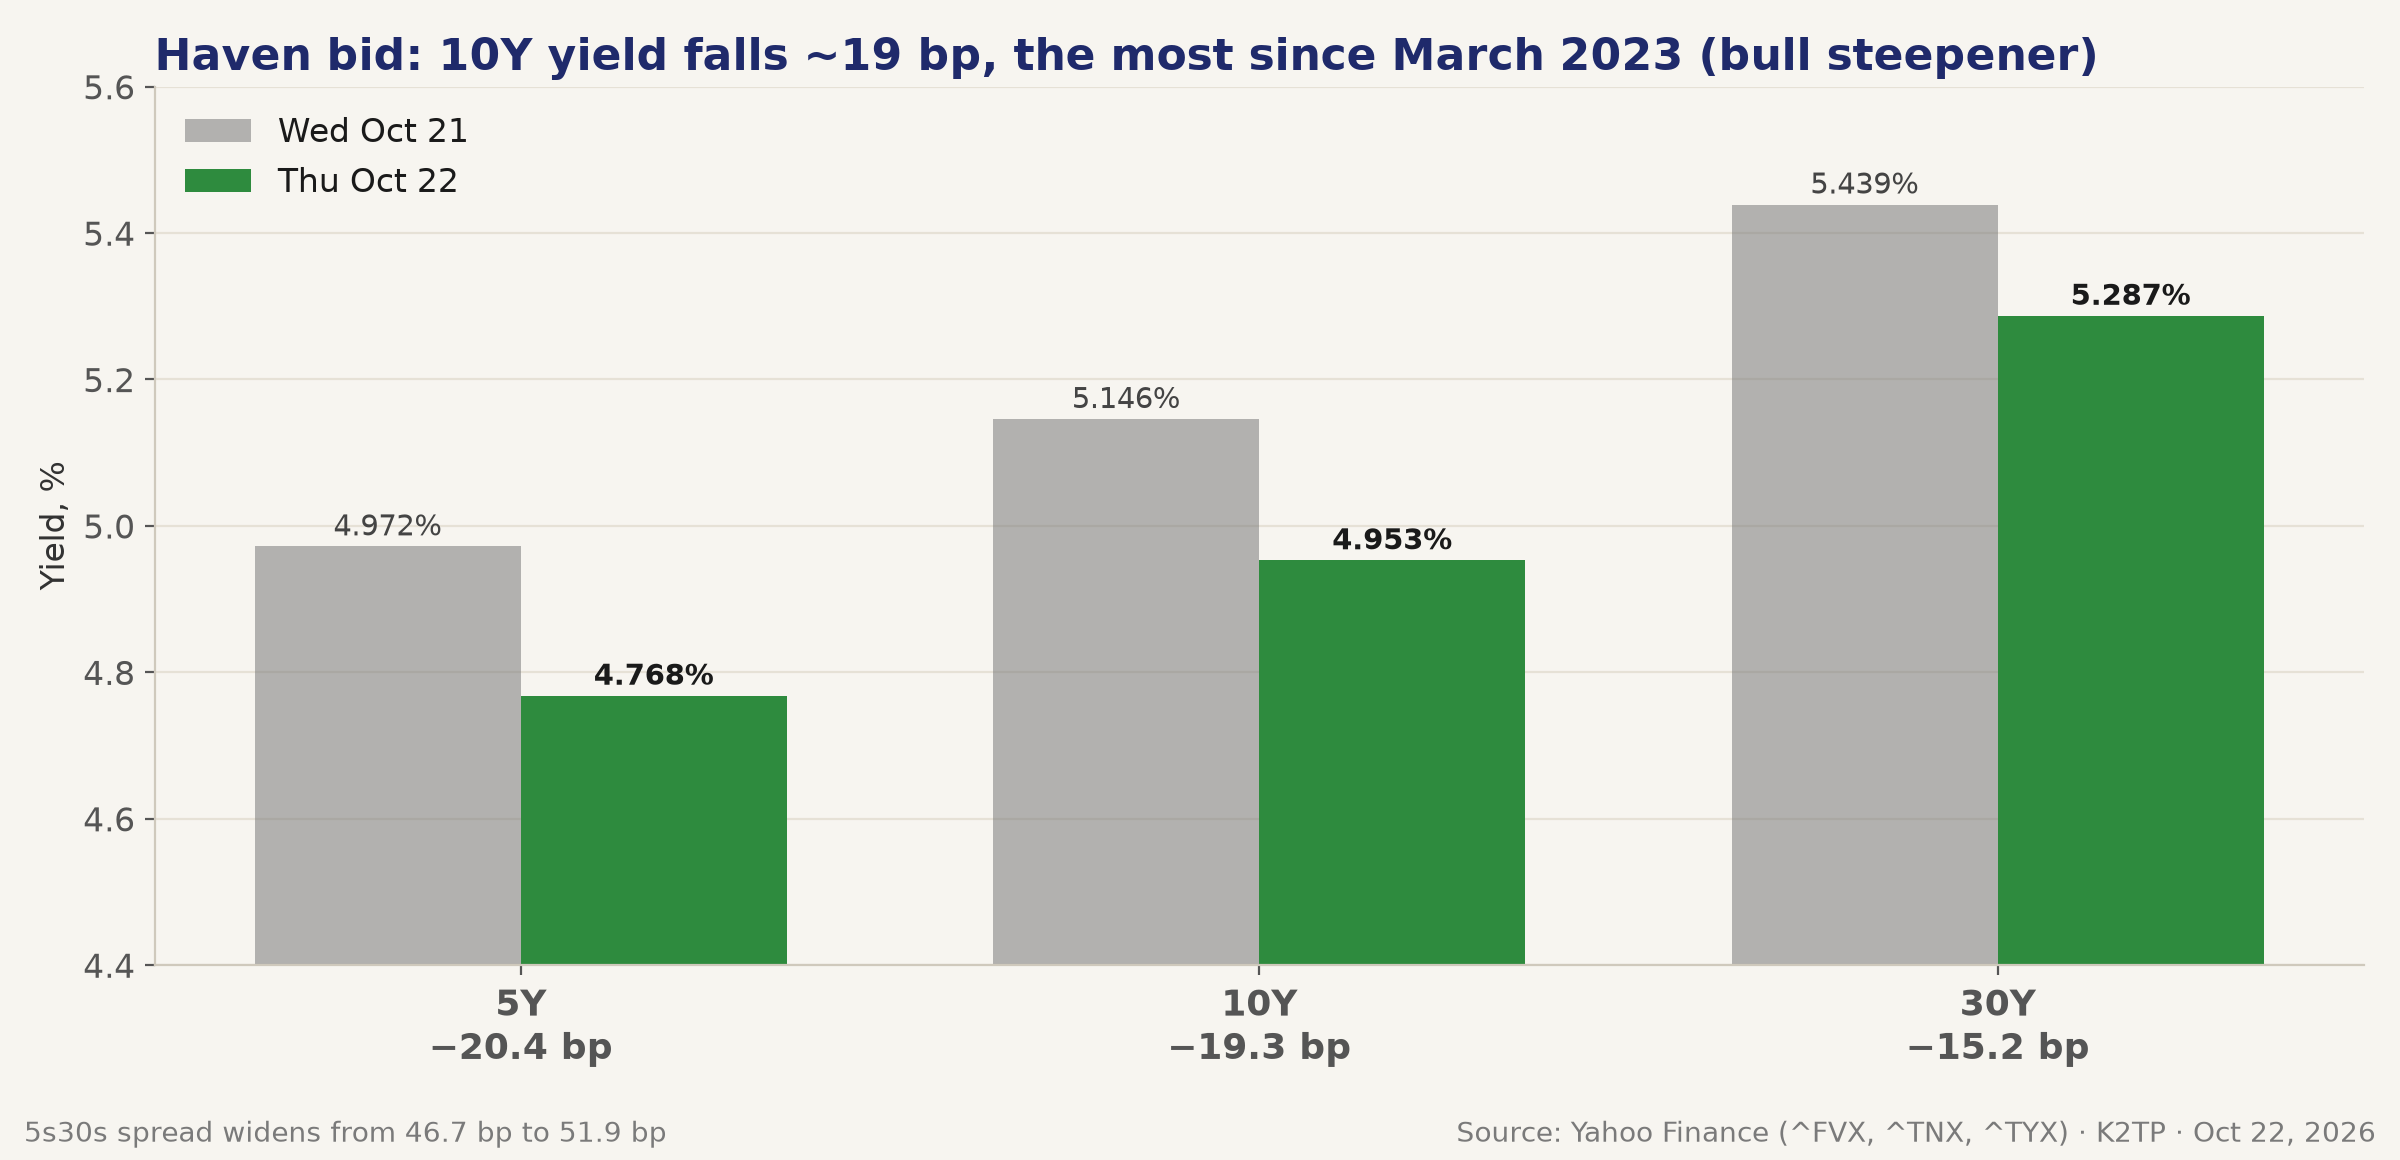
- Closing yields: 10Y 4.953% (−19.3 bp, range 4.939–5.054%), 5Y 4.768% (−20.4 bp), 30Y 5.287% (−15.2 bp); the 10Y broke below 5% for the first time in nearly a month (WSJ) 🟢
- 5s30s steepened from 46.7 bp to 51.9 bp: a bull steepener led by the belly
- Data: initial jobless claims 194K vs 200K expected, continuing claims 1.728M; Kansas City Fed manufacturing 16 (from 20); September Leading Economic Index flat at 99.6 vs −0.2% expected (Conference Board, Seeking Alpha)
- Auctions: 5-year TIPS stopped at 2.367% with a 0.7 bp tail and bid-to-cover 2.41; 4-week bill 3.945% (previous 4.000%)
- The Fed is in its blackout before the Oct 27–28 FOMC; markets still price some chance of a 25 bp hike by year-end (Reuters) but no longer fully price it (FinancialJuice via the Pre-Close brief); no fresh CME FedWatch reading
- Gold and BTC missed the haven bid: gold fell more than 2% during the session (Pre-Close brief), and USD/JPY hit a one-month low of 156.53 tonight
→ This is fear buying, not a growth signal. Lower yields help XLRE, XLU and small caps, but with Brent above $113, falling yields alone are not enough to re-rate tech.
OIL HITS A FIVE-MONTH HIGH ON THE GULF
- Brent settled $113.17 (+4%), a five-month high; December WTI $99.47 (+2.39%) 🔴
- Drivers: Houthi attacks in Saudi Arabia (a drone hit Dammam's King Fahd airport on Wednesday, one killed and eight injured) and a New York Times report on US-Israeli plans for renewed strikes on Iran
- Two-way headlines: Trump said Iran is "making up fake hits, mines" to drive up oil; Qatar's PM and Rubio discussed easing tensions; Rubio reaffirmed the US commitment to freedom of navigation through Hormuz
- After the close: Trump invoked the DPA for petroleum capacity; tonight the Saudi-led coalition said it destroyed a Houthi ballistic missile fired at Riyadh
- Tonight (about 7 PM PT, Yahoo): Brent $114.14 (+0.86%), WTI $100.45 (+0.99%)
- Energy stocks did not follow oil: XLE −0.87%, Valero −2.40%
→ Oil is setting risk sentiment and inflation risk before the FOMC. Brent above $113 makes it hard for the Fed to lean dovish even with yields lower.
SPX DROPS, HOLDS ITS LOW, THEN RECOVERS ON THE MOC
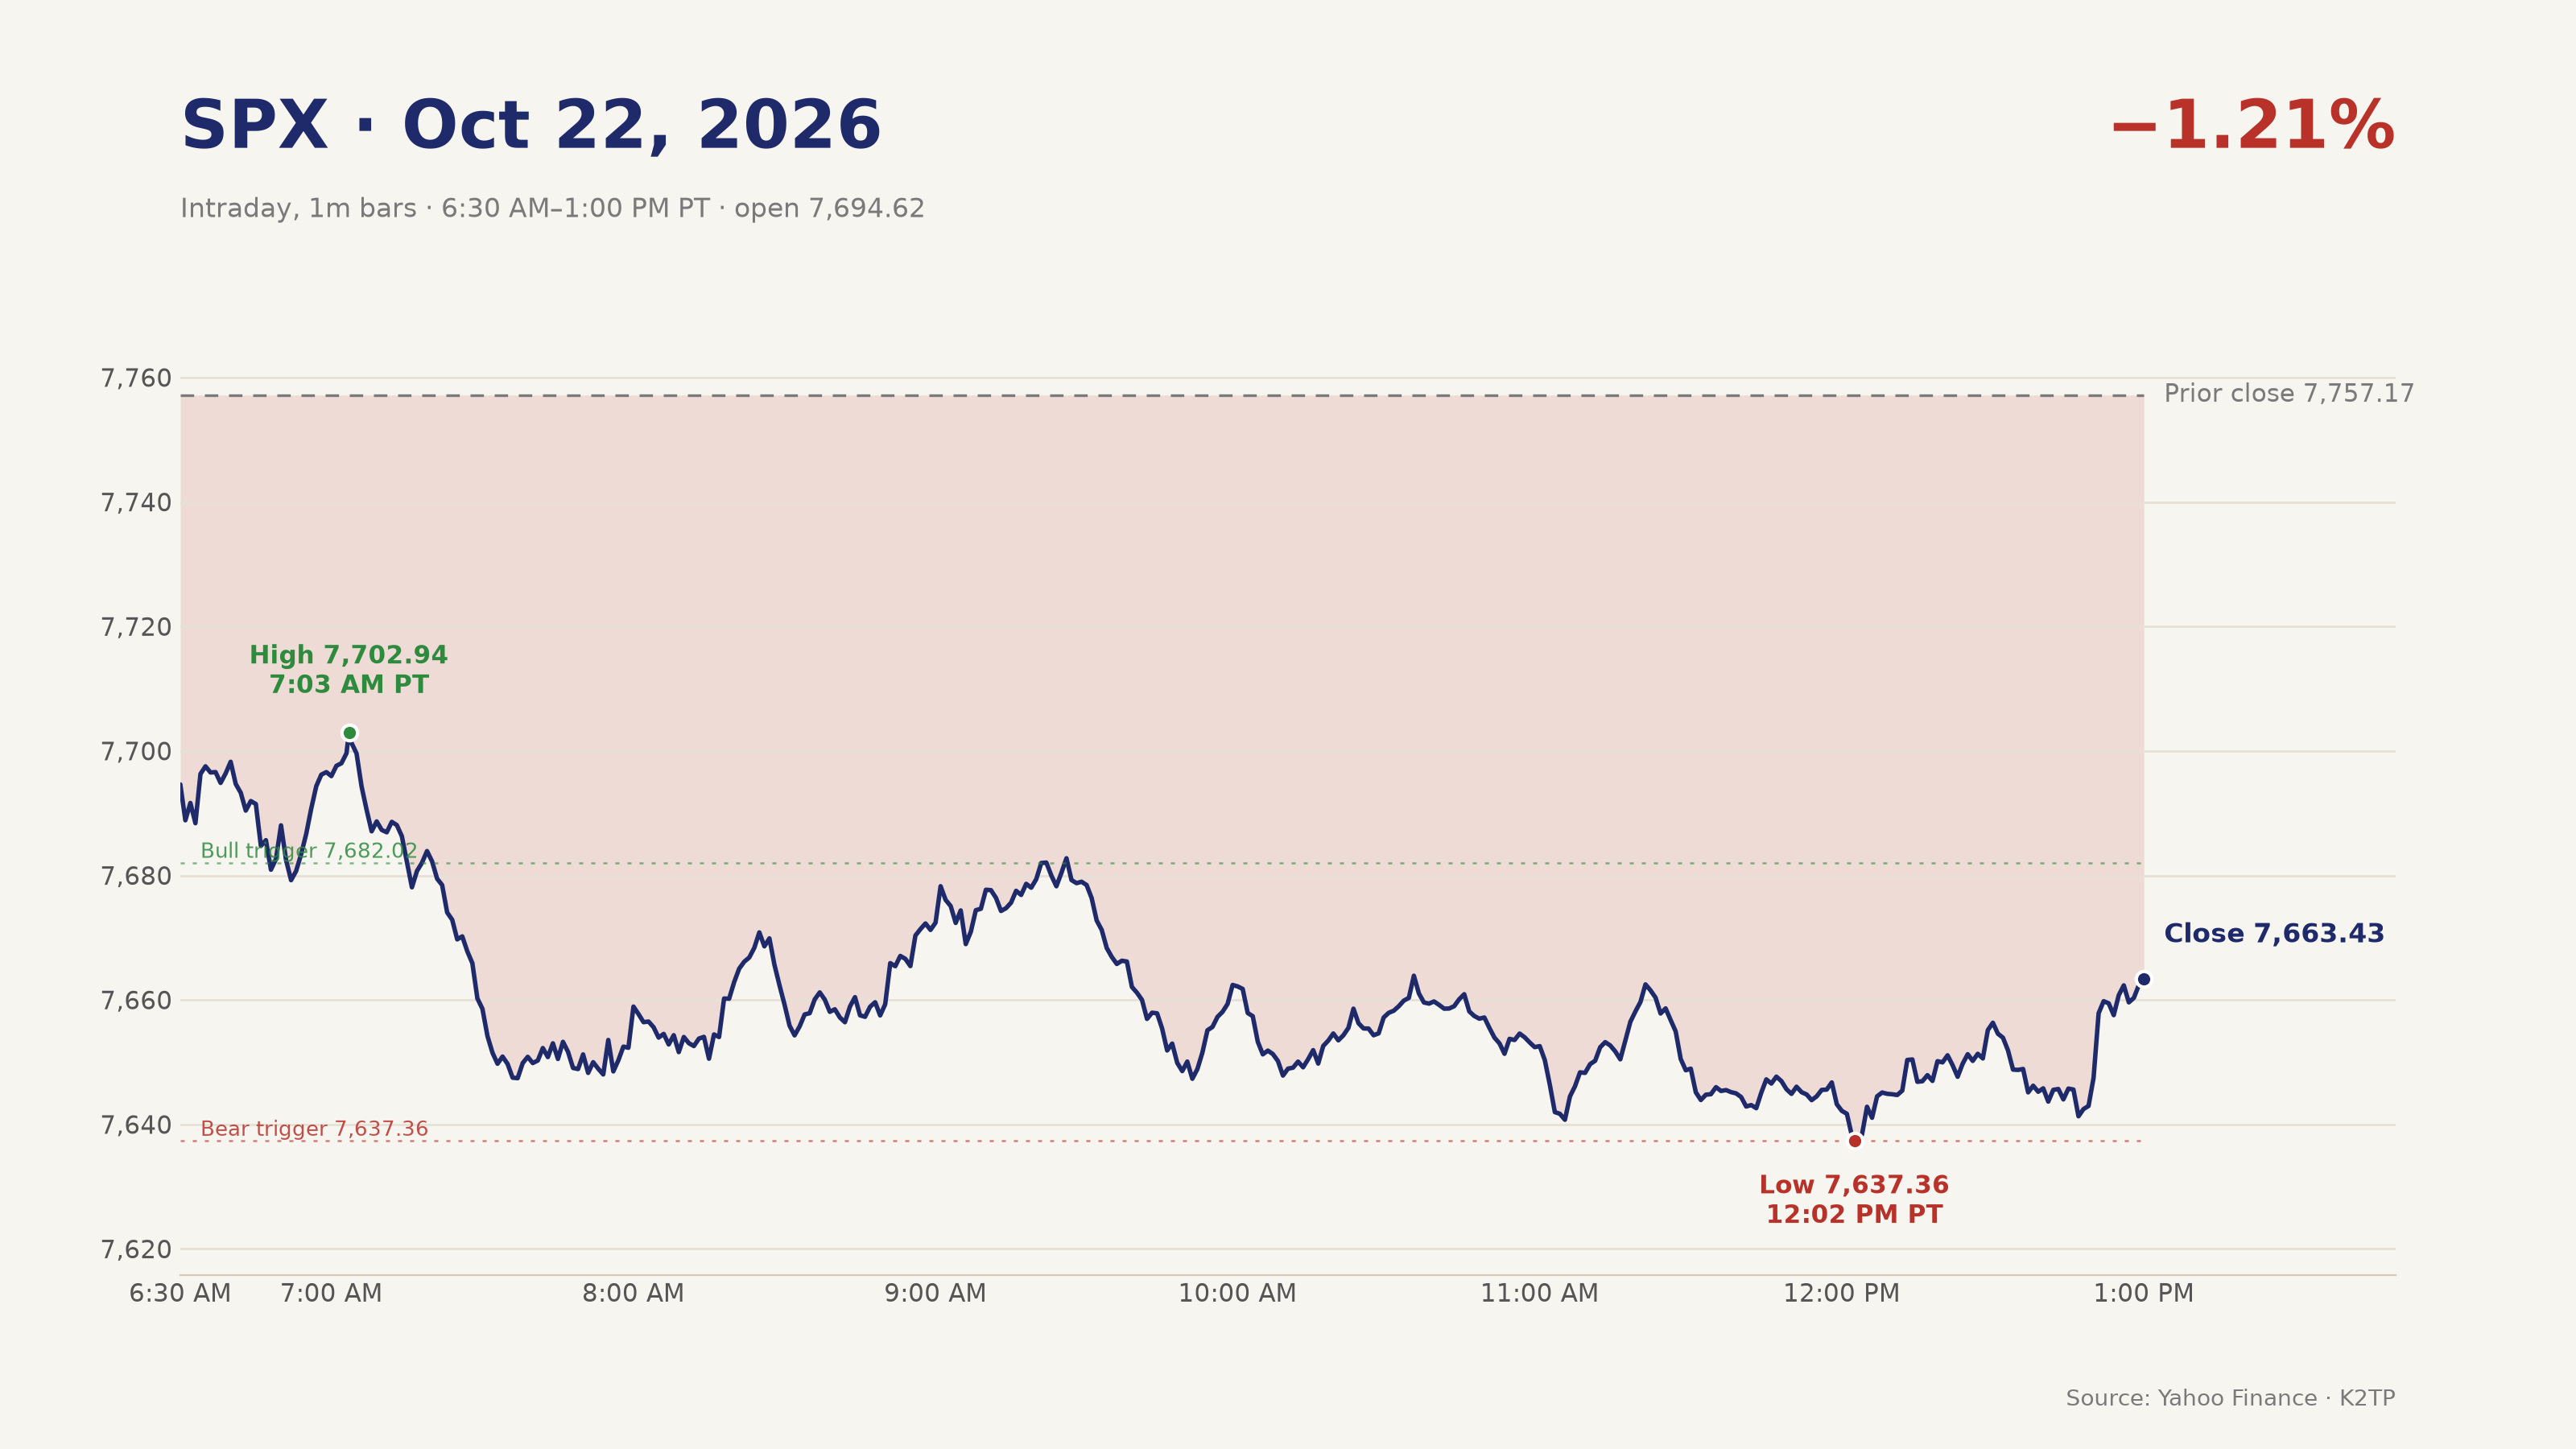
- Opened 7,694.62 and peaked at 7,702.94 at 7:03 AM PT, still 54 points below Wednesday's close
- Fell to 7,646.05 at 7:35 AM PT, bounced to 7,683.13 at 9:20 AM PT (the Midday brief recorded 7,682.02 with VIX 18.43)
- Drifted lower in the afternoon: 7,639.86 at 11:04 AM PT, session low 7,637.36 at 12:02 PM PT; the Pre-Close brief had 7,645.43 with VIX 20.00
- A $2.93B buy-side MOC imbalance lifted SPX from 7,645.60 at 12:45 PM PT to a close of 7,663.43 (−93.74 points), 26.07 points above the low
- The Pre-Close Bear trigger (SPX below 7,637.36 with VIX above 20.06) did not fire: VIX touched 20.31, but SPX held its low and VIX closed at 19.03. The Bull trigger (above 7,682.02 with VIX below 19.37) was only half met
→ The index did not panic: the 7,637.36 low held and buyers showed up late. But every intraday bounce was sold below 7,703, so the short-term bias stays lower.
AFTER HOURS: WESTERN DIGITAL BEATS BUT STILL FALLS
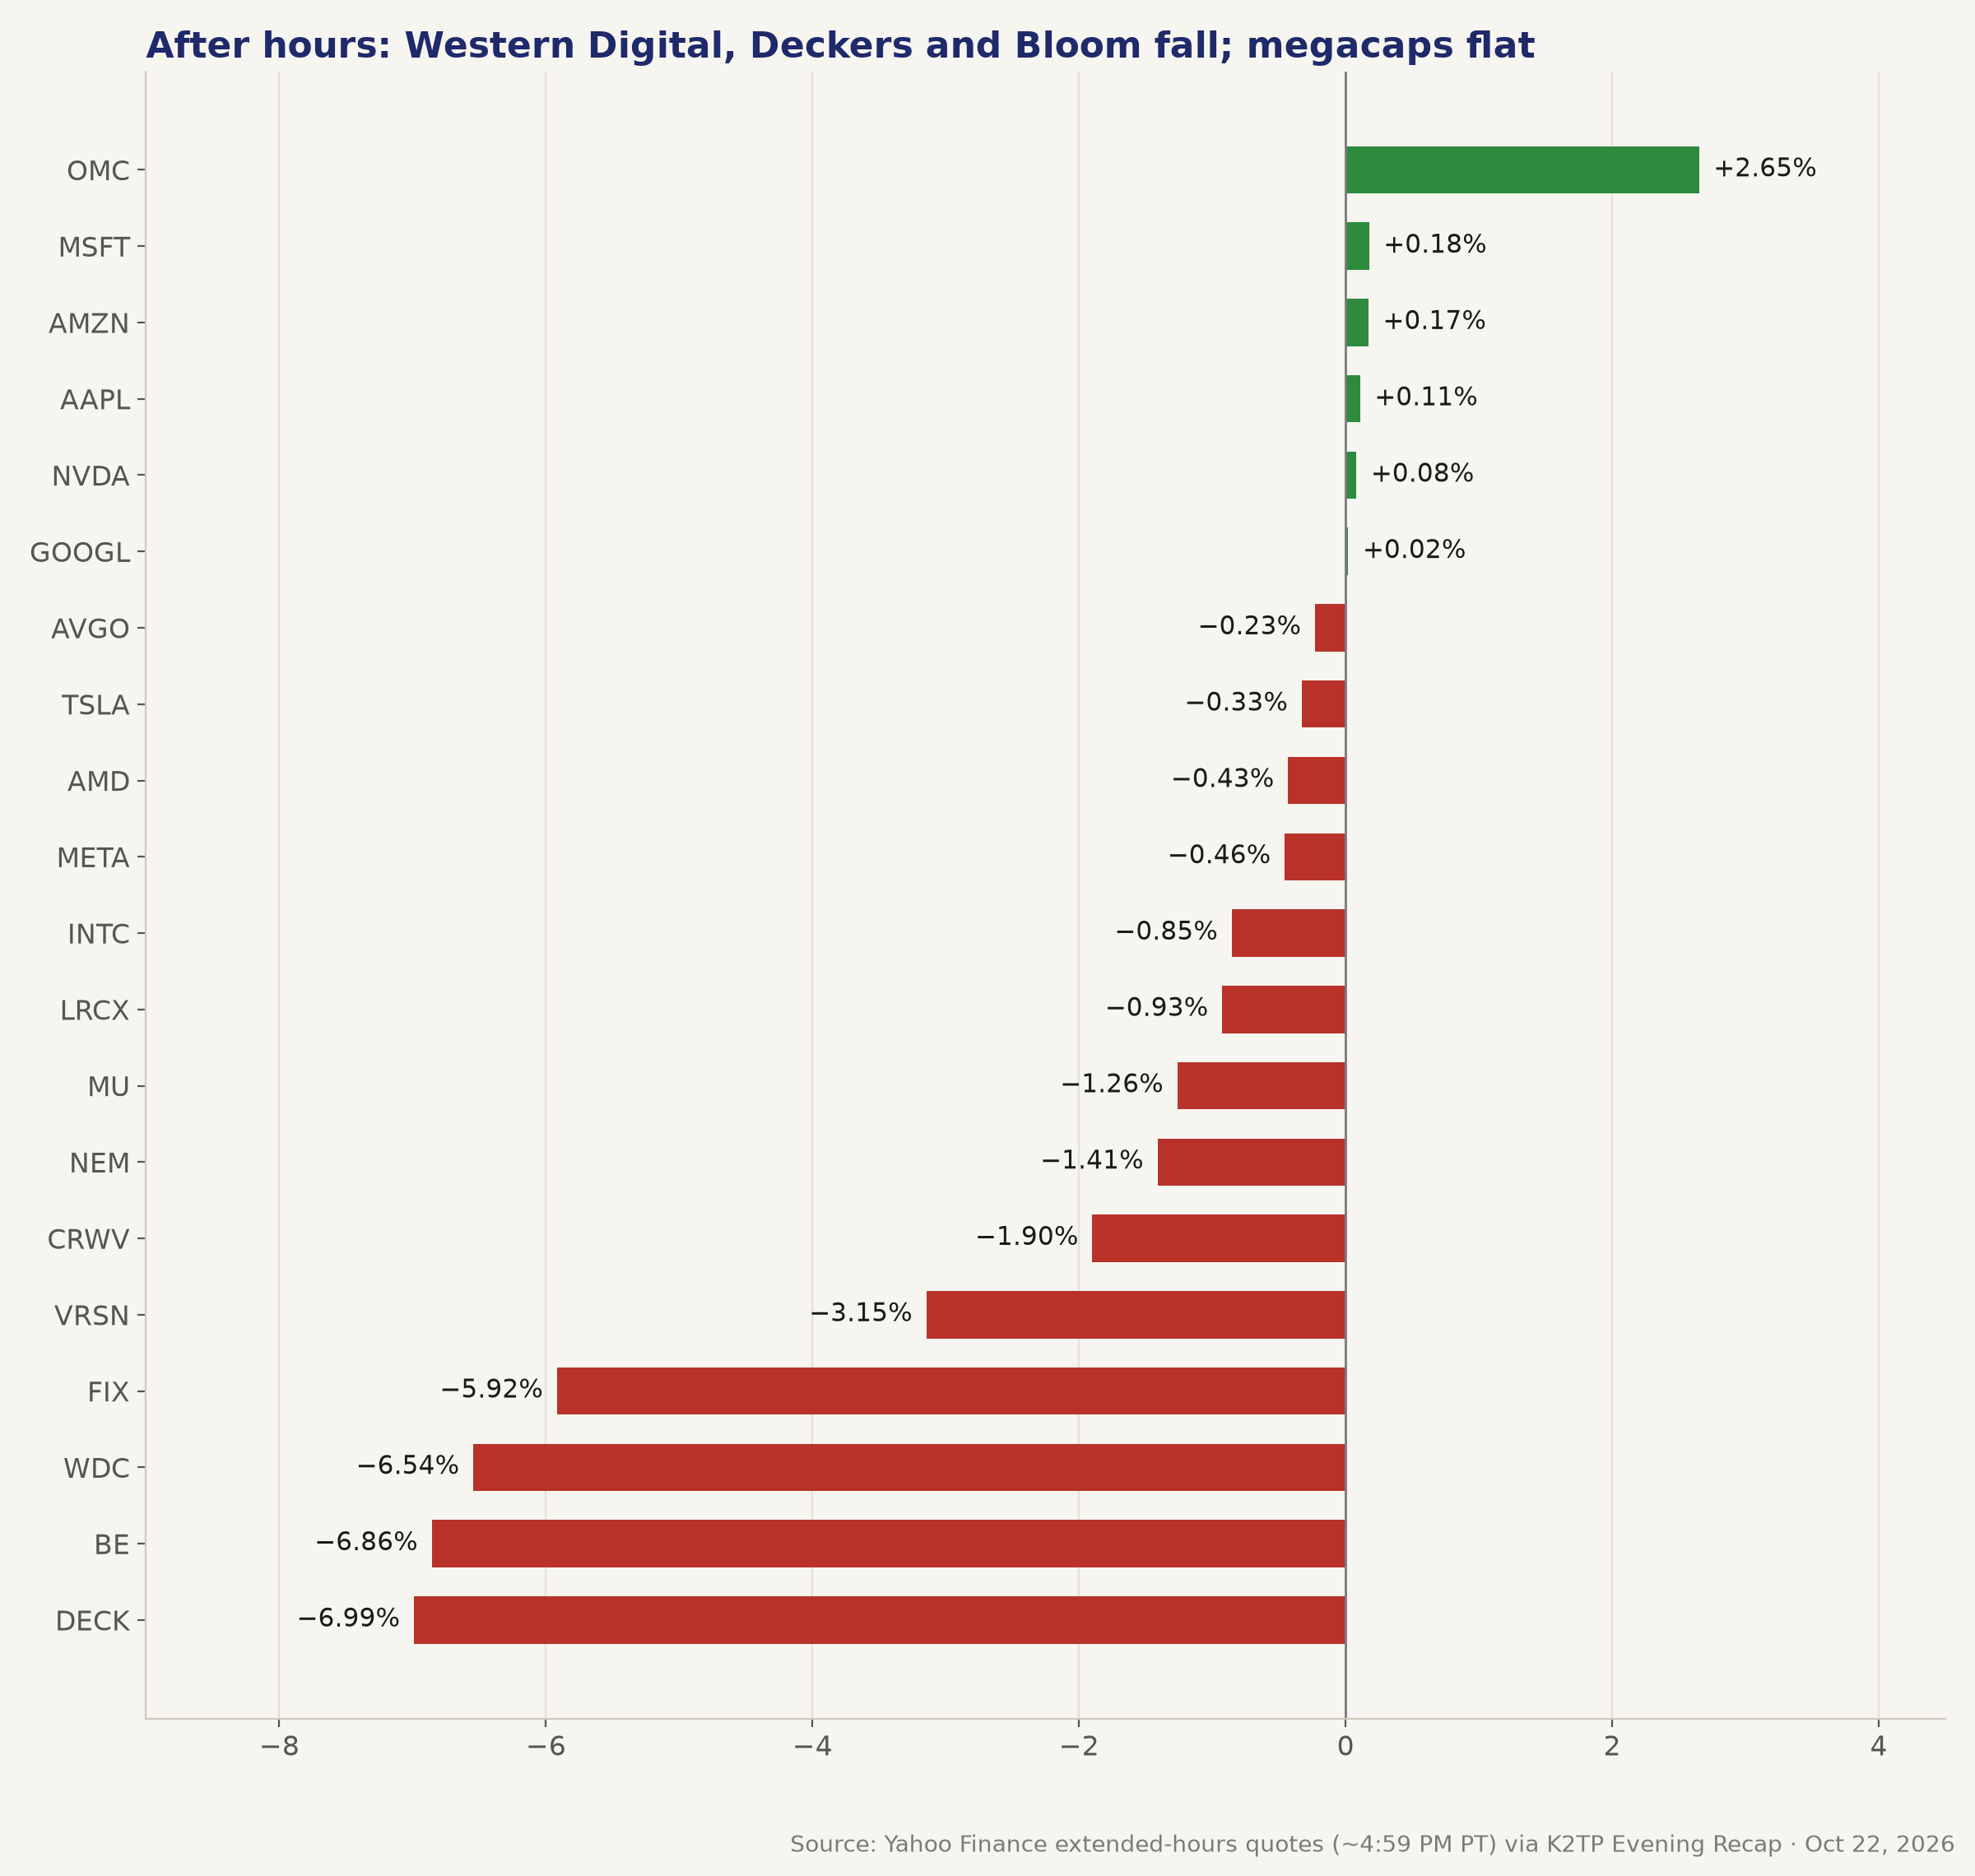
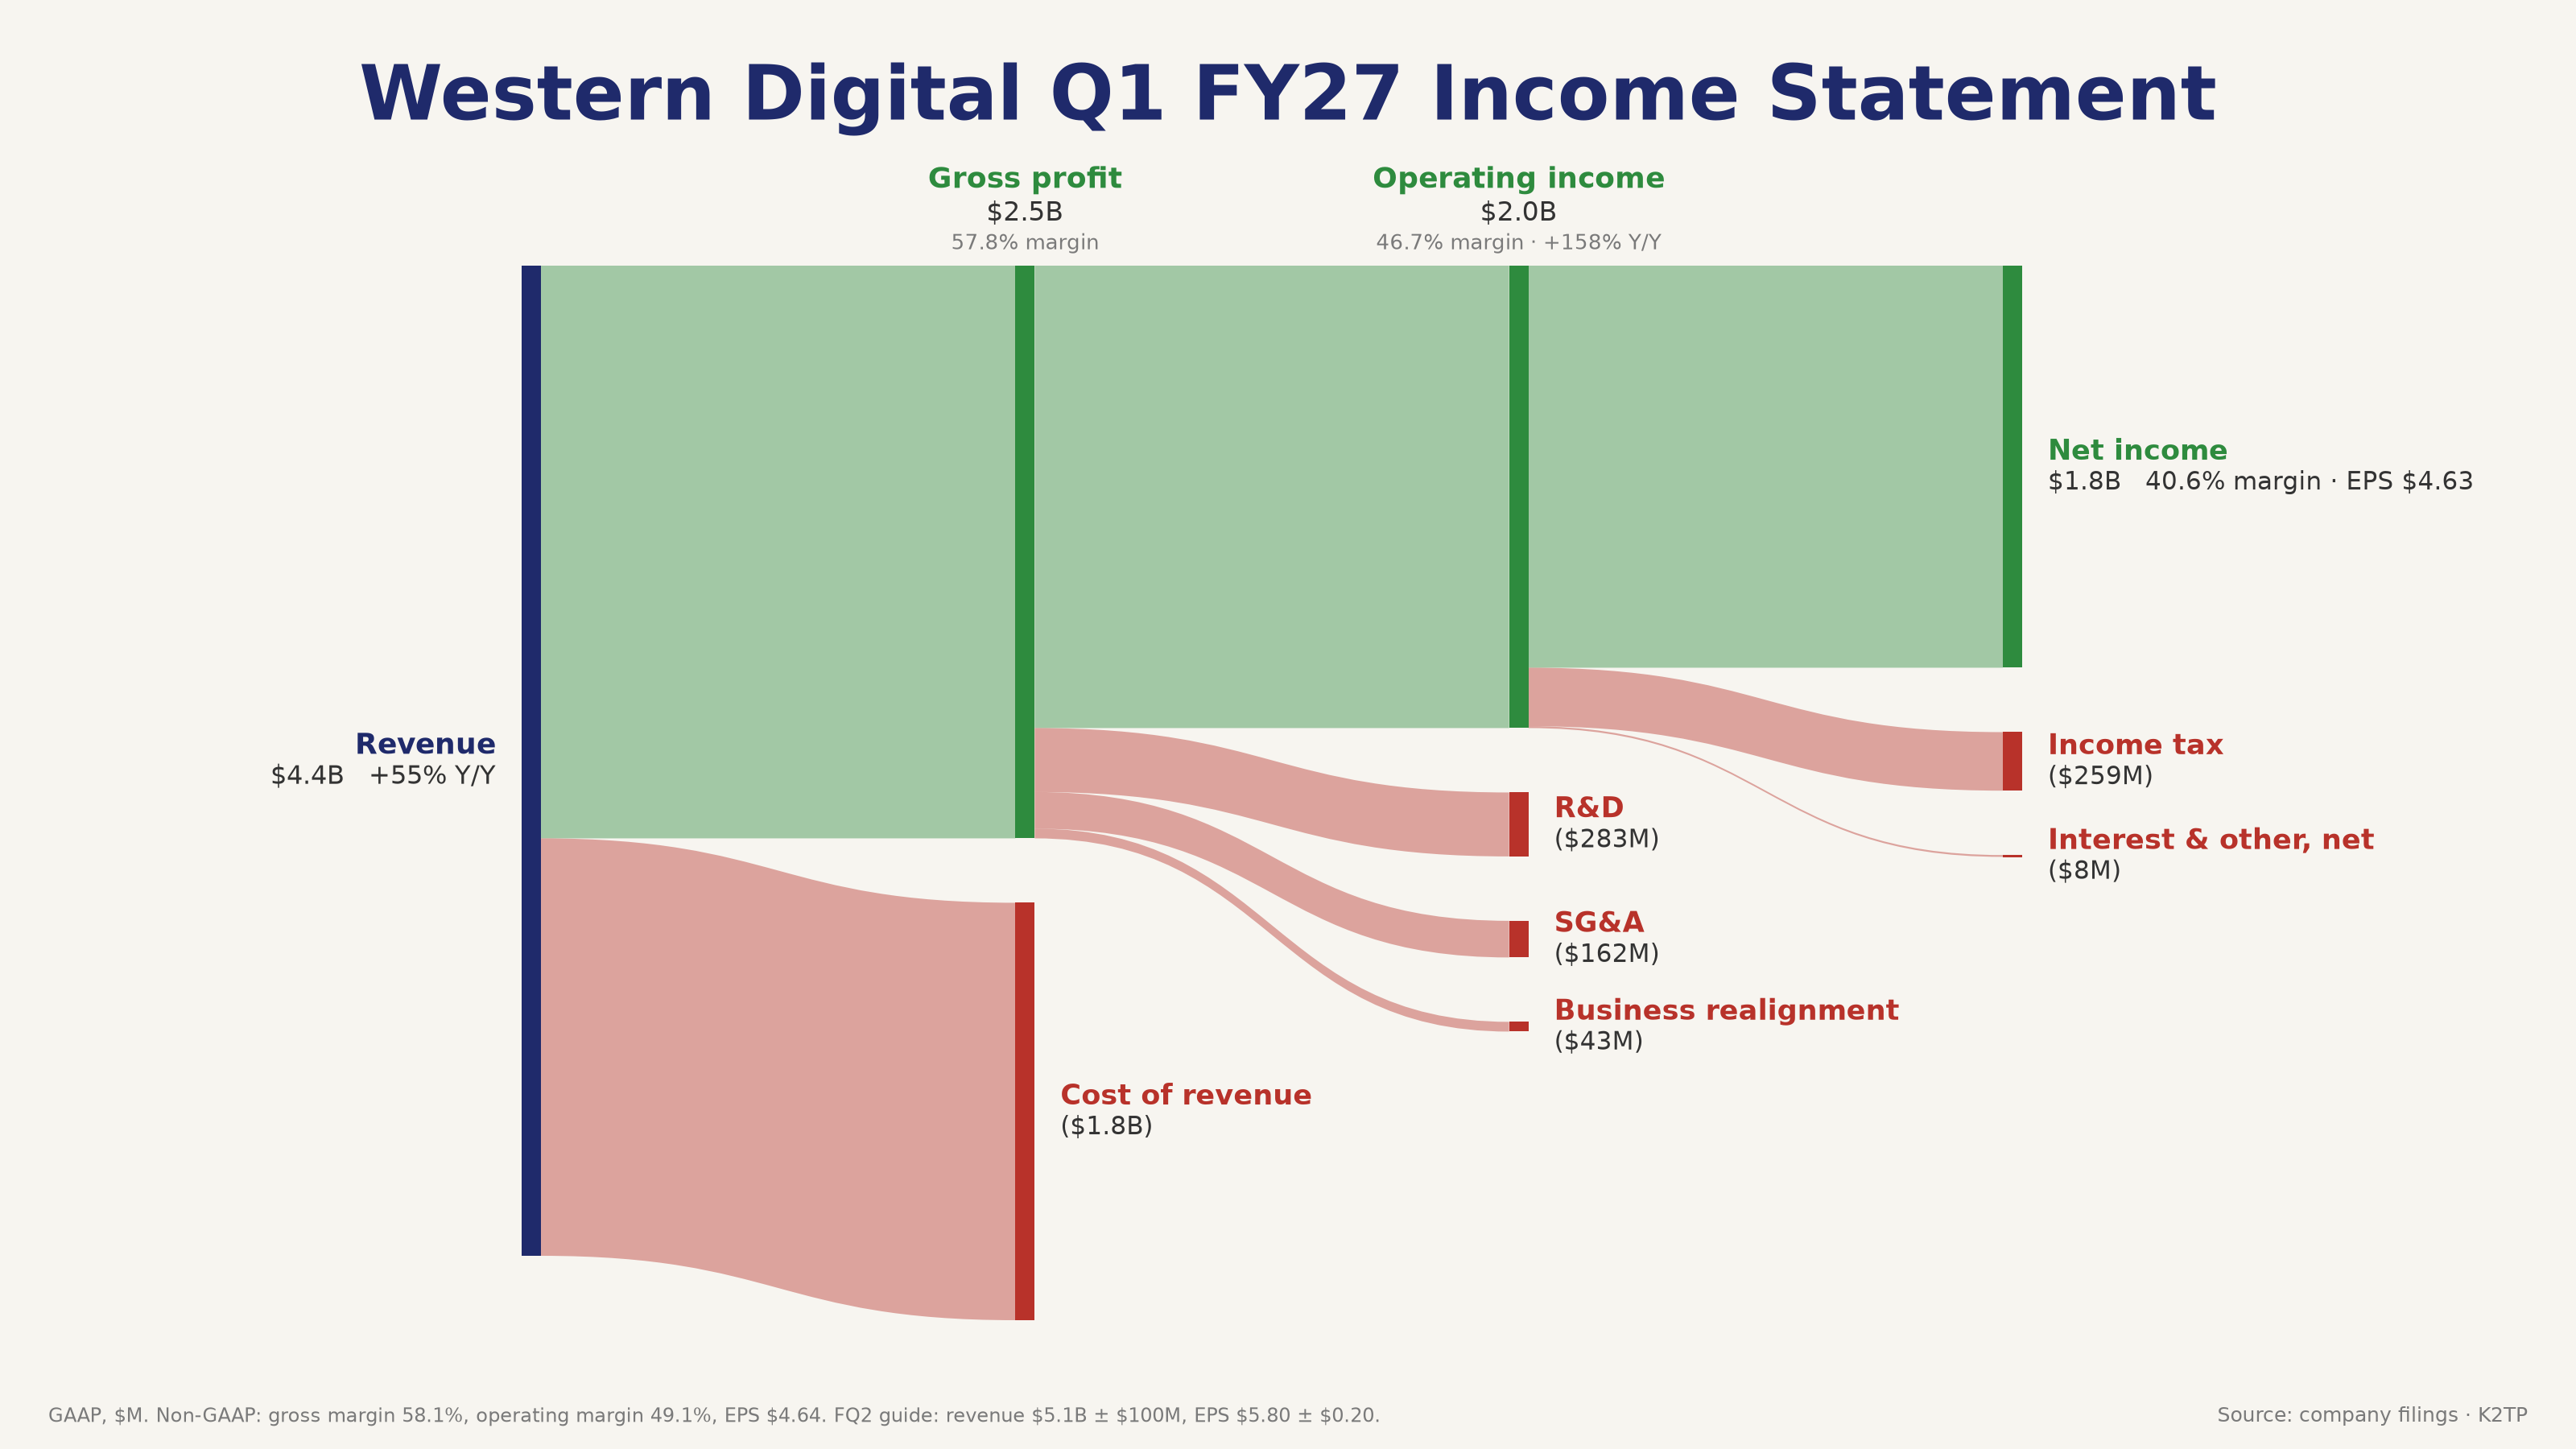
- Western Digital (WDC) −6.54% to $331.01 (8-K): revenue $4.38B (+55% YoY) vs $4.14B expected; non-GAAP EPS $4.64 vs $4.09; non-GAAP gross margin 58.1%, operating margin 49.1%
- FQ2 guide: revenue $5.1B ± $100M (consensus $4.57B), EPS $5.80 ± $0.20; dividend +17% to $0.175 a quarter; shares rose about 4% at first, then reversed as management flagged rising input costs and capex of 4–6% of revenue (Investing.com) 🔴
- Deckers (DECK) −6.99%: first revenue miss ($1.48B vs $1.51B), full-year revenue guide $5.70–5.725B vs $5.88B expected 🔴
- Bloom Energy (BE) −6.86% and Comfort Systems (FIX) −5.92% despite beats (FIX: CFO retiring); VeriSign (VRSN) −3.15% on EPS of $2.35 vs $2.46
- Omnicom (OMC) +2.65%: adjusted EPS $2.73 vs $2.67; Newmont (NEM) −1.41%; RingCentral about +14% (unconfirmed, Investing.com)
- Megacaps roughly flat after hours; MU −1.26% in sympathy with WDC
→ Even a strong AI-storage report could not break the selling. Right now positioning, not fundamentals, is driving the AI trade.
MARKET: INDEXES FALL, THE AVERAGE STOCK HOLDS UP
Indices (close):
- SPX 7,663.43 (−1.21%), range 7,637.36–7,702.94
- NDX 28,958.69 (−2.90%); Nasdaq Composite 26,008.86 (−2.60%)
- DJIA 52,867.98 (+0.02%)
- RUT 2,784.03 (+0.11%)
- RSP 218.22 (+0.73%)
- SOX 10,731.98 (−6.72%)
Intraday path: Premarket ES −0.94% and NQ −1.59% after Meta and the Houthi headlines. SPX opened 7,694.62, peaked at 7,702.94 at 7:03 AM PT, fell to 7,646.05 at 7:35 AM PT, was at 7,682.02 at midday, hit its 7,637.36 low at 12:02 PM PT, was at 7,645.43 before the close and closed at 7,663.43. For the week, SPX is roughly flat (CNBC).
Sector rotation:
- Gainers: XLP +3.31%, XLU +2.07%, XLV +1.32%, XLF +1.09%, XLRE +1.09%, XLB +0.72%
- Decliners: XLK −3.29%, XLC −1.42%, XLI −0.94%, XLE −0.87%, XLY −0.45%
- Megacaps: AAPL +1.23%; MSFT −2.23%, TSLA −3.08%, GOOGL −3.15%, AVGO −4.31%, NVDA −4.40%, TSM −4.52%, AMZN −4.57%, MU −6.26%, META −6.98%, AMD −8.10%
Internals:
- NYSE: advancers narrowly outnumbered decliners (1.01-to-1); 173 new highs vs 366 new lows (Reuters)
- Nasdaq: 2,022 advancers vs 2,766 decliners (1.37-to-1 decliners)
- S&P 500: 40 new 52-week highs, 4 new lows; RSP and RUT beat SPX, so the damage was concentrated in large-cap AI names
Volatility:
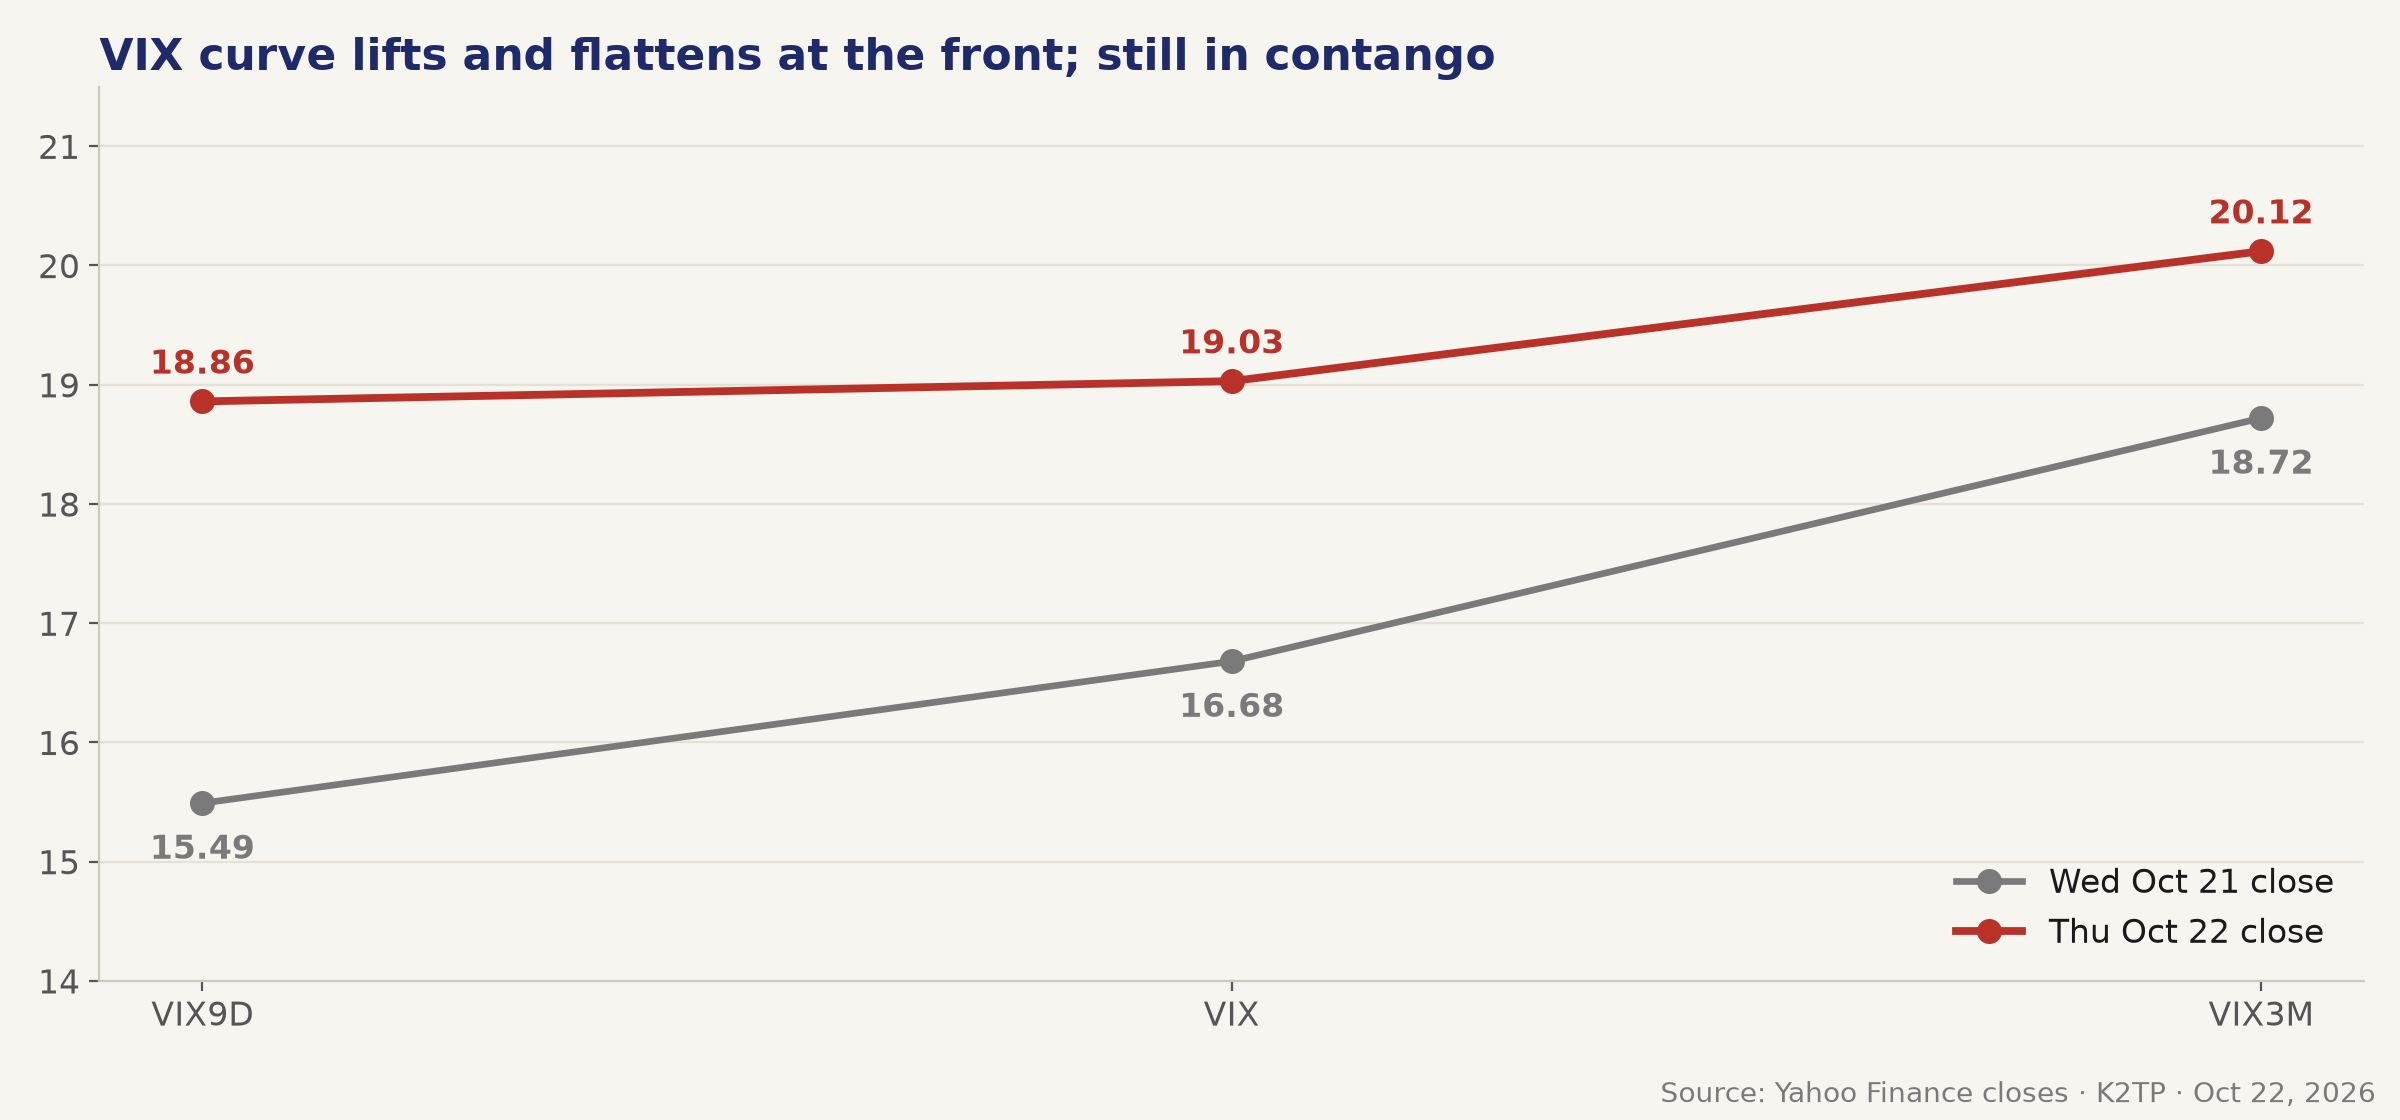
- VIX 19.03 (+14.09%), range 17.71–20.31
- VIX9D 18.86 (from 15.49), VIX3M 20.12 (from 18.72): the whole curve shifted up and flattened at the front, but stays in contango
- VVIX 107.94 (+14.16%)
Cross-asset:
- DXY about 101.67; gold about $4,008.60 tonight (−1.28% from $4,060.40); BTC about $81,218 (Yahoo, about 7 PM PT); USD/JPY at a one-month low of 156.53
Global:
- Asia (Thursday): Hang Seng −3.91%, Kospi −3.52%, Nikkei −2.65%, Shanghai −2.07%, Taiwan −0.54%
- Europe: Euro Stoxx 50 −1.94%, CAC −1.39%, DAX −1.07%, FTSE −0.26%; France's 10-year yield rose 50 bp above Italy's for the first time
- Tonight (about 7 PM PT, Yahoo): Nikkei about −1.6%, Kospi about −1.7%; Japan September core CPI +2.1% YoY; Japan flash manufacturing PMI 53.3 (from 54.1); Australia flash composite PMI 47.7 (from 51.3)
Key SPX levels:
- 7,757.17: Wednesday close
- 7,702.94: Thursday high, Bull trigger
- 7,682.02: midday level, Pre-Close Bull trigger
- 7,663.43: close
- 7,646.05: morning low
- 7,637.36: Thursday low, Bear trigger
- VIX: 17.71 and 20.31
Option seller corner:
- Bull case: SPX above 7,702.94 with VIX below 17.71 moves the regime back to TRANSITION. Then consider resuming small far-OTM SPX put spreads to capture the richer premium.
- Bear case: SPX below 7,637.36 with VIX above 20.31 deepens RISK-OFF. Then cut short put size, use only defined-risk spreads, and avoid NDX short puts.
- VIX near 19 and VVIX above 100 make premium more attractive, but VIX9D is now close to VIX: near-term risk is being priced, not overpriced. Set wider strikes, especially on NDX and chips.
- Friday brings PMI, UMich and weekend Gulf headline risk, then the FOMC next week: avoid holding unhedged short premium over the weekend; WDC, BE, FIX and DECK carry gap risk at the open.
BOTTOM LINE
- Meta reignited fears about AI capex and funding: META −6.98%, SOX −6.72%, NDX −2.90%, SPX −1.21% (worst since July).
- Money did not leave the market, it rotated into staples, utilities, defense, financials and bonds: RSP +0.73%, Dow +0.02%, 10Y −19.3 bp to 4.953%.
- Regime 🔴 RISK-OFF. SPX held its 7,637.36 low on the MOC, but WDC's after-hours drop, Brent above $113 and a Houthi missile at Riyadh keep risk high; SPX needs to clear 7,702.94 with VIX below 17.71 to return to TRANSITION.
What to watch tomorrow (PT):
- Before the open: American Express, SLB, HCA Healthcare, Autoliv, Booz Allen Hamilton, Infosys
- 6:45 AM: S&P Global October flash PMI (manufacturing forecast 55.4 vs 55.9; services 57.9 vs 58.8)
- 7:00 AM: final October UMich consumer sentiment (forecast 46.3, prior 48.1); 1-year/5-year inflation expectations (forecast 4.7%/3.5%, prior 4.6%/3.4%)
- Monday Oct 26: $69B 2-year note auction
- Oct 27–28: FOMC, decision at 11:00 AM on Oct 28; Fed blackout through Oct 29
Bull expectation: Gulf headlines calm, Brent slips below $113, SOX stabilizes after two days of selling, SPX clears 7,702.94 and VIX breaks below 17.71. Bear expectation: the Gulf escalates and pushes Brent above $114, AI infrastructure keeps selling after WDC, BE and FIX, SPX loses 7,637.36 and VIX rises above 20.31.
Sources: 4 K2TP briefs for 10/22/2026 (Pre-Market, Midday, Pre-Close, Evening Recap). Closing, intraday and after-hours prices from Yahoo Finance; breadth, news and data from Reuters, AP, CNBC, WSJ, Conference Board, Investing.com and FinancialJuice; Sankeys from P&G and Western Digital Q1 FY27 releases (8-K Ex. 99.1, SEC EDGAR). Analysis: K2TP Framework.