Market 10/21: SpaceX and Chips Push SPX Past Tuesday's High as Breadth Thins; Tesla and Lam Slip After Hours
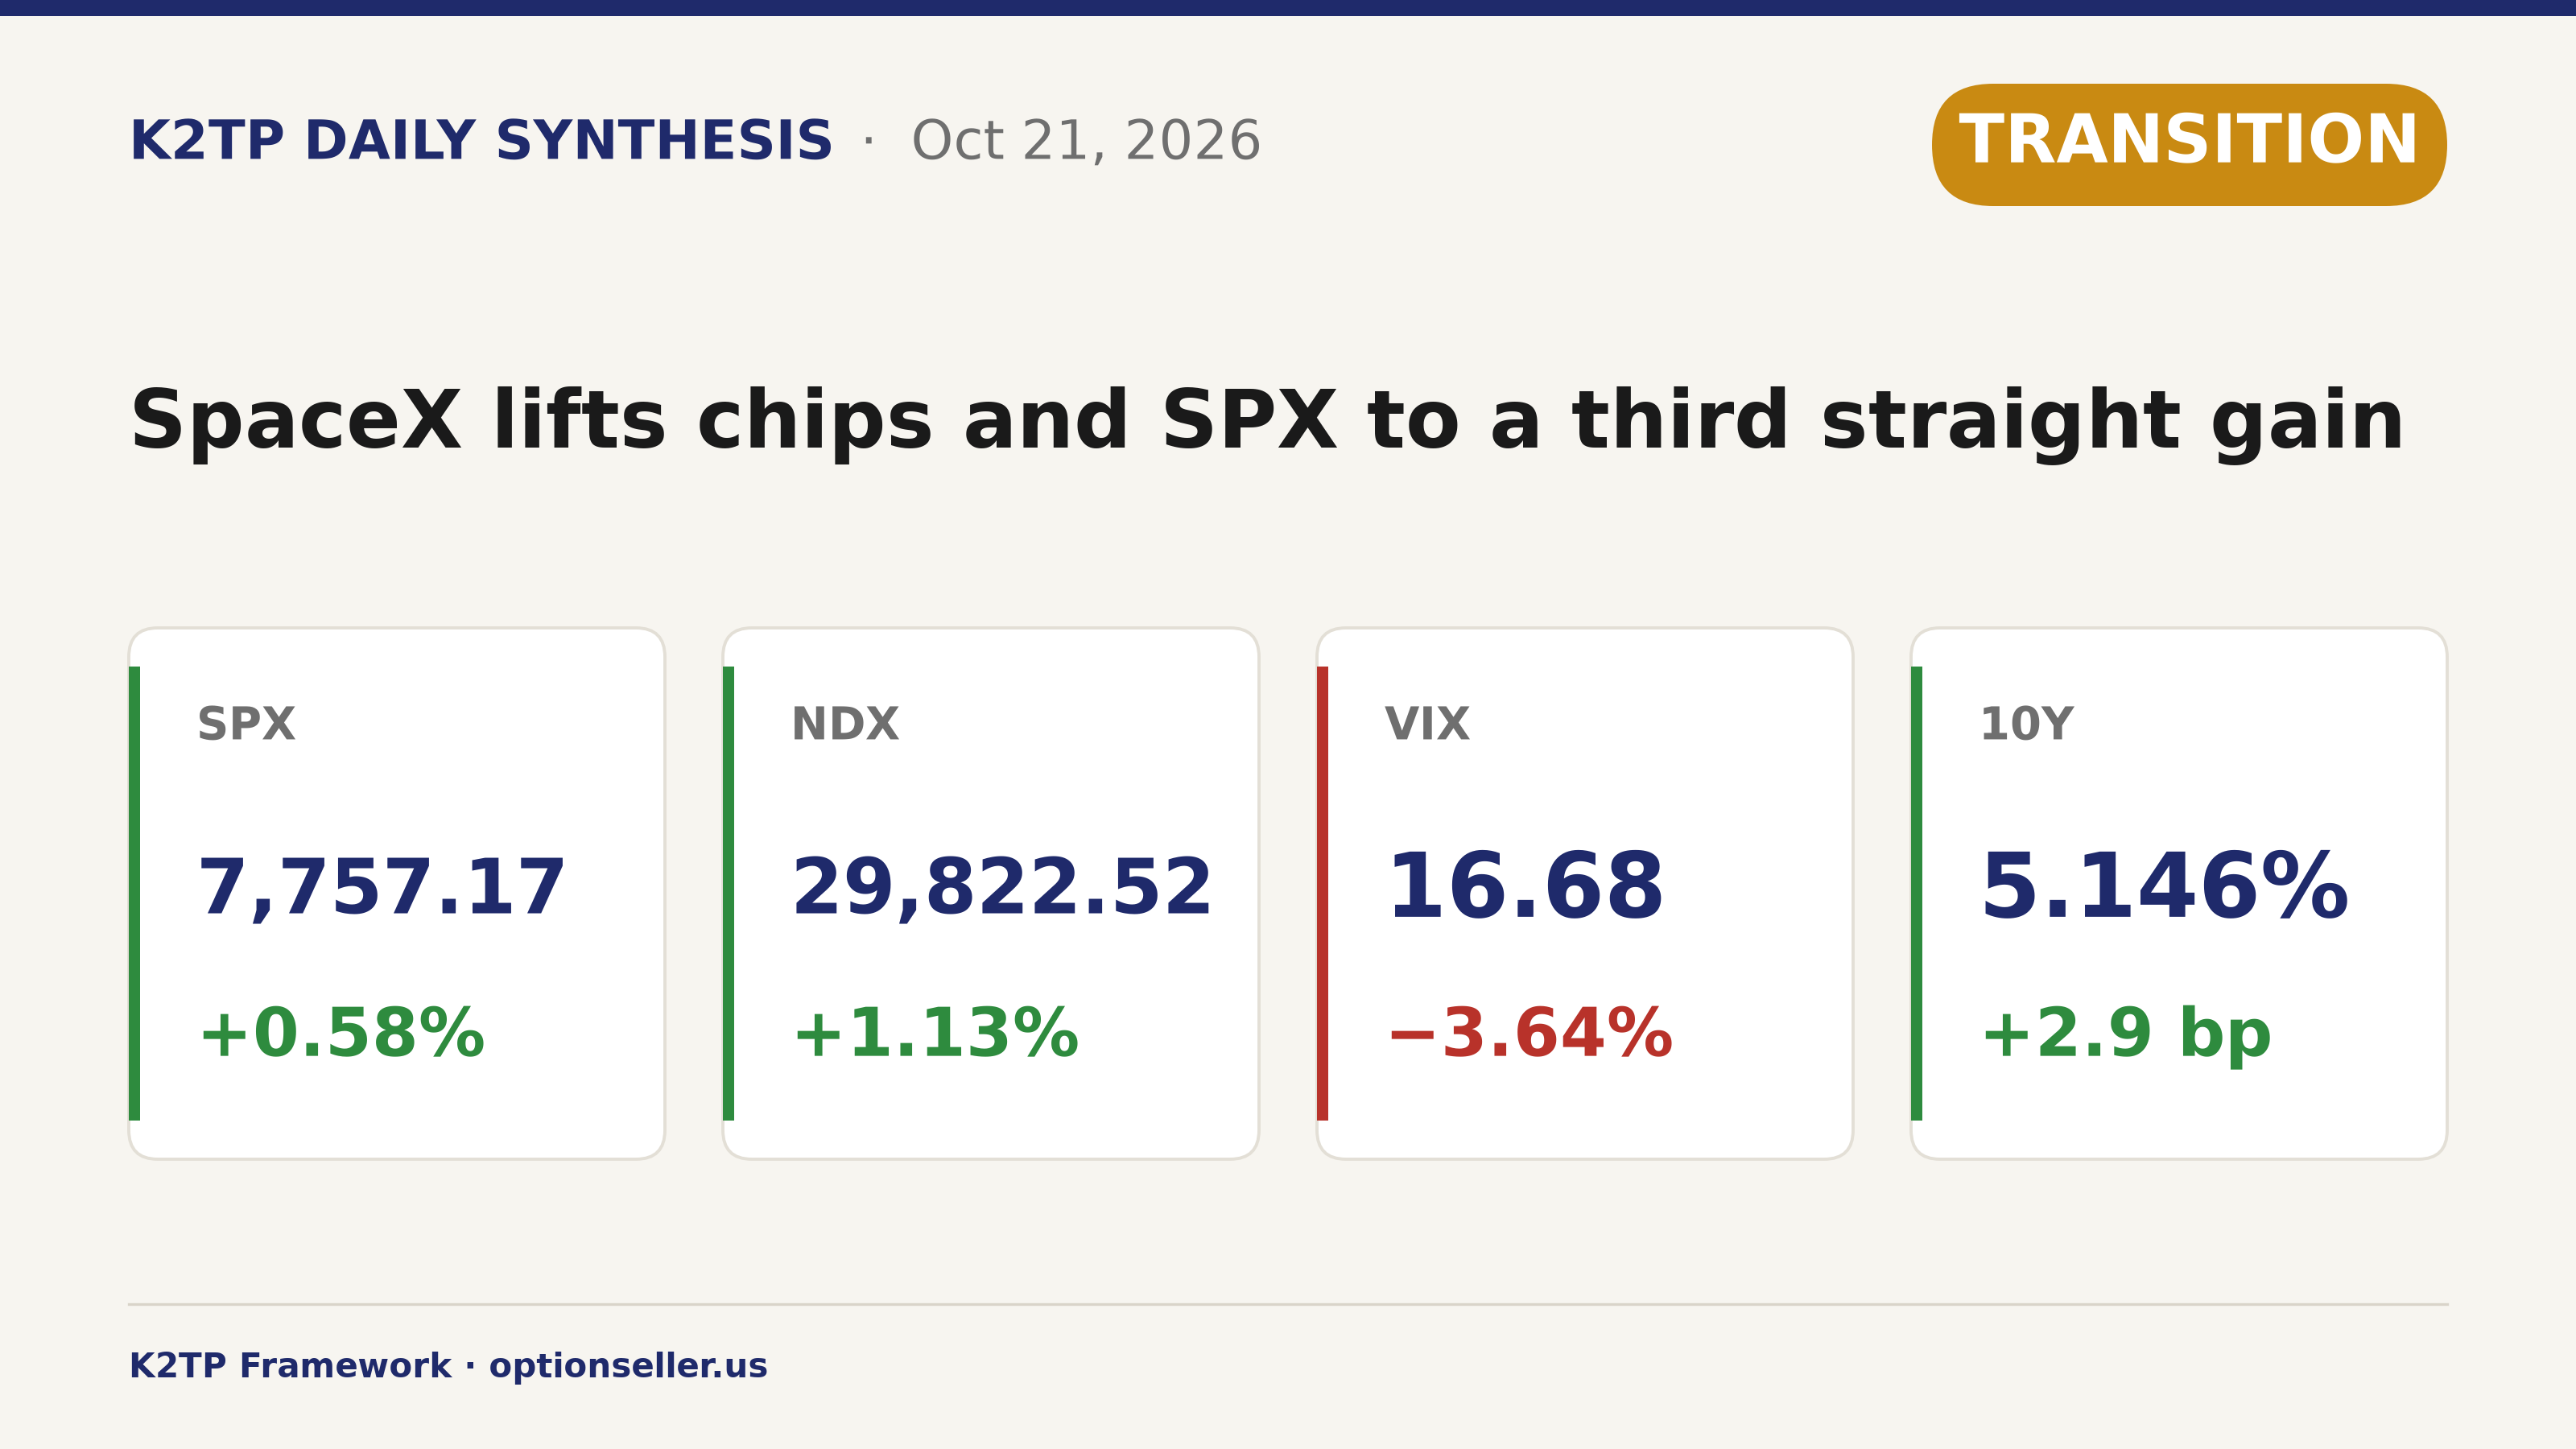
SPX +0.58%, NDX +1.13%, VIX −3.64%. AI hardware led a third straight gain, but the rally narrowed, yields rose after a tailing 20-year auction, and Gulf headlines pulled futures lower tonight.
KEY HEADLINES
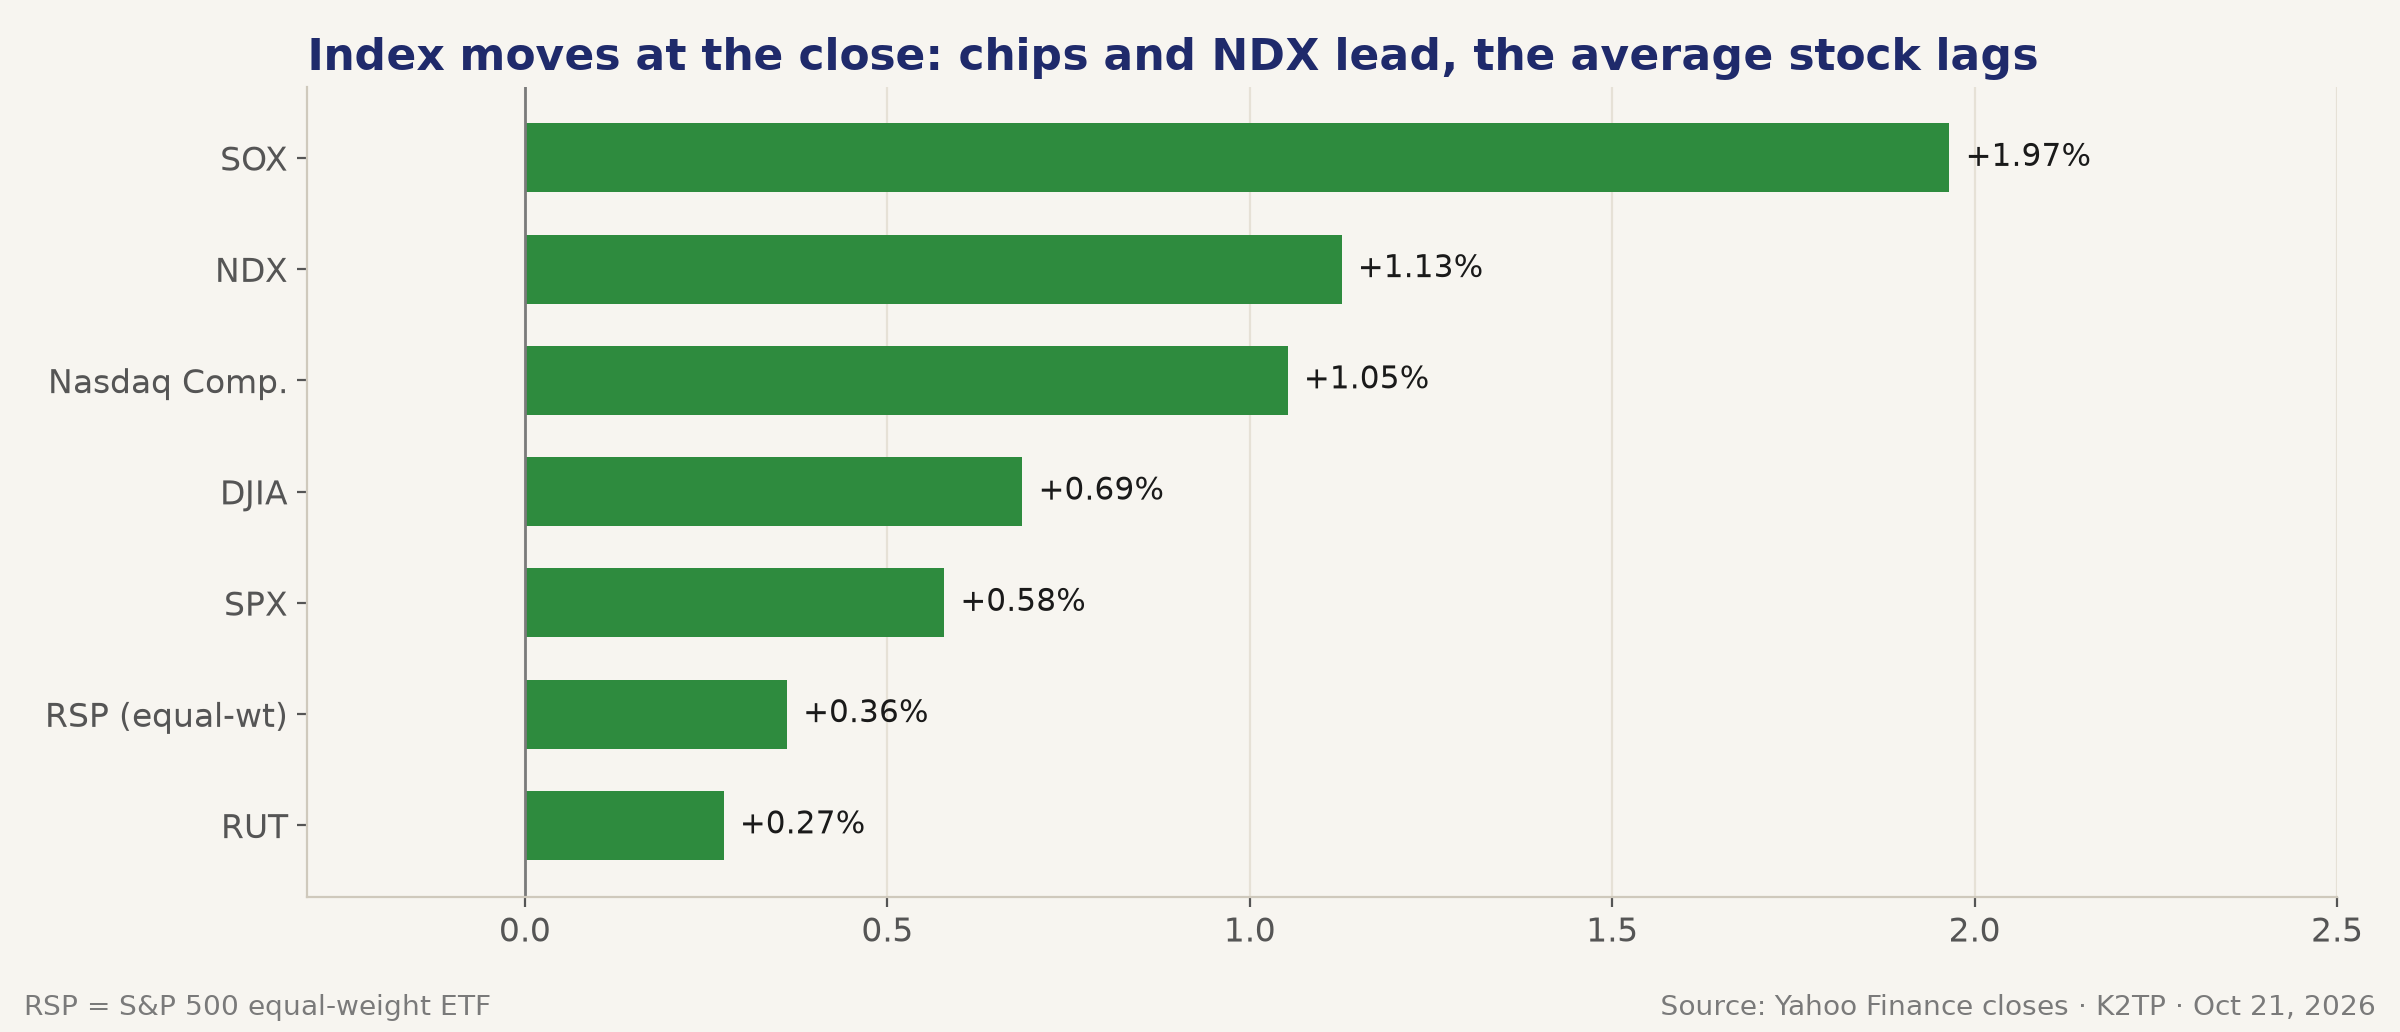
- SPX +0.58% to 7,757.17, a third straight gain (CNBC) and a close above Tuesday's 7,748.42 high; NDX +1.13%, SOX +1.97%, Dow +0.69%
- SpaceX (SPCX) +7.79% and Super Micro (SMCI) +9.55% lifted AI hardware; technology was the best S&P 500 sector (Reuters), XLK +1.67%
- Breadth thinned: RSP +0.36% and RUT +0.27% trailed SPX; NYSE advancers led only 1.37-to-1, with more new lows (221) than new highs (131)
- Communication services capped the gain: AT&T −6.45%, Netflix −5.31%, GOOGL −1.62%, XLC −1.11%
- The $13B 20-year auction stopped at 5.469% with a 0.9 bp tail; 10Y +2.9 bp to 5.146%, 5Y +3.7 bp to 4.972%
- A Gulf headline knocked SPX from 7,770.40 (11:16 AM PT) to 7,730.96 (12:03 PM PT) before it recovered into the close
- VIX 16.68 (−3.64%), VIX9D 15.49, VIX3M 18.72
- After hours: Meta +2.12% on a revenue beat; Tesla −3.32%, IBM −4.64% and Lam Research −7.41% reversed lower
- Tonight (around 7 PM PT): ES −0.47%, NQ −0.91%, Brent $110.33 on reports of US evacuations from some Middle East posts
- Regime: 🟡 TRANSITION into Thursday; it tipped to RISK-ON at midday but breadth, rates and futures did not confirm
SPACEX AND SUPER MICRO REVIVE THE AI HARDWARE TRADE
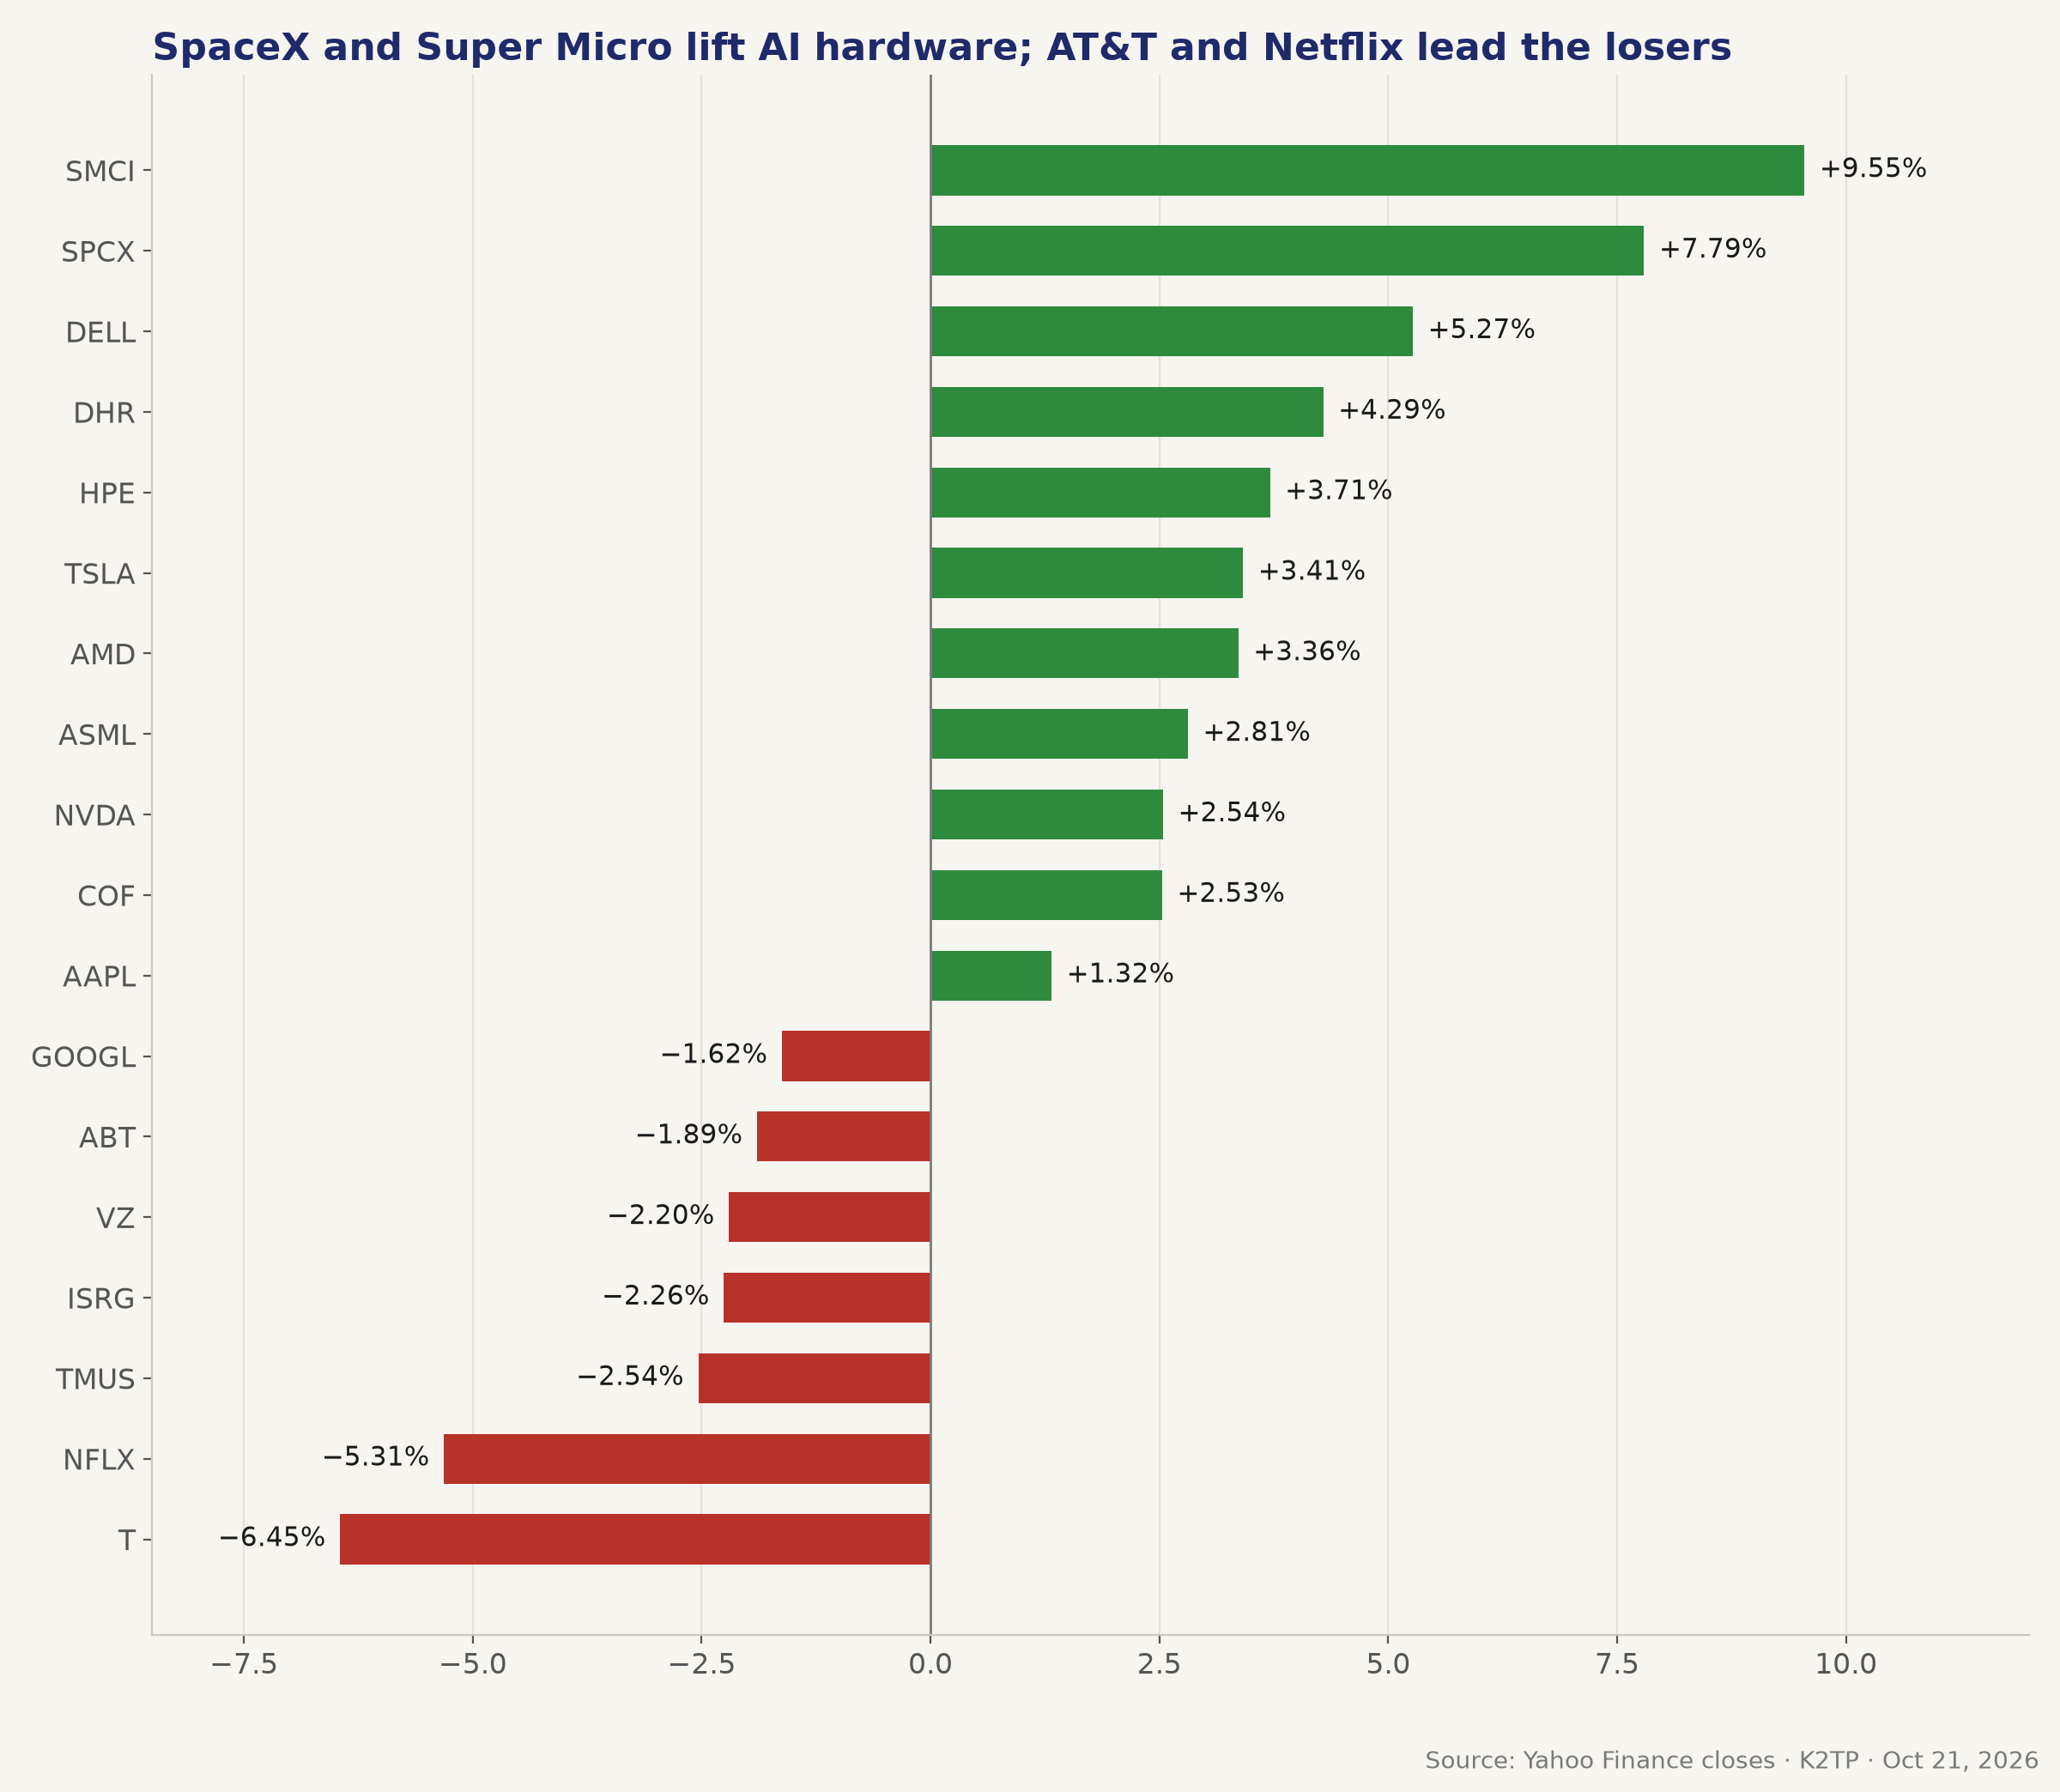
- SpaceX (SPCX) +7.79% to $159.31 (high $166.18) after Tuesday night's report: Q3 revenue +161% to $14.58B and its first profit as a public company 🟢
- Super Micro (SMCI) +9.55% to $35.57 after raising its fiscal Q1 revenue outlook to $18.5B–$19.5B from $14.5B–$15.5B
- Read-through: Dell +5.27%, HPE +3.71%, AMD +3.36%, ASML +2.81%, NVDA +2.54%, MU +1.96%, TSM +1.60%; SOX +1.97% to 11,505.56
- WSJ cited bullish comments from Nvidia's Jensen Huang in Berlin (via the K2TP Pre-Close brief)
- NDX +1.13% to 29,822.52 beat SPX by 55 bp; Nasdaq Composite +1.05%
- CoreWeave (CRWV) −0.50% after a $64.58 high: not all of AI infrastructure joined in
→ SpaceX and Super Micro reassured the market on AI demand, and money went back into semis and servers. This time the leadership was narrow: tech moved, the average stock barely did.
TESLA RALLIES ON MERGER TALK, THEN REVERSES AFTER RESULTS
- In regular hours TSLA +3.41% to $386.47 after Elon Musk called a SpaceX–Tesla merger "a good idea" and both companies formed special committees 🟢
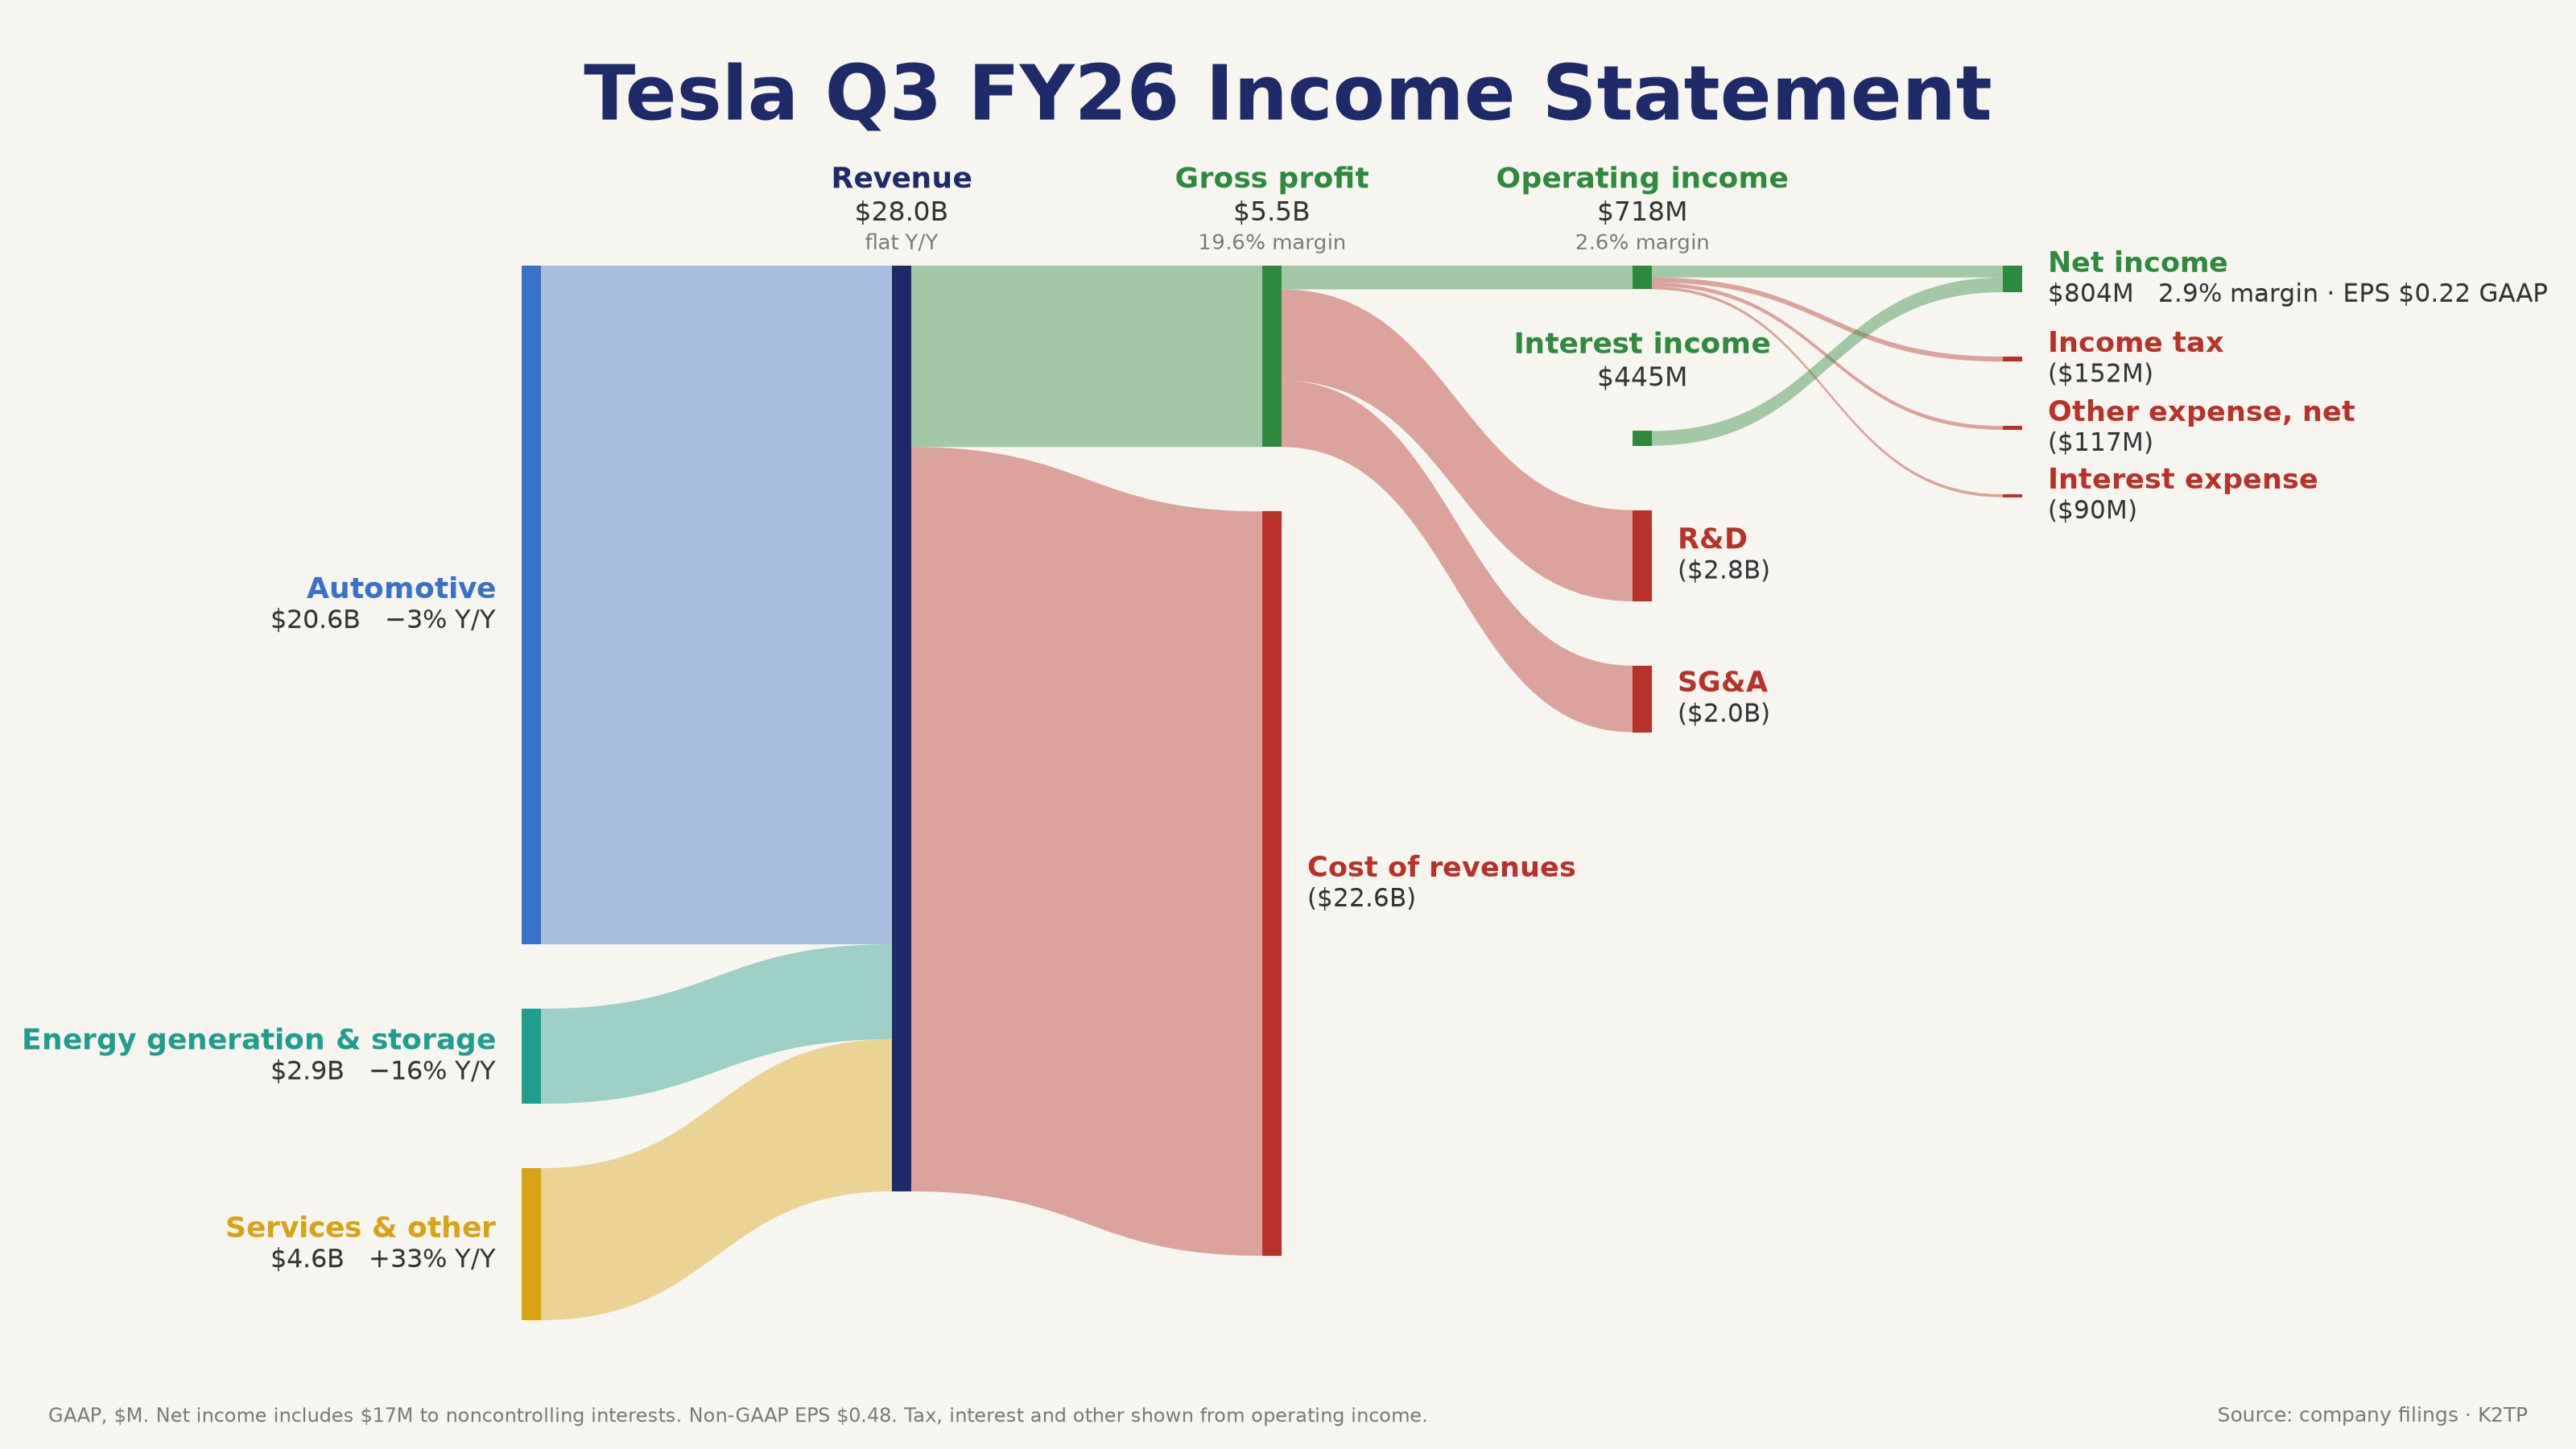
- Q3 (8-K): revenue $28.05B, flat y/y, vs $28.13B expected; non-GAAP EPS $0.48 vs $0.44; GAAP EPS $0.22; gross margin 19.6%; operating margin 2.6%
- Segments: automotive $20.56B (−3% y/y), energy $2.88B (−16%), services and other $4.61B (+33%); deliveries 486,532 (−2%); active FSD subscriptions 1.74M
- Free cash flow $1.53B; capex $4.73B in the quarter
- On the call, 2026 capex was cut to about $20B from more than $25B; Optimus needs "at least a year, maybe a little longer" to reach 20,000 units a week; EU-wide FSD approval was pushed toward Q1 (Yahoo, Reuters)
- TSLA rose about 2% on the release, then fell 3.32% to $373.63 after hours 🔴
→ The merger story was priced in before the report. The quarter itself was mixed, and the call gave the market reasons to take profits.
META BEATS ON REVENUE; THE LEGAL CHARGE HITS EPS
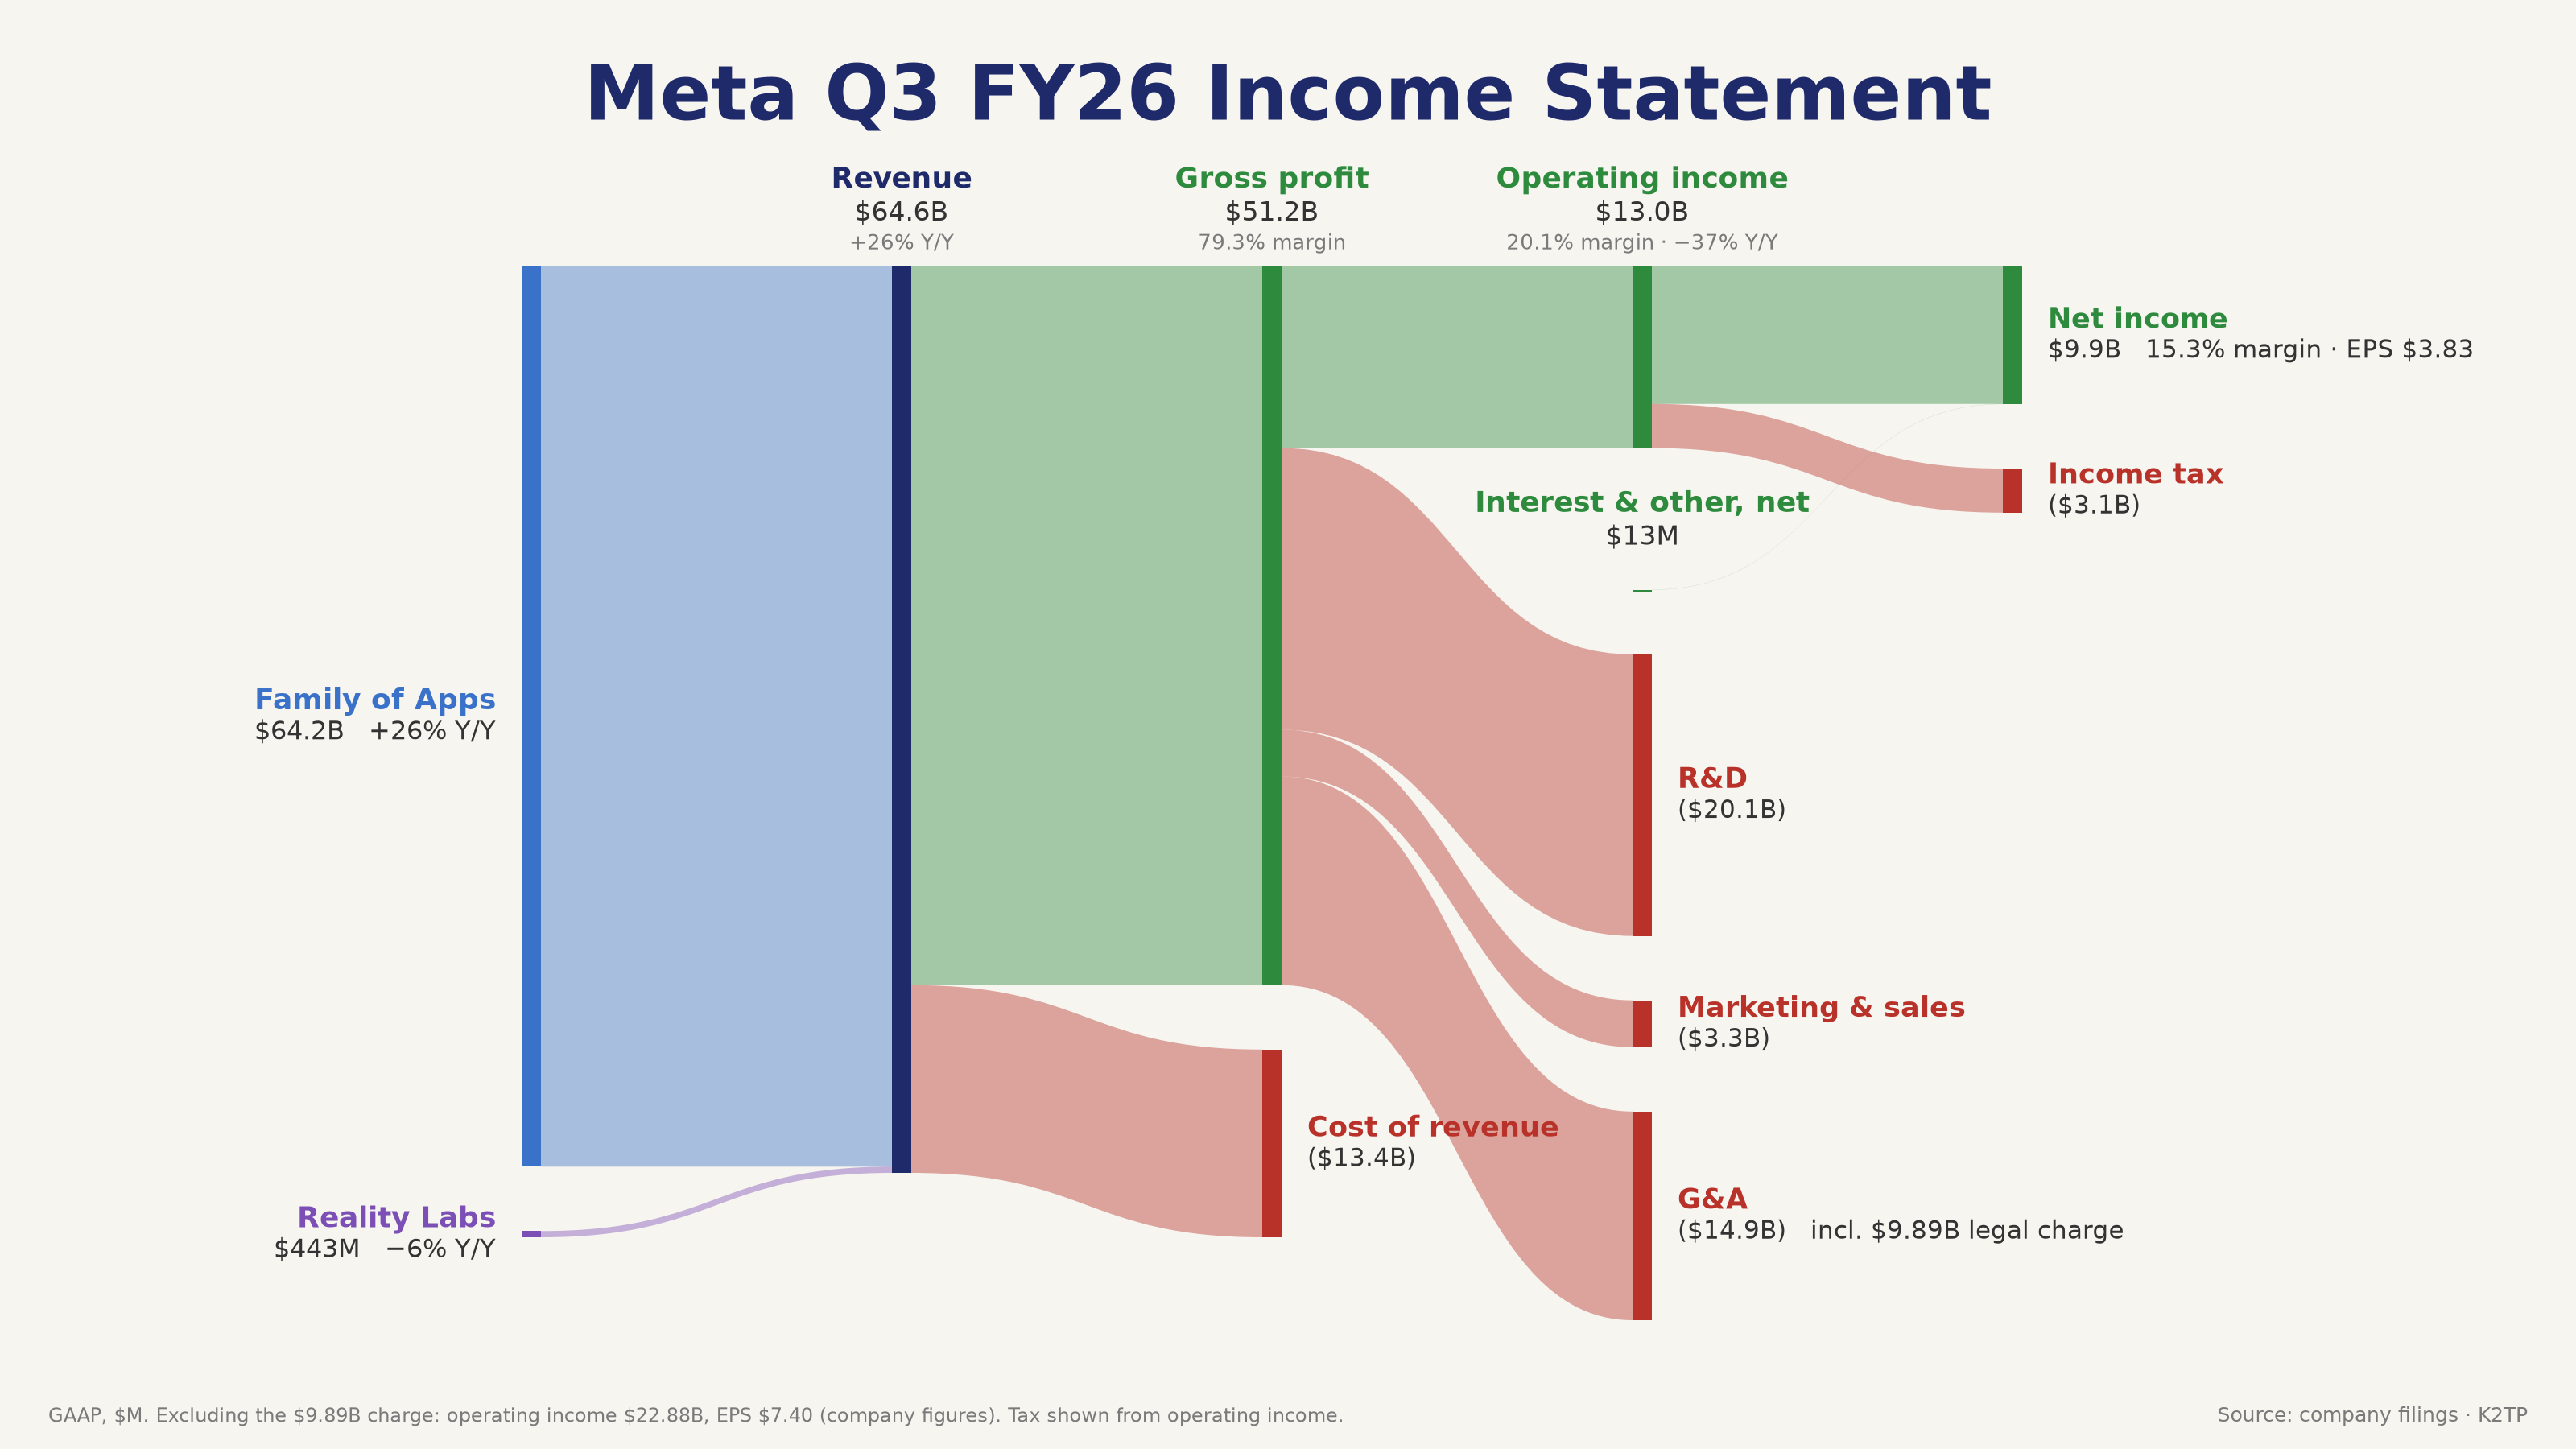
- Q3 (8-K): revenue $64.60B, +26% y/y, vs $63.33B expected (Investing.com); ad impressions +10%, average price per ad +14% 🟢
- GAAP EPS $3.83 includes a $9.89B charge for the agreement with state attorneys general; excluding it, operating income was $22.88B and EPS $7.40 (company figures)
- Q4 revenue guide $73B–$76B vs a $73.57B estimate; 2026 total expenses raised to $175B–$179B to include the charge
- 2026 capex narrowed to $135B–$145B from $130B–$145B; Q3 capex $34.91B; free cash flow −$2.12B
- Headcount 66,775 (−15% y/y); Reality Labs losses of $18B–$19B expected in 2026; a new Class C common stock was announced
- No 2027 revenue outlook: budget and capacity plans are still being set
- META closed +0.47% at $697.52 and traded +2.12% at $712.31 after hours (about +4% early, per Investing.com) 🟢
→ Meta delivered a revenue beat and a solid guide without lifting capex further. That was enough for a moderate gain, but it did not offset Tesla and chip equipment after hours.
COMMUNICATION SERVICES AND DEFENSIVES CAP THE INDEX
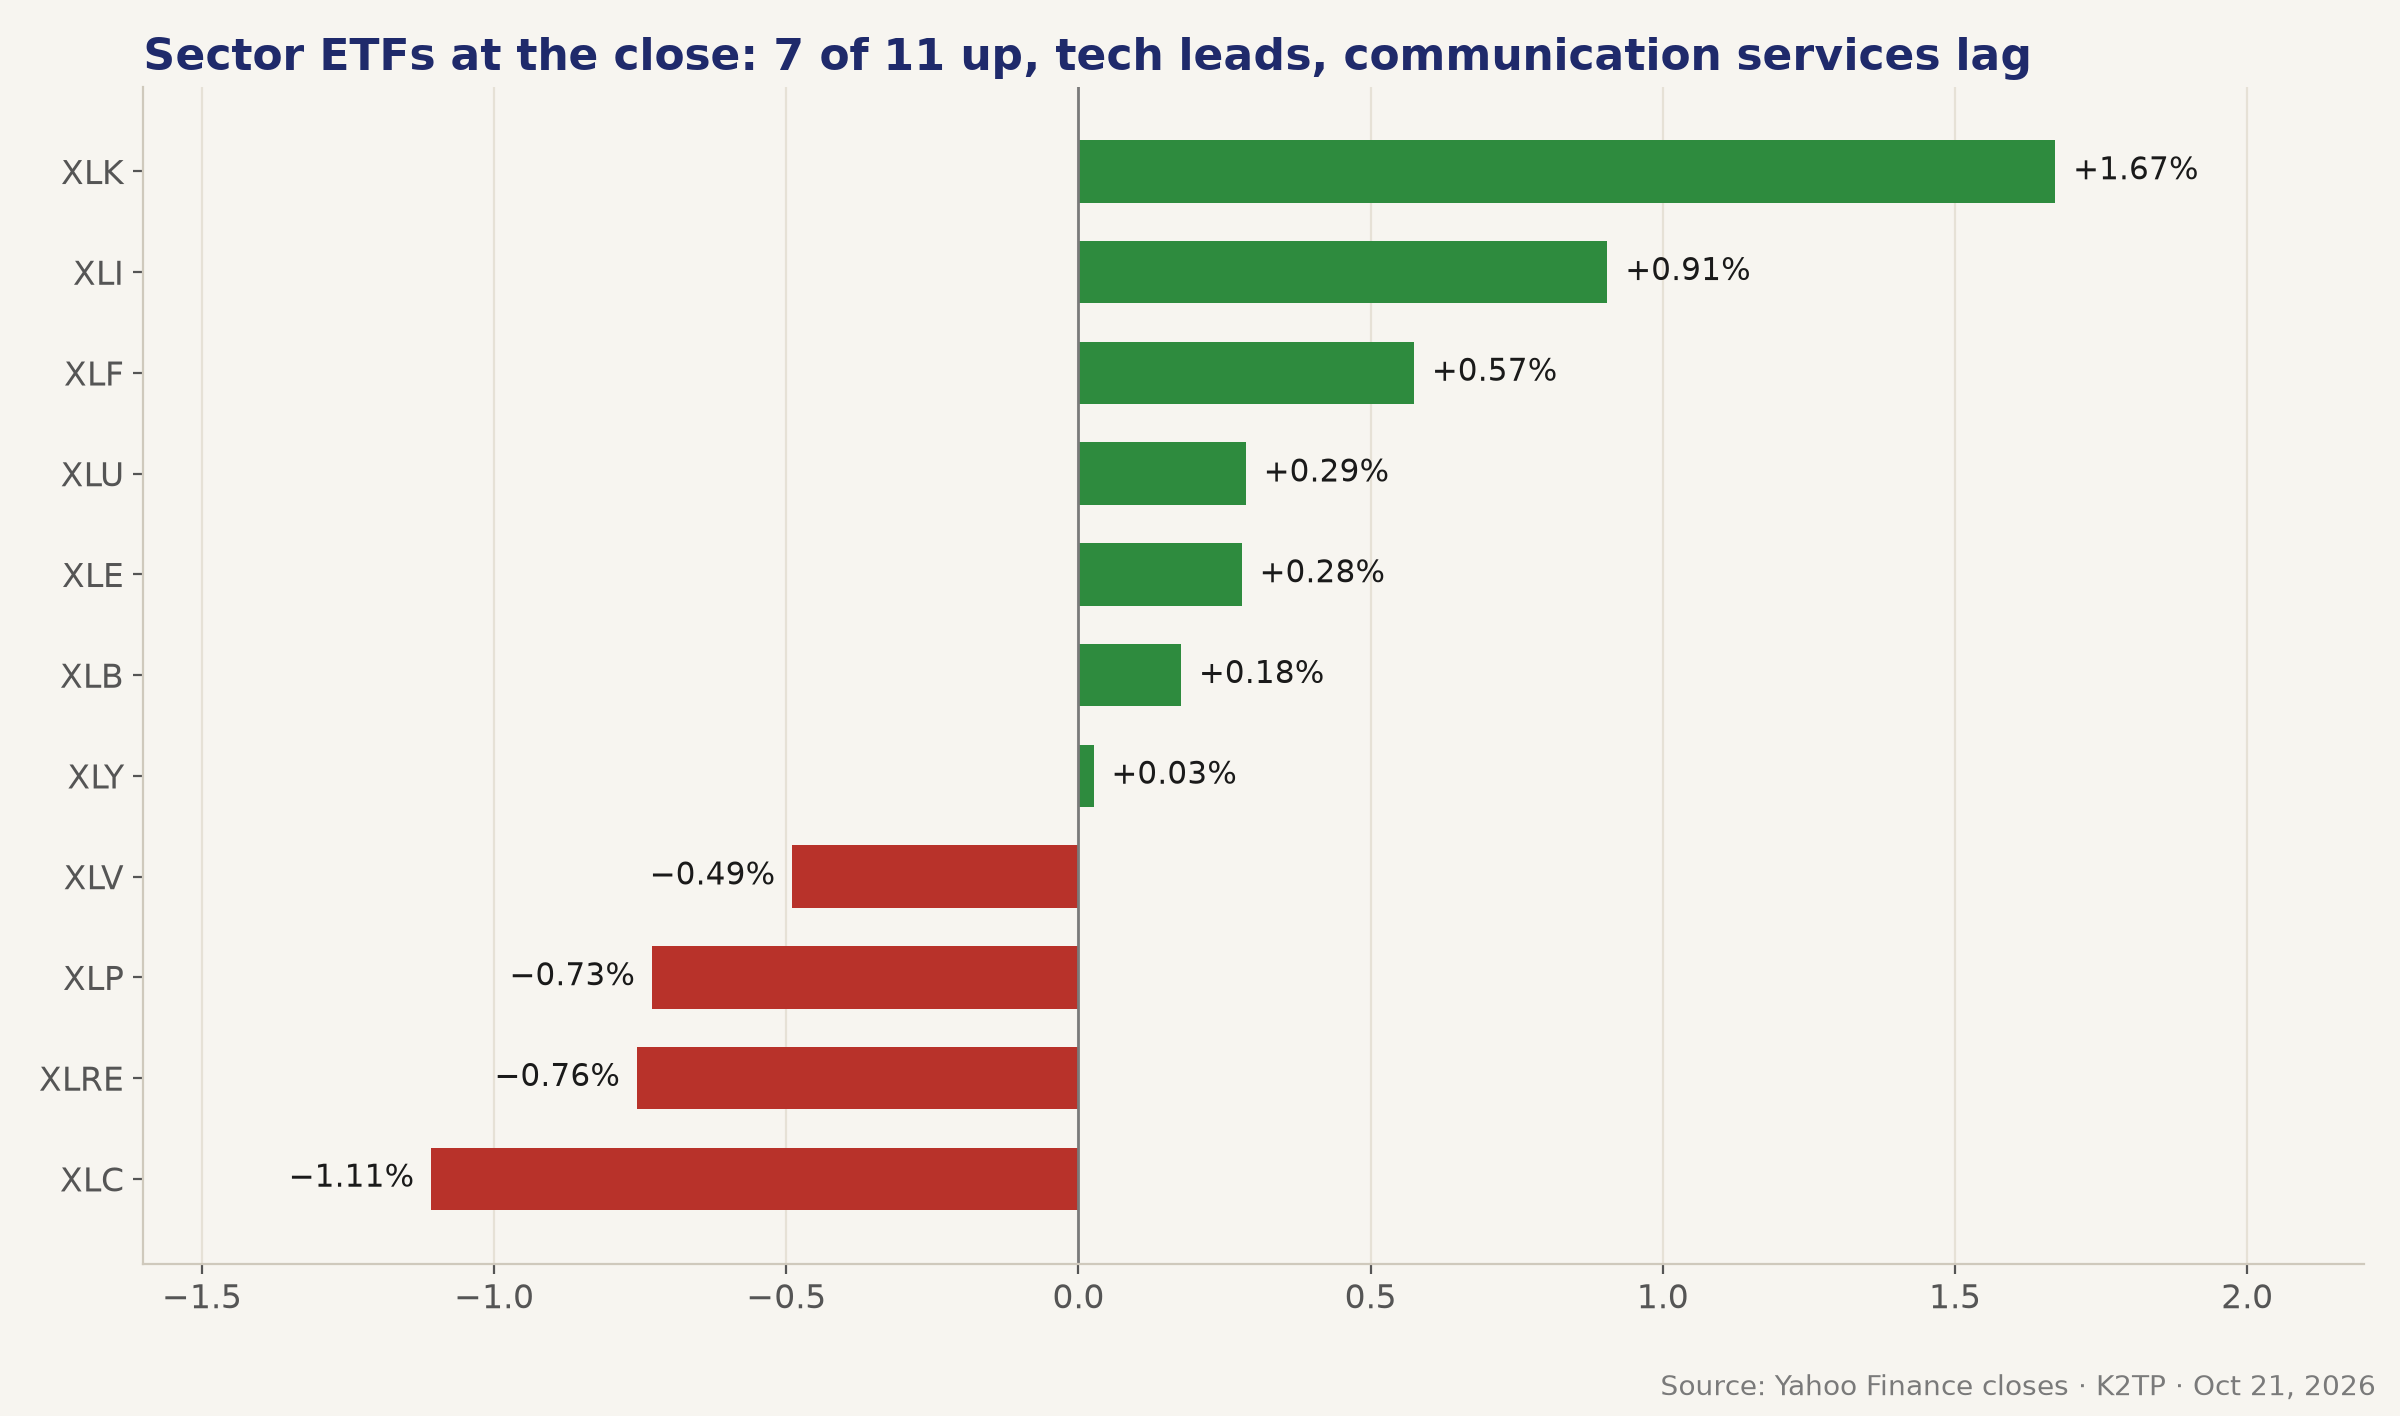
- 7 of 11 sector ETFs rose: XLK +1.67%, XLI +0.91%, XLF +0.57%, XLU +0.29%, XLE +0.28%, XLB +0.18%, XLY +0.03%
- Decliners: XLC −1.11%, XLRE −0.76%, XLP −0.73%, XLV −0.49%; Tuesday's leader, healthcare, gave some back (LLY −1.01%)
- AT&T (T) −6.45% despite beating and raising EPS guidance, on capex and worries SpaceX becomes a stronger wireless rival (Reuters); Verizon −2.20%, T-Mobile −2.54% 🔴
- Netflix (NFLX) −5.31% to $65.04 on its weak Q4 outlook and lower ad forecast
- Other reports: Danaher (DHR) +4.29% after raising EPS guidance, reversing a −3.35% pre-market move 🟢; Capital One (COF) +2.53%; Thermo Fisher (TMO) +0.97%; Abbott (ABT) −1.89% after cutting its 2026 sales growth forecast; Elevance (ELV) −1.37%; Philip Morris (PM) −1.22%
- Intuitive Surgical (ISRG) −2.26% after recovering from a $398.99 low
→ The rotation into defensives from Tuesday stopped. Money went back to tech, and telecom paid the price as SpaceX was seen as a new competitor.
A TAILING 20-YEAR AUCTION PUSHES YIELDS HIGHER
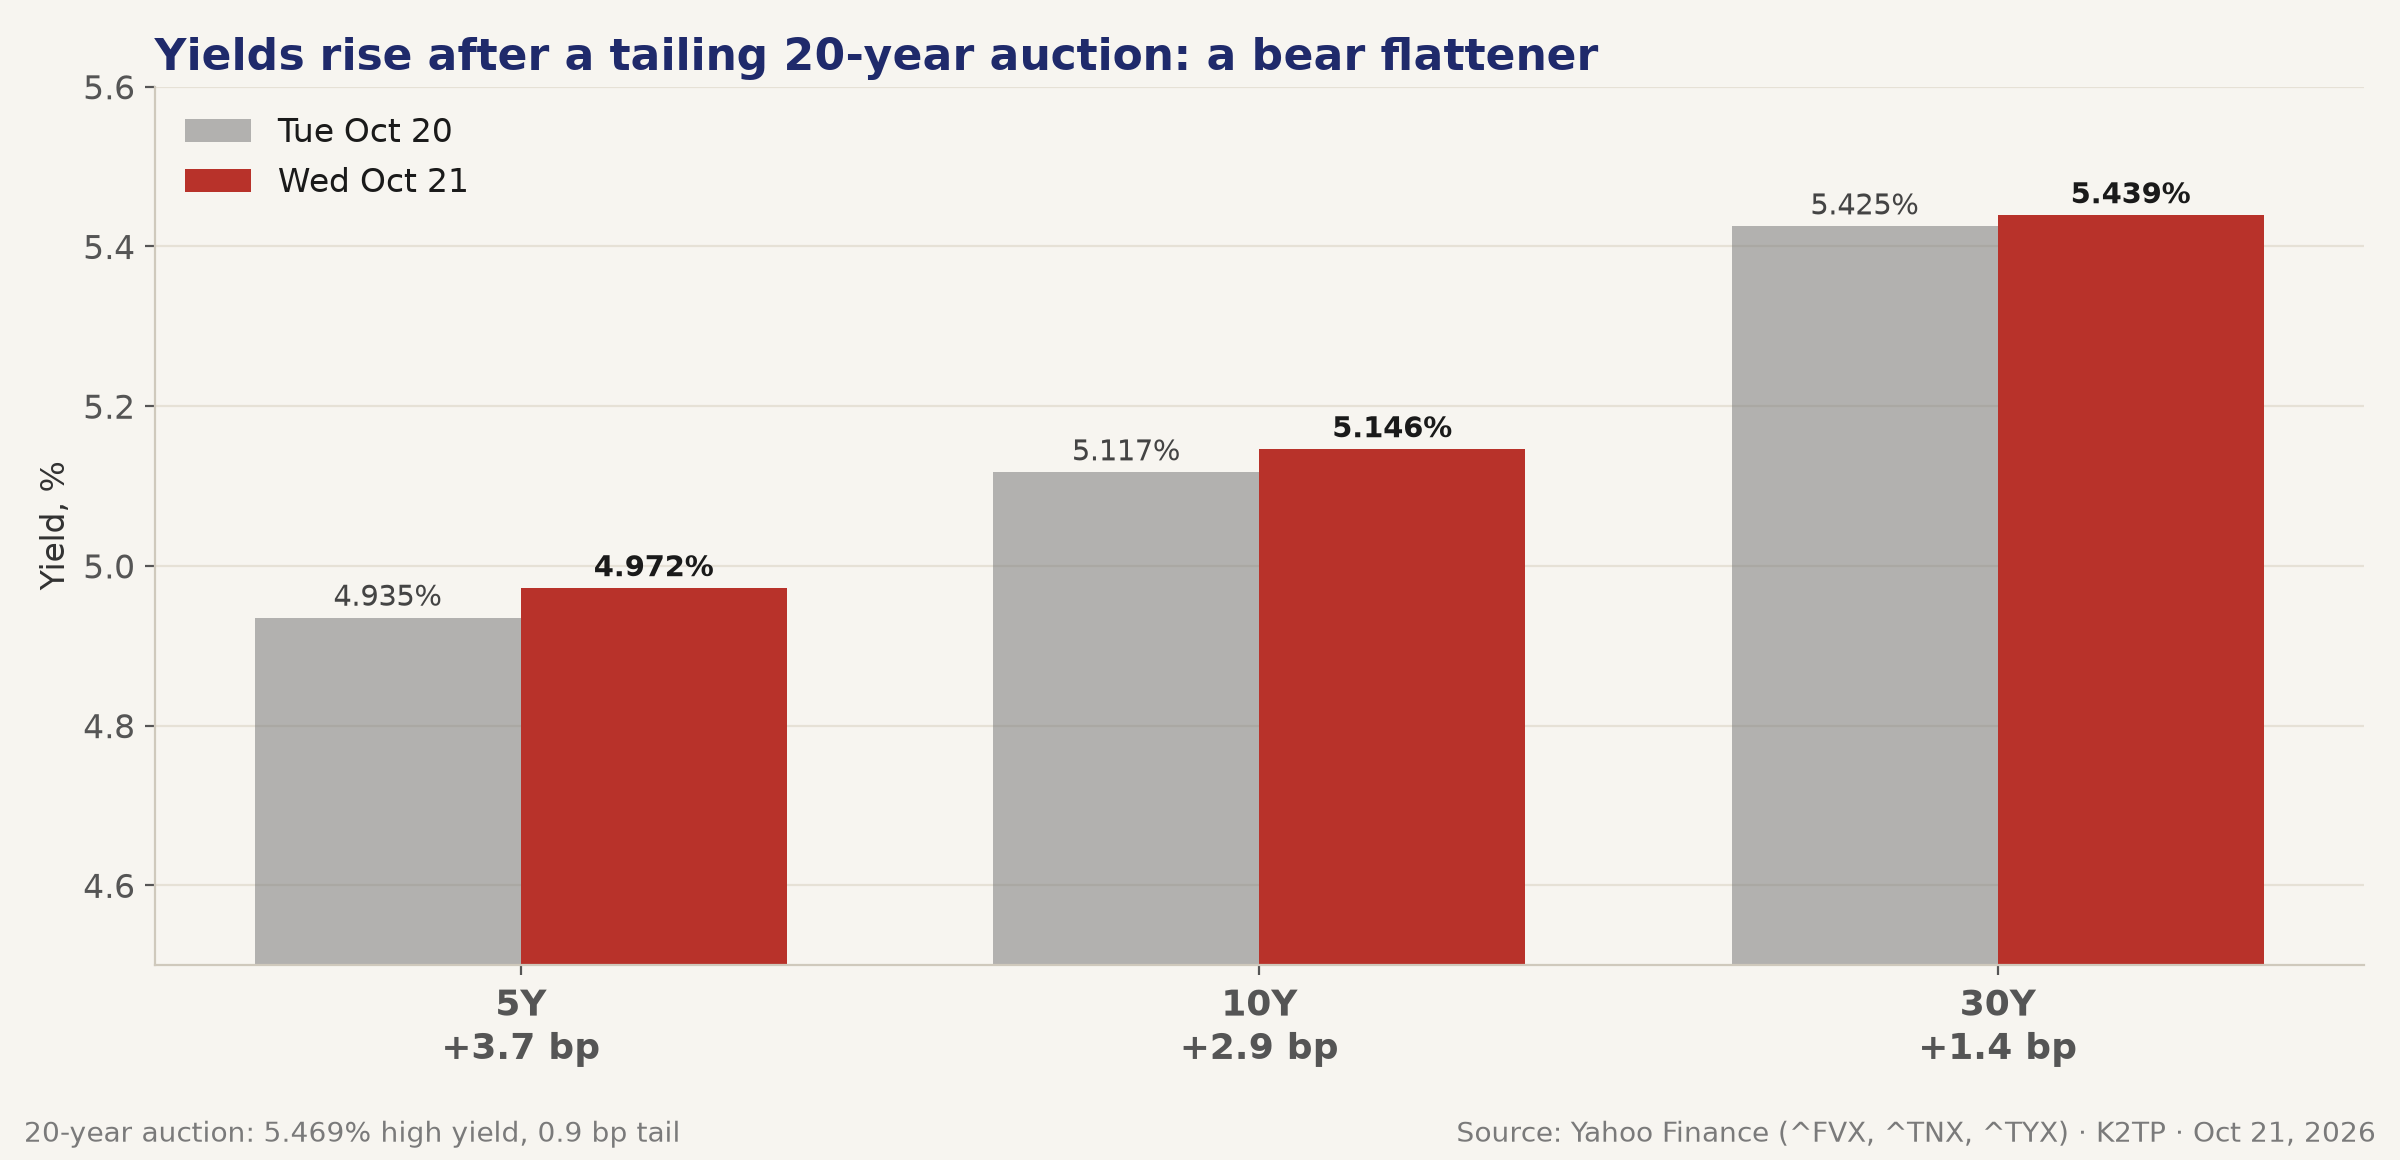
- 20-year reopening ($13B): high yield 5.469% vs 5.460% when-issued, a 0.9 bp tail (0.2 bp average); bid-to-cover 2.73 vs 2.57 in September; indirects 58.2%, directs 31.6%, dealers 10.3% 🔴
- The K2TP Pre-Close brief notes 5.469% was the highest 20-year stop since 1986 (Dow Jones via MarketScreener)
- Closing yields: 10Y 5.146% (+2.9 bp), 5Y 4.972% (+3.7 bp), 30Y 5.439% (+1.4 bp); 5s30s narrowed from 49.0 bp to 46.7 bp (a bear flattener led by the belly)
- The 10Y touched 5.081% early, then rose all afternoon
- France's 10-year yield topped 5% for the first time since 2002 (Reuters, WSJ)
- Fed: blackout before the Oct 27–28 FOMC; no fresh CME FedWatch reading for Wednesday (last: 14.9% October hike odds on Tuesday)
→ A soft auction and higher global yields took back Tuesday's drop. Equities ignored it today, but a 10Y near 5.15% keeps a ceiling on valuations into the FOMC.
OIL AND GULF HEADLINES RETURN AS THE RISK
- EIA: crude stocks −3.06M barrels vs −0.3M expected; gasoline −3.0M, distillates +1.7M
- December WTI settled at $97.15 (−0.69%) and Brent at $108.82 (+0.03%)
- An 11:48 AM PT report relayed by FinancialJuice that the State Department is preparing ordered departures from US embassies across the Gulf coincided with the midday drop in SPX
- After the close (unconfirmed, FinancialJuice citing NBC): US troops and diplomats are evacuating some Middle East posts, Iran threatened US targets if strikes resume, and Saudi aviation reported one killed in an attack on Dammam's King Fahd airport
- Tonight (around 7 PM PT, Yahoo): Brent $110.33 (+1.39%), December WTI $98.36 (+1.25%)
→ The crude draw did not lift oil during the session, but Gulf headlines are again driving the war-risk premium. Brent above $110 is the main risk for rates and futures into Thursday.
SPX BREAKS OUT, SHAKES, AND CLOSES ABOVE THE LINE
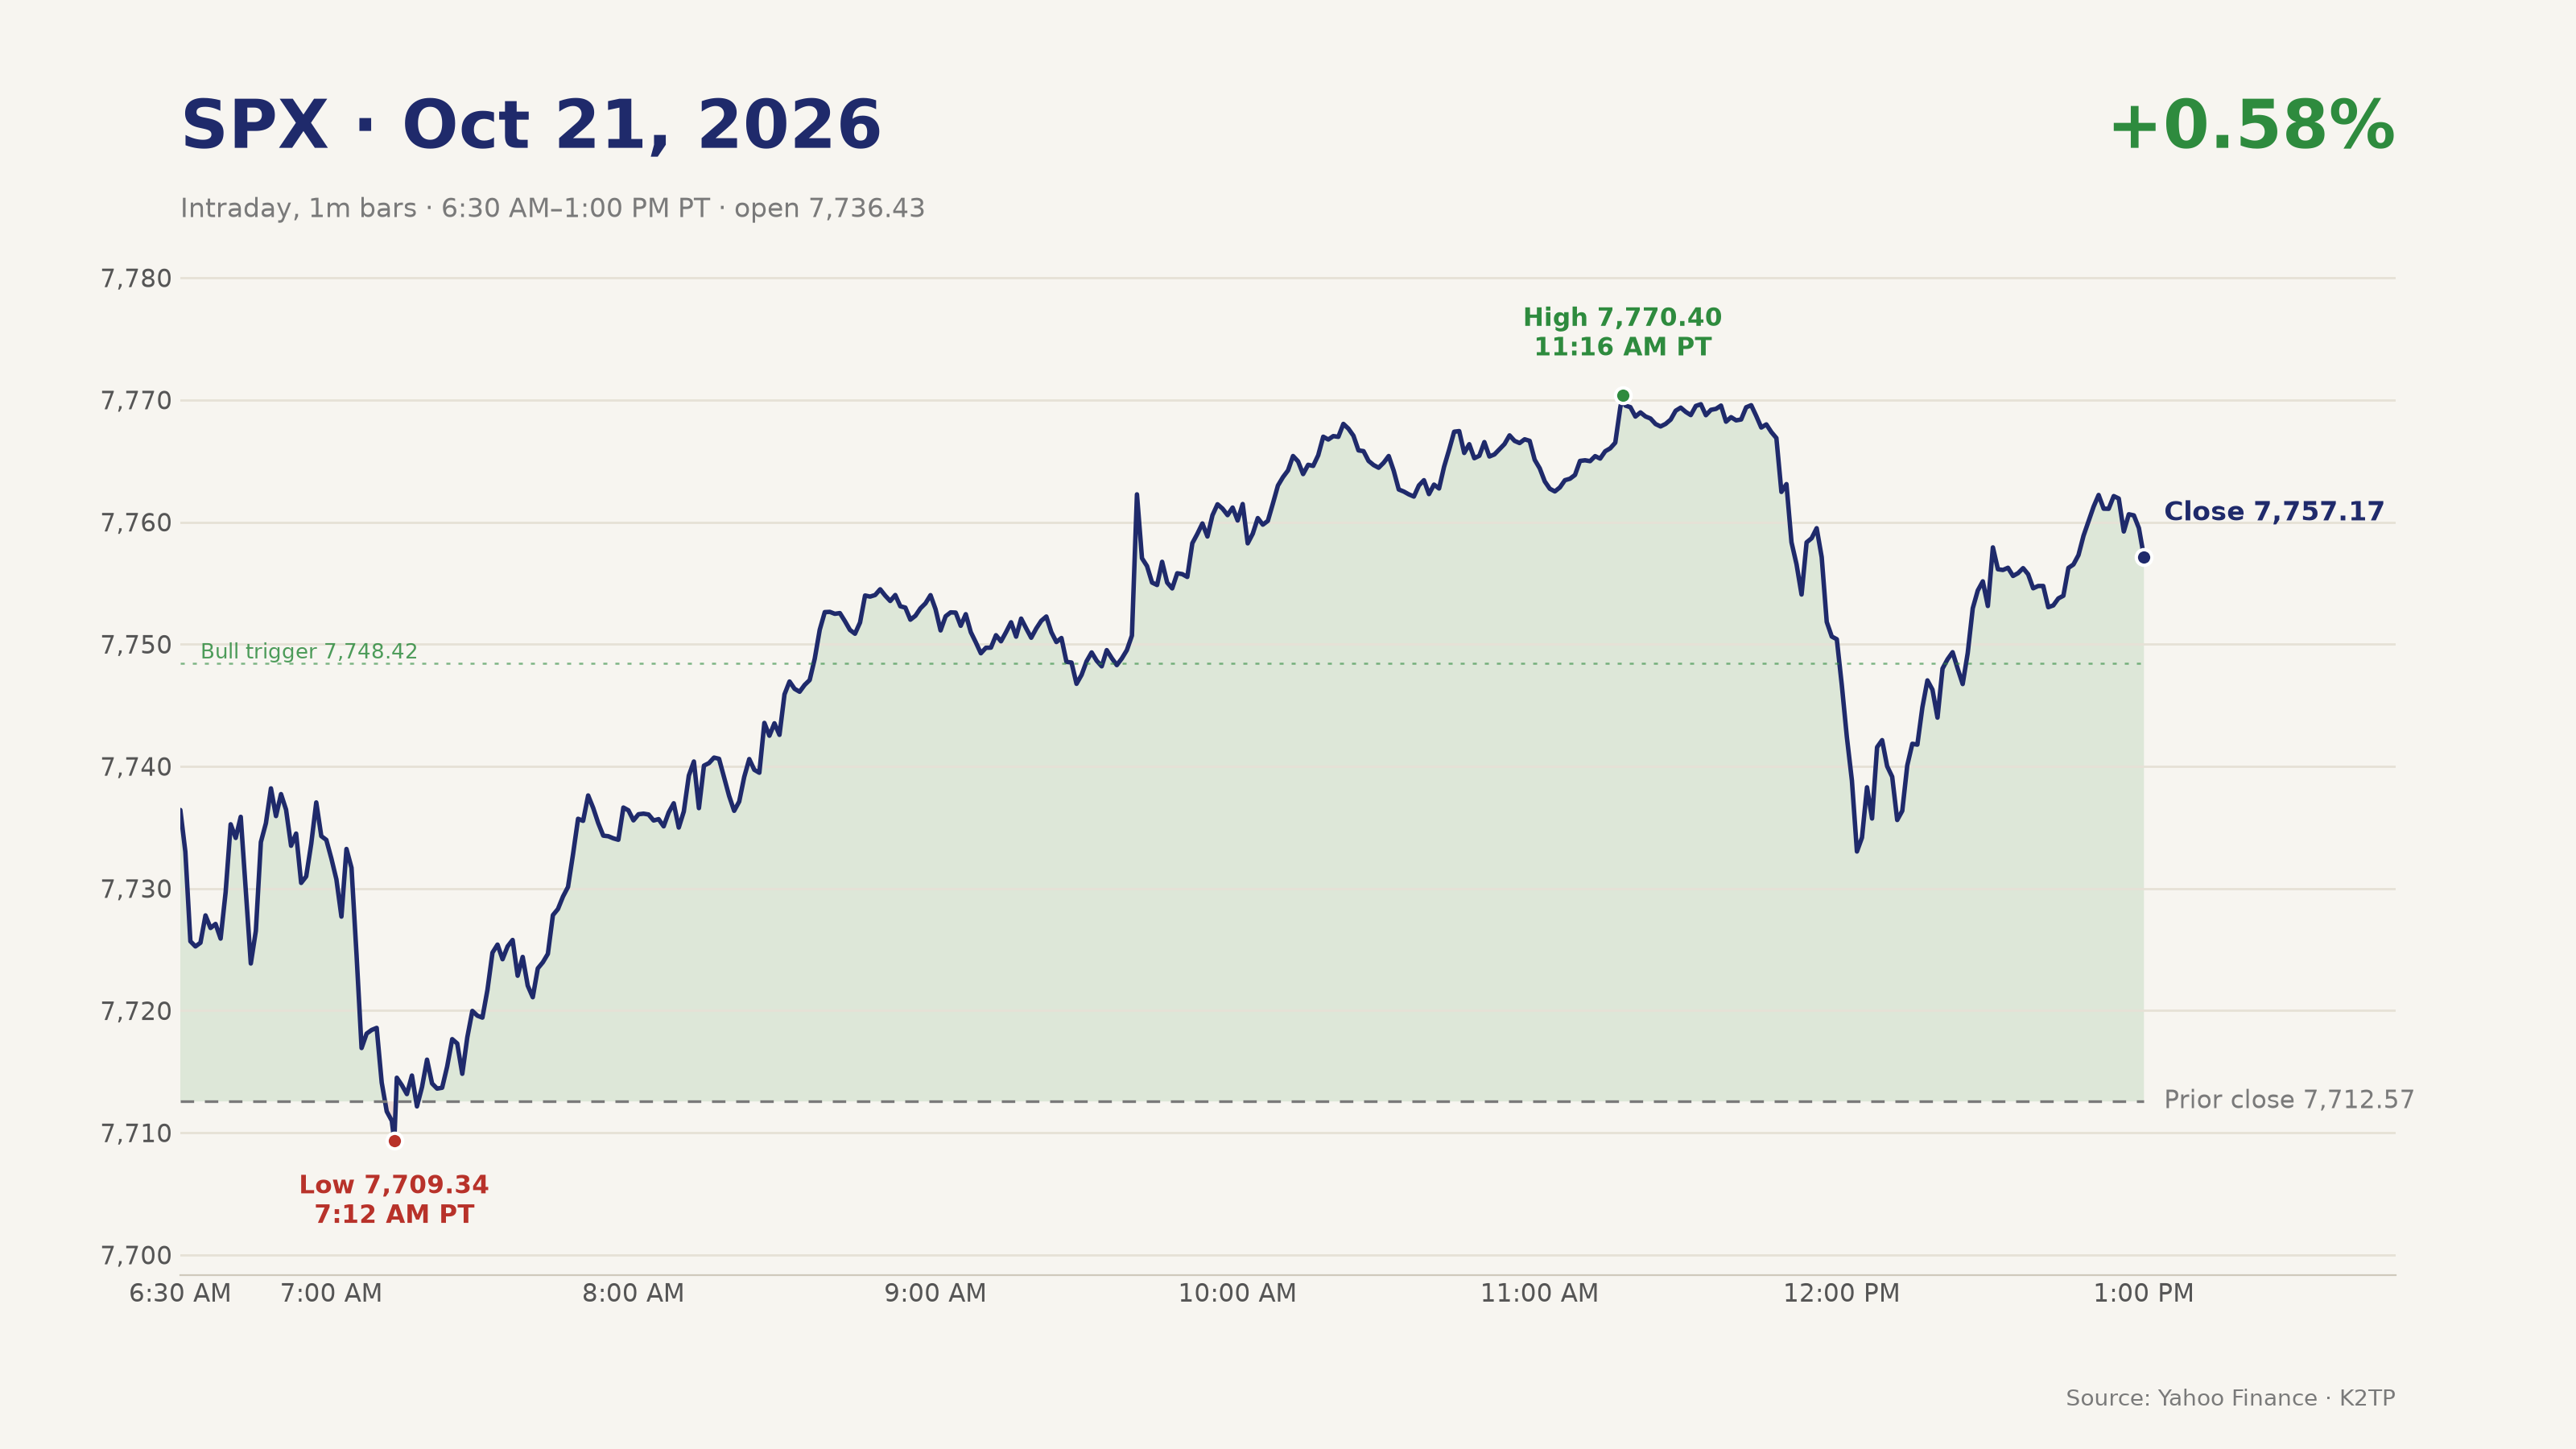
- Opened at 7,736.43; low of 7,709.34 at 7:12 AM PT, still above Tuesday's close
- Crossed 7,748.42 by midday (7,752.15 at midday, VIX 16.60), which tipped the K2TP Midday read to RISK-ON
- High of 7,770.40 at 11:16 AM PT, then a drop to 7,730.96 at 12:03 PM PT on the Gulf headline; pre-close 7,739.43
- Closed at 7,757.17 (+44.60 points), 8.75 points above 7,748.42 and 13.23 points below the high
- The Pre-Close Bull trigger (SPX close above 7,748.42 with VIX under 16.51) was half met: VIX closed at 16.68. The Bear trigger (SPX under 7,709.34 with VIX above 17.46) did not fire
→ A real breakout above Tuesday's high, but it shook hard on one headline and VIX never broke 16.51. Price improved; confirmation did not come.
AFTER HOURS: META UP, TESLA, IBM AND LAM DOWN
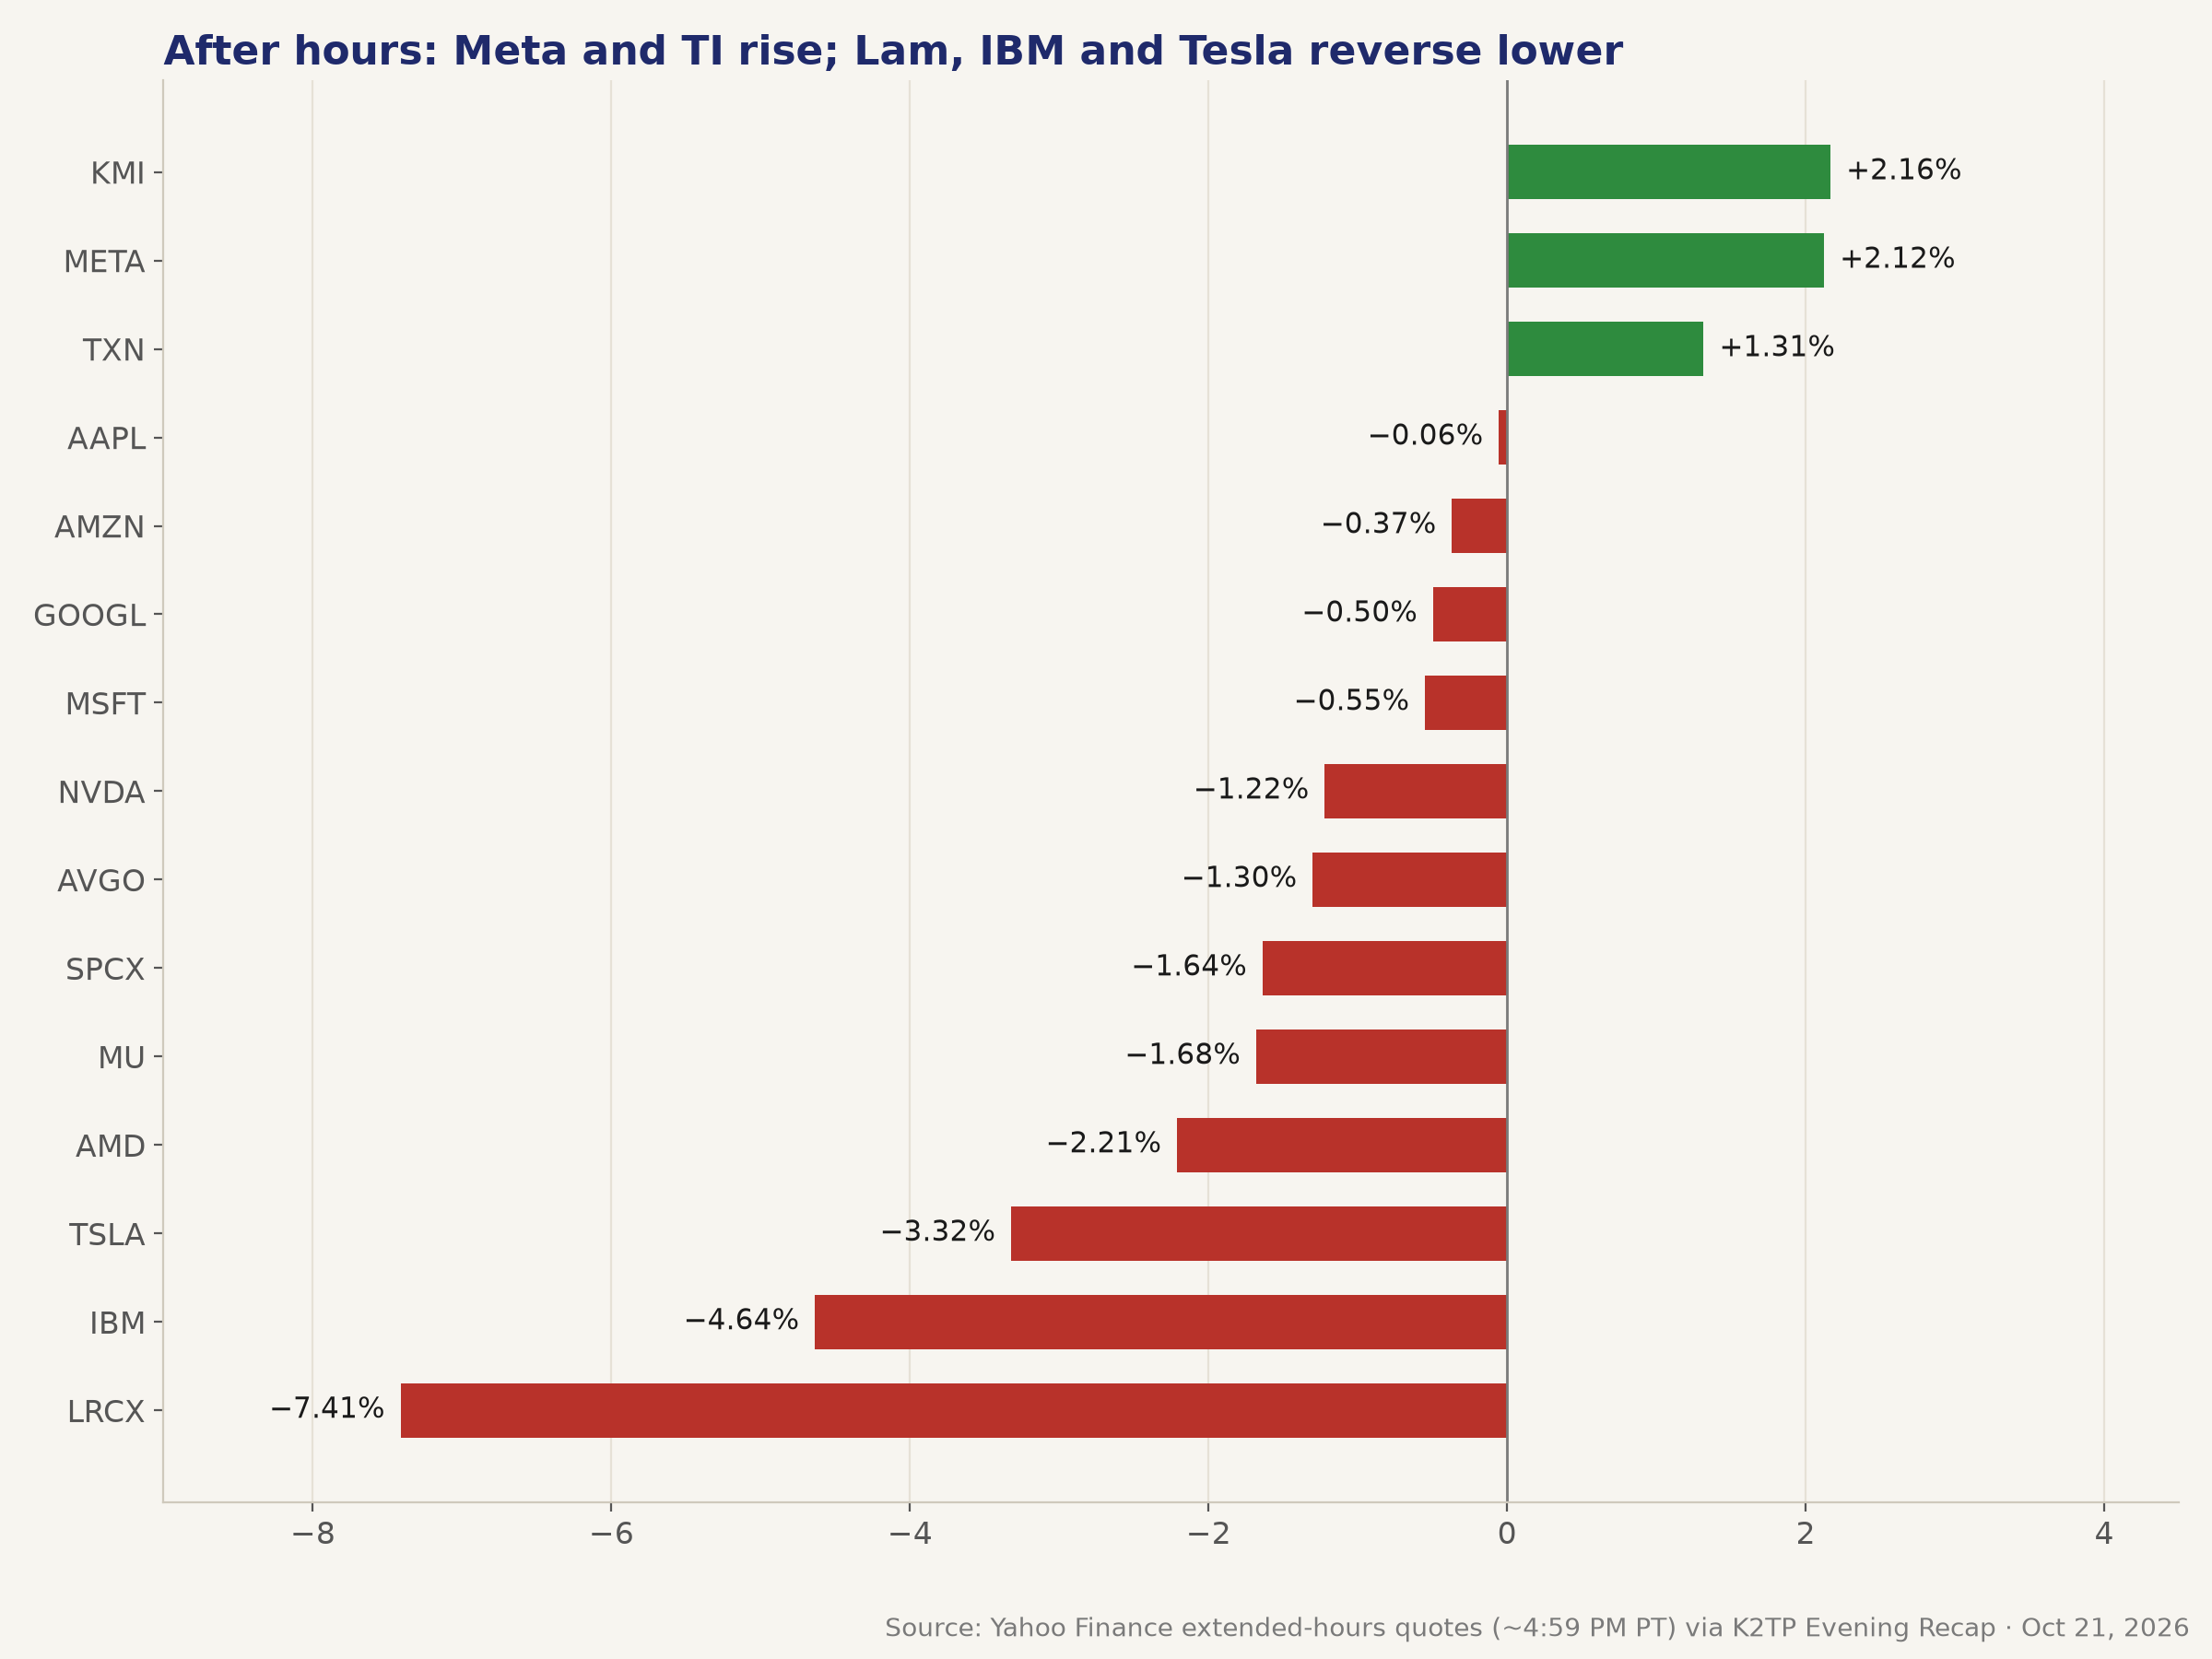
- Lam Research (LRCX) −7.41% to $241.48: record revenue of $8.22B, non-GAAP EPS $2.20; December-quarter guide $8.60B ± $0.40B and EPS $2.33 ± $0.15, only slightly above estimates 🔴
- Chip equipment pulled the group: NVDA −1.22%, AMD −2.21%, MU −1.68%, AVGO −1.30%, SPCX −1.64%; KLA and Applied Materials fell in sympathy (Investing.com)
- IBM −4.64% to $239.80: operating EPS $2.95 vs $2.86, revenue $17.10B vs $16.83B, but full-year constant-currency growth held at 4%–5%; an early ~4% gain reversed 🔴
- Texas Instruments (TXN) +1.31%: EPS $2.62 vs $2.42; revenue $6.06B vs $5.93B; Q4 revenue guide $5.80B–$6.30B vs $5.73B; data center revenue +95% y/y 🟢
- Kinder Morgan (KMI) +2.16%: EPS $0.35 on $4.53B revenue
- Tonight (around 7 PM PT, Yahoo): ES 7,763.75 (−0.47%), NQ 29,733.25 (−0.91%)
→ Tonight's reaction is mixed: Meta and TI held up, while chip equipment and Tesla gave back part of the day's AI gains. Thursday's open starts from a weaker NQ.
MARKET: PRICE UP, PARTICIPATION DOWN
Indices (close):
- SPX 7,757.17 (+0.58%), day range 7,709.34–7,770.40
- NDX 29,822.52 (+1.13%); Nasdaq Composite 26,702.86 (+1.05%)
- DJIA 52,856.09 (+0.69%)
- RUT 2,781.02 (+0.27%)
- RSP 216.64 (+0.36%)
- SOX 11,505.56 (+1.97%)
Session path: ES +0.30% and NQ +0.58% pre-market on SpaceX and Super Micro. SPX opened at 7,736.43, fell to 7,709.34 at 7:12 AM PT, was 7,752.15 at midday, peaked at 7,770.40 at 11:16 AM PT, dropped to 7,730.96 at 12:03 PM PT, was 7,739.43 at pre-close and closed at 7,757.17.
Sector Rotation:
- Gainers: XLK +1.67%, XLI +0.91%, XLF +0.57%, XLU +0.29%, XLE +0.28%, XLB +0.18%, XLY +0.03%
- Decliners: XLC −1.11%, XLRE −0.76%, XLP −0.73%, XLV −0.49%
- Mega-caps: TSLA +3.41%, AMD +3.36%, NVDA +2.54%, TSM +1.60%, AAPL +1.32%, AVGO +1.03%, META +0.47%, MSFT +0.20%; AMZN −0.10%, GOOGL −1.62%
Market Internals:
- NYSE: advancers led decliners 1.37-to-1; 131 new highs vs 221 new lows (Reuters)
- Nasdaq: 2,690 advancers vs 2,068 decliners (1.3-to-1)
- Early in the session NYSE breadth was 2.06-to-1; it faded through the afternoon
Volatility:
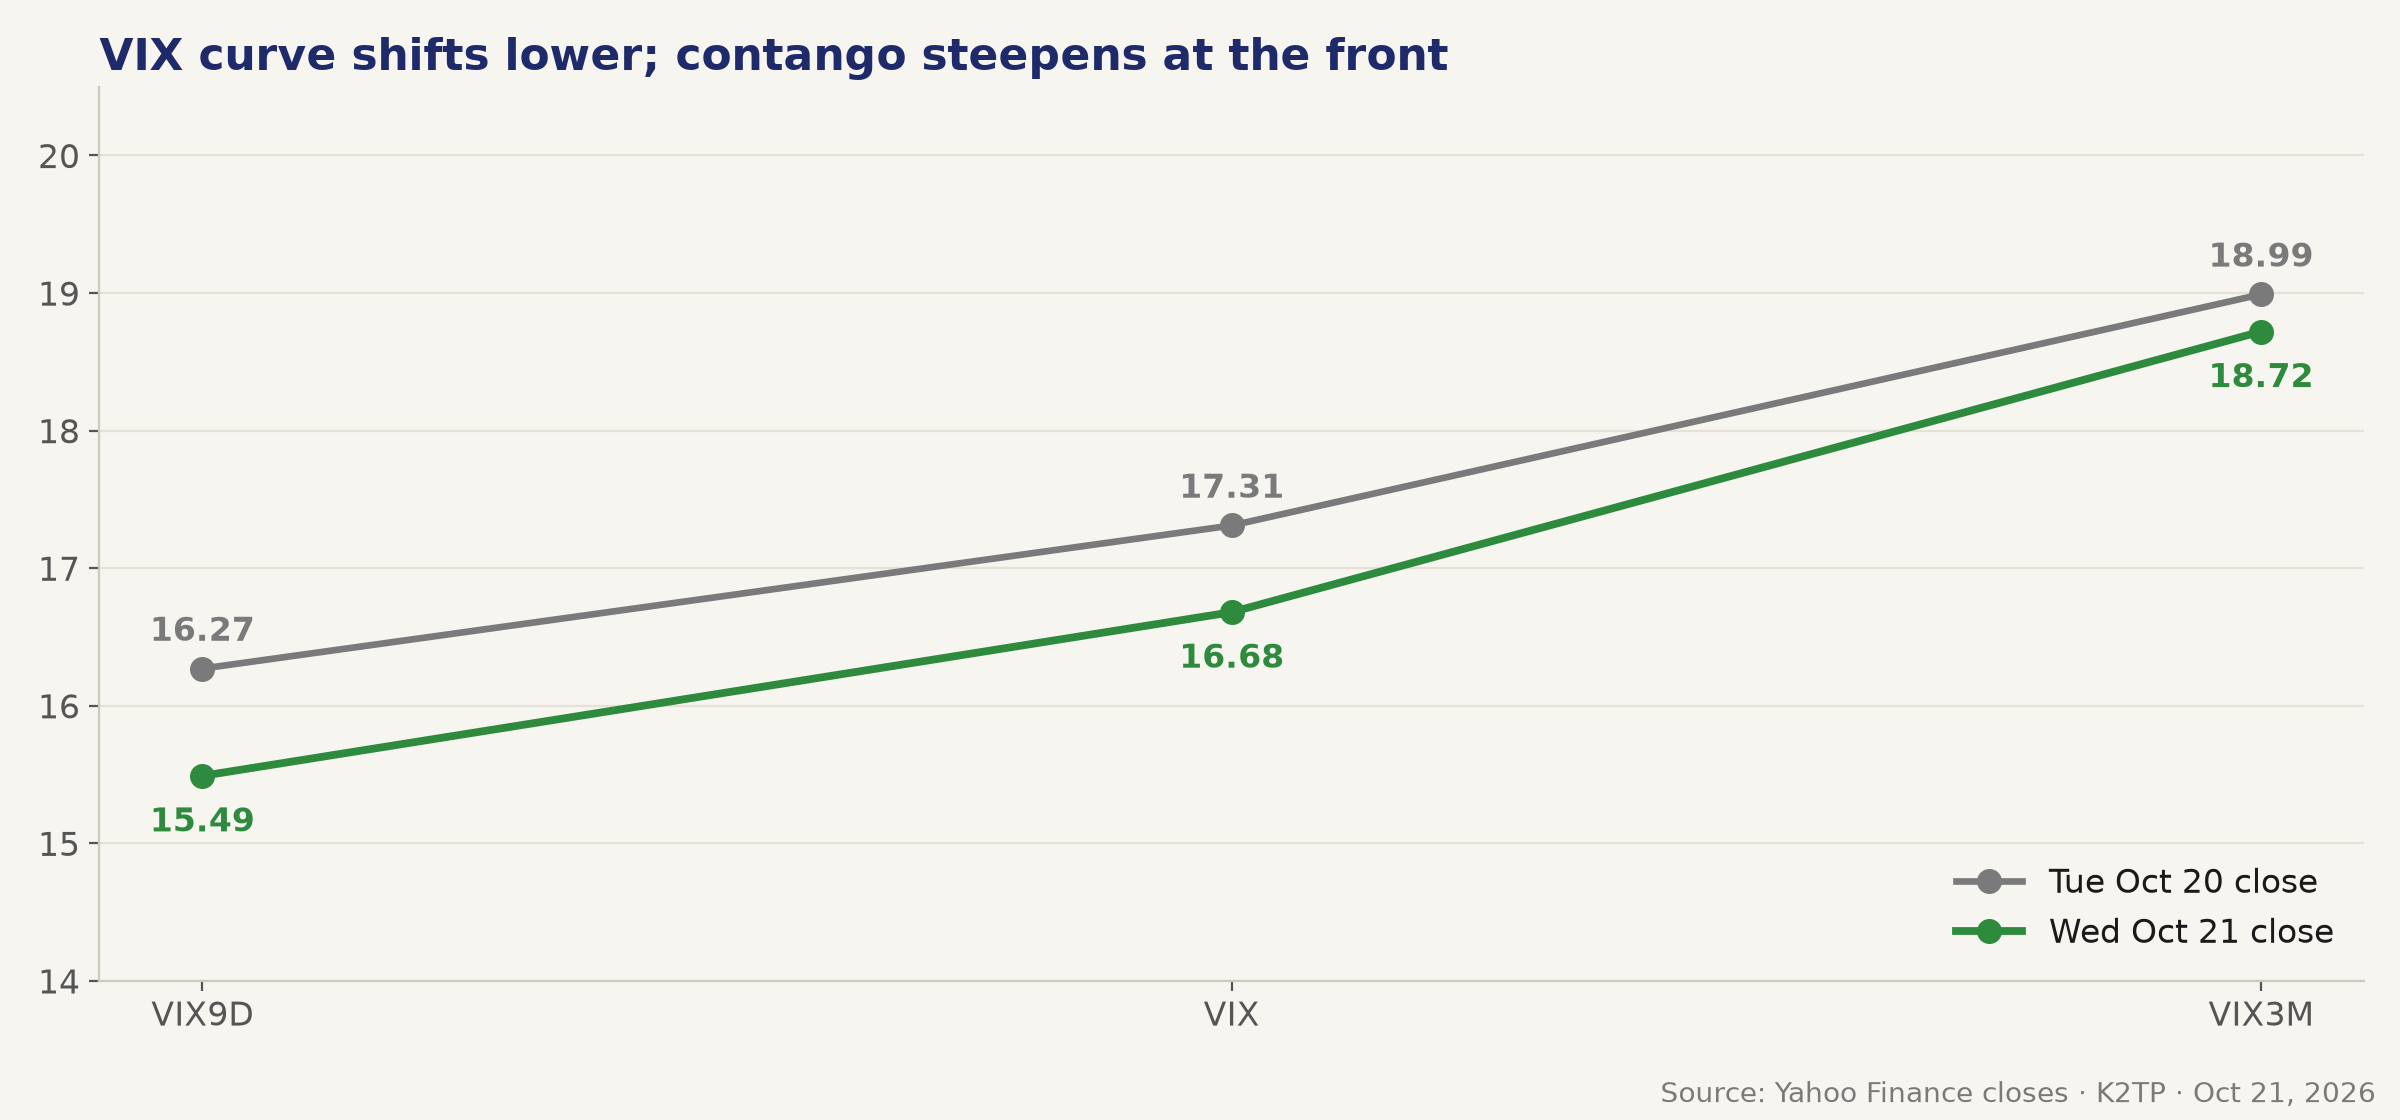
- VIX 16.68 (−3.64%), range 16.51–17.58
- VIX9D 15.49 (from 16.27), VIX3M 18.72 (from 18.99): the curve shifted lower and the front end fell fastest
- VVIX 94.55 (−2.68%)
Cross-asset:
- DXY about 101.73; gold about $4,127 tonight (−0.56%); BTC about $83,300 (Yahoo, around 7 PM PT)
Global:
- Asia (Wednesday): Kospi +3.29%, Nikkei +0.85%, Taiwan +0.14%; Hang Seng −2.21%, Shanghai −0.48%
- Europe: Euro Stoxx 50 +1.40%, DAX +1.35%, CAC +1.06%, FTSE +0.19%
- Tonight (around 6:50 PM PT, Yahoo): Nikkei −0.67%, Kospi −1.93%; the Bank of Korea held its base rate at 3.00%
SPX Key Levels:
- 7,770.40: Wednesday's high, Bull line
- 7,757.17: close
- 7,748.42: Tuesday's high, now first support
- 7,730.96: low of the midday Gulf-headline drop
- 7,712.57: Tuesday's close
- 7,709.34: Wednesday's low, Bear line
- VIX: 16.51 and 17.58
Option-seller angle:
- Bull case: SPX above 7,770.40 with VIX under 16.51 tips the regime to RISK-ON. Far OTM SPX put spreads then make sense, with moderate size into Friday's PMIs and next week's FOMC.
- Bear case: SPX under 7,709.34 with VIX above 17.58 pulls the tape toward RISK-OFF. Then cut short-put size and favor defined-risk spreads.
- VIX9D under VIX and contango to VIX3M still favor short-dated index premium sellers, but tonight's Gulf headlines and NQ −0.91% argue for wider strikes on NDX than on SPX.
- After-hours reversals in TSLA, LRCX and IBM raise single-name gap risk at the open; avoid tight Iron Condors on those names until the open settles.
BOTTOM LINE
- AI hardware led a third straight SPX gain and a close above 7,748.42: SOX +1.97%, NDX +1.13%, SPCX +7.79%, SMCI +9.55%.
- The rally narrowed (RSP +0.36%, NYSE 1.37-to-1, more new lows than highs) while a tailing 20-year auction lifted the 10Y to 5.146%.
- The regime stays 🟡 TRANSITION. Meta beat, but Tesla, Lam and IBM reversed lower after hours, and Gulf headlines pushed ES −0.47% tonight; confirmation needs SPX above 7,770.40 with VIX under 16.51.
What to watch tomorrow (PT):
- Before the open: Procter & Gamble, Comcast, Honeywell, Lockheed Martin, Union Pacific, Blackstone, Valero, American Airlines, Dow
- 5:30 AM: initial jobless claims (prior 199K, forecast 200K)
- 7:00 AM: Conference Board Leading Economic Index (Sep); 8:00 AM: Kansas City Fed manufacturing survey (Oct)
- After the close: Western Digital, Newmont, Bloom Energy, Deckers, VeriSign, Omnicom, Comfort Systems
- Friday 6:45 AM: S&P Global flash October PMIs (manufacturing 55.5 expected vs 55.9; services 58.0 vs 58.8)
- Oct 27–28: FOMC, decision at 11:00 AM on Oct 28; Fed blackout through Oct 29
Expected (Bull): Gulf headlines calm, Brent slips back under $110, ES recovers tonight's loss, SPX takes out 7,770.40 and VIX breaks below 16.51. Expected (Bear): Gulf escalation pushes Brent higher, Tesla and chip equipment drag NQ at the open, SPX loses 7,709.34 and VIX rises above 17.58.
Sources: 4 K2TP briefs for Oct 21, 2026 (Pre-Market, Midday, Pre-Close, Evening Recap). Closing, intraday and after-hours prices from Yahoo Finance; breadth, auction and news from Reuters, CNBC, Dow Jones, WSJ, Investing.com and FinancialJuice; Sankeys from Meta's Q3 2026 press release and Tesla's Q3 2026 Update (8-K Ex. 99.1, SEC EDGAR). Analysis: K2TP Framework.