Market 10/19: Amazon and Chips Lift the Nasdaq, SOX Snaps Its Longest Losing Streak Since 2008
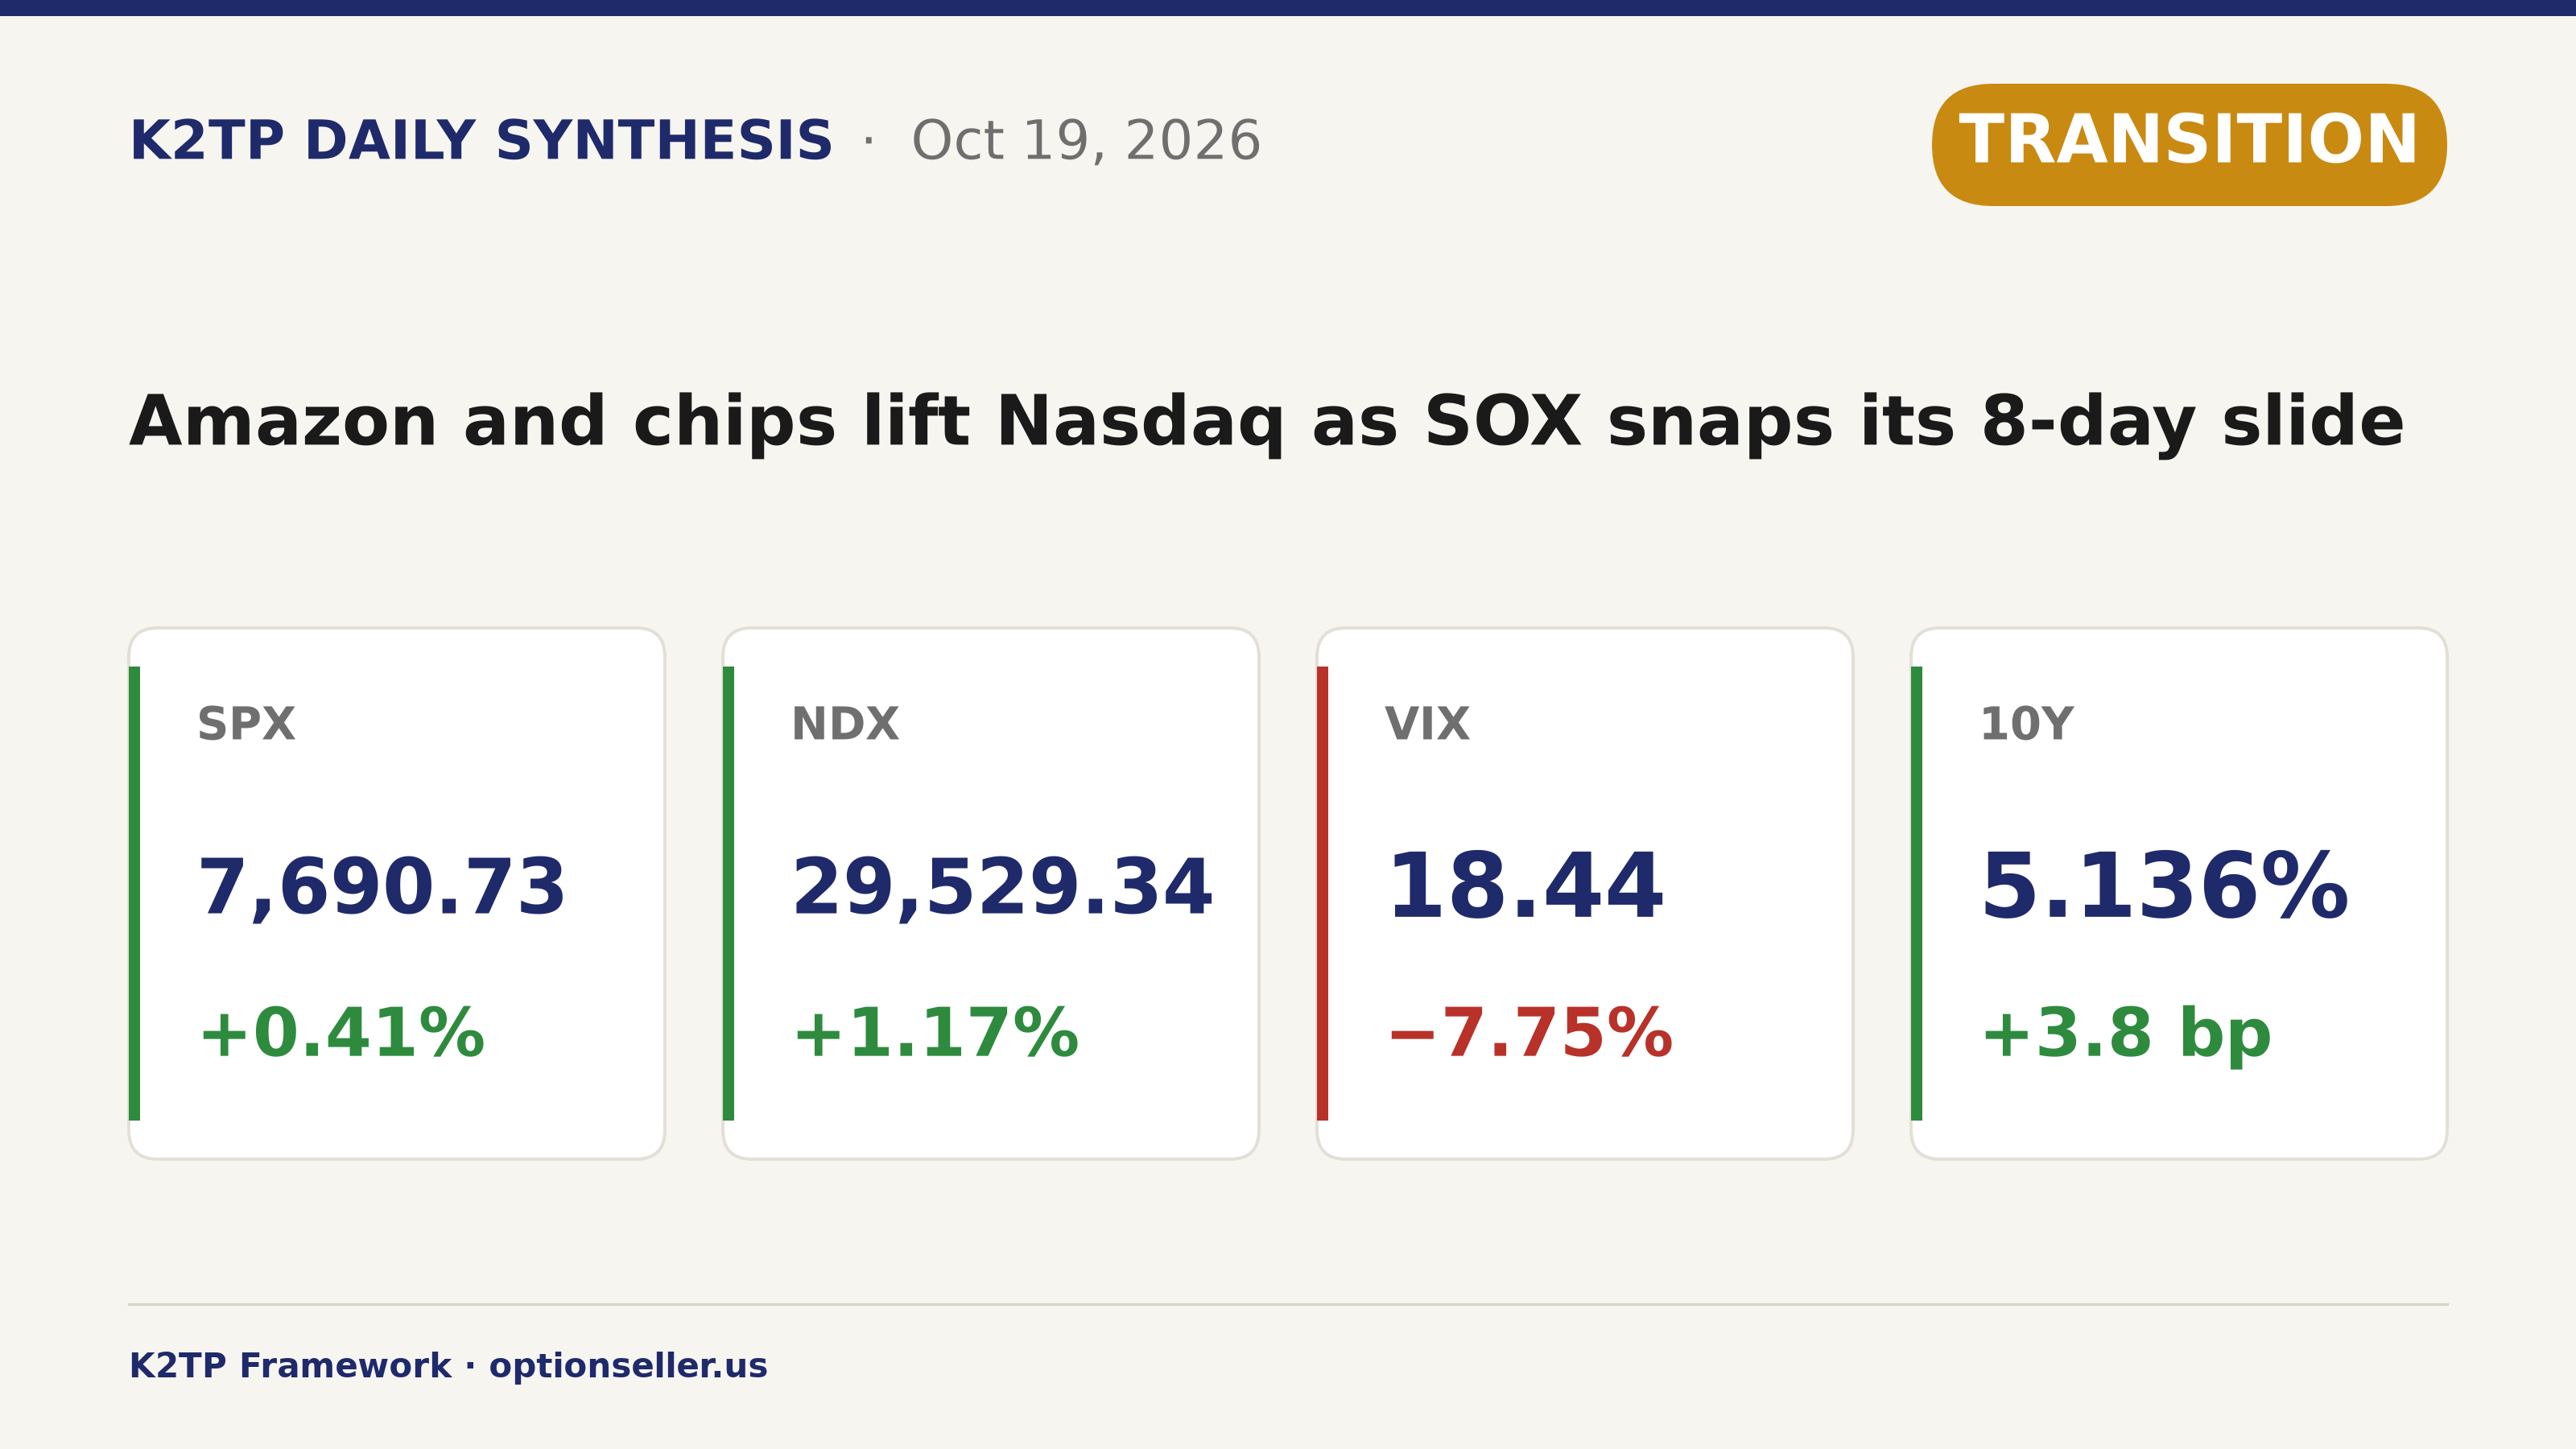
SPX +0.41%, NDX +1.17%, VIX −7.75%. Mega-caps and semis carried the bounce while the average stock, bonds and Europe slipped, and SPX faded into the close.
KEY HEADLINES
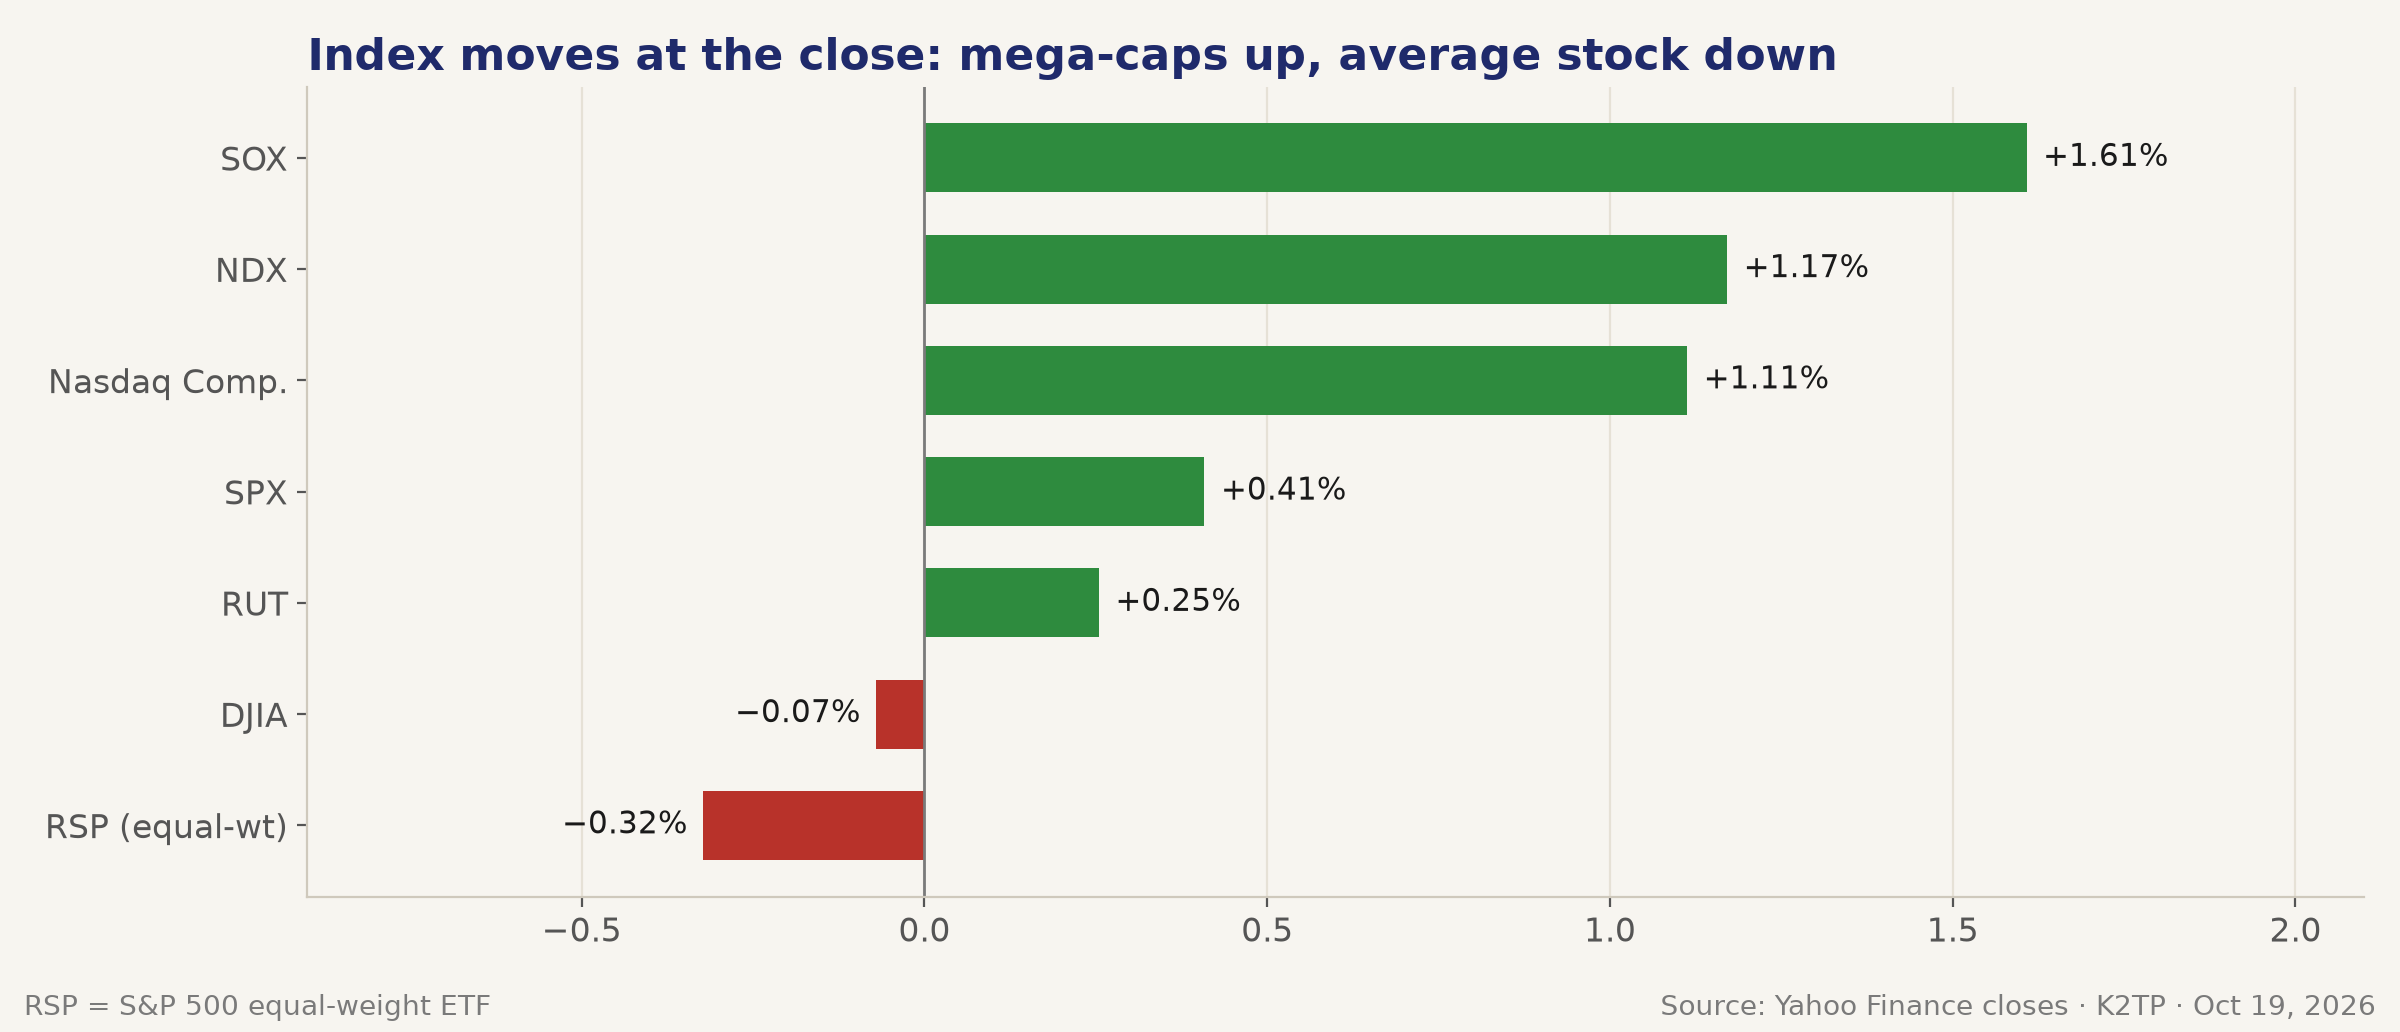
- SPX +0.41% to 7,690.73 and NDX +1.17% to 29,529.34; the Dow −0.07% and equal-weight RSP −0.32%
- SOX +1.61% snapped an eight-day, ~15.7% losing streak, its longest since October 2008 (Reuters)
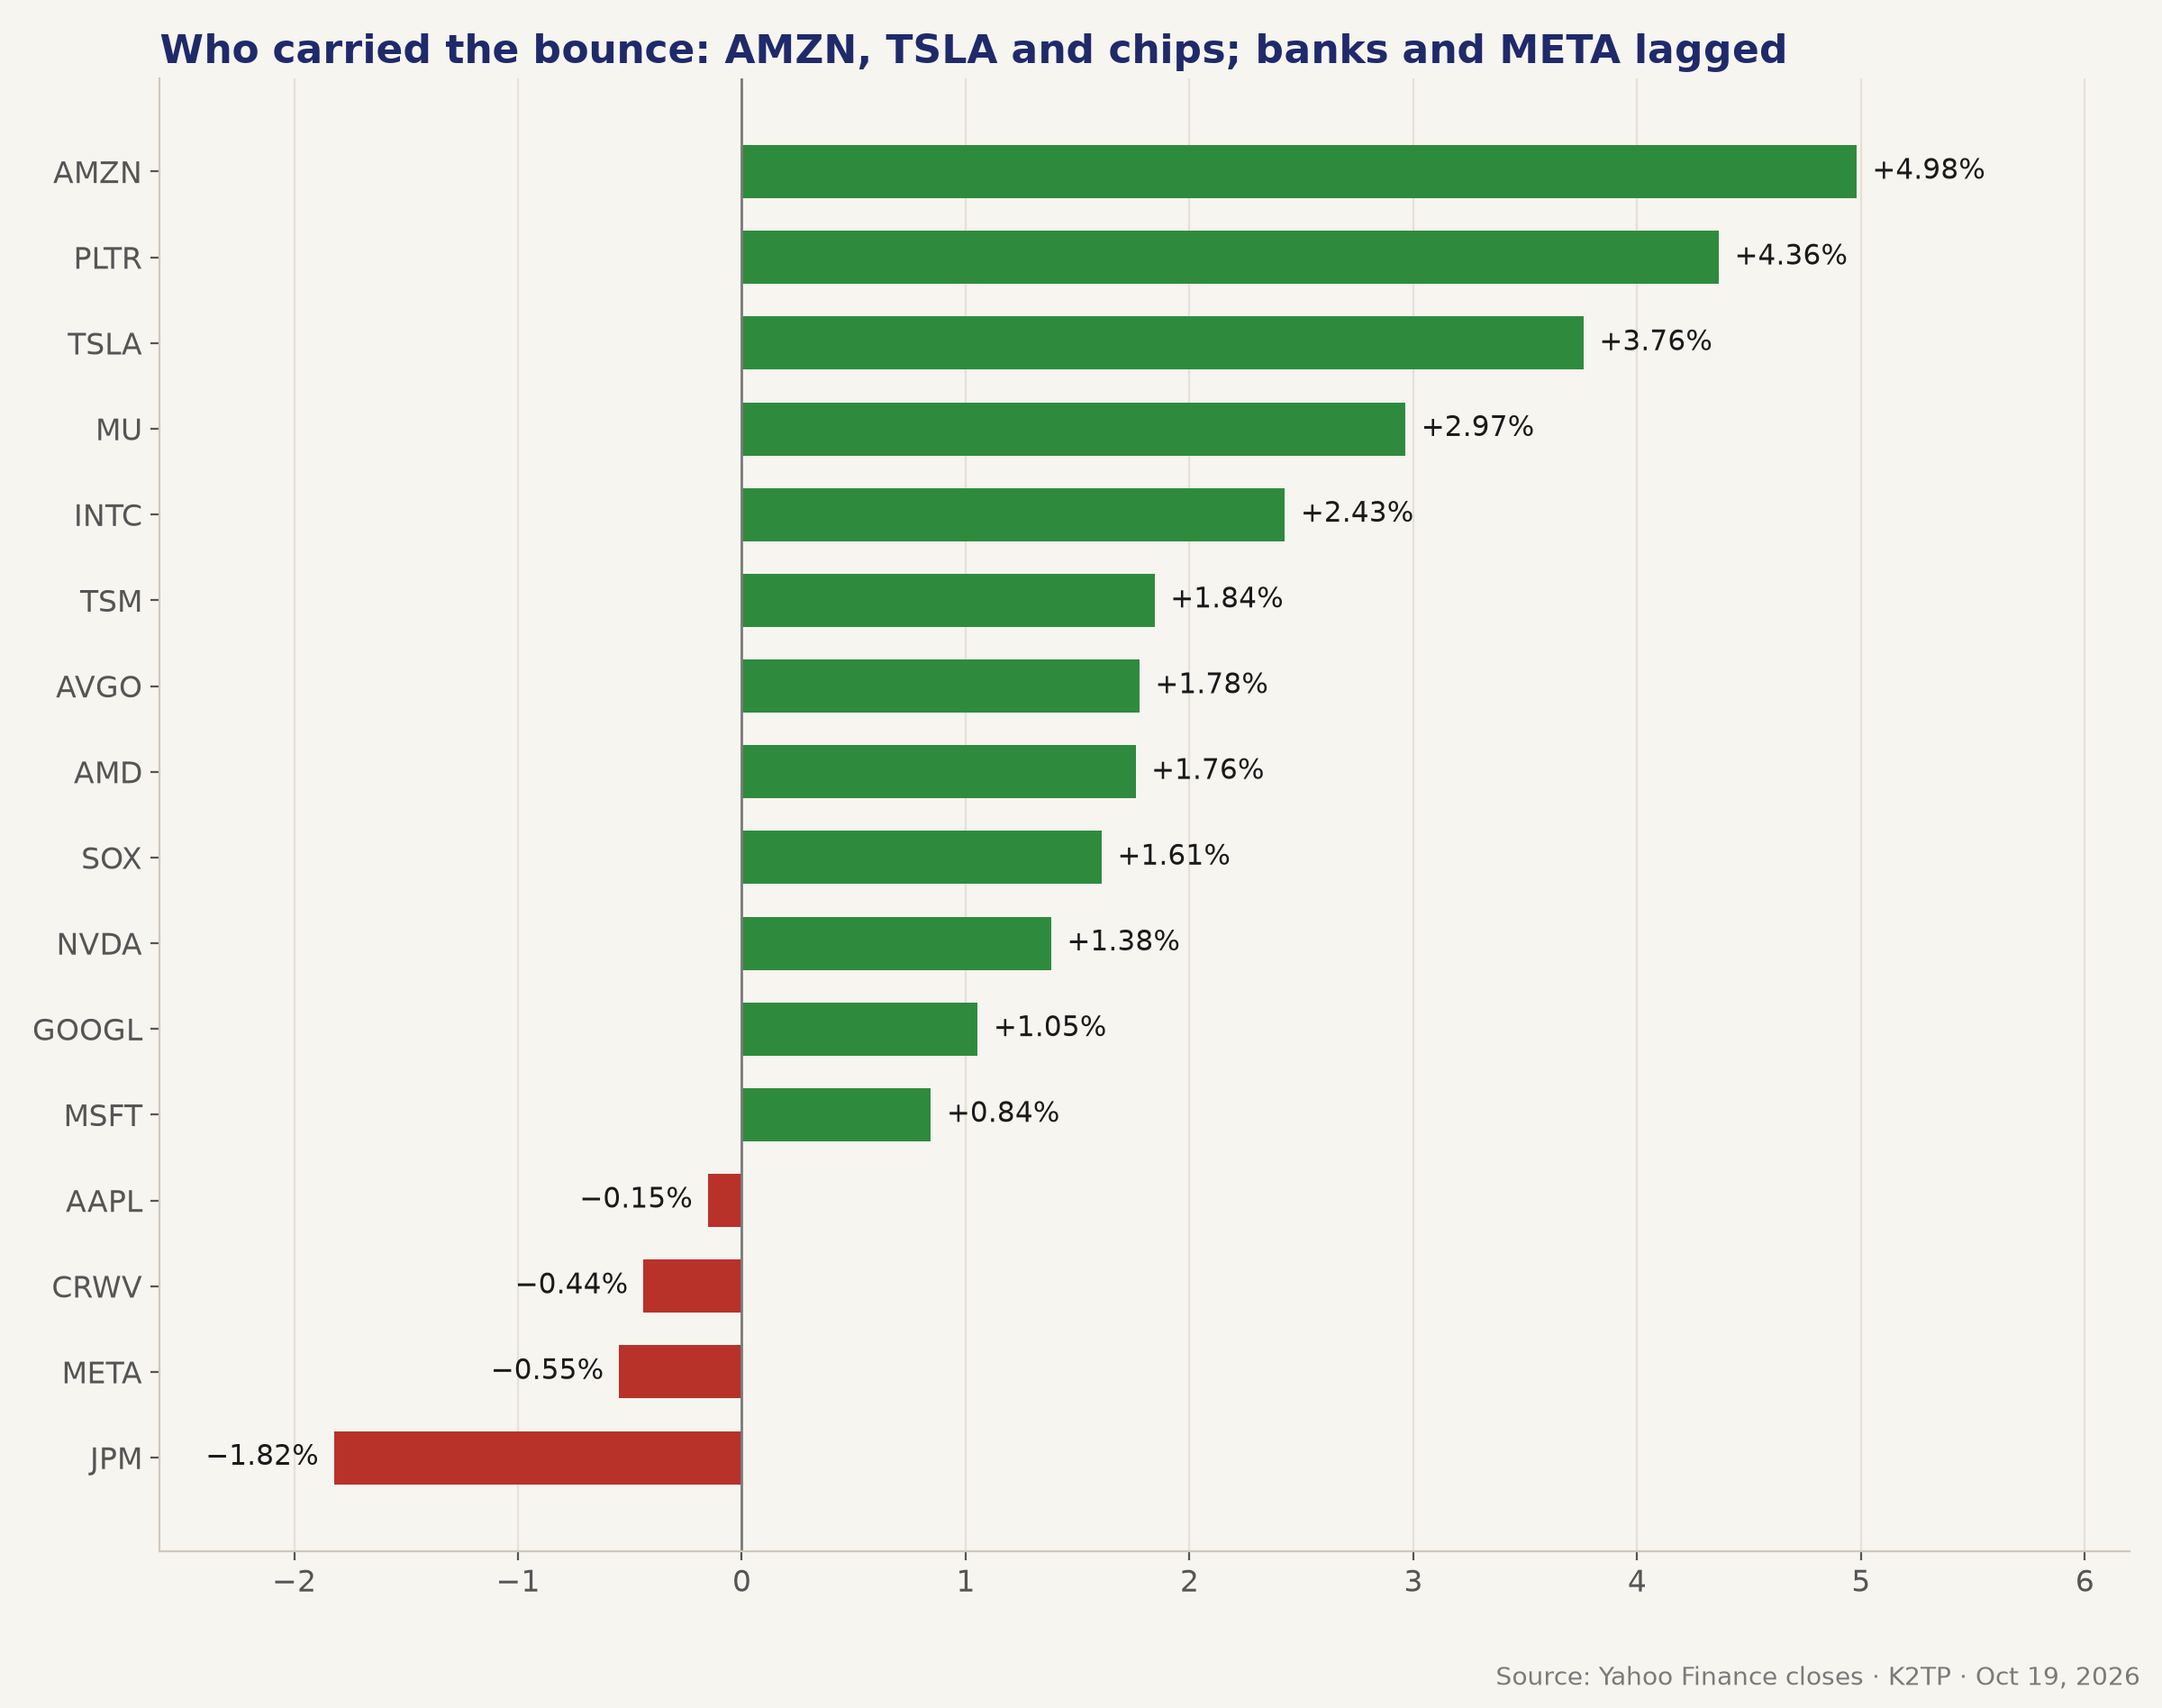
- AMZN +4.98% after Morgan Stanley named it a top pick ($350 target); TSLA +3.76%. Those two explain most of the SPX–RSP gap
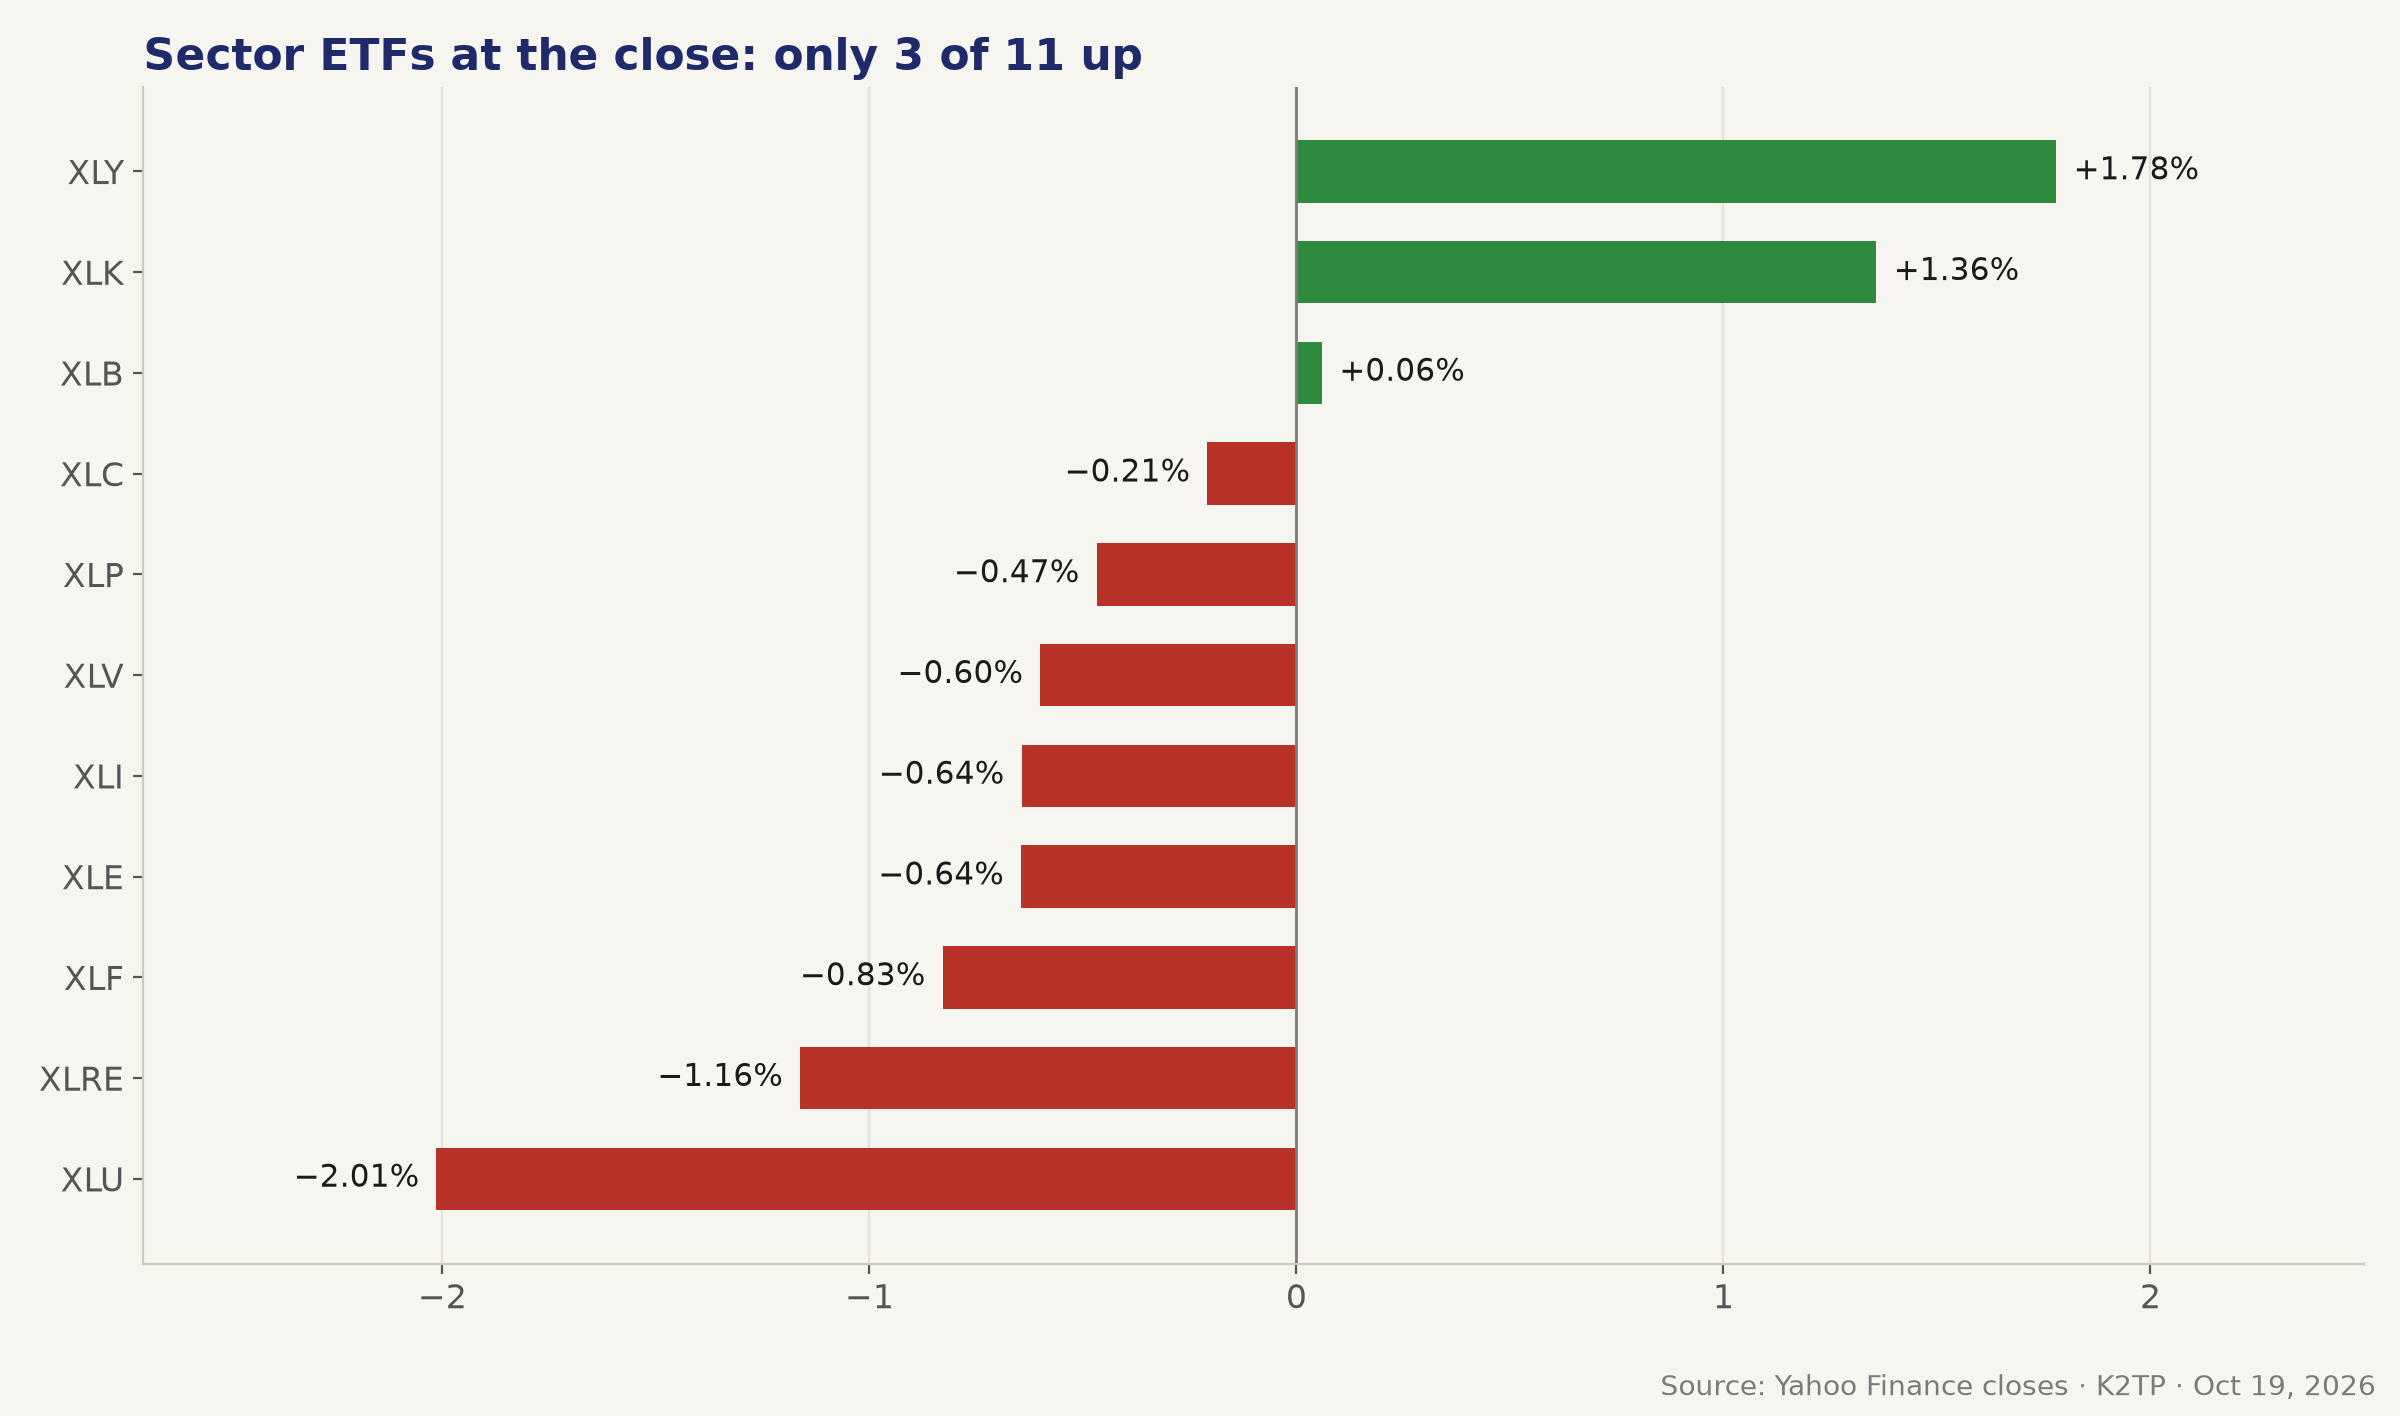
- Only 3 of 11 sector ETFs rose; NYSE decliners led 1.69-to-1 on below-average volume
- SPX faded ~19 points in the final 18 minutes and closed 0.83 points below Friday's 7,691.56 line
- 10Y +3.8 bp to 5.136%, 2Y 4.77% (+3 bp): last week's haven bid reversed; NAHB fell to 29, lowest since June 2012
- November WTI settled +2.2% at $103.66 after Houthi attacks on Saudi sites; Brent −0.3% at $109.55
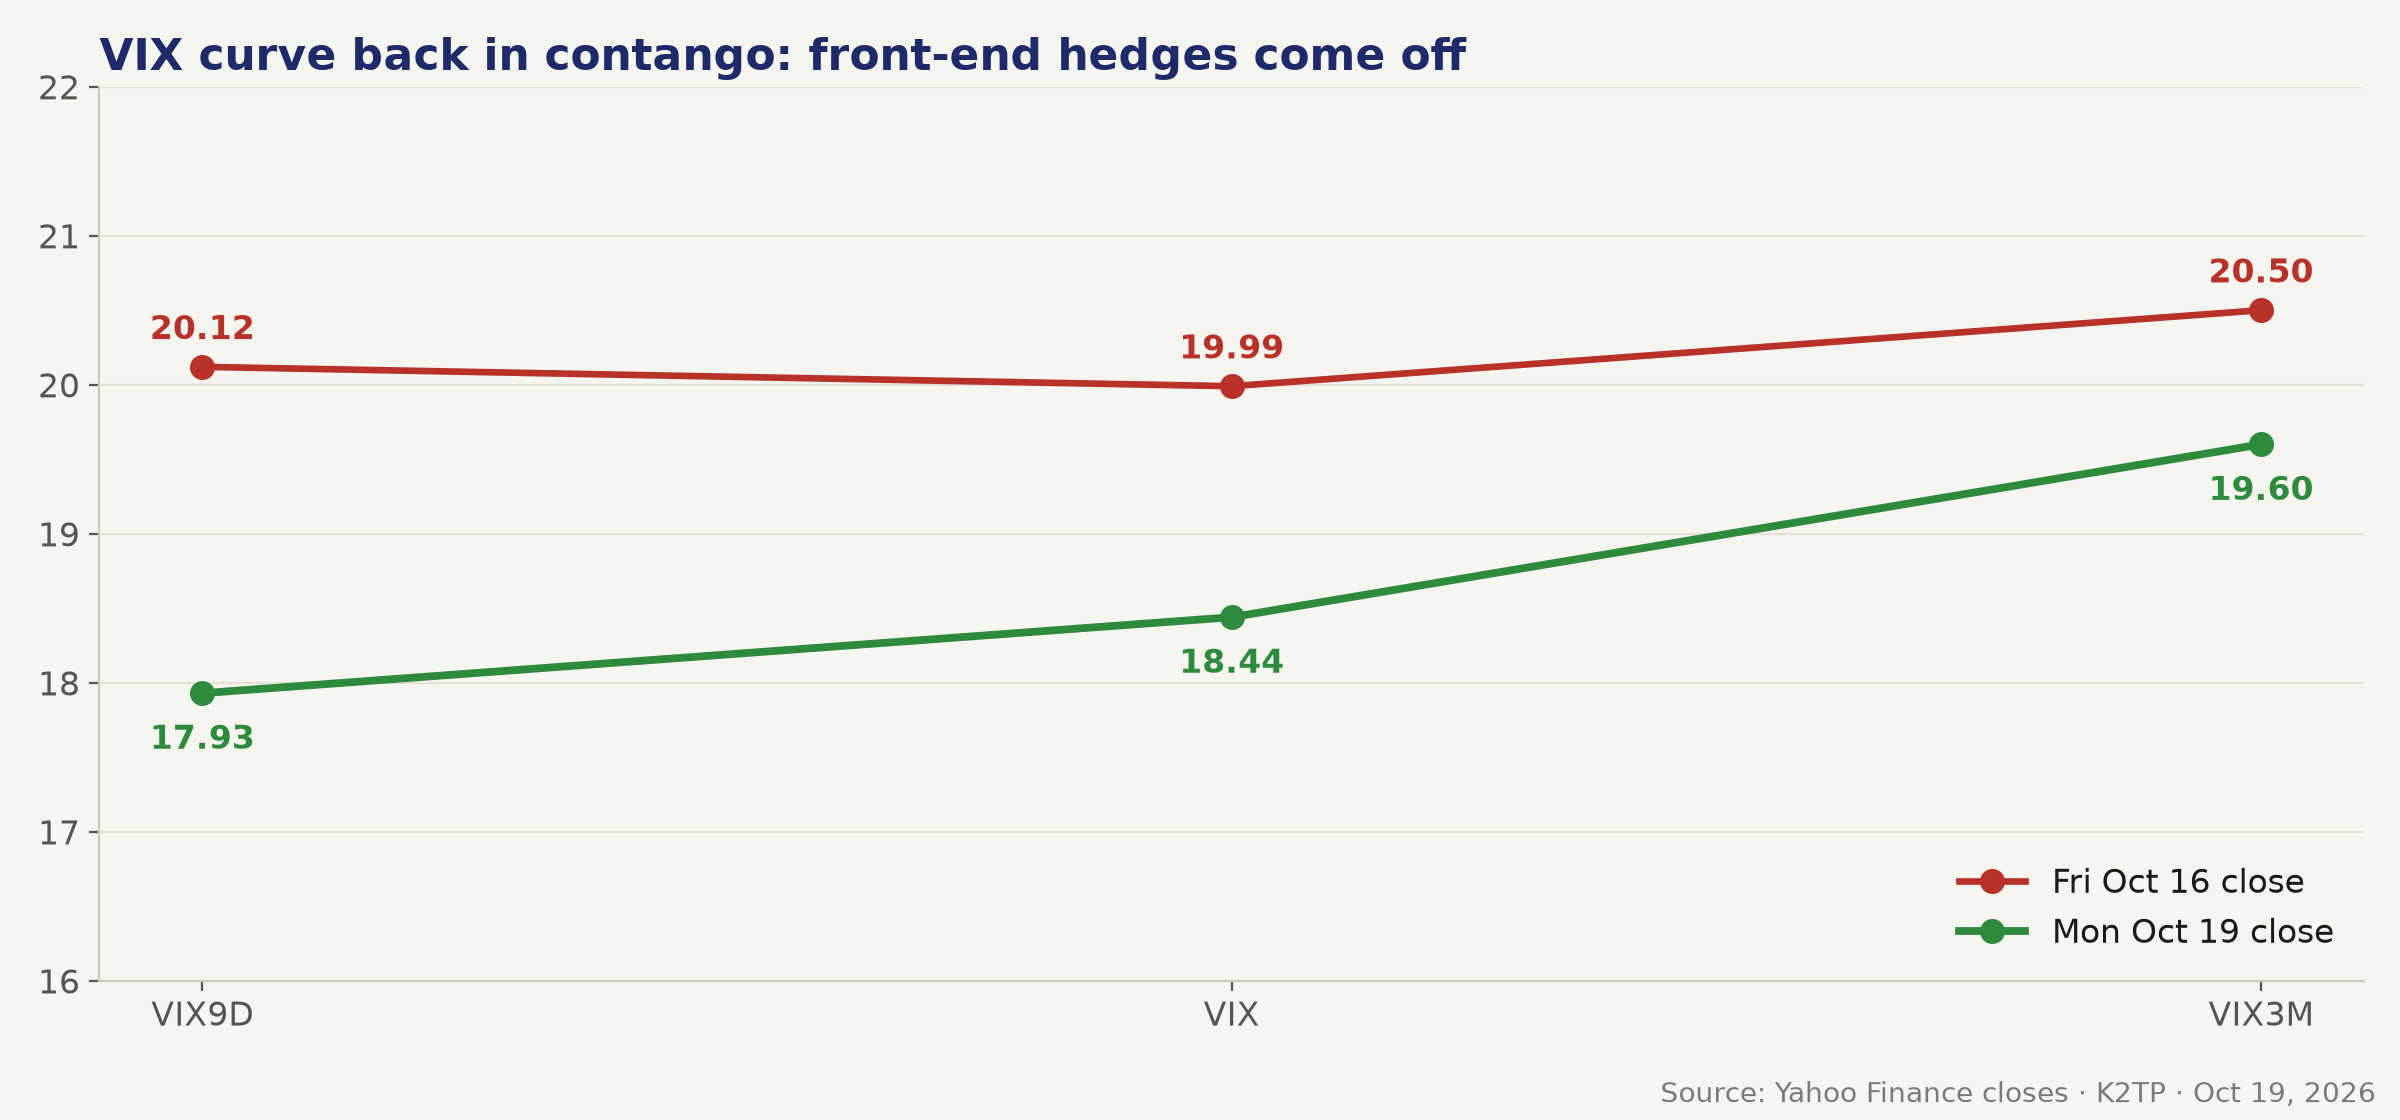
- VIX 18.44 (−7.75%) and the curve is back in contango (VIX9D 17.93 < VIX < VIX3M 19.60)
- After the close: Steel Dynamics missed its own EPS guidance (−4.6% after hours); Zions beat on EPS
- Regime: 🔴 RISK-OFF pre-market → 🟡 TRANSITION from midday into the close
SOX SNAPS ITS LONGEST LOSING STREAK SINCE 2008
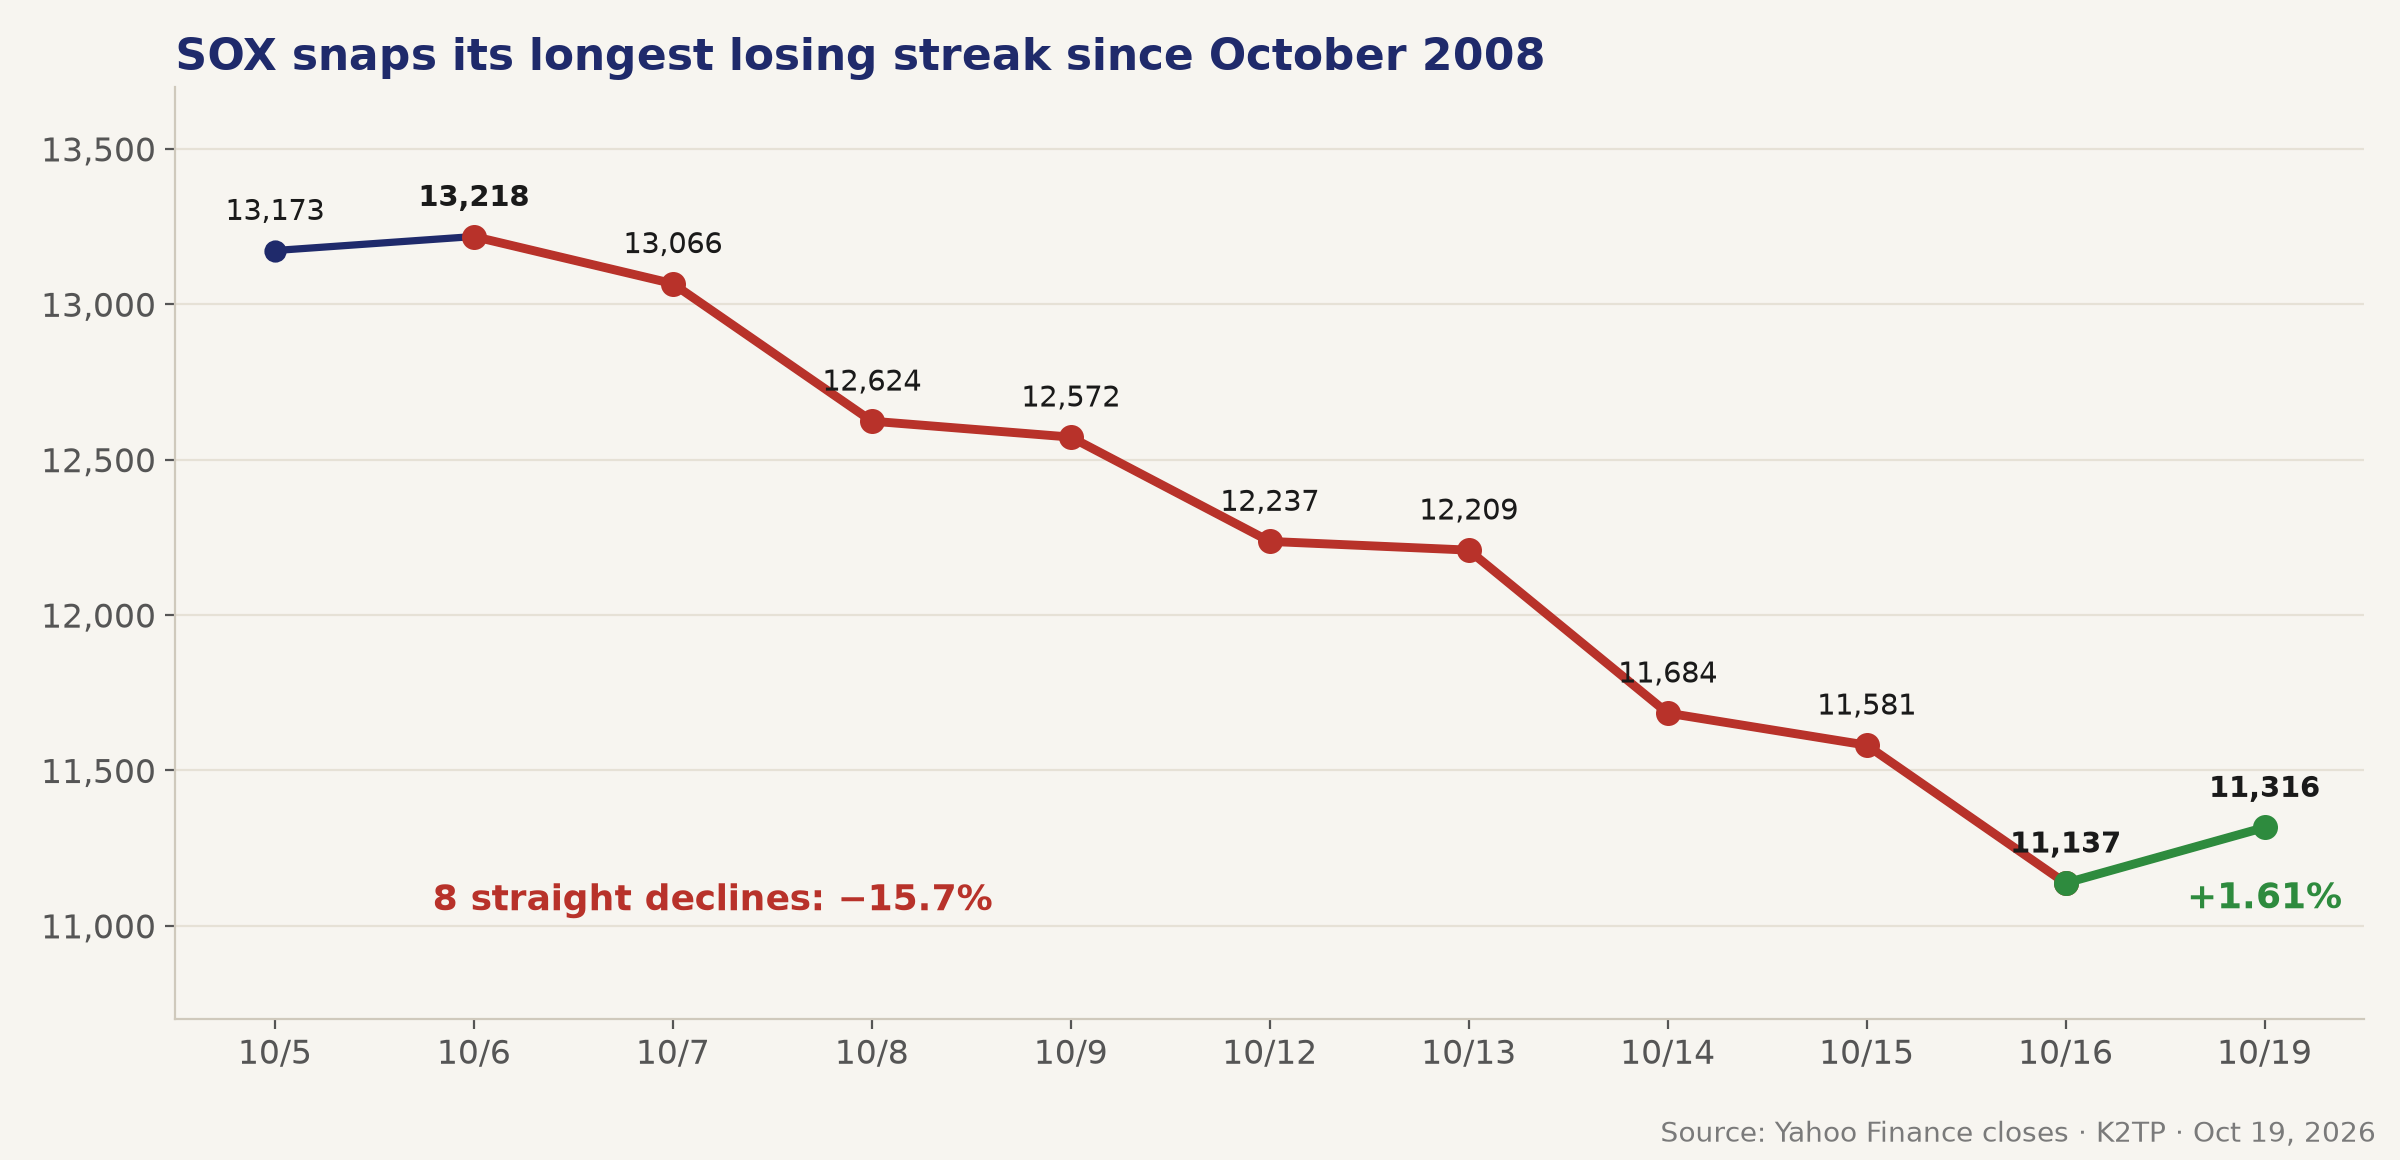
- SOX: 11,137.29 → 11,316.34 (+1.61%), after being up about 3.7% around 8:40 AM PT; session high 11,550.92 🟢
- The streak: eight straight declines from 13,217.82 (Oct 6) to 11,137.29 (Oct 16), −15.7%
- Chips at the close: SNDK +5.53%, MRVL +4.06%, MU +2.97%, INTC +2.43% (JPMorgan upgrade to neutral), TSM +1.84%, AVGO +1.78%, AMD +1.76%, NVDA +1.38%
- Most chip leaders closed below their opens: AMD 551.78 → 538.05, INTC 94.53 → 92.03, MU 913.55 → 904.90
- CoreWeave (CRWV) −0.44% to $61.12: up 7.35% pre-market on a Goldman Sachs upgrade to buy, then reversed (low $59.25)
- A Rosenblatt trader told Reuters "nothing changed" over the weekend except that sentiment was oversold, and the market is "far from out of the woods"
→ This was short covering in last week's most-sold group, not a new trend. CRWV failing to hold its upgrade pop shows the AI-credit worry has eased but not cleared.
AMAZON AND TESLA CARRY SPX; THE AVERAGE STOCK FALLS
- AMZN +4.98% to $262.45 (high $263.72): Morgan Stanley's Brian Nowak named it a top pick and raised the target to $350 from $335, citing AWS growth and margins, Bedrock, AI shopping and robotics 🟢
- TSLA +3.76% to $368.06 two days before its report; PLTR +4.36%
- Laggards: META −0.55% before Wednesday's report, AAPL −0.15%
- Sector ETFs: only 3 of 11 up (XLY +1.78%, XLK +1.36%, XLB +0.06%); Reuters had the S&P consumer discretionary sector +2.7%
- RSP −0.32% vs SPX +0.41%, a 73 bp gap; RUT +0.25%; NDX beat SPX by 76 bp
→ An index rally the average stock did not join. With breadth this narrow, SPX depends on a handful of mega-caps right before their earnings.
SPX HOLDS THE RANGE BUT SELLS OFF INTO THE CLOSE
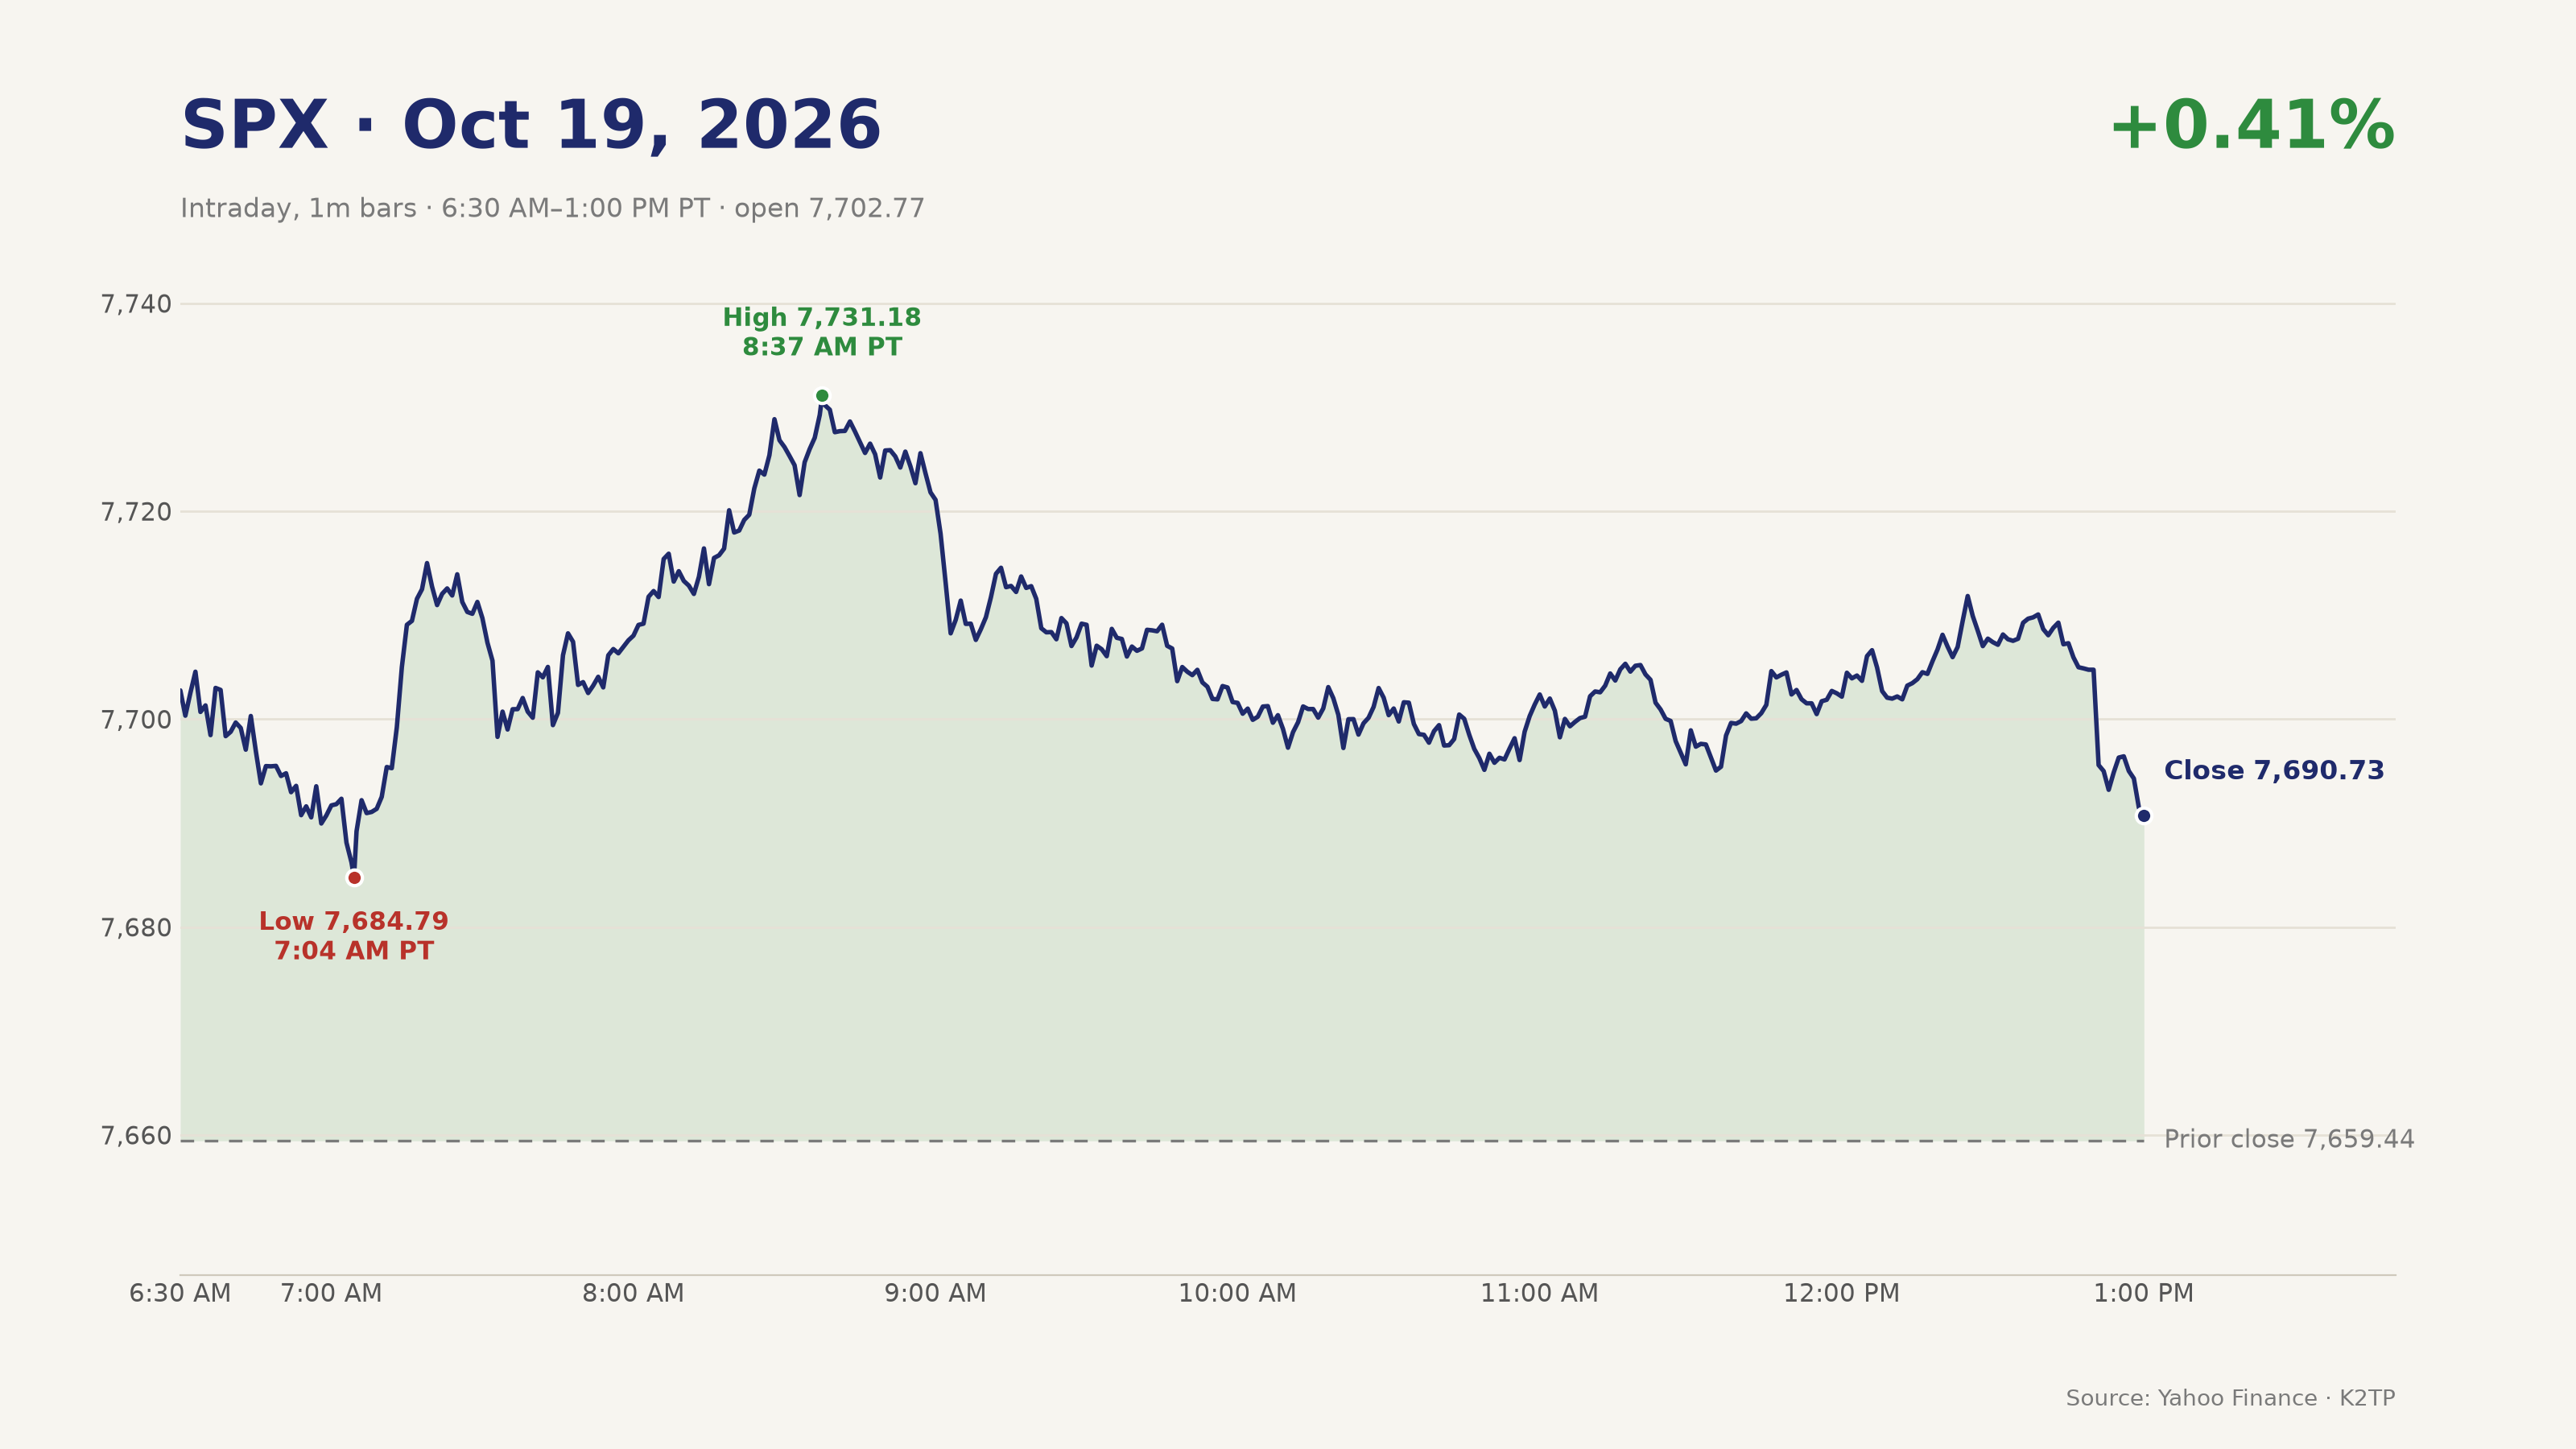
- Open 7,702.77; early low 7,684.79 at 7:04 AM PT, briefly under Friday's 7,691.56 midday low
- High 7,731.18 at 8:37 AM PT as chips peaked; midday 7,704.28 (+0.59%); pre-close 7,705.23 (+0.60%)
- The whole afternoon stayed inside the 7,684.79–7,731.18 morning range
- Late fade: 7,709.29 at 12:42 PM PT → 7,690.73 at the close (about −19 points), while VIX rose from 18.13 to 18.44
- Close: 7,690.73 (+31.29 points), 0.83 points under 7,691.56 and 5.94 points above the session low
- Triggers: three of four pre-market Bull conditions were met by midday (SPX above 7,691.56, VIX under 20, SOX green), but the breadth condition never was. Neither midday nor pre-close trigger fired
→ Buyers did not hold the afternoon gains into the close. It looks like low conviction before the earnings run, not a breakdown.
TREASURIES: THE HAVEN BID REVERSES
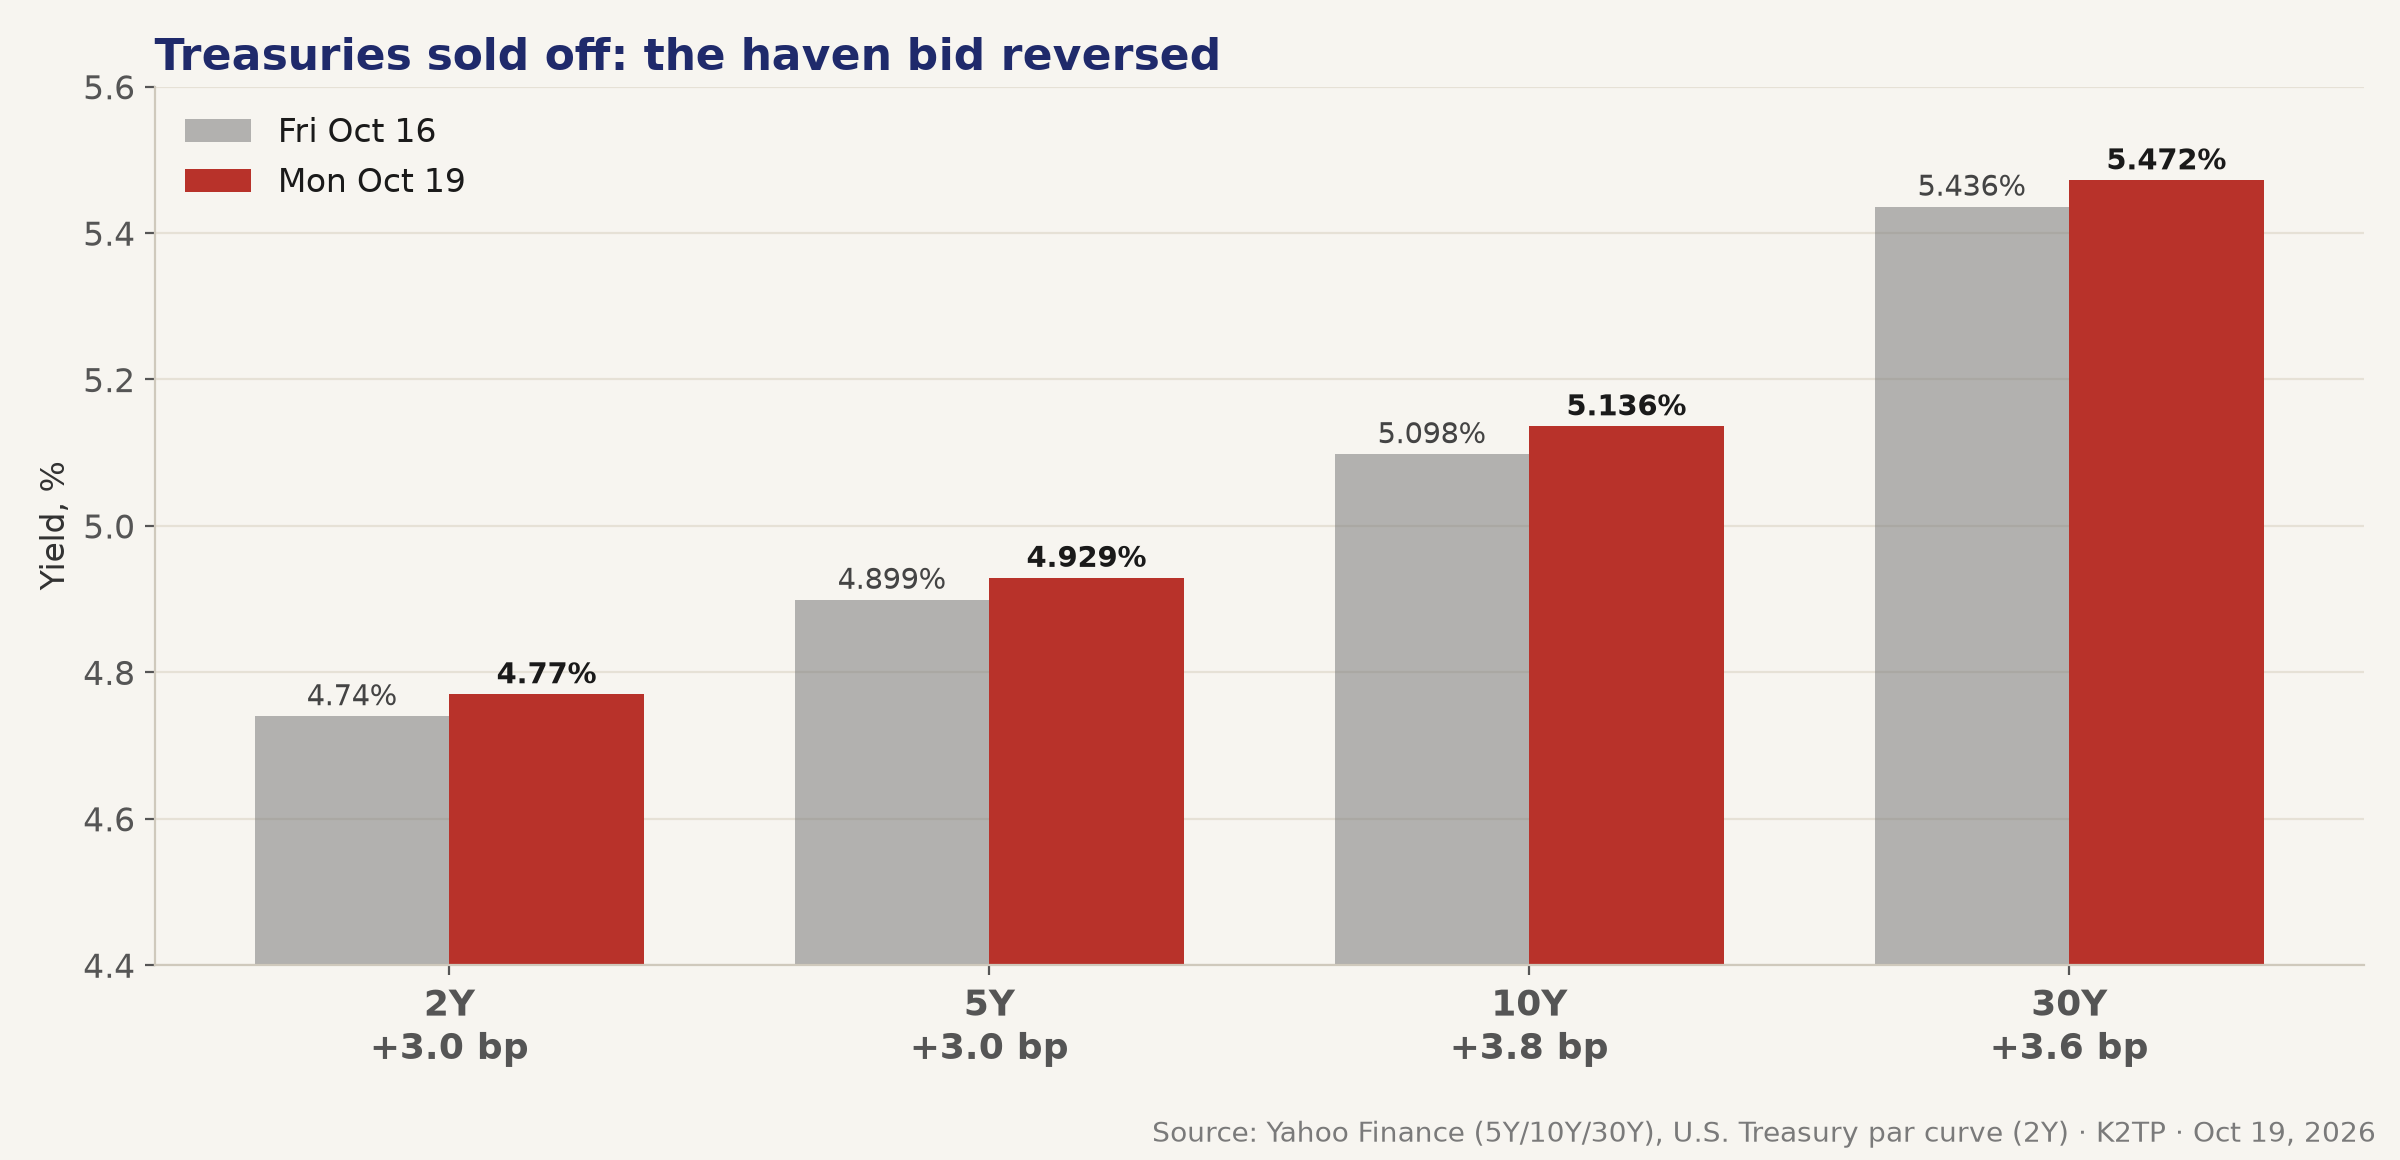
- 10Y 5.136% (+3.8 bp), high 5.150%; 5Y 4.929% (+3.0 bp); 30Y 5.472% (+3.6 bp); 2Y 4.77% (+3 bp, Treasury par curve)
- The 10-year TIPS breakeven was 2.349% at midday (Reuters), so the move was in real yields
- WSJ: bond investors braced for a possible Fed hike in response to energy-driven inflation
- October hike odds: 16.1% (pre-market, Investing.com) → 17.2% (CME FedWatch, midday and close); hold 82.8%. The Fed is in blackout before the Oct 27–28 FOMC
- NAHB builder sentiment: 29 vs 31 expected and 32 prior, the lowest since June 2012 🔴. Bonds ignored it
- Bond proxies sold off: XLU −2.01%, XLRE −1.16%
→ Last week's 14.6 bp drop in the 10Y is partly unwinding. A 10Y back above 5.1% caps how far long-duration growth can rebound.
OIL: NOVEMBER WTI JUMPS ON HOUTHI ATTACKS, BRENT FLAT
- November WTI: settled $103.66 (+2.2%), high $104.18 at 11:30 AM PT, after $100.47 pre-market 🔴
- Brent: settled $109.55 (−0.3%), but touched $110.69 intraday; overnight high $110.25
- Morning relief: President Trump decided to waive some sanctions on Russia (Reuters), and Brent fell to $106.82 overnight
- Afternoon reversal: Reuters tied it to renewed Houthi attacks on Saudi energy, airport and military facilities
- December WTI is near $98.86, so much of the front-month spike reflects the November contract's expiry on Tuesday
- XLE −0.64% despite the oil move
→ The supply risk premium has not gone away. Brent above $110.69 is now the oil line in the Bear case.
EUROPE: FRENCH STRESS HITS STOCKS AND BANKS
- Weekend cost-of-living protests in France turned violent; French 10-year yields rose 9 bp to 4.875% pre-market (Reuters)
- European closes: Euro Stoxx 50 −0.96%, DAX −1.18%, FTSE 100 −1.08%, CAC 40 −1.11%
- US big banks were weak too: WFC −2.47%, C −2.07%, JPM −1.82%, BAC −1.64%; XLF −0.83%. No direct link to Europe is confirmed
- Other movers: Ameriprise (AMP) −4.07% on a Bank of America downgrade; Datadog (DDOG) +5.36% on a Bernstein upgrade
- China: Q3 GDP +4.5% y/y vs 4.4% expected; September retail sales +1.1% vs 0.5%; the Kospi closed Monday +1.76%
→ So far it is a European sovereign and bank story. It would matter more for US stocks if it reached US credit or Treasury yields.
EARNINGS: STEEL DYNAMICS, ZIONS, FIFTH THIRD AND CLEVELAND-CLIFFS
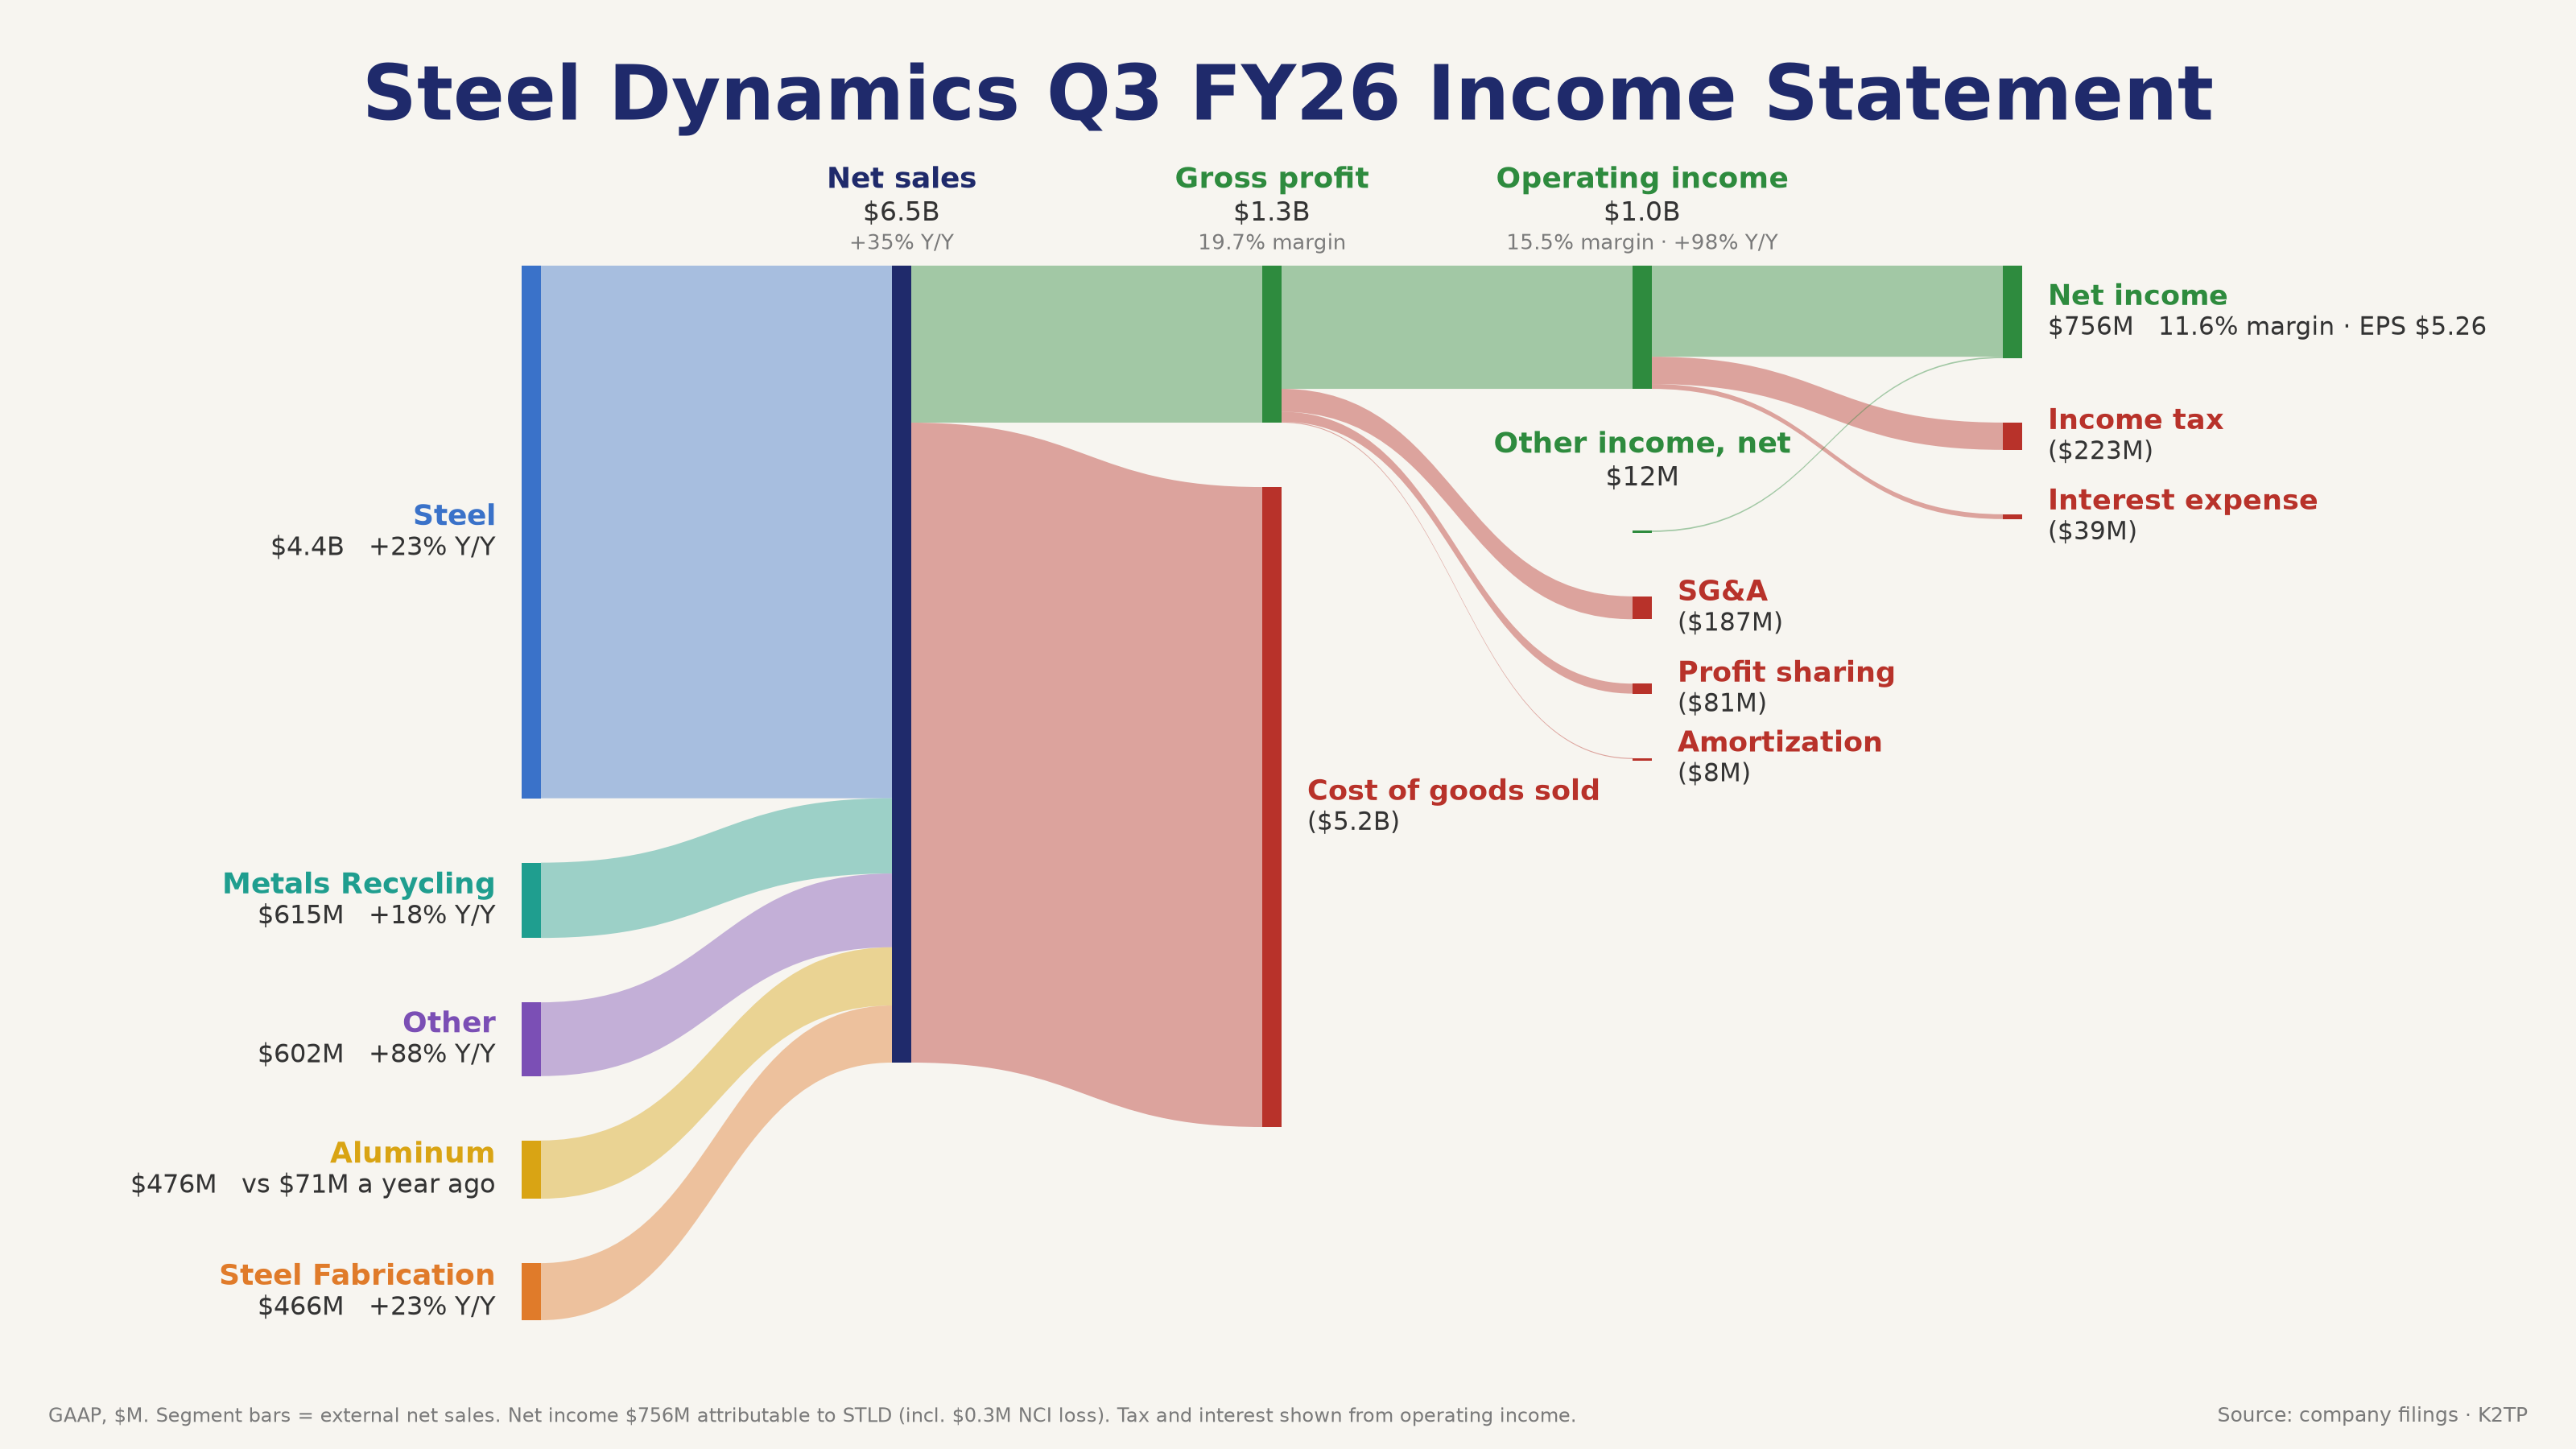
- Steel Dynamics (STLD), after the close: net sales $6.51B (+35% y/y; Zacks consensus $6.11B) 🟢; diluted EPS $5.26, below its own $5.34–$5.38 guidance and the ~$5.42 Zacks consensus 🔴 (estimates vary by source)
- STLD: record 3.8M tons of steel shipments; operating income $1.01B; net income $756M; $276M of buybacks. Shares $245.17 (+1.92%) at the close → $233.79 (−4.64%) after hours
- Zions (ZION), after the close: EPS $1.78 vs ~$1.65 expected 🟢; revenue $881M vs ~$890M expected 🔴; NIM 3.23% (from 3.27%); net charge-offs only $3M. Shares $63.14 → $63.68 (+0.85%) after hours
- Fifth Third (FITB), before the open: adjusted EPS $1.13 vs the $1.09 Zacks consensus 🟢 (reported $0.90 after $0.23 of merger and other charges); revenue $3.28B FTE (+42% y/y) vs $3.34B expected; NII +49% after the Comerica deal. Shares +0.28%
- Cleveland-Cliffs (CLF) +16.34% after a Q3 beat (adjusted EPS $0.28 vs the $0.21 FactSet estimate)
→ Steel demand is strong (record shipments, Cliffs' beat), but STLD's miss against its own guidance hit the stock. Regional bank credit still looks clean.
MARKET: MEGA-CAPS UP, THE AVERAGE STOCK DOWN
Indices (close):
- SPX 7,690.73 (+0.41%), day range 7,684.79–7,731.18
- NDX 29,529.34 (+1.17%); Nasdaq Composite 26,430.89 (+1.11%)
- DJIA 51,966.03 (−0.07%)
- RUT 2,728.30 (+0.25%)
- RSP 213.40 (−0.32%)
- SOX 11,316.34 (+1.61%)
Session path: ES +0.46% (7,739.75) pre-market as chips bounced and Brent eased. SPX opened at 7,702.77, dipped to 7,684.79 at 7:04 AM PT, peaked at 7,731.18 at 8:37 AM PT, was 7,704.28 at midday and 7,705.23 at pre-close, then slid to 7,690.73 in the final minutes.
Sector Rotation:
- Gainers: XLY +1.78%, XLK +1.36%, XLB +0.06%
- Laggards: XLU −2.01%, XLRE −1.16%, XLF −0.83%, XLE −0.64%, XLI −0.64%, XLV −0.60%, XLP −0.47%, XLC −0.21%
- Mega-caps: AMZN +4.98%, TSLA +3.76%, AVGO +1.78%, NVDA +1.38%, GOOGL +1.05%, MSFT +0.84%; AAPL −0.15%, META −0.55%
Market Internals:
- NYSE: decliners led 1.69-to-1; 83 new highs vs 265 new lows (Reuters)
- Nasdaq: 2,258 advancers vs 2,647 decliners; 31 new highs vs 361 new lows
- S&P 500: 12 new 52-week highs, 2 new lows
- Volume: 15.27B shares vs a 17.26B 20-day average
Volatility:
- VIX 18.44 (−7.75%), range 17.39–18.93 (high before the open)
- VIX9D 17.93 (from 20.12), VIX3M 19.60 (from 20.50): back in contango after Friday's flat curve
- VVIX 106.93 (−2.71%)
Cross-asset:
- DXY 101.98 (+0.14%); gold settled $4,160.10 (−0.50%); BTC ~$81,500 (−0.6%)
Global:
- Asia (Monday): Nikkei −0.62% (64,916.70), Kospi +1.76% (5,768.01), Shanghai +0.39%
- Europe: Euro Stoxx 50 −0.96%, DAX −1.18%, FTSE −1.08%, CAC −1.11%
- Tonight (around 7:00 PM PT): Kospi −2.8% and Nikkei −0.8%, with SK Hynix down more than 4% on AI concerns (Yonhap). ES +0.16% and NQ +0.02%, recovering from NQ −0.47% around 6:25 PM PT
SPX Key Levels:
- 7,756.84: Friday's high
- 7,731.18: Monday's high, the Bull line
- 7,691.56: Friday's midday low, closed just below it
- 7,690.73: close
- 7,684.79: Monday's low, the Bear line
- VIX: 17.39 and 18.93
Option-seller angle:
- Bull case: SPX above 7,731.18 with VIX under 17.39 would tilt the read toward RISK-ON into Netflix. Even then, keep put premium far out of the money, because breadth is narrow.
- Bear case: SPX under 7,684.79 with VIX above 18.93 sends the regime back to RISK-OFF before Meta and Tesla. Cut short-put size or use defined-risk spreads.
- The VIX curve is back in contango, which helps premium sellers. But Netflix (Tue), Meta and Tesla (Wed) are event risks, so avoid short straddles or tight Iron Condors on NDX and single names through Wednesday.
- Overnight Asian chip weakness argues against opening 0DTE positions in the first hour on Tuesday.
BOTTOM LINE
- Chips and Amazon gave the Nasdaq a real bounce, and SOX snapped its longest losing streak since 2008. But only 3 of 11 sectors rose and RSP fell.
- Yields rose, oil kept its risk premium, and SPX gave back most of its gain in the last 18 minutes.
- The regime moved from RISK-OFF to TRANSITION. It needs SPX above 7,731.18 with VIX under 17.39 to tilt toward RISK-ON.
What to watch tomorrow (PT):
- Before the open: GE Aerospace, RTX, GM, 3M, Northrop Grumman, Halliburton
- 5:30 AM: September housing starts (prior 1.275M, consensus 1.30M) and building permits
- Session: November WTI contract expiry
- After the close: Netflix, SpaceX, Intuitive Surgical, Capital One, Chubb, United Airlines
- Wednesday: 20-year bond auction at 10:00 AM; Meta, Tesla, Lam Research, Texas Instruments and IBM after the close
- Oct 27–28: FOMC
Expected (Bull): SPX above 7,731.18 with VIX under 17.39, SOX above 11,293.45 and the 10Y back under 5.10%. Expected (Bear): SPX under 7,684.79 with VIX above 18.93 and Brent above $110.69.
Sources: 4 K2TP briefs for Oct 19, 2026 (Pre-Market, Midday, Pre-Close, Evening Recap). Closing prices from Yahoo Finance; oil settlements, breadth and news from Reuters, WSJ and CNBC; 2Y from the U.S. Treasury par yield curve; earnings from the STLD, ZION and FITB releases; Sankey from Steel Dynamics' official Q3 2026 release. Analysis: K2TP Framework.