Market 10/16: AI-Debt Selloff and $110 Brent Sink the Nasdaq, SPX Logs Its Worst Week Since June
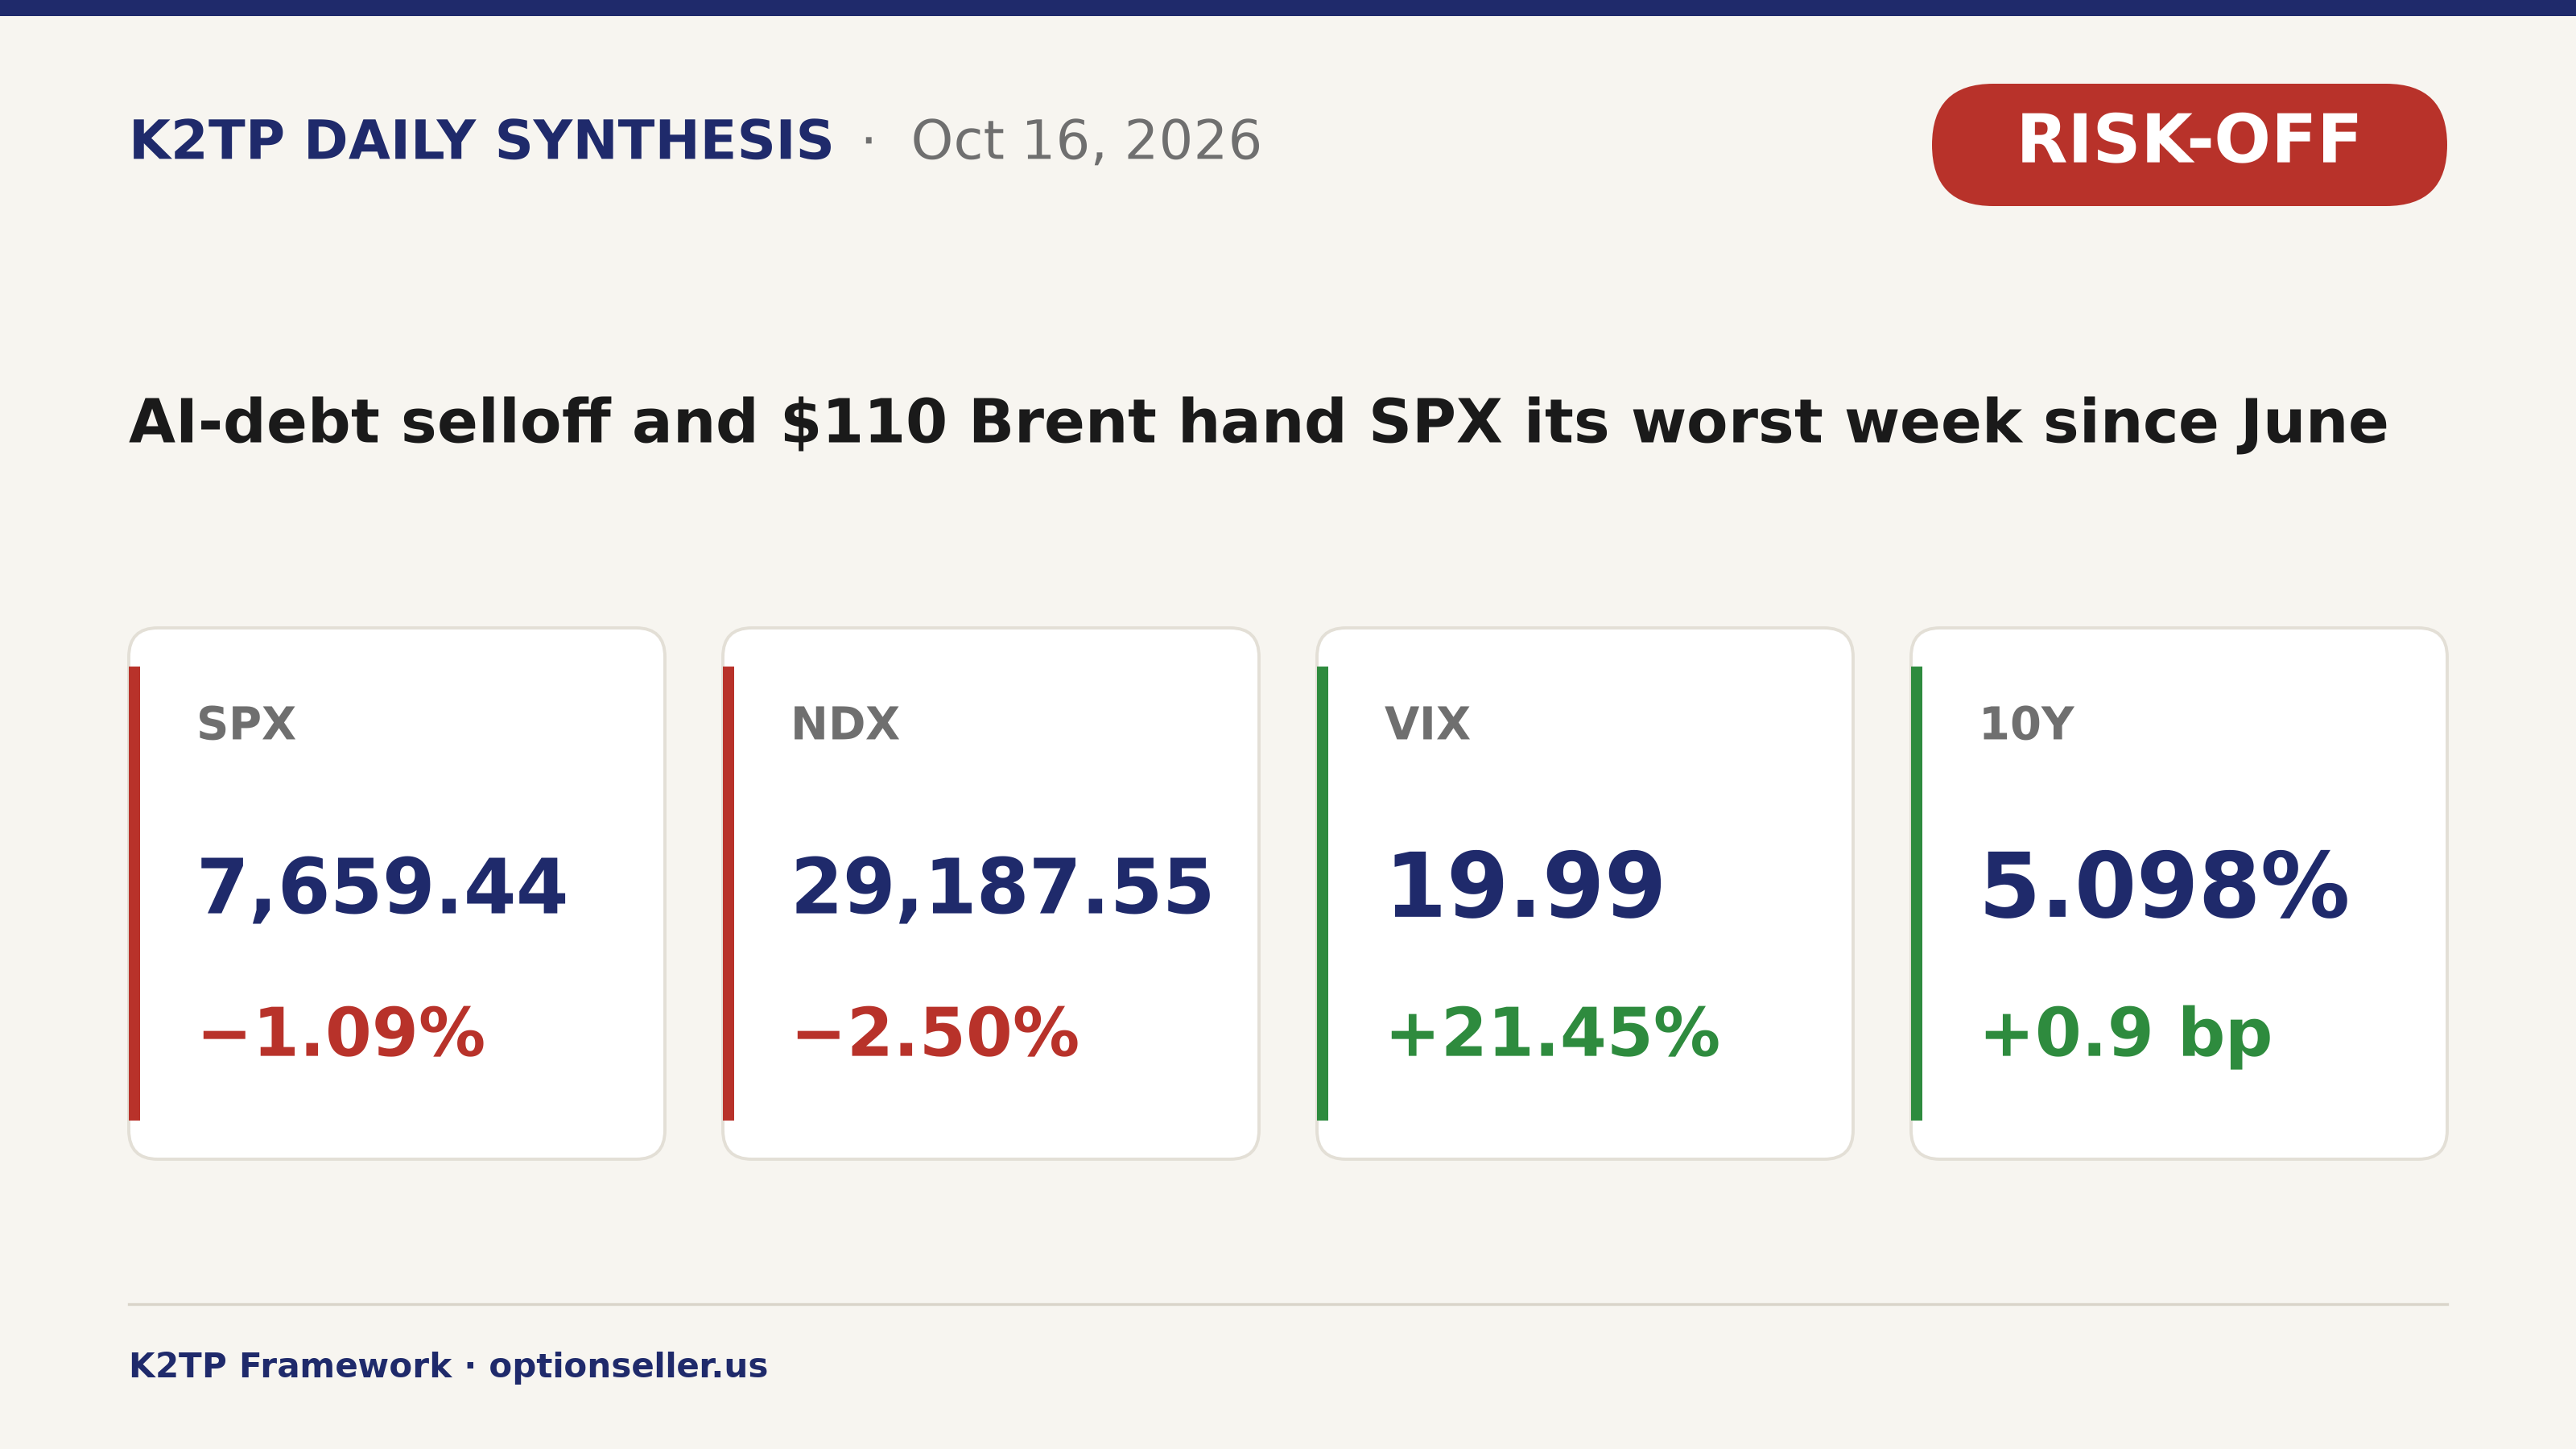
SPX −1.09%, NDX −2.50%, VIX +21.45%. CoreWeave's debt stress spread through chips and platforms while oil jumped into the weekend.
KEY HEADLINES
- SPX −1.09% to 7,659.44 after failing at a 7,756.84 opening high; NDX −2.50%, Dow −0.34%
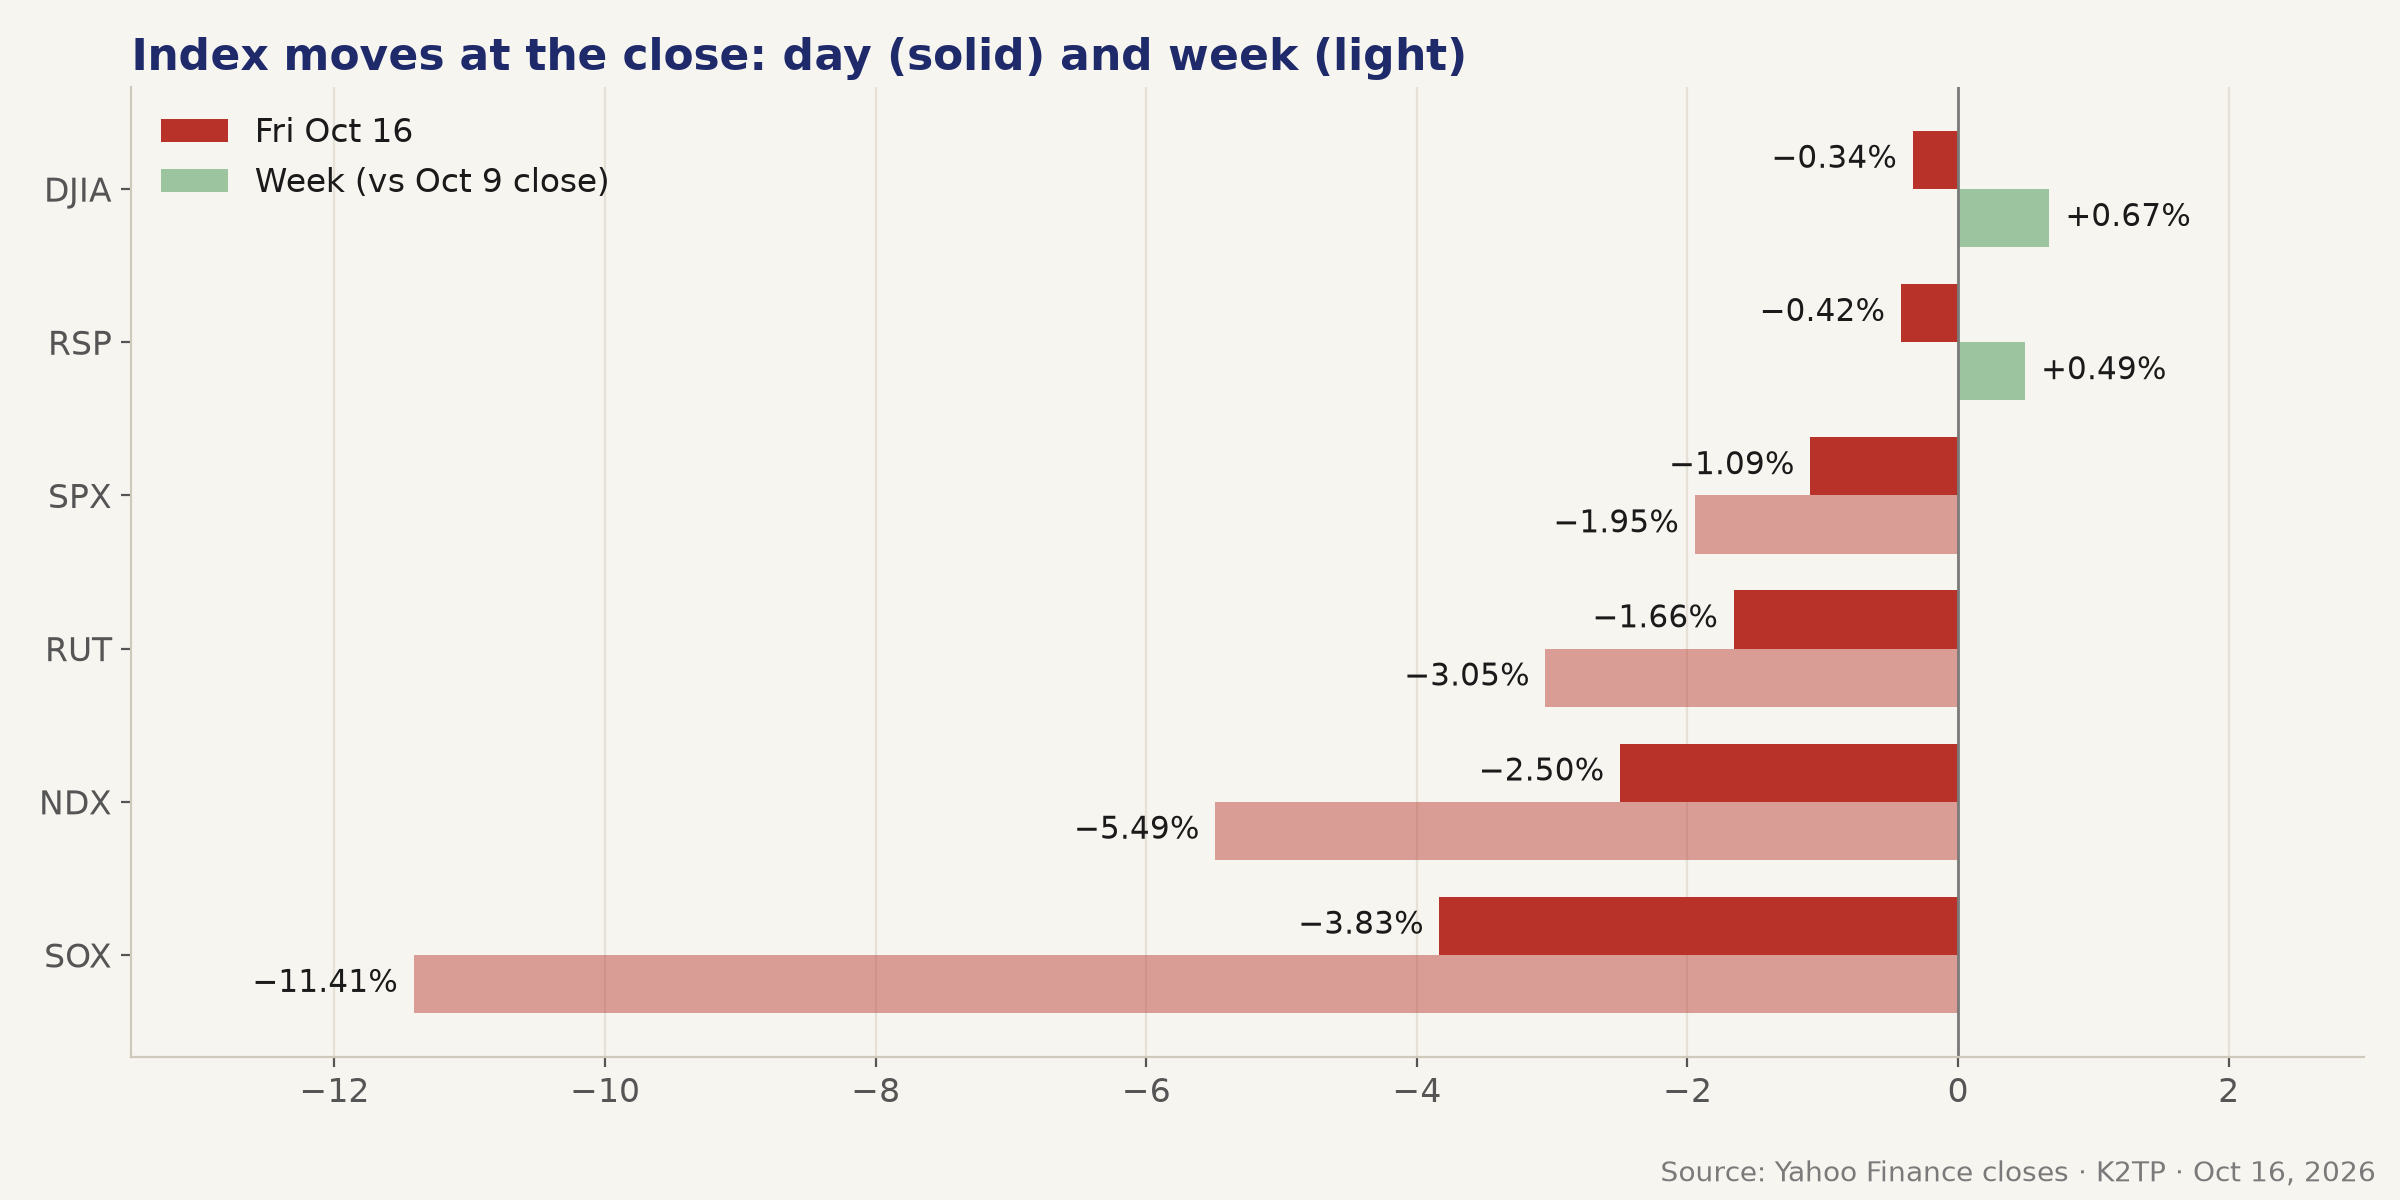
- Worst week since June: SPX −1.95%, Nasdaq Composite −4.48%, NDX −5.49%; the Dow still gained 0.67%
- CoreWeave −11.91% to $61.39, about −25% in five sessions; its bonds yield above 15% (Reuters)
- SOX −3.83%, an eighth straight decline and −11.41% on the week
- Brent settled +3.7% at $109.86 after touching $110 for the first time since May; XLE +2.52% led
- VIX 19.99 (+21.45%), intraday high 22.31; the VIX curve went nearly flat
- 10Y barely moved: 5.098% (+0.9 bp). The selloff was not rates-driven
- Hot import prices (+1.1% m/m vs +0.8% expected); industrial production +0.7%
- Warsh gave no October guidance; October hike odds ~16% before the open
- Regime: 🟡 TRANSITION pre-market → 🔴 RISK-OFF from midday into the close
AI-DEBT STRESS SPREADS FROM NEOCLOUDS TO CHIPS AND PLATFORMS
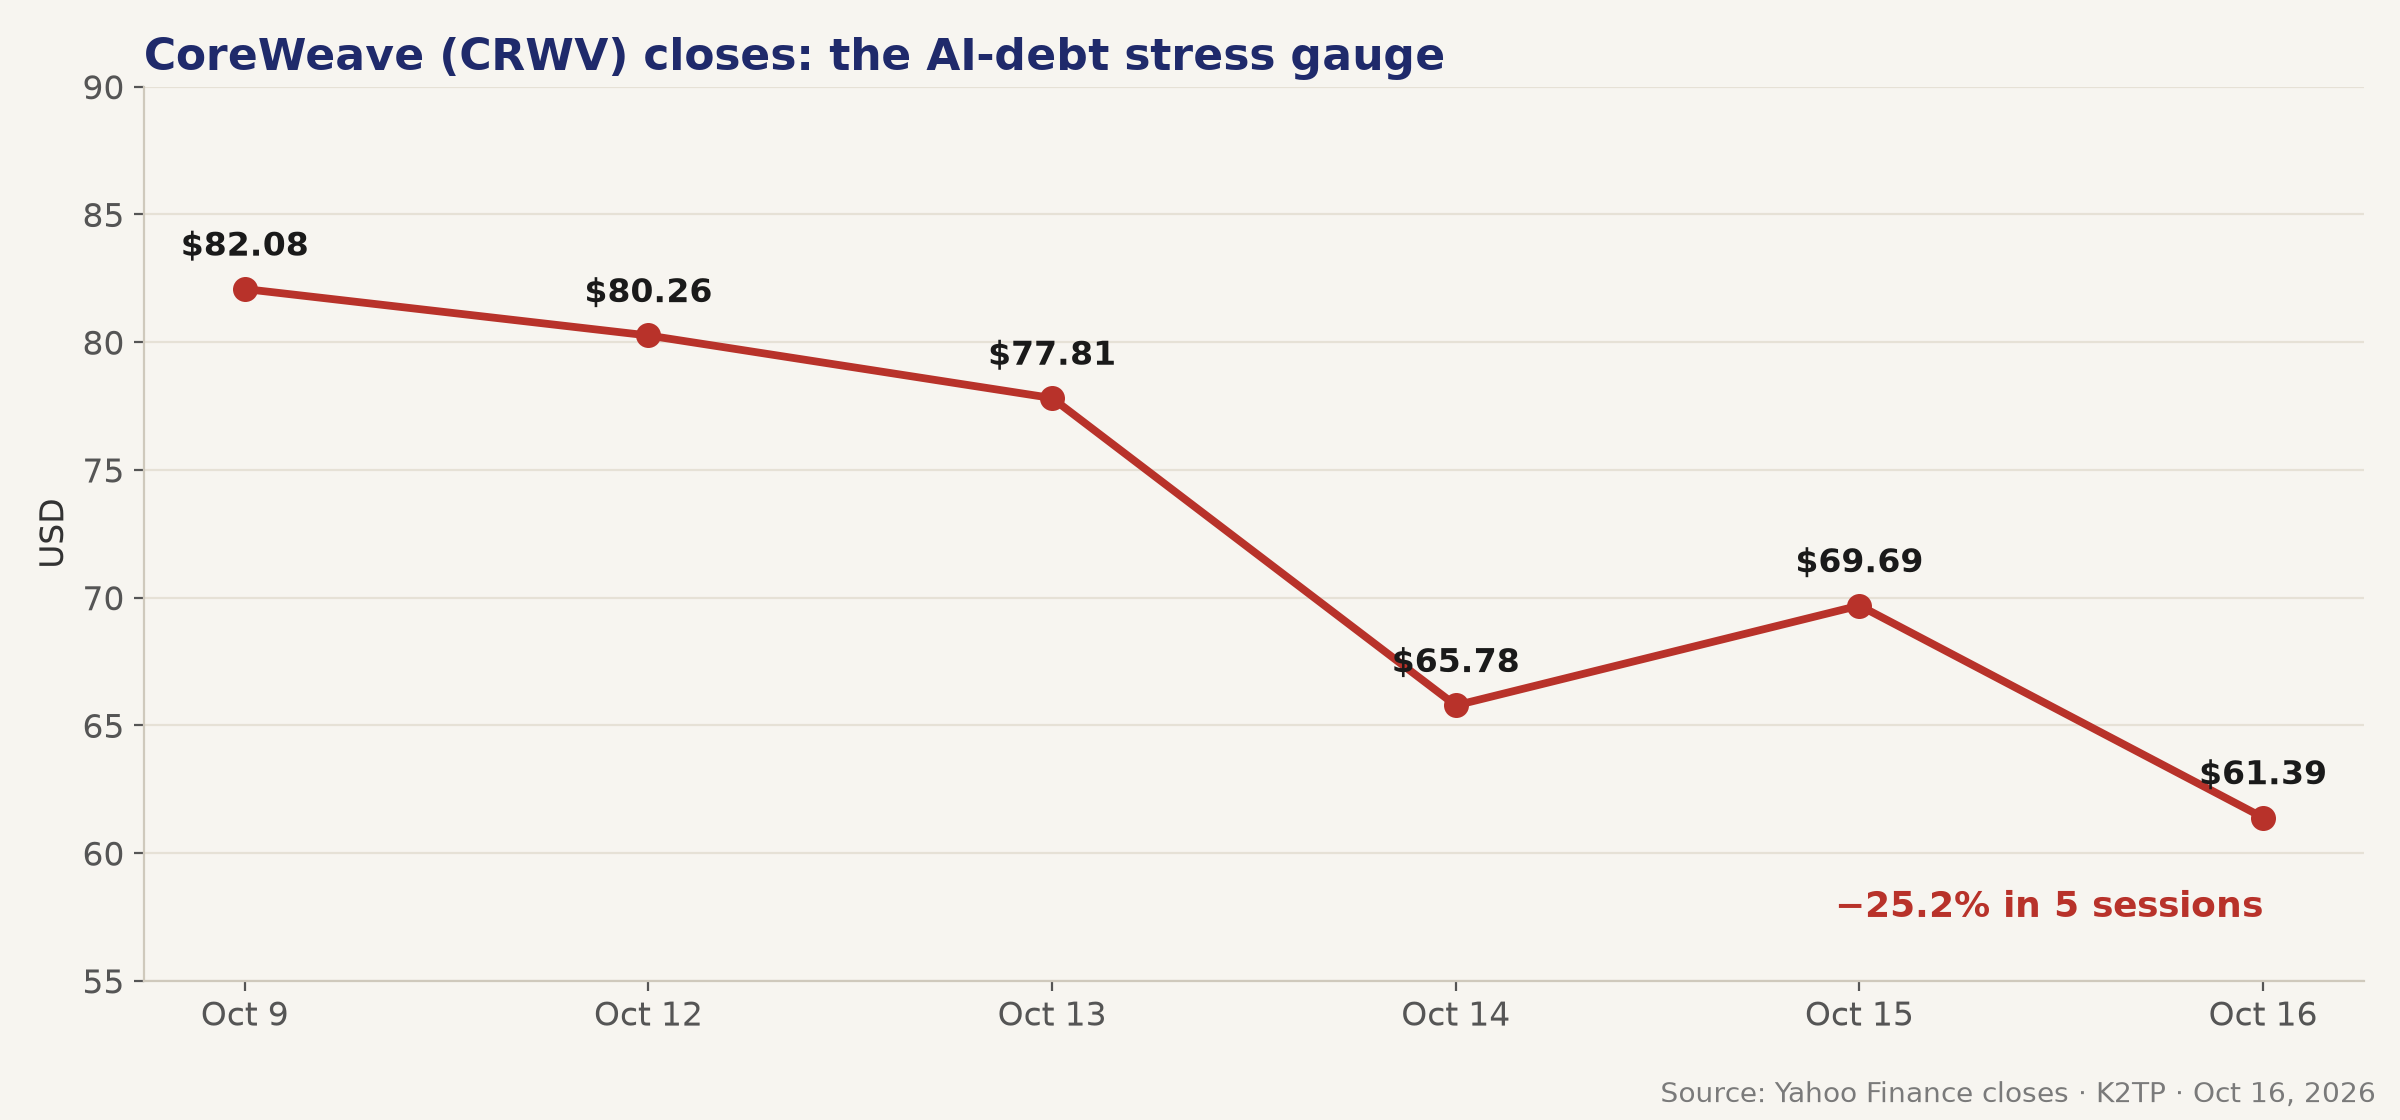
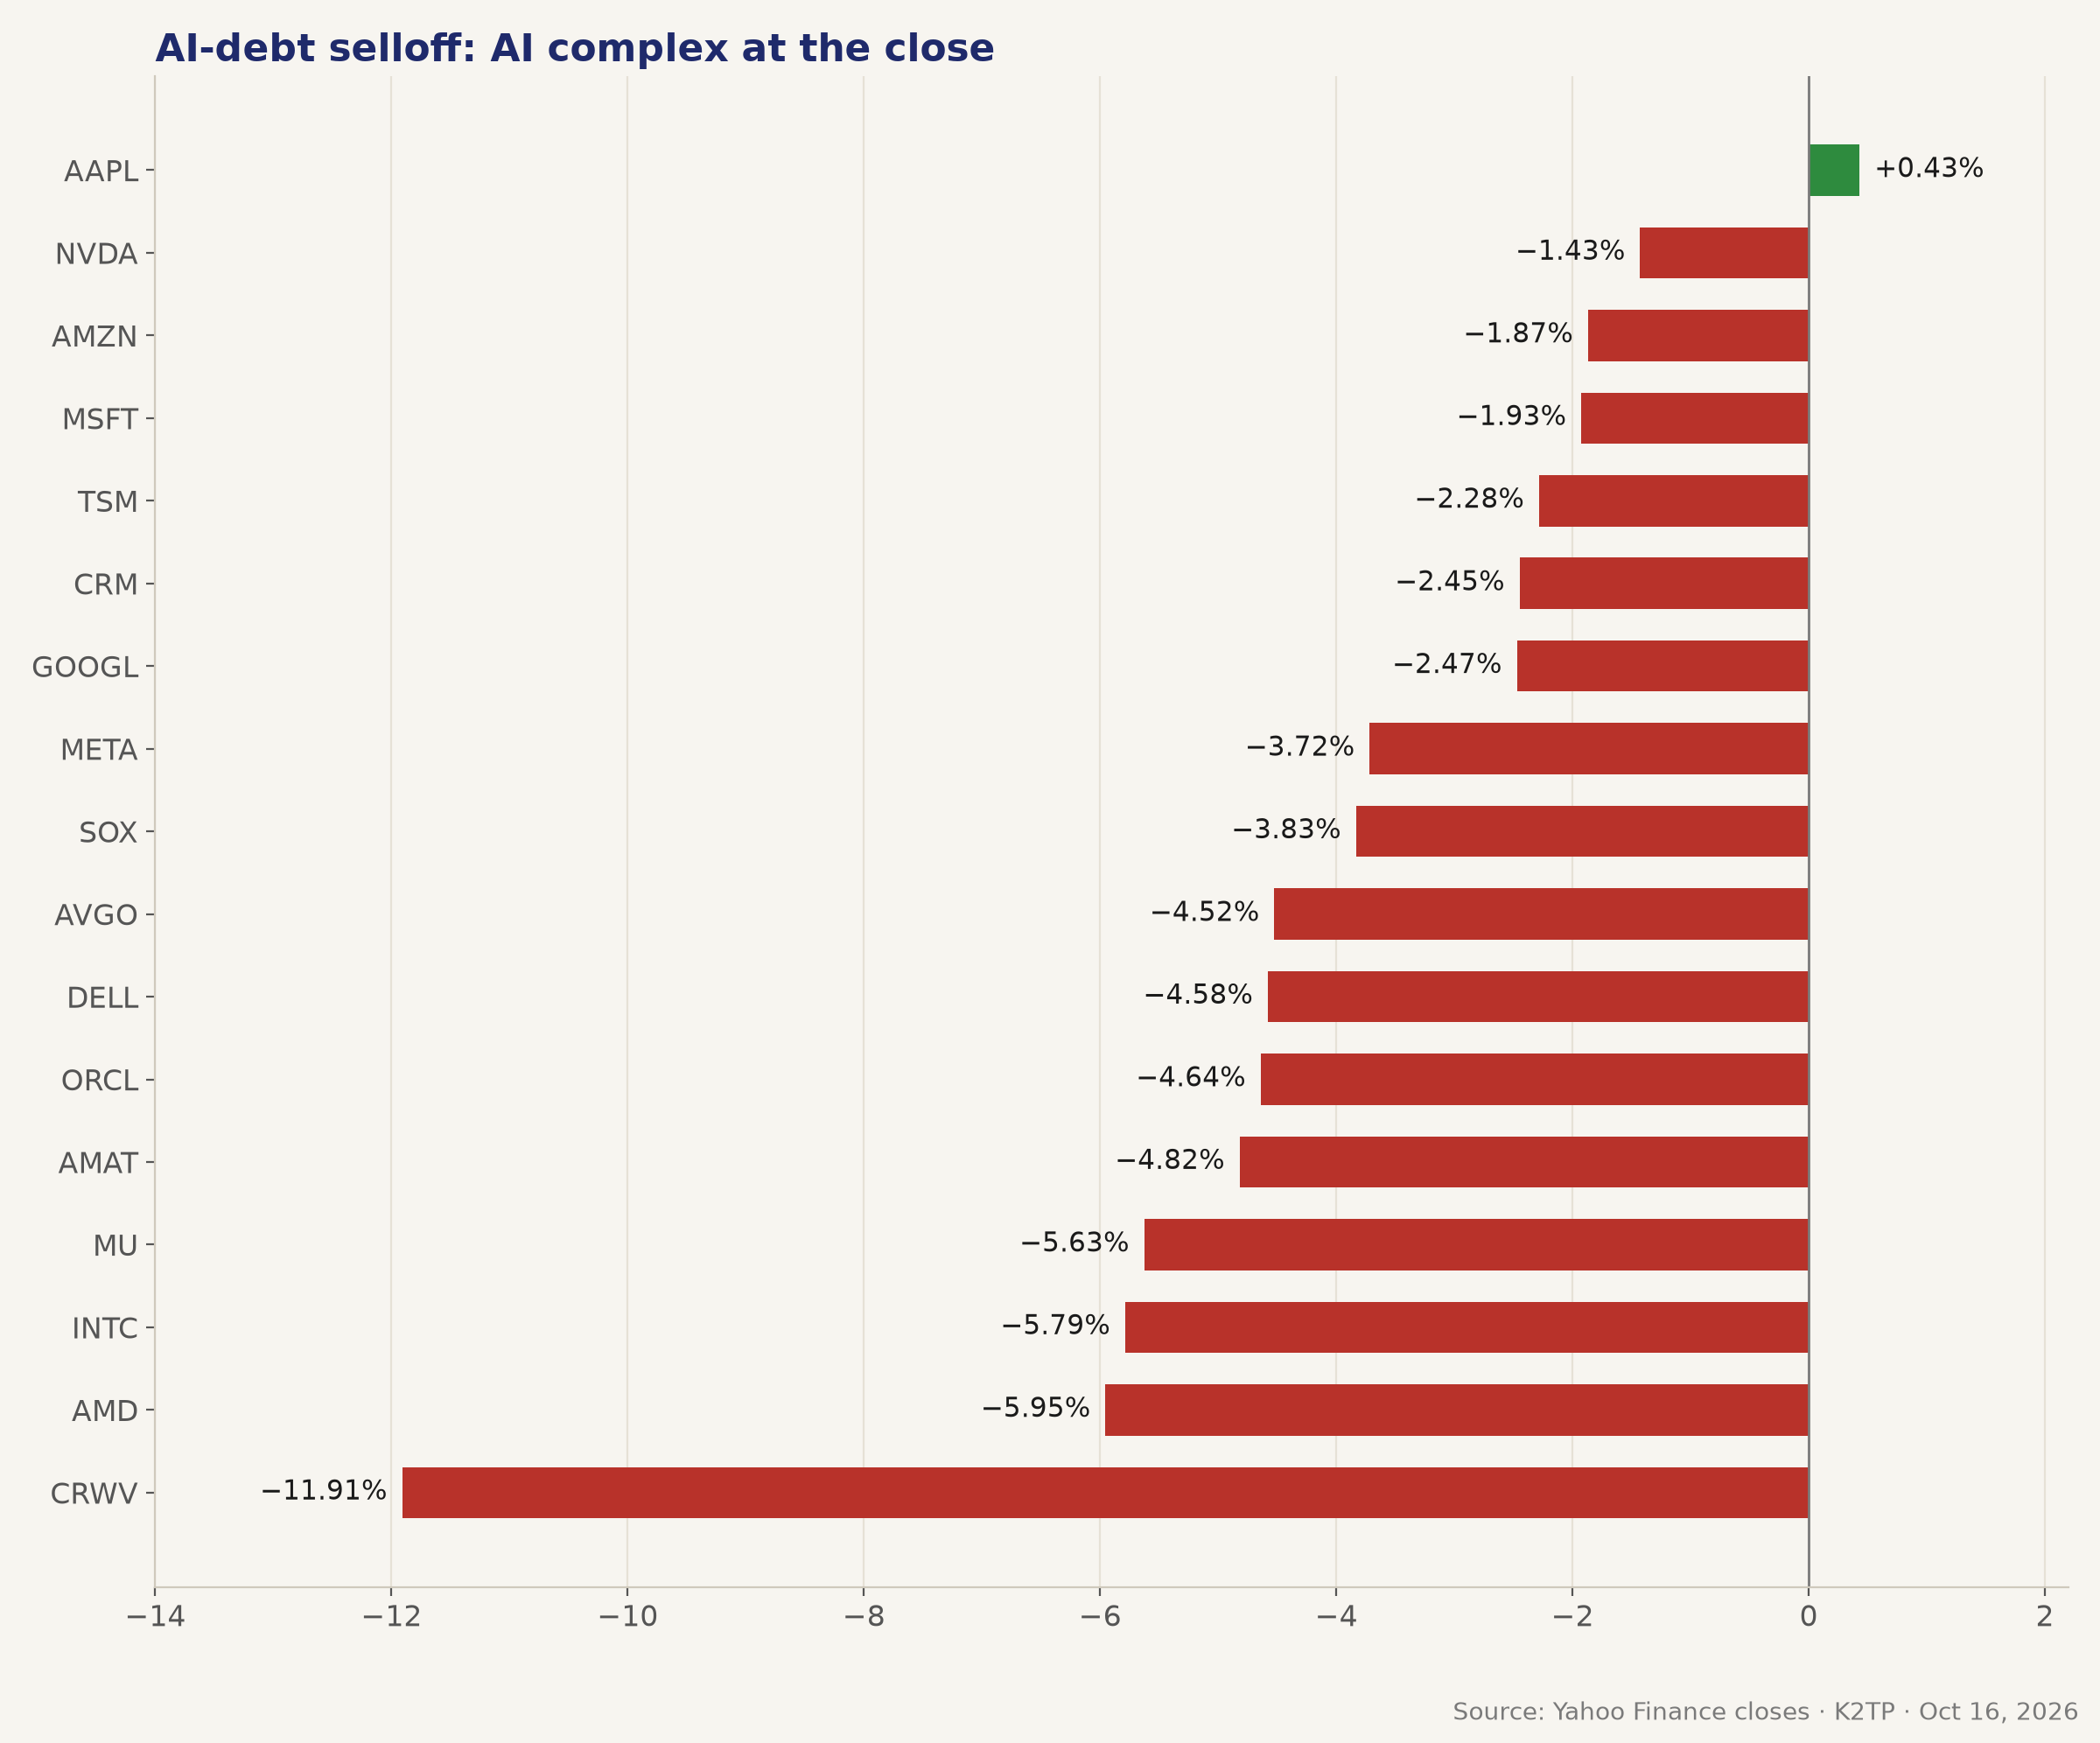
- CoreWeave (CRWV): $69.69 → $61.39 (−11.91%); $82.08 on Oct 9, so about −25% in five sessions 🔴
- Reuters: CoreWeave bonds sold off this week to yields above 15%; some Anthropic investors are weighing a lower IPO valuation
- Chips: AMD −5.95%, INTC −5.79%, MU −5.63%, AMAT −4.82%, AVGO −4.52%, TSM −2.28%, NVDA −1.43%
- Platforms and software: ORCL −4.64%, DELL −4.58%, META −3.72%, GOOGL −2.47%, CRM −2.45%, MSFT −1.93%, AMZN −1.87%
- AAPL +0.43% was the only large mega-cap to close green
- Thursday's Huang-driven CRWV bounce (+5.94%) fully faded
→ The market is pricing the cost of AI credit, not AI demand. Until CRWV and its bonds stabilize, any semis bounce is a trade, not a turn.
SPX FAILS AT THE OPEN AND BREAKS EVERY BEAR LINE
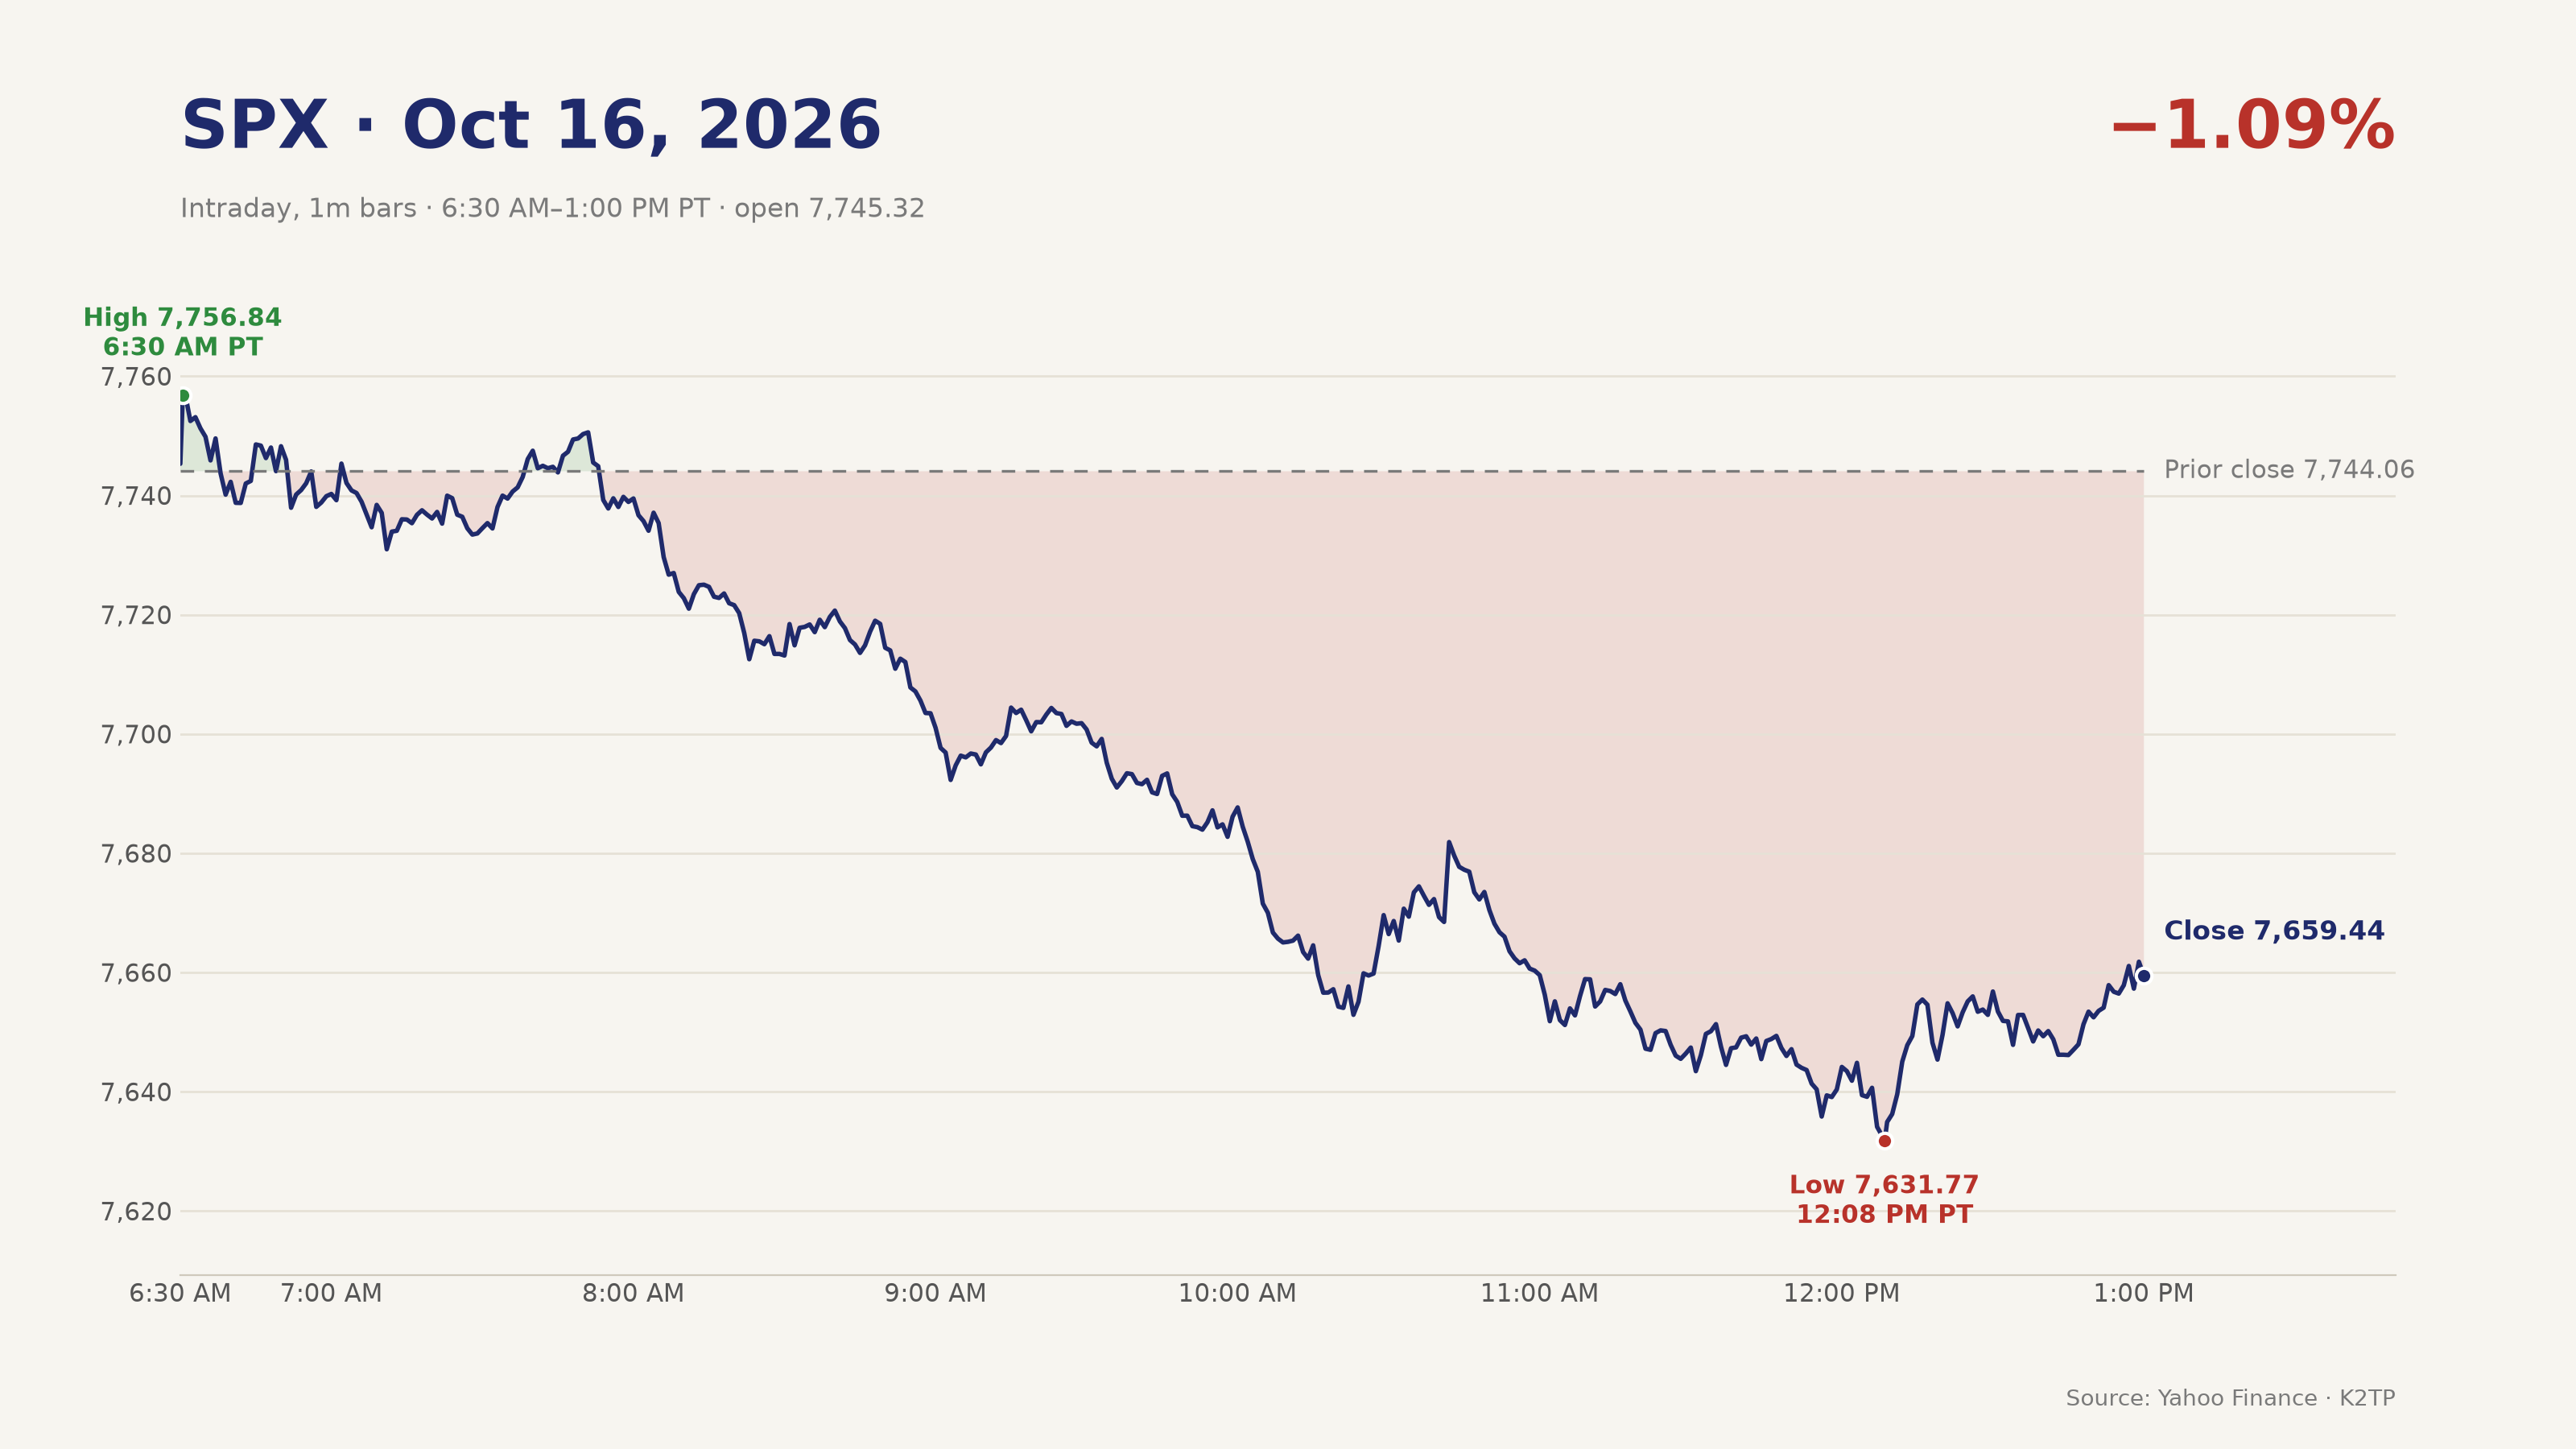
- Open 7,745.32, high 7,756.84 in the first minute (6:30 AM PT), then a steady slide
- Midday 7,702.65 (−0.53%); pre-close 7,634.21 (−1.42%)
- Session low 7,631.77 at 12:08 PM PT, then a ~28-point bounce into the close at 7,659.44 (−84.62 points)
- Pre-market Bear (SPX under 7,718.94, VIX above 16.46) fired by midday; the midday Bear (SPX under 7,691.56, VIX above 17.34) fired by pre-close
- The pre-close Bear (SPX under 7,634.12 and VIX above 22.31) did not confirm: SPX dipped under 7,634.12, but VIX closed at 19.99, below its 22.31 high
→ The final-hour bounce trimmed the loss but stayed far below 7,691.56. The close was not a reversal.
OIL: BRENT TOUCHES $110 ON MIDDLE EAST SUPPLY FEARS
- Brent: settled $109.86 (+$3.94, +3.7%), the highest since May 19; it touched $110 intraday (Reuters) 🔴
- WTI (Yahoo CL=F): $99.04 (+2.63%), intraday high $99.34
- Drivers (Reuters): a surge in attacks around the Strait of Hormuz over the past 10 days, and doubts over how much diesel Russia can deliver
- Offsets: the IEA agreed to release more than 20M barrels of fuel; the DOE requested proposals for an exchange of up to 17M barrels from the SPR
- XLE +2.52%, the best sector ETF
→ Oil near $100–110 after a week of hot CPI and PPI pressures P/E multiples, especially for long-duration growth (Reuters: "High oil prices… tend to weigh on the price/earnings multiple").
HOT IMPORT PRICES, FIRM INDUSTRIAL PRODUCTION
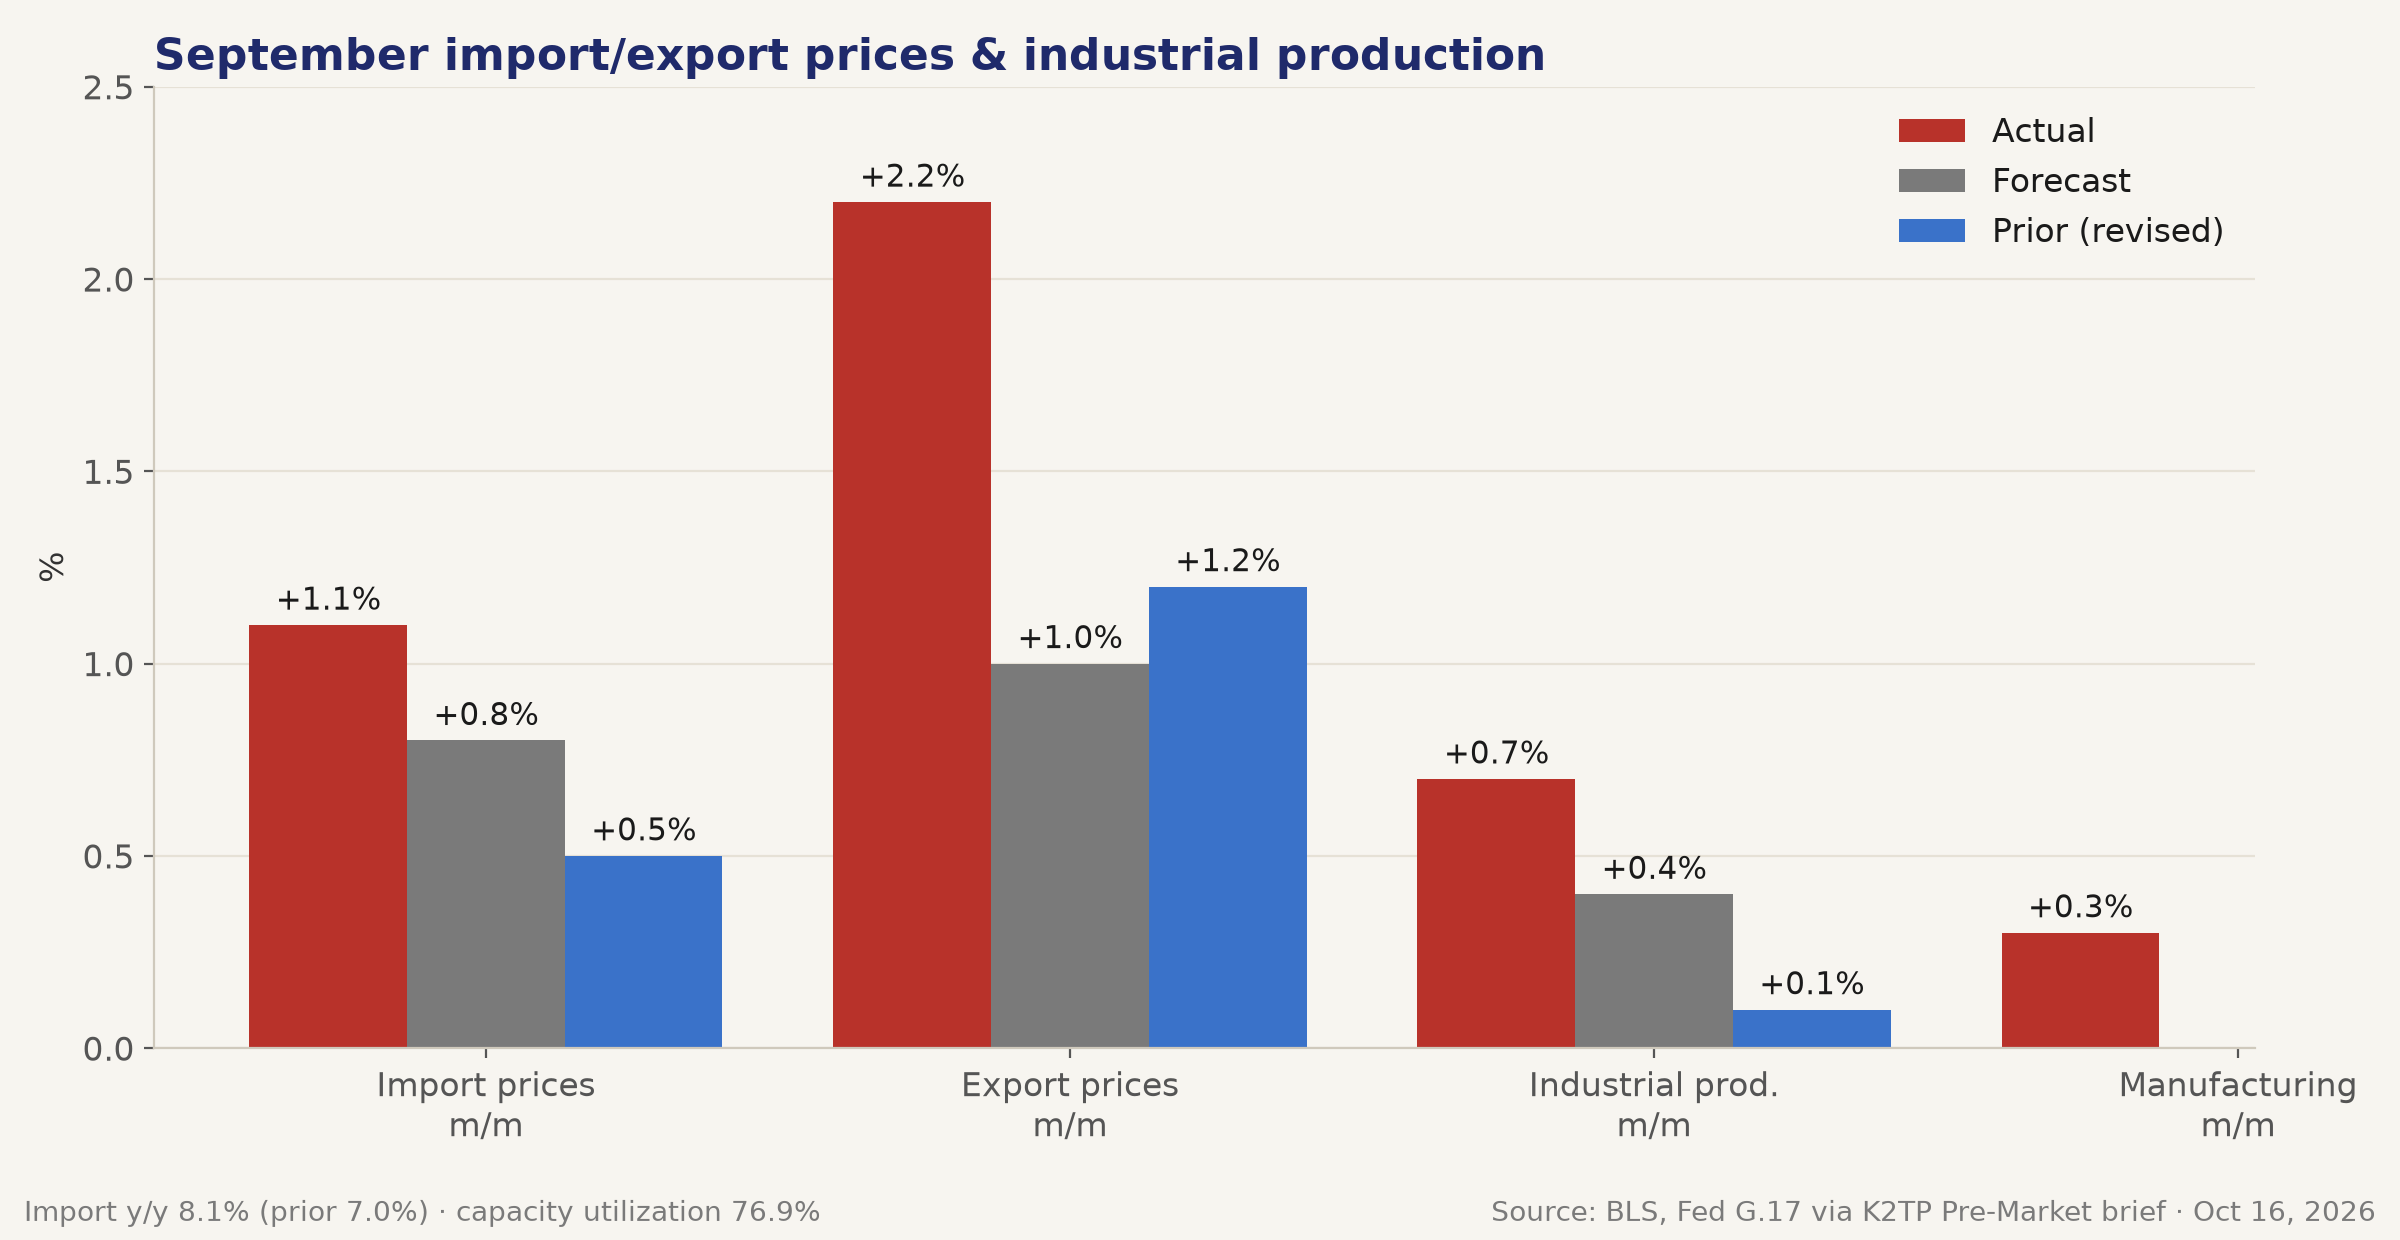
- Import prices: +1.1% m/m (forecast +0.8%, prior revised +0.5%) 🔴; 8.1% y/y (prior 7.0%)
- Export prices: +2.2% m/m (forecast +1.0%, prior revised +1.2%) 🔴
- Industrial production: +0.7% m/m (forecast +0.4%, August revised +0.1%) 🟢; manufacturing +0.3%, utilities +3.5%
- Capacity utilization: 76.9% (August revised 76.4%)
→ The third hot price print of the week, after CPI and PPI. Activity is firm, which leaves no reason for the Fed to turn dovish.
FED: WARSH GIVES NO GUIDANCE, HIKE RISK SHIFTS LATER
- Warsh at the IMF in Bangkok: he does not "prejudge meetings" and the Fed is "not in that business anymore" on previewing decisions; he called AI the most consequential economic change of his lifetime
- October hike odds: ~29% (Thu evening) → ~16.1% / hold ~83.9% (Investing.com Fed Rate Monitor, ~5:45 AM PT). No verified refresh later in the day
- Barclays now expects 25 bp hikes in December and January (Reuters)
- FOMC: Oct 27–28
→ October looks like a hold, but the hike path has moved later rather than disappeared. That keeps the long end from cushioning a growth selloff.
TREASURIES: NO HAVEN BID
- 10Y: 5.098% (+0.9 bp); 5Y 4.899% (unchanged); 30Y 5.436% (+0.7 bp); 13-week bill 4.070% (−1.8 bp)
- 2Y 4.734% (−1.3 bp) per MarketWatch, its largest one-week retreat since August
- Week: 10Y 5.244% → 5.098% (−14.6 bp). MarketWatch says the 30Y posted its biggest weekly drop in more than a year
- DXY 101.78 (−0.06%); gold $4,186.70 (+0.40%); BTC ~$81,300 (−1.03%)
→ Equities fell 1–2.5% while the 10Y barely moved. Higher oil cancelled the usual flight-to-quality bid.
ROTATION CUSHION SHRINKS: DEFENSIVES HOLD, TECH BREAKS
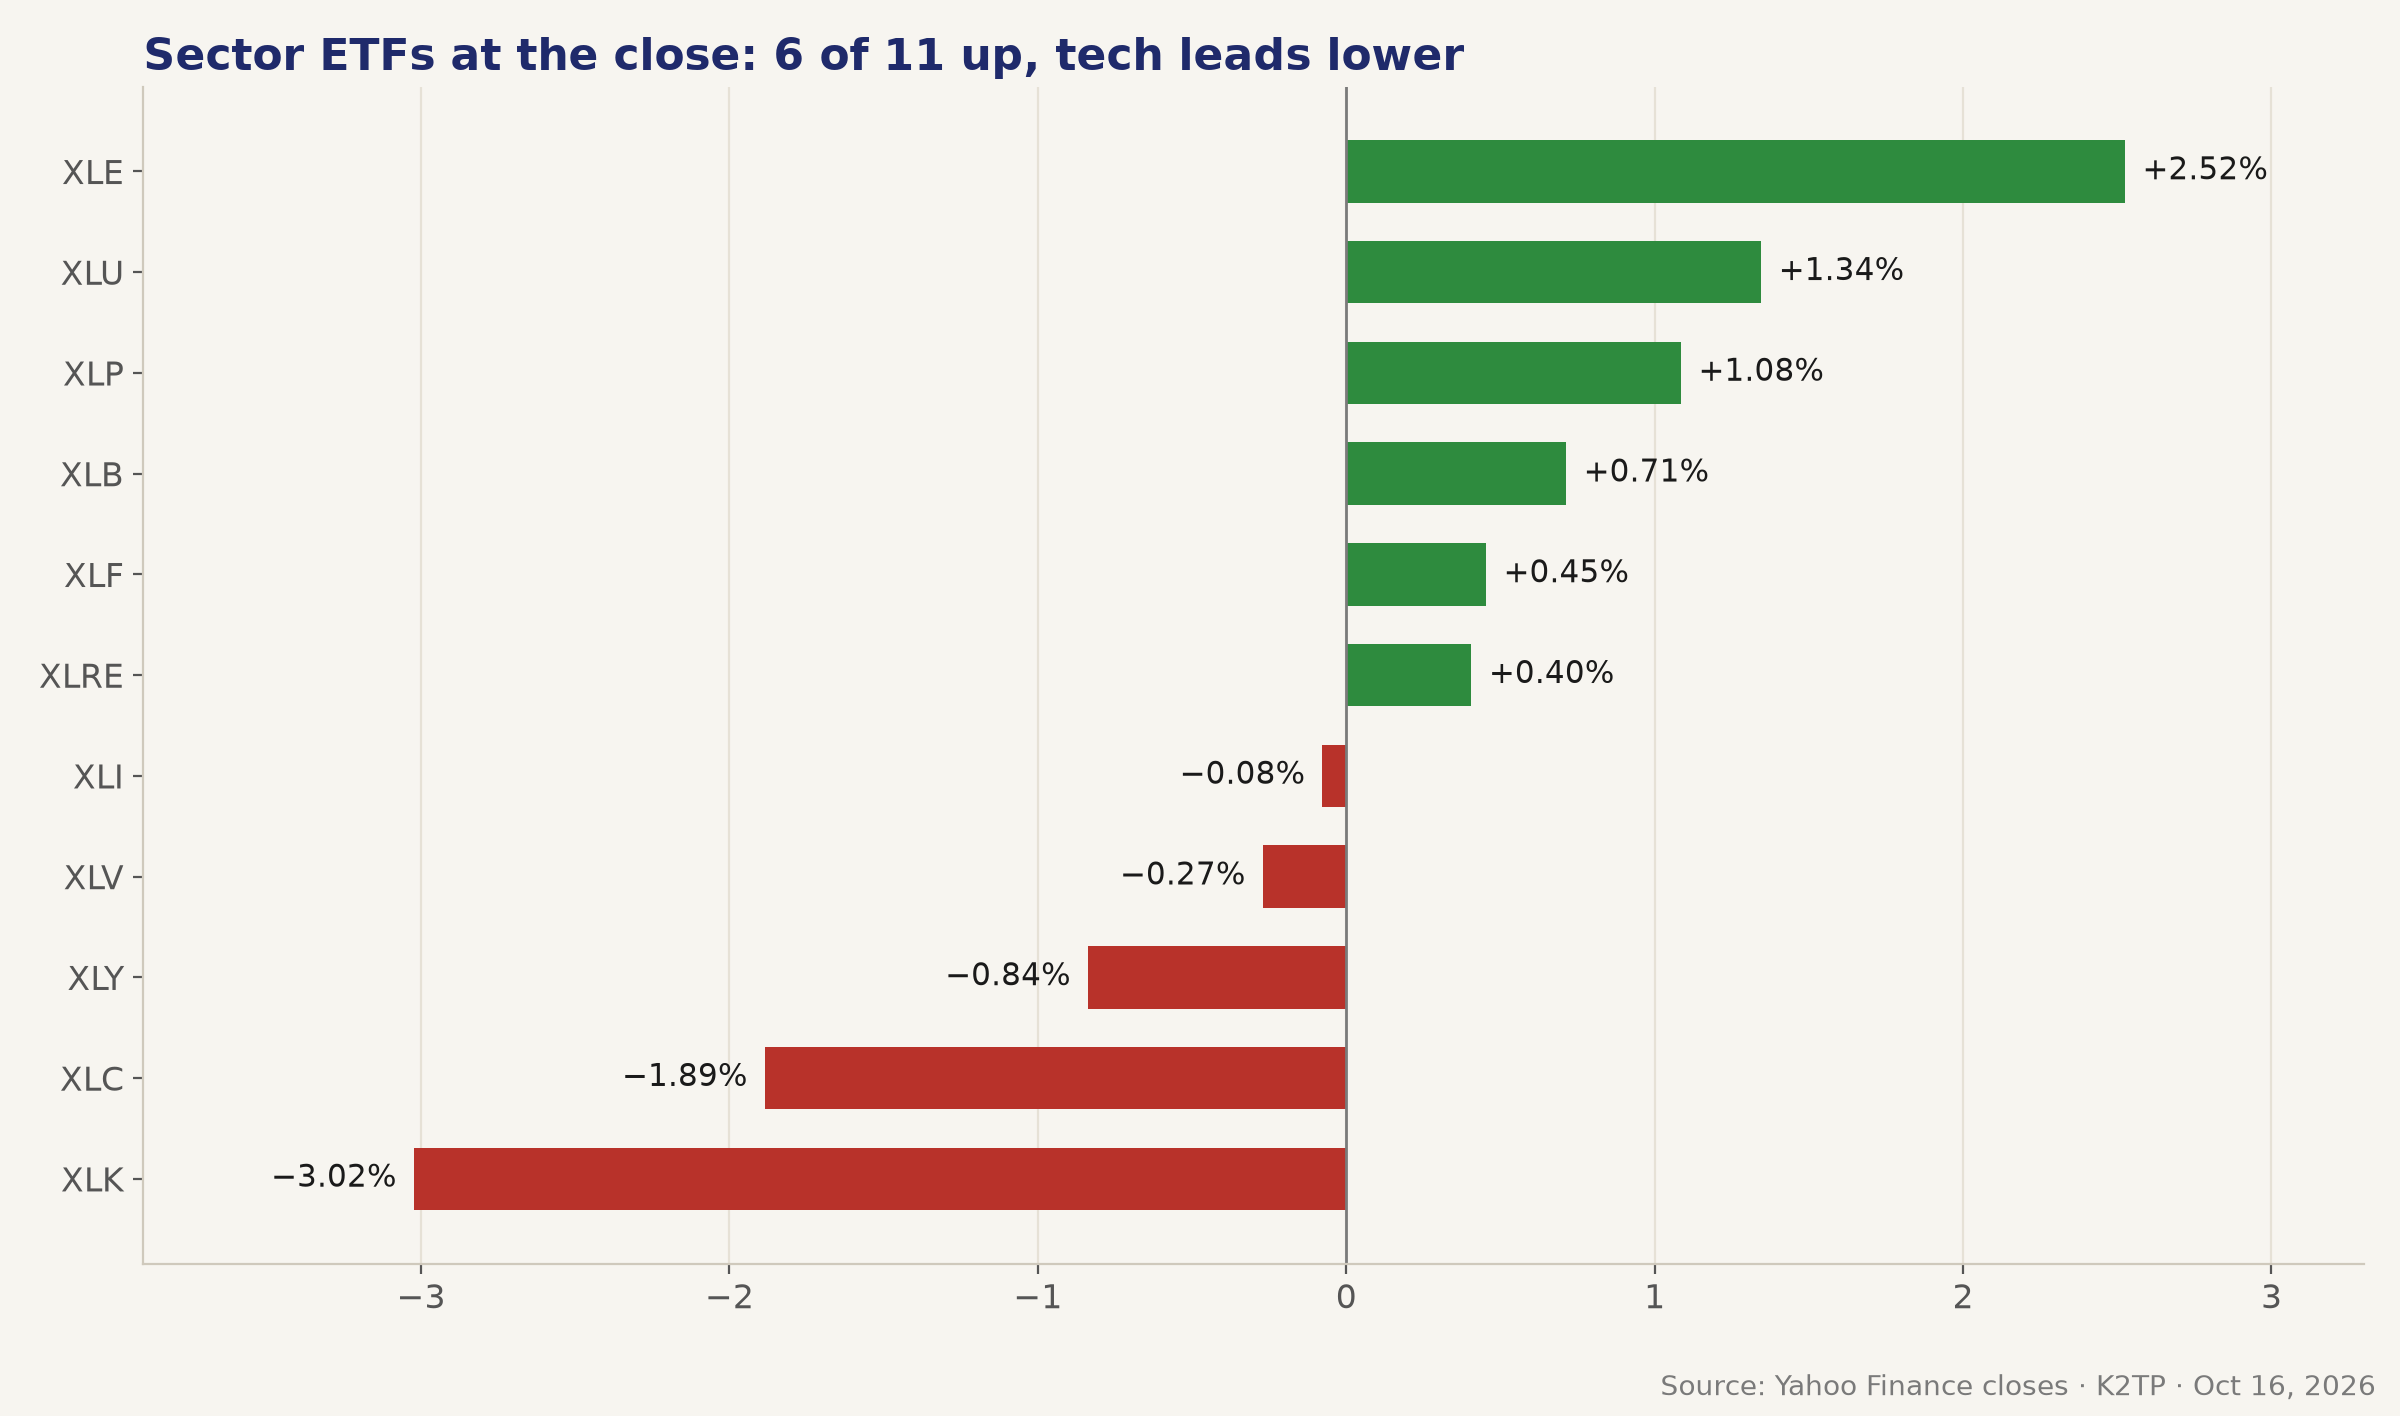
- 6 of 11 sector ETFs closed higher: XLE +2.52%, XLU +1.34%, XLP +1.08%, XLB +0.71%, XLF +0.45%, XLRE +0.40%
- Laggards: XLK −3.02%, XLC −1.89%, XLY −0.84%, XLV −0.27%, XLI −0.08%
- RSP −0.42% vs SPX −1.09%: the average stock fell much less than the cap-weighted index
- But RUT −1.66% joined the slide, so the rotation trade (Dow, small caps) no longer offset AI
- Big banks firm: WFC +1.35%, JPM +1.25%, C +0.85%; BAC −0.91%, SCHW −2.34%
→ Money is hiding in energy, utilities and staples rather than rotating into small caps. That is a defensive tape, not a healthy one.
EARNINGS: REGIONAL BANKS AND TRAVELERS
- Travelers (TRV): net income $1.917B, EPS $9.04; core EPS $9.18 vs $8.14 a year ago; combined ratio 86.8%; record net investment income $1.098B. Shares +1.47% 🟢
- Truist (TFC): diluted EPS $0.56; adjusted EPS $1.16 (+12% y/y), reflecting the RAC loan sale and a securities repositioning. Shares +1.07%
- M&T Bank (MTB): net income $775M, diluted EPS $5.04 (vs $4.82 a year ago). Shares −1.54%
- Citizens (CFG): net income $636M (+29% y/y), EPS $1.41 (+34% y/y), ROTCE 15.1%, dividend raised 13% to $0.52. Shares −0.11%
- After the close: no major after-hours reports
→ Bank and insurer results were solid, which helped XLF stay green. The market's problem is AI financing, not bank credit.
MARKET: AI SELLING OVERWHELMS THE DEFENSIVE BID
Indices (close):
- SPX 7,659.44 (−1.09%), day range 7,631.77–7,756.84
- NDX 29,187.55 (−2.50%); Nasdaq Composite 26,140.03 (−2.15%)
- DJIA 52,002.41 (−0.34%)
- RUT 2,721.37 (−1.66%)
- RSP 214.09 (−0.42%)
- SOX 11,137.29 (−3.83%)
Week (vs Oct 9 close):
- SPX −1.95%, NDX −5.49%, Nasdaq Composite −4.48%, RUT −3.05%, SOX −11.41%
- DJIA +0.67% and RSP +0.49% finished the week higher
- The Nasdaq snapped a four-week winning streak; SPX fell for the fourth time in six weeks (Investopedia)
Session path: ES +0.17% (7,804.25) pre-market after Warsh. SPX opened at 7,745.32, tagged 7,756.84 in the first minute and never recovered. It was 7,702.65 at midday and 7,634.21 at pre-close, hit 7,631.77 at 12:08 PM PT, and closed at 7,659.44.
Sector Rotation:
- Gainers: XLE +2.52%, XLU +1.34%, XLP +1.08%, XLB +0.71%
- Laggards: XLK −3.02%, XLC −1.89%, XLY −0.84%
- Mega-caps: AAPL +0.43%; NVDA −1.43%, AMZN −1.87%, MSFT −1.93%, TSLA −2.13%, GOOGL −2.47%, META −3.72%, AVGO −4.52%
Market Internals:
- At pre-close (Reuters): S&P 500 decliners outnumbered advancers 1.3-to-1; Nasdaq 49 new highs vs 263 new lows
- Official closing A/D totals: unavailable
Volatility:
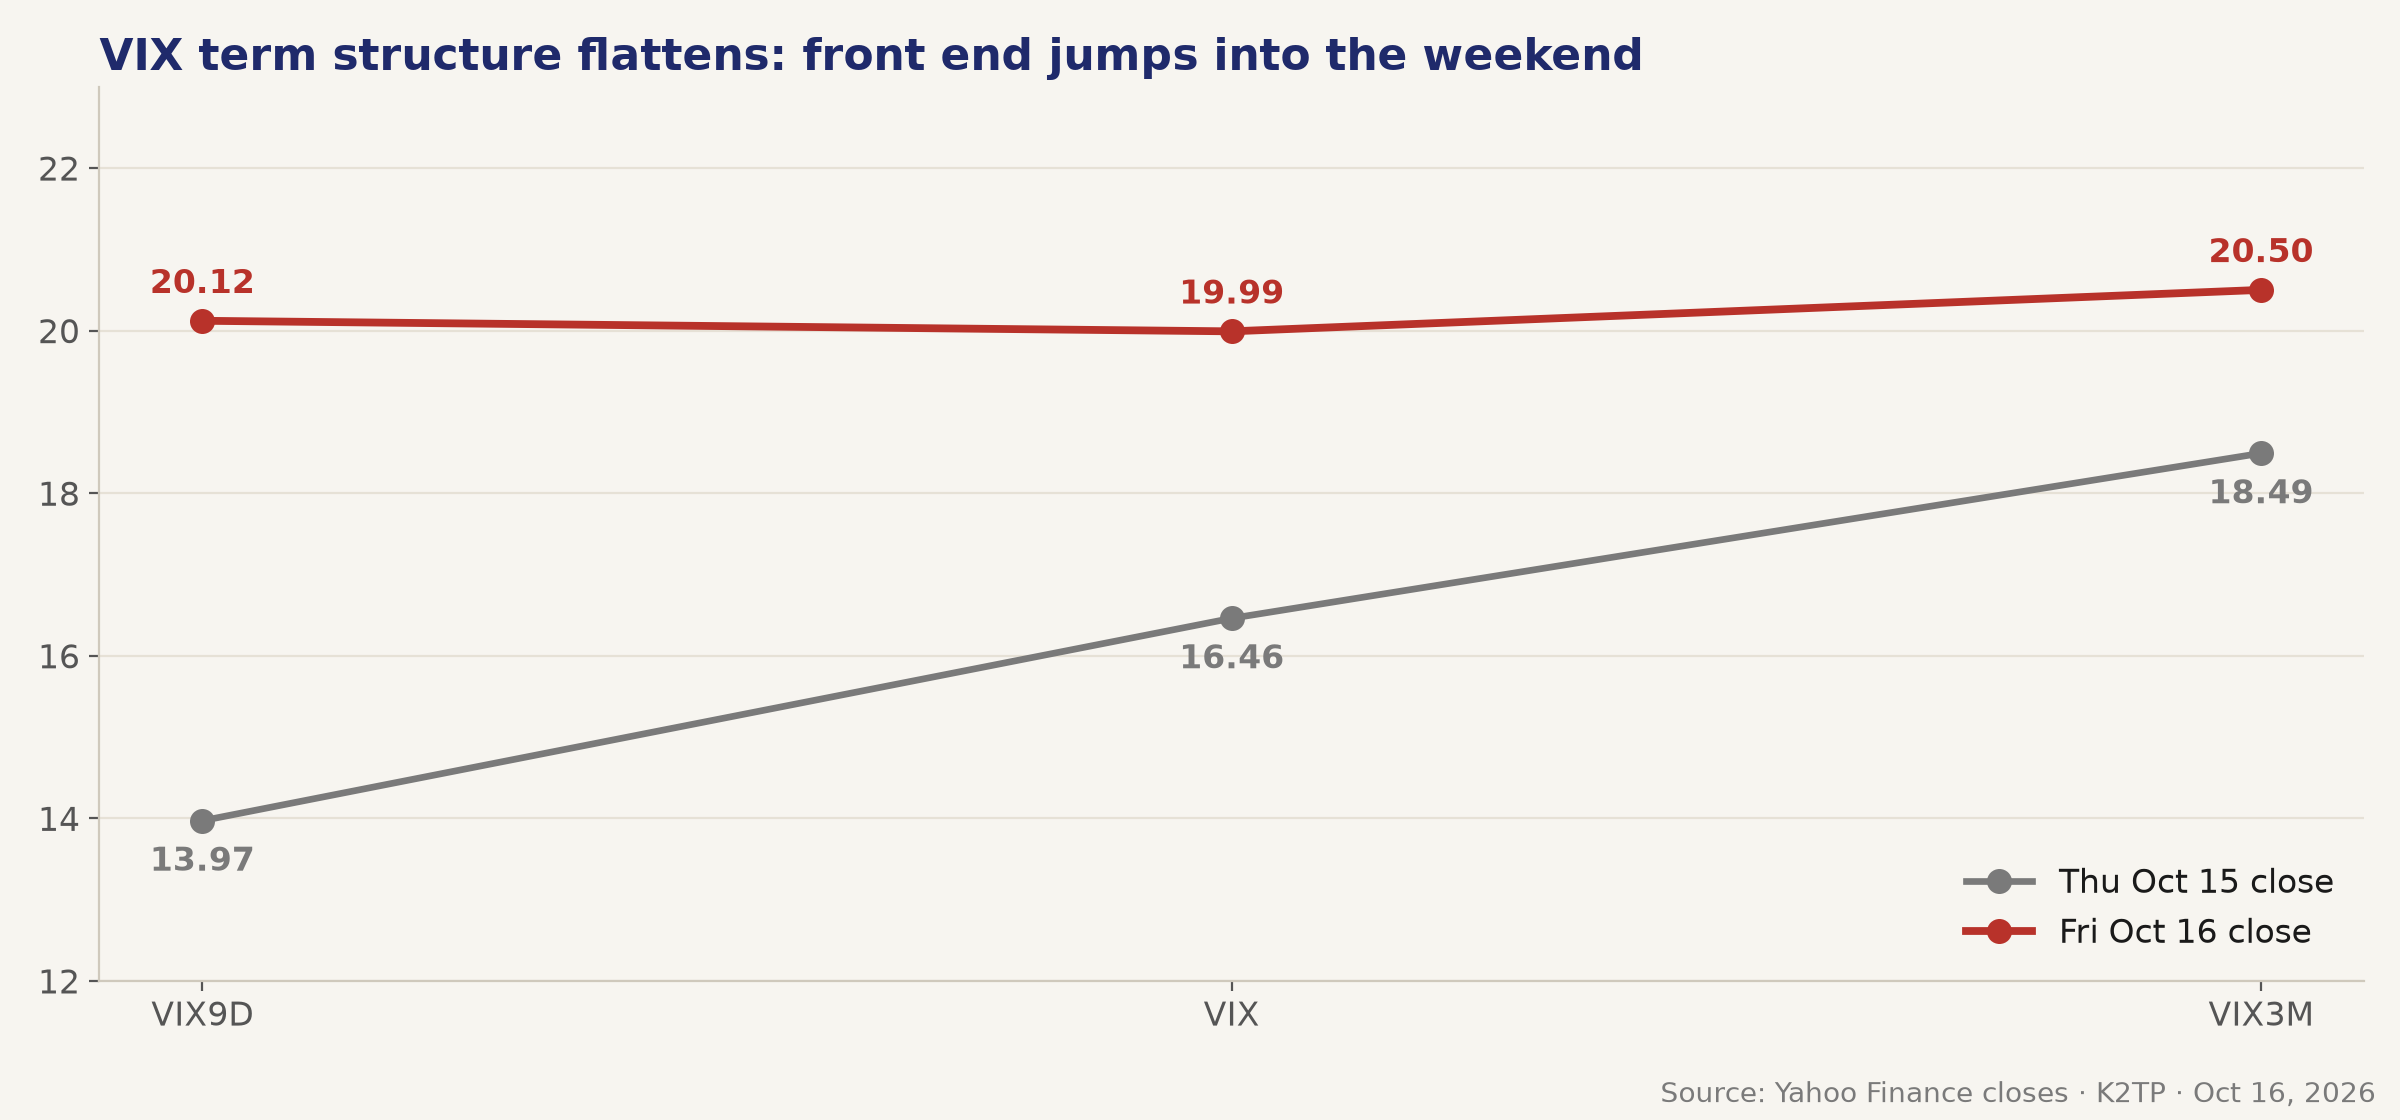
- VIX 19.99 (+21.45%), range 15.72–22.31
- VIX9D 20.12 (from 13.97), VIX3M 20.50 (from 18.49): the curve is nearly flat, and VIX9D sits above VIX
- Front-end hedging demand jumped into a weekend with oil risk
Global:
- Asia (Friday): Nikkei +1.39% (65,324.29), Hang Seng +0.52%, Shanghai +0.24%
- Europe closed before the US selloff: STOXX 50 +0.58%, DAX +0.95%, FTSE +0.38%
SPX Key Levels:
- 7,756.84: Friday's high
- 7,744.06: Thursday's close
- 7,691.56: midday low, the first line to reclaim
- 7,659.44: close
- 7,631.77: Friday's low
- VIX: 20.00 and 22.31
Option-seller angle:
- Bull case: SPX back above 7,691.56 with VIX under 20 would signal Friday's flush was OpEx/weekend hedging. Even then, only sell put premium far out of the money and in small size.
- Bear case: SPX under 7,631.77 with VIX above 22.31 opens a deeper de-risking leg. Cut short-put size or move to defined-risk spreads.
- Avoid tight Iron Condors on NDX and semis: SOX has fallen eight straight days and VIX9D is above VIX.
- Weekend gap risk is two-sided (Hormuz headlines, AI credit). Avoid 0DTE positions at Monday's open until the first hour sets direction.
BOTTOM LINE
- The AI-debt story widened from CoreWeave to chips and mega-cap platforms. NDX fell 2.50% on the day and 5.49% on the week.
- Brent near $110 and a flat 10Y meant bonds offered no cushion. VIX jumped 21% and the term structure flattened.
- The regime closed the week at RISK-OFF. It can only return to TRANSITION once CRWV/SOX stabilize and SPX reclaims 7,691.56.
What to watch next week (PT):
- Weekend: Middle East / Strait of Hormuz headlines and the Brent $110 line
- CoreWeave stock and bonds as the AI-credit gauge
- Earnings season shifts into high gear: Tesla, Meta, Netflix and Procter & Gamble report next week (Reuters). LSEG sees Q3 earnings up more than 30%
- Oct 27–28: FOMC
Expected (Bull): SPX above 7,691.56 with VIX under 20 and SOX snapping its losing streak. Expected (Bear): SPX under 7,631.77 with VIX above 22.31 and Brent above $110.
Sources: 3 K2TP briefs for Oct 16, 2026 (Pre-Market, Midday, Pre-Close; the Evening Recap was not yet available). Closing prices from Yahoo Finance; oil settlements, news and breadth from Reuters, AP, MarketWatch and Investopedia; earnings from TRV, TFC, MTB and CFG releases. Analysis: K2TP Framework.