Market 10/15: Hot PPI, Bonds Rally, Rotation Out of AI Snaps SPX's 3-Day Slide
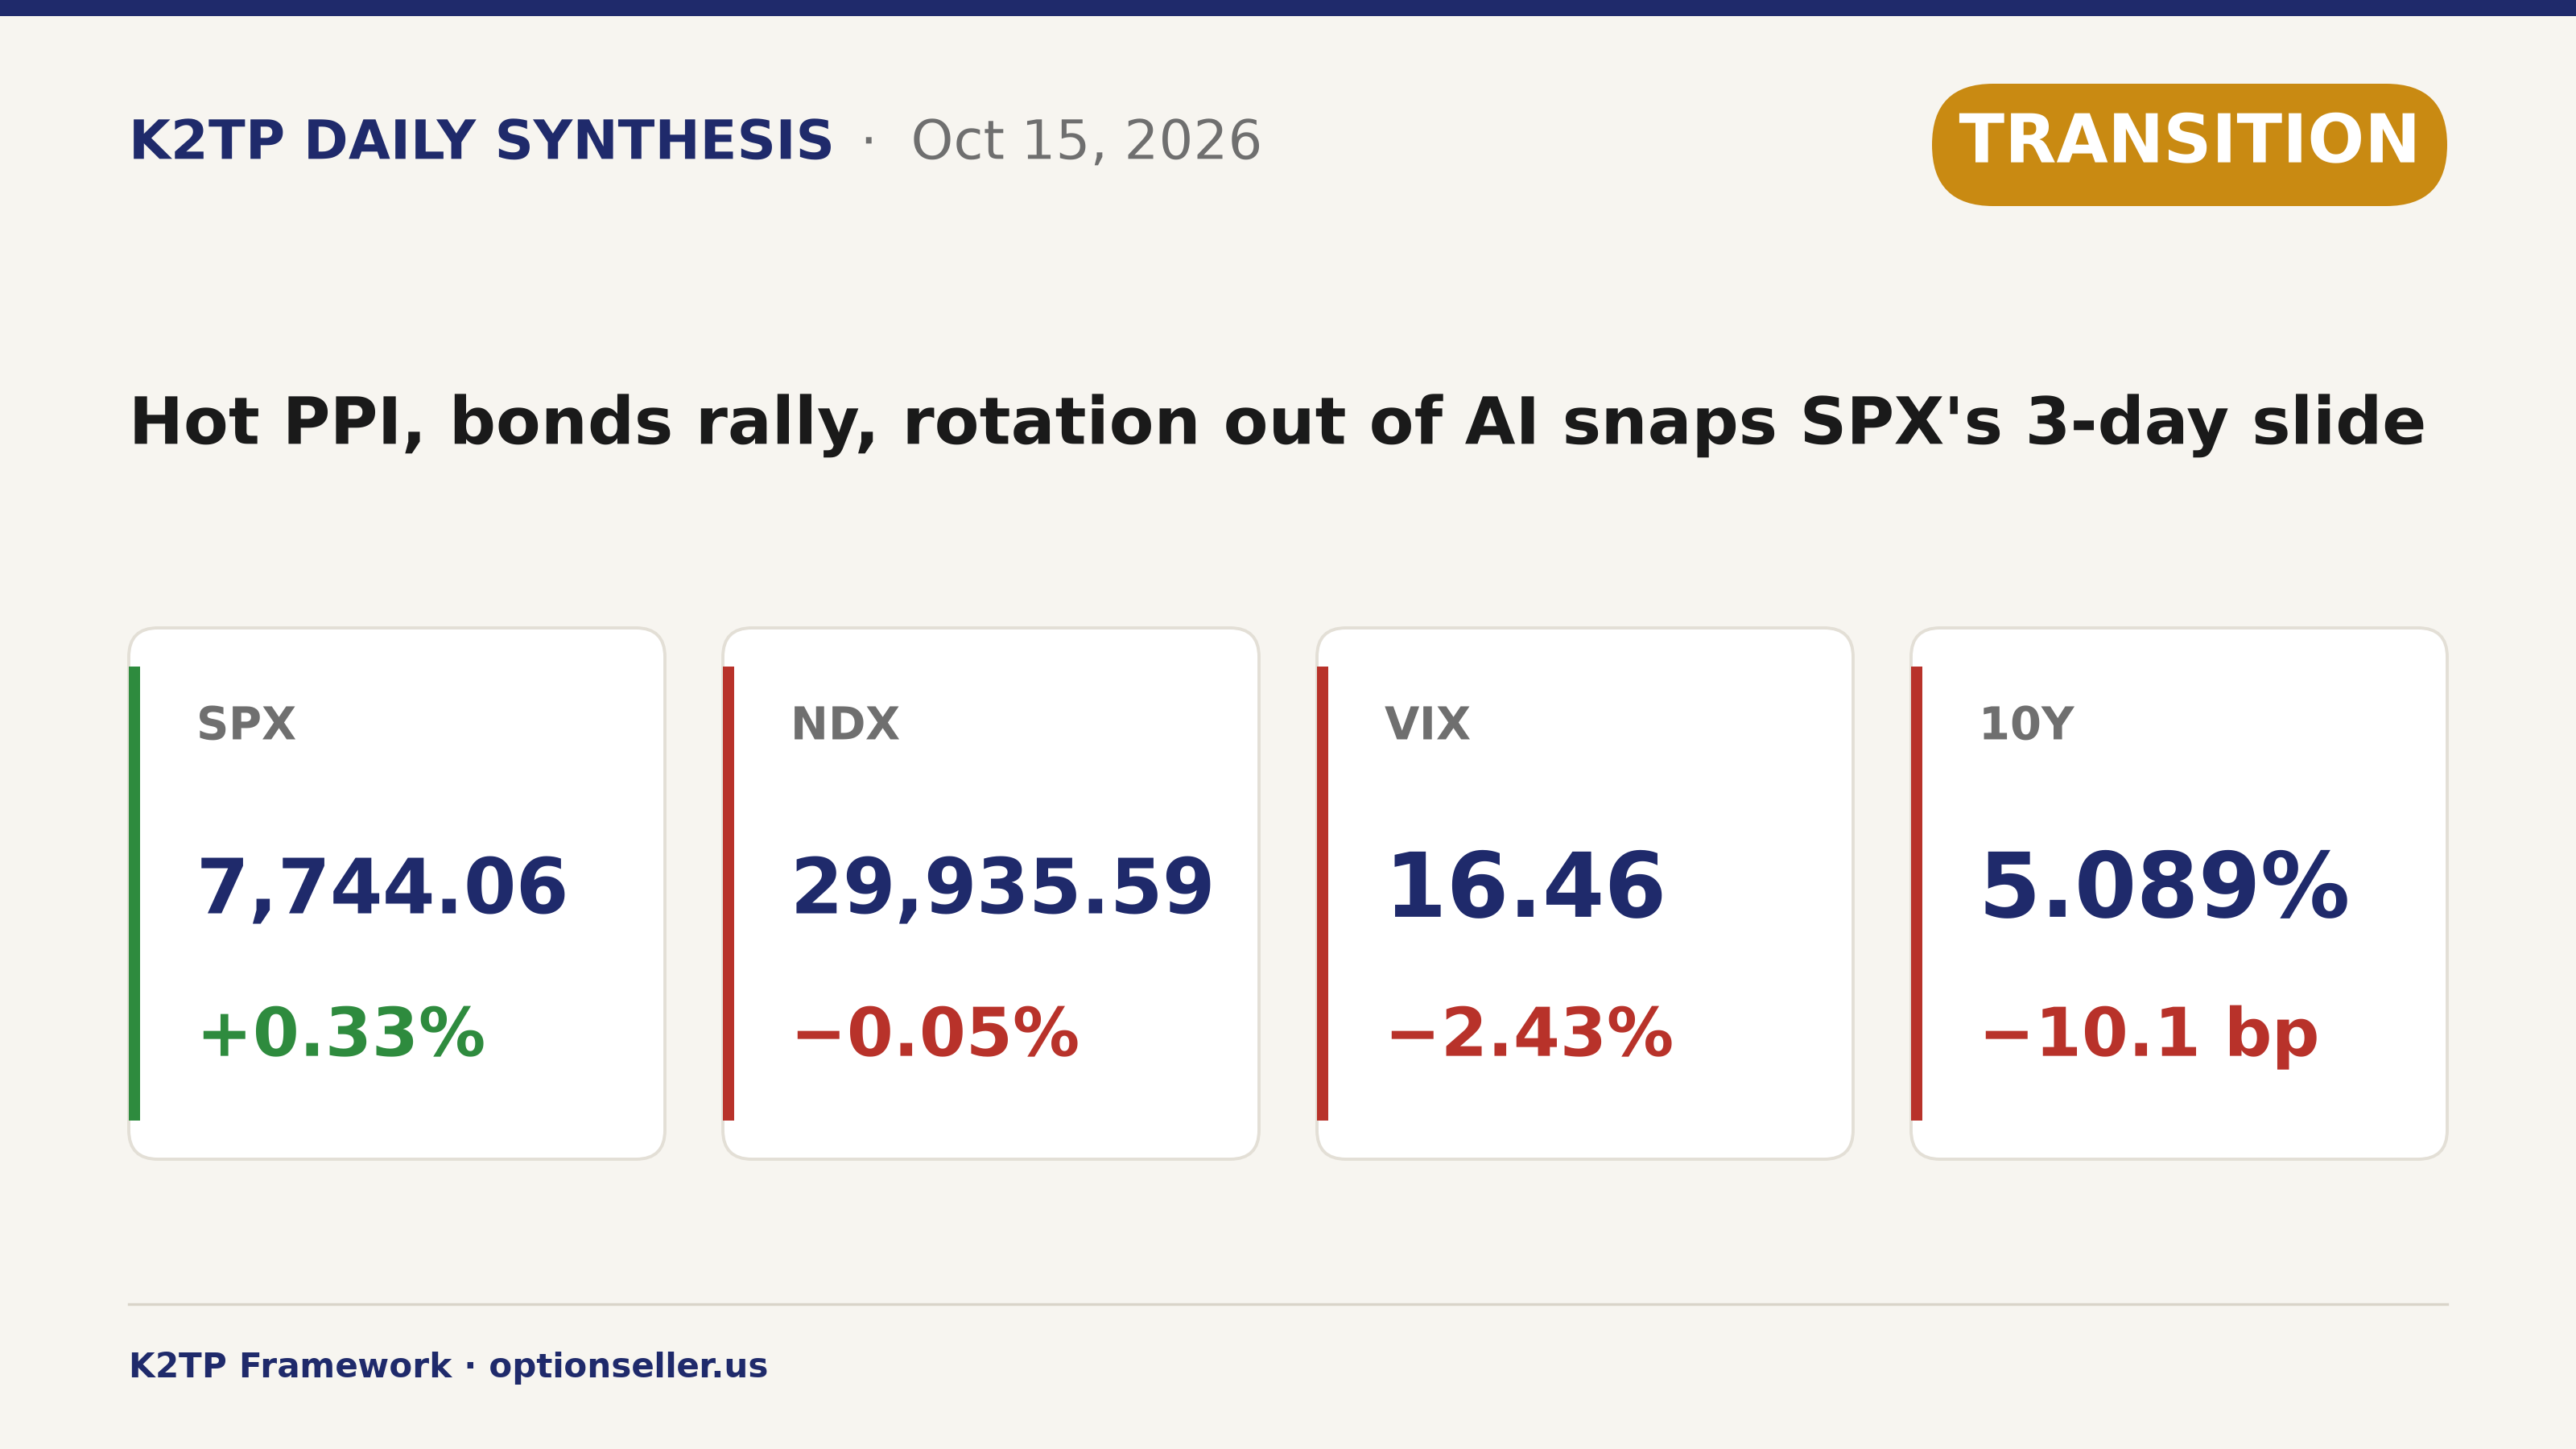
SPX +0.33%, NDX −0.05%, VIX −2.43%. Bonds bought the hot PPI; money rotated out of AI into everything else.
KEY HEADLINES
- September PPI hot: +1.3% m/m, 6.3% y/y; core +0.7% vs +0.3% expected
- Retail sales +0.8% beat; Empire 25.5 beat, Philly Fed 20.9 missed
- Bonds rallied anyway: 10Y −10.1 bp to 5.089%
- October hike odds eased: ~35% → ~29%
- Rotation out of AI: Dow +1.08%, RUT +1.38%, RSP +1.37%; NDX −0.05%
- SPX +0.33%, snapping a three-day losing streak
- TSMC beat-and-raise, but TSM −1.80% and SOX −0.88%, a seventh straight decline
- AI infrastructure split: CRWV +5.94%, ORCL +3.00%; DELL −9.07% (pre-close)
- Oil: EIA crude draw of −8.557M barrels; WTI $95.86
- After hours: Alcoa beat on EPS; IBKR and J.B. Hunt slipped
- Regime: 🔴 RISK-OFF pre-market → 🟡 TRANSITION by midday and into the close
SEPTEMBER PPI RUNS HOT RIGHT AFTER CPI
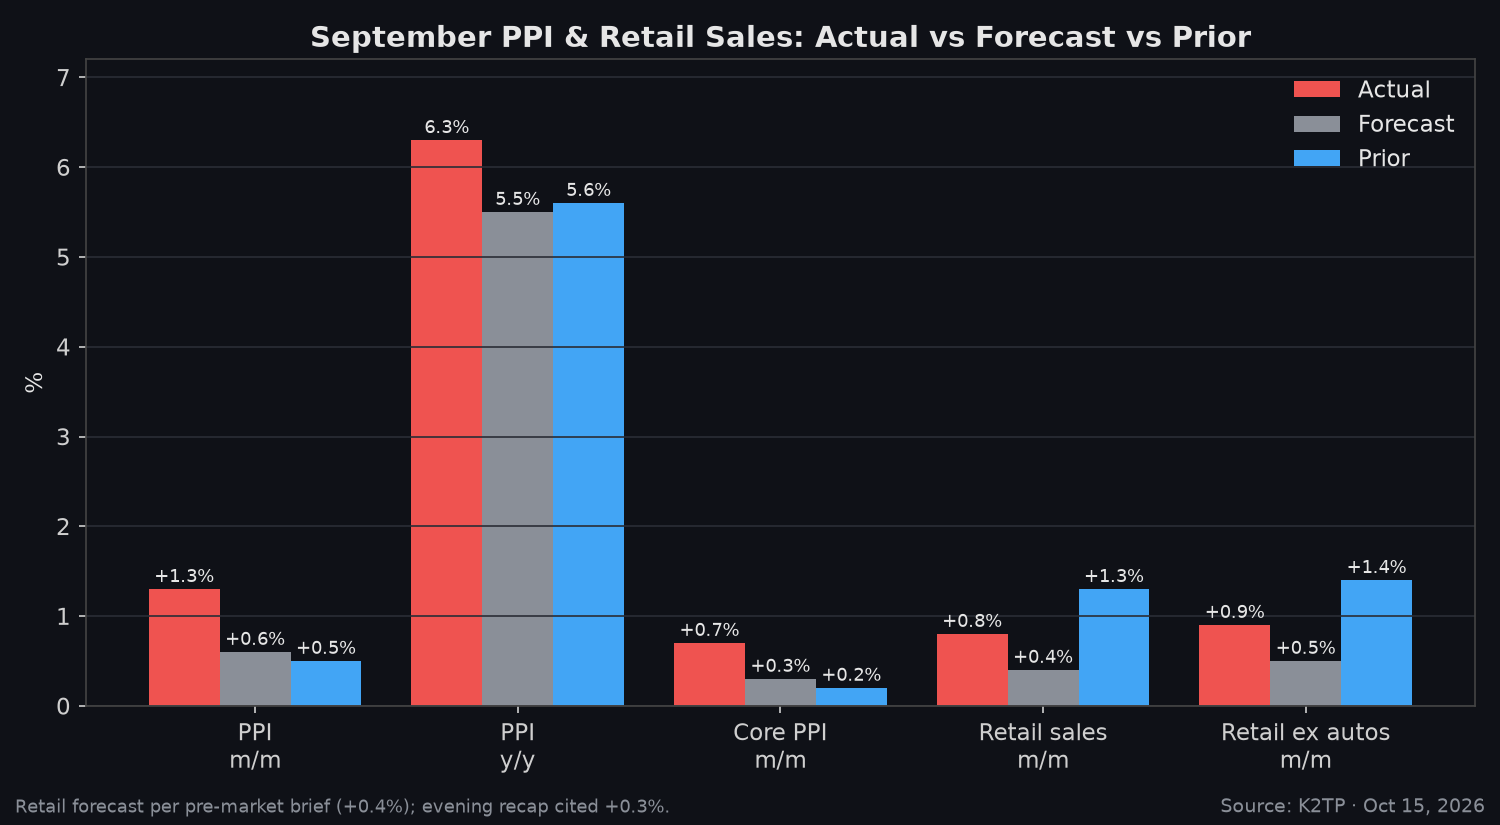
- PPI: +1.3% m/m (forecast +0.6%, prior +0.5%) 🔴, the largest since 2022
- PPI: 6.3% y/y (forecast 5.5%, prior 5.6%) 🔴
- Core PPI: +0.7% m/m (forecast +0.3%, prior +0.2%) 🔴
- Ex food, energy and trade: +0.5%; CNBC pointed to energy/diesel pass-through and war-related supply shocks
- Released at 5:30 AM PT. ES −0.31% (7,746.50) and NQ −1.23% (29,811.75) ahead of the open
→ Two hot inflation prints in two days, but the market read PPI as energy-heavy and did not reprice the Fed higher.
RETAIL SALES BEAT, REGIONAL SURVEYS MIXED
- Retail sales: +0.8% m/m (forecast +0.4%, prior +1.3%) 🟢
- Retail sales ex autos: +0.9% m/m (forecast +0.5%, prior +1.4%) 🟢
- Initial jobless claims: 199K (forecast 200K, prior 198K)
- Empire State: 25.5 (forecast 10.3, prior 7.6) 🟢
- Philly Fed: 20.9 (forecast 28.4, prior 37.8) 🔴, still in expansion
→ The consumer is still spending. That keeps the hawkish case alive even though yields fell.
FED: OCTOBER HIKE ODDS EASE TO ~29%
- CME FedWatch, October hike: ~35% (Wed evening) → ~29% (Thu morning; Reuters cited ~27%) → ~29% (Thu afternoon)
- Still above the ~22% from early in the week
- Odds of at least one hike by December: near 91%
- FOMC meets Oct 27–28. Fed Chair Warsh speaks with IMF's Georgieva at 8:30 PM PT tonight
→ Hot PPI did not push hike odds back up. Warsh's tone tonight is the next test.
TREASURIES: 10Y DOWN 10 BP DESPITE HOT PPI
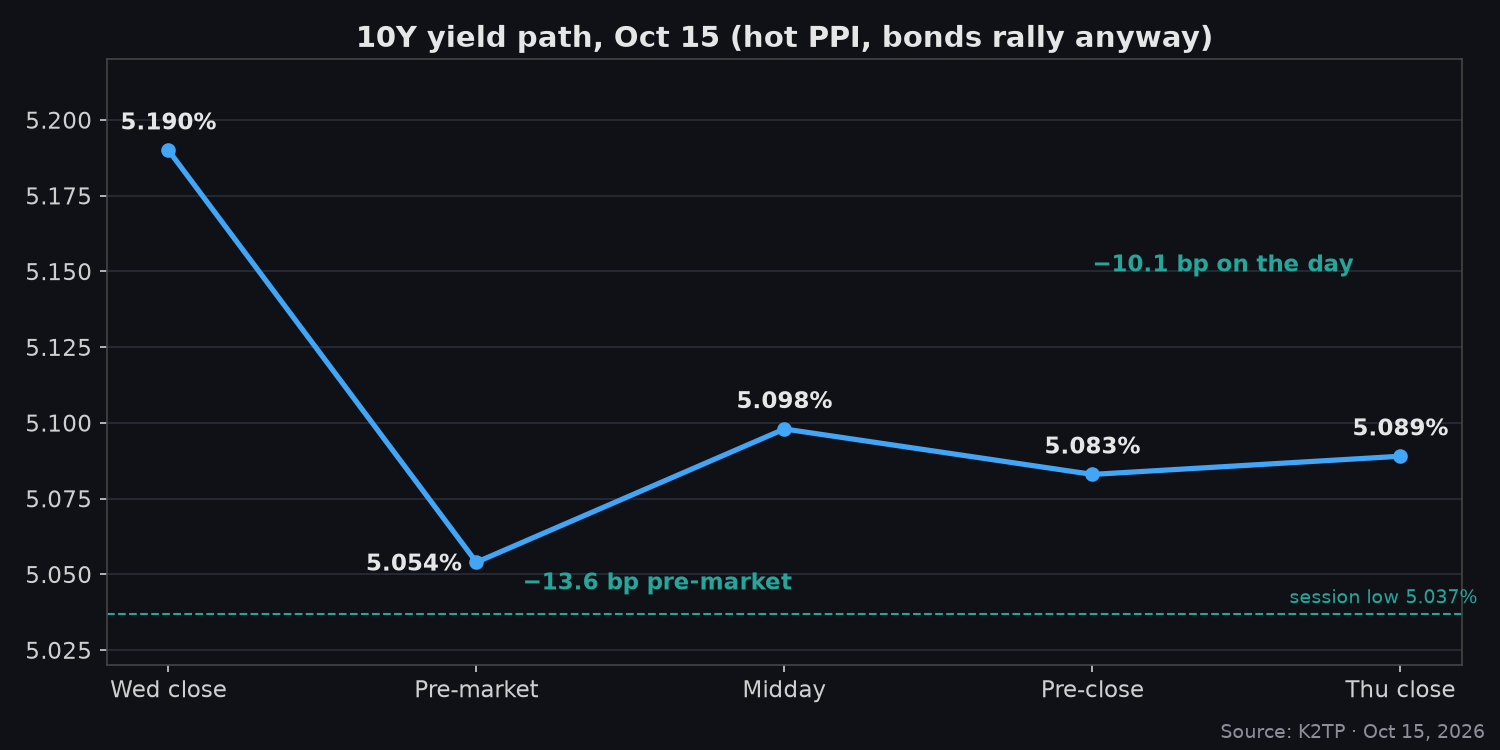
- 10Y: 5.190% → 5.054% pre-market (−13.6 bp) → session low 5.037% → 5.098% midday → 5.089% close (−10.1 bp) 🟢
- 5Y: 4.899% (−9.3 bp); 30Y: 5.429% (−9.6 bp)
- Curve: 5s30s 53.0 bp, roughly flat vs 53.3 bp Wednesday
- 13-week bill 4.088% (+0.3 bp); DXY 102.03 (−0.51%)
- Gold $4,179.20; BTC $82,093
→ The briefs read this as flight-to-quality, not a dovish repricing. Lower long-end yields cushioned rate-sensitive groups.
ROTATION OUT OF AI: DOW AND SMALL CAPS LEAD
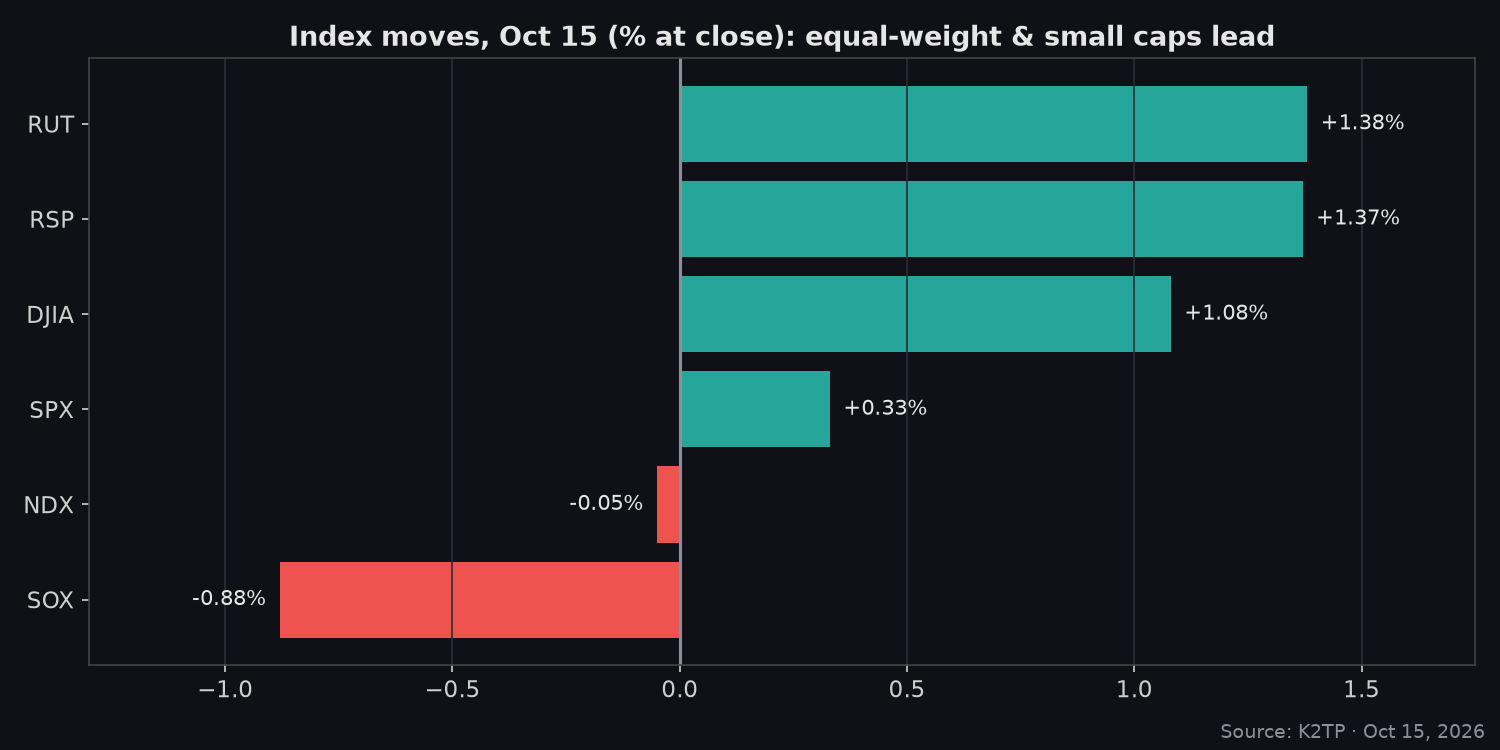
- RUT +1.38%, RSP +1.37%, DJIA +1.08% vs SPX +0.33% and NDX −0.05%
- Equal-weight beat cap-weight by about 104 bp
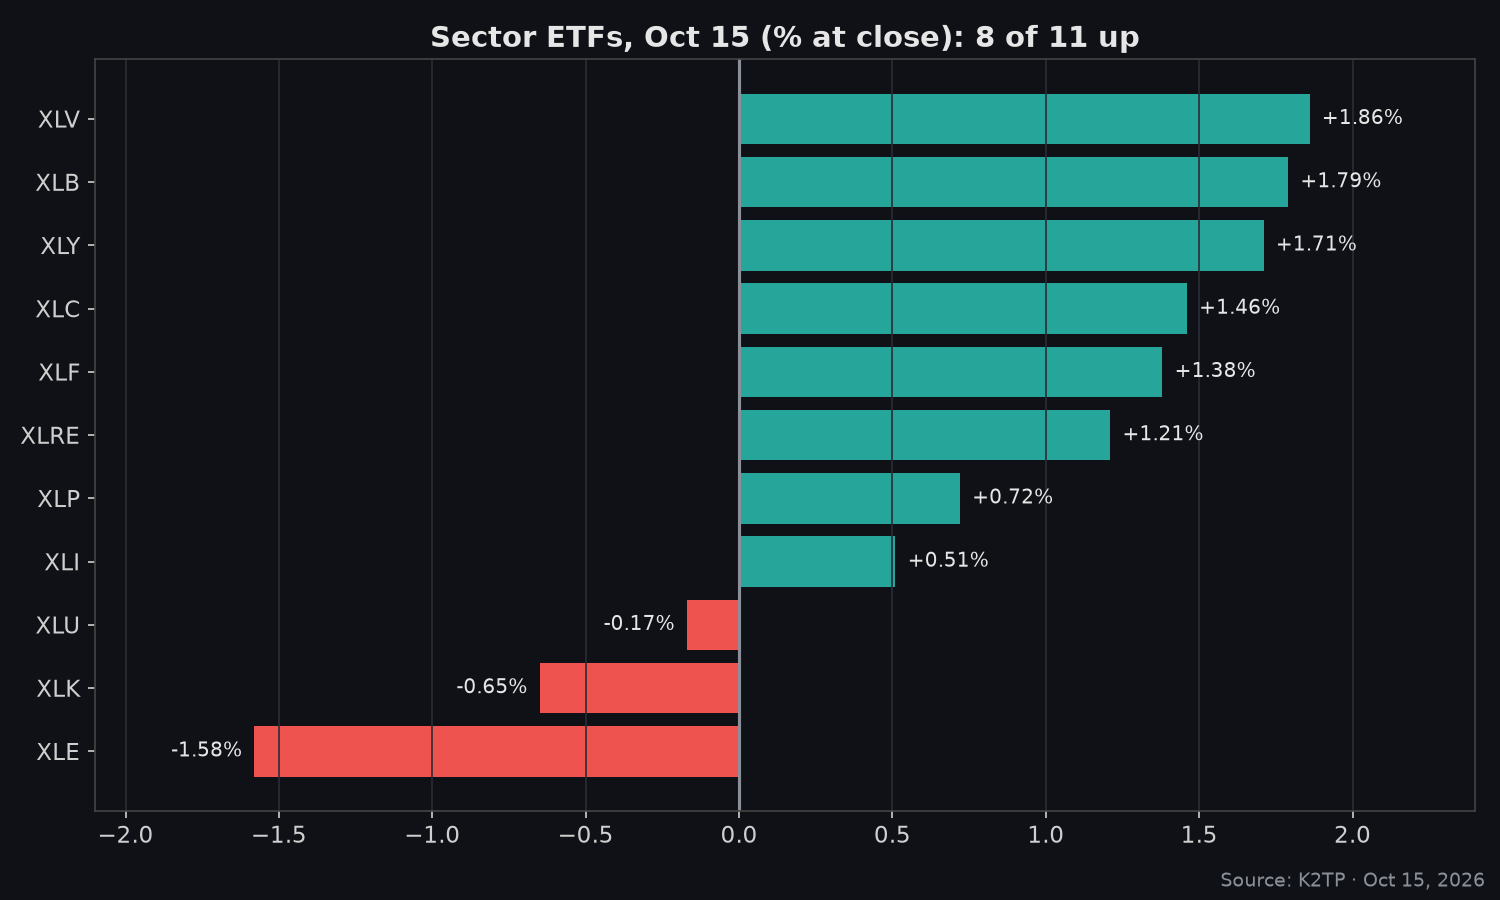
- 8 of 11 sector ETFs closed higher: XLV +1.86%, XLB +1.79%, XLY +1.71%, XLC +1.46%, XLF +1.38%
- Laggards: XLE −1.58%, XLK −0.65%, XLU −0.17%
- Defensive and value leaders at pre-close: LLY +4.85%, UNH +3.65%, WMT +1.79% (Deutsche Bank upgrade), BLK +3.89%, WFC +2.58%
→ Money did not leave equities. It moved from AI into health care, financials, consumer and small caps.
TSMC: BEAT-AND-RAISE, BUT MARGIN DILUTION WEIGHS
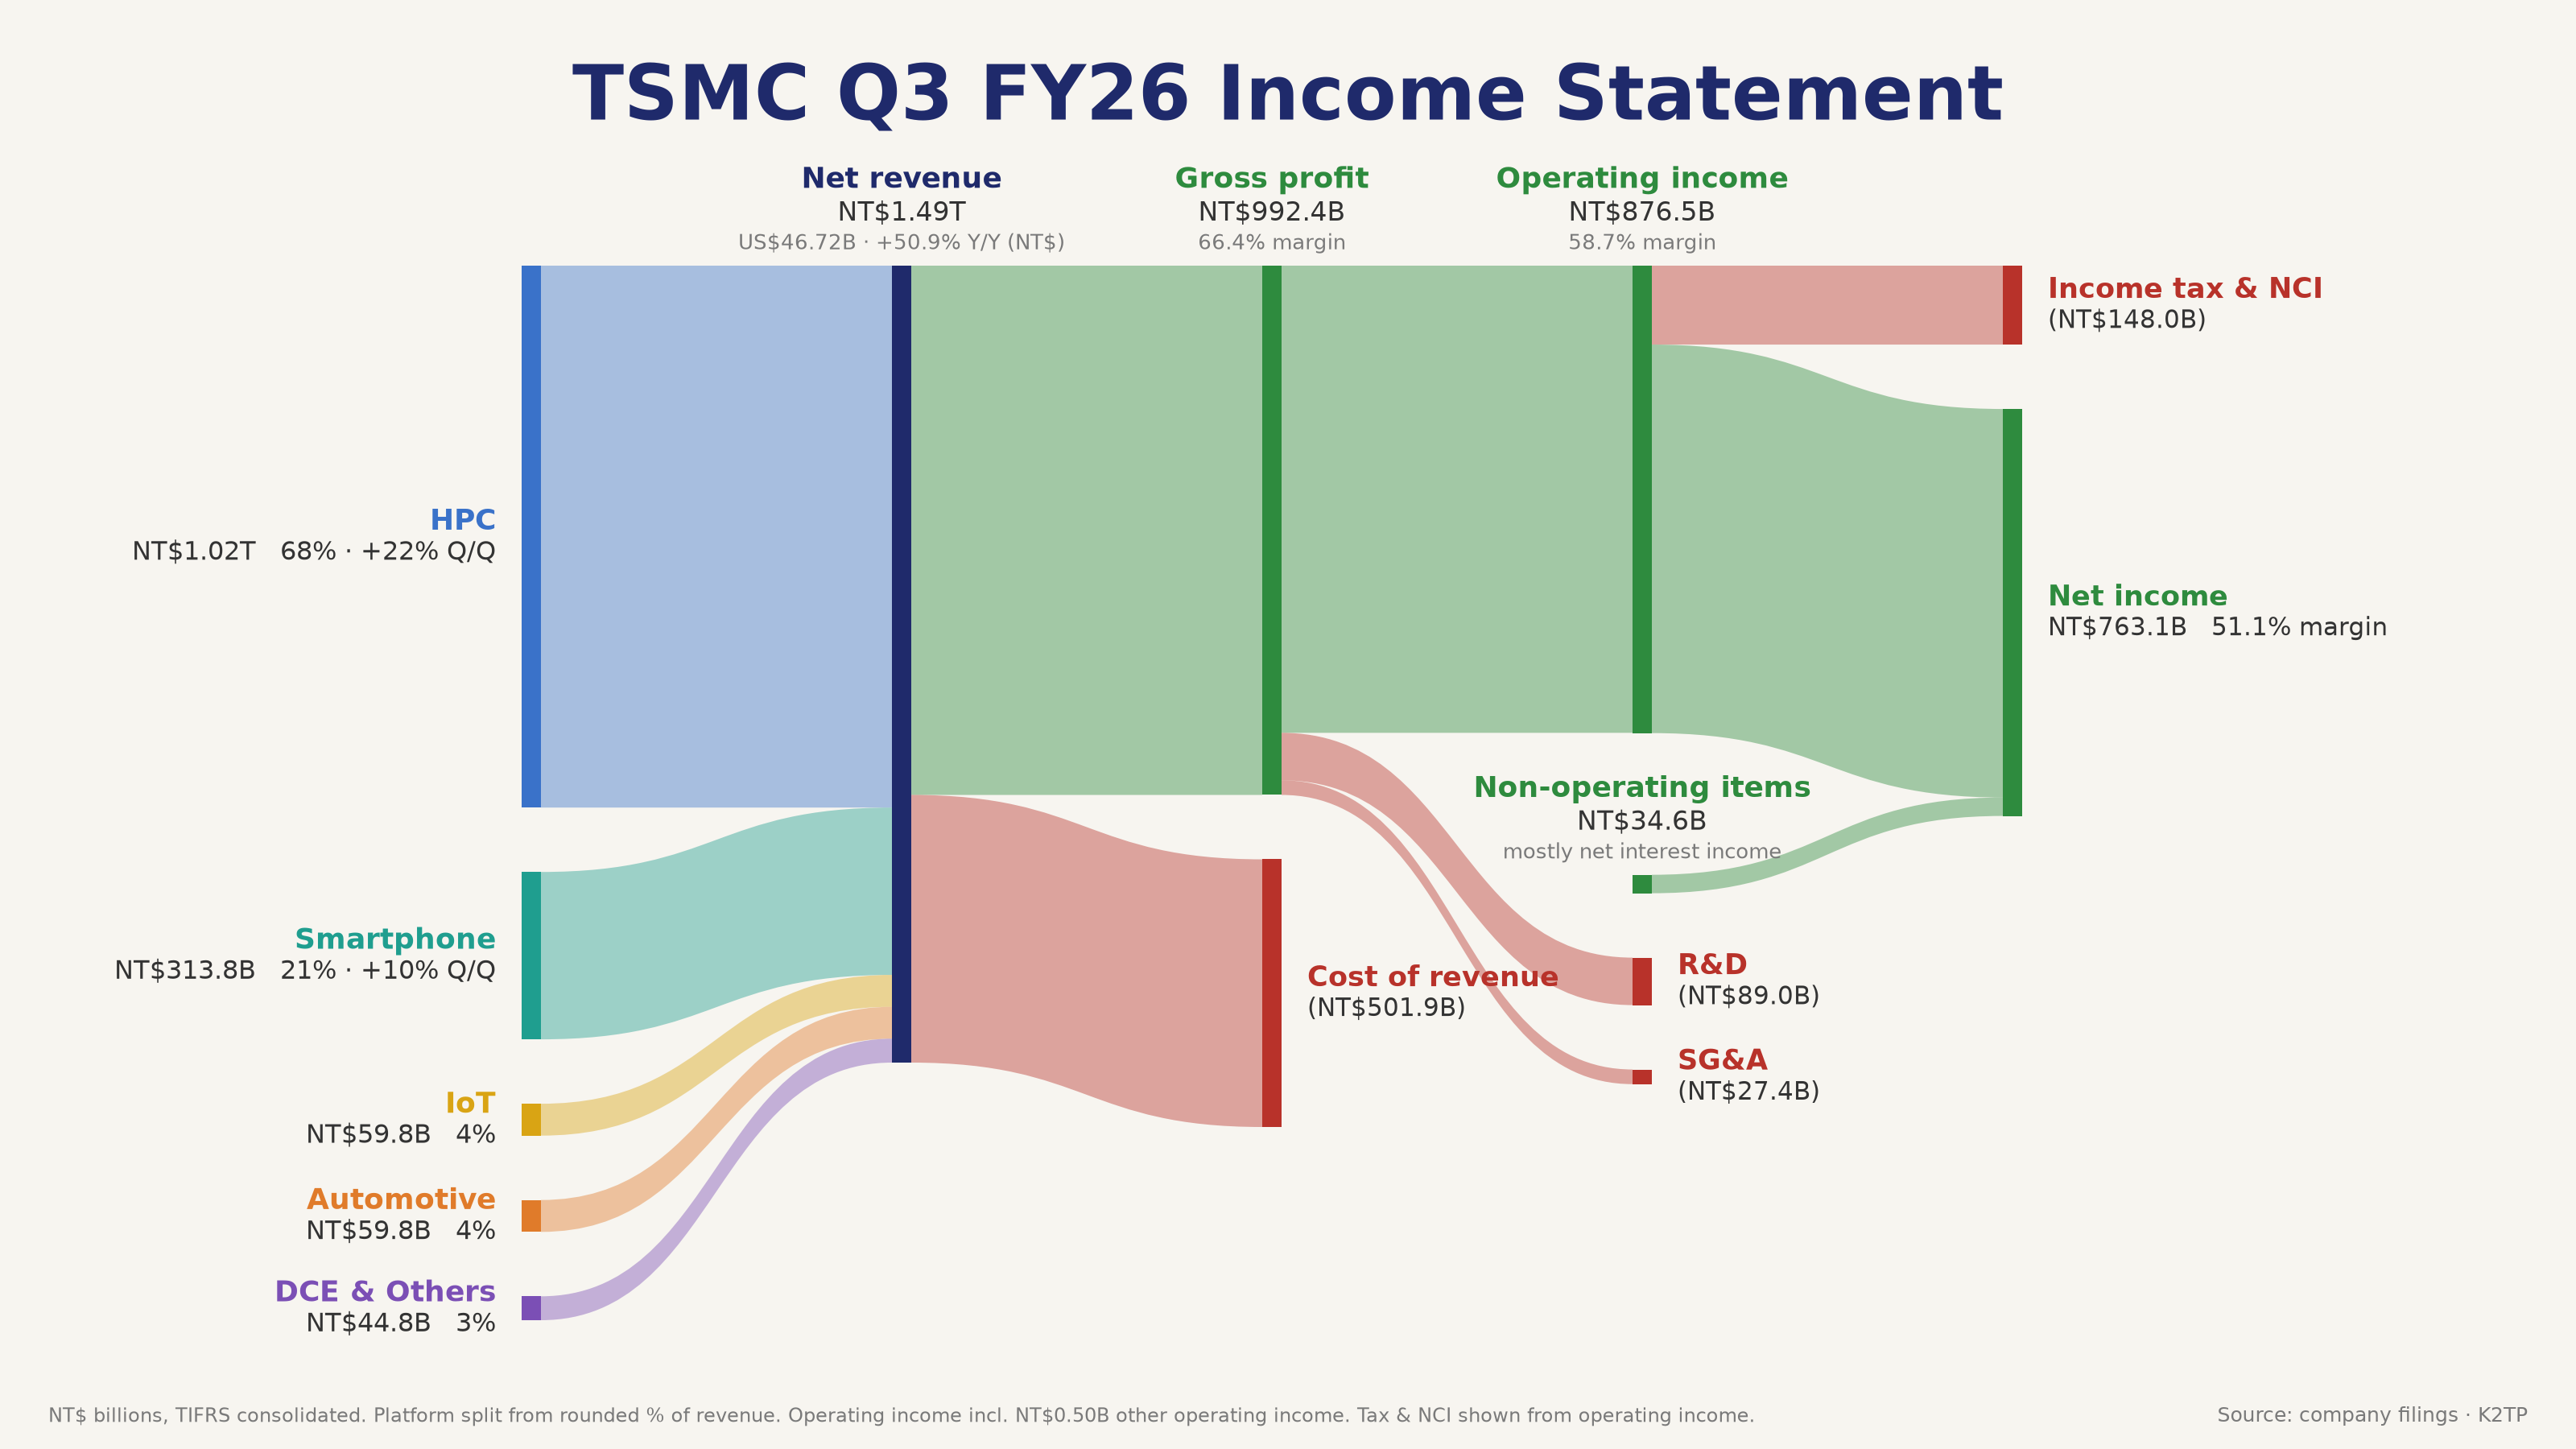
- Revenue: NT$1.49T (beat); US$46.72B vs the prior $44.6–45.8B guide 🟢
- Net profit: NT$763.1B, +68.7% y/y (beat vs ~NT$746B) 🟢
- Gross margin 66.4%, operating margin 58.7%
- Q4 revenue guide: $52.3–54.3B (+58% y/y at the midpoint) 🟢
- 2026 USD revenue growth raised to ~44%; capex guide still ~$60–65B
- CFO flagged ~2% gross-margin dilution from capacity build; CEO sounded prudent on 2027 🔴
- TSM ADR: 430.00 (Wed) → 417.18 (−2.98%) midday → 422.25 (−1.80%) close
→ AI demand is intact, but the margin and capex story kept semis from a relief bid.
SEMIS DOWN A 7TH STRAIGHT DAY, AI INFRASTRUCTURE SPLITS
- SOX: −2.62% at midday (11,377.98) → −0.88% close (11,581.22), off the 11,171.79 low 🔴
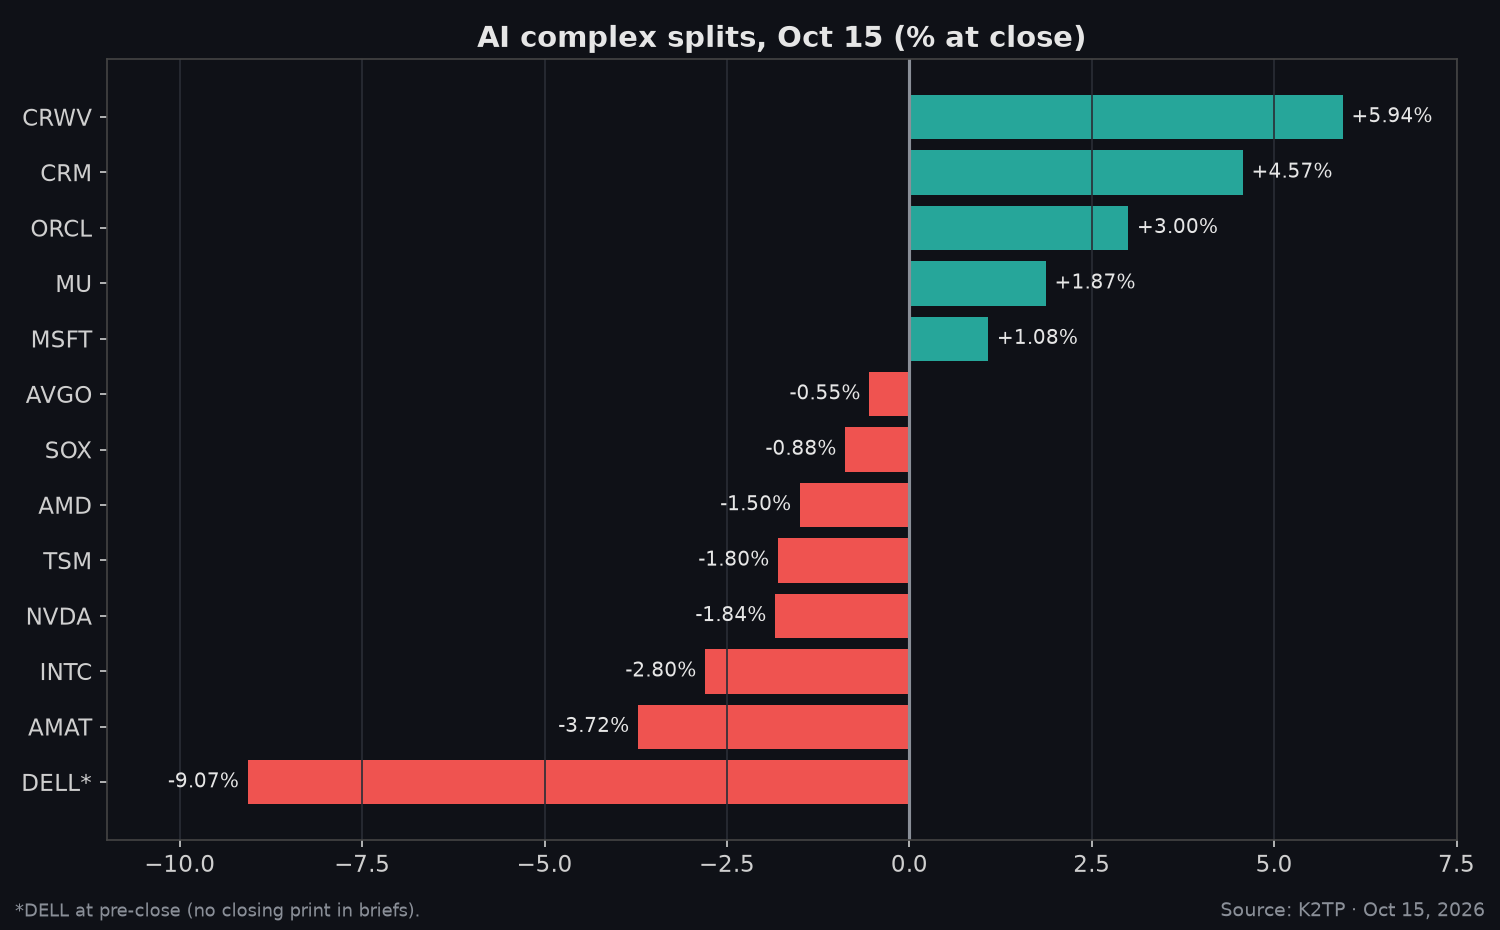
- Laggards: AMAT −3.72%, INTC −2.80%, NVDA −1.84%, TSM −1.80%, AMD −1.50%, AVGO −0.55%
- MU flipped to +1.87% by the close
- CRWV +5.94% after Jensen Huang said CoreWeave's strength is "improving every day"; ORCL +3.00% (bouncing after −8.83% Wed); CRM +4.57%
- DELL −9.07% (pre-close); AI debt-financing worries are still the story
- A reported 45% sequential jump in Anthropic's quarterly revenue offered little early reprieve (Reuters)
→ The late bounce in debt-heavy names looks more like short covering than a new uptrend. SOX has not turned up yet.
OIL: EIA DRAW KEEPS WTI NEAR $96
- EIA crude: −8.557M barrels (forecast +0.2M, prior −3.186M)
- WTI: $94.08 pre-market → $96.68 midday (high $96.74) → $95.86 close (+2.09%)
- Brent $105.38 (−0.64%); Hormuz shipping headlines kept a risk premium in the complex
- XLE −1.58%, the weakest sector ETF
→ High oil keeps feeding the PPI/CPI story into Friday's import prices, even though energy stocks lagged.
EARNINGS AFTER THE CLOSE: AA, IBKR, JBHT
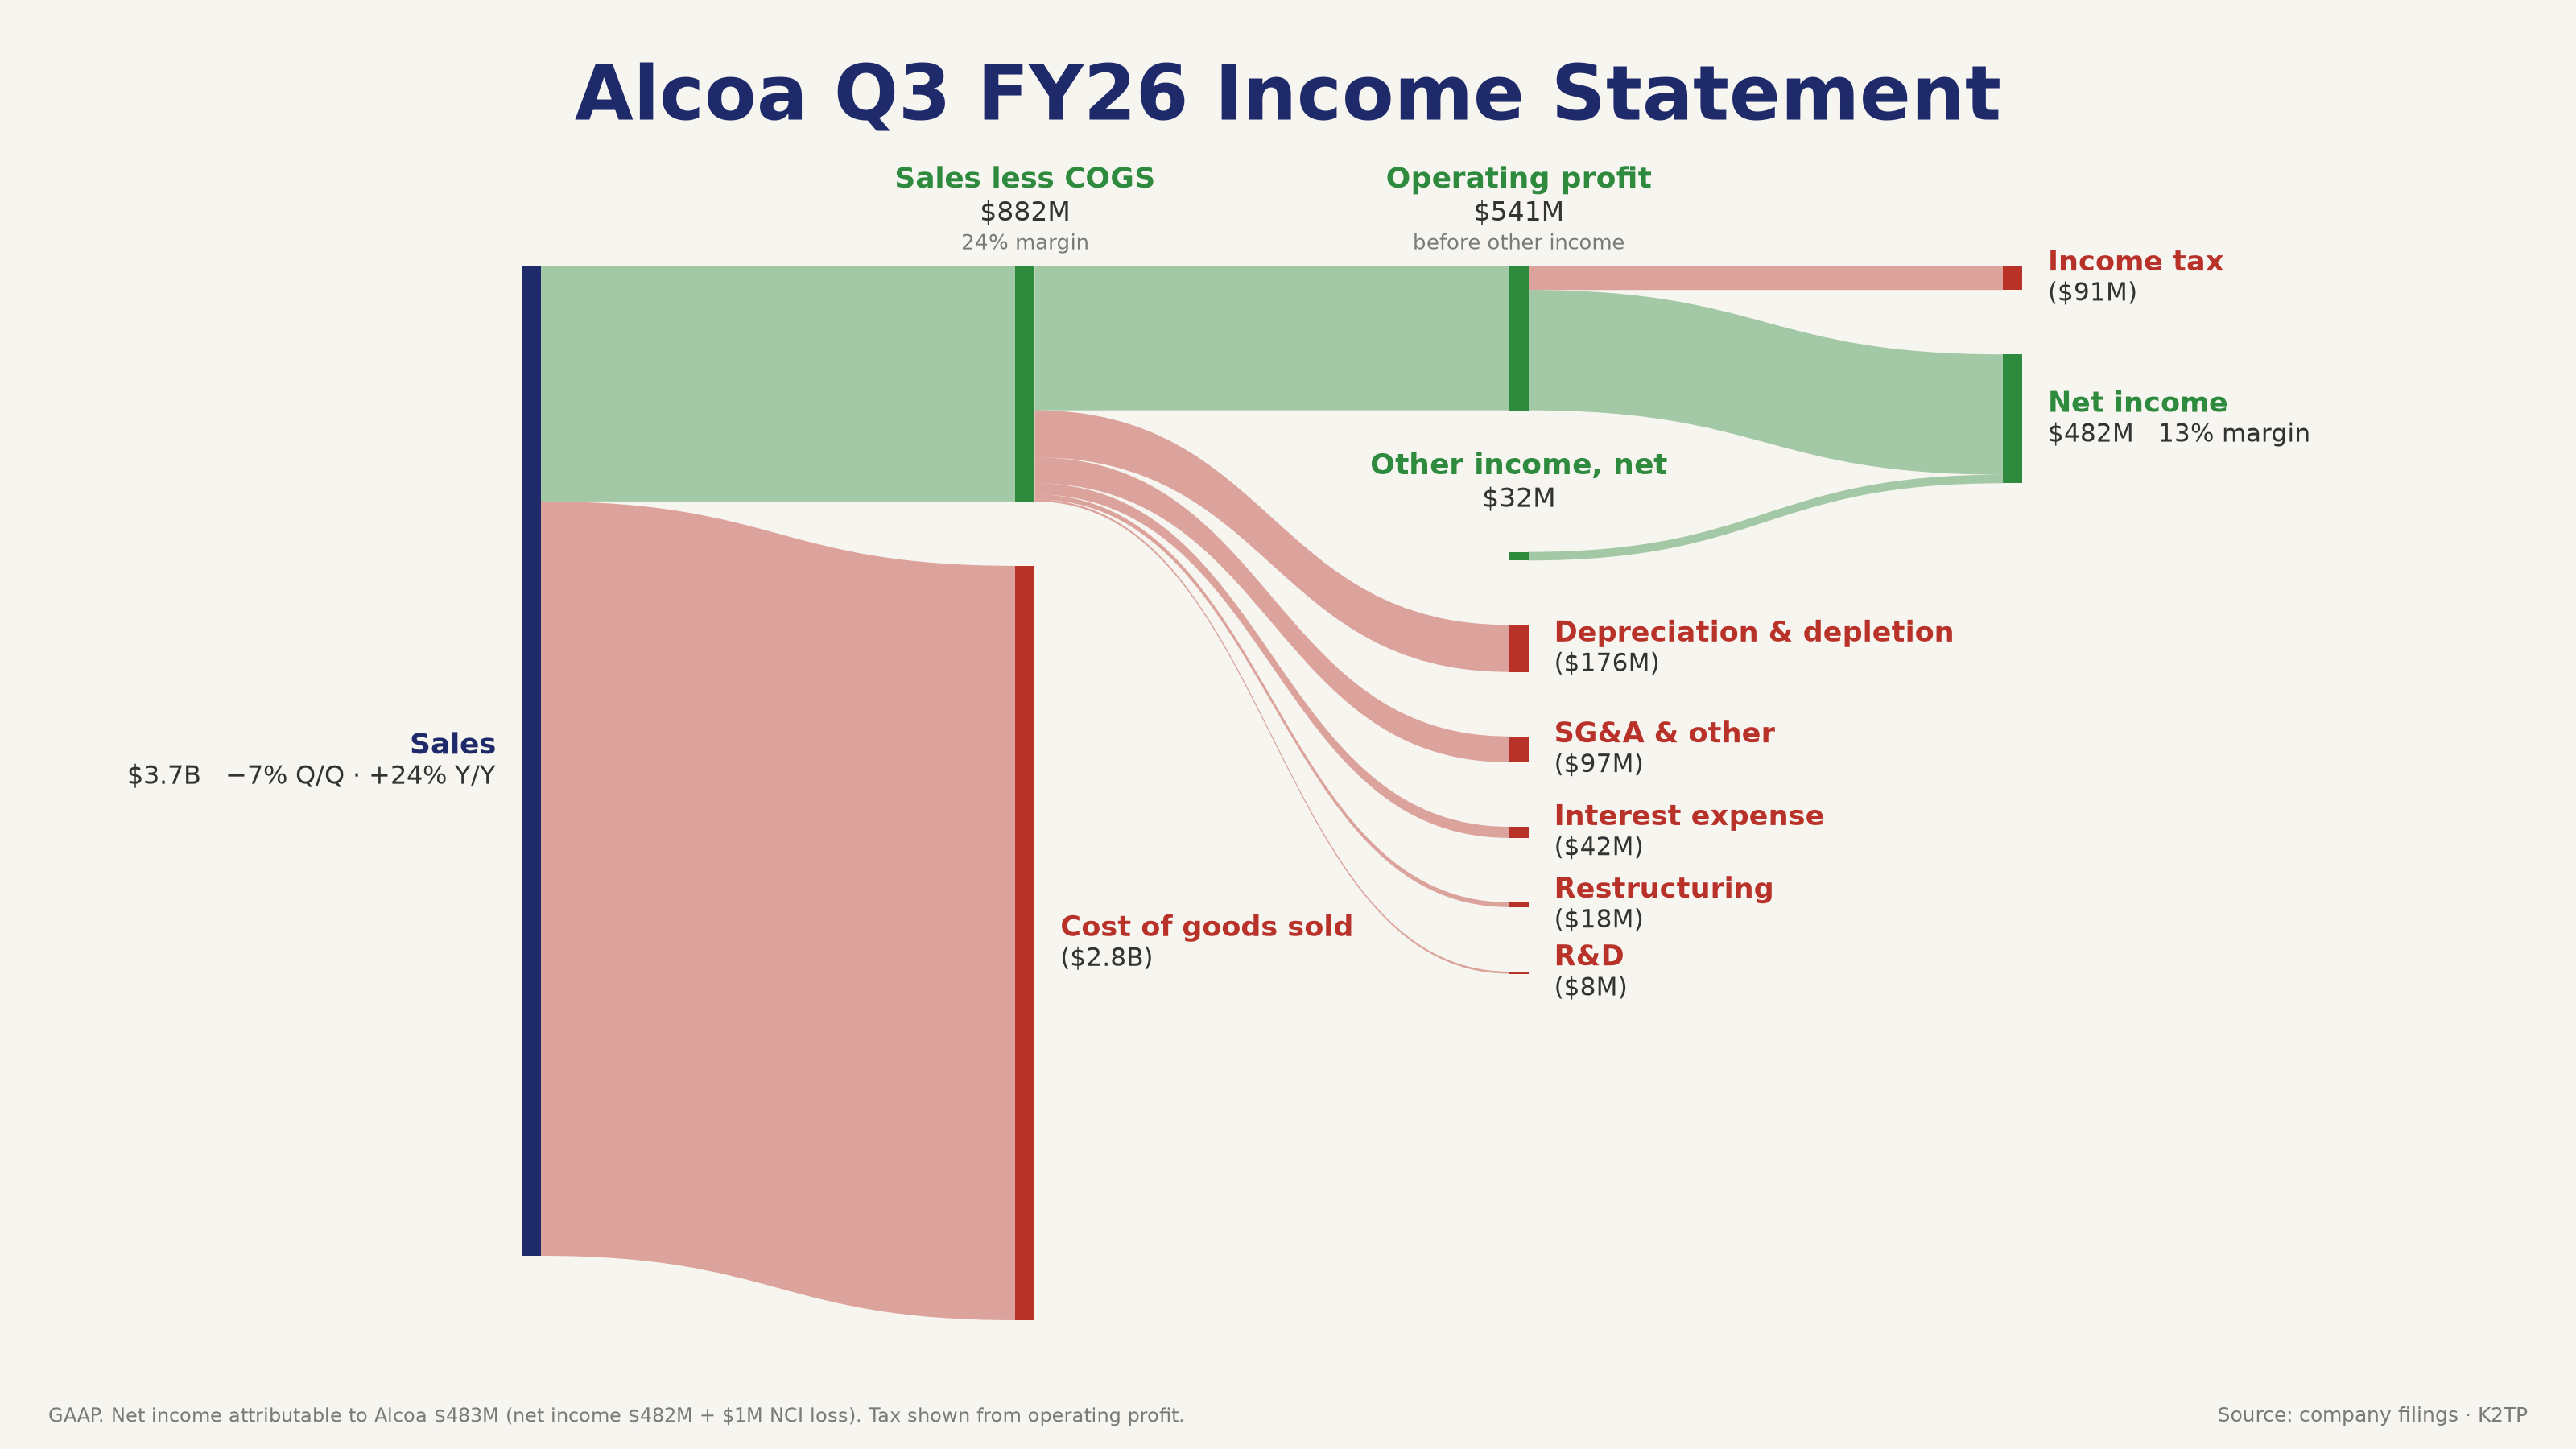
- Alcoa: adjusted EPS $1.82 (forecast ~$1.47) 🟢; revenue $3.70B (forecast ~$3.79B) 🔴. Shares about +2% after hours
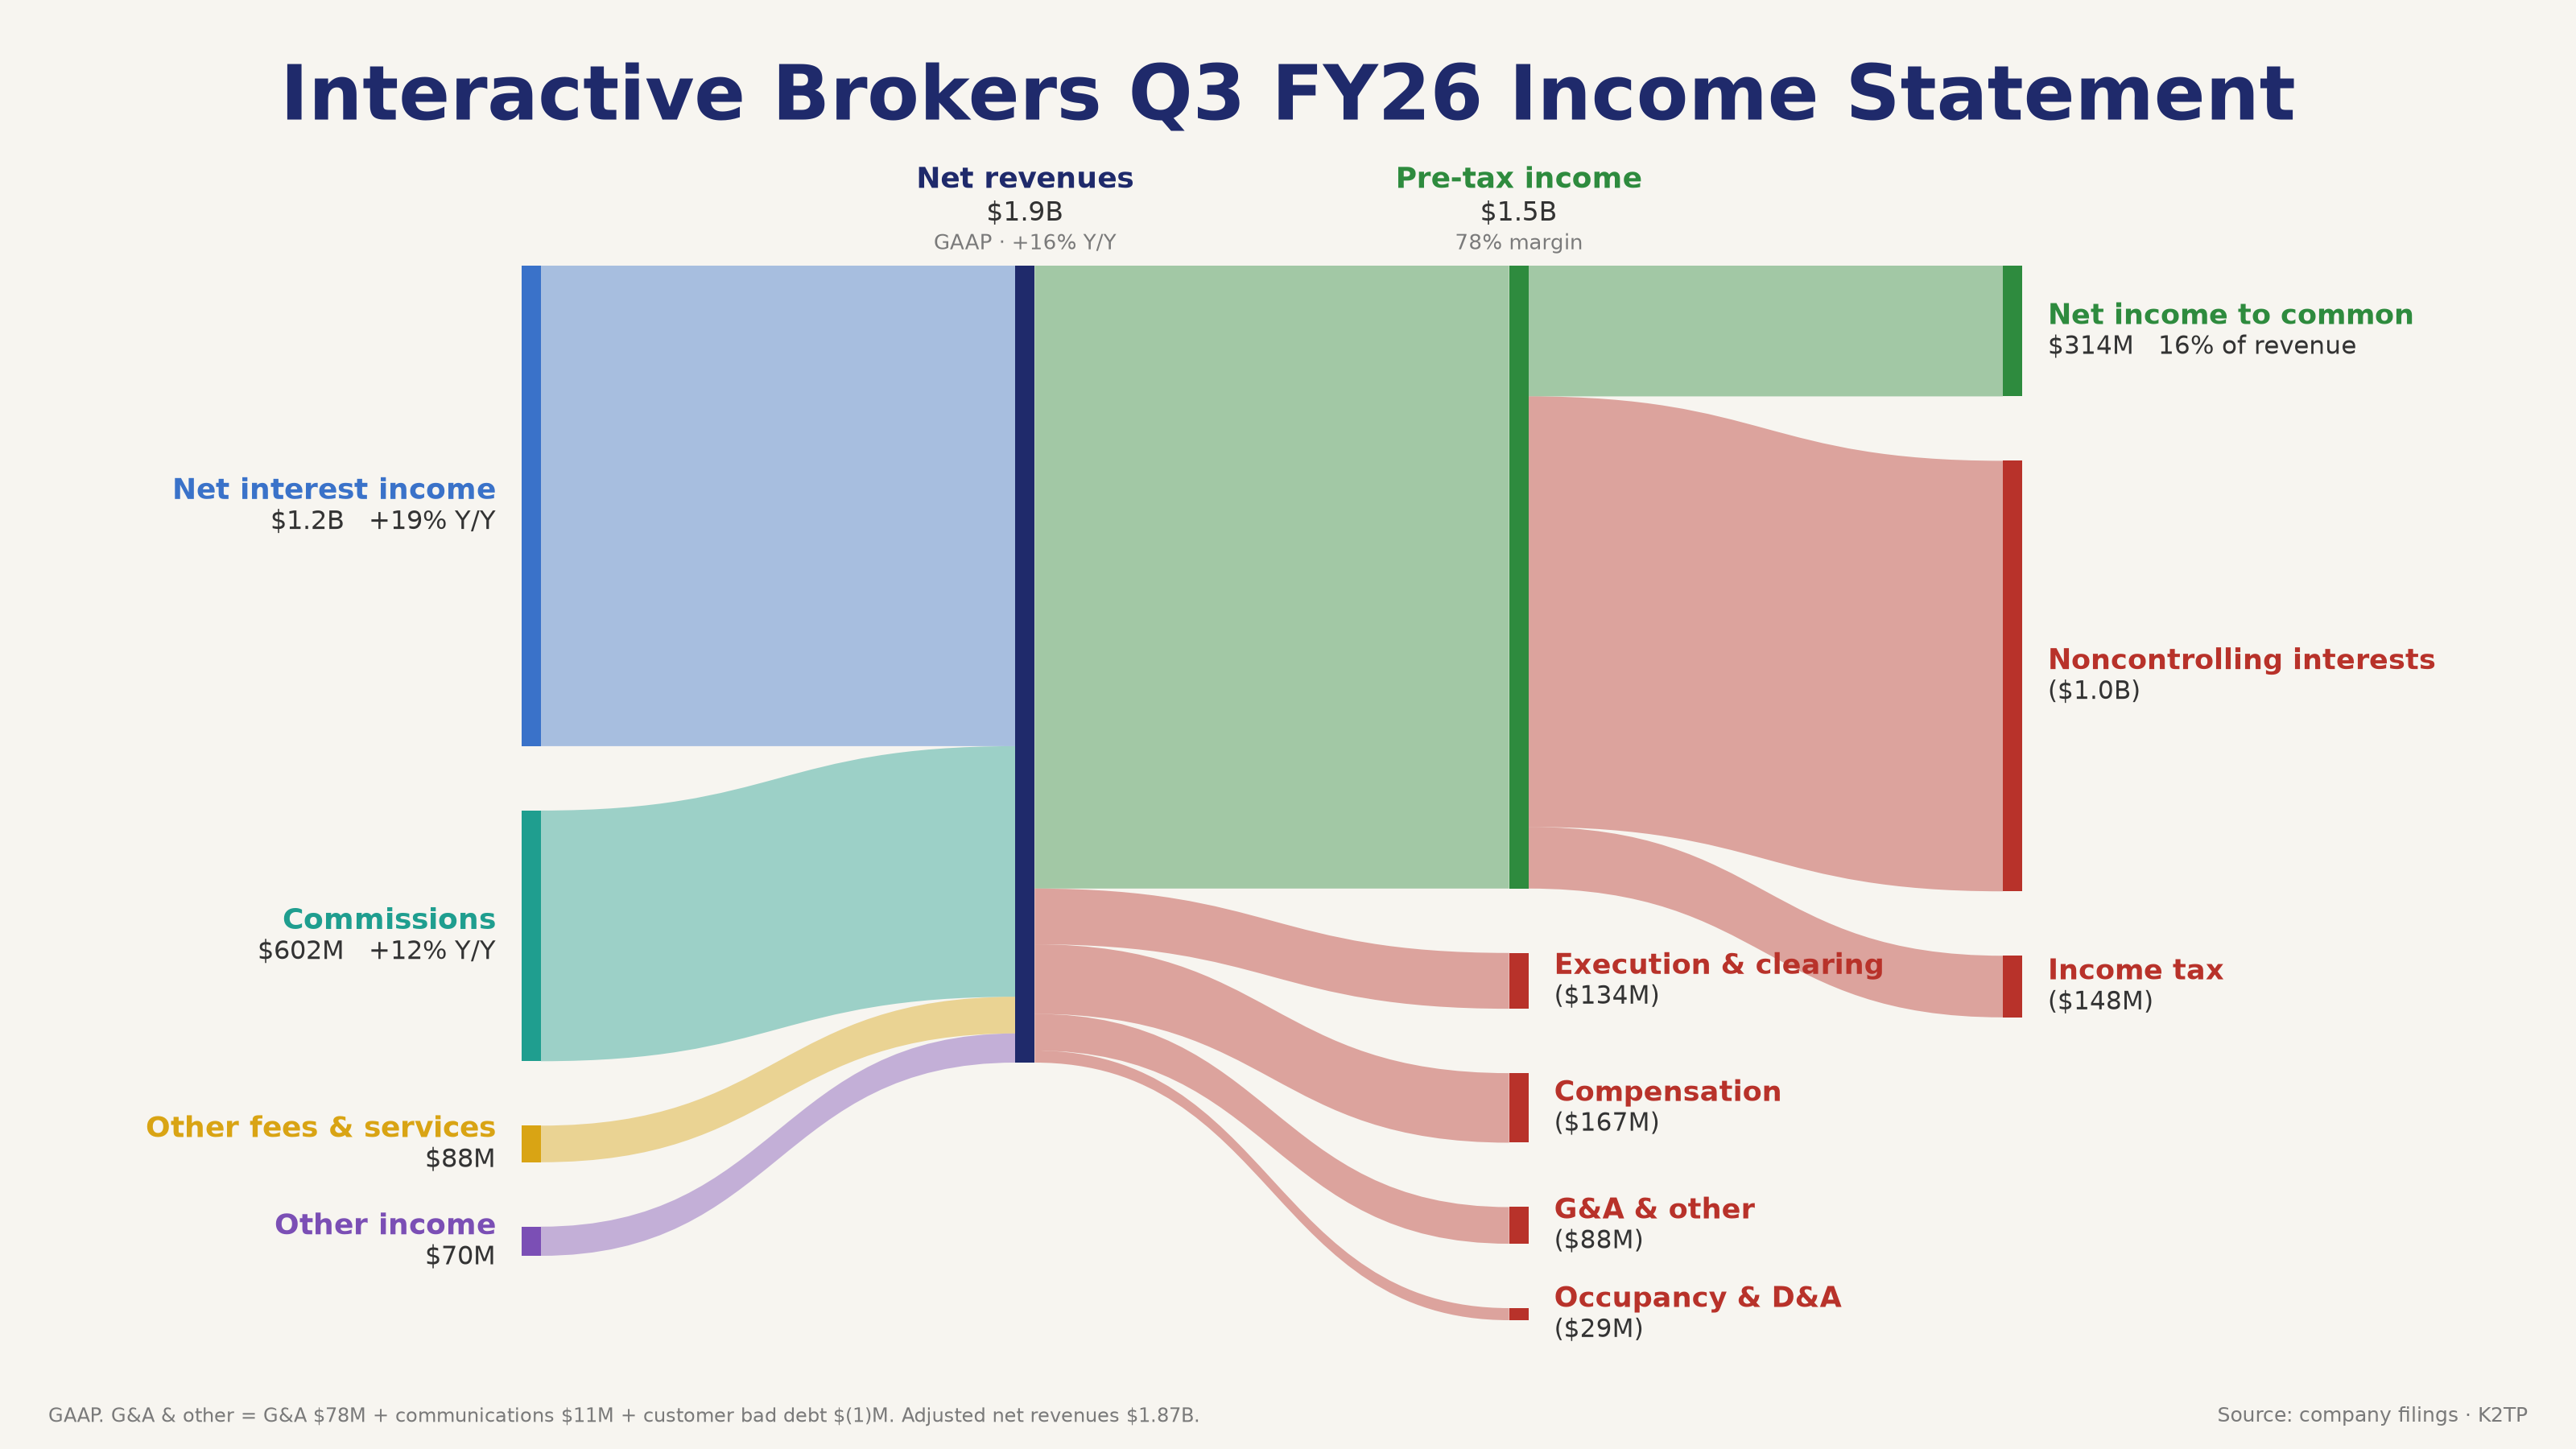
- Interactive Brokers: adjusted EPS $0.67 (forecast $0.68) 🔴; GAAP net revenue $1.91B (adjusted $1.87B). Shares about −1% after hours
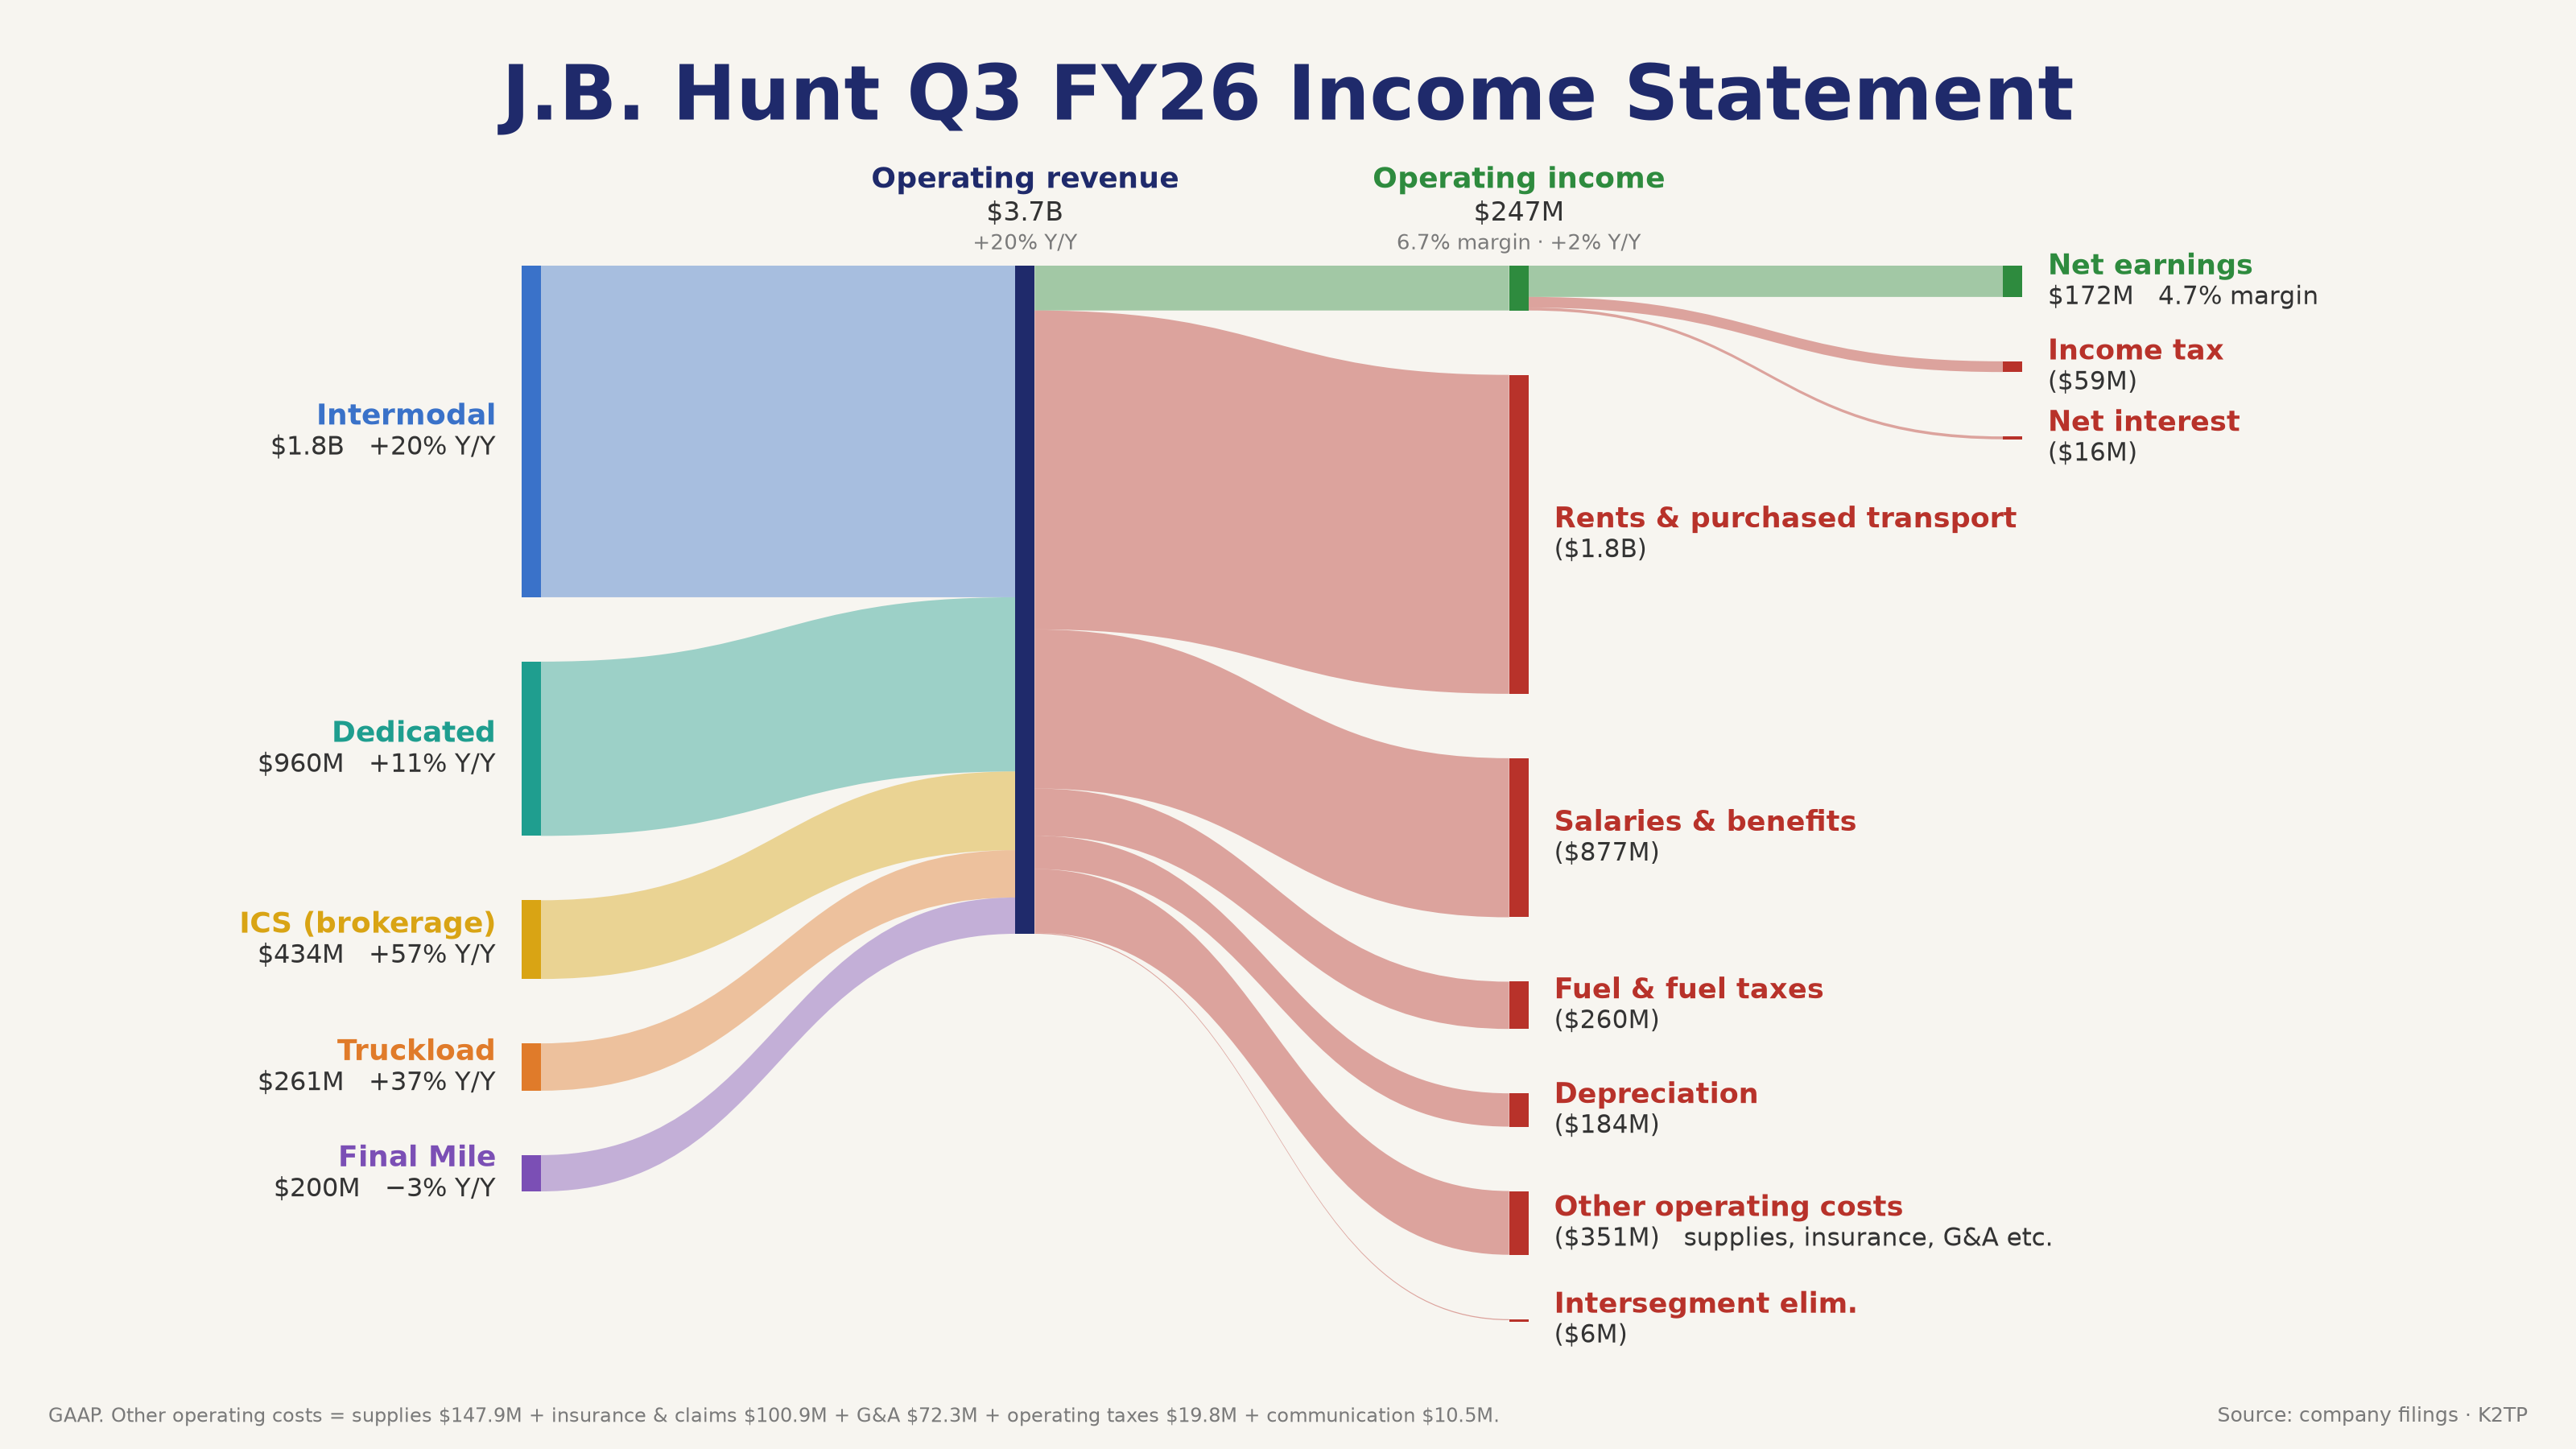
- J.B. Hunt: EPS $1.82 (forecast $1.89) 🔴; revenue $3.68B (forecast $3.57B) 🟢. Shares down more than 2% after hours
- Varonis (VRNS): ~$6.3B all-cash deal with Proofpoint; shares up more than 2% after hours
- In session: ManpowerGroup (MAN) −15.82% on a revenue miss and a CEO transition
→ No after-hours report big enough to move the index. MAN fits the cooling-labor narrative but is idiosyncratic.
MARKET: ROTATION LIFTS SPX, NDX STALLS
Indices (close):
- SPX 7,744.06 (+0.33%), day range 7,669.66–7,754.15
- NDX 29,935.59 (−0.05%)
- RUT 2,767.27 (+1.38%)
- DJIA 52,177.69 (+1.08%)
- RSP 215.00 (+1.37%)
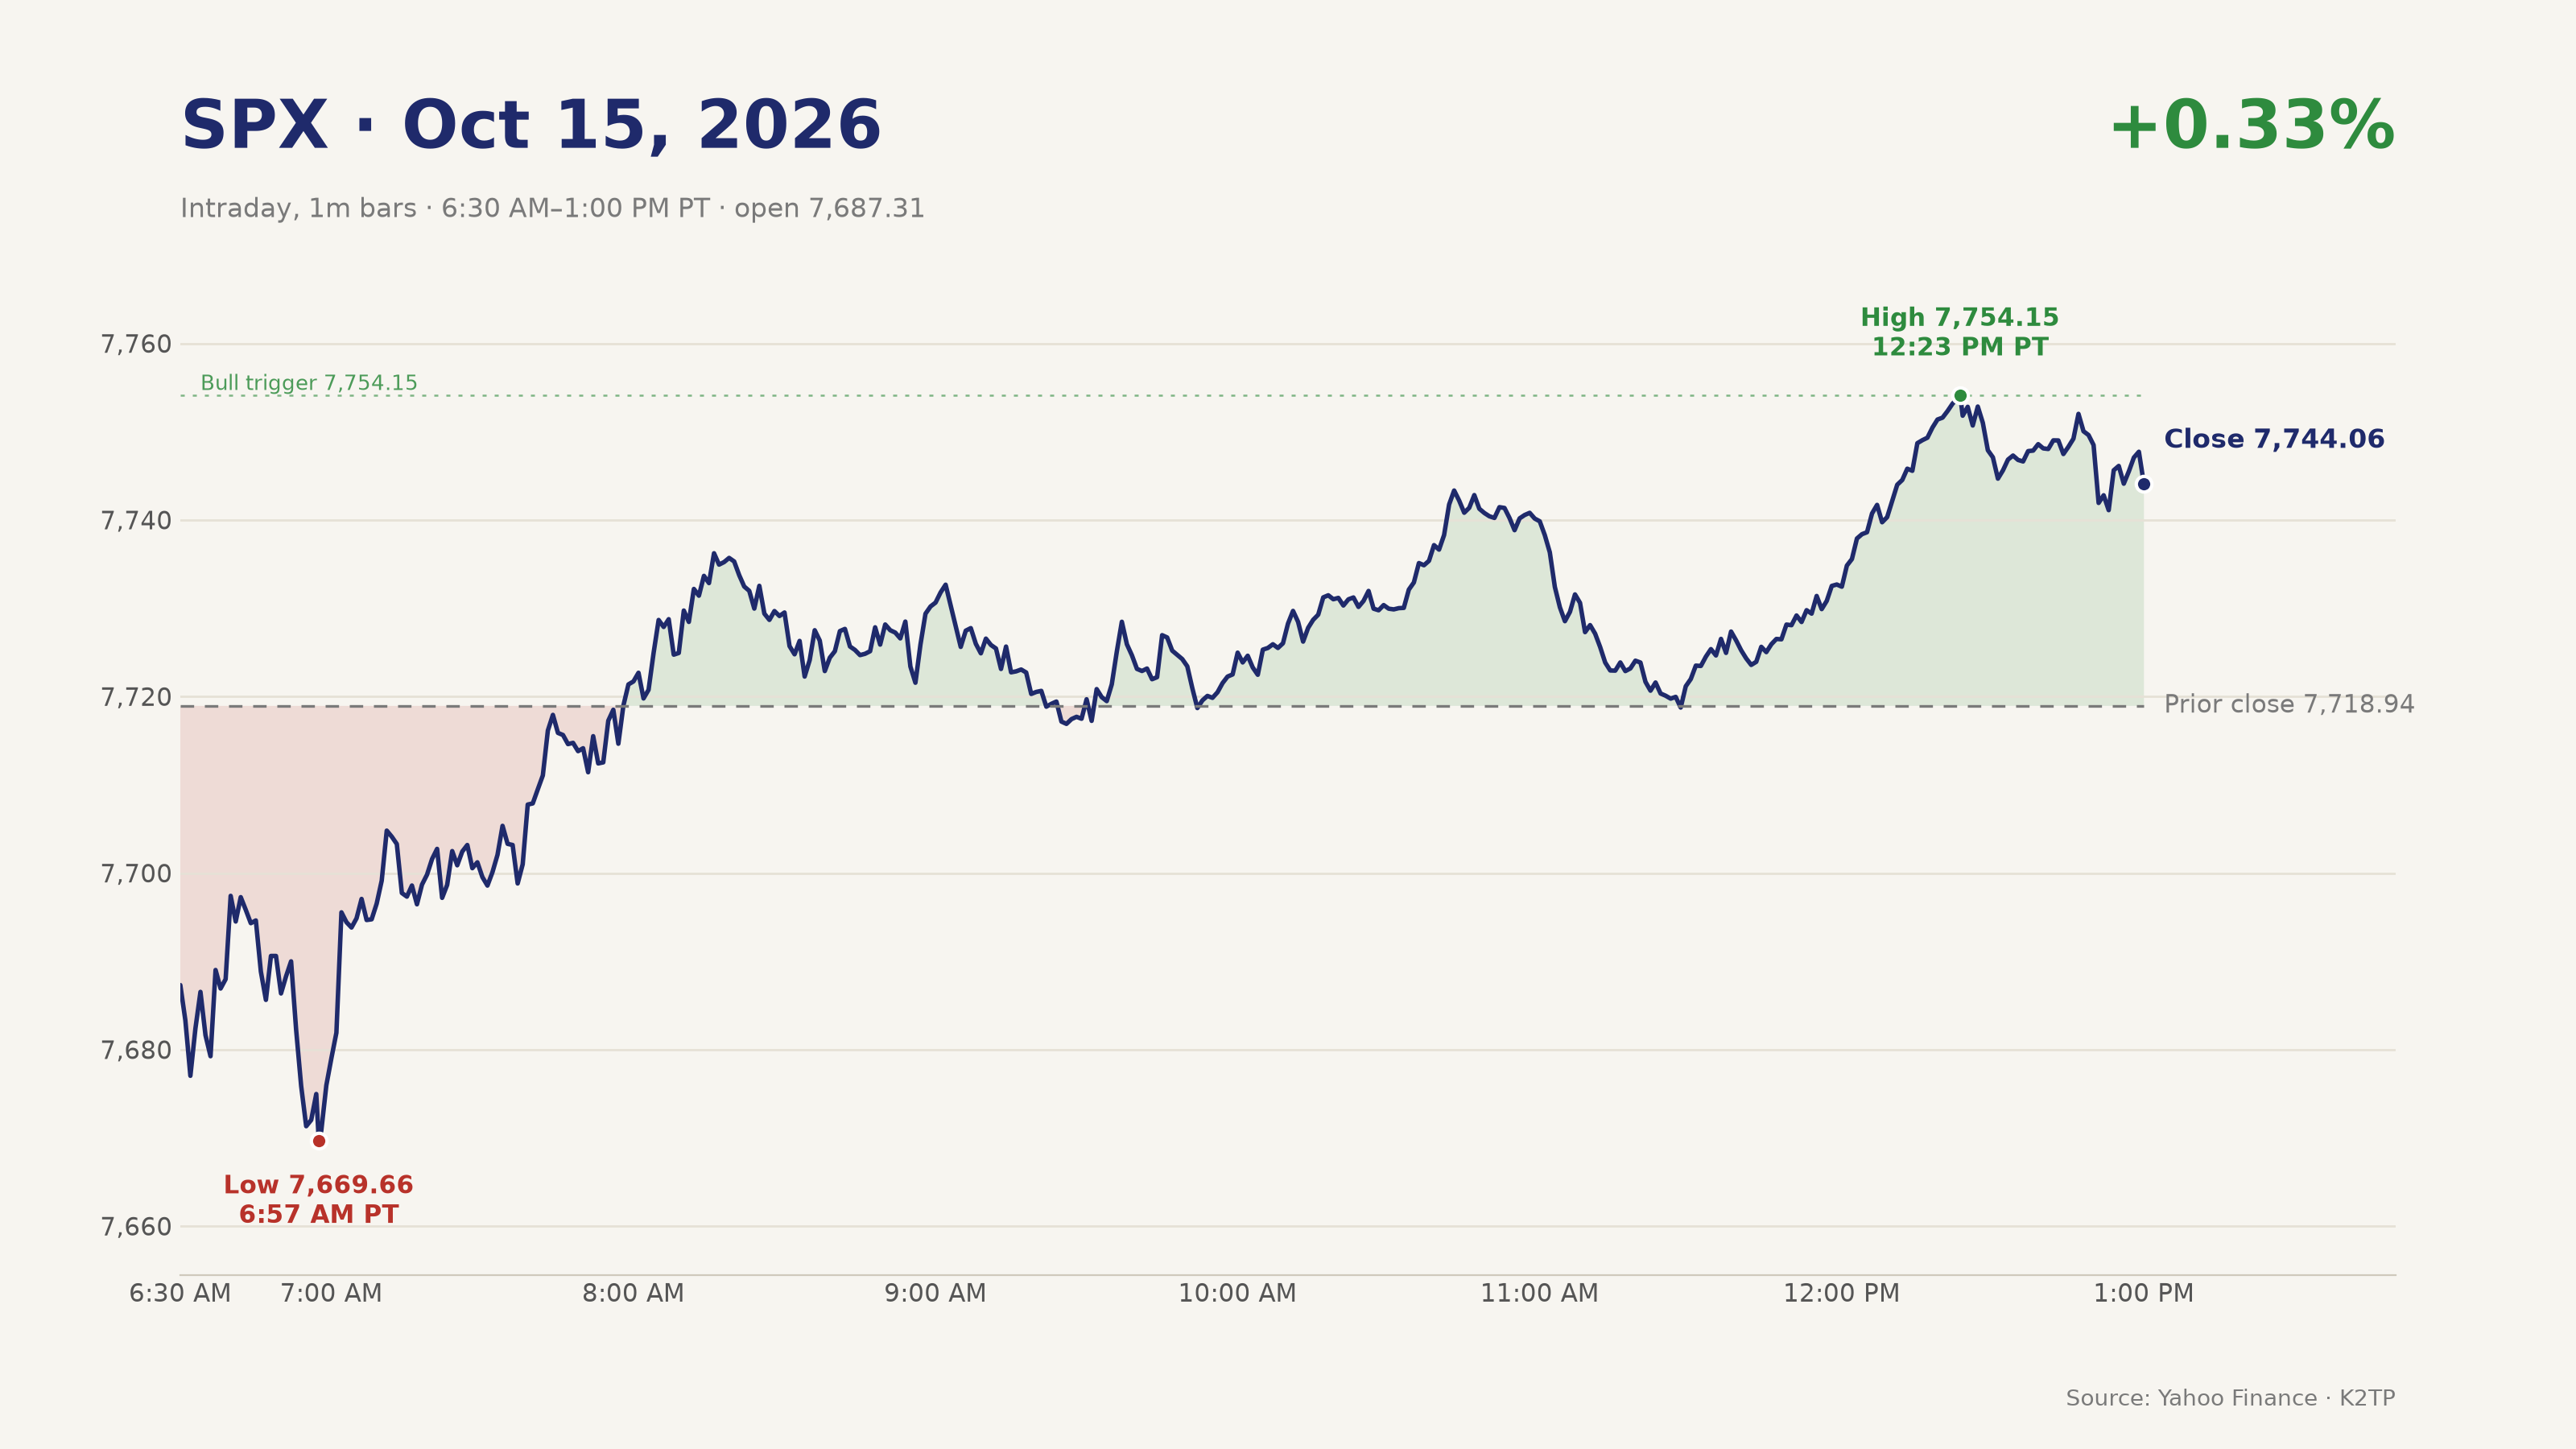
Session path: ES −0.31% pre-market. After the open both pre-market Bear triggers fired (SPX low 7,669.66, VIX high 18.01) and then reversed. By midday SPX was flat at 7,718.18 (−0.01%). At pre-close SPX was +0.28% (7,740.66), and it closed at 7,744.06 after a 7,754.15 high.
Sector Rotation:
- Gainers: XLV +1.86%, XLB +1.79%, XLY +1.71%, XLC +1.46%, XLF +1.38%, XLRE +1.21%
- Laggards: XLE −1.58%, XLK −0.65%, XLU −0.17%
- Mega-caps: MSFT +1.08%, GOOGL +0.45%, AMZN +0.27%; NVDA −1.84%, TSLA −1.29%, AAPL −0.28%
Market Internals:
- As of 9:44 AM PT: NYSE advancers led 2.34:1, Nasdaq 1.52:1
- S&P 500: 23 new highs, no new lows; Nasdaq: 51 new highs vs 351 new lows
- Official closing A/D totals: unavailable
Volatility:
- VIX 16.46 (−2.43%), range 16.34–18.01
- At pre-close: VIX3M 18.58, term structure in Contango
- Vol is easing but not calm, with Warsh tonight and OpEx tomorrow
Global:
- Asia sold off hard: Nikkei −4.90%, KOSPI about −7%, Shanghai −2.46%, Hang Seng −1.16%
- Europe mixed: STOXX 50 −0.36%, DAX +0.33% at the close; FTSE +0.99% (pre-market read)
- Early Friday: Nikkei futures pointed higher; Kospi and ASX opened firmer
SPX Key Levels:
- 7,754.15: today's high, also the Bull trigger
- 7,745.15: pre-close high
- 7,744.06: close
- 7,718.94: Wednesday's close, also the Bear trigger
- 7,693.31: Wednesday's low
- 7,669.66: today's low
- VIX: 16.34, 16.46 and 16.87
Option-seller angle:
- Bull case: SPX above 7,754.15 with VIX under 16.34 and SOX green would favor put-side premium. Keep size moderate until Warsh is out of the way.
- Bear case: SPX under 7,718.94 with VIX above 16.87 and 10Y above 5.19% would put RISK-OFF back on. Widen strikes or cut short-put size.
- Avoid tight Iron Condors on NDX and semis while SOX has fallen seven straight days.
- Event risk is stacked: Warsh at 8:30 PM PT tonight, then import prices and industrial production, then monthly OpEx. Avoid opening 0DTE positions before the data.
BOTTOM LINE
- Hot PPI did not break the market. Bonds rallied 10 bp, hike odds eased and SPX snapped its three-day losing streak.
- The bid came from rotation, not from AI. Dow, small caps and equal-weight led while NDX was flat and SOX fell a seventh day.
- The regime moved from RISK-OFF to TRANSITION, tilting constructive. It cannot become RISK-ON while semis lag.
What to watch (PT):
- 8:30 PM tonight: Fed Chair Warsh fireside with IMF's Georgieva
- Friday pre-open: regional bank and insurance earnings (TFC, TRV, MTB, CFG, RF)
- Friday data calendar
| Release | Time PT | Forecast | Prior |
|---|---|---|---|
| Import prices m/m | 5:30 AM | +0.9% | +0.7% |
| Export prices m/m | 5:30 AM | +1.0% | +0.6% |
| Industrial production m/m | 6:15 AM | +0.4% | 0.0% |
| Capacity utilization | 6:15 AM | 76.5% | 76.3% |
- Friday: monthly OpEx (standard October monthly, not triple witching)
- Oct 27–28: FOMC
Expected (Bull): SPX above 7,754.15 with VIX under 16.34 and SOX green. Expected (Bear): SPX under 7,718.94 with VIX above 16.87 and 10Y above 5.19%.
Sources: 4 K2TP briefs for Oct 15, 2026 (Pre-Market, Midday, Pre-Close, Evening Recap); earnings Sankeys from official Q3 2026 company releases. Analysis: K2TP Framework.