Market 10/14: Hot CPI, AI Infrastructure Unwinds, SOX Down a 6th Straight Day
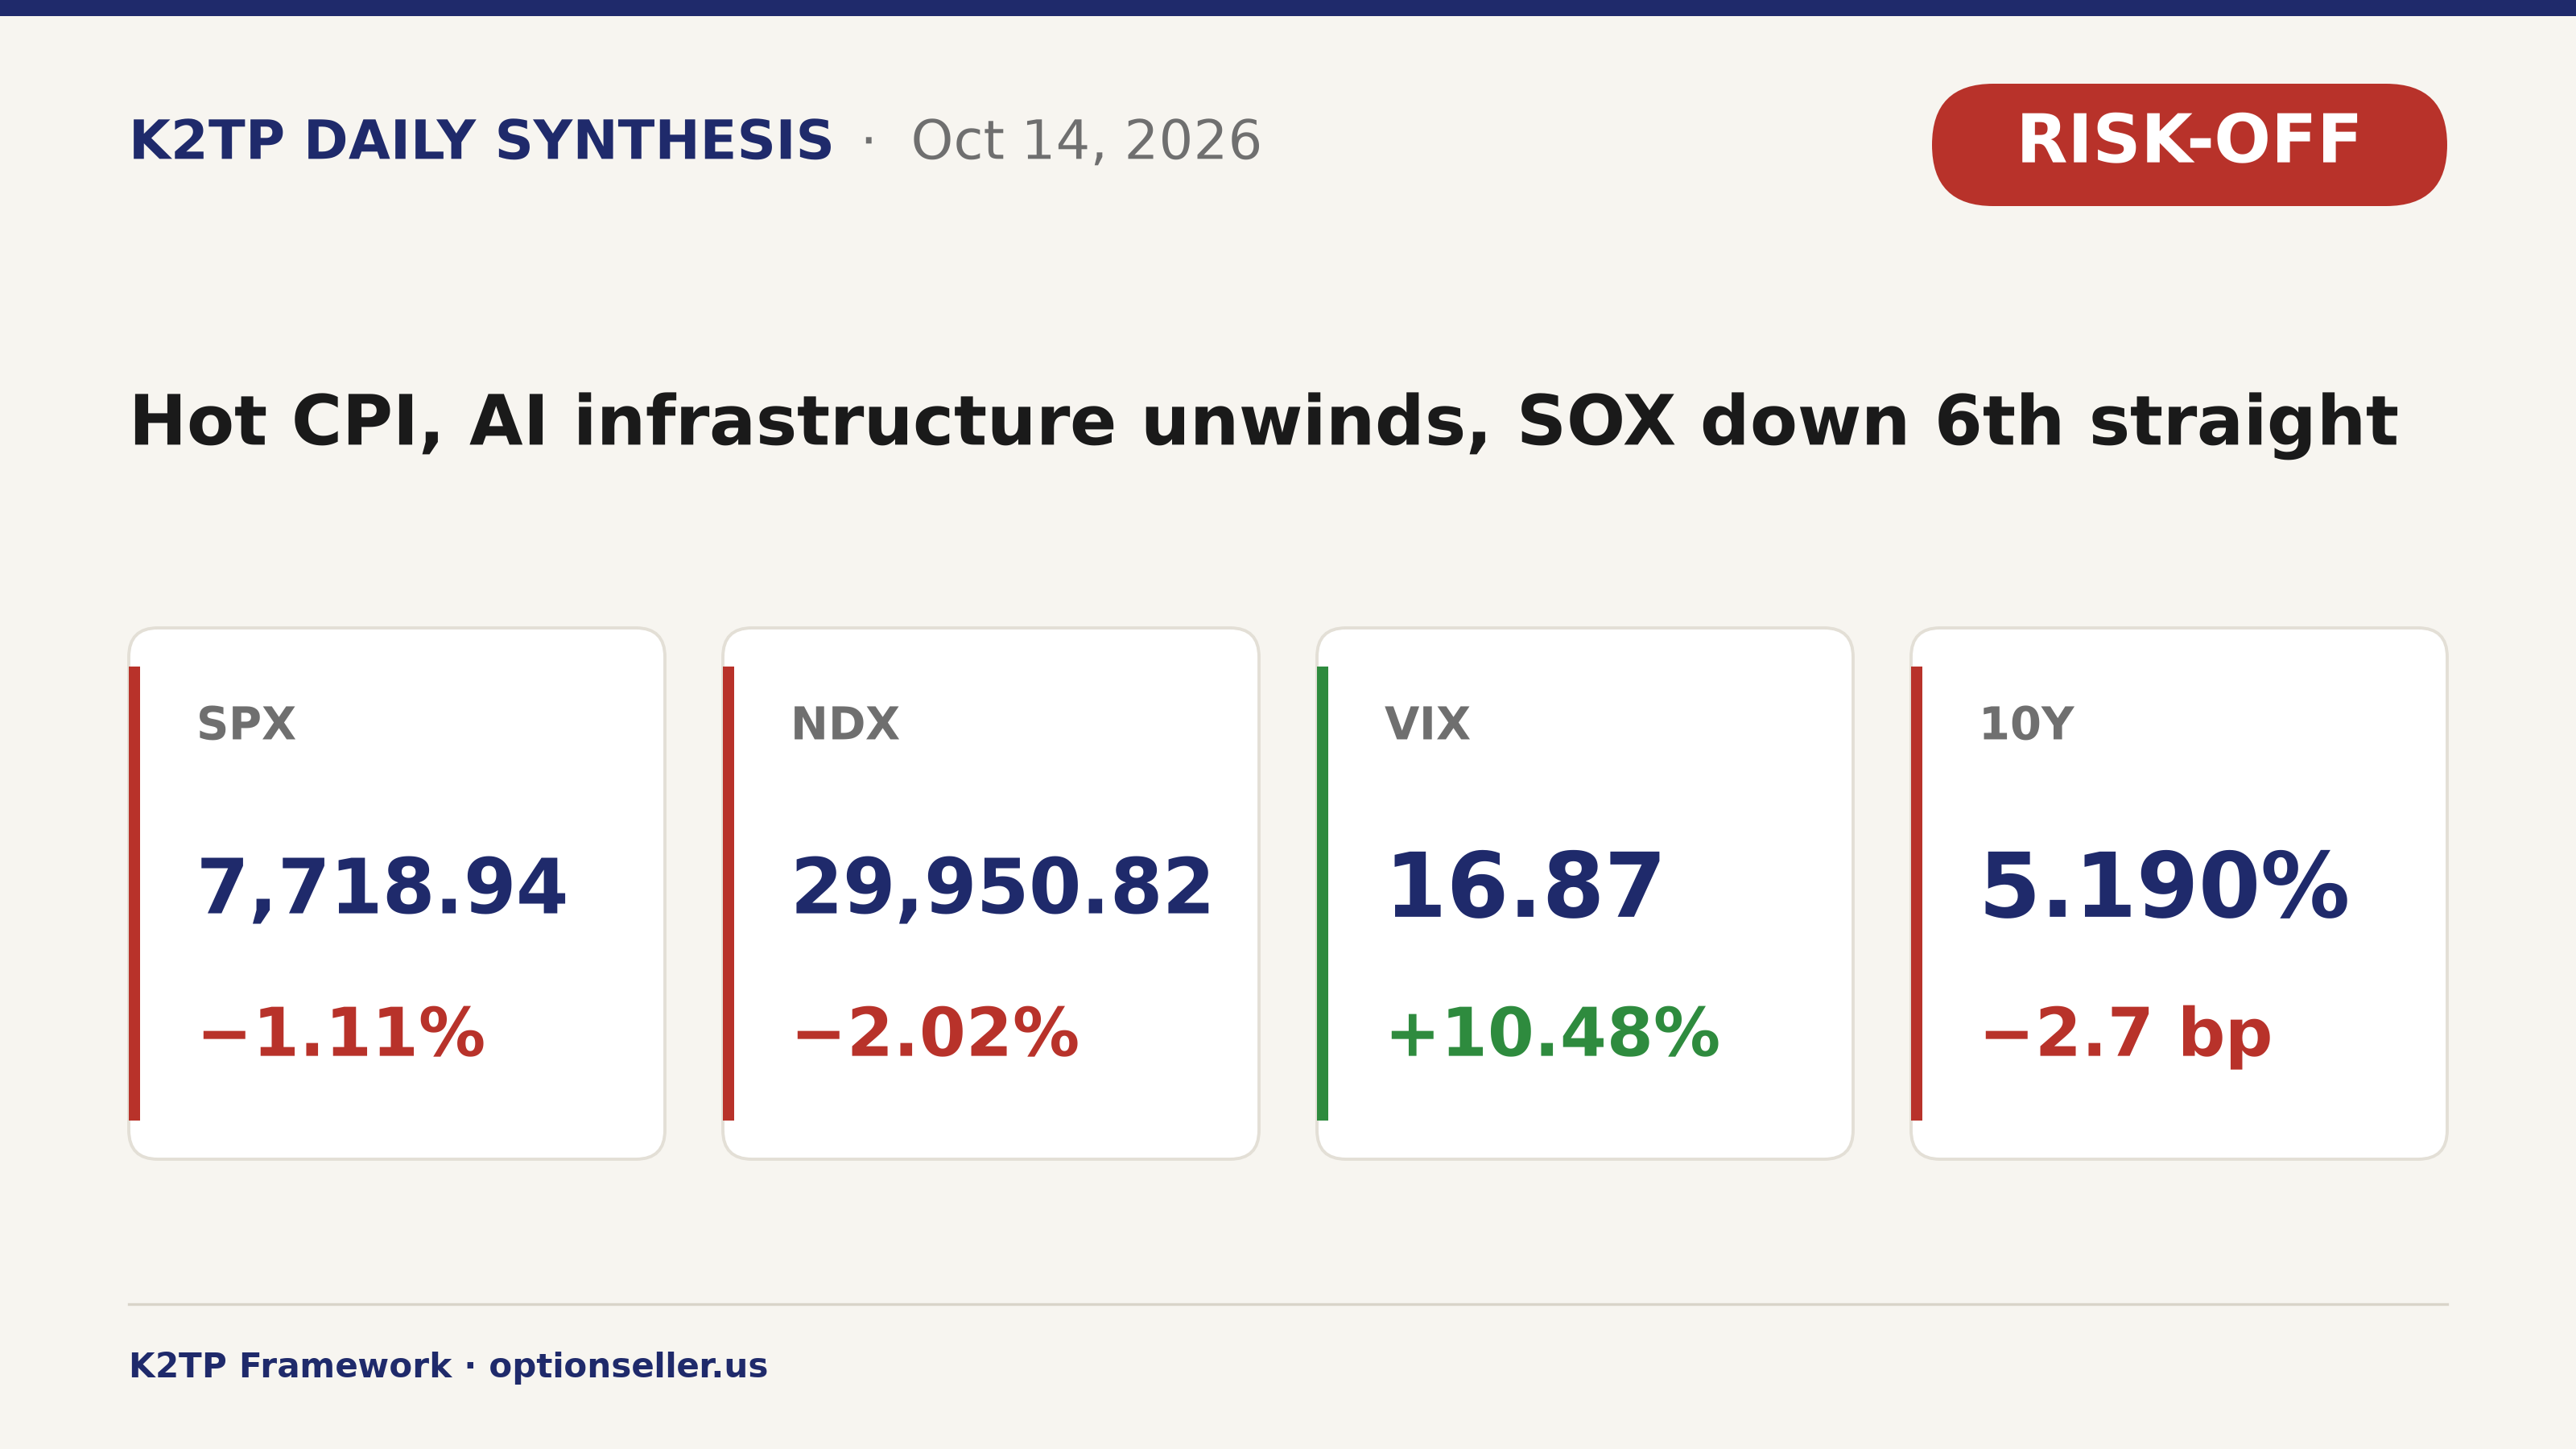
SPX −1.11%, NDX −2.02%, VIX +10.48%. Bonds reversed the spike; growth equities did not follow.
KEY HEADLINES
- September CPI hot: core +0.3% m/m vs +0.2% expected
- October hike odds: 22% → 53.7% (midday) → ~35% (evening)
- 10Y spiked to 5.325%, then reversed to close at 5.190%
- AI infrastructure unwind: ORCL −8.83%, DELL −11.27%, CoreWeave −15%
- SOX −4.30%, a sixth straight decline
- Bank of America: EPS miss on a $1.2B AML settlement
- Morgan Stanley: beat, but the stock fell
- ASML: €11.7B in sales, yet the ADR fell with semis
- Beige Book: slight growth, broadening price pressure
- Market: defensive rotation (XLV, XLP, XLE); Dow nearly flat
SEPTEMBER CPI HOTTER THAN EXPECTED
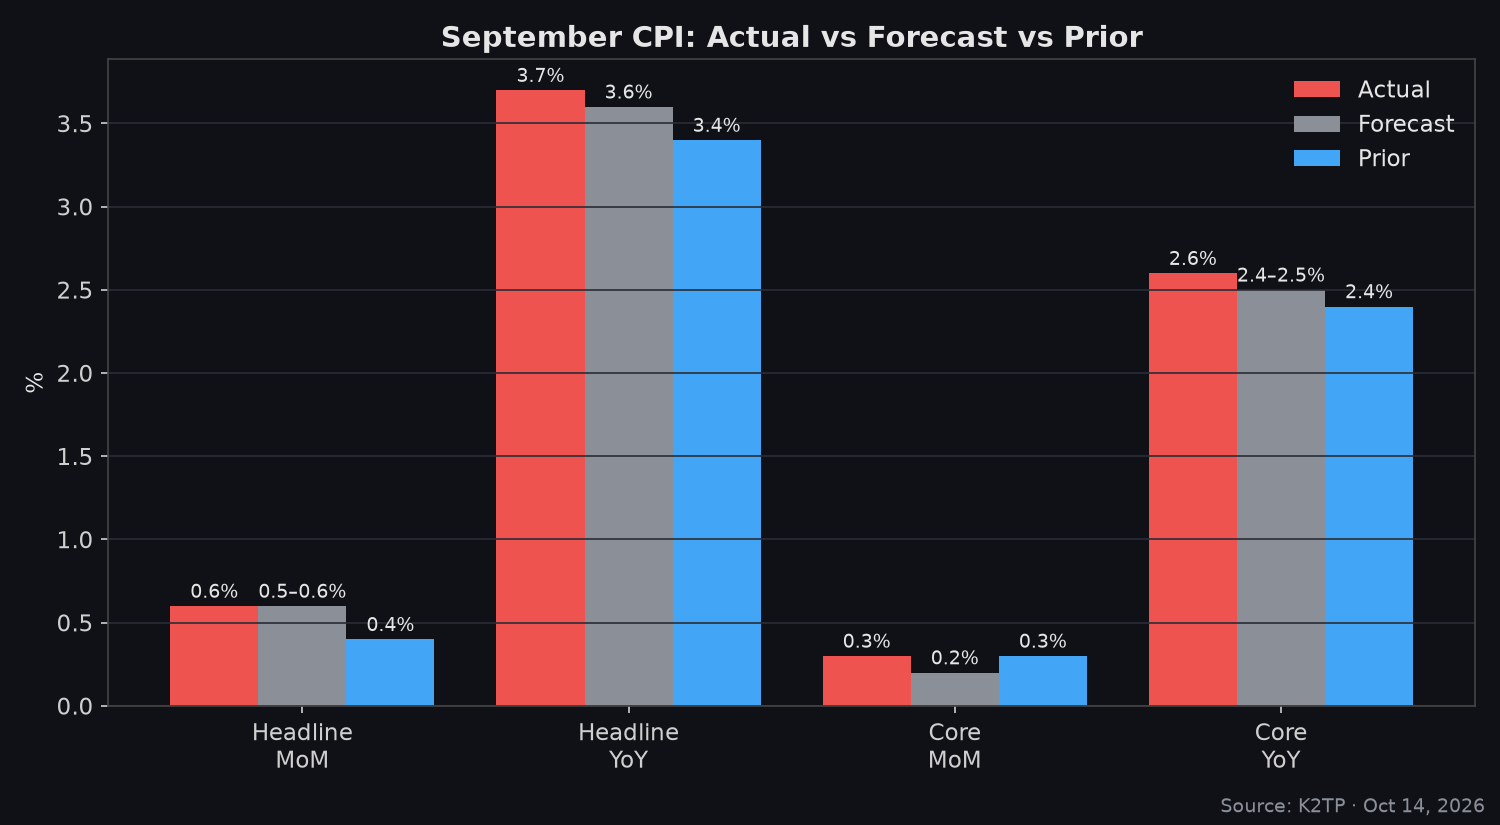
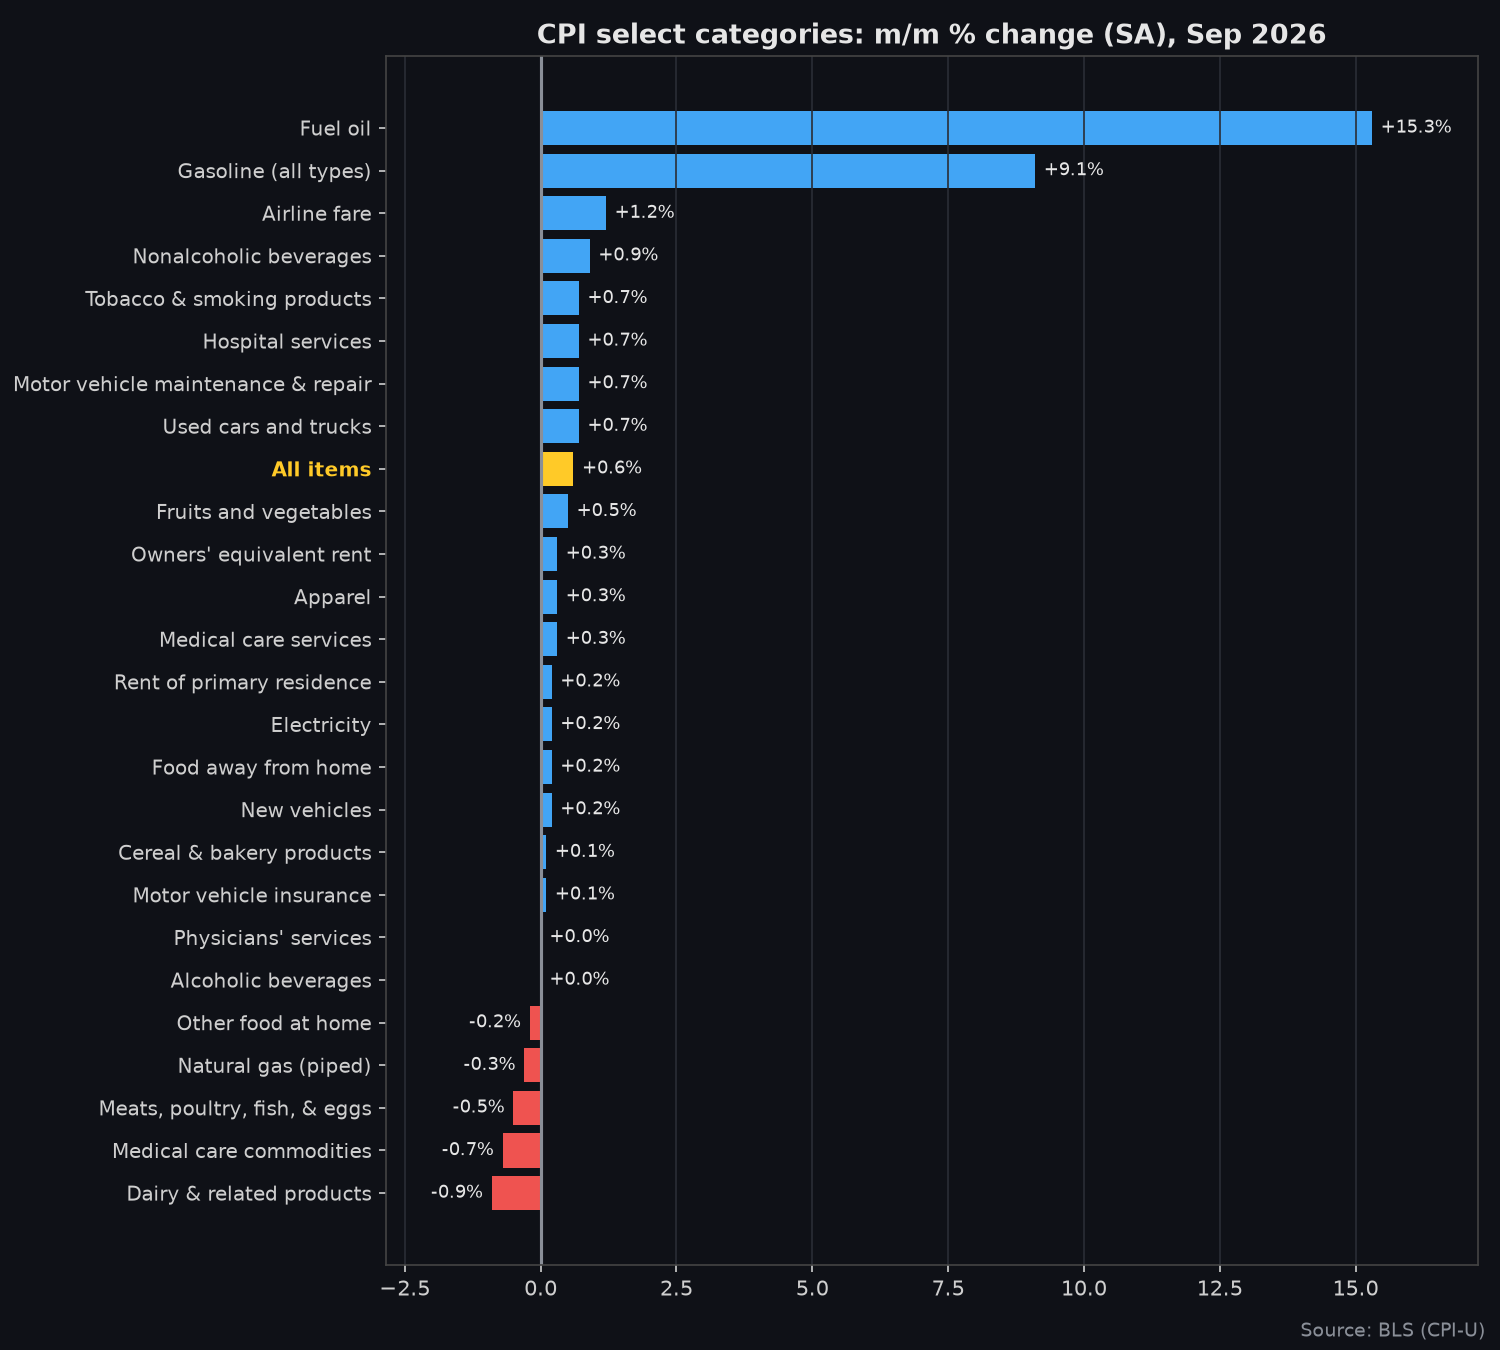
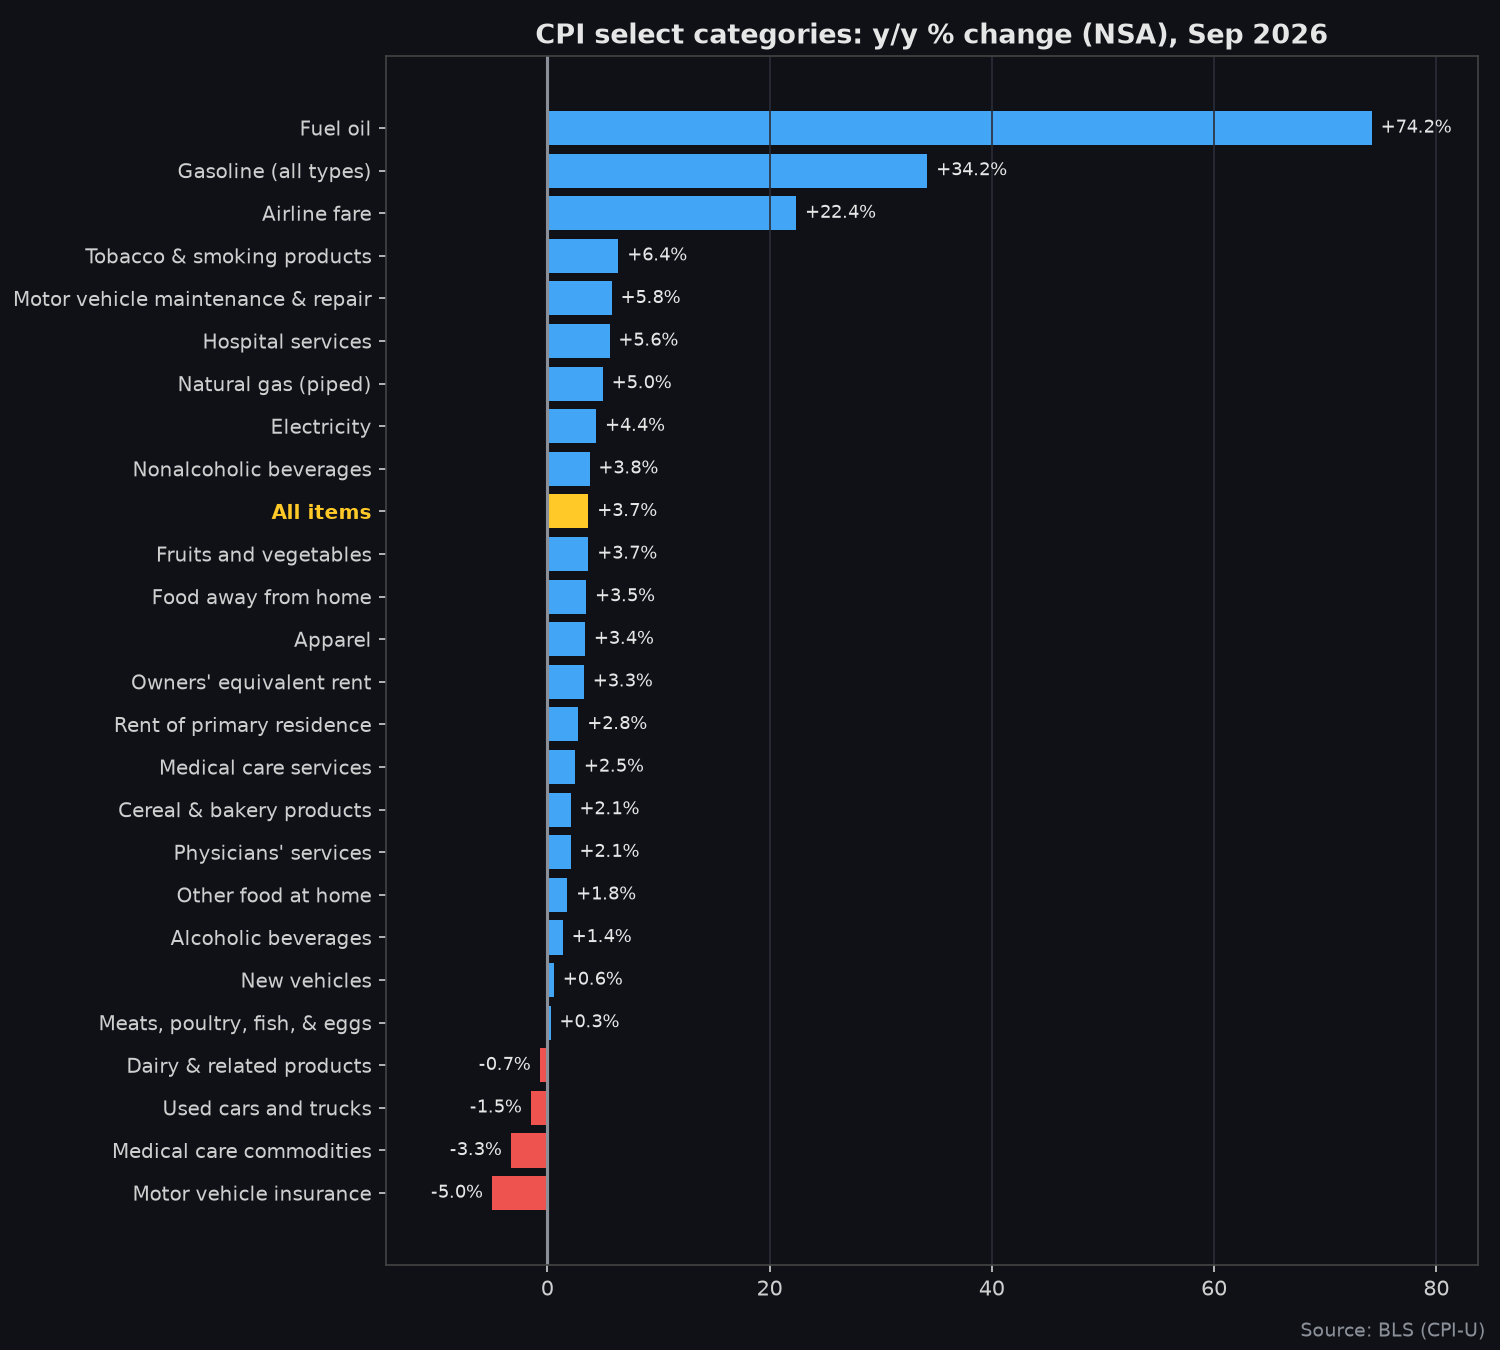
- Headline: +0.6% m/m (forecast +0.5% to +0.6%, prior +0.4%) 🔴
- Headline: 3.7% y/y (forecast 3.6%, prior 3.4%) 🔴
- Core: +0.3% m/m (forecast +0.2%, prior +0.3%) 🔴
- Core: 2.6% y/y (forecast 2.4% to 2.5%, prior 2.4%) 🔴
- Biggest monthly gain in five months; energy drove much of the headline jump
- Released at 5:30 AM PT. ES −0.34% and NQ −0.69% just before the open
→ This is the second straight 0.3% core month, and it reopens the hawkish path Collins described on Tuesday.
FED: OCTOBER HIKE ODDS SWING HARD
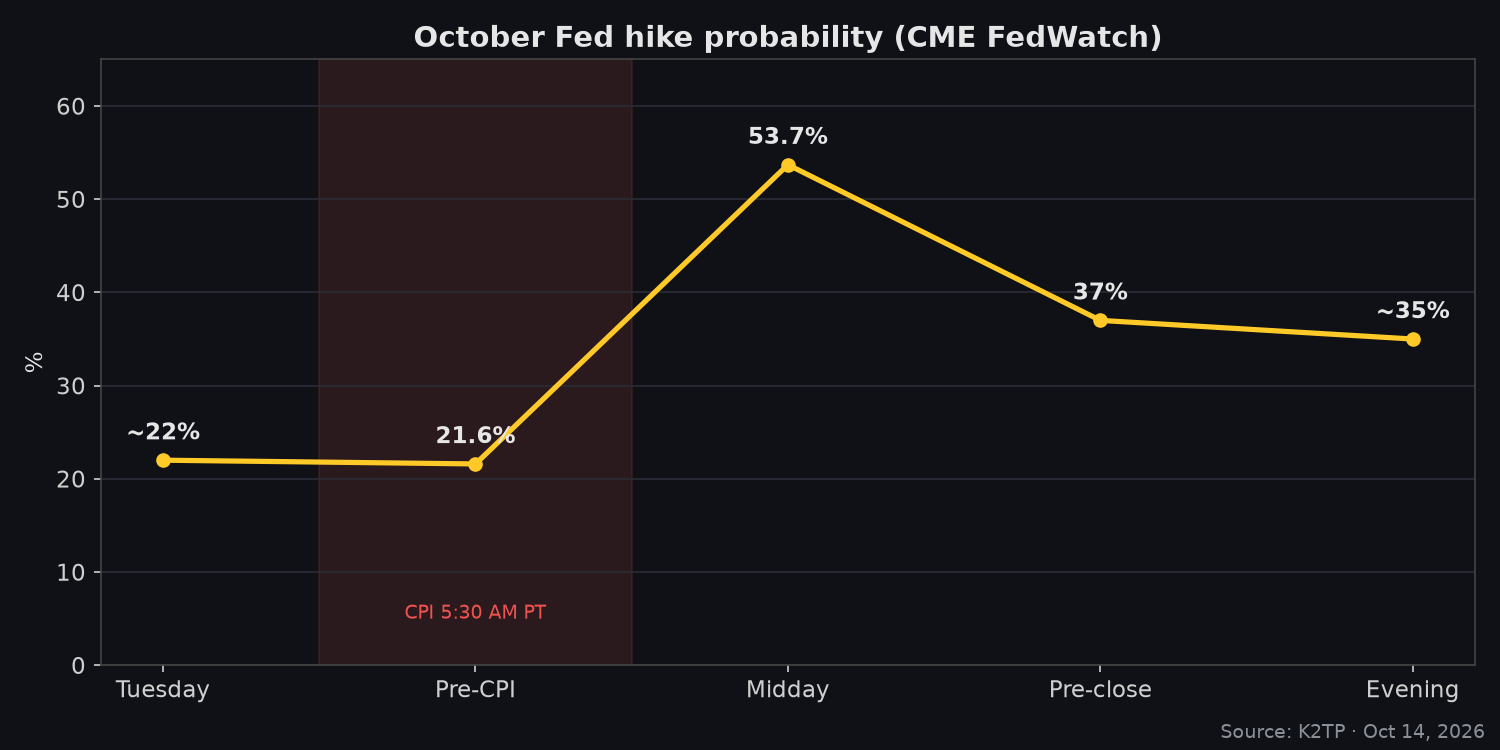
- CME FedWatch, October hike: ~22% (Tue) → 21.6% (just before CPI) → 53.7% (midday) → 37% (pre-close) → ~35% (evening)
- Odds of at least one hike by year-end: >95% at midday, >90% in the evening
- At midday, odds of +50 bp by December were about 40%
- Bowman: the Fed has time to wait after its September hike
- FOMC meets Oct 27–28
→ Hike odds have come off the peak but are still well above yesterday's. Thursday's PPI sets the next leg.
TREASURIES: SPIKE, THEN A FULL REVERSAL
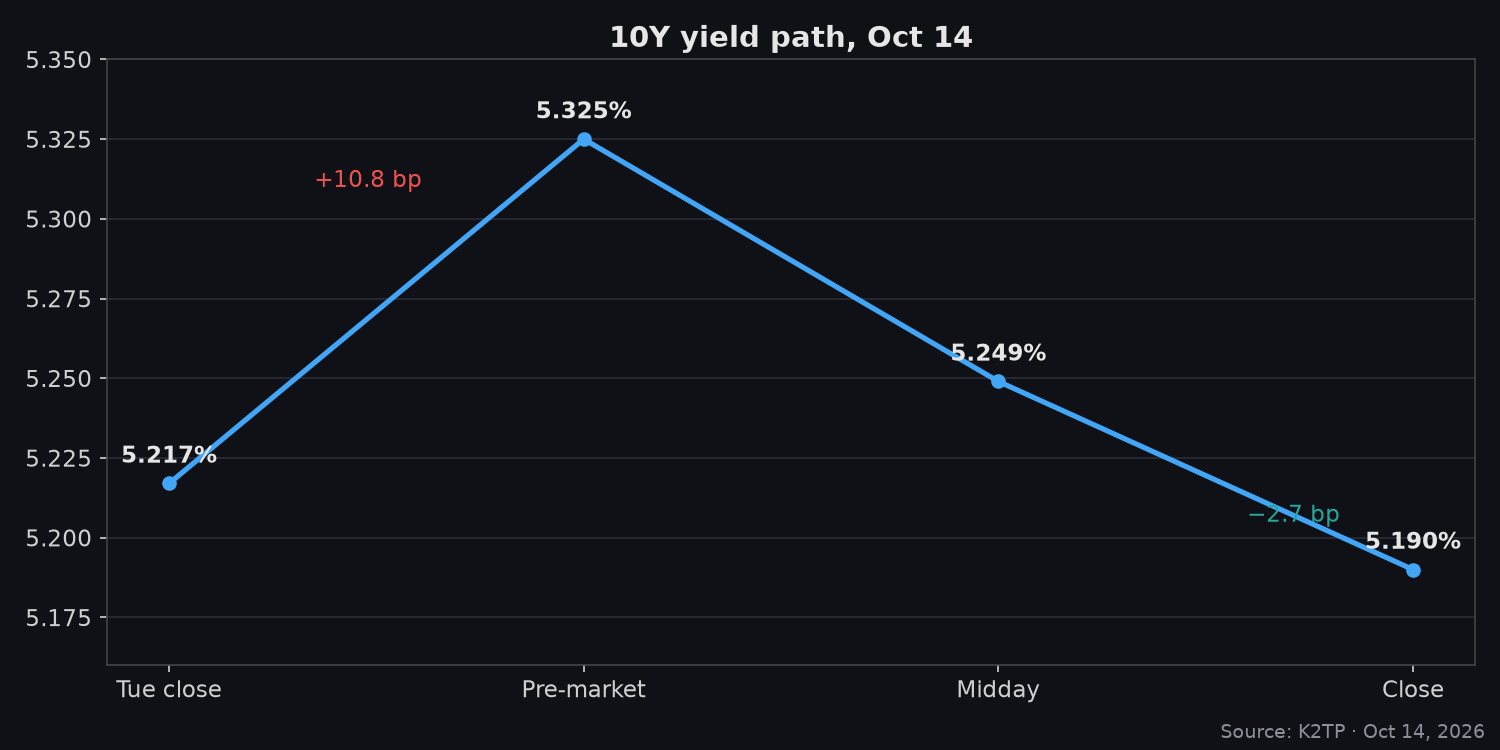
- 10Y: 5.217% → 5.325% pre-market (+10.8 bp) → 5.249% at midday → 5.190% close (−2.7 bp) 🟢
- 5Y: 5.147% (+14.0 bp) pre-market → 4.992% (−1.5 bp)
- 30Y: 5.620% → 5.525% (−3.8 bp)
- Curve: bear flattener in the morning (5s30s 47.3 bp) → bull flattening by the close (5s30s 53.3 bp vs 55.6 bp Tuesday)
- DXY 102.53 (+0.34%), gold $4,125.20, WTI $95.10, Brent $106.00
→ Bonds erased the CPI spike, but growth equities did not follow. The selling is about AI positioning, not the yield level.
AI INFRASTRUCTURE UNWIND, SOX DOWN SIX STRAIGHT DAYS
- SOX −4.30% to 11,684.38, a sixth straight decline 🔴
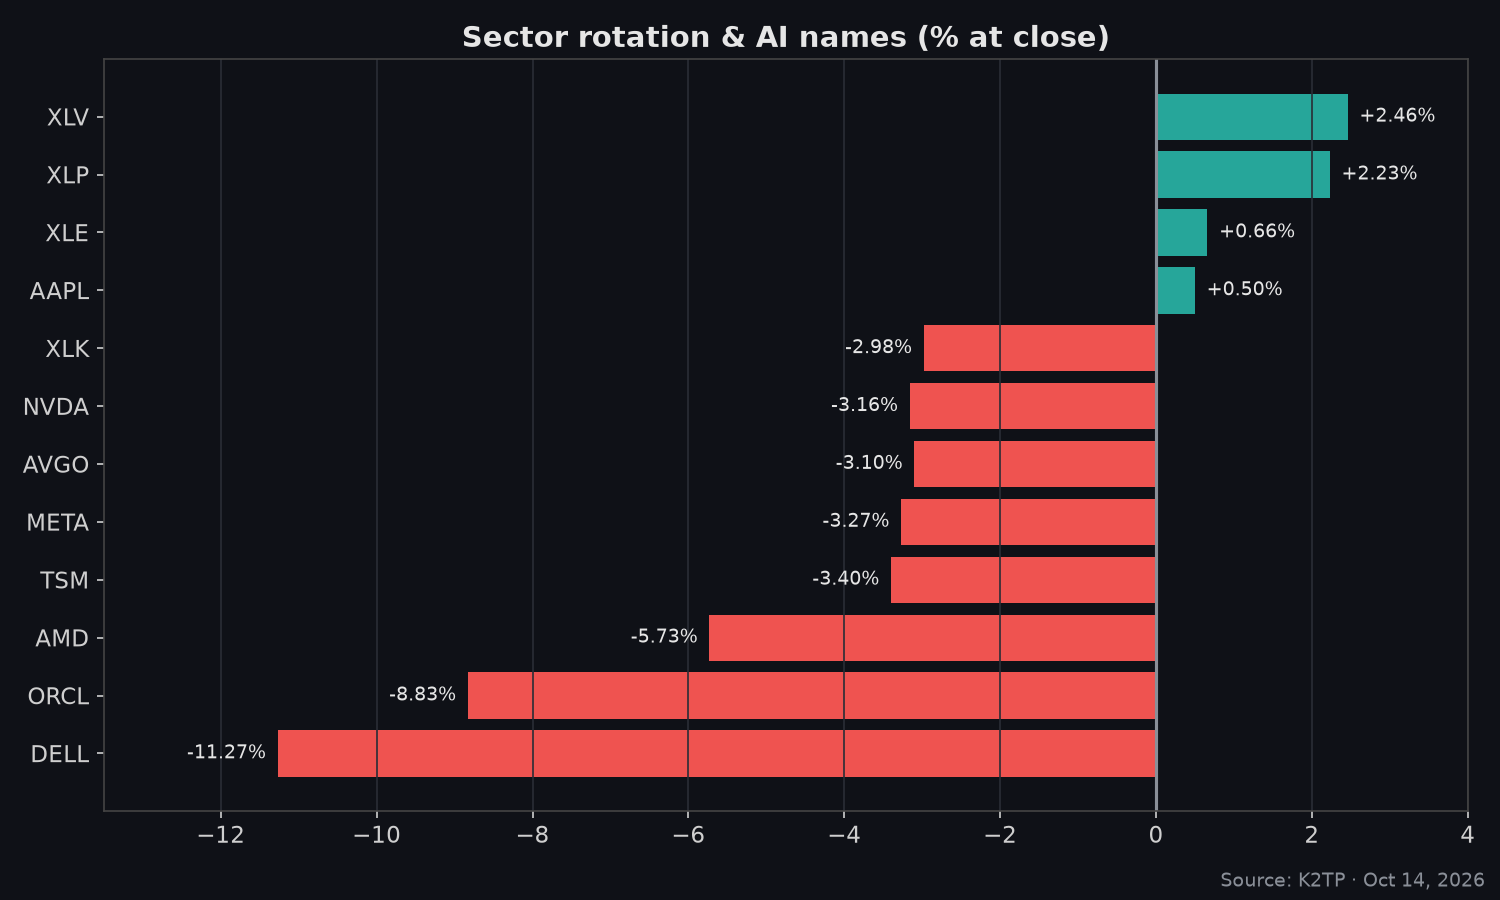
- ORCL −8.83%, DELL −11.27%, AMD −5.73%, TSM −3.40%, META −3.27%, NVDA −3.16%, AVGO −3.10%
- Barclays cut DELL and HPE to equal-weight; HPE −7.6% (pre-close)
- CoreWeave −15%, Nebius −10% (pre-close) as financing costs came into focus
- XLK −2.98%, the weakest sector
→ Higher-for-longer rates hit the most levered AI build-out names. Money did not rotate back into semis for shelter this time.
BANK OF AMERICA: Q3 MISS, $1.2B AML SETTLEMENT
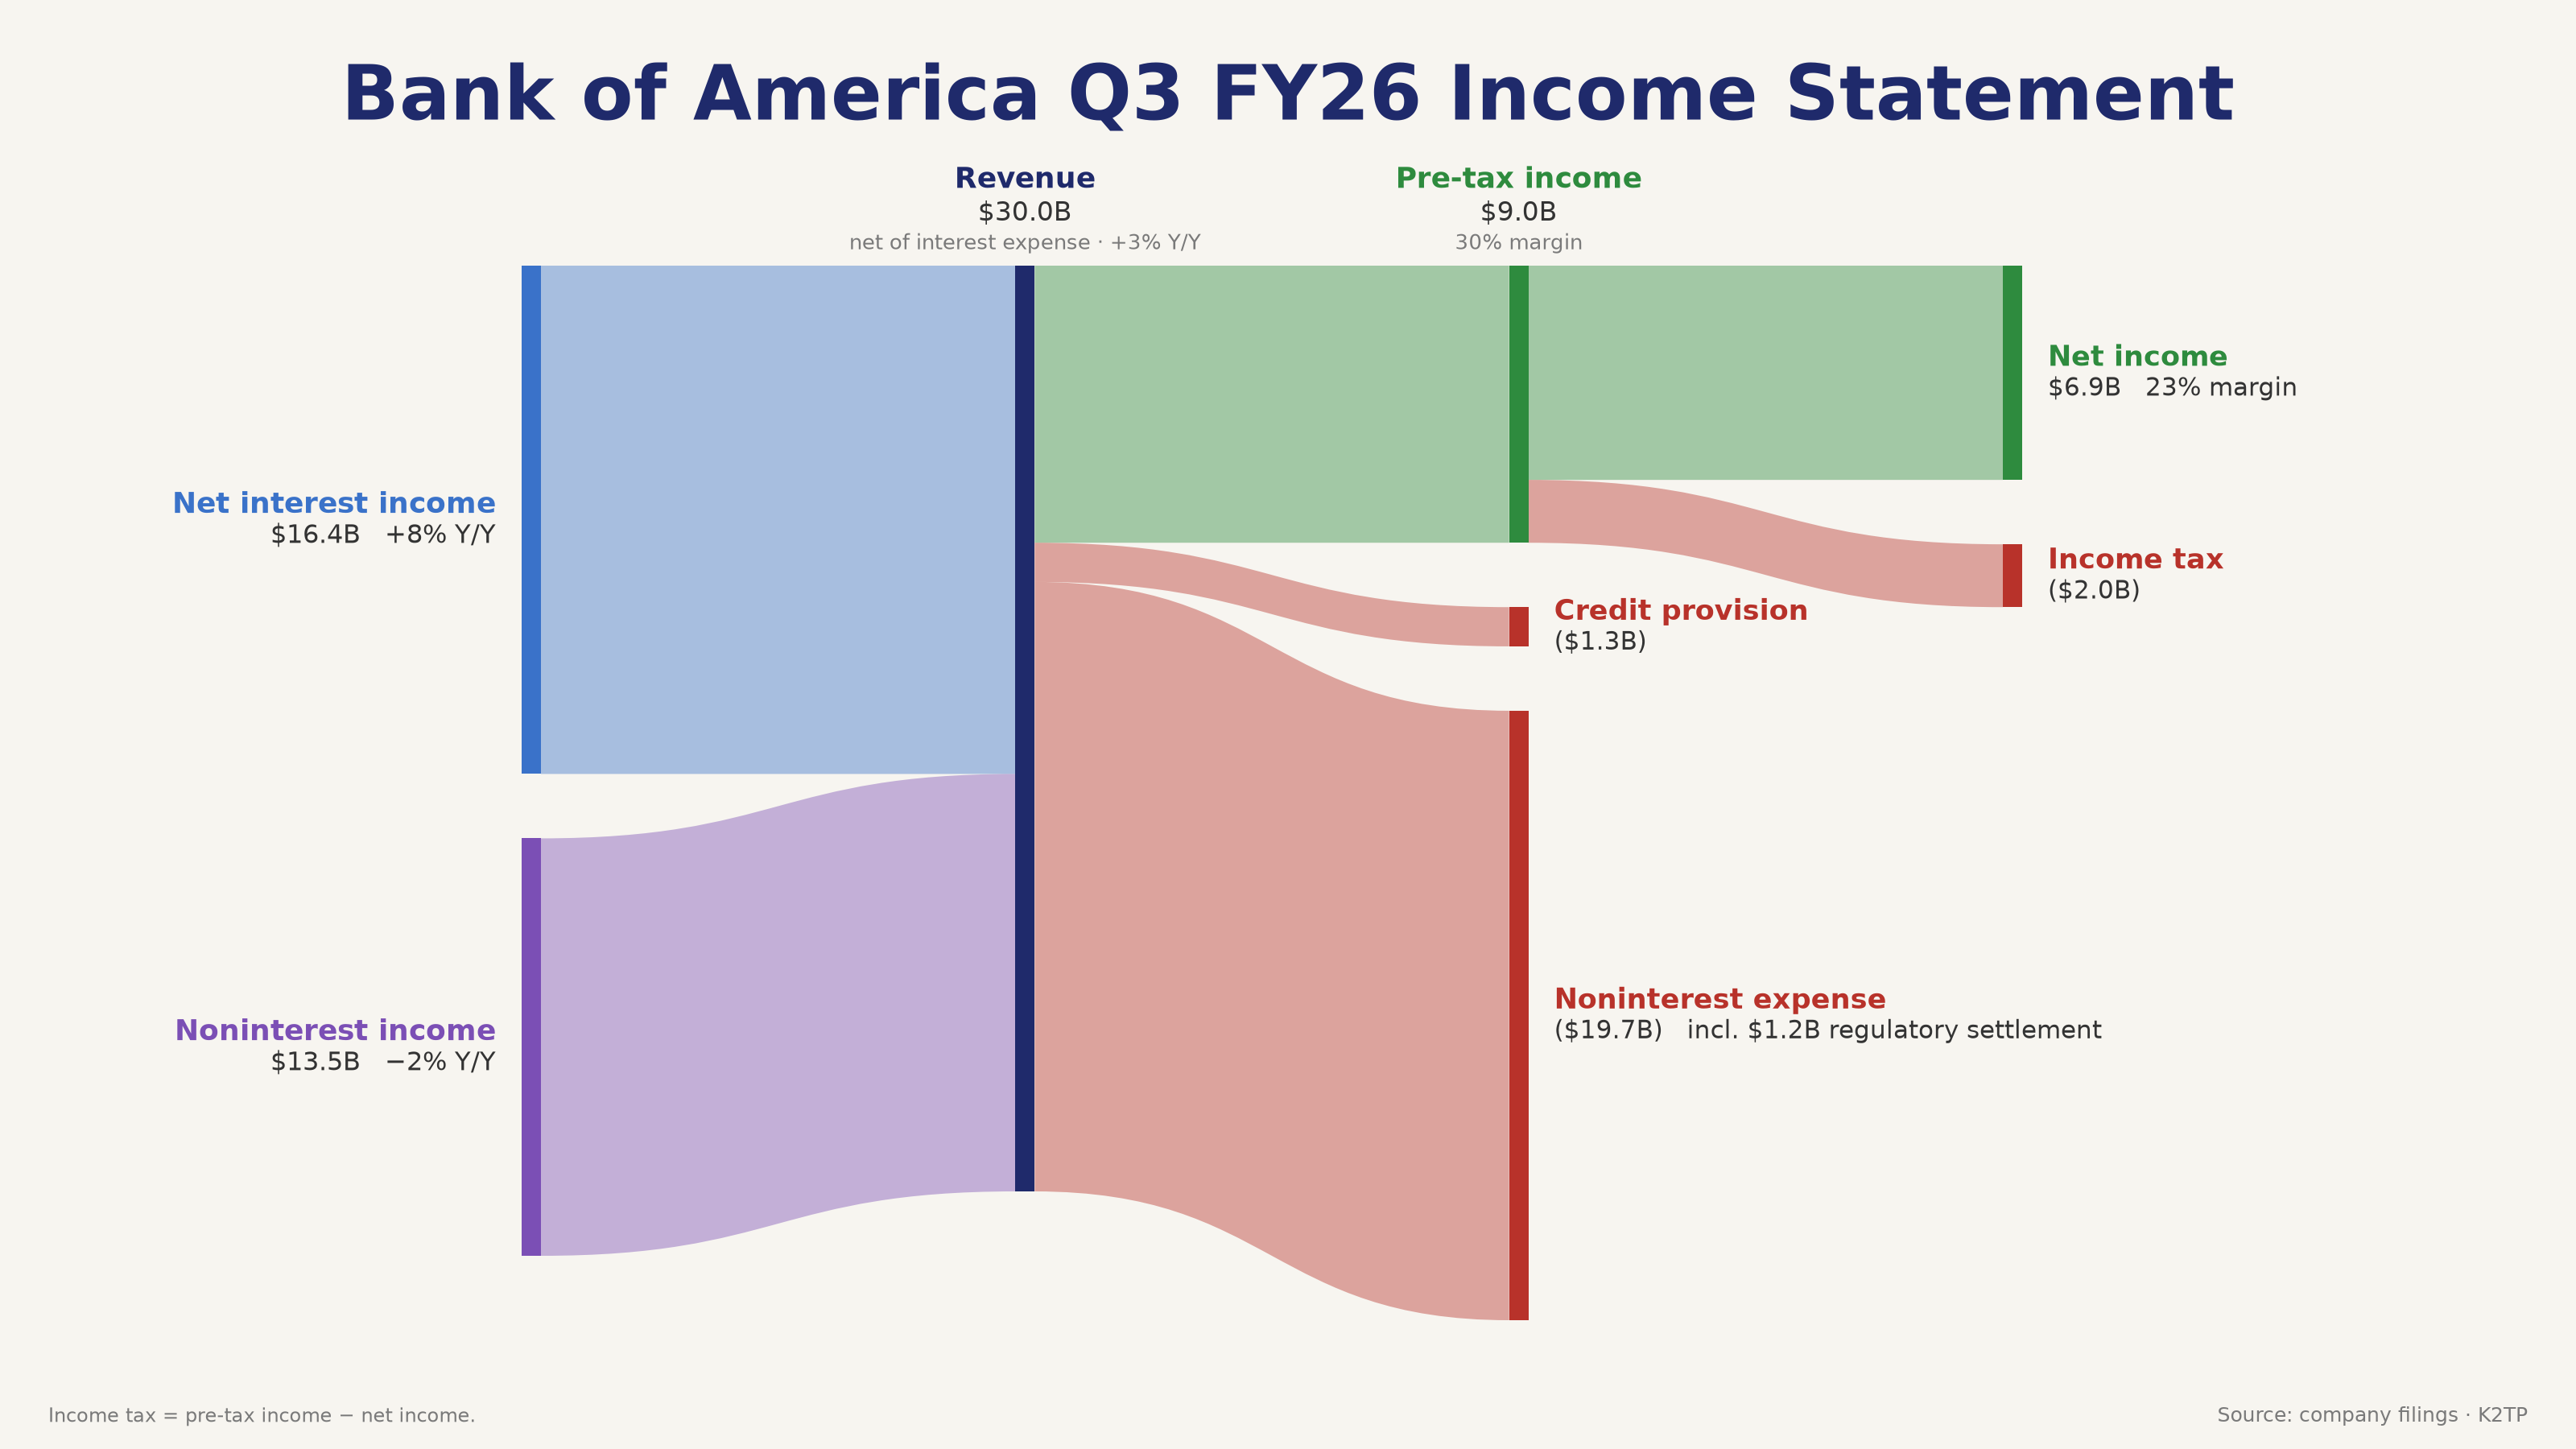
- EPS: $1.08 (forecast $1.11) 🔴
- Revenue: ~$29.96B (forecast ~$30.58B) 🔴
- $1.2B OCC/FinCEN AML settlement, non-deductible, cut EPS by about $0.17 🔴
- NII +8%, average loans +6% 🟢
- Stock: −7.81% pre-market → −5.38% at midday → −5.09% pre-close
→ The settlement plus hot CPI weighed on BAC. It recovered off the lows but is still the weakest of the banks.
MORGAN STANLEY: BEAT, BUT THE STOCK FELL
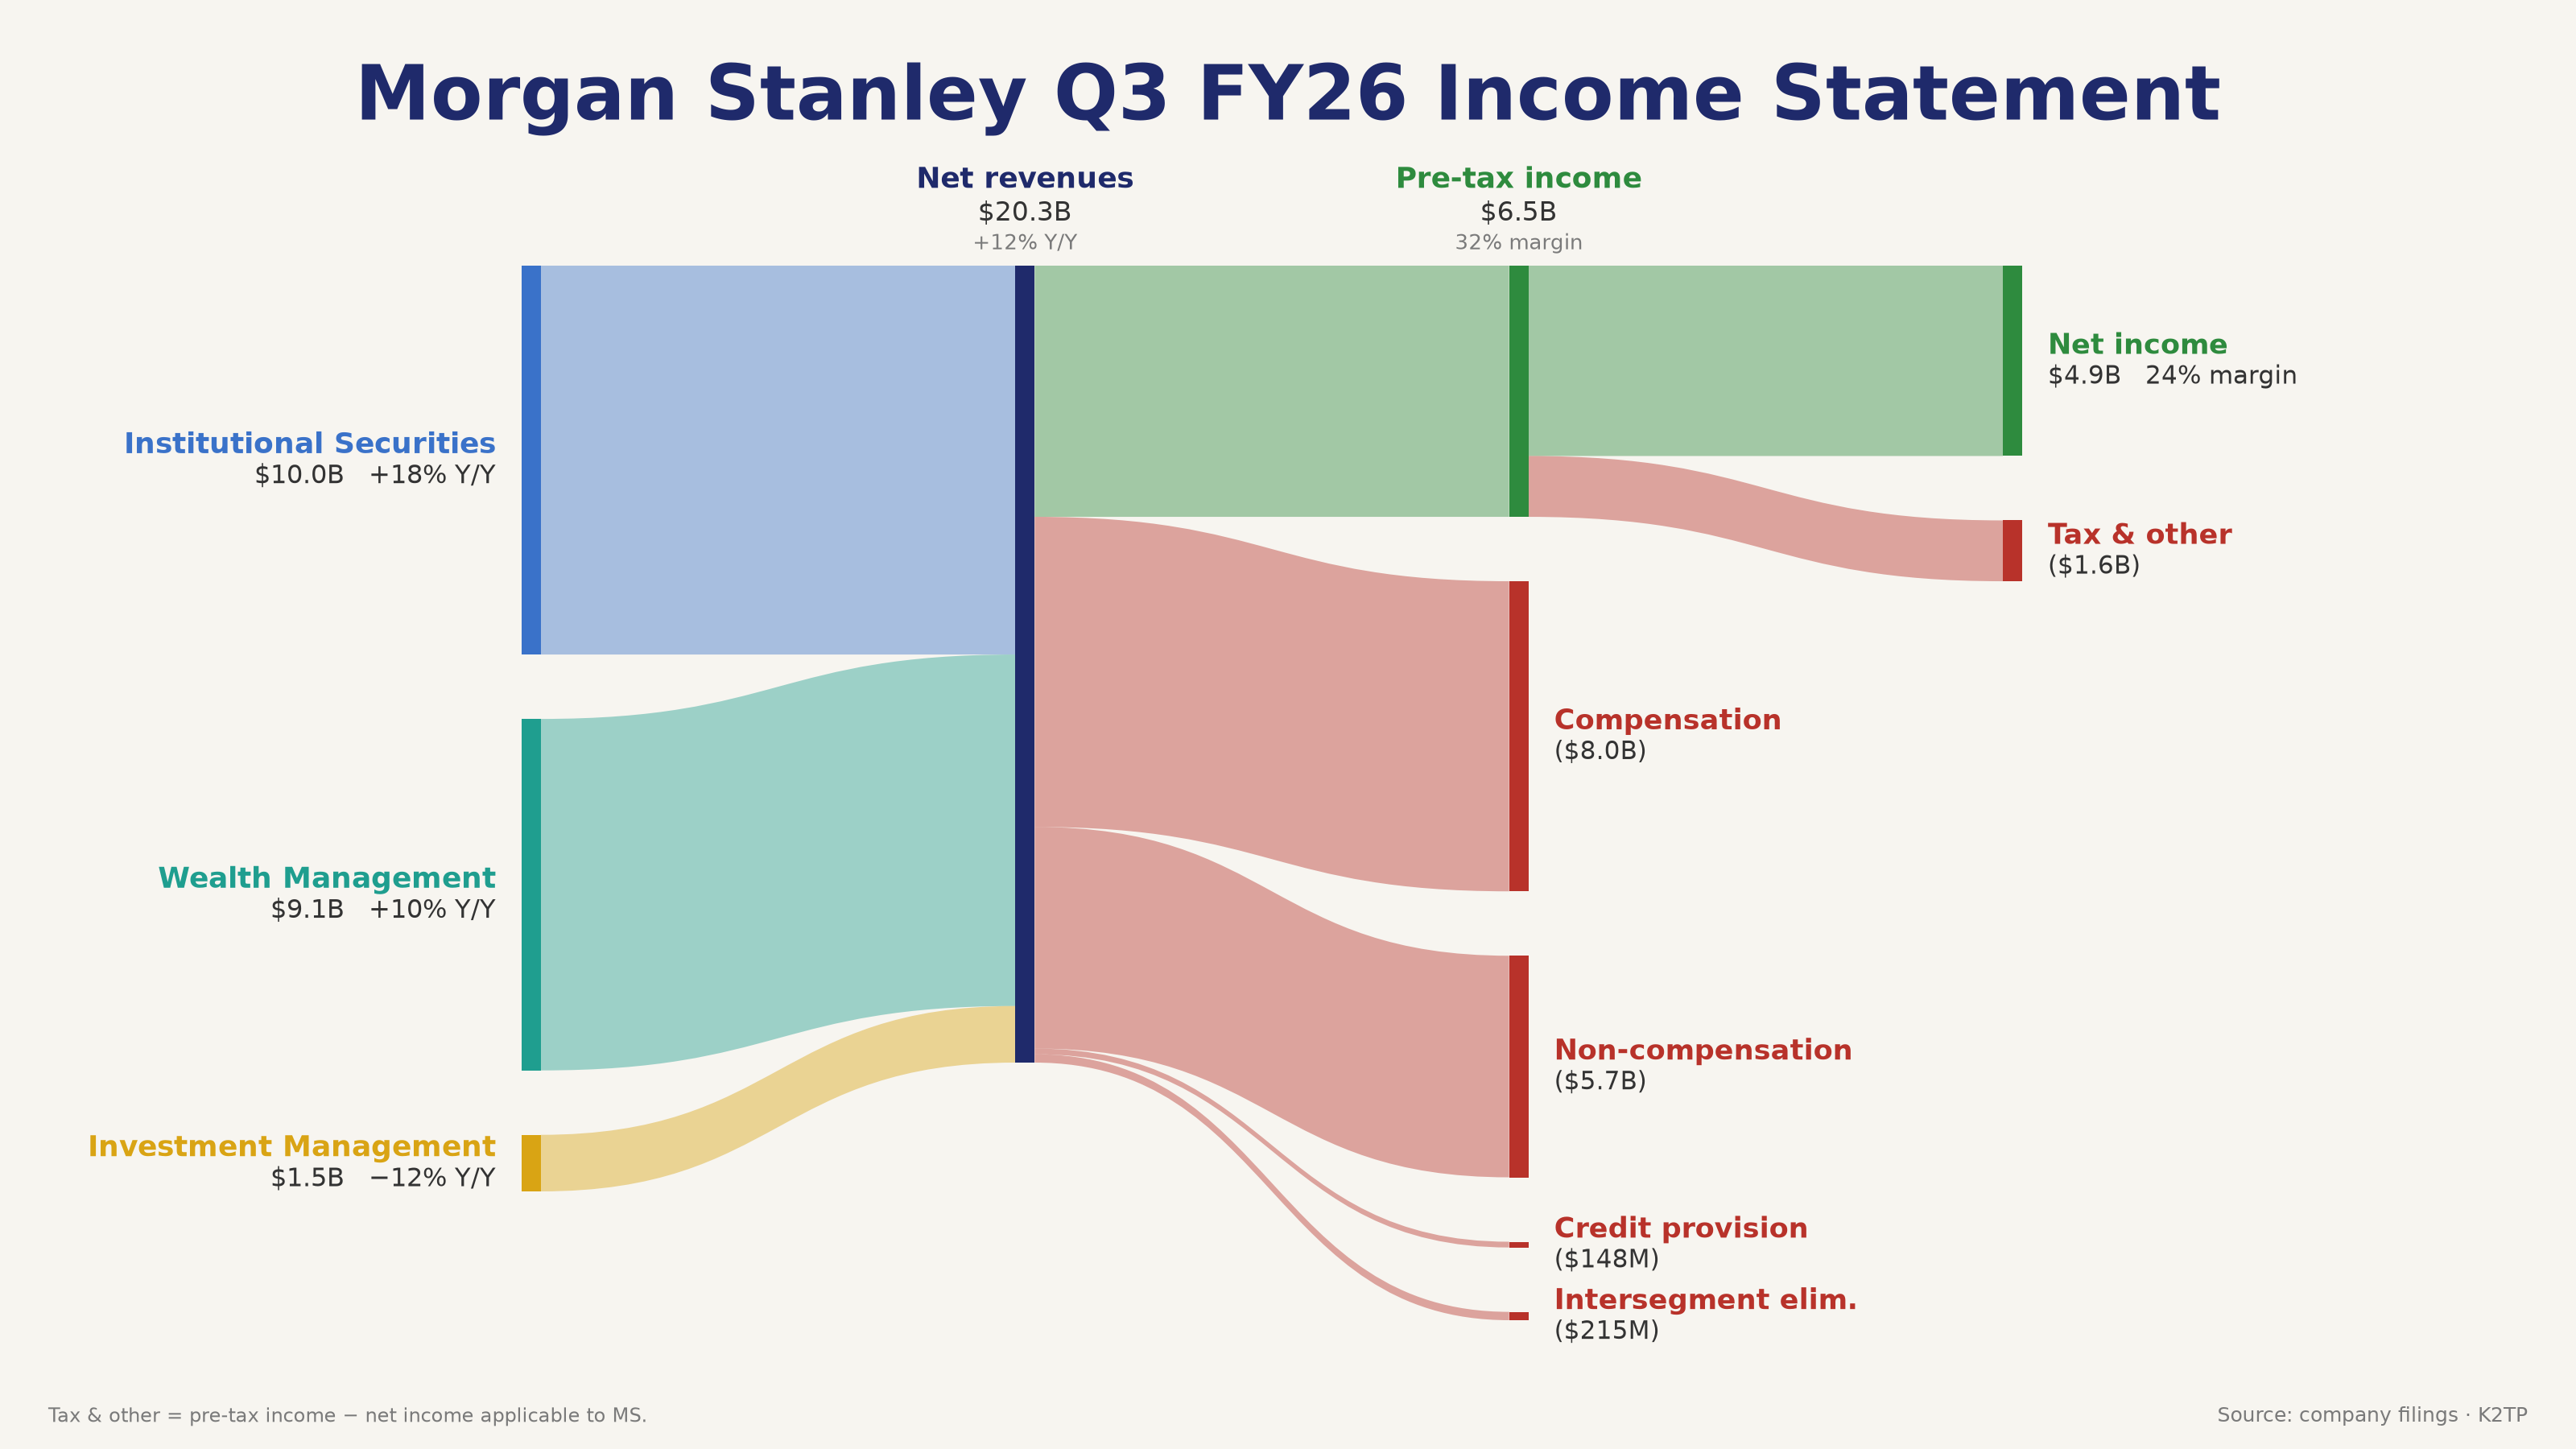
- EPS: $3.03 (forecast ~$2.93) 🟢
- Revenue: $20.3B (forecast ~$19.9B), +12% y/y 🟢
- Equities trading: $5.80B (+41%) 🟢
- Wealth Management: record ~$9.1B in revenue, $232B in net new assets 🟢
- Stock: −2.85% pre-market → −3.48% at midday → −3.10% pre-close
→ A clean beat could not offset CPI.
OTHER REPORTS: ASML, PGR, BLK
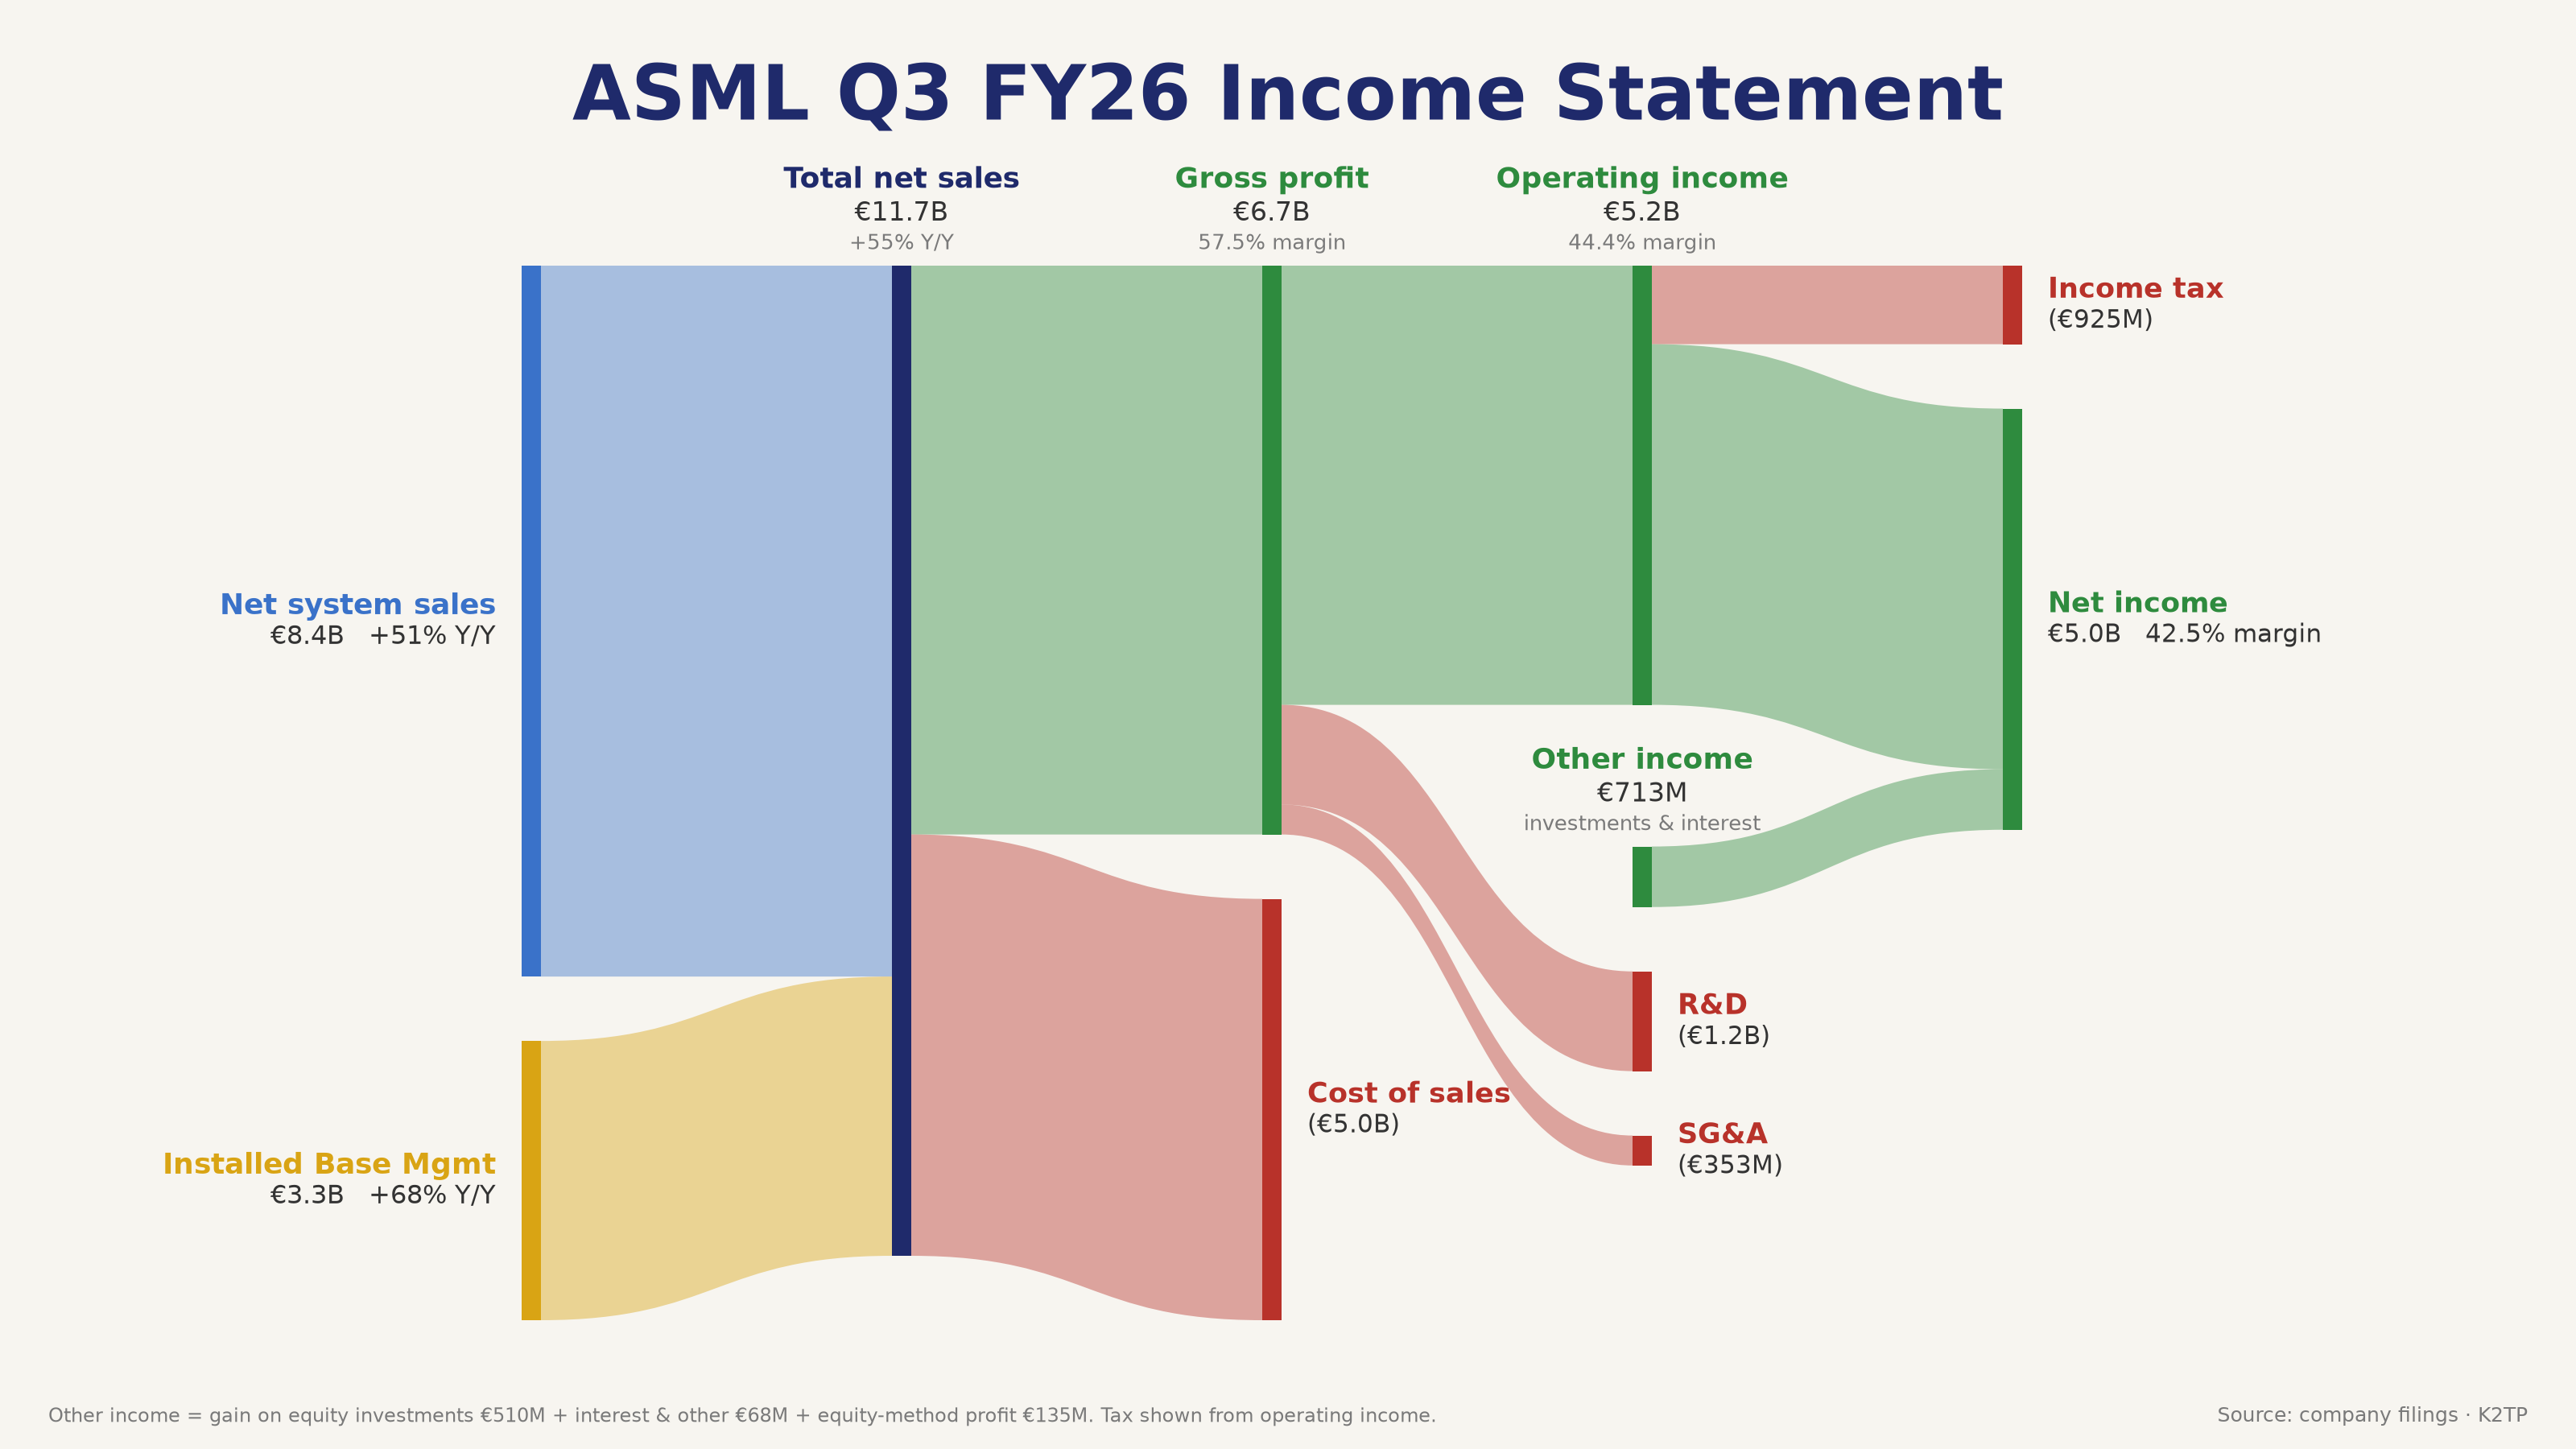
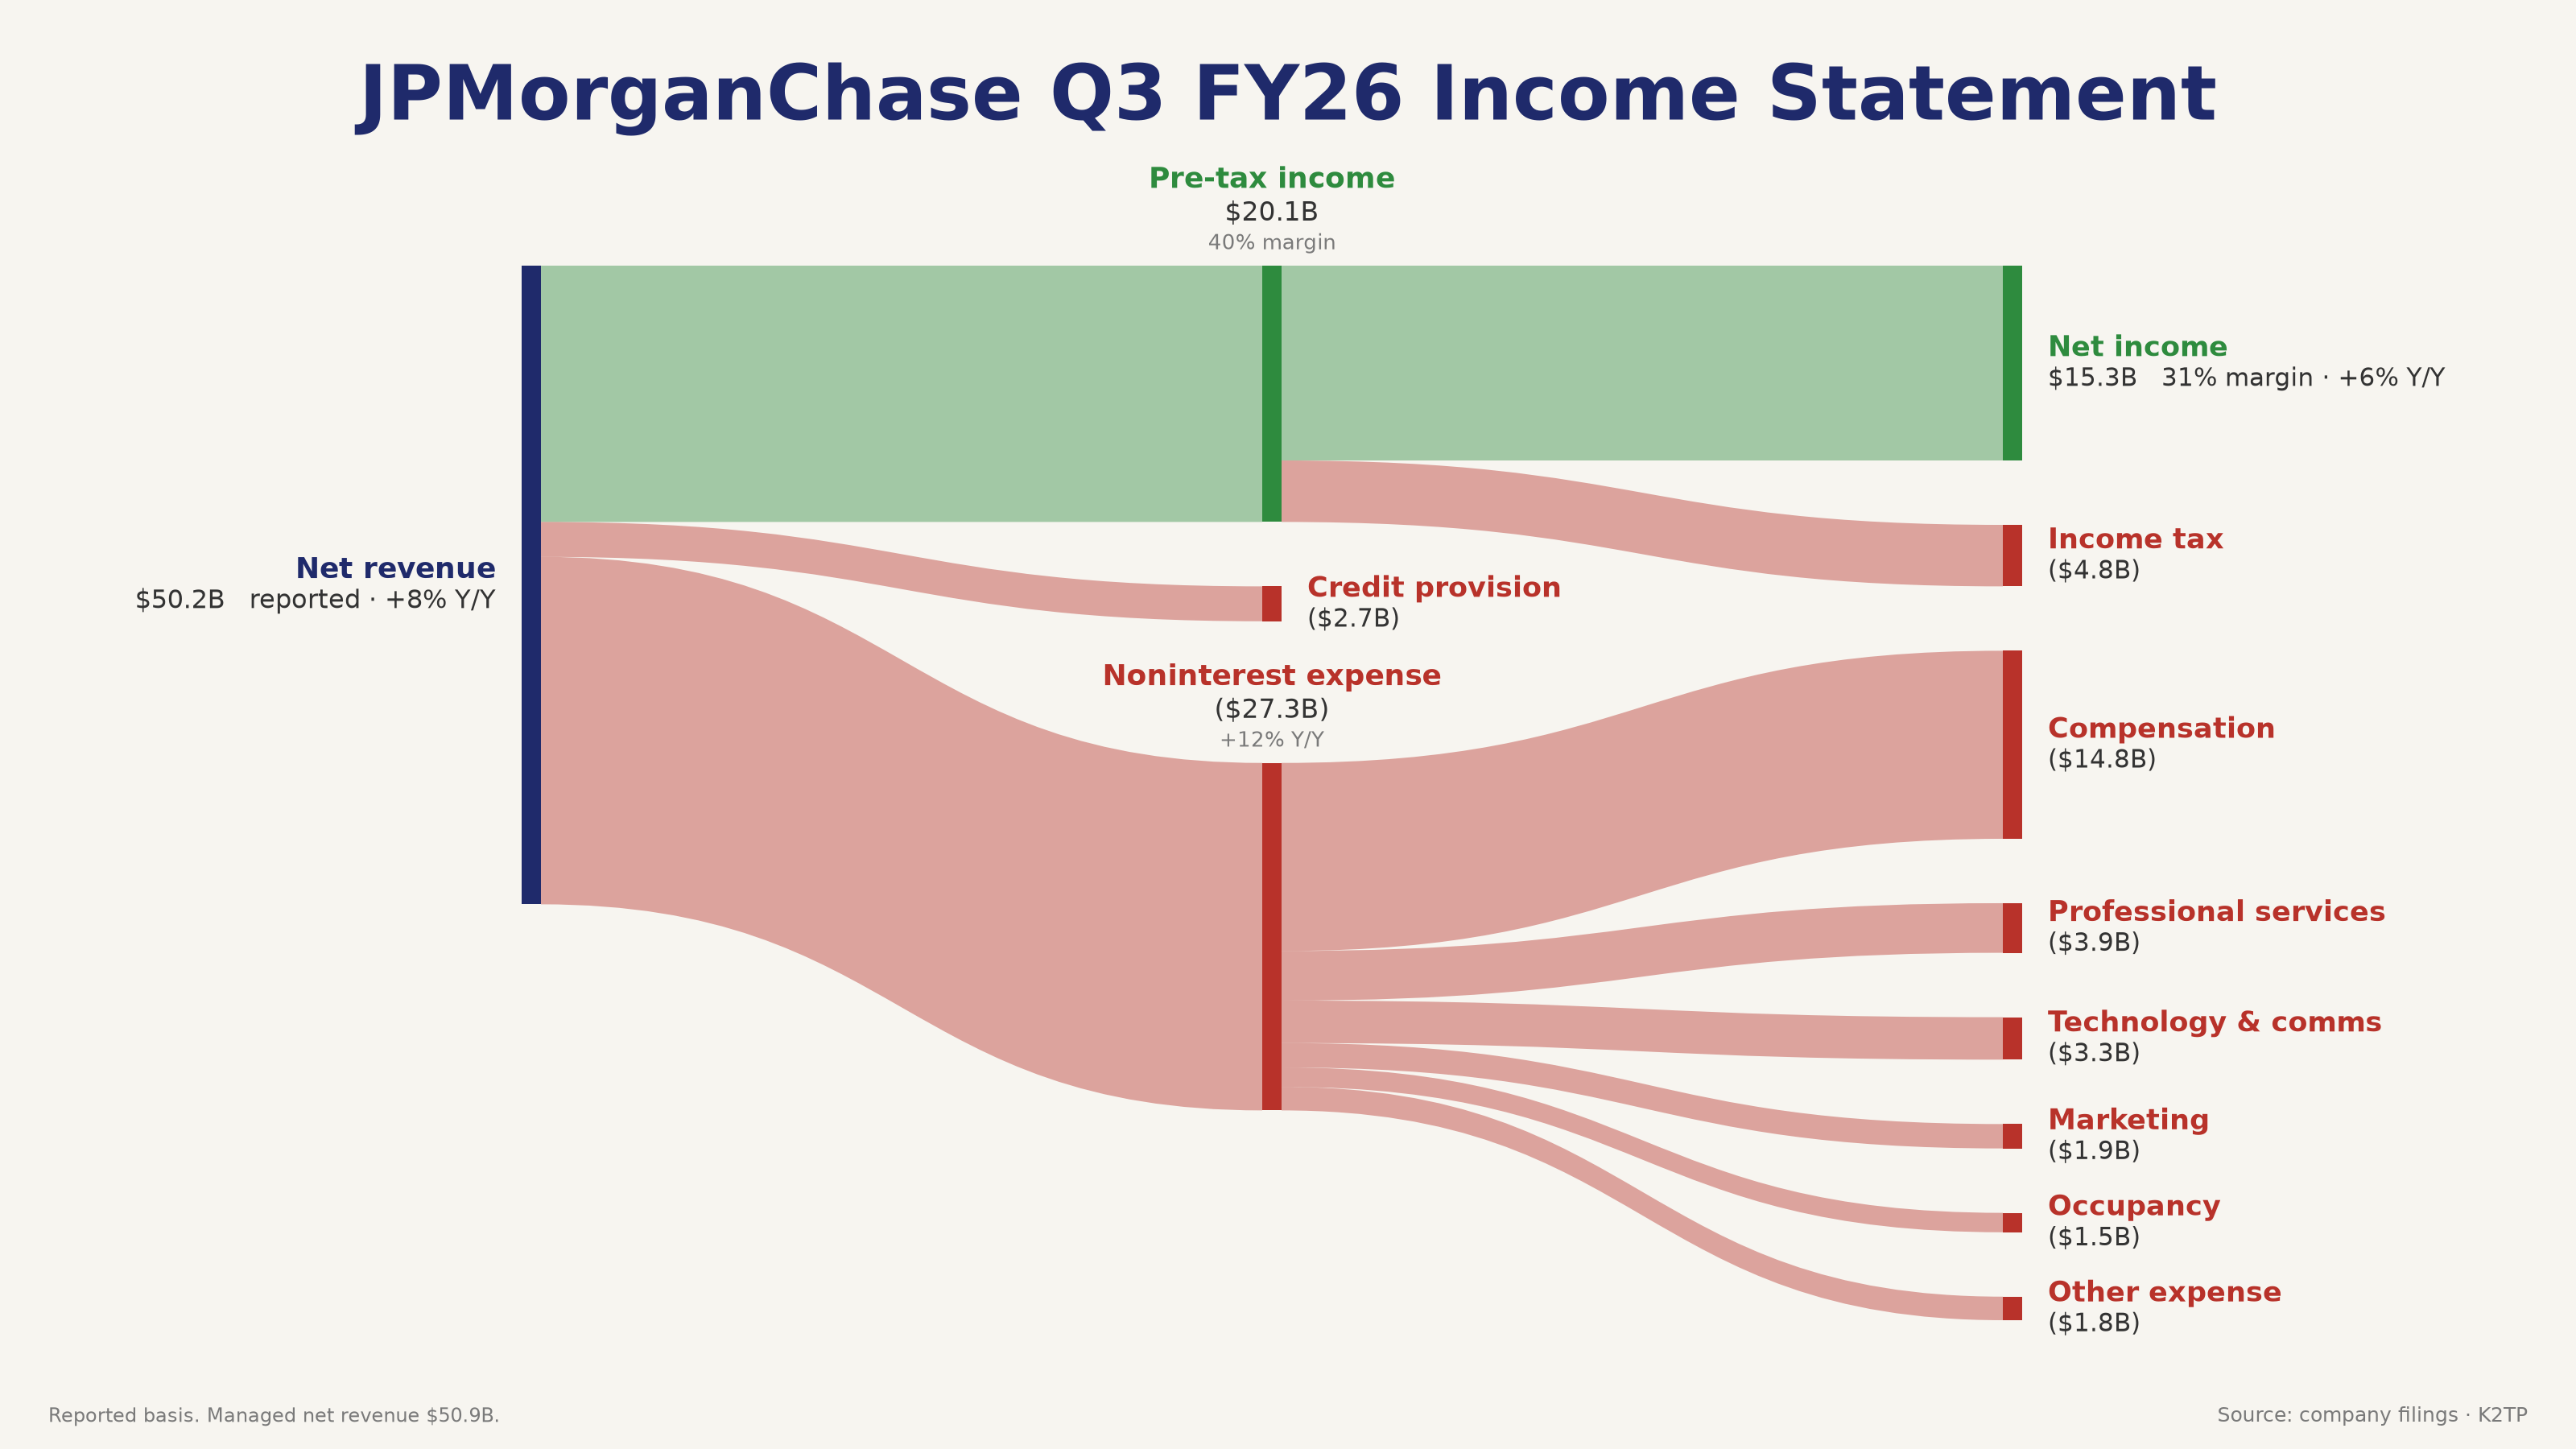
- ASML: Q3 sales €11.7B, gross margin 57.5%, net income €5.0B; Q4 guide €14.2–15.2B; FY2026 €44–45B 🟢. ADR −2.60% pre-market and −2.46% pre-close 🔴
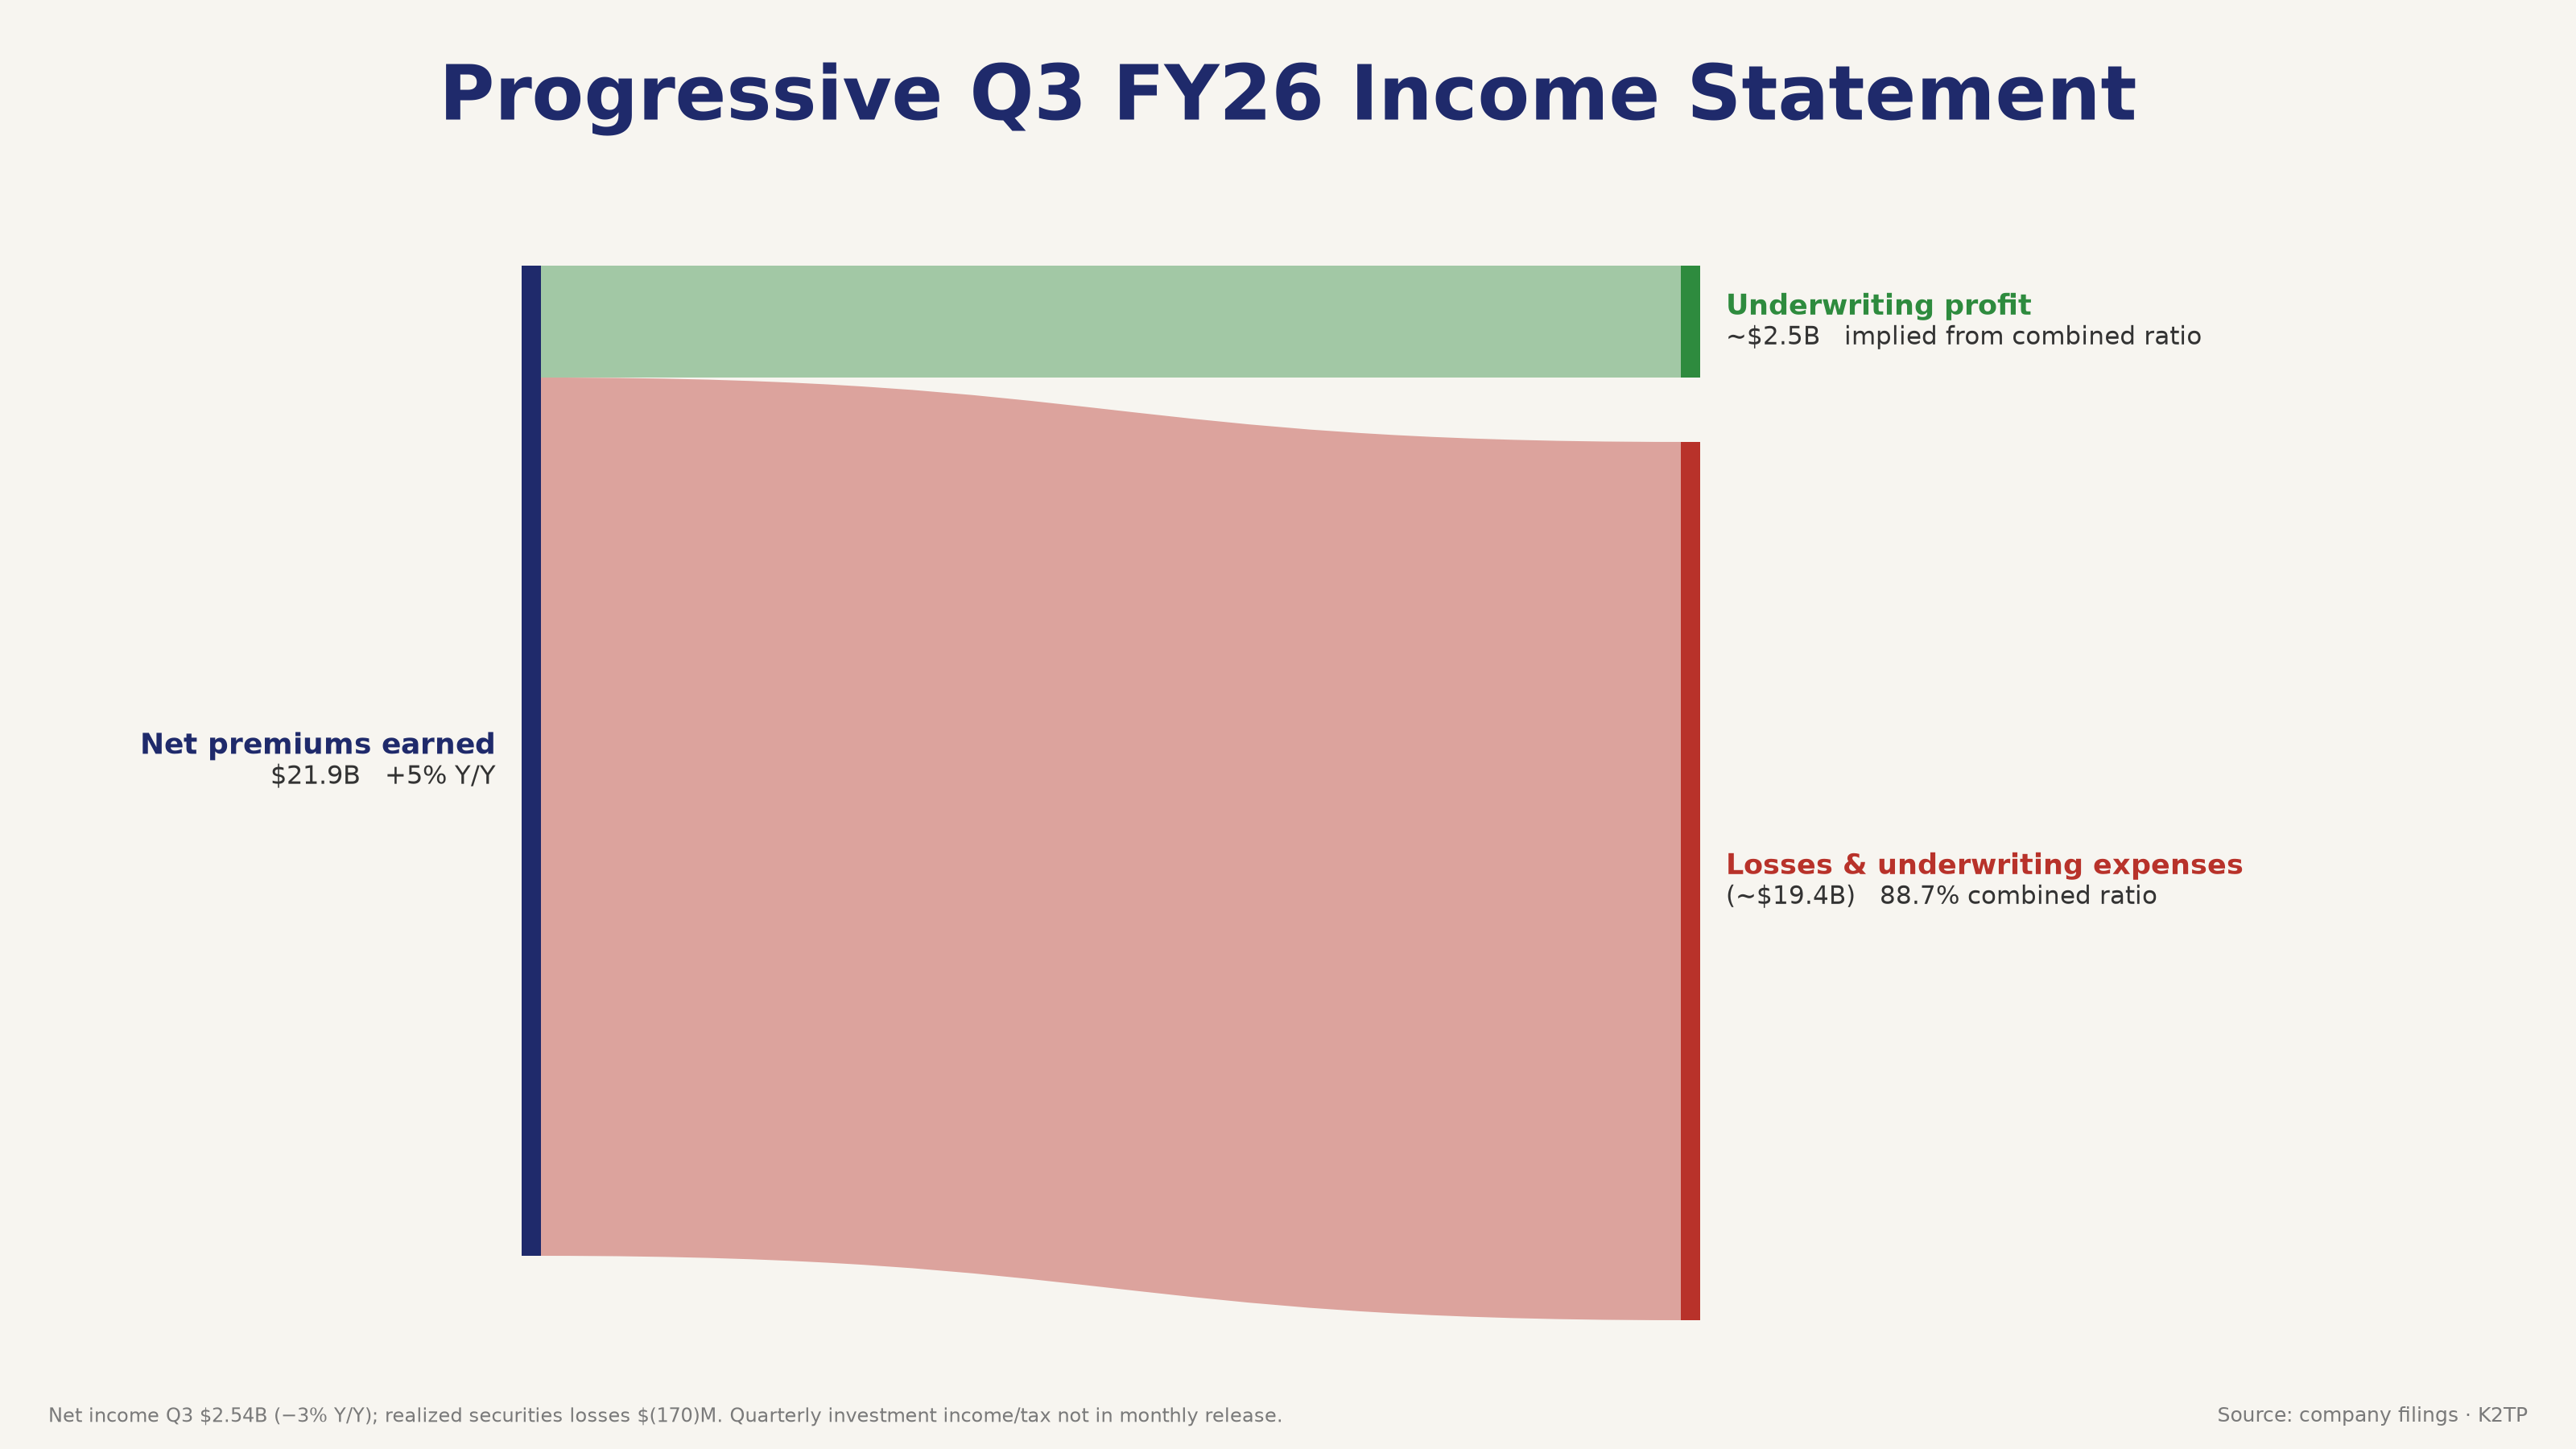
- PGR: Q3 net income $2.54B (−3% y/y) on $170M of realized securities losses; combined ratio 88.7%. Stock −8.25% → −4.28% (earnings detail not independently confirmed)
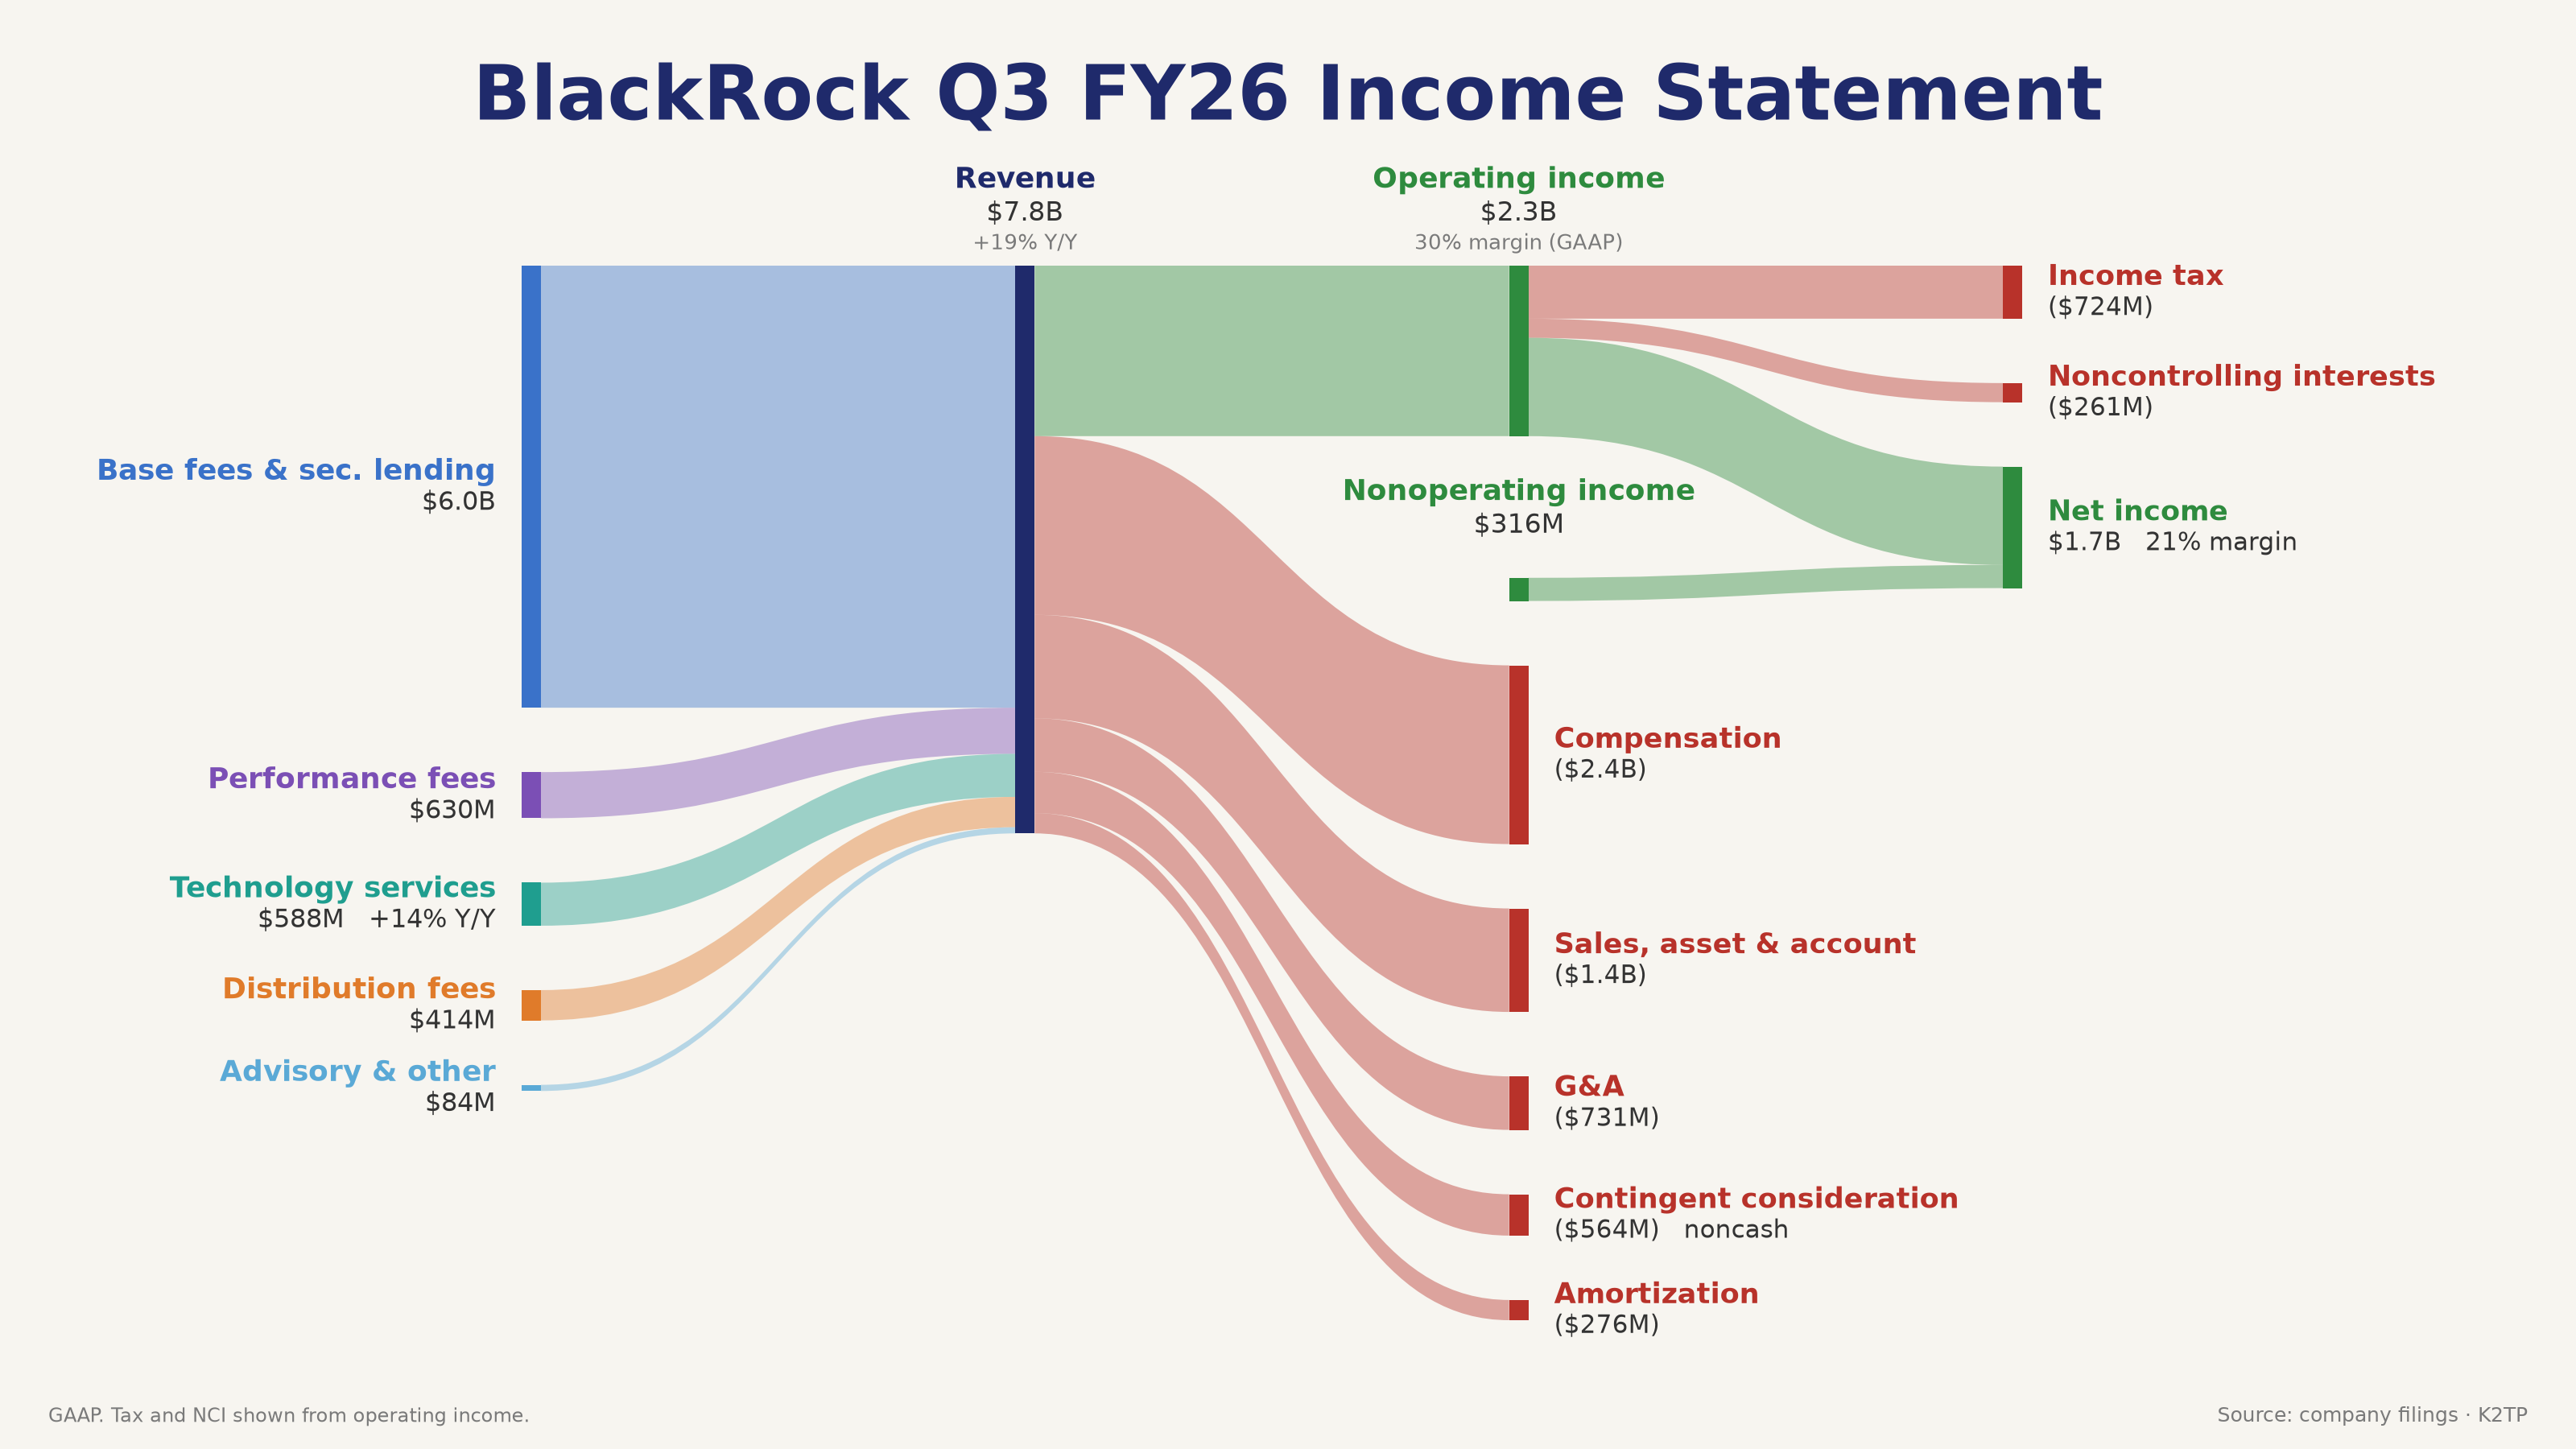
- BLK: adjusted EPS ~$15.93 (forecast ~$14.30) 🟢, AUM ~$15.49T (unconfirmed source). Stock +0.30%
- JPM +0.97% at pre-close, cushioning XLF
→ ASML's beat could not escape the money leaving semis.
BEIGE BOOK: SLIGHT GROWTH, BROADENING PRICES
- Activity: 2 districts moderate growth, 3 modest, 4 slight, 3 no change
- Consumer spending mostly flat, driven by high-income households
- Prices: robust in 3 districts, moderate in 8
→ Soft activity with firm prices keeps the stagflation worry alive, and cyclicals got no relief bid.
MARKET: SEMIS BLEED, MONEY HIDES IN DEFENSIVES
Indices (close):
- SPX 7,718.94 (−1.11%), day range 7,693.31–7,789.15
- NDX 29,950.82 (−2.02%)
- RUT 2,729.53 (−1.93%)
- DJIA 51,621.48 (−0.09%)
- RSP −0.58%: equal-weight beat cap-weight because the large AI names took the heaviest selling
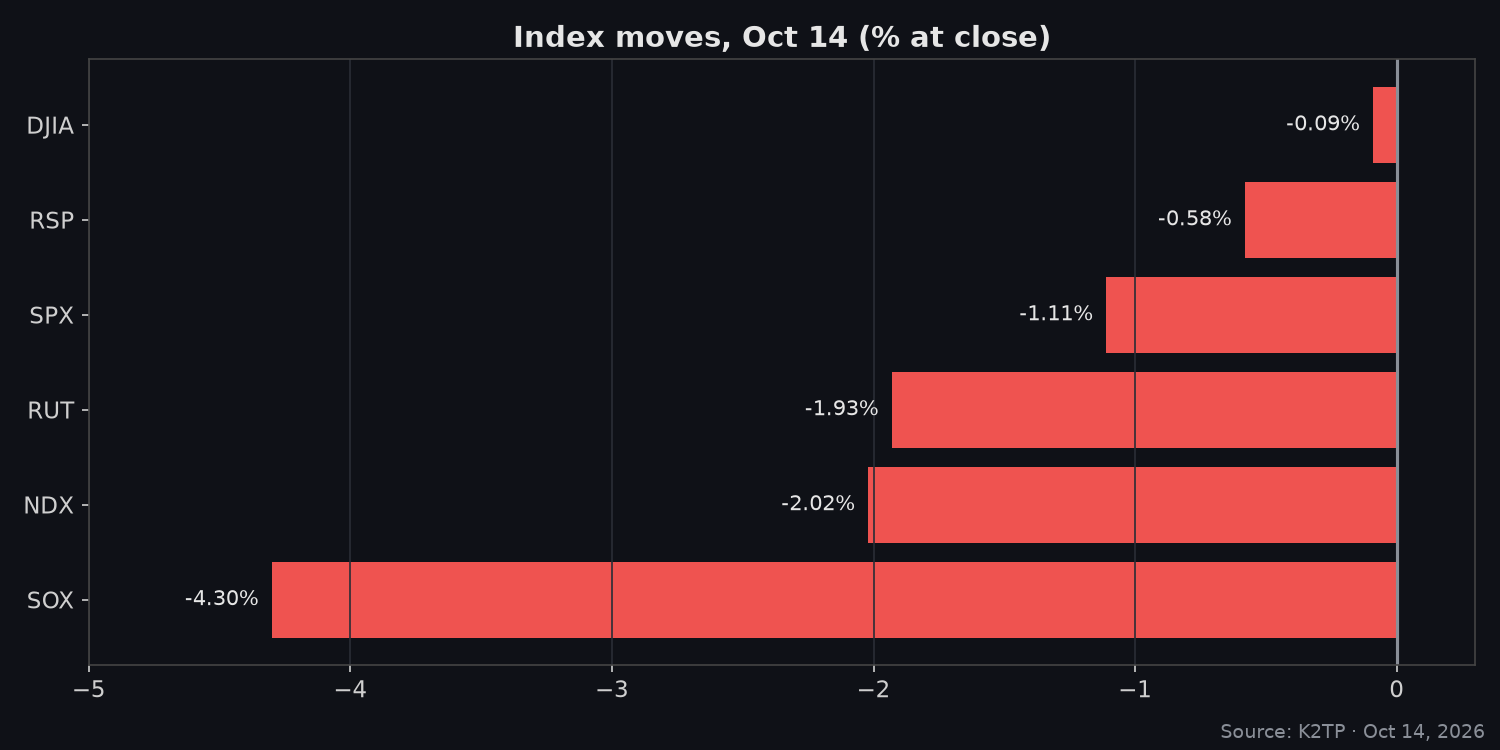
Session path: ES −0.34% pre-market. By midday SPX was −1.10%, through Friday's low of 7,779.34. At pre-close SPX was −1.30% (7,703.86) and tagged the 7,693.31 day low. A late bounce lifted SPX back above the 7,716.80 midday low into the close.
Sector Rotation:
- Gainers: XLV +2.46% (UNH +4.01%, JNJ +2.00% at pre-close), XLP +2.23%, XLE +0.66%
- Laggards: XLK −2.98%
- AAPL +0.50% was the only gaining mega-cap
Market Internals:
- Decliners/advancers around 9:30 AM PT: NYSE 4.42:1, Nasdaq 3.78:1
- Later in the day, S&P 500 decliners led 1.7:1
- Nasdaq: 22 new highs vs 466 new lows
Volatility:
- VIX 16.87 (+10.48%), day high 17.45
- At pre-close: VIX9D 14.76, VIX3M 18.93, term structure still in Contango
- Front Vol is not yet richer than back months, so short-dated hedging demand is not in panic
SPX Key Levels:
- 7,789.15: today's high, also the Bull trigger
- 7,779.34: Friday's low, already broken
- 7,718.94: close
- 7,716.80: midday low
- 7,693.31: today's low, also the Bear trigger
- 7,731.26: last Thursday's low
- VIX: 16.46/16.50 and 17.45
Option-seller angle:
- Bear case: if SPX breaks 7,693.31 and VIX clears 17.45, ranges will expand. Widen strikes or cut short-put size.
- Avoid tight Iron Condors or strangles on NDX and semis while SOX is down six straight sessions and TSMC has not reported.
- Event risk is stacked: TSMC tonight, PPI and retail sales at 5:30 AM PT, Warsh Thursday evening, then Friday OpEx. Avoid opening 0DTE or 1DTE positions before the data.
BOTTOM LINE
- Hot CPI lit the fuse, but by the close the selling was about AI and growth-duration positioning. Yields fell below Tuesday's level and equities still did not recover.
- Money rotated into defensives (health care, staples, energy) and did not go back to semis.
- Market Structure stays RISK-OFF. The late bounce reclaimed 7,716.80, but VIX is still above 16.46.
What to watch (PT):
- 11:00 PM tonight: TSMC Q3 call. Prior Q3 revenue guide was $44.6–45.8B, gross margin 65–67%.
- 5:30 AM: data calendar
| Release | Forecast | Prior |
|---|---|---|
| Retail sales m/m | +0.3% | +1.2% |
| Core retail sales m/m | +0.6% | +1.4% |
| PPI m/m | +0.6% | +0.4% |
| Core PPI m/m | +0.3% | +0.2% |
| Jobless claims | 199K | 197K |
| Empire State | 12.1 | 7.6 |
| Philly Fed | 28.2 | 37.8 |
- 8:00 AM: EIA crude inventories
- 8:30 PM: Fed Chair Warsh with IMF's Georgieva
- Friday: monthly OpEx
Expected (Bull): SPX reclaims 7,789.15 with VIX under 16.50 and SOX green. Expected (Bear): SPX under 7,693.31 with VIX above 17.45 and hike odds back toward 45%+.
Sources: 4 K2TP briefs for Oct 14, 2026 (Pre-Market, Midday, Pre-Close, Evening Recap). Analysis: K2TP Framework.