Market 11/4: A post-election relief rally as Democrats talk of ending the Iran war; oil crashes 8%, VIX drops 20% and the Dow jumps 3%, while chips sink; APP soars after hours and QCOM slides on its guide
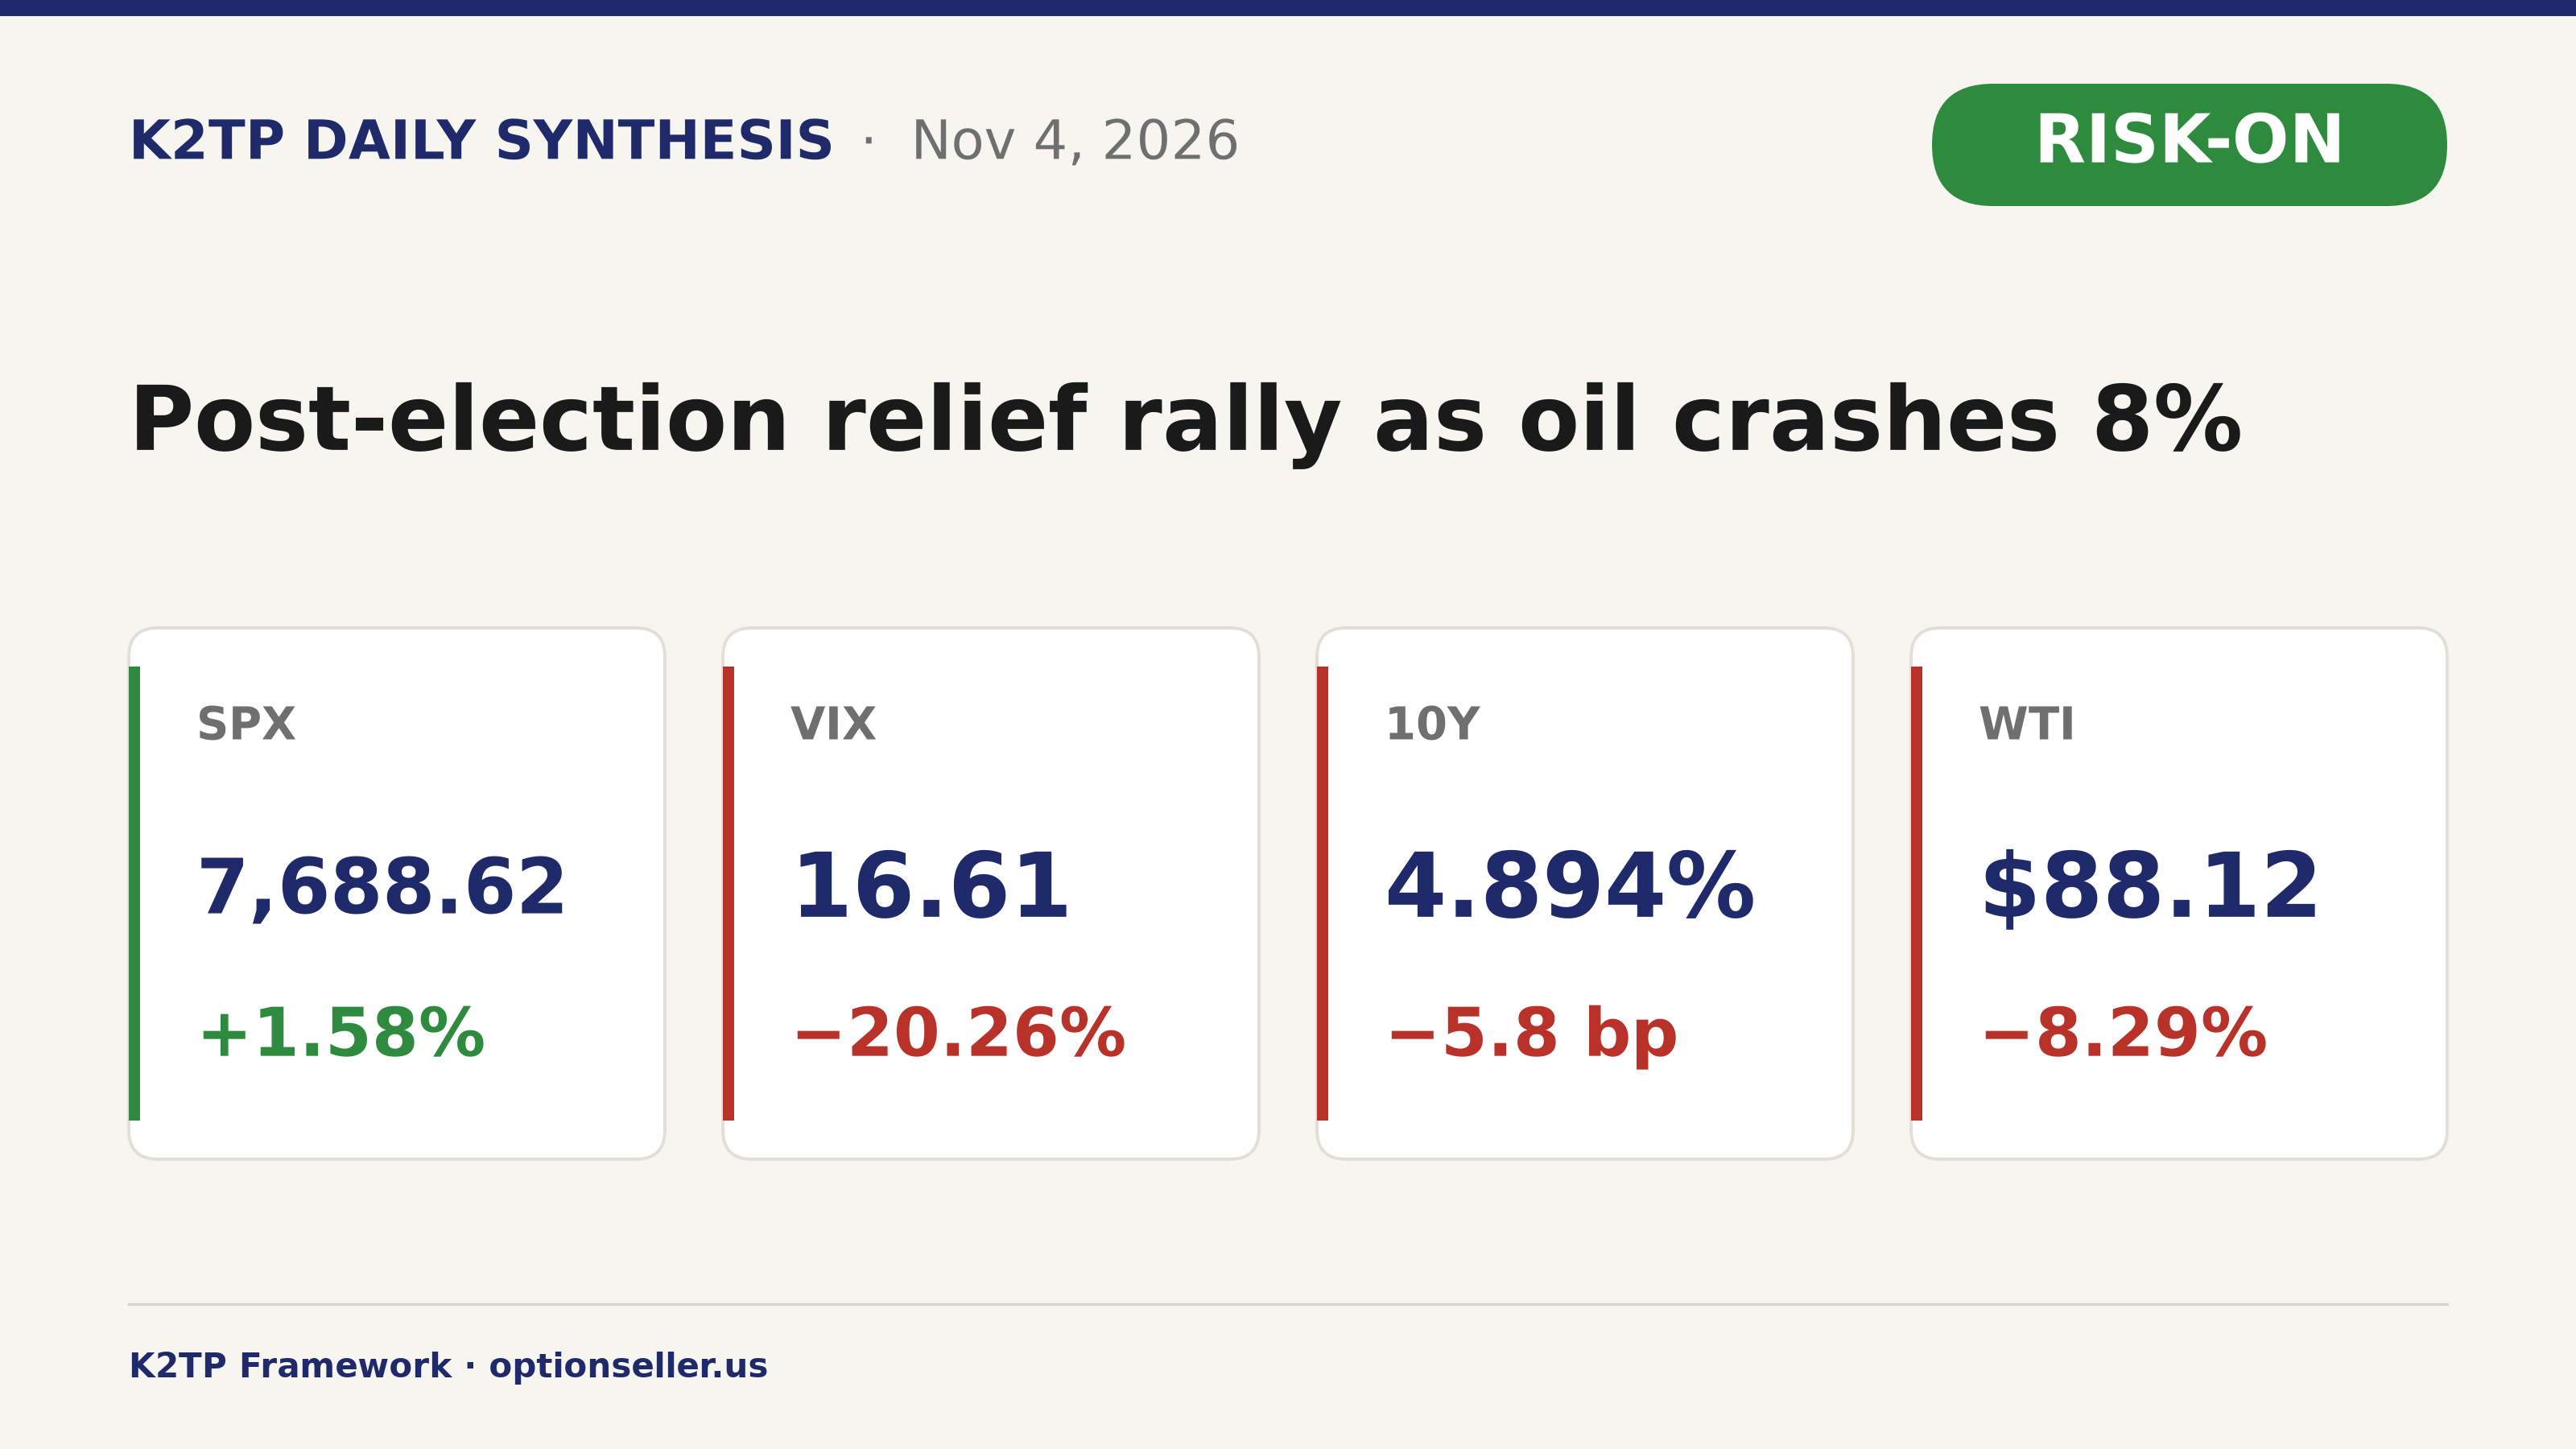
SPX +1.58%, DJIA +3.03%, NDX +0.91%, RUT +1.58%, RSP +1.86%, SOX −3.13%, VIX −20.26% to 16.61. MSFT +6.68%, AMZN +6.12% and AAPL +5.31% lead while MU −7.00%, ARM −5.28% and NVDA −3.17% fall; 8 of 11 sector ETFs rise. WTI settles $88.12 (−8.29%), Brent $94.62 (−8.67%); the 10Y falls 5.8 bp to 4.894%. After hours APP about +23%, QCOM about −7.7%, ARM about −2%; ES −0.09%, NQ −0.54%.
KEY HEADLINES
- Politics: with Democrats projected to win the House and the Senate, Schumer says "we will end the war", Vance says "the reason we lost is the war", and Jeffries expects at least 255 House seats. Trump says "the Iran war will end whenever I want it to" and that he is not replacing Hegseth 🟢
- Oil crash: WTI settled $88.12 (−$7.97, −8.29%), Brent $94.62 (−$8.98, −8.67%), Brent's lowest settle since August 31; XLE −4.74% is the worst sector
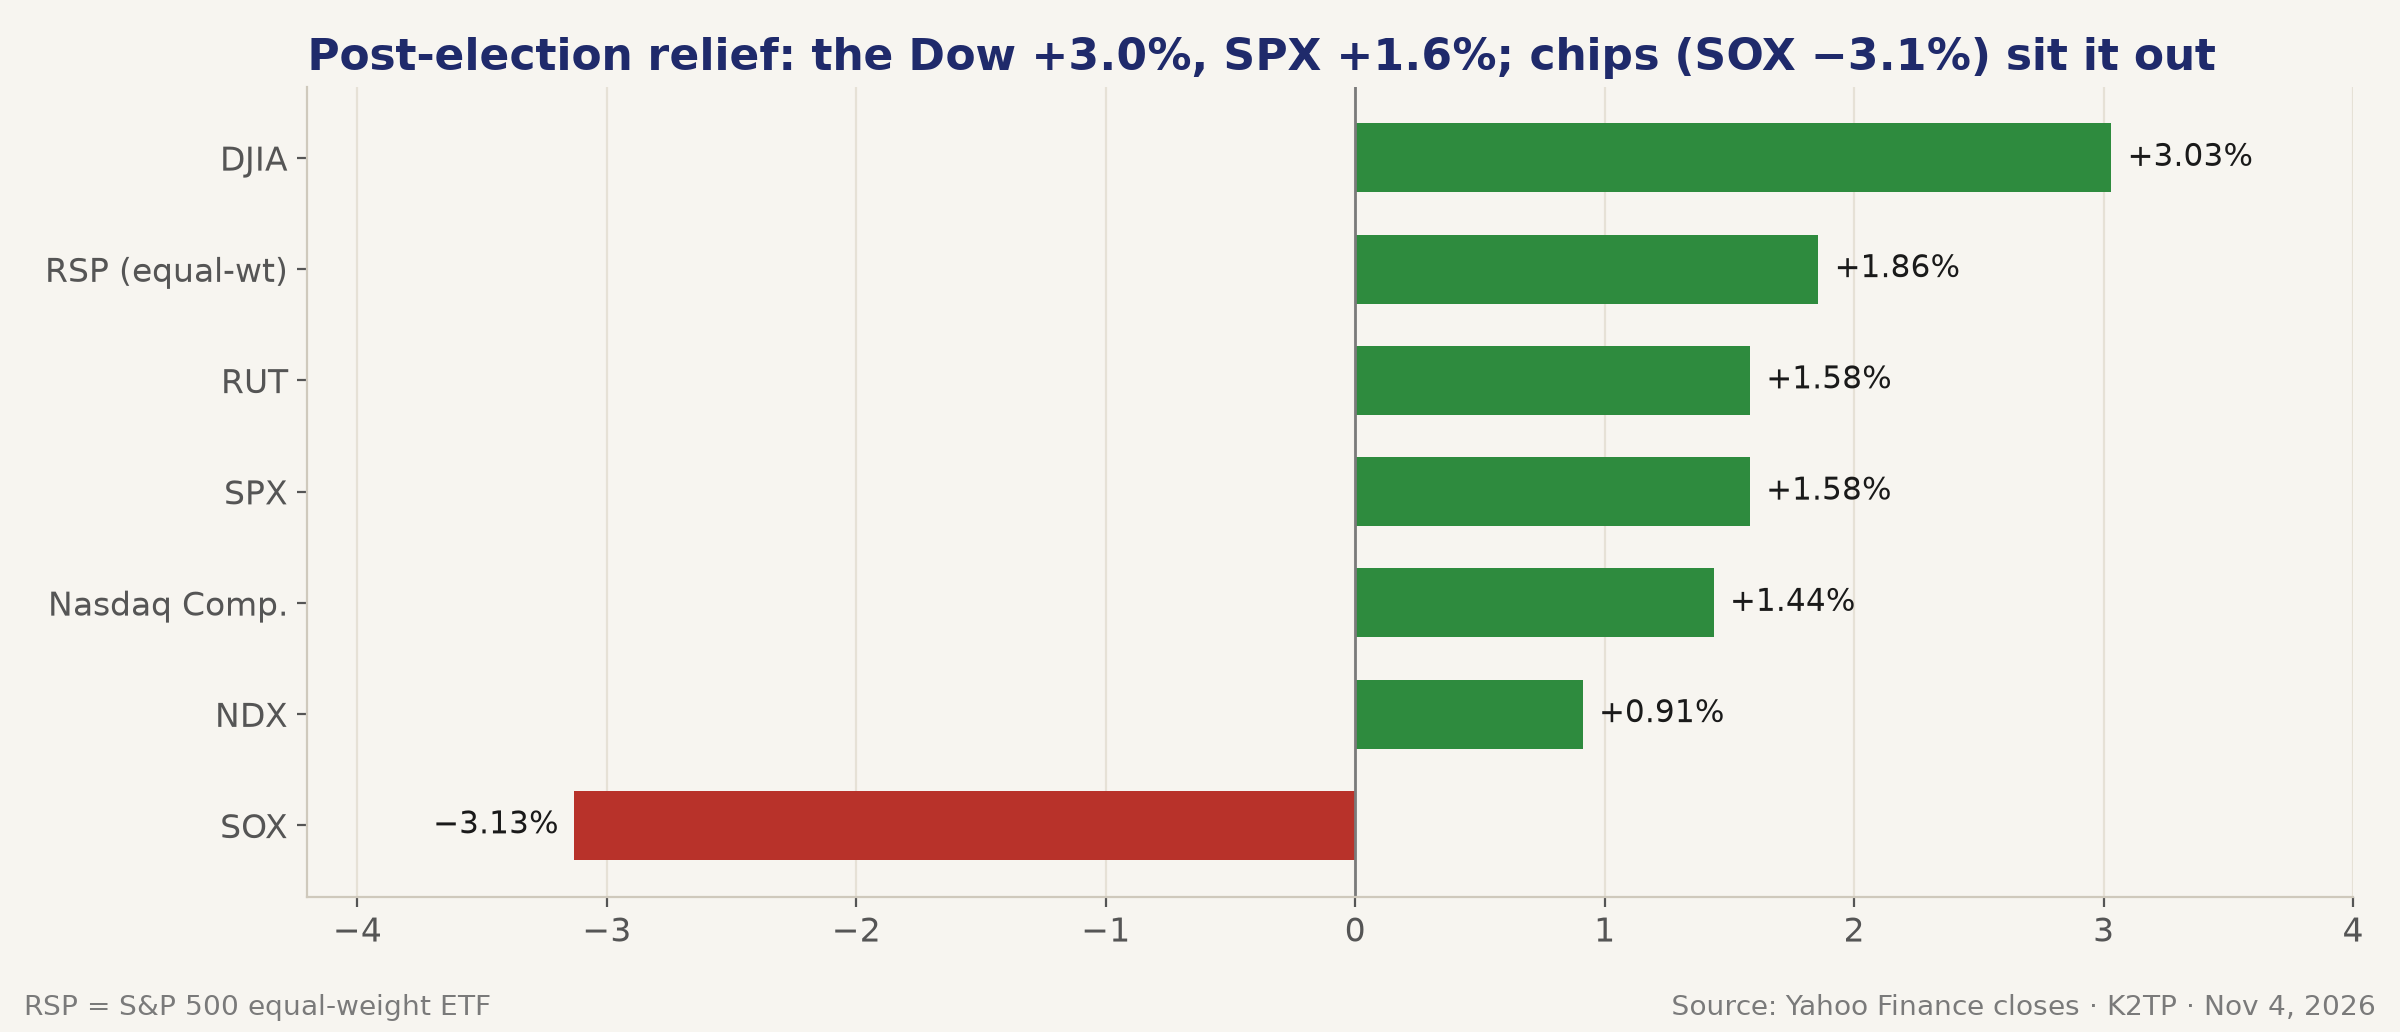
- SPX +1.58% to 7,688.62 (range 7,635.81–7,715.57); DJIA +3.03% to 53,356.12; NDX +0.91% to 28,437.17; RUT +1.58% to 2,856.95; Nasdaq Composite +1.44%
- Volatility collapses: VIX −20.26% to 16.61 (low 16.57); VIX9D 15.19 is back under VIX3M 18.80, so the curve is in contango again; VVIX −15.82% to 90.41
- Broad breadth: RSP +1.86% beats SPX; 8 of 11 sectors up, led by XLY +4.26%, XLC +3.47%, XLF +3.51% and XLP +3.36%
- Leadership split: MSFT +6.68%, AMZN +6.12%, AAPL +5.31%, GOOGL +3.18%; chips fall with SOX −3.13% (STX −8.13%, MU −7.00%, WDC −6.77%, ARM −5.28%, NVDA −3.17%)
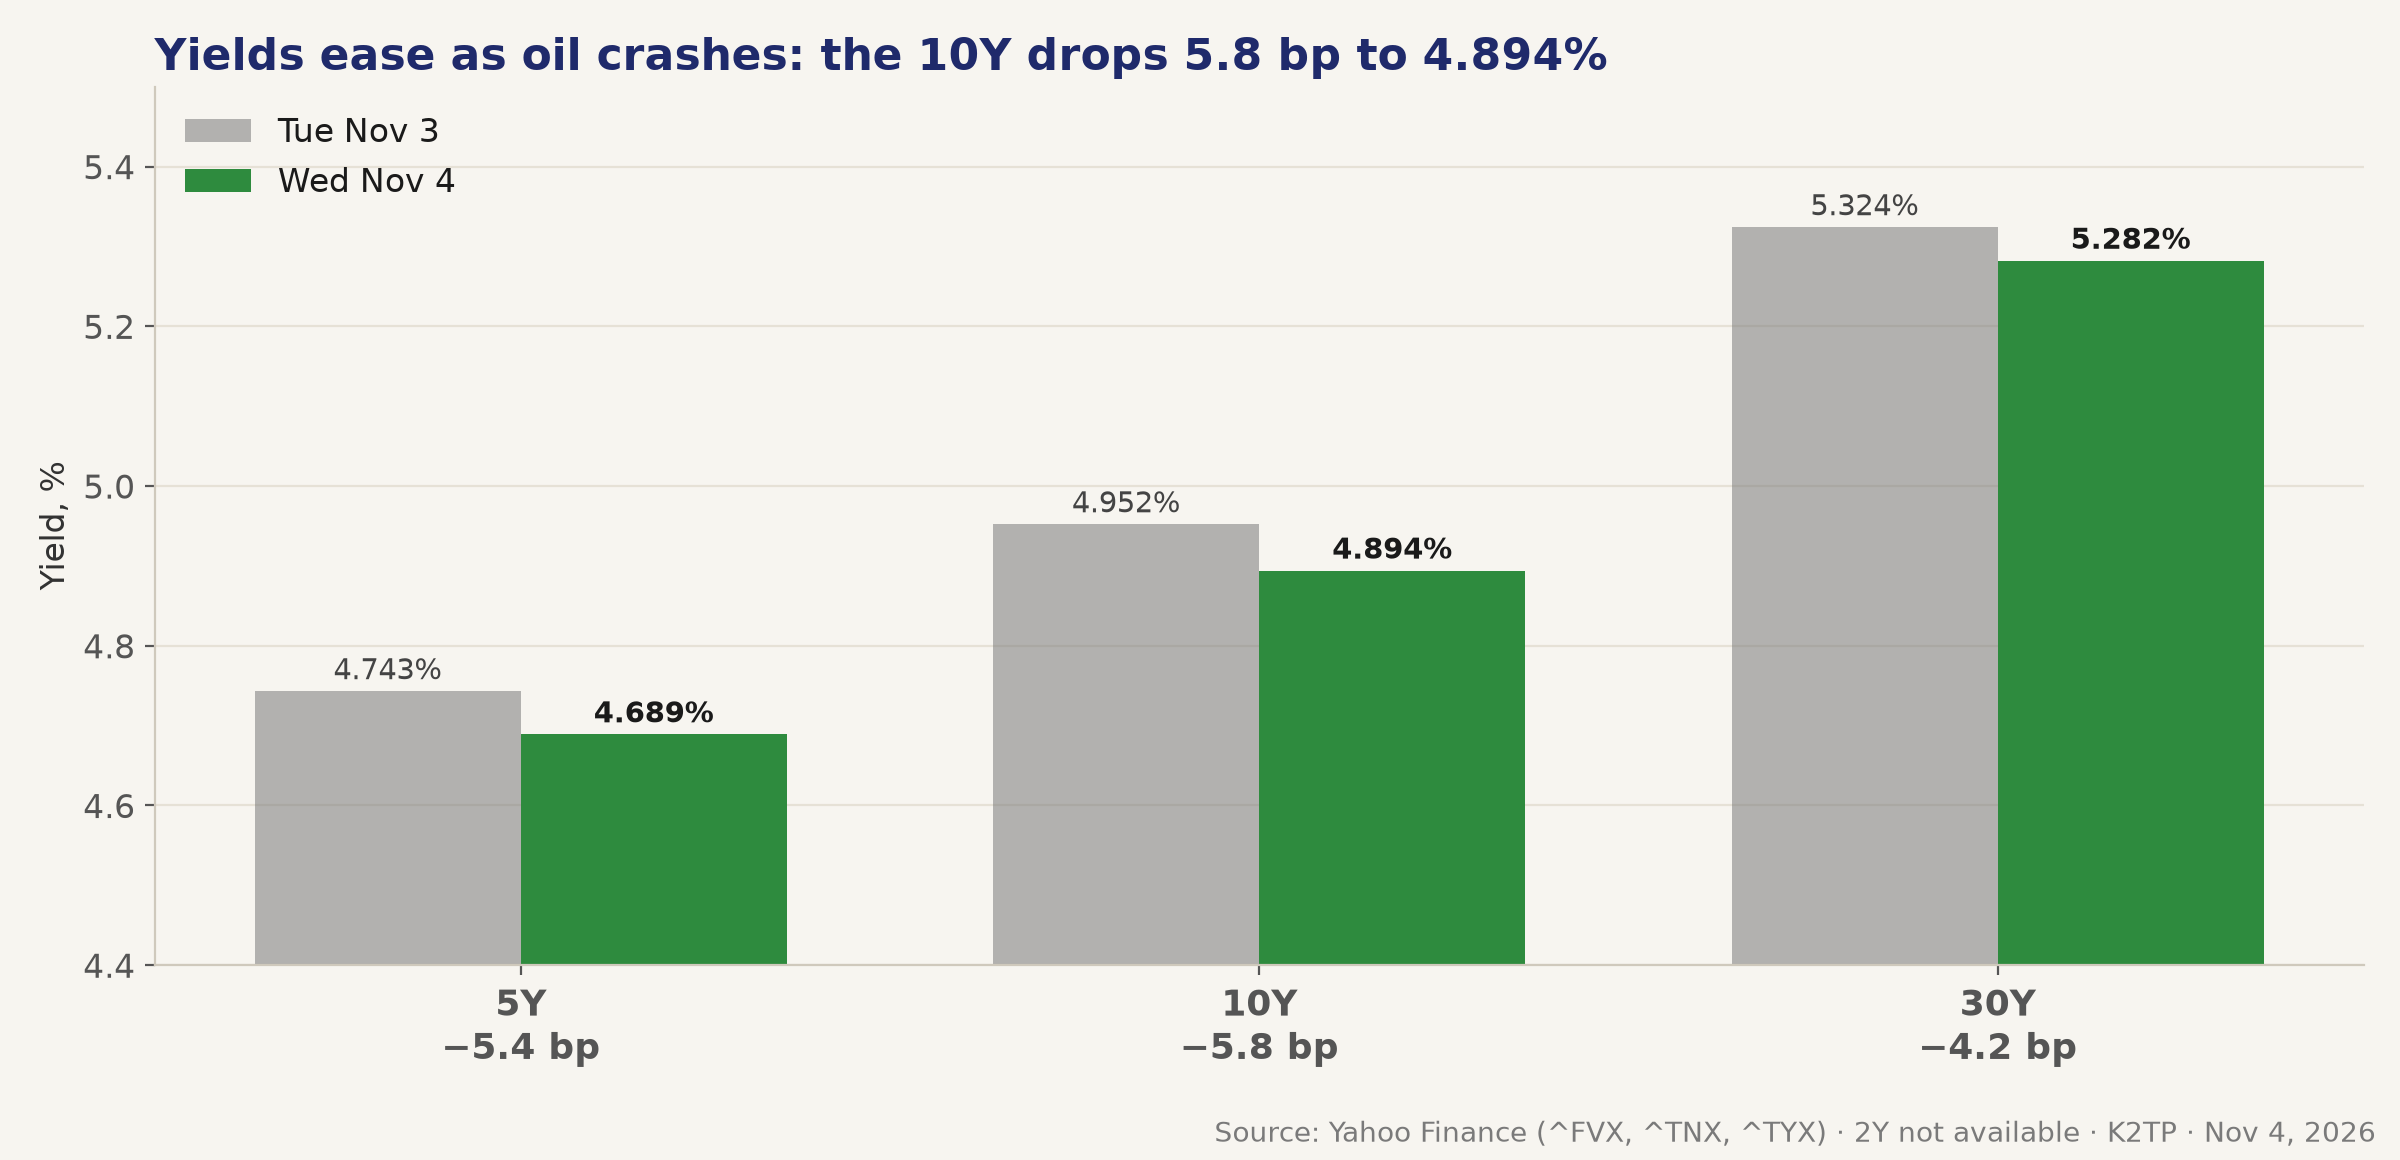
- Data: ADP 86K vs 67K expected; ISM Services 54.5 vs 54.8 with prices paid 73 vs 74.6; the 10Y falls to 4.894% and the 5Y to 4.689%
- After hours: APP (8-K Ex. 99.1) revenue $2,185M (+55% Y/Y), diluted EPS $4.30, Q4 revenue guide $2,365–2,395M, about +23%; QCOM non-GAAP EPS $2.17 vs $2.16 but the Q1 EPS guide of $2.15–2.35 is below about $2.32 expected, about −7.7%; ARM beats, about −2%
- FedWatch: a December 25 bp hike is now priced at about 81.5%, up from about 76.9% earlier
- Regime: 🟡 TRANSITION pre-market → 🟢 RISK-ON at midday, pre-close and the Evening Recap
- Thursday: jobless claims and productivity at 5:30 AM PT, Hammack around 5:50 AM PT; payrolls Friday 5:30 AM PT
THE ELECTION AFTERMATH: MARKETS READ IT AS AN END TO THE WAR
- Overnight, ES fell as much as 1.4% (NQ as much as 2.4%) to a 7,490 low, then turned positive after Trump accepted the results; at 5:30 AM PT ES was 7,667.25 (+0.93%) and implied SPX was about 7,639
- Jeffries says Democrats will win at least 255 House seats; Schumer says "we will end the war"; Vance says "the reason we lost is the war"
- CBS reported Trump was asking advisers whether Defense Secretary Hegseth should go; by the afternoon Trump said he is not replacing him
- Trump said "the Iran war will end whenever I want it to" and that price, not the war, cost the GOP the midterms; he later said the loss was "largely" about the war but "worth it"
- Al-Jadeed, citing Arab diplomats, says US-Iran talks made significant progress and will be clearer on Friday (unconfirmed)
- Pre-market policy trade: TSLA −4.46%, PLTR −4.67%, ORCL −3.60%, DJT −10.92%, solar names about +8%; at the close DJT −24.54%, LMT −6.88%, FSLR +4.63%, UNH +1.22%
→ The Democratic Senate was the bear case on Tuesday night, yet the market chose to read it as pressure to end the Iran war: oil and VIX fell, and money spread into the rest of the market. The shift from 🟡 TRANSITION to 🟢 RISK-ON was in place by midday.
OIL CRASHES 8%: ENERGY SINKS, CONSUMERS RALLY
- WTI −7.71% to $88.68 at midday, settled $88.12 (−8.29%); Brent settled $94.62 (−8.67%), its lowest since August 31; WTI traded near $87.03 in the evening
- That came despite EIA crude stocks falling 0.865M barrels (forecast −1.7M) and distillates −3.565M; the UAE is weighing a third pipeline to bypass the Strait of Hormuz
- The Treasury added shadow-fleet sanctions and Bessent warned of more; Iranian state media said a US MQ-1 drone was shot down over Qeshm Island (unconfirmed)
- Energy: XLE −4.74%, XOM −4.62%, CVX −3.69%; lower fuel costs lift XLY +4.26% (HD +6.53%, NKE +5.22%) and XLP +3.36% (WMT +3.45%, EL +6.31%)
→ The market is pricing out the war premium in oil fast. Lower oil feeds into lower yields and supports consumer names, the same chain that runs in reverse when oil rises.
YIELDS FALL ON A COOLER ISM SERVICES
- 5:15 AM PT: ADP 86K vs 67K expected (prior 90K); MBA 30-year mortgage rate 7.30%
- 7:00 AM PT: ISM Services 54.5 vs 54.8 expected (prior 54.9); prices paid 73 vs 74.6, new orders 55.9 vs 58.5, employment 51.4 vs 50; S&P Global services PMI final 56.1 vs 57.9
- Closing yields: 5Y 4.689% (−5.4 bp), 10Y 4.894% (−5.8 bp), 30Y 5.282% (−4.2 bp); 5s30s about 59.3 bp; the 2Y close is unavailable
- The Treasury accepted $6B in a buyback of 2037–2046 coupons ($39.636B offered); ECB's Kazaks said rates may need to rise gradually
- FedWatch: a December hike at about 81.5% (hold about 18.5%), up from about 76.9% earlier
→ Softer services prices and lower oil pulled yields down even though the odds of a December hike went up. For stocks, the oil and VIX drop mattered more than the Fed odds on Wednesday; payrolls on Friday will test that.
BIG TECH PLATFORMS LEAD, CHIPS SINK
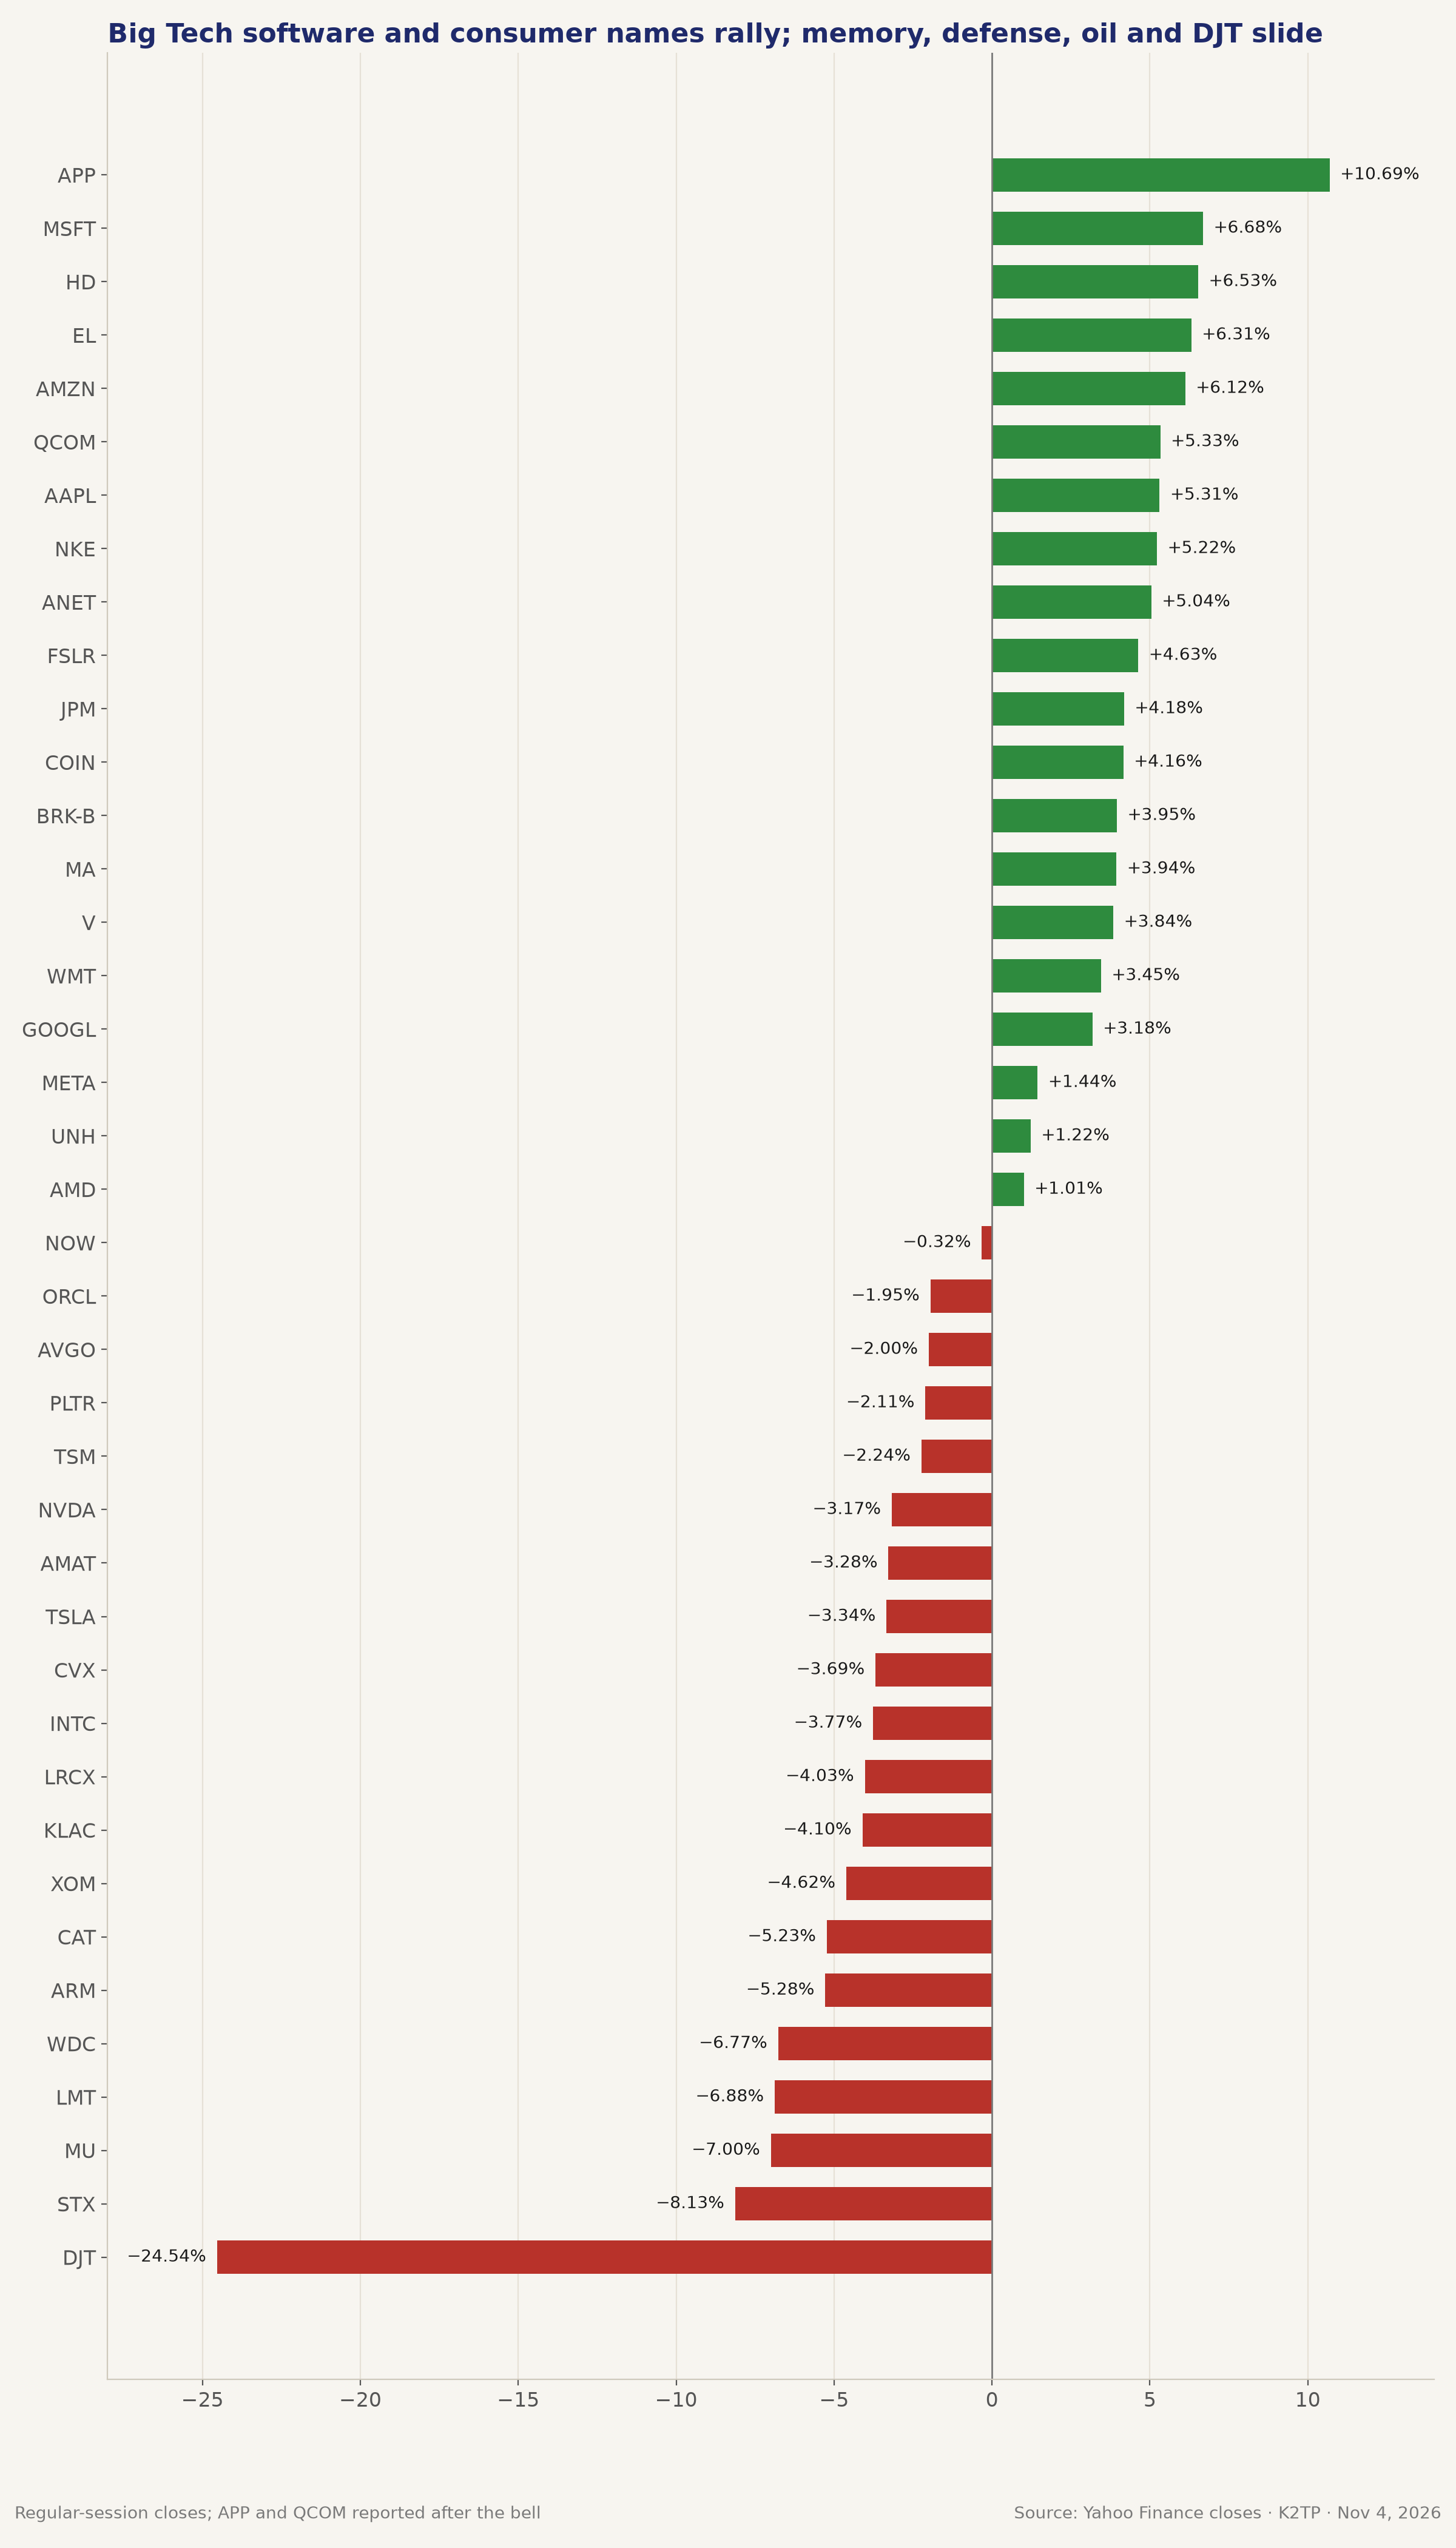
- Mega-caps: MSFT +6.68% to 555.80, AMZN +6.12%, AAPL +5.31%, GOOGL +3.18%, META +1.44%
- Chips: SOX −3.13% (low 10,064.73); STX −8.13%, MU −7.00%, WDC −6.77%, ARM −5.28%, KLAC −4.10%, LRCX −4.03%, INTC −3.77%, AMAT −3.28%, NVDA −3.17%, TSM −2.24%, AVGO −2.00%
- AMD traded as high as 514.61 after Tuesday's beat but closed only +1.01% at 488.78; BofA cut its target to $650 from $720
- Financials and payments: JPM +4.18%, BRK-B +3.95%, MA +3.94%, V +3.84%, COIN +4.16%
- Apple is cutting internal AI usage budgets (some engineers' daily cap cut to $200 from $300); Axios reports Meta is buying AI startup Conductor
- Flows: the market-on-open imbalance was a 131.5M-share buy for the S&P 500 but a 28.7M-share sell for the Nasdaq 100; CNN Fear & Greed was 29/100 at 7:19 AM PT
→ Money is rotating out of this year's AI hardware winners (memory, storage, chip equipment) into the mega-cap platforms and the broader market. That is why NDX (+0.91%) trails SPX (+1.58%) and the Dow (+3.03%).
8 OF 11 SECTORS UP: A BROAD RALLY
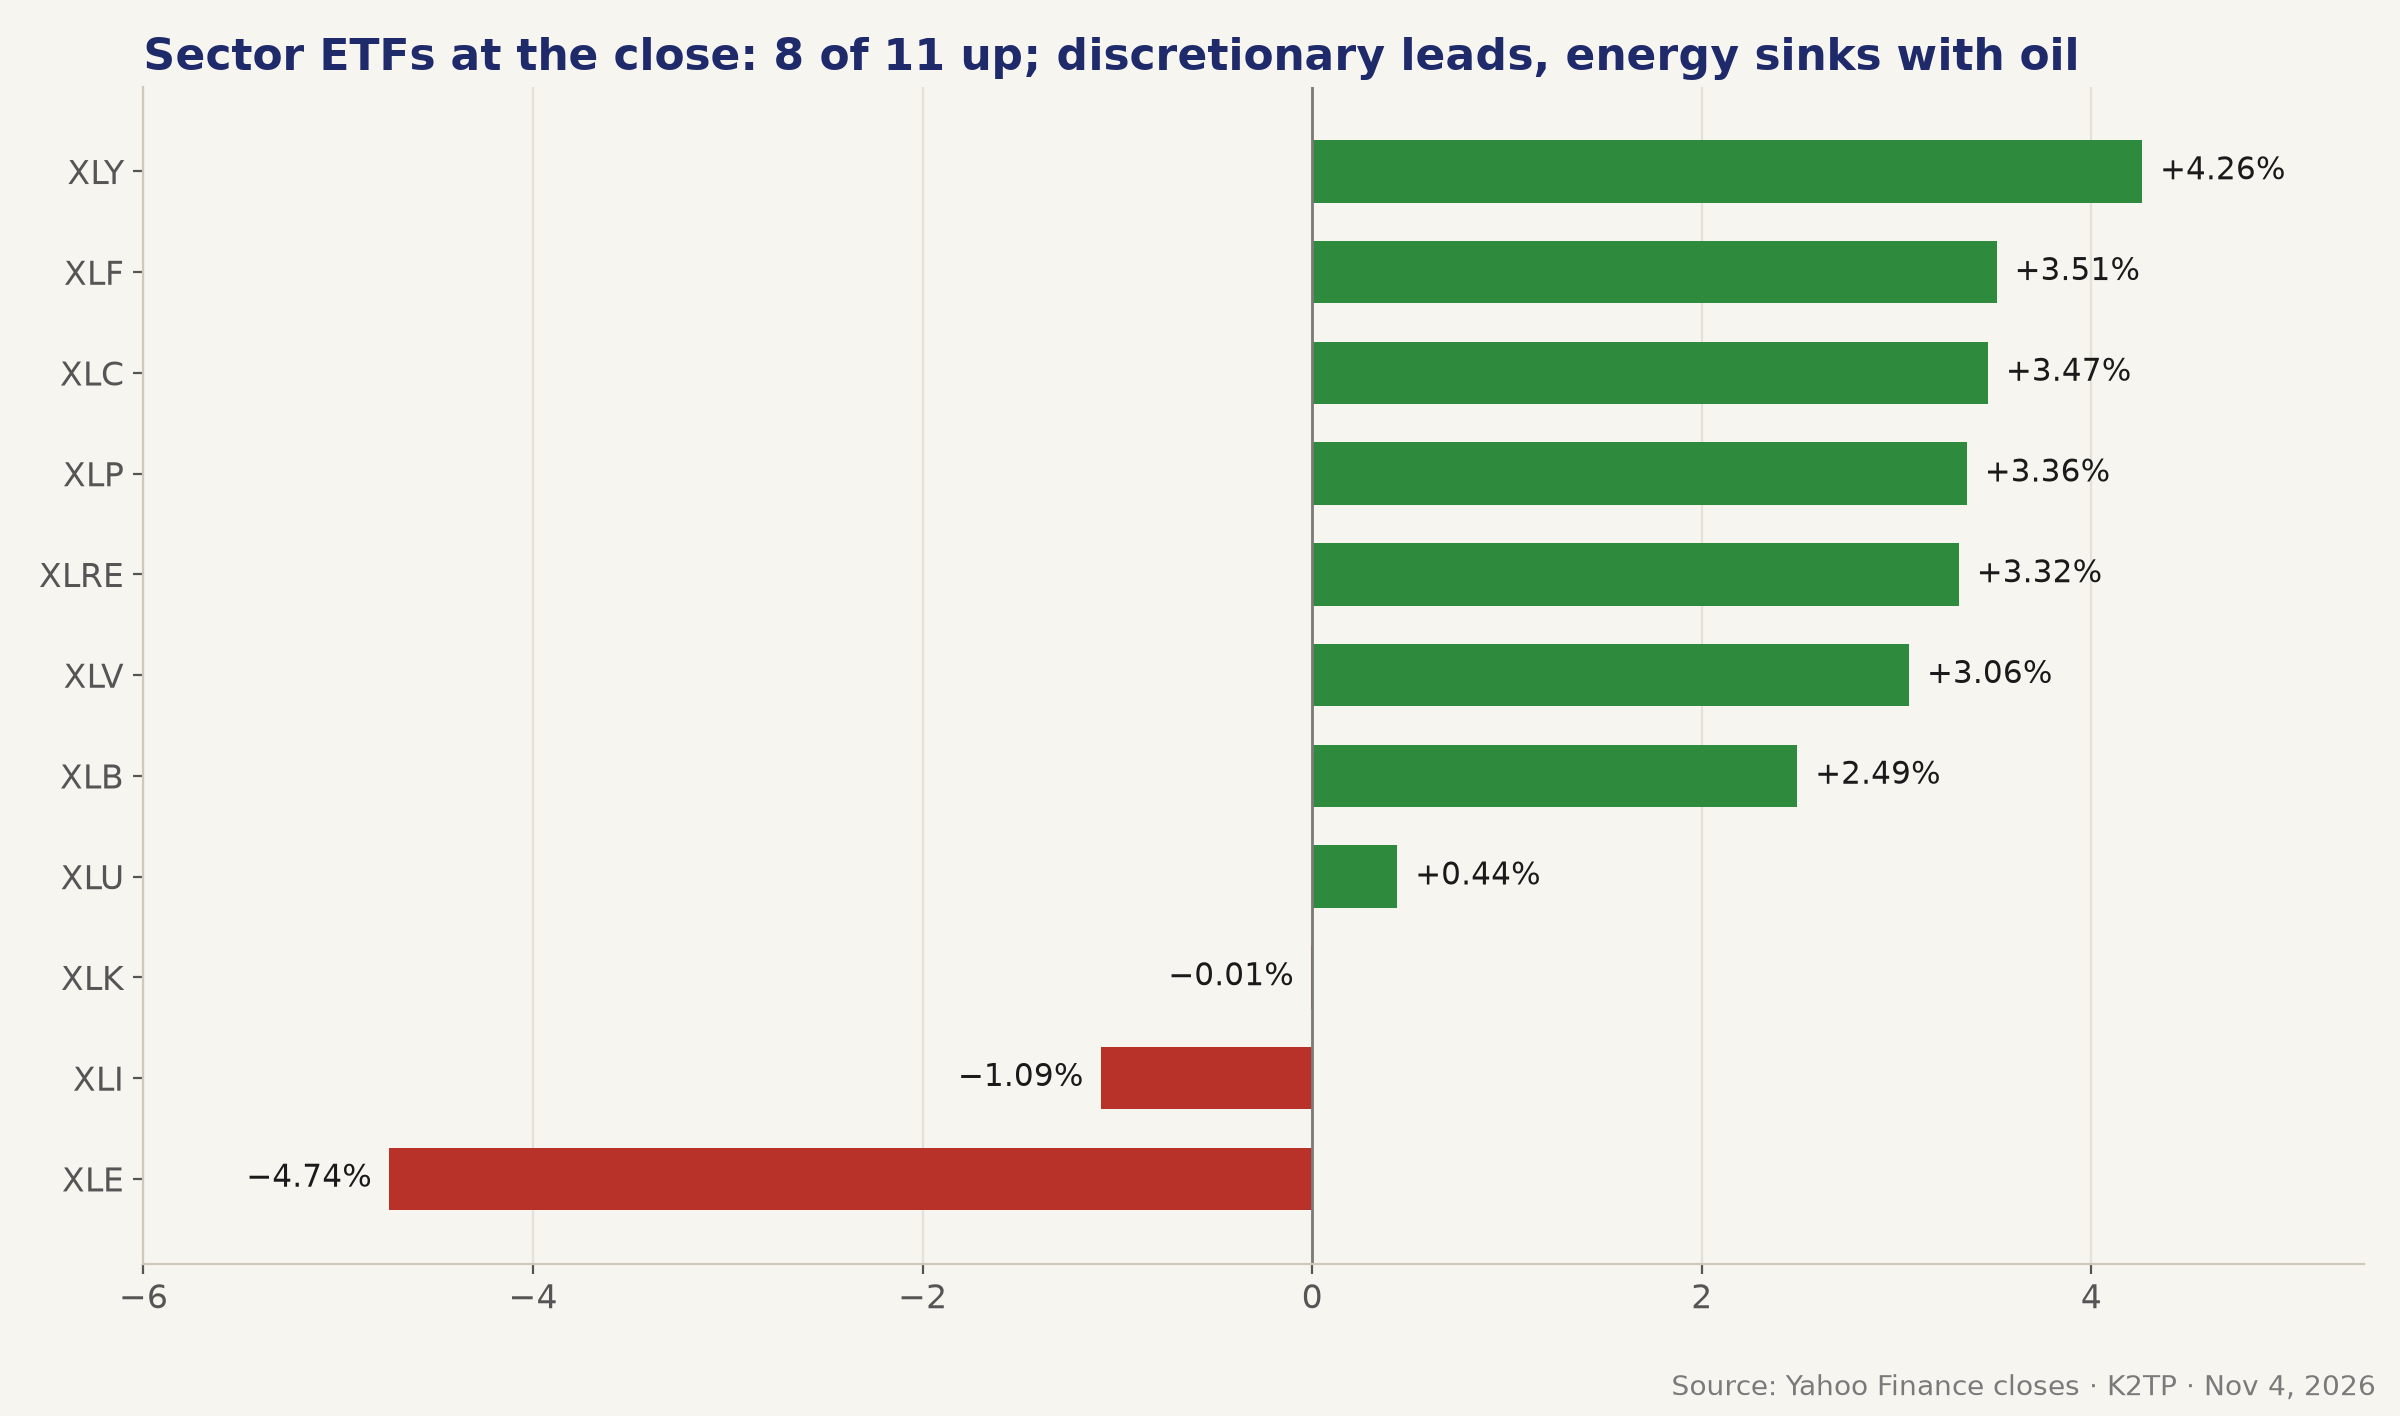
- Up: XLY +4.26%, XLF +3.51%, XLC +3.47%, XLP +3.36%, XLRE +3.32%, XLV +3.06%, XLB +2.49%, XLU +0.44%; down: XLK −0.01%, XLI −1.09%, XLE −4.74% 🟢
- RSP +1.86% vs SPX +1.58%; SPY +1.65%, QQQ +0.97%, IWM +1.51%
- XLI is hurt by defense and machinery (LMT −6.88%, CAT −5.23%); XLK is flat because chip losses offset MSFT and AAPL
→ Unlike Tuesday, this is a rally that most stocks joined. The equal-weight index beating SPX is the strongest sign that the regime has really moved to RISK-ON.
APP SOARS, QCOM SLIDES ON ITS GUIDE
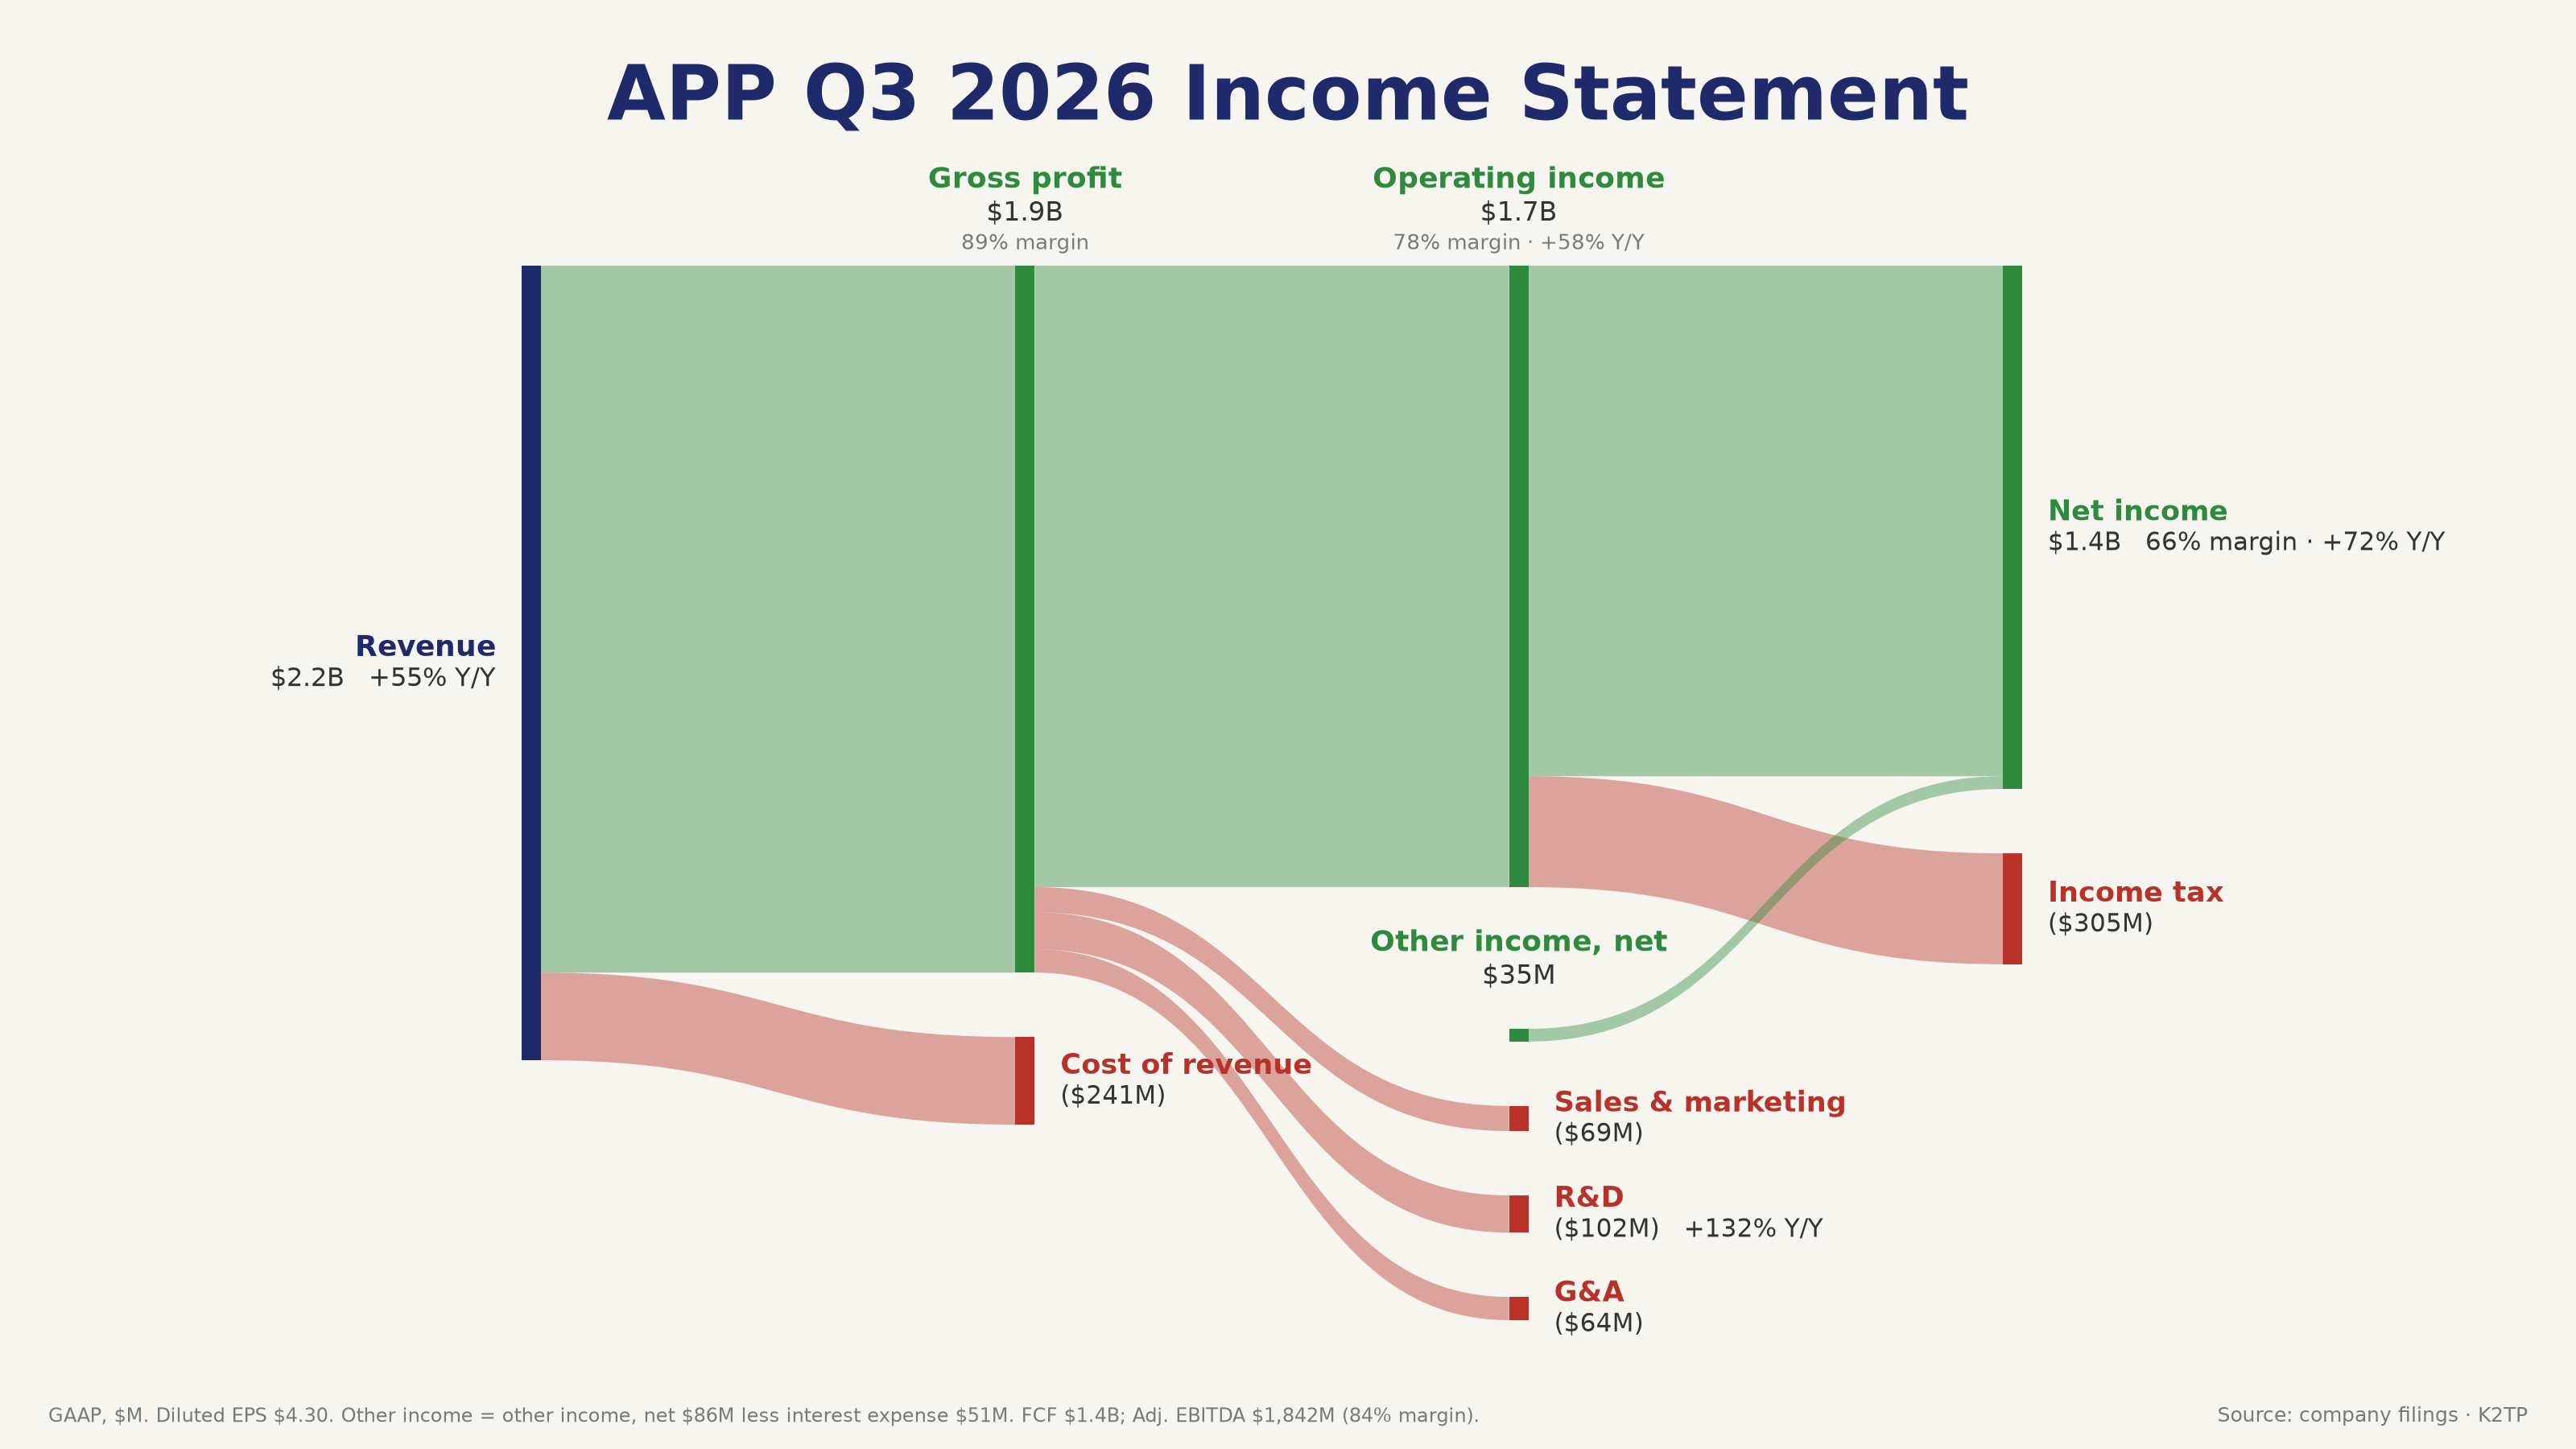
- AppLovin (APP, 8-K Ex. 99.1, Q3 2026): revenue $2,185M (+55% Y/Y) vs about $2.08B expected; gross profit $1,944M (89% margin); operating income $1,709M (78% margin, +58% Y/Y); net income $1,439M (+72%), diluted EPS $4.30 🟢
- APP Q4 guide: revenue $2,365–2,395M vs about $2.25B expected, adjusted EBITDA $1,995–2,025M (84–85% margin); FCF $1.4B in Q3; buybacks of $1.4B in the quarter and the authorization raised by $3.2B to $3.6B
- APP closed +10.69% at 271.75 and traded about +23% after hours near $333.80
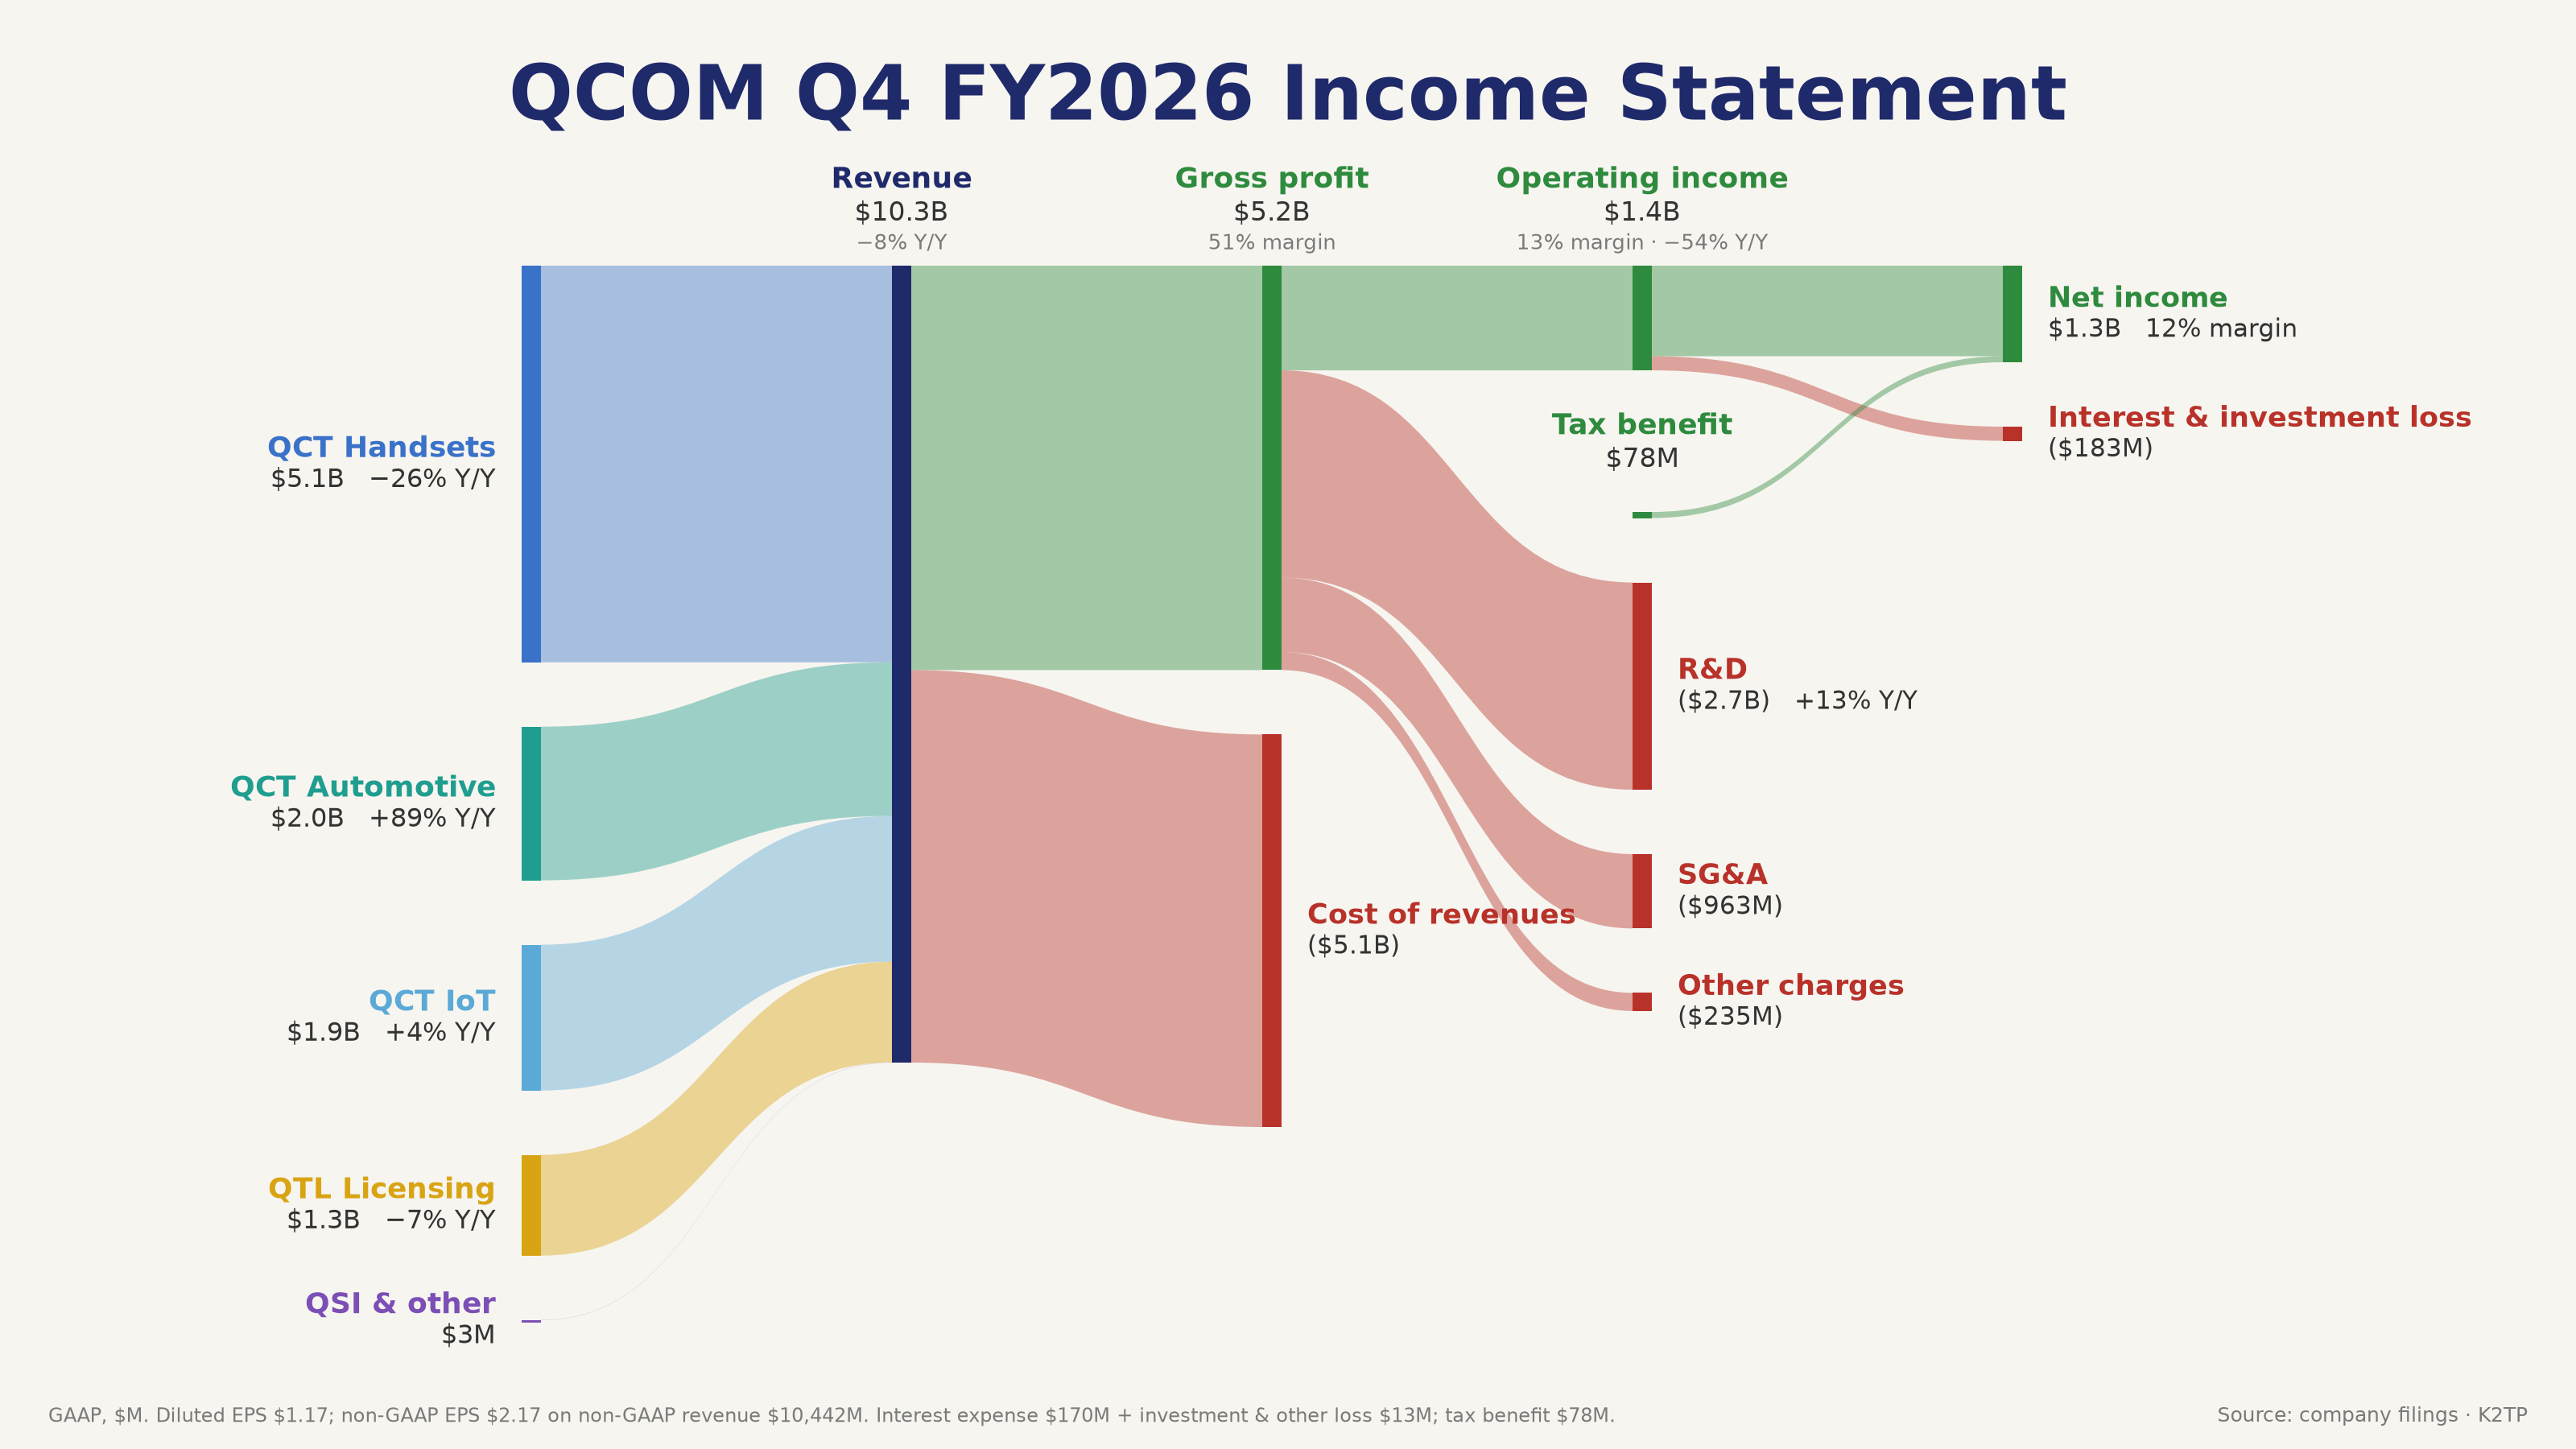
- Qualcomm (QCOM, 8-K Ex. 99.1, Q4 FY2026): GAAP revenue $10,322M (−8% Y/Y); non-GAAP revenue $10,442M vs about $10.12B expected; non-GAAP EPS $2.17 vs $2.16, GAAP EPS $1.17 🟡
- QCT revenue streams: Handsets $5,137M (−26% Y/Y), Automotive $1,990M (+89%), IoT $1,888M (+4%); QTL licensing $1,304M (−7%)
- GAAP operating income $1,356M (13% margin, −54% Y/Y); R&D $2,684M (+13%)
- Q1 FY27 guide: revenue $10.4–11.2B, non-GAAP EPS $2.15–2.35 vs about $2.32 expected; Qualcomm says industry input costs are rising and it expects the full benefit of its price increases to show in QCT gross margins only in the second half of fiscal 2027
- QCOM closed +5.33% at 173.19 and traded about −7.7% after hours near $160.37
- ARM: adjusted EPS $0.52 vs $0.47, revenue $1.44B vs $1.38B, royalty revenue $773M vs $707M; about −2% after hours near $188.47 after −5.28% in the session
→ APP's beat-and-raise is a strong signal for ad-tech software, but QCOM's guide and its warning about input costs add more pressure on chips, which were already the weak spot of the day. That is why NQ (−0.54%) is weaker than ES (−0.09%) tonight.
SPX: A GAP UP FROM THE OPEN, HIGH AT 10:05 AM, A SOFT CLOSE
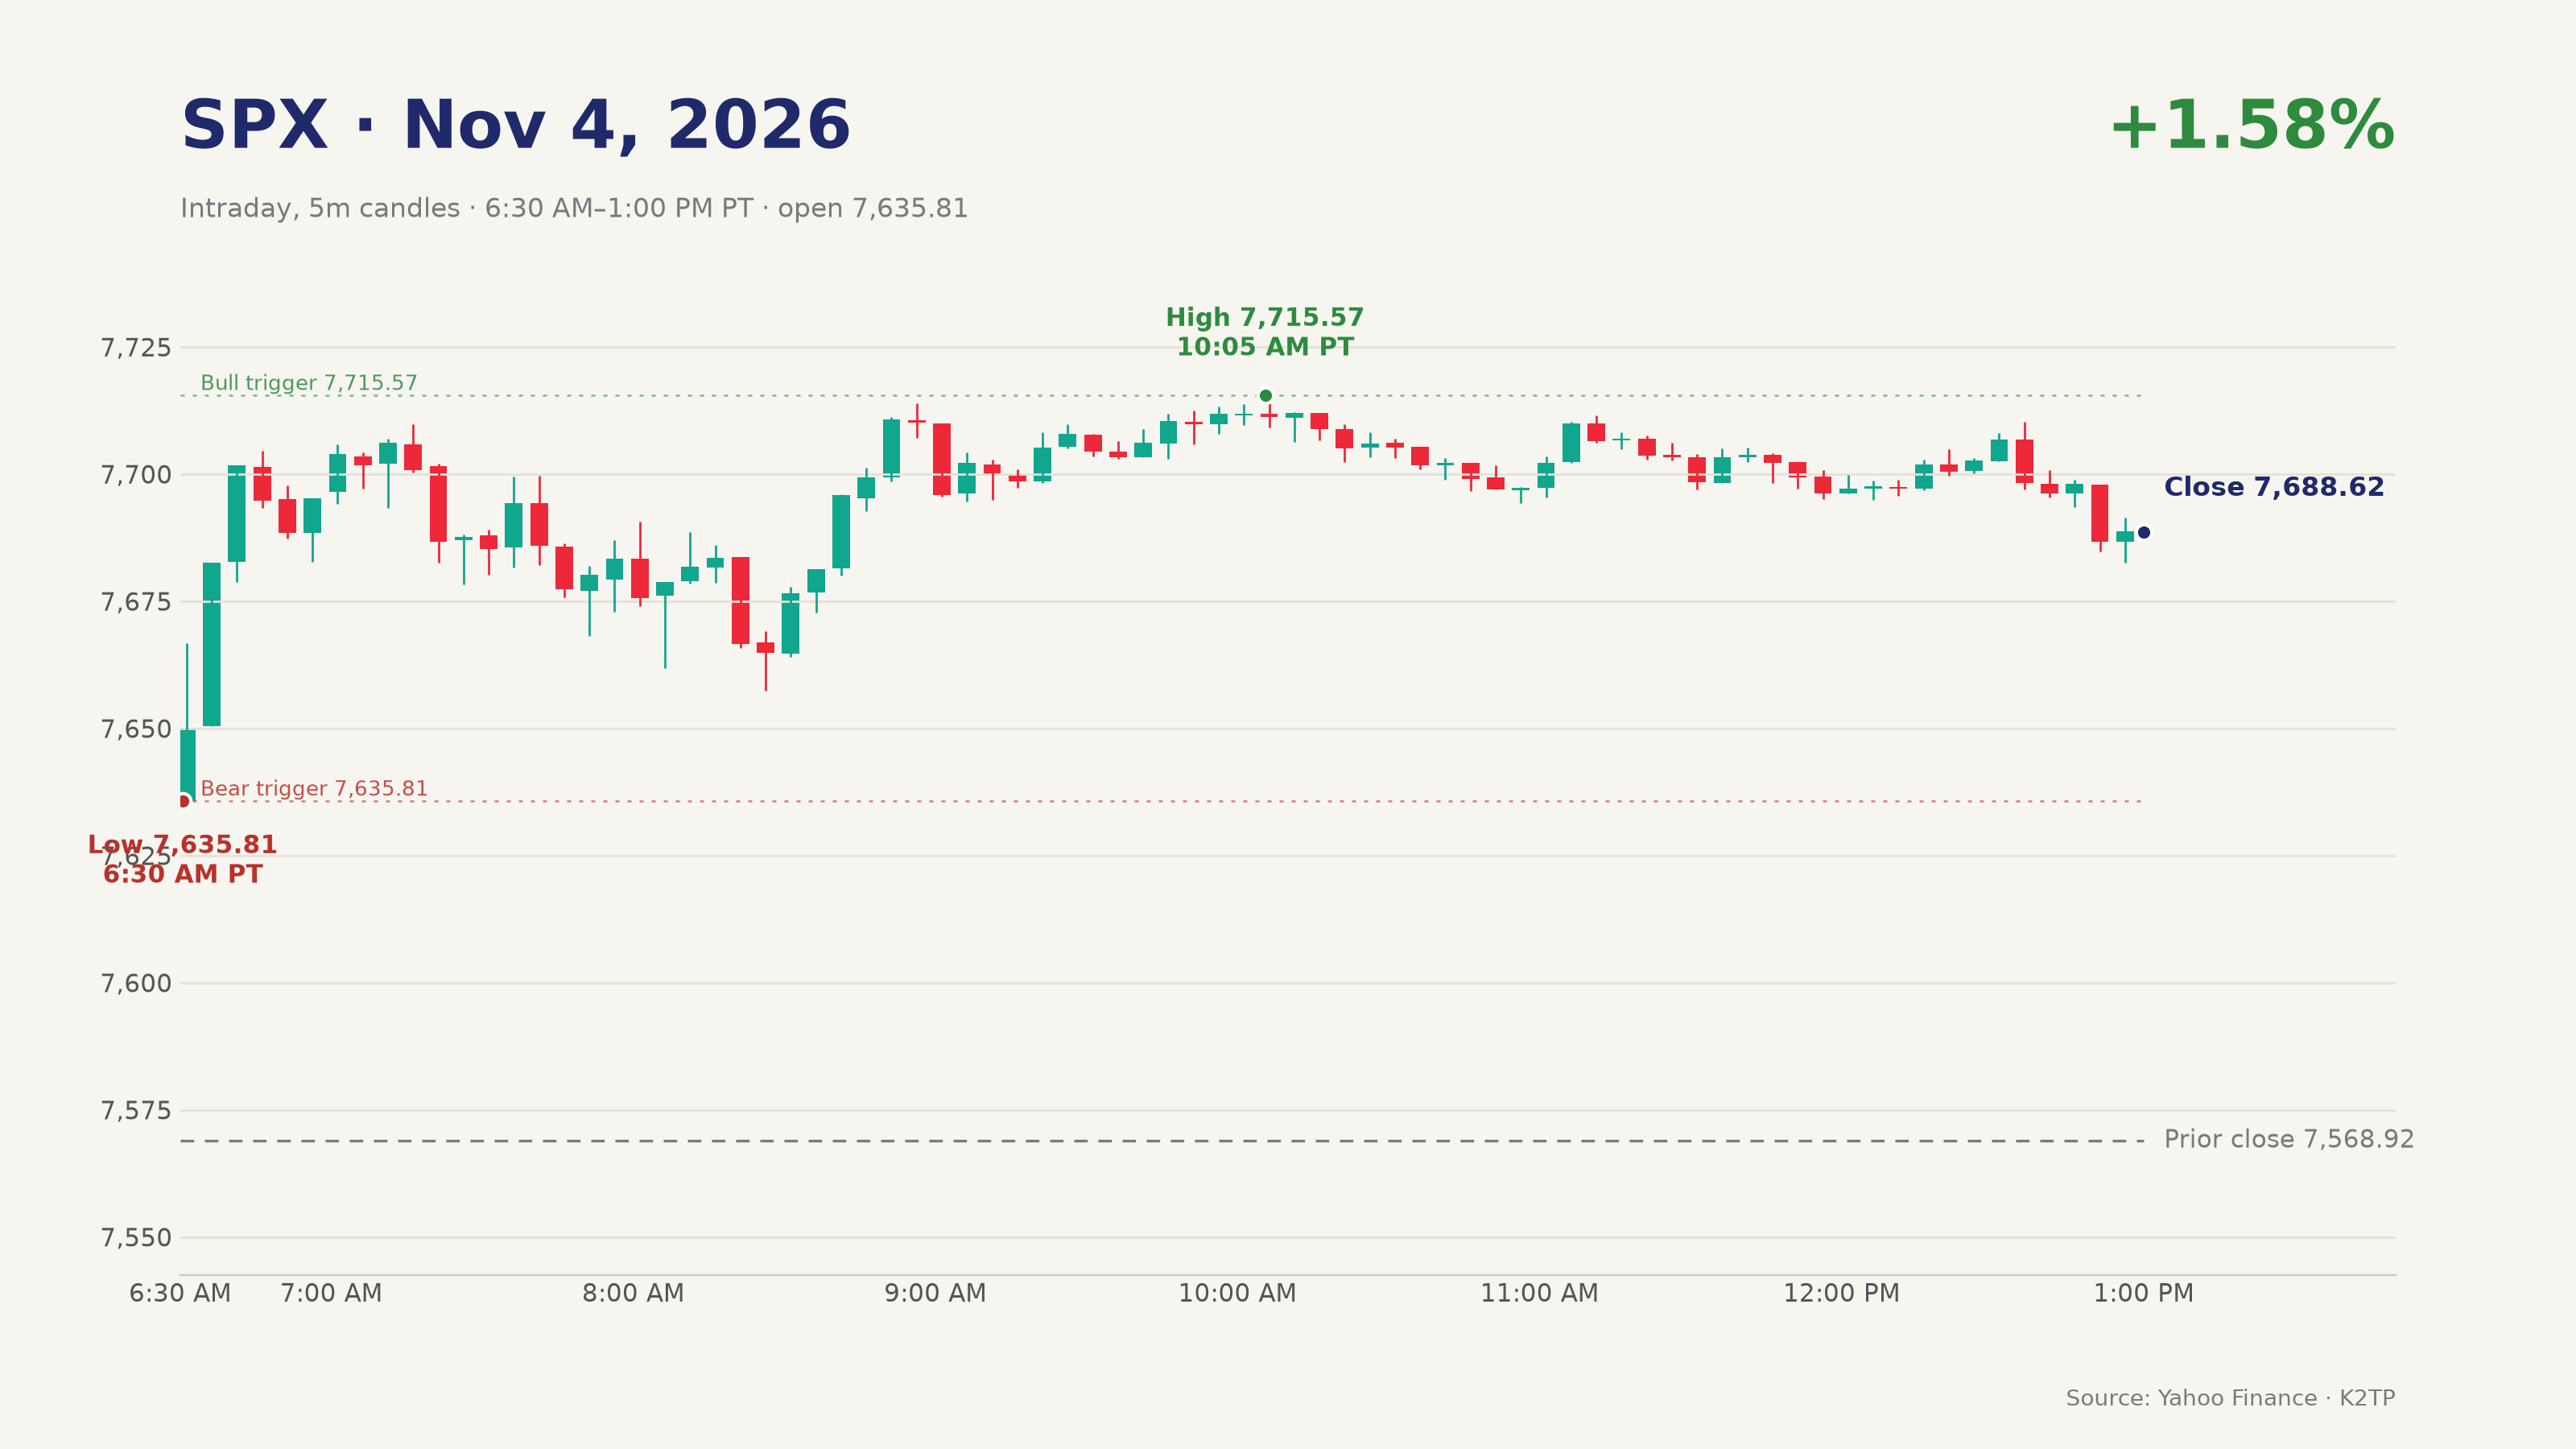
- Pre-market: ES +0.93%, implied SPX about 7,639; the Bull line was SPX above 7,662.23 with VIX under 18.03
- SPX opened at its 7,635.81 low at 6:30 AM PT and reached 7,704.64 by 6:45 AM PT; both halves of the pre-market Bull line were met
- A dip to 7,657.38 around 8:25 AM PT, then a run to the 7,715.57 high at 10:05 AM PT
- It held between about 7,695 and 7,712 through midday, was 7,698.10 at pre-close, then slipped to 7,682.56 around 12:55 PM PT and closed at 7,688.62
- No Bear line came close: SPX never traded below 7,635.81
→ A gap-and-go day with no retest of the open. The close is 27 points under the high, a sign that buyers eased off into the after-hours earnings.
MARKET: A BROAD RISK-ON RALLY, CHIPS THE EXCEPTION
Indices (close):
- SPX 7,688.62 (+1.58%), range 7,635.81–7,715.57
- NDX 28,437.17 (+0.91%); Nasdaq Composite 25,736.51 (+1.44%)
- DJIA 53,356.12 (+3.03%)
- RUT 2,856.95 (+1.58%)
- RSP 223.33 (+1.86%)
- SOX 10,268.65 (−3.13%)
Intraday path: ES +0.93% pre-market after the overnight 7,490 low. SPX opened at 7,635.81 (the low), jumped to 7,704.64 by 6:45 AM PT, dipped to 7,657.38 around 8:25 AM PT, hit 7,715.57 at 10:05 AM PT, was 7,698.92 at midday and 7,698.10 at pre-close, and closed at 7,688.62.
Sector rotation:
- Up: XLY +4.26%, XLF +3.51%, XLC +3.47%, XLP +3.36%, XLRE +3.32%, XLV +3.06%, XLB +2.49%, XLU +0.44%
- Down: XLK −0.01%, XLI −1.09%, XLE −4.74%
- Mega-caps: MSFT +6.68%, AMZN +6.12%, AAPL +5.31%, GOOGL +3.18%, META +1.44%, AMD +1.01%, AVGO −2.00%, NVDA −3.17%, TSLA −3.34%
Market internals:
- RSP +1.86% vs SPX +1.58%; QQQ +0.97%, IWM +1.51%
- 8 of 11 sectors up, from 7 of 11 pre-market and 9 of 11 at midday and pre-close
- NYSE advance/decline at the close: unavailable
Volatility: 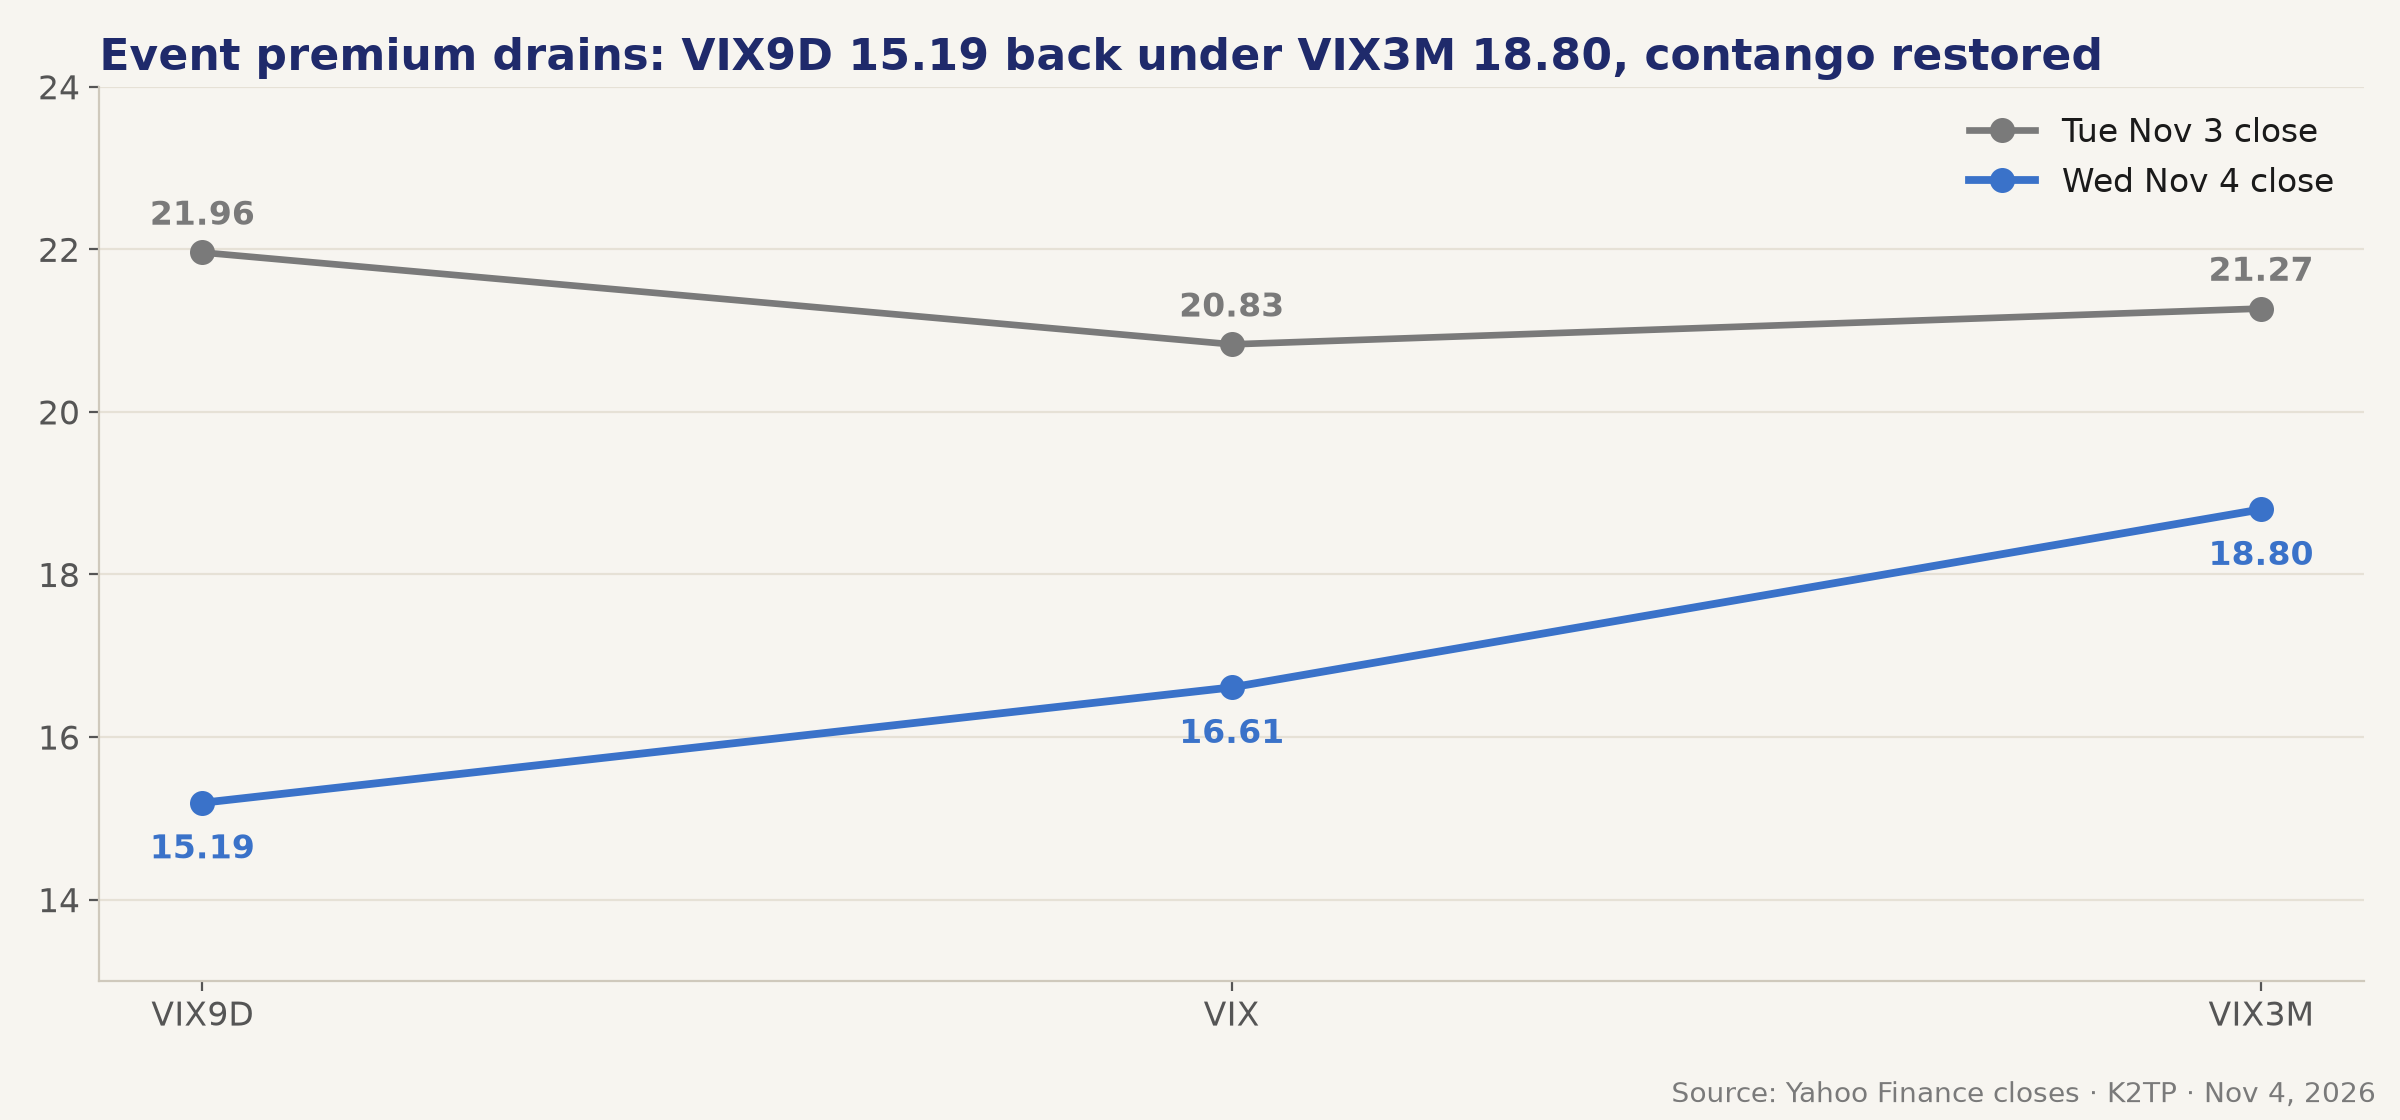
- VIX 16.61 (−20.26%), range 16.57–19.22
- VIX9D 15.19 (from 21.96), VIX3M 18.80 (from 21.27): the curve is back in contango
- VVIX 90.41 (−15.82%)
- Gamma levels: unavailable
Cross-asset:
- Yields: 5Y 4.689%, 10Y 4.894%, 30Y 5.282%; 13-week bill 4.025%; 2Y unavailable
- WTI settled $88.12, Brent $94.62; about $87.03 and $93.77 tonight
- Gold about $4,140 (+1.6%) tonight; DXY 101.27 (−0.23%); BTC about $80,500 (+4.1%)
Global:
- Europe: Euro Stoxx 50 +1.97%, DAX +2.22%, CAC 40 +1.96%, FTSE 100 +1.79%; Eurozone CPI 4.0%; the Riksbank hiked to 2%
- Asia, Thursday session: Nikkei −0.44%, Kospi −3.18%, Taiwan down more than 2%, Hang Seng +3.04%, Shanghai +0.09%; Japan services PMI 51.7 and hawkish BoJ minutes
Key SPX levels:
- 7,715.57: Wednesday's high; the Bull line is SPX above it with VIX under 16.57
- 7,688.62: Wednesday's close; ES 7,714.50 tonight
- 7,662.23: Monday's high, the breakout level from the morning
- 7,635.81: Wednesday's low and open; the Bear line is SPX under it with VIX above 18.30
- 7,568.92: Tuesday's close, the bottom of the gap
- VIX: 16.57 and 18.30
Option seller corner (Thursday):
- Vol has been crushed: VIX 16.61 and VIX9D 15.19 are well below Tuesday's levels, so premium is much cheaper than before the vote. Short premium now earns less, so be pickier about strikes and size.
- Bull scenario: SPX above 7,715.57 with VIX under 16.57; far-OTM SPX put spreads below 7,635.81 (Wednesday's low) are reasonable, with the gap at 7,568.92 as the deeper reference.
- Bear scenario: SPX under 7,635.81 with VIX above 18.30; then the unfilled gap toward 7,568.92 is the target. Defined-risk only; no naked puts into claims at 5:30 AM PT and payrolls on Friday.
- Single names: QCOM and ARM gapped down after earnings; put sellers should strike below the after-hours levels (about $160 and $188) and wait for the open to settle. APP implied vol will drop after the print, but a 23% gap up leaves a lot of room to fall; strike below the 271.75 close.
- Favor SPX over NDX: chips are the weak spot, and NQ is weaker than ES tonight.
BOTTOM LINE
- The market read the Democratic sweep as pressure to end the Iran war: oil fell 8%, VIX fell 20%, yields fell, and the Dow gained 3% with broad breadth (RSP +1.86%, 8 of 11 sectors).
- Chips are the exception (SOX −3.13%), and QCOM's guide after hours adds to that pressure, while APP surges.
- Regime 🟢 RISK-ON. 7,635.81 is the line to hold; above 7,715.57 with VIX under 16.57 the rally extends.
Watch Thursday (PT):
- Tonight: QCOM, ARM and APP after-hours moves; Asia led by Taiwan (−2%)
- 5:30 AM: initial jobless claims (197K expected vs 194K), Q3 productivity (about 2.5% expected) and unit labor costs (about 0.6%)
- About 5:50 AM: Fed's Hammack
- 6:30 AM: the cash open; whether chips stabilize after QCOM
- After 1:00 PM: ABNB, NET, TEAM and LITE earnings
- Friday 5:30 AM: October payrolls (65K expected vs 29K prior), unemployment 4.2%, average hourly earnings 0.3%; UMich at 7:00 AM
Bull expectation: oil stays soft, the 10Y holds near or under 4.90%, APP strength absorbs QCOM and ARM, and SPX holds above 7,715.57 with VIX under 16.57. Bear expectation: chip selling spreads to NVDA and AVGO, claims revive December hike fears, and SPX breaks 7,635.81 with VIX above 18.30.
Sources: 3 K2TP briefs for 11/4/2026 (Pre-Market, Midday, Pre-Close) and the 11/4 Evening Recap. Official closes, intraday data and futures from Yahoo Finance; data and headlines from FinancialJuice, CNBC and Business Wire; FedWatch from CME; Al-Jadeed and the Iranian drone report are unconfirmed. APP and QCOM Sankeys from each company's press release (8-K Ex. 99.1), SEC EDGAR. Analysis: K2TP Framework.