Market 10/27: Broadcom's $63B Anthropic deal keeps chips running and SPX clears Monday's high; Boeing sinks the Dow and oil slips under $100 before the FOMC
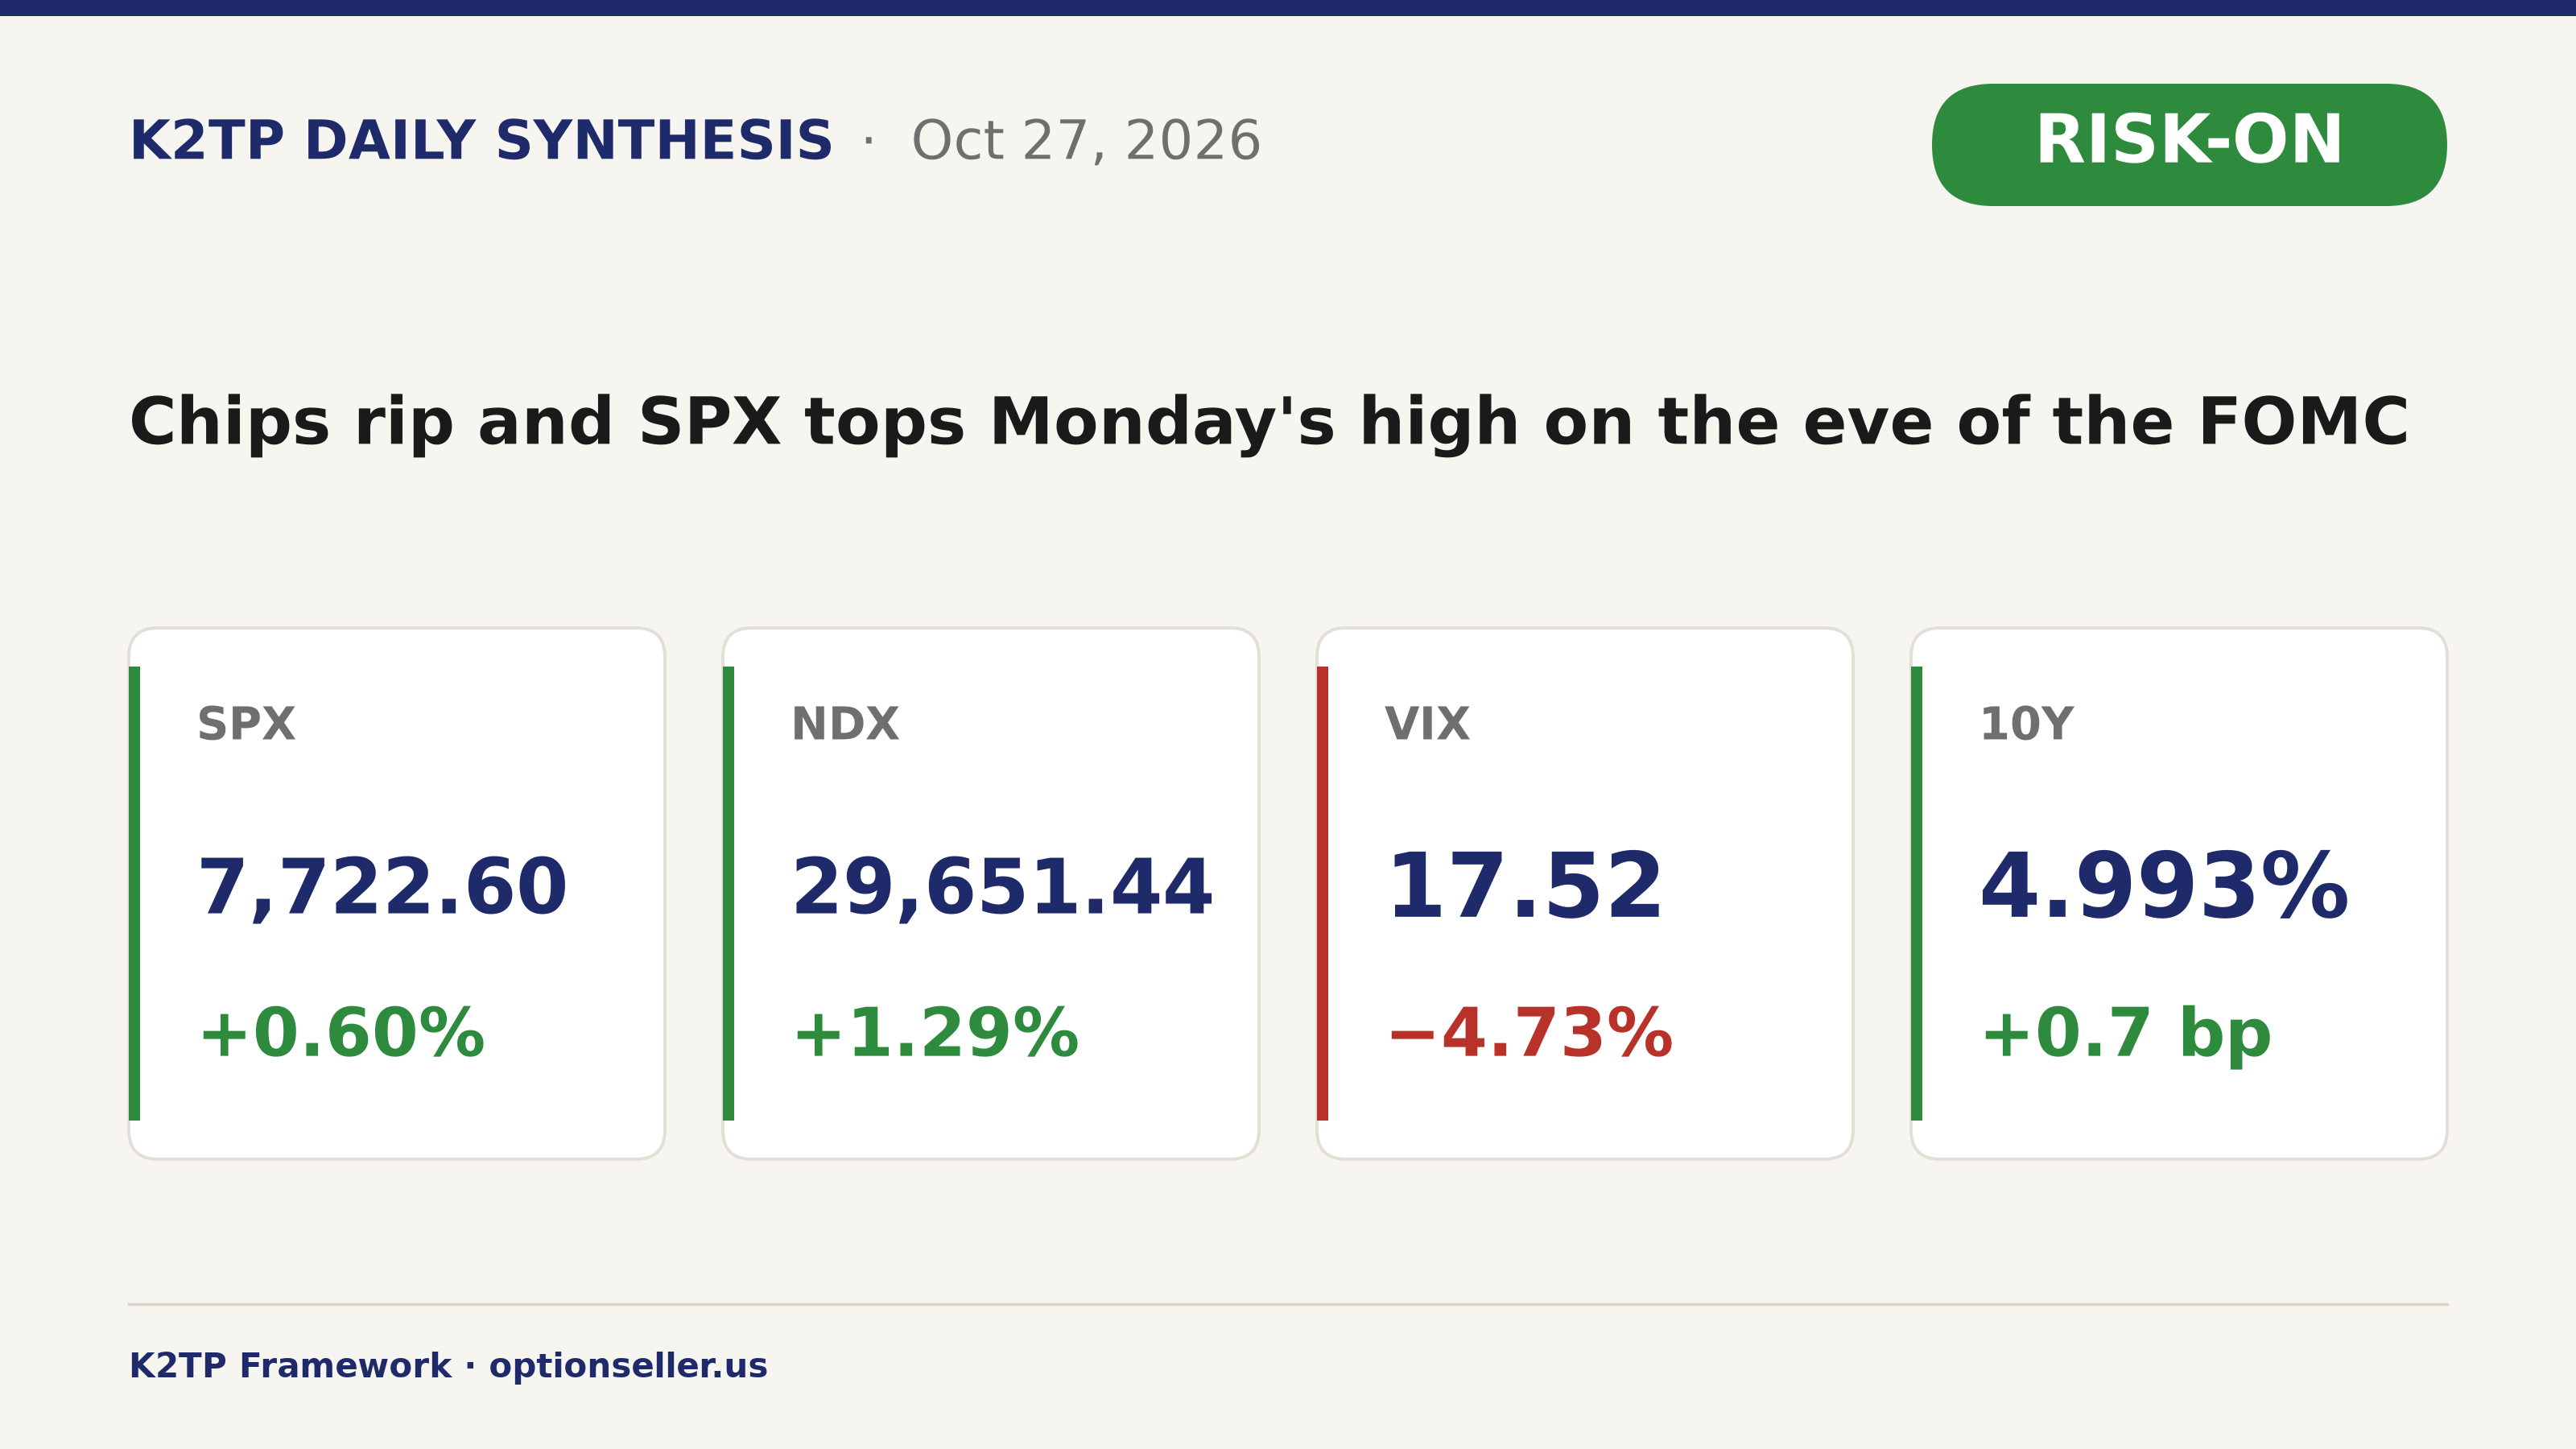
SPX +0.60%, NDX +1.29%, DJIA +0.03%, VIX −4.73% to 17.52. SOX +3.60% with AMD +5.45% and AVGO +4.00% in front; BA −10.69% and XYL −14.21% after earnings; December WTI settled at $99.90, its first settle under $100 in this run.
KEY HEADLINES
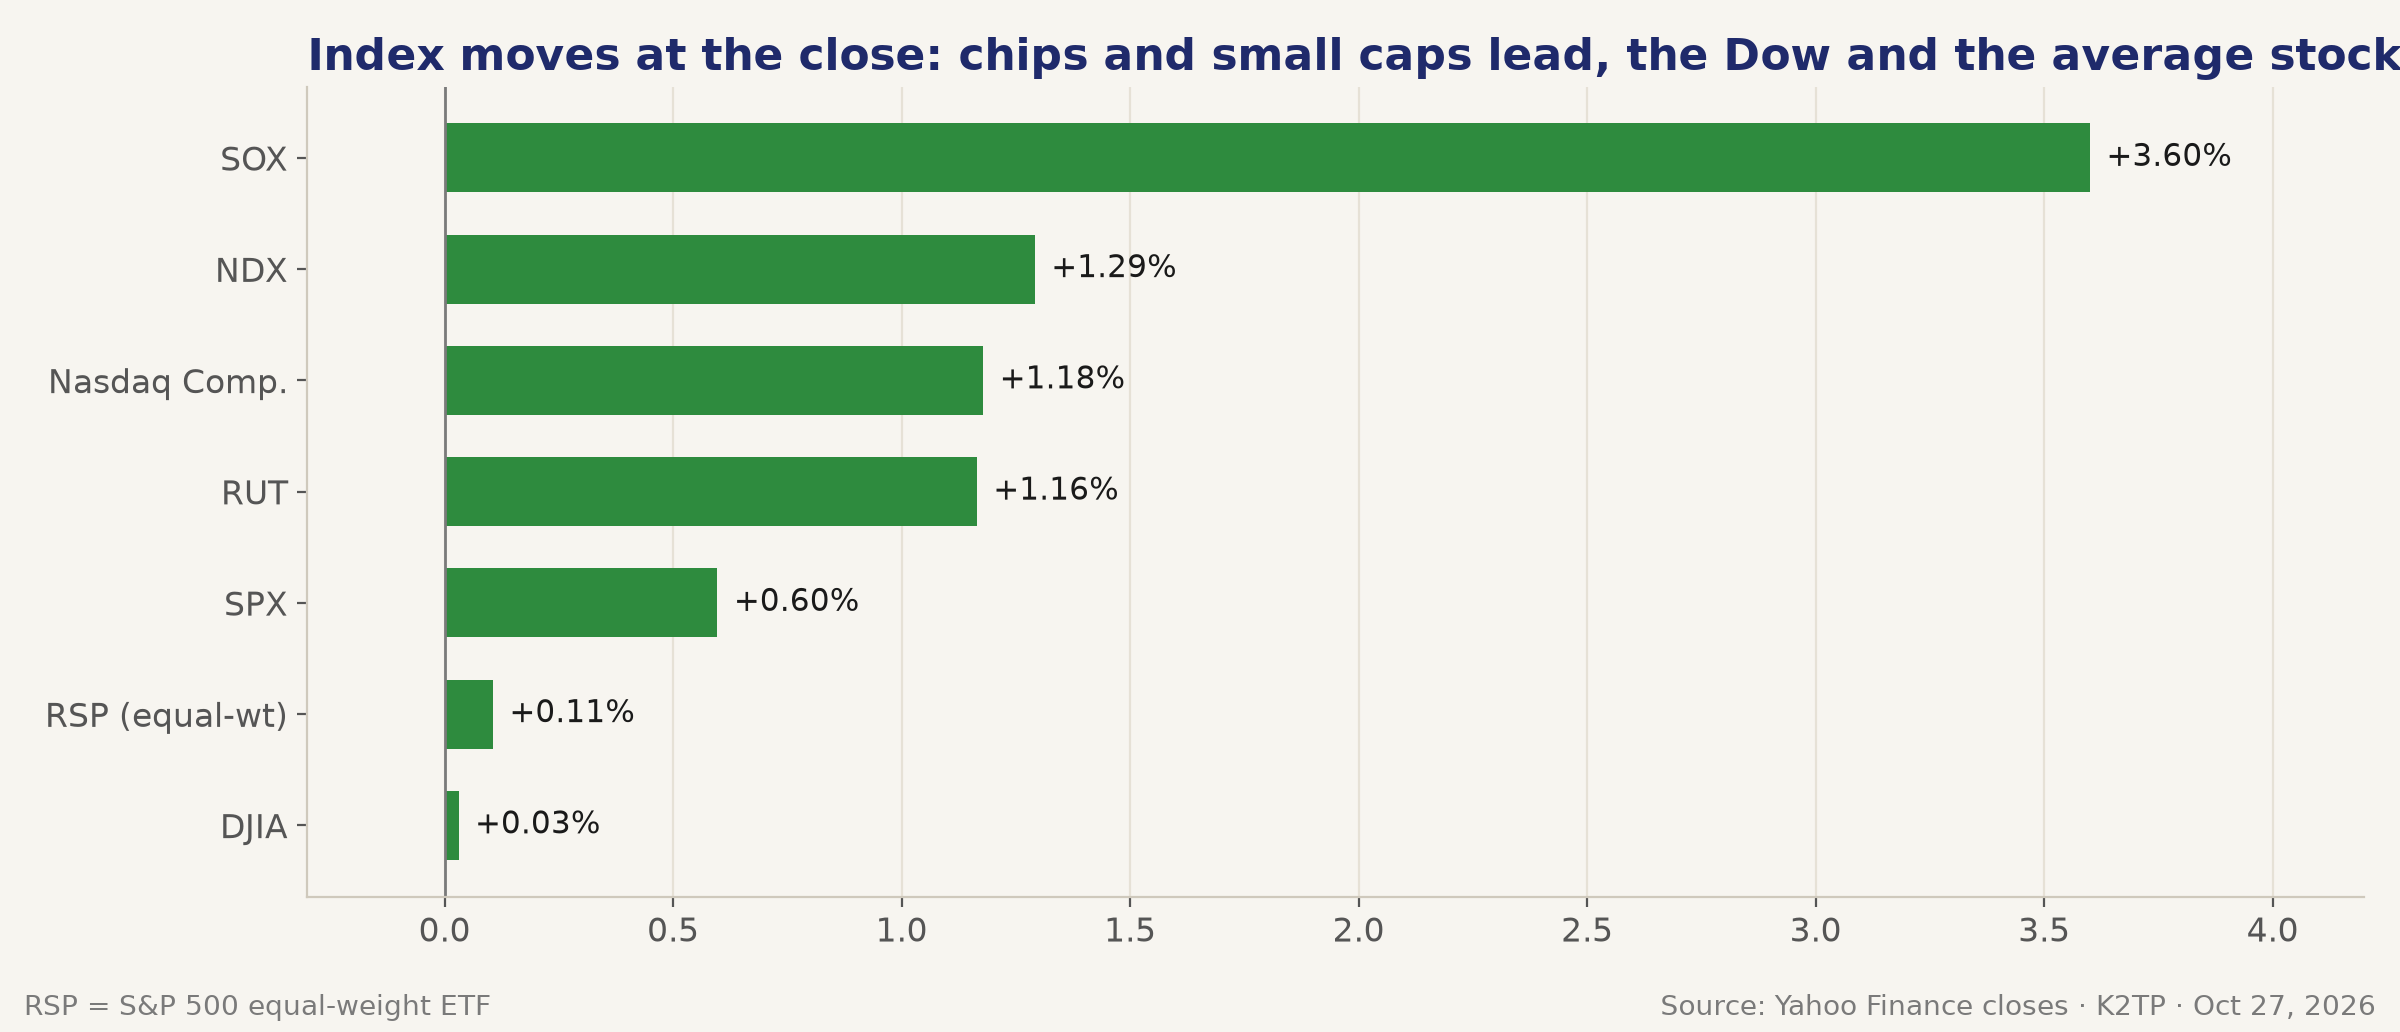
- SPX +0.60% to 7,722.60 (+45.83 pts); NDX +1.29% to 29,651.44; Nasdaq Composite +1.18%; DJIA +0.03% to 52,377.57; RUT +1.16%
- Bank of America, Citi, Morgan Stanley and Blackstone are providing $63B to finance Anthropic's purchase of Broadcom chips; SOX +3.60% to 11,482.51, AMD +5.45%, AVGO +4.00%, INTC +3.61%, TSM +2.95%, MU +2.77%
- Oracle announced an expanded OpenAI partnership, Google TPUs on OCI, a larger Vera Rubin deal with Nvidia and new pacts with Intel and Cerebras; ORCL +3.55%
- SPX held above Monday's 7,702.13 high with VIX under 17.79, so the regime moved up to RISK-ON by midday; the day high was 7,736.24 at 12:45 PM PT
- The rally was narrow: equal-weight RSP +0.11%, only 5 of 11 sector ETFs up, XLE −2.05% the weakest
- Boeing −10.69% on a core loss of $0.34 per share vs $0.21 expected; Xylem −14.21%; UPS +5.75% on an EPS beat and a higher revenue guide
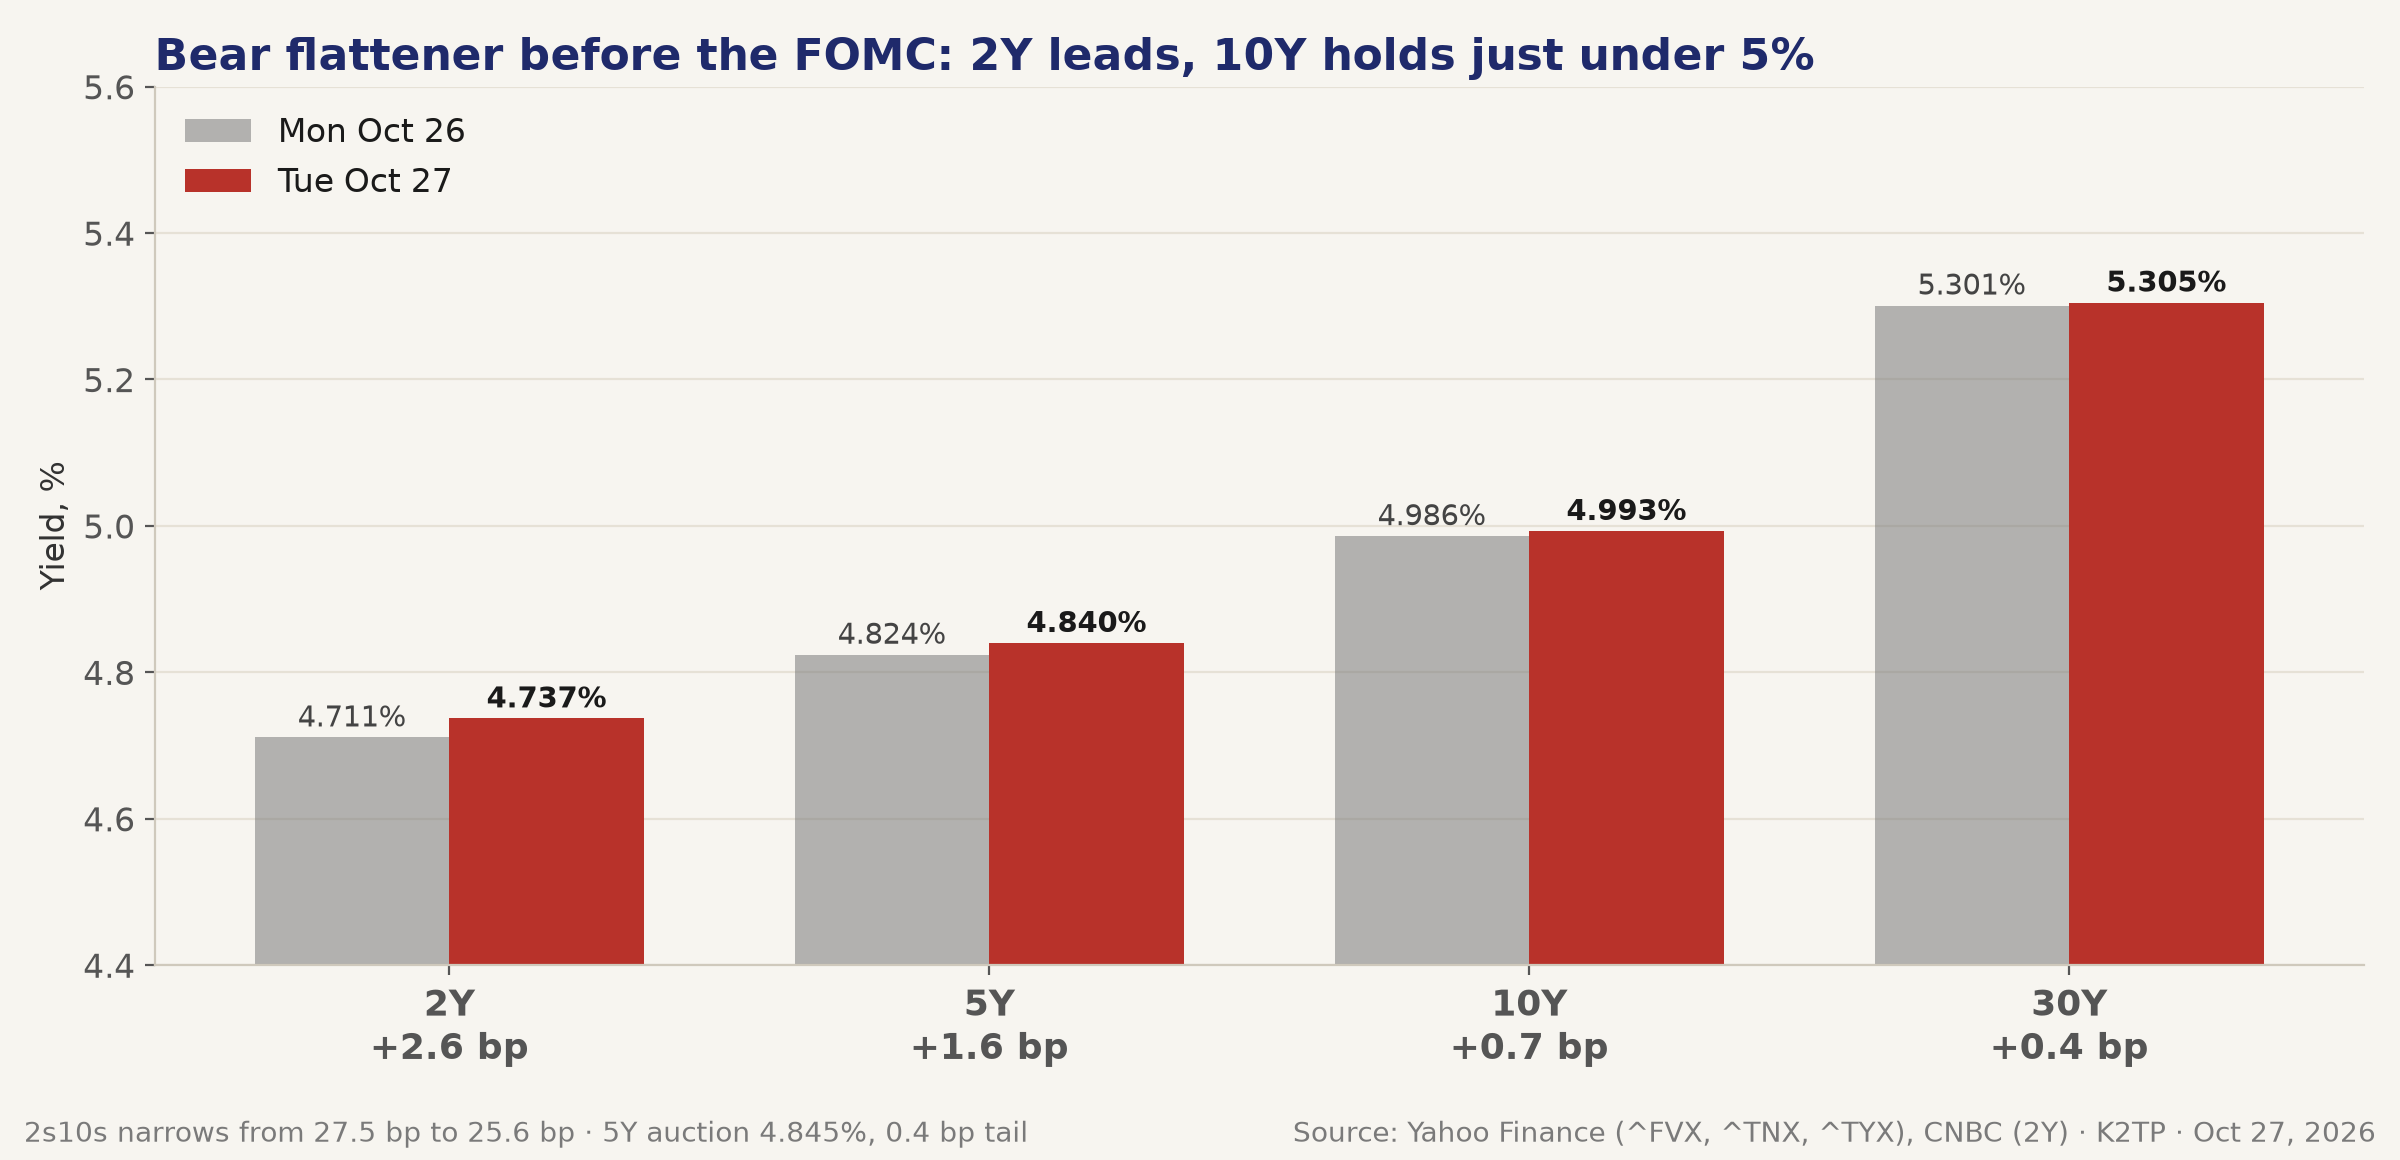
- Conference Board confidence 91.7 vs 81 expected; new home sales 676K vs 650.5K; 2Y +2.6 bp to 4.737%, 10Y 4.993% (+0.7 bp); the 5-year auction tailed 0.4 bp
- December WTI settled at $99.90 (−1.83%) as Iran's leadership discussed conditions for ending the war, but it was back near $100.95 tonight
- After hours: Seagate −5.52% despite a beat and raise, NXP −7.31%, Robinhood −7.63%, Teradyne −5.14%, Visa −1.15%; GOOGL +0.93% on a report that OpenAI plans to buy Google's AI chips
- Regime: 🟢 RISK-ON (narrow), up from TRANSITION; FOMC decision Wednesday at 11:00 AM PT
BROADCOM'S ANTHROPIC FINANCING AND ORACLE'S DEALS EXTEND THE CHIP RALLY
- Bank of America, Citi, Morgan Stanley and Blackstone are providing $63B of financing for Anthropic's purchase of Broadcom technology (Midday brief) 🟢
- Before the open, Nvidia said it will invest $3B in Meta's equity offering and broaden the partnership, and DA Davidson upgraded Broadcom to Buy with a $400 target after the Anthropic S-1 (Pre-Market brief)
- Oracle announced an expanded OpenAI partnership, Google TPUs on OCI, a larger Vera Rubin deal with Nvidia and new pacts with Intel and Cerebras; ORCL was +4.74% at midday and closed +3.55%
- Chips led all day: SOX +3.60% to 11,482.51 (high 11,527.33); AMD +5.45%, AVGO +4.00%, INTC +3.61%, TSM +2.95%, MU +2.77%, NVDA +0.90%
- AI hardware names outside the index also ran: CLS +12.12% on its first 2027 outlook, WDC +6.95%, CRWV +7.94%
- NDX +1.29% beat SPX +0.60% by 69 bp, and SOX more than tripled the NDX gain
→ For the second day running, AI capital is flowing to the suppliers. But the gains are piling into one group, so Microsoft and Alphabet's capex numbers on Wednesday are the real test.
A NARROW RISK-ON: ENERGY AND DEFENSIVES LAG
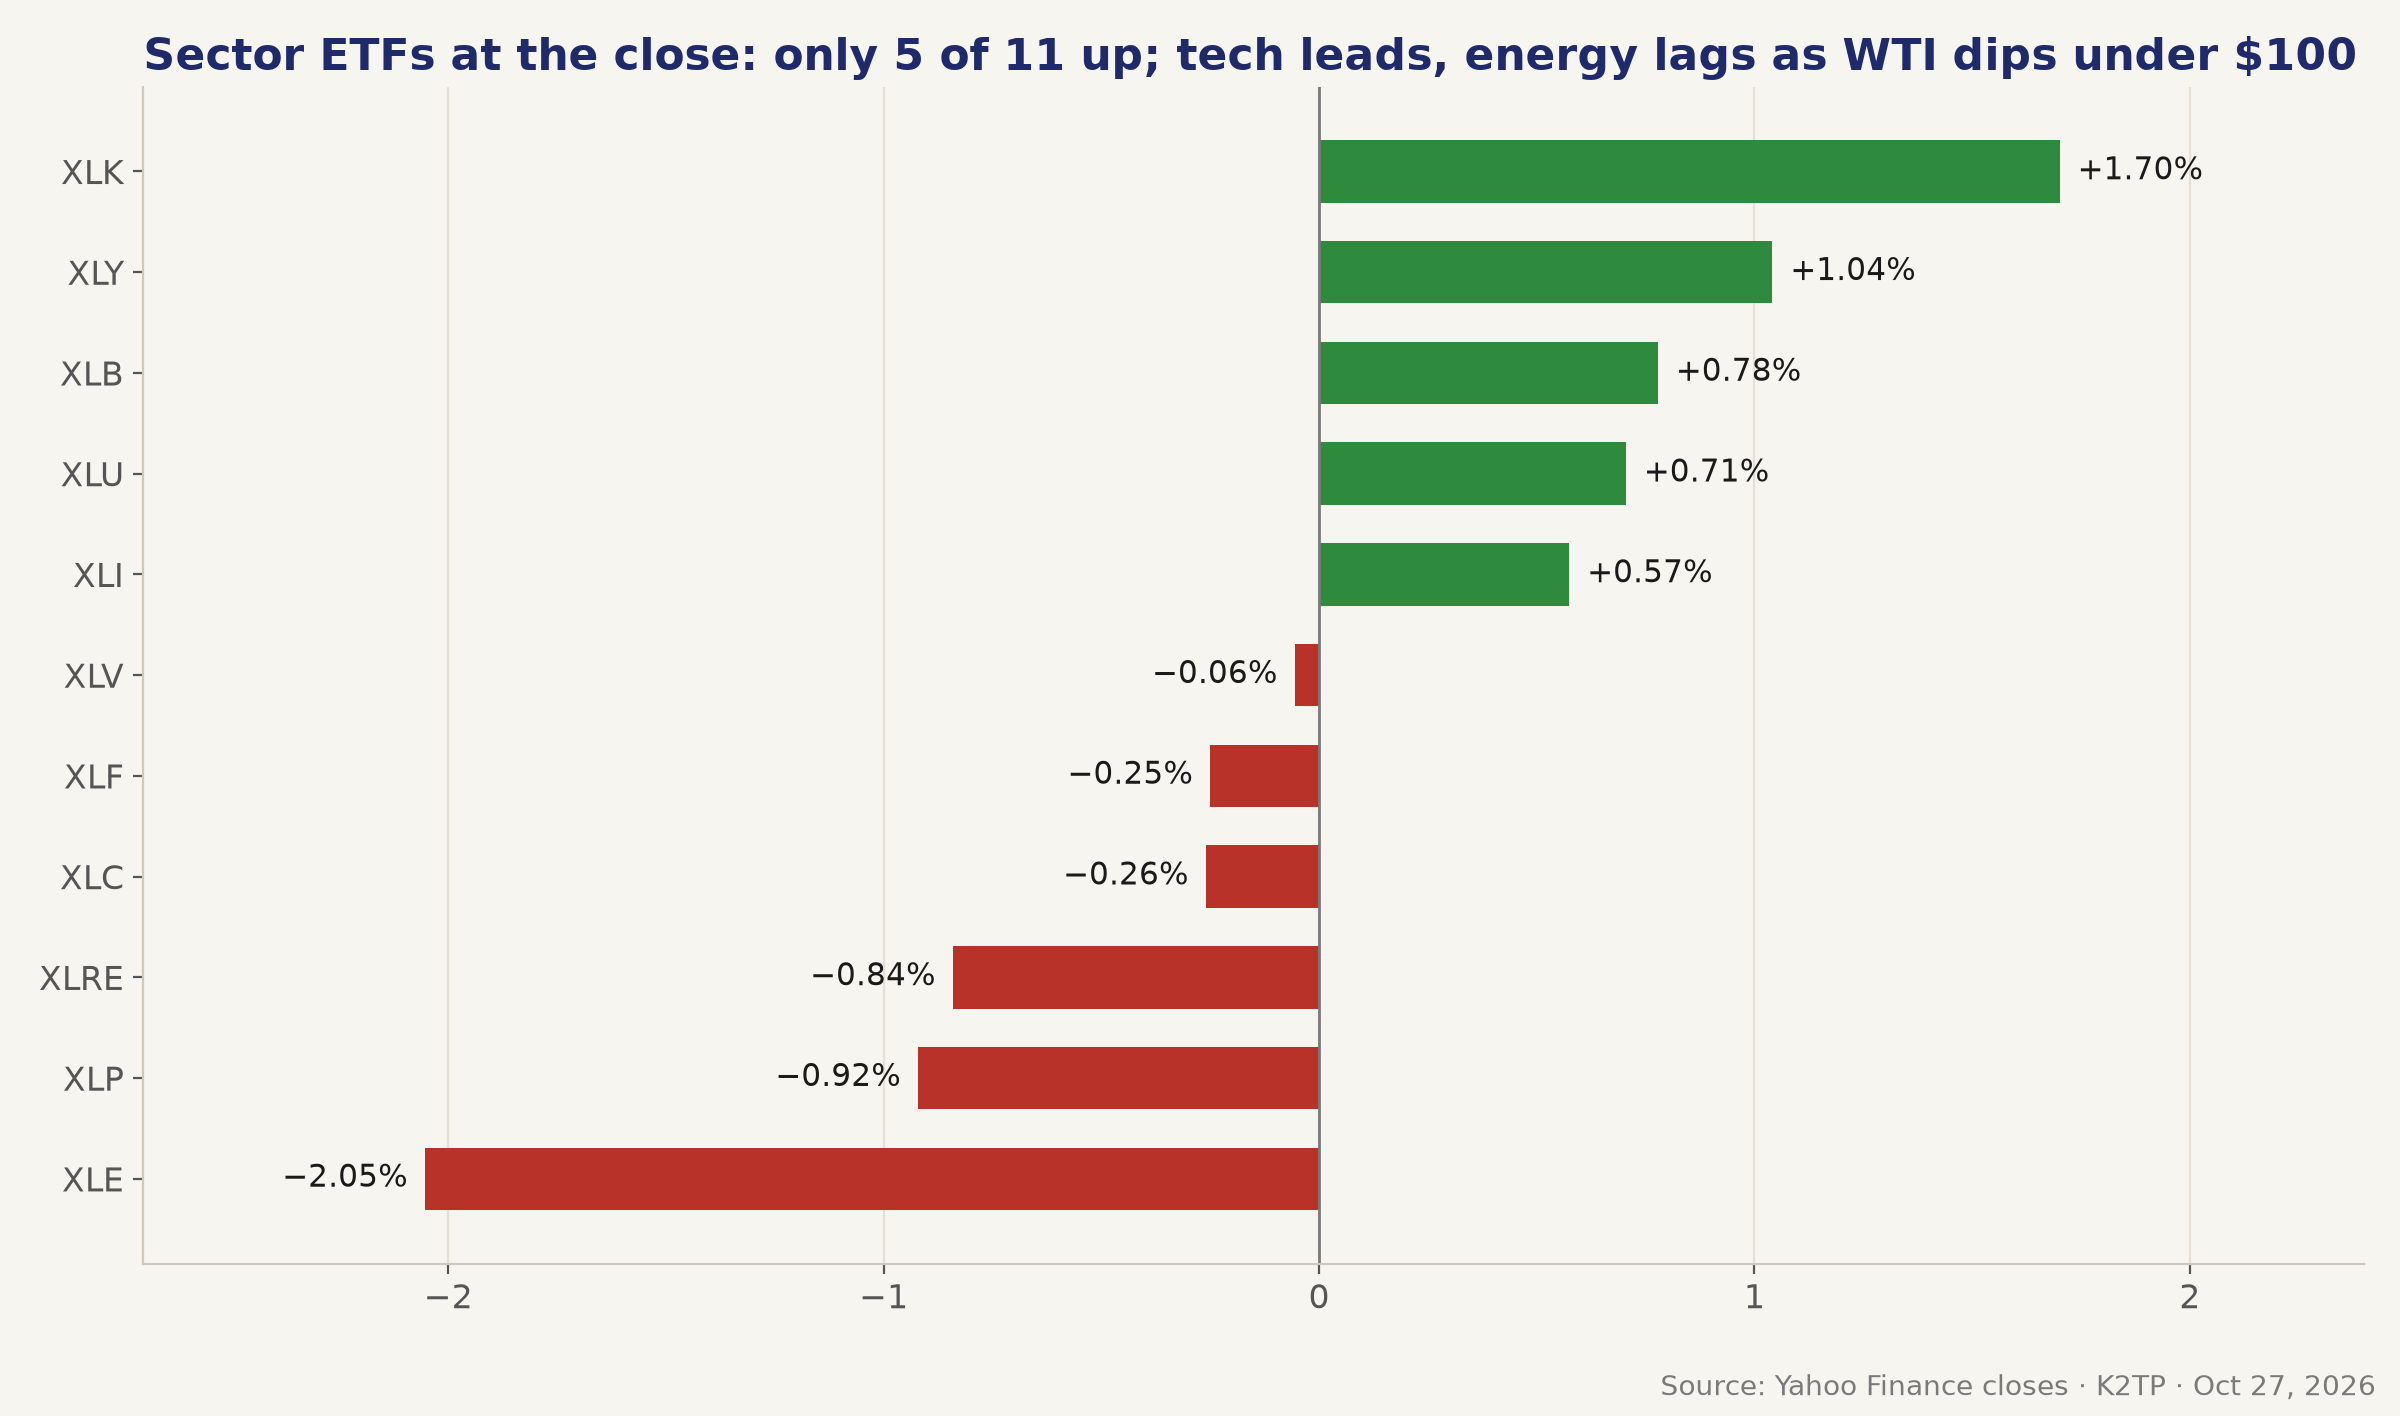
- 5/11 sector ETFs rose: XLK +1.70%, XLY +1.04%, XLB +0.78%, XLU +0.71%, XLI +0.57%; XLV −0.06%, XLF −0.25%, XLC −0.26%, XLRE −0.84%, XLP −0.92%, XLE −2.05%
- Equal-weight RSP +0.11% trailed SPX by 49 bp; at midday it was −0.08% and at pre-close −0.02%
- Small caps did join: RUT +1.16% and IWM +1.15% kept pace with tech after the strong confidence data
- TSLA +4.04% carried XLY; AMZN +1.61%, GOOGL +1.19%, AAPL +0.93%; MSFT −0.24%
- META −1.64% and NFLX −2.16% kept XLC lower; a Delaware lawsuit challenges Meta's stock deal (FinancialJuice, unconfirmed)
- NYSE advance/decline data were unavailable in all four briefs
→ Small caps make this better than a pure mega-cap rally, but six sectors down and a flat equal-weight index mean RISK-ON rests on chips. Watch whether breadth broadens after the Fed.
EARNINGS: BOEING AND XYLEM SLIDE, UPS RALLIES; VISA AND SEAGATE FALL AFTER HOURS
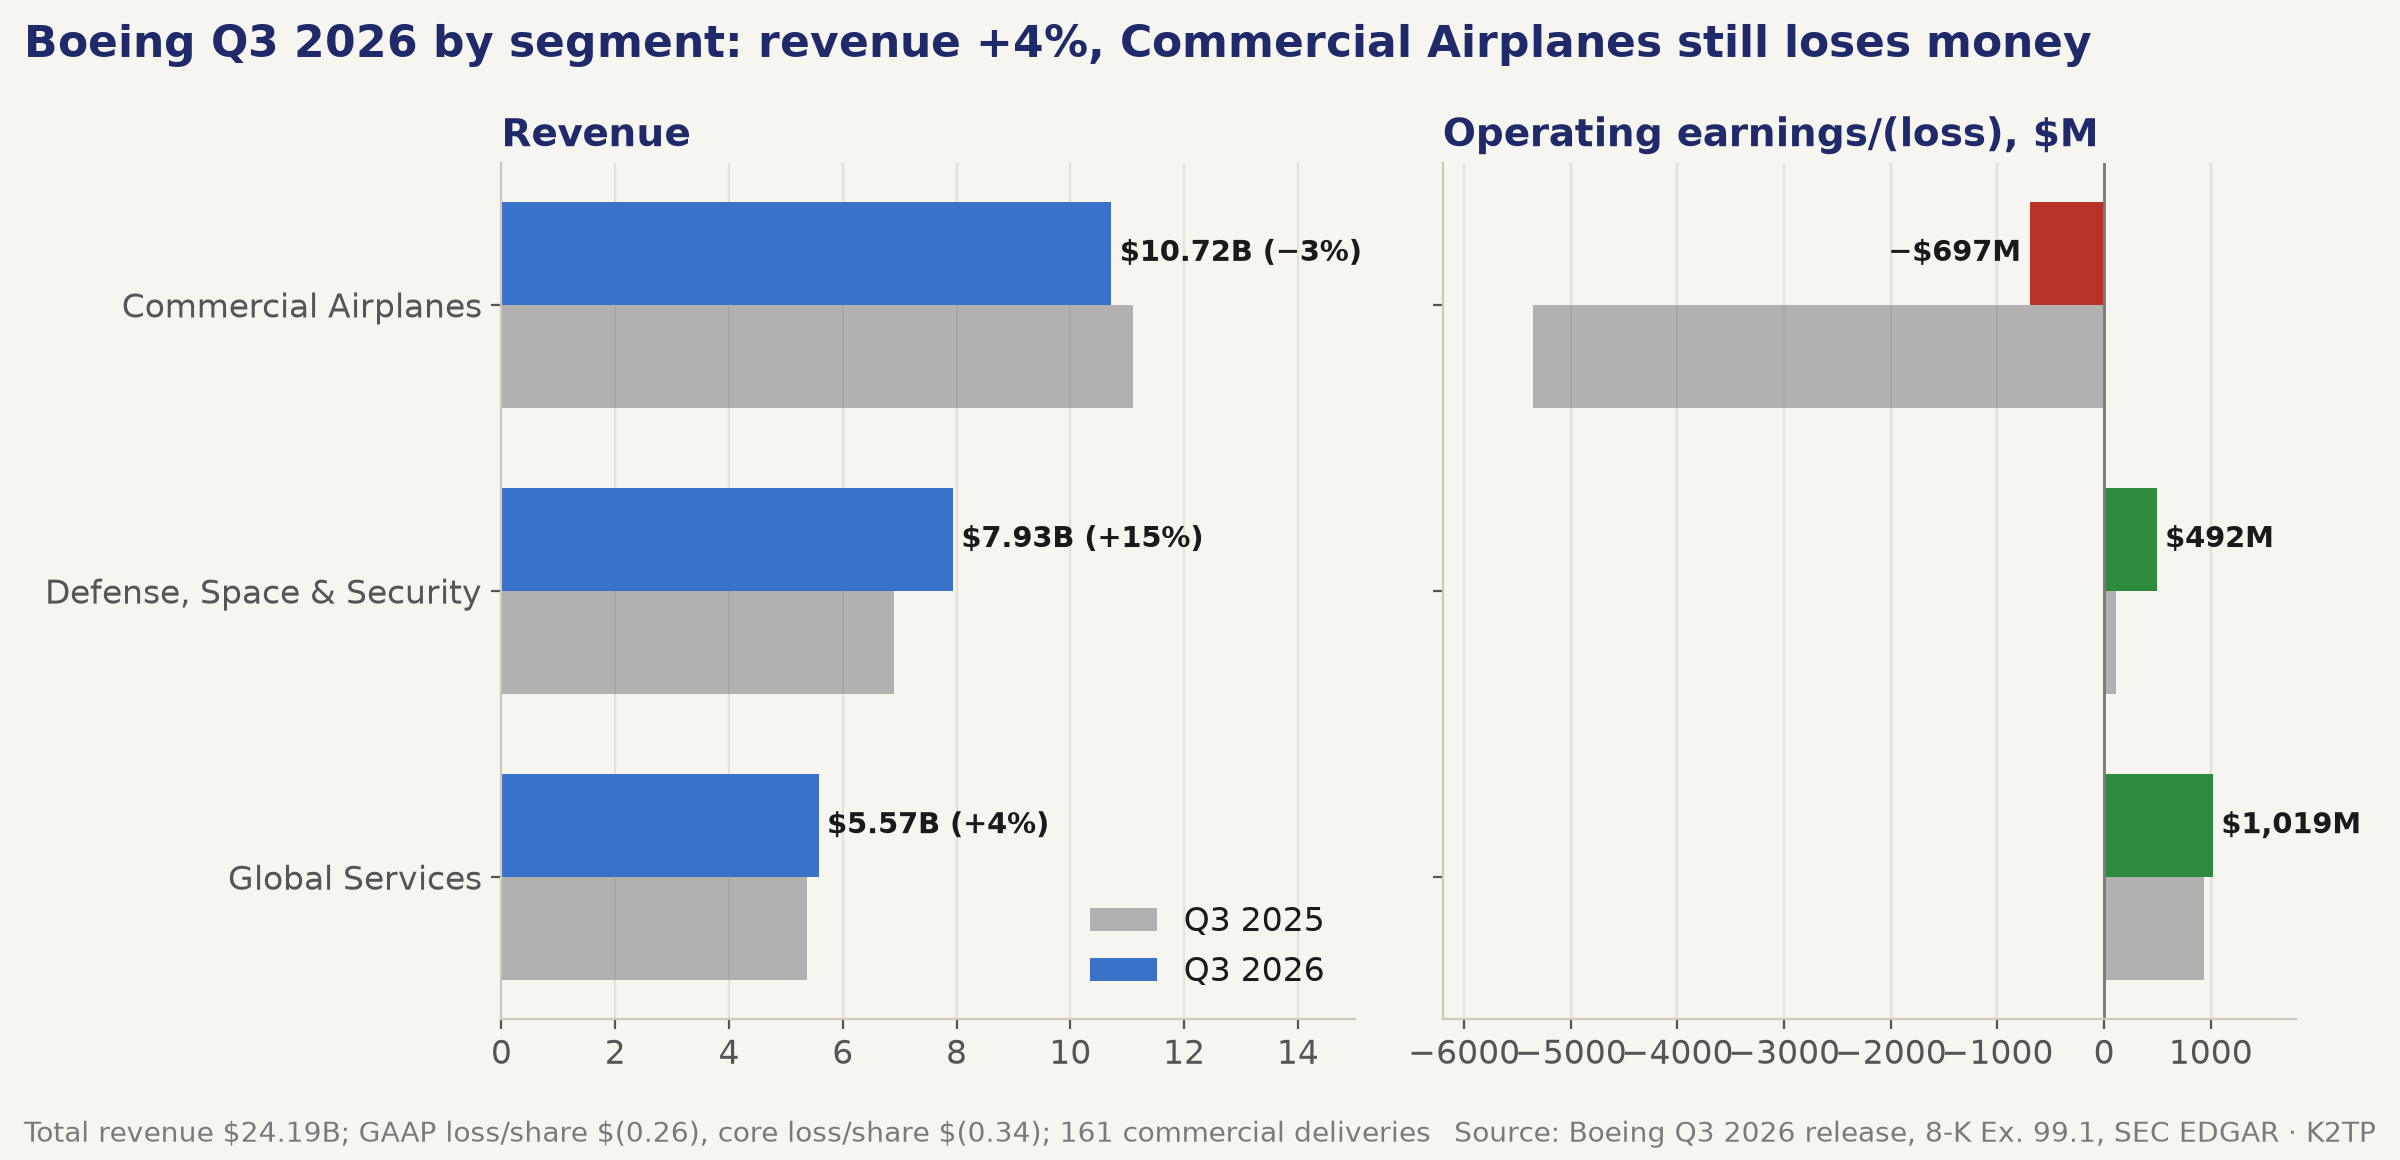
- Boeing (8-K Ex. 99.1): revenue $24.19B (+4% YoY), GAAP loss $(0.26) per share, core loss $(0.34) vs $(0.21) expected (Pre-Market brief); operating earnings $354M vs a $4.78B loss a year ago; free cash flow $464M 🔴
- Commercial Airplanes revenue fell 3% to $10.72B and lost $697M on 161 deliveries; Defense, Space & Security revenue +15% to $7.94B with $492M operating earnings; Global Services $5.57B and $1.02B
- BA −10.69% to 168.18 and held the Dow at +0.03%
- UPS adj. EPS $1.69 vs $1.63 and a higher full-year revenue guide near $92.6B; UPS +5.75% to 106.09, up from +1.67% before the open 🟢
- Coca-Cola comparable EPS $0.91 vs $0.88, unit case volume +5% and a raised profit target, yet KO −1.64%; PayPal adj. EPS $1.45 vs $1.31 on revenue $8.58B vs $8.71B, PYPL +2.00%
- S&P Global faded from +4.04% before the open to −0.38%; Xylem fell from −8.50% to −14.21%; Corning −1.13%; JetBlue +18.99% on its Q4 margin outlook
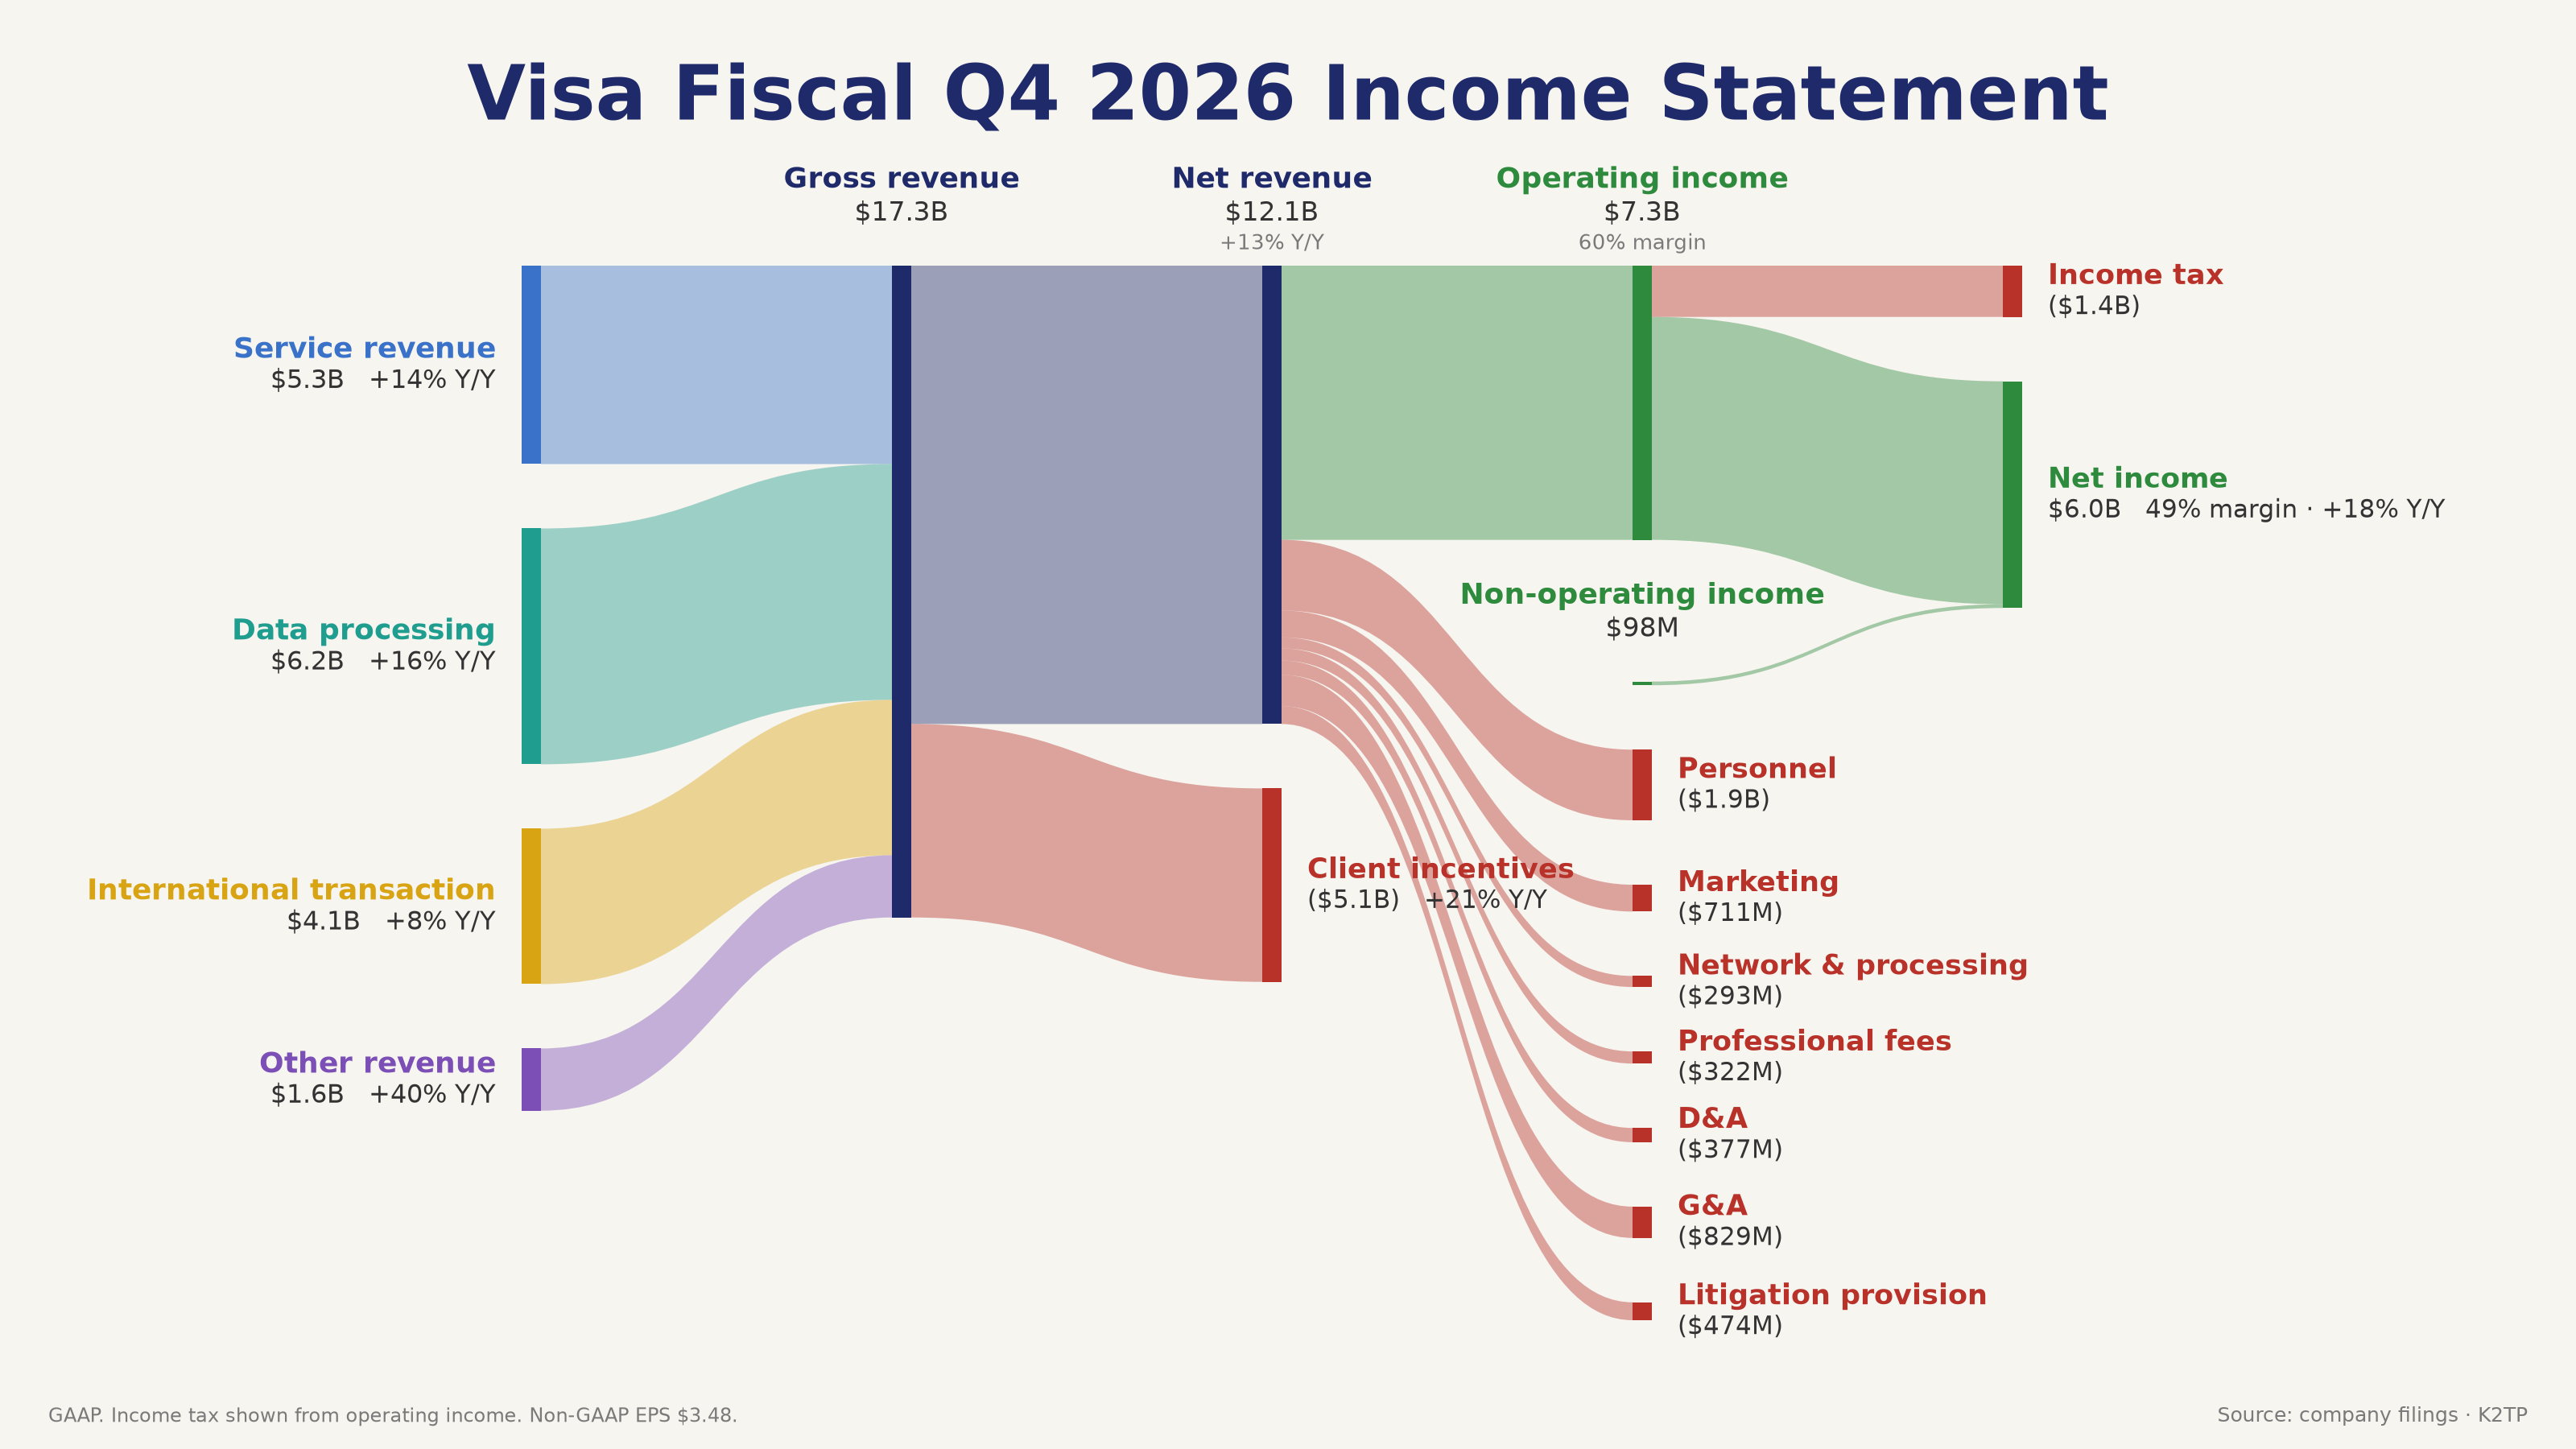
- Visa (8-K Ex. 99.1, fiscal Q4): net revenue $12.14B (+13%), GAAP EPS $3.19, non-GAAP EPS $3.48 vs $3.44 expected (CNBC); dividend +16% to $0.78; V −1.15% after hours
- Seagate adj. EPS $7.68 vs $7.39 and a Q2 revenue guide of $4.70B–$4.90B vs $4.56B, yet STX −5.52% after hours; NXP −7.31% on a Q4 revenue guide of $3.85B vs $3.86B consensus; Robinhood −7.63% as crypto revenue fell 55%; Teradyne −5.14%; Enphase about −14%; PPG about +7% (CNBC, Investing.com)
→ After hours, AI hardware fell even on beats and raises, which shows how high the bar is before Microsoft and Alphabet. Boeing's commercial unit is still losing money despite the revenue growth.
THE BIG SINGLE-STOCK MOVES
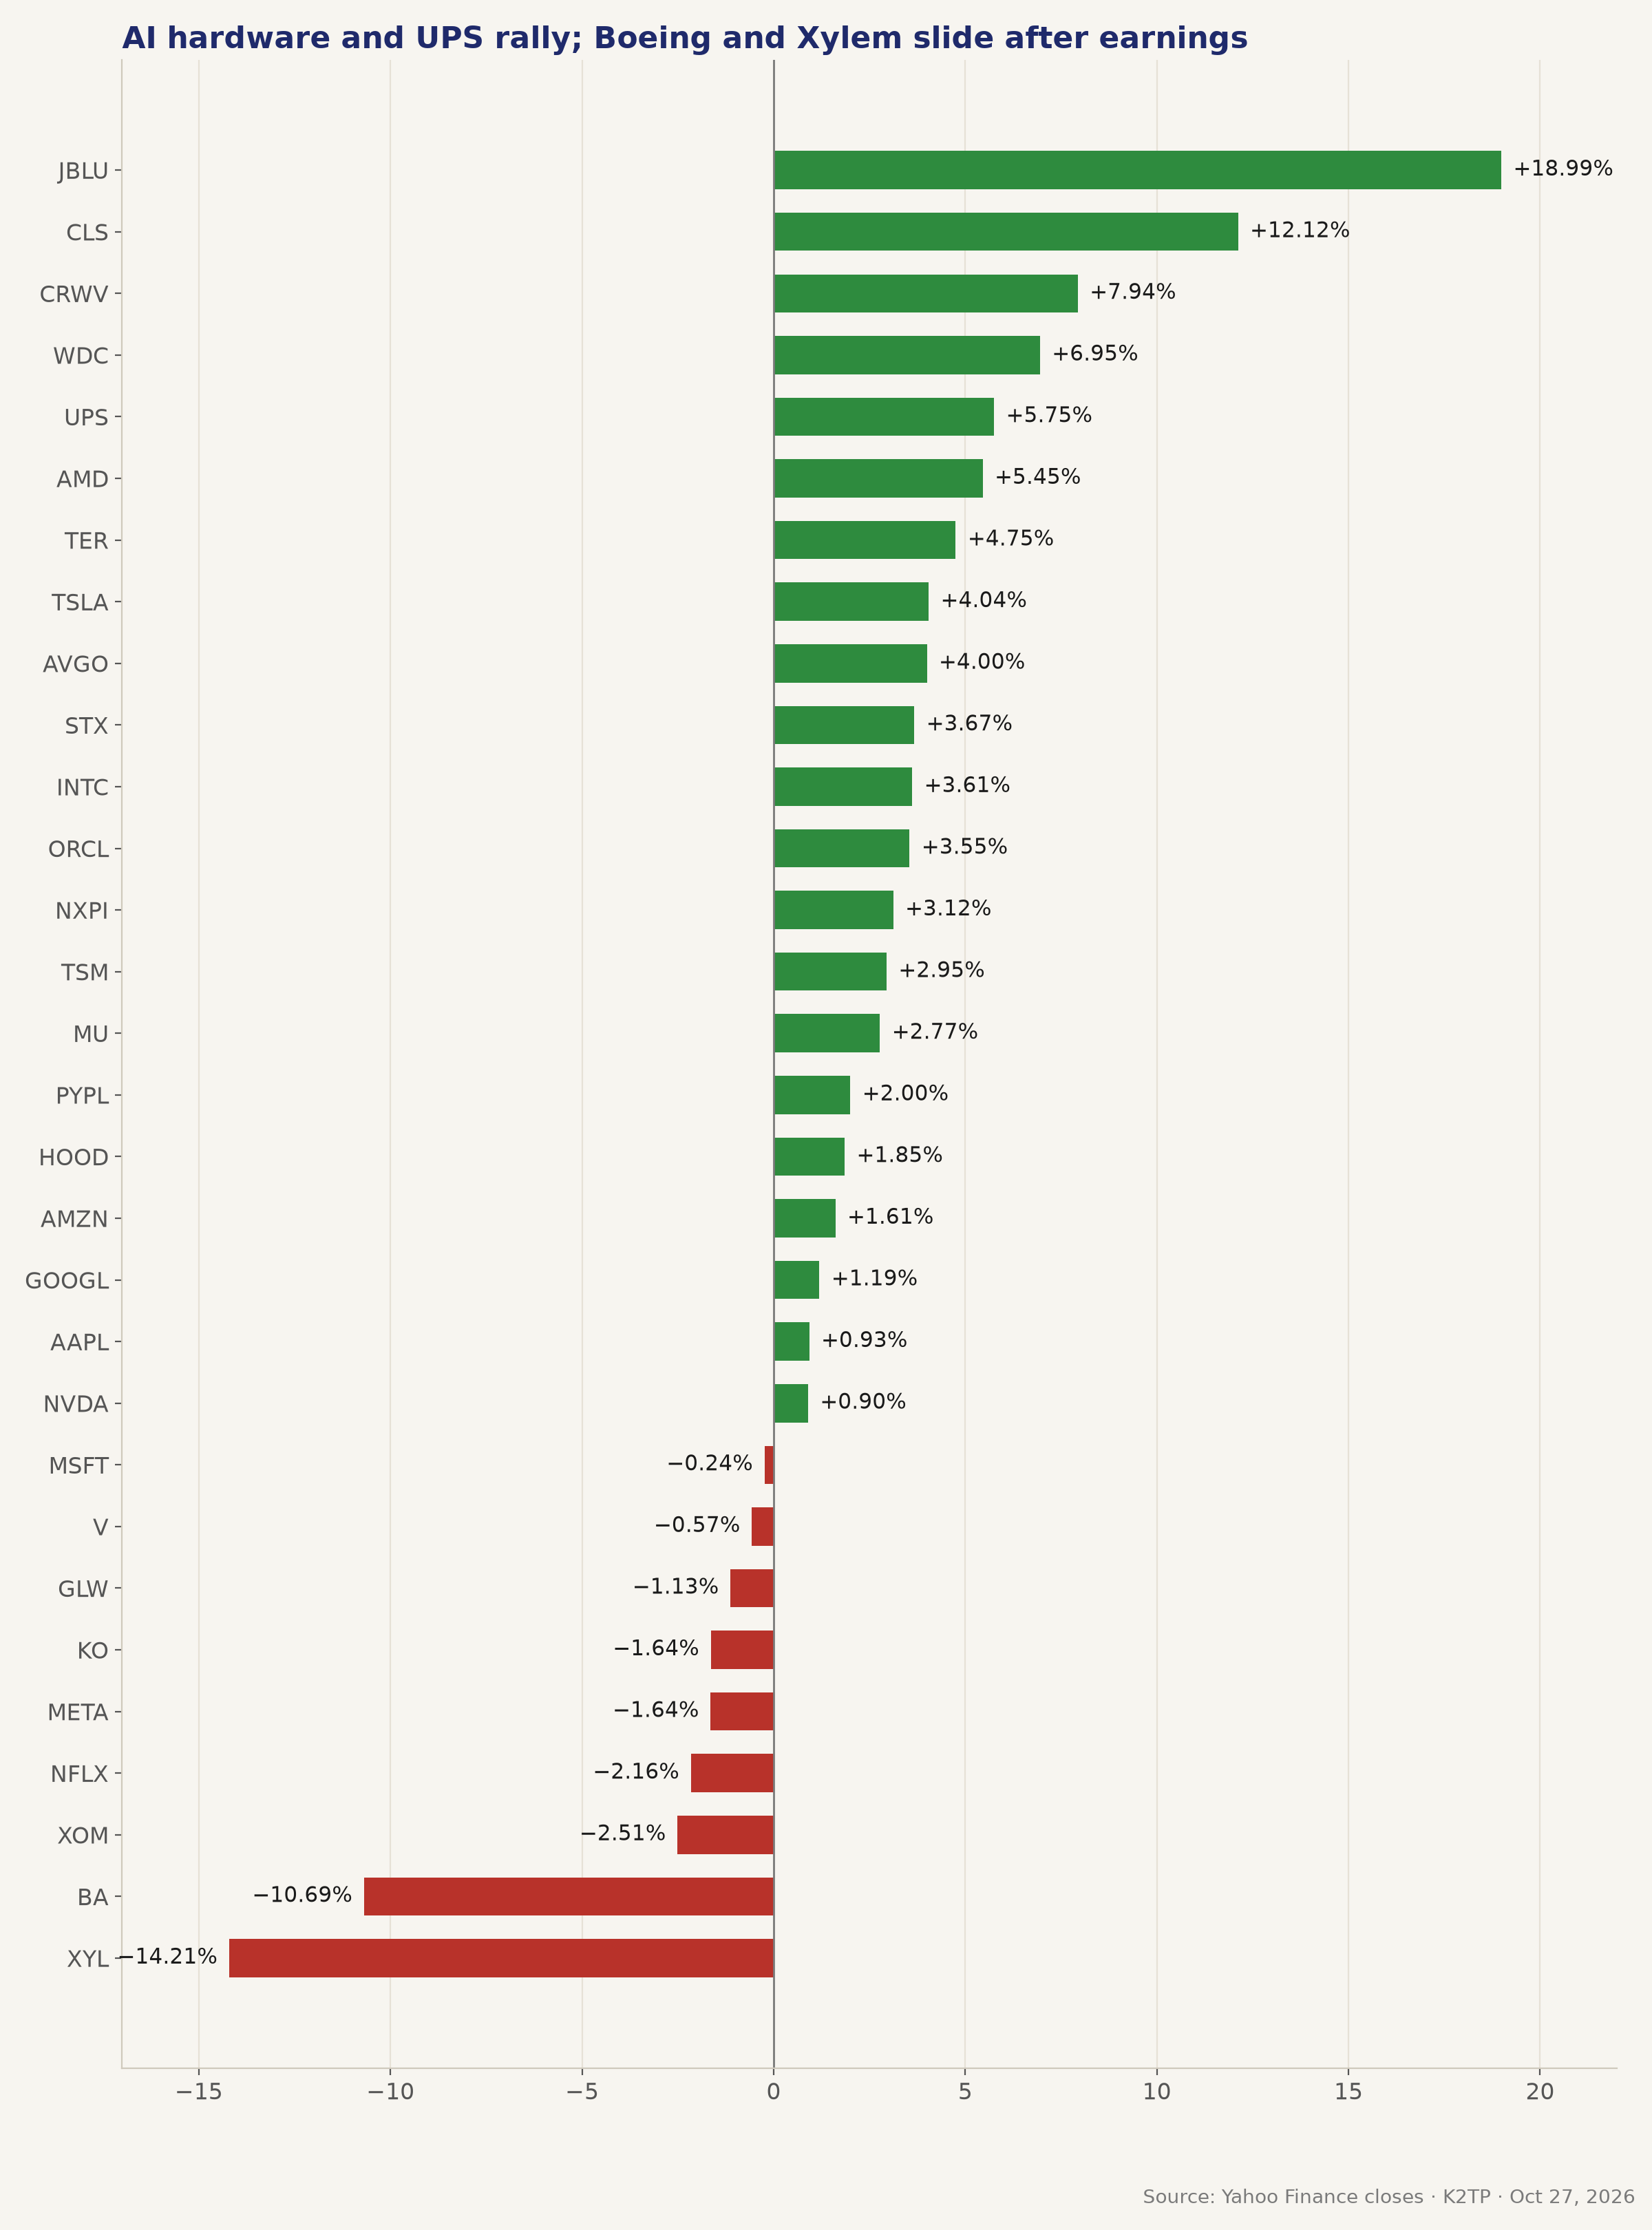
- Gainers: JBLU +18.99%, CLS +12.12%, CRWV +7.94%, WDC +6.95%, UPS +5.75%, AMD +5.45%, TER +4.75%, TSLA +4.04%
- Losers: XYL −14.21%, BA −10.69%, XOM −2.51%, NFLX −2.16%, LMT −1.92%, META −1.64%, KO −1.64%
- STX +3.67%, TER +4.75% and NXPI +3.12% in regular hours before falling 5% to 7% after their reports
→ The biggest moves were company-specific. The after-hours drops in STX, NXPI and TER are the first sign that the chip bid could run out of steam at the open.
OIL SLIPS UNDER $100, THEN RECOVERS TONIGHT
- December WTI settled at $99.90 (−1.83%), its first settle under $100 in this run; the intraday low was $99.80 (Pre-Close and Midday briefs) 🟡
- Driver: Iran's Supreme Leader met security chief Mohsen Rezaei about conditions for ending the war; Energy Secretary Wright said refined product flows from Hormuz have increased
- Risk remains: before the open, Saudi Arabia contained a fire near the Ras Tanura oil hub after an attack the Houthis claimed; tonight Saudi Arabia said it intercepted a Houthi missile aimed at Taif (FinancialJuice)
- Tonight WTI is about $100.95 and Brent about $110.60; a Pentagon estimate puts the cost of Iran war operations above $47B
- XLE −2.05%, XOM −2.51%, CVX −1.63%; gold $4,060.50 at the close and about $4,072.60 tonight
→ A dip under $100 helped consumers and cyclicals, but crude bounced back above $100 tonight, so the inflation side of Wednesday's FOMC is still live.
FRONT END LEADS A BEAR FLATTENER INTO THE FED
- Conference Board confidence 91.7 vs 81 expected, up 7.5 points; 12-month inflation expectations eased to 5.8%; new home sales 676K vs 650.5K; Richmond Fed −2 vs 0 (Midday brief)
- Durable goods +1.8% vs 1.9% expected, ex-transportation +0.5% vs 0.6%; Case-Shiller 20-city +2.65% y/y vs 2.61% (Pre-Market and Midday briefs)
- The $70B 5-year auction stopped at 4.845% with a 0.4 bp tail; bid-to-cover 2.33 from 2.21, indirects 60.0%; the Treasury bought back $6B of 2046–2056 coupons (Pre-Close brief) 🟡
- Closing yields: 2Y 4.737% (+2.6 bp), 5Y 4.840% (+1.6 bp), 10Y 4.993% (+0.7 bp, range 4.972–5.007%), 30Y 5.305% (+0.4 bp); 2s10s narrowed from 27.5 bp to 25.6 bp
- FedWatch shows about a 92% chance of a hold at 3.75%–4.00% on Wednesday (CNBC), and Reuters says traders price a hike in December
→ The front end is pricing a hawkish hold. What Warsh signals about December matters more than the decision itself.
SPX DIPS AT THE OPEN, THEN CLEARS MONDAY'S HIGH
- Pre-market: ES +0.43%, NQ +0.58%; implied SPX near 7,710, just above Monday's 7,702.13 high, with VIX at 17.78
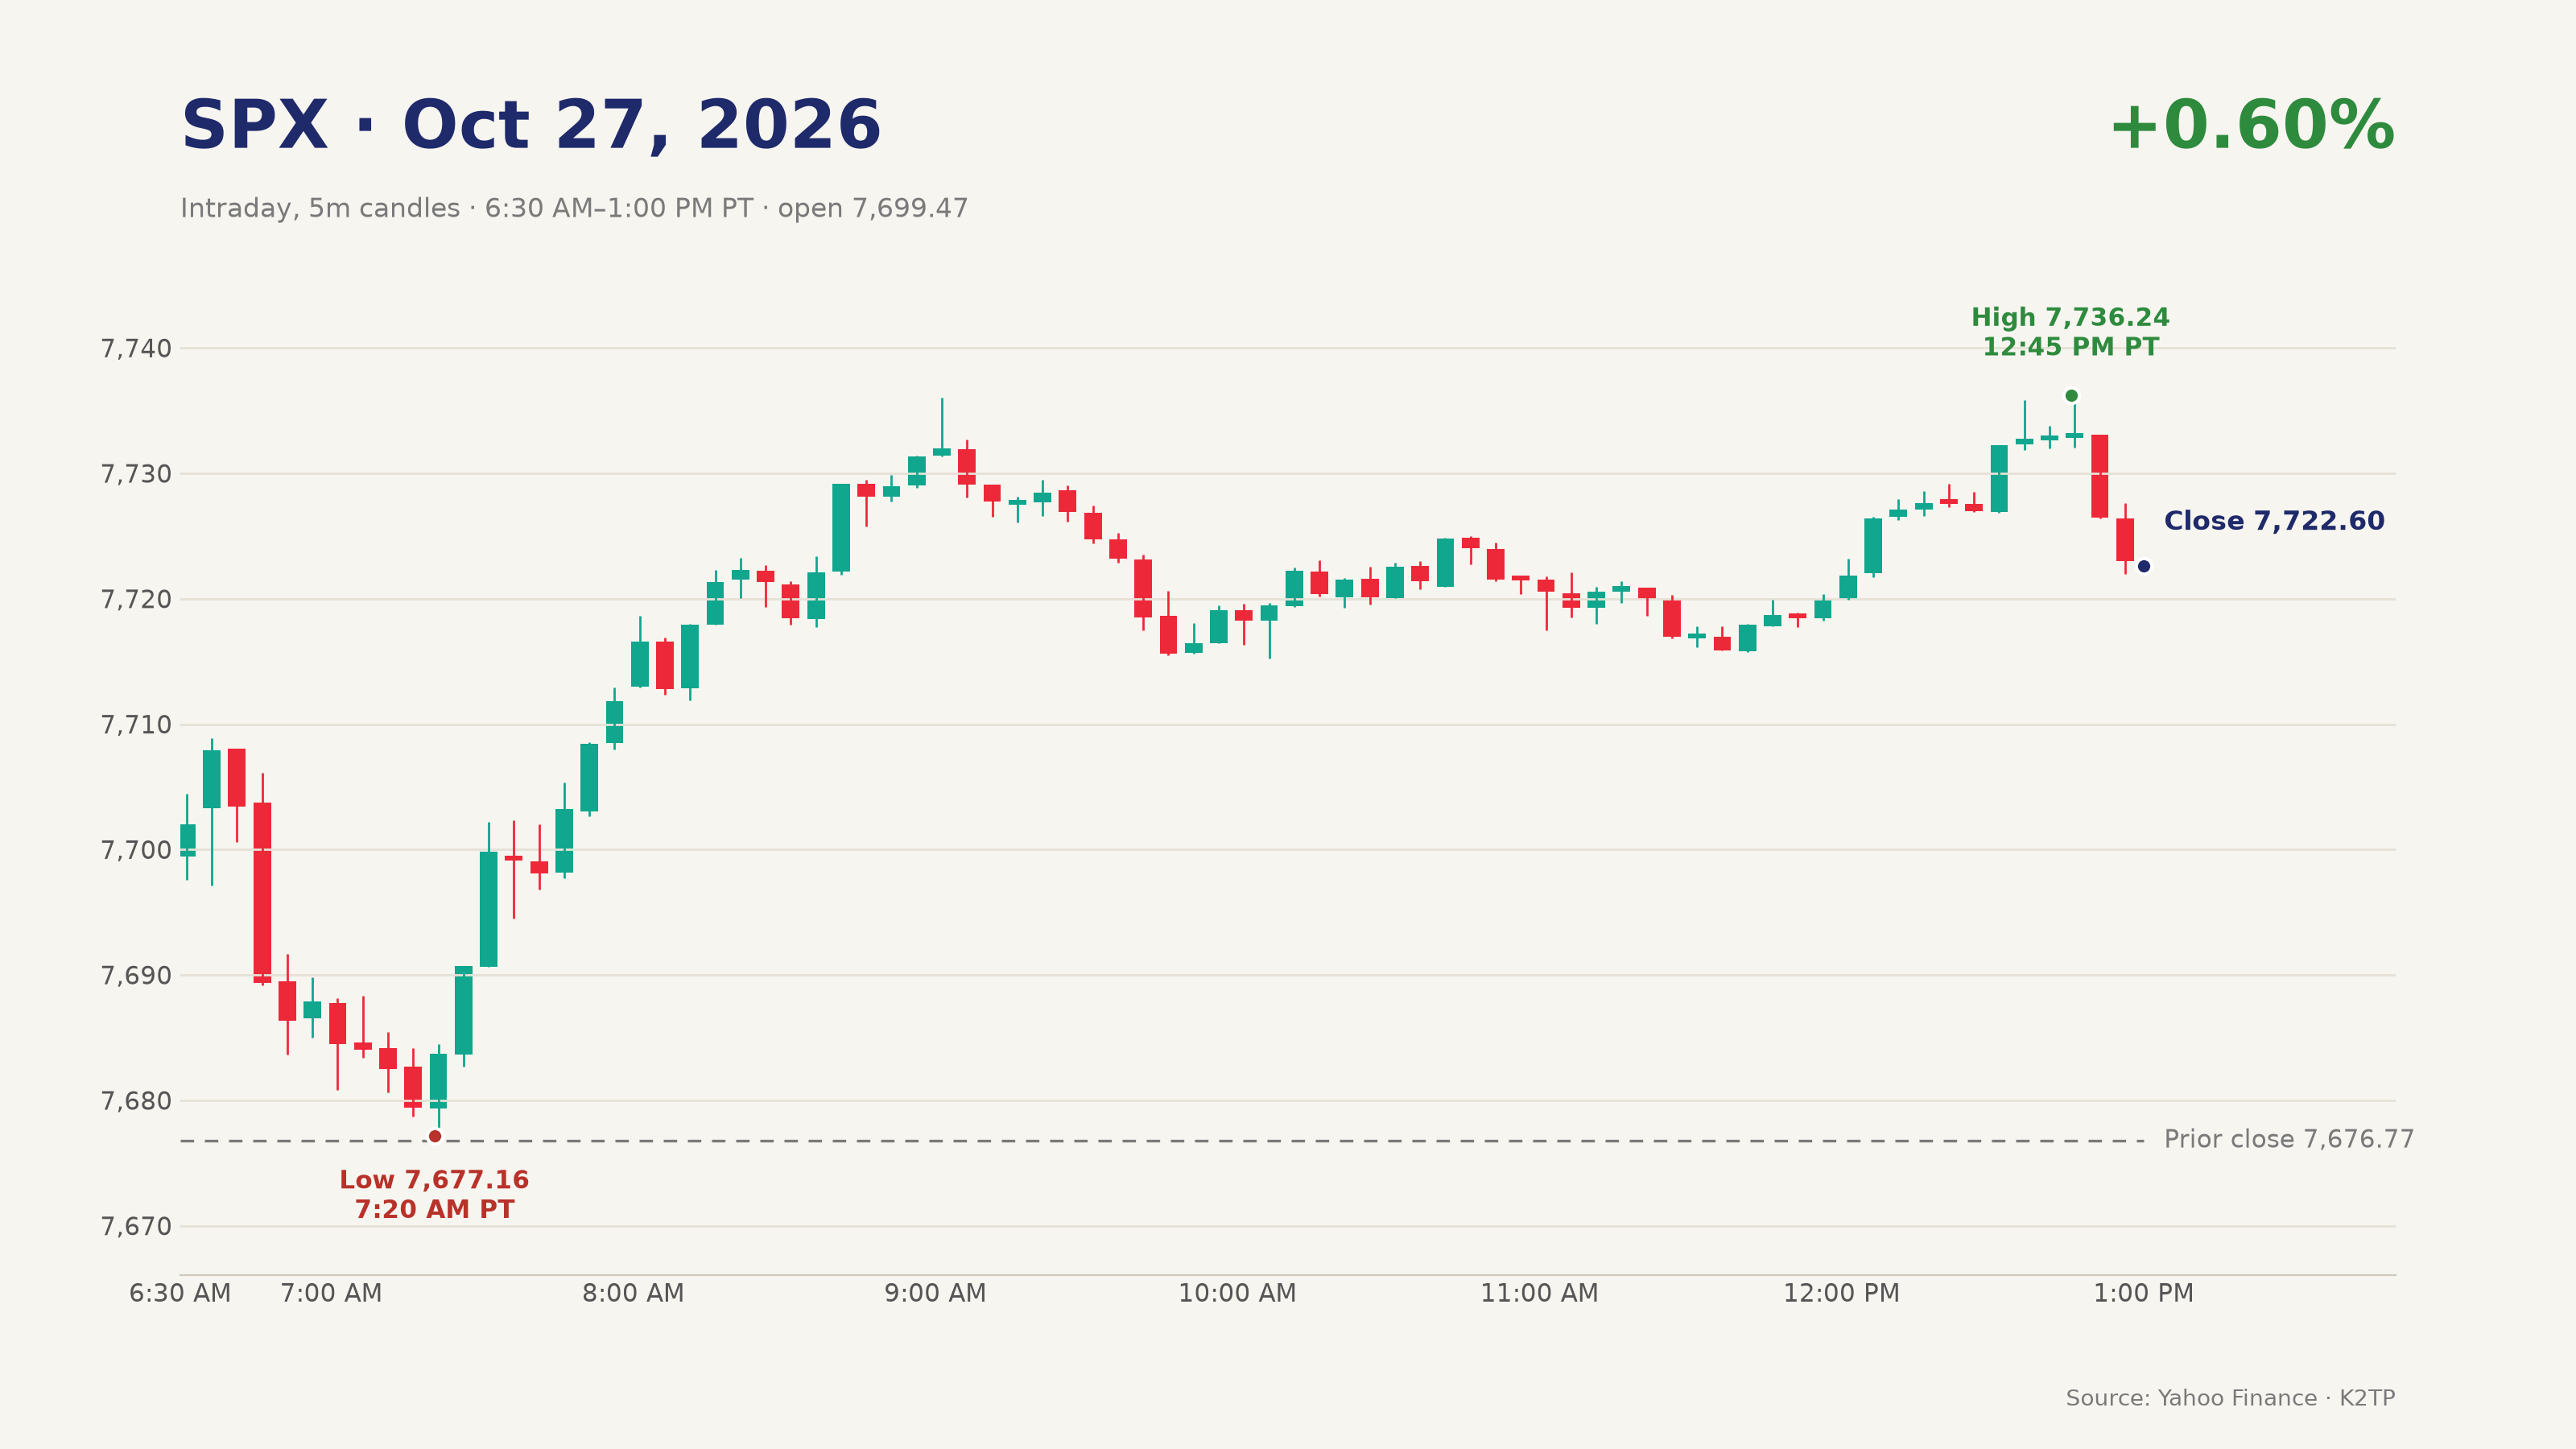
- SPX opened at 7,699.47, fell to the day low of 7,677.16 at 7:20 AM PT, just above Monday's 7,676.77 close, then reclaimed 7,702.13 before 8:00 AM PT
- With SPX above 7,702.13 and VIX under 17.79, the pre-market line was met and the regime moved from TRANSITION to RISK-ON by midday
- The morning high of 7,736.06 came around 9:00 AM PT; SPX was at 7,726.77 at midday and 7,727.59 at pre-close
- The day high of 7,736.24 came at 12:45 PM PT, and VIX touched 17.43, but SPX closed at 7,722.60 and VIX at 17.52, so the pre-close Bull line (above 7,736.06 with VIX under 17.51) was not confirmed
→ Buyers defended Monday's close at the open and held SPX above Monday's high all day. 7,702–7,736 is the range going into the Fed.
MARKET: CHIPS PUSH SPX ABOVE MONDAY'S HIGH AS BOEING AND ENERGY LAG
Indices (close):
- SPX 7,722.60 (+0.60%), range 7,677.16–7,736.24
- NDX 29,651.44 (+1.29%); Nasdaq Composite 26,477.81 (+1.18%)
- DJIA 52,377.57 (+0.03%)
- RUT 2,818.87 (+1.16%)
- RSP 217.52 (+0.11%)
- SOX 11,482.51 (+3.60%)
Intraday path: Pre-market ES +0.43% and NQ +0.58% on the Nvidia–Meta stake and the Celestica and Broadcom moves. SPX opened at 7,699.47, hit the low of 7,677.16 at 7:20 AM PT, reclaimed Monday's 7,702.13 high before 8:00 AM PT, reached 7,736.06 around 9:00 AM PT, was 7,726.77 at midday and 7,727.59 at pre-close, set the day high of 7,736.24 at 12:45 PM PT and closed at 7,722.60.
Sector rotation:
- Up: XLK +1.70%, XLY +1.04%, XLB +0.78%, XLU +0.71%, XLI +0.57%
- Down: XLV −0.06%, XLF −0.25%, XLC −0.26%, XLRE −0.84%, XLP −0.92%, XLE −2.05%
- Mega-cap: AMD +5.45%, TSLA +4.04%, AVGO +4.00%, MU +2.77%, AMZN +1.61%, GOOGL +1.19%, AAPL +0.93%, NVDA +0.90%; MSFT −0.24%, META −1.64%
Internals:
- RSP +0.11% vs SPX +0.60%; IWM +1.15% and RUT +1.16% kept pace with tech
- NYSE and Nasdaq advance/decline data were unavailable today
- 5 of 11 sectors up: the rally is narrow and leans on chips
Volatility:
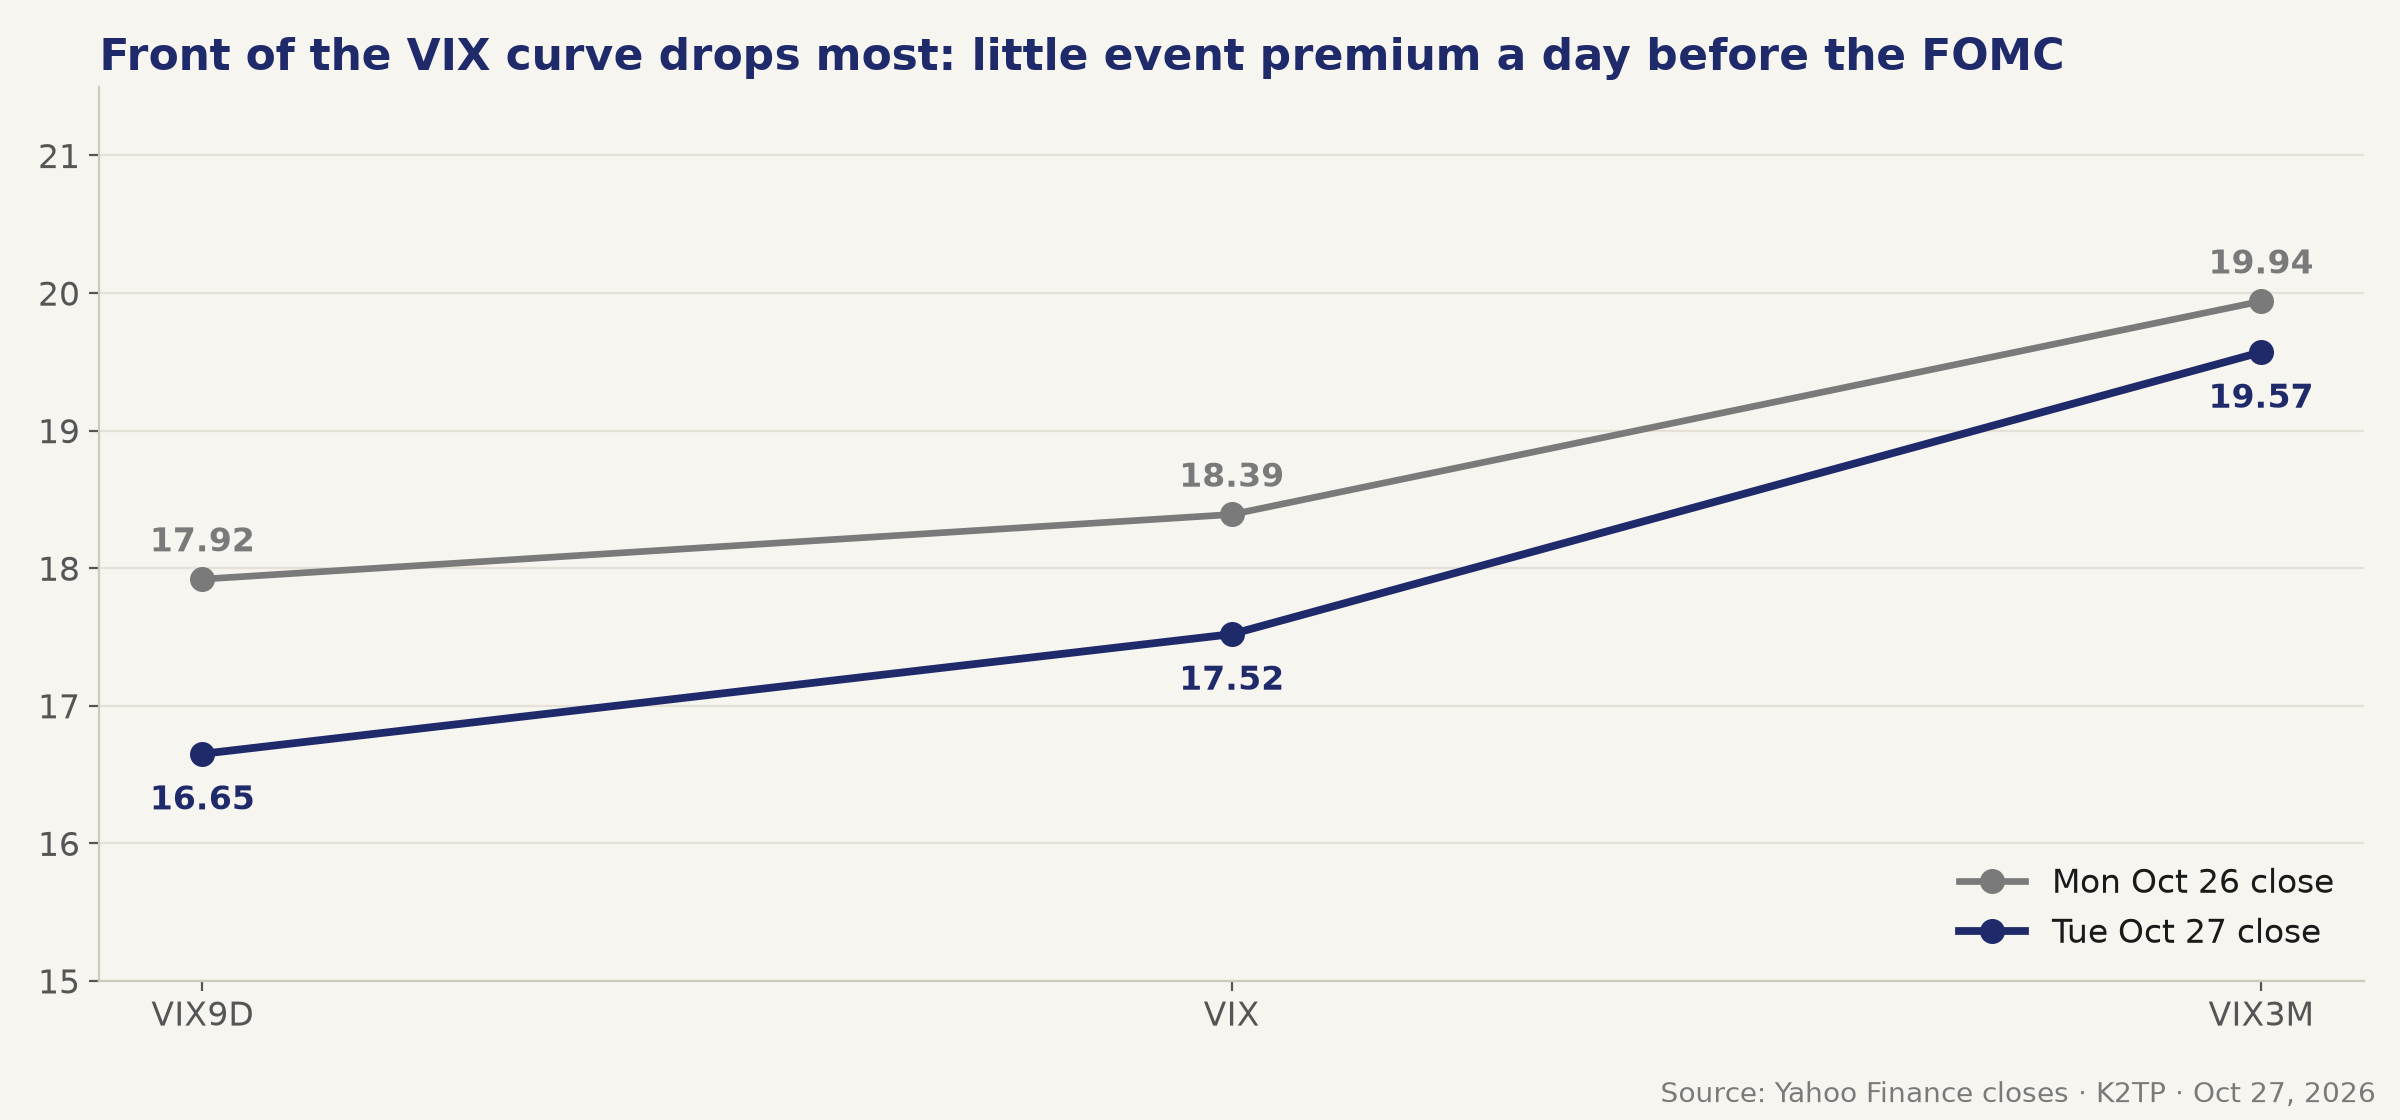
- VIX 17.52 (−4.73%), range 17.43–18.55
- VIX9D 16.65, VIX3M 19.57: the curve shifted lower and stays in contango, with the front end lowest
- VVIX 99.45 (−1.95%)
Cross-asset:
- WTI December settled at $99.90 (−1.83%), about $100.95 tonight; Brent about $110.60 tonight
- Gold $4,060.50 at the close; DXY 102.41 (+0.09%); BTC about $80,720 tonight (Evening Recap)
- ES 7,758.75 tonight (+0.01%); NQ 29,844.00 (+0.11%)
Global:
- Asia (Tuesday, Pre-Market brief): Kospi +3.09%, Nikkei +1.73%, Shanghai −1.14%
- Europe at the close: Euro Stoxx 50 +0.79%, DAX +0.71%, FTSE 100 −0.75% (Pre-Close brief)
- Tonight: RBNZ held at 2.75% vs a forecast hike to 3% on a 4–3 vote and NZD fell 1.4%; Australia's Q3 CPI rose 1.3% q/q vs 1.2%; Nikkei +1.17%, Kospi +4.72% (Evening Recap)
Key SPX levels:
- 7,736.24: Tuesday's high, Bull trigger
- 7,727.59: pre-close level
- 7,722.60: close
- 7,702.13: Monday's high, Invalidation line
- 7,677.16: Tuesday's low, Bear trigger
- 7,676.77: Monday's close
- VIX: 17.43 and 18.55
Option seller corner:
- Bull case: SPX above 7,736.24 with VIX under 17.43 broadens RISK-ON. Even then, add new far-OTM SPX put spreads only after the 11:00 AM PT decision and Warsh's 11:30 AM PT press conference.
- Bear case: SPX under 7,677.16 with VIX above 18.55 sends the regime back to TRANSITION. Then cut short-put size and use only defined-risk spreads, especially on NDX and semis.
- VIX9D 16.65 sits below VIX 17.52 and VIX3M 19.57, so near-dated premium is cheap even though it covers the FOMC, Microsoft and Alphabet, and Thursday's GDP and PCE. Selling those expirations pays little for the event risk.
- Avoid short premium through single-stock earnings (MSFT, GOOGL, NOW, KLAC on Wednesday). Semis carry gap risk after the after-hours selling in STX, NXPI and TER.
BOTTOM LINE
- Broadcom's $63B Anthropic financing and Oracle's AI deals kept chips running (SOX +3.60%), and SPX closed 20.47 pts above Monday's 7,702.13 high.
- The gains were narrow: RSP +0.11%, 5 of 11 sectors up, Boeing −10.69% held the Dow flat, and AI hardware fell after hours even on beats.
- Regime 🟢 RISK-ON (narrow). We go into Wednesday RISK-ON while SPX holds above 7,702.13; a hawkish December signal from Warsh, oil back above $100 and chip selling spreading at the open are the main risks. A close under 7,702.13 returns the read to TRANSITION.
What to watch Wednesday (PT):
- Before the open: GE Vernova, Vertiv, Boston Scientific
- 5:30 AM: advance goods trade balance (Sep); 6:45 AM: Bank of Canada decision (2.25%, hold expected); 7:30 AM: EIA crude inventories (API −2.03M)
- 11:00 AM: FOMC decision (hold at 3.75%–4.00%, about 92%); 11:30 AM: Warsh press conference
- After the close: Microsoft, Alphabet, ServiceNow, KLA, T-Mobile
- Thursday 5:30 AM: Q3 GDP (forecast 3.0%) and September PCE (forecast 3.6% y/y)
Bull expectation: Warsh holds without a firm December hike signal, SPX takes out 7,736.24 with VIX under 17.43, and RSP and the other sectors join the chip rally. Bear expectation: Warsh signals a December hike and the 2Y jumps, after-hours chip selling spreads, SPX loses 7,677.16 and VIX rises above 18.55.
Sources: the four K2TP briefs for 10/27/2026 (Pre-Market, Midday, Pre-Close, Evening Recap). Official closing and intraday prices from Yahoo Finance; oil settlements, news and data from CNBC, Reuters, Investopedia, Investing.com and FinancialJuice; Boeing chart and Visa Sankey from the Q3 2026 releases of Boeing (8-K Ex. 99.1) and Visa (fiscal Q4 2026, 8-K Ex. 99.1), SEC EDGAR. Analysis: K2TP Framework.