Market 10/20: Healthcare and Small Caps Lead a Broad Rotation as Mega-Caps Hold the Nasdaq Back
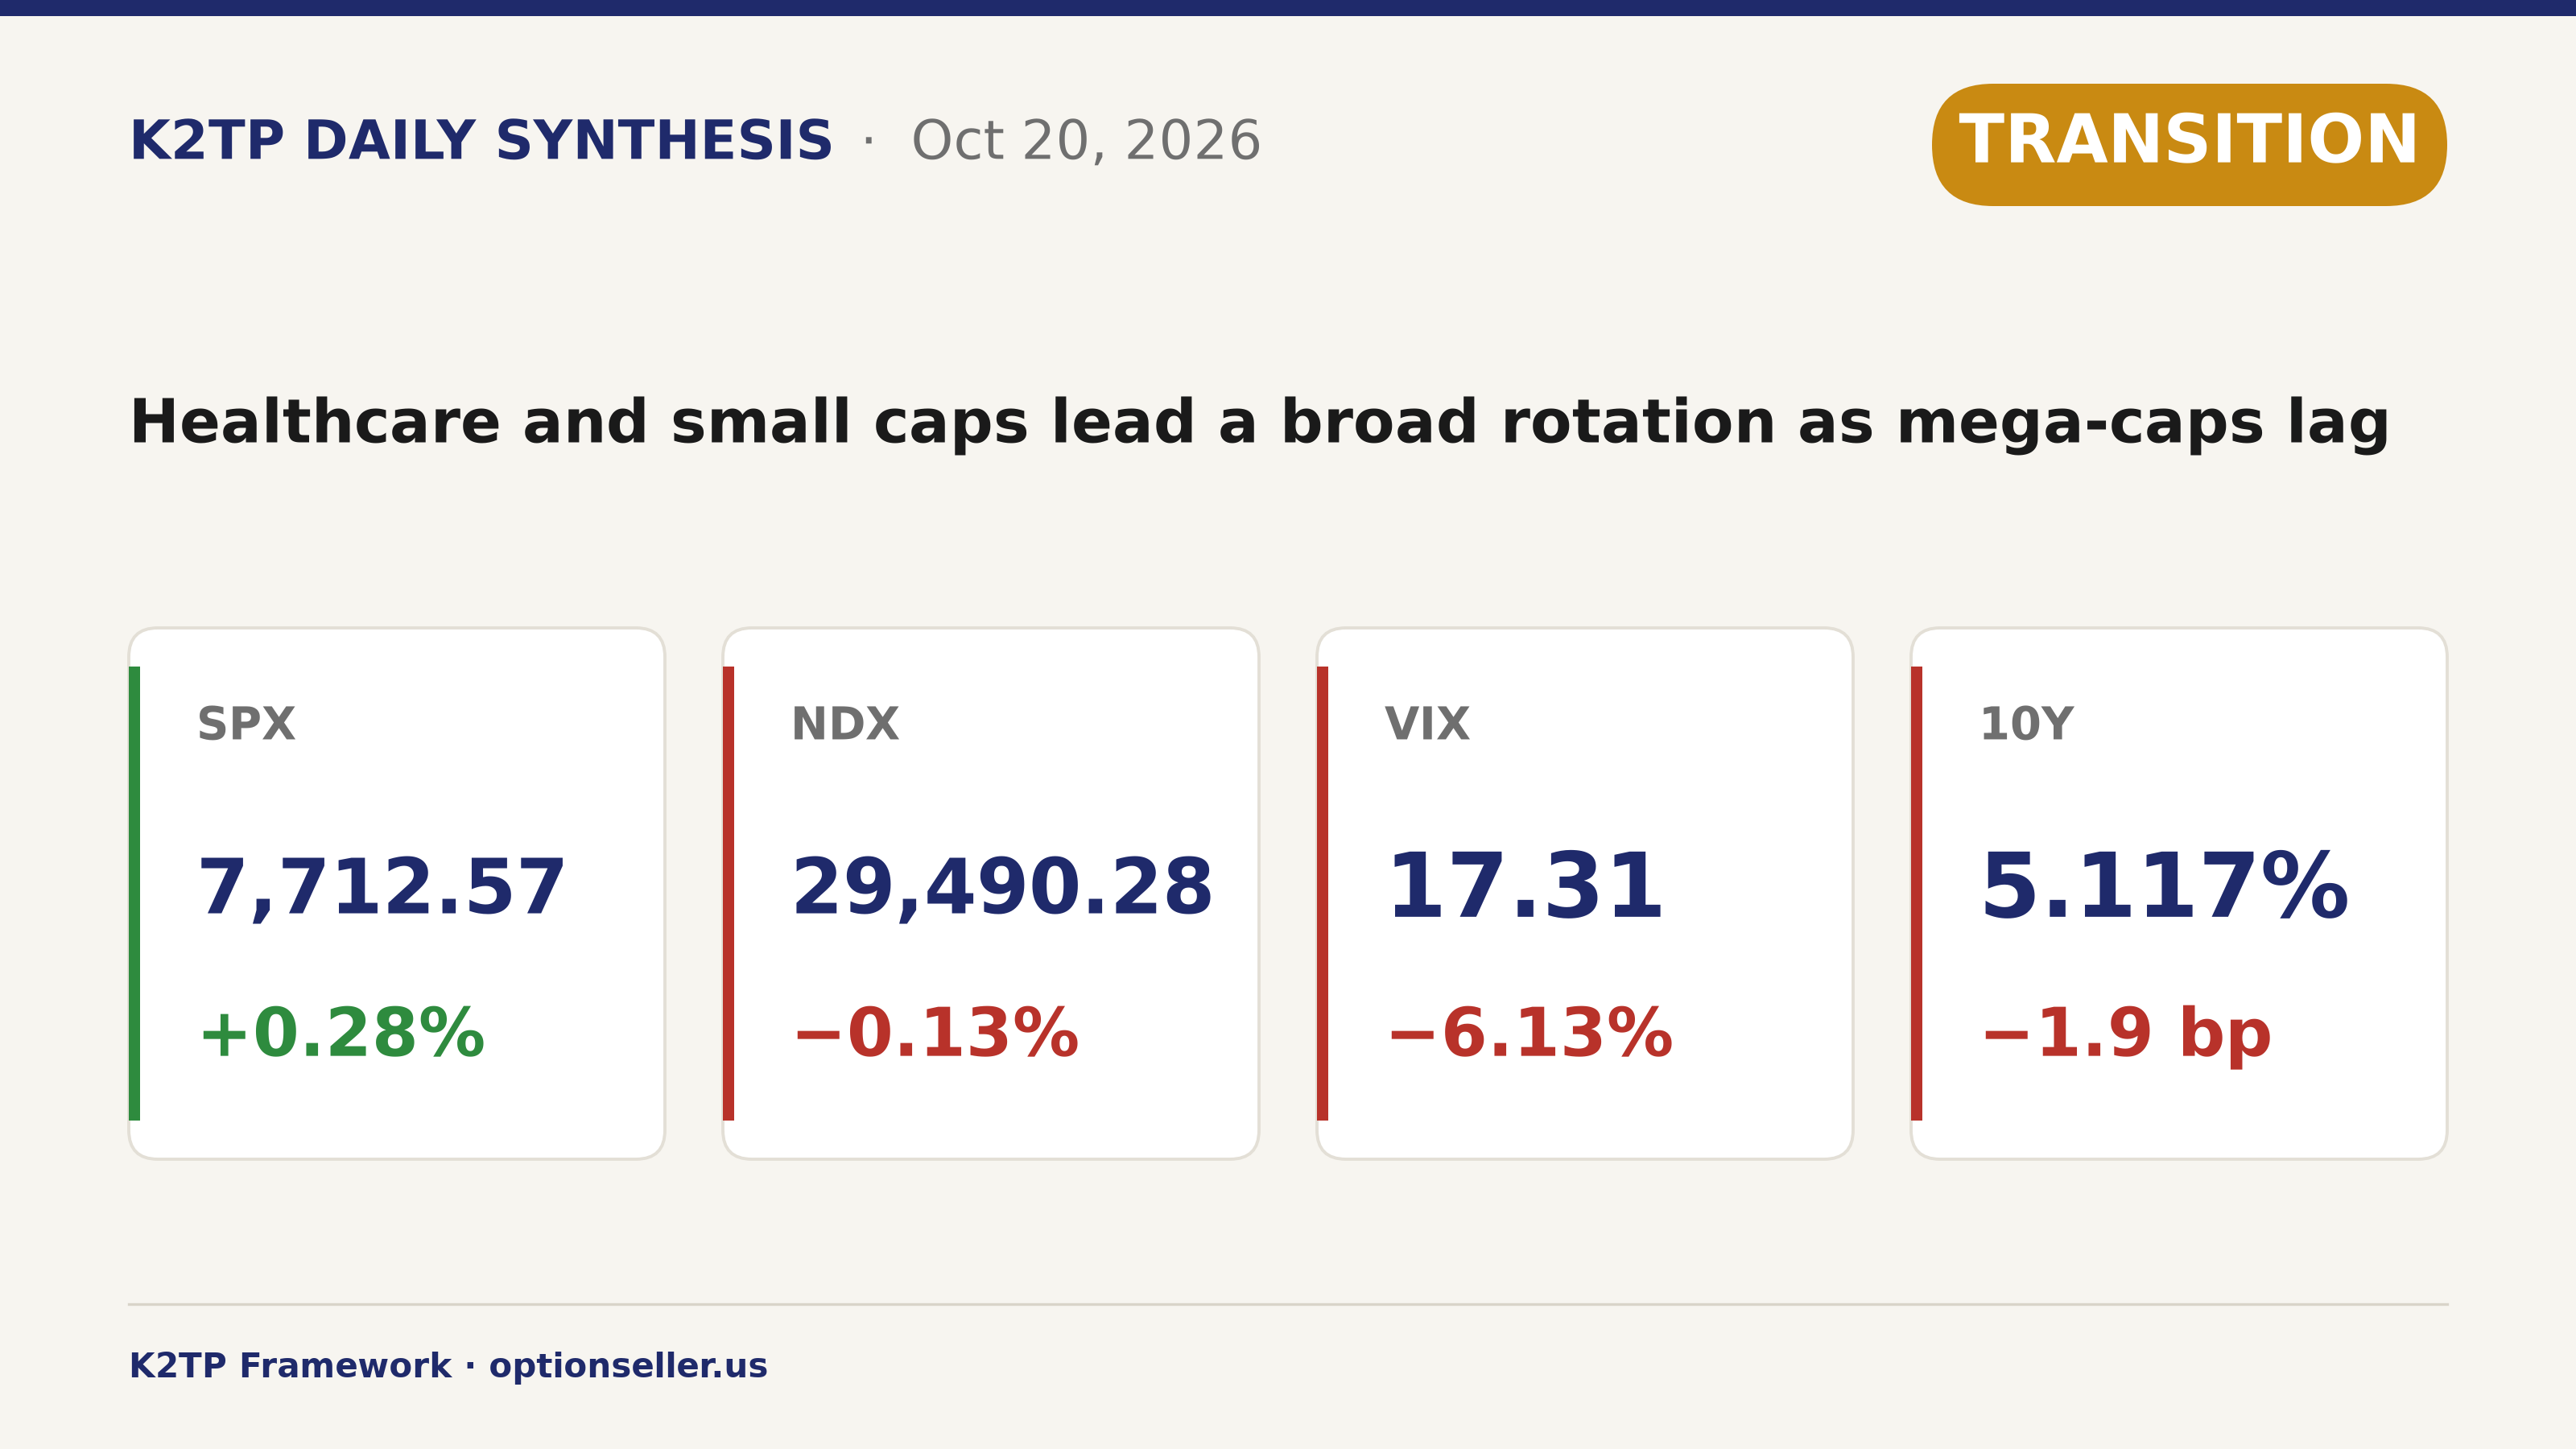
SPX +0.28%, NDX −0.13%, VIX −6.13%. Breadth was the best in weeks, long-end yields fell with oil and housing, and after the close SpaceX lifted the AI complex.
KEY HEADLINES
- SPX +0.28% to 7,712.57, the Dow +1.02%, RUT +1.65% (its biggest gain since Aug 4, per Reuters) and equal-weight RSP +1.15%; NDX −0.13%
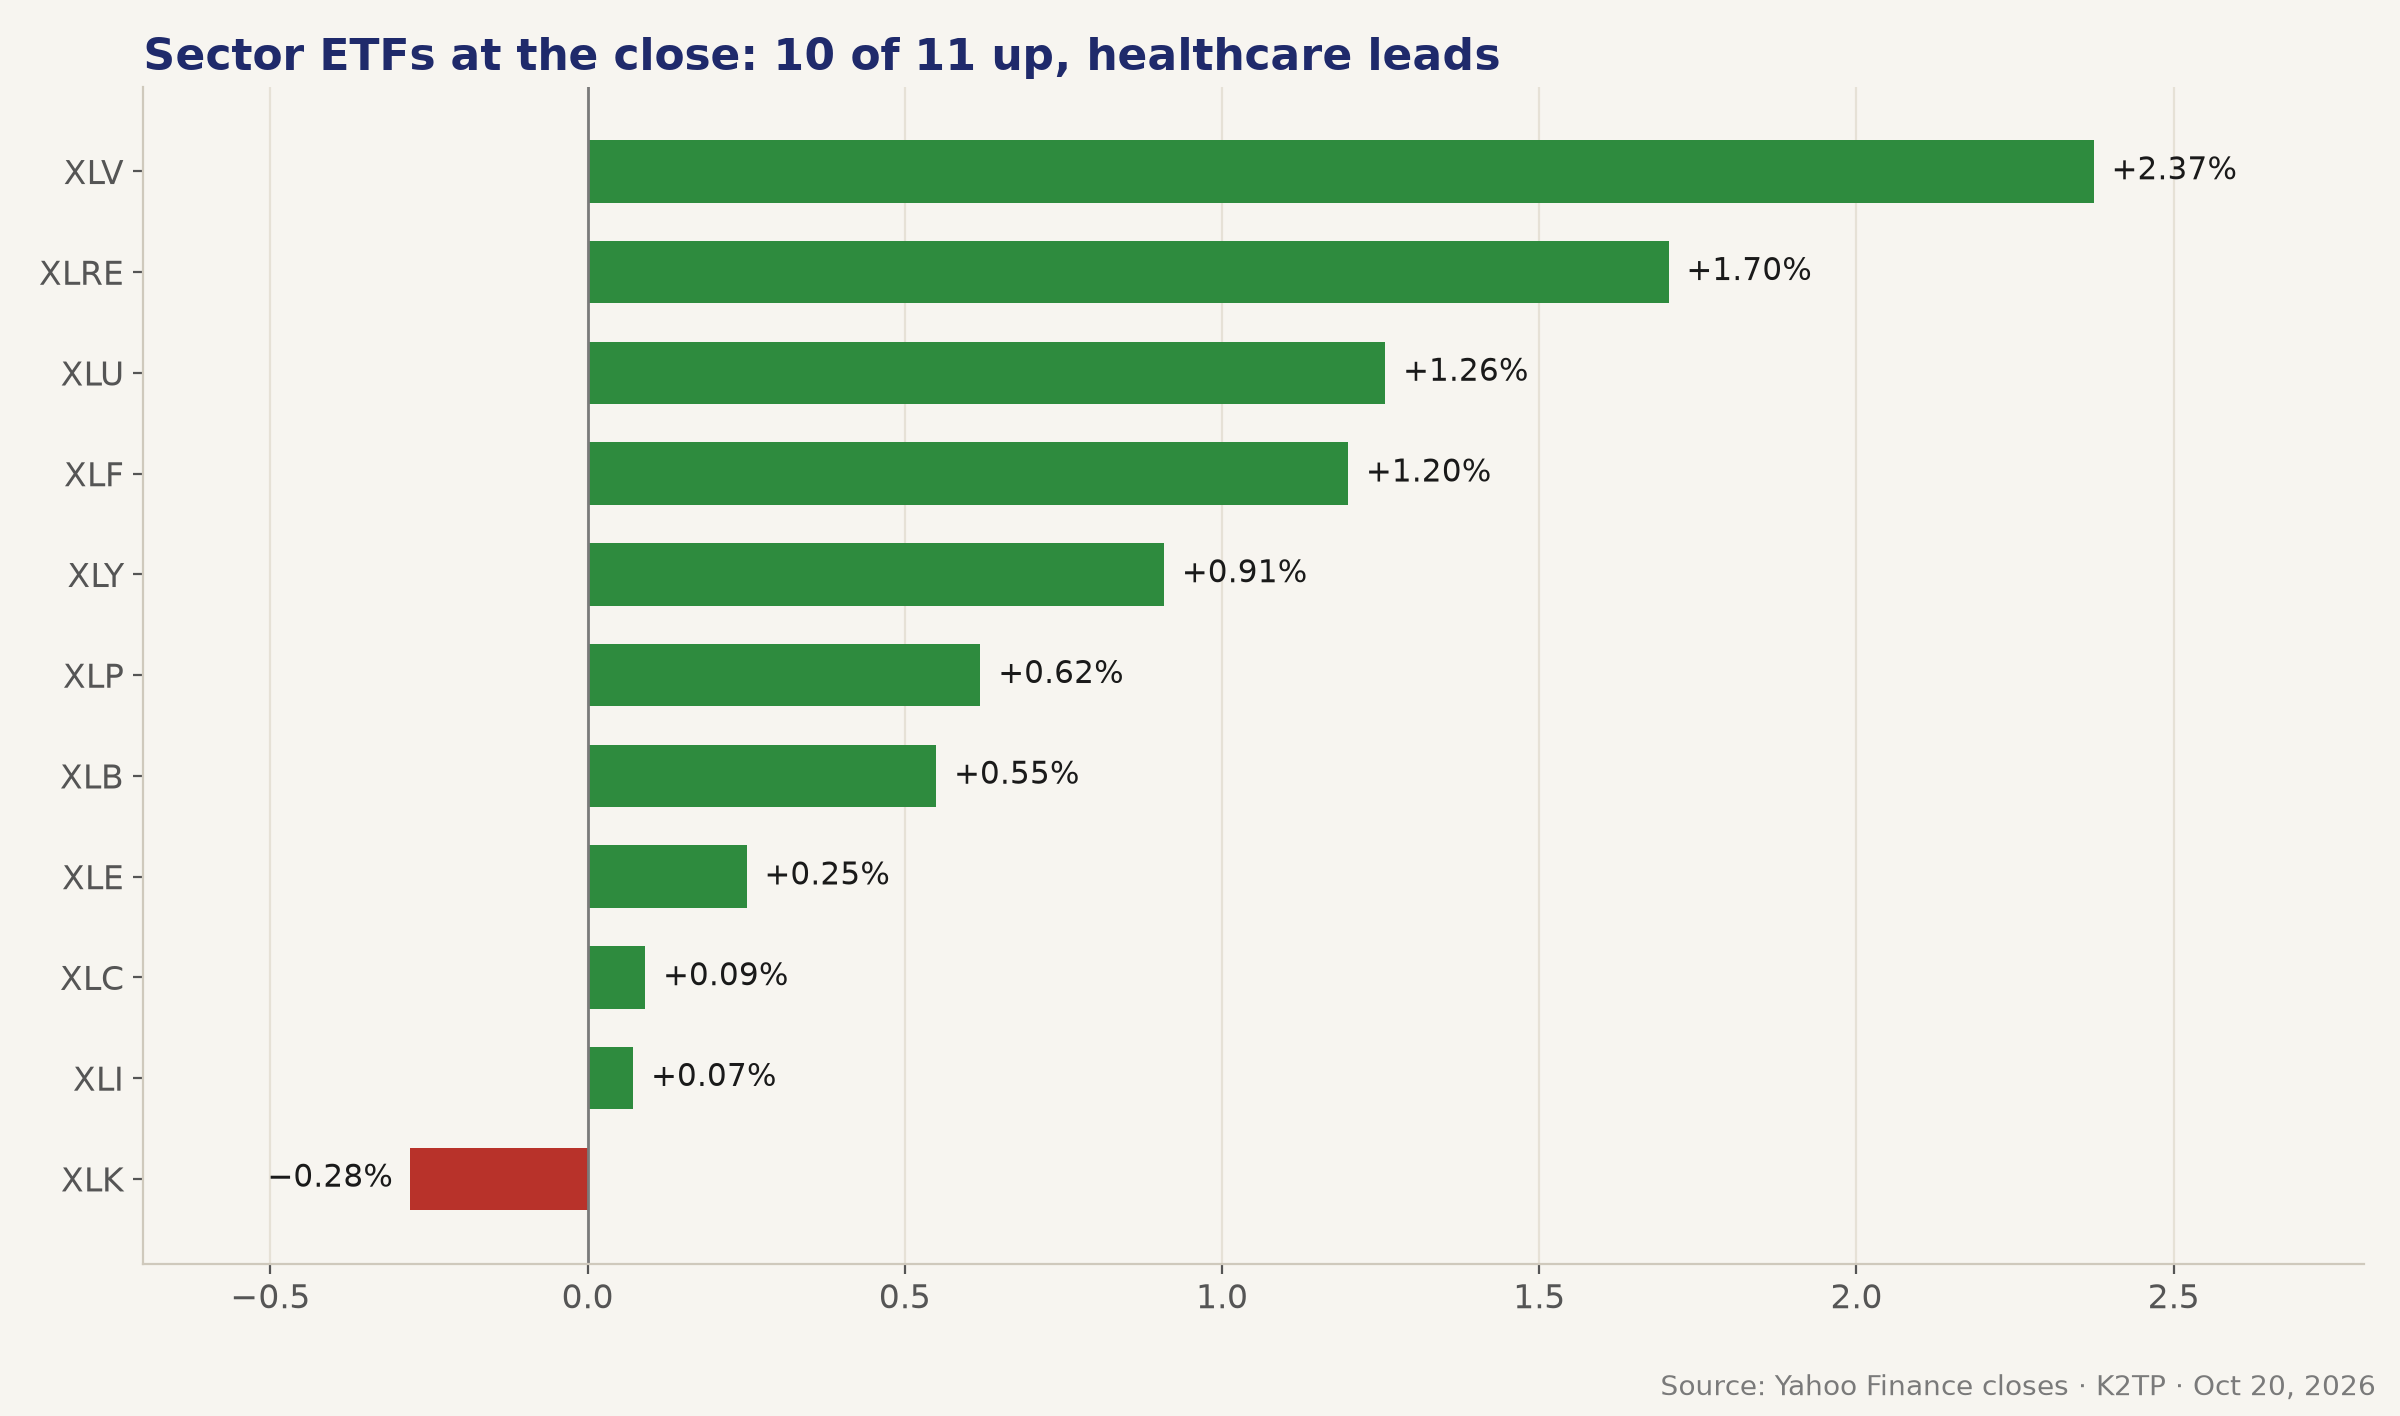
- 9 of 11 S&P 500 sectors rose; healthcare hit a record, XLV +2.37%, and LLY (+3.49%) was the S&P 500's biggest point contributor
- META −1.59%, GOOGL −1.13% and AAPL −1.00% kept NDX red; the S&P 500 value index rose 0.9% while growth fell 0.2% (Reuters)
- NYSE advancers outnumbered decliners 2.04-to-1, a full reversal from Monday
- Weak housing: September starts 1.221M (1.30M expected); pending home sales −7.3% to the lowest since the series began in 2001
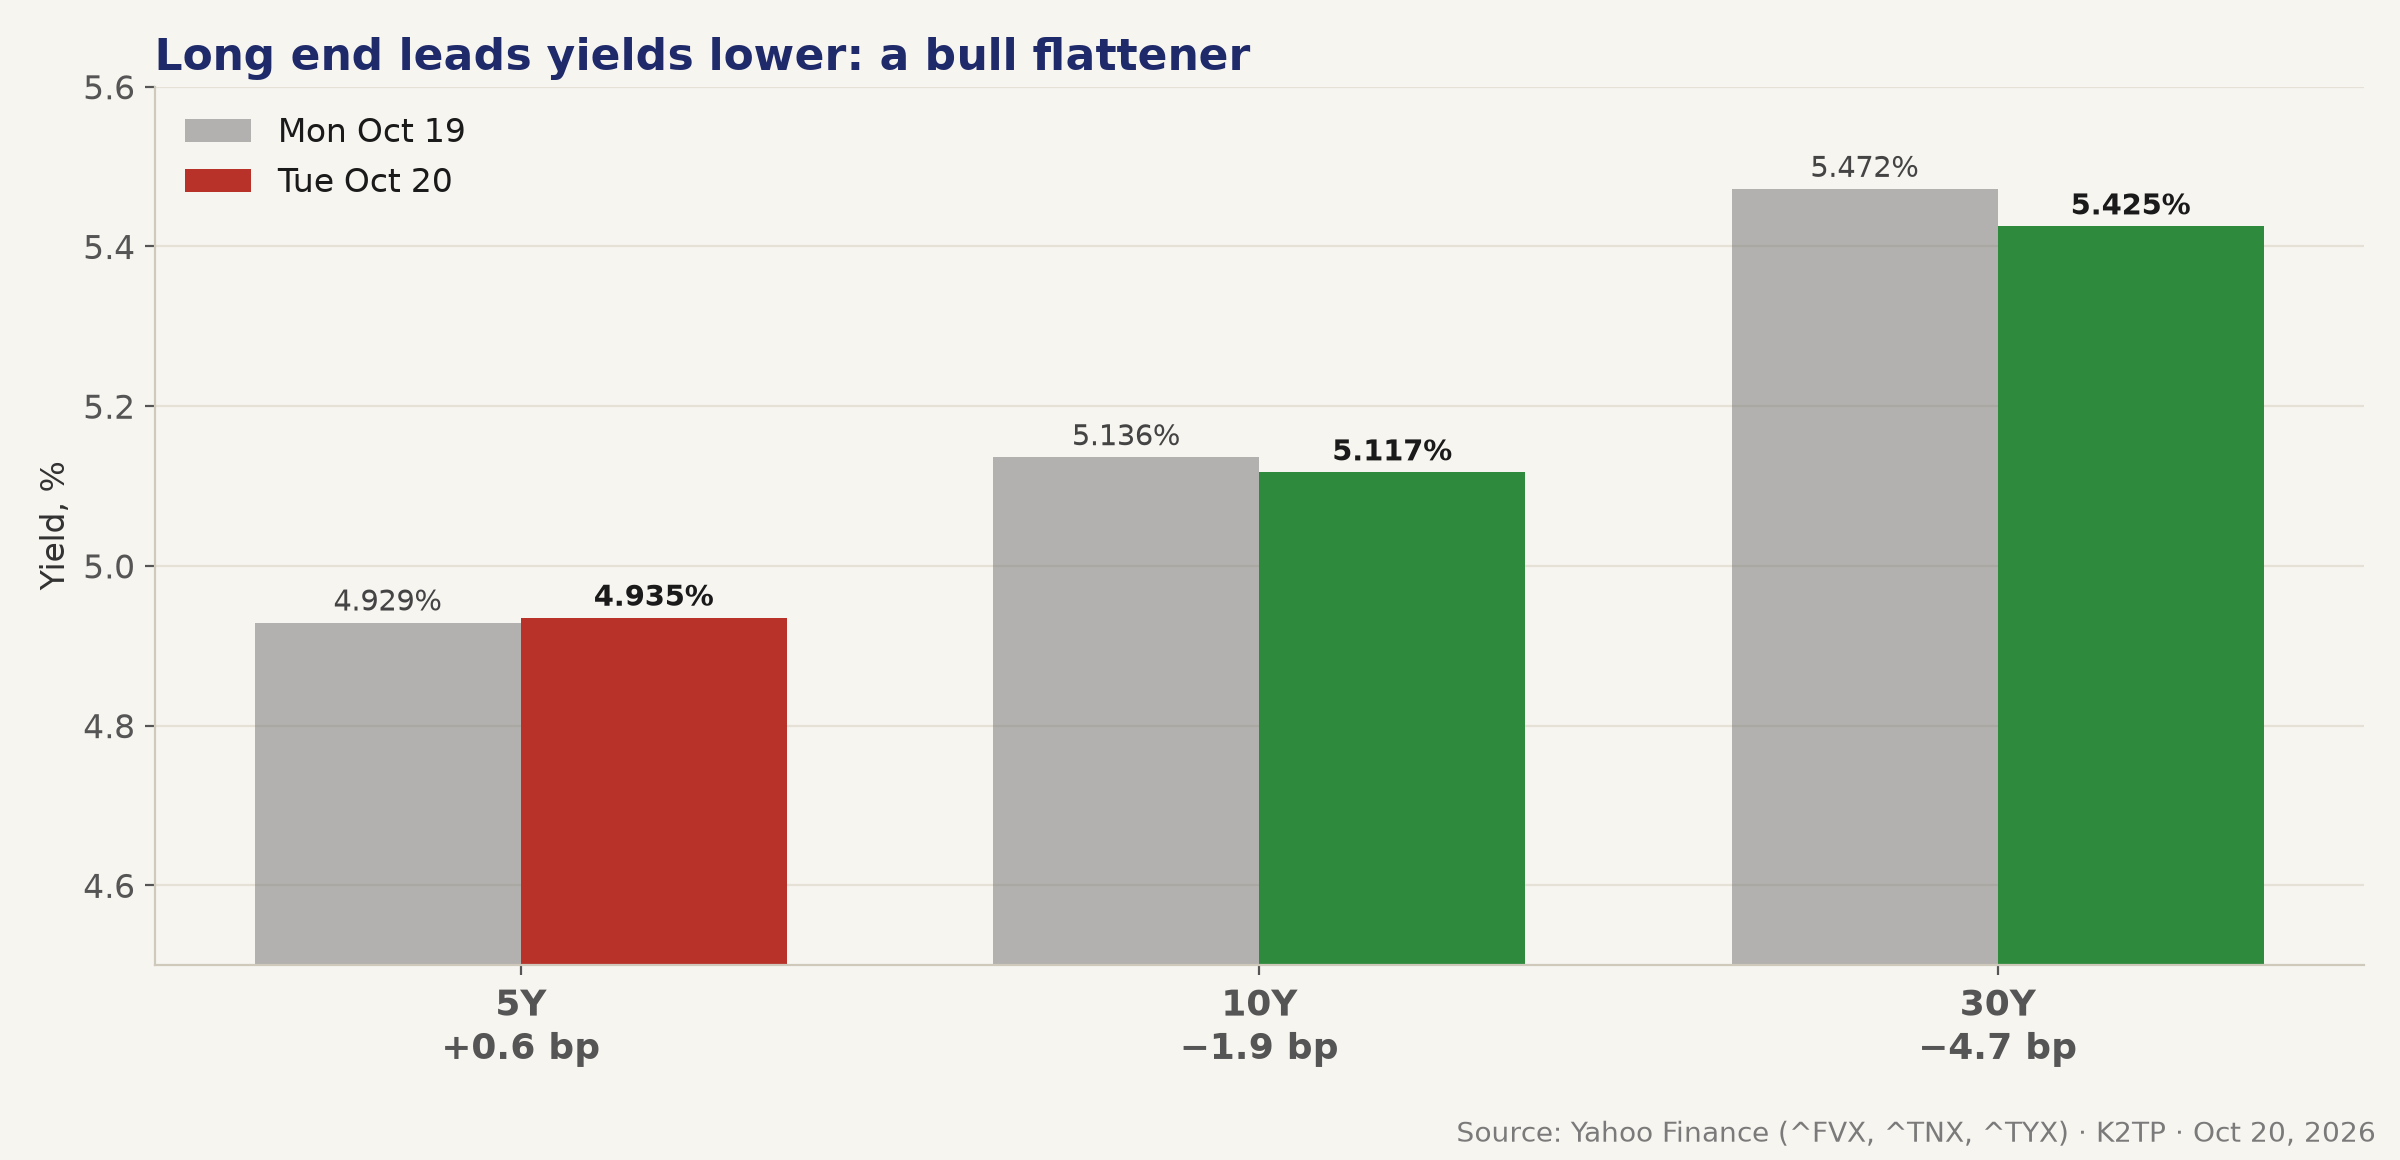
- 10Y −1.9 bp to 5.117% and 30Y −4.7 bp to 5.425%; October hike odds fell from 17.2% to 14.9% (CME FedWatch via Reuters)
- Brent touched $111.99, then settled −0.69% at $108.79; December WTI settled at $97.82
- VIX 17.31 (−6.13%), VVIX 97.15 (−9.15%)
- After hours: SpaceX +8.06% on 161% revenue growth, lifting SMCI +15.52%, AMD +3.04% and NVDA +2.09%; Netflix −5.78% and Intuitive Surgical −6.95%
- Regime: 🟡 TRANSITION all day, leaning RISK-ON on breadth and vol, with mega-cap tech still the holdout
A BROAD ROTATION: HEALTHCARE HITS A RECORD, SMALL CAPS BREAK OUT
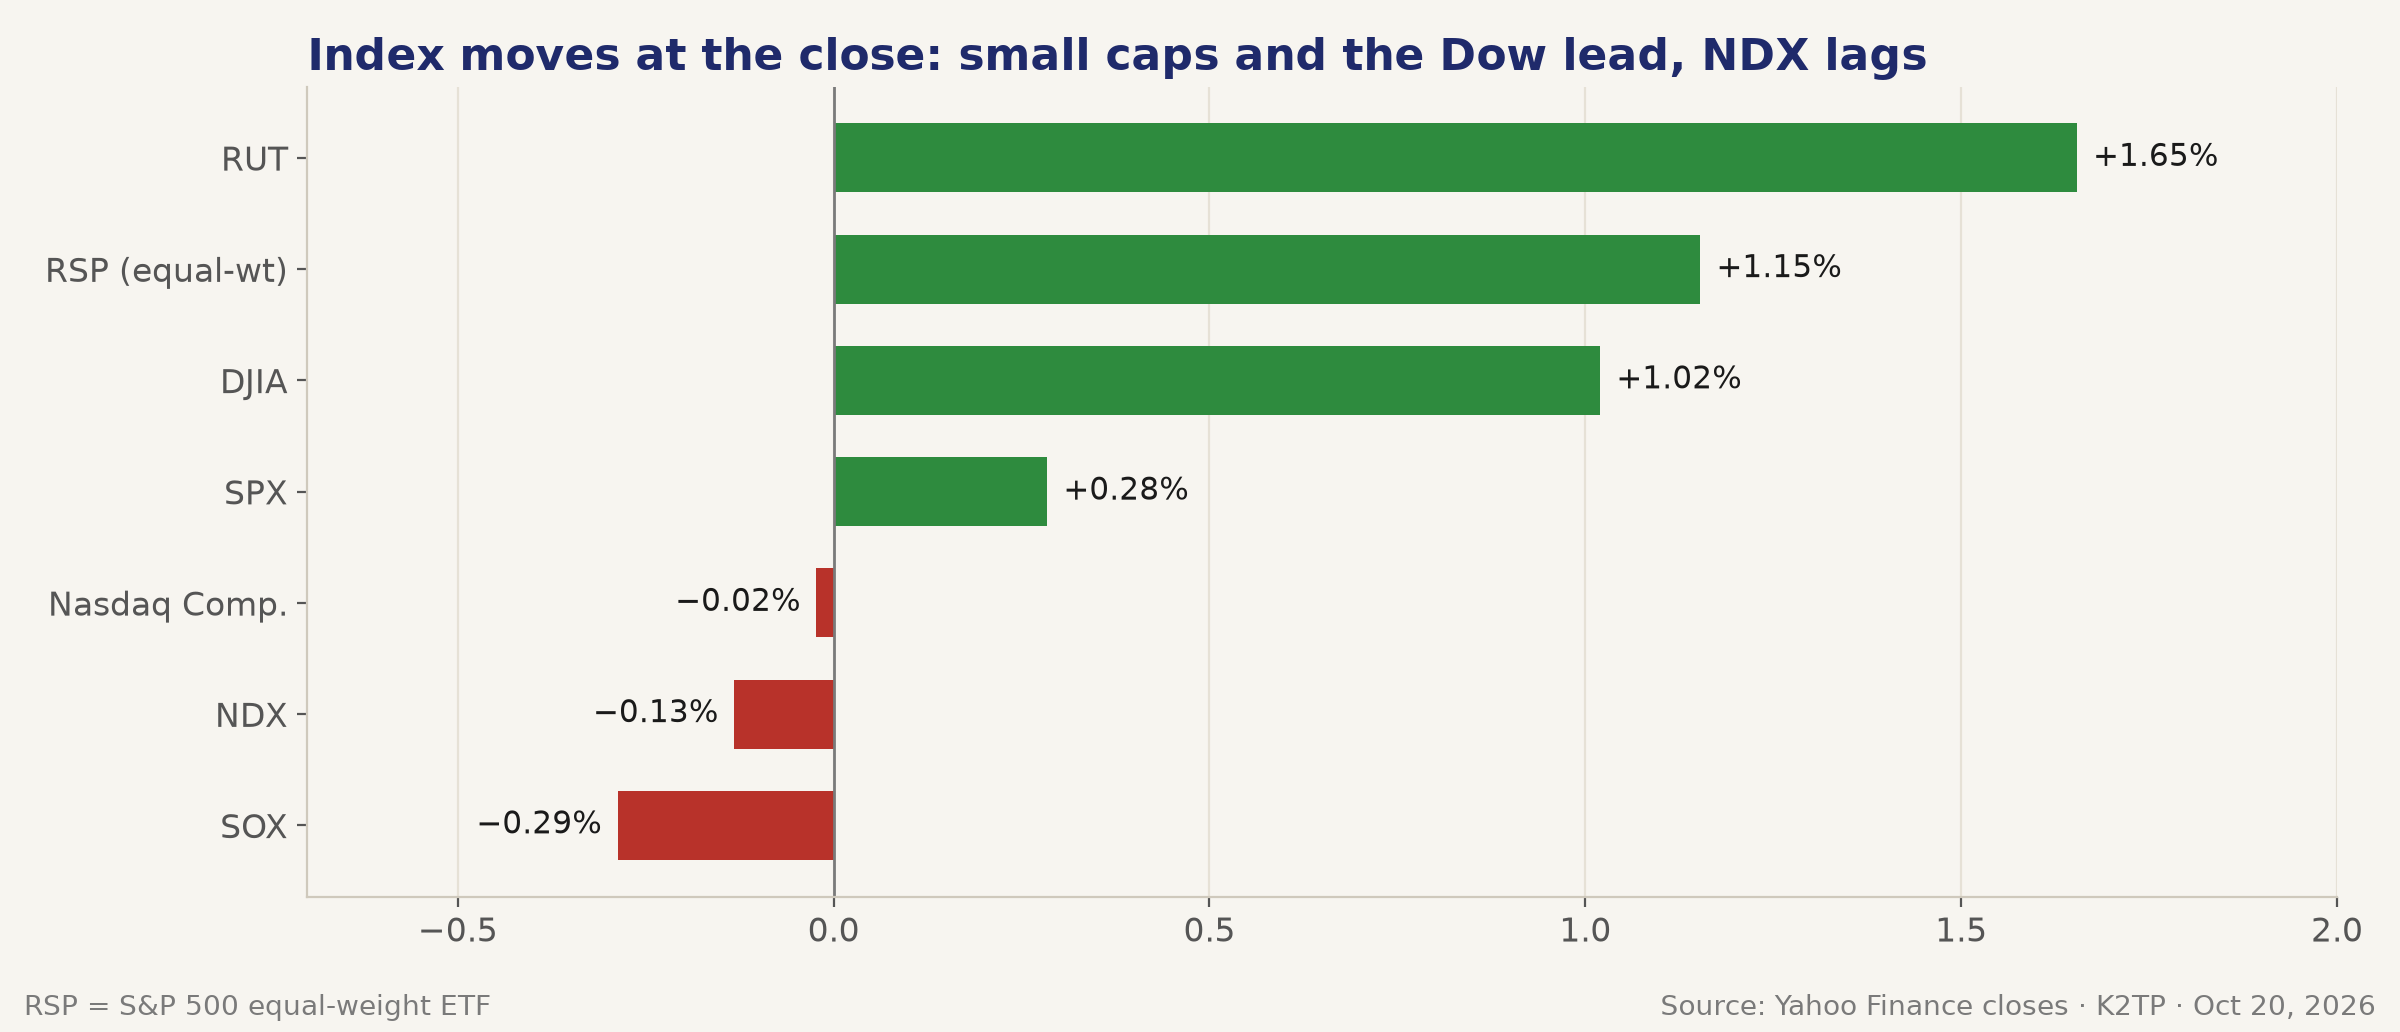
- RUT +1.65% to 2,773.42 and the Dow +1.02% to 52,495.88, while SPX rose only 0.28% and NDX fell 0.13% 🟢
- RSP +1.15% beat SPX by 87 bp; on Monday it lagged by 73 bp
- Sector ETFs: 10 of 11 up, led by XLV +2.37%, XLRE +1.70%, XLU +1.26%, XLF +1.20% and XLY +0.91%; only XLK fell (−0.28%)
- Healthcare: LLY +3.49% to $1,283.66 (high $1,311.75), MRK +3.25%, UNH +3.04%; the S&P 500 healthcare index set a record (Reuters)
- Mega-caps: META −1.59%, GOOGL −1.13%, AAPL −1.00% (Loop Capital downgrade before the open), MSFT −0.31%, NVDA −0.29%; the S&P communication services index fell 0.9% (Reuters)
- SOX −0.29% to 11,283.81 after an 11,043.24–11,460.13 range
→ Money left crowded AI and communication names for healthcare, banks, real estate and small caps. Breadth was far better than Monday, but SPX can't break out while its biggest weights fall.
EARNINGS IN THE SESSION: GUIDANCE GETS PAID, SMALL BEATS DON'T
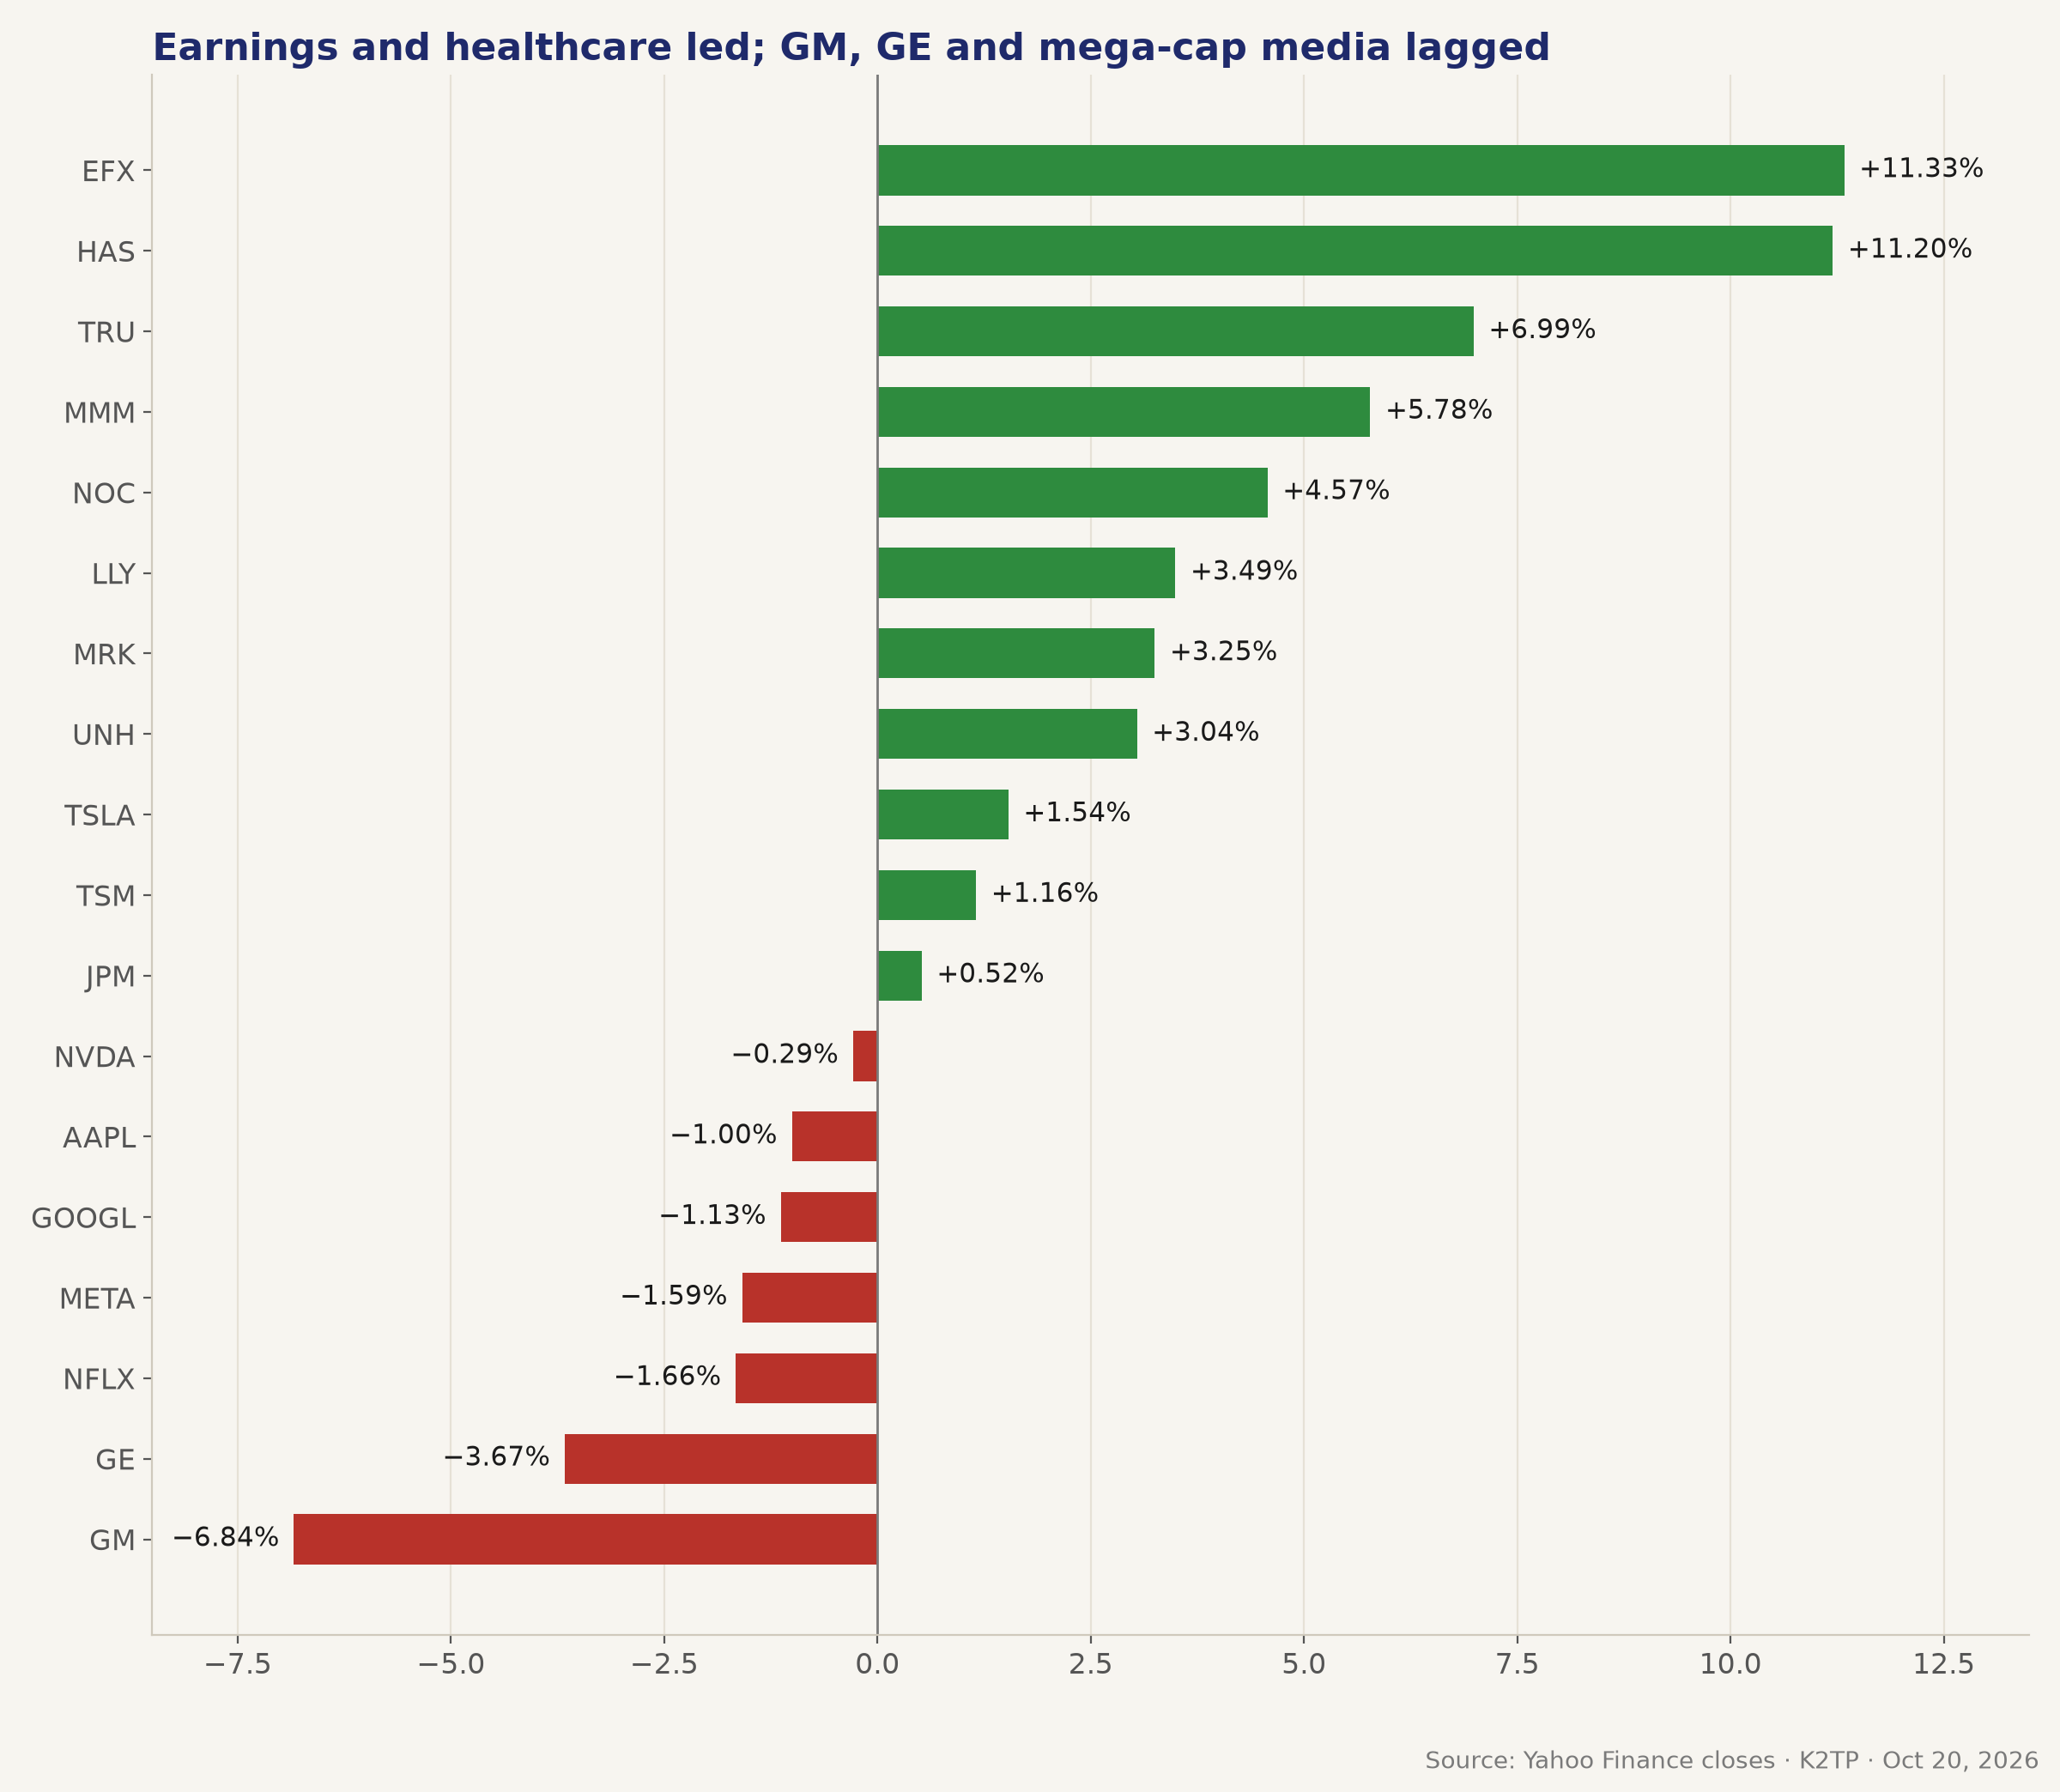
- Equifax (EFX) +11.33% and Hasbro (HAS) +11.20% led the S&P 500; TransUnion (TRU) +6.99% alongside Equifax 🟢
- EFX: Q3 revenue +10% y/y, in line, even as it trimmed the midpoint of its 2026 revenue guidance to $6.661B on weak mortgage activity (Benzinga)
- 3M (MMM) +5.78%: adjusted EPS $2.50 vs $2.38 (LSEG), a raised 2026 profit forecast and an expanded Amazon data-center deal with a warrant worth over $521M
- Northrop (NOC) +4.57%: EPS $7.89 vs $7.18 (LSEG); revenue $11.12B, slightly short of $11.14B
- General Motors (GM) −6.84%, the S&P 500's worst performer: adjusted EPS $3.70 vs $3.69 and a $20B buyback, but a full-year EPS guide of $12.75–$13.75 against a $13.41 consensus midpoint (Benzinga) 🔴
- GE Aerospace (GE) −3.67%: adjusted EPS $2.25 vs $2.01 and 2026 EPS guidance raised to $8.00–$8.10, but free cash flow of $2.0B missed the $2.2B estimate
- RTX closed only +0.64% after a 2.24% pre-market gain, despite beating on both lines
→ Good numbers weren't enough. The market paid for raised guidance and new business lines, and took profits in crowded industrials that only beat narrowly.
WEAK HOUSING PULLS LONG-END YIELDS LOWER
- September housing starts: 1.221M vs 1.30M expected and a revised 1.288M in August (−5.2%); single-family −4.6% to 859K; permits 1.400M (−0.2%) 🔴
- September pending home sales: −7.3% m/m and −11.3% y/y to an index of 66.0, the lowest since the series began in 2001; NAR blamed "fast-rising mortgage rates" 🔴
- Mortgage rates averaged 7.40% last week, the highest in nearly three years (Reuters)
- Closing yields: 10Y 5.117% (−1.9 bp), 30Y 5.425% (−4.7 bp), 5Y 4.935% (+0.6 bp); 5s30s narrowed from 54.3 bp to 49.0 bp (a bull flattener)
- 2Y: no closing print yet; about 4.76% at pre-close (Benzinga)
- October hike odds: 17.2% → 14.9% (CME FedWatch via Reuters), versus 22.1% a week ago and 57.6% a month ago. Cboe, citing CME FedWatch: about 83% odds of an October hold, but 73.7% odds of a December hike
→ Weak housing and softer oil pulled the long end down and helped rate-sensitive groups. But the market still prices tightening by December, so oil remains the swing factor for rates.
OIL REVERSES FROM A SIX-MONTH HIGH
- Brent touched $111.99 early on Houthi attacks on Saudi infrastructure, then settled at $108.79 (−0.69%) 🟢
- Reuters: traders weighed a meeting between Iran's president and Pakistan's army chief, a US-Iran mediator
- Unconfirmed (Yahoo Finance, Benzinga): a US official said President Trump has no plans to attack Iran before the midterm elections, while Iran's Revolutionary Guard threatened undersea cables in the Strait of Hormuz
- December WTI settled at $97.82; the November contract expired near $101.09, versus $103.66 on Monday
- Tonight (around 6:55 PM PT): Brent $110.17, December WTI $99.00 (Yahoo)
- United Airlines (UAL) sees Q4 jet fuel at $4.80 a gallon vs $3.90 in Q3 and cut guidance
→ Oil stopped adding pressure during the session, but Brent's bounce tonight shows Gulf headlines remain the biggest two-way risk.
SPX SWEEPS BOTH EDGES, THEN SETTLES IN THE MIDDLE
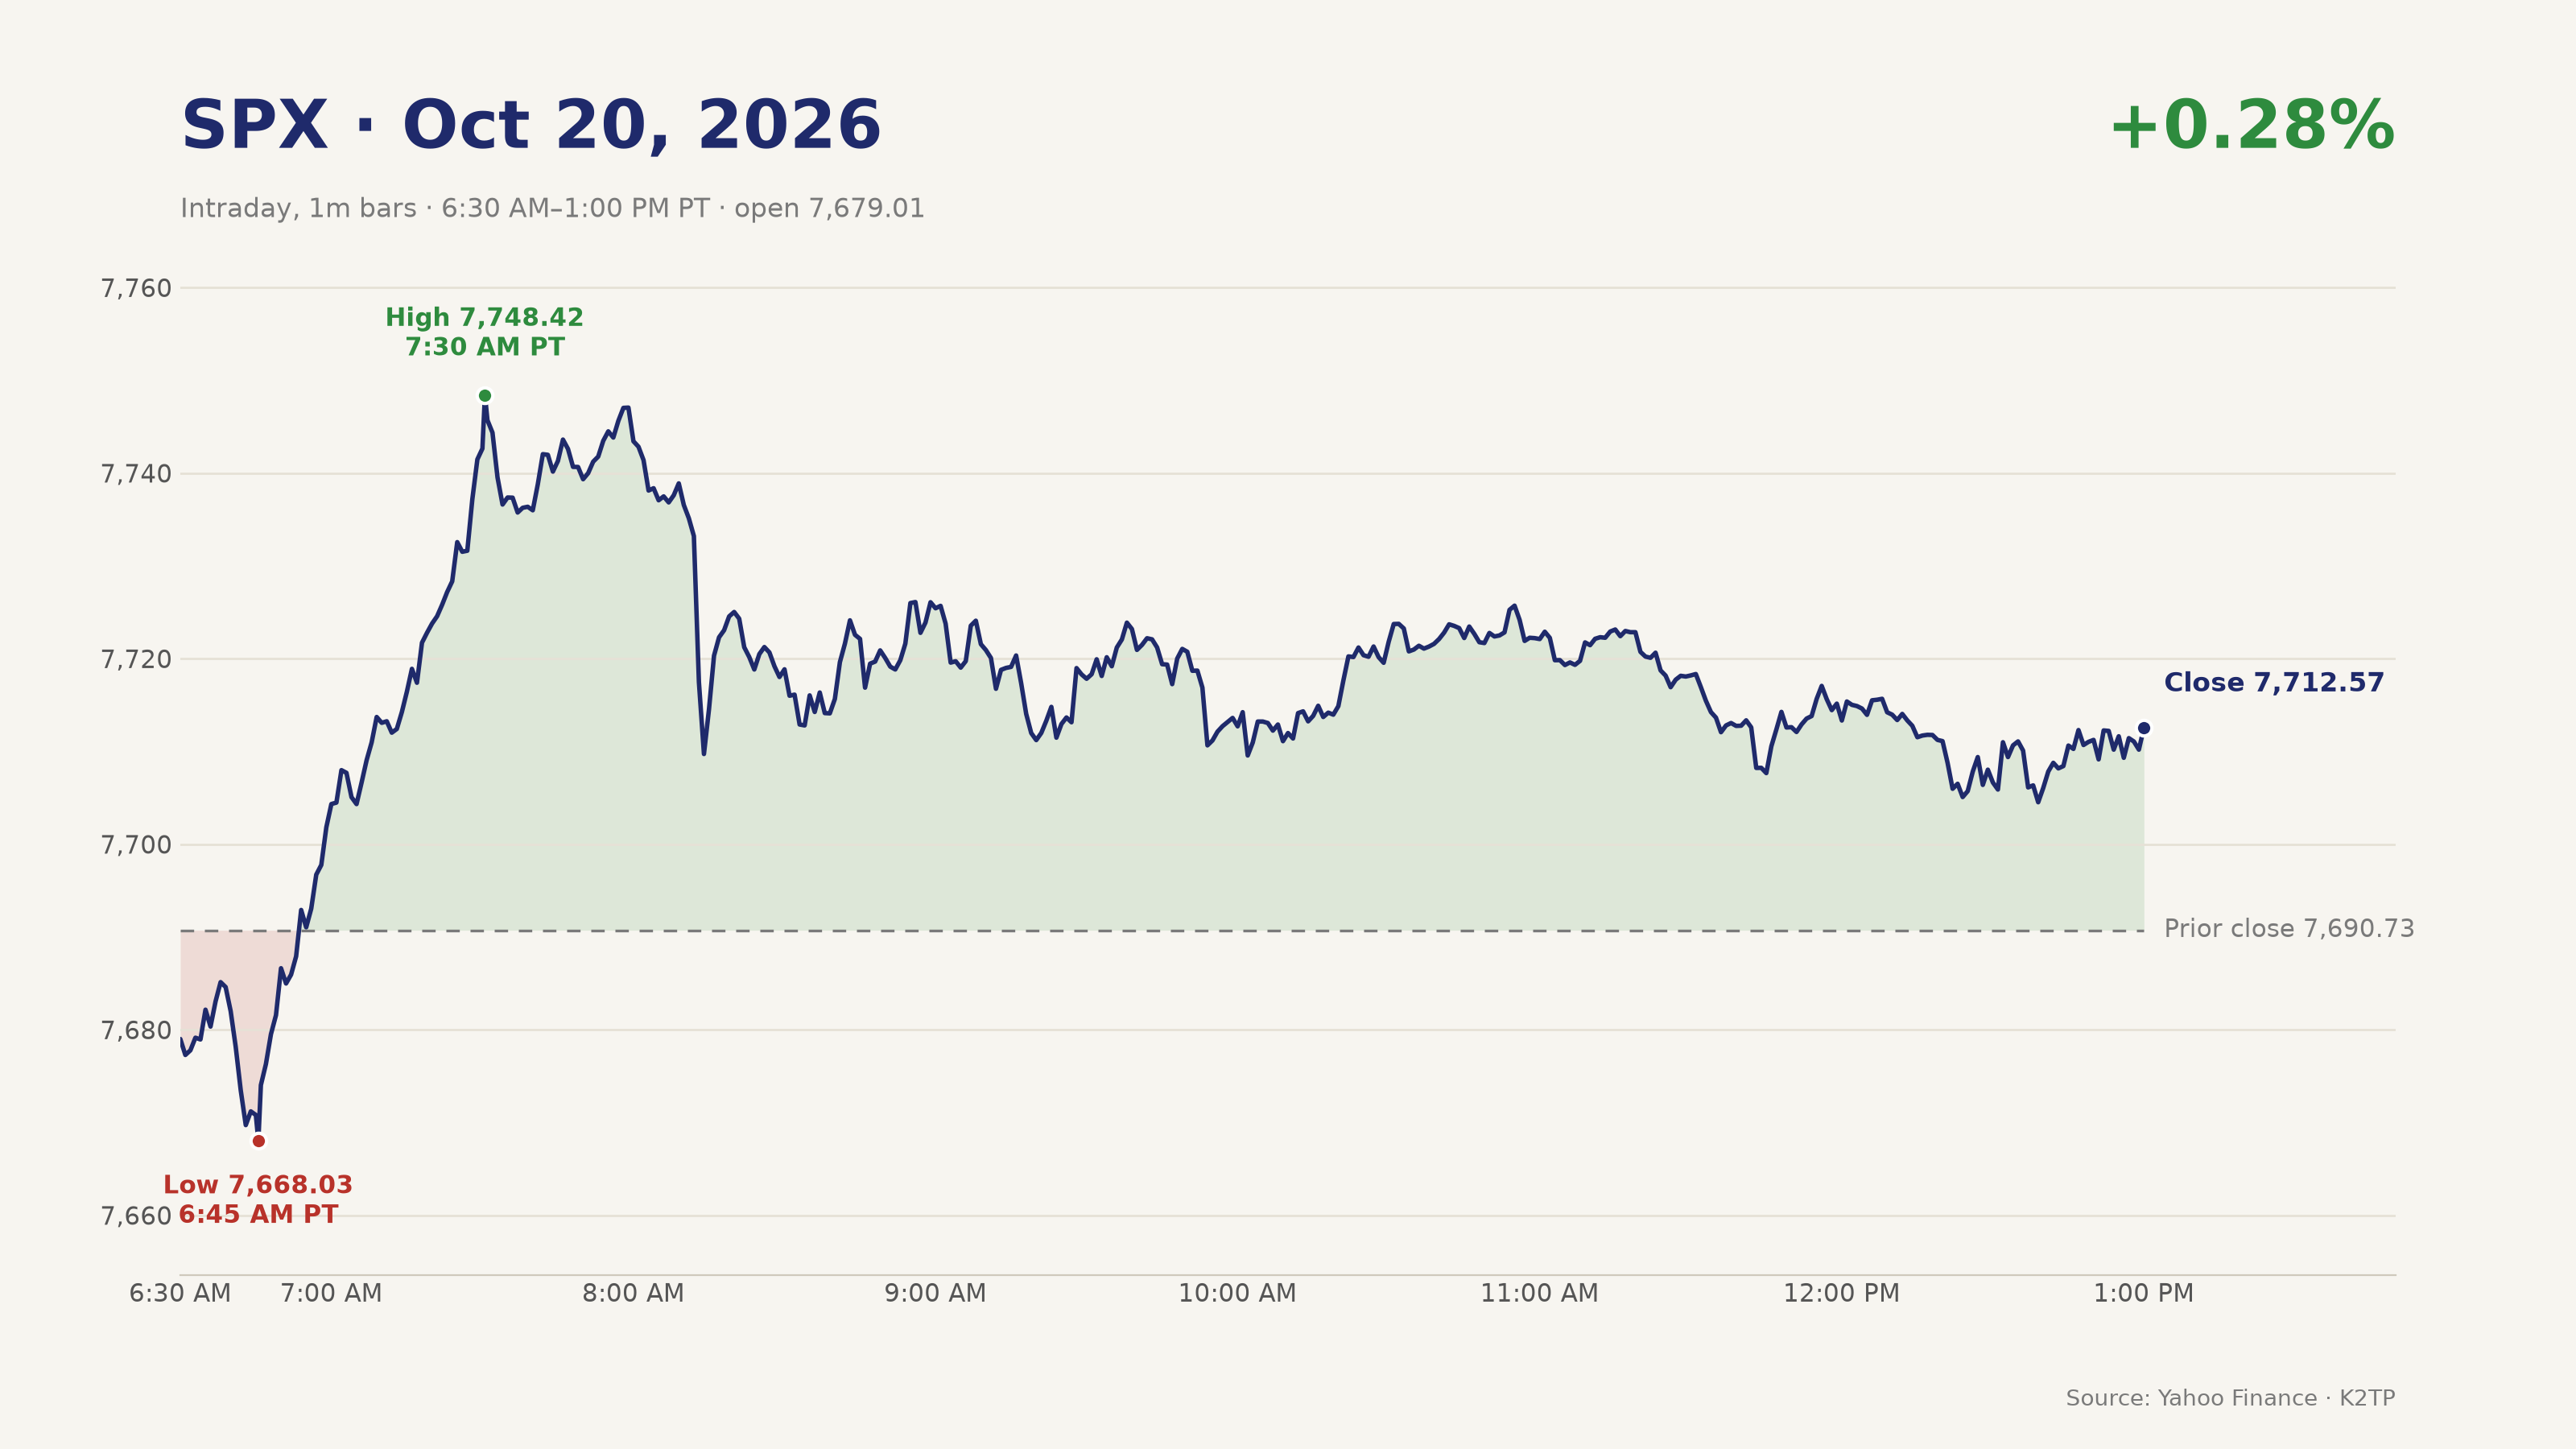
- Opened at 7,679.01, below Monday's close; low of 7,668.03 at 6:45 AM PT, under the 7,684.79 Bear line
- High of 7,748.42 at 7:30 AM PT, above the 7,731.18 Bull line, then a sharp drop just after 8:00 AM PT
- Midday 7,713.60 (+0.30%); pre-close 7,713.87 (+0.30%)
- Closed at 7,712.57 (+21.84 points), 35.85 points below the high
- Neither Pre-Close trigger fired (Bull: SPX above 7,748.42 with VIX under 17.25; Bear: SPX under 7,690.73 with VIX above 18.44); VIX closed at 17.31, just 0.06 above the 17.25 line
→ An 80-point range in the first hour, then a flat day. Breadth had buyers, but not enough for SPX to clear the high while mega-caps stayed weak.
AFTER HOURS: SPACEX LIFTS AI, NETFLIX AND INTUITIVE SLIDE
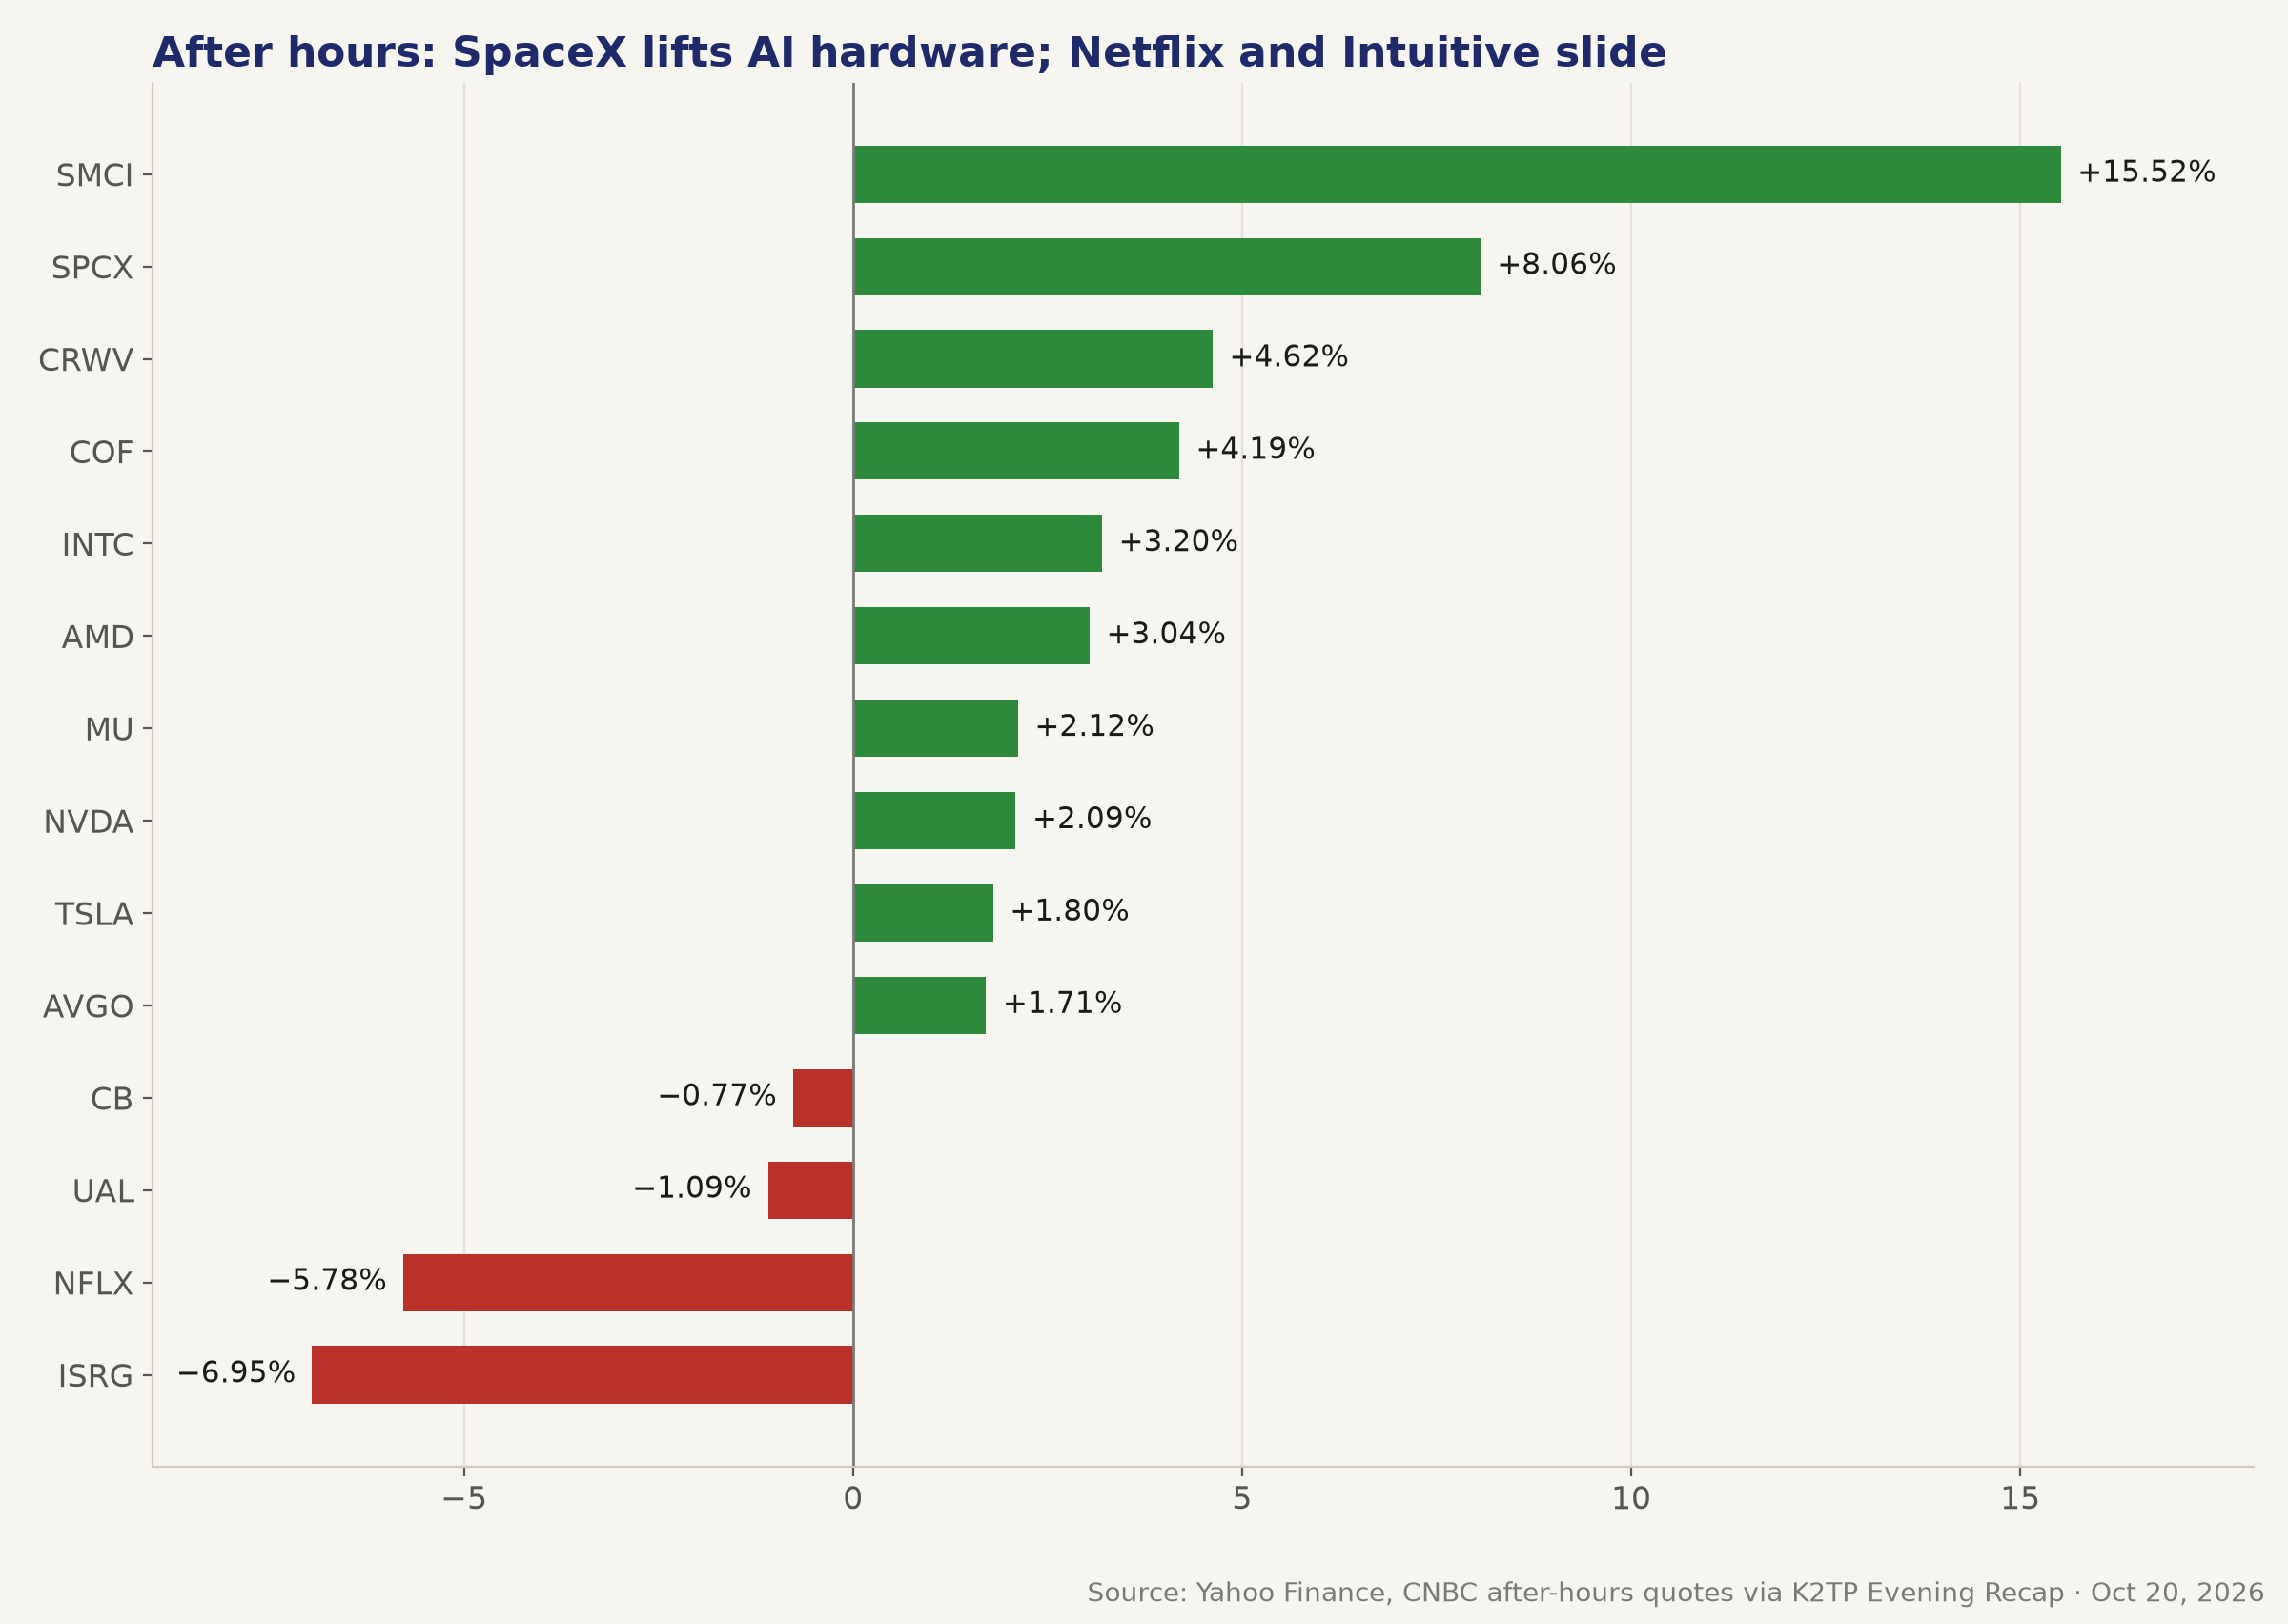
- SpaceX (SPCX) +8.06% to $159.70: revenue $14.58B (+161% y/y) vs $12.72B (LSEG); net income $4.4B; Super Intelligence revenue $7.56B; Q3 capex $19.59B; Q1 2027 revenue guide of $33B–$37B vs a $22.2B estimate (CNBC) 🟢
- Elon Musk said a merger with Tesla would be a "good idea" and that both boards have formed special committees to discuss a tie-up; TSLA +1.80% after hours. SpaceX's adjusted EPS differs by source (45 cents per CNBC, 35 cents per TipRanks)
- AI read-through: SMCI +15.52% after raising its fiscal Q1 revenue guide to $18.5B–$19.5B from $14.5B–$15.5B; CRWV +4.62%, INTC +3.20%, AMD +3.04%, MU +2.12%, NVDA +2.09%, AVGO +1.71%
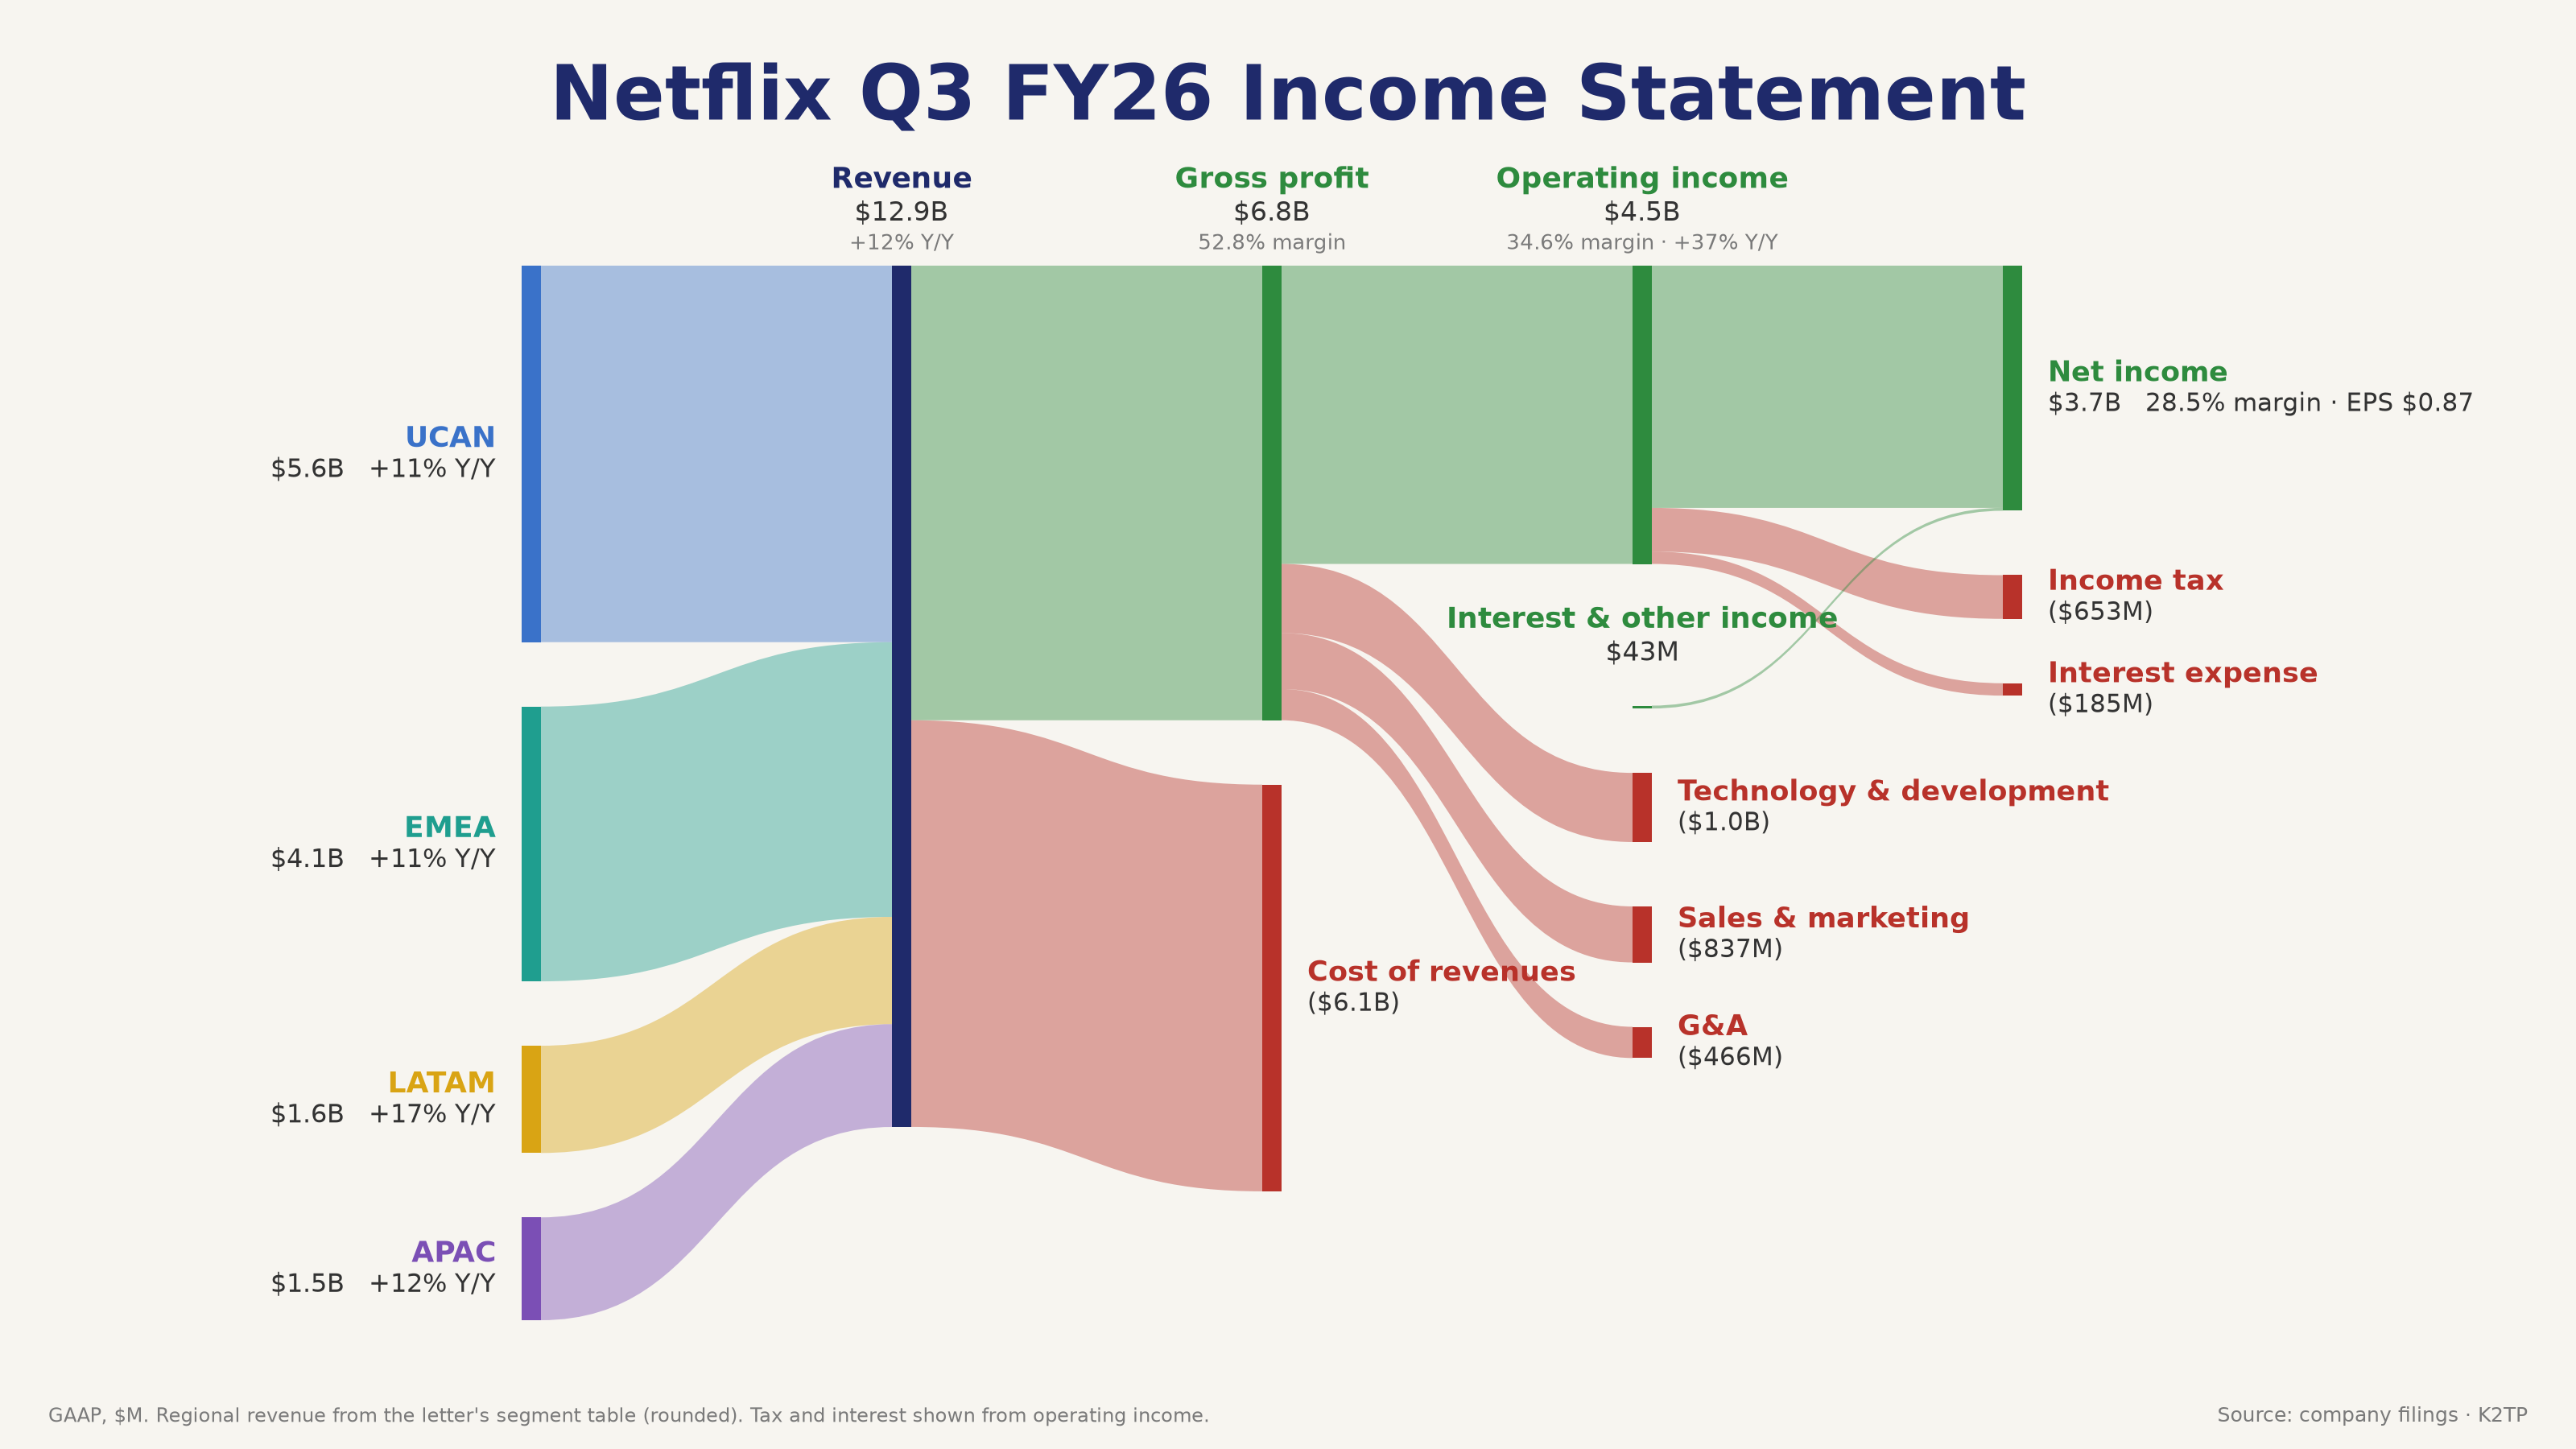
- Netflix (NFLX) −5.78% to $64.72: revenue $12.87B (+12% y/y), in line with its forecast; EPS $0.87 vs $0.82 expected; operating margin 34.6% (from 28.2%) 🟢. But the Q4 EPS guide is $0.67 vs $0.73, the Q4 operating margin guide is 26.0% (including ~120 bp from headcount reductions), 2026 ad revenue was cut to ~$2.7B from ~$3B, and the 2026 FCF outlook to ~$12.0B from $12.5B 🔴
- Intuitive Surgical (ISRG) −6.95%: revenue $3.05B, non-GAAP EPS $3.00; a $450M antitrust-settlement charge; 2026 procedure growth narrowed to 14%–15%
- Capital One (COF) +4.19%: net income $3.5B, EPS $5.61, adjusted EPS $6.69. United Airlines (UAL) −1.09% after missing on revenue and EPS. Chubb (CB) −0.77% despite a beat
- Tonight (around 6 PM PT): NQ +0.64% to 29,866, ES +0.21% to 7,771.25
→ SpaceX shows AI spending is still very strong, enough to revive chips after hours. Netflix was punished for guidance and ads, not for Q3. Meta and Tesla on Wednesday night decide whether tech joins the rotation.
MARKET: STRONG BREADTH, MEGA-CAPS SIT OUT
Indices (close):
- SPX 7,712.57 (+0.28%), day range 7,668.03–7,748.42
- NDX 29,490.28 (−0.13%); Nasdaq Composite 26,424.82 (−0.02%)
- DJIA 52,495.88 (+1.02%)
- RUT 2,773.42 (+1.65%)
- RSP 215.86 (+1.15%)
- SOX 11,283.81 (−0.29%)
Session path: ES −0.15% and NQ −0.43% pre-market as the Kospi fell 3.73% and AI names were sold again. SPX opened at 7,679.01, fell to 7,668.03 at 6:45 AM PT, peaked at 7,748.42 at 7:30 AM PT, was 7,713.60 at midday and 7,713.87 at pre-close, and closed at 7,712.57.
Sector Rotation:
- Gainers: XLV +2.37%, XLRE +1.70%, XLU +1.26%, XLF +1.20%, XLY +0.91%, XLP +0.62%, XLB +0.55%, XLE +0.25%, XLC +0.09%, XLI +0.07%
- Decliners: XLK −0.28%
- Mega-caps: TSLA +1.54%, TSM +1.16%, AMZN +0.07%; AVGO −0.07%, NVDA −0.29%, MSFT −0.31%, AAPL −1.00%, GOOGL −1.13%, META −1.59%
Market Internals:
- NYSE: advancers outnumbered decliners 2.04-to-1; 114 new highs vs 236 new lows (Reuters)
- Nasdaq: 3,245 advancers vs 1,608 decliners; 46 new highs vs 266 new lows
- S&P 500: 22 new 52-week highs, 1 new low
- Volume: 15.91B shares vs a 17.15B 20-day average
Volatility:
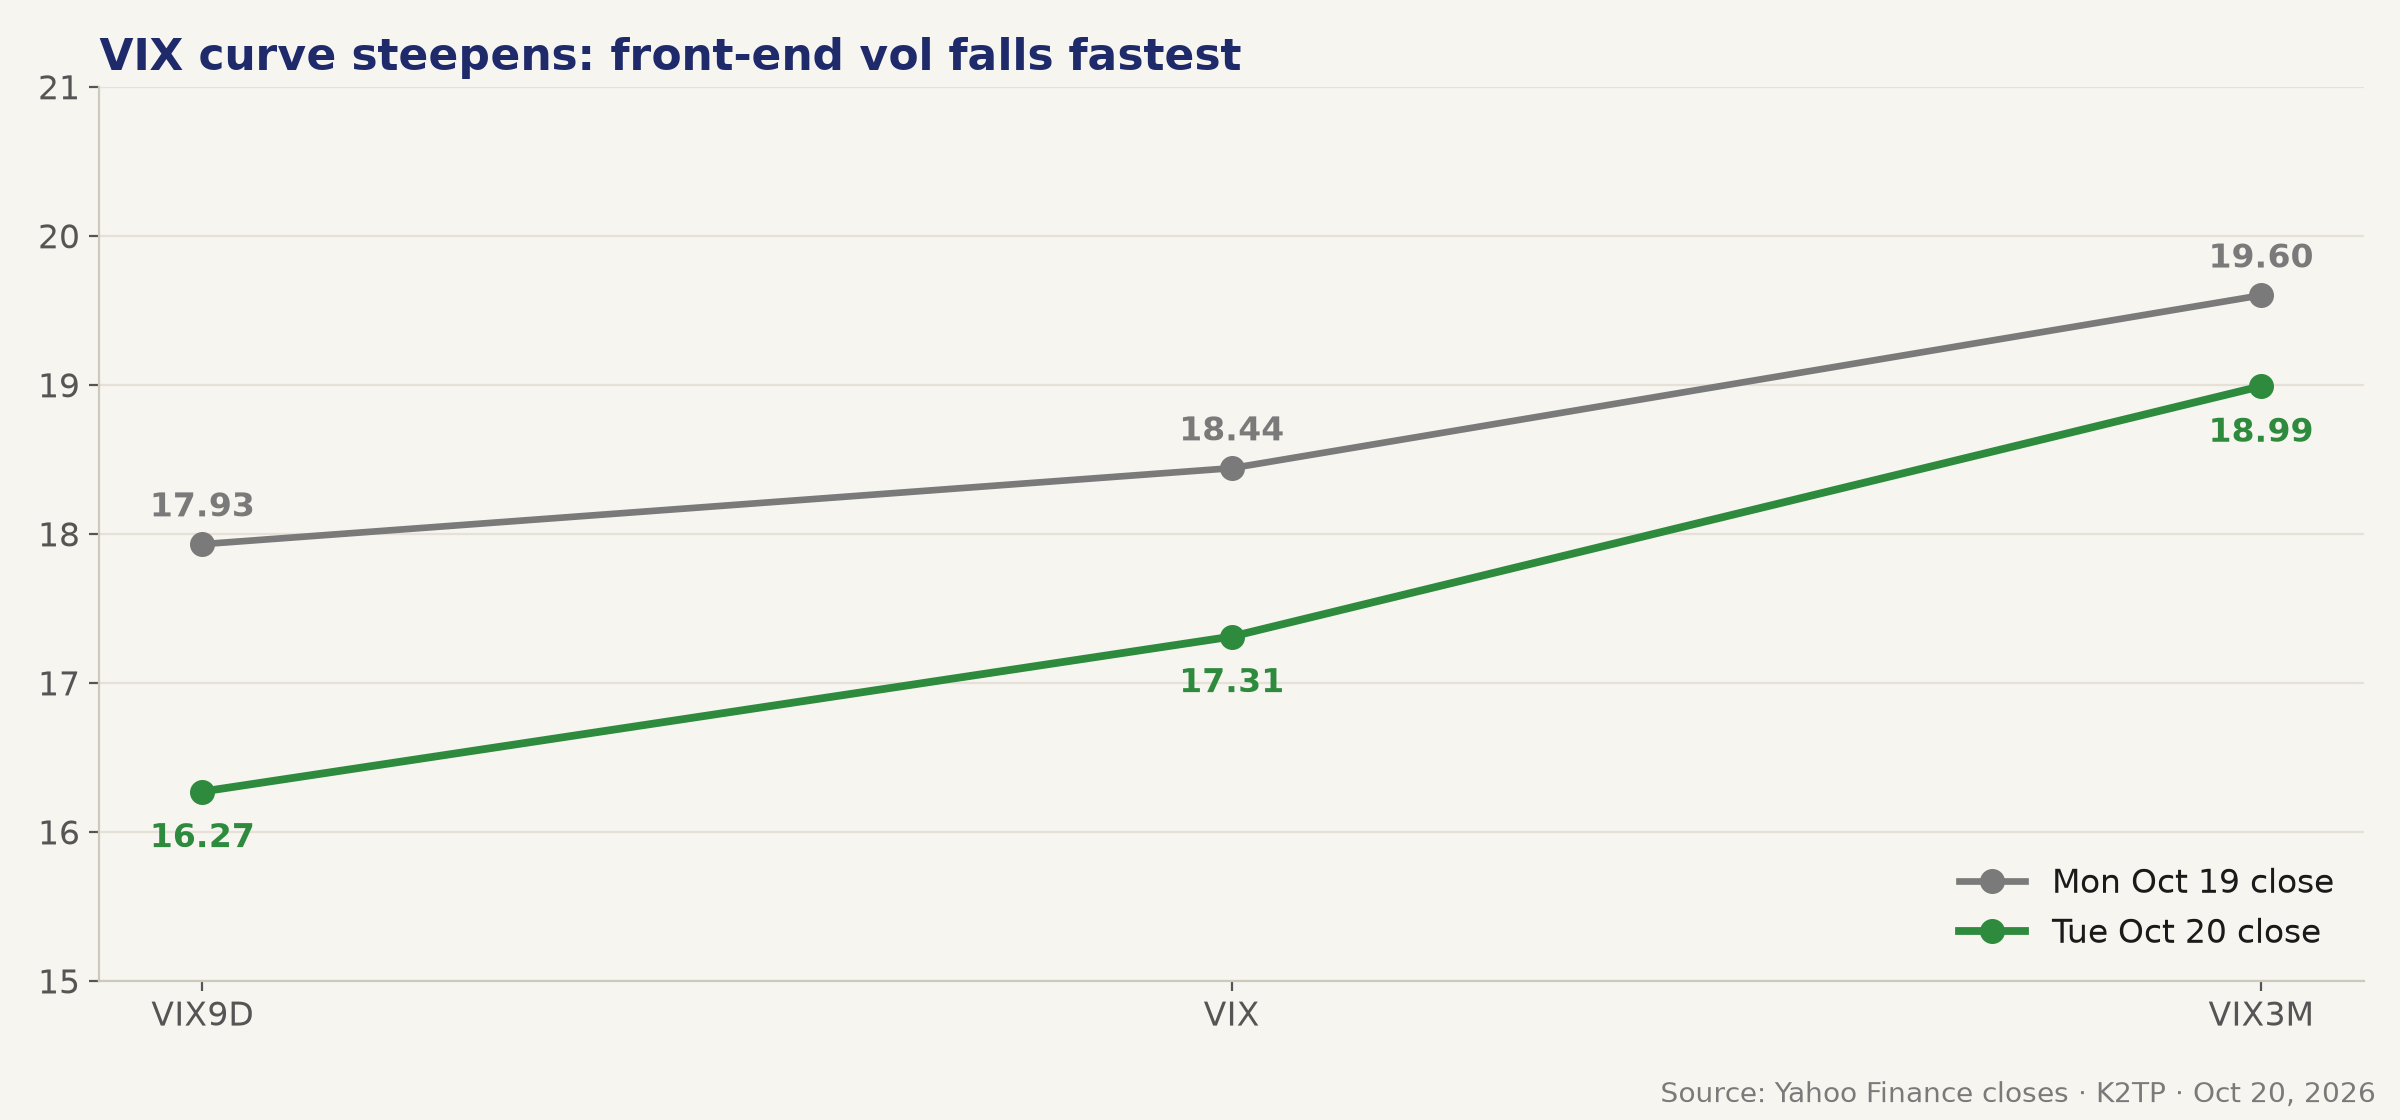
- VIX 17.31 (−6.13%), range 17.25–19.13 (overnight high)
- VIX9D 16.27 (from 17.93), VIX3M 18.99 (from 19.60): steeper contango, with the front end falling fastest
- VVIX 97.15 (−9.15%)
Cross-asset:
- DXY about 101.7–101.8; gold settled at $4,142.60; BTC about $82,900 (+1.3%)
Global:
- Asia (Tuesday): Kospi −3.73%, Taiwan −1.86%, Nikkei −1.30%, Hang Seng −1.32%
- Europe: Euro Stoxx 50 −0.38%, DAX −0.06%, FTSE −0.29%, CAC −0.38%
- Tonight (around 6:50 PM PT, Yahoo): Kospi +4.06%, Nikkei +1.59%, Hang Seng +0.56%
SPX Key Levels:
- 7,748.42: Tuesday's high, Bull line
- 7,731.18: Monday's high
- 7,712.57: close
- 7,690.73: Monday's close
- 7,684.79: Monday's low
- 7,668.03: Tuesday's low, Bear line
- VIX: 17.25 and 18.44
Option-seller angle:
- Bull case: an SPX close above 7,748.42 with VIX under 17.25 tips the regime to RISK-ON. Far OTM SPX put spreads then make sense, but keep size moderate before Meta and Tesla.
- Bear case: an SPX close under 7,668.03 with VIX above 18.44 pulls the tape toward RISK-OFF. Then cut short-put size and favor defined-risk spreads.
- VIX9D under VIX and a steeper contango favor short-dated index premium sellers. But Meta, Tesla, Lam Research, Texas Instruments and IBM report Wednesday night, so avoid short straddles or tight Iron Condors on NDX and single names through Wednesday's close.
- Money is flowing into healthcare, banks and small caps; far OTM short puts fit those groups better than mega-cap tech before earnings.
BOTTOM LINE
- The broadest rotation in weeks: RUT +1.65%, RSP +1.15%, 10 of 11 sector ETFs up and a record in healthcare.
- Mega-cap tech sat out, so SPX rose only 0.28% and NDX slipped. Weak housing and an oil reversal pulled long-end yields and VIX lower.
- The regime stays 🟡 TRANSITION, leaning RISK-ON. SpaceX lifted AI after hours; confirmation needs SPX above 7,748.42 with VIX under 17.25.
What to watch tomorrow (PT):
- 4:00 AM: MBA mortgage applications
- Before the open: AT&T, Thermo Fisher, Abbott, NextEra, CME, Danaher, Elevance, Moody's, Philip Morris
- 7:30 AM: EIA crude inventories
- 10:00 AM: $13B 20-year bond auction (last high yield 5.42%)
- After the close: Meta (EPS est. $6.53), Tesla ($0.45), Lam Research, Texas Instruments, IBM
- Thursday 5:30 AM: initial jobless claims (prior 199K, forecast 200K); Friday 6:45 AM: S&P Global flash October PMIs
- Oct 27–28: FOMC, decision at 11:00 AM on Oct 28
Expected (Bull): NQ holds tonight's gain, SPX closes above 7,748.42, VIX under 17.25, and the 20-year auction clears without a tail with the 10Y under 5.136%. Expected (Bear): SPX under 7,668.03, VIX above 18.44, Brent back above $112, or a weak auction lifting the 10Y above 5.136%.
Sources: 4 K2TP briefs for Oct 20, 2026 (Pre-Market, Midday, Pre-Close, Evening Recap). Closing and after-hours prices from Yahoo Finance; breadth, Fed odds and news from Reuters, CNBC, Benzinga, AP and Cboe; housing data from the U.S. Census Bureau and NAR; Sankey from Netflix's official Q3 2026 shareholder letter (8-K, SEC EDGAR). Analysis: K2TP Framework.